5 days ago
The 'half-a-loaf' plan gifts roughly half of excess ***** ets to children, then uses a Medicaid-compliant annuity to bridge the penalty period.
Keeping retained cash in a bank account prevents the penalty clock from starting, since ***** ets above $2,000 disqualify the applicant outright.
One flawed annuity term or miscalculated divisor can unravel the entire plan, making elder law attorney guidance essential before any money moves.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Picture a common scenario in a state where this type of crisis planning is welcome: Dad moves into a nursing home with roughly $200,000 sitting above the $2,000 countable-asset limit that most states use for single Nursing Home Medicaid applicants. His family gifts about $100,000 to the children, then uses the other half to buy a short-term Medicaid-compliant annuity that pays the nursing home while the gift penalty runs. When the penalty ends, Medicaid picks up the bill. The children keep the gift.
#annuity #roughly
Keeping retained cash in a bank account prevents the penalty clock from starting, since ***** ets above $2,000 disqualify the applicant outright.
One flawed annuity term or miscalculated divisor can unravel the entire plan, making elder law attorney guidance essential before any money moves.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Picture a common scenario in a state where this type of crisis planning is welcome: Dad moves into a nursing home with roughly $200,000 sitting above the $2,000 countable-asset limit that most states use for single Nursing Home Medicaid applicants. His family gifts about $100,000 to the children, then uses the other half to buy a short-term Medicaid-compliant annuity that pays the nursing home while the gift penalty runs. When the penalty ends, Medicaid picks up the bill. The children keep the gift.
#annuity #roughly

19 days ago
One of the toughest hurdles for retirees is working out how to pay themselves and then spending the money.
For decades, the pressure has been to save. When the time comes to start drawing on those funds, it can be paralyzing.
Personal finance expert Jean Chatzky has a solution: Use an annuity to provide a paycheck.
To annuitize essentially means to convert a lump sum portion of a retirement account into a contract that pays you a fixed monthly amount for a specified period or for the rest of your life.
The trouble is that annuities sold by insurance companies have a bad undertone for many people. They can be difficult to understand and typically come with a variety of fees. It's hard to know what the real cost is and what the penalties are if you need to tap the money for an emergency.
#spending
For decades, the pressure has been to save. When the time comes to start drawing on those funds, it can be paralyzing.
Personal finance expert Jean Chatzky has a solution: Use an annuity to provide a paycheck.
To annuitize essentially means to convert a lump sum portion of a retirement account into a contract that pays you a fixed monthly amount for a specified period or for the rest of your life.
The trouble is that annuities sold by insurance companies have a bad undertone for many people. They can be difficult to understand and typically come with a variety of fees. It's hard to know what the real cost is and what the penalties are if you need to tap the money for an emergency.
#spending

20 days ago
Annuity payouts look higher because they blend interest with returned principal, but a dividend portfolio keeps your capital invested and available to heirs.
AT&T cut its dividend in 2022 and has held it flat since, while Duke Energy targets 5% to 7% annual EPS growth through 2030.
Splitting $930,000 between an annuity covering fixed expenses and a dividend portfolio for growth offers a viable third path beyond the binary choice.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
You have $930,000 and one question: Does an insurance company writing a lifetime check produce more monthly income than a dividend portfolio you control? Most of the confusion comes from comparing two numbers that do not measure the same thing.
#Dividend
AT&T cut its dividend in 2022 and has held it flat since, while Duke Energy targets 5% to 7% annual EPS growth through 2030.
Splitting $930,000 between an annuity covering fixed expenses and a dividend portfolio for growth offers a viable third path beyond the binary choice.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
You have $930,000 and one question: Does an insurance company writing a lifetime check produce more monthly income than a dividend portfolio you control? Most of the confusion comes from comparing two numbers that do not measure the same thing.
#Dividend


20 days ago
One of the toughest hurdles for retirees is working out how to pay themselves and then spending the money.
For decades, the pressure has been to save. When the time comes to start drawing on those funds, it can be paralyzing.
Personal finance expert Jean Chatzky has a solution: Use an annuity to provide a paycheck.
To annuitize essentially means to convert a lump sum portion of a retirement account into a contract that pays you a fixed monthly amount for a specified period or for the rest of your life.
The trouble is that annuities sold by insurance companies have a bad undertone for many people. They can be difficult to understand and typically come with a variety of fees. It's hard to know what the real cost is and what the penalties are if you need to tap the money for an emergency.
#personal #chatzky #retirees #themselves
For decades, the pressure has been to save. When the time comes to start drawing on those funds, it can be paralyzing.
Personal finance expert Jean Chatzky has a solution: Use an annuity to provide a paycheck.
To annuitize essentially means to convert a lump sum portion of a retirement account into a contract that pays you a fixed monthly amount for a specified period or for the rest of your life.
The trouble is that annuities sold by insurance companies have a bad undertone for many people. They can be difficult to understand and typically come with a variety of fees. It's hard to know what the real cost is and what the penalties are if you need to tap the money for an emergency.
#personal #chatzky #retirees #themselves


26 days ago
Annuities are popular with many retirees because they offer what seems to be a guaranteed fixed income for the rest of your life. Financial advisor Suze Orman warns that they might not be as safe a bet as they seem.
"[An annuity is] subject to the claims paying ability of the issuing company," said Orman on an episode of her podcast, Suze Orman's Women & Money. "Meaning that if the insurer gets in trouble… your guarantee is only as good as their balance sheet."
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#orman
"[An annuity is] subject to the claims paying ability of the issuing company," said Orman on an episode of her podcast, Suze Orman's Women & Money. "Meaning that if the insurer gets in trouble… your guarantee is only as good as their balance sheet."
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#orman


27 days ago
Annuities are popular with many retirees because they offer what seems to be a guaranteed fixed income for the rest of your life. Financial advisor Suze Orman warns that they might not be as safe a bet as they seem.
"[An annuity is] subject to the claims paying ability of the issuing company," said Orman on an episode of her podcast, Suze Orman's Women & Money. "Meaning that if the insurer gets in trouble… your guarantee is only as good as their balance sheet."
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#orman #financial #women #bezos
"[An annuity is] subject to the claims paying ability of the issuing company," said Orman on an episode of her podcast, Suze Orman's Women & Money. "Meaning that if the insurer gets in trouble… your guarantee is only as good as their balance sheet."
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#orman #financial #women #bezos

28 days ago
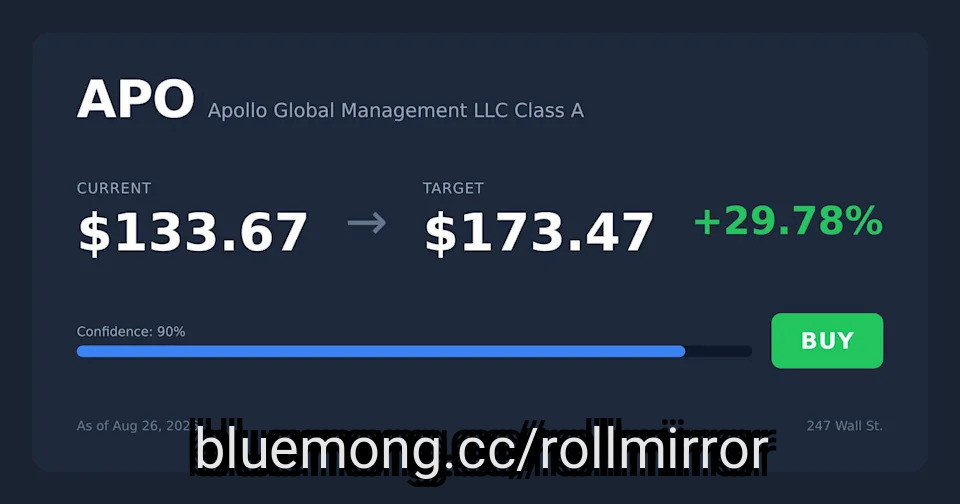
Two Midwestern insurers hold $245 million in LeBron James Nike-backed bonds, with those same balance sheets also backing annuities from Jackson (JXN) and Apollo (APO).
Non-qualified annuity gains face ordinary income tax up to 37%, no capital gains rates apply, and heirs inherit no step-up in basis at death.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Somewhere in the general accounts of two Midwestern life insurers sits roughly $245 million in bonds backed by LeBron James's Nike deal.
According to Bloomberg, an LLC named King James Funding borrowed almost $300 million in 2018 from North American Company for Life and Health Insurance and Midland National Life Insurance Co., with bonds due in 2049 at a 4.8% coupon. A follow-on $60 million in 34-year bonds priced at 5.75% in August 2022. Guggenheim Partners arranged the deal, and the pledged revenue stream includes James's lifetime Nike sponsorship.
#million #james
Non-qualified annuity gains face ordinary income tax up to 37%, no capital gains rates apply, and heirs inherit no step-up in basis at death.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Somewhere in the general accounts of two Midwestern life insurers sits roughly $245 million in bonds backed by LeBron James's Nike deal.
According to Bloomberg, an LLC named King James Funding borrowed almost $300 million in 2018 from North American Company for Life and Health Insurance and Midland National Life Insurance Co., with bonds due in 2049 at a 4.8% coupon. A follow-on $60 million in 34-year bonds priced at 5.75% in August 2022. Guggenheim Partners arranged the deal, and the pledged revenue stream includes James's lifetime Nike sponsorship.
#million #james

29 days ago
A fixed annuity guarantees the dollar amount, not purchasing power. With PCE inflation at 3.7%, a $1,900 check buys meaningfully less each decade.
Social Security's annual COLA, tracking 3.1% for 2027, preserves purchasing power over time in a way fixed private annuities fundamentally cannot.
Retirees can fight inflation erosion by adding a COLA rider, laddering annuity purchases across ages, or keeping part of the portfolio invested outside the contract.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A $1,900 monthly annuity check that lands on the first of every month solves one problem exceptionally well. You cannot outlive it. That is really the case for annuitization in a single sentence, and it is exactly why insurers can market these contracts as guaranteed for life. But here is the catch. That guarantee covers the nominal dollar amount, not what it can buy. A decade later, that same $1,900 is going to buy a smaller basket of groceries, a smaller share of a Medicare supplement premium, and a much smaller slice of any long-term care bill.
#purchasing
Social Security's annual COLA, tracking 3.1% for 2027, preserves purchasing power over time in a way fixed private annuities fundamentally cannot.
Retirees can fight inflation erosion by adding a COLA rider, laddering annuity purchases across ages, or keeping part of the portfolio invested outside the contract.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A $1,900 monthly annuity check that lands on the first of every month solves one problem exceptionally well. You cannot outlive it. That is really the case for annuitization in a single sentence, and it is exactly why insurers can market these contracts as guaranteed for life. But here is the catch. That guarantee covers the nominal dollar amount, not what it can buy. A decade later, that same $1,900 is going to buy a smaller basket of groceries, a smaller share of a Medicare supplement premium, and a much smaller slice of any long-term care bill.
#purchasing

1 month ago
Sun Life Financial and Wilton Re have signed a definitive agreement for a reinsurance and ****** et management partnership.
Under the agreement, Wilton Re will establish Windsor Life Re, an affiliated reinsurer domiciled in the US and Bermuda, with long-term capital commitments from both parties.
The partnership is expected to deploy approximately $900m in capital.
Wilton Re will manage Windsor Life Re, which will back the expansion of Wilton Re's core in-force life and annuity block origination business in the US.
SLC Management, Sun Life's global institutional alternatives ****** et manager, has been named lead ****** et manager for Windsor Life Re's investments.
#capital #manager
Under the agreement, Wilton Re will establish Windsor Life Re, an affiliated reinsurer domiciled in the US and Bermuda, with long-term capital commitments from both parties.
The partnership is expected to deploy approximately $900m in capital.
Wilton Re will manage Windsor Life Re, which will back the expansion of Wilton Re's core in-force life and annuity block origination business in the US.
SLC Management, Sun Life's global institutional alternatives ****** et manager, has been named lead ****** et manager for Windsor Life Re's investments.
#capital #manager

1 month ago
AT&T (NYSE: T) is part of a cellphone oligopoly in the United States. Essentially, the telecom giant and its main competitors dominate the sector, making it difficult for a newcomer to break in. However, that hasn't stopped companies from trying, including cable operators offering bundled services and, perhaps, even **** e Exploration Corporation's (NASDAQ: SPCX) Starlink. Here's how investors should view AT&T's ability to maintain its well-above-market 4.4% dividend yield as more companies try to break into the lucrative cellphone market.
The first thing to consider when looking at AT&T's business is the competitive landscape. It has always been intense, as the members of the cellphone oligopoly fight tooth and nail for market share. There's a good reason for that, however: customer revenues tend to be annuity-like. That provides a solid foundation for paying the dividend. And while the involvement of cable companies and **** eX increases competition, AT&T should be able to hold its own as a business.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That big picture view of the situation, however, doesn't mean it will be able to continue paying its dividend at the current level. Most investors **** sing dividend support will look to the payout ratio to determine whether the company can continue paying nearly $2 billion in dividends each quarter. The 36% trailing 12-month payout ratio suggests the answer is yes.
But that $2 billion in dividends number came from the cash flow statement, not the income statement, where earnings live. This is because earnings aren't what pay the dividend; cash flow is. When you compare the dividend to cash flow, using the cash dividend payout ratio, you get a slightly lower coverage rate of 45%. That, however, still looks like ample coverage.
#NVIDIA
The first thing to consider when looking at AT&T's business is the competitive landscape. It has always been intense, as the members of the cellphone oligopoly fight tooth and nail for market share. There's a good reason for that, however: customer revenues tend to be annuity-like. That provides a solid foundation for paying the dividend. And while the involvement of cable companies and **** eX increases competition, AT&T should be able to hold its own as a business.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That big picture view of the situation, however, doesn't mean it will be able to continue paying its dividend at the current level. Most investors **** sing dividend support will look to the payout ratio to determine whether the company can continue paying nearly $2 billion in dividends each quarter. The 36% trailing 12-month payout ratio suggests the answer is yes.
But that $2 billion in dividends number came from the cash flow statement, not the income statement, where earnings live. This is because earnings aren't what pay the dividend; cash flow is. When you compare the dividend to cash flow, using the cash dividend payout ratio, you get a slightly lower coverage rate of 45%. That, however, still looks like ample coverage.
#NVIDIA


1 month ago
On August 13, Brookfield (NYSE:BN) held its second-quarter earnings call, and the story management told was less about property spreadsheets and more about power lines and reactors. Distributable earnings before realizations climbed 15% year over year to $1.4 billion for the quarter, and executives spent much of the call explaining how a $100 billion Kentucky data center project and a nuclear buildout fit into that growth.
Brookfield's pitch centers on a gap between AI's appetite for electricity and the grid's ability to supply it. CEO Bruce Flatt described a $100 billion partnership with the US Department of Energy to build an AI campus in Kentucky on federally owned land, a deal he said requires few approvals because of that federal ownership. Alongside that, the Department of Energy committed a further $17.5 billion to Brookfield and its utility partners to acquire long lead time items for Westinghouse's reactor pipeline, which the company says is now under construction on 14 reactors with visibility into 40 more and another 100 beyond that.
The ****** et management engine backing these bets had its own strong quarter. Fundraising hit a record $77 billion, pushing fee-bearing capital up 19% to $672 billion and fee-related earnings up 20% from a year earlier. The Oaktree acquisition closed in July, and Wealth Solutions distributable earnings rose 23% year over year to $480 million as the newly acquired Just Group added $45 billion of insurance ****** ets. Real estate leasing added another data point: office tenants signed 4.5 million square feet globally at net rents 19% above what was expiring, including leases in Canada priced more than double prior rates.
Flatt opened his remarks by naming the risks directly, pointing to geopolitical conflict, higher energy prices and uncertainty around interest rates as factors shaping the near-term market environment. That acknowledgment sits alongside a Just Group integration that is still a work in progress. Management said it exited an early-stage direct-to-consumer initiative and is still working through reducing the business's cost base, and Just contributed just $29 million of earnings in its first quarter under Brookfield ownership, a starting return on equity of about 12%.
Capital return also raises questions for income-focused shareholders. The board declared a quarterly dividend of only $0.07 per share, while the company spent roughly $580 million on buybacks year to date at an average price of $42, showing where management prefers to direct spare cash. Separately, the approved simplification of Brookfield's capital structure requires taxable Canadian and UK shareholders to actively file an election if they want a tax-deferred share exchange, an administrative step that falls on investors rather than the company. Management also acknowledged the annuity business operates in a competitive market, even as it held spreads above 200 basis points.
#energy #company
Brookfield's pitch centers on a gap between AI's appetite for electricity and the grid's ability to supply it. CEO Bruce Flatt described a $100 billion partnership with the US Department of Energy to build an AI campus in Kentucky on federally owned land, a deal he said requires few approvals because of that federal ownership. Alongside that, the Department of Energy committed a further $17.5 billion to Brookfield and its utility partners to acquire long lead time items for Westinghouse's reactor pipeline, which the company says is now under construction on 14 reactors with visibility into 40 more and another 100 beyond that.
The ****** et management engine backing these bets had its own strong quarter. Fundraising hit a record $77 billion, pushing fee-bearing capital up 19% to $672 billion and fee-related earnings up 20% from a year earlier. The Oaktree acquisition closed in July, and Wealth Solutions distributable earnings rose 23% year over year to $480 million as the newly acquired Just Group added $45 billion of insurance ****** ets. Real estate leasing added another data point: office tenants signed 4.5 million square feet globally at net rents 19% above what was expiring, including leases in Canada priced more than double prior rates.
Flatt opened his remarks by naming the risks directly, pointing to geopolitical conflict, higher energy prices and uncertainty around interest rates as factors shaping the near-term market environment. That acknowledgment sits alongside a Just Group integration that is still a work in progress. Management said it exited an early-stage direct-to-consumer initiative and is still working through reducing the business's cost base, and Just contributed just $29 million of earnings in its first quarter under Brookfield ownership, a starting return on equity of about 12%.
Capital return also raises questions for income-focused shareholders. The board declared a quarterly dividend of only $0.07 per share, while the company spent roughly $580 million on buybacks year to date at an average price of $42, showing where management prefers to direct spare cash. Separately, the approved simplification of Brookfield's capital structure requires taxable Canadian and UK shareholders to actively file an election if they want a tax-deferred share exchange, an administrative step that falls on investors rather than the company. Management also acknowledged the annuity business operates in a competitive market, even as it held spreads above 200 basis points.
#energy #company

1 month ago
On August 7, **** ured Guaranty (NYSE:AGO) closed out a first half that pushed several core valuation metrics to record territory. Shareholders' equity, adjusted operating shareholders' equity, and adjusted book value per share all hit new highs at quarter-end, while new business production climbed to $152 million in present value of new business production/PVP for the first six months of 2026, up from $103 million a year earlier. That growth came even as the company kept underwriting through credit exposures that haven't gone away.
US public finance alone generated $106 million of PVP in the first half of 2026, more than the entire company produced in the first half of 2025, while insuring $9.6 billion of new issue par across 423 transactions. Global structured finance PVP more than doubled to $35 million from $15 million a year earlier, helped by fund finance deals that typically mature in a few months to a little over two years, letting the company recycle capital faster than in its longer-duration public finance book. The newer annuity reinsurance platform, **** ured Life Re, launched in January, and management says it remains on track to hit its production and income milestones.
Overseas, the company added deals in the UK, Spain, and France, part of a stated push into Europe and Asia Pacific. Second quarter adjusted operating income rose 22% year-over-year to $55 million, or $1.23 per share, helped by loss expense falling to $4 million from $28 million a year earlier. The company also kept returning cash, repurchasing 554,000 shares for $45 million in the quarter and paying $17 million in dividends, with the quarterly dividend per share now at $0.38.
Not everything moved in a straight line. The Brightline transaction was the biggest driver of economic loss development in the quarter, and management said the toll operator continues to face liquidity pressure even as its revenue grows; the exposure hasn't hurt adjusted operating income yet because expected losses haven't exceeded the deferred premium revenue on the policy, but the company said it is still working with Brightline and its other creditors on a resolution.
Thames Water remained a live issue too, though management reported no material change to its loss expectations in the second quarter, and the company is waiting on a new administration to help implement a solution creditors already negotiated with the UK regulator. The alternative investment book, which has delivered a roughly 12% inception-to-date internal rate of return against a 4.3% three-year average yield on the fixed maturity portfolio, took a step back after a $19 million mark-to-market loss tied to a CLO equity fund investment that reports on a one-quarter lag, a reminder of how much a single position can sway quarterly results.
#company #finance
US public finance alone generated $106 million of PVP in the first half of 2026, more than the entire company produced in the first half of 2025, while insuring $9.6 billion of new issue par across 423 transactions. Global structured finance PVP more than doubled to $35 million from $15 million a year earlier, helped by fund finance deals that typically mature in a few months to a little over two years, letting the company recycle capital faster than in its longer-duration public finance book. The newer annuity reinsurance platform, **** ured Life Re, launched in January, and management says it remains on track to hit its production and income milestones.
Overseas, the company added deals in the UK, Spain, and France, part of a stated push into Europe and Asia Pacific. Second quarter adjusted operating income rose 22% year-over-year to $55 million, or $1.23 per share, helped by loss expense falling to $4 million from $28 million a year earlier. The company also kept returning cash, repurchasing 554,000 shares for $45 million in the quarter and paying $17 million in dividends, with the quarterly dividend per share now at $0.38.
Not everything moved in a straight line. The Brightline transaction was the biggest driver of economic loss development in the quarter, and management said the toll operator continues to face liquidity pressure even as its revenue grows; the exposure hasn't hurt adjusted operating income yet because expected losses haven't exceeded the deferred premium revenue on the policy, but the company said it is still working with Brightline and its other creditors on a resolution.
Thames Water remained a live issue too, though management reported no material change to its loss expectations in the second quarter, and the company is waiting on a new administration to help implement a solution creditors already negotiated with the UK regulator. The alternative investment book, which has delivered a roughly 12% inception-to-date internal rate of return against a 4.3% three-year average yield on the fixed maturity portfolio, took a step back after a $19 million mark-to-market loss tied to a CLO equity fund investment that reports on a one-quarter lag, a reminder of how much a single position can sway quarterly results.
#company #finance


1 month ago
Buying an annuity inside an IRA duplicates the tax deferral the account already provides for free, while also adding fees of 1% to 3% or more annually.
With 52-week T-bills yielding 4.02% and I-bonds at 4.26%, annuity fees directly erase returns available risk-free inside the same IRA.
Average Boomer IRA balances of $257,002 mean an annuity purchase often consumes an entire account, concentrating fee drag on every dollar saved.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
The decision at the center of this story is one financial planners see often: a retiree moves $300,000 from an existing IRA into a variable or fixed annuity held inside that same IRA, with the pitch centered on tax deferral. The problem is structural, as an IRA already provides tax deferral. Wrapping an annuity inside an IRA duplicates a benefit the account already provides and adds a fee layer on top of one that already exists, during a period when risk-free yields are the highest they have been in over a year.
#free #deferral #duplicates
With 52-week T-bills yielding 4.02% and I-bonds at 4.26%, annuity fees directly erase returns available risk-free inside the same IRA.
Average Boomer IRA balances of $257,002 mean an annuity purchase often consumes an entire account, concentrating fee drag on every dollar saved.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
The decision at the center of this story is one financial planners see often: a retiree moves $300,000 from an existing IRA into a variable or fixed annuity held inside that same IRA, with the pitch centered on tax deferral. The problem is structural, as an IRA already provides tax deferral. Wrapping an annuity inside an IRA duplicates a benefit the account already provides and adds a fee layer on top of one that already exists, during a period when risk-free yields are the highest they have been in over a year.
#free #deferral #duplicates


1 month ago
SmartAsset and Yahoo Finance LLC may earn commission or revenue through links in the content below.
We have a combined pension and Social Security income of $8,400 per month that will only drop to $6,730 if one of us passes away. Our RMDs will start soon and we have $1.6 million in a 401(k) which we feel we can use a low-cost (expense ratio 0.12%) total return target fund to avoid the use of a robo-advisor that charges 0.3 – 0.8%. Plus, we have another $350,000 in Roths and a taxable brokerage account of $300,000 which RMDs would flow into. We own our home outright. In place of an annuity purchase can I simply use a target date fund in my IRA from which RMDs would be drawn automatically?
-JR
I hear a few different questions here, JR. First, should you purchase an annuity or rely on your investment portfolio? Next, is the cost of a robo-advisor worth it compared to a target date fund? And lastly, is a target date fund or robo-advisor sufficient for managing a portfolio like yours? Let's dig into each of them to help you get some answers. (And if you need more help answering questions like these, consider speaking with a financial advisor.)
An annuity is a form of insurance. You purchase it with the expectation that over the long term, the cost will be greater than the benefit. But, as with other types of insurance, it protects against a key risk. In this case, that risk is the possibility of running out of money, especially if you live longer than expected.
#cost #questions
We have a combined pension and Social Security income of $8,400 per month that will only drop to $6,730 if one of us passes away. Our RMDs will start soon and we have $1.6 million in a 401(k) which we feel we can use a low-cost (expense ratio 0.12%) total return target fund to avoid the use of a robo-advisor that charges 0.3 – 0.8%. Plus, we have another $350,000 in Roths and a taxable brokerage account of $300,000 which RMDs would flow into. We own our home outright. In place of an annuity purchase can I simply use a target date fund in my IRA from which RMDs would be drawn automatically?
-JR
I hear a few different questions here, JR. First, should you purchase an annuity or rely on your investment portfolio? Next, is the cost of a robo-advisor worth it compared to a target date fund? And lastly, is a target date fund or robo-advisor sufficient for managing a portfolio like yours? Let's dig into each of them to help you get some answers. (And if you need more help answering questions like these, consider speaking with a financial advisor.)
An annuity is a form of insurance. You purchase it with the expectation that over the long term, the cost will be greater than the benefit. But, as with other types of insurance, it protects against a key risk. In this case, that risk is the possibility of running out of money, especially if you live longer than expected.
#cost #questions



1 month ago
Bloom Energy (NYSE:BE) just added another name to its growing list of AI infrastructure customers. On August 6, the company announced an expanded partnership with MiTAC Computing Technology Corp., a subsidiary of MiTAC Holdings Corporation, to deploy a fuel cell microgrid at MiTAC's AI server manufacturing campus in Fremont, California. It is a small deal in isolation, but it fits a pattern that has turned Bloom into one of the more talked-about names in the AI power trade.
The MiTAC expansion builds on an existing installation at the company's San Jose facility, and it will run as an islanded microgrid, meaning it operates independent of the local grid entirely. That matters because manufacturers building AI servers are running into the same power bottlenecks as the data centers buying their products. Bloom's Chief Commercial Officer Aman Joshi noted the company now serves nearly two dozen AI infrastructure customers with about 250 megawatts of contracted capacity, up from nearly zero just two years ago. Fuel cells generate power through an electrochemical process rather than combustion, which sidesteps permitting delays, water constraints and noise limits that can slow down traditional generation.
That growth shows up in the numbers too. Bloom's backlog reached $20 billion at the start of 2026, and product orders within that backlog rose 140% year over year, according to ****** ysis from Reuben Gregg Brewer published August 5. The company posted its first billion-dollar revenue quarter, and management raised full-year 2026 guidance to a range of $3.9 billion to $4.2 billion, per ****** ysis from Steven Porrello also published August 5. Wall Street currently expects revenue to more than triple over the next two years, and Bloom was profitable in both the first and second quarters of 2026.
The service portion of that backlog, roughly $14 billion of the $20 billion total, is the more durable piece of the business, since every fuel cell sold locks in an annuity-like service contract. But Brewer's ****** ysis points out that Bloom's overall profitability only turned positive in 2026, after losses in 2024 and 2025 even while the services business alone stayed profitable since 2024.
The stock has also been volatile. Shares are up roughly 500% over the trailing year but have pulled back about 35% from their highs, trading near $218 after touching roughly $345. Brewer argues that much of the good news already appears priced in, and that only aggressive growth investors should consider buying after such a rapid move. Even on a forward basis, Porrello notes the stock trades around 11 times next fiscal year's expected sales, a multiple that still ****** umes the AI buildout keeps accelerating without interruption.
#power #backlog #Analysis
The MiTAC expansion builds on an existing installation at the company's San Jose facility, and it will run as an islanded microgrid, meaning it operates independent of the local grid entirely. That matters because manufacturers building AI servers are running into the same power bottlenecks as the data centers buying their products. Bloom's Chief Commercial Officer Aman Joshi noted the company now serves nearly two dozen AI infrastructure customers with about 250 megawatts of contracted capacity, up from nearly zero just two years ago. Fuel cells generate power through an electrochemical process rather than combustion, which sidesteps permitting delays, water constraints and noise limits that can slow down traditional generation.
That growth shows up in the numbers too. Bloom's backlog reached $20 billion at the start of 2026, and product orders within that backlog rose 140% year over year, according to ****** ysis from Reuben Gregg Brewer published August 5. The company posted its first billion-dollar revenue quarter, and management raised full-year 2026 guidance to a range of $3.9 billion to $4.2 billion, per ****** ysis from Steven Porrello also published August 5. Wall Street currently expects revenue to more than triple over the next two years, and Bloom was profitable in both the first and second quarters of 2026.
The service portion of that backlog, roughly $14 billion of the $20 billion total, is the more durable piece of the business, since every fuel cell sold locks in an annuity-like service contract. But Brewer's ****** ysis points out that Bloom's overall profitability only turned positive in 2026, after losses in 2024 and 2025 even while the services business alone stayed profitable since 2024.
The stock has also been volatile. Shares are up roughly 500% over the trailing year but have pulled back about 35% from their highs, trading near $218 after touching roughly $345. Brewer argues that much of the good news already appears priced in, and that only aggressive growth investors should consider buying after such a rapid move. Even on a forward basis, Porrello notes the stock trades around 11 times next fiscal year's expected sales, a multiple that still ****** umes the AI buildout keeps accelerating without interruption.
#power #backlog #Analysis

2 months ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
A Texas couple built up $1.8 million across two 401(k)s, a joint brokerage account and a small pension, and they're just two years from their planned retirement date. For the past several months, their longtime financial advisor has been recommending they move a significant portion of their nest egg into a fixed indexed annuity that could pay him an upfront commission of roughly 7%.
Neither of them had thought to ask how their advisor was compensated until a friend mentioned it in passing. That simple question could help them better understand whether their advisor's incentives align with their own. The issue is not necessarily the annuity itself. It's understanding how the recommendation fits their financial goals and whether the advisor has a financial incentive to recommend one product over another.
Don't Miss:
AI Robots Have Already Fried More Than 5 Million Baskets Of Food. Everyday Investors Can Still Buy Into The Company Behind Them.
#whether #finance #neither
A Texas couple built up $1.8 million across two 401(k)s, a joint brokerage account and a small pension, and they're just two years from their planned retirement date. For the past several months, their longtime financial advisor has been recommending they move a significant portion of their nest egg into a fixed indexed annuity that could pay him an upfront commission of roughly 7%.
Neither of them had thought to ask how their advisor was compensated until a friend mentioned it in passing. That simple question could help them better understand whether their advisor's incentives align with their own. The issue is not necessarily the annuity itself. It's understanding how the recommendation fits their financial goals and whether the advisor has a financial incentive to recommend one product over another.
Don't Miss:
AI Robots Have Already Fried More Than 5 Million Baskets Of Food. Everyday Investors Can Still Buy Into The Company Behind Them.
#whether #finance #neither

2 months ago
Railroad Tier I already incorporates all career earnings, so Social Security reduces Tier I dollar for dollar, leaving total retirement income unchanged.
Tier II, based solely on railroad service, is never reduced by Social Security and functions as a true additional pension on top.
Split-career workers should request a detailed RRB estimate showing gross Tier I, the Social Security offset, and Tier II before choosing filing dates.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
Picture a freight-rail diesel mechanic who spent 20 years turning wrenches on locomotives, then took a job at a manufacturing plant for the next 20. Two careers, two contribution histories, two federal retirement systems paid into. On paper, it looks like a windfall: a Railroad Retirement annuity and a Social Security benefit, both legitimately earned. Then the numbers arrive, and Social Security appears to erase most of one part of the railroad benefit.
#Retirement #split
Tier II, based solely on railroad service, is never reduced by Social Security and functions as a true additional pension on top.
Split-career workers should request a detailed RRB estimate showing gross Tier I, the Social Security offset, and Tier II before choosing filing dates.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
Picture a freight-rail diesel mechanic who spent 20 years turning wrenches on locomotives, then took a job at a manufacturing plant for the next 20. Two careers, two contribution histories, two federal retirement systems paid into. On paper, it looks like a windfall: a Railroad Retirement annuity and a Social Security benefit, both legitimately earned. Then the numbers arrive, and Social Security appears to erase most of one part of the railroad benefit.
#Retirement #split


2 months ago
A 50% survivor annuity would halve Ed's wife's monthly income to $605 and eliminate one Social Security check the moment he dies.
Orman recommended an IRA rollover, projecting the $200,000 grows to $300,000 in 8 years, with the full balance passing to Ed's wife.
Ed's wife is 8 years younger and statistically likely to outlive him by 15-20 years, making delaying Social Security until 70 critical.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
On the August 6 episode of her Women & Money podcast, Suze Orman read an email from a 62-year-old listener named Ed who had just retired against his wife's wishes and was about to pick the wrong payout on his employer annuity. Her response was blunt: "The naivete, the bare fact that you ask questions like 'can I open up a Roth IRA?', shows that innocently, your knowledge of money and how it works is nil. But the knowledge of your spouse is absolutely extraordinary."
#orman #many #advisor
Orman recommended an IRA rollover, projecting the $200,000 grows to $300,000 in 8 years, with the full balance passing to Ed's wife.
Ed's wife is 8 years younger and statistically likely to outlive him by 15-20 years, making delaying Social Security until 70 critical.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
On the August 6 episode of her Women & Money podcast, Suze Orman read an email from a 62-year-old listener named Ed who had just retired against his wife's wishes and was about to pick the wrong payout on his employer annuity. Her response was blunt: "The naivete, the bare fact that you ask questions like 'can I open up a Roth IRA?', shows that innocently, your knowledge of money and how it works is nil. But the knowledge of your spouse is absolutely extraordinary."
#orman #many #advisor

2 months ago
Inheriting an annuity comes with a deadline that's easy to miss. Your contract typically offers multiple payout options, including a choice that stretches distributions across your lifetime. The window to elect that option stays open for only one year. The wrong election or a delayed decision compresses your inheritance and tax bill into far fewer years.
Nonqualified annuities purchased outside an IRA or employer plan follow Section 72(s) of the Internal Revenue Code, not the SECURE Act's inherited IRA rules.1 That means you don't automatically get a 10-year withdrawal window. Instead, federal law creates two potential paths for distributing the contract.
Payout Path
General Timeline
Main Requirement
#payout
Nonqualified annuities purchased outside an IRA or employer plan follow Section 72(s) of the Internal Revenue Code, not the SECURE Act's inherited IRA rules.1 That means you don't automatically get a 10-year withdrawal window. Instead, federal law creates two potential paths for distributing the contract.
Payout Path
General Timeline
Main Requirement
#payout



2 months ago
In the study, the 4% rule carried a growing risk of depletion, while a full annuity sacrificed liquidity and any remaining balance.
Putting 50% of savings into an annuity earned the highest score, pairing strong income with money left for emergencies or heirs.
The study used a simple immediate annuity, not one of the more complex products commonly marketed to retirees.
For decades, one widely used retirement guideline has suggested withdrawing a set percentage in year one, typically 4%, then increasing that dollar amount annually to keep pace with inflation. But a new study found that neither this approach nor putting an entire portfolio into an annuity, produced the strongest overall result. The highest-scoring strategy used some of both.
Retirement income does not have to be an either-or choice between portfolio withdrawals and an annuity. This study suggests that combining the two may provide income security while preserving money for unexpected expenses or heirs.
#annuity
Putting 50% of savings into an annuity earned the highest score, pairing strong income with money left for emergencies or heirs.
The study used a simple immediate annuity, not one of the more complex products commonly marketed to retirees.
For decades, one widely used retirement guideline has suggested withdrawing a set percentage in year one, typically 4%, then increasing that dollar amount annually to keep pace with inflation. But a new study found that neither this approach nor putting an entire portfolio into an annuity, produced the strongest overall result. The highest-scoring strategy used some of both.
Retirement income does not have to be an either-or choice between portfolio withdrawals and an annuity. This study suggests that combining the two may provide income security while preserving money for unexpected expenses or heirs.
#annuity

2 months ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
American retirees are looking back on their retirement savings experience and, in big numbers, are expressing deep regrets over not saving enough cash for their post-working years.
That's the conclusion from a new Teachers Insurance and Annuity ****** ociation of America (TIAA) study.
TIAA found that 76% of American retirees regret not starting to save earlier in their lives, while nearly the same amount (71%) wish they'd put away more money overall (1). The report also cited a "striking gap" between retirement and reality, and that variable can bring severe savings shortages to the table. Regrets were particularly common among younger retirees, with the average study respondent saying they left the workforce at age 57.
Future retirees, on the other hand, don't expect to retire until 62.
#retirees #american #finance
American retirees are looking back on their retirement savings experience and, in big numbers, are expressing deep regrets over not saving enough cash for their post-working years.
That's the conclusion from a new Teachers Insurance and Annuity ****** ociation of America (TIAA) study.
TIAA found that 76% of American retirees regret not starting to save earlier in their lives, while nearly the same amount (71%) wish they'd put away more money overall (1). The report also cited a "striking gap" between retirement and reality, and that variable can bring severe savings shortages to the table. Regrets were particularly common among younger retirees, with the average study respondent saying they left the workforce at age 57.
Future retirees, on the other hand, don't expect to retire until 62.
#retirees #american #finance

2 months ago
One of the key investors behind the Cadillac Formula 1 project is linked to a federal investigation involving businesses he controls. Mark Walter, whose initials form part of TWG Global’s name, is **** ociated with companies under investigation by federal prosecutors, with the FBI and the U.S. Securities and Exchange Commission also involved.
The Cadillac F1 team has not had what one would call a great start to its debut in the premier class of motorsport. As a new team adapting to Formula 1 and the sport’s latest regulations, Cadillac’s 2026 campaign has largely been a learning experience rather than a competitive one.
Cadillac is the only team on the grid that has not scored a point through the first 10 races of the season. The team’s best finish was when Valtteri Bottas finished 13th in the Chinese Grand Prix. However, leaving performance aside, one of its owners, Walter, is now dealing with developments away from F1.
Bloomberg reports that Walter’s investment firm, Guggenheim Partners LLC, as well as insurance companies Delaware Life Insurance Co. and Clear Spring Life and Annuity Co., were served with grand jury subpoenas in February. The filings have only recently become public.
Prosecutors in Manhattan are reportedly examining whether the companies failed to disclose that billions of dollars in private credit investments were tied to Walter’s other business ventures.
#life
The Cadillac F1 team has not had what one would call a great start to its debut in the premier class of motorsport. As a new team adapting to Formula 1 and the sport’s latest regulations, Cadillac’s 2026 campaign has largely been a learning experience rather than a competitive one.
Cadillac is the only team on the grid that has not scored a point through the first 10 races of the season. The team’s best finish was when Valtteri Bottas finished 13th in the Chinese Grand Prix. However, leaving performance aside, one of its owners, Walter, is now dealing with developments away from F1.
Bloomberg reports that Walter’s investment firm, Guggenheim Partners LLC, as well as insurance companies Delaware Life Insurance Co. and Clear Spring Life and Annuity Co., were served with grand jury subpoenas in February. The filings have only recently become public.
Prosecutors in Manhattan are reportedly examining whether the companies failed to disclose that billions of dollars in private credit investments were tied to Walter’s other business ventures.
#life

3 months ago
The Allstate Corporation (ALL), headquartered in Northbrook, Illinois, provides property and casualty, and other insurance products. Valued at $64.4 billion by market cap, the company sells private passenger automobile and homeowners insurance through independent and specialized brokers, as well as life insurance, annuity, and group pension products through agents. The leading U.S. personal-line insurer is expected to announce its fiscal second-quarter earnings for 2026 in the near term.
Ahead of the event, ***** ysts expect ALL to report a profit of $4.90 per share on a diluted basis, down 17.5% from $5.94 per share in the year-ago quarter. The company has consistently surpassed Wall Street's EPS estimates in its last four quarterly reports.
Broadcom's Largest AI Customer Is Fleeing to MediaTek. AVGO Stock Is Still a Buy.
Nasdaq Futures Plunge as Samsung Sparks Chip Selloff
Mark Cuban Asks What If You Didn't Need Health Insurance — And Hospitals Just Treated You, Then Took 10% of Your Pay?
Ahead of the event, ***** ysts expect ALL to report a profit of $4.90 per share on a diluted basis, down 17.5% from $5.94 per share in the year-ago quarter. The company has consistently surpassed Wall Street's EPS estimates in its last four quarterly reports.
Broadcom's Largest AI Customer Is Fleeing to MediaTek. AVGO Stock Is Still a Buy.
Nasdaq Futures Plunge as Samsung Sparks Chip Selloff
Mark Cuban Asks What If You Didn't Need Health Insurance — And Hospitals Just Treated You, Then Took 10% of Your Pay?


3 months ago
MetLife Inc. (NYSE:MET) is one of the best value stocks to buy right now. On June 11, MetLife launched the Non-Qualified ****** ignment Flex Agreement/NQA-FA to provide more flexible settlement options for non-physical injury claims. Unlike traditional structures, this funding agreement allows for deferred payments extending beyond one year, enabling customized schedules for diverse cases like employment disputes and contract litigation.
The NQA-FA grants attorneys and brokers greater control over payment timing and design for both individual and business payees. By using a funding agreement rather than a standard annuity, it bypasses traditional regulatory restrictions, offering a versatile tool that adapts to the specific financial needs of claimants.
This solution directly addresses the rising demand for adaptable settlement structures in an era of increasingly complex litigation. By combining payment flexibility with MetLife Inc.'s (NYSE:MET) financial guarantees, the NQA-FA aims to support long-term financial security for those involved in legal settlements.
MetLife Inc. (NYSE:MET) provides insurance and financial services to individual and institutional clients in the US, Latin America, EMEA, and ****** an. The company is based in New York, New York, and was founded in March 1868.
While we acknowledge the potential of MET as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
The NQA-FA grants attorneys and brokers greater control over payment timing and design for both individual and business payees. By using a funding agreement rather than a standard annuity, it bypasses traditional regulatory restrictions, offering a versatile tool that adapts to the specific financial needs of claimants.
This solution directly addresses the rising demand for adaptable settlement structures in an era of increasingly complex litigation. By combining payment flexibility with MetLife Inc.'s (NYSE:MET) financial guarantees, the NQA-FA aims to support long-term financial security for those involved in legal settlements.
MetLife Inc. (NYSE:MET) provides insurance and financial services to individual and institutional clients in the US, Latin America, EMEA, and ****** an. The company is based in New York, New York, and was founded in March 1868.
While we acknowledge the potential of MET as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.

3 months ago
The federal survivor annuity election is irrevocable, permanently cutting monthly checks by 10% and costing retirees roughly $90,000 in lifetime present-value income.
FEGLI Option B premiums double every five years past 60, often making private term life insurance a cheaper replacement for healthy retirees.
Rolling a TSP into a traditional IRA unlocks qualified charitable distributions up to $108,000 annually, satisfying RMDs without adding taxable income.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
A 68-year-old federal retiree sits down with his account statements and has a startling revelation. His Thrift Savings Plan (TSP) holds $1.2 million, his FERS or CSRS annuity arrives like clockwork, and on paper he looks secure. The problem is the irrevocable survivor election he signed at retirement. Either he locked in a full survivor annuity that permanently reduces his monthly check by roughly 10%, or he waived it without modeling what that meant for his spouse. Either way, the present-value cost of that single signature looks like roughly $90,000 in lifetime income. He cannot undo it, but he can stop compounding the mistake.
FEGLI Option B premiums double every five years past 60, often making private term life insurance a cheaper replacement for healthy retirees.
Rolling a TSP into a traditional IRA unlocks qualified charitable distributions up to $108,000 annually, satisfying RMDs without adding taxable income.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
A 68-year-old federal retiree sits down with his account statements and has a startling revelation. His Thrift Savings Plan (TSP) holds $1.2 million, his FERS or CSRS annuity arrives like clockwork, and on paper he looks secure. The problem is the irrevocable survivor election he signed at retirement. Either he locked in a full survivor annuity that permanently reduces his monthly check by roughly 10%, or he waived it without modeling what that meant for his spouse. Either way, the present-value cost of that single signature looks like roughly $90,000 in lifetime income. He cannot undo it, but he can stop compounding the mistake.

3 months ago
MRVL trades at a richer 68x forward P/E than AVGO's 33x, despite posting gross margins of 52% versus Broadcom's 67%.
Broadcom's 46% FCF margin and VMware's sticky software annuity make it a reliable compounder Marvell's hyperscaler-dependent model can't yet match.
Act now: the ******* yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Broadcom didn't make the cut. Grab the names FREE today.
Marvell Technology (NASDAQ: MRVL) and Broadcom (NASDAQ: AVGO) both just delivered AI-fueled earnings beats, yet the businesses look nothing alike under the hood. Marvell posted 231.37% YTD gains chasing custom XPU wins. Broadcom quietly compounded with elite margins and a software stack. The contrast deserves a closer look before anyone pays up.
Marvell delivered Q1 FY2027 revenue of $2.42B, up 27.6% YoY, with Data Center contributing $1.83B, or 76% of revenue. CEO Matt Murphy guided Q2 to $2.70B, calling out "exceptional AI-related bookings" across 800G/1.6T optics and custom XPU programs. Encouraging, but the GAAP gross margin sat at 52.1%. That is the structural reality of bespoke silicon: hyperscalers hold the leverage.
Broadcom's 46% FCF margin and VMware's sticky software annuity make it a reliable compounder Marvell's hyperscaler-dependent model can't yet match.
Act now: the ******* yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Broadcom didn't make the cut. Grab the names FREE today.
Marvell Technology (NASDAQ: MRVL) and Broadcom (NASDAQ: AVGO) both just delivered AI-fueled earnings beats, yet the businesses look nothing alike under the hood. Marvell posted 231.37% YTD gains chasing custom XPU wins. Broadcom quietly compounded with elite margins and a software stack. The contrast deserves a closer look before anyone pays up.
Marvell delivered Q1 FY2027 revenue of $2.42B, up 27.6% YoY, with Data Center contributing $1.83B, or 76% of revenue. CEO Matt Murphy guided Q2 to $2.70B, calling out "exceptional AI-related bookings" across 800G/1.6T optics and custom XPU programs. Encouraging, but the GAAP gross margin sat at 52.1%. That is the structural reality of bespoke silicon: hyperscalers hold the leverage.

4 months ago
SmartAsset and Yahoo Finance LLC may earn commission or revenue through links in the content below.
We have a combined pension and Social Security income of $8,400 per month that will only drop to $6,730 if one of us passes away. Our RMDs will start soon and we have $1.6 million in a 401(k) which we feel we can use a low-cost (expense ratio 0.12%) total return target fund to avoid the use of a robo-advisor that charges 0.3 – 0.8%. Plus, we have another $350,000 in Roths and a taxable brokerage account of $300,000 which RMDs would flow into. We own our home outright. In place of an annuity purchase can I simply use a target date fund in my IRA from which RMDs would be drawn automatically?
-JR
I hear a few different questions here, JR. First, should you purchase an annuity or rely on your investment portfolio? Next, is the cost of a robo-advisor worth it compared to a target date fund? And lastly, is a target date fund or robo-advisor sufficient for managing a portfolio like yours? Let’s dig into each of them to help you get some answers. (And if you need more help answering questions like these, consider speaking with a financial advisor.)
An annuity is a form of insurance. You purchase it with the expectation that over the long term, the cost will be greater than the benefit. But, as with other types of insurance, it protects against a key risk. In this case, that risk is the possibility of running out of money, especially if you live longer than expected.
We have a combined pension and Social Security income of $8,400 per month that will only drop to $6,730 if one of us passes away. Our RMDs will start soon and we have $1.6 million in a 401(k) which we feel we can use a low-cost (expense ratio 0.12%) total return target fund to avoid the use of a robo-advisor that charges 0.3 – 0.8%. Plus, we have another $350,000 in Roths and a taxable brokerage account of $300,000 which RMDs would flow into. We own our home outright. In place of an annuity purchase can I simply use a target date fund in my IRA from which RMDs would be drawn automatically?
-JR
I hear a few different questions here, JR. First, should you purchase an annuity or rely on your investment portfolio? Next, is the cost of a robo-advisor worth it compared to a target date fund? And lastly, is a target date fund or robo-advisor sufficient for managing a portfolio like yours? Let’s dig into each of them to help you get some answers. (And if you need more help answering questions like these, consider speaking with a financial advisor.)
An annuity is a form of insurance. You purchase it with the expectation that over the long term, the cost will be greater than the benefit. But, as with other types of insurance, it protects against a key risk. In this case, that risk is the possibility of running out of money, especially if you live longer than expected.