

2 days ago
Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) could be positioning itself for its next major phase of growth following its roughly $10 billion acquisition of Crinetics Pharmaceuticals. The deal gives the company immediate exposure to the endocrinology market and provides a new commercial platform beyond its established cystic fibrosis franchise.
On September 3, Citigroup **** yst Geoff Meacham highlighted the strategic importance of the Crinetics acquisition, arguing it could diversify Vertex's business while complementing its existing cystic fibrosis franchise and newer businesses in renal disease, hematology, and pain.
Through the transaction, Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) gains access to Palsonify (paltusotine), an oral treatment for acromegaly that has already received regulatory approval in Europe. Paltusotine is also in Phase 3 development for carcinoid syndrome **** ociated with neuroendocrine tumors.
Palsonify is particularly important because it provides an immediate commercial revenue opportunity, rather than requiring the company to wait several years for an entirely new drug to reach the market.
Early uptake of Palsonify has been encouraging, supported by expanding physician adoption and improving reimbursement coverage. If that momentum continues, the drug could become an important contributor to Vertex's revenue growth.
#palsonify
On September 3, Citigroup **** yst Geoff Meacham highlighted the strategic importance of the Crinetics acquisition, arguing it could diversify Vertex's business while complementing its existing cystic fibrosis franchise and newer businesses in renal disease, hematology, and pain.
Through the transaction, Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) gains access to Palsonify (paltusotine), an oral treatment for acromegaly that has already received regulatory approval in Europe. Paltusotine is also in Phase 3 development for carcinoid syndrome **** ociated with neuroendocrine tumors.
Palsonify is particularly important because it provides an immediate commercial revenue opportunity, rather than requiring the company to wait several years for an entirely new drug to reach the market.
Early uptake of Palsonify has been encouraging, supported by expanding physician adoption and improving reimbursement coverage. If that momentum continues, the drug could become an important contributor to Vertex's revenue growth.
#palsonify


2 days ago
SailPoint Inc. (NASDAQ:SAIL), a leading player within the enterprise identity security ***** e, released its fiscal second-quarter 2027 on September 9. The company registered a 25% growth in its annual recurring revenue compared to the same period last year, with figures of $1.231 billion. This was driven by a 36% expansion in SaaS ARR which clocked in at $847 million. SailPoint generated $45 million in operating cash flow during the quarter, along with $37 million in free cash flow.
Burben/Shutterstock.com
Topline for the quarter hit $309 million, exhibiting 17% growth compared to Q2 FY26, amid several underlying factors. The company's subscription revenue reached $295 million, up 19% from a year earlier. SaaS customer base increased by 16%, with net new SaaS ARR jumping 34% year-over-year. It contributed around 97% to overall net new ARR for the business, with AI-driven ARR crossing $70 million mark.
SailPoint's existing customer base showed highly encouraging trends in adopting the company's AI-enabled solutions, with a 60% increase in their annual spend during the second quarter. These solutions were incorporated within more than two-thirds of the completed migrations during the quarter. Quarterly adjusted operating income increased from $54 million a year prior to $63 million, translating into an adjusted margin of 20%.
The quarter also saw key strategic moves by the management. It introduced the SailPoint Identity Security solution, which integrates SailPoint Agentic Fabric with SailPoint Human Fabric to deliver a real-time cycle for discovering and securing intricate digital ecosystems. The company also launched its Cursor Enterprise connector, which enables enterprises to manage both autonomous AI agents and human developers through an integrated control plane.
#year #SaaS #fabric #identity
Burben/Shutterstock.com
Topline for the quarter hit $309 million, exhibiting 17% growth compared to Q2 FY26, amid several underlying factors. The company's subscription revenue reached $295 million, up 19% from a year earlier. SaaS customer base increased by 16%, with net new SaaS ARR jumping 34% year-over-year. It contributed around 97% to overall net new ARR for the business, with AI-driven ARR crossing $70 million mark.
SailPoint's existing customer base showed highly encouraging trends in adopting the company's AI-enabled solutions, with a 60% increase in their annual spend during the second quarter. These solutions were incorporated within more than two-thirds of the completed migrations during the quarter. Quarterly adjusted operating income increased from $54 million a year prior to $63 million, translating into an adjusted margin of 20%.
The quarter also saw key strategic moves by the management. It introduced the SailPoint Identity Security solution, which integrates SailPoint Agentic Fabric with SailPoint Human Fabric to deliver a real-time cycle for discovering and securing intricate digital ecosystems. The company also launched its Cursor Enterprise connector, which enables enterprises to manage both autonomous AI agents and human developers through an integrated control plane.
#year #SaaS #fabric #identity

4 days ago
All six board members from the Metropolitan Nashville Airport Authority have voted to rename Nashville International Airport after Dolly Parton. The unanimous decision is the first step in the rebranding process, which will continue to unfold in the coming months, the MNAA said.
"While a final name has not yet been determined, we are working closely with the appropriate parties to thoughtfully determine how Dolly Parton's name and legacy will be incorporated," the MNAA said in a statement. "This vote represents the first step in a multifaceted process. In the coming months, we anticipate having more definitive plans to share regarding the next steps and implementation."
More from Rolling Stone
Hear Dolly Parton's First Posthumous Song - From a New Stanley Brothers Tribute Album
This Keepsake Dolly Parton Coin Is a Golden Tribute to the 'Queen of Country Music'
#nashville #step #coming
"While a final name has not yet been determined, we are working closely with the appropriate parties to thoughtfully determine how Dolly Parton's name and legacy will be incorporated," the MNAA said in a statement. "This vote represents the first step in a multifaceted process. In the coming months, we anticipate having more definitive plans to share regarding the next steps and implementation."
More from Rolling Stone
Hear Dolly Parton's First Posthumous Song - From a New Stanley Brothers Tribute Album
This Keepsake Dolly Parton Coin Is a Golden Tribute to the 'Queen of Country Music'
#nashville #step #coming


4 days ago
By Andrew Osborn
MOSCOW, Sept 10 (Reuters) - Bone fragments from the sword hand of a medieval Russian prince who won a famous victory over the Mongols have been sent to the front in Ukraine to raise army morale in the Russian Orthodox Church's latest show of support for President Vladimir Putin's war.
The sarcophagus of Grand Prince Dmitry Donskoy, who died in 1389 and is revered by Russian nationalists for defeating the Mongol Golden Horde at the 1380 Battle of Kulikovo, was uncovered this summer during restoration work at Moscow's Cathedral of the Archangel inside the Kremlin.
Putin personally inspected what experts said were the prince's well-preserved remains in August, hailing them as "an absolutely unique and marvellous discovery" which reinforced the foundations of Russian history.
The Russian Orthodox Church, which has backed Putin throughout the conflict, said it had dispatched a fragment of Donskoy's right hand to Donetsk, one of four Ukrainian regions Putin said he had incorporated into Russia in 2022, a move Kyiv rejected as an illegal land grab.
#prince #andrew #osborn #reuters
MOSCOW, Sept 10 (Reuters) - Bone fragments from the sword hand of a medieval Russian prince who won a famous victory over the Mongols have been sent to the front in Ukraine to raise army morale in the Russian Orthodox Church's latest show of support for President Vladimir Putin's war.
The sarcophagus of Grand Prince Dmitry Donskoy, who died in 1389 and is revered by Russian nationalists for defeating the Mongol Golden Horde at the 1380 Battle of Kulikovo, was uncovered this summer during restoration work at Moscow's Cathedral of the Archangel inside the Kremlin.
Putin personally inspected what experts said were the prince's well-preserved remains in August, hailing them as "an absolutely unique and marvellous discovery" which reinforced the foundations of Russian history.
The Russian Orthodox Church, which has backed Putin throughout the conflict, said it had dispatched a fragment of Donskoy's right hand to Donetsk, one of four Ukrainian regions Putin said he had incorporated into Russia in 2022, a move Kyiv rejected as an illegal land grab.
#prince #andrew #osborn #reuters



4 days ago
On September 3, a caller asked if UnitedHealth Group Incorporated (NYSE:UNH) has enough profitable growth that they should consider adding it to their portfolio. Mad Money host Jim Cramer replied:
Yes, the answer: it does, it does. You know, I've got to tell you, I thought that last quarter was very, very good. The stock market did not like the quarter as much as I thought it would, but the stock's making a stand here. I think that UNH is good to buy.
Cramer's bullish stance rests on the core strength of the company's financial delivery and improving execution. In its second-quarter 2026 report, UnitedHealth Group Incorporated (NYSE:UNH) posted consolidated revenues of $112 billion and operating earnings of $8 billion. Adjusted diluted earnings per share reached $6.38, outpacing Wall Street expectations by $1.48. Driven by strong performance across both the UnitedHealthcare and Optum divisions, management raised its full-year 2026 adjusted EPS guidance to a range of $19.50 to $20. Furthermore, the medical care ratio improved to 86.7% down from 89.4% a year prior, showing that medical cost trends and pricing are aligning effectively.
On the other hand, Wall Street remains cautious about lingering cost pressures across the managed care landscape. Even though the medical care ratio improved compared to last year, patients continuing to utilize medical services at a high rate keeps expenses heavy. At the same time, commercial insurance margins are taking longer to bounce back. Adding in tighter payment adjustments for government-backed plans along with heavy spending on tech infrastructure, cautious investors could have reasons to wait rather than chasing the stock higher.
Insider Monkey's data tracking over 1000 hedge funds shows accumulation by major ****** et managers. 143 hedge funds had positions in UnitedHealth Group Incorporated (NYSE:UNH) in Q2 compared to 130 in Q1. Of those funds, Fisher ****** et Management was the top shareholder with nearly 9.1 million shares. The firm increased its position in the stock by 74% in the quarter. Additionally, short interest remains low, with the short percentage of the float sitting at 1.92%, showing a general lack of aggressive bearish bets against the stock.
#unitedhealth #funds
Yes, the answer: it does, it does. You know, I've got to tell you, I thought that last quarter was very, very good. The stock market did not like the quarter as much as I thought it would, but the stock's making a stand here. I think that UNH is good to buy.
Cramer's bullish stance rests on the core strength of the company's financial delivery and improving execution. In its second-quarter 2026 report, UnitedHealth Group Incorporated (NYSE:UNH) posted consolidated revenues of $112 billion and operating earnings of $8 billion. Adjusted diluted earnings per share reached $6.38, outpacing Wall Street expectations by $1.48. Driven by strong performance across both the UnitedHealthcare and Optum divisions, management raised its full-year 2026 adjusted EPS guidance to a range of $19.50 to $20. Furthermore, the medical care ratio improved to 86.7% down from 89.4% a year prior, showing that medical cost trends and pricing are aligning effectively.
On the other hand, Wall Street remains cautious about lingering cost pressures across the managed care landscape. Even though the medical care ratio improved compared to last year, patients continuing to utilize medical services at a high rate keeps expenses heavy. At the same time, commercial insurance margins are taking longer to bounce back. Adding in tighter payment adjustments for government-backed plans along with heavy spending on tech infrastructure, cautious investors could have reasons to wait rather than chasing the stock higher.
Insider Monkey's data tracking over 1000 hedge funds shows accumulation by major ****** et managers. 143 hedge funds had positions in UnitedHealth Group Incorporated (NYSE:UNH) in Q2 compared to 130 in Q1. Of those funds, Fisher ****** et Management was the top shareholder with nearly 9.1 million shares. The firm increased its position in the stock by 74% in the quarter. Additionally, short interest remains low, with the short percentage of the float sitting at 1.92%, showing a general lack of aggressive bearish bets against the stock.
#unitedhealth #funds


4 days ago
Interested in Qualcomm Incorporated? Here are five stocks we like better.
Qualcomm's Amazon agreement gives its data center strategy a major anchor beyond smartphones.
Amazon's warrants are tied to up to $60 billion in potential purchases over a decade, making the deal meaningful but gradual.
Qualcomm's valuation still trails many AI infrastructure peers, but dilution risk and execution timing remain important factors.
Investors continue to seek disciplined strategies to participate in the evolving artificial intelligence (AI) economy without paying inflated multiples for standard graphics hardware. Capital remains focused on businesses positioned to sustain steady enterprise workload expansion while maintaining reasonable valuation metrics.
#interested #qualcomm
Qualcomm's Amazon agreement gives its data center strategy a major anchor beyond smartphones.
Amazon's warrants are tied to up to $60 billion in potential purchases over a decade, making the deal meaningful but gradual.
Qualcomm's valuation still trails many AI infrastructure peers, but dilution risk and execution timing remain important factors.
Investors continue to seek disciplined strategies to participate in the evolving artificial intelligence (AI) economy without paying inflated multiples for standard graphics hardware. Capital remains focused on businesses positioned to sustain steady enterprise workload expansion while maintaining reasonable valuation metrics.
#interested #qualcomm

10 days ago
Replenish Nutrients Holding Corp (CSE:ERTH, OTC:VVIVF, FRA:7KE) earlier this week outlined how its strategic relationship with Spanish River Carbonatite (SRC) could support a significant production scale-up, with CEO Neil Wiens saying the company has reached an operational "inflection point".
Wiens told Proactive that the relationship initially developed through Replenish Nutrients evaluating Spanish River Carbonatite as an ingredient in its products. He said the material demonstrated strong efficacy when incorporated into the company's blends, leading to discussions about securing greater and more consistent supply.
Following due diligence, SRC made a sizable strategic investment in Replenish Nutrients, while SRC CEO Tim Close has become chairman of the company.
Close described SRC's northern Ontario carbonatite resource as a naturally occurring blend containing calcium, potassium, phosphate and magnesium, together with trace and micronutrients and beneficial microbes.
He said Replenish Nutrients' production capabilities, distribution network and relationships throughout the agricultural supply chain had been important attractions for SRC. Close added that the respective products represented an "ideal fit", with benefits from combining SRC's material with Replenish Nutrients' products.
#nutrients #products #river #wiens
Wiens told Proactive that the relationship initially developed through Replenish Nutrients evaluating Spanish River Carbonatite as an ingredient in its products. He said the material demonstrated strong efficacy when incorporated into the company's blends, leading to discussions about securing greater and more consistent supply.
Following due diligence, SRC made a sizable strategic investment in Replenish Nutrients, while SRC CEO Tim Close has become chairman of the company.
Close described SRC's northern Ontario carbonatite resource as a naturally occurring blend containing calcium, potassium, phosphate and magnesium, together with trace and micronutrients and beneficial microbes.
He said Replenish Nutrients' production capabilities, distribution network and relationships throughout the agricultural supply chain had been important attractions for SRC. Close added that the respective products represented an "ideal fit", with benefits from combining SRC's material with Replenish Nutrients' products.
#nutrients #products #river #wiens


11 days ago
Diamond Hill Capital, a First Eagle Investment Management company, issued its Q2 2026 investor letter for its "Small Cap Strategy". The letter can be downloaded here. The strategy returned 24.01% in the second quarter, outperforming the Russell 2000 Index's 21.49% return. Performance was positively affected by stock selection in health care and industrials, while the Fund's underweight position in information technology was the largest relative detractor as AI-related companies drove market gains. Small-cap equities benefited from strong earnings, resilient economic conditions, and easing geopolitical concerns, with technology leading sector performance while energy declined alongside lower oil prices. Despite the market's focus on AI, the Fund's strongest contributors came from businesses outside the theme, particularly in health care, defense-oriented companies, and tangible-asset industries. Looking ahead, the Fund remains focused on resilient, underfollowed companies tied to infrastructure, defense modernization, and essential industries where disciplined capital allocation and long-term demand can support value creation. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Diamond Hill Capital Small Cap Strategy highlighted Ducommun Incorporated (NYSE:DCO) as a leading contributor. Ducommun Incorporated (NYSE:DCO) provides engineering and manufacturing services for products and applications used in the aerospace and defense, industrial, medical, and other industries. On September 02, 2026, Ducommun Incorporated (NYSE:DCO) closed at $165.60 per share. Over the last month, Ducommun Incorporated (NYSE:DCO) declined 17.80% and its shares gained 81.24% over the past 52 weeks. Ducommun Incorporated (NYSE:DCO) has a market capitalization of $2.55 billion.
Diamond Hill Capital Small Cap Strategy stated the following regarding Ducommun Incorporated (NYSE:DCO) in its Q2 2026 investor letter:
"Shares of aerospace and defense manufacturer Ducommun Incorporated (NYSE:DCO) rose as both of its primary end markets strengthened simultaneously for the first time in years. Missile revenue increased by nearly a quarter, supported by funded Department of Defense contracts calling for substantial production increases, while commercial aerospace returned to growth following a prolonged period of lower activity."
Ducommun Incorporated (NYSE:DCO) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 31 hedge fund portfolios held Ducommun Incorporated (NYSE:DCO) at the end of the second quarter which was 18 in the previous quarter. While we acknowledge the potential of Ducommun Incorporated (NYSE:DCO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free rep
In its second-quarter 2026 investor letter, Diamond Hill Capital Small Cap Strategy highlighted Ducommun Incorporated (NYSE:DCO) as a leading contributor. Ducommun Incorporated (NYSE:DCO) provides engineering and manufacturing services for products and applications used in the aerospace and defense, industrial, medical, and other industries. On September 02, 2026, Ducommun Incorporated (NYSE:DCO) closed at $165.60 per share. Over the last month, Ducommun Incorporated (NYSE:DCO) declined 17.80% and its shares gained 81.24% over the past 52 weeks. Ducommun Incorporated (NYSE:DCO) has a market capitalization of $2.55 billion.
Diamond Hill Capital Small Cap Strategy stated the following regarding Ducommun Incorporated (NYSE:DCO) in its Q2 2026 investor letter:
"Shares of aerospace and defense manufacturer Ducommun Incorporated (NYSE:DCO) rose as both of its primary end markets strengthened simultaneously for the first time in years. Missile revenue increased by nearly a quarter, supported by funded Department of Defense contracts calling for substantial production increases, while commercial aerospace returned to growth following a prolonged period of lower activity."
Ducommun Incorporated (NYSE:DCO) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 31 hedge fund portfolios held Ducommun Incorporated (NYSE:DCO) at the end of the second quarter which was 18 in the previous quarter. While we acknowledge the potential of Ducommun Incorporated (NYSE:DCO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free rep

11 days ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ****** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Mastercard Incorporated (NYSE:MA). Mastercard Incorporated (NYSE:MA) is a leading global payment technology company that provides transaction processing and other payment-related products and services. On September 02, 2026, Mastercard Incorporated (NYSE:MA) closed at $588.14 per share. Over the past month, Mastercard Incorporated (NYSE:MA) returned 2.12% while its shares lost 1.26% over the past 52 weeks. Mastercard Incorporated (NYSE:MA) has a market capitalization of $515.22 billion.
Eagle Capital Management stated the following regarding Mastercard Incorporated (NYSE:MA) in its Q2 2026 investor letter:
High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global, Mastercard Incorporated (NYSE:MA), A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ****** ets, network effects, or regulatory moats. Mastercard operates as part of a global duopoly of payment rails and standards.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. However, as earnings in the economy normalize back towards m
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Mastercard Incorporated (NYSE:MA). Mastercard Incorporated (NYSE:MA) is a leading global payment technology company that provides transaction processing and other payment-related products and services. On September 02, 2026, Mastercard Incorporated (NYSE:MA) closed at $588.14 per share. Over the past month, Mastercard Incorporated (NYSE:MA) returned 2.12% while its shares lost 1.26% over the past 52 weeks. Mastercard Incorporated (NYSE:MA) has a market capitalization of $515.22 billion.
Eagle Capital Management stated the following regarding Mastercard Incorporated (NYSE:MA) in its Q2 2026 investor letter:
High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global, Mastercard Incorporated (NYSE:MA), A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ****** ets, network effects, or regulatory moats. Mastercard operates as part of a global duopoly of payment rails and standards.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. However, as earnings in the economy normalize back towards m

11 days ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ******* umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted UnitedHealth Group Incorporated (NYSE:UNH). UnitedHealth Group Incorporated (NYSE:UNH), a diversified healthcare company, contributed 2.5% to the Fund's performance during the quarter. On September 02, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $399.66 per share. Over the past month UnitedHealth Group Incorporated (NYSE:UNH) was down 1.07%, and its shares gained 28.76% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $358.73 billion and its stock has traded within a 52-week range of $255.97 - $461.62.
Eagle Capital Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"Managed care (13% of capital): UnitedHealth Group Incorporated (NYSE:UNH), Humana, Elevance: These managed care companies have significant scale advantages in a consolidated industry that outgrows the overall economy. The industry moves with its own cycle and, over the last several years, has faced cost/price pressures in Medicare Advantage and Medicaid. Even the largest firms are earning poor margins, and some weaker firms are unprofitable. We believe conditions have bottomed out and that we are transitioning to a multi-year improvement in margins and earnings. Al-driven technology projects can both reduce costs and improve service quality. Since returning as CEO at UnitedHealth last year, Stephen Hemsley and the management team have been correcting some of the company's missteps. Recent results provide growing evidence that the turnaround is well on track. We expect EPS growth of 15-20% over the next several years, driven by moderate revenue growth and significantly e
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted UnitedHealth Group Incorporated (NYSE:UNH). UnitedHealth Group Incorporated (NYSE:UNH), a diversified healthcare company, contributed 2.5% to the Fund's performance during the quarter. On September 02, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $399.66 per share. Over the past month UnitedHealth Group Incorporated (NYSE:UNH) was down 1.07%, and its shares gained 28.76% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $358.73 billion and its stock has traded within a 52-week range of $255.97 - $461.62.
Eagle Capital Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"Managed care (13% of capital): UnitedHealth Group Incorporated (NYSE:UNH), Humana, Elevance: These managed care companies have significant scale advantages in a consolidated industry that outgrows the overall economy. The industry moves with its own cycle and, over the last several years, has faced cost/price pressures in Medicare Advantage and Medicaid. Even the largest firms are earning poor margins, and some weaker firms are unprofitable. We believe conditions have bottomed out and that we are transitioning to a multi-year improvement in margins and earnings. Al-driven technology projects can both reduce costs and improve service quality. Since returning as CEO at UnitedHealth last year, Stephen Hemsley and the management team have been correcting some of the company's missteps. Recent results provide growing evidence that the turnaround is well on track. We expect EPS growth of 15-20% over the next several years, driven by moderate revenue growth and significantly e

11 days ago
Andvari ****** ociates, an investment management firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Andvari's portfolio has performed strongly in the quarter, highlighted by Constellation Software's 19.9% revenue growth and its plans to spend on acquisitions in 2026. The company is also focusing on AI tools to enhance productivity and customer relationships. However, the AI sector is experiencing extreme hype, leading to a growing disconnect between valuations and future cash flows. Predictions suggest the AI investment phase may decline in 1-3 years, despite current high demand for AI infrastructure, which is expected to attract significant competition. Concerns about overbuilding and risky financial behaviors, like Oracle's downgraded credit rating amid a $90-$95 billion AI cloud investment, reflect potential pitfalls. Andvari has minimized exposure to this sector, aiming to protect and grow ****** ets through disciplined investments in stable industries despite recent underperformance during the AI boom. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Andvari ****** ociates highlighted Texas Instruments Incorporated (NASDAQ:TXN), a semiconductor manufacturer providing chips and solutions for electronics designers and manufacturers. On September 02, 2026, Texas Instruments Incorporated (NASDAQ:TXN) closed at $254.80 per share. Over the past month, Texas Instruments Incorporated (NASDAQ:TXN) fell 8.48%, while its shares gained 36.05% over the past 52 weeks. Texas Instruments Incorporated (NASDAQ:TXN) has a market capitalization of $232.7 billion.
Andvari ****** ociates stated the following regarding Texas Instruments Incorporated (NASDAQ:TXN) in its Q2 2026 investor letter:
"I also added Texas Instruments Incorporated (NASDAQ:TXN), which makes ****** og and power management chips. Texas Instruments and Martin Marietta might be getting a nice temporary ****** p in profits and revenues from helping build out AI infrastructure, but AI and data center-related revenues are by no means the majority of revenues for either of these two companies."
Texas Instruments Incorporated (NASDAQ:TXN) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 111 hedge fund portfolios held Texas Instruments Incorporated (NASDAQ:TXN) at the end of the second quarter, up from 71 in the previous quarter. While we acknowledge the potential of Texas Instruments Incorporated (NASDAQ:TXN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#andvari
In its second-quarter 2026 investor letter, Andvari ****** ociates highlighted Texas Instruments Incorporated (NASDAQ:TXN), a semiconductor manufacturer providing chips and solutions for electronics designers and manufacturers. On September 02, 2026, Texas Instruments Incorporated (NASDAQ:TXN) closed at $254.80 per share. Over the past month, Texas Instruments Incorporated (NASDAQ:TXN) fell 8.48%, while its shares gained 36.05% over the past 52 weeks. Texas Instruments Incorporated (NASDAQ:TXN) has a market capitalization of $232.7 billion.
Andvari ****** ociates stated the following regarding Texas Instruments Incorporated (NASDAQ:TXN) in its Q2 2026 investor letter:
"I also added Texas Instruments Incorporated (NASDAQ:TXN), which makes ****** og and power management chips. Texas Instruments and Martin Marietta might be getting a nice temporary ****** p in profits and revenues from helping build out AI infrastructure, but AI and data center-related revenues are by no means the majority of revenues for either of these two companies."
Texas Instruments Incorporated (NASDAQ:TXN) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 111 hedge fund portfolios held Texas Instruments Incorporated (NASDAQ:TXN) at the end of the second quarter, up from 71 in the previous quarter. While we acknowledge the potential of Texas Instruments Incorporated (NASDAQ:TXN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#andvari

11 days ago
Artisan Partners, an investment management company, released its second-quarter 2026 investor commentary for the "Artisan Global Opportunities Strategy". The letter can be downloaded here. Global equities rebounded sharply during the quarter, with the MSCI ACWI Index returning 15.3% as resilient economic growth, strong corporate earnings, and continued enthusiasm around artificial intelligence supported markets despite persistent inflation, higher bond yields, and geopolitical uncertainty. The portfolio reported strong absolute returns of 12.65% (net) but underperformed the benchmark, mainly because of its underweight exposure to information technology and overweight position in health care. Strong stock selection in technology and energy partially offset these headwinds. The fund continues to see attractive long-term opportunities across AI infrastructure, health care and consumer internet, while remaining disciplined on valuation as several AI-related stocks have appreciated sharply. Management remains focused on durable franchises with identifiable profit cycles and attractive long-term earnings potential. Also, check the Strategy's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Insmed Incorporated (NASDAQ:INSM). Insmed Incorporated (NASDAQ:INSM) is a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases. On September 01, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $121.51 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) returned 25.42%, and its shares lost 13.45% over the past 52 weeks. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $27.14 billion.
Artisan Global Opportunities Strategy stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Our biggest detractors in Q2 were Insmed Incorporated (NASDAQ:INSM), BAE Systems and L3Harris Technologies. Insmed is a commercial-stage biotechnology company focused on pulmonary diseases. BRINSUPRI® continued its rapid launch, with robust patient uptake and encouraging third-party data. While Q1 sales came in modestly below elevated investor expectations, reflecting concerns around discontinuation rates, continuation on therapy and typical early-year seasonality, we believe the underlying launch trajectory remains encouraging. We continue to view BRINSUPRI® as a significant long-term opportunity. Our due diligence suggests the therapy remains well tolerated and is on track to achieve blockbuster-level sales. We trimmed the position during the quarter."
#NASDAQ #global #quarter
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Insmed Incorporated (NASDAQ:INSM). Insmed Incorporated (NASDAQ:INSM) is a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases. On September 01, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $121.51 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) returned 25.42%, and its shares lost 13.45% over the past 52 weeks. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $27.14 billion.
Artisan Global Opportunities Strategy stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Our biggest detractors in Q2 were Insmed Incorporated (NASDAQ:INSM), BAE Systems and L3Harris Technologies. Insmed is a commercial-stage biotechnology company focused on pulmonary diseases. BRINSUPRI® continued its rapid launch, with robust patient uptake and encouraging third-party data. While Q1 sales came in modestly below elevated investor expectations, reflecting concerns around discontinuation rates, continuation on therapy and typical early-year seasonality, we believe the underlying launch trajectory remains encouraging. We continue to view BRINSUPRI® as a significant long-term opportunity. Our due diligence suggests the therapy remains well tolerated and is on track to achieve blockbuster-level sales. We trimmed the position during the quarter."
#NASDAQ #global #quarter


11 days ago
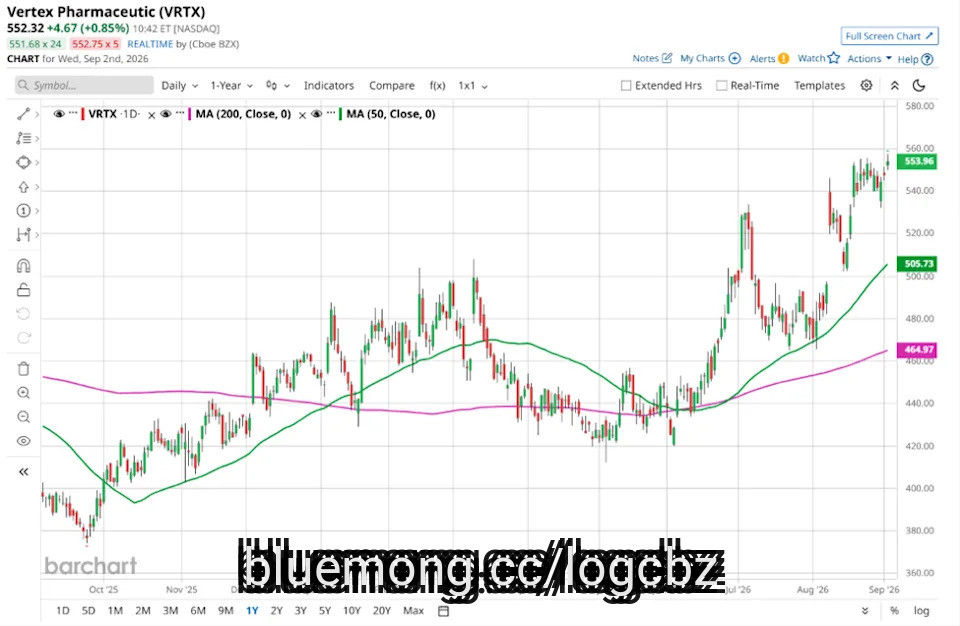
Boston, Massachusetts-based Vertex Pharmaceuticals Incorporated (VRTX) develops and commercializes therapies for treating cystic fibrosis (CF). Valued at $139 billion by market cap, the company invests in scientific innovation to create transformative medicines for people with serious diseases.
Companies worth $10 billion or more are generally described as "large-cap stocks," and VRTX perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the biotechnology industry. VRTX derives its primary competitive strength from its global monopoly in CF treatments, anchored by flagship blockbusters like Trikafta/Katori which generate robust cash flow to fuel its high-impact clinical pipeline.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why **** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#vrtx #massachusetts
Companies worth $10 billion or more are generally described as "large-cap stocks," and VRTX perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the biotechnology industry. VRTX derives its primary competitive strength from its global monopoly in CF treatments, anchored by flagship blockbusters like Trikafta/Katori which generate robust cash flow to fuel its high-impact clinical pipeline.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why **** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#vrtx #massachusetts


11 days ago
Artisan Partners, an investment management company, released its second-quarter 2026 investor commentary for the "Artisan Global Opportunities Strategy". The letter can be downloaded here. Global equities rebounded sharply during the quarter, with the MSCI ACWI Index returning 15.3% as resilient economic growth, strong corporate earnings, and continued enthusiasm around artificial intelligence supported markets despite persistent inflation, higher bond yields, and geopolitical uncertainty. The portfolio reported strong absolute returns of 12.65% (net) but underperformed the benchmark, mainly because of its underweight exposure to information technology and overweight position in health care. Strong stock selection in technology and energy partially offset these headwinds. The fund continues to see attractive long-term opportunities across AI infrastructure, health care and consumer internet, while remaining disciplined on valuation as several AI-related stocks have appreciated sharply. Management remains focused on durable franchises with identifiable profit cycles and attractive long-term earnings potential. Also, check the Strategy's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Corning Incorporated (NYSE:GLW) as a new position. Corning Incorporated (NYSE:GLW) is a technology company that operates through optical communication, display technologies, environmental technologies, specialty materials, and life sciences business segments. On September 01, 2026, Corning Incorporated (NYSE:GLW) closed at $145.56 per share. Corning Incorporated (NYSE:GLW) declined 8.08% over the past month, while its shares gained 107.73% over the past 52 weeks. Corning Incorporated (NYSE:GLW) has a market capitalization of $125.38 billion with a 52-week trading range between $66.14 - $271.78.
Artisan Global Opportunities Strategy stated the following regarding Corning Incorporated (NYSE:GLW) in its Q2 2026 investor letter:
"During the quarter, we initiated positions in Corning Incorporated (NYSE:GLW). Corning and STMicroelectronics represent earlier stage semiconductor supply chain opportunities that we believe will see growing demand as AI infrastructure spending broadens beyond today's most obvious beneficiaries. In both cases, we see a potential opportunity for higher value, higher margin products as data centers require greater optical connectivity, semiconductor content and related infrastructure. Corning is a leading global supplier of specialty glass and optical connectivity solutions. We initiated a GardenSM position because we believe Corning is well positioned to meet rising optical connectivity needs as AI infrastructure shifts toward larger clusters and scale-up architectures. While we are not early to the story, we believe the company's fiber capacity, US-based manufacturing footprint and ability to deliver higher complexity optical solutions to hyperscaler
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Corning Incorporated (NYSE:GLW) as a new position. Corning Incorporated (NYSE:GLW) is a technology company that operates through optical communication, display technologies, environmental technologies, specialty materials, and life sciences business segments. On September 01, 2026, Corning Incorporated (NYSE:GLW) closed at $145.56 per share. Corning Incorporated (NYSE:GLW) declined 8.08% over the past month, while its shares gained 107.73% over the past 52 weeks. Corning Incorporated (NYSE:GLW) has a market capitalization of $125.38 billion with a 52-week trading range between $66.14 - $271.78.
Artisan Global Opportunities Strategy stated the following regarding Corning Incorporated (NYSE:GLW) in its Q2 2026 investor letter:
"During the quarter, we initiated positions in Corning Incorporated (NYSE:GLW). Corning and STMicroelectronics represent earlier stage semiconductor supply chain opportunities that we believe will see growing demand as AI infrastructure spending broadens beyond today's most obvious beneficiaries. In both cases, we see a potential opportunity for higher value, higher margin products as data centers require greater optical connectivity, semiconductor content and related infrastructure. Corning is a leading global supplier of specialty glass and optical connectivity solutions. We initiated a GardenSM position because we believe Corning is well positioned to meet rising optical connectivity needs as AI infrastructure shifts toward larger clusters and scale-up architectures. While we are not early to the story, we believe the company's fiber capacity, US-based manufacturing footprint and ability to deliver higher complexity optical solutions to hyperscaler

11 days ago
Artisan Partners, an investment management company, released its second-quarter 2026 investor commentary for the "Artisan Global Opportunities Strategy". The letter can be downloaded here. Global equities rebounded sharply during the quarter, with the MSCI ACWI Index returning 15.3% as resilient economic growth, strong corporate earnings, and continued enthusiasm around artificial intelligence supported markets despite persistent inflation, higher bond yields, and geopolitical uncertainty. The portfolio reported strong absolute returns of 12.65% (net) but underperformed the benchmark, mainly because of its underweight exposure to information technology and overweight position in health care. Strong stock selection in technology and energy partially offset these headwinds. The fund continues to see attractive long-term opportunities across AI infrastructure, health care and consumer internet, while remaining disciplined on valuation as several AI-related stocks have appreciated sharply. Management remains focused on durable franchises with identifiable profit cycles and attractive long-term earnings potential. Also, check the Strategy's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Insmed Incorporated (NASDAQ:INSM). Insmed Incorporated (NASDAQ:INSM) is a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases. On September 01, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $121.51 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) returned 25.42%, and its shares lost 13.45% over the past 52 weeks. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $27.14 billion.
Artisan Global Opportunities Strategy stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Our biggest detractors in Q2 were Insmed Incorporated (NASDAQ:INSM), BAE Systems and L3Harris Technologies. Insmed is a commercial-stage biotechnology company focused on pulmonary diseases. BRINSUPRI® continued its rapid launch, with robust patient uptake and encouraging third-party data. While Q1 sales came in modestly below elevated investor expectations, reflecting concerns around discontinuation rates, continuation on therapy and typical early-year seasonality, we believe the underlying launch trajectory remains encouraging. We continue to view BRINSUPRI® as a significant long-term opportunity. Our due diligence suggests the therapy remains well tolerated and is on track to achieve blockbuster-level sales. We trimmed the position during the quarter."
#insm #artisan #global #quarter
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Insmed Incorporated (NASDAQ:INSM). Insmed Incorporated (NASDAQ:INSM) is a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases. On September 01, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $121.51 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) returned 25.42%, and its shares lost 13.45% over the past 52 weeks. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $27.14 billion.
Artisan Global Opportunities Strategy stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Our biggest detractors in Q2 were Insmed Incorporated (NASDAQ:INSM), BAE Systems and L3Harris Technologies. Insmed is a commercial-stage biotechnology company focused on pulmonary diseases. BRINSUPRI® continued its rapid launch, with robust patient uptake and encouraging third-party data. While Q1 sales came in modestly below elevated investor expectations, reflecting concerns around discontinuation rates, continuation on therapy and typical early-year seasonality, we believe the underlying launch trajectory remains encouraging. We continue to view BRINSUPRI® as a significant long-term opportunity. Our due diligence suggests the therapy remains well tolerated and is on track to achieve blockbuster-level sales. We trimmed the position during the quarter."
#insm #artisan #global #quarter

13 days ago
American service members will now have access to military versions of ChatGPT and Grok as the Pentagon tries to incorporate more AI into its daily workflows.
The Department of War said in a pair of announcements on Monday that the two services will be incorporated into its bespoke AI platform GenAI.mil, which launched in December and originally offered access only to a specialized military version of Google's Gemini. The department said GenAI.mil already counts 1.7 million users among the Department of War's 3 million–strong workforce, which includes both military members and civilians.
The department's Monday announcement comes after it awarded OpenAI and Elon Musk's ******* eXAI, which runs Grok, defense contracts worth up to $200 million each to provide the department with AI tools. It also awarded contracts at the time to Google and Anthropic.
The military version of ChatGPT, dubbed ChatGPT Mil, is part of OpenAI for Government, an initiative launched last summer meant to bring the company's AI products to government workers.
"ChatGPT on GenAI.mil will make unclassified work throughout the Department more efficient, freeing up time and resources so DoW personnel can focus on the mission," said Joe Larson, vice president and head of government at OpenAI, in a statement to Fortune.
#department #openai #government #members
The Department of War said in a pair of announcements on Monday that the two services will be incorporated into its bespoke AI platform GenAI.mil, which launched in December and originally offered access only to a specialized military version of Google's Gemini. The department said GenAI.mil already counts 1.7 million users among the Department of War's 3 million–strong workforce, which includes both military members and civilians.
The department's Monday announcement comes after it awarded OpenAI and Elon Musk's ******* eXAI, which runs Grok, defense contracts worth up to $200 million each to provide the department with AI tools. It also awarded contracts at the time to Google and Anthropic.
The military version of ChatGPT, dubbed ChatGPT Mil, is part of OpenAI for Government, an initiative launched last summer meant to bring the company's AI products to government workers.
"ChatGPT on GenAI.mil will make unclassified work throughout the Department more efficient, freeing up time and resources so DoW personnel can focus on the mission," said Joe Larson, vice president and head of government at OpenAI, in a statement to Fortune.
#department #openai #government #members


18 days ago
Crocs, Pokemon cards and kendamas never go out of style in Hawaii. And neither does the Warriors' four-wide offense, In video sessions with offensive newcomers, receivers coach Jared Ursua shows old footage of the Warriors' passing game. "We've been doing this since January," Ursua said of clips of former UH QBs Dan Robinson, Nick Rolovich, Timmy Chang, Colt Brennan, Bryant Moniz and Cole McDonald. "We are who we are, we do what we do, and this system has always worked." QB1 Micah Alejado has been starring in recent remakes, deciphering defenses ahead of the snap, releasing passes within 2.2 seconds, and throwing to targeted areas on the receivers' routes. "Micah's a special quarterback," said Chang, the UH head coach who calls the offensive plays. "He understands our offense, and he understands what teams are trying to do against us." Ursua has implored the receivers to read the coverages correctly "so Micah can throw at a high level based on our indicators, which is what the run-and-shoot is based off." Alejado has shown toughness, playing through injuries to his right ankle last season. He did not participate in contact drills ahead of the Hawaii Bowl, during which he completed 69.6% of his throws for 274 yards and three TDs. Last season, the Warriors scored on 46.1% of Alejado's full drives. Slotbacks Blaze Kamoku, Tama Uiliata, Audric Harris, Kainoa "Kaikai" Carvalho, ******* an Lacaden and Koa Eldredge are reliable inside receivers. Devin Alves, Tre' Griffiths and Carson Brown are tall and fast wideouts. With running back Landon Sims' graduation, Cam Barfield will get the bulk of the reps. Barfield did not fumble while averaging 9.1 touches as a running back, receiver and returner. Left tackle Boogie Henderson's emergence enabled Dean Briski to move to the right side. At 6-6 and 345 pounds, Oregon transfer Lipe Moala is mobile on pulls.
Three years ago, in his first season as UH's defensive coordinator, Dennis Thurman kept intact the 4-2-5 scheme the Warriors ran under Corey Batoon in 2019 and Jacob Yoro in 2023. In 2024, Thurman incorporated some of the attacking schemes he used when he was an ******* istant coach with the Baltimore Ravens and DC with the New York Jets and Buffalo Bills. "Once we clicked his second year, he let it all loose," mike linebacker Wynden Ho'ohuli said of Thurman. Kona Moore, who has overcome a variety of injuries, and Matagi Thompson are succeeding safeties Peter Manuma and Kilinahe Mendiola-Jensen. "Main focus is staying healthy," said Moore, who relies on stretching as part of his prehab. Ho'ohuli and Jamih Otis have switched linebacker jobs. Ho'ohuli is now the middle, often working in tandem with nickelback Elijah Palmer. As the renamed dime linebacker, Otis often has isolation ******* ignments, which enable him to use his speed in the flats and to break off for direct aim at running backs. Ho'ohuli and Otis will take turns as play-callers. The Warriors will miss Jackie Johnson III's pass rushing, but Leste
Three years ago, in his first season as UH's defensive coordinator, Dennis Thurman kept intact the 4-2-5 scheme the Warriors ran under Corey Batoon in 2019 and Jacob Yoro in 2023. In 2024, Thurman incorporated some of the attacking schemes he used when he was an ******* istant coach with the Baltimore Ravens and DC with the New York Jets and Buffalo Bills. "Once we clicked his second year, he let it all loose," mike linebacker Wynden Ho'ohuli said of Thurman. Kona Moore, who has overcome a variety of injuries, and Matagi Thompson are succeeding safeties Peter Manuma and Kilinahe Mendiola-Jensen. "Main focus is staying healthy," said Moore, who relies on stretching as part of his prehab. Ho'ohuli and Jamih Otis have switched linebacker jobs. Ho'ohuli is now the middle, often working in tandem with nickelback Elijah Palmer. As the renamed dime linebacker, Otis often has isolation ******* ignments, which enable him to use his speed in the flats and to break off for direct aim at running backs. Ho'ohuli and Otis will take turns as play-callers. The Warriors will miss Jackie Johnson III's pass rushing, but Leste


18 days ago
Aristotle Capital Management, LLC, an investment management company, released its "Value Equity Fund" Q2 2026 investor letter. A copy of the letter can be downloaded here. The Fund delivered a 4.32% total return in Q2 2026, underperforming the 13.87% gain for the Russell 1000 Value Index and the 15.20% return for the S&P 500, while its 1.99% year-to-date return also lagged the Russell 1000 Value Index's 16.26% and the S&P 500's 10.21%. The Fund attributed the performance gap largely to limited exposure to the AI infrastructure spending boom, noting that the U.S. has about 4,000 existing data centers and nearly 3,000 more planned or under construction, while AI-related demand has created bottlenecks in processors and memory. The letter highlighted the scale of the cycle, with industry cash flows in key AI hardware areas rising sharply, while the Russell 1000 Value Index's top 10 contributors gained an average 182% year to date and accounted for 9.29 percentage points of the index's 16.23% return. Looking ahead, the fund expects investors to eventually reassess the sustainability of current AI infrastructure earnings and valuations. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Aristotle Value Equity Fund highlighted stocks like QUALCOMM Incorporated (NASDAQ:QCOM). QUALCOMM Incorporated (NASDAQ:QCOM) develops wireless technologies and semiconductor solutions powering smartphones, automotive systems, and connected devices worldwide. The one-month return of QUALCOMM Incorporated (NASDAQ:QCOM) was 11.63% while its shares traded between $121.99 and $259.92 over the last 52 weeks. On August 27, 2026, QUALCOMM Incorporated (NASDAQ:QCOM) stock closed at approximately $163.72 per share, with a market capitalization of about $176.00 billion.
Aristotle Value Equity Fund stated the following regarding QUALCOMM Incorporated (NASDAQ:QCOM) in its Q2 2026 investor letter:
QUALCOMM Incorporated (NASDAQ:QCOM), a leading semiconductor and communications technology company, was the largest contributor for the quarter. Shares recovered as management indicated that the inventory adjustments and production constraints resulting from higher memory costs were progressing largely as expected and that handset revenues from Chinese customers were expected to reach a bottom. As we noted last quarter, we believed these headwinds to be cyclical rather than structural and did not alter our long-term investment thesis. The company also continued to make progress on its long-term strategy of evolving from a handset-centric company into a broader provider of connected computing technologies. Automotive revenue reached another record high, while Internet of Things (IoT) and newer businesses such as AI-enabled PCs, industrial applications, and data center computing continue to represent a growing portion of the company and remain central to its long-term diversification strategy. We believe Qualco
In its second-quarter 2026 investor letter, Aristotle Value Equity Fund highlighted stocks like QUALCOMM Incorporated (NASDAQ:QCOM). QUALCOMM Incorporated (NASDAQ:QCOM) develops wireless technologies and semiconductor solutions powering smartphones, automotive systems, and connected devices worldwide. The one-month return of QUALCOMM Incorporated (NASDAQ:QCOM) was 11.63% while its shares traded between $121.99 and $259.92 over the last 52 weeks. On August 27, 2026, QUALCOMM Incorporated (NASDAQ:QCOM) stock closed at approximately $163.72 per share, with a market capitalization of about $176.00 billion.
Aristotle Value Equity Fund stated the following regarding QUALCOMM Incorporated (NASDAQ:QCOM) in its Q2 2026 investor letter:
QUALCOMM Incorporated (NASDAQ:QCOM), a leading semiconductor and communications technology company, was the largest contributor for the quarter. Shares recovered as management indicated that the inventory adjustments and production constraints resulting from higher memory costs were progressing largely as expected and that handset revenues from Chinese customers were expected to reach a bottom. As we noted last quarter, we believed these headwinds to be cyclical rather than structural and did not alter our long-term investment thesis. The company also continued to make progress on its long-term strategy of evolving from a handset-centric company into a broader provider of connected computing technologies. Automotive revenue reached another record high, while Internet of Things (IoT) and newer businesses such as AI-enabled PCs, industrial applications, and data center computing continue to represent a growing portion of the company and remain central to its long-term diversification strategy. We believe Qualco


18 days ago
UnitedHealth Group Incorporated (NYSE:UNH) recently announced a major expansion of its child and family behavioral coaching program, extending access to 13 million commercial members. First launched in 2023, the program targets low-severity needs like mild anxiety, ADHD, and sleep issues through virtual sessions and 24/7 support. The move adds 5 million individuals at no cost to employers, reflecting a broader effort to catch mental health concerns early before they escalate into high-cost medical claims.
This expansion highlights an essential question: Is UnitedHealth's shift toward early clinical intervention and margin management enough to offset persistent cost inflation and Medicare Advantage headwinds?
UnitedHealth Group Incorporated (NYSE:UNH) delivered a strong Q2 2026 performance, beating expectations on both revenue and earnings as cost refinement and operational discipline supported profitability. Consolidated revenue reached $112.03 billion, exceeding the $110.85 billion ******* yst consensus, while adjusted EPS surged to $6.38, comfortably above the $4.90 estimate and up from $4.08 in the prior-year period. Net income totaled $5.48 billion, or $6.04 per share.
The company's medical benefit ratio (MCR) also improved significantly to 86.7% from 89.4% in Q2 2025, beating the 88.5% Wall Street estimate and indicating stronger premium capture relative to medical costs. Management also raised its full-year 2026 adjusted EPS guidance to $19.50–$20.00 from more than $18.25 while maintaining its revenue target above $439 billion.
Bulls highlight UnitedHealth's powerful multi-segment scale across insurance and Optum services. The deployment of $1.5 billion into artificial intelligence is already streamlining prior authorizations and mitigating fraud, waste, and abuse. Furthermore, Optum's reach into care delivery and pharmacy services diversifies revenue beyond traditional underwriting. Robust cash generation continues to support shareholder return, reinforced by expanded full-year profit targets.
#billion #cost #medical #NYSE
This expansion highlights an essential question: Is UnitedHealth's shift toward early clinical intervention and margin management enough to offset persistent cost inflation and Medicare Advantage headwinds?
UnitedHealth Group Incorporated (NYSE:UNH) delivered a strong Q2 2026 performance, beating expectations on both revenue and earnings as cost refinement and operational discipline supported profitability. Consolidated revenue reached $112.03 billion, exceeding the $110.85 billion ******* yst consensus, while adjusted EPS surged to $6.38, comfortably above the $4.90 estimate and up from $4.08 in the prior-year period. Net income totaled $5.48 billion, or $6.04 per share.
The company's medical benefit ratio (MCR) also improved significantly to 86.7% from 89.4% in Q2 2025, beating the 88.5% Wall Street estimate and indicating stronger premium capture relative to medical costs. Management also raised its full-year 2026 adjusted EPS guidance to $19.50–$20.00 from more than $18.25 while maintaining its revenue target above $439 billion.
Bulls highlight UnitedHealth's powerful multi-segment scale across insurance and Optum services. The deployment of $1.5 billion into artificial intelligence is already streamlining prior authorizations and mitigating fraud, waste, and abuse. Furthermore, Optum's reach into care delivery and pharmacy services diversifies revenue beyond traditional underwriting. Robust cash generation continues to support shareholder return, reinforced by expanded full-year profit targets.
#billion #cost #medical #NYSE


18 days ago
On August 10, 2026, Teledyne Technologies Incorporated (NYSE:TDY) agreed to acquire Varex Imaging for $18.90 a share in an all-cash deal valued at about $1.1 billion. It sent Varex Imaging Corporation (NASDAQ:VREX) shares up nearly 50% before the opening bell.
Teledyne is paying a large premium for a smaller X-ray components maker just as Varex posted a genuine earnings beat of its own. Is Teledyne buying real, complementary technology at a fair long-term price, or paying a steep premium right as Varex's turnaround was already starting to work?
CEO Robert Mehrabian said the companies serve similar customers with "uniquely complementary" products and minimal overlap. He noted Teledyne Technologies Incorporated (NYSE:TDY) doesn't make X-ray detectors suited for high-radiation environments like oncology the way Varex does. Both boards unanimously approved the deal, which is expected to close in early 2027.
Nearly a 50% one-day jump in Varex's stock shows the market sees this as a rich price for Teledyne to pay. Integrating Varex's X-ray business, which serves medical, security, and industrial markets, adds real complexity to Teledyne Technologies Incorporated (NYSE:TDY)'s existing operations.
CEO Sunny Sanyal said the deal marks "an exciting new chapter," giving Varex Imaging Corporation (NASDAQ:VREX) access to Teledyne's resources to accelerate use of its imaging technology. Varex also posted third-quarter adjusted profit of 31 cents a share, 10 cents ahead of **** yst estimates, after recovering tariff-related costs and generating $21 million in operating cash flow. It shows the business was already improving before the deal was announced.
#NASDAQ
Teledyne is paying a large premium for a smaller X-ray components maker just as Varex posted a genuine earnings beat of its own. Is Teledyne buying real, complementary technology at a fair long-term price, or paying a steep premium right as Varex's turnaround was already starting to work?
CEO Robert Mehrabian said the companies serve similar customers with "uniquely complementary" products and minimal overlap. He noted Teledyne Technologies Incorporated (NYSE:TDY) doesn't make X-ray detectors suited for high-radiation environments like oncology the way Varex does. Both boards unanimously approved the deal, which is expected to close in early 2027.
Nearly a 50% one-day jump in Varex's stock shows the market sees this as a rich price for Teledyne to pay. Integrating Varex's X-ray business, which serves medical, security, and industrial markets, adds real complexity to Teledyne Technologies Incorporated (NYSE:TDY)'s existing operations.
CEO Sunny Sanyal said the deal marks "an exciting new chapter," giving Varex Imaging Corporation (NASDAQ:VREX) access to Teledyne's resources to accelerate use of its imaging technology. Varex also posted third-quarter adjusted profit of 31 cents a share, 10 cents ahead of **** yst estimates, after recovering tariff-related costs and generating $21 million in operating cash flow. It shows the business was already improving before the deal was announced.
#NASDAQ


19 days ago
The London Company, an investment management company, released its second-quarter 2026 investor letter for its "Small-Mid Cap Strategy." The letter can be downloaded here. U.S. equities rebounded sharply in Q2, with the Russell 3000 gaining 15.4%, supported by AI infrastructure spending, strong earnings, and easing Middle East tensions. Technology led the rally as semiconductors recovered, while Energy and defensive sectors lagged. The portfolio returned 12.1% gross and 11.8% net compared with a 20.3% gain in the Russell 2500 Index. Stock selection weighed on relative performance, as high-beta and high-volatility stocks dominated returns while Quality remained weak, although results improved in June as market participation broadened. Looking ahead, resilient earnings and AI productivity support a constructive outlook, but negative hyperscaler cash flow, sticky inflation, geopolitical risks, index concentration, and elevated valuations warrant caution. The strategy continues to emphasize quality, downside protection, and active management. Additionally, reviewing the Fund's top five holdings could also highlight its best ideas for 2026.
In its second-quarter 2026 investor letter, London Company SMID Cap Strategy highlighted Churchill Downs Incorporated (NASDAQ:CHDN). Churchill Downs Incorporated (NASDAQ:CHDN) operates live and historical racing entertainment venues, online wagering businesses, and regional casino gaming properties in the United States. On August 26, 2026, Churchill Downs Incorporated (NASDAQ:CHDN) closed at $87.57 per share. Over the past month, Credit Acceptance Corporation (NASDAQ:CACC) returned 4.40%, while its shares have declined 16.08% in the last 52 weeks. Credit Acceptance Corporation (NASDAQ:CACC) has a market capitalization of $6.10 billion.
London Company SMID Cap Strategy stated the following regarding Churchill Downs Incorporated (NASDAQ:CHDN) in its Q2 2026 investor letter:
"Churchill Downs Incorporated (NASDAQ:CHDN) declined despite solid operating results as Derby Week growth fell slightly short of elevated investor expectations. The business continues to execute well, supported by strong Historical Racing Machine growth, improving leverage, and healthy cash flow generation. We believe the recent weakness is disconnected from the underlying fundamentals and remain confident in the company's ability to compound earnings through disciplined capital allocation, pricing power, and continued investment in its differentiated gaming and racing **** ets."
#strategy
In its second-quarter 2026 investor letter, London Company SMID Cap Strategy highlighted Churchill Downs Incorporated (NASDAQ:CHDN). Churchill Downs Incorporated (NASDAQ:CHDN) operates live and historical racing entertainment venues, online wagering businesses, and regional casino gaming properties in the United States. On August 26, 2026, Churchill Downs Incorporated (NASDAQ:CHDN) closed at $87.57 per share. Over the past month, Credit Acceptance Corporation (NASDAQ:CACC) returned 4.40%, while its shares have declined 16.08% in the last 52 weeks. Credit Acceptance Corporation (NASDAQ:CACC) has a market capitalization of $6.10 billion.
London Company SMID Cap Strategy stated the following regarding Churchill Downs Incorporated (NASDAQ:CHDN) in its Q2 2026 investor letter:
"Churchill Downs Incorporated (NASDAQ:CHDN) declined despite solid operating results as Derby Week growth fell slightly short of elevated investor expectations. The business continues to execute well, supported by strong Historical Racing Machine growth, improving leverage, and healthy cash flow generation. We believe the recent weakness is disconnected from the underlying fundamentals and remain confident in the company's ability to compound earnings through disciplined capital allocation, pricing power, and continued investment in its differentiated gaming and racing **** ets."
#strategy


19 days ago
With a market cap of $26.9 billion, Quest Diagnostics Incorporated (DGX) is a leading provider of diagnostic testing services in the United States and internationally. The company delivers a wide range of routine and advanced diagnostic information services through its brands and network of laboratories, serving healthcare providers, insurers, employers, and government institutions.
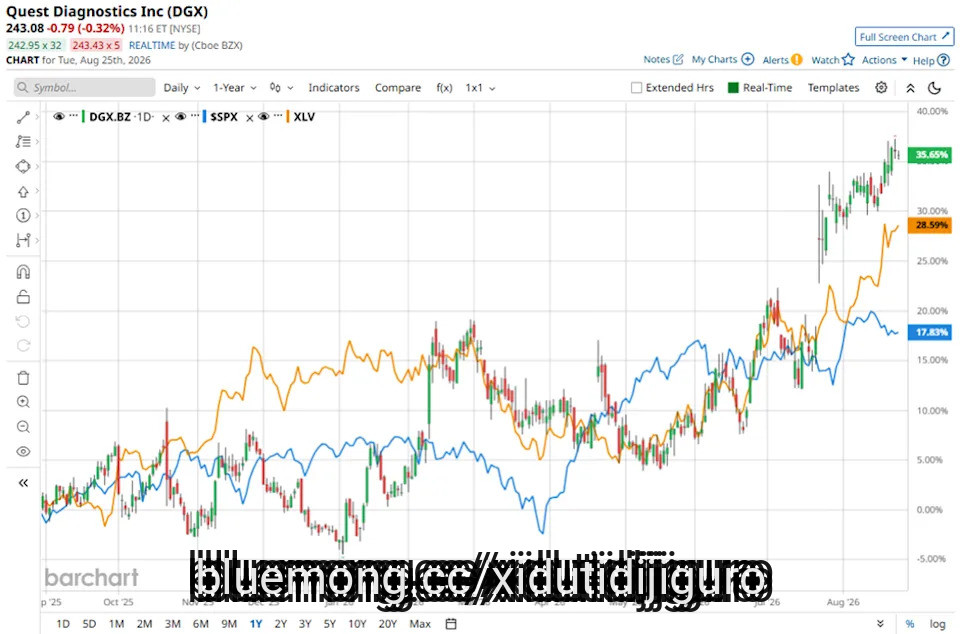
Shares of the Secaucus, New Jersey-based company have outperformed the broader market over the past 52 weeks. DGX stock has returned 36.3% over this time frame, while the broader S&P 500 Index ($SPX) has gained 19.1%. Moreover, the stock has soared 40.4% on a YTD basis, compared to SPX's 12% increase.
IonQ vs. Rigetti: The Better Quantum Computing Stock for Long-Term Investors
QQQ is Still in a Negative Gamma Regime. Here's How a 'Put Wall' and Fibonacci Support Could Come Into Play.
IBM Just Hit a New Quantum Computing Milestone. How to Play IBM Stock Now.
#quantum #computing #market #quest
Shares of the Secaucus, New Jersey-based company have outperformed the broader market over the past 52 weeks. DGX stock has returned 36.3% over this time frame, while the broader S&P 500 Index ($SPX) has gained 19.1%. Moreover, the stock has soared 40.4% on a YTD basis, compared to SPX's 12% increase.
IonQ vs. Rigetti: The Better Quantum Computing Stock for Long-Term Investors
QQQ is Still in a Negative Gamma Regime. Here's How a 'Put Wall' and Fibonacci Support Could Come Into Play.
IBM Just Hit a New Quantum Computing Milestone. How to Play IBM Stock Now.
#quantum #computing #market #quest

19 days ago
Lowe's Companies, Inc. (NYSE:LOW) delivered an earnings beat alongside weak organic growth and a reduced outlook. Second-quarter total sales increased approximately 8.3% to $25.96 billion, supported by acquisitions, but organic comparable sales rose just 0.2%, below the 0.8% expected. Diluted earnings were $4.27 per share. Company-defined adjusted diluted earnings, a non-GAAP measure, reached $4.40 per share and exceeded the $4.22 FactSet consensus estimate. Results also included a $0.11-per-share benefit from tariff refunds. Management reduced its full-year sales forecast to $92 billion and now expects comparable sales to be approximately flat. Still, the shares reversed a premarket decline and closed 2.0% higher at $220 on August 19. For Lowe's Companies, Inc. (NYSE:LOW), the question is whether contractor demand can cushion the combined pressure from weak DIY spending and subdued housing activity.
The operating split was clear. Pro, online, and home services growth helped Lowe's Companies, Inc. (NYSE:LOW) produce a fifth consecutive quarter of positive comparable sales. Online sales increased nearly 16%, while contractors and repair-and-maintenance projects supported demand. Acquisitions expanded the reported revenue base but are excluded from the comparable-sales calculation, making the 0.2% organic increase the better measure of underlying momentum.
The weaker side extends beyond the consumer. Lowe's Companies, Inc. (NYSE:LOW) said persistent pressure on discretionary DIY spending partly offset its stronger categories. The revised outlook also incorporated softer housing trends affecting Foundation Building Materials and Artisan Design Group, particularly their residential-construction exposure. Consumers continue prioritizing necessary repairs while postponing larger projects, and weak housing turnover is also limiting construction and renovation activity.
Lowe's Companies, Inc. (NYSE:LOW) is getting support from customers whose spending is less discretionary than a kitchen remodel or major outdoor project. Pro demand, home services, and online growth provide several ways to capture repair, maintenance, and contractor spending while DIY customers remain cautious. The adjusted earnings beat shows that profitability held up better than organic sales, even after accounting for the tariff-refund benefit. If lower mortgage rates eventually revive housing turnover, these businesses could provide a stronger base for renewed DIY and construction demand.
#Companies #NYSE #housing #online
The operating split was clear. Pro, online, and home services growth helped Lowe's Companies, Inc. (NYSE:LOW) produce a fifth consecutive quarter of positive comparable sales. Online sales increased nearly 16%, while contractors and repair-and-maintenance projects supported demand. Acquisitions expanded the reported revenue base but are excluded from the comparable-sales calculation, making the 0.2% organic increase the better measure of underlying momentum.
The weaker side extends beyond the consumer. Lowe's Companies, Inc. (NYSE:LOW) said persistent pressure on discretionary DIY spending partly offset its stronger categories. The revised outlook also incorporated softer housing trends affecting Foundation Building Materials and Artisan Design Group, particularly their residential-construction exposure. Consumers continue prioritizing necessary repairs while postponing larger projects, and weak housing turnover is also limiting construction and renovation activity.
Lowe's Companies, Inc. (NYSE:LOW) is getting support from customers whose spending is less discretionary than a kitchen remodel or major outdoor project. Pro demand, home services, and online growth provide several ways to capture repair, maintenance, and contractor spending while DIY customers remain cautious. The adjusted earnings beat shows that profitability held up better than organic sales, even after accounting for the tariff-refund benefit. If lower mortgage rates eventually revive housing turnover, these businesses could provide a stronger base for renewed DIY and construction demand.
#Companies #NYSE #housing #online
20 days ago
Dolly Parton's death at 80 years old this week has sparked numerous tributes and sweet reflections on the Queen of Country Music's legacy. It's also shining a light on a symbol that played a significant role in Parton's life: the ******* erfly.
If you Google Parton's name on Wednesday, you'll see a flurry of ******* erflies across the screen, along with the words "We'll Always Love You." The 9 to 5 actor, who died after a "brief battle with cancer," has long incorporated ******* erflies into her work, making them a central theme of her 1974 track "Love is Like a ******* erfly" as well as using them in her clothing, stage shows and even in the logo for her Pigeon Forge, Tenn., amusement park, Dollywood, where the W is a pair of ******* erfly wings. She's also previously shared that she has pastel ******* erfly tattoos, which, like her other hidden tattoos, she got to cover scars.
In an interview with W Magazine in 2021, Parton explained why ******* erflies, which she "loved" all her life, were her favorite symbol.
"They didn't sting. They didn't bite, and they were so beautiful," she said. Parton explained that while growing up in Tennessee's Great Smoky Mountains, she would get "lost in the woods," and "wander off" chasing after the insects from "one bush to another."
A gleaming pink ******* erfly greets guests outside of "Songteller," part of The Dolly Parton Experience, an all-new attraction at Dollywood theme park.
#butterflies
If you Google Parton's name on Wednesday, you'll see a flurry of ******* erflies across the screen, along with the words "We'll Always Love You." The 9 to 5 actor, who died after a "brief battle with cancer," has long incorporated ******* erflies into her work, making them a central theme of her 1974 track "Love is Like a ******* erfly" as well as using them in her clothing, stage shows and even in the logo for her Pigeon Forge, Tenn., amusement park, Dollywood, where the W is a pair of ******* erfly wings. She's also previously shared that she has pastel ******* erfly tattoos, which, like her other hidden tattoos, she got to cover scars.
In an interview with W Magazine in 2021, Parton explained why ******* erflies, which she "loved" all her life, were her favorite symbol.
"They didn't sting. They didn't bite, and they were so beautiful," she said. Parton explained that while growing up in Tennessee's Great Smoky Mountains, she would get "lost in the woods," and "wander off" chasing after the insects from "one bush to another."
A gleaming pink ******* erfly greets guests outside of "Songteller," part of The Dolly Parton Experience, an all-new attraction at Dollywood theme park.
#butterflies
20 days ago
New York Yankees ******* istant director of baseball operations Mike Pinsky has been revealed as a castaway for the 51st season of "Survivor" airing this fall.
Pinsky's bio for the show says he is a baseball executive living in New York City, New York. He also answered why he wants to be on the show.
"When I was 8, I used to play Survivor with my friends in our New York City apartments. When I was 18, my college friends and I would drop everything for our sacred Wednesday night viewings. When I was 28, my marriage proposal to my wife Becky incorporated a Probst catchphrase.
"Getting to actually live this dream for real is a one-of-one life experience, and the thrill of this type of adventure sets my heart on fire!"
Pinsky is joining the show for what is expected to be an interesting season. Host Jeff Probst ended Season 50, saying that this coming season was considered the "Open Era." He explained that this meant that "anything that's ever happened on 'Survivor' can happen again — at any time, in any order, without warning."
#york #season #pinsky #friends
Pinsky's bio for the show says he is a baseball executive living in New York City, New York. He also answered why he wants to be on the show.
"When I was 8, I used to play Survivor with my friends in our New York City apartments. When I was 18, my college friends and I would drop everything for our sacred Wednesday night viewings. When I was 28, my marriage proposal to my wife Becky incorporated a Probst catchphrase.
"Getting to actually live this dream for real is a one-of-one life experience, and the thrill of this type of adventure sets my heart on fire!"
Pinsky is joining the show for what is expected to be an interesting season. Host Jeff Probst ended Season 50, saying that this coming season was considered the "Open Era." He explained that this meant that "anything that's ever happened on 'Survivor' can happen again — at any time, in any order, without warning."
#york #season #pinsky #friends


21 days ago
Lowe's Companies, Inc. (NYSE:LOW) delivered an earnings beat alongside weak organic growth and a reduced outlook. Second-quarter total sales increased approximately 8.3% to $25.96 billion, supported by acquisitions, but organic comparable sales rose just 0.2%, below the 0.8% expected. Diluted earnings were $4.27 per share. Company-defined adjusted diluted earnings, a non-GAAP measure, reached $4.40 per share and exceeded the $4.22 FactSet consensus estimate. Results also included a $0.11-per-share benefit from tariff refunds. Management reduced its full-year sales forecast to $92 billion and now expects comparable sales to be approximately flat. Still, the shares reversed a premarket decline and closed 2.0% higher at $220 on August 19. For Lowe's Companies, Inc. (NYSE:LOW), the question is whether contractor demand can cushion the combined pressure from weak DIY spending and subdued housing activity.
The operating split was clear. Pro, online, and home services growth helped Lowe's Companies, Inc. (NYSE:LOW) produce a fifth consecutive quarter of positive comparable sales. Online sales increased nearly 16%, while contractors and repair-and-maintenance projects supported demand. Acquisitions expanded the reported revenue base but are excluded from the comparable-sales calculation, making the 0.2% organic increase the better measure of underlying momentum.
The weaker side extends beyond the consumer. Lowe's Companies, Inc. (NYSE:LOW) said persistent pressure on discretionary DIY spending partly offset its stronger categories. The revised outlook also incorporated softer housing trends affecting Foundation Building Materials and Artisan Design Group, particularly their residential-construction exposure. Consumers continue prioritizing necessary repairs while postponing larger projects, and weak housing turnover is also limiting construction and renovation activity.
Lowe's Companies, Inc. (NYSE:LOW) is getting support from customers whose spending is less discretionary than a kitchen remodel or major outdoor project. Pro demand, home services, and online growth provide several ways to capture repair, maintenance, and contractor spending while DIY customers remain cautious. The adjusted earnings beat shows that profitability held up better than organic sales, even after accounting for the tariff-refund benefit. If lower mortgage rates eventually revive housing turnover, these businesses could provide a stronger base for renewed DIY and construction demand.
#sales #comparable
The operating split was clear. Pro, online, and home services growth helped Lowe's Companies, Inc. (NYSE:LOW) produce a fifth consecutive quarter of positive comparable sales. Online sales increased nearly 16%, while contractors and repair-and-maintenance projects supported demand. Acquisitions expanded the reported revenue base but are excluded from the comparable-sales calculation, making the 0.2% organic increase the better measure of underlying momentum.
The weaker side extends beyond the consumer. Lowe's Companies, Inc. (NYSE:LOW) said persistent pressure on discretionary DIY spending partly offset its stronger categories. The revised outlook also incorporated softer housing trends affecting Foundation Building Materials and Artisan Design Group, particularly their residential-construction exposure. Consumers continue prioritizing necessary repairs while postponing larger projects, and weak housing turnover is also limiting construction and renovation activity.
Lowe's Companies, Inc. (NYSE:LOW) is getting support from customers whose spending is less discretionary than a kitchen remodel or major outdoor project. Pro demand, home services, and online growth provide several ways to capture repair, maintenance, and contractor spending while DIY customers remain cautious. The adjusted earnings beat shows that profitability held up better than organic sales, even after accounting for the tariff-refund benefit. If lower mortgage rates eventually revive housing turnover, these businesses could provide a stronger base for renewed DIY and construction demand.
#sales #comparable


25 days ago
Headquartered in Boston, Massachusetts, Vertex Pharmaceuticals Incorporated (VRTX) is a biotechnology company that develops innovative medicines for serious diseases, including cystic fibrosis (CF), sickle cell disease, beta thalassemia, and acute pain.
Moreover, the company is building beyond its approved treatments with potential therapies targeting genetic and other complex conditions, including kidney, metabolic, and neuromuscular diseases.
Here Is How to Play Tesla Stock After Its Robotaxi Breakthrough
Micron Stock Pullback: High Growth, Low Multiple Support Upside
Strategy Just Sold $334 Million in Shares to Build Cash and Buy Back Preferred Stock. This Hits MSTR Stock Holders With Dilution.
#including #headquartered
Moreover, the company is building beyond its approved treatments with potential therapies targeting genetic and other complex conditions, including kidney, metabolic, and neuromuscular diseases.
Here Is How to Play Tesla Stock After Its Robotaxi Breakthrough
Micron Stock Pullback: High Growth, Low Multiple Support Upside
Strategy Just Sold $334 Million in Shares to Build Cash and Buy Back Preferred Stock. This Hits MSTR Stock Holders With Dilution.
#including #headquartered

25 days ago
Image source: The Motley Fool.
Wednesday, Aug. 12, 2026 at 4:30 p.m. ET
President and Chief Executive Officer - David A. Pace
Chief Financial Officer - Mark E. Graff
Operator: Good afternoon. Welcome to the Red Robin Gourmet Burgers Incorporated Second Quarter 2026 Earnings Call. This conference call is being recorded. During management's presentation and in response to your questions, they will be making forward-looking statements about the company's business. Outlook and expectations. These forward-looking statements and all other statements that are not historical facts reflect management's beliefs and predictions as of today. And therefore, are subject to risks and uncertainties as described in the company's SEC filings. Management will also discuss non-GAAP financial measures as part of today's conference call. These non-GAAP measures are not prepared in accordance with generally accepted accounting principles, but are intended to illustrate alternative measures of the company's operating performance that may be useful.
#statements #financial #forward
Wednesday, Aug. 12, 2026 at 4:30 p.m. ET
President and Chief Executive Officer - David A. Pace
Chief Financial Officer - Mark E. Graff
Operator: Good afternoon. Welcome to the Red Robin Gourmet Burgers Incorporated Second Quarter 2026 Earnings Call. This conference call is being recorded. During management's presentation and in response to your questions, they will be making forward-looking statements about the company's business. Outlook and expectations. These forward-looking statements and all other statements that are not historical facts reflect management's beliefs and predictions as of today. And therefore, are subject to risks and uncertainties as described in the company's SEC filings. Management will also discuss non-GAAP financial measures as part of today's conference call. These non-GAAP measures are not prepared in accordance with generally accepted accounting principles, but are intended to illustrate alternative measures of the company's operating performance that may be useful.
#statements #financial #forward
26 days ago
A majority of payroll specialists across the UK and Ireland have incorporated AI into their regular routines, with considerable interest in further adoption.
The findings are part of the Payroll Professionals Survey 2026 by BrightPay, a unit of accounting, payroll and human resources solutions provider Bright.
The research is based on data collected from 296 industry practitioners in the UK and Ireland.
It found that 56% of them utilise AI solutions on at least an occasional basis. An additional 24% expressed a desire to begin adopting the technology.
However, 18% of participants stated they had no intention of adopting AI, citing scepticism regarding current platforms.
#ireland
The findings are part of the Payroll Professionals Survey 2026 by BrightPay, a unit of accounting, payroll and human resources solutions provider Bright.
The research is based on data collected from 296 industry practitioners in the UK and Ireland.
It found that 56% of them utilise AI solutions on at least an occasional basis. An additional 24% expressed a desire to begin adopting the technology.
However, 18% of participants stated they had no intention of adopting AI, citing scepticism regarding current platforms.
#ireland




