

8 days ago
Joe Mazzulla declares Payton Pritchard will be key to Jayson Tatum-led Celtics' success originally appeared on The Sporting News. Add The Sporting News as a Preferred Source by clicking here.
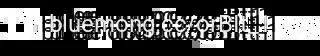
When you lose a key player in the offseason, the question remains: who fills that production hole? The Boston Celtics do not seem to worry about this conundrum at all. With Jaylen Brown gone, they have filled all the gaps by committee. Hugo Gonzalez and Baylor Scheierman get to play both ends with hustle. Paul George still has that fringe NBA All-Star quality and can shoot the lights out. However, Coach Joe Mazzulla is looking at a key player. It's none other than Payton Pritchard. The Celtics head coach has all the belief in their guard and even noted specific traits that will make him helpful to the squad led by Jayson Tatum.
For a long time, a few monoliths have described Payton Pritchard. He's been seen as the Celtics' offensive spark plug, or the guy you give the ball to in the clutch. Now, he will be up for bigger roles in Coach Joe Mazzulla's system due to the Jaylen Brown trade.
There are obviously a lot of doubts about Pritchard. Much of it stems from the fact that he's an undersized guard and the running belief that he could be a defensive liability. Coach Mazzulla does not think that way at all. In fact, the Celtics head honcho outlined what made their veteran guard special. Those same traits could also make a big difference on a team centered around Jayson Tatum, according to Jay King of The Athletic.
"He just plays with a chip on his shoulder, but doesn't have an ego. And I think that's a balance that's difficult for people to be able to have. Like, if you tell him he's starting, if you tell him he's coming off the bench, if you tell him he's playing 20 (minutes), if you tell him he's playing 30, the chip on his shoulder never changes. He doesn't need the affirmation to be an elite competitor. And so I think a coach that gives you the freedom to just do what makes the most sense at that particular time," the Celtics head coach declared.
#payton #tatum #guard

8 days ago
Browns' Jared Verse calls impressive rookie 'hooper' after beating Ravens appeared first on ClutchPoints. Add ClutchPoints as a Preferred Source by clicking here.
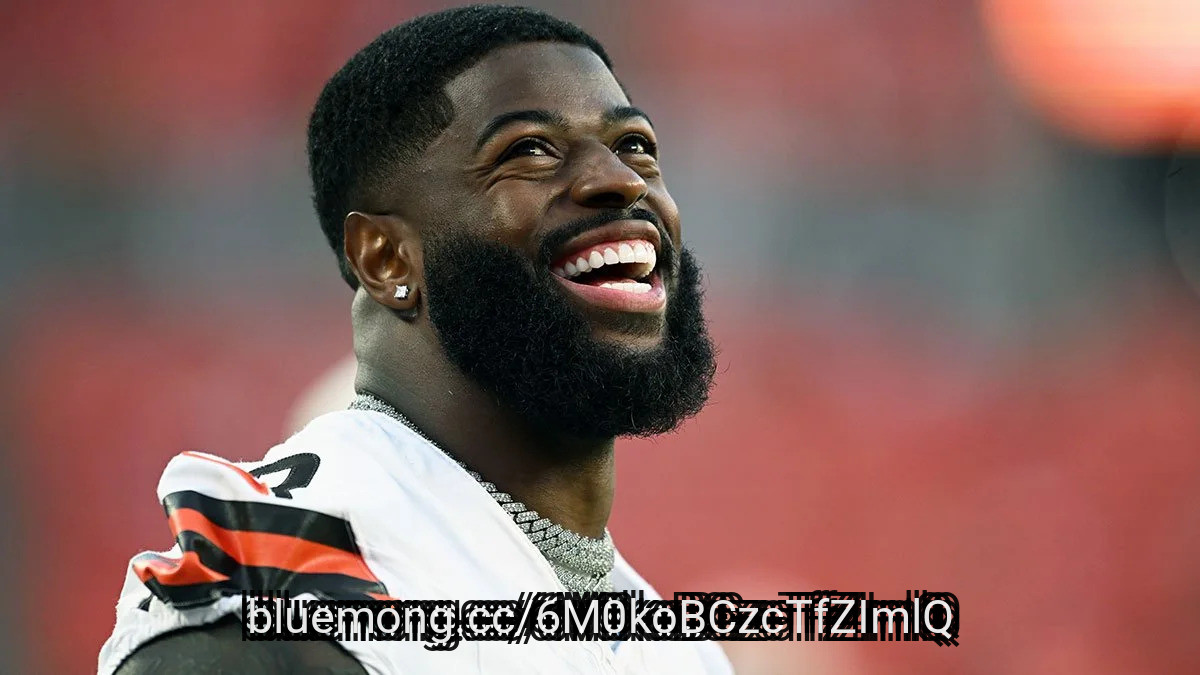
Cleveland Browns defensive end Jared Verse had nothing but praise for linebacker Carson Schwesinger following Sunday's dramatic 13-10 victory over the Baltimore Ravens. The Browns had been monitoring Schwesinger's injury concerns entering the matchup.
Schwesinger delivered another impressive performance, recording a game-high 13 tackles and forcing a crucial fumble despite being playing through an ankle injury.
Speaking after the game, Verse highlighted his teammate's toughness and reliability. "He has an old-school linebacker mindset," Verse said. "He's a hooper. You can count on him for anything."
Watch sports LIVE with fuboTV (free trial)
#Browns #jared #Ravens #hooper

20 days ago
Procter & Gamble has raised its dividend for 70 straight years while Johnson & Johnson covers its roughly $12.6 billion dividend run rate 1.56 times with free cash flow.
Coca-Cola posted its strongest Trademark volume growth in 17 years, and ADP's operating cash flow covers its dividend more than twice over while still funding buybacks.
Lowe's carries the lowest payout ratio in the group at 41% and trades at just 15 times earnings after falling 24% year to date.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Yield is relatively easy to find. A dividend that keeps arriving through recessions, patent cliffs and housing slumps is much harder to find, and that kind of reliability is the hook for this group. Every name below covers its payout with real cash flow, has a long record of raises and keeps its payout ratio at a level that leaves room for mistakes. Procter & Gamble (NYSE:PG) sets the standard: management says its latest increase marks the 70th consecutive year of dividend increases and 136th consecutive year of dividend payments, putting it firmly in the Dividend Kings club (we ranked ten of them by valuation in a free report here). The other four pair long dividend records with cash flow that covers the payout.
#cash #year #procter #gamble
1 month ago
Former President Obama on Friday slammed President Trump over his handling of how to approach artificial intelligence amid “doomsday” warnings coming from some in the tech industry about the technology’s potential existential threat to humanity.
Obama said during an interview at Colgate University in New York that the federal government must regulate AI, before referring to comments made by one Trump adviser.
“I heard one of Donald Trump’s main advisers on this make the argument that, ‘The market will take care of AI,'” the former president said. “‘These companies will solve the safety issues because they have every incentive to do so — if it turns out to be dangerous, people will just sue them, and they’re worried about financial liability.'”
“That’s not how we treat airlines,” Obama added. “Or drug companies, or food companies.”
Obama continued to say that AI could become a threat at a human level if it falls into the clutches of “bad humans” and if self-improving AI models realize they no longer need humans. He referred to Trump again in that his successor has said regulations on AI are “for losers.”
#obama #president #university


1 month ago
Elon Musk has never shied away from ambitious timelines, and his most recent one connects two companies directly together. In a post on X dated September 13, Musk stated that he is "highly confident" that **** e Exploration Technologies Corp. (NASDAQ:SPCX) will transport NVIDIA Corporation (NASDAQ:NVDA) Vera Rubin NVL72 AI computers into orbit next year, repeating a plan that has already moved both companies' stock this year.
The comment strengthens **** eX's Starmind concept, which aims to establish AI data centers in orbit rather than on the ground. The first satellite, named Starmind AI1, will carry a **** e-optimized version of NVIDIA's Vera Rubin NVL72 rack-scale system. The standard terrestrial NVL72 combines 72 Rubin GPUs and 36 Vera CPUs, although **** eX and NVIDIA have not disclosed the final configuration of the orbital version. **** e Exploration Technologies Corp. (NASDAQ:SPCX) plans to launch the satellite in the fourth quarter of 2027 and reach substantial scale by 2028. Musk's plan isn't new; during **** eX's first earnings conference as a public company in August, he stated that the company would build exclusively on NVIDIA hardware in the future, calling the Vera Rubin architecture the best available AI computer design.
Musk's central point is that **** e is, in the long run, the most cost-effective area to develop AI computing. He cites solar power availability in orbit as a crucial advantage, and estimates that within two to three years, **** e might become the lowest-cost place for AI computing in general, describing the orbital architecture as simpler, less expensive, denser, and lighter than a standard data-center rack. Not everyone believes the physics and economics will align on Musk's timeframe. Microsoft President Brad Smith has publicly questioned the broader concept, telling reporters that he would be surprised if companies actually transferred computation from land to low-Earth orbit.
For NVIDIA Corporation (NASDAQ:NVDA), the read-through is simple: **** e-based computing would represent a new, if early-stage and speculative, source of demand for its Vera Rubin platform, on top of the company's strong position in terrestrial AI infrastructure. According to some **** yst models, **** eX accounts for approximately 5% of NVIDIA's revenue.
SpaceX's reasoning is more convoluted. The plan is entirely dependent on the success of Starship, **** eX's next-generation rocket system, which still needs to demonstrate its capacity to handle launch frequency and reliability on the scale Musk describes. When Musk said during **** eX's August earnings call that the company would build its future AI infrastructure exclusively on NVIDIA, NVDA shares rose more than 4%, while **** eX's shares fell more than 10% before paring losses, reflecting investor concerns about execution risk and capital intensity, despite the fact that the NVIDIA relationship was well received.
#Companies

1 month ago
Palantir (PLTR) CEO Alex Karp has dropped a blunt theory about the AI industry's safety push.
The outspoken AI executive said that some companies might need government ownership to escape the financial consequences of their technology.
In his CNBC interview, Karp framed nationalization as the destination he believes those businesses are moving toward, with liability protection the prize.
His startling comments come as the industry's conversation shifts towards safeguards and whether development should slow down. Moreover, that also raises the question of who shoulders the risks created along the way?
Karp zeroes in on customers' intellectual property. He said businesses working with Palantir believe that their ideas and data are being fed into AI models, putting their competitive advantages at risk.
#businesses #alex #cnbc #moreover

1 month ago
GE Vernova Inc. (NYSE:GEV) is trying to recover after an 8.5% decline, with Bernstein defending the stock as "wired to win" and highlighting that data centers account for only 38% of its electrification order book. This supports the argument that the company's utility exposure extends beyond AI power demand alone. That diversification is a real consideration, but it does not directly address the concern raised by GLJ Research. The firm's Sell rating is not based on doubts about AI-driven power demand. Instead, GLJ Research argues that GE Vernova is still a fundamentally cyclical gas-turbine manufacturer, while its current valuation reflects an **** umption that the ongoing boom can remain permanent.
GE Vernova shares stabilized after an 8.5% decline triggered by GLJ Research's new Sell rating and broader concerns that a slowdown in AI spending could weigh on the company's order book. Bernstein **** yst Sunaina Ocalan directly challenged the view that GE Vernova's outlook depends mainly on AI infrastructure spending:
While data center orders were $5 billion in H1 2026, or about 38% of electrification orders, the remaining 62% was utility-driven. Utility spend should continue to grow, supported by grid reliability and resilience investments. A slowdown in data center demand may alleviate generation bottlenecks but would do little to address existing grid constraints.
Bernstein continues to rate the stock a Buy with a $1,298 price target, while nearly 80% of **** ysts covering GE Vernova also have a Buy rating. In a separate development, the company announced a wind turbine supply agreement with Eurus Energy Holdings in **** an.
GLJ Research's Gordon Johnson argued that GE Vernova's turbines being sold out does not justify the stock trading at roughly 38.9x forward EV/EBITDA at the time the report was released. Johnson described the company as "a cyclical gas turbine manufacturer priced as a secular compounder," highlighting the premium valuation placed on a fundamentally cyclical business. His model estimates 2027 EBITDA at $7.42 billion, which is 22% below Wall Street consensus. The lower forecast is partly based on the timing of turbine orders, as equipment scheduled for 2027 delivery was ordered in 2024, before the company introduced its more recent price increase.
#bernstein #turbine #Stock #data

1 month ago
Ondas Inc. (NASDAQ:ONDS) completed its acquisitions of GATE Technologies Ltd. and Bron Technologies on September 14, adding electronic safety and fuzing components used across precision weapons. GATE supplies the technology, while Bron provides manufacturing and certification capabilities in Poland.
Base consideration comprises $105 million in cash and $100 million in equity. The SEC filing specifies an additional $25 million working-capital adjustment. Of the stock consideration, approximately $22.5 million is scheduled for issuance within nine months, subject to conditions. Performance payments could add up to $185 million.
The investment question is whether owning qualified components can improve supply reliability and profitability enough to justify the purchase price and manufacturing investment.
GATE's technology is integrated into dozens of weapons systems. Qualification and integration requirements can make replacing a supplier difficult, supporting repeat demand as customer programs enter production. Ondas Inc. (NASDAQ:ONDS) can therefore participate in orders across multiple manufacturers alongside sales of its own systems.
Management says approximately 80% of GATE's revenue comes from outside the Middle East. The combination of Israeli engineering and Polish production provides an established international base. U.S.-produced finished products and integrated systems are targeted for the first half of 2027, potentially expanding access to programs with domestic sourcing requirements.
#ondas

1 month ago
Platform liability coverage is typically excess insurance, paying only after your homeowner's policy denies the claim, and that policy likely excludes business use.
Denise found a standalone commercial liability policy cost 4 times her homeowner's premium, exceeding her total pool rental income.
Before renting any home **** et, compare net rental income against a standalone liability policy quote to determine if the side hustle is actually profitable.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
A woman named Denise recently called into The Ramsey Show after discovering that the liability coverage she relied on for renting her backyard pool as a side hustle for about three years might not be as strong as she believed.
#policy #denise


1 month ago
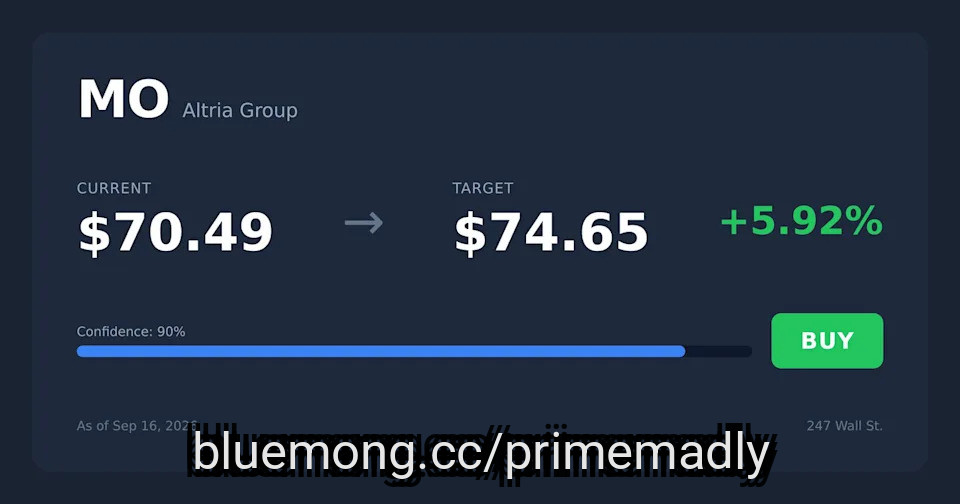
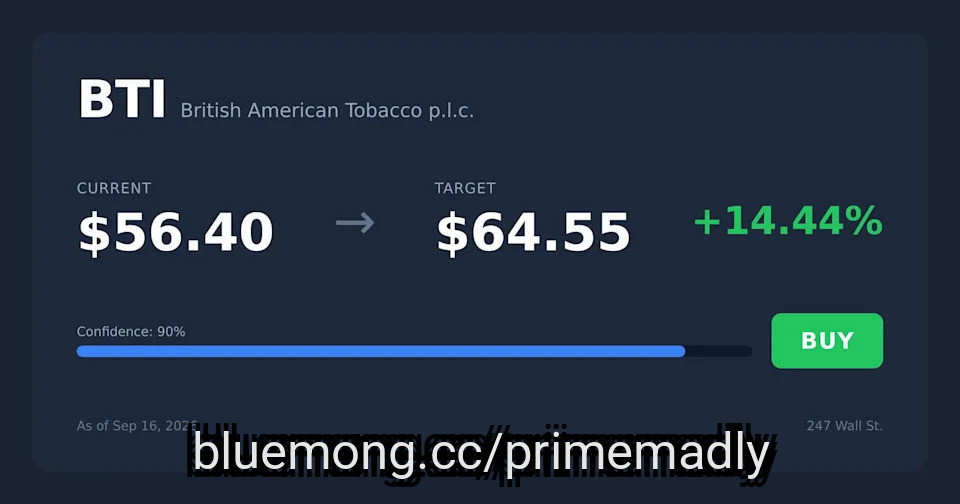
BTI yields 5.83% and beats MO on growth, trading at a cheaper forward P/E of 11 with EPS guidance of 5 to 8% versus Altria's 2.5 to 5.5%.
Altria wins on income reliability, having raised its dividend 60 times in 56 years with a 6.10% yield paid in dollars with zero currency risk.
BTI's Modern Oral segment surged 47% while Altria's nicotine pouch share fell 4 points and cigarette volumes dropped 10% in 2025.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
For a retirement-focused investor weighing high-yield tobacco names, the question is direct: British American Tobacco (NYSE:BTI) or Altria Group (NYSE:MO), which screens better for income investors right now? Both throw off cash, both trade at single-digit-to-low-teens forward earnings, and both are racing to replace shrinking combustible volumes with nicotine pouches, vapor, and heated tobacco. But when you line them up on the metrics that actually matter for a retiree cashing checks, one name comes out ahead.
#tobacco


1 month ago
Cipher Digital (NASDAQ: CIFR) stock is roaring higher on Wednesday. The company's share price was up 13.9% as of 10:35 a.m. ET. At the same point in the daily session, the S&P 500 and the Nasdaq Composite were up 0.2% and 0.6%, respectively.
After recent sell-offs driven by concerns about the potential for increased regulation in the artificial intelligence (AI) industry, stocks in the category are seeing some rebound trading in today's session. In addition to that bullish catalyst, Cipher Digital stock is getting a big boost from news connected to its Texas data center projects.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The potential for AI to create dangerous outcomes has been a center-stage news item and point of political discussion recently, and increased focus on the topic has powered some valuation pullbacks for artificial intelligence companies. Calls for increased regulation of the AI industry have caused concerns among investors that growth in the category could be impeded, but stocks in the ******* e are broadly seeing some rebound momentum in today's trading.
Before the market opened this morning, the Electric Reliability Council of Texas (ERCOT) published an update through its Batch Zero evaluation framework indicating grid capacity of up to 3.2 gigawatts for Cipher's data centers in the state. The update bodes well for the scaling of the company's AI compute business, and investors are bidding up the stock today in response.
#Stock #cipher #same

1 month ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Mettler-Toledo International Inc. (NYSE:MTD). Mettler-Toledo International Inc. (NYSE:MTD) manufactures and supplies precision instruments and services in the Americas, Europe, Asia, and internationally. On September 15, 2026, Mettler-Toledo International Inc. (NYSE:MTD) closed at $1,330.40 per share. Over the past month, Mettler-Toledo International Inc. (NYSE:MTD) declined 6.64%, and its shares gained 4.43% over the past 52 weeks. Mettler-Toledo International Inc. (NYSE:MTD) has a market capitalization of $26.66 billion.
Weitz Multi Cap Equity Fund stated the following regarding Mettler-Toledo International Inc. (NYSE:MTD) in its Q2 2026 investor letter:
"Less familiar to shareholders may be our new position in Mettler-Toledo International Inc. (NYSE:MTD), a global supplier of precision measurement instruments across laboratory, industrial and food retailing applications where accuracy, reliability and regulatory compliance are vital. Its highly specialized sales and service organization is a key competitive advantage, working collaboratively with customers to optimize their workflows and improve productivity, reinforcing long-term customer relationships. We have long admired Mettler's business and purchased a small position during a brief period of price dislocation during the quarter."
Mettler-Toledo International Inc. (NYSE:MTD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 48 hedge fund portfolios held Mettler-Toledo International Inc. (NYSE:MTD) at the end of the second quarter, down from 50 in the previous quarter. While we acknowledge the potential of Mettler-Toledo International Inc. (NYSE:MTD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mettler #quarter


1 month ago
Britain's royal family has taken the unusual step of publicly challenging claims made by Princess Diana's brother, Earl Spencer, in his upcoming memoir.
Departing from the monarchy's traditional "never complain, never explain" approach, Buckingham Palace responded Wednesday to Spencer's recollection of a phone call between himself and King Charles, in the wake of Diana's death in 1997. According to Spencer, the call took place after Spencer objected to Prince William and Prince Harry, then 15 and 12, walking behind their mother's coffin at her funeral.
In an excerpt from the book Swan Song: Diana, My Sister published by Britain's Daily Mail, Spencer wrote, "He unleashed down the phone what I have always taken to be his pent-up contempt for Diana, and his horror that the world was so bowled over by her death. 'Rest ****** ured,' he hissed, 'we'll forget her soon enough.'"
While the palace didn't directly address whether the comment was made, the statement questioned the reliability of Spencer's recollection, saying, "While we do not comment on books as a matter of principle, His Majesty is mindful that the pain of fraternal grief can cloud reason, affect judgment and color memory in ways others do not recognize, even many years after such a loss."
The statement echoes the palace's reaction to claims made by Harry and Meghan Markle during their 2021 interview with Oprah Winfrey that an unnamed royal had made a remark about their son's skin color before he was born and that the monarchy failed to help a suicidal Meghan. A response issued on behalf of Queen Elizabeth II at that time said that "recollections may vary."
#spencer #meghan #palace #taken


1 month ago
Choosing between a clean energy innovator and a traditional oil giant reflects a core tension in today's market. Investors must decide if Bloom Energy (NYSE:BE) or Diamondback Energy (NASDAQ:FANG) is the better buy.
Bloom Energy manufactures solid oxide fuel cells that provide reliable onsite power, targeting the surging demand from artificial intelligence infrastructure. Diamondback Energy focuses on extracting oil and gas from the Permian Basin, prioritizing operational efficiency and shareholder returns. While both operate in the energy **** e, their business models, risk profiles, and valuation metrics differ significantly for 2026 investors.
Bloom Energy serves as a prominent player among renewable energy stocks, focusing on solid oxide technology for onsite electricity and hydrogen production. The company targets large-load customers in the data center, semiconductor, and industrial sectors where power reliability is critical. Key partnerships include an agreement with American Electric Power (NASDAQ:AEP) to provide up to one gigawatt of fuel cells and a financing framework worth nearly $5.0 billion with Brookfield (NYSE:BN).
In FY 2025, Bloom Energy reported revenue of approximately $2.0 billion, which represents a growth rate of roughly 37.3% compared to the prior year. Despite this robust top-line performance, the company reported a net loss of nearly $88.4 million for the same period. This loss widened from a net loss of approximately $29.2 million in FY 2024, although the net margin of negative 4.4% in FY 2025 was a significant improvement over the negative 22.7% margin seen in FY 2023.
As of its December 2025 balance sheet, Bloom Energy holds a debt-to-equity ratio of 3.9x. This ratio measures total debt against shareholder equity, indicating the company relies moderately on borrowed funds to fuel its expansion. The current ratio, which measures a company's ability to cover short-term debts with its short-term **** ets, stands at a strong 6.0x. For FY 2025, free cash flow reached close to $57.2 million, which is the cash remaining after paying for operating costs and equipment investments.
#bloom #million


1 month ago
Cipher Digital (NASDAQ: CIFR) stock is roaring higher on Wednesday. The company's share price was up 13.9% as of 10:35 a.m. ET. At the same point in the daily session, the S&P 500 and the Nasdaq Composite were up 0.2% and 0.6%, respectively.
After recent sell-offs driven by concerns about the potential for increased regulation in the artificial intelligence (AI) industry, stocks in the category are seeing some rebound trading in today's session. In addition to that bullish catalyst, Cipher Digital stock is getting a big boost from news connected to its Texas data center projects.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The potential for AI to create dangerous outcomes has been a center-stage news item and point of political discussion recently, and increased focus on the topic has powered some valuation pullbacks for artificial intelligence companies. Calls for increased regulation of the AI industry have caused concerns among investors that growth in the category could be impeded, but stocks in the ******* e are broadly seeing some rebound momentum in today's trading.
Before the market opened this morning, the Electric Reliability Council of Texas (ERCOT) published an update through its Batch Zero evaluation framework indicating grid capacity of up to 3.2 gigawatts for Cipher's data centers in the state. The update bodes well for the scaling of the company's AI compute business, and investors are bidding up the stock today in response.
#NVIDIA #Stock #increased #flashing


1 month ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Mettler-Toledo International Inc. (NYSE:MTD). Mettler-Toledo International Inc. (NYSE:MTD) manufactures and supplies precision instruments and services in the Americas, Europe, Asia, and internationally. On September 15, 2026, Mettler-Toledo International Inc. (NYSE:MTD) closed at $1,330.40 per share. Over the past month, Mettler-Toledo International Inc. (NYSE:MTD) declined 6.64%, and its shares gained 4.43% over the past 52 weeks. Mettler-Toledo International Inc. (NYSE:MTD) has a market capitalization of $26.66 billion.
Weitz Multi Cap Equity Fund stated the following regarding Mettler-Toledo International Inc. (NYSE:MTD) in its Q2 2026 investor letter:
"Less familiar to shareholders may be our new position in Mettler-Toledo International Inc. (NYSE:MTD), a global supplier of precision measurement instruments across laboratory, industrial and food retailing applications where accuracy, reliability and regulatory compliance are vital. Its highly specialized sales and service organization is a key competitive advantage, working collaboratively with customers to optimize their workflows and improve productivity, reinforcing long-term customer relationships. We have long admired Mettler's business and purchased a small position during a brief period of price dislocation during the quarter."
Mettler-Toledo International Inc. (NYSE:MTD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 48 hedge fund portfolios held Mettler-Toledo International Inc. (NYSE:MTD) at the end of the second quarter, down from 50 in the previous quarter. While we acknowledge the potential of Mettler-Toledo International Inc. (NYSE:MTD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Equity #fund #weitz

1 month ago
With the news that Philadelphia Eagles offensive lineman Landon ******* erson was being placed on IR with a knee injury, ******* erson himself seemed fine with the development — especially since, in the guard's view, he had no business being on the field in Week 1.
In an interview on Philadelphia's 94 WIP radio, which took place very shortly after the IR news landed, ******* erson offered a blunt ******* sment of his play in the Eagles' narrow 24-22 win over the Washington Commanders on Sunday.
"Honestly, (to) address the elephant in the room, I played like sh** yesterday," ******* erson said. "I was a complete liability yesterday and, again, that was my fault … I shouldn't be out there until I feel healthy."
Dickerson said that he got "rolled up on" in practice last month during training camp, but continued to push through the injury. Imaging on Monday confirmed that he had a bone bruise in his right knee.
Dickerson found out that he was being placed on IR while live on air: After being read a report from the Philadelphia Inquirer's Jeff McClane, who was the first to report the news, the Eagles' starting left guard admitted to WIP that he hadn't been officially told, but that he knew it "was kind of the plan."
#Eagles #yesterday


1 month ago
The Eagles will place left guard Landon ***** erson on injured reserve with a knee injury.
Dickerson appeared on WIP's "Players Lounge Show" as news hit that he was headed to IR with what he described as a bone bruise in his right knee.
He said he "played like ***** " in the Eagles' 24-22 win over the Commanders on Sunday.
"I was a complete liability yesterday," ***** erson said, via Alexis Chassen of bleedinggreennation.com. "Again, that was my fault. I know I said earlier in camp I shouldn't be out there until I feel healthy. A few weeks ago, [I] got rolled up on in practice. I thought as weeks went by it would get better. It didn't, and we kind of went out there and finally got some imaging on it today, figured out what was wrong with it.
"Really the best plan going forward is to put me on IR, so I can get this thing better to have a good stretch at the back end of the season versus kind of what happened last year, go out there limping through 18 weeks. I don't think anyone wants to see that again because that was just ugly. I don't want to do that again, because that was just some BS."
#Eagles #knee #kind #players



1 month ago
On August 6, The RealReal (NASDAQ:REAL) reported second quarter results that beat its own outlook and pushed the resale luxury marketplace to raise its full year guidance. Gross merchandise value hit an all time high of $617 million, up 22% from a year earlier, and management pointed to four straight quarters of GMV growth above 20%. But a wider net loss sitting next to those record numbers complicates the story for anyone weighing the stock today.
The headline number is GMV of $617 million for the quarter ended June 30, up 22% year over year, with total revenue climbing 17% to $193 million. Consignment revenue grew 15% while Direct Revenue, the company's owned inventory channel, grew 26%, showing both sides of the business contributing to the acceleration. Profitability moved in the same direction. Gross margin reached 74.4%, up 10 basis points from a year ago, and Adjusted EBITDA margin jumped to 7%, a 290 basis point improvement that management called nearly 300 basis points of expansion.
The buyer base backs up the growth story rather than just the pricing. Trailing twelve-month active buyers rose 11% to 1,107,000, and average order value climbed 13% to $659, meaning existing shoppers are spending meaningfully more per transaction, not just showing up more often. That combination gave management enough confidence to raise full-year guidance to $2.54 billion to $2.57 billion in GMV and $788 million to $797 million in total revenue, alongside third-quarter Adjusted EBITDA guidance of $13.5 million to $14.5 million.
Despite the operating improvements, GAAP losses widened. Net loss came in at $27 million, or 14.1% of total revenue, compared to $11 million, or 6.9% of total revenue, a year earlier. GAAP basic net loss per share was $0.23 versus $0.10 in the prior year period, and diluted net loss per share was $0.23 versus $0.13. Much of that swing traces to a $(18.6) million non-cash adjustment tied to the change in fair value of warrant liability, a factor unrelated to how the underlying business performed. On a non-GAAP basis, basic and diluted net loss per share actually narrowed to $0.01 from $0.06, underscoring how much of the GAAP gap is accounting rather than operations.
There is also a transparency wrinkle in the guidance itself. The RealReal said it has not reconciled its forward-looking Adjusted EBITDA figures to GAAP net income or loss, citing components like payroll tax expense on employee stock transactions that it cannot predict with reasonable certainty. That leaves investors trusting a non-GAAP target without the usual bridge back to the bottom line.
#adjusted

1 month ago
On August 6, PureCycle Technologies (NASDAQ:PCT) reported second-quarter results for the period ended June 30, and buried in the numbers was something the plastics recycler has chased for years: an actual branded product on store shelves. Select Downy detergent caps made with PureCycle's PureFive resin entered commercial production for Procter & Gamble during the quarter, the first tangible sign the company's purification technology can clear a major consumer brand's supply chain. Revenue came in at $4.5 million, up roughly 173% from a year earlier and the sixth straight quarter of sequential growth.
The Downy win was not an isolated event. PureCycle said select Tide caps are scheduled for retail production in the third quarter, with Vicks ZzzQuil PURE Zzzs child-resistant lids targeted for the fourth quarter of 2026. Seven customer conversions took place during the quarter, alongside six new commercial partnerships spanning closures, automotive, film, and food packaging, including Amcor, Motherson, and Innovia Films. Regulation is doing real work here too. New Jersey's Department of Environmental Protection approved PureFive as post-consumer recycled content, a decision that arrives as the state's food contact exemption expires in January 2027 and its recycled content requirement climbs to 20%, while California's SB54 is already in effect.
Operationally, the Ironton facility's planned turnaround finished ahead of schedule and under budget, with more than 170 reliability and rate projects completed and inspections showing no corrosion on major equipment. On-site compounding, commissioned in April, is now running 24 hours a day, five days a week, with plans to expand to seven by the fourth quarter. PureCycle also picked up ISO 9001:2015 certification in May and closed the quarter with $236.9 million in total liquidity after a June capital raise.
The other side of the ledger is harder to ignore. PureCycle posted a net loss of $142.2 million for the quarter, and adjusted EBITDA actually widened to a loss of $31.7 million from a loss of $27.8 million a year earlier, a shift the company attributes to smaller non-cash addbacks rather than weaker operations. PureFive production fell to 4.5 million pounds for the quarter, a direct result of the planned turnaround, even though output was still up about 32% from a year ago. Growth is not coming cheap either. Full-year 2026 project spending guidance was raised to a range of $45 million to $50 million, up from the prior $39 million to $45 million.
#year #loss


1 month ago
During the September 3 episode of Mad Money, Jim Cramer mentioned Microsoft Corporation (NASDAQ:MSFT) for its unconventional approach to powering hyperscale data centers in partnership with Chevron Corporation (NYSE:CVX). He said:
How about Microsoft? Look, Mr. Softee is getting religion. They've realized that by giving us more disclosure on Azure, their cloud infrastructure business, we'll find more things to like. They're right. In the end, I come to praise Microsoft CFO Amy Hood, not bury her. They've been very clever getting power for the data centers, pumping it right out of the Permian. They got this deal with Chevron as a partner… 2.67 gigawatts. No one's talking about it. It's the cleanest behind the meter plan for power I have seen yet. People even, and this is not a stretch, I'm not kidding, people even like Copilot.
CFO Amy Hood provided Wall Street with a much clearer look at actual cloud demand by breaking down detailed Azure growth metrics and data center capacity constraints. At the same time, enterprise adoption of Microsoft 365 Copilot is moving past initial trials, with major corporations deploying the AI ***** istant across workforce segments.
A major highlight of the company's infrastructure strategy is a twenty-year agreement with Chevron Corporation (NYSE:CVX) for a proposed 2.67-gigawatt natural gas power plant in West Texas. Designed to supply dedicated off-grid electricity directly to a hyperscale data center in the Permian Basin, the project bypasses regional grid transmission queues to secure reliable power for continuous AI workloads. Microsoft Corporation's (NASDAQ:MSFT) president of Cloud Operations + Innovation, Noelle Walsh, commented:
Our agreement with Chevron helps ensure we'll have dedicated, large-scale power to support the evolution and reliability of advanced compute. Through this partnership, we're delighted to grow with and become a deeper part of the West Texas community.
#chevron #power #they 've

1 month ago
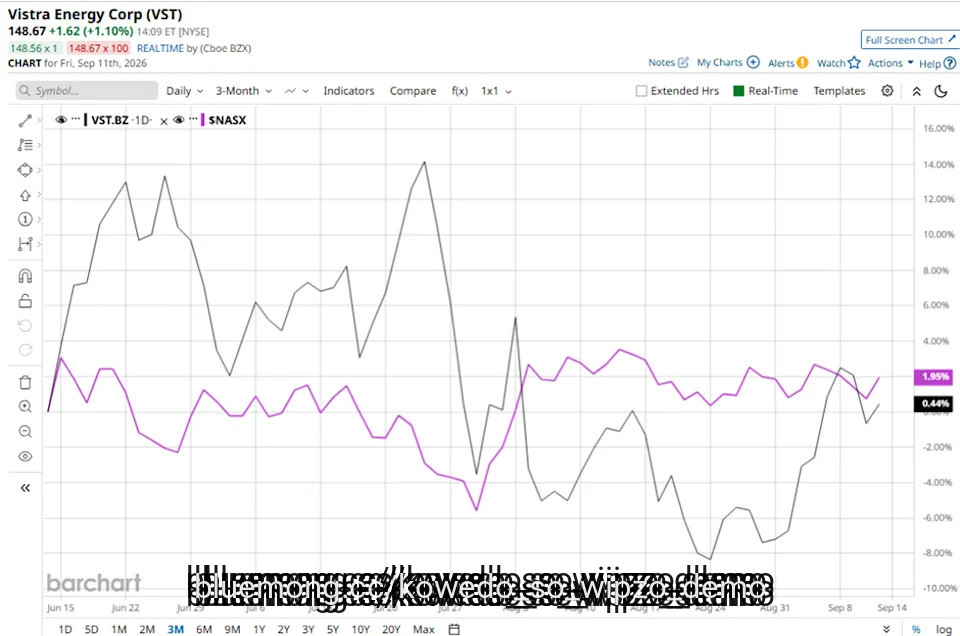
With a market cap of $49.4 billion, Vistra Corp. (VST) is a leading integrated electricity and power generation company. The company provides essential energy resources to customers, businesses, and communities across the United States, with a strong focus on reliability, affordability, and sustainability.
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Vistra fits this criterion perfectly. Vistra operates a diverse and efficient power generation portfolio spanning natural gas, nuclear, coal, solar, and battery energy storage, complemented by a customer-centric retail business.
Why It's Time to Load Up on Intel Stock
Google Plans to Build Mammoth Solar Farm on an Abandoned Coal Mine. This Penny Stock Just Won the Deal.
NVDA Stock Alert: What to Know as Nvidia Faces DOJ Probe
#Stock #energy #corp


1 month ago
Deutsche Bank Aktiengesellschaft (NYSE:DB) said on September 7 that it had settled a Frankfurt lawsuit brought by former banker Dario Schiraldi, according to Reuters. He had sought €152 million in damages, but the settlement amount was not disclosed. The bank said the agreement would have only a small financial effect on third-quarter earnings.
The distinction matters: €152 million was the claim, while the payment remains confidential. The earnings impact also does not establish the cash cost, because a settlement payment may discharge a liability for which an expense was recognized earlier.
Four former employees continue to pursue claims exceeding £600 million in London. The Frankfurt agreement therefore reduces the number of unresolved cases without establishing the cost of resolving the wider dispute.
Deutsche Bank Aktiengesellschaft (NYSE:DB) has removed one source of litigation uncertainty. The Frankfurt court confirmed that Schiraldi withdrew his case ahead of the scheduled hearing. Investors now have management's ***** sment of a limited near-term earnings effect instead of an unresolved damages demand.
The agreement also shows that negotiated resolutions are possible. It was the second settlement involving the six former employees who brought related claims. Further agreements could reduce litigation costs and management distraction if acceptable terms can be reached.
#million


1 month ago
FirstEnergy Corp. (NYSE:FE), through its Potomac Edison subsidiary, proposed a $52.8 million Maryland distribution-rate adjustment to support investment in aging infrastructure, grid modernization and electric-system reliability. If approved, the request would increase the average residential customer's monthly bill by approximately 5.3%.
Potomac Edison said its electric rates were 25% below the average of its in-state peers as of June 1. The utility expects its residential rates to remain the lowest among Maryland's investor-owned electric utilities even after the proposed adjustment.
The proposed reliability program includes Supervisory Control and Data Acquisition technology, replacement of substation reclosers, new circuit ties and automation, overhead-conductor upgrades, aging underground-cable replacement and removal of high-risk trees near power lines. The Maryland Public Service Commission must review and approve the request before any adjustment can take effect.
The proposal connects the requested revenue to specific reliability investments. SCADA technology can give operators greater visibility into system conditions, while reclosers, circuit ties, and automation can isolate problems and reroute electricity. These capabilities can reduce the number of customers affected by outages and shorten restoration times.
Reconductoring, underground-cable replacement and vegetation management address physical causes of service interruptions. The investments could also improve resilience during severe weather, potentially lowering emergency-response costs and reducing the disruption experienced by customers.
#proposed #maryland #aging

2 months ago
SpaceX (NASDAQ:SPCX) has been building its AI business at warp speed. It turns out to be much more challenging to rapidly build reliable data centers than expected. Some of its facilities ran without backup power for months. That recently led the company to make some changes, including reshuffling its leadership team to ensure it can meet a looming deadline for a $920 million-a-month compute deal with Alphabet's (NASDAQ:GOOG)(NASDAQ:GOOGL) Google.
Here's a look at what went wrong and how **** eX is racing to fix the problem.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: The Motley Fool.
Engineering and reliability issues have surfaced at **** eX data center sites in Tennessee and Mississippi. According to a recent report by The Information, several sites operated without backup cooling and power systems as the company pushed to expand capacity as fast as possible. That publication has previously reported issues at **** eX data center sites, including that its Macrohand facility in Tennessee had to rely on over 100 mobile chillers and recorded uptime well below the company's 99.9% internal target. Meanwhile, the company used temporary gas turbines at its Mississippi data center longer than expected due to supply chain issues in delaying 41 permanent units. Temporary outages of the power and cooling systems have interrupted AI model training.
#company #NVIDIA #signal #power


2 months ago
SpaceEx (SPCX) stock is on the move Thursday as investors sort through a number of headlines affecting the rocket-and-satellite company.
The most consequential came from The Information, which reported that ******* eX and CEO Elon Musk are overhauling how the company builds its data centers, a shift that could slow the pace of new construction.
According to the report, a new management team from the company's rocket division is prioritizing reliability over speed, installing more backup power and cooling systems, and testing data centers more thoroughly before they go live.
The change is a departure from what Musk and xAI (now part of ******* eX) used to build at its Colossus campus in Tennessee, where the AI unit brought its first data center online in just 122 days, a timeline Nvidia (NVDA) CEO Jensen Huang called "superhuman."
But that speed came with trade-offs like frequent outages, including a construction-related outage at the Memphis facility last week that knocked some Grok models offline and affected compute customers like Anthropic (ANTH.PVT) and Google (GOOG, GOOGL), The Information said.
#rocket

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
The decision will see the planned closure of Cone Denim's Jiaxing facility in Zhejiang province, marking a major step in its ongoing strategic transformation.
Cone Denim says the withdrawal follows a "comprehensive review" of its manufacturing footprint, the global denim market and changes in customer sourcing needs.
Recent changes in global trade, evolving customer strategies, cost pressures, supply chain considerations and broader geopolitical circumstances all contributed to the determination to curtail denim production in China.
Cone Denim president Steve Maggard explained: "We are positioning Cone Denim for its next chapter of success, with a clear priority to continue delivering for our customers with the quality, innovation, reliability, and service that have defined Cone Denim for generations.
"Closing the China facility was a difficult but necessary decision as we position Cone Denim for long-term competitiveness in a changing global market. While this marks a significant change in our manufacturing network, our commitment to serving customers remains unchanged, and we are committed to supporting our customers, employees, suppliers, and local stakeholders through this transition with transparency, care, and disciplined execution."
#global #changes


2 months ago
On August 5, OraSure Technologies (NASDAQ:OSUR) reported second-quarter 2026 results that included its first GAAP net income in years, a headline number of $6.2 million versus a $19.7 million loss a year earlier. Revenue of $30.6 million beat the company's own guidance range and climbed 9.7% from the prior quarter. But look past the top line and the story splits in two, one part driven by real operating progress, the other by an accounting adjustment tied to a regulatory setback.
Some of this quarter's improvement came from actual operations. Gross margin expanded to 43.5% on a GAAP basis, up from 42.1% a year earlier, and non-GAAP gross margin rose to 44.2% from 43.2%. Diagnostics revenue grew 1% year over year to $19.4 million, helped by higher syphilis test sales and the addition of BioMedomics' Sickle SCAN product line. OraSure also picked up two regulatory wins during the quarter. In June 2026, the FDA cleared its Colli-Pee Dx urine collection kit for use with Roche's **** ually transmitted infection tests, letting patients collect samples at home instead of in a clinic.
The following month, the FDA granted Emergency Use Authorization for the second-generation OraQuick Ebola 2.0 Rapid Antigen Test, which can detect all four Ebola virus strains known to cause disease in humans. Cash used in operating activities improved to $23.8 million over the first six months of 2026, down from $30 million a year earlier, a sign the cash burn is easing. The company also kept buying back stock, repurchasing $22 million of shares, or 7.7 million shares, against its $40 million authorization, retiring more than 10% of shares outstanding.
The GAAP profit that headlines this quarter didn't come from the business getting more profitable. It came almost entirely from a $22.6 million reduction in a contingent consideration liability, an accounting entry triggered when OraSure updated its regulatory submission plan for the CT/NG test on its Sherlock platform. Strip that adjustment out and the underlying trend looks different. Non-GAAP operating loss widened to $14.7 million from $13.2 million a year earlier, and non-GAAP net loss came in at $13.8 million, roughly in line with last year's $14.2 million loss. The regulatory event behind that accounting gain is itself a setback.
In July, OraSure withdrew its InteliQuick CT/NG molecular self-test submission after receiving FDA feedback, meaning the product's path to market is now delayed while the company prepares a future resubmission. Total revenue for the quarter was still down 2% year over year, and core revenue, which excludes COVID-19 and Risk **** sment Testing, was flat. Six-month revenue fell 4% to $58.6 million. Sample Management Solutions revenue stayed flat year over year at $9.9 million, showing no growth driver of its own. Cash and equivalents fell to $161 million at quarter-end from $199.3 million at the end of 2025, pulled down by continued buybacks and cash used in operations.
#year #gaap #reven

2 months ago
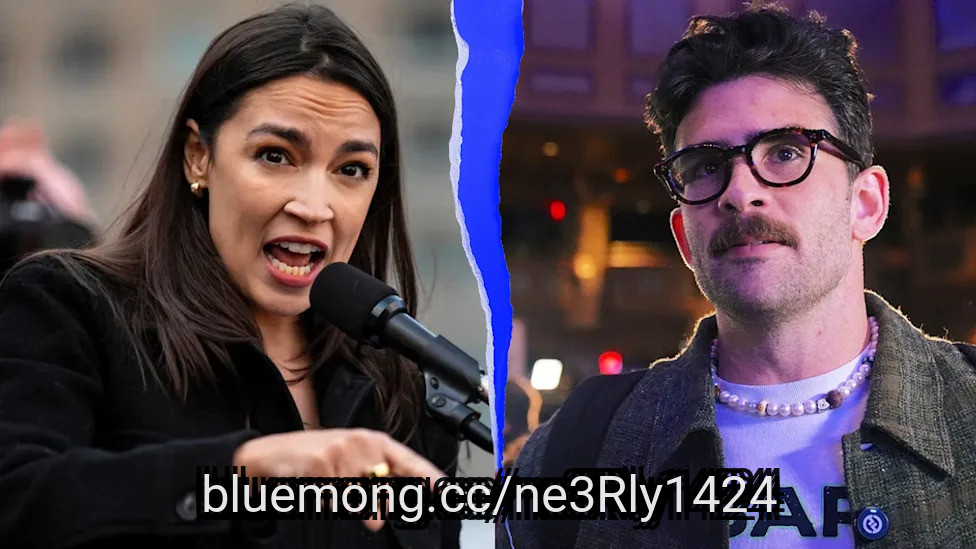
Hasan Piker hears the growing chorus of Democrats condemning him for incendiary statements, and he has a message for the party: "My job is not to make the Democratic Party look good."
The far-left Twitch streamer has boosted socialist candidates even as he created headaches for the broader Democratic Party in a midterm election cycle where it hopes to make major gains. The 35-year-old Piker — whose polarizing stances range from defending communist Chinese dictator Mao Zedong to comparing Zionism to "Nazism" — is a darling of the Democratic Socialists of America, but a potential liability for mainstream Democrats as November approaches.
Piker said Democratic Party officials have not reached out to coordinate a strategy.
"I have not had a conversation with anyone from the DNC," Piker said. "That would be very funny."
James Carville Decries 'Idiot' Hasan Piker, Orders Dsa To Change Its Name
#democratic

2 months ago
On August 5, Southwest Gas Holdings (NYSE:SWX) reported second quarter results for the period ended June 30 and reaffirmed its full year 2026 guidance. Net income attributable to the company reached $42.1 million, a sharp turnaround from a $40.2 million loss in the same quarter of 2025. But the number that stood out was the Great Basin 2028 Expansion Project, where contracted demand has grown enough that management now expects capital costs of $2.3 billion instead of the $1.7 billion baked into current five year guidance.
Southwest Gas's growth story increasingly runs through Nevada. Binding precedent agreements for the Great Basin 2028 Expansion Project have grown to roughly 1 billion cubic feet per day of contracted demand, and the company has fielded another 1.8 billion cubic feet of expressions of interest for phases running from 2029 through 2035. Based on that demand, management now projects an annual margin of $270 million to $300 million once the pipeline is in service, on capital investment of about $2.3 billion.
Regulators have been cooperating too. California's Public Utilities Commission approved the non-cost-of-capital pieces of Southwest Gas's rate case, adding roughly $40 million of incremental annual revenue and triggering recognition of $9.7 million of previously deferred first-quarter income. Nevada regulators approved a Triennial Resource Plan with prudency pre-determinations for about $186 million of capital spending, and the company filed for a general rate case increase of roughly $74 million.
Arizona's new System Integrity Mechanism, effective April 1 this year, lets Southwest Gas recover safety and reliability spending faster, up to a $50 million annual cap. The company put $520 million into its network in the first six months of 2026, including $115 million toward Great Basin, and closed the quarter with $270.5 million in cash and nearly $1 billion in available liquidity.
Look past the headline swing to profit, and the picture gets murkier. The core natural gas distribution segment actually earned less this quarter, with its contribution to net income falling from $45.6 million a year earlier to $40.8 million, and its adjusted net income slipping from $33.7 million to $31 million. Depreciation and amortization rose $8.7 million, or 13%, as gas plant in service grew 7% year over year, a reminder that heavy pipeline spending shows up in expenses well before it shows up in rates.
#million #company #basin


