
10 days ago
The CLARITY Act's 49-50 Senate failure sent XRP down 8% and invalidated every major **** yst price target built on the bill passing.
ChatGPT's 90-day forecast puts XRP's central estimate at $1.20, down from $1.30, and identifies the $1.20 to $1.23 range as the key near-term battleground.
Weekly XRP ETF inflows fell from $110 million to $19 million, while a second Fed rate hike in October threatens further downside pressure.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
XRP (CRYPTO:XRP) holders spent this year anticipating the Digital **** et Market Clarity Act, a bill intended to write XRP's commodity status into federal law rather than leaving it subject to regulatory changes. The bill reached the Senate floor with 126 Democratic amendments included but failed on a procedural vote on September 15, 2026, with cloture ending 49 to 50.
#clarity #october #Crypto


12 days ago
Shares of Nvidia Corp (NASDAQ:NVDA) stock are inching 0.4% higher to trade at $211.72 this afternoon, taking a breather after five-straight losing sessions, including yesterday's AI-induced selloff of 3.4%. The equity is still up 13.3% in 2026, however, and a rebound could soon be on the way, per a historically bullish trendline.
According to Schaeffer's Senior Quantitative ***** yst Rocky White, NVDA is trading within 0.75 times the 126-day moving average's 20-day average true range (ATR), after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above that trendline.
This setup has appeared 11 times over the last decade, after which the stock was higher one month later 82% of the time, averaging a 6.2% gain. From its current perch, a move of this caliber would put the equity just shy of $225.
NVDA sports a 50-day put/call volume ratio at the International Securities Exchange (ISE), Cboe Options Exchange (CBOE), and NASDAQ OMX PHLX (PHLX) that stands higher than 83% of readings from the past year. Should this bearish sentiment begin to unwind, it could trigger a new round of tailwinds for the shares.
Options are looking affordable as well. The stock's Schaeffer's Volatility Index (SVI) of 34% stands higher than just 2% of all other readings from the past year. In other words, near-term option traders are pricing in low volatility expectations at the moment.
#NASDAQ #cboe #phlx

27 days ago
MD Sass, a boutique ****** et management firm, published its second-quarter investor update for its flagship, the "MD Sass Concentrated Value Strategy." The letter can be downloaded here. In the first half of 2026, AI infrastructure stocks led the market, with the Russell 1000 Value increasing by 16.3%, outpacing the S&P 500 (10.2%) and Russell 1000 Growth (5.3%). This growth was fueled by semiconductor, memory, and hardware companies benefiting from AI development, even though they are considered cyclical. These sectors, representing only 7.7% of the Russell 1000 Value at the start of the year, contributed nearly 70% of its returns. The portfolio gained 10.0% in the second quarter, net of fees, compared to 13.9% for the Russell 1000 Value Index. Year-to-date, the strategy returned 6.6%, net of fees, versus 16.3% for the Index. The portfolio faced challenges due to limited exposure to companies with the greatest upside from AI infrastructure investments. It also lacked exposure to the Energy sector, which returned about 20% in the first half amid geopolitical tensions with Iran that increased commodity prices, affecting performance. The firm recognizes the importance of adapting its strategies while maintaining core investment principles as it explores future opportunities in emerging technological themes. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, MD Sass Concentrated Value Strategy highlighted Knight-Swift Transportation Holdings Inc. (NYSE:KNX). Knight-Swift Transportation Holdings Inc. (NYSE:KNX) is a freight transportation services provider that operates through Truckload, Less-than-truckload (LTL), Logistics, and Intermodal segments. On August 28, 2026, Knight-Swift Transportation Holdings Inc. (NYSE:KNX) closed at $67.24 per share, reflecting a market capitalization of $10.94 billion. Knight-Swift Transportation Holdings Inc. (NYSE:KNX) posted a one‑month return of ‑1.04%, while its shares gained 54.24% over the past 52 weeks.
MD Sass Concentrated Value Strategy stated the following regarding Knight-Swift Transportation Holdings Inc. (NYSE:KNX) in its Q2 2026 investor letter:
"Knight-Swift Transportation Holdings Inc. (NYSE:KNX) operates the largest full-truckload fleet in North America and operates approximately 21,000 tractors across its irregular route and dedicated fleets. Excluding fuel surcharges and intersegment transactions, Truckload represents approximately 63% of revenue, less-than-truckload represents 19%, logistics 8%, and intermodal 5%.
Trucking is a cyclical, fragmented, and historically low-margin business, and for those reasons we have avoided it. So why own it now? We believe the industry is entering a rate cycle that is meaningfully different from the demand-driven cycles of the past. This cycle is being manufactured on the supply side through a combination of economic attrition, regulatory enforcement, and increased legal liability. Importantly

28 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Why we like it: The Discover it Cash Back is our top choice because it was the highest-ranking Discover card in the cash-back, 0% APR, balance transfer, and rewards categories. This is definitely due to its high-quality benefits and features, such as 0% intro APR offers, a generous welcome bonus, and an elevated rewards rate — all with a $0 annual fee.
Read our full Discover it Cash Back Credit Card review
Why we like it: The Discover it Miles is a straightforward travel rewards card that makes earning miles on any eligible purchase easy. You don't have to worry about different spending categories since you get 1.5x miles on all qualifying purchases. As a new cardholder, you can also take advantage of the generous Discover Match welcome bonus.
Read our full Discover it Miles review
#card #rewards #categories
1 month ago
Tuniu Corporation's (NASDAQ:TOUR) ADSs closed lower after the company reported its second-quarter results. Net revenue increased 3.0% year over year to RMB138.9 million, while packaged-tour revenue rose 6.8% to RMB121.1 million as organized tours continued to grow.
However, cost of revenue increased 27.9% to RMB62.5 million, substantially outpacing the top line. Gross profit declined 11.1% to RMB76.4 million, and gross margin contracted to 55.0% from 63.8%. Tuniu consequently swung to a RMB6.1 million operating loss from RMB7.1 million of operating income a year earlier.
Packaged-tour growth indicates that demand for Tuniu's core travel products remains intact. The company has been expanding small-group, private and customized tour offerings in response to demand for more personalized and flexible travel options.
Tuniu also remained marginally profitable below the operating line. GAAP net income attributable to ordinary shareholders was RMB0.7 million. Company-defined non-GAAP net income attributable to ordinary shareholders was RMB2.2 million after excluding share-based compensation and amortization of acquired intangible **** ets.
Liquidity provides additional room to absorb uneven travel demand. Tuniu ended June with approximately RMB1.0 billion in cash and cash equivalents, restricted cash, short-term investments, and long-term deposits. Management said during the earnings call that Tuniu generated RMB46.9 million of operating cash flow while recording RMB1.4 million of capital expenditures.
#tuniu #company #revenue #demand

1 month ago
Micron (NASDAQ: MU) stock tumbled 5.5% in the first five minutes of trading Monday after tech news site WCCTech reported the Trump Administration has decided to permit Apple (NASDAQ: AAPL) to purchase memory chips from Chinese suppliers ChangXin Memory Technologies (CXMT) and Yangtze Memory Technologies Corp (YMTC).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Respectively, CXMT is a maker of low-cost DRAM chips, while YMTC manufactures NAND. Micron produces both kinds of memory chips. According to WCCTech, the DRAM and NAND that Apple might source from China would only be used in Apple products sold in China.
As such, this news isn't a global threat to Micron. It is, however, at least a threat to the company's market share in China, and perhaps in other countries to which China might ship Apple products, should those start to filter out.
Not everyone thinks it's time to press the panic **** on. In a note on StreetInsider.com this morning, Lynx Equity Research **** yst KC Rajkumar says calls for investors to sell Micron are an "overreaction," citing concerns about the quality of Chinese wares and the inability of CXMT and YMTC to scale production sufficiently to meet Apple's needs.
#memory

1 month ago
The earnings statement is where most investors go first when ****** sing a company's financial results. On that score, Amazon (NASDAQ: AMZN) looks like it had a breakout quarter in the second quarter of 2026, with earnings of $5.75 per diluted share, up from $1.68 in the same quarter of 2025. But there's a winkle here, and the story gets even more complicated when you step back and examine the cash flow statement.
Earnings are created by complying with generally accepted accounting principles (GAAP). They are, even at the best of times, just a hazy snapshot of a company's performance. That's highlighted by Amazon's $5.75 second-quarter earnings figure, which includes $69 billion in "other" income. That isn't likely to be repeated, as it is related to the company's investment in Anthropic. And if Anthropic's value declines, that benefit could actually reverse.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
But the presence of that number, which was actually larger than the company's $51.3 billion in operating income, highlights why investors also look at the cash flow statement. The cash flow statement shows where the company's cash is generated and how it is used. For years, large technology companies like Amazon generated huge amounts of cash, allowing them to amass large cash balances to fund their businesses, capital investment needs, and acquisitions.
Artificial intelligence (AI) has changed the cash flow story. Over the past 12 months, Amazon generated around $161.4 billion in cash, up 33% year over year, but spent $169 billion, meaning the company spent around $7.6 billion more in cash than its business generated. Those are very large numbers, with AI spending driving a significant share of the company's capital investment plan.
#cash #earnings
1 month ago
Strategy (NASDAQ: $MSTR) left its Bitcoin (CRYPTO: $BTC) holdings unchanged over the past week as the price of the largest cryptocurrency rose more than 20%.
The company sold 18.26 million shares of its common stock, increased its cash reserves to $5.1 billion U.S., and repurchased $136.4 million of its preferred stock (NASDAQ: $STRC).
However, Strategy did not buy or sell any Bitcoin in the last week as the price jumped 24% from $63,000 U.S. to above $78,000 U.S.
More From Cryptoprowl:
Canadian Defense Tech Firm Jumps 92% as Government Revenue Boosts Margins
#million #strc

1 month ago
Stripe has a new fintech playbook for the AI era.
Following the company's January purchase of the usage-based billing startup Metronome, the purchase of OpenRouter makes it clear that Stripe believes it can apply its payments-infrastructure approach to developer infrastructure.
"Stripe acquiring OpenRouter is less about buying a product and more about buying position," said Jeremy Jonker, managing partner at the fintech-focused firm Infinity Ventures. "For fintech more broadly, this is a signal that the next competitive battleground is around monetizing AI usage. The companies that win will be the ones sitting at the choke point between AI consumption and the invoice."
OpenRouter, which is backed by Andreessen Horowitz and Sequoia, reportedly sold for around $8 billion, though a formal purchase price was not disclosed.
The company is essentially an evolution of the business Stripe has already been running.
#openrouter #infrastructure #buying #around

2 months ago
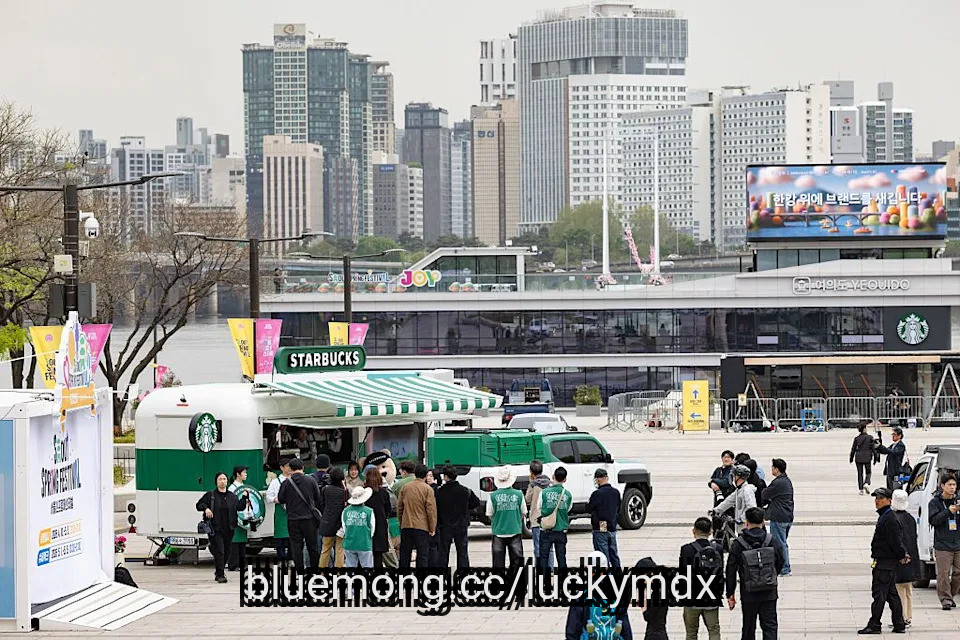
(Bloomberg) -- Starbucks Korea posted its first quarterly loss since it started operations 27 years ago after a marketing debacle triggered a boycott, criticism from President Lee Jae Myung, and a police raid of its corporate offices.
Most Read from Bloomberg
Walter Sells Lakers, Seeks More Cash to Pay Loans Amid DOJ Probe
Phoebe Gates Knew Phia Shopping App Took Credit for Sales It Didn't Drive
Trump Seeks Immediate Halt to Judge's Penalties in IRS Case
#Lakers
Most Read from Bloomberg
Walter Sells Lakers, Seeks More Cash to Pay Loans Amid DOJ Probe
Phoebe Gates Knew Phia Shopping App Took Credit for Sales It Didn't Drive
Trump Seeks Immediate Halt to Judge's Penalties in IRS Case
#Lakers
2 months ago
US-based investment company McIntyre Partnerships delivered flat performance in H1 2026, returning 0% gross and -1% net compared to the Russell 2000 Value Index's 23% return. A copy of the letter can be downloaded here. The second quarter results were a complete reversal of Q1 results, with the portfolio appreciating 23.0% (gross) and 23.3% (net), outperforming the index's 17.3%. The overall market surge contributed to this performance, alongside several positive developments related to the firm's holdings. Since inception, the fund has returned ~16% gross and ~12% net per annum, surpassing the benchmark's return of ~9% per annum. The portfolio is highly concentrated, with QDEL as the largest holding, creating volatility. Despite mixed results, the firm remains confident in the portfolio, particularly with QDEL viewed as a key investment opportunity. Potential for further growth is expected from several large investments with promising catalysts. In addition, you can check the Strategy's top 5 holdings to determine its best picks for 2026.
In its Q2 2026 investor letter, McIntyre Partnerships highlighted Sotera Health Company (NASDAQ:SHC). Sotera Health Company (NASDAQ:SHC) is a US-based company that provides sterilization solutions, lab testing, and advisory services for the healthcare industry. On August 7, 2026, Sotera Health Company (NASDAQ:SHC) closed at $18.86 per share, reflecting a market capitalization of $5.38 billion. Sotera Health Company (NASDAQ:SHC) posted a one-month return of 5.04%, while its shares gained 25.61% over the past 52 weeks.
McIntyre Partnerships stated the following regarding Sotera Health Company (NASDAQ:SHC) in its Q2 2026 investor letter:
"Sotera Health Company (NASDAQ:SHC) saw positive Q1 results, with the key Sterigenics segment continuing its return to HSD organic growth following the COVID destocking in 2023 and 2024. Further, SHC also had positive legal news regarding its Georgia litigation, where the judge threw out 5 lawsuits with reasoning that implies the remaining 450 cases are likely to be rejected as well. While I believe the judge's ruling implies current liability is sub-$50MM, I estimate a worst-case $400k per case settlement, or $180MM, even if appeals reverse the decision. This compares to SHC's 2026 EBITDA of ~$640MM. The company also saw a CEO transition, with its long-time CEO transitioning to Executive Chairman and the hiring of CEO Shader from Viant, a medical device services company where he served as CEO. We are encouraged that former CEO Petras remains on the board and intends to play an active role in ensuring a smooth transition.
Finally, and most importantly, following Q1 earnings, SHC's former private equity owners sold the last of their shares. I believe the PE firms' selling pressure, via predictable quarterly block trades, has been a considerable overhang on SHC's shares over the past year. With this overhang gone, I believe SHC is well positioned to reweight towards peers. I es




