

22 hours ago
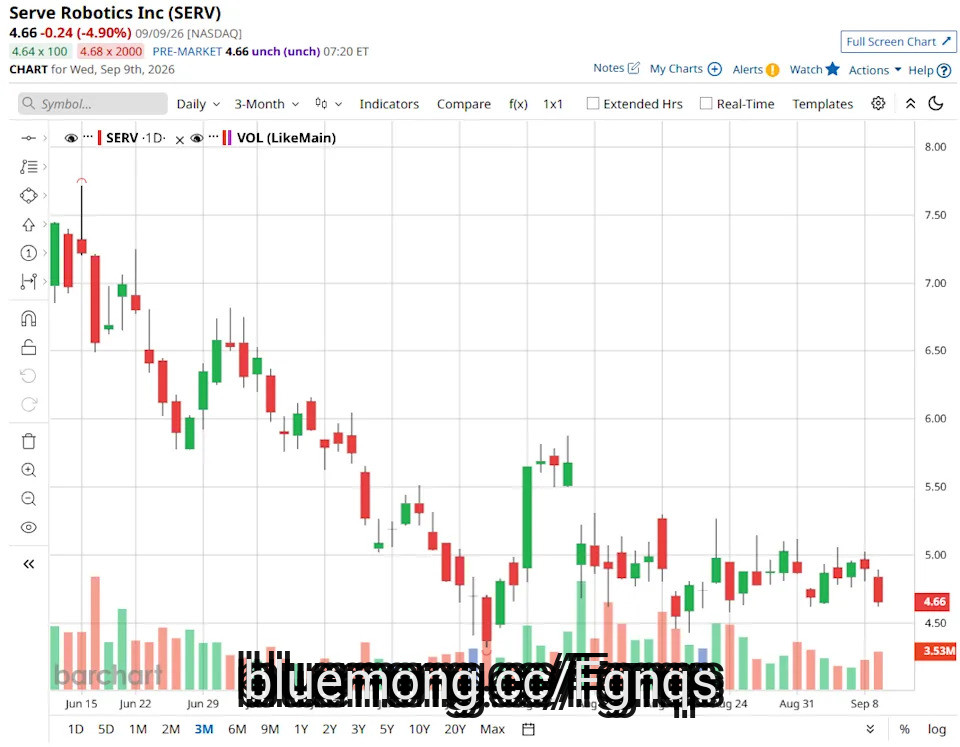
Serve Robotics (SERV) shares have tumbled roughly 20% since the autonomous delivery company lowered its 2026 revenue guidance on Aug. 6. The cut came despite quarterly revenue surging 404% year-over-year (YOY). Serve Robotics also said it may not renew its foundational partnership with Uber (UBER) after it expires in early 2027. The development follows Serve's first decline in Uber Eats delivery volume in 17 consecutive quarters. However, Serve has $240 million in cash and is intentionally expanding into DoorDash (DASH), healthcare robotics, and advertising. The debate now is whether the reset reflects deeper trouble or a strategic effort to diversify beyond a weakening partnership.
Investors should also look closely at the short interest number when it comes to SERV stock. Serve Robotics has a short percentage of float of 31.3%. That's an extremely high number for any company but also brings with it an opportunity — namely, a potential short squeeze. For that to happen, though, there needs to be some retail interest in SERV stock.
Dear ***** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#company
Investors should also look closely at the short interest number when it comes to SERV stock. Serve Robotics has a short percentage of float of 31.3%. That's an extremely high number for any company but also brings with it an opportunity — namely, a potential short squeeze. For that to happen, though, there needs to be some retail interest in SERV stock.
Dear ***** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#company



23 hours ago
Following an impressive second quarter FY27, Navan Inc. (NASDAQ:NAVN) announced its acquisition of BoomPop, an AI-powered meetings and events platform that has been recognized by Inc. as one of the fastest-growing private companies in America. Launched in 2023, BoomPop offers end-to-end event management solutions to enterprises, by leveraging artificial intelligence capabilities. Its offerings cover the entire spectrum of event management procedures including venue selection, vendor sourcing, contractual agreement, payments, and more. For Navan, this deal build on an existing alliance between the two entities, which was announced earlier in February. It marks the company's strategic push to expand its footprint across the meetings and events segment, where a large chunk of the spending is still done outside managed platforms.
LStockStudio/Shutterstock.com
The BoomPop acquisition follows a persistent enterprise market momentum reported by the company in its second quarter results, allowing Navan to enter into collaborative agreements with several leading companies during the quarter. These included Enbridge, Ingersoll Rand, ****** mins, and Evotec. Navan also concluded the deal to acquire Smartrips, a well-reputed travel management business, with the aim of bolstering its presence across a rapidly-growing Latin American market.
Notably, Navan registered adjusted net income of $14 million during the second quarter compared to an $8 million loss in Q2 FY26. It came at the back of year-over-year growth figures of 39% and 35% for subscription revenue and usage revenue, respectively.
Through full integration of BoomPop's staff and technology, Navan intends to expand its current meetings and events operations, accelerate its product development timeline, and satisfy growing customer interest. The company aims to deliver a more seamless experience covering travel, expense, meetings, and events.
#navan
LStockStudio/Shutterstock.com
The BoomPop acquisition follows a persistent enterprise market momentum reported by the company in its second quarter results, allowing Navan to enter into collaborative agreements with several leading companies during the quarter. These included Enbridge, Ingersoll Rand, ****** mins, and Evotec. Navan also concluded the deal to acquire Smartrips, a well-reputed travel management business, with the aim of bolstering its presence across a rapidly-growing Latin American market.
Notably, Navan registered adjusted net income of $14 million during the second quarter compared to an $8 million loss in Q2 FY26. It came at the back of year-over-year growth figures of 39% and 35% for subscription revenue and usage revenue, respectively.
Through full integration of BoomPop's staff and technology, Navan intends to expand its current meetings and events operations, accelerate its product development timeline, and satisfy growing customer interest. The company aims to deliver a more seamless experience covering travel, expense, meetings, and events.
#navan


23 hours ago
On September 1, Korn Ferry (NYSE:KFY) completed its £850 million acquisition of UK-based AMS, from OMERS Private Equity. The deal combines two well-reputed brands, resulting in a highly well-rounded solutions provider and a leading business within the global talent and organizational consulting **** e. It offers a broader market reach to Korn Ferry, along with more extensive coverage spanning several new industries.
Copyright: baranq / 123RF Stock Photo
AMS acquisition extends Korn Ferry's existing growth trajectory, which was highlighted in the company's recently announced first quarter results. It was the sixth back-to-back quarter of topline growth, which augments the durability of Korn Ferry's fundamental business model. The company also delivered a 9% growth in its adjusted diluted EPS of $1.43, relative to the same period last year.
The AMS deal results in several strategic benefits for Korn Ferry. Based on its long-standing client relationships, AMS offers robust operational strength, along with prospects of consistent, recurring income. Such relationships also enable the company to deliver technology-led solutions at scale.
Financing of this transaction involved a mix of existing cash, share issuance and borrowings. At closing, Korn Ferry paid approximately £473 million and $326 million in cash, covering consideration to the sellers, repayment of AMS indebtedness and other transaction obligations, and issued 3,118,628 Korn Ferry shares to the sellers.
#business
Copyright: baranq / 123RF Stock Photo
AMS acquisition extends Korn Ferry's existing growth trajectory, which was highlighted in the company's recently announced first quarter results. It was the sixth back-to-back quarter of topline growth, which augments the durability of Korn Ferry's fundamental business model. The company also delivered a 9% growth in its adjusted diluted EPS of $1.43, relative to the same period last year.
The AMS deal results in several strategic benefits for Korn Ferry. Based on its long-standing client relationships, AMS offers robust operational strength, along with prospects of consistent, recurring income. Such relationships also enable the company to deliver technology-led solutions at scale.
Financing of this transaction involved a mix of existing cash, share issuance and borrowings. At closing, Korn Ferry paid approximately £473 million and $326 million in cash, covering consideration to the sellers, repayment of AMS indebtedness and other transaction obligations, and issued 3,118,628 Korn Ferry shares to the sellers.
#business


1 day ago
Moscow is preparing for a final test of a new ballistic missile capable of striking targets hundreds of miles away and potentially maneuvering in ways that could challenge Ukraine's already strained air defenses, a defense ******* yst warned Monday.
The warning comes as Ukrainian military officials said that Russia could conduct the test in the coming months and potentially in live-fire strikes.
"According to our estimates, Russia plans to conduct final tests of a new type of ballistic missile with a range of up to 800 km by the end of this year," Vadym Skibitskyi, deputy head of the Defence Intelligence of Ukraine (DIU), said at a meeting of the Ukraine-NATO Interparliamentary Council, according to Ukrainian news outlet Ukrainska Pravda.
"If, for instance, this 800-kilometer missile has more advanced maneuverability, well then that's going to create greater problems for Ukraine in that they're going to need the more sophisticated interceptors to get them," Tom Karako, director of the Missile Defense Project at the Center for Strategic and International Studies, told Fox News Digital.
Russia Deploys North Korean Missile Unit To Ukraine; Moscow-pyongyang Axis Deepens: Report
#ukrainian #defense #ballistic
The warning comes as Ukrainian military officials said that Russia could conduct the test in the coming months and potentially in live-fire strikes.
"According to our estimates, Russia plans to conduct final tests of a new type of ballistic missile with a range of up to 800 km by the end of this year," Vadym Skibitskyi, deputy head of the Defence Intelligence of Ukraine (DIU), said at a meeting of the Ukraine-NATO Interparliamentary Council, according to Ukrainian news outlet Ukrainska Pravda.
"If, for instance, this 800-kilometer missile has more advanced maneuverability, well then that's going to create greater problems for Ukraine in that they're going to need the more sophisticated interceptors to get them," Tom Karako, director of the Missile Defense Project at the Center for Strategic and International Studies, told Fox News Digital.
Russia Deploys North Korean Missile Unit To Ukraine; Moscow-pyongyang Axis Deepens: Report
#ukrainian #defense #ballistic


1 day ago
For much of the past year, the "AI trade" has been focused on infrastructure: processors, data centers, and cloud capacity. Snowflake Inc. (NYSE:SNOW)'s blowout quarter, which was reported after the market closed on September 2, provided something unique: clear evidence that AI is translating into real, incremental spending within software companies that are closer to the end customer. The reaction echoed throughout corporate software the next morning, adding to a rally that, for Salesforce, Inc. (NYSE:CRM) in particular, had already begun for its own reasons.
Snowflake Inc. (NYSE:SNOW) boosted its fiscal 2027 product revenues target to $6.07 billion from $5.84 billion, following a 37% increase in second-quarter product revenue to $1.49 billion. CEO Sridhar Ramaswamy stated that the company's AI products accounted for around half of that growth acceleration, which ****** ysts took as implying that AI demand is increasing Snowflake's core data platform, instead of just adoption of standalone AI add-ons. UBS ****** yst Karl Keirstead said the figures, together with Palantir and Databricks' rapid growth, gave compelling proof of robust enterprise AI adoption.
Snowflake's beat rippled across enterprise software, with ServiceNow, Atlassian, Adobe, Intuit, and Salesforce, Inc. (NYSE:CRM) all up 3.5% to 6% on the same day, while the sector-wide iShares Expanded Tech-Software ETF rose 3%.
That Snowflake-driven spike was piled on top of a much bigger adjustment made by Salesforce, Inc. (NYSE:CRM) on its own. The company released its second-quarter fiscal 2027 results on August 26, a week before Snowflake Inc. (NYSE:SNOW), with revenue of $11.35 billion, up 11% year-over-year, with current remaining performance obligations up 14% to $33.5 billion and adjusted EPS of $5.90, exceeding the $3.27 consensus. Along with those results, Salesforce and Anthropic announced Claudeforce, an expanded partnership that initially brings Salesforce data, workflows and business logic directly into Claude through a plugin with 37 prebuilt sales skills. The companies plan additional integrations across Claude, Salesforce and Slack. That said, Salesforce recorded $2.61 billion in net gains on strategic investments during the quarter, which added $2.53 per share to non-GAAP EPS.
Taken together, the two events suggest that enterprise AI adoption can increase the value and consumption of established software platforms when AI is connected to existing corporate data and workflows
#billion #software #data #quarter
Snowflake Inc. (NYSE:SNOW) boosted its fiscal 2027 product revenues target to $6.07 billion from $5.84 billion, following a 37% increase in second-quarter product revenue to $1.49 billion. CEO Sridhar Ramaswamy stated that the company's AI products accounted for around half of that growth acceleration, which ****** ysts took as implying that AI demand is increasing Snowflake's core data platform, instead of just adoption of standalone AI add-ons. UBS ****** yst Karl Keirstead said the figures, together with Palantir and Databricks' rapid growth, gave compelling proof of robust enterprise AI adoption.
Snowflake's beat rippled across enterprise software, with ServiceNow, Atlassian, Adobe, Intuit, and Salesforce, Inc. (NYSE:CRM) all up 3.5% to 6% on the same day, while the sector-wide iShares Expanded Tech-Software ETF rose 3%.
That Snowflake-driven spike was piled on top of a much bigger adjustment made by Salesforce, Inc. (NYSE:CRM) on its own. The company released its second-quarter fiscal 2027 results on August 26, a week before Snowflake Inc. (NYSE:SNOW), with revenue of $11.35 billion, up 11% year-over-year, with current remaining performance obligations up 14% to $33.5 billion and adjusted EPS of $5.90, exceeding the $3.27 consensus. Along with those results, Salesforce and Anthropic announced Claudeforce, an expanded partnership that initially brings Salesforce data, workflows and business logic directly into Claude through a plugin with 37 prebuilt sales skills. The companies plan additional integrations across Claude, Salesforce and Slack. That said, Salesforce recorded $2.61 billion in net gains on strategic investments during the quarter, which added $2.53 per share to non-GAAP EPS.
Taken together, the two events suggest that enterprise AI adoption can increase the value and consumption of established software platforms when AI is connected to existing corporate data and workflows
#billion #software #data #quarter

1 day ago
On August 10, Red Violet Inc. (NASDAQ:RDVT) reported second-quarter 2026 results for the period ended June 30 that showed the company converting growth into profit at an accelerating clip. Revenue rose 23% to $26.7 million, and net income nearly doubled to $5 million. For a company built on selling identity intelligence to businesses, watching net margin move from 12% to 19% says that growth is not costing more to produce.
Gross profit climbed 29% to $20.2 million, pushing gross margin to 76% from 72%, while adjusted EBITDA jumped 48% to $11.2 million as its margin widened to 42% from 35%. Adjusted net income rose 58% to $7.2 million. Cash generation told the same story: operating cash flow increased 42% to a record $10.6 million for the quarter. None of that came from adding customers who barely move the needle. Red Violet signed on 447 new IDI customers in the quarter, a company record, ending with 10,869 customers on the platform.
FOREWARN, its product built for real estate agents, picked up 25,493 new users to reach 443,173, and 660 REALTOR ****** ociations across the country are now under contract to use it. The company also closed an underwritten public offering in August that sold 1,916,667 shares, including 250,000 shares from the underwriters' full exercise of their option, generating net proceeds of about $109.0 million. Between the funds already on hand and this new raise, Red Violet says it holds over $160 million in cash and carries no debt, money earmarked for working capital and possible acquisitions.
CEO Derek Dubner called it what he described as "the strongest pipeline of strategic initiatives" in the company's history. The company also repurchased 74,500 shares by June 30, paying $41.87 per share on average, and had $15.5 million left on its buyback authorization.
The August offering that padded Red Violet's cash balance also added 1,916,667 new shares to the count, arriving in the same year that per-share profit is climbing fastest. Diluted earnings came in a penny below basic at $0.34, and adjusted diluted earnings landed at $0.50 versus $0.51 on a basic basis, a gap new shares will only widen going forward. There is also a timing tension worth sitting with: Red Violet spent part of the quarter buying back its own stock at an average of $41.87 a share, then turned around weeks later and sold new shares to the public.
#million
Gross profit climbed 29% to $20.2 million, pushing gross margin to 76% from 72%, while adjusted EBITDA jumped 48% to $11.2 million as its margin widened to 42% from 35%. Adjusted net income rose 58% to $7.2 million. Cash generation told the same story: operating cash flow increased 42% to a record $10.6 million for the quarter. None of that came from adding customers who barely move the needle. Red Violet signed on 447 new IDI customers in the quarter, a company record, ending with 10,869 customers on the platform.
FOREWARN, its product built for real estate agents, picked up 25,493 new users to reach 443,173, and 660 REALTOR ****** ociations across the country are now under contract to use it. The company also closed an underwritten public offering in August that sold 1,916,667 shares, including 250,000 shares from the underwriters' full exercise of their option, generating net proceeds of about $109.0 million. Between the funds already on hand and this new raise, Red Violet says it holds over $160 million in cash and carries no debt, money earmarked for working capital and possible acquisitions.
CEO Derek Dubner called it what he described as "the strongest pipeline of strategic initiatives" in the company's history. The company also repurchased 74,500 shares by June 30, paying $41.87 per share on average, and had $15.5 million left on its buyback authorization.
The August offering that padded Red Violet's cash balance also added 1,916,667 new shares to the count, arriving in the same year that per-share profit is climbing fastest. Diluted earnings came in a penny below basic at $0.34, and adjusted diluted earnings landed at $0.50 versus $0.51 on a basic basis, a gap new shares will only widen going forward. There is also a timing tension worth sitting with: Red Violet spent part of the quarter buying back its own stock at an average of $41.87 a share, then turned around weeks later and sold new shares to the public.
#million

1 day ago
On September 10, LightPath Technologies (NASDAQ:LPTH) reported fiscal fourth-quarter and full-year results that turned a multiyear strategic bet into a financial statement. Revenue nearly doubled for the year, margins expanded, and the company walked away from its last manufacturing ties to China. For a small-cap optics supplier that spent years explaining a strategy, this was the quarter the strategy started explaining itself.
Annual revenue climbed 92.7% to $71.7 million from $37.2 million, and the fourth quarter alone hit a record $21.2 million, up 73.8% year over year. That growth is not just volume. Full-year gross margin expanded to 36% from 27.2%, and the fourth quarter came in even higher at 39.4%, because ****** emblies, modules and cameras now make up 44% of annual sales instead of being sold as raw components.
CEO Sam Rubin said the shift reflects both a change in what LightPath sells and better execution on what it already made, noting every one of its four product groups improved margin for the year. Backlog finished at $110.9 million, up 197% from $37.4 million a year earlier, with $85.6 million of it scheduled for delivery within 12 months. Weeks after the fiscal year closed, the company booked another $24 million in counter-UAS orders, and some of those programs have already moved to monthly delivery cadences of tens of units.
LightPath also completed its exit from China, selling its subsidiary there for $4.5 million paid out over five years, leaving the company with no manufacturing footprint in a country that increasingly can't supply the defense primes it depends on. That matters because defense programs face a deadline this decade to source optics away from covered nations, and qualification cycles run two to three years, meaning the sourcing decisions being made now will determine who wins contracts in 2029 and 2030.
The company's fourth-quarter net loss narrowed to $4.1 million from $7.1 million a year earlier, but full-year operating expenses jumped to $45.5 million from $22 million, and $15.6 million of that was a noncash charge tied to G5 Infrared outperforming the earnout targets set at acquisition. Management called that charge mostly behind the business now that the final G5 payout has been accrued for January 2027, but it is a reminder that acquisition accounting can swing the income statement even when operations are healthy.
#year #quarter #China
Annual revenue climbed 92.7% to $71.7 million from $37.2 million, and the fourth quarter alone hit a record $21.2 million, up 73.8% year over year. That growth is not just volume. Full-year gross margin expanded to 36% from 27.2%, and the fourth quarter came in even higher at 39.4%, because ****** emblies, modules and cameras now make up 44% of annual sales instead of being sold as raw components.
CEO Sam Rubin said the shift reflects both a change in what LightPath sells and better execution on what it already made, noting every one of its four product groups improved margin for the year. Backlog finished at $110.9 million, up 197% from $37.4 million a year earlier, with $85.6 million of it scheduled for delivery within 12 months. Weeks after the fiscal year closed, the company booked another $24 million in counter-UAS orders, and some of those programs have already moved to monthly delivery cadences of tens of units.
LightPath also completed its exit from China, selling its subsidiary there for $4.5 million paid out over five years, leaving the company with no manufacturing footprint in a country that increasingly can't supply the defense primes it depends on. That matters because defense programs face a deadline this decade to source optics away from covered nations, and qualification cycles run two to three years, meaning the sourcing decisions being made now will determine who wins contracts in 2029 and 2030.
The company's fourth-quarter net loss narrowed to $4.1 million from $7.1 million a year earlier, but full-year operating expenses jumped to $45.5 million from $22 million, and $15.6 million of that was a noncash charge tied to G5 Infrared outperforming the earnout targets set at acquisition. Management called that charge mostly behind the business now that the final G5 payout has been accrued for January 2027, but it is a reminder that acquisition accounting can swing the income statement even when operations are healthy.
#year #quarter #China

1 day ago
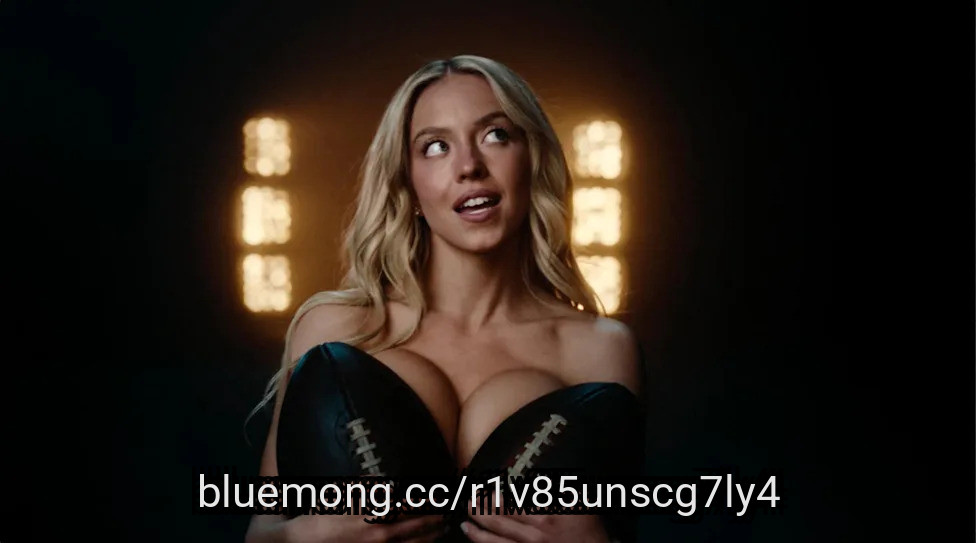
After days of facing backlash from sports fans for her nearly nude Novig ad, Sydney Sweeney is now facing backlash from proper female athletes, calling on the actress to "do better."
The ad spot, released last Wednesday, sees Sweeney strip down to virtually nothing, strategically covering herself with various pieces of sports equipment. Novig is a new sports trading and betting app, and in the ad, Sweeney notes that Novig is just sports: "No betting on wars or deaths and no politics," she says, "just you, your takes and sports."
"I don't know wtf Sydney Sweeney was doing, but it's 2026," British athlete Lucy Davis wrote in a post to Instagram. "Stop **** ualizing women in sport."
"We've got to always think about those young girls, always," she added in the caption.
The Novig ad criticism comes after the actress' American Eagle jeans ad went viral last year. Many called out the phrasing of "Sydney Sweeney has great jeans" as a play on "genes," and called it a promotion of eugenics.
#backlash
The ad spot, released last Wednesday, sees Sweeney strip down to virtually nothing, strategically covering herself with various pieces of sports equipment. Novig is a new sports trading and betting app, and in the ad, Sweeney notes that Novig is just sports: "No betting on wars or deaths and no politics," she says, "just you, your takes and sports."
"I don't know wtf Sydney Sweeney was doing, but it's 2026," British athlete Lucy Davis wrote in a post to Instagram. "Stop **** ualizing women in sport."
"We've got to always think about those young girls, always," she added in the caption.
The Novig ad criticism comes after the actress' American Eagle jeans ad went viral last year. Many called out the phrasing of "Sydney Sweeney has great jeans" as a play on "genes," and called it a promotion of eugenics.
#backlash


1 day ago
Vale S.A. (NYSE:VALE) is considering making its debut in China's domestic bond market as soon as this year, with CFO Marcelo Bacci saying the company is preparing for a potential Panda bond issuance. The move would be strategically significant because China accounts for roughly half of Vale's revenue, making renminbi financing a natural extension of its relationship with its largest market. Bloomberg reported that Vale is still ****** sing the market, including whether it can obtain a maturity longer than the typical two-, three-, or five-year terms available to international issuers.
The timing is also favorable for Vale because China's Panda bond market is expanding rapidly. Reuters reported that foreign issuers have increasingly turned to Asian bond markets to diversify funding sources, while Chinese yuan bond issuance has reached record levels in 2026. For Vale S.A. (NYSE:VALE), the potential transaction therefore looks less like a necessity for raising capital and more like an effort to diversify its investor base, potentially lower funding costs, and build a longer-term financing relationship with Chinese investors.
The strongest bullish argument is that Vale S.A. (NYSE:VALE) could potentially lower and diversify its cost of capital by accessing a large pool of Chinese investors at a time when renminbi funding remains relatively inexpensive. Reuters noted that Chinese onshore and offshore yuan bond markets have experienced record issuance this year, with foreign borrowers increasingly using these markets to diversify away from traditional funding currencies. If Vale can achieve competitive pricing, a Panda bond could provide an additional funding channel alongside its established dollar financing, reducing its dependence on a single market.
The move could also create a better natural match between Vale's revenues and its financing currency. Because China represents approximately half of Vale's revenue, raising at least some debt in renminbi could provide a degree of currency alignment with its Chinese business exposure. More importantly, establishing itself as a repeat issuer could strengthen Vale's relationships with Chinese banks and institutional investors, potentially giving it access to another source of capital when global dollar markets become less attractive.
There is also a broader strategic benefit. China is actively expanding the Panda bond market and encouraging international companies to use it. Official Chinese data showed that more than 160 billion yuan of Panda bonds were issued during the first half of 2026, up 69% year over year, demonstrating that the market is becoming more established and liquid. Vale entering this market could therefore position the company early in a growing financing ecosystem rather than waiting until it becomes more crowded.
#chinese #bond #panda #China
The timing is also favorable for Vale because China's Panda bond market is expanding rapidly. Reuters reported that foreign issuers have increasingly turned to Asian bond markets to diversify funding sources, while Chinese yuan bond issuance has reached record levels in 2026. For Vale S.A. (NYSE:VALE), the potential transaction therefore looks less like a necessity for raising capital and more like an effort to diversify its investor base, potentially lower funding costs, and build a longer-term financing relationship with Chinese investors.
The strongest bullish argument is that Vale S.A. (NYSE:VALE) could potentially lower and diversify its cost of capital by accessing a large pool of Chinese investors at a time when renminbi funding remains relatively inexpensive. Reuters noted that Chinese onshore and offshore yuan bond markets have experienced record issuance this year, with foreign borrowers increasingly using these markets to diversify away from traditional funding currencies. If Vale can achieve competitive pricing, a Panda bond could provide an additional funding channel alongside its established dollar financing, reducing its dependence on a single market.
The move could also create a better natural match between Vale's revenues and its financing currency. Because China represents approximately half of Vale's revenue, raising at least some debt in renminbi could provide a degree of currency alignment with its Chinese business exposure. More importantly, establishing itself as a repeat issuer could strengthen Vale's relationships with Chinese banks and institutional investors, potentially giving it access to another source of capital when global dollar markets become less attractive.
There is also a broader strategic benefit. China is actively expanding the Panda bond market and encouraging international companies to use it. Official Chinese data showed that more than 160 billion yuan of Panda bonds were issued during the first half of 2026, up 69% year over year, demonstrating that the market is becoming more established and liquid. Vale entering this market could therefore position the company early in a growing financing ecosystem rather than waiting until it becomes more crowded.
#chinese #bond #panda #China

1 day ago
The Cooper Companies, Inc. (NASDAQ:COO) cut its fiscal 2026 profit and revenue forecasts after weaker-than-expected demand for contact lenses weighed on its CooperVision business. The company now expects adjusted earnings of $4.51–$4.55 per share, down from its previous forecast of $4.58–$4.66, while revenue guidance was reduced to $4.23–$4.25 billion from $4.29–$4.32 billion. Third-quarter revenue came in at $1.07 billion, below Wall Street's $1.10 billion estimate, although adjusted EPS of $1.15 beat expectations.
The weakness was concentrated in CooperVision, where revenue fell to $717 million. Cooper said a reduction in U.S. channel inventory hurt results and is expected to continue affecting the fourth quarter. At the same time, the company completed its strategic review and decided to retain CooperSurgical rather than sell the business.
The biggest bullish argument is that some of the current weakness may be temporary rather than a fundamental deterioration in the contact lens market. The Cooper Companies, Inc. (NASDAQ:COO) specifically pointed to U.S. channel inventory reductions, meaning part of the sales pressure reflects distributors and customers working through existing stock rather than consumers permanently abandoning contact lenses. If inventories normalize, CooperVision could see a recovery in sales growth.
Cooper also continues to have a strong position in the global contact lens market. The company is investing in new products, expanding CooperVision's sales and marketing organization and improving inventory and logistics operations. Its strategic review also identified opportunities to reduce costs and improve operational efficiency.
There are encouraging signs beneath the weak headline numbers. Adjusted third-quarter EPS still increased 4% year over year to $1.15, while free cash flow jumped 66% to $273 million. The Cooper Companies, Inc. (NASDAQ:COO) also increased its share-repurchase authorization from $2 billion to $3 billion, giving the company another way to support per-share earnings if the stock remains depressed.
#Companies #revenue #contact #coopervision
The weakness was concentrated in CooperVision, where revenue fell to $717 million. Cooper said a reduction in U.S. channel inventory hurt results and is expected to continue affecting the fourth quarter. At the same time, the company completed its strategic review and decided to retain CooperSurgical rather than sell the business.
The biggest bullish argument is that some of the current weakness may be temporary rather than a fundamental deterioration in the contact lens market. The Cooper Companies, Inc. (NASDAQ:COO) specifically pointed to U.S. channel inventory reductions, meaning part of the sales pressure reflects distributors and customers working through existing stock rather than consumers permanently abandoning contact lenses. If inventories normalize, CooperVision could see a recovery in sales growth.
Cooper also continues to have a strong position in the global contact lens market. The company is investing in new products, expanding CooperVision's sales and marketing organization and improving inventory and logistics operations. Its strategic review also identified opportunities to reduce costs and improve operational efficiency.
There are encouraging signs beneath the weak headline numbers. Adjusted third-quarter EPS still increased 4% year over year to $1.15, while free cash flow jumped 66% to $273 million. The Cooper Companies, Inc. (NASDAQ:COO) also increased its share-repurchase authorization from $2 billion to $3 billion, giving the company another way to support per-share earnings if the stock remains depressed.
#Companies #revenue #contact #coopervision


1 day ago
HSBC Holdings plc (NYSE:HSBC) is winding down its transaction services business in Germany, with more than 300 positions at HSBC Transaction Services GmbH and HSBC Service Company Germany GmbH expected to be phased out by 2028. The division provides securities processing, administration and custody services.
HSBC said the move is part of its broader strategy to strengthen its position in businesses where it has competitive advantages and sees stronger growth opportunities. The decision follows HSBC Germany's sale of its private banking business to BNP Paribas last year, highlighting the bank's continued effort to streamline its European operations.
Northfoto/Shutterstock.com
The biggest positive for HSBC Holdings plc (NYSE:HSBC) is that the German exit could improve the bank's efficiency and profitability over time. Rather than continuing to allocate capital and employees to a transaction-services operation that HSBC apparently sees as less strategically attractive, the bank can redirect resources toward areas where it has stronger competitive advantages. This fits CEO Georges Elhedery's broader restructuring strategy of reducing complexity, cutting costs and concentrating HSBC on businesses with better growth prospects. Reuters has reported that HSBC has already been selling non-core operations as part of this transformation, while its shares have risen substantially since the restructuring began.
The timing could also be constructive. Germany's economy remains under pressure, with industrial production falling unexpectedly in July and manufacturing activity still facing significant challenges. Reducing exposure to a business tied to the German market could therefore protect HSBC Holdings plc (NYSE:HSBC) from maintaining costs in an environment where growth is relatively weak.
#german
HSBC said the move is part of its broader strategy to strengthen its position in businesses where it has competitive advantages and sees stronger growth opportunities. The decision follows HSBC Germany's sale of its private banking business to BNP Paribas last year, highlighting the bank's continued effort to streamline its European operations.
Northfoto/Shutterstock.com
The biggest positive for HSBC Holdings plc (NYSE:HSBC) is that the German exit could improve the bank's efficiency and profitability over time. Rather than continuing to allocate capital and employees to a transaction-services operation that HSBC apparently sees as less strategically attractive, the bank can redirect resources toward areas where it has stronger competitive advantages. This fits CEO Georges Elhedery's broader restructuring strategy of reducing complexity, cutting costs and concentrating HSBC on businesses with better growth prospects. Reuters has reported that HSBC has already been selling non-core operations as part of this transformation, while its shares have risen substantially since the restructuring began.
The timing could also be constructive. Germany's economy remains under pressure, with industrial production falling unexpectedly in July and manufacturing activity still facing significant challenges. Reducing exposure to a business tied to the German market could therefore protect HSBC Holdings plc (NYSE:HSBC) from maintaining costs in an environment where growth is relatively weak.
#german


1 day ago
Howmet Aerospace Inc. (NYSE:HWM) is facing a mixed outlook after GE Aerospace agreed to acquire Consolidated Precision Products (CPP) for about $11.75 billion to secure more control over critical engine castings and expand production capacity. The announcement initially hit Howmet shares, which fell about 10%, as investors worried that GE could eventually rely less on outside suppliers such as Howmet.
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial



2 days ago
Dow Inc. (NYSE:DOW) is reportedly considering selling its 35% stake in Sadara Chemical, its $20 billion chemicals joint venture with Saudi Aramco, as the company continues to reshape its portfolio amid a prolonged downturn in the global chemicals industry. No final decision has been made, and Aramco or another strategic or financial investor could potentially acquire Dow's stake.
The potential exit comes as Sadara has become a significant financial burden for Dow. As of June 30, Dow Inc. (NYSE:DOW) had a negative investment balance of $793 million in Sadara and had suspended recognition of its share of the venture's equity losses in the first quarter. Dow has also been exposed to Sadara's financing obligations and previously disclosed that the venture had drawn on a credit facility.
At the same time, Sadara remains a major industrial ****** et, operating a complex in Jubail with more than 3 million metric tons of annual chemicals and plastics capacity. Its operations were disrupted earlier this year by the Middle East conflict, adding transportation, supply-chain, and operating pressures to an industry already dealing with weak demand and global oversupply.
The strongest argument for Dow Inc. (NYSE:DOW) is that exiting Sadara could remove a persistent drag on cash flow and allow management to redirect capital toward businesses with better returns. Dow's exposure to Sadara is no longer simply an investment in a large Saudi chemicals complex; the company has accumulated a negative investment balance and financial obligations ****** ociated with the venture. A sale could therefore reduce Dow's exposure to future funding requirements and limit the amount of capital that could otherwise have to be committed to the partnership.
That would be particularly valuable because Dow is already trying to improve its cash generation. Management has said its objective is to reach free-cash-flow breakeven while pursuing significant cost reductions. In March, CEO Jim Fitterling said Dow's goal was to avoid putting additional cash into Sadara during 2026, while describing the venture as having low operating cash costs but more challenging fixed costs and financing obligations.
#chemicals
The potential exit comes as Sadara has become a significant financial burden for Dow. As of June 30, Dow Inc. (NYSE:DOW) had a negative investment balance of $793 million in Sadara and had suspended recognition of its share of the venture's equity losses in the first quarter. Dow has also been exposed to Sadara's financing obligations and previously disclosed that the venture had drawn on a credit facility.
At the same time, Sadara remains a major industrial ****** et, operating a complex in Jubail with more than 3 million metric tons of annual chemicals and plastics capacity. Its operations were disrupted earlier this year by the Middle East conflict, adding transportation, supply-chain, and operating pressures to an industry already dealing with weak demand and global oversupply.
The strongest argument for Dow Inc. (NYSE:DOW) is that exiting Sadara could remove a persistent drag on cash flow and allow management to redirect capital toward businesses with better returns. Dow's exposure to Sadara is no longer simply an investment in a large Saudi chemicals complex; the company has accumulated a negative investment balance and financial obligations ****** ociated with the venture. A sale could therefore reduce Dow's exposure to future funding requirements and limit the amount of capital that could otherwise have to be committed to the partnership.
That would be particularly valuable because Dow is already trying to improve its cash generation. Management has said its objective is to reach free-cash-flow breakeven while pursuing significant cost reductions. In March, CEO Jim Fitterling said Dow's goal was to avoid putting additional cash into Sadara during 2026, while describing the venture as having low operating cash costs but more challenging fixed costs and financing obligations.
#chemicals


2 days ago
Sydney Sweeney has come under fire for another advertising campaign.
The Euphoria actor has teamed up with Novig, a new platform that combines sports trading with prediction-market features and is restricted to users aged 21 and above.
But the conversation isn't about the platform, which she is the new strategic partner and equity holder for. Instead, the marketing campaign has sparked a debate about how women are represented in sports.
The minute-long ad, ****** led "Just Sports," features the Christy actress posing in nothing but strategically placed footballs, basketball hoops, hockey pads, and a pool cue. The concept is that the platform focuses on sports and nothing else.
Marissa Womack, manager of game day promotions for the Harrisburg Senators, addressed the video and its backlash in a TikTok video: "This isn't about me being jealous or insecure. It's about the fact that this is already a male-dominated field where we constantly have to prove we belong. When the only representation is ****** ualization, you see fewer and fewer young women wanting to pursue this industry."
#sports #platform #nothing
The Euphoria actor has teamed up with Novig, a new platform that combines sports trading with prediction-market features and is restricted to users aged 21 and above.
But the conversation isn't about the platform, which she is the new strategic partner and equity holder for. Instead, the marketing campaign has sparked a debate about how women are represented in sports.
The minute-long ad, ****** led "Just Sports," features the Christy actress posing in nothing but strategically placed footballs, basketball hoops, hockey pads, and a pool cue. The concept is that the platform focuses on sports and nothing else.
Marissa Womack, manager of game day promotions for the Harrisburg Senators, addressed the video and its backlash in a TikTok video: "This isn't about me being jealous or insecure. It's about the fact that this is already a male-dominated field where we constantly have to prove we belong. When the only representation is ****** ualization, you see fewer and fewer young women wanting to pursue this industry."
#sports #platform #nothing

2 days ago
Sydney Sweeney's latest ad campaign has landed very differently with some of the women who have spent their lives competing in sports.
Four-time Olympic gold medalist Ariarne ***** mus is among a growing group of athletes criticizing Sweeney's new "Just Sports" campaign for Novig, a sports prediction market. The campaign shows Sweeney nude or minimally dressed while footballs, basketballs, hockey equipment and other sports gear strategically cover her body.
Athletes including former UCLA gymnast Gracie Kramer, Olympic swimmer Lani Pallister, British sprinter Amy Hunt and water polo Olympian Tilly Kearns have responded by putting competition, training and athletic achievement back at the center of their own posts.
Sweeney is more closely tied to the campaign than a typical celebrity spokesperson. Novig announced that she joined the company as a strategic partner and equity holder, while Sweeney said she had participated in the creative process from the beginning.
The four-time Olympic champion, who retired from competitive swimming in 2025, wrote on Instagram that she had believed this kind of marketing belonged in the past.
#four
Four-time Olympic gold medalist Ariarne ***** mus is among a growing group of athletes criticizing Sweeney's new "Just Sports" campaign for Novig, a sports prediction market. The campaign shows Sweeney nude or minimally dressed while footballs, basketballs, hockey equipment and other sports gear strategically cover her body.
Athletes including former UCLA gymnast Gracie Kramer, Olympic swimmer Lani Pallister, British sprinter Amy Hunt and water polo Olympian Tilly Kearns have responded by putting competition, training and athletic achievement back at the center of their own posts.
Sweeney is more closely tied to the campaign than a typical celebrity spokesperson. Novig announced that she joined the company as a strategic partner and equity holder, while Sweeney said she had participated in the creative process from the beginning.
The four-time Olympic champion, who retired from competitive swimming in 2025, wrote on Instagram that she had believed this kind of marketing belonged in the past.
#four

2 days ago
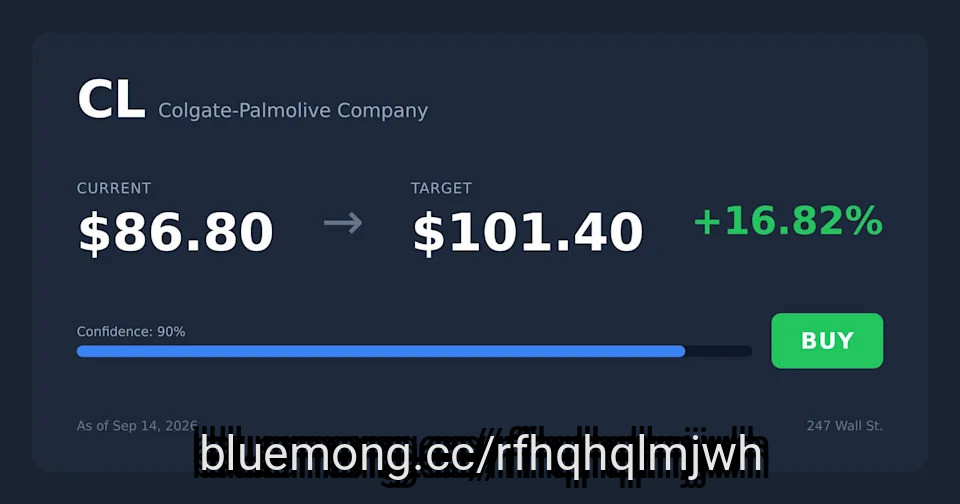
Colgate-Palmolive (CL) hired Goldman Sachs to explore selling Softsoap, Irish Spring, and Speed Stick as North America revenue fell 3% in Q2 2026.
Private equity leads as the likeliest buyer, with every named strategic acquirer blocked by scale gaps, leverage limits, or an active acquisition lock-up.
The real test is whether shedding mature brands resolves Colgate's self-described long-term North America turnaround or simply makes the company smaller.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Colgate-Palmolive didn't make the cut. Enter your email to see the names that beat CL. The report is free. Enter your email and see if any of your stocks made the cut.
Colgate-Palmolive (NYSE:CL) is reportedly shopping a slice of its portfolio that many investors forgot it still owned. Reuters reported on Friday, September 11, 2026, citing unnamed sources, that Colgate is exploring a sale of Softsoap, Irish Spring, and Speed Stick and has hired Goldman Sachs to run the process.
#palmolive #goldman #irish
Private equity leads as the likeliest buyer, with every named strategic acquirer blocked by scale gaps, leverage limits, or an active acquisition lock-up.
The real test is whether shedding mature brands resolves Colgate's self-described long-term North America turnaround or simply makes the company smaller.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Colgate-Palmolive didn't make the cut. Enter your email to see the names that beat CL. The report is free. Enter your email and see if any of your stocks made the cut.
Colgate-Palmolive (NYSE:CL) is reportedly shopping a slice of its portfolio that many investors forgot it still owned. Reuters reported on Friday, September 11, 2026, citing unnamed sources, that Colgate is exploring a sale of Softsoap, Irish Spring, and Speed Stick and has hired Goldman Sachs to run the process.
#palmolive #goldman #irish

3 days ago
Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) could be positioning itself for its next major phase of growth following its roughly $10 billion acquisition of Crinetics Pharmaceuticals. The deal gives the company immediate exposure to the endocrinology market and provides a new commercial platform beyond its established cystic fibrosis franchise.
On September 3, Citigroup **** yst Geoff Meacham highlighted the strategic importance of the Crinetics acquisition, arguing it could diversify Vertex's business while complementing its existing cystic fibrosis franchise and newer businesses in renal disease, hematology, and pain.
Through the transaction, Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) gains access to Palsonify (paltusotine), an oral treatment for acromegaly that has already received regulatory approval in Europe. Paltusotine is also in Phase 3 development for carcinoid syndrome **** ociated with neuroendocrine tumors.
Palsonify is particularly important because it provides an immediate commercial revenue opportunity, rather than requiring the company to wait several years for an entirely new drug to reach the market.
Early uptake of Palsonify has been encouraging, supported by expanding physician adoption and improving reimbursement coverage. If that momentum continues, the drug could become an important contributor to Vertex's revenue growth.
#palsonify
On September 3, Citigroup **** yst Geoff Meacham highlighted the strategic importance of the Crinetics acquisition, arguing it could diversify Vertex's business while complementing its existing cystic fibrosis franchise and newer businesses in renal disease, hematology, and pain.
Through the transaction, Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) gains access to Palsonify (paltusotine), an oral treatment for acromegaly that has already received regulatory approval in Europe. Paltusotine is also in Phase 3 development for carcinoid syndrome **** ociated with neuroendocrine tumors.
Palsonify is particularly important because it provides an immediate commercial revenue opportunity, rather than requiring the company to wait several years for an entirely new drug to reach the market.
Early uptake of Palsonify has been encouraging, supported by expanding physician adoption and improving reimbursement coverage. If that momentum continues, the drug could become an important contributor to Vertex's revenue growth.
#palsonify


3 days ago
LONDON, Sept 11 (Reuters) - Intelligence services must not dwell too much on past threats but accept that a new strategic shock along the lines of the 9/11 attacks could already be in preparation where they are not looking, the head of Britain's MI5 spy agency said.
In an opinion piece published on Friday to mark 25 years since al Qaeda militants crashed hijacked passenger jets into the World Trade Center in New York and the Pentagon, MI5's Director General Ken McCallum said security agencies had to be ready to adapt to current and future challenges.
"We know that the next strategic shock will, by definition, not resemble the last one. That is perhaps the most important lesson of all," McCallum wrote in the commentary for the Independent newspaper.
"We must of course always learn from the last attack – but must beware of preparing brilliantly to fight yesterday's enemy, using yesterday's methods, against yesterday's target ... The uncomfortable truth is that the next strategic shock may already be taking shape somewhere we are not yet looking."
Al Qaeda, though diminished, remains a threat, as does the aspiration of that group and other militants for mass casualty attacks, McCallum said.
#next
In an opinion piece published on Friday to mark 25 years since al Qaeda militants crashed hijacked passenger jets into the World Trade Center in New York and the Pentagon, MI5's Director General Ken McCallum said security agencies had to be ready to adapt to current and future challenges.
"We know that the next strategic shock will, by definition, not resemble the last one. That is perhaps the most important lesson of all," McCallum wrote in the commentary for the Independent newspaper.
"We must of course always learn from the last attack – but must beware of preparing brilliantly to fight yesterday's enemy, using yesterday's methods, against yesterday's target ... The uncomfortable truth is that the next strategic shock may already be taking shape somewhere we are not yet looking."
Al Qaeda, though diminished, remains a threat, as does the aspiration of that group and other militants for mass casualty attacks, McCallum said.
#next



3 days ago
SailPoint Inc. (NASDAQ:SAIL), a leading player within the enterprise identity security ***** e, released its fiscal second-quarter 2027 on September 9. The company registered a 25% growth in its annual recurring revenue compared to the same period last year, with figures of $1.231 billion. This was driven by a 36% expansion in SaaS ARR which clocked in at $847 million. SailPoint generated $45 million in operating cash flow during the quarter, along with $37 million in free cash flow.
Burben/Shutterstock.com
Topline for the quarter hit $309 million, exhibiting 17% growth compared to Q2 FY26, amid several underlying factors. The company's subscription revenue reached $295 million, up 19% from a year earlier. SaaS customer base increased by 16%, with net new SaaS ARR jumping 34% year-over-year. It contributed around 97% to overall net new ARR for the business, with AI-driven ARR crossing $70 million mark.
SailPoint's existing customer base showed highly encouraging trends in adopting the company's AI-enabled solutions, with a 60% increase in their annual spend during the second quarter. These solutions were incorporated within more than two-thirds of the completed migrations during the quarter. Quarterly adjusted operating income increased from $54 million a year prior to $63 million, translating into an adjusted margin of 20%.
The quarter also saw key strategic moves by the management. It introduced the SailPoint Identity Security solution, which integrates SailPoint Agentic Fabric with SailPoint Human Fabric to deliver a real-time cycle for discovering and securing intricate digital ecosystems. The company also launched its Cursor Enterprise connector, which enables enterprises to manage both autonomous AI agents and human developers through an integrated control plane.
#year #SaaS #fabric #identity
Burben/Shutterstock.com
Topline for the quarter hit $309 million, exhibiting 17% growth compared to Q2 FY26, amid several underlying factors. The company's subscription revenue reached $295 million, up 19% from a year earlier. SaaS customer base increased by 16%, with net new SaaS ARR jumping 34% year-over-year. It contributed around 97% to overall net new ARR for the business, with AI-driven ARR crossing $70 million mark.
SailPoint's existing customer base showed highly encouraging trends in adopting the company's AI-enabled solutions, with a 60% increase in their annual spend during the second quarter. These solutions were incorporated within more than two-thirds of the completed migrations during the quarter. Quarterly adjusted operating income increased from $54 million a year prior to $63 million, translating into an adjusted margin of 20%.
The quarter also saw key strategic moves by the management. It introduced the SailPoint Identity Security solution, which integrates SailPoint Agentic Fabric with SailPoint Human Fabric to deliver a real-time cycle for discovering and securing intricate digital ecosystems. The company also launched its Cursor Enterprise connector, which enables enterprises to manage both autonomous AI agents and human developers through an integrated control plane.
#year #SaaS #fabric #identity

3 days ago
On September 9, AeroVironment Inc. (NASDAQ:AVAV) revealed its Q1 FY27 results, posting its highest ever first quarter revenue. Topline figure of $480.5 million marked a 6% year-over-year growth, fueled by a $15.5 million jump in product sales and a $10.3 million expansion of service revenue. The company reported a book-to-bill ratio of 1.4, after total bookings for the quarter came in at $0.7 billion. Let's explore the underlying drivers of AeroVironment's impressive first quarter print.
Photo by NASA on Unsplash
The first quarter record topline figure reflects on strength across the underlying business lines. The Autonomous Systems (AxS) and the ***** e, Cyber and Directed Energy (SCDE) segments contributed $346 million and $134.5 million to the total revenue, respectively. The overall gross profit jumped 31% during the quarter to $124.6 million. This pushed gross margin to 26% from 21% posted a year earlier.
Adjusted diluted earnings per share for the first quarter almost doubled, from $0.32 in the same period last year to of $0.59 in the recently concluded quarter. The company also increased its funded backlog, which clocked in at $1.5 billion, compared to $1.2 billion recorded on April 30.
With a strong backlog position and landmark strategic wins, management upheld its full-year guidance, with topline figures estimated to land between $2.125 billion and $2.225 billion. It has forecasted an adjusted EBITDA ranging from $305 million to $325 million, along with diluted EPS between $3.02 and $3.34 on adjusted basis.
#million #quarter #billion #first
Photo by NASA on Unsplash
The first quarter record topline figure reflects on strength across the underlying business lines. The Autonomous Systems (AxS) and the ***** e, Cyber and Directed Energy (SCDE) segments contributed $346 million and $134.5 million to the total revenue, respectively. The overall gross profit jumped 31% during the quarter to $124.6 million. This pushed gross margin to 26% from 21% posted a year earlier.
Adjusted diluted earnings per share for the first quarter almost doubled, from $0.32 in the same period last year to of $0.59 in the recently concluded quarter. The company also increased its funded backlog, which clocked in at $1.5 billion, compared to $1.2 billion recorded on April 30.
With a strong backlog position and landmark strategic wins, management upheld its full-year guidance, with topline figures estimated to land between $2.125 billion and $2.225 billion. It has forecasted an adjusted EBITDA ranging from $305 million to $325 million, along with diluted EPS between $3.02 and $3.34 on adjusted basis.
#million #quarter #billion #first

3 days ago
NVIDIA Corporation (NASDAQ:NVDA) is expanding its global AI infrastructure ambitions, with Australia emerging as an important new market for its growing portfolio of GPUs, CPUs, networking products, and AI software.
On September 9, it announced strategic partnerships with Australian NVIDIA Cloud Partners (NCPs) and AI infrastructure providers as it works with local partners toward an AI infrastructure buildout of up to 2 gigawatts by 2027.
The initiative will expand the availability of land, power, and data center shell capacity designed to host multiple generations of Nvidia's DSX AI factory infrastructure. While the buildout is designed to meet Australia's growing demand for AI computing, it could also create a significant new source of demand for Nvidia's hardware and software ecosystem.
The Australian buildout could benefit NVIDIA Corporation (NASDAQ:NVDA) beyond the initial sale of GPUs. Nvidia will provide its DSX platform, accelerated computing, networking, software, and ecosystem support to the emerging network of AI factories. DSX is also compatible with Nvidia's CUDA ecosystem.
As enterprises, universities, government agencies, and startups increasingly build AI workloads around Nvidia's architecture, the company could strengthen CUDA's position as the underlying software platform for AI development and deployment.
#NASDAQ #australian
On September 9, it announced strategic partnerships with Australian NVIDIA Cloud Partners (NCPs) and AI infrastructure providers as it works with local partners toward an AI infrastructure buildout of up to 2 gigawatts by 2027.
The initiative will expand the availability of land, power, and data center shell capacity designed to host multiple generations of Nvidia's DSX AI factory infrastructure. While the buildout is designed to meet Australia's growing demand for AI computing, it could also create a significant new source of demand for Nvidia's hardware and software ecosystem.
The Australian buildout could benefit NVIDIA Corporation (NASDAQ:NVDA) beyond the initial sale of GPUs. Nvidia will provide its DSX platform, accelerated computing, networking, software, and ecosystem support to the emerging network of AI factories. DSX is also compatible with Nvidia's CUDA ecosystem.
As enterprises, universities, government agencies, and startups increasingly build AI workloads around Nvidia's architecture, the company could strengthen CUDA's position as the underlying software platform for AI development and deployment.
#NASDAQ #australian

3 days ago
The Iran-backed Houthi rebels in Yemen have taken control of a strategic Red Sea coastline, further complicating shipping routes in the region. At the same time, strikes inside Saudi Arabia forced the shutdown of a critical oil pipeline, the country's energy ministry confirmed.
#Iran #houthi #arabia #taken
#Iran #houthi #arabia #taken


4 days ago
The desperate pleas for air cover from Yemeni generals started coming mid-morning on Thursday. An advance by the Iran-backed Houthis toward Yemen's strategic port city of Mocha was in full swing, and backup support from chief ally Saudi Arabia was nowhere in sight.
"The Houthis committed everything they had – waves upon waves of fighters … along with their available ballistic missiles and weapons," a senior Yemeni source attached to their military forces told CNN. The source said he contacted the United States Central Command (CENTCOM) and was ******* ured the US was "watching the situation closely and that Saudi air support was coming."
"But the air support never came," the source said. "And Mocha has now fallen."
Hours later, on Friday, the Houthis captured another key coastal ******* et, Perim Island, at the mouth of the Red Sea. The island splits the Bab al-Mandeb Strait in two, giving Tehran de facto control over another key shipping route.
The Houthis' rapid advance amounts to an extraordinary 36 hours in a conflict that had been largely on ice for years. But the kindling for renewed fighting had been laid for months amid the conflict between the United States and Iran, as Tehran seeks to use oil prices – and their impact on the global economy – as leverage.
#saudi
"The Houthis committed everything they had – waves upon waves of fighters … along with their available ballistic missiles and weapons," a senior Yemeni source attached to their military forces told CNN. The source said he contacted the United States Central Command (CENTCOM) and was ******* ured the US was "watching the situation closely and that Saudi air support was coming."
"But the air support never came," the source said. "And Mocha has now fallen."
Hours later, on Friday, the Houthis captured another key coastal ******* et, Perim Island, at the mouth of the Red Sea. The island splits the Bab al-Mandeb Strait in two, giving Tehran de facto control over another key shipping route.
The Houthis' rapid advance amounts to an extraordinary 36 hours in a conflict that had been largely on ice for years. But the kindling for renewed fighting had been laid for months amid the conflict between the United States and Iran, as Tehran seeks to use oil prices – and their impact on the global economy – as leverage.
#saudi



4 days ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributed record-breaking results to a 'stellar' market environment where geopolitical tensions, specifically the closure of the Strait of Hormuz, have significantly increased ton-mile dislocation.
The company is executing a massive $3.1 billion fleet renewal program involving 26 newbuildings, with management noting that these ****** ets have already appreciated by approximately 30% since contracting.
Strategic positioning focuses on a 'balanced' model, using fixed-rate charters to cover all-in break-even costs while utilizing spot and profit-sharing contracts to capture market upside.
Management highlighted an unprecedented appetite from major oil companies, who are now seeking long-term charters of up to 7 years for vessels aged 10 years or younger.
#management #years #hormuz
Management attributed record-breaking results to a 'stellar' market environment where geopolitical tensions, specifically the closure of the Strait of Hormuz, have significantly increased ton-mile dislocation.
The company is executing a massive $3.1 billion fleet renewal program involving 26 newbuildings, with management noting that these ****** ets have already appreciated by approximately 30% since contracting.
Strategic positioning focuses on a 'balanced' model, using fixed-rate charters to cover all-in break-even costs while utilizing spot and profit-sharing contracts to capture market upside.
Management highlighted an unprecedented appetite from major oil companies, who are now seeking long-term charters of up to 7 years for vessels aged 10 years or younger.
#management #years #hormuz
4 days ago
Investors hammered Cooper Companies (COO) on Thursday after the medtech's fiscal third-quarter sales lagged Wall Street's expectations, leading to a guidance cut.
Specifically, the CooperVision segment — which sells contact lenses — missed expectations by 4.5%, William Blair **** yst Steven Lichtman said in a report. The miss was due to destocking. Further, the company opted against selling its CooperSurgical business following a strategic review.
"The 'no sale' is a surprise after management highlighted prospective buyers on the last earnings call," he said. "With CVI (CooperVision) results also disappointing, the stock moves back into the penalty box."
On today's stock market, Cooper Companies shares toppled 14.7%, closing at 54.17. Shares are already trading well below their key moving averages, IBD MarketSurge charts show.
Cooper said it couldn't sell the surgical division due to competition for its implantable contraceptive, Paragard, an intrauterine device. In June, Organon (OGN) licensed Miudella, a rival to Cooper's non-hormonal IUD. Cooper is also facing fertility litigation, BofA Securities **** yst Travis Steed said in a note to clients.
#Companies #expectations #investors #wall
Specifically, the CooperVision segment — which sells contact lenses — missed expectations by 4.5%, William Blair **** yst Steven Lichtman said in a report. The miss was due to destocking. Further, the company opted against selling its CooperSurgical business following a strategic review.
"The 'no sale' is a surprise after management highlighted prospective buyers on the last earnings call," he said. "With CVI (CooperVision) results also disappointing, the stock moves back into the penalty box."
On today's stock market, Cooper Companies shares toppled 14.7%, closing at 54.17. Shares are already trading well below their key moving averages, IBD MarketSurge charts show.
Cooper said it couldn't sell the surgical division due to competition for its implantable contraceptive, Paragard, an intrauterine device. In June, Organon (OGN) licensed Miudella, a rival to Cooper's non-hormonal IUD. Cooper is also facing fertility litigation, BofA Securities **** yst Travis Steed said in a note to clients.
#Companies #expectations #investors #wall

4 days ago
Zhihu Inc. (NYSE:ZH) disclosed on September 6 that a wholly owned subsidiary had signed a conditional RMB1.5 billion cash commitment to Tianjin Lisi Xingshen Equity Investment Partnership. The agreement, dated September 4, requires shareholder approval, with payments funded internally through capital calls.
Zhihu Inc. (NYSE:ZH) expects to hold no more than 30% of the fund and will have no role in daily management or individual investment decisions. The blind-pool structure asks shareholders to approve a manager and strategy before specific investments are identified. The fund targets early-to-mid-stage private AI and technology companies with significant mainland China connections.
The strategic rationale fits the company's existing capabilities. Zhihu Inc. (NYSE:ZH) is developing AI search, expert-data solutions and AI-enabled content businesses. Exposure to foundation models, infrastructure, robotics and applications could create technology partnerships and help identify emerging customer needs.
A specialist fund also supplies investment research, deal sourcing and portfolio oversight that would require substantial internal resources to replicate. For shareholders, the potential benefit combines investment returns with commercial opportunities for the core content platform. Any cooperation would still require separate **** sment and agreement.
There is an operating business to build around. Second-quarter paid content and intellectual-property operations revenue increased to RMB425.9 million from RMB408.2 million. Zhihu Inc. (NYSE:ZH) also reduced total operating expenses by 13% to RMB469.4 million. These results support a focused approach in which outside technology complements established content and expert relationships.
#content #technology #million
Zhihu Inc. (NYSE:ZH) expects to hold no more than 30% of the fund and will have no role in daily management or individual investment decisions. The blind-pool structure asks shareholders to approve a manager and strategy before specific investments are identified. The fund targets early-to-mid-stage private AI and technology companies with significant mainland China connections.
The strategic rationale fits the company's existing capabilities. Zhihu Inc. (NYSE:ZH) is developing AI search, expert-data solutions and AI-enabled content businesses. Exposure to foundation models, infrastructure, robotics and applications could create technology partnerships and help identify emerging customer needs.
A specialist fund also supplies investment research, deal sourcing and portfolio oversight that would require substantial internal resources to replicate. For shareholders, the potential benefit combines investment returns with commercial opportunities for the core content platform. Any cooperation would still require separate **** sment and agreement.
There is an operating business to build around. Second-quarter paid content and intellectual-property operations revenue increased to RMB425.9 million from RMB408.2 million. Zhihu Inc. (NYSE:ZH) also reduced total operating expenses by 13% to RMB469.4 million. These results support a focused approach in which outside technology complements established content and expert relationships.
#content #technology #million


5 days ago
Daktronics Inc. (NASDAQ:DAKT) reported its Q1 FY27 results, showing continued momentum across core segments and its strategic push. The company reported topline figures of $234.6 million, which grew 7.1% compared to the same period last year. This growth was primarily driven by impressive numbers across the Live Events, Transportation, and International units. The diluted EPS of $0.40 was the highest quarterly figure in the last twelve quarters, exhibiting a substantial growth of more than 21%. The business generated $31.4 million in cash from operations, which pushed the cash balance to $154.6 million by the quarter end, after accounting for $4.4 million expenditure on share repurchases.
Copyright: rawpixel / 123RF Stock Photo
The recently reported results point to enhanced profitability and the company's ongoing operational excellence initiatives, which would strengthen investor confidence. An impressive cash position backed with robust operating cash flows would enable Daktronics to pursue its 3-year strategic plan around growth, operational strength, and efficient capital allocation.
For growth, management focused on vertical market expansion during the quarter, with investments in service offerings and software to facilitate recurring revenue growth and customer value.
For operational excellence, the company took several initiatives around supply chain and manufacturing. These include scaling up of Mexico operations, adding automation, refining procurement, and more. Product backlog reached $311.3 million, the sixth straight quarter it has stayed above $300 million, pointing to continued demand spread across the company's varied business segments.
#million #cash #results
Copyright: rawpixel / 123RF Stock Photo
The recently reported results point to enhanced profitability and the company's ongoing operational excellence initiatives, which would strengthen investor confidence. An impressive cash position backed with robust operating cash flows would enable Daktronics to pursue its 3-year strategic plan around growth, operational strength, and efficient capital allocation.
For growth, management focused on vertical market expansion during the quarter, with investments in service offerings and software to facilitate recurring revenue growth and customer value.
For operational excellence, the company took several initiatives around supply chain and manufacturing. These include scaling up of Mexico operations, adding automation, refining procurement, and more. Product backlog reached $311.3 million, the sixth straight quarter it has stayed above $300 million, pointing to continued demand spread across the company's varied business segments.
#million #cash #results


5 days ago
Two cybersecurity heavyweights, Rubrik, Inc. (NYSE:RBRK) and CrowdStrike Holdings, Inc. (NASDAQ:CRWD), both released Q2 FY2027 earnings in late August/early September while deepening their strategic alliance. On September 1, the companies announced a joint agentic identity resilience workflow orchestrated by CrowdStrike's Charlotte Agentic SOAR. By uniting CrowdStrike's Falcon Next-Gen Identity Security with Rubrik's Identity Resilience, joint customers can now detect, investigate, and recover from compromised identity environments in hours instead of days.
Den Rise/Shutterstock.com
CrowdStrike continues to operate at a massive scale with strong cash generation and expanding margins. For Q2 FY2027, CrowdStrike reported total revenue of $1.47 billion, up 26% year-over-year, with annual recurring revenue (ARR) reaching $5.84 billion (up 25%) after adding a record $333 million in net new ARR. GAAP net income turned positive at $5.3 million ($0.01 per diluted share), while non-GAAP net income reached $322.9 million ($0.31 per diluted share). Operating cash flow hit a Q2 record of $530.3 million, with free cash flow reaching $377.4 million. Expanding its momentum, CrowdStrike announced a partnership with OpenAI on September 2 to secure Codex agents and integrate GPT-5.6 Cyber into Falcon, prompting Raymond James to raise its price target to $250 from $240 on September 3, citing an "AI double whammy."
Rubrik, meanwhile, represents the hyper-growth challenger outperforming Wall Street's top-line expectations. For Q2 FY2027, Rubrik's total revenue surged 38% year-over-year to $427.3 million (up 43% when normalized for material rights), while Subscription ARR grew 33% to $1.66 billion. While GAAP net loss per share narrowed to $(0.30), Rubrik achieved non-GAAP net income per share of $0.20 ($0.47–$0.53 guidance for full FY27). Operating cash flow reached $76.8 million, generating $65.7 million in free cash flow. While CrowdStrike holds the stronger overall financial profile given its $5.84 billion ARR scale and $377.4 million free cash flow generation, Rubrik leads in top-line growth velocity.
CrowdStrike's bull case rests on its leadership in endpoint and identity security, proven GAAP and non-GAAP profitability, and deep AI integrations with platforms such as OpenAI and Charlotte AI, which could drive further platform consolidation and high-margin ARR growth. However, slower percentage growth compared with younger peers, elevated valuation multiples, and lingering customer scrutiny following past software update disruptions remain key risks.
#flow
Den Rise/Shutterstock.com
CrowdStrike continues to operate at a massive scale with strong cash generation and expanding margins. For Q2 FY2027, CrowdStrike reported total revenue of $1.47 billion, up 26% year-over-year, with annual recurring revenue (ARR) reaching $5.84 billion (up 25%) after adding a record $333 million in net new ARR. GAAP net income turned positive at $5.3 million ($0.01 per diluted share), while non-GAAP net income reached $322.9 million ($0.31 per diluted share). Operating cash flow hit a Q2 record of $530.3 million, with free cash flow reaching $377.4 million. Expanding its momentum, CrowdStrike announced a partnership with OpenAI on September 2 to secure Codex agents and integrate GPT-5.6 Cyber into Falcon, prompting Raymond James to raise its price target to $250 from $240 on September 3, citing an "AI double whammy."
Rubrik, meanwhile, represents the hyper-growth challenger outperforming Wall Street's top-line expectations. For Q2 FY2027, Rubrik's total revenue surged 38% year-over-year to $427.3 million (up 43% when normalized for material rights), while Subscription ARR grew 33% to $1.66 billion. While GAAP net loss per share narrowed to $(0.30), Rubrik achieved non-GAAP net income per share of $0.20 ($0.47–$0.53 guidance for full FY27). Operating cash flow reached $76.8 million, generating $65.7 million in free cash flow. While CrowdStrike holds the stronger overall financial profile given its $5.84 billion ARR scale and $377.4 million free cash flow generation, Rubrik leads in top-line growth velocity.
CrowdStrike's bull case rests on its leadership in endpoint and identity security, proven GAAP and non-GAAP profitability, and deep AI integrations with platforms such as OpenAI and Charlotte AI, which could drive further platform consolidation and high-margin ARR growth. However, slower percentage growth compared with younger peers, elevated valuation multiples, and lingering customer scrutiny following past software update disruptions remain key risks.
#flow



5 days ago
Braze Inc. (NASDAQ:BRZE) turned in a strong second quarter. The reputed customer engagement platform showcased continued momentum across both its product strategy and financial performance. The company generated topline figure of $227.2 million, an impressive 26.2% increase compared to the same period last year. This revenue growth was fueled by upselling gains, customer additions and renewals. The company posted $24.2 million in cash flow from operating activities, a monumental growth relative to $7 million in the same period a year ago. This was paired with $21.7 million in free cash flow, against $3.5 million during Q2 FY26.
Jirsak/Shutterstock.com
The quarter brought several meaningful strategic moves. Braze broadened its BrazeAI Operator tool, which allows users to build new Canvas steps straight from conversational prompts. The company also signed a three-year Strategic Collaboration Agreement with AWS to support collaborative co-selling and go-to-market initiatives. The arrangement will incentivize AWS sellers for integrating Braze within their accounts.
For the latest quarter, subscription revenue jumped to $207.7 million from $171.8 million a year prior, while professional services and other revenue more than doubled, reaching $19.6 million. Dollar-based net retention among larger accounts, defined as those with annual recurring revenue of $500,000 or more, edged up to 112% in comparison to 111% a year earlier. Profitability metrics improved considerably as well, with adjusted operating income jumping to $22 million from $6 million, and adjusted diluted EPS increasing from $0.15 to $0.19.
Management cited growing demand for measurable return on investment as the primary force behind faster uptake of Braze's AI product lineup, which includes BrazeAI Operator, BrazeAI Agent Console, and BrazeAI Decisioning Studio.
#revenue
Jirsak/Shutterstock.com
The quarter brought several meaningful strategic moves. Braze broadened its BrazeAI Operator tool, which allows users to build new Canvas steps straight from conversational prompts. The company also signed a three-year Strategic Collaboration Agreement with AWS to support collaborative co-selling and go-to-market initiatives. The arrangement will incentivize AWS sellers for integrating Braze within their accounts.
For the latest quarter, subscription revenue jumped to $207.7 million from $171.8 million a year prior, while professional services and other revenue more than doubled, reaching $19.6 million. Dollar-based net retention among larger accounts, defined as those with annual recurring revenue of $500,000 or more, edged up to 112% in comparison to 111% a year earlier. Profitability metrics improved considerably as well, with adjusted operating income jumping to $22 million from $6 million, and adjusted diluted EPS increasing from $0.15 to $0.19.
Management cited growing demand for measurable return on investment as the primary force behind faster uptake of Braze's AI product lineup, which includes BrazeAI Operator, BrazeAI Agent Console, and BrazeAI Decisioning Studio.
#revenue


5 days ago
Casey's General Stores Inc. (NASDAQ:CASY), the third-largest convenience chain and fifth-biggest pizza brand within the U.S., released its first quarter results, showing early traction from the company's recently announced three-year strategic plan. For the recent quarter, inside same-store sales jumped 3.2% year-over-year, and 7.7% on a two-year stacked basis, leading to inside margins of 42.2%. Total inside gross profit stood at $749.8 million, rising 6.3% compared to the same period last year. The company posted net income of $273.7 million, exhibiting a 27.1% increase relative to Q1 last year. This translated into a 27.7% jump in diluted EPS which rose to $7.37.
Foodio/Shutterstock.com
Casey's is building on its three-year roadmap which rests on three core pillars. These include acceleration of growth across food and beverage, scaling up its store footprint, and elevating its operational efficiency.
Food remains a major growth enabler for the broader business, with prepared foods and nonalcoholic beverages currently driving the expansion of inside sales. Wings sales within Des Moines market also posted a 20% year-over-year sales jump. This positions the company to benefit from a larger opportunity of ramping up the offerings across roughly 3,000 stores, and cements Casey's reputation as a food destination.
The retailer also plans to expand its operations with at least 400 stores through a mix of acquisitions, and ground-up development of new stores. The integration of Fikes Wholesale, owner of CEFCO Convenience Stores and Casey's largest acquisition to date, demonstrates its capacity to expand through dealmaking. Management said the integration remains ahead of schedule.
#stores #largest
Foodio/Shutterstock.com
Casey's is building on its three-year roadmap which rests on three core pillars. These include acceleration of growth across food and beverage, scaling up its store footprint, and elevating its operational efficiency.
Food remains a major growth enabler for the broader business, with prepared foods and nonalcoholic beverages currently driving the expansion of inside sales. Wings sales within Des Moines market also posted a 20% year-over-year sales jump. This positions the company to benefit from a larger opportunity of ramping up the offerings across roughly 3,000 stores, and cements Casey's reputation as a food destination.
The retailer also plans to expand its operations with at least 400 stores through a mix of acquisitions, and ground-up development of new stores. The integration of Fikes Wholesale, owner of CEFCO Convenience Stores and Casey's largest acquisition to date, demonstrates its capacity to expand through dealmaking. Management said the integration remains ahead of schedule.
#stores #largest


