2 days ago
SK Hynix is exploring something it has never done before: manufacturing memory chips in the United States.
Reuters reported on September 16 that the Korean memory giant is discussing several possibilities with Intel Corporation (NASDAQ:INTC), including leasing part of Intel's long-delayed Ohio complex or forming a venture involving Intel and large cloud customers. SK Hynix said no specific plan has been finalized.
For Micron Technology, Inc. (NASDAQ:MU), the talks matter because one of its strongest strategic advantages is being the major U.S.-based memory producer while AI has made DRAM and HBM increasingly scarce.
Intel has committed enormous capital to Ohio, with the broader project potentially reaching around $100 billion over time. Delays have pushed planned production into the next decade. A tenant or joint-venture partner could therefore help Intel share the financial burden of developing the Ohio site rather than relying entirely on its own foundry demand to justify the buildout.
That is the bull case. The bear case is that exploratory talks are a long way from revenue. Bringing advanced Korean memory production to the U.S. could face cost problems, technology-transfer restrictions and objections from Seoul. Intel still needs its core manufacturing roadmap to work.
#long
2 days ago
Investors eager to buy into the futuristic vision of profitable driverless vehicles will get their chance soon. May Mobility is aiming to become the first U.S. publicly listed pure-play option for an autonomous ride-hailing technology company. It is poised to go public through a special purpose acquisition company (SPAC), merging with ACP Holdings Acquisition (NASDAQ: ACGC) that values the combined company at roughly $1.4 billion.
It's expected to operate as May Mobility. trading on the Nasdaq exchange under MAY. But before investors get too excited, let's pump the brakes and take a look at the details.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
It's easy for investors to get excited about the opportunity, but many might not be aware of the potential market size or growth prospects. The global robotaxi market is projected to reach about $415 billion by 2035, with the U.S. accounting for a roughly $48 billion slice of that pie. The fleet of U.S. commercial autonomous vehicles (AVs) is projected to expand from only about 4,000 vehicles currently to around 35,000 by 2030 -- or about 8% of the ride-sharing market.
A year ago this month, Bank of America projected that the long-term U.S. total addressable market (TAM) for AV ride-hailing is a trillion-dollar opportunity as companies such as May Mobility aim to replace the drivers that take roughly 70% of every fare. It's also important for investors to realize how early in the game this is: Alphabet's Waymo, with an estimated $350 million in annualized revenue, would represent only about 0.5% of U.S. ride-hailing bookings.
#vehicles #company #roughly #billion
9 days ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ******* ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio
9 days ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson

9 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell
9 days ago
On September 9, 2026, Signet Jewelers Limited (NYSE:SIG) reported second-quarter net profit of more than $52 million, reversing a net loss of over $9 million a year earlier, with adjusted earnings per share of $2.19 beating ***** yst estimates of $1.72 by a wide margin. It sent shares up as much as 24% in trading.
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited


9 days ago
On September 4, 2026, the Wall Street Journal reported that Starbucks Corporation (NASDAQ:SBUX)' longtime chai latte devotees have turned against the company's reformulated recipe, introduced in March. It reduced sweetener and shifted from a pre-made concentrate to a new base with just two grams of sugar.
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer
9 days ago
On September 9, 2026, Reuters reported that Stellantis N.V. (NYSE:STLA) is recalling 201,976 Jeep vehicles in the U.S., including certain Grand Cherokee, Wagoneer and Grand Wagoneer models. It happened after the National Highway Traffic Safety Administration found a software error that can prevent the tire-pressure monitoring system from detecting low tire pressure or alerting the driver, raising crash risk.
Dealers will update the affected radio-frequency hub software free of charge. The recall is the latest in a year that has already included a 1.5-million-vehicle Ram seat-belt recall, a 955,000-vehicle camera-glitch recall in August, and more than 1 million Wranglers and Gladiators recalled in June for fire risk.
The recall should carry a relatively limited direct financial burden because Stellantis N.V. (NYSE:STLA) can fix the defect with a software update. The recall covers 201,976 Jeep vehicles, but Stellantis does not need to replace a physical component. A software-based remedy should reduce parts and labor costs and allow dealers to complete the repair relatively quickly, limiting the recall's immediate impact on earnings and cash flow.
Stellantis has already begun rebuilding its financial performance, giving investors a stronger foundation to absorb another recall. Second-quarter net profit reached €293 million compared with a €1.87 billion loss a year earlier. Revenue surged 13% to €43.5 billion. The business also generated €1 billion in industrial free cash flow during the quarter, showing real improvement as CEO Antonio Filosa executes his turnaround plan.
Strong North American demand shows the recall has not yet undermined demand for Stellantis' key Jeep and Ram products. Second-quarter North American shipments increased 38% to 445,000 vehicles. It was backed up by refreshed models, including the Jeep Grand Wagoneer and Grand Cherokee and the Ram 1500. So the company enters this recall with improving volumes and strong demand for several of the brands that matter most to its North American turnaround.
#software

9 days ago
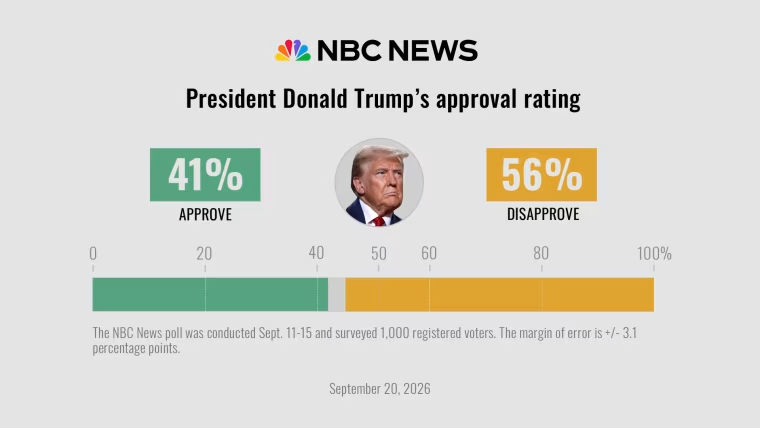
President Donald Trump’s sinking ratings threaten to drag down Republicans in November’s midterm elections, as voters blame him for high prices and a shaky economy, according to a new NBC News poll.
The president’s approval rating stands at 41% among registered voters, a second-term low in the poll, with a majority (55%) of voters saying they believe Trump’s policies have hurt the economy. That’s up from 48% in March, before the Iran war pushed up prices on gas and other goods and cemented the rising cost of living as voters’ most pressing issue.
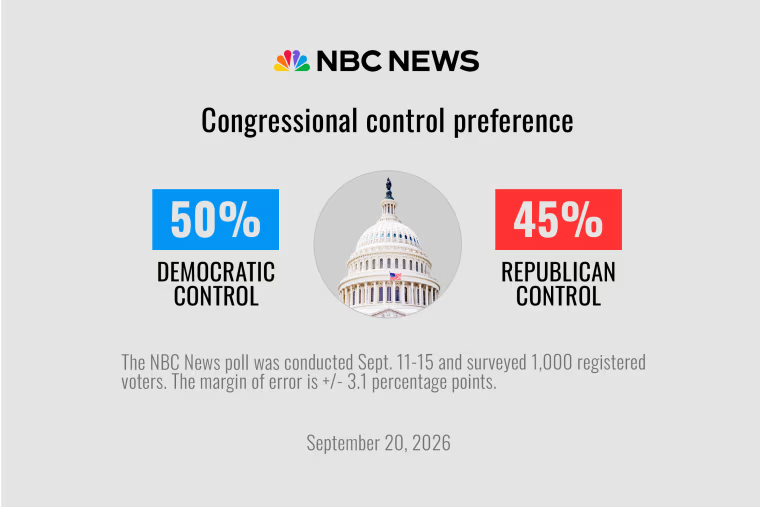
Democrats hold a 5-point edge in the battle for control of Congress, 50%-45% — not nearly as large a lead as the 12-point advantage the party enjoyed at this point before the 2018 election, when Democrats rode an anti-Trump wave to the House majority in his first midterm as president. Despite that lead, the Democratic Party is still viewed more negatively than Trump and the GOP.
That could help Republicans, along with the fact that the fight for control of the House and especially the Senate is playing out in traditionally Republican parts of the country. Democrats would have to flip multiple states Trump carried by double digits in 2024 to win the Senate.
“We have a classic battle between these numbers and the political geography in which this campaign will be decided,” said Republican pollster Bill McInturff of Public Opinion Strategies, whose firm conducted the survey alongside Democratic firm Hart Research ***** ociates. “And the Republicans are still standing because of the geography in which this election will be won or lost.”
#president
10 days ago
Sempra (NYSE:SRE) added a long-term customer commitment on September 14, when its infrastructure subsidiary announced a 20-year sales and purchase agreement with Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR). The agreement covers approximately 0.8 million tonnes annually of liquefied natural gas, or LNG.
Supply will come from the subsidiary's contracted liquefaction capacity at Port Arthur LNG Phase 2 in Texas. The project is under construction, with trains 3 and 4 expected to begin commercial operations in 2030 and 2031, respectively. The agreement improves visibility into future sales, while the earnings contribution depends on delivery and contract economics.
Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR) becomes the infrastructure subsidiary's first South American LNG customer. That broadens the geographic base of buyers and establishes a commercial relationship extending over two decades.
For Sempra (NYSE:SRE), the practical benefit is an external buyer for part of the subsidiary's contracted capacity. Securing that relationship before startup could reduce the need to find buyers for the covered volumes as production approaches, while supporting longer-term supply planning.
The annual commitment equals approximately 6.2% of Phase 2's planned 13-million-tonne annual capacity. This provides a measure of scale, although it does not establish the percentage of capacity still available for sale.
#agreement #petr #supply #term
10 days ago
EDINBURG, Texas (AP) — Quinten Martinez, pumping gas under a hot South Texas sun, remembers a time when fueling up didn't require difficult decisions.
"Is it going to be groceries this week?" asked the 28-year-old Amazon delivery driver as he watched the numbers tick higher. "Is it gonna be getting gas in our tank to go to work?"
He shook his head when asked about President Donald Trump's **** ertion last week that higher gas prices are a small price to pay for the war with Iran.
"I don't feel like it's a good trade-off," Martinez said. "I don't feel like this is good for anyone."
Voters across the country, and across the political spectrum, tend to agree.
#martinez #don 't #like


10 days ago
Transocean Ltd. (NYSE:RIG) received a boost on September 15 when the company announced that it had secured an approximately $80 million contract for its Deepwater Conqueror ultra-deepwater drillship in Equatorial Guinea. The estimated 170-day campaign with an undisclosed operator is expected to begin next year, directly following the rig's current contract in the US Gulf.
Built in 2016, the DSME 12000-design Deepwater Conqueror can operate in water depths of up to 12,000 feet and drill to a maximum depth of 40,000 feet.
The $80 million award provides Transocean with additional contract revenue and improves visibility into the company's future revenue base. If the award includes attractive day rates and limited mobilization costs, it could contribute positively to operating margins and cash flows. The company's backlog stood at approximately $6.7 billion as of August 5, 2026.
The contract could also improve the utilization of its high-value drilling rig. Since ultra-deepwater rigs require substantial investment, securing work for an idle or underutilized rig could help spread fixed operating costs over a larger revenue base. Deepwater Conqueror will move directly from its US Gulf contract to Equatorial Guinea, avoiding a gap between the two programs.
The latest award also provides Transocean with an alternative destination for its rigs. The company had already signaled in its Q2 earnings call that the growing demand for new deepwater contracts in Africa would also help offset a decline in awards in the US Gulf.
#deepwater #contract #gulf #equatorial
10 days ago
GOOG trades at a P/E of 14 versus META's 24, with Cloud revenue surging 82% while META's operating margins collapsed from 43% to 31%.
META's Reality Labs bleeds roughly $4B per quarter, 2026 capex is projected between $130B and $145B, and active litigation makes it a volatile aggressive-growth bet rather than a retirement hold.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Google didn't make the cut. Enter your email to see the names that beat GOOG. The report is free. Enter your email and see if any of your stocks made the cut.
Alphabet (NASDAQ:GOOG) and Meta Platforms (NASDAQ:META) just unleashed rival consumer AI agents (Google's family-focused CC, a shared agent supporting up to six family members, and Meta's single-user Muse, aiming for higher autonomy across a user's digital life, including commerce), and the retirement-focused investor writing one check today needs a clear answer: which mega-cap deserves the slot?
Both stocks are pouring tens of billions into AI infrastructure. Both consumer AI agents (not just chatbots) are designed to take real actions on a user's behalf rather than only answering questions. However, CC is a family-oriented productivity and logistics agent tightly tied to the Google ecosystem. Muse is a more general-purpose personal agent aiming for higher autonomy across a user's digital life, including commerce. They compete in the emerging "AI agent that actually does things" category, but target different use cases and user models.
#stocks #family


10 days ago
Helfstein estimates META needs 115 million paying Muse subscribers at $20/month to unlock $28 billion in AI revenue, but doubts it happens.
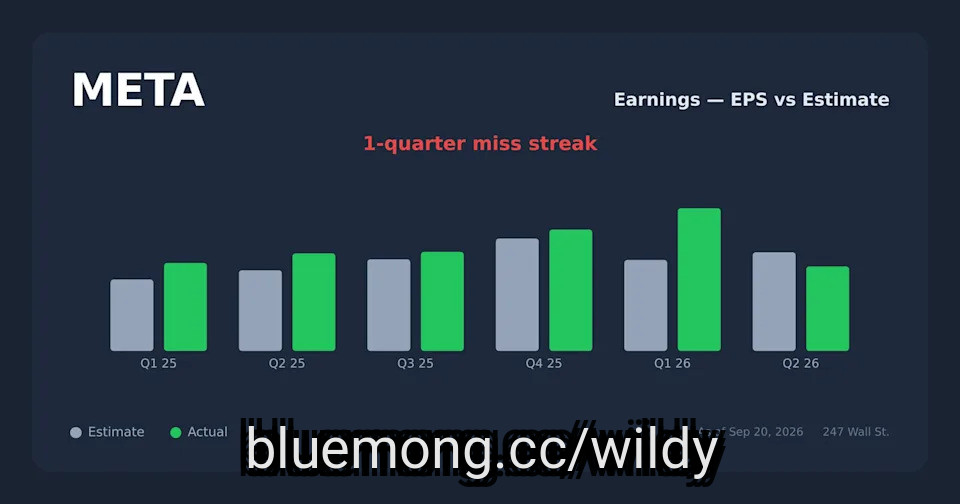
META's Q2 operating margin collapsed from 43% to 31%, while full-year capex guidance soared to a range of $130 billion to $145 billion.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Meta didn't make the cut. Enter your email to see the names that beat METAPLATFORMS. The report is free. Enter your email and see if any of your stocks made the cut.
Jason Helfstein, Oppenheimer's Managing Director and Senior ******* yst covering the Internet sector, laid out a striking scenario in a September 2026 note: Meta Platforms (NASDAQ:META) would need roughly 115 million paying Muse subscribers at a $20/month price point to generate about $27.5 to $28 billion in annual AI agent revenue. His conclusion, however, was skeptical. For long-term investors, the math frames just how high the bar is for Meta stock to earn a consumer-AI premium on top of its advertising engine.
Ticker
#million
10 days ago
The 'half-a-loaf' plan gifts roughly half of excess ***** ets to children, then uses a Medicaid-compliant annuity to bridge the penalty period.
Keeping retained cash in a bank account prevents the penalty clock from starting, since ***** ets above $2,000 disqualify the applicant outright.
One flawed annuity term or miscalculated divisor can unravel the entire plan, making elder law attorney guidance essential before any money moves.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Picture a common scenario in a state where this type of crisis planning is welcome: Dad moves into a nursing home with roughly $200,000 sitting above the $2,000 countable-asset limit that most states use for single Nursing Home Medicaid applicants. His family gifts about $100,000 to the children, then uses the other half to buy a short-term Medicaid-compliant annuity that pays the nursing home while the gift penalty runs. When the penalty ends, Medicaid picks up the bill. The children keep the gift.
#annuity #roughly
10 days ago
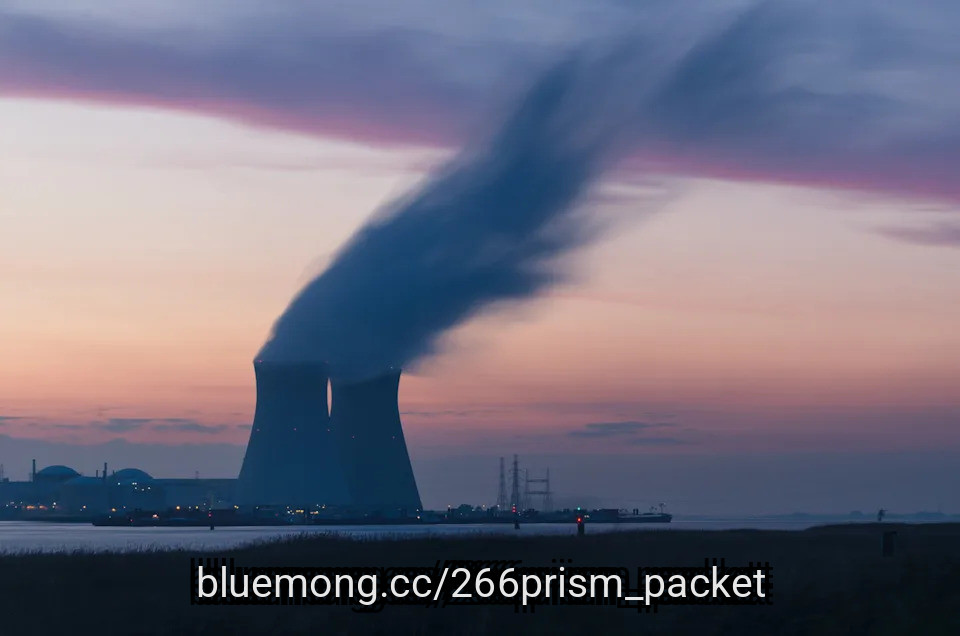
NextEra Energy, Inc. (NYSE:NEE) announced on September 8 that it had secured a loan of up to $1.9 billion from the U.S. Department of Energy to support the restart of a shuttered nuclear power plant in Iowa. The Duane Arnold Energy Center ceased operations in 2020 after 45 years of service. The plant is now expected to resume operations in early 2029, pending regulatory approvals.
The federal funding is intended to help restore the facility and add reliable generation capacity as the US electricity demand soars to record levels amid the AI boom. To help meet the growing demand, President Trump is making efforts to accelerate the expansion of nuclear energy. He has signed an executive order to get 10 large conventional reactors under construction by 2030 and has also called for federal funding to support the restart of shuttered nuclear plants.
John Ketchum, Chairman, President, and CEO of NextEra Energy, commented:
"Restarting Duane Arnold is about delivering new power to meet new demand while generating billions of dollars in economic value for Iowans. Just as importantly, it shows how America can support rapid economic growth and rising electricity demand while helping keep power affordable for existing customers. By bringing new generation online to serve new demand, we can strengthen the grid, create hundreds of good-paying jobs and help ensure Iowa families and businesses are not asked to bear the costs of growth. We appreciate the Administration's leadership in advancing America's nuclear renaissance and share its commitment to an all-of-the-above energy strategy that expands supply, strengthens energy security and keeps America competitive."
Photo by Frédéric Paulussen on Unsplash
#duane #arnold
10 days ago
Marathon Petroleum Corporation (NYSE:MPC) has substantially outperformed the wider market this year, supported by an unusually sharp surge in global refining margins as the prolonged Iran crisis has significantly tightened global refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
With Marathon up by over 150% since the beginning of 2026, there are now concerns that the stock may have topped out. However, the ****** ysts over at Morgan Stanley are convinced that the rally still has further room to run. On September 14, Morgan Stanley ****** yst Joe Laetsch significantly raised the firm's price target on MPC from $265 to $453, while reaffirming an 'Overweight' rating on the shares.
The target boost reflects an upside of over 9% from the current price level and even exceeds the stock's record high of just under $411 per share achieved earlier this month. The Morgan Stanley update comes amid broader Wall Street optimism surrounding the American refining giant, with ****** ysts from Raymon James, UBS, and several others also improving their respective outlooks on MPC.
Morgan Stanley's vote of confidence suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, especially given the fresh wave of attacks between Washington and Tehran. Even if the conflict in the Middle East subsides, the region's refined fuel output is expected to remain relatively tight, since the damaged or idled refineries in the Middle East are likely to take some time to return to full operations.
As the largest refiner by volume in the United States, Marathon has significant operating leverage to capitalize on the current high-margin environment. The company already demonstrated its ability to translate the high crack spreads into material earnings when it delivered an almost fourfold increase in profits in the second quarter.
#morgan #marathon #stanley #middle

10 days ago
GE Vernova Inc. (NYSE:GEV) received a boost on September 16 after CEO Scott Strazik stated that the company's backlog could hit the $200 billion mark "very early" in 2027, sooner than Wall Street had expected. The company expects the "strong and durable demand" to drive accelerated growth after its backlog had reached $167 billion at the end of the second quarter of 2026.
GEV has gained by almost 50% over the last year but is down by more than 14% over the last month, reflecting growing investor concerns surrounding the AI trade. The stock also came under pressure on September 14 when GLJ Research slammed it with a 'Sell' rating and a Street-low price target of $470, describing the company as "a cyclical gas turbine manufacturer priced as a secular compounder".
The update builds on extraordinarily strong momentum for GE Vernova, powered by the incredibly strong demand for its power equipment amid the AI data center boom. The company's backlog of $176 billion at the end of Q2 grew $13 billion from the previous quarter and was up 37% YoY, providing it with visibility into earnings well into the 2030s.
Notably, GE Vernova is translating this demand into financial improvement rather than simply a very large order book. The company's revenue grew by 22% YoY to $11.1 billion in the second quarter, while its free cash flow reached $5.1 billion, already exceeding its full-year 2025 level. Given the high demand, GEV raised its 2026 revenue forecast to $45.5 billion-$46.5 billion, up from its previous range of $44.5 billion-$45.5 billion.
The ongoing AI boom has been a major growth catalyst for GE Vernova, as its data center-related orders exceeded $5 billion in the first half of this year, more than double 2025's total. According to Barron's, power availability has become a key constraint for data center operators, and this strong demand has effectively constrained GEV's turbine capacity, which can support pricing and the value of scarce delivery slots.
#billion #year #data #center

10 days ago
On August 6, Targa Resources Corp. (NYSE:TRGP) reported a record second quarter. Adjusted EBITDA reached $1.60 billion, a 38% jump from the same period a year earlier, and management now expects full-year results near the top of its guidance range. Targa moves and processes natural gas and natural gas liquids out of the Permian Basin, and these numbers suggest that system is running fuller than ever.
The strength came from volume, not just price. Adjusted EBITDA also climbed 14% from the first quarter, helped by Permian gas volumes that added over 450 million cubic feet of daily throughput. Some producers held back output because Waha gas prices went negative, and Targa still set a volume record. Volumes for NGL pipelines, fractionation, and LPG exports also hit records, helped by Train 11, a new fractionator in Mont Belvieu, Texas, that started up early in the quarter.
Construction is also landing on time. East Driver, a new processing plant serving the Midland side of the Permian, started up late in the quarter and ahead of schedule, and the other gathering and logistics projects are tracking their plans. Shareholders get a cut too. On July 16, Targa declared a $1.25 per share quarterly dividend, 25% above the payout for the second quarter of 2025, payable August 14 to holders of record on July 31. It also spent $80 million buying back shares during the quarter.
Growth at this pace costs real money. Targa plans about $4.5 billion in net growth spending this year, and its consolidated debt stood at $19,578 million on June 30. About $3.2 billion of liquidity gives it a cushion. In July, it also extended its receivables securitization facility to July 30, 2027 and raised the size to as much as $800 million. More borrowing capacity helps, but it is still borrowing.
Not every dollar of the profit surge is as steady as a pipeline volume. Management tied the higher outlook partly to strong marketing margin and optimization work in the first two quarters, and the quarter's jump in marketing margin came from greater optimization opportunities. That kind of income can be lumpy. Meanwhile, lower natural gas prices trimmed margins in the gathering business, and the Waha curtailments showed that producers can pull back when local prices turn ugly.
#record
10 days ago
If you are planning to retire next year, do you feel ready? If you answered yes, do you feel financially prepared to do so? If you answered maybe or no to the second question, you're likely in the majority.
That was the finding of a survey by **** et Preservation Wealth & Tax of 1,000 Americans who are over 55 and planning to retire in 2026.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#wealth #answered #jeff #bezos

10 days ago
If you're trying to choose between the Vanguard S&P 500 ETF (NYSEMKT: VOO) and the State Street SPDR S&P 500 ETF (NYSEMKT: SPY), it might seem they're essentially interchangeable. They're both huge and track the same index.
At a high level, that's probably true. But if you want to dive deep and get picky, a few factors set them apart.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The State Street SPDR S&P 500 ETF has an expense ratio of 0.0945%. The Vanguard S&P 500 ETF charges just 0.03%. Given that the index has historically returned about 10% per year, this fee difference may seem immaterial. But I will take any advantage I can get.
Because of their sizes, trading spreads (the difference between the buying (ask) price and the selling (bid) price of a stock) are virtually nothing, so spreads aren't really a consideration here. But if you can own the exact same index for a third of the cost, why not?
#index #same
10 days ago
California entrepreneur Eric Schiffer warned that the state's proposed billionaire wealth tax could drive some of its most successful business leaders out of California, predicting a "giant sucking sound" of entrepreneurs heading for the exits if voters approve the measure.
Schiffer, chairman of family office Patriarch and CEO of Reputation Management Consultants, told FOX Business he works with several billionaire clients, including some in California, and said many are unhappy about the proposal.
"I think the impact of this passing in California is a giant sucking sound of all of these entrepreneurs being sucked out of California because they're just not going to want to stay," Schiffer said.
"Why would anyone stay if they have spent their life building wealth that they were already taxed on?
Mark Cuban Tells Ro Khanna 'You Don't Understand Business,' Threatens Investment Shift Over Billionaire Tax
#california #billionaire
10 days ago
For the record:
1:38 p.m. Sept. 19, 2026: An earlier version of this article stated KCAL's helicopter is owned by Angel City Air. It is owned by Helicopters Inc.
Whether it's a brush fire, a mass shooting, a car chase or the aftermath of a major storm, viewers in Los Angeles are used to getting the news from above.
Television news helicopter coverage has become one of the most important elements of any local newscast, with the high-flying helicopters roaring overhead a common fixture of breaking news scenes.
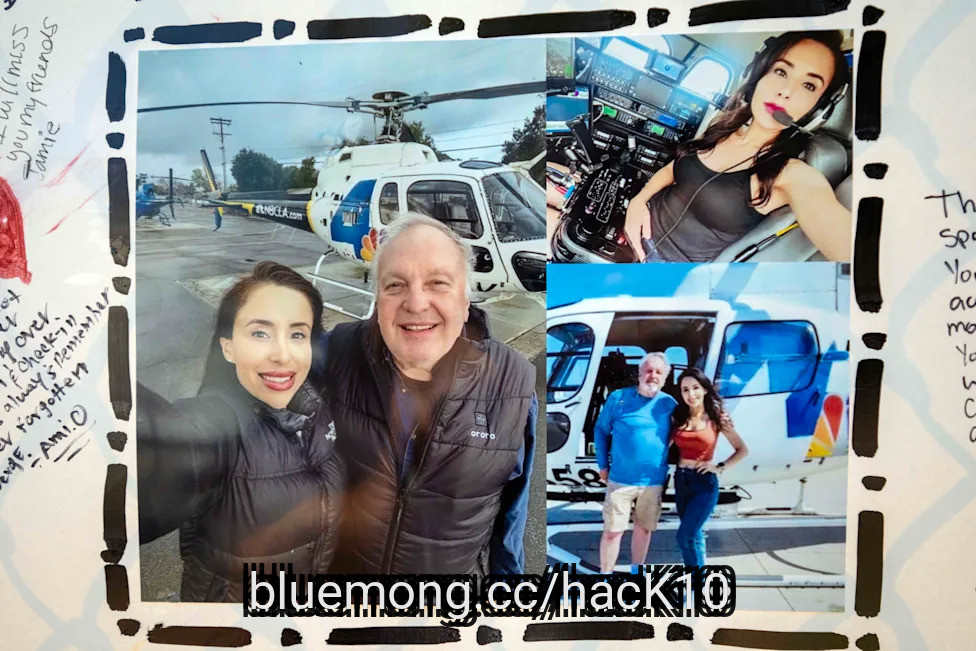
These images are so ubiquitous, it may have been easy to take them for granted, until Tuesday, when an NBC4 helicopter carrying reporter Eliana Moreno and pilot George Marciniw crashed while covering breaking news in Chatsworth. Both died, along with a bystander on the ground.
The tragedy has prompted soul-searching in the world of TV news helicopter pilots and focused attention on safety issues.
#city #whether #angeles
10 days ago
On Monday, Sept. 21, Sandisk (NASDAQ:SNDK) takes a spot in the S&P 100, a subset of the S&P 500 (SNPINDEX:^GSPC) made up of 100 of its largest blue-chip companies. Dell Technologies, Palo Alto Networks, and Arista Networks enter with it. The announcement came from S&P Dow Jones Indices on Sept. 4, and the changes take effect before Monday's open.
Four companies are leaving to make room: Nike (NYSE:NKE), Colgate-Palmolive, Simon Property Group, and Honeywell Aerospace.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The swap says a lot about how 2026 has gone. Sandisk shares have gained more than 600% this year, more than any other stock in the S&P 500.
Nike's stock, meanwhile, reached a 52-week low this week. And Sandisk, worth about $260 billion, is currently more than four times the size of the roughly $54 billion sportswear giant.
#sandisk #networks #four #Companies

10 days ago
Shark Tank entrepreneur Kevin O'Leary only found out his mom was rich when she died.
"She kept this little account secret from both of her husbands her whole life, she was married twice," O'Leary told the Motley Fool. "The executor called me up and said, 'You've got to come down here, your mother has died a very wealthy woman.'"
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#o 'leary #died #fool #you 've
10 days ago
Intel Corporation (NASDAQ:INTC) is targeting a potentially significant opportunity through its strategic Terafab partnership with companies **** ociated with Elon Musk, including **** eX, Tesla, and xAI. The initiative is part of an ambitious semiconductor manufacturing project focused on producing advanced chips for artificial intelligence (AI), robotics, autonomous vehicles, and other compute-intensive applications.
On September 15, Tigress Financial highlighted the strategic importance of the alliance to Intel's turnaround prospects. The research firm reiterated its Buy rating on Intel and raised its price target to $145 from $118, citing the company's long-term growth opportunity.
The Terafab partnership could provide Intel's foundry business with exposure to customers that have substantial AI and high-performance computing requirements. Securing external customers could help Intel increase manufacturing scale while improving the utilization and economics of its foundry operations.
The partnership could also support Intel Corporation (NASDAQ:INTC)'s efforts to improve its semiconductor manufacturing technology. Greater production volumes and engagement with demanding customers could provide opportunities to improve manufacturing economics, yields, and scalability as Intel works to strengthen its competitive position in advanced chip manufacturing.
Beyond manufacturing scale, Terafab could expand Intel's role in the broader AI semiconductor supply chain. The company has historically been heavily **** ociated with CPUs, but growing its foundry business could give it greater exposure to AI accelerators, custom silicon, and other specialized compute applications. A relationship with major AI-focused customers could also help provide greater visibility into future manufacturing demand.
#Intel

10 days ago
Accenture plc (NYSE:ACN) investors are having a rough year, with the shares down more than 25%. Now Wall Street is divided over the company's outlook.
Morgan Stanley raised its price target on Accenture to $175 from $130 on September 14. Accenture shares soared more than 6% in afternoon trading following the price target increase, even though the firm reiterated its Equal weight rating on the stock.
Meanwhile, UBS recently maintained a Buy rating on the stock with a price target of $275. The bank pointed to confidence in the company's positioning around AI and, in separate notes, its acquisition strategy. However, Wells Fargo downgraded Accenture to Equal Weight. According to Wells Fargo, macroeconomic pressures could weigh on fiscal 2027 growth expectations.
The question is whether Accenture's expanding AI capabilities and acquisitions can translate into long-term growth.
Accenture's AI fortunes are tied to enterprise deployment of the technology. The company has formed a joint business group with Google Cloud to deploy AI engineers across enterprise clients. That arrangement gives Accenture another channel through which AI adoption can create demand for consulting, implementation, and integration services.
#fargo

10 days ago
For custom chip designer Broadcom Inc. (NASDAQ:AVGO), the debate is all about whether the demand for AI products will sustain and grow. It is among the few firms capable of designing custom AI chips that big technology firms rely on to supplement NVIDIA's high-power and expensive AI chips. Anthropic CEO Dario Amodei's latest remarks about the need to slow down AI development due to safety concerns have generated quite a buzz, and Cramer discussed what Broadcom Inc. (NASDAQ:AVGO)'s CEO told him when asked about AI infrastructure development losing traction:
"What's refuted by Hock Tan, of course, maybe Hock Tan is one of the biggest providers of semis, other than NVIDIA, and when I asked him about, give me a prediction about the AI slowdown, would there be one, he said, not in the least. We see the demand for compute infrastructure for development of AI and inference as extremely strong and durable. So I know those stocks were the most heavily hammered, other than the fiber stocks. But David, when you listen to what Hock Tan said last night on Mad Money, you are inclined to do buying.
"I think David, you recognize, and a lot of people don't, when you're speaking about Hock Tan, whom I had on, you're talking about a 1.6 trillion dollar company. This isn't just someone. . .worried about what orders are going to be. . .this man has more orders than almost anybody other than Jensen Huang. So I think Carl, when we get very, very negative we still have to rely on the facts And the facts do not support there are some people who are very worried about mankind, I did not get the mankind worry when I spoke yesterday."
The CNBC TV host's remarks about Broadcom Inc. (NASDAQ:AVGO) sit right at the center of the debate for the firm. This debate is about whether it will be able to continue to capture additional orders for custom AI chips. Looking at the third quarter earnings, released on September 2nd, the growth narrative appears to be quite strong.
It boosts Cramer's claims of Broadcom Inc. (NASDAQ:AVGO) experiencing strong orders, as during the quarter, the firm's revenue grew by 86%, AI semiconductor revenue jumped by 221% and fiscal year 2026 guidance implied 186% annual AI revenue growth. Not to mention, CEO Tan reaffirmed that Broadcom Inc. (NASDAQ:AVGO) could pull in $115 billion in annual AI chip sales in 2027 and a whopping $230 billion in 2028.
#orders #debate #strong


10 days ago
Eli Lilly (LLY) trades near $1,150, up about 52% over the past year, and is now worth more than a trillion dollars. At that size the easy read is that the big money has been made. But Lilly has barely started selling Foundayo, its oral obesity medicine, outside the United States. So how much is left? The scenario below starts from Lilly's own trailing numbers, but the growth, margin, and multiple it ***** umes are ours. It is not a forecast and not a price target.
Almost all of the upside is revenue. The scenario caps growth at 30% a year. That is well below the 49.6% Lilly grew over the past twelve months, though only a little below the roughly 32% pace of its own 2026 guide. Revenue still climbs from $79.7 billion to $175.0 billion by year three.
The engine is incretins. Mounjaro and Zepbound together made $14.9 billion in the second quarter of 2026, $6.3 billion more than a year earlier. Net margin eases to 30.7% in the scenario, so earnings roughly double.
Then the multiple takes its cut. Lilly's P/E of 38.5x already sits below its three-year average of 68.9x, and the scenario trims it further to 33.6x because slower growth will not support even today's multiple. On those ***** umptions the stock would be worth about $2,024 in three years, roughly 76% above today.
LLY
#below #roughly #revenue