
25 days ago
On August 6, Targa Resources Corp. (NYSE:TRGP) reported a record second quarter. Adjusted EBITDA reached $1.60 billion, a 38% jump from the same period a year earlier, and management now expects full-year results near the top of its guidance range. Targa moves and processes natural gas and natural gas liquids out of the Permian Basin, and these numbers suggest that system is running fuller than ever.
The strength came from volume, not just price. Adjusted EBITDA also climbed 14% from the first quarter, helped by Permian gas volumes that added over 450 million cubic feet of daily throughput. Some producers held back output because Waha gas prices went negative, and Targa still set a volume record. Volumes for NGL pipelines, fractionation, and LPG exports also hit records, helped by Train 11, a new fractionator in Mont Belvieu, Texas, that started up early in the quarter.
Construction is also landing on time. East Driver, a new processing plant serving the Midland side of the Permian, started up late in the quarter and ahead of schedule, and the other gathering and logistics projects are tracking their plans. Shareholders get a cut too. On July 16, Targa declared a $1.25 per share quarterly dividend, 25% above the payout for the second quarter of 2025, payable August 14 to holders of record on July 31. It also spent $80 million buying back shares during the quarter.
Growth at this pace costs real money. Targa plans about $4.5 billion in net growth spending this year, and its consolidated debt stood at $19,578 million on June 30. About $3.2 billion of liquidity gives it a cushion. In July, it also extended its receivables securitization facility to July 30, 2027 and raised the size to as much as $800 million. More borrowing capacity helps, but it is still borrowing.
Not every dollar of the profit surge is as steady as a pipeline volume. Management tied the higher outlook partly to strong marketing margin and optimization work in the first two quarters, and the quarter's jump in marketing margin came from greater optimization opportunities. That kind of income can be lumpy. Meanwhile, lower natural gas prices trimmed margins in the gathering business, and the Waha curtailments showed that producers can pull back when local prices turn ugly.
#record
28 days ago
Interested in 3M Company? Here are five stocks we like better.
3M says it is ahead of its 2027 targets, citing 5.4% second-quarter organic growth, higher margins, improved execution and on-time, in-full delivery rising to about 90%.
Data centers are a major growth priority. Its expanded beam optics technology has been standardized by Microsoft Azure, is being evaluated by five other hyperscalers, and could address a market approaching $2 billion within the next two years.
Innovation and cost reductions are supporting the outlook: 3M plans more than 350 new-product launches this year, is consolidating factories, expects to offset $150 million–$175 million in oil-related costs through pricing, and is tracking above its 25% operating-margin goal for next year.
3 Stocks Whose Charts May Be Signaling the Next Big Move
#company

1 month ago
On August 13, a federal appeals court ruled in favor of Gilead Sciences, Inc. (NASDAQ:GILD), upholding a preliminary injunction that bars the defendants from importing or facilitating the sale of foreign-market Gilead-branded medications in the US. The US Court of Appeals for the Fourth Circuit found that the differences between Gilead's HIV medication for the US market and the foreign versions being imported were "material, not theoretical." The controversy began in December 2024 when Gilead Sciences, Inc. (NASDAQ:GILD) filed suit against a number of companies, including third-party administrator Meritain Health, pharmacy benefit manager ProAct, and pharmacies Rx Valet and Advanced Pharmacy, alleging illegal imports of its best-selling HIV drug Biktarvy.
The dispute dates back to December 2024, when Gilead Sciences, Inc. (NASDAQ:GILD) sued a group of companies, including third-party administrator Meritain Health, pharmacy benefit manager ProAct, and pharmacies Rx Valet and Advanced Pharmacy, alleging illegal imports of its top-selling HIV drug Biktarvy. The lawsuit arose from a specific instance in which a patient in Maryland received the medicine in the mail from Turkey, with label instructions written in Turkish.
A federal district court in Baltimore ruled in Gilead's favor and ordered a preliminary injunction, determining that the company was likely to succeed on its Lanham Act trademark violation and unfair competition arguments. As the case continued, the injunction was increased to include new sellers like CanaRx, ElectRx, and ScriptSourcing. The defendants filed an appeal with the Fourth Circuit, and the district judge declined to suspend the injunction while the appeal was pending, thus the import restriction has been in effect the entire time. The recent ruling maintains the order rather than overturning it.
In court documents, Rx Valet stated that the Turkish-sourced Biktarvy was chemically identical to the US version, which was offered at a significantly higher price. Meritain, for its part, said that it has never supported getting non-FDA-approved pharmaceuticals from outside the US and denies the claims, despite being named as a defendant.
The Fourth Circuit rejected the defendants' main argument that the imported and domestic versions of Biktarvy are interchangeable. The court's judgment that the two versions differ materially, not just in packaging or labeling, but also in the quality-control protocols that each version goes through before reaching a patient, challenges the basic argument that these alternative funding programs have used to support their business model.
#gild

1 month ago
On August 3, The Andersons Inc. (NASDAQ:ANDE) reported second-quarter results that dwarfed last year's numbers, with net income attributable to the company climbing to $57 million, or $1.65 per diluted share, from just $7.9 million, or $0.23 per share, a year earlier. Adjusted net income reached $74 million, or $2.15 per share, versus $8.4 million, or $0.24 per share, in the second quarter of 2025. The turnaround leaned almost entirely on one business: renewable fuels.
Renewables did the heavy lifting. The segment posted a record second-quarter pretax income of $65 million, with the adjusted figure reaching $88 million, on record plant output and strong merchandising execution. Andersons credited its low-carbon strategy for $24 million in 45Z producer tax credits during the quarter, plus the first-quarter finalization of the Renewable Volume Obligations, which firmed up commodity markets and opened trading opportunities for the merchandising desk. Gains in distillers corn oil and RIN pricing also helped. Segment adjusted EBITDA came in at $103 million, more than triple the $30 million posted a year earlier.
Agribusiness improved too, if more modestly, with pretax income of $20 million, both on a GAAP and adjusted basis, up from $17 million in the prior-year quarter. Fertilizer margins strengthened even as volumes fell, and merchandising benefited from higher commodity prices and early-quarter volatility. The company is pushing further into low-carbon fuels, preparing a debottlenecking project at its Clymers, Indiana ethanol plant and advancing a Class VI well permit to capture more 45Z value. A new soybean meal export operation at the Port of Houston is expected online in the fourth quarter. Operating cash flow of $488 million for the quarter, up from $299 million a year earlier, gave the company room to keep funding those projects while holding long-term debt to EBITDA below its 2.5-times target.
The numbers come with caveats. Cash and cash equivalents stood at just $66.5 million at the end of the second quarter, down from $351 million a year earlier, even as short-term debt climbed to $314 million from $104 million. Much of that swing traces to working capital timing and investment spending rather than distress, but it leaves less cushion than the company carried a year ago.
In Agribusiness, the fertilizer and merchandising gains were partly offset by fuel surcharges, a reminder that the segment's profitability still moves with input costs it does not control. Andersons also warned that a drier stretch across its western growing regions could weigh on grain-asset profits this fall, even though better conditions in the eastern corn belt cut the other way, and that grower economics could limit fertilizer purchasing heading into the fall application season.
#million #year #income #Share

1 month ago
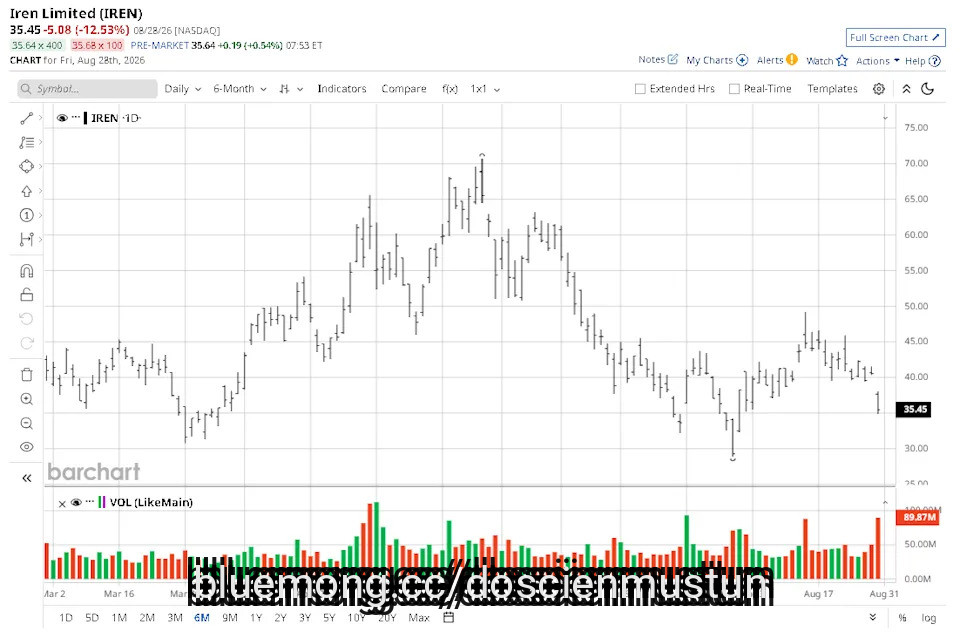
Iren Limited (IREN) shares tanked on Aug. 28 as investors panicked over a $684 million quarterly loss driven by non-cash impairments and massive upcoming capital expenditures. But the market's reaction to IREN's earnings release overlooks a major positive: the Nasdaq-listed firm has locked in $4 billion in contracted annualized recurring revenue (ARR) for 2026.
Following the post-earnings decline, IREN stock is trading at nearly half its price in late May.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
#Stock #limited