

6 days ago
Welltower (WELL) pays out only 52% of normalized FFO, while Ventas (VTR) raised its dividend 8% and improved leverage to a decade-low 4.4x.
Baby boomers turning 80 now number nearly 70 million, yet builders started only 1,000 new senior housing units last quarter.
Sabra's 6% yield comes with a dividend flat since 2020 and a $102 million non-cash loan loss provision recorded in Q2.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Welltower didn't make the cut. Enter your email to see the names that beat WELL. The report is free. Enter your email and see if any of your stocks made the cut.
Senior housing has one of the clearest demand stories in real estate. On its third-quarter call, Ventas (NYSE:VTR) noted that the baby boomer generation, a cohort of nearly 70 million individuals, began turning 80 this year. Builders started only 1,000 units of new senior housing in the quarter. More 80-year-olds and very few new buildings push occupancy and rents higher, but operator health, labor costs, and government reimbursement decide how much of that reaches shareholders. The four REITs below are all equity REITs that own buildings. None is a mortgage REIT. Dividend safety is measured on FFO, FAD, or AFFO coverage, the cash-flow figures REITs actually pay dividends from.
#senior #million #housing #ventas
Baby boomers turning 80 now number nearly 70 million, yet builders started only 1,000 new senior housing units last quarter.
Sabra's 6% yield comes with a dividend flat since 2020 and a $102 million non-cash loan loss provision recorded in Q2.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Welltower didn't make the cut. Enter your email to see the names that beat WELL. The report is free. Enter your email and see if any of your stocks made the cut.
Senior housing has one of the clearest demand stories in real estate. On its third-quarter call, Ventas (NYSE:VTR) noted that the baby boomer generation, a cohort of nearly 70 million individuals, began turning 80 this year. Builders started only 1,000 units of new senior housing in the quarter. More 80-year-olds and very few new buildings push occupancy and rents higher, but operator health, labor costs, and government reimbursement decide how much of that reaches shareholders. The four REITs below are all equity REITs that own buildings. None is a mortgage REIT. Dividend safety is measured on FFO, FAD, or AFFO coverage, the cash-flow figures REITs actually pay dividends from.
#senior #million #housing #ventas

7 days ago
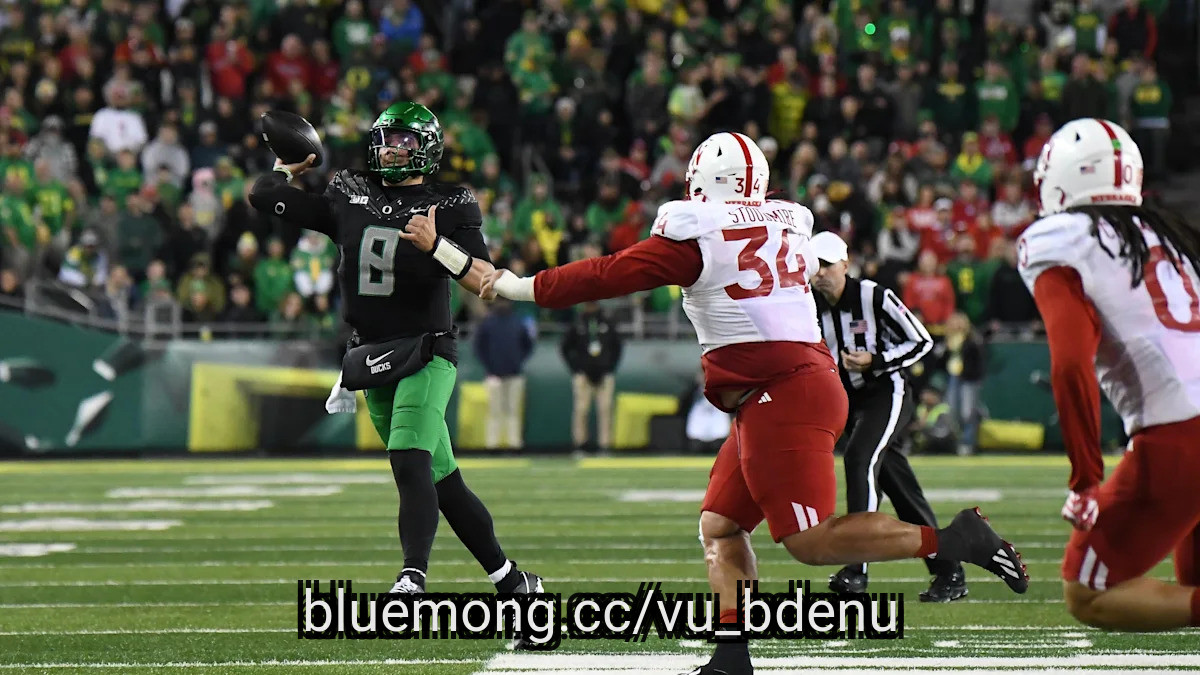
UW and Nebraska face off in Lincoln this weekend for the first time as conference foes. The long and storied history between the two teams stretches exactly 101 years and two weeks to the day between the very first match up in 1925 and this Saturday's game. That shared history primarily revolves around the four games played during the 1990s when both programs were at their peak. The 1991 game featured a furious second half comeback in Lincoln that built the momentum towards UW's eventual national championship. The Cornhuskers' return trip to Seattle in 1992 set the stage for the loudest recorded home crowd in college football history. Five years later, Nebraska returned to Montlake to get their revenge for the previous two games while on their way to their own national championship in 1997 in Tom Osborne's final season.
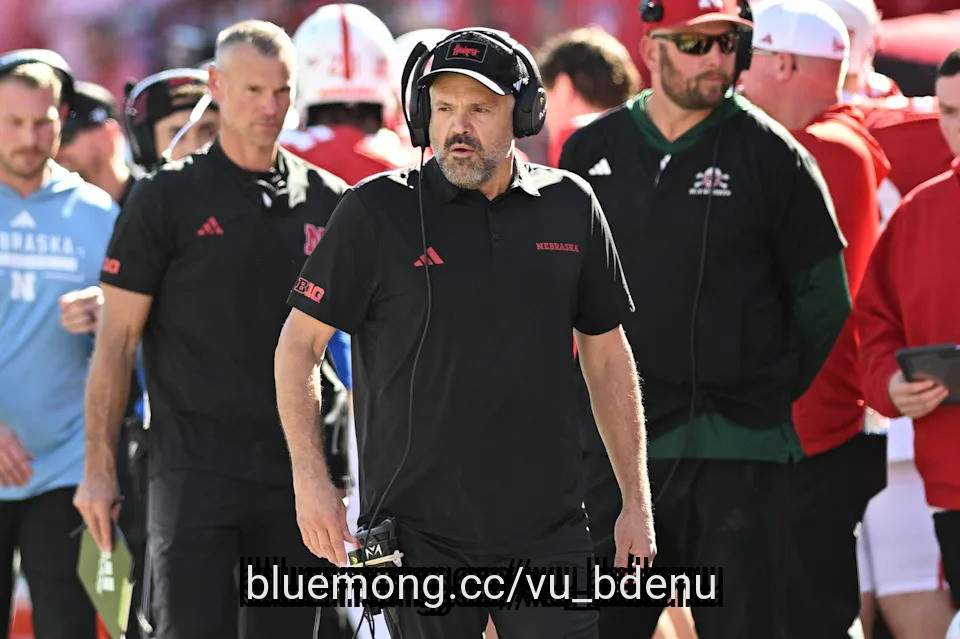
For these two programs, the current stakes of this weekend's game are much lower, although not entirely without significance. Both Washington and Nebraska enter Saturday night's matchup at a crossroads in their seasons. Nebraska sits at 5-2 overall and 2-2 in Big Ten play, but the Cornhuskers are coming off consecutive close losses to Indiana and Oregon. Despite those defeats, Matt Rhule's team has established itself as one of the league's most physical and statistically dominant defenses, keeping every game within reach through disciplined play, strong linebacker action, and excellent situational defense.
Washington, meanwhile, is 4-3 overall and 1-3 in conference play. The Huskies snapped a three-game losing streak with a 38-26 victory over Purdue before their bye week and arrive in Lincoln needing momentum to salvage their Big Ten campaign. Jedd Fisch's offense remains heavily dependent on its passing attack, ranking among the conference's better aerial units, but questions at quarterback and a struggling rushing offense persist.
Over Matt Rhule's four years at Nebraska, the Cornhuskers have embraced a physical and gritty, defensive-oriented identity as a program. Under first-year defensive coordinator, Rob Aurich, Nebraska has maintained the aggressive, fundamentally sound identity Nebraska built under Rhule. The Cornhuskers rank 14th nationally in scoring defense, 9th in total defense, and are holding opponents to just 171 passing yards and 99 rushing yards per game on average. Their suffocating rushing defense on early downs often position them in 3rd & long passing situations where they pressure packages and blanketing secondary can create plays. This formula is what has allowed Nebraska to lead the FBS in defensive 3rd down conversion percentage at just 19%. To put that statistic into perspective, Nebraska's defense has allowed just eight third down conversions in their four Big Ten conference games this season, including games with just one allowed against Maryland and Indiana.
Nebraska typically operates from a multiple-front structure, mixing even-front and odd-front looks while emphasizing gap discipline and disgui
For these two programs, the current stakes of this weekend's game are much lower, although not entirely without significance. Both Washington and Nebraska enter Saturday night's matchup at a crossroads in their seasons. Nebraska sits at 5-2 overall and 2-2 in Big Ten play, but the Cornhuskers are coming off consecutive close losses to Indiana and Oregon. Despite those defeats, Matt Rhule's team has established itself as one of the league's most physical and statistically dominant defenses, keeping every game within reach through disciplined play, strong linebacker action, and excellent situational defense.
Washington, meanwhile, is 4-3 overall and 1-3 in conference play. The Huskies snapped a three-game losing streak with a 38-26 victory over Purdue before their bye week and arrive in Lincoln needing momentum to salvage their Big Ten campaign. Jedd Fisch's offense remains heavily dependent on its passing attack, ranking among the conference's better aerial units, but questions at quarterback and a struggling rushing offense persist.
Over Matt Rhule's four years at Nebraska, the Cornhuskers have embraced a physical and gritty, defensive-oriented identity as a program. Under first-year defensive coordinator, Rob Aurich, Nebraska has maintained the aggressive, fundamentally sound identity Nebraska built under Rhule. The Cornhuskers rank 14th nationally in scoring defense, 9th in total defense, and are holding opponents to just 171 passing yards and 99 rushing yards per game on average. Their suffocating rushing defense on early downs often position them in 3rd & long passing situations where they pressure packages and blanketing secondary can create plays. This formula is what has allowed Nebraska to lead the FBS in defensive 3rd down conversion percentage at just 19%. To put that statistic into perspective, Nebraska's defense has allowed just eight third down conversions in their four Big Ten conference games this season, including games with just one allowed against Maryland and Indiana.
Nebraska typically operates from a multiple-front structure, mixing even-front and odd-front looks while emphasizing gap discipline and disgui


1 month ago
GNL paid out more in dividends than it earned in operating cash for four straight years and has already slashed its quarterly dividend from $0.53 to $0.19; PSEC's NAV fell from $6.56 to $5.71 while distributions exceeded net investment income.
IEP carries a 30% yield but posted net losses every year from 2019 through 2025 and slashed distributions from $2 to $0.50 per quarter while units dropped 66% over five years.
BEP and CWEN both rely on billions in annual financing inflows to fund distributions, with BEP's 2025 capex hitting $6.7 billion against just $1.5 billion in operating cash flow.
Building a portfolio and living off one are two completely different skills, and almost ******* ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
One stock on this list has a forward yield of about 30%. For a retiree, a number like that looks like a solid paycheck. A high yield only means something if the payout is sustainable, and each of the five names below has spent years sending out more cash than the business brought in.
#distributions #operating #slashed
IEP carries a 30% yield but posted net losses every year from 2019 through 2025 and slashed distributions from $2 to $0.50 per quarter while units dropped 66% over five years.
BEP and CWEN both rely on billions in annual financing inflows to fund distributions, with BEP's 2025 capex hitting $6.7 billion against just $1.5 billion in operating cash flow.
Building a portfolio and living off one are two completely different skills, and almost ******* ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
One stock on this list has a forward yield of about 30%. For a retiree, a number like that looks like a solid paycheck. A high yield only means something if the payout is sustainable, and each of the five names below has spent years sending out more cash than the business brought in.
#distributions #operating #slashed


1 month ago
Google and Constellation Energy announced a 20-year power purchase agreement on Tuesday to bring 890 megawatts of new nuclear capacity onto the PJM Interconnection grid, with Constellation committing more than $4.3 billion to fund the build-out.
The capacity will be generated through turbine, steam generator, and digital control system upgrades at 11 Constellation nuclear units in Illinois, Pennsylvania, and New Jersey, the companies said. The first uprate is expected to be delivered by 2028. The agreement is expected to sustain roughly 4,400 existing jobs and create approximately 7,200 new construction jobs during the building period.
Alongside the power purchase agreement, the companies entered into a separate 15-year energy supply agreement covering an additional 2,700 megawatts from Constellation's existing fleet in the PJM market, the company said.
"We're committed to meeting our growth responsibly by actively investing in clean, reliable power that brings new capacity to our nation's grids," Amanda Peterson Corio, global head of energy and power at Google, said in a statement. "Our agreement with Constellation to fund nuclear reactor uprates will strengthen the PJM grid, which serves 67 million people, all while protecting energy affordability and supporting local union jobs."
Joe Dominguez, chairman, president and CEO of Constellation, said in a statement that the collaboration "can serve as a model for how technology companies and the energy industry can work together to responsibly develop the digital economy."
#energy #capacity #Jobs
The capacity will be generated through turbine, steam generator, and digital control system upgrades at 11 Constellation nuclear units in Illinois, Pennsylvania, and New Jersey, the companies said. The first uprate is expected to be delivered by 2028. The agreement is expected to sustain roughly 4,400 existing jobs and create approximately 7,200 new construction jobs during the building period.
Alongside the power purchase agreement, the companies entered into a separate 15-year energy supply agreement covering an additional 2,700 megawatts from Constellation's existing fleet in the PJM market, the company said.
"We're committed to meeting our growth responsibly by actively investing in clean, reliable power that brings new capacity to our nation's grids," Amanda Peterson Corio, global head of energy and power at Google, said in a statement. "Our agreement with Constellation to fund nuclear reactor uprates will strengthen the PJM grid, which serves 67 million people, all while protecting energy affordability and supporting local union jobs."
Joe Dominguez, chairman, president and CEO of Constellation, said in a statement that the collaboration "can serve as a model for how technology companies and the energy industry can work together to responsibly develop the digital economy."
#energy #capacity #Jobs

1 month ago
Three decades ago, the advent and proliferation of the internet lit a fire under Wall Street's major indexes. Today, the artificial intelligence (AI) infrastructure build-out is stoking the same enthusiasm and fueling a multitrillion-dollar addressable opportunity.
Though dozens of tech-driven companies are benefiting from the AI revolution, Nvidia (NASDAQ:NVDA), Palantir Technologies (NASDAQ:PLTR), and Google parent Alphabet (NASDAQ:GOOGL)(NASDAQ:GOOG) are at the forefront of this game-changing technology.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nvidia's graphics processing units hold a virtual monopoly in AI-accelerated data centers, making it one of the most widely held stocks among retail investors.
Image source: Getty Images.
#NVIDIA #three #nvda
Though dozens of tech-driven companies are benefiting from the AI revolution, Nvidia (NASDAQ:NVDA), Palantir Technologies (NASDAQ:PLTR), and Google parent Alphabet (NASDAQ:GOOGL)(NASDAQ:GOOG) are at the forefront of this game-changing technology.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nvidia's graphics processing units hold a virtual monopoly in AI-accelerated data centers, making it one of the most widely held stocks among retail investors.
Image source: Getty Images.
#NVIDIA #three #nvda


2 months ago
On September 9, 2026, Apple Inc. (NASDAQ:AAPL) unveiled the iPhone Duo, its first foldable smartphone and the biggest change to the iPhone's design in nearly 20 years, at the first product launch event led by new CEO John Ternus since he succeeded Tim Cook on September 1. The book-style, passport-shaped device opens into a 7.6-inch display, Apple's largest ever, starts at $1,999 for the 256-gigabyte model and rises to $3,199 for 2 terabytes of storage. This makes it the most expensive iPhone Apple has ever sold, with availability set for October 23.
The iPhone Duo gives Apple Inc. (NASDAQ:AAPL) a new premium growth opportunity in a mature smartphone market. Apple entered the foldable market with the $1,999 Duo. It creates a new high-end product category within its largest hardware franchise. ******* ysts expect Apple to take a real share of the foldable market. The firm's brand strength and large installed base could help speed up use of foldable smartphones.
The Duo creates a materially different iPhone experience that could encourage upgrades and attract Android users. The device opens to a 7.6-inch display, supports side-by-side multitasking, and offers a tablet-like experience in a pocketable design. Apple also shows the Duo's ******* anium frame, custom hinge, A20 Pro chip, and Apple Intelligence features. It gives customers several reasons to pay a substantial premium for the new form factor.
The launch solidifies Apple's hardware innovation strategy under new CEO John Ternus. The Duo represents Apple's most significant iPhone redesign since the iPhone X. It gives Ternus an opportunity to reignite enthusiasm around the company's hardware portfolio. The product also expands Apple's ability to monetize its ecosystem through higher-value hardware, services, and accessories as customers spend more time using a larger, more versatile iPhone.
The $1,999 starting price could keep the Duo a niche product. Reuters reported that the global foldable market could account for less than 3% of smartphone sales in 2026. ******* ysts expect only about 6 million Duo units as Apple Inc. (NASDAQ:AAPL) enters the category. Even strong market share would turn into a relatively small contribution compared with Apple's broader iPhone business.
#iphone #aapl
The iPhone Duo gives Apple Inc. (NASDAQ:AAPL) a new premium growth opportunity in a mature smartphone market. Apple entered the foldable market with the $1,999 Duo. It creates a new high-end product category within its largest hardware franchise. ******* ysts expect Apple to take a real share of the foldable market. The firm's brand strength and large installed base could help speed up use of foldable smartphones.
The Duo creates a materially different iPhone experience that could encourage upgrades and attract Android users. The device opens to a 7.6-inch display, supports side-by-side multitasking, and offers a tablet-like experience in a pocketable design. Apple also shows the Duo's ******* anium frame, custom hinge, A20 Pro chip, and Apple Intelligence features. It gives customers several reasons to pay a substantial premium for the new form factor.
The launch solidifies Apple's hardware innovation strategy under new CEO John Ternus. The Duo represents Apple's most significant iPhone redesign since the iPhone X. It gives Ternus an opportunity to reignite enthusiasm around the company's hardware portfolio. The product also expands Apple's ability to monetize its ecosystem through higher-value hardware, services, and accessories as customers spend more time using a larger, more versatile iPhone.
The $1,999 starting price could keep the Duo a niche product. Reuters reported that the global foldable market could account for less than 3% of smartphone sales in 2026. ******* ysts expect only about 6 million Duo units as Apple Inc. (NASDAQ:AAPL) enters the category. Even strong market share would turn into a relatively small contribution compared with Apple's broader iPhone business.
#iphone #aapl

2 months ago
On September 9, 2026, Independence Realty Trust, Inc. (NYSE:IRT) and Centerspace announced a definitive all-stock merger agreement. It creates a combined middle-market apartment REIT with a pro forma equity market capitalization of about $5.0 billion and a total enterprise value of approximately $8.1 billion, encompassing more than 44,000 units.
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management

2 months ago
On September 16, Air Products (NYSE:APD) said it had signed a long-term deal to supply high-purity gases to a leading chipmaker, backed by roughly $250 million of its own money in Arizona. It is the company's second semiconductor supply win, and the two projects together carry more than $900 million of investment. That is a notable turn for a company that has been pulling back from big clean-energy projects.
The Arizona project plays to what Air Products already does. It will build, own, and operate the equipment, from hydrogen generation units and carbon dioxide purification to bulk supply for three gases: helium, hydrogen, and carbon dioxide. That means the customer's gas supply runs through equipment Air Products owns. Supply is targeted to start in phases, so the buildout can move alongside the customer's expansion plans. And this is familiar ground. Air Products has supplied electronics makers for more than 40 years, and its Chandler facility has served the Phoenix chip cluster since 1981, with a pipeline system carrying ultra-high purity nitrogen around the area.
The core business gives the deal a solid floor. In the fiscal third quarter, reported on July 30, adjusted earnings per share rose 12% to $3.47, and management lifted its full-year outlook to an adjusted $13.39 to $13.49 per share. Margins widened as well, so growth is showing up as profit. Chips appear elsewhere in the results too, since the company announced a deal to build four large air separation units to serve a chipmaker's growth in Taiwan.
The cost of the pivot is hard to ignore. On June 30, Air Products announced it would not go ahead with its Louisiana Clean Energy Complex and would discontinue a zero-carbon liquid hydrogen facility in Casa Grande, Arizona, plus other smaller clean energy distribution projects. The exits triggered roughly $2.9 billion in pre-tax charges, which is why the company posted a GAAP loss of $6.47 per share in the third quarter even as its underlying earnings grew. Adjusted results leave that hit out, but the GAAP numbers show what the retreat cost.
Owning the ****** ets also means funding them. Air Products expects about $3.5 billion of capital spending in fiscal 2026, and the Arizona plant alone is a commitment of approximately $250 million, with supply arriving in phases. The release also leaves gaps: it does not name the customer or say how long the contract runs, so the length of the revenue stream is unclear. Elsewhere, Europe's operating income rose only 2% as costs climbed, and management says it is still cautious about the economic backdrop.
#clean #adjusted
The Arizona project plays to what Air Products already does. It will build, own, and operate the equipment, from hydrogen generation units and carbon dioxide purification to bulk supply for three gases: helium, hydrogen, and carbon dioxide. That means the customer's gas supply runs through equipment Air Products owns. Supply is targeted to start in phases, so the buildout can move alongside the customer's expansion plans. And this is familiar ground. Air Products has supplied electronics makers for more than 40 years, and its Chandler facility has served the Phoenix chip cluster since 1981, with a pipeline system carrying ultra-high purity nitrogen around the area.
The core business gives the deal a solid floor. In the fiscal third quarter, reported on July 30, adjusted earnings per share rose 12% to $3.47, and management lifted its full-year outlook to an adjusted $13.39 to $13.49 per share. Margins widened as well, so growth is showing up as profit. Chips appear elsewhere in the results too, since the company announced a deal to build four large air separation units to serve a chipmaker's growth in Taiwan.
The cost of the pivot is hard to ignore. On June 30, Air Products announced it would not go ahead with its Louisiana Clean Energy Complex and would discontinue a zero-carbon liquid hydrogen facility in Casa Grande, Arizona, plus other smaller clean energy distribution projects. The exits triggered roughly $2.9 billion in pre-tax charges, which is why the company posted a GAAP loss of $6.47 per share in the third quarter even as its underlying earnings grew. Adjusted results leave that hit out, but the GAAP numbers show what the retreat cost.
Owning the ****** ets also means funding them. Air Products expects about $3.5 billion of capital spending in fiscal 2026, and the Arizona plant alone is a commitment of approximately $250 million, with supply arriving in phases. The release also leaves gaps: it does not name the customer or say how long the contract runs, so the length of the revenue stream is unclear. Elsewhere, Europe's operating income rose only 2% as costs climbed, and management says it is still cautious about the economic backdrop.
#clean #adjusted

2 months ago
Nvidia (NASDAQ:NVDA) has constructed an artificial intelligence (AI) empire over the past few years. The company sells the world's most powerful AI chips, known as graphics processing units (GPUs), and an entire portfolio of related tools that are generating triple-digit growth and record levels of revenue.
Investors have piled into Nvidia stock to gain access to this incredible growth story, and so far, they've scored a major win. The stock has soared about 800% over the past five years. But, in recent times, investors have worried about one particular challenge: competition. Though Nvidia remains in the lead, a number of companies also sell AI chips -- and these products are becoming more powerful with each update.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
These players include chip companies like Advanced Micro Devices as well as broader tech giants like Amazon (NASDAQ:AMZN). All of this has prompted some investors to pause before getting in on Nvidia stock at this stage of the AI story. Nvidia stock has climbed about 14% this year, which isn't a big leap for this stock.
Just recently, however, some bright news emerged during Amazon's earning call. In fact, these 15 words from Amazon chief Andy Jassy may eliminate Nvidia's biggest risk.
#chips
Investors have piled into Nvidia stock to gain access to this incredible growth story, and so far, they've scored a major win. The stock has soared about 800% over the past five years. But, in recent times, investors have worried about one particular challenge: competition. Though Nvidia remains in the lead, a number of companies also sell AI chips -- and these products are becoming more powerful with each update.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
These players include chip companies like Advanced Micro Devices as well as broader tech giants like Amazon (NASDAQ:AMZN). All of this has prompted some investors to pause before getting in on Nvidia stock at this stage of the AI story. Nvidia stock has climbed about 14% this year, which isn't a big leap for this stock.
Just recently, however, some bright news emerged during Amazon's earning call. In fact, these 15 words from Amazon chief Andy Jassy may eliminate Nvidia's biggest risk.
#chips

2 months ago
Applied Materials (NASDAQ:AMAT) primarily generates its revenue by designing, developing, manufacturing, and selling the critical fabrication equipment, specialized factory automation software, and materials engineering solutions utilized to produce integrated circuits for customers globally.
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily


2 months ago
If you're trying to build a consumer-focused corner of your portfolio that can grow through a lot of different economic backdrops, three names stand out right now: Church & Dwight Co. (NYSE: CHD), YETI Holdings (NYSE: YETI), and Newell Brands (NASDAQ: NWL). Each of these is making deliberate moves in 2026 and into 2027 that communicate to me more about their future than any single rocky quarter's earnings line.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Church & Dwight has built its identity on everyday products like baking soda, laundry detergents, and cleaners that quietly show up in millions of homes. In May 2026, it moved to deepen that footprint by buying the Miss Mouth's Messy Eater brand, a fast-growing, non-toxic stain remover built for parents. It's a small thing on paper, but it fits this successful company's patterns: Keep layering niche, repeat-use products into an existing distribution machine instead of chasing flashy new categories.
The company's first-quarter 2026 update backs that strategy up. Organic sales rose 5% even though reported net sales were basically flat due to past portfolio pruning, per company management. Management described 2026 as a year of "volume-driven" organic growth, meaning they're focused on selling more units to real customers, not just leaning on price increases. On top of that, Church & Dwight extended its long dividend record yet again. Although it is not quite a Dividend King, it has consistently raised its dividend for 29 years.
For investors, my advice here is straightforward: Treat Church & Dwight as a core holding in a consumer bucket. It's unlikely to deliver fireworks in a single year, but it keeps making acquisitions to deepen its understanding of existing categories.
#flashing #organic
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Church & Dwight has built its identity on everyday products like baking soda, laundry detergents, and cleaners that quietly show up in millions of homes. In May 2026, it moved to deepen that footprint by buying the Miss Mouth's Messy Eater brand, a fast-growing, non-toxic stain remover built for parents. It's a small thing on paper, but it fits this successful company's patterns: Keep layering niche, repeat-use products into an existing distribution machine instead of chasing flashy new categories.
The company's first-quarter 2026 update backs that strategy up. Organic sales rose 5% even though reported net sales were basically flat due to past portfolio pruning, per company management. Management described 2026 as a year of "volume-driven" organic growth, meaning they're focused on selling more units to real customers, not just leaning on price increases. On top of that, Church & Dwight extended its long dividend record yet again. Although it is not quite a Dividend King, it has consistently raised its dividend for 29 years.
For investors, my advice here is straightforward: Treat Church & Dwight as a core holding in a consumer bucket. It's unlikely to deliver fireworks in a single year, but it keeps making acquisitions to deepen its understanding of existing categories.
#flashing #organic


2 months ago
On September 18, Prudential Financial (NYSE:PRU) announced it will sell every share it holds in Alexforbes, a company listed on the Johannesburg Stock Exchange. Two buyers are splitting the stake. Alexforbes will repurchase roughly 372.8 million shares itself, and ARC AF Holdings will take about 74.1 million more. The package is worth about $185 million, a small number for a company managing $1.642 trillion. But the message matters more than the money. A plan Prudential laid out in August is now turning into signed agreements.
The logic is easy to follow. Prudential wants to operate in fewer places and put its money, people and attention where it thinks it can win for years. Andy Sullivan, the chief executive, says the aim is to lean harder on ***** et management, retirement and protection, and get those units working together more closely. David Legher, who leads emerging markets, called Alexforbes a successful investment, so this reads as a planned exit rather than a retreat from a problem.
The core business is giving management room to be choosy. On August 4, Prudential reported second-quarter net income of $985 million, up from $533 million a year earlier. That happened even though a charge from the yearly ***** umption update grew to $299 million from $134 million, so the underlying engine ran strong enough to absorb a bigger hit. The company also returned $743 million to shareholders in the quarter and held $4.2 billion in highly liquid ***** ets at the parent level. That does not look like a seller in a hurry.
Start with what has not happened yet. The deals are expected to close in the first half of 2027, and they still need Alexforbes shareholders to approve the buyback, along with regulatory sign-off. Until then, $185 million is an agreed price, not cash in the bank. Prudential also said New Veld's involvement continues before completion, so the company stays tied to the ***** et for now.
Then there is the size. Set against those trillions in ***** ets, this sale will not move results either way. Its value is strategic, and strategy takes years to judge. Prudential is giving up a foothold in a partnership it called important, and its remaining businesses have their own snags. Sales in Prudential of ***** an are suspended, and management said that weighed on international results even as earnings held up.
#august #money
The logic is easy to follow. Prudential wants to operate in fewer places and put its money, people and attention where it thinks it can win for years. Andy Sullivan, the chief executive, says the aim is to lean harder on ***** et management, retirement and protection, and get those units working together more closely. David Legher, who leads emerging markets, called Alexforbes a successful investment, so this reads as a planned exit rather than a retreat from a problem.
The core business is giving management room to be choosy. On August 4, Prudential reported second-quarter net income of $985 million, up from $533 million a year earlier. That happened even though a charge from the yearly ***** umption update grew to $299 million from $134 million, so the underlying engine ran strong enough to absorb a bigger hit. The company also returned $743 million to shareholders in the quarter and held $4.2 billion in highly liquid ***** ets at the parent level. That does not look like a seller in a hurry.
Start with what has not happened yet. The deals are expected to close in the first half of 2027, and they still need Alexforbes shareholders to approve the buyback, along with regulatory sign-off. Until then, $185 million is an agreed price, not cash in the bank. Prudential also said New Veld's involvement continues before completion, so the company stays tied to the ***** et for now.
Then there is the size. Set against those trillions in ***** ets, this sale will not move results either way. Its value is strategic, and strategy takes years to judge. Prudential is giving up a foothold in a partnership it called important, and its remaining businesses have their own snags. Sales in Prudential of ***** an are suspended, and management said that weighed on international results even as earnings held up.
#august #money


2 months ago
This story was originally published on Trucking Dive. To receive daily news and insights, subscribe to our free daily Trucking Dive newsletter.
Truckload LLC, doing business as Expedite Express, filed for Chapter 11 bankruptcy last week, a process typically done to reorganize operations.
The Southwest Florida-based carrier estimated its **** ets between $100,000 and $500,000 with estimated liabilities of $50,000 or less, per a voluntary petition in court. The business also suggested it had at least 50 creditors.
The business has four power units and eight drivers, according to a federal database as of early June, and provides services across North America, per its website.
Expedite Express joins a list of trucking companies declaring bankruptcy in 2026 as financial and operational challenges continue to batter the industry.
#dive #estimated #chapter
Truckload LLC, doing business as Expedite Express, filed for Chapter 11 bankruptcy last week, a process typically done to reorganize operations.
The Southwest Florida-based carrier estimated its **** ets between $100,000 and $500,000 with estimated liabilities of $50,000 or less, per a voluntary petition in court. The business also suggested it had at least 50 creditors.
The business has four power units and eight drivers, according to a federal database as of early June, and provides services across North America, per its website.
Expedite Express joins a list of trucking companies declaring bankruptcy in 2026 as financial and operational challenges continue to batter the industry.
#dive #estimated #chapter

2 months ago
Nebius Group (NASDAQ: NBIS) stock surged sharply higher Thursday morning, gaining as much as 11.2%. As of 2:27 p.m. ET, the stock had given back most of those gains, but was still up 2.1%.
The catalyst that sent the artificial intelligence (AI) and neocloud specialist higher was a report that the company is raising some prices.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is one of several neocloud operators that stockpile graphics processing units (GPUs) and provide on-demand AI processing. The company announced that it will raise the price for access to on-demand Nvidia (NASDAQ: NVDA) GPUs by roughly 20%, effective Oct. 1.
H100 chips -- $4.50 per GPU hour, up 17%
#Stock #neocloud
The catalyst that sent the artificial intelligence (AI) and neocloud specialist higher was a report that the company is raising some prices.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is one of several neocloud operators that stockpile graphics processing units (GPUs) and provide on-demand AI processing. The company announced that it will raise the price for access to on-demand Nvidia (NASDAQ: NVDA) GPUs by roughly 20%, effective Oct. 1.
H100 chips -- $4.50 per GPU hour, up 17%
#Stock #neocloud

2 months ago
Nvidia (NVDA) has been powering the ongoing artificial intelligence (AI) boom. Its graphics processing units (GPUs), central processing units (CPUs), networking products, and increasingly integrated AI systems continue to benefit from enormous investments in data center infrastructure. As a result, NVDA has continued to deliver impressive financial results.
Notably, concerns about a potential slowdown in AI development have weighed on semiconductor stocks, raising fears that the enormous spending on AI infrastructure could eventually moderate. However, demand for Nvidia's products is unlikely to slow, and the company could continue delivering extraordinary growth.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#nvda #processing #units #infrastructure
Notably, concerns about a potential slowdown in AI development have weighed on semiconductor stocks, raising fears that the enormous spending on AI infrastructure could eventually moderate. However, demand for Nvidia's products is unlikely to slow, and the company could continue delivering extraordinary growth.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#nvda #processing #units #infrastructure


2 months ago
On September 11, Elastic (NYSE:ESTC) rolled out Elasticsearch Vector Database, a new serverless offering the company says lets developers ship large-scale vector search and AI applications without stitching together the usual pile of infrastructure themselves. The launch landed less than three weeks after Elastic posted first-quarter fiscal 2027 results on August 27, for the period ended July 31, giving investors a fresh product story to weigh against a quarter that already showed accelerating growth.
The new database automates what used to require manual **** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#elastic #vector #company
The new database automates what used to require manual **** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#elastic #vector #company

2 months ago
This story was originally published on Restaurant Dive. To receive daily news and insights, subscribe to our free daily Restaurant Dive newsletter.
Chipotle will expand its Apprentice program by placing these employees in over 4,200 company-owned locations by the end of 2027, the chain said in a press release Tuesday.
Apprentices — high-performing employees working toward a management position — are currently in about 75% of its restaurants. Adding more apprentices will create additional opportunities for crew members to advance their careers, while the organization builds a deeper management bench.
These up-and-coming leaders are a key part of the chain's unit growth strategy, particularly as it expands towards 7,000 restaurants in the U.S. and Canada. This year, it expects to open between 350 to 370 company-owned units.
Developing its leadership pipeline is part of the chain's Recipe for Growth strategy, which also includes strengthening its core menu, improving brand messaging and menu innovations, modernizing its business model with technology and expanding its global reach.
#restaurant #dive #employees
Chipotle will expand its Apprentice program by placing these employees in over 4,200 company-owned locations by the end of 2027, the chain said in a press release Tuesday.
Apprentices — high-performing employees working toward a management position — are currently in about 75% of its restaurants. Adding more apprentices will create additional opportunities for crew members to advance their careers, while the organization builds a deeper management bench.
These up-and-coming leaders are a key part of the chain's unit growth strategy, particularly as it expands towards 7,000 restaurants in the U.S. and Canada. This year, it expects to open between 350 to 370 company-owned units.
Developing its leadership pipeline is part of the chain's Recipe for Growth strategy, which also includes strengthening its core menu, improving brand messaging and menu innovations, modernizing its business model with technology and expanding its global reach.
#restaurant #dive #employees

2 months ago
The U.S. fuel crisis stemming from the ongoing war in Iran has now reached the retail shelf, with Costco Wholesale (COST) nearly doubling the price of its Kirkland Signature full-synthetic motor oil from roughly $30 to $58 per 5-quart two-pack, while simultaneously capping purchases at two units per membership every seven days.
It's an extraordinary move for a retailer whose entire brand identity rests on bulk buying at deep discounts, and it signals that severe supply chain disruptions are spreading well beyond the gasoline pump.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#supply #wholesale
It's an extraordinary move for a retailer whose entire brand identity rests on bulk buying at deep discounts, and it signals that severe supply chain disruptions are spreading well beyond the gasoline pump.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#supply #wholesale

2 months ago
On August 14, the Pentagon announced framework agreements with The Boeing Company (NYSE:BA) and RTX Corporation (NYSE:RTX) to increase component production for the SM-3 Block IIA and SM-3 Block IB interceptors. Both agreements are intended to increase the output of a group of ship-fired, surface-to-air interceptors that serve as the foundation for the Aegis Ballistic Missile Defense System, the sea-based shield used by the US Navy to intercept ballistic missiles.
The announcement had little impact on the shares of both companies, with The Boeing Company (NYSE:BA) down around 0.4% and RTX Corporation (NYSE:RTX) down about 1% during the day.
RTX Corporation (NYSE:RTX) alone inked five separate Pentagon deals earlier this year to greatly boost output of Tomahawk cruise missiles, AMRAAM air-to-air missiles, and the Standard Missile family, with Tomahawk production expected to increase sixteenfold, from approximately 60 to 1,000 units per year.
Congress has provided financial support for the effort. The 2026 defense spending bill provided multiyear procurement authority for eight critical munitions and more than $6.3 billion for 13 critical munitions, while the Pentagon's fiscal 2027 budget request calls for roughly $95 billion in missile procurement.
Rising tensions with Iran have added urgency to rebuild US missile inventories. During the June 2025 12-day Israel-Iran war, US forces reportedly used more than 150 THAAD interceptors. This highlights the pressure that sustained conflict can place on American missile-defense stockpiles.
#missile #corporation #missiles #pentagon
The announcement had little impact on the shares of both companies, with The Boeing Company (NYSE:BA) down around 0.4% and RTX Corporation (NYSE:RTX) down about 1% during the day.
RTX Corporation (NYSE:RTX) alone inked five separate Pentagon deals earlier this year to greatly boost output of Tomahawk cruise missiles, AMRAAM air-to-air missiles, and the Standard Missile family, with Tomahawk production expected to increase sixteenfold, from approximately 60 to 1,000 units per year.
Congress has provided financial support for the effort. The 2026 defense spending bill provided multiyear procurement authority for eight critical munitions and more than $6.3 billion for 13 critical munitions, while the Pentagon's fiscal 2027 budget request calls for roughly $95 billion in missile procurement.
Rising tensions with Iran have added urgency to rebuild US missile inventories. During the June 2025 12-day Israel-Iran war, US forces reportedly used more than 150 THAAD interceptors. This highlights the pressure that sustained conflict can place on American missile-defense stockpiles.
#missile #corporation #missiles #pentagon

2 months ago
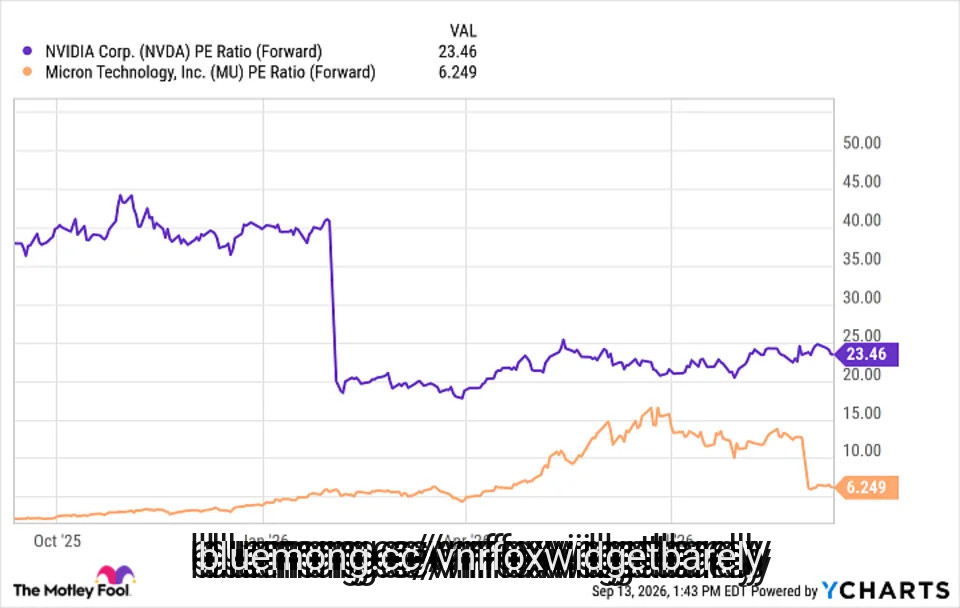
Between 2023 and 2025, Nvidia (NASDAQ: NVDA) was the market's most obvious artificial intelligence (AI) trade. During this period, the stock went parabolic, surging by 1,180% and turning the chipmaker into the world's most valuable company by market cap. On a split-adjusted basis, that was a climb from about $14 per share to $186 by the end of 2025.
Currently, Nvidia stock sits around $218, up another 17% year to date. This is what it looks like when a company owns a scarce product that's in heavy demand -- in this case, graphics processing units (GPUs).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron Technology's (NASDAQ: MU) rocket-like move came a bit later, but hit much harder. Memory chips were an afterthought during the initial GPU gold rush. But as training clusters got larger and inference workloads got hungrier, supplies of high bandwidth memory (HBM) started running short. Prices for HBM soared, and Micron stock responded epically -- rising 239% in 2025 and another 242% so far this year. This type of price action indicates the market has recognized that memory is no longer just another tech commodity -- its supply is one of the key bottlenecks dictating the pace at which data centers can be built.
Nvidia and Micron are not the same bet. While Nvidia sells engines, Micron is selling the tanks for the fuel these engines cannot operate without. This begs the question: At this point, which of these AI chip stocks would be the better one to buy and hold for the next five years?
#signal #Stock #chipmaker
Currently, Nvidia stock sits around $218, up another 17% year to date. This is what it looks like when a company owns a scarce product that's in heavy demand -- in this case, graphics processing units (GPUs).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron Technology's (NASDAQ: MU) rocket-like move came a bit later, but hit much harder. Memory chips were an afterthought during the initial GPU gold rush. But as training clusters got larger and inference workloads got hungrier, supplies of high bandwidth memory (HBM) started running short. Prices for HBM soared, and Micron stock responded epically -- rising 239% in 2025 and another 242% so far this year. This type of price action indicates the market has recognized that memory is no longer just another tech commodity -- its supply is one of the key bottlenecks dictating the pace at which data centers can be built.
Nvidia and Micron are not the same bet. While Nvidia sells engines, Micron is selling the tanks for the fuel these engines cannot operate without. This begs the question: At this point, which of these AI chip stocks would be the better one to buy and hold for the next five years?
#signal #Stock #chipmaker


2 months ago
Fast-growing stocks and artificial intelligence (AI) seem to go hand in hand, and there are several examples of stocks growing their revenue at 50%, 100%, or even 200%. But none quite touch how rapidly Nebius (NASDAQ: NBIS) is growing. During its most recent quarter, revenue rose by a jaw-dropping 454% year over year. What's even more impressive is that this growth rate is expected to last through the rest of the year, and 2027's will also be elevated.
It's starting to make a lot of sense that Nvidia (NASDAQ: NVDA) is investing in Nebius, and there's still a great buying opportunity here for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is a neocloud business that provides AI-focused cloud computing power to its clients. Among its biggest clients are Meta Platforms and Microsoft, each of which has signed multi-year deals with Nebius to expand capacity. Both Microsoft and Meta have their own data centers, and Microsoft rents out its capacity to others, so why are they renting from Nebius?
Nebius' deal with Nvidia provides it with leading hardware before others, so it's a way to gain early access to the best computing units. Furthermore, these companies like having a bit of flexibility and not having to build too many data centers, as well as getting their hands on as much computing capacity as quickly as possible.
#Microsoft
It's starting to make a lot of sense that Nvidia (NASDAQ: NVDA) is investing in Nebius, and there's still a great buying opportunity here for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is a neocloud business that provides AI-focused cloud computing power to its clients. Among its biggest clients are Meta Platforms and Microsoft, each of which has signed multi-year deals with Nebius to expand capacity. Both Microsoft and Meta have their own data centers, and Microsoft rents out its capacity to others, so why are they renting from Nebius?
Nebius' deal with Nvidia provides it with leading hardware before others, so it's a way to gain early access to the best computing units. Furthermore, these companies like having a bit of flexibility and not having to build too many data centers, as well as getting their hands on as much computing capacity as quickly as possible.
#Microsoft


2 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
The oil crisis is leaking into other parts of the car. Costco, the land of big and cheap, flipped the script and doubled the price of its full-synthetic motor oil and started rationing purchases. As crude pushes toward $100 a barrel, a 10-quart case that cost roughly $30 now runs $57.99, with purchases capped at two units per member per week.
U.S. diesel crossed $6 a gallon for the first time this week, and global oil inventories have drawn down more than 500 million barrels since the U.S.-Iran conflict began. This is affecting the entire crude industrial complex.
Base oil, which is the feedstock for motor oil, comes from the same barrel as gasoline and diesel so when refiners can earn more finishing crude into fuel than into lubricants, lubricant stock gets squeezed first.
The pressure for Costco, however, is more intense: Its signature Kirkland oil carries GM's Dexos1 Gen 3 certification, which requires manufacturers to pay GM separately per product and per unit sold. As a result, and much against its brand ethos, changing your own oil with Kirkland product now costs roughly what an independent shop would charge, thus eroding the DIY savings case entirely.
#crude #motor #case #week
The oil crisis is leaking into other parts of the car. Costco, the land of big and cheap, flipped the script and doubled the price of its full-synthetic motor oil and started rationing purchases. As crude pushes toward $100 a barrel, a 10-quart case that cost roughly $30 now runs $57.99, with purchases capped at two units per member per week.
U.S. diesel crossed $6 a gallon for the first time this week, and global oil inventories have drawn down more than 500 million barrels since the U.S.-Iran conflict began. This is affecting the entire crude industrial complex.
Base oil, which is the feedstock for motor oil, comes from the same barrel as gasoline and diesel so when refiners can earn more finishing crude into fuel than into lubricants, lubricant stock gets squeezed first.
The pressure for Costco, however, is more intense: Its signature Kirkland oil carries GM's Dexos1 Gen 3 certification, which requires manufacturers to pay GM separately per product and per unit sold. As a result, and much against its brand ethos, changing your own oil with Kirkland product now costs roughly what an independent shop would charge, thus eroding the DIY savings case entirely.
#crude #motor #case #week

2 months ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend


2 months ago
New York-based Take-Two Interactive Software, Inc. (TTWO) is a major global video-game publisher and developer behind some of the industry's biggest franchises, including Grand Theft Auto, Red Dead Redemption, NBA 2K, Borderlands, Civilization, WWE 2K, and Zynga's mobile games. Its business spans console, PC, and mobile gaming through three key labels: Rockstar Games, 2K, and Zynga.
Companies with a market cap between $10 billion and $200 billion are typically referred to as "large-cap stocks, and TTWO, with a market cap of $41.7 billion, fits the label. The company's biggest competitive advantage is its deep portfolio of highly recognizable intellectual property. Rockstar's Grand Theft Auto franchise alone has sold more than 470 million units, while GTA V has surpassed 230 million units sold worldwide. Moreover, Grand Theft Auto VI is scheduled for Nov. 19, 2026, alongside new installments of NBA 2K, WWE 2K, PGA TOUR 2K and other franchises.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#grand #theft #ttwo
Companies with a market cap between $10 billion and $200 billion are typically referred to as "large-cap stocks, and TTWO, with a market cap of $41.7 billion, fits the label. The company's biggest competitive advantage is its deep portfolio of highly recognizable intellectual property. Rockstar's Grand Theft Auto franchise alone has sold more than 470 million units, while GTA V has surpassed 230 million units sold worldwide. Moreover, Grand Theft Auto VI is scheduled for Nov. 19, 2026, alongside new installments of NBA 2K, WWE 2K, PGA TOUR 2K and other franchises.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#grand #theft #ttwo

2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
The oil crisis is leaking into other parts of the car. Costco, the land of big and cheap, flipped the script and doubled the price of its full-synthetic motor oil and started rationing purchases. As crude pushes toward $100 a barrel, a 10-quart case that cost roughly $30 now runs $57.99, with purchases capped at two units per member per week.
U.S. diesel crossed $6 a gallon for the first time this week, and global oil inventories have drawn down more than 500 million barrels since the U.S.-Iran conflict began. This is affecting the entire crude industrial complex.
Base oil, which is the feedstock for motor oil, comes from the same barrel as gasoline and diesel so when refiners can earn more finishing crude into fuel than into lubricants, lubricant stock gets squeezed first.
The pressure for Costco, however, is more intense: Its signature Kirkland oil carries GM's Dexos1 Gen 3 certification, which requires manufacturers to pay GM separately per product and per unit sold. As a result, and much against its brand ethos, changing your own oil with Kirkland product now costs roughly what an independent shop would charge, thus eroding the DIY savings case entirely.
#costco #Stock #roughly
The oil crisis is leaking into other parts of the car. Costco, the land of big and cheap, flipped the script and doubled the price of its full-synthetic motor oil and started rationing purchases. As crude pushes toward $100 a barrel, a 10-quart case that cost roughly $30 now runs $57.99, with purchases capped at two units per member per week.
U.S. diesel crossed $6 a gallon for the first time this week, and global oil inventories have drawn down more than 500 million barrels since the U.S.-Iran conflict began. This is affecting the entire crude industrial complex.
Base oil, which is the feedstock for motor oil, comes from the same barrel as gasoline and diesel so when refiners can earn more finishing crude into fuel than into lubricants, lubricant stock gets squeezed first.
The pressure for Costco, however, is more intense: Its signature Kirkland oil carries GM's Dexos1 Gen 3 certification, which requires manufacturers to pay GM separately per product and per unit sold. As a result, and much against its brand ethos, changing your own oil with Kirkland product now costs roughly what an independent shop would charge, thus eroding the DIY savings case entirely.
#costco #Stock #roughly
2 months ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#devices #NASDAQ #letter
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#devices #NASDAQ #letter
2 months ago
New York-based Take-Two Interactive Software, Inc. (TTWO) is a major global video-game publisher and developer behind some of the industry's biggest franchises, including Grand Theft Auto, Red Dead Redemption, NBA 2K, Borderlands, Civilization, WWE 2K, and Zynga's mobile games. Its business spans console, PC, and mobile gaming through three key labels: Rockstar Games, 2K, and Zynga.
Companies with a market cap between $10 billion and $200 billion are typically referred to as "large-cap stocks, and TTWO, with a market cap of $41.7 billion, fits the label. The company's biggest competitive advantage is its deep portfolio of highly recognizable intellectual property. Rockstar's Grand Theft Auto franchise alone has sold more than 470 million units, while GTA V has surpassed 230 million units sold worldwide. Moreover, Grand Theft Auto VI is scheduled for Nov. 19, 2026, alongside new installments of NBA 2K, WWE 2K, PGA TOUR 2K and other franchises.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#theft #auto #Stock #biggest
Companies with a market cap between $10 billion and $200 billion are typically referred to as "large-cap stocks, and TTWO, with a market cap of $41.7 billion, fits the label. The company's biggest competitive advantage is its deep portfolio of highly recognizable intellectual property. Rockstar's Grand Theft Auto franchise alone has sold more than 470 million units, while GTA V has surpassed 230 million units sold worldwide. Moreover, Grand Theft Auto VI is scheduled for Nov. 19, 2026, alongside new installments of NBA 2K, WWE 2K, PGA TOUR 2K and other franchises.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#theft #auto #Stock #biggest



2 months ago
On September 11, Elastic (NYSE:ESTC) rolled out Elasticsearch Vector Database, a new serverless offering the company says lets developers ship large-scale vector search and AI applications without stitching together the usual pile of infrastructure themselves. The launch landed less than three weeks after Elastic posted first-quarter fiscal 2027 results on August 27, for the period ended July 31, giving investors a fresh product story to weigh against a quarter that already showed accelerating growth.
The new database automates what used to require manual ***** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#quarter #fiscal #year #operating
The new database automates what used to require manual ***** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#quarter #fiscal #year #operating

2 months ago
On September 14, Coda Octopus Group (NASDAQ:CODA) reported third-quarter fiscal 2026 results that quietly crossed a threshold the company had never reached in its public history: positive retained earnings, after years of operating at an accumulated deficit. Revenue rose 9.2% year over year to $7.7 million, and pretax income climbed 16% to $1.8 million, even as instability in the Middle East knocked down the marine technology unit that has long been the company's calling card. The reason the quarter held together anyway comes down to where the growth actually showed up.
Defense engineering revenue jumped 68.3% to $2.7 million during the quarter, and the momentum did not look like a one-time ****** p. Sustainment spares orders have already topped $2.4 million year to date, and one prime contractor customer's new multiyear repair and sustainment award has since fed additional subcontract work back to Coda Octopus. On the newer end of the business, the company's US defense engineering team is now supporting several prime contractors building rugged, deployable RF electronic warfare systems for unmanned platforms, helicopters, airborne pods, and ground vehicles.
The DAVID diving system added its own proof points. Coda Octopus has delivered 24 DAVID systems to the US Navy to date, including 16 untethered units earlier in the year, and the Navy's authorization for use ****** sment on that untethered system was completed during the year, clearing it for full operational deployment. Since the quarter closed, the Navy has placed about $1.4 million in additional orders covering tethered systems and DAVID Flex adoption, including four units bought specifically for diving school and academy training. A European navy that already bought in is also expected to firm up a procurement roadmap later this year, while the new Nano sonar is being tested by subsea robotics OEMs and research groups for next-generation autonomous platforms. All of that arrived alongside $31.7 million in cash, no debt, and a balance sheet management says can fund acquisitions.
None of that offsets what happened in marine technology, the segment that still generates the largest share of revenue. Marine tech sales fell 15.2% to $3.4 million as customer activity slowed across the Middle East and parts of Asia, and hardware revenue specifically dropped 17.8% to $2.3 million. Improved rental utilization, with rental revenue up 131.1%, cushioned the blow but did not reverse it, and management has tied the weakness directly to geopolitical conditions it cannot control.
#revenue #david
Defense engineering revenue jumped 68.3% to $2.7 million during the quarter, and the momentum did not look like a one-time ****** p. Sustainment spares orders have already topped $2.4 million year to date, and one prime contractor customer's new multiyear repair and sustainment award has since fed additional subcontract work back to Coda Octopus. On the newer end of the business, the company's US defense engineering team is now supporting several prime contractors building rugged, deployable RF electronic warfare systems for unmanned platforms, helicopters, airborne pods, and ground vehicles.
The DAVID diving system added its own proof points. Coda Octopus has delivered 24 DAVID systems to the US Navy to date, including 16 untethered units earlier in the year, and the Navy's authorization for use ****** sment on that untethered system was completed during the year, clearing it for full operational deployment. Since the quarter closed, the Navy has placed about $1.4 million in additional orders covering tethered systems and DAVID Flex adoption, including four units bought specifically for diving school and academy training. A European navy that already bought in is also expected to firm up a procurement roadmap later this year, while the new Nano sonar is being tested by subsea robotics OEMs and research groups for next-generation autonomous platforms. All of that arrived alongside $31.7 million in cash, no debt, and a balance sheet management says can fund acquisitions.
None of that offsets what happened in marine technology, the segment that still generates the largest share of revenue. Marine tech sales fell 15.2% to $3.4 million as customer activity slowed across the Middle East and parts of Asia, and hardware revenue specifically dropped 17.8% to $2.3 million. Improved rental utilization, with rental revenue up 131.1%, cushioned the blow but did not reverse it, and management has tied the weakness directly to geopolitical conditions it cannot control.
#revenue #david

2 months ago
Broadcom (NASDAQ: AVGO) has been one of the quieter top-performing investments throughout the AI arms race. If you invested $5,000 at the start of the AI arms race in 2023, that sum is now worth more than $32,000. However, investors must look forward, not backward. Luckily, Broadcom's future is brighter than ever, and I think a $5,000 investment now could lead to a much larger sum later.
While it won't be able to repeat the incredible performance it gave investors over the past three and a half years, I think it's still worth buying now.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Broadcom does a lot of different things as a company, ranging from software to virtual desktops to networking hardware. However, the most exciting product development over the past few years has been its custom AI chips. Instead of going head-to-head with companies in the GPU ***** e, which excel at all types of workloads, Broadcom is partnering directly with AI hyperscalers to develop chips purpose-built for their workloads. These units can provide better performance at a lower price tag than their GPU counterparts, but only when the workloads are properly configured.
Broadcom has several big-name clients, including Alphabet (NASDAQ: GOOG) (NASDAQ: GOOGL), Meta Platforms (NASDAQ: META), OpenAI, and Anthropic, to name a few. These companies have all chosen to partner with Broadcom over some other competitors in this ***** e, and the results have been simply incredible.
#NVIDIA #meta
While it won't be able to repeat the incredible performance it gave investors over the past three and a half years, I think it's still worth buying now.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Broadcom does a lot of different things as a company, ranging from software to virtual desktops to networking hardware. However, the most exciting product development over the past few years has been its custom AI chips. Instead of going head-to-head with companies in the GPU ***** e, which excel at all types of workloads, Broadcom is partnering directly with AI hyperscalers to develop chips purpose-built for their workloads. These units can provide better performance at a lower price tag than their GPU counterparts, but only when the workloads are properly configured.
Broadcom has several big-name clients, including Alphabet (NASDAQ: GOOG) (NASDAQ: GOOGL), Meta Platforms (NASDAQ: META), OpenAI, and Anthropic, to name a few. These companies have all chosen to partner with Broadcom over some other competitors in this ***** e, and the results have been simply incredible.
#NVIDIA #meta


