

2 months ago
Advanced Micro Devices (NASDAQ: AMD) stock rose 6.3% on Thursday, Sept. 17, 2026, after a neocloud operator said a price hike was coming for the use of chips across its stack, with AMD CPUs seeing a substantial **** p.
The S&P 500 and the Nasdaq Composite rose 1.1% and 1.7%, respectively, on Thursday.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius, which rents out the use of chips from AMD and Nvidia, told customers it would soon charge a higher rate. Nebius said that Nvidia GPU prices would increase from 17% to 21%, while AMD's EPYC Genoa CPU rates will increase 25%, while supply constrained memory offerings would see a 41% **** p.
The announcement helps reassure investors that compute demand is still strong across AI, including demand for CPUs, which AMD has pushed in recent months. The company's stock was also rising amid a broader rally across the stock market.
#signal #thursday
The S&P 500 and the Nasdaq Composite rose 1.1% and 1.7%, respectively, on Thursday.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius, which rents out the use of chips from AMD and Nvidia, told customers it would soon charge a higher rate. Nebius said that Nvidia GPU prices would increase from 17% to 21%, while AMD's EPYC Genoa CPU rates will increase 25%, while supply constrained memory offerings would see a 41% **** p.
The announcement helps reassure investors that compute demand is still strong across AI, including demand for CPUs, which AMD has pushed in recent months. The company's stock was also rising amid a broader rally across the stock market.
#signal #thursday


2 months ago
Nebius Group (NASDAQ: NBIS) stock surged sharply higher Thursday morning, gaining as much as 11.2%. As of 2:27 p.m. ET, the stock had given back most of those gains, but was still up 2.1%.
The catalyst that sent the artificial intelligence (AI) and neocloud specialist higher was a report that the company is raising some prices.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is one of several neocloud operators that stockpile graphics processing units (GPUs) and provide on-demand AI processing. The company announced that it will raise the price for access to on-demand Nvidia (NASDAQ: NVDA) GPUs by roughly 20%, effective Oct. 1.
H100 chips -- $4.50 per GPU hour, up 17%
#Stock #neocloud
The catalyst that sent the artificial intelligence (AI) and neocloud specialist higher was a report that the company is raising some prices.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is one of several neocloud operators that stockpile graphics processing units (GPUs) and provide on-demand AI processing. The company announced that it will raise the price for access to on-demand Nvidia (NASDAQ: NVDA) GPUs by roughly 20%, effective Oct. 1.
H100 chips -- $4.50 per GPU hour, up 17%
#Stock #neocloud


2 months ago
Comments from Anthropic CEO Dario Amodei and OpenAI CEO Sam Altman calling for a more measured approach to frontier AI development contributed to a sharp selloff across neoclouds and data center stocks. Bernstein identified CoreWeave Inc. (NASDAQ:CRWV) as the most exposed name because of its rural footprint and focus on AI training. The concern represents a genuine structural argument. However, it marks the second time this year that the same group of stocks has faced concerns over the sustainability of AI demand. There is also an important tension within Bernstein's own note, which highlights CoreWeave's exposure while acknowledging that most of its backlog remains shielded by contracts.
Bernstein cautioned that a slowdown in AI training could weigh on data center developers. The warning followed Amodei's weekend comments urging the industry to deliberately slow the pace of frontier AI capability gains, along with similar remarks from Sam Altman. According to ****** yst Madison Rezaei, slower training activity would likely reduce demand for rural data center sites designed for latency-insensitive workloads. The ****** yst pointed out that rural and Tier 3 markets account for 70% of the industry's 488GW pipeline. CoreWeave was identified as the most exposed name in the firm's coverage. ****** yst Madison Rezaei remarked:
We estimate that 25% of their existing active U.S. power, with an additional ~74% of their contracted power, is situated in Tier 3 and Tier 4 markets.
However, there is a key counterpoint within Bernstein's own note:
The backlog is primarily comprised of take-or-pay contracts, so we do not anticipate a threat there but could see a pullback in demand for the contracted-not-yet-sold rural power if training development slows.
#training #analyst
Bernstein cautioned that a slowdown in AI training could weigh on data center developers. The warning followed Amodei's weekend comments urging the industry to deliberately slow the pace of frontier AI capability gains, along with similar remarks from Sam Altman. According to ****** yst Madison Rezaei, slower training activity would likely reduce demand for rural data center sites designed for latency-insensitive workloads. The ****** yst pointed out that rural and Tier 3 markets account for 70% of the industry's 488GW pipeline. CoreWeave was identified as the most exposed name in the firm's coverage. ****** yst Madison Rezaei remarked:
We estimate that 25% of their existing active U.S. power, with an additional ~74% of their contracted power, is situated in Tier 3 and Tier 4 markets.
However, there is a key counterpoint within Bernstein's own note:
The backlog is primarily comprised of take-or-pay contracts, so we do not anticipate a threat there but could see a pullback in demand for the contracted-not-yet-sold rural power if training development slows.
#training #analyst

2 months ago
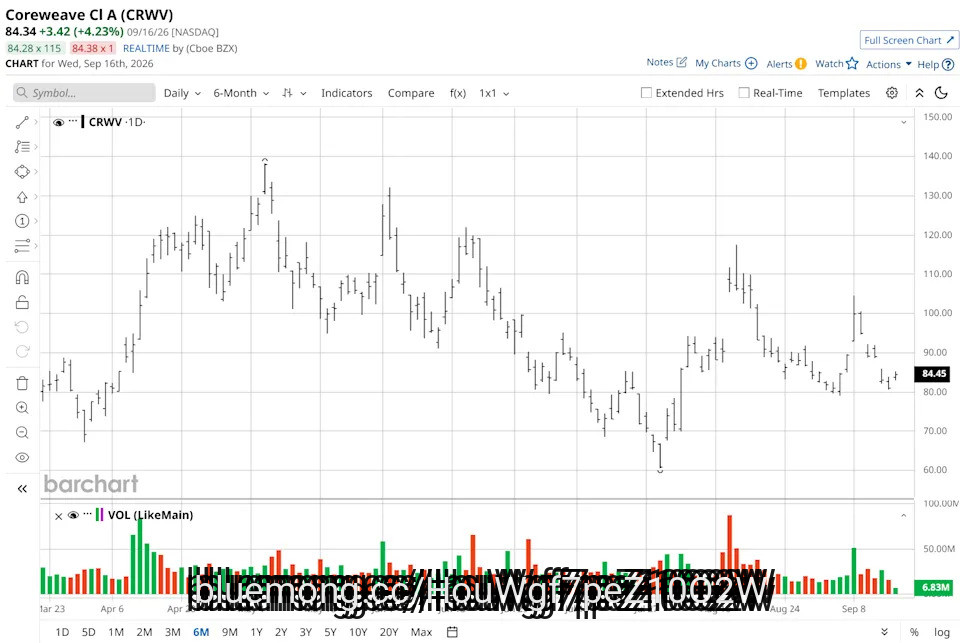
CoreWeave (CRWV), purely from the perspective of revenue growth, still looks attractive. However, CRWV stock is telling a different story. In the past 52 weeks, the stock has corrected by 29%.
Amidst this weak performance, Bernstein issued a warning. That "slowdown in the training of artificial intelligence models could negatively affect data center developers and neoclouds." Further, CoreWeave is one of the "most exposed" to this risk.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Why It's Time to Load Up on Nvidia Stock
#bernstein #billionaire #charlie
Amidst this weak performance, Bernstein issued a warning. That "slowdown in the training of artificial intelligence models could negatively affect data center developers and neoclouds." Further, CoreWeave is one of the "most exposed" to this risk.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Why It's Time to Load Up on Nvidia Stock
#bernstein #billionaire #charlie


2 months ago
Fast-growing stocks and artificial intelligence (AI) seem to go hand in hand, and there are several examples of stocks growing their revenue at 50%, 100%, or even 200%. But none quite touch how rapidly Nebius (NASDAQ: NBIS) is growing. During its most recent quarter, revenue rose by a jaw-dropping 454% year over year. What's even more impressive is that this growth rate is expected to last through the rest of the year, and 2027's will also be elevated.
It's starting to make a lot of sense that Nvidia (NASDAQ: NVDA) is investing in Nebius, and there's still a great buying opportunity here for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is a neocloud business that provides AI-focused cloud computing power to its clients. Among its biggest clients are Meta Platforms and Microsoft, each of which has signed multi-year deals with Nebius to expand capacity. Both Microsoft and Meta have their own data centers, and Microsoft rents out its capacity to others, so why are they renting from Nebius?
Nebius' deal with Nvidia provides it with leading hardware before others, so it's a way to gain early access to the best computing units. Furthermore, these companies like having a bit of flexibility and not having to build too many data centers, as well as getting their hands on as much computing capacity as quickly as possible.
#Microsoft
It's starting to make a lot of sense that Nvidia (NASDAQ: NVDA) is investing in Nebius, and there's still a great buying opportunity here for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is a neocloud business that provides AI-focused cloud computing power to its clients. Among its biggest clients are Meta Platforms and Microsoft, each of which has signed multi-year deals with Nebius to expand capacity. Both Microsoft and Meta have their own data centers, and Microsoft rents out its capacity to others, so why are they renting from Nebius?
Nebius' deal with Nvidia provides it with leading hardware before others, so it's a way to gain early access to the best computing units. Furthermore, these companies like having a bit of flexibility and not having to build too many data centers, as well as getting their hands on as much computing capacity as quickly as possible.
#Microsoft


2 months ago
A company that specializes in autonomous power deployment said it has raised $31.8 million to scale its operations, with investments from major groups including Google and Bill Gates-founded Breakthrough Energy Ventures (BEV). California-based Planted said the new capital expands its robotic fleet. The company said the funding also supports the launch of Sage, its next-generation robot, as demand outpaces the company's current capacity.Planted on September 15 said the funding round was led by Piva Capital and RA Capital Management Planetary Health, with participation from Gigascale Capital and Open AI-backer Khosla Ventures, along with Google and BEV. Gigascale Capital was founded by former Meta executive Mike Schroepfer."Globally, solar needs to be deployed about five times faster than it is today to hit the scale experts project we'll need by 2050, and the gap is growing as the industry confronts constraints involving supply chains, land, interconnection, and skilled labor," said Eric Brown, CEO of Planted. "The way to close that gap is to turn the construction of a power plant into a manufacturing problem: building robots and deployment systems, not just projects. We have robots in the field proving the model works today. This round is how we scale it."
Brown's group on Tuesday said a record 664 GW of solar photovoltaic power was installed worldwide last year, but noted terawatts of new generation capacity are needed to meet projected demand. The company said it combines planning software, high-density terrain-following solar arrays, storage, and field robotics into one system, which enables Planted to build on parcels of land that legacy trackers cannot use. The company said its system also delivers twice the energy per acre, resulting in smaller project footprints and a lower profile on the landscape.Planted said its array "is simplified, designed for automation, and defined in software," and thus can deliver new power generation capacity in months rather than years. Planted's most recent build, a 28-MW behind-the-meter project serving a neocloud data center, went from first call to power in 10 months, with field construction completed in under three months.Planted on Tuesday said the company's development model "is proven and bankable," and noted its projects carry independent engineering validation and project financing. The company completed Bowes Solar, an 11-MW project in Illinois for Cultivate Power, and will next build Aligned Climate Capital's Armoracia project on 16 acres, 10 fewer than the original design required. The denser redesign moved the project through local review after the initial layout was rejected, according to the company. Planted, which deployed more than 10 MW in 2025, is on track for 100 MW in 2026, a 10x jump in a single year, with a project pipeline of more than 20 GW.The company said Sage, the next-generation robot, will be deployed later this year.
#Solar
Brown's group on Tuesday said a record 664 GW of solar photovoltaic power was installed worldwide last year, but noted terawatts of new generation capacity are needed to meet projected demand. The company said it combines planning software, high-density terrain-following solar arrays, storage, and field robotics into one system, which enables Planted to build on parcels of land that legacy trackers cannot use. The company said its system also delivers twice the energy per acre, resulting in smaller project footprints and a lower profile on the landscape.Planted said its array "is simplified, designed for automation, and defined in software," and thus can deliver new power generation capacity in months rather than years. Planted's most recent build, a 28-MW behind-the-meter project serving a neocloud data center, went from first call to power in 10 months, with field construction completed in under three months.Planted on Tuesday said the company's development model "is proven and bankable," and noted its projects carry independent engineering validation and project financing. The company completed Bowes Solar, an 11-MW project in Illinois for Cultivate Power, and will next build Aligned Climate Capital's Armoracia project on 16 acres, 10 fewer than the original design required. The denser redesign moved the project through local review after the initial layout was rejected, according to the company. Planted, which deployed more than 10 MW in 2025, is on track for 100 MW in 2026, a 10x jump in a single year, with a project pipeline of more than 20 GW.The company said Sage, the next-generation robot, will be deployed later this year.
#Solar


2 months ago
A company that specializes in autonomous power deployment said it has raised $31.8 million to scale its operations, with investments from major groups including Google and Bill Gates-founded Breakthrough Energy Ventures (BEV). California-based Planted said the new capital expands its robotic fleet. The company said the funding also supports the launch of Sage, its next-generation robot, as demand outpaces the company's current capacity.Planted on September 15 said the funding round was led by Piva Capital and RA Capital Management Planetary Health, with participation from Gigascale Capital and Open AI-backer Khosla Ventures, along with Google and BEV. Gigascale Capital was founded by former Meta executive Mike Schroepfer."Globally, solar needs to be deployed about five times faster than it is today to hit the scale experts project we'll need by 2050, and the gap is growing as the industry confronts constraints involving supply chains, land, interconnection, and skilled labor," said Eric Brown, CEO of Planted. "The way to close that gap is to turn the construction of a power plant into a manufacturing problem: building robots and deployment systems, not just projects. We have robots in the field proving the model works today. This round is how we scale it."
Brown's group on Tuesday said a record 664 GW of solar photovoltaic power was installed worldwide last year, but noted terawatts of new generation capacity are needed to meet projected demand. The company said it combines planning software, high-density terrain-following solar arrays, storage, and field robotics into one system, which enables Planted to build on parcels of land that legacy trackers cannot use. The company said its system also delivers twice the energy per acre, resulting in smaller project footprints and a lower profile on the landscape.Planted said its array "is simplified, designed for automation, and defined in software," and thus can deliver new power generation capacity in months rather than years. Planted's most recent build, a 28-MW behind-the-meter project serving a neocloud data center, went from first call to power in 10 months, with field construction completed in under three months.Planted on Tuesday said the company's development model "is proven and bankable," and noted its projects carry independent engineering validation and project financing. The company completed Bowes Solar, an 11-MW project in Illinois for Cultivate Power, and will next build Aligned Climate Capital's Armoracia project on 16 acres, 10 fewer than the original design required. The denser redesign moved the project through local review after the initial layout was rejected, according to the company. Planted, which deployed more than 10 MW in 2025, is on track for 100 MW in 2026, a 10x jump in a single year, with a project pipeline of more than 20 GW.The company said Sage, the next-generation robot, will be deployed later this year.
#project #next
Brown's group on Tuesday said a record 664 GW of solar photovoltaic power was installed worldwide last year, but noted terawatts of new generation capacity are needed to meet projected demand. The company said it combines planning software, high-density terrain-following solar arrays, storage, and field robotics into one system, which enables Planted to build on parcels of land that legacy trackers cannot use. The company said its system also delivers twice the energy per acre, resulting in smaller project footprints and a lower profile on the landscape.Planted said its array "is simplified, designed for automation, and defined in software," and thus can deliver new power generation capacity in months rather than years. Planted's most recent build, a 28-MW behind-the-meter project serving a neocloud data center, went from first call to power in 10 months, with field construction completed in under three months.Planted on Tuesday said the company's development model "is proven and bankable," and noted its projects carry independent engineering validation and project financing. The company completed Bowes Solar, an 11-MW project in Illinois for Cultivate Power, and will next build Aligned Climate Capital's Armoracia project on 16 acres, 10 fewer than the original design required. The denser redesign moved the project through local review after the initial layout was rejected, according to the company. Planted, which deployed more than 10 MW in 2025, is on track for 100 MW in 2026, a 10x jump in a single year, with a project pipeline of more than 20 GW.The company said Sage, the next-generation robot, will be deployed later this year.
#project #next


2 months ago
When a caller inquired about IREN Limited (NASDAQ:IREN) during the lightning round on September 3, Mad Money host Jim Cramer said:
If you're going to do neocloud, you got to do, the only one I like is CoreWeave with Michael Intrator. The others I think are too speculative for me.
The two companies are at different stages of building their AI businesses. CoreWeave, Inc. (NASDAQ:CRWV) reported $2.575 billion of second-quarter revenue, up approximately 112% from a year earlier. Its revenue backlog stood at approximately $104 billion as of June 30, excluding more than $25 billion of additional customer commitments secured in early July. Furthermore, active power reached 1.5 gigawatts, while contracted power rose to approximately 3.7 gigawatts. CEO Michael Intrator said on the company's second-quarter earnings call that "our near-term capacity remains effectively sold out." He also described broadening customer demand and rapidly expanding enterprise adoption.
Meanwhile, IREN Limited's (NASDAQ:IREN) AI Cloud Services revenue reached $128.8 million in fiscal 2026, compared with $16.4 million a year earlier. Total fiscal 2026 revenue was $707 million, including $578.2 million from Bitcoin mining. The company reported $4 billion of contracted AI annualized run rate revenue for 2026 capacity, with $1 billion of operating ARR as of August 26. CEO Daniel Roberts said on August 27 that its 2026 capacity was "largely sold out." Roberts said recent three-year contracts represented more than $20 million of revenue per megawatt and that customer prepayments represented 45%-55% of ****** ociated GPU capital expenditures.
CoreWeave, Inc.'s (NASDAQ:CRWV) capital requirements remain substantial. The company spent $9.4 billion on capital expenditures in the second quarter and raised its 2026 CapEx forecast to $35 billion-$39 billion. It also reported $640 million of net interest expense and a $626 million net loss for the quarter. Total debt stood at $35.6 billion as of June 30.
#billion #revenue
If you're going to do neocloud, you got to do, the only one I like is CoreWeave with Michael Intrator. The others I think are too speculative for me.
The two companies are at different stages of building their AI businesses. CoreWeave, Inc. (NASDAQ:CRWV) reported $2.575 billion of second-quarter revenue, up approximately 112% from a year earlier. Its revenue backlog stood at approximately $104 billion as of June 30, excluding more than $25 billion of additional customer commitments secured in early July. Furthermore, active power reached 1.5 gigawatts, while contracted power rose to approximately 3.7 gigawatts. CEO Michael Intrator said on the company's second-quarter earnings call that "our near-term capacity remains effectively sold out." He also described broadening customer demand and rapidly expanding enterprise adoption.
Meanwhile, IREN Limited's (NASDAQ:IREN) AI Cloud Services revenue reached $128.8 million in fiscal 2026, compared with $16.4 million a year earlier. Total fiscal 2026 revenue was $707 million, including $578.2 million from Bitcoin mining. The company reported $4 billion of contracted AI annualized run rate revenue for 2026 capacity, with $1 billion of operating ARR as of August 26. CEO Daniel Roberts said on August 27 that its 2026 capacity was "largely sold out." Roberts said recent three-year contracts represented more than $20 million of revenue per megawatt and that customer prepayments represented 45%-55% of ****** ociated GPU capital expenditures.
CoreWeave, Inc.'s (NASDAQ:CRWV) capital requirements remain substantial. The company spent $9.4 billion on capital expenditures in the second quarter and raised its 2026 CapEx forecast to $35 billion-$39 billion. It also reported $640 million of net interest expense and a $626 million net loss for the quarter. Total debt stood at $35.6 billion as of June 30.
#billion #revenue
2 months ago
CNBC reported that NVIDIA Corporation (NASDAQ:NVDA) CFO Colette Kress told investors on August 26 that fiscal 2028 revenue growth will reach 70%, far above the 44% average **** yst estimate tracked by LSEG, marking the company's first-ever year-ahead revenue forecast.
Applied to the roughly $396 billion consensus estimate for fiscal 2027, that guidance implies fiscal 2028 revenue near $673 billion to $700 billion. It would put Nvidia ahead of Apple and Alphabet and behind only Amazon among U.S. tech companies by revenue. The forecast followed fiscal second-quarter results that beat expectations across the board: revenue more than doubled to $96.22 billion, up 106% year over year, with data center revenue of $89 billion, up 117%, now making up 92% of total sales.
CEO Jensen Huang told investors AI has reached the point where it is doing productive, profitable work and that computing capacity itself is now translating directly into revenue. Shares jumped roughly 8.7% on the news, lifting the broader semiconductor sector. Management said the 70% figure shows supply constraints, primarily memory component shortages, rather than a ceiling on actual demand, and the outlook excludes China data center revenue.
The current quarter already delivered, not just promised. Revenue of $96.22 billion beat estimates by roughly $4 billion, and data center revenue's 117% year-over-year jump shows the AI buildout is generating historic growth today, not just in a projection.
NVIDIA Corporation (NASDAQ:NVDA)'s customer base is broadening, which could reduce concentration risk. Huang said demand is now coming from hyperscale cloud providers alongside sovereign AI programs, neoclouds, AI startups, and enterprises. It means future growth depends less on any single large customer's spending decisions.
#year #corporation
Applied to the roughly $396 billion consensus estimate for fiscal 2027, that guidance implies fiscal 2028 revenue near $673 billion to $700 billion. It would put Nvidia ahead of Apple and Alphabet and behind only Amazon among U.S. tech companies by revenue. The forecast followed fiscal second-quarter results that beat expectations across the board: revenue more than doubled to $96.22 billion, up 106% year over year, with data center revenue of $89 billion, up 117%, now making up 92% of total sales.
CEO Jensen Huang told investors AI has reached the point where it is doing productive, profitable work and that computing capacity itself is now translating directly into revenue. Shares jumped roughly 8.7% on the news, lifting the broader semiconductor sector. Management said the 70% figure shows supply constraints, primarily memory component shortages, rather than a ceiling on actual demand, and the outlook excludes China data center revenue.
The current quarter already delivered, not just promised. Revenue of $96.22 billion beat estimates by roughly $4 billion, and data center revenue's 117% year-over-year jump shows the AI buildout is generating historic growth today, not just in a projection.
NVIDIA Corporation (NASDAQ:NVDA)'s customer base is broadening, which could reduce concentration risk. Huang said demand is now coming from hyperscale cloud providers alongside sovereign AI programs, neoclouds, AI startups, and enterprises. It means future growth depends less on any single large customer's spending decisions.
#year #corporation


2 months ago
Applied Digital (NASDAQ:APLD) primarily generates its revenue by operating centralized digital infrastructure campuses and providing dedicated computing services designed for high-performance workloads across the North American region.
It recently signed an additional facility lease for a new campus and secured supplemental credit financing for ongoing construction, while reporting an operating margin of -45% for the quarter ended May 31, 2026.
IREN (NASDAQ:IREN) earns the majority of its ongoing revenue by managing vertically integrated data center facilities and actively mining digital **** ets across its international infrastructure footprint.
While integrating a newly acquired European data center developer and closing the purchase of cloud software provider Mirantis, it recorded an operating margin of -452% for the quarter ended June 30, 2026.
Revenue serves as a primary starting point for investors to evaluate a corporation's ability to attract paying clients and generate gross business volume before standard operational expenses, local taxes, or daily administrative costs are finally subtracted. For neocloud operations such as Applied Digital and IREN, revenue growth is essential to understanding if their costly artificial intelligence infrastructure buildouts are paying off.
#applied #across
It recently signed an additional facility lease for a new campus and secured supplemental credit financing for ongoing construction, while reporting an operating margin of -45% for the quarter ended May 31, 2026.
IREN (NASDAQ:IREN) earns the majority of its ongoing revenue by managing vertically integrated data center facilities and actively mining digital **** ets across its international infrastructure footprint.
While integrating a newly acquired European data center developer and closing the purchase of cloud software provider Mirantis, it recorded an operating margin of -452% for the quarter ended June 30, 2026.
Revenue serves as a primary starting point for investors to evaluate a corporation's ability to attract paying clients and generate gross business volume before standard operational expenses, local taxes, or daily administrative costs are finally subtracted. For neocloud operations such as Applied Digital and IREN, revenue growth is essential to understanding if their costly artificial intelligence infrastructure buildouts are paying off.
#applied #across


2 months ago
CNBC reported that NVIDIA Corporation (NASDAQ:NVDA)'s Groq 3 LPX rack is in full production and will be deployed alongside its Vera CPUs and Rubin GPUs at neocloud Nebius later this year, Nvidia senior director Dion Harris told reporters.
The rack marks the commercialization of technology from Nvidia's $20 billion purchase of Groq's ***** ets in December, its largest deal on record. Each liquid-cooled rack packages 256 Groq chips. Nvidia said the rack can deliver 3,400 tokens per second, noting a benchmark from Artificial ***** ysis. Groq's chips are manufactured by Samsung, unlike Nvidia's own GPUs, which are made by Taiwan Semiconductor Manufacturing Co.
The $20 billion Groq deal represents a manageable financial risk for NVIDIA Corporation (NASDAQ:NVDA) relative to the strategic capabilities it could add to the company. Bernstein ***** yst Stacy Rasgon told CNBC that Nvidia is financially strong enough to absorb a deal of this size with little impact on its overall position. That gives Nvidia the flexibility to make large strategic investments while expanding into new AI chip technologies without materially straining its balance sheet.
Groq's technology extends Nvidia's dominance across the full AI compute stack rather than creating a rival product line. LPX handles low-latency inference while Nvidia's GPUs continue handling training and large-context processing. The rack can pair with Vera Rubin chips without customers changing their CUDA workflows, deepening the software lock-in that has made Nvidia hard to displace.
Execution has been fast, which matters in a market moving this quickly. Nvidia went from announcing the Groq purchase in December to full production and a named customer, Nebius, in eight months. It is a pace that shows Nvidia can absorb acquired technology and ship it rather than let it stall in integration.
#rack
The rack marks the commercialization of technology from Nvidia's $20 billion purchase of Groq's ***** ets in December, its largest deal on record. Each liquid-cooled rack packages 256 Groq chips. Nvidia said the rack can deliver 3,400 tokens per second, noting a benchmark from Artificial ***** ysis. Groq's chips are manufactured by Samsung, unlike Nvidia's own GPUs, which are made by Taiwan Semiconductor Manufacturing Co.
The $20 billion Groq deal represents a manageable financial risk for NVIDIA Corporation (NASDAQ:NVDA) relative to the strategic capabilities it could add to the company. Bernstein ***** yst Stacy Rasgon told CNBC that Nvidia is financially strong enough to absorb a deal of this size with little impact on its overall position. That gives Nvidia the flexibility to make large strategic investments while expanding into new AI chip technologies without materially straining its balance sheet.
Groq's technology extends Nvidia's dominance across the full AI compute stack rather than creating a rival product line. LPX handles low-latency inference while Nvidia's GPUs continue handling training and large-context processing. The rack can pair with Vera Rubin chips without customers changing their CUDA workflows, deepening the software lock-in that has made Nvidia hard to displace.
Execution has been fast, which matters in a market moving this quickly. Nvidia went from announcing the Groq purchase in December to full production and a named customer, Nebius, in eight months. It is a pace that shows Nvidia can absorb acquired technology and ship it rather than let it stall in integration.
#rack

2 months ago
It's always good to look for new investment ideas. While investors can look at various sectors, I like to focus on artificial intelligence (AI) stocks. This technology is still in its early stages and can fundamentally change societies. Autonomous vehicles, humanoid robots, drones, and AI chatbots are some of the products and services that can scale rapidly as AI evolves.
That's why the two stocks I am buying in 2027 revolve around that theme. I already have positions in each of these companies and intend to build on them in 2027.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Iren (NASDAQ: IREN) is my favorite neocloud stock. Nebius (NASDAQ: NBIS) is also a strong contender and slightly ahead of Iren in revenue recognition, but I do not believe Nebius should have a market cap almost four times Iren's.
The neocloud thesis is straightforward. Hyperscalers need access to compute, and companies like Iren create the data centers that supply hyperscalers with the necessary chips, power, software, and facilities.
#flashing #hyperscalers
That's why the two stocks I am buying in 2027 revolve around that theme. I already have positions in each of these companies and intend to build on them in 2027.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Iren (NASDAQ: IREN) is my favorite neocloud stock. Nebius (NASDAQ: NBIS) is also a strong contender and slightly ahead of Iren in revenue recognition, but I do not believe Nebius should have a market cap almost four times Iren's.
The neocloud thesis is straightforward. Hyperscalers need access to compute, and companies like Iren create the data centers that supply hyperscalers with the necessary chips, power, software, and facilities.
#flashing #hyperscalers


2 months ago
Shares of Dell Technologies Inc (NASDAQ:DELL) climbed more than 10% Wednesday after the company posted broad-based earnings strength and raised its full-year guidance well above expectations, driven by surging demand for AI servers.
Fiscal second-quarter revenue was $47 billion, up 58% year over year, beating the $46 billion consensus estimate. The company guided full-year revenue to $192 billion, up from a prior outlook of $167 billion.
Bank of America reiterated its Buy rating and raised its price objective to $600 from $505, citing Dell's position as a beneficiary of agentic AI adoption across NeoClouds, sovereign, enterprise and edge computing.
BofA said demand continues to outpace supply by roughly 30% in fiscal 2027, with an even larger gap expected in fiscal 2028, creating a favorable pricing environment.
Dell's AI server business was a standout, with revenue, orders and backlog all coming in well above BofA's estimates. AI server revenue reached $16.4 billion, orders totaled $60.9 billion and backlog nearly doubled quarter over quarter to $95 billion. Dell raised its fiscal 2027 AI server revenue guidance by $14 billion to $74 billion.
#dell #year #quarter
Fiscal second-quarter revenue was $47 billion, up 58% year over year, beating the $46 billion consensus estimate. The company guided full-year revenue to $192 billion, up from a prior outlook of $167 billion.
Bank of America reiterated its Buy rating and raised its price objective to $600 from $505, citing Dell's position as a beneficiary of agentic AI adoption across NeoClouds, sovereign, enterprise and edge computing.
BofA said demand continues to outpace supply by roughly 30% in fiscal 2027, with an even larger gap expected in fiscal 2028, creating a favorable pricing environment.
Dell's AI server business was a standout, with revenue, orders and backlog all coming in well above BofA's estimates. AI server revenue reached $16.4 billion, orders totaled $60.9 billion and backlog nearly doubled quarter over quarter to $95 billion. Dell raised its fiscal 2027 AI server revenue guidance by $14 billion to $74 billion.
#dell #year #quarter

2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Record revenue and EPS were driven by the compounding benefits of a modernized operating model, enabling earnings to grow faster than revenue through significant operating leverage.
Management attributes the 122% growth in traditional servers to a structural shift where customers view IT as a value driver rather than a cost center, accelerating the refresh of an aged installed base.
AI server momentum is broadening across Neoclouds, sovereigns, and enterprise customers, with the customer count surpassing 6,500 as organizations move from design to production.
Storage returned to growth and share gains, fueled by strong demand for Dell IP products and early tailwinds from AI workloads requiring massive data movement and protection.
#Growth #management #storage
Record revenue and EPS were driven by the compounding benefits of a modernized operating model, enabling earnings to grow faster than revenue through significant operating leverage.
Management attributes the 122% growth in traditional servers to a structural shift where customers view IT as a value driver rather than a cost center, accelerating the refresh of an aged installed base.
AI server momentum is broadening across Neoclouds, sovereigns, and enterprise customers, with the customer count surpassing 6,500 as organizations move from design to production.
Storage returned to growth and share gains, fueled by strong demand for Dell IP products and early tailwinds from AI workloads requiring massive data movement and protection.
#Growth #management #storage
2 months ago
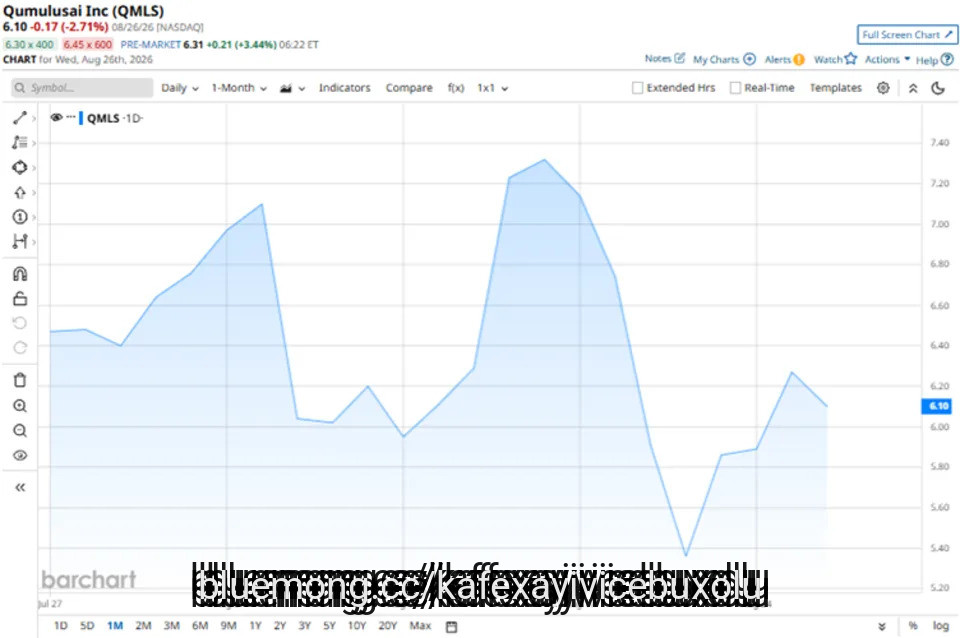
After going public in July following a direct listing, QumulusAI (QMLS) has gained attention on Wall Street as an artificial intelligence (AI) name and cloud partner of Nvidia (NVDA). QumulusAI buys and deploys Nvidia GPUs to run AI training and inference workloads for customers.
Recently, the neocloud provider scored a huge data center win. In an amendment to its surface lease at its Oklahoma data center, the company extended its potential tenure at the site through Jan. 31, 2044. This replaces the original lease's single five-year renewal option with three consecutive five-year renewal options.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#NVIDIA #fans
Recently, the neocloud provider scored a huge data center win. In an amendment to its surface lease at its Oklahoma data center, the company extended its potential tenure at the site through Jan. 31, 2044. This replaces the original lease's single five-year renewal option with three consecutive five-year renewal options.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#NVIDIA #fans

2 months ago
Nvidia Corp. (NASDAQ:NVDA) just posted a quarter that would make any other chipmaker blush. On its August 26 earnings call, the company reported $96.2 billion in revenue, more than double what it made a year earlier, and said AI demand has crossed into something it calls an inflection point. But buried inside the good news sat two admissions that matter just as much: memory costs are rising faster than expected, and Nvidia is now underwriting some of its own customers' growth. Both cut against the simple growth story.
Data center revenue reached $89 billion, up 117% year over year, and the ACIE segment, which covers AI labs, cloud providers, industrial and enterprise customers outside the big hyperscalers, grew 138% year over year to $40.0 billion. Management said that segment now represents roughly half of Nvidia's data center business, a sign that governments and specialized cloud operators are becoming nearly as important as Amazon or Microsoft. Sovereign AI revenue, sold mostly through regional NeoCloud partners, grew 35% sequentially and more than tripled from a year ago, and those partners are expected to exit the year with 8 gigawatts of installed capacity, up from roughly 3 gigawatts at the end of 2025.
The bigger shift is how much of each data center dollar Nvidia now keeps for itself. Management said the revenue potential per gigawatt of capacity has climbed from $18 billion in the Hopper generation to $40 billion with the upcoming Vera Rubin platform, as Nvidia sells the CPUs, networking gear and software around its chips rather than just the chips themselves. Networking revenue hit a record, up 18% sequentially, with Spectrum-X Ethernet sales growing 2.6 times year over year. Amazon deepened its own commitment too, agreeing to deploy an additional 2 million Nvidia GPUs through the second quarter of fiscal 2029 alongside new Vera CPUs, while adopting Nvidia's Omniverse and robotics software for its warehouse fleet.
None of this looks like a company running out of runway. Nvidia returned $26 billion to shareholders in the quarter, split between $20 billion in buybacks and $6 billion in dividends, with about $99 billion still left on its repurchase authorization. Global venture funding into AI topped $400 billion in the first half of 2026 alone, with roughly 70% of that money earmarked for compute, which happens to be exactly what Nvidia sells.
Growth this fast is not free. Gross margin held at 75% this quarter, but CFO Colette Kress told investors it will bottom out at 71% to 72% in the fourth quarter as memory component costs spike, and that the size of those price increases has already exceeded the company's own expectations and is set to climb further into next year. Operating expenses are rising too, up 11% sequentially to $8.2 billion, with guidance near $9 billion for the next quarter, and inventory swelled to $31.6 billion as Nvidia stocks up ahead of the Vera Rubin launch.
#vera
Data center revenue reached $89 billion, up 117% year over year, and the ACIE segment, which covers AI labs, cloud providers, industrial and enterprise customers outside the big hyperscalers, grew 138% year over year to $40.0 billion. Management said that segment now represents roughly half of Nvidia's data center business, a sign that governments and specialized cloud operators are becoming nearly as important as Amazon or Microsoft. Sovereign AI revenue, sold mostly through regional NeoCloud partners, grew 35% sequentially and more than tripled from a year ago, and those partners are expected to exit the year with 8 gigawatts of installed capacity, up from roughly 3 gigawatts at the end of 2025.
The bigger shift is how much of each data center dollar Nvidia now keeps for itself. Management said the revenue potential per gigawatt of capacity has climbed from $18 billion in the Hopper generation to $40 billion with the upcoming Vera Rubin platform, as Nvidia sells the CPUs, networking gear and software around its chips rather than just the chips themselves. Networking revenue hit a record, up 18% sequentially, with Spectrum-X Ethernet sales growing 2.6 times year over year. Amazon deepened its own commitment too, agreeing to deploy an additional 2 million Nvidia GPUs through the second quarter of fiscal 2029 alongside new Vera CPUs, while adopting Nvidia's Omniverse and robotics software for its warehouse fleet.
None of this looks like a company running out of runway. Nvidia returned $26 billion to shareholders in the quarter, split between $20 billion in buybacks and $6 billion in dividends, with about $99 billion still left on its repurchase authorization. Global venture funding into AI topped $400 billion in the first half of 2026 alone, with roughly 70% of that money earmarked for compute, which happens to be exactly what Nvidia sells.
Growth this fast is not free. Gross margin held at 75% this quarter, but CFO Colette Kress told investors it will bottom out at 71% to 72% in the fourth quarter as memory component costs spike, and that the size of those price increases has already exceeded the company's own expectations and is set to climb further into next year. Operating expenses are rising too, up 11% sequentially to $8.2 billion, with guidance near $9 billion for the next quarter, and inventory swelled to $31.6 billion as Nvidia stocks up ahead of the Vera Rubin launch.
#vera


2 months ago
NVDA's ACIE segment, which covers enterprise, neocloud, and sovereign buyers, hit $40 billion with 138% year-over-year growth, outpacing hyperscaler revenue's 13% sequential gain.
Sovereign AI revenue more than tripled year over year, with neocloud partners targeting eight gigawatts of installed NVIDIA capacity by year-end.
NVIDIA carries $108.5 billion in guarantee obligations for neocloud partners, and days sales outstanding jumped from 45 to 60 days, signaling elevated financing risk.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
NVIDIA (NASDAQ:NVDA) delivered $89.023 billion of Data Center revenue in its most recent fiscal second quarter, but the customer mix beneath that number may matter more than the record itself. Direct hyperscaler sales totaled $49 billion, up 13% sequentially. ACIE, covering AI cloud providers, industrial customers, enterprises and sovereign buyers, reached $40 billion after 25% sequential growth and 138% year-over-year growth. Management expects ACIE to drive most of next quarter's Data Center growth before hyperscale reaccelerates as Vera Rubin supply improves. That is a striking rebalancing for a company long described as dependent on a handful of technology giants.
#year #sovereign #center
Sovereign AI revenue more than tripled year over year, with neocloud partners targeting eight gigawatts of installed NVIDIA capacity by year-end.
NVIDIA carries $108.5 billion in guarantee obligations for neocloud partners, and days sales outstanding jumped from 45 to 60 days, signaling elevated financing risk.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
NVIDIA (NASDAQ:NVDA) delivered $89.023 billion of Data Center revenue in its most recent fiscal second quarter, but the customer mix beneath that number may matter more than the record itself. Direct hyperscaler sales totaled $49 billion, up 13% sequentially. ACIE, covering AI cloud providers, industrial customers, enterprises and sovereign buyers, reached $40 billion after 25% sequential growth and 138% year-over-year growth. Management expects ACIE to drive most of next quarter's Data Center growth before hyperscale reaccelerates as Vera Rubin supply improves. That is a striking rebalancing for a company long described as dependent on a handful of technology giants.
#year #sovereign #center


2 months ago
Applied Digital (NASDAQ: APLD) and TeraWulf (NASDAQ: WULF) are two of the top AI stocks riding the data center wave. Both neocloud companies develop and operate facilities that serve hyperscalers, but their stock returns have been a little different this year.
TeraWulf is up by 36%, while Applied Digital has gained just 11%. Is that gap just a fluke, or is it a sign of things to come? Here's what investors should consider.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Gigawatts are the name of the game when it comes to ****** yzing neocloud and colocation providers that offer IT capacity to hyperscalers. The more gigawatts a company has, the more revenue it can make.
Applied Digital has secured 1.4 gigawatts of contracted critical IT load, which comes to roughly $36 billion in total contracted lease revenue. Most of these contracts have 15-year terms, including two deals for 300 megawatts at the company's Delta Forge 1 and Polaris Forge 3 sites.
#applied #digital #NASDAQ #terawulf
TeraWulf is up by 36%, while Applied Digital has gained just 11%. Is that gap just a fluke, or is it a sign of things to come? Here's what investors should consider.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Gigawatts are the name of the game when it comes to ****** yzing neocloud and colocation providers that offer IT capacity to hyperscalers. The more gigawatts a company has, the more revenue it can make.
Applied Digital has secured 1.4 gigawatts of contracted critical IT load, which comes to roughly $36 billion in total contracted lease revenue. Most of these contracts have 15-year terms, including two deals for 300 megawatts at the company's Delta Forge 1 and Polaris Forge 3 sites.
#applied #digital #NASDAQ #terawulf

2 months ago
VRT and EQIX both raised 2026 guidance fueled by AI demand, with Vertiv targeting $14 billion in sales and Equinix posting a record 9,700 net interconnections in Q2.
DLR holds a record $1.9 billion backlog and 1.4 gigawatts under construction, with CEO Andy Power projecting double-digit earnings growth in 2027.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Equinix didn't make the cut. Grab the names FREE today.
The AI capex story now extends well beyond GPUs. As hyperscalers, neoclouds, and sovereign customers race to stand up inference and training capacity, the bottleneck has moved to the physical layer: power, cooling, interconnection, and megawatts of pre-leased shell. That is where the picks in this month's list live. Three US-listed names offer complementary exposure across the data center stack, and each just raised guidance for full-year 2026 on the back of accelerating AI demand.
Below are the three data center stocks worth researching this August, backed by tool-verified pricing, ***** yst consensus, and management commentary from the most recent earnings reports.
#demand #earnings
DLR holds a record $1.9 billion backlog and 1.4 gigawatts under construction, with CEO Andy Power projecting double-digit earnings growth in 2027.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Equinix didn't make the cut. Grab the names FREE today.
The AI capex story now extends well beyond GPUs. As hyperscalers, neoclouds, and sovereign customers race to stand up inference and training capacity, the bottleneck has moved to the physical layer: power, cooling, interconnection, and megawatts of pre-leased shell. That is where the picks in this month's list live. Three US-listed names offer complementary exposure across the data center stack, and each just raised guidance for full-year 2026 on the back of accelerating AI demand.
Below are the three data center stocks worth researching this August, backed by tool-verified pricing, ***** yst consensus, and management commentary from the most recent earnings reports.
#demand #earnings

3 months ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment **** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted NVIDIA Corporation (NASDAQ:NVDA). NVIDIA Corporation (NASDAQ:NVDA) is a leading data center-scale AI infrastructure company that operates through Compute & Networking and Graphics segments. On August 18, 2026, NVIDIA Corporation (NASDAQ:NVDA) closed at $219.74 per share. The one-month return of NVIDIA Corporation (NASDAQ:NVDA) was 3.62% and its shares gained 25.28% over the past 52 weeks. NVIDIA Corporation (NASDAQ:NVDA) has a market capitalization of $5.32 trillion.
Eagle Capital Management stated the following regarding NVIDIA Corporation (NASDAQ:NVDA) in its Q2 2026 investor letter:
"NVIDIA Corporation (NASDAQ:NVDA) has dominated the market for Al accelerator chips and has become the most profitable company in the U.S. However, its largest customers have internal silicon programs that are likely to reduce NVIDIA's share over time. Google TPUs and Amazon's Trainium chips are the most competitive, but Microsoft, Meta, OpenAl, and Anthropic all have programs in various stages. When the market was small, custom programs were uneconomic. At today's scale, R&D can be amortized across the larger base. Moreover, NVIDIA's 75-80% gross margin implies it is marking up Taiwan Semiconductor ("TSMC") wafers by 4-5x. Custom programs don't have to be as good as NVIDIA to offer better price/performance to the end customer.
NVIDIA is investing in the neocloud industry to support demand for its chips and weaken hyperscalers' position. Ironically, by selling its chips at high prices, it makes the neoclouds high-cost operators, and therefore less likely to succeed against vertically integrated hyperscalers over the long term. As NVIDIA's market share crests and begins to fall, ma
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted NVIDIA Corporation (NASDAQ:NVDA). NVIDIA Corporation (NASDAQ:NVDA) is a leading data center-scale AI infrastructure company that operates through Compute & Networking and Graphics segments. On August 18, 2026, NVIDIA Corporation (NASDAQ:NVDA) closed at $219.74 per share. The one-month return of NVIDIA Corporation (NASDAQ:NVDA) was 3.62% and its shares gained 25.28% over the past 52 weeks. NVIDIA Corporation (NASDAQ:NVDA) has a market capitalization of $5.32 trillion.
Eagle Capital Management stated the following regarding NVIDIA Corporation (NASDAQ:NVDA) in its Q2 2026 investor letter:
"NVIDIA Corporation (NASDAQ:NVDA) has dominated the market for Al accelerator chips and has become the most profitable company in the U.S. However, its largest customers have internal silicon programs that are likely to reduce NVIDIA's share over time. Google TPUs and Amazon's Trainium chips are the most competitive, but Microsoft, Meta, OpenAl, and Anthropic all have programs in various stages. When the market was small, custom programs were uneconomic. At today's scale, R&D can be amortized across the larger base. Moreover, NVIDIA's 75-80% gross margin implies it is marking up Taiwan Semiconductor ("TSMC") wafers by 4-5x. Custom programs don't have to be as good as NVIDIA to offer better price/performance to the end customer.
NVIDIA is investing in the neocloud industry to support demand for its chips and weaken hyperscalers' position. Ironically, by selling its chips at high prices, it makes the neoclouds high-cost operators, and therefore less likely to succeed against vertically integrated hyperscalers over the long term. As NVIDIA's market share crests and begins to fall, ma


3 months ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ****** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted NVIDIA Corporation (NASDAQ:NVDA). NVIDIA Corporation (NASDAQ:NVDA) is a leading data center-scale AI infrastructure company that operates through Compute & Networking and Graphics segments. On August 18, 2026, NVIDIA Corporation (NASDAQ:NVDA) closed at $219.74 per share. The one-month return of NVIDIA Corporation (NASDAQ:NVDA) was 3.62% and its shares gained 25.28% over the past 52 weeks. NVIDIA Corporation (NASDAQ:NVDA) has a market capitalization of $5.32 trillion.
Eagle Capital Management stated the following regarding NVIDIA Corporation (NASDAQ:NVDA) in its Q2 2026 investor letter:
"NVIDIA Corporation (NASDAQ:NVDA) has dominated the market for Al accelerator chips and has become the most profitable company in the U.S. However, its largest customers have internal silicon programs that are likely to reduce NVIDIA's share over time. Google TPUs and Amazon's Trainium chips are the most competitive, but Microsoft, Meta, OpenAl, and Anthropic all have programs in various stages. When the market was small, custom programs were uneconomic. At today's scale, R&D can be amortized across the larger base. Moreover, NVIDIA's 75-80% gross margin implies it is marking up Taiwan Semiconductor ("TSMC") wafers by 4-5x. Custom programs don't have to be as good as NVIDIA to offer better price/performance to the end customer.
NVIDIA is investing in the neocloud industry to support demand for its chips and weaken hyperscalers' position. Ironically, by selling its chips at high prices, it makes the neoclouds high-cost operators, and therefore less likely to succeed against vertically integrated hyperscalers over the long term. As NVIDIA's market share crests and begins to fall,
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted NVIDIA Corporation (NASDAQ:NVDA). NVIDIA Corporation (NASDAQ:NVDA) is a leading data center-scale AI infrastructure company that operates through Compute & Networking and Graphics segments. On August 18, 2026, NVIDIA Corporation (NASDAQ:NVDA) closed at $219.74 per share. The one-month return of NVIDIA Corporation (NASDAQ:NVDA) was 3.62% and its shares gained 25.28% over the past 52 weeks. NVIDIA Corporation (NASDAQ:NVDA) has a market capitalization of $5.32 trillion.
Eagle Capital Management stated the following regarding NVIDIA Corporation (NASDAQ:NVDA) in its Q2 2026 investor letter:
"NVIDIA Corporation (NASDAQ:NVDA) has dominated the market for Al accelerator chips and has become the most profitable company in the U.S. However, its largest customers have internal silicon programs that are likely to reduce NVIDIA's share over time. Google TPUs and Amazon's Trainium chips are the most competitive, but Microsoft, Meta, OpenAl, and Anthropic all have programs in various stages. When the market was small, custom programs were uneconomic. At today's scale, R&D can be amortized across the larger base. Moreover, NVIDIA's 75-80% gross margin implies it is marking up Taiwan Semiconductor ("TSMC") wafers by 4-5x. Custom programs don't have to be as good as NVIDIA to offer better price/performance to the end customer.
NVIDIA is investing in the neocloud industry to support demand for its chips and weaken hyperscalers' position. Ironically, by selling its chips at high prices, it makes the neoclouds high-cost operators, and therefore less likely to succeed against vertically integrated hyperscalers over the long term. As NVIDIA's market share crests and begins to fall,

3 months ago
Space Exploration Technologies Corp. (NASDAQ:SPCX) held its first earnings call as a public company earlier this month, and Elon Musk set an aggressive target: an annualized revenue run rate of $100 billion by December, more than tripling the company's current run rate of just over $30 billion.
According to a Financial Times report, Deutsche Bank revisited that target after the results and mapped out the specific deals it thinks could actually get ****** eX there.
Musk insisted the number isn't a stretch goal, telling ****** ysts on the call that it's roughly what ****** e Exploration Technologies Corp. (NASDAQ:SPCX) would hit "if we basically did nothing" beyond letting existing deals ramp up. That raises the real question: is $100 billion really just a matter of contracts already in motion, or does hitting it require several fast-moving, unproven pieces to land at once?
Photo from Firefly Aerospace website
Deutsche Bank's math shows real building blocks already in place. ****** eX's neocloud business, which provides AI compute capacity to outside customers, generated $1.6 billion in revenue in the second quarter, entirely from Anthropic. That single contract should take it to roughly $3.75 billion in quarterly revenue by the third quarter. A separate agreement with Google, worth up to $920 million a month, starts ramping next month and hits its full run rate in October. ****** e Exploration Technologies Corp. (NASDAQ:SPCX) has also signed a new $6.7 billion deal spanning six months that Deutsche Bank suspects could be with the U.S. government. The bank expects at least one more large compute deal to get signed before year-end.
#exploration #NASDAQ #deutsche
According to a Financial Times report, Deutsche Bank revisited that target after the results and mapped out the specific deals it thinks could actually get ****** eX there.
Musk insisted the number isn't a stretch goal, telling ****** ysts on the call that it's roughly what ****** e Exploration Technologies Corp. (NASDAQ:SPCX) would hit "if we basically did nothing" beyond letting existing deals ramp up. That raises the real question: is $100 billion really just a matter of contracts already in motion, or does hitting it require several fast-moving, unproven pieces to land at once?
Photo from Firefly Aerospace website
Deutsche Bank's math shows real building blocks already in place. ****** eX's neocloud business, which provides AI compute capacity to outside customers, generated $1.6 billion in revenue in the second quarter, entirely from Anthropic. That single contract should take it to roughly $3.75 billion in quarterly revenue by the third quarter. A separate agreement with Google, worth up to $920 million a month, starts ramping next month and hits its full run rate in October. ****** e Exploration Technologies Corp. (NASDAQ:SPCX) has also signed a new $6.7 billion deal spanning six months that Deutsche Bank suspects could be with the U.S. government. The bank expects at least one more large compute deal to get signed before year-end.
#exploration #NASDAQ #deutsche


3 months ago
Another day, another round of upside for a neocloud. Following CoreWeave's (CRWV) and Nebius' (NBIS) time in the sun, Sydney-based Iren Limited (IREN) saw its shares end the week about 9% higher after it revealed that its first cloud deployment for Microsoft (MSFT) was complete, and it has also received the Exemplar Cloud status from Nvidia (NVDA).
Iren's Horizon 1 is the first of four deployments from the company to Microsoft under a five-year, $9.7 billion contract inked last year in November. Here, Nvidia validated Iren's GB300 NVL72 deployment and granted it the Exemplar Cloud status. Iren joins CoreWeave, Nebius, AWS, Azure, and Oracle Cloud Infrastructure in receiving this recognition.
A $210 Billion Reason to Buy AMD Stock Here
CoreWeave vs Nebius: Both Companies Reported Strong Earnings, But Here's the Stock You Should Buy
As Oracle Deepens Its Partnership with AWS, Here's How You Should Play ORCL Stock
#cloud #NVIDIA
Iren's Horizon 1 is the first of four deployments from the company to Microsoft under a five-year, $9.7 billion contract inked last year in November. Here, Nvidia validated Iren's GB300 NVL72 deployment and granted it the Exemplar Cloud status. Iren joins CoreWeave, Nebius, AWS, Azure, and Oracle Cloud Infrastructure in receiving this recognition.
A $210 Billion Reason to Buy AMD Stock Here
CoreWeave vs Nebius: Both Companies Reported Strong Earnings, But Here's the Stock You Should Buy
As Oracle Deepens Its Partnership with AWS, Here's How You Should Play ORCL Stock
#cloud #NVIDIA


3 months ago
Nebius (NASDAQ: NBIS) has been steadily raising its capacity guidance for the end of 2026. The company told investors in February that it expected to have 3 gigawatts of contracted power by the end of 2026. That number jumped to 4 gigawatts in May, and when the company released second-quarter results in August, it told investors to expect 5 gigawatts by the end of the year.
This steady growth comes as the company adds new sites throughout North America and Europe. It also suggests that the stock's rally isn't close to over, even though its price has almost tripled year to date.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius operates in one of the hottest industries right now. It's the largest of the neocloud providers -- a group of companies that's playing a critical role in the artificial intelligence (AI) boom. Tech giants like Meta Platforms (NASDAQ: META) and Microsoft (NASDAQ: MSFT) have already turned to Nebius to help them meet their AI capacity needs.
Meta Platforms has made multiple cloud compute deals this year, in addition to one last year. Its biggest deal came in at $27 billion over the next five years. It's split between a five-year, $12 billion agreement and a second five-year, $15 billion deal. Nebius says it will start to deliver this capacity in early 2027.
#meta
This steady growth comes as the company adds new sites throughout North America and Europe. It also suggests that the stock's rally isn't close to over, even though its price has almost tripled year to date.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius operates in one of the hottest industries right now. It's the largest of the neocloud providers -- a group of companies that's playing a critical role in the artificial intelligence (AI) boom. Tech giants like Meta Platforms (NASDAQ: META) and Microsoft (NASDAQ: MSFT) have already turned to Nebius to help them meet their AI capacity needs.
Meta Platforms has made multiple cloud compute deals this year, in addition to one last year. Its biggest deal came in at $27 billion over the next five years. It's split between a five-year, $12 billion agreement and a second five-year, $15 billion deal. Nebius says it will start to deliver this capacity in early 2027.
#meta
3 months ago
There is a plausible scenario in which Elon Musk's ******* eX (SPCX) reaches its ambitious goal of $100 billion in annual recurring revenue (ARR) by year-end.
SpaceX reiterated its goal of reaching $100 billion in ARR by year-end, a target that may not be as insane as it appeared on the company's earnings call transcript last week.
"As a baseline, 2Q's [ARR] run-rate was just $31 billion, meaning management is aiming to more than triple that in just six months. We see this target as likely very achievable, driven mainly by neocloud and Cursor contribution," Deutsche Bank ******* yst and ******* eX bull Edison Yu said in a note on Monday.
"Neocloud carrying the largest load In 2Q, neocloud revenue was $1.6b billion, all coming from Anthropic (ANTH.PVT); this deal alone should ramp up to $3.75 billion in 3Q in quarterly revenue," Yu explained. "In addition, the Google (GOOG, GOOGL) agreement is set to ramp up next month and hit full $920m/month rate beginning in Oct. Then most recently, ******* eX signed a $6.7bn over six month deal which we suspect could possibly be with the US government. And lastly, we expect one more large neocloud deal to get potentially signed before year-end considering industry compute supply/demand dynamics. Putting it all together, this could generate $45- 50bn of ARR exiting December."
Here's how Yu estimates this number will be reached:
#revenue #deal
SpaceX reiterated its goal of reaching $100 billion in ARR by year-end, a target that may not be as insane as it appeared on the company's earnings call transcript last week.
"As a baseline, 2Q's [ARR] run-rate was just $31 billion, meaning management is aiming to more than triple that in just six months. We see this target as likely very achievable, driven mainly by neocloud and Cursor contribution," Deutsche Bank ******* yst and ******* eX bull Edison Yu said in a note on Monday.
"Neocloud carrying the largest load In 2Q, neocloud revenue was $1.6b billion, all coming from Anthropic (ANTH.PVT); this deal alone should ramp up to $3.75 billion in 3Q in quarterly revenue," Yu explained. "In addition, the Google (GOOG, GOOGL) agreement is set to ramp up next month and hit full $920m/month rate beginning in Oct. Then most recently, ******* eX signed a $6.7bn over six month deal which we suspect could possibly be with the US government. And lastly, we expect one more large neocloud deal to get potentially signed before year-end considering industry compute supply/demand dynamics. Putting it all together, this could generate $45- 50bn of ARR exiting December."
Here's how Yu estimates this number will be reached:
#revenue #deal


3 months ago
On August 11, QumulusAI (NASDAQ:QMLS), a neocloud infrastructure provider, signed a GPU-as-a-Service agreement with DRW, a diversified global trading firm, to supply a dedicated Nvidia Blackwell B300 cluster. The capacity will be served from QumulusAI's U.S. data center footprint, carrying an initial one-year term and three one-year renewal options that could run up to four years in total.
The agreement follows a string of major AI infrastructure deals, pushing QMLS's total announced customer agreements past $246 million since early June. Previously on August 7, QumulusAI signed an agreement with an agentic hedge fund to provide Nvidia Blackwell GPU capacity. It also signed a $71.9 million, three-year agreement with an AI Inference platform provider to supply NVIDIA Blackwell B300 and B200 capacity.
These agreements signify a growing pipeline for QMLS that is supportive of management's fiscal 2026 targets. The company expects forward ARR of $300 million for fiscal year 2026 and approximately 30x growth in fiscal 2026 over fiscal 2025. This outlook is backed by executed contract revenue to date, expected renewals, deposit-backed compute capacity reservations and projected contract signings.
The particular DRW agreement in discussion expands QumulusAI's addressable markets beyond the current AI inference platforms that have driven much of its recent contract growth. DRW is the company's second financial-markets customer after the unnamed agentic hedge fund. Moreover, the deal signifies how QMLS is demonstrating that the demand for its GPU infrastructure spans across multiple customer categories.
The bear case here is that QMLS is yet to prove that it can execute on growth despite the strong flow of customer announcements. Particularly for the DRW agreement, the contract has an initial one-year term while the rest of the three years depend on annual renewals.
#contract
The agreement follows a string of major AI infrastructure deals, pushing QMLS's total announced customer agreements past $246 million since early June. Previously on August 7, QumulusAI signed an agreement with an agentic hedge fund to provide Nvidia Blackwell GPU capacity. It also signed a $71.9 million, three-year agreement with an AI Inference platform provider to supply NVIDIA Blackwell B300 and B200 capacity.
These agreements signify a growing pipeline for QMLS that is supportive of management's fiscal 2026 targets. The company expects forward ARR of $300 million for fiscal year 2026 and approximately 30x growth in fiscal 2026 over fiscal 2025. This outlook is backed by executed contract revenue to date, expected renewals, deposit-backed compute capacity reservations and projected contract signings.
The particular DRW agreement in discussion expands QumulusAI's addressable markets beyond the current AI inference platforms that have driven much of its recent contract growth. DRW is the company's second financial-markets customer after the unnamed agentic hedge fund. Moreover, the deal signifies how QMLS is demonstrating that the demand for its GPU infrastructure spans across multiple customer categories.
The bear case here is that QMLS is yet to prove that it can execute on growth despite the strong flow of customer announcements. Particularly for the DRW agreement, the contract has an initial one-year term while the rest of the three years depend on annual renewals.
#contract

3 months ago
Core Scientific, Inc. (NASDAQ:CORZ) announced a major infrastructure partnership with Advanced Micro Devices, Inc. (NASDAQ:AMD) on July 28, giving the chipmaker's ecosystem access to more than 500 megawatts of U.S. data-center capacity beginning in 2027. The arrangement can expand to 2.5 gigawatts. Core Scientific shares rallied in premarket trading.
The agreement is more substantial than the initial announcement suggested. Core Scientific's earnings release described 15-year agreements covering approximately 530 megawatts across five sites, with more than $14 billion of potential base contracted revenue. Its regulatory filing provided an important distinction: AMD directly leased 377 megawatts, while an unnamed neocloud leased another 152 megawatts under agreements that give AMD certain equipment protections and rights if that customer defaults.
The larger story, however, began nine months earlier. Core Scientific shareholders rejected an all-stock acquisition by CoreWeave whose announcement-date implied equity value was approximately $9 billion. The fixed exchange ratio valued CORZ at $20.40 per share when the transaction was announced in July 2025, but the value shareholders would have received at closing was not fixed and moved with CoreWeave's share price.
In January, Gullane Capital Partners founder Trip Miller, who had opposed the sale, predicted that Core Scientific would secure new AI customers. "I expect them to announce deals for AI with third parties other than CoreWeave," he told Business Insider.
The new agreements appear to deliver precisely that customer diversification. Taken together, AMD's 377-megawatt direct lease and the neocloud's 152-megawatt lease exceed Miller's roughly 400-megawatt expectation, although AMD itself did not directly lease the full 529 megawatts. The question is whether the agreements prove that shareholders were right to preserve Core Scientific's independence, or merely give the company a large, capital-intensive opportunity whose ultimate value remains uncertain.
#lease
The agreement is more substantial than the initial announcement suggested. Core Scientific's earnings release described 15-year agreements covering approximately 530 megawatts across five sites, with more than $14 billion of potential base contracted revenue. Its regulatory filing provided an important distinction: AMD directly leased 377 megawatts, while an unnamed neocloud leased another 152 megawatts under agreements that give AMD certain equipment protections and rights if that customer defaults.
The larger story, however, began nine months earlier. Core Scientific shareholders rejected an all-stock acquisition by CoreWeave whose announcement-date implied equity value was approximately $9 billion. The fixed exchange ratio valued CORZ at $20.40 per share when the transaction was announced in July 2025, but the value shareholders would have received at closing was not fixed and moved with CoreWeave's share price.
In January, Gullane Capital Partners founder Trip Miller, who had opposed the sale, predicted that Core Scientific would secure new AI customers. "I expect them to announce deals for AI with third parties other than CoreWeave," he told Business Insider.
The new agreements appear to deliver precisely that customer diversification. Taken together, AMD's 377-megawatt direct lease and the neocloud's 152-megawatt lease exceed Miller's roughly 400-megawatt expectation, although AMD itself did not directly lease the full 529 megawatts. The question is whether the agreements prove that shareholders were right to preserve Core Scientific's independence, or merely give the company a large, capital-intensive opportunity whose ultimate value remains uncertain.
#lease
3 months ago
Core Scientific, Inc. (NASDAQ:CORZ) announced a major infrastructure partnership with Advanced Micro Devices, Inc. (NASDAQ:AMD) on July 28, giving the chipmaker's ecosystem access to more than 500 megawatts of U.S. data-center capacity beginning in 2027. The arrangement can expand to 2.5 gigawatts. Core Scientific shares rallied in premarket trading.
The agreement is more substantial than the initial announcement suggested. Core Scientific's earnings release described 15-year agreements covering approximately 530 megawatts across five sites, with more than $14 billion of potential base contracted revenue. Its regulatory filing provided an important distinction: AMD directly leased 377 megawatts, while an unnamed neocloud leased another 152 megawatts under agreements that give AMD certain equipment protections and rights if that customer defaults.
The larger story, however, began nine months earlier. Core Scientific shareholders rejected an all-stock acquisition by CoreWeave whose announcement-date implied equity value was approximately $9 billion. The fixed exchange ratio valued CORZ at $20.40 per share when the transaction was announced in July 2025, but the value shareholders would have received at closing was not fixed and moved with CoreWeave's share price.
In January, Gullane Capital Partners founder Trip Miller, who had opposed the sale, predicted that Core Scientific would secure new AI customers. "I expect them to announce deals for AI with third parties other than CoreWeave," he told Business Insider.
The new agreements appear to deliver precisely that customer diversification. Taken together, AMD's 377-megawatt direct lease and the neocloud's 152-megawatt lease exceed Miller's roughly 400-megawatt expectation, although AMD itself did not directly lease the full 529 megawatts. The question is whether the agreements prove that shareholders were right to preserve Core Scientific's independence, or merely give the company a large, capital-intensive opportunity whose ultimate value remains uncertain.
#agreements
The agreement is more substantial than the initial announcement suggested. Core Scientific's earnings release described 15-year agreements covering approximately 530 megawatts across five sites, with more than $14 billion of potential base contracted revenue. Its regulatory filing provided an important distinction: AMD directly leased 377 megawatts, while an unnamed neocloud leased another 152 megawatts under agreements that give AMD certain equipment protections and rights if that customer defaults.
The larger story, however, began nine months earlier. Core Scientific shareholders rejected an all-stock acquisition by CoreWeave whose announcement-date implied equity value was approximately $9 billion. The fixed exchange ratio valued CORZ at $20.40 per share when the transaction was announced in July 2025, but the value shareholders would have received at closing was not fixed and moved with CoreWeave's share price.
In January, Gullane Capital Partners founder Trip Miller, who had opposed the sale, predicted that Core Scientific would secure new AI customers. "I expect them to announce deals for AI with third parties other than CoreWeave," he told Business Insider.
The new agreements appear to deliver precisely that customer diversification. Taken together, AMD's 377-megawatt direct lease and the neocloud's 152-megawatt lease exceed Miller's roughly 400-megawatt expectation, although AMD itself did not directly lease the full 529 megawatts. The question is whether the agreements prove that shareholders were right to preserve Core Scientific's independence, or merely give the company a large, capital-intensive opportunity whose ultimate value remains uncertain.
#agreements


3 months ago
After spending nearly $16 billion on artificial intelligence infrastructure in the second quarter, Elon Musk used ****** eX's first earnings call as a public company on Tuesday to explain why he believes ****** eX is uniquely positioned to dominate the AI compute race: rocket scientists.
Defending the company's aggressive investment in AI, Musk argued that the engineering expertise required to design reusable rockets and satellites translates directly to building AI data centers, comparing the company's advantage in the market to "the New York Yankees going in and playing a Little League team."
Data centers are a "trivial problem" compared to what ****** eX's rocket engineers work on every day, Musk said.
"We're taking a small amount of the expertise that we use for rockets and satellites, and applying that to scaling terrestrial data centers," he said, arguing that even a fraction of ****** eX's aerospace engineering experience produces "an amazing outcome" when applied to AI infrastructure.
Musk made the boast without naming any of his "little league" rivals. ****** eX is a relative newcomer to the data center business, an industry long dominated by the giant cloud services providers such as Amazon, Microsoft, and Alphabet-owned Google. All three of those business reported record growth in their cloud divisions for their most recent earnings reports. A growing crop of "neocloud" startups are also racing to build the data centers and computing capacity needed to power artificial intelligence.
#SpaceX #artificial #infrastructure
Defending the company's aggressive investment in AI, Musk argued that the engineering expertise required to design reusable rockets and satellites translates directly to building AI data centers, comparing the company's advantage in the market to "the New York Yankees going in and playing a Little League team."
Data centers are a "trivial problem" compared to what ****** eX's rocket engineers work on every day, Musk said.
"We're taking a small amount of the expertise that we use for rockets and satellites, and applying that to scaling terrestrial data centers," he said, arguing that even a fraction of ****** eX's aerospace engineering experience produces "an amazing outcome" when applied to AI infrastructure.
Musk made the boast without naming any of his "little league" rivals. ****** eX is a relative newcomer to the data center business, an industry long dominated by the giant cloud services providers such as Amazon, Microsoft, and Alphabet-owned Google. All three of those business reported record growth in their cloud divisions for their most recent earnings reports. A growing crop of "neocloud" startups are also racing to build the data centers and computing capacity needed to power artificial intelligence.
#SpaceX #artificial #infrastructure


3 months ago
Neocloud provider CoreWeave (CRWV) saw its stock rise by 21.5% intraday on July 30 as the company announced a partnership with Leidos Holdings (LDOS) to provide artificial intelligence (AI) cloud services to United Stated federal agencies, so that they can deploy and operate AI at mission scale. This extends CoreWeave's reach into addressing U.S. Intelligence Community (IC) and Department of Defense's (DoD) unique requirements.
This also diversifies CoreWeave's customer base, as government contracts bring stability and are spread across a broad number of agencies, which is important for a company that relies on its top customers for a major portion of its revenue.
Palantir Is Set to Deliver Strong Q2. **** ysts See 60% Upside Potential for PLTR Stock.
Earnings, PMI and Other Key Things to Watch this Week
Seagate Rallies on Strong Q4 Results and Guidance. What Does This Mean for STX Stock Here.
#leidos
This also diversifies CoreWeave's customer base, as government contracts bring stability and are spread across a broad number of agencies, which is important for a company that relies on its top customers for a major portion of its revenue.
Palantir Is Set to Deliver Strong Q2. **** ysts See 60% Upside Potential for PLTR Stock.
Earnings, PMI and Other Key Things to Watch this Week
Seagate Rallies on Strong Q4 Results and Guidance. What Does This Mean for STX Stock Here.
#leidos



