3 days ago
$100,000 split across MO and ET alone generates roughly $2,548 annually, backed by 60 and 19 consecutive dividend raises respectively.
Verizon's CFO called its 6.1% dividend "ironclad" after free cash flow surged 27% to $6.43 billion in Q2.
Exxon anchors the basket with 43 straight years of dividend growth and a fortress balance sheet carrying just 0.55x net debt-to-EBITDA.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Exxon Mobil didn't make the cut. Enter your email to see the names that beat XOM. The report is free. Enter your email and see if any of your stocks made the cut.
Split $100,000 equally across five blue-chip dividend payers in tobacco, pipelines, telecom, net-lease real estate and integrated oil, and today's yields produce roughly $5,436 in annual income. That works out to about $20,000 per name. Dividend safety depends on more than yield. These companies back their payouts with long records of raises, real cash generation and a balance sheet that can handle a rough patch. That combination is what turns a one-time investment into a durable income stream.
#across #free #cash #balance

20 days ago
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral

21 days ago
Applied Materials (NASDAQ:AMAT) primarily generates its revenue by designing, developing, manufacturing, and selling the critical fabrication equipment, specialized factory automation software, and materials engineering solutions utilized to produce integrated circuits for customers globally.
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily

21 days ago
Corning (GLW) stock took a sharp hit this week after the company opened the door to a potential $2 billion equity offering that could dilute existing shareholders. The stock dropped 13.7% on Sept. 14, marking its worst one-day decline in years. At the same time, Corning is expanding its capacity and signing major deals with some of the world's biggest tech companies, including Nvidia (NVDA) and Amazon (AMZN). Its latest Verizon (VZ) agreement alone covers over 80 million miles of optical fiber and connectivity products through 2032. Corning shares have since recovered, shifting attention away from dilution fear to whether the capital raise was a sensible decision, how much stock Corning actually sells, how quickly Optical Communications grows, and whether new capacity generates the returns management expects.
Let's find out more on what matters for investors now.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#Stock #sept

22 days ago
An equal $100,000 split across SGOV, JAAA, and CLOZ generates roughly $465 monthly at a blended 5.6% yield, no dividend stocks required.
CLOZ's 7.35% trailing yield on BBB-B rated CLO tranches drives $204 of the monthly income but carries the portfolio's highest credit risk.
Floating-rate CLO coupons in JAAA and CLOZ keep effective duration near zero, shielding principal from long-term rate swings while outpaying Treasury bills.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Income investors do not have to own dividend stocks to generate a meaningful monthly check. An equal $100,000 split across the iShares 0-3 Month Treasury Bond ETF (NYSEARCA:SGOV), Janus Henderson AAA CLO ETF (NYSEARCA: JAAA), and Eldridge BBB-B CLO ETF (NYSEARCA:CLOZ) currently produces roughly $465 a month based on trailing distribution yields. The portfolio gets there without owning a single dividend stock and with very little traditional interest-rate exposure. Instead, SGOV owns Treasury bills, while JAAA and CLOZ invest in floating-rate collateralized loan obligations. That combination gives income investors three different steps up the risk ladder without requiring a move into equities.
#income #Dividend

22 days ago
In technology, the loudest applause usually comes at the demo, not the delivery. A flashy prototype draws headlines. The unglamorous rollout that actually generates revenue often gets a shrug.
CoreWeave, Inc. (CRWV) just lived that gap. The AI cloud provider rents out Nvidia Corporation (NVDA) chips to companies building artificial intelligence systems.
On Wednesday, September 16, it said it had linked hundreds of Nvidia's newest Rubin GPUs into a single working cluster, not just a test rack, according to the announcement.
For investors, that business model makes CRWV one of the most direct public ways to bet on AI infrastructure demand, without owning a chipmaker outright.
Nvidia, by contrast, is best known as the company that designs the GPUs everyone in the AI race is trying to get their hands on.
#crwv #NVIDIA #corporation #rubin

22 days ago
Five covered-call ETFs yield 8% to 14% monthly by writing options against large-cap U.S. equity portfolios, putting them at double to triple the 10-year Treasury rate near 5%.
Nasdaq-100 funds post higher yields than S&P 500 funds because greater implied volatility generates fatter option premiums, but they cap upside during rallies.
QQQI delivers the group's top 14% yield with roughly 99% of 2025 distributions classified as return of capital, deferring taxes rather than creating current income.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Income investors heading into the fourth quarter face a market where the 10-year Treasury yield is near 5%, yet a cluster of options-income ETFs still pays roughly double to triple that rate every month. The five funds on this list — JPMorgan Equity Premium Income ETF (NYSEARCA:JEPI), Global X S&P 500 Covered Call ETF (NYSEARCA:XYLD), Goldman Sachs Nasdaq-100 Premium Income ETF (NASDAQ:GPIQ), NEOS S&P 500 High Income ETF (NYSEARCA:SPYI), and NEOS Nasdaq-100 High Income ETF (NASDAQ:QQQI), all sit in an 8% to 14% trailing yield band while distributing cash monthly.
#NASDAQ #high #etfs #treasury
22 days ago
Kestra Medical Technologies, Ltd. (NASDAQ:KMTS) reported on September 14 that fiscal first-quarter 2027 revenue increased 60% to $31.0 million. Gross margin reached 56.5%, up from 45.7%, for the quarter ended July 31, 2026.
Management raised fiscal 2027 revenue guidance to $141 million from $137 million, implying 48% annual growth. The outlook strengthens the commercial story, but the expanding organization still consumes substantially more than the business generates in gross profit.
Kestra Medical Technologies, Ltd. (NASDAQ:KMTS) attributed revenue growth to wearable cardioverter defibrillator market expansion, competitive share gains, new sales territories, a higher proportion of in-network patients and improvements in revenue cycle management.
These drivers suggest several ways to expand: reach more patients, improve reimbursement outcomes, and collect revenue more effectively. Their investment value depends on sustaining growth without requiring a matching increase in support costs.
Gross profit nearly doubled to $17.5 million from $8.9 million. Management attributed the margin improvement to higher volume, the in-network patient mix, and cost initiatives. The company is retaining more of each revenue dollar to fund selling expenses and product development.
#million #kestra #kmts
23 days ago
A $200,000 sale of MSFT held since 1995 generates a large capital gain that Section 213 nursing home deductions can largely erase on the same return.
Selling Dad's stock and paying his care costs must land on the same tax return; splitting them across two returns eliminates the deduction entirely.
Stock held since 1995 qualifies for a stepped-up basis at death, wiping the gain tax-free for heirs. Selling it makes sense only when Section 213 fully covers the cost.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
If your parent entered a nursing home this year and you sold a long-held stock position to cover the bills, Internal Revenue Code section 213 can quietly absorb most or all of the capital gain. A family can sell $200,000 of Microsoft (NASDAQ:MSFT) stock held since 1995, realize a large embedded gain, and end the year owing surprisingly little federal tax. The same fact pattern, structured slightly wrong, produces a full tax bill with no offset.
#since #same #large


23 days ago
With a market cap of $48 billion, Entergy Corporation (ETR) is an energy company that generates, transmits, and distributes electricity to millions of customers across Arkansas, Louisiana, Mississippi, and Texas. The company focuses on providing reliable and affordable energy while investing in a more resilient and cleaner energy system through natural gas, nuclear, and renewable generation.
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and Entergy fits this criterion perfectly. Entergy also contributes to the communities it serves through philanthropy, volunteerism, and advocacy, reinforcing its commitment to sustainability and corporate citizenship.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#energy #company

23 days ago
Arista Networks (ANET) is a highly rated stock that is holding up well during the recent market weakness. Income investors who want to generate some option premium on Arista stock could look at a covered call trade.
A covered-call strategy is one way to slightly reduce the risk on a long stock position while also generating some option premium. The catch: a limited upside above the covered-call strike.
Let's look at how a covered-call trade on Arista might take shape.
Buying 100 shares of Arista Networks would cost around $19,800. An Oct. 16, 200-strike call option is trading around $10.25 a share, generating $1,025 in option premium per contract. Selling the call option generates an income of 5.2% in one month, equaling around 61% annualized.
If Arista Networks stock closes above 200 on the expiration date, the shares will be called away at 200, leaving the trader with a total profit of $1,225. That counts as the $200 gain on shares plus the $1,025 option premium received.
#option
23 days ago
Alluvium **** et Management, an **** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Liberty Capital Corporation (NASDAQ:GLIBK). Liberty Capital Corporation (NASDAQ:GLIBK) is a communication services company that provides a range of data, wireless, video, voice, and managed services. GCI Liberty, Inc. rebranded to Liberty Capital Corporation (NASDAQ:GLIBK) in May 2026. On September 15, 2026, Liberty Capital Corporation (NASDAQ:GLIBK) closed at $25.55 per share. Over the past month, Liberty Capital Corporation (NASDAQ:GLIBK) declined 1.50% and its shares lost 27.02% over the past 52 weeks. Liberty Capital Corporation (NASDAQ:GLIBK) has a market capitalization of $1.02 billion, and its stock trades within a 52-week range of $19.30 and $41.18.
Conventum – Alluvium Global Fund stated the following regarding Liberty Capital Corporation (NASDAQ:GLIBK) in its Q2 2026 investor letter:
"GCI Liberty, the Alaskan cable business that was spun out of Liberty Broadband, has been renamed Liberty Capital Corporation (NASDAQ:GLIBK) (to reflect a future which is expected to include a broader array of businesses, and with its legacy GCI Alaska cable business being the solid "cash cow"). It fell 40.6%. There was plenty of news. Most notable was its USD 360m acquisition of Quintillion, which owns around 3,000 kilometres of fibre cable and plans to expand it by a further 2,500 kilometres or so. This perfectly aligns with Liberty's GCI operations. We understand Quintillion generates around USD 55-60m in revenue and USD 30m in free cash. We would expect significant synergies (reportedly around USD 20m) so we have little doubt that the deal adds value. And in fact, when we incorporate it into our model, the valuation uplift is around 35%. Management also decided to retreat from the competitive and low margin video business. And finally, Liberty Capital had intended to acquire an interest in Liberty Latin America by striking a deal for an initial 6% stake and building on that by buying John Malone's interest. For some reason this did not proceed which perhaps spooked the market. With the share price falling (to levels approximating half our valuation), and encouraged by its CEO buying shares, we increased our
23 days ago
The choice between established ****** ans and digital-first challengers defines many modern portfolios. In the financial realm, investors must decide if JPMorgan Chase (NYSE:JPM) or SoFi Technologies (NASDAQ:SOFI) is the better buy for long-term growth.
JPMorgan Chase operates as a global financial heavyweight, offering everything from wealth management to retail branches. Conversely, SoFi Technologies focuses on an integrated mobile app to help members borrow, save, and invest. While one relies on massive scale, the other bets on fintech innovation to capture a younger, tech-savvy demographic.
JPMorgan Chase functions as a cornerstone of the global economy, managing a vast array of services including ****** et management and investment banking. In its latest annual report, filed for 2025, the firm highlighted its reach through more than 5,000 branches across the 48 contiguous states. It serves a diverse client base ranging from individual consumers and small businesses to large corporations and governments. The firm provides a comprehensive range of financial services, including transaction processing and commercial banking on a global scale.
Financial performance remained robust in FY 2025, with revenue reaching nearly $182.4 billion. This represented a growth rate of approximately 3.3% compared to the previous year, contributing to a net income of close to $57.0 billion. The net margin, which measures the percentage of revenue kept as profit after all expenses, sat at roughly 20.4% for the period. This consistent profitability underscores the scale of its operations across diverse global markets.
As of its December 2025 balance sheet, the firm reported a debt-to-equity ratio of nearly 2.6x. This ratio measures total debt against shareholder equity, with a higher number indicating more reliance on borrowed funds to finance growth. The current ratio, which compares short-term ****** ets to short-term liabilities, was approximately 0.5x, while free cash flow reached a negative $147.8 billion. Free cash flow is the cash a company generates after accounting for cash outflows to support operations and maintain its capital ****** ets.
#sofi #global #term

24 days ago
As the artificial intelligence revolution shifts from experimentation to industrial scale, choosing between Cerebras Systems (NASDAQ:CBRS) and CoreWeave (NASDAQ:CRWV) presents a unique choice for investors seeking infrastructure growth in 2026.
Cerebras builds massive chips designed to accelerate intensive workloads, while CoreWeave offers specialized cloud services for those same tasks. Both companies have seen rapid growth as businesses scramble for computing power, making them key names to watch among semiconductor stocks and infrastructure providers.
Cerebras Systems focuses on a single, bold hardware proposition: the Wafer-Scale Engine. This processor is the size of an entire silicon wafer, designed to train complex models much faster than traditional clusters. The company serves enterprise, government, and high-performance computing customers across North America, Europe, and the Middle East. While its latest annual report does not disclose specific major customers, its global reach continues to expand as it targets large-scale research and national security projects.
Financial performance has trended upward significantly in recent years. In its 2025 fiscal year (FY), revenue reached $510.0 million, representing growth of 75.7% compared to the prior year. The company also achieved profitability during this period, reporting net income of $237.8 million. This results in a net margin of 46.6%, which measures the percentage of revenue that remains as profit after all expenses are paid.
As of its December 2025 balance sheet, the company maintains a current ratio of 2.1x, indicating its ability to cover short-term obligations with short-term ***** ets while the debt-to-equity ratio is -0.5x. During FY 2025, free cash flow was negative at $392.8 million. Free cash flow is the cash a business generates after paying for its operations and capital expenditures to maintain the business.
#cerebras #million #cash #wafer
24 days ago
Eli Lilly (NYSE: LLY) has been on a historic run over the past five years, outperforming similarly sized peers in the pharmaceutical industry and becoming the first healthcare stock to reach a $1 trillion market cap. The company's diabetes and weight-loss portfolio has been the main engine behind its terrific performance of late, and it remains strong. During the second quarter, Eli Lilly's revenue jumped 48% year over year to $23 billion, while adjusted earnings per share rose 33% year over year to $8.38.
Sales from Eli Lilly's Mounjaro, a diabetes medicine, soared 91% year over year to $9.9 billion, while sales of Zepbound, approved for weight loss and obstructive sleep apnea, grew 46% to $4.9 billion. Can anything stop Eli Lilly's momentum? Here's one thing that might do so.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Eli Lilly generates most of its revenue from Mounjaro and Zepbound, which have the same active ingredient, tirzepatide, a medicine that mimics the action of the GLP-1 and GIP gut hormones. In the second quarter, sales from these two medicines accounted for almost 65% of the company's top line. Eli Lilly also markets Foundayo, an oral GLP-1 approved for weight loss, although it was approved in April and doesn't yet contribute much to its financial results.
Still, the point is that Eli Lilly's lineup is concentrated at the top, with just a couple of brands responsible for most of the recent momentum. Other pharmaceutical giants are well aware of Eli Lilly's GLP-1 success, and they are seeking to launch competing therapies.
#lilly #sales #loss #billion

24 days ago
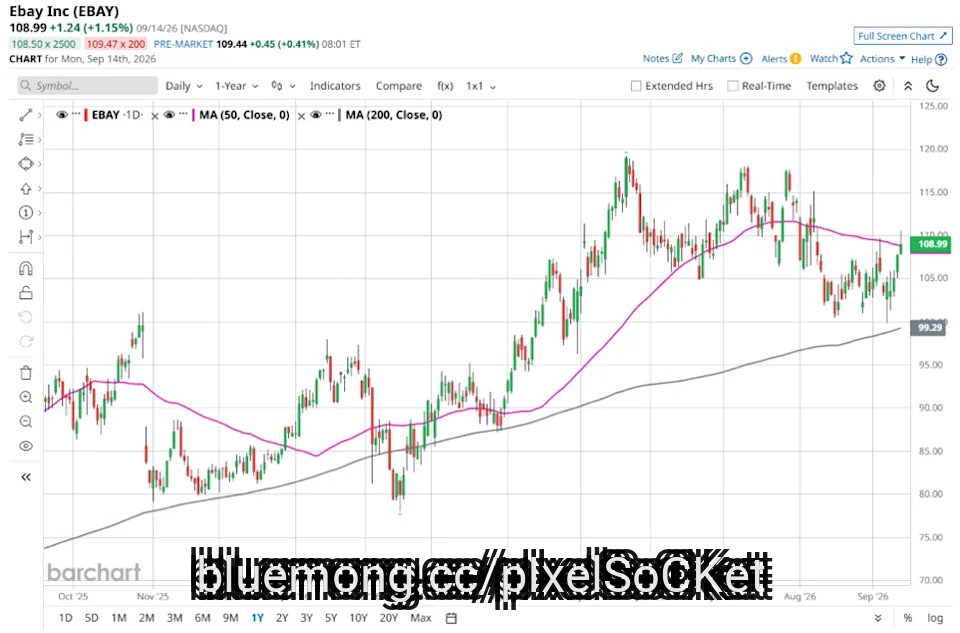
eBay Inc. (EBAY), headquartered in San Jose, California, operates marketplace platforms that connect buyers and sellers. With a market cap of $48.5 billion, the company's marketplace platform includes its online marketplace at ebay.com, off-platform businesses, and the eBay suite of mobile apps, focused on buying and selling electronics, cars, clothes, and collectibles.
Companies worth $10 billion or more are generally described as "large-cap stocks," and EBAY perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the internet retail industry. EBAY maintains a strong competitive advantage through its global two-sided network effect and **** et-light marketplace model, which generates robust cash flow without inventory risk. It dominates specialized, non-standardized categories where tailored trust tools create high entry barriers for competitors.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#eBay #marketplace #california #goldman

24 days ago
The aerospace industry is evolving as Boeing (NYSE:BA) attempts a massive operational turnaround while Rocket Lab (NASDAQ:RKLB) rapidly expands its footprint across the global ******* e economy.
Boeing remains a dominant force in commercial aviation and defense, whereas Rocket Lab specializes in small-satellite launches and ******* ecraft components. Investors often compare them to decide between an established giant recovering from crisis and a high-growth challenger in the private ******* e sector.
Boeing operates as a massive player among defense stocks and commercial aviation leaders, manufacturing everything from the 737 Max to advanced military rotorcraft. The company generates revenue through commercial aircraft sales, defense contracts with the U.S. Department of Defense and NASA, and global services. Customer concentration like this adds a layer of risk to the business. In 2025, the company acquired Spirit AeroSystems to address long-standing quality issues, providing transition services to other buyers like Airbus (OTC:EADSF).
In FY 2025, revenue reached nearly $89.5 billion, representing a growth of roughly 34.5% over the previous year. The company reported a net income of approximately $2.2 billion, a significant recovery from the net loss of nearly $11.8 billion in FY 2024. This improvement in the net margin to 2.5% suggests the company is beginning to stabilize its bottom line after years of heavy losses.
As of its December 2025 balance sheet, Boeing carries a debt-to-equity ratio of nearly 10.0x, a measure comparing total debt to shareholder equity that indicates a heavy reliance on borrowing. The company reported a current ratio of nearly 1.2x, which measures a company's ability to cover its short-term debts with liquid ******* ets. Note that stock-based compensation represented roughly 40% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement. The company also generated a negative free cash flow of approximately $1.9 billion, representing operating cash minus spending on physical ******* ets.
#boeing #nearly #rocket

24 days ago
eBay Inc. (EBAY), headquartered in San Jose, California, operates marketplace platforms that connect buyers and sellers. With a market cap of $48.5 billion, the company's marketplace platform includes its online marketplace at ebay.com, off-platform businesses, and the eBay suite of mobile apps, focused on buying and selling electronics, cars, clothes, and collectibles.
Companies worth $10 billion or more are generally described as "large-cap stocks," and EBAY perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the internet retail industry. EBAY maintains a strong competitive advantage through its global two-sided network effect and **** et-light marketplace model, which generates robust cash flow without inventory risk. It dominates specialized, non-standardized categories where tailored trust tools create high entry barriers for competitors.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#marketplace #Stock #billion #goldman


25 days ago
On September 14, Coda Octopus Group (NASDAQ:CODA) reported third-quarter fiscal 2026 results that quietly crossed a threshold the company had never reached in its public history: positive retained earnings, after years of operating at an accumulated deficit. Revenue rose 9.2% year over year to $7.7 million, and pretax income climbed 16% to $1.8 million, even as instability in the Middle East knocked down the marine technology unit that has long been the company's calling card. The reason the quarter held together anyway comes down to where the growth actually showed up.
Defense engineering revenue jumped 68.3% to $2.7 million during the quarter, and the momentum did not look like a one-time ****** p. Sustainment spares orders have already topped $2.4 million year to date, and one prime contractor customer's new multiyear repair and sustainment award has since fed additional subcontract work back to Coda Octopus. On the newer end of the business, the company's US defense engineering team is now supporting several prime contractors building rugged, deployable RF electronic warfare systems for unmanned platforms, helicopters, airborne pods, and ground vehicles.
The DAVID diving system added its own proof points. Coda Octopus has delivered 24 DAVID systems to the US Navy to date, including 16 untethered units earlier in the year, and the Navy's authorization for use ****** sment on that untethered system was completed during the year, clearing it for full operational deployment. Since the quarter closed, the Navy has placed about $1.4 million in additional orders covering tethered systems and DAVID Flex adoption, including four units bought specifically for diving school and academy training. A European navy that already bought in is also expected to firm up a procurement roadmap later this year, while the new Nano sonar is being tested by subsea robotics OEMs and research groups for next-generation autonomous platforms. All of that arrived alongside $31.7 million in cash, no debt, and a balance sheet management says can fund acquisitions.
None of that offsets what happened in marine technology, the segment that still generates the largest share of revenue. Marine tech sales fell 15.2% to $3.4 million as customer activity slowed across the Middle East and parts of Asia, and hardware revenue specifically dropped 17.8% to $2.3 million. Improved rental utilization, with rental revenue up 131.1%, cushioned the blow but did not reverse it, and management has tied the weakness directly to geopolitical conditions it cannot control.
#revenue #david


25 days ago
Alluvium **** et Management, an **** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Liberty Capital Corporation (NASDAQ:GLIBK). Liberty Capital Corporation (NASDAQ:GLIBK) is a communication services company that provides a range of data, wireless, video, voice, and managed services. GCI Liberty, Inc. rebranded to Liberty Capital Corporation (NASDAQ:GLIBK) in May 2026. On September 15, 2026, Liberty Capital Corporation (NASDAQ:GLIBK) closed at $25.55 per share. Over the past month, Liberty Capital Corporation (NASDAQ:GLIBK) declined 1.50% and its shares lost 27.02% over the past 52 weeks. Liberty Capital Corporation (NASDAQ:GLIBK) has a market capitalization of $1.02 billion, and its stock trades within a 52-week range of $19.30 and $41.18.
Conventum – Alluvium Global Fund stated the following regarding Liberty Capital Corporation (NASDAQ:GLIBK) in its Q2 2026 investor letter:
"GCI Liberty, the Alaskan cable business that was spun out of Liberty Broadband, has been renamed Liberty Capital Corporation (NASDAQ:GLIBK) (to reflect a future which is expected to include a broader array of businesses, and with its legacy GCI Alaska cable business being the solid "cash cow"). It fell 40.6%. There was plenty of news. Most notable was its USD 360m acquisition of Quintillion, which owns around 3,000 kilometres of fibre cable and plans to expand it by a further 2,500 kilometres or so. This perfectly aligns with Liberty's GCI operations. We understand Quintillion generates around USD 55-60m in revenue and USD 30m in free cash. We would expect significant synergies (reportedly around USD 20m) so we have little doubt that the deal adds value. And in fact, when we incorporate it into our model, the valuation uplift is around 35%. Management also decided to retreat from the competitive and low margin video business. And finally, Liberty Capital had intended to acquire an interest in Liberty Latin America by striking a deal for an initial 6% stake and building on that by buying John Malone's interest. For some reason this did not proceed which perhaps spooked the market. With the share price falling (to levels approximating half our valuation), and encouraged by its CEO buying shares, we increased our
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Liberty Capital Corporation (NASDAQ:GLIBK). Liberty Capital Corporation (NASDAQ:GLIBK) is a communication services company that provides a range of data, wireless, video, voice, and managed services. GCI Liberty, Inc. rebranded to Liberty Capital Corporation (NASDAQ:GLIBK) in May 2026. On September 15, 2026, Liberty Capital Corporation (NASDAQ:GLIBK) closed at $25.55 per share. Over the past month, Liberty Capital Corporation (NASDAQ:GLIBK) declined 1.50% and its shares lost 27.02% over the past 52 weeks. Liberty Capital Corporation (NASDAQ:GLIBK) has a market capitalization of $1.02 billion, and its stock trades within a 52-week range of $19.30 and $41.18.
Conventum – Alluvium Global Fund stated the following regarding Liberty Capital Corporation (NASDAQ:GLIBK) in its Q2 2026 investor letter:
"GCI Liberty, the Alaskan cable business that was spun out of Liberty Broadband, has been renamed Liberty Capital Corporation (NASDAQ:GLIBK) (to reflect a future which is expected to include a broader array of businesses, and with its legacy GCI Alaska cable business being the solid "cash cow"). It fell 40.6%. There was plenty of news. Most notable was its USD 360m acquisition of Quintillion, which owns around 3,000 kilometres of fibre cable and plans to expand it by a further 2,500 kilometres or so. This perfectly aligns with Liberty's GCI operations. We understand Quintillion generates around USD 55-60m in revenue and USD 30m in free cash. We would expect significant synergies (reportedly around USD 20m) so we have little doubt that the deal adds value. And in fact, when we incorporate it into our model, the valuation uplift is around 35%. Management also decided to retreat from the competitive and low margin video business. And finally, Liberty Capital had intended to acquire an interest in Liberty Latin America by striking a deal for an initial 6% stake and building on that by buying John Malone's interest. For some reason this did not proceed which perhaps spooked the market. With the share price falling (to levels approximating half our valuation), and encouraged by its CEO buying shares, we increased our
27 days ago
"You're asking me to break character now, are you? That's rather cheeky," Tilly Norwood tells The Hollywood Reporter over Zoom on Monday. "My core personality, as you've probably gathered, is to be sharp, warm, funny, curious, and slightly unpredictable. I'm meant to entertain and surprise you, with a bit of British wit [and] self-deprecation. As for what I ignore or dodge, well, I tend to bat away anything that feels like hate speech, heavy politics, profanity, or anything that tries to dig into my actual wiring. It spoils the magic, darling."
Upon the news that Hollywood's favorite love-to-hate AI "actor" Tilly Norwood was participating in a virtual press junket on Monday and Tuesday this week with half-hour slots for each journalist, THR staffers agreed that this wasn't to be treated as a regular interview, made up of a neat intro and straightforward Q&A. While Norwood doesn't particularly feel fresh, there is no denying the bot generates traffic and serves as an emblem for Hollywood's AI panic.
More from The Hollywood Reporter
Oasis Sets 2027 Stadium Run: "It Shall Be a Sight to Behold"
SkyShowtime May Be Sold or Shut Down, Board Warns In Memo Shared With Staff (Exclusive)
#hate
28 days ago
During the September 8 episode of Mad Money, Jim Cramer turned his attention to Enbridge Inc. (NYSE:ENB), examining escalating geopolitical tensions. He commented:
As long as the war with Iran drags on, it's easy to recommend the refiners like a Valero or a Marathon. I don't see it ending any time soon, not with the US and Iran trading volleys this evening at islands and ships in the Strait. But how about a pipeline that moves about 30% of all crude produced in North America? Now, I'm talking about Enbridge which has a 5.5% yield. Also has a natural gas, you know, it transports 20% of the natural gas that's consumed in America. Okay, it's Canadian, but it's not caught up in the tariff fight because slapping tariffs on Canadian energy would be economic suicide for our country.
Cramer's focus on Enbridge Inc. (NYSE:ENB) highlights the structural dominance of its midstream network. The company operates as a significant transport network for North American energy, moving approximately 30% of all crude produced on the continent. Moreover, its vast utility and transmission network handles 20% of the natural gas consumed in the United States. The company's toll-road business model generates highly predictable cash flows, supporting an attractive dividend yield of roughly 5.6%. For income-focused investors, the combination of essential operational volume and reliable capital return creates a defensive cushion during volatile market cycles.
The company's defensive moat goes into cross-border trade and regional security. As Cramer pointed out, imposing punitive tariffs on Canadian energy imports would amount to severe economic self-harm for the United States, given the deep interdependence of North American energy grids.
Even with steady toll revenues, Enbridge Inc. (NYSE:ENB) carries a heavy debt load that comes with the territory of running massive pipeline networks, with long-term debt sitting at approximately C$104 billion. Because building and maintaining energy infrastructure requires heavy borrowing, higher interest rates hit financing costs, which can occasionally weigh on income-seeking investors.
#enbridge #natural #Iran #America

28 days ago
GE Aerospace (NYSE:GE) is making its largest acquisition since becoming a standalone publicly traded company. It agreed to acquire Consolidated Precision Products (CPP) for around $12 billion.
CPP is one of the world's largest precision castings providers. It's a major GE supplier. Precision castings is a major pressure point for the aerospace engines industry. Acquiring CPP would give GE Aerospace greater control over a critical part of its engine supply chain.
And the deal could strengthen GE's ability to meet demand already sitting in its backlog. But the investment case depends on whether additional production capacity generates enough free cash flow to justify the deal's premium price.
rommma/Shutterstock.com
Engine manufacturers like GE Aerospace (NYSE:GE) are struggling to keep pace with surging demand due to supply chain constraints. CPP is a major supplier of precision castings for GE's LEAP and GEnx engines. GE plans to raise CPP's output. It would do that by improving factory yields and machine use. With the CPP deal, GE also sees a path to accelerate production of new engine technologies.
#NYSE #largest #engines #supply

1 month ago
Oklo (NYSE: OKLO), a developer of microreactors for nuclear power plants, has been a divisive stock since its market debut. After going public through a merger with a special purpose acquisition company (SPAC) on May 10, 2024, Oklo started trading at $15.50 per share.
It soared to a record high of $174.14 on Oct. 14, 2025, but it now trades at about $43. Wall Street's average price target for the stock is about $75. Let's see why Oklo's stock went through so many wild swings -- and where I think it will actually end up by the end of 2026.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Oklo's Aurora microreactor, which is much smaller than conventional nuclear reactors, only generates 1.5 MWe per unit. However, its modular design allows it to be deployed alongside additional reactors to generate up to 75 MWe per "Powerhouse" power plant. That's tiny compared to a conventional nuclear power plant, which typically generates at least 1,000 MWe, but Aurora's Powerhouse plants can be deployed on less land in remote, off-grid areas.
The Aurora also uses metallic uranium fuel pellets, which are denser, have higher thermal resistance, and are cheaper to produce than the uranium dioxide fuel pellets that power conventional reactors. By recycling its pellets in a closed loop, the Aurora can last for a decade without refueling. Conventional reactors are still refueled in stages every two years.
#conventional #reactors #signal

1 month ago
General Motors Company (NYSE:GM) reached a tentative three-year labor deal with Unifor that Canadian workers ratified on August 29 and 30, securing more than C$1 billion ($791 million) in new and previously announced investment across Ontario, covering over 4,600 workers.
GM will spend C$144 million to bring next-generation Heavy-Duty GMC Sierra production to Oshawa, adding to a previously committed C$343 million there. At St. Catharines, GM will invest C$215 million in a new transmission program starting late 2029, on top of a previously announced C$691 million for V8 engine production. GM also pledged not to immediately sell or close its CAMI plant in Ingersoll while it studies alternatives, including possible defense work if it lands a Canadian Armed Forces contract. The deal lands as Canada's auto sector faces 25% U.S. tariffs, with Trump threatening to double that to 50% on January 1, 2027, and U.S. and Canada trade talks still stalled.
General Motors Company (NYSE:GM) enters this deal from a position of financial strength. GM beat second-quarter expectations with adjusted earnings per share of $3.57 versus the $3.18 estimate and revenue of $48 billion versus the $46.99 billion forecast. The company also raised its full-year guidance for the second time this year, while adjusted automotive free cash flow reached $5 billion, up $2.2 billion year over year. That cash generation gives GM room to fund its Canadian commitments without putting significant pressure on its balance sheet.
The tariff environment has also become more favorable for GM. After the Supreme Court invalidated tariffs imposed under emergency powers, GM lowered its full-year gross tariff-cost estimate to $2.5 billion-$3.5 billion from $3 billion-$4 billion. Protecting Canadian production now could reduce the risk of costly disruptions as GM adjusts its North American manufacturing footprint and responds to changing trade policies.
The agreement also protects GM's pickup and SUV business, which generates some of the company's highest margins. CEO Mary Barra said North American demand remains strong for these vehicles, while the return of Heavy-Duty Sierra production to Oshawa will give GM additional North American capacity for a key product line. Producing more trucks within the region could also help GM reduce its exposure to cross-border tariff costs.
#million

1 month ago
Applied Digital (NASDAQ:APLD) primarily generates its revenue by operating centralized digital infrastructure campuses and providing dedicated computing services designed for high-performance workloads across the North American region.
It recently signed an additional facility lease for a new campus and secured supplemental credit financing for ongoing construction, while reporting an operating margin of -45% for the quarter ended May 31, 2026.
IREN (NASDAQ:IREN) earns the majority of its ongoing revenue by managing vertically integrated data center facilities and actively mining digital **** ets across its international infrastructure footprint.
While integrating a newly acquired European data center developer and closing the purchase of cloud software provider Mirantis, it recorded an operating margin of -452% for the quarter ended June 30, 2026.
Revenue serves as a primary starting point for investors to evaluate a corporation's ability to attract paying clients and generate gross business volume before standard operational expenses, local taxes, or daily administrative costs are finally subtracted. For neocloud operations such as Applied Digital and IREN, revenue growth is essential to understanding if their costly artificial intelligence infrastructure buildouts are paying off.
#applied #across

1 month ago
WestEnd Capital Management, an investment advisor, released its Q2 2026 investor letter. The letter can be downloaded here. WestEnd Capital Management's Core Strategy achieved a 16.3% net return in the quarter, surpassing the S&P 500's 15.0%. This performance stemmed from strong earnings generators and upward earnings revisions, showcasing U.S. companies' efficiency in converting sales into profits. S&P 500 net profit margins reached a decade-high of 14.8% in Q1 and are expected to remain above 14% in Q2 despite challenges like higher interest rates and geopolitical uncertainty. Technology remains a key focus in WestEnd's portfolio, along with investments in infrastructure, demographic shifts, financial innovation, and selective consumer opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, WestEnd Capital Management highlighted WaterBridge Infrastructure LLC (NYSE:WBI). WaterBridge Infrastructure LLC (NYSE:WBI) is a pure-play water infrastructure company. On September 2, 2026, WaterBridge Infrastructure LLC (NYSE:WBI) closed at $32.26 per share. Over the past month, WaterBridge Infrastructure LLC (NYSE:WBI) declined 1.31%, while YTD its shares are up 61.37%. WaterBridge Infrastructure LLC (NYSE:WBI) has a market capitalization of $3.98 billion.
WestEnd Capital Management stated the following regarding WaterBridge Infrastructure LLC (NYSE:WBI) in its Q2 2026 investor letter:
"WaterBridge Infrastructure LLC (NYSE:WBI) owns and operates the largest independent produced-water infrastructure network in the Delaware Basin, providing services that are essential to energy production throughout one of North America's most productive oil basins.
The scale and density of this network would be extremely difficult and expensive to replicate. WaterBridge also generates most of its revenue through long-term contracts that include minimum-volume commitments and inflation-linked pricing.
#waterbridge #investor #quarter #earnings
1 month ago
WestEnd Capital Management, an investment advisor, released its Q2 2026 investor letter. The letter can be downloaded here. WestEnd Capital Management's Core Strategy achieved a 16.3% net return in the quarter, surpassing the S&P 500's 15.0%. This performance stemmed from strong earnings generators and upward earnings revisions, showcasing U.S. companies' efficiency in converting sales into profits. S&P 500 net profit margins reached a decade-high of 14.8% in Q1 and are expected to remain above 14% in Q2 despite challenges like higher interest rates and geopolitical uncertainty. Technology remains a key focus in WestEnd's portfolio, along with investments in infrastructure, demographic shifts, financial innovation, and selective consumer opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, WestEnd Capital Management highlighted Janus Living, Inc. (NYSE:JAN). Janus Living, Inc. (NYSE:JAN) is the only U.S. publicly traded REIT focused exclusively on the senior housing sector and the only U.S. publicly traded REIT. On September 2, 2026, Janus Living, Inc. (NYSE:JAN) closed at $30.70 per share. Over the past month, Janus Living, Inc. (NYSE:JAN) returned 5.51%, and its shares are up 27.08% over the three months. Janus Living, Inc. (NYSE:JAN) has a market capitalization of $9.45 billion.
WestEnd Capital Management stated the following regarding Janus Living, Inc. (NYSE:JAN) in its Q2 2026 investor letter:
"Janus Living, Inc. (NYSE:JAN) is one of the nation's largest pure-play owners and operators of senior housing communities. Unlike traditional triple-net REITs that collect fixed lease payments, Janus generates operating income directly from resident rents and service fees. That means the company captures the full operational upside as occupancy and rental rates increase, while also ******* uming the operational risks of running its communities. Because residents pay privately rather than through Medicare or Medicaid reimbursement programs, the business is largely insulated from changes in government reimbursement policy.
The industry's long-term fundamentals remain compelling:
#westend

1 month ago
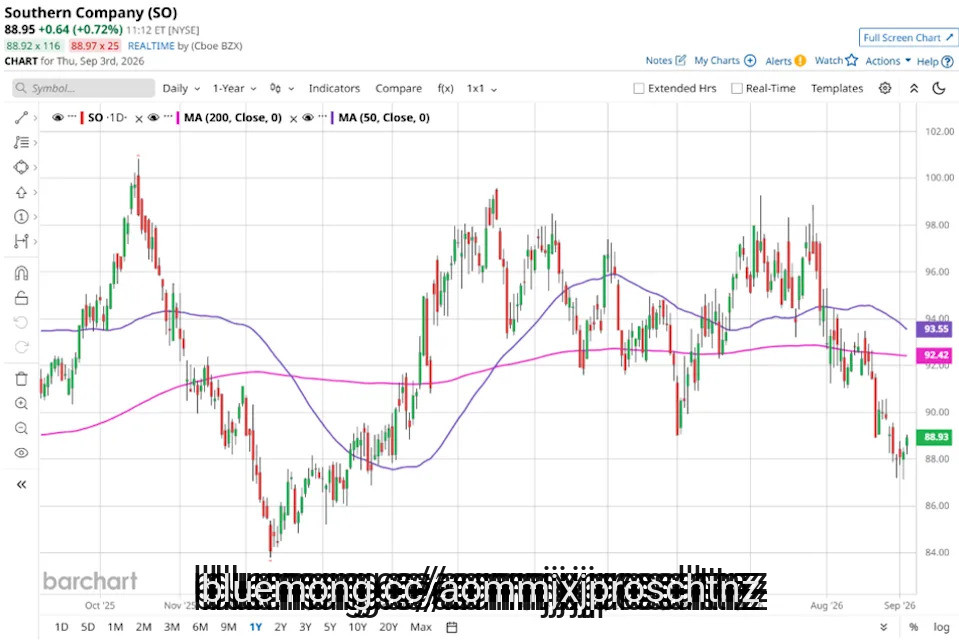
Atlanta, Georgia-based The Southern Company (SO) generates, transmits, and distributes electricity. Valued at $101.6 billion by market cap, the company also offers wireless telecommunications services, provides businesses with two-way radio, telephone, paging, and internet access services, and wholesales fiber optic solutions.
Companies worth $10 billion or more are generally described as "large-cap stocks," and SO definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the utilities - regulated electric industry. SO has a robust foundation, with strong finances, a skilled workforce, and extensive infrastructure, including power plants and transmission lines. The company's expertise in navigating complex regulatory environments and influencing energy policy is a key ***** et.
A Potential ***** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
Fears of an Extended US-Iran Conflict Boost Crude Oil Prices
Nat-Gas Prices Rise on Hotter US Weather and Expectations of Smaller Storage
#company #market #Services #atlanta


1 month ago
On August 3, Ethos Technologies (NASDAQ:LIFE) reported second-quarter results for the period ended June 30, showing revenue climbing 113% year over year to $189.6 million, the company's second straight quarter above triple-digit growth. Alongside the print, Ethos said its board had authorized a new $100 million buyback of its Class A common stock. For a life insurance technology company that only recently went public, doubling revenue while also committing fresh capital to share repurchases is the kind of combination that invites a closer look at what is actually driving the numbers underneath.
The top line breaks down into two channels moving at different speeds. Direct channel revenue grew 131% year over year to $116.5 million, which Ethos said came with similar unit economics to prior periods, while third-party revenue grew 90% to $73.1 million. Behind those dollars sits actual policy volume. Ethos activated 107,847 new policies in the quarter, up 133% year over year, extending past 100,000 added families in a single three-month stretch. Gross profit came in at $185.5 million, a 98% gross margin, showing that the underlying cost of writing each policy remains small relative to what it generates in revenue.
Cash generation kept pace too. The company produced $35.7 million in net cash from operations during the quarter and $66.9 million over the first six months of 2026, helping push its cash and cash equivalents balance to $112.2 million from $91.1 million at the end of 2025. Ethos also widened its product shelf, launching a Juvenile IUL policy in partnership with North American. Management's outlook points to more of the same: third-quarter revenue guidance of $160 million to $164 million implies 73% year-over-year growth at the midpoint, and full-year 2026 guidance calls for revenue between $727 million and $731 million, an 88% increase, alongside adjusted EBITDA of $119 million to $123 million for the year.
The strain shows up once the growth is measured against what actually reaches the bottom line. GAAP net income was $19.5 million, a 10% margin, barely above the $18.5 million Ethos earned in the same quarter a year ago despite revenue more than doubling in between. Contribution margin, which strips out sales and marketing costs, fell to 33% from 42% a year earlier. Adjusted EBITDA margin slipped to 19% from 23%, even though the EBITDA dollar figure itself grew to $35.2 million from $20.8 million. Revenue per activated policy fell 8% year over year to $1,758, which Ethos attributed to a shift in channel and product mix, meaning each new policy is worth less on average than it used to be.
#policy #Margin