17 hours ago
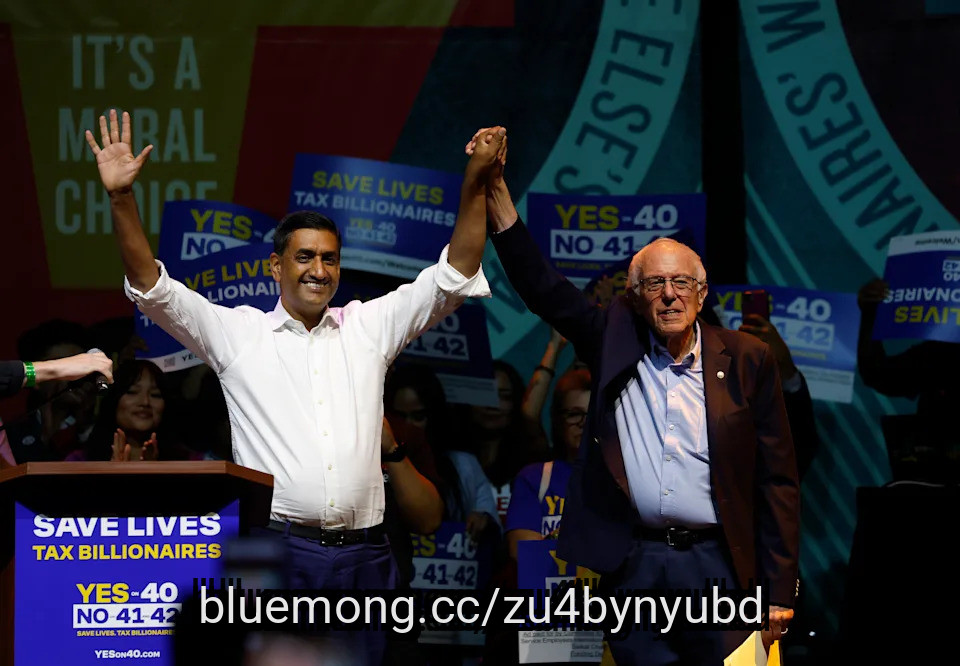
California's proposed billionaire tax appeared headed for defeat on Wednesday in one of the final verdicts from voters in an election week that saw a wave of anti-billionaire sentiment elsewhere.
The latest results on Wednesday afternoon showed California's Proposition 40 down by over 11 percentage points, with 60% of votes counted but the race not yet formally called.
The referendum would amend California's constitution and impose a one-time 5% tax on California residents and trusts with ***** ets over $1 billion on Jan. 1, 2026. The revenue would primarily go toward healthcare, as well as food ***** istance and education.
Some ***** ets, such as real property and certain retirement accounts and pensions, were excluded.
The measure was estimated to impact about 200 billionaires in the state. It faced fierce opposition from many in Big Tech and lost steam with voters as Election Day neared.
#wednesday #election #voters #proposed
The latest results on Wednesday afternoon showed California's Proposition 40 down by over 11 percentage points, with 60% of votes counted but the race not yet formally called.
The referendum would amend California's constitution and impose a one-time 5% tax on California residents and trusts with ***** ets over $1 billion on Jan. 1, 2026. The revenue would primarily go toward healthcare, as well as food ***** istance and education.
Some ***** ets, such as real property and certain retirement accounts and pensions, were excluded.
The measure was estimated to impact about 200 billionaires in the state. It faced fierce opposition from many in Big Tech and lost steam with voters as Election Day neared.
#wednesday #election #voters #proposed

18 hours ago
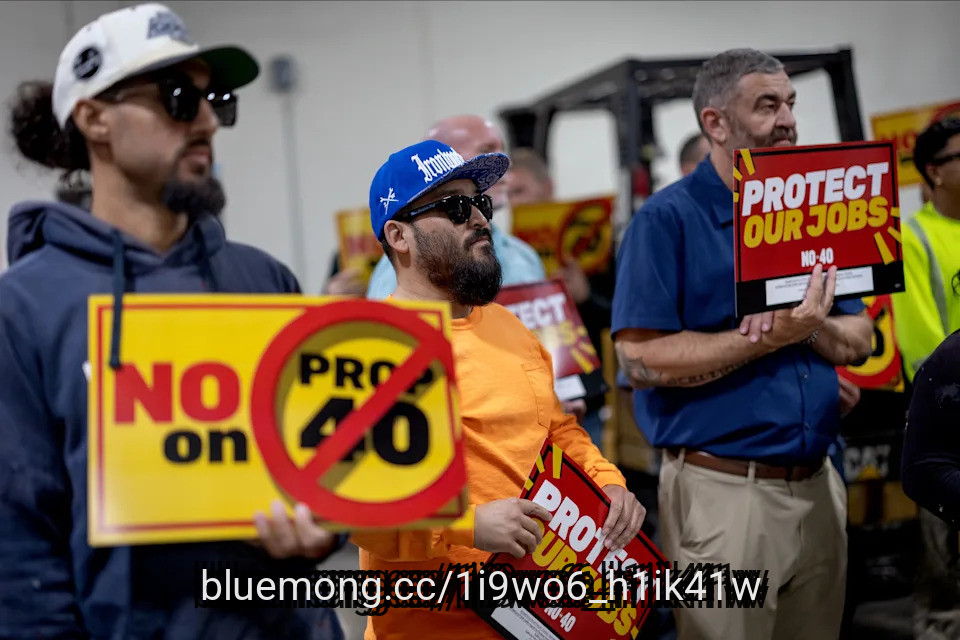
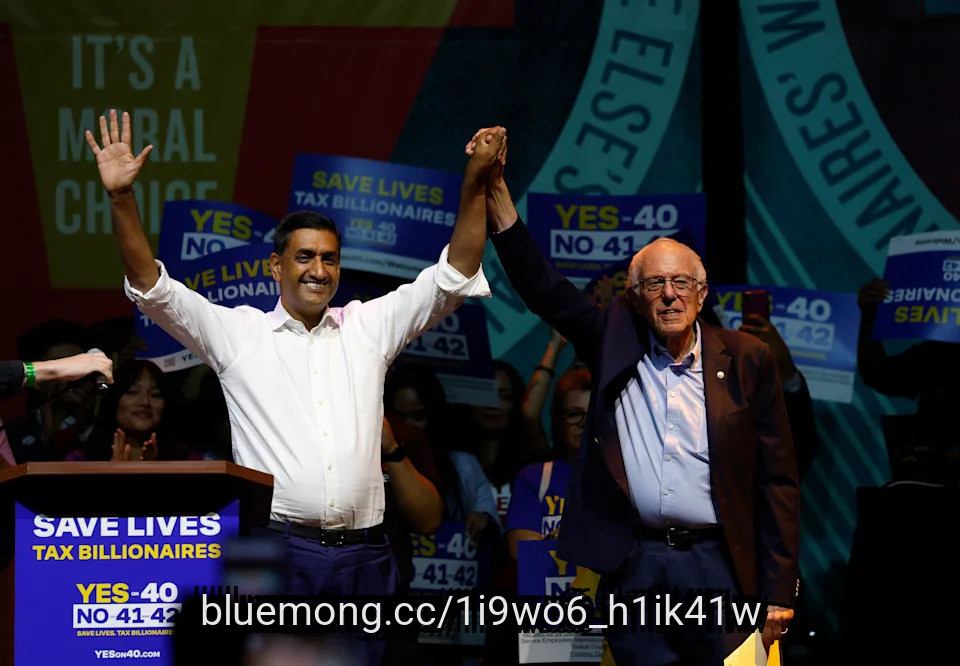
California's proposed billionaire tax appeared headed for defeat on Wednesday in one of the final verdicts from voters in an election week that saw a wave of anti-billionaire sentiment elsewhere.
The latest results on Wednesday afternoon showed California's Proposition 40 down by over 11 percentage points, with 60% of votes counted but the race not yet formally called.
The referendum would amend California's constitution and impose a one-time 5% tax on California residents and trusts with **** ets over $1 billion on Jan. 1, 2026. The revenue would primarily go toward healthcare, as well as food **** istance and education.
Some **** ets, such as real property and certain retirement accounts and pensions, were excluded.
The measure was estimated to impact about 200 billionaires in the state. It faced fierce opposition from many in Big Tech and lost steam with voters as Election Day neared.
#wednesday #election #voters #appeared
The latest results on Wednesday afternoon showed California's Proposition 40 down by over 11 percentage points, with 60% of votes counted but the race not yet formally called.
The referendum would amend California's constitution and impose a one-time 5% tax on California residents and trusts with **** ets over $1 billion on Jan. 1, 2026. The revenue would primarily go toward healthcare, as well as food **** istance and education.
Some **** ets, such as real property and certain retirement accounts and pensions, were excluded.
The measure was estimated to impact about 200 billionaires in the state. It faced fierce opposition from many in Big Tech and lost steam with voters as Election Day neared.
#wednesday #election #voters #appeared

6 days ago
UW and Nebraska face off in Lincoln this weekend for the first time as conference foes. The long and storied history between the two teams stretches exactly 101 years and two weeks to the day between the very first match up in 1925 and this Saturday's game. That shared history primarily revolves around the four games played during the 1990s when both programs were at their peak. The 1991 game featured a furious second half comeback in Lincoln that built the momentum towards UW's eventual national championship. The Cornhuskers' return trip to Seattle in 1992 set the stage for the loudest recorded home crowd in college football history. Five years later, Nebraska returned to Montlake to get their revenge for the previous two games while on their way to their own national championship in 1997 in Tom Osborne's final season.
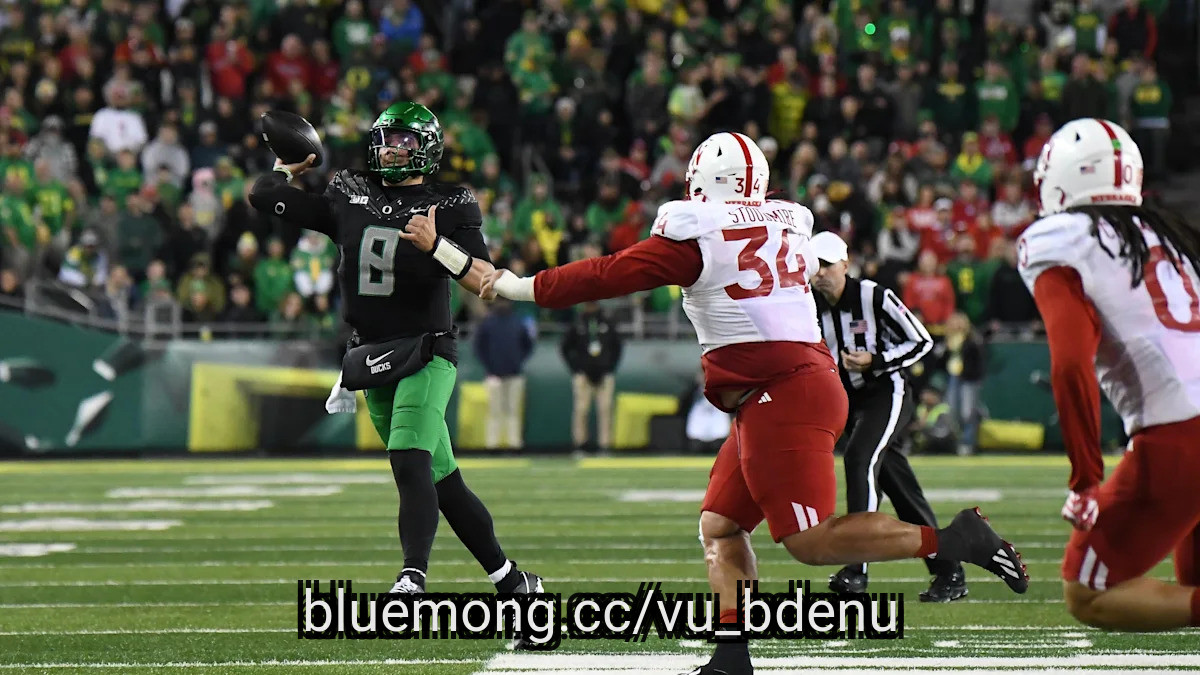
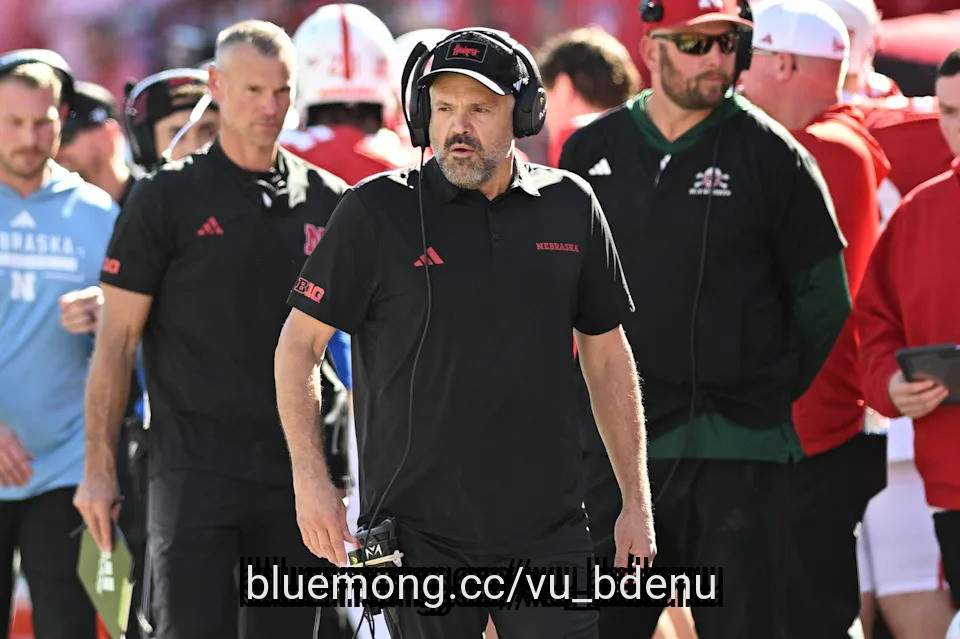
For these two programs, the current stakes of this weekend's game are much lower, although not entirely without significance. Both Washington and Nebraska enter Saturday night's matchup at a crossroads in their seasons. Nebraska sits at 5-2 overall and 2-2 in Big Ten play, but the Cornhuskers are coming off consecutive close losses to Indiana and Oregon. Despite those defeats, Matt Rhule's team has established itself as one of the league's most physical and statistically dominant defenses, keeping every game within reach through disciplined play, strong linebacker action, and excellent situational defense.
Washington, meanwhile, is 4-3 overall and 1-3 in conference play. The Huskies snapped a three-game losing streak with a 38-26 victory over Purdue before their bye week and arrive in Lincoln needing momentum to salvage their Big Ten campaign. Jedd Fisch's offense remains heavily dependent on its passing attack, ranking among the conference's better aerial units, but questions at quarterback and a struggling rushing offense persist.
Over Matt Rhule's four years at Nebraska, the Cornhuskers have embraced a physical and gritty, defensive-oriented identity as a program. Under first-year defensive coordinator, Rob Aurich, Nebraska has maintained the aggressive, fundamentally sound identity Nebraska built under Rhule. The Cornhuskers rank 14th nationally in scoring defense, 9th in total defense, and are holding opponents to just 171 passing yards and 99 rushing yards per game on average. Their suffocating rushing defense on early downs often position them in 3rd & long passing situations where they pressure packages and blanketing secondary can create plays. This formula is what has allowed Nebraska to lead the FBS in defensive 3rd down conversion percentage at just 19%. To put that statistic into perspective, Nebraska's defense has allowed just eight third down conversions in their four Big Ten conference games this season, including games with just one allowed against Maryland and Indiana.
Nebraska typically operates from a multiple-front structure, mixing even-front and odd-front looks while emphasizing gap discipline and disgui
For these two programs, the current stakes of this weekend's game are much lower, although not entirely without significance. Both Washington and Nebraska enter Saturday night's matchup at a crossroads in their seasons. Nebraska sits at 5-2 overall and 2-2 in Big Ten play, but the Cornhuskers are coming off consecutive close losses to Indiana and Oregon. Despite those defeats, Matt Rhule's team has established itself as one of the league's most physical and statistically dominant defenses, keeping every game within reach through disciplined play, strong linebacker action, and excellent situational defense.
Washington, meanwhile, is 4-3 overall and 1-3 in conference play. The Huskies snapped a three-game losing streak with a 38-26 victory over Purdue before their bye week and arrive in Lincoln needing momentum to salvage their Big Ten campaign. Jedd Fisch's offense remains heavily dependent on its passing attack, ranking among the conference's better aerial units, but questions at quarterback and a struggling rushing offense persist.
Over Matt Rhule's four years at Nebraska, the Cornhuskers have embraced a physical and gritty, defensive-oriented identity as a program. Under first-year defensive coordinator, Rob Aurich, Nebraska has maintained the aggressive, fundamentally sound identity Nebraska built under Rhule. The Cornhuskers rank 14th nationally in scoring defense, 9th in total defense, and are holding opponents to just 171 passing yards and 99 rushing yards per game on average. Their suffocating rushing defense on early downs often position them in 3rd & long passing situations where they pressure packages and blanketing secondary can create plays. This formula is what has allowed Nebraska to lead the FBS in defensive 3rd down conversion percentage at just 19%. To put that statistic into perspective, Nebraska's defense has allowed just eight third down conversions in their four Big Ten conference games this season, including games with just one allowed against Maryland and Indiana.
Nebraska typically operates from a multiple-front structure, mixing even-front and odd-front looks while emphasizing gap discipline and disgui


6 days ago
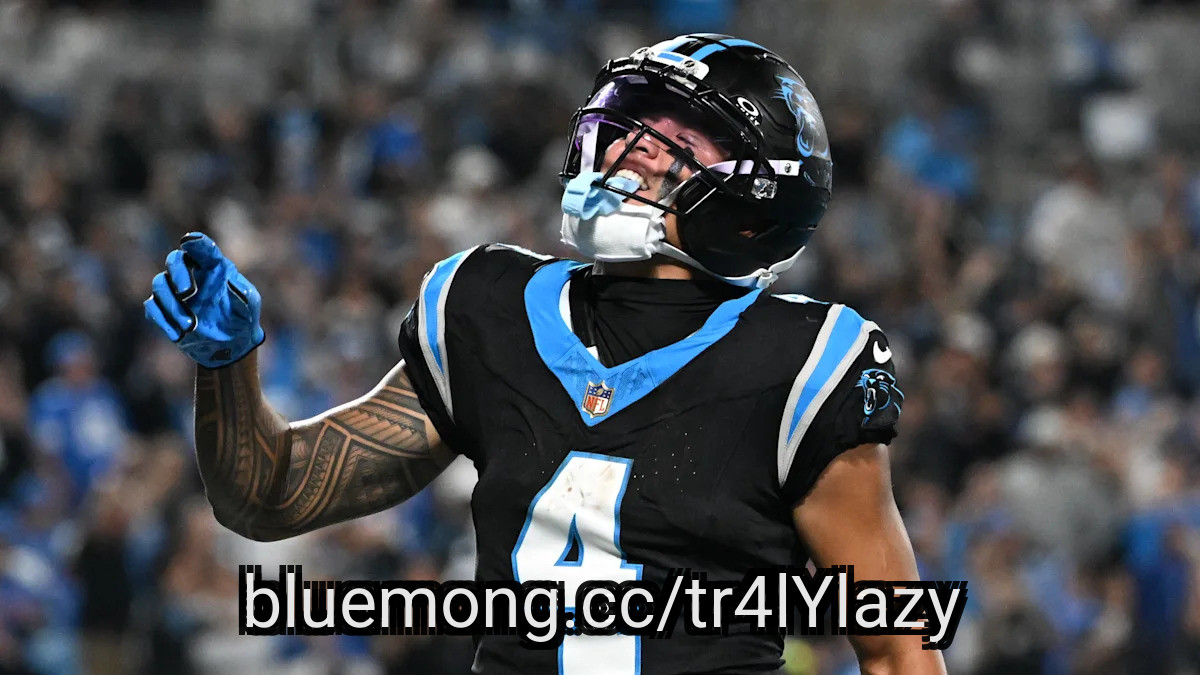
Carolina Panthers WR Tetairoa McMillan had six receptions for 58 yards against the Green Bay Packers in Week 8. He was targeted a team-high 11 times in the loss.
SOURCE: USA TODAY
Why It Matters: With Bryce Young under duress on Thursday night, the passing game was primarily quick hitters with the hope that the wideouts could break a tackle or two and make a big play. It rarely worked out that way, however, and as a result McMillan averaged just 9.7 yards per catch. It was his third largely disappointing performance in his last five games and second in a row. We all saw what this passing attack could look like early this season, so McMillan's upside remains substantial, but the Panthers need to figure out a way to keep Young upright so he can take more downfield shots. While it's too soon to downgrade McMillan below WR2 status, his recent production has not been on that level.
This article originally appeared on USA TODAY: Tetairoa McMillan leads Carolina in receiving on Thursday night
#mcmillan
SOURCE: USA TODAY
Why It Matters: With Bryce Young under duress on Thursday night, the passing game was primarily quick hitters with the hope that the wideouts could break a tackle or two and make a big play. It rarely worked out that way, however, and as a result McMillan averaged just 9.7 yards per catch. It was his third largely disappointing performance in his last five games and second in a row. We all saw what this passing attack could look like early this season, so McMillan's upside remains substantial, but the Panthers need to figure out a way to keep Young upright so he can take more downfield shots. While it's too soon to downgrade McMillan below WR2 status, his recent production has not been on that level.
This article originally appeared on USA TODAY: Tetairoa McMillan leads Carolina in receiving on Thursday night
#mcmillan

6 days ago
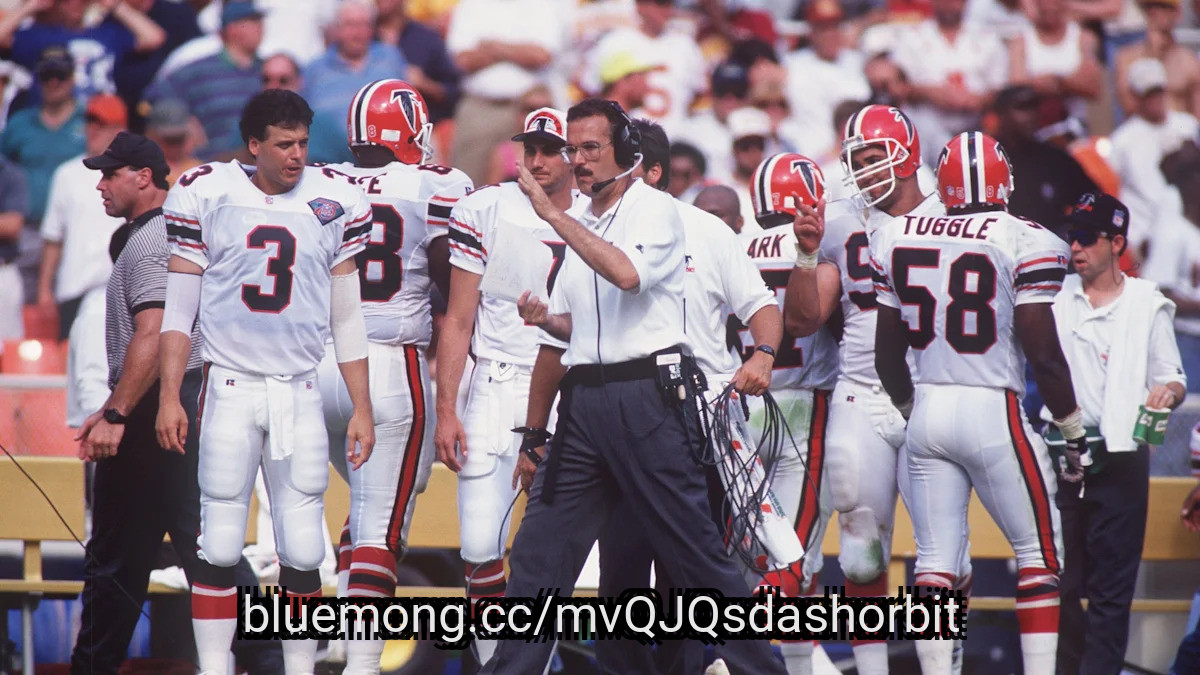
Jones spent time in Atlanta as both a quarterback and head coach, leaving a unique mark on the franchise's history.
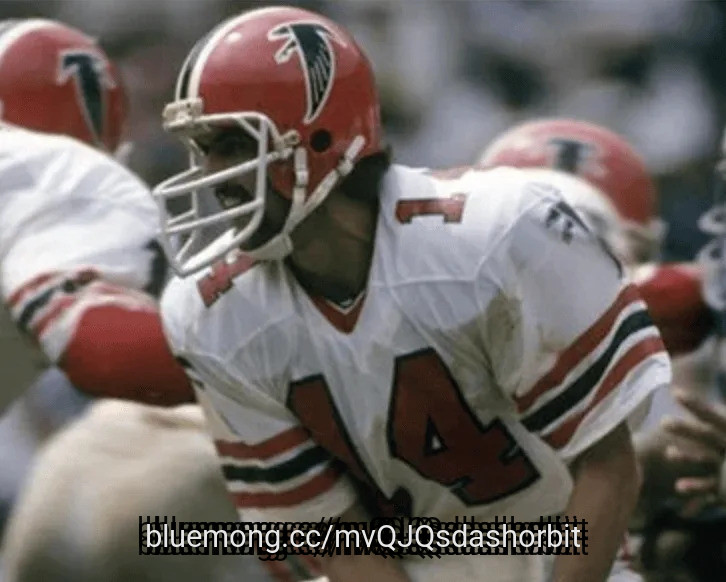
The Atlanta Falcons have lost another familiar figure from their history, as former quarterback and head coach June Jones passed away on Thursday at the age of 73.
Jones had a lengthy football career that took him across the NFL, college football, and beyond, but his connection to Atlanta was particularly unique. It's not often that a player gets the opportunity to return to the same franchise as a coach, much less lead the team as its head coach. Jones was one of the rare individuals who experienced both sides of that relationship with the Falcons.
Jones originally joined Atlanta as an undrafted quarterback in 1977, spending five seasons with the franchise through 1981. Primarily serving as a backup, he appeared in 17 games and threw for 923 yards and three touchdowns. His playing career wasn't particularly memorable statistically, but his time in Atlanta would prove to be just the beginning of his relationship with the franchise.
After transitioning into coaching, Jones eventually returned to Atlanta in 1991 as offensive coordinator under Jerry Glanville. When Glanville departed following the 1993 season, Jones was promoted to head coach, a position he held from 1994 through 1996.
#jones #atlanta #coach #falcons
The Atlanta Falcons have lost another familiar figure from their history, as former quarterback and head coach June Jones passed away on Thursday at the age of 73.
Jones had a lengthy football career that took him across the NFL, college football, and beyond, but his connection to Atlanta was particularly unique. It's not often that a player gets the opportunity to return to the same franchise as a coach, much less lead the team as its head coach. Jones was one of the rare individuals who experienced both sides of that relationship with the Falcons.
Jones originally joined Atlanta as an undrafted quarterback in 1977, spending five seasons with the franchise through 1981. Primarily serving as a backup, he appeared in 17 games and threw for 923 yards and three touchdowns. His playing career wasn't particularly memorable statistically, but his time in Atlanta would prove to be just the beginning of his relationship with the franchise.
After transitioning into coaching, Jones eventually returned to Atlanta in 1991 as offensive coordinator under Jerry Glanville. When Glanville departed following the 1993 season, Jones was promoted to head coach, a position he held from 1994 through 1996.
#jones #atlanta #coach #falcons

28 days ago
Republican efforts to reduce national gas prices in the weeks before Election Day were derailed in the Senate by infighting among GOP lawmakers and members of the administration who could not agree on how to ease consumers’ pain at the pump.
The divisions within the Senate Republican conference over how to lower gas and diesel prices — even if temporarily — were driven primarily by geographic differences.
Senators from oil-refining states shot down proposals from farm-state senators to ban the export of diesel or to loosen restrictions on the sale of E15 gasoline with higher ethanol content.
“You’re talking about regional politics, and it gets bogged down in the politics of energy, and the fiefdoms around it,” said Ron Bonjean, a GOP strategist and former Senate leadership aide.
There were divisions that went beyond geography, too.
#republican
The divisions within the Senate Republican conference over how to lower gas and diesel prices — even if temporarily — were driven primarily by geographic differences.
Senators from oil-refining states shot down proposals from farm-state senators to ban the export of diesel or to loosen restrictions on the sale of E15 gasoline with higher ethanol content.
“You’re talking about regional politics, and it gets bogged down in the politics of energy, and the fiefdoms around it,” said Ron Bonjean, a GOP strategist and former Senate leadership aide.
There were divisions that went beyond geography, too.
#republican

29 days ago
Ray Fisher became internationally recognizable as the technologically enhanced superhero Cyborg, but his career began far from the world of comic book blockbusters. The American actor developed his craft through theater before making the leap to major Hollywood productions. His upbringing, particularly the influence of his mother and grandmother, helped shape the values he later carried into his professional life. When Fisher encountered difficulties behind the scenes of Justice League, he chose to speak publicly about his experience. That decision became an important part of a career increasingly ****** ociated with both performance and workplace accountability.
Born in Baltimore, Maryland, Fisher grew up in Lawnside, New Jersey, in a large family raised primarily by his mother and grandmother. He has described both women as his real life superheroes, praising the determination and strength they demonstrated while he was growing up. His interest in acting became serious during high school, when encouragement from a teacher led him to audition for theatrical productions.
Fisher continued developing as a stage performer and eventually established himself in professional theater. One of his most demanding early roles was Muhammad Ali in the Off Broadway production Fetch Clay, Make Man. Preparing to portray the legendary boxer required substantial physical transformation as well as the ability to capture Ali's confidence and personality. The experience demonstrated the discipline Fisher could bring to a role before Hollywood audiences became familiar with him.
His major screen opportunity arrived when Zack Snyder selected him to play Victor Stone, better known as Cyborg, in the DC film universe. Fisher made a brief appearance in Batman v Superman: Dawn of Justice before receiving a much larger role in Justice League. Production changed significantly after Snyder left the project and Joss Whedon took over during post production. The theatrical version released in 2017 reduced much of Cyborg's original storyline.
In 2020, Fisher publicly accused Whedon of inappropriate and unprofessional behavior during the Justice League reshoots. WarnerMedia subsequently conducted an investigation after Fisher raised concerns involving the production. In December 2020, the company announced that the investigation had concluded and that remedial action had been taken, without publicly detailing what those measures involved.
#justice #became #hollywood #whedon
Born in Baltimore, Maryland, Fisher grew up in Lawnside, New Jersey, in a large family raised primarily by his mother and grandmother. He has described both women as his real life superheroes, praising the determination and strength they demonstrated while he was growing up. His interest in acting became serious during high school, when encouragement from a teacher led him to audition for theatrical productions.
Fisher continued developing as a stage performer and eventually established himself in professional theater. One of his most demanding early roles was Muhammad Ali in the Off Broadway production Fetch Clay, Make Man. Preparing to portray the legendary boxer required substantial physical transformation as well as the ability to capture Ali's confidence and personality. The experience demonstrated the discipline Fisher could bring to a role before Hollywood audiences became familiar with him.
His major screen opportunity arrived when Zack Snyder selected him to play Victor Stone, better known as Cyborg, in the DC film universe. Fisher made a brief appearance in Batman v Superman: Dawn of Justice before receiving a much larger role in Justice League. Production changed significantly after Snyder left the project and Joss Whedon took over during post production. The theatrical version released in 2017 reduced much of Cyborg's original storyline.
In 2020, Fisher publicly accused Whedon of inappropriate and unprofessional behavior during the Justice League reshoots. WarnerMedia subsequently conducted an investigation after Fisher raised concerns involving the production. In December 2020, the company announced that the investigation had concluded and that remedial action had been taken, without publicly detailing what those measures involved.
#justice #became #hollywood #whedon



29 days ago
A woman claims she's cracked the code on identifying people you need to stay away from. In a TikTok video, Sid (sidandlisten) explained that her extensive experience watching true crime documentaries, along with her background in managing a YouTube channel that focused on true crime at one point, has given her insights into the types of people to be cautious of when dating.
"If you are dating someone and they have dead eyes, like, they. They. It doesn't express anything, and they just kind of look at you like this without moving their eyes or anything like that, and, like, there's just, like, no movement. There's no movement at all," Sid said. As she mentioned this, she stared blankly into the camera in an effort to show what the expression would look like in person.
Sid then highlighted another thing people should look out for when dating: pursed lips. "And they purse their lips like this when they're talking, and their eyes are really dead. Run!," Sid said in her video's conclusion.
Sid's video has gained more than 2 million views, with thousands of people liking, commenting, sharing, and saving it. Speaking of the comments, some people appear to agree with Sid, primarily because of their personal experience.
One person wrote, "this is 100% True. my grandma used to always tell my mum "you can tell a person by their eyes", needless to say I didn't heed this information and ended up in a relationship where I was almost part of the next true crime series…(run before they start planning to skin you alive folks LOL…)" Another person said, "girl I can see it. I used to avoid people I would meet and had an empty look in their eyes 20 even 30 years ago… you can just tell when someone is basically possessed…"
#like #people #dating
"If you are dating someone and they have dead eyes, like, they. They. It doesn't express anything, and they just kind of look at you like this without moving their eyes or anything like that, and, like, there's just, like, no movement. There's no movement at all," Sid said. As she mentioned this, she stared blankly into the camera in an effort to show what the expression would look like in person.
Sid then highlighted another thing people should look out for when dating: pursed lips. "And they purse their lips like this when they're talking, and their eyes are really dead. Run!," Sid said in her video's conclusion.
Sid's video has gained more than 2 million views, with thousands of people liking, commenting, sharing, and saving it. Speaking of the comments, some people appear to agree with Sid, primarily because of their personal experience.
One person wrote, "this is 100% True. my grandma used to always tell my mum "you can tell a person by their eyes", needless to say I didn't heed this information and ended up in a relationship where I was almost part of the next true crime series…(run before they start planning to skin you alive folks LOL…)" Another person said, "girl I can see it. I used to avoid people I would meet and had an empty look in their eyes 20 even 30 years ago… you can just tell when someone is basically possessed…"
#like #people #dating

29 days ago
US authorities have arrested a 30-year-old from Washington state in connection with the February school shooting in Tumbler Ridge, British Columbia.
James Cody Bryant was arrested in Bellingham, Washington, on Tuesday morning on a charge of conspiracy to murder persons in a foreign country, according to the US Justice Department. The February attack on a secondary school in the small town at the foothills of the Rocky Mountains was Canada’s deadliest school shooting in decades, leaving eight people dead, including six children, and dozens wounded.
Bryant appeared in court Tuesday afternoon in Seattle. CNN has reached out to Bryant’s lawyer for comment. A hearing has been set for October 20.
Bryant was allegedly “in repeated contact with” the 18-year-old Canadian shooter, Jesse Van Rootselaar, “offering advice, sending money and even agreeing to live stream the horrific event” on Twitch, said Neil Floyd, the acting US attorney for the Western District of Washington, at a press conference in Seattle.
The money Bryant gave the shooter amounted to a little over $100, primarily to buy a lighter and a pair of shoes that Van Rootselaar “wanted to have when she conducted this killing spree,” Floyd said. The two discussed sending weapons to Van Rootselaar, but Bryant was uncomfortable with doing so and refused, according to a complaint filed in court on Friday.
#bryant #washington #school #year
James Cody Bryant was arrested in Bellingham, Washington, on Tuesday morning on a charge of conspiracy to murder persons in a foreign country, according to the US Justice Department. The February attack on a secondary school in the small town at the foothills of the Rocky Mountains was Canada’s deadliest school shooting in decades, leaving eight people dead, including six children, and dozens wounded.
Bryant appeared in court Tuesday afternoon in Seattle. CNN has reached out to Bryant’s lawyer for comment. A hearing has been set for October 20.
Bryant was allegedly “in repeated contact with” the 18-year-old Canadian shooter, Jesse Van Rootselaar, “offering advice, sending money and even agreeing to live stream the horrific event” on Twitch, said Neil Floyd, the acting US attorney for the Western District of Washington, at a press conference in Seattle.
The money Bryant gave the shooter amounted to a little over $100, primarily to buy a lighter and a pair of shoes that Van Rootselaar “wanted to have when she conducted this killing spree,” Floyd said. The two discussed sending weapons to Van Rootselaar, but Bryant was uncomfortable with doing so and refused, according to a complaint filed in court on Friday.
#bryant #washington #school #year


1 month ago
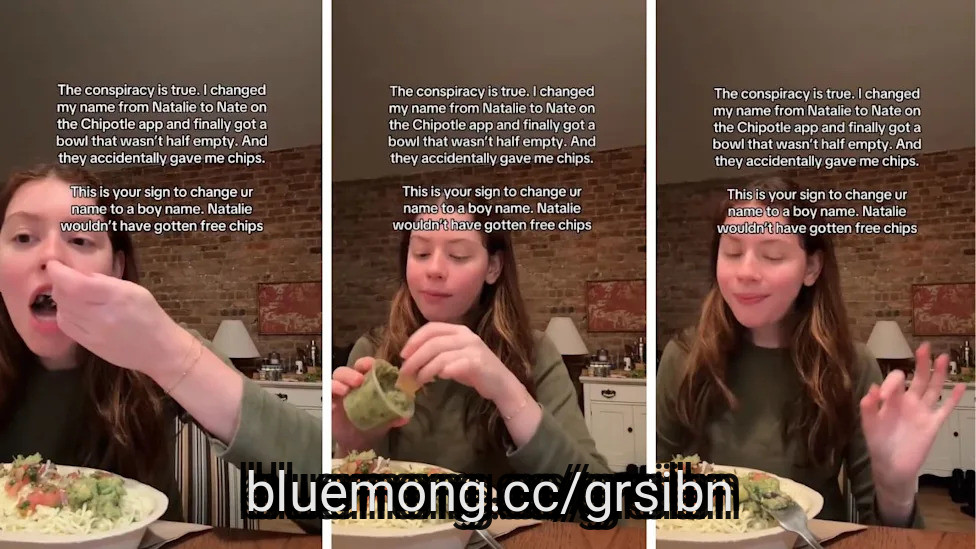
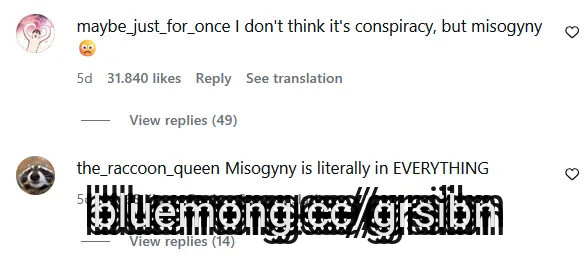
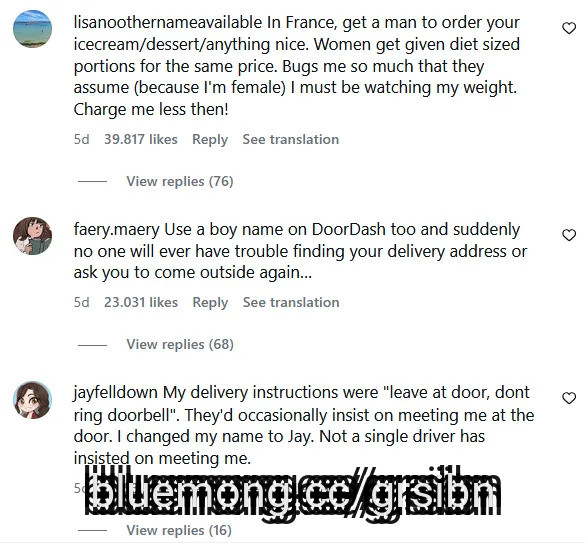
A woman's experiment with changing the name on her food order has gone viral after she claimed that using a man's name in the Chipotle app supposedly resulted in noticeably larger portions.
The story spread across TikTok and Instagram, prompting other women to share similar experiences in which changing the name attached to an order to a more masculine one purportedly affected the food quantity they received.
Natalie Melissa Kelly, known online as Style By Natalie, is a New York City-based content creator who primarily posts about fashion, her daily life and other lifestyle topics.
Her biggest viral moment, however, came from a video about a much more routine activity: ordering food from Chipotle.
Originally posted to TikTok in December 2025 and later reposted to Instagram in September 2026, the video shows Kelly claiming that she received more food than usual from Chipotle after placing her order under a masculine name.
#changing
The story spread across TikTok and Instagram, prompting other women to share similar experiences in which changing the name attached to an order to a more masculine one purportedly affected the food quantity they received.
Natalie Melissa Kelly, known online as Style By Natalie, is a New York City-based content creator who primarily posts about fashion, her daily life and other lifestyle topics.
Her biggest viral moment, however, came from a video about a much more routine activity: ordering food from Chipotle.
Originally posted to TikTok in December 2025 and later reposted to Instagram in September 2026, the video shows Kelly claiming that she received more food than usual from Chipotle after placing her order under a masculine name.
#changing

1 month ago
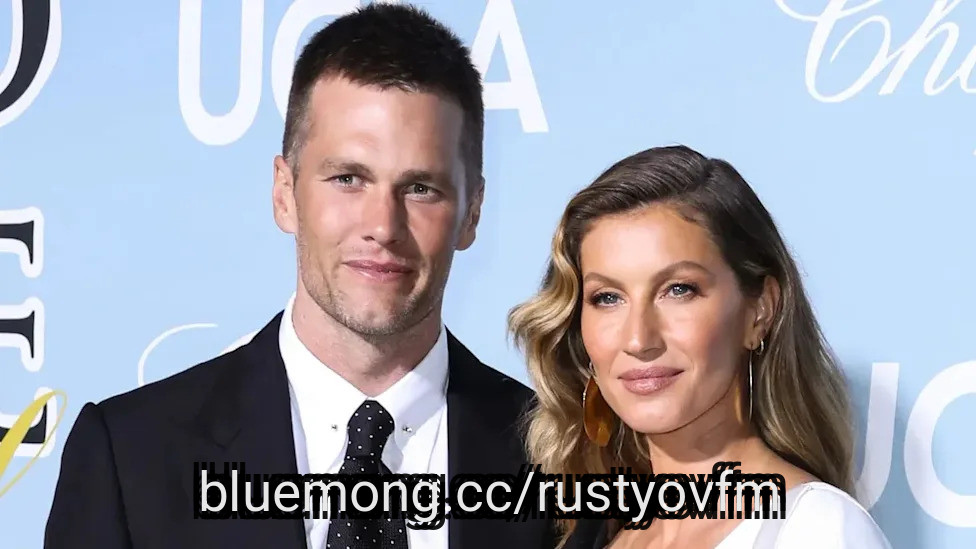
A new biography about Tom Brady includes details about the end of his marriage to Gisele Bündchen. "Brady: An American Story and the Price of Greatness" was written by sports journalist Lars Anderson and released on Sept. 29, 2026.
The book draws on more than 350 interviews with people who knew Brady on and off the field. It includes accounts about the couple's marriage and their 2022 divorce. Bündchen has previously said the reasons for their split were more complicated than reports that linked it primarily to Brady's football career.
Anderson's biography examines Brady's life beyond his record-setting football career. Publisher Celadon Books says the author conducted more than 350 original interviews with people who knew Brady on and off the field. The book explores his childhood, career, family life, and retirement.
It also examines what Anderson presents as the personal cost of Brady's intense commitment to football and his pursuit of success. The marriage receives considerable attention because it overlapped with some of Brady's biggest professional achievements. Brady and Bündchen married in 2009 and remained together for 13 years before finalizing their divorce in October 2022.
They share a son, Benjamin, and a daughter, Vivian. Both described the divorce as difficult while emphasizing that their children would remain a priority as they moved forward separately.
#book
The book draws on more than 350 interviews with people who knew Brady on and off the field. It includes accounts about the couple's marriage and their 2022 divorce. Bündchen has previously said the reasons for their split were more complicated than reports that linked it primarily to Brady's football career.
Anderson's biography examines Brady's life beyond his record-setting football career. Publisher Celadon Books says the author conducted more than 350 original interviews with people who knew Brady on and off the field. The book explores his childhood, career, family life, and retirement.
It also examines what Anderson presents as the personal cost of Brady's intense commitment to football and his pursuit of success. The marriage receives considerable attention because it overlapped with some of Brady's biggest professional achievements. Brady and Bündchen married in 2009 and remained together for 13 years before finalizing their divorce in October 2022.
They share a son, Benjamin, and a daughter, Vivian. Both described the divorce as difficult while emphasizing that their children would remain a priority as they moved forward separately.
#book


1 month ago
An Australian woman went viral after sharing a video of an unusually pristine frozen food section at her local supermarket. The clip showcased rows of products stacked with near-perfect uniformity, with the meticulous organization extending across multiple freezers and different types of frozen goods.
Sarah Mae Ahern, or sarahmaeahern on Instagram, is an Australian musician and content creator whose posts primarily focus on her music career, along with occasional glimpses into life with her husband Alex and their child.
Ahern's breakout viral video, however, came from an unexpected trip to the supermarket. While grocery shopping with her husband, the pair encountered a frozen food section where seemingly every item had been arranged perfectly in place.
They filmed the display and shared it online, where the video amassed nearly 11 million views, more than 610,000 likes and roughly 7,500 comments over the following three months.
"We are looking at how perfectly stacked everything is in this freezer section," Alex says, while Ahern films him as she laughs, before she pans over to said freezers, which display frozen desserts, pastries and ice cream, every product in it neatly organized.
#freezers
Sarah Mae Ahern, or sarahmaeahern on Instagram, is an Australian musician and content creator whose posts primarily focus on her music career, along with occasional glimpses into life with her husband Alex and their child.
Ahern's breakout viral video, however, came from an unexpected trip to the supermarket. While grocery shopping with her husband, the pair encountered a frozen food section where seemingly every item had been arranged perfectly in place.
They filmed the display and shared it online, where the video amassed nearly 11 million views, more than 610,000 likes and roughly 7,500 comments over the following three months.
"We are looking at how perfectly stacked everything is in this freezer section," Alex says, while Ahern films him as she laughs, before she pans over to said freezers, which display frozen desserts, pastries and ice cream, every product in it neatly organized.
#freezers

2 months ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer

2 months ago
The transition toward renewable energy is creating massive opportunities for infrastructure providers. Eos Energy Enterprises (NASDAQ:EOSE) and GE Vernova (NYSE:GEV) represent two distinct ways to play this trend in 2026.
Eos focuses on specialized zinc-based batteries for long-duration energy storage. GE Vernova is a diversified giant that services a massive portion of the world's electricity grid. Comparing these two helps clarify whether you prefer a high-growth disruptor or an established power leader.
Eos Energy Enterprises produces aqueous zinc batteries designed as a safer, scalable alternative to lithium-ion. It operates primarily within the industrial stocks **** e, targeting utilities and commercial developers. Customer concentration like this adds a layer of risk to the business, as two clients accounted for approximately 70% of total revenue in 2025.
In FY 2025, revenue reached approximately $114.2 million. This represents growth of nearly 631.8% compared to the prior fiscal year. The company reported a pre-tax net loss of roughly $969.6 million, resulting in a negative net margin of approximately 849.1%.
As of its December 2025 balance sheet, the company had a debt-to-equity ratio of -1.0x. This value indicates that total liabilities exceed shareholder equity. The current ratio, which measures the ability to cover short term obligations with short term **** ets, was approximately 4.9x, while free cash flow was nearly negative $265.0 million.
#enterprises #massive #Growth
Eos focuses on specialized zinc-based batteries for long-duration energy storage. GE Vernova is a diversified giant that services a massive portion of the world's electricity grid. Comparing these two helps clarify whether you prefer a high-growth disruptor or an established power leader.
Eos Energy Enterprises produces aqueous zinc batteries designed as a safer, scalable alternative to lithium-ion. It operates primarily within the industrial stocks **** e, targeting utilities and commercial developers. Customer concentration like this adds a layer of risk to the business, as two clients accounted for approximately 70% of total revenue in 2025.
In FY 2025, revenue reached approximately $114.2 million. This represents growth of nearly 631.8% compared to the prior fiscal year. The company reported a pre-tax net loss of roughly $969.6 million, resulting in a negative net margin of approximately 849.1%.
As of its December 2025 balance sheet, the company had a debt-to-equity ratio of -1.0x. This value indicates that total liabilities exceed shareholder equity. The current ratio, which measures the ability to cover short term obligations with short term **** ets, was approximately 4.9x, while free cash flow was nearly negative $265.0 million.
#enterprises #massive #Growth

2 months ago
Shell plc (NYSE:SHEL) is a global group of energy and petrochemical companies with a presence in over 70 countries. The stock has delivered gains of over 23% since the beginning of 2026 and even hit its all-time high earlier in March, driven primarily by soaring oil prices and solid earnings amid supply disruptions in the Middle East.
Following a slight pullback over the last few months, Shell has started to regain momentum, and Morgan Stanley expects the rally to continue. On September 3, the investment bank upgraded SHEL from 'Equal Weight' to 'Overweight', while also raising its price target from $81.60 to $101.30. The target boost implies an upside of 9% from the current levels and even exceeds Shell's previous record high of almost $95 per share achieved earlier this year.
Morgan Stanley noted that the concerns surrounding Shell's long-term resource longevity have now eased, with the company now positioned to sustain production growth through 2030 and stabilize output thereafter. The ******* yst firm believes that while the stock has been weighed down due to its dividend policy, there is now "potential for a significant acceleration. As a result, Morgan Stanley promoted SHEL to top-pick status.
Shell completed the acquisition of ARC Resources earlier this month, addressing the resource-depletion concerns that have weighed down its valuation. The $16.4 billion deal has significantly expanded the energy giant's gas reserves and will boost its production by 370,000 boed. Additionally, the strategic move expands Shell's exposure to the North American gas market and bolsters its position in a region that is emerging as a key player in the global LNG supply.
Shell's recent upstream investments provide further support to Morgan Stanley's bullish thesis. The company announced earlier this month that it had agreed to acquire a 30% interest in BP's Conifer exploration prospect in the US Gulf, and a 50% stake in the Tupinamba exploration block in Brazil's Santos Basin. Additionally, it also recently signed a preliminary agreement for the acquisition of production rights over Ghana's South Deepwater Tano Cape Three Points oil and gas block.
#shel #production #energy #Stock
Following a slight pullback over the last few months, Shell has started to regain momentum, and Morgan Stanley expects the rally to continue. On September 3, the investment bank upgraded SHEL from 'Equal Weight' to 'Overweight', while also raising its price target from $81.60 to $101.30. The target boost implies an upside of 9% from the current levels and even exceeds Shell's previous record high of almost $95 per share achieved earlier this year.
Morgan Stanley noted that the concerns surrounding Shell's long-term resource longevity have now eased, with the company now positioned to sustain production growth through 2030 and stabilize output thereafter. The ******* yst firm believes that while the stock has been weighed down due to its dividend policy, there is now "potential for a significant acceleration. As a result, Morgan Stanley promoted SHEL to top-pick status.
Shell completed the acquisition of ARC Resources earlier this month, addressing the resource-depletion concerns that have weighed down its valuation. The $16.4 billion deal has significantly expanded the energy giant's gas reserves and will boost its production by 370,000 boed. Additionally, the strategic move expands Shell's exposure to the North American gas market and bolsters its position in a region that is emerging as a key player in the global LNG supply.
Shell's recent upstream investments provide further support to Morgan Stanley's bullish thesis. The company announced earlier this month that it had agreed to acquire a 30% interest in BP's Conifer exploration prospect in the US Gulf, and a 50% stake in the Tupinamba exploration block in Brazil's Santos Basin. Additionally, it also recently signed a preliminary agreement for the acquisition of production rights over Ghana's South Deepwater Tano Cape Three Points oil and gas block.
#shel #production #energy #Stock

2 months ago
Applied Materials (NASDAQ:AMAT) primarily generates its revenue by designing, developing, manufacturing, and selling the critical fabrication equipment, specialized factory automation software, and materials engineering solutions utilized to produce integrated circuits for customers globally.
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily

2 months ago
Interested in Apollo Global Management Inc.? Here are five stocks we like better.
Apollo expects interest rates to remain higher for longer, while estimating only a 10%–20% chance of a recession over the next year. Consumer spending, inflation and AI infrastructure investment are supporting economic activity, though geopolitical and energy risks remain.
The firm views AI primarily as a large-scale financing opportunity, providing structured capital to investment-grade companies involved in digital infrastructure, energy, logistics and defense rather than betting on individual technology winners.
Apollo reported strong institutional fundraising, including a $12 billion first close for its Fund XI, and expects private-equity industry consolidation as smaller or overexpanded managers struggle to return capital. Its high-grade capital-solutions business has completed more than 200 transactions totaling roughly $150 billion.
Baggage Claim: Apollo's $7.7 Billion Bid to Acquire easyJet
#apollo #infrastructure #energy #grade
Apollo expects interest rates to remain higher for longer, while estimating only a 10%–20% chance of a recession over the next year. Consumer spending, inflation and AI infrastructure investment are supporting economic activity, though geopolitical and energy risks remain.
The firm views AI primarily as a large-scale financing opportunity, providing structured capital to investment-grade companies involved in digital infrastructure, energy, logistics and defense rather than betting on individual technology winners.
Apollo reported strong institutional fundraising, including a $12 billion first close for its Fund XI, and expects private-equity industry consolidation as smaller or overexpanded managers struggle to return capital. Its high-grade capital-solutions business has completed more than 200 transactions totaling roughly $150 billion.
Baggage Claim: Apollo's $7.7 Billion Bid to Acquire easyJet
#apollo #infrastructure #energy #grade

2 months ago
AGNC Investment (NASDAQ: AGNC) completed its IPO in May 2008 at $20 per share. Today, shares of the mortgage REIT trade at around $10 per share, a staggering 50% below their IPO price.
However, the company's monthly dividends have more than offset the slump in its share price. AGNC has paid out over $50 per share in ****** ulative dividends since its IPO, more than double its IPO price. With dividends reinvested, it has significantly outperformed mortgage REITs and other financial stocks since its IPO.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
AGNC Investment's founders formed it in the depths of the financial crisis, seeing an opportunity to create a leading Agency MBS (mortgage-backed securities guaranteed against credit losses by government agencies like Fannie Mae). It invests in Agency MBS on a leveraged basis, primarily through repurchase agreements, and uses dynamic risk management strategies to navigate market risks, including interest rate changes.
The company has had to maneuver around several market cycles, unexpected events, and market volatility over the years, which have weighed on its investment returns and earnings. AGNC Investment has still managed to significantly expand its Agency MBS portfolio (it reached $97.2 billion at the end of the second quarter), financed primarily by selling stock. As a result, its shares outstanding have risen a staggering 7,660% since its IPO. This combination of earnings volatility and dilution is why its share prices have fallen 50% since the IPO.
#since #agency #dividends
However, the company's monthly dividends have more than offset the slump in its share price. AGNC has paid out over $50 per share in ****** ulative dividends since its IPO, more than double its IPO price. With dividends reinvested, it has significantly outperformed mortgage REITs and other financial stocks since its IPO.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
AGNC Investment's founders formed it in the depths of the financial crisis, seeing an opportunity to create a leading Agency MBS (mortgage-backed securities guaranteed against credit losses by government agencies like Fannie Mae). It invests in Agency MBS on a leveraged basis, primarily through repurchase agreements, and uses dynamic risk management strategies to navigate market risks, including interest rate changes.
The company has had to maneuver around several market cycles, unexpected events, and market volatility over the years, which have weighed on its investment returns and earnings. AGNC Investment has still managed to significantly expand its Agency MBS portfolio (it reached $97.2 billion at the end of the second quarter), financed primarily by selling stock. As a result, its shares outstanding have risen a staggering 7,660% since its IPO. This combination of earnings volatility and dilution is why its share prices have fallen 50% since the IPO.
#since #agency #dividends


2 months ago
Interested in Equinix, Inc.? Here are five stocks we like better.
Equinix plans to invest $5 billion to $7 billion annually in data-center development, primarily in established markets where customer demand and infrastructure needs are already visible.
The company controls about 3 gigawatts of designed power, with 600–700 megawatts under development, and is targeting cash-on-cash returns in the low 20% range with typical stabilization in two to three years.
AI adoption is accelerating among enterprise customers, driving expected demand for higher-density facilities, liquid cooling and additional interconnections; however, executives said AI-related business still represents a minority of Equinix's revenue today.
3 Stocks Built for Higher Rates—And 2 That Could Break
#higher #demand #here #built
Equinix plans to invest $5 billion to $7 billion annually in data-center development, primarily in established markets where customer demand and infrastructure needs are already visible.
The company controls about 3 gigawatts of designed power, with 600–700 megawatts under development, and is targeting cash-on-cash returns in the low 20% range with typical stabilization in two to three years.
AI adoption is accelerating among enterprise customers, driving expected demand for higher-density facilities, liquid cooling and additional interconnections; however, executives said AI-related business still represents a minority of Equinix's revenue today.
3 Stocks Built for Higher Rates—And 2 That Could Break
#higher #demand #here #built

2 months ago
CoinShares PLC (NASDAQ:CSHR) reported approximately $27.6 million in net inflows for the first half of 2026, yet U.S. GAAP revenue fell 35.7% to $51.4 million from $80 million. The September 14 results show that attracting **** ets and restoring earnings are different challenges.
Asset Management revenue declined to $40 million from $59.6 million. CoinShares PLC (NASDAQ:CSHR) attributed that decline primarily to lower average **** ets under management (AUM) following weaker digital-asset prices. Product mix and a targeted fee reduction add another hurdle: the revenue generated by each dollar of **** ets.
Positive flows during a difficult market provide evidence of demand. The physically backed product platform generated approximately $155.9 million in net inflows during the half. That suggests CoinShares PLC (NASDAQ:CSHR) can attract capital even when market performance reduces the value of existing holdings.
CoinShares PLC (NASDAQ:CSHR) reported that AUM recovered to approximately $6.93 billion by August 31 from $5.52 billion at June 30. Whether that recovery restores fee revenue depends on average **** ets and product mix.
A broader product mix also has strategic value. Lower-fee products may reach customers who would otherwise invest elsewhere. For CoinShares PLC (NASDAQ:CSHR), accepting a lower fee can make economic sense if it secures durable **** ets at an attractive cost.
#revenue
Asset Management revenue declined to $40 million from $59.6 million. CoinShares PLC (NASDAQ:CSHR) attributed that decline primarily to lower average **** ets under management (AUM) following weaker digital-asset prices. Product mix and a targeted fee reduction add another hurdle: the revenue generated by each dollar of **** ets.
Positive flows during a difficult market provide evidence of demand. The physically backed product platform generated approximately $155.9 million in net inflows during the half. That suggests CoinShares PLC (NASDAQ:CSHR) can attract capital even when market performance reduces the value of existing holdings.
CoinShares PLC (NASDAQ:CSHR) reported that AUM recovered to approximately $6.93 billion by August 31 from $5.52 billion at June 30. Whether that recovery restores fee revenue depends on average **** ets and product mix.
A broader product mix also has strategic value. Lower-fee products may reach customers who would otherwise invest elsewhere. For CoinShares PLC (NASDAQ:CSHR), accepting a lower fee can make economic sense if it secures durable **** ets at an attractive cost.
#revenue

2 months ago
Crane Company (NYSE:CR) announced a definitive agreement on September 14 to acquire Trillium Flow Technologies' U.S. pump business for approximately $240 million. The operations primarily serve municipal water and wastewater customers and are expected to generate approximately $115 million in full-year revenue. Closing is expected in the fourth quarter, subject to regulatory approvals and customary conditions.
The acquisition would add Floway, Wemco, Roto-Jet and WSP to Process Flow Technologies. Their installed equipment base supports service, repair, retrofit and replacement demand, giving the transaction a recurring-revenue rationale.
Crane Company (NYSE:CR) disclosed a price of approximately 14.6 times estimated 2026 adjusted EBITDA. Adjusted EBITDA is a company-defined non-GAAP measure based on earnings before interest, taxes, depreciation, and amortization, with further adjustments. The announcement did not specify the target's adjustments or provide a GAAP reconciliation.
Water and wastewater systems require reliable pumping equipment throughout their operating lives. An established installed base creates opportunities to sell replacement parts, restore equipment, and upgrade performance long after the original sale.
For Crane Company (NYSE:CR), those customer relationships could make revenue less dependent on winning entirely new projects. Service capability and product familiarity may also help retain customers when equipment eventually needs replacement.
#NYSE
The acquisition would add Floway, Wemco, Roto-Jet and WSP to Process Flow Technologies. Their installed equipment base supports service, repair, retrofit and replacement demand, giving the transaction a recurring-revenue rationale.
Crane Company (NYSE:CR) disclosed a price of approximately 14.6 times estimated 2026 adjusted EBITDA. Adjusted EBITDA is a company-defined non-GAAP measure based on earnings before interest, taxes, depreciation, and amortization, with further adjustments. The announcement did not specify the target's adjustments or provide a GAAP reconciliation.
Water and wastewater systems require reliable pumping equipment throughout their operating lives. An established installed base creates opportunities to sell replacement parts, restore equipment, and upgrade performance long after the original sale.
For Crane Company (NYSE:CR), those customer relationships could make revenue less dependent on winning entirely new projects. Service capability and product familiarity may also help retain customers when equipment eventually needs replacement.
#NYSE


2 months ago
Comments from Anthropic CEO Dario Amodei and OpenAI CEO Sam Altman calling for a more measured approach to frontier AI development contributed to a sharp selloff across neoclouds and data center stocks. Bernstein identified CoreWeave Inc. (NASDAQ:CRWV) as the most exposed name because of its rural footprint and focus on AI training. The concern represents a genuine structural argument. However, it marks the second time this year that the same group of stocks has faced concerns over the sustainability of AI demand. There is also an important tension within Bernstein's own note, which highlights CoreWeave's exposure while acknowledging that most of its backlog remains shielded by contracts.
Bernstein cautioned that a slowdown in AI training could weigh on data center developers. The warning followed Amodei's weekend comments urging the industry to deliberately slow the pace of frontier AI capability gains, along with similar remarks from Sam Altman. According to ****** yst Madison Rezaei, slower training activity would likely reduce demand for rural data center sites designed for latency-insensitive workloads. The ****** yst pointed out that rural and Tier 3 markets account for 70% of the industry's 488GW pipeline. CoreWeave was identified as the most exposed name in the firm's coverage. ****** yst Madison Rezaei remarked:
We estimate that 25% of their existing active U.S. power, with an additional ~74% of their contracted power, is situated in Tier 3 and Tier 4 markets.
However, there is a key counterpoint within Bernstein's own note:
The backlog is primarily comprised of take-or-pay contracts, so we do not anticipate a threat there but could see a pullback in demand for the contracted-not-yet-sold rural power if training development slows.
#training #analyst
Bernstein cautioned that a slowdown in AI training could weigh on data center developers. The warning followed Amodei's weekend comments urging the industry to deliberately slow the pace of frontier AI capability gains, along with similar remarks from Sam Altman. According to ****** yst Madison Rezaei, slower training activity would likely reduce demand for rural data center sites designed for latency-insensitive workloads. The ****** yst pointed out that rural and Tier 3 markets account for 70% of the industry's 488GW pipeline. CoreWeave was identified as the most exposed name in the firm's coverage. ****** yst Madison Rezaei remarked:
We estimate that 25% of their existing active U.S. power, with an additional ~74% of their contracted power, is situated in Tier 3 and Tier 4 markets.
However, there is a key counterpoint within Bernstein's own note:
The backlog is primarily comprised of take-or-pay contracts, so we do not anticipate a threat there but could see a pullback in demand for the contracted-not-yet-sold rural power if training development slows.
#training #analyst
2 months ago
Cognyte Software Ltd. (NASDAQ:CGNT) reported on September 9 that revenue for the fiscal second quarter ended July 31, 2026, increased 12.0% to $109.2 million. Total software revenue, comprising software and software services, rose 20.9% to $100.8 million.
Company-defined non-GAAP adjusted EBITDA increased 35.7% to $14.9 million. The measure adds depreciation, amortization, stock-based compensation, restructuring costs, and other specified adjustments to GAAP operating income. Yet quarterly billings fell to $76.3 million from $93.0 million. The central question is whether a more profitable revenue mix can produce stronger cash generation while sustaining future growth.
The portfolio transition is visible in the revenue base. Total software revenue represented more than 92% of sales. Recurring revenue, primarily support contracts and subscription offerings, reached $56.2 million, or 51.4% of total revenue.
For Cognyte Software Ltd. (NASDAQ:CGNT), a larger recurring base could make revenue more predictable and support continued product investment. Renewals also create opportunities to expand customer relationships without rebuilding the sales pipeline from scratch. The benefit depends on retention and expansion within those accounts.
Profitability improved under both accounting measures. GAAP operating margin increased to 4.3% from 2.8%, while adjusted EBITDA margin expanded to 13.6% from 11.3%. That combination strengthens the case that the transition is improving operating economics, even after recognizing expenses excluded from adjusted results.
#gaap #NASDAQ
Company-defined non-GAAP adjusted EBITDA increased 35.7% to $14.9 million. The measure adds depreciation, amortization, stock-based compensation, restructuring costs, and other specified adjustments to GAAP operating income. Yet quarterly billings fell to $76.3 million from $93.0 million. The central question is whether a more profitable revenue mix can produce stronger cash generation while sustaining future growth.
The portfolio transition is visible in the revenue base. Total software revenue represented more than 92% of sales. Recurring revenue, primarily support contracts and subscription offerings, reached $56.2 million, or 51.4% of total revenue.
For Cognyte Software Ltd. (NASDAQ:CGNT), a larger recurring base could make revenue more predictable and support continued product investment. Renewals also create opportunities to expand customer relationships without rebuilding the sales pipeline from scratch. The benefit depends on retention and expansion within those accounts.
Profitability improved under both accounting measures. GAAP operating margin increased to 4.3% from 2.8%, while adjusted EBITDA margin expanded to 13.6% from 11.3%. That combination strengthens the case that the transition is improving operating economics, even after recognizing expenses excluded from adjusted results.
#gaap #NASDAQ


2 months ago
Oddity Tech Ltd. (NASDAQ:ODD) reported second-quarter revenue of approximately $181 million on September 9, down 25% from $241 million a year earlier. Company-defined non-GAAP adjusted EBITDA fell to $13 million from $70 million. This measure excludes net financial income, income taxes, depreciation and amortization, share-based compensation, and certain unusual or nonrecurring items from net income.
Management attributed the disruption primarily to an advertising-algorithm problem affecting IL MAKIAGE. Oddity Tech Ltd. (NASDAQ:ODD) expects third-quarter revenue to decline approximately 5% year over year, with adjusted EBITDA of $18 million to $20 million. The sequential improvement describes a narrowing year-over-year revenue decline.
Management's diagnosis centers on distorted advertising signals that impair IL MAKIAGE's ability to reach suitable customers at acceptable acquisition costs. Oddity Tech Ltd. (NASDAQ:ODD) is testing changes with its largest advertising partner to retrain the algorithm. If those changes restore profitable customer acquisition, the existing brand could recover without a fundamental overhaul of its products.
Other brands provide operating evidence beyond that hypothesis. SpoiledChild delivered double-digit quarterly revenue growth, and management expects at least 35% growth for 2026, approaching $350 million in revenue. Management expects METHODIQ's first-year revenue to exceed SpoiledChild's first-year result.
These results support the argument that Oddity Tech Ltd. (NASDAQ:ODD) can build additional brands using its technology platform. A broader sales base could gradually reduce dependence on IL MAKIAGE, while successful customer retention would help recover upfront advertising spending over multiple purchases.
#revenue #NASDAQ #advertising #expects
Management attributed the disruption primarily to an advertising-algorithm problem affecting IL MAKIAGE. Oddity Tech Ltd. (NASDAQ:ODD) expects third-quarter revenue to decline approximately 5% year over year, with adjusted EBITDA of $18 million to $20 million. The sequential improvement describes a narrowing year-over-year revenue decline.
Management's diagnosis centers on distorted advertising signals that impair IL MAKIAGE's ability to reach suitable customers at acceptable acquisition costs. Oddity Tech Ltd. (NASDAQ:ODD) is testing changes with its largest advertising partner to retrain the algorithm. If those changes restore profitable customer acquisition, the existing brand could recover without a fundamental overhaul of its products.
Other brands provide operating evidence beyond that hypothesis. SpoiledChild delivered double-digit quarterly revenue growth, and management expects at least 35% growth for 2026, approaching $350 million in revenue. Management expects METHODIQ's first-year revenue to exceed SpoiledChild's first-year result.
These results support the argument that Oddity Tech Ltd. (NASDAQ:ODD) can build additional brands using its technology platform. A broader sales base could gradually reduce dependence on IL MAKIAGE, while successful customer retention would help recover upfront advertising spending over multiple purchases.
#revenue #NASDAQ #advertising #expects


2 months ago
Avantor (AVTR) exhibits strong technical momentum, recently setting a new year-to-date high.
Shares are up more than 22% over the past year.
AVTR maintains a 100% "Buy" technical opinion from Barchart.
Most ******* ysts see AVTR as undervalued, but I recommend a tight stop loss given its volatility and only moderate fundamental outlook.
Valued at $10.44 billion, Avantor (AVTR) is a provider of critical products and services primarily to the biopharma, healthcare, education, government, advanced technologies, and applied materials industries.
#avantor #year #exhibits
Shares are up more than 22% over the past year.
AVTR maintains a 100% "Buy" technical opinion from Barchart.
Most ******* ysts see AVTR as undervalued, but I recommend a tight stop loss given its volatility and only moderate fundamental outlook.
Valued at $10.44 billion, Avantor (AVTR) is a provider of critical products and services primarily to the biopharma, healthcare, education, government, advanced technologies, and applied materials industries.
#avantor #year #exhibits



2 months ago
Wasatch Global Investors, an **** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Real REMAX Group Inc. (NASDAQ:REAX). Real REMAX Group Inc. (NASDAQ:REAX) is a real estate technology company that provides **** le, mortgage, wallet, and franchising and ancillary services. The Real Brokerage, Inc. changed its name to Real REMAX Group Inc. (NASDAQ:REAX) in August 2026. On September 15, 2026, Real REMAX Group Inc. (NASDAQ:REAX) closed at $19.27 per share. Over the past month, Real REMAX Group Inc. (NASDAQ:REAX) declined 30.93%, but its shares are down 61.84% over the past year. Real REMAX Group Inc. (NASDAQ:REAX) has a market capitalization of $422.42 million, and its stock has traded within a 52-week range of $15.50 to $52.50.
Wasatch Long/Short Alpha Fund stated the following regarding Real REMAX Group Inc. (NASDAQ:REAX) in its Q2 2026 investor letter:
"Among shorts, contributors to Fund performance were those stocks that declined in price. One of our largest contributors was REMAX Group Inc. (NASDAQ:REAX). The company operates a cloud-based real estate platform operating across the U.S. and Canada. Real Brokerage's stock was down due to concerns about how AI may disrupt its business model."
Real REMAX Group Inc. (NASDAQ:REAX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 25 hedge fund portfolios held Real REMAX Group Inc. (NASDAQ:REAX) at the end of the second quarter, compared to 21 in the previous quarter. While we acknowledge the potential of Real REMAX Group Inc. (NASDAQ:REAX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#real #remax #NASDAQ #long
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Real REMAX Group Inc. (NASDAQ:REAX). Real REMAX Group Inc. (NASDAQ:REAX) is a real estate technology company that provides **** le, mortgage, wallet, and franchising and ancillary services. The Real Brokerage, Inc. changed its name to Real REMAX Group Inc. (NASDAQ:REAX) in August 2026. On September 15, 2026, Real REMAX Group Inc. (NASDAQ:REAX) closed at $19.27 per share. Over the past month, Real REMAX Group Inc. (NASDAQ:REAX) declined 30.93%, but its shares are down 61.84% over the past year. Real REMAX Group Inc. (NASDAQ:REAX) has a market capitalization of $422.42 million, and its stock has traded within a 52-week range of $15.50 to $52.50.
Wasatch Long/Short Alpha Fund stated the following regarding Real REMAX Group Inc. (NASDAQ:REAX) in its Q2 2026 investor letter:
"Among shorts, contributors to Fund performance were those stocks that declined in price. One of our largest contributors was REMAX Group Inc. (NASDAQ:REAX). The company operates a cloud-based real estate platform operating across the U.S. and Canada. Real Brokerage's stock was down due to concerns about how AI may disrupt its business model."
Real REMAX Group Inc. (NASDAQ:REAX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 25 hedge fund portfolios held Real REMAX Group Inc. (NASDAQ:REAX) at the end of the second quarter, compared to 21 in the previous quarter. While we acknowledge the potential of Real REMAX Group Inc. (NASDAQ:REAX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#real #remax #NASDAQ #long

2 months ago
Wasatch Global Investors, an ****** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Bloom Energy Corporation (NYSE:BE). Bloom Energy Corporation (NYSE:BE), designs and manufactures solid-oxide fuel cell systems for clean, reliable, on-site power generation. On September 15, 2026, Bloom Energy Corporation closed at $259.35 per share. Over the past month, Bloom Energy Corporation returned 25.51%, and its shares are up 225.53% over the past year. Bloom Energy Corporation has a market capitalization of $76.39 billion, and its stock has traded within a 52-week range of $61.37 to $351.28.
Wasatch Long/Short Alpha Fund stated the following regarding Bloom Energy Corporation (NYSE:BE) in its Q2 2026 investor letter:
"Turning to short positions, detractors from Fund performance were those stocks that rose in price. One of the largest detractors was Bloom Energy Corporation (NYSE:BE). Bloom Energy sells natural, gas-powered fuel cells that help data centers generate power on-site before the centers can connect to the electrical grid. Bloom's stock price has increased significantly in recent months, and we believe it is representative of some of the AI-related exuberance in the small cap market."
Bloom Energy Corporation (NYSE:BE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 116 hedge fund portfolios held Bloom Energy Corporation (NYSE:BE) at the end of the second quarter, up from 91 in the previous quarter. While we acknowledge the potential of Bloom Energy Corporation (NYSE:BE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Bloom Energy Corporation (NYSE:BE). Bloom Energy Corporation (NYSE:BE), designs and manufactures solid-oxide fuel cell systems for clean, reliable, on-site power generation. On September 15, 2026, Bloom Energy Corporation closed at $259.35 per share. Over the past month, Bloom Energy Corporation returned 25.51%, and its shares are up 225.53% over the past year. Bloom Energy Corporation has a market capitalization of $76.39 billion, and its stock has traded within a 52-week range of $61.37 to $351.28.
Wasatch Long/Short Alpha Fund stated the following regarding Bloom Energy Corporation (NYSE:BE) in its Q2 2026 investor letter:
"Turning to short positions, detractors from Fund performance were those stocks that rose in price. One of the largest detractors was Bloom Energy Corporation (NYSE:BE). Bloom Energy sells natural, gas-powered fuel cells that help data centers generate power on-site before the centers can connect to the electrical grid. Bloom's stock price has increased significantly in recent months, and we believe it is representative of some of the AI-related exuberance in the small cap market."
Bloom Energy Corporation (NYSE:BE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 116 hedge fund portfolios held Bloom Energy Corporation (NYSE:BE) at the end of the second quarter, up from 91 in the previous quarter. While we acknowledge the potential of Bloom Energy Corporation (NYSE:BE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund

2 months ago
Hewlett Packard Enterprise Company (HPE) is becoming a major beneficiary of the enterprise artificial intelligence (AI) infrastructure growth. While many companies are working on AI applications, Hewlett Packard primarily focuses on infrastructure, supplying servers, networking, and other technology essential for large-scale AI deployment.
The company's latest quarterly results showed rising demand, with both revenue and profit exceeding **** yst expectations and robust growth across all segments. Its integration of Juniper Networks has further strengthened the company's position in AI networking, giving the company greater access to the infrastructure needs driven by AI's rapid growth.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#infrastructure #company #juniper
The company's latest quarterly results showed rising demand, with both revenue and profit exceeding **** yst expectations and robust growth across all segments. Its integration of Juniper Networks has further strengthened the company's position in AI networking, giving the company greater access to the infrastructure needs driven by AI's rapid growth.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#infrastructure #company #juniper



2 months ago
When a caller inquired about SoFi Technologies, Inc. (NASDAQ:SOFI) during the September 10 episode of Mad Money, Jim Cramer commented:
Well, you know, it's a financial tech. It's a bank, but let's put it this way: It's doing as well as it can, but it has a very high price-to-earnings multiple versus the others in its cohort. So, it's going to mark time until the earnings continue to go up. I do like the company. I like the management. I wouldn't mind you owning it for the long term.
SoFi Technologies, Inc. (NASDAQ:SOFI) reported record second-quarter adjusted net revenue of $1.2 billion, up 40% year over year, while GAAP net income rose 61% to $156.6 million. Adjusted EBITDA increased 44% to $358 million. Loan originations reached a record $14.8 billion, while members increased 35% to 15.8 million and deposits reached $45.5 billion. Moreover, at the September 8 Goldman Sachs conference, CFO Chris Lapointe said SoFi generated approximately 40% year-over-year revenue growth in each of the first two quarters and approximately 30% adjusted EBITDA margins. He also said the company had outpaced the Rule of 40 for 20 consecutive quarters. Additionally, the company raised its 2026 adjusted net revenue outlook to $4.75 billion to $4.85 billion but maintained its adjusted EPS outlook at $0.60.
A concern is that SoFi Technologies, Inc.'s (NASDAQ:SOFI) earnings growth may not be sufficient to justify the multiple investors are paying. SoFi is trading at a premium valuation compared to its traditional banking peers, with Yahoo Finance's latest data showing a trailing P/E of 35.12 and a forward P/E of 21.51. That valuation leaves the shares sensitive to a slowdown in earnings growth. Credit performance is another important consideration as SoFi expands its lending business. For the six months ended June 30, total net charge-offs were $406.1 million, up $77.2 million from the prior-year period, while the total net charge-off ratio declined to 1.91% from 2.24%. The increase in charge-offs was driven primarily by higher personal-loan net charge-offs and student-loan net charge-offs, reflecting growth in average loans.
According to Insider Monkey, which tracks more than 1,000 hedge funds, 44 hedge funds held SoFi in Q2, down from 47 in Q1. Its short interest stood at about 14% to 15% of the float. SoFi Technologies, Inc.'s (NASDAQ:SOFI) growth and improving profitability give Cramer's long-term view a fundamental basis, but its valuation still leaves the stock dependent on continued earnings growth. The company's ability to turn strong revenue and loan growth into higher earnings will remain important to the stock's valuation.
#earnings #adjusted #million #charge
Well, you know, it's a financial tech. It's a bank, but let's put it this way: It's doing as well as it can, but it has a very high price-to-earnings multiple versus the others in its cohort. So, it's going to mark time until the earnings continue to go up. I do like the company. I like the management. I wouldn't mind you owning it for the long term.
SoFi Technologies, Inc. (NASDAQ:SOFI) reported record second-quarter adjusted net revenue of $1.2 billion, up 40% year over year, while GAAP net income rose 61% to $156.6 million. Adjusted EBITDA increased 44% to $358 million. Loan originations reached a record $14.8 billion, while members increased 35% to 15.8 million and deposits reached $45.5 billion. Moreover, at the September 8 Goldman Sachs conference, CFO Chris Lapointe said SoFi generated approximately 40% year-over-year revenue growth in each of the first two quarters and approximately 30% adjusted EBITDA margins. He also said the company had outpaced the Rule of 40 for 20 consecutive quarters. Additionally, the company raised its 2026 adjusted net revenue outlook to $4.75 billion to $4.85 billion but maintained its adjusted EPS outlook at $0.60.
A concern is that SoFi Technologies, Inc.'s (NASDAQ:SOFI) earnings growth may not be sufficient to justify the multiple investors are paying. SoFi is trading at a premium valuation compared to its traditional banking peers, with Yahoo Finance's latest data showing a trailing P/E of 35.12 and a forward P/E of 21.51. That valuation leaves the shares sensitive to a slowdown in earnings growth. Credit performance is another important consideration as SoFi expands its lending business. For the six months ended June 30, total net charge-offs were $406.1 million, up $77.2 million from the prior-year period, while the total net charge-off ratio declined to 1.91% from 2.24%. The increase in charge-offs was driven primarily by higher personal-loan net charge-offs and student-loan net charge-offs, reflecting growth in average loans.
According to Insider Monkey, which tracks more than 1,000 hedge funds, 44 hedge funds held SoFi in Q2, down from 47 in Q1. Its short interest stood at about 14% to 15% of the float. SoFi Technologies, Inc.'s (NASDAQ:SOFI) growth and improving profitability give Cramer's long-term view a fundamental basis, but its valuation still leaves the stock dependent on continued earnings growth. The company's ability to turn strong revenue and loan growth into higher earnings will remain important to the stock's valuation.
#earnings #adjusted #million #charge

2 months ago
Steel and materials markets fluctuated between rallies and pullbacks as the US-Canada trade relationship shifted from near agreement to open dispute. Nucor Corporation (NYSE:NUE) and Cleveland-Cliffs Inc. (NYSE:CLF) rose on August 25, after discussions between the two countries broke down, a turnaround from the week before, when several of the same stocks fell on hopes that a new deal would decrease steel and aluminum tariffs. The VanEck Steel ETF gained 1.6% on the day, while the State Street Materials Select Sector SPDR reached an intraday high. The rise didn't last: by the end of the week, the materials ETF had slipped to negative territory, while the steel ETF was about flat, though, both remain substantially up for 2026.
The volatility traces a rapid escalation. On August 19, Bloomberg reported that the US and Canada had tentatively agreed to reduce tariffs on Canadian steel and aluminum to 25% and vehicle charges to 15%. That optimism was dashed within days: on August 22, the US imposed 50% tariffs on a wide variety of Canadian exports, and Canadian Prime Minister Mark Carney responded by declaring Canada officially "at war" with the United States, saying "You're at war when you're attacked, and we got attacked."
On August 25, Ottawa announced counter-tariffs of C$27.6 billion on American goods, which took effect on September 8 at rates ranging from 15% to 50%. The dispute has continued to escalate since then, with Washington announcing additional restrictions and tariffs on Canadian goods in September, reinforcing the view that a quick resolution remains unlikely.
Atsi Sheth, Moody's chief credit officer, put it bluntly: "Expect much more of this uncertainty for some time to come." Investors initially welcomed tariffs as good news for US steelmakers facing less Canadian competition, but the back-and-forth negotiations, as well as Canada's reaction, have made predicting a steady outcome difficult.
The more intriguing story is how differently the aforementioned companies are positioned. Nucor Corporation (NYSE:NUE) relies primarily on scrap-based electric arc furnace steelmaking, while Cleveland-Cliffs Inc. (NYSE:CLF) operates a vertically integrated model with internally sourced iron ore, scrap and other raw materials. Both have meaningful domestic raw-material exposure, although their production models differ substantially. Nucor Corporation (NYSE:NUE) is up more than 50% year-to-date, while Cleveland-Cliffs Inc. (NYSE:CLF), despite similar structural insulation, remains negative for 2026, which **** ysts attribute to balance sheet stress rather than tariffs.
#august #nucor #corporation #cleveland
The volatility traces a rapid escalation. On August 19, Bloomberg reported that the US and Canada had tentatively agreed to reduce tariffs on Canadian steel and aluminum to 25% and vehicle charges to 15%. That optimism was dashed within days: on August 22, the US imposed 50% tariffs on a wide variety of Canadian exports, and Canadian Prime Minister Mark Carney responded by declaring Canada officially "at war" with the United States, saying "You're at war when you're attacked, and we got attacked."
On August 25, Ottawa announced counter-tariffs of C$27.6 billion on American goods, which took effect on September 8 at rates ranging from 15% to 50%. The dispute has continued to escalate since then, with Washington announcing additional restrictions and tariffs on Canadian goods in September, reinforcing the view that a quick resolution remains unlikely.
Atsi Sheth, Moody's chief credit officer, put it bluntly: "Expect much more of this uncertainty for some time to come." Investors initially welcomed tariffs as good news for US steelmakers facing less Canadian competition, but the back-and-forth negotiations, as well as Canada's reaction, have made predicting a steady outcome difficult.
The more intriguing story is how differently the aforementioned companies are positioned. Nucor Corporation (NYSE:NUE) relies primarily on scrap-based electric arc furnace steelmaking, while Cleveland-Cliffs Inc. (NYSE:CLF) operates a vertically integrated model with internally sourced iron ore, scrap and other raw materials. Both have meaningful domestic raw-material exposure, although their production models differ substantially. Nucor Corporation (NYSE:NUE) is up more than 50% year-to-date, while Cleveland-Cliffs Inc. (NYSE:CLF), despite similar structural insulation, remains negative for 2026, which **** ysts attribute to balance sheet stress rather than tariffs.
#august #nucor #corporation #cleveland