35 mins. ago
FYEE beat JEPI on a $100,000 investment in 2026, paying $7,023 versus $6,070, but FYEE's quarterly payout has fallen from $0.82 to $0.56 per share.
JEPI's monthly distributions better match recurring expenses for retirees, while FYEE's quarterly schedule suits investors who reinvest or can wait between payments.
FYEE's lower share price ($30 vs. JEPI's $56) means $100,000 buys nearly twice as many shares, which is why it delivers more cash despite lower per-share payouts.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
The JPMorgan Equity Premium Income ETF (NYSEARCA:JEPI) built its following on a simple promise. It holds lower-volatility U.S. stocks, adds income from S&P 500 call-option premium, and sends a check every month. JEPI holders value that rhythm, and JEPI remains the default name in covered-call income. On an identical $100,000 investment this year, though, the Fidelity Yield Enhanced Equity ETF (CBOE:FYEE) has paid more cash while writing far fewer checks.
#income #quarterly

1 hr. ago
GNL paid out more in dividends than it earned in operating cash for four straight years and has already slashed its quarterly dividend from $0.53 to $0.19; PSEC's NAV fell from $6.56 to $5.71 while distributions exceeded net investment income.
IEP carries a 30% yield but posted net losses every year from 2019 through 2025 and slashed distributions from $2 to $0.50 per quarter while units dropped 66% over five years.
BEP and CWEN both rely on billions in annual financing inflows to fund distributions, with BEP's 2025 capex hitting $6.7 billion against just $1.5 billion in operating cash flow.
Building a portfolio and living off one are two completely different skills, and almost ******* ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
One stock on this list has a forward yield of about 30%. For a retiree, a number like that looks like a solid paycheck. A high yield only means something if the payout is sustainable, and each of the five names below has spent years sending out more cash than the business brought in.
#distributions #operating #slashed

3 hours ago
Energy Transfer (NYSE: ET) is one of the largest U.S.-listed master limited partnerships (MLPs) specializing in the ownership of pipelines and other midstream energy ***** ets. Based on current prices, Energy Transfer has a forward distribution yield of 6.64%.
In other words, add up its quarterly cash distributions and divide by the current stock price, and you'll get approximately this figure. Considering this, let's run the numbers and see how many shares of this pipeline stock you'd need to own in order to earn $250 monthly.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Considering the complexities of MLPs and taxation, we will focus on a gross dividend income of $250 per month from an Energy Transfer position, for purposes of our calculation. A monthly payout of $250 comes out to $3,000 per year. Energy Transfer pays $1.36 per share in annual distributions.
Divide $3,000 by $1.36, and you get 2,205 shares, worth around $45,136 based on Energy Transfer's current stock price. From this position, you'd generate around $2,998.80 in dividend income annually, or just under $250 per month.
#transfer #mlps #considering

4 hours ago
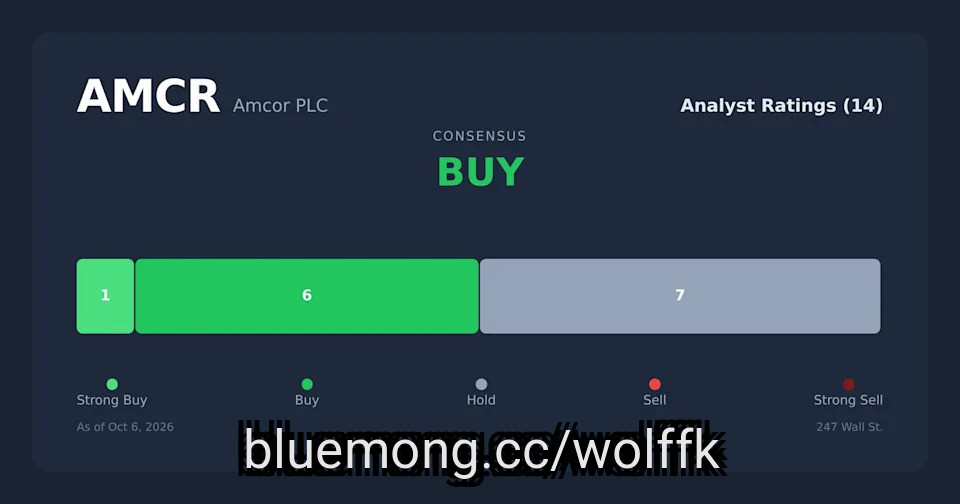
Five dividend stocks yielding 5% to 6.6% earned broad Wall Street Buy ratings, balancing income dependability with **** yst-backed conviction.
Dividend payers delivered 9% annualized returns over 50 years, more than double the 4% annualized return of non-dividend-paying stocks.
Verizon trades at 9x estimated 2026 earnings, has raised its dividend for 20 consecutive years, and targets $21.5 billion in free cash flow.
Building a portfolio and living off one are two completely different skills, and almost **** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Investors love dividend stocks because they provide dependable passive income streams and an excellent opportunity for solid total return. Total return includes interest, capital gains, dividends, and distributions realized over time. In other words, the total return on an investment or portfolio consists of income and stock appreciation. At 24/7 Wall St., we have focused on dividend stocks for 20 years because, despite the stock market's ups and downs, many people need reliable passive income streams to supplement their income from employment or other sources such as Social Security and pensions.
#stocks #total #free

7 hours ago
A $700,000 inherited IRA forces the daughter to withdraw annually for 10 years, stacking on her salary and generating $182,580 in federal taxes.
If the father had converted at 22%, his $154,000 tax bill would have been $28,580 less than his daughter pays at her higher rate.
Converting only wins when the parent's rate is lower than the heir's, making a conversation about the child's income the essential first step.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
His plan was simple: leave the IRA invested, take only the required distributions, and let the rest pass to his daughter. When he died at 82, the account still held $700,000. His daughter inherited the money, but she also inherited the tax bill, with withdrawals taxed at her rate during her peak earning years.
#rate #income

8 hours ago
Florida exempts a $600,000 IRA from Medicaid's $2,000 **** et limit once the account enters payout status through RMDs or regular distributions.
Every IRA distribution counts as income against Florida's $2,982 monthly cap, and nearly all of it goes directly to the nursing home.
A named IRA beneficiary keeps the remaining balance out of probate, blocking Florida's estate recovery claim under Fla. Stat. § 409.9101.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A Florida retiree entering long-term care with $600,000 in her IRA looks like an automatic Medicaid denial. A single applicant there can't hold more than $2,000 in countable **** ets. Thankfully, Florida's IRA Medicaid rules leave a narrow opening: once a retirement account is in payout status, the state can exclude the balance from the **** et count. This means withdrawals still count, each distribution is treated as income, and that income ends up paying most of her nursing home bill.
#Florida


17 days ago
QQQI holders forfeited roughly $11 per share in total return versus QQQ over 31 months, equal to about $2,194 on a $10,000 stake.
Nearly 99% of QQQI's 2025 distributions were return of capital, meaning investors received their own money back, not income, with a shrinking cost basis.
QQQM and JEPQ serve as alternative ways to access the same underlying index.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Every month, a NEOS Nasdaq-100 High Income ETF (NASDAQ:QQQI) holder gets a distribution check. In August 2026, it was $0.6518 per share. The annualized forward rate sits at $7.8216. The check feels like income, but the total-return record tells a different story. Since QQQI's first ex-dividend date, holders have quietly foregone roughly $10.97 per share in total return compared to a matching Nasdaq-100 position that costs a fraction to own.
#high

18 days ago
Five covered-call ETFs yield 8% to 14% monthly by writing options against large-cap U.S. equity portfolios, putting them at double to triple the 10-year Treasury rate near 5%.
Nasdaq-100 funds post higher yields than S&P 500 funds because greater implied volatility generates fatter option premiums, but they cap upside during rallies.
QQQI delivers the group's top 14% yield with roughly 99% of 2025 distributions classified as return of capital, deferring taxes rather than creating current income.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Income investors heading into the fourth quarter face a market where the 10-year Treasury yield is near 5%, yet a cluster of options-income ETFs still pays roughly double to triple that rate every month. The five funds on this list — JPMorgan Equity Premium Income ETF (NYSEARCA:JEPI), Global X S&P 500 Covered Call ETF (NYSEARCA:XYLD), Goldman Sachs Nasdaq-100 Premium Income ETF (NASDAQ:GPIQ), NEOS S&P 500 High Income ETF (NYSEARCA:SPYI), and NEOS Nasdaq-100 High Income ETF (NASDAQ:QQQI), all sit in an 8% to 14% trailing yield band while distributing cash monthly.
#NASDAQ #high #etfs #treasury
18 days ago
Generating $2,200 monthly in dividends requires between $264,000 at a 10% yield and $754,000 at a 3.5% yield, with higher yields carrying greater principal erosion risk.
A blended portfolio of SCHD (35%), DGRO (25%), VYM (20%), and JEPI (20%) hits a 3.9% weighted yield requiring about $670,000 to reach the $2,200 target.
A 3.5% yield growing 8% annually doubles income in roughly nine years, while a flat 10% yield stays stagnant or declines if distributions are cut.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Turning zero into $2,200 a month in dividend income requires only two things: a target yield and the capital to support it. The annualized goal is $26,400, which lands somewhere between covering a mortgage payment and replacing a part-time salary. The capital needed depends entirely on the yield you choose, and the yield you choose determines how durable that income actually is.
#yield #choose #dgro

18 days ago
The financial unraveling of Jon Venetos' Lurin Capital is now the subject of a Federal Bureau of Investigation probe.
An email sent to an investor from the FBI's Dallas Division shared with The Real Deal revealed that the agency has opened an investigation into Venetos, Lurin Capital and **** ociated entities. The note provided an email address through which victims can provide comments and ask questions: LurinVictimsfbi.gov.
The Real Deal also obtained a public link to an FBI form **** led "Lurin Investigation Questionnaire" seeking information from "possible victim" investors. The form asks for details about investors' contributions and any distributions received.
The company's downfall has been punctuated by claims of fraudulent dealings from lenders and former Lurin employees. Keybank accused Venetos of transferring $25,000 from his accounts with the bank to a personal account. Vista Bank accused him of falsifying account statements from the lender in an attempt to take out loans elsewhere.
In addition, a former employee who worked in property management and asked to remain anonymous claimed Lurin lied on reimbursement requests to lenders by inflating costs of repairs and submitting invoices for work that wasn't done.
#email
An email sent to an investor from the FBI's Dallas Division shared with The Real Deal revealed that the agency has opened an investigation into Venetos, Lurin Capital and **** ociated entities. The note provided an email address through which victims can provide comments and ask questions: LurinVictimsfbi.gov.
The Real Deal also obtained a public link to an FBI form **** led "Lurin Investigation Questionnaire" seeking information from "possible victim" investors. The form asks for details about investors' contributions and any distributions received.
The company's downfall has been punctuated by claims of fraudulent dealings from lenders and former Lurin employees. Keybank accused Venetos of transferring $25,000 from his accounts with the bank to a personal account. Vista Bank accused him of falsifying account statements from the lender in an attempt to take out loans elsewhere.
In addition, a former employee who worked in property management and asked to remain anonymous claimed Lurin lied on reimbursement requests to lenders by inflating costs of repairs and submitting invoices for work that wasn't done.

22 days ago
ARCC yields nearly 10% with 17 years of stable dividends, while VICI's 7% yield comes with 100% occupancy and 40-year inflation-linked leases.
Pfizer yields 6% at a forward P/E of 10, delivering five straight EPS beats while prioritizing its dividend over buybacks in 2026.
Roth IRA placement turbocharges all four picks since their distributions are taxed as ordinary income in taxable accounts.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Altria didn't make the cut. Enter your email to see the names that beat MO. The report is free. Enter your email and see if any of your stocks made the cut.
Roth IRAs let dividends compound tax-free forever, which makes them the ideal wrapper for names that spit out ordinary-income distributions taxed at your marginal rate outside the account. The four below yield well above the S&P 500 average, and each brings a different flavor of durable cash flow: a business development company, a gaming net-lease REIT, a tobacco cash machine, and a large-cap pharma. As one reference point, Ares Capital (NASDAQ:ARCC) alone reports $1.92 in annualized dividends per share, a payout policy backed by 17 years of stable or increasing regular quarterly dividends.
#dividends #arcc #four

24 days ago
What's been exciting about Robinhood Chain (RHC) is seeing tokens attempt new mechanisms to answer questions like: why would someone hold this token? How can we make participating in this token attractive? And, more broadly, how can market activity around a token overall be designed to contribute to its success?
All new projects should ask this and the best ones do, but when you have a new chain, with a new market and new infrastructure, it can be sort of a "clean slate" or fresh design ***** e and breathe new life into the solutions to such questions.
The dominant answer right now seems to be distributions: hold this token and get stock, tokens, etc. Below are projects which execute this with a twist, expanding either the type of rewards or the source for rewards that end up in the hands of holders.
Others attempt to answer the second question, experimenting with new infrastructure that tries to make market activity, of whatever kind, directly contribute to the token's success.
These are all shared to give you a sense of what novelty can look like amidst this meta and act as a guiding force to understand what's been done, what's working, and overall where to direct your attention towards.
#make


24 days ago
A ~$1.7M portfolio split evenly between SCHD and JEPI targets $7,700/month using each fund's forward payout rate.
JEPI's monthly distributions have dropped sharply since 2022 as volatility fell, and recent payouts still vary from $0.34 to $0.45 per share.
Hold JEPI in an IRA and SCHD in a taxable account to maximize after-tax income from this two-fund strategy.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A portfolio of roughly $1.7 million, split evenly between SCHD and JEPI, targets $7,700 a month in distributions using each fund's current forward payout rate. Two tickers, one brokerage screen, nothing to rebalance beyond keeping the halves even. For a reader who finds a seven-holding portfolio intimidating, that simplicity is genuinely appealing, and it deserves to be said before the caveats begin.
#targets
25 days ago
President Donald Trump pledged Wednesday to send every American adult $5,000 if Republicans retain control of the House and Senate in the midterm elections, an extraordinary gambit to reverse his party's sagging fortunes in November.
The dubious promise would most likely cost more than $1 trillion and require congressional approval, and would further exacerbate the country's nearly $1.8 trillion annual budget deficit and concerns about inflation.
"If the Republicans win, you win with us and you get $5,000," Trump said during the GOP's midterm convention in Dallas. "It will be called the Trump Dividend."
He likened the payments to a corporation's distributions to shareholders, citing "our tremendous strength and success economically."
Within an hour, Vice President JD Vance appeared to try to walk back Trump's proposal — at least in part — by suggesting the dividend payments would not go to the wealthy. Vance suggested it could be paid for by U.S. tariff revenues, though the suggested payment dwarfs what the U.S. has taken in through the protectionist measures.
#president #republicans #midterm #suggested


25 days ago
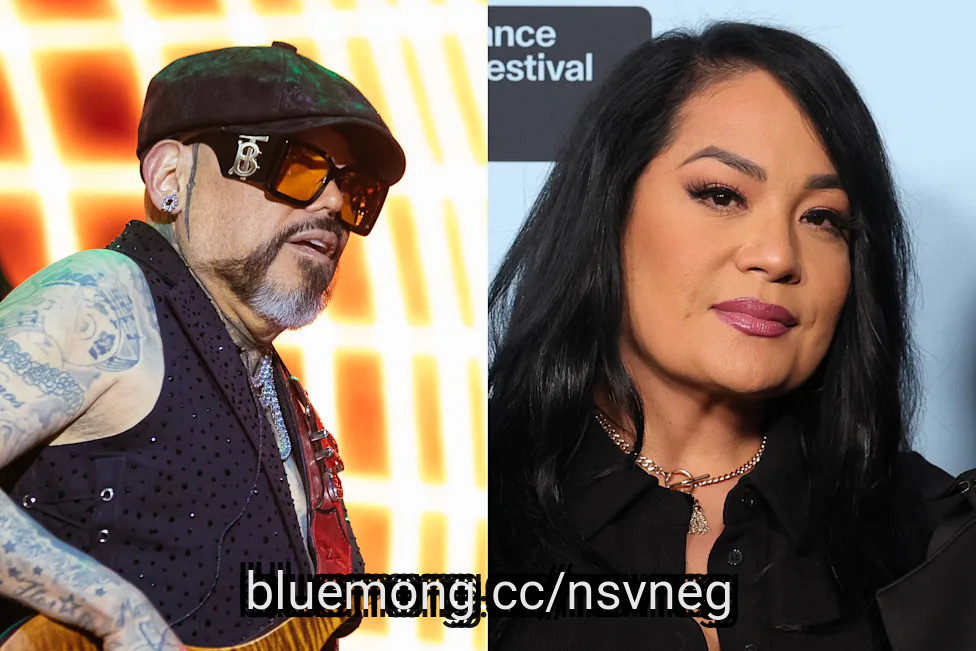
The public legal dispute between members of Selena Quintanilla's family has intensified. Abraham "A.B." Quintanilla III has officially sued his sister, Suzette Quintanilla-Arriago, over profits related to their famed sister's estate.
In a lawsuit filed on Sept. 10, and obtained by Rolling Stone, Quintanilla III seeks an unspecified amount in damages and monetary relief exceeding $1 million. The suit alleges that as the manager of Selena's estate, Quintanilla-Arriago has not provided A.B. "with a complete accounting of the ******* ets, liabilities, revenues, expenses, transactions, distributions, and net profits" and "failed or refused to pay [him] the full amount of net profits and proceeds due to him."
More from Rolling Stone
N.O.R.E. Calls Carmen Bryan's ******* ual ******* ault Claims 'Entirely False'
Jay-Z Loses Appeal to Revive Extortion, Defamation Lawsuit Against Lawyer Who Filed Rape Claim
#profits #arriago #filed
25 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
A health savings account (HSA) is a type of account that lets you save — and potentially invest — for healthcare expenses while earning tax benefits along the way. Depending on your financial situation and immediate medical needs, an HSA can even be a valuable retirement planning tool. But HSAs aren't available to everyone. Continue reading to learn how HSAs work, their rules, and pros and cons.
A health savings account is a tax-advantaged account you can use to pay for qualifying medical expenses, including prescription medications, eyeglasses, doctor's visits, and more. Some HSAs function like a savings account, while others give you the option to invest your funds for future use.
HSAs are known for their triple tax advantage: You fund them with pre-tax dollars, your contributions grow tax-free, and withdrawals are tax-free as long as you use them for qualifying medical expenses. For this reason, HSAs can be a valuable retirement savings tool if you don't need the funds to pay for immediate medical needs.
Unlike flexible spending accounts (FSAs), HSA contributions don't expire at the end of the year. This means you can contribute to your account year after year without the need to "use it or lose it." HSAs aren't subject to required minimum distributions, either.
#account #medical #year
26 days ago
A $400,000 inherited IRA can become much more expensive if you get the withdrawal timing wrong. Many non-spouse beneficiaries must empty the account within 10 years, and some also have annual RMDs. Delaying distributions could concentrate more taxable income into later years and potentially push more of your money into higher tax brackets.
For many non-spouse beneficiaries, an inherited IRA must be emptied by December 31 of the year containing the 10th1 anniversary of the original owner's death. Certain beneficiaries qualify for different rules.
The 10-year deadline may not be the only requirement. If the original owner died on or after their required beginning date, a non-spouse beneficiary subject to the 10-year rule generally must also take annual RMDs during the 10-year period.
Missing a required distribution can trigger an excise tax of up to 25% of the amount not withdrawn. This makes it important to know whether annual withdrawals apply instead of ****** uming you can leave the entire account untouched until year 10.
Traditional inherited IRA distributions are generally taxed as ordinary income. Leaving a large amount until the final years could force you to withdraw more at once, potentially pushing more of the $400,000 into higher tax brackets.
#year #spouse #beneficiaries #account


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
26 days ago
Energy Transfer (NYSE: ET) and Enterprise Products Partners (NYSE: EPD) are both popular stocks among income investors. They're both midstream pipeline companies that are well-insulated from volatile commodity prices because they simply charge downstream and upstream "tolls" to use their infrastructure. As long as those resources keep flowing through their pipelines, they can generate plenty of cash to fund their big distributions.
Energy Transfer, which operates more than 140,000 miles of pipeline across 44 states, pays a forward yield of 6.3%. Enterprise, which operates over 50,000 miles of pipeline across 27 states, pays a forward yield of 5.6%. Both companies have historically spent only about half of their distributable cash flow (DCF) on distributions, so they can easily cover those yields.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
But before you buy Energy Transfer and Enterprise as high-yield plays, you should be aware of an issue which investors often overlook. Both companies are master limited partnerships (MLPs) instead of traditional corporations, so they treat their investors as partners rather than shareholders. Let's see how that key difference makes them more complicated investments.
MLPs are pass-through entities that allow their income to directly flow to their partners. By comparison, traditional corporations are separate, taxable entities that hold their own income.
#NVIDIA #investors #Companies

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
28 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
Ever wondered what it would be like to have seven-figures in your 401(k) plan? Well, for at least 769,000 Americans, that's a reality. That's the number of people with at least $1 million in their 401(k) at the end of June 2026, according to Fidelity data cited by Yahoo Finance (1).
That's a tiny fraction of adults with retirement accounts. If you're in this club, you're extremely lucky. You're also sitting on a relatively large IOU to the tax authorities. At age 73, the Internal Revenue Service (IRS) (2) imposes required minimum distributions (RMDs), which are generally taxed as ordinary income.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Get your free guide from Priority Gold
#like #wealth #ever
1 month ago
No withdrawal order eliminates RMDs from a traditional IRA. Only Roth conversions, qualified charitable distributions, or never owning one in the first place can genuinely shrink them.
IRMAA surcharges hit Medicare premiums two years after the income that triggers them, jumping joint filers from $203 to $284 monthly by crossing $218,000 MAGI.
Letting an IRA compound untouched through your 60s forces larger RMDs at 73, often pushing retirees into higher brackets and through IRMAA cliffs simultaneously.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
A $2.1 million nest egg split evenly between a taxable brokerage account and a traditional IRA can throw off a six-figure income. What most retirees miss is that where each holding sits and when each dollar comes out determine whether Medicare surcharges and a swollen required minimum distribution eat that income a decade later.
#medicare #surcharges #retirees #magi

1 month ago
Delaying the first RMD to April 1 stacks two distributions on one tax return, potentially bundling over $150,000 in income for a $2 million IRA.
Medicare sets 2028 premiums using 2026 income, so a bunched RMD year can trigger IRMAA surcharges costing a married couple nearly $5,770 extra annually.
Taking the first RMD by December 31 instead of April 1 keeps both distributions on separate returns and eliminates the income-stacking problem entirely.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A retiree turned 73 in 2025 and used the option Congress left him. Instead of taking his first required minimum distribution (RMD) by December 31, he delayed it until April 1, 2026. The second RMD was still due December 31, 2026. Two withdrawals landed on one tax return, and Medicare does not care that the first one "belonged" to 2025. Both dollars became 2026 income. The April deadline bought three months. It did not buy another tax year.
#taking #instead
1 month ago
Americold Realty Trust, Inc. (NYSE:COLD) completed a cold-storage joint venture with EQT's Active Core Infrastructure fund covering 12 U.S. temperature-controlled warehouses with more than $1.3 billion of gross ***** et value. EQT acquired 70% of Americold-EQT Cold Storage Partnership, while Americold Realty Trust, Inc. (NYSE:COLD) retained 30% and became the day-to-day manager.
Americold Realty Trust, Inc. (NYSE:COLD) received approximately $1.1 billion of net cash proceeds and intends to use the cash to repay outstanding consolidated debt. Based on rounded announced figures, the proceeds equal approximately 25% of the latest reported net debt of $4.4 billion. Americold Realty Trust, Inc. (NYSE:COLD) projects that the eventual debt repayment will reduce annual interest expense by approximately $46 million and lower leverage by roughly 0.75 turn.
The structure remains more complicated than a simple ***** et sale. The joint venture drew $845.5 million under mortgage financing at closing. Americold Realty Trust, Inc. (NYSE:COLD) and EQT each appoint three members to the six-person board. Americold Realty Trust, Inc. (NYSE:COLD) also has maximum net exposure of up to $70 million under a 10-year income-support arrangement if specified performance thresholds are not achieved.
Those savings should offset part of the surrendered income while improving financial flexibility and reducing refinancing pressure.
Americold Realty Trust, Inc. (NYSE:COLD) retains exposure to distributions and appreciation through the 30% ownership interest. The management role preserves operating continuity, while equal board representation provides governance influence despite the minority economic stake.
#americold #trust #NYSE #debt
1 month ago
Hitting $112,800 annually in dividends demands $3.22M at conservative yields but just $1.06M from high-yield BDCs and mortgage REITs.
A 3.5% dividend yield growing 8% annually doubles income in nine years without adding a single dollar of new capital.
After-tax spending needs of $75,000 to $85,000, not gross salary, should anchor your capital target, shrinking the required portfolio at every tier.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A target of $9,400 a month in dividend income works out to $112,800 a year, all from distributions and without dipping into principal. That is roughly what a mid-career software engineer takes home, or what a two-earner household clears in a coastal metro. The math is straightforward division. Divide your income target by your portfolio yield, and that tells you how much capital you need. The interesting part is what shifts as the yield climbs.
#capital #target #Portfolio #without

1 month ago
Defunct Yellow Corp. has reached settlement agreements with four multiemployer pension plans totaling up to $526 million to resolve remaining withdrawal liability claims. The deals are supported by its largest shareholder, MFN Partners, and would bring an end to a legal battle that began shortly after the less-than-truckload carrier filed for bankruptcy in August 2023.
(Yellow previously agreed to terms with most of the MEPPs it once contributed to on behalf of employees.)
New York State Teamsters Conference Pension and Retirement Fund, Western Conference of Teamsters Pension Trust Fund, and Western Pennsylvania Teamsters and Employers Pension Fund would receive the bulk of the funds. New York Teamsters are seeking approval for a $300 million claim.
A federal bankruptcy court in Delaware has been asked to approve the plan, which "will bring the current multi-year long MEPP litigation in these cases to an end … thus allowing the Liquidating Trust to begin making meaningful distributions to general unsecured claimants."
As part of the deal, MFN has agreed to drop its pending appeals and will waive its right to file certain legal fees and expenses.
#teamsters #conference #western
1 month ago
Cher found her son Elijah Blue Allman's absence in court a rewarding situation!
The singer has now received the judge's approval to give her ongoing case in New Hampshire the attention needed to proceed, along with ground rules for her son to secure an attorney.
Cher has been working to ensure Elijah Blue Allman gets a legally appointed conservator to protect the six-figure annual trust distributions her son receives from Greg Allman's estate.
©1998 RAMEY PHOTO AGENCY/ MEGA
The singer scored a procedural win in the ongoing conservatorship case as a Los Angeles court has now agreed to pause the proceedings. Meanwhile, a separate guardianship dispute is unfolding in New Hampshire.
#case


1 month ago
TSLW's 29% price drop looks worse than TSLA's 22% YTD loss, but trailing distributions of nearly $18 per share account for most of the gap.
Only 20% of TSLW is actual Tesla stock; 67% sits in Treasury bill collateral and 12% in derivatives that generate the weekly option income.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
If you bought Roundhill Tesla WeeklyPay ETF (CBOE:TSLW) for the paychecks, the paychecks arrived. A distribution hit your account almost every Friday in 2026, most recently $0.183637 per share paid on August 25. Then you looked at the price chart. TSLW opened the year at $24.82 and closed August 28 at $17.56, a price return of negative 29.26%. Something is missing from that picture.
TSLW is a weekly income vehicle wrapped around Tesla exposure. Distributions are paid out of net ****** et value on each ex-date. That mechanical drop is baked into the price line you see. That drop reflects cash that left the fund and, in theory, landed in your brokerage account, separate from any expense ratio or fund-inflicted loss.
#august
1 month ago
IRA withdrawals cannot satisfy 401(k) RMDs. Each 401(k) requires its own separate distribution, no matter how much you pull from the IRA.
Missing a 401(k) RMD triggers a 25% excise tax, but filing Form 5329 within two years cuts that penalty to 10%.
Rolling old 401(k)s into a single traditional IRA via direct trustee-to-trustee transfer reduces multiple RMD calculations to one annual withdrawal.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
At age 73, retirement savers face a firm deadline set by the IRS. That is when Required Minimum Distributions begin under the SECURE 2.0 Act, and the IRS begins expecting a slice of the pre-tax money that has been growing untouched for decades. The mechanics look simple on paper: calculate the amount, take the withdrawal, and report it on the tax return. Real accounts complicate that picture, and one woman's story shows why.
#withdrawal #missing
1 month ago
JEPQ's ~4.7% forward yield requires roughly $842,000 to generate $39,600 annually, nearly double the commonly cited $420,000 entry point.
A 30% Nasdaq-100 drawdown would shrink a $420,000 JEPQ stake to ~$294,000, while its floating distributions have already declined from 2023 highs.
JEPQ distributions are taxed as ordinary income, cutting the after-tax yield to ~7.4% for retirees in the 22% federal bracket.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Let us say you are 68 and your goal is $3,300 a month in portfolio income. That works out to about $39,600 a year, which is close to what a single retiree typically gets from an average Social Security check plus a small pension. The real question is not just how much capital you need to park to hit that number, but what you have to sacrifice in exchange.
#distributions #Portfolio #learn #security
1 month ago
Vipshop Holdings Limited (NYSE:VIPS) reported sharply higher GAAP earnings for the second quarter of 2026, but the increase came primarily from a commercial real estate investment trust transaction rather than the retail business.
At 5:16 a.m. EDT on August 25, the shares were down 4.9% in premarket trading. They recovered most of that decline before closing 1.1% lower at $14.16.
Revenue fell 4.3% year over year to RMB24.7 billion. GAAP net income attributable to Vipshop's shareholders nevertheless increased 189.1% to RMB4.31 billion. GAAP diluted earnings rose to RMB8.82 per ADS from RMB2.91.
The company listed a commercial REIT covering two Shan Shan outlets and subscribed for 49% of the units. The transaction generated RMB7.70 billion of gross proceeds, a RMB5.79 billion investment gain, and RMB1.63 billion of related tax expense.
The resulting RMB4.16 billion after-tax REIT amount represented approximately 148% of the RMB2.82 billion year-over-year increase in GAAP net income attributable to shareholders. Other items offset part of that benefit, including a RMB1.56 billion withholding-tax expense ***** ociated with historical dividend distributions.
#billion #year #shan

1 month ago
Large-cap value is beating the broader market in 2026, but VTV, COWZ, and DHS capture the rotation differently. VTV offers broad traditional value exposure, COWZ targets companies with high free-cash-flow yields, and DHS emphasizes high-dividend stocks.
COWZ offers the strongest quality-oriented value tilt. Its free-cash-flow methodology has helped it outperform while avoiding some weaknesses of traditional valuation screens, although investors pay a higher 0.49% expense ratio.
VTV and DHS fill clearer portfolio roles. VTV is the ultra-low-cost core option at 0.03%, while DHS offers the highest income focus with monthly distributions and a yield around 3%.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Large-cap value has quietly outrun the broader market in 2026, and three exchange-traded funds capture that shift while paying meaningful dividends: the Vanguard Value ETF (NYSEARCA:VTV), the Pacer US Cash Cows 100 ETF (CBOE:COWZ), and the WisdomTree U.S. High Dividend Fund (NYSEARCA:DHS). Each is beating the S&P 500 year to date, but each defines "value" differently, which matters more than the shared headline.
#cowz #investors