

5 days ago
On September 8, 2026, the Wall Street Journal reported United Natural Foods, Inc. (NYSE:UNFI)'s fiscal fourth-quarter results, in which adjusted earnings per share of $0.69 beat ***** yst expectations even as revenue of $7.64 billion came in below consensus.
The grocery wholesaler guided for fiscal 2027 net sales of $31.2 billion to $31.8 billion, a return to growth after full-year fiscal 2026 sales declined 2% to $31.2 billion. The business said full-year adjusted EBITDA rose 27% to $701 million and free cash flow hit a record $323 million as it continued executing what CEO Sandy Douglas called its second year of a value-creation strategy.
United Natural Foods, Inc. (NYSE:UNFI)'s turnaround is improving the financial metrics that matter most for a food distributor. Full-year adjusted EBITDA increased 27%. Net debt fell by $295 million and net leverage improved to 2.2 times. The stronger balance sheet gives UNFI more financial flexibility as it works to return to sales growth.
UNFI's natural-products business is providing an important growth engine. Fourth-quarter natural-products sales increased 6.6%, even as conventional-products sales declined 8.6%. The stronger performance in natural products backs up UNFI's strategy of expanding business with customers that can drive growth as the business restructures its operations.
Management also expects fiscal 2027 sales to reach $31.2 billion to $31.8 billion, up from $31.15 billion in fiscal 2026. Adjusted EPS should reach $3.00 to $3.50 versus $2.65 previously. Management anticipates about 10 basis points of margin expansion at the midpoint, which could help UNFI reach its fiscal 2028 margin target a year earlier than planned.
#billion
The grocery wholesaler guided for fiscal 2027 net sales of $31.2 billion to $31.8 billion, a return to growth after full-year fiscal 2026 sales declined 2% to $31.2 billion. The business said full-year adjusted EBITDA rose 27% to $701 million and free cash flow hit a record $323 million as it continued executing what CEO Sandy Douglas called its second year of a value-creation strategy.
United Natural Foods, Inc. (NYSE:UNFI)'s turnaround is improving the financial metrics that matter most for a food distributor. Full-year adjusted EBITDA increased 27%. Net debt fell by $295 million and net leverage improved to 2.2 times. The stronger balance sheet gives UNFI more financial flexibility as it works to return to sales growth.
UNFI's natural-products business is providing an important growth engine. Fourth-quarter natural-products sales increased 6.6%, even as conventional-products sales declined 8.6%. The stronger performance in natural products backs up UNFI's strategy of expanding business with customers that can drive growth as the business restructures its operations.
Management also expects fiscal 2027 sales to reach $31.2 billion to $31.8 billion, up from $31.15 billion in fiscal 2026. Adjusted EPS should reach $3.00 to $3.50 versus $2.65 previously. Management anticipates about 10 basis points of margin expansion at the midpoint, which could help UNFI reach its fiscal 2028 margin target a year earlier than planned.
#billion

5 days ago
During market uncertainty, cautious investors may feel compelled to sell everything while they wait for the dust to settle. But Ross Gerber believes that, to paraphrase Rudyard Kipling, if you can keep your head when everyone else is losing theirs, you'll reap even bigger rewards.
The Gerber Kawasaki CEO says that while inflation, higher bond yields, oil prices, and Federal Reserve rate hikes can pressure stocks, he does not think investors should abandon equities wholesale. Instead, he advocates for a more defensive approach.
He recommends investors trim holdings with valuations that look stretched relative to their growth, build reserves in cash and short-duration fixed income **** ets, and keep long-term positions in companies that he believes still have strong earnings support, such as Nvidia.
And for investors trying to navigate an environment where corporate earnings remain strong while macroeconomic risks pressure stock valuations, that distinction matters. Gerber's framework is less about calling the market's next move than deciding which risks a portfolio can absorb—and which positions still deserve capital.
Here is a closer look at Gerber's defensive-focused strategy.
#gerber #pressure #still
The Gerber Kawasaki CEO says that while inflation, higher bond yields, oil prices, and Federal Reserve rate hikes can pressure stocks, he does not think investors should abandon equities wholesale. Instead, he advocates for a more defensive approach.
He recommends investors trim holdings with valuations that look stretched relative to their growth, build reserves in cash and short-duration fixed income **** ets, and keep long-term positions in companies that he believes still have strong earnings support, such as Nvidia.
And for investors trying to navigate an environment where corporate earnings remain strong while macroeconomic risks pressure stock valuations, that distinction matters. Gerber's framework is less about calling the market's next move than deciding which risks a portfolio can absorb—and which positions still deserve capital.
Here is a closer look at Gerber's defensive-focused strategy.
#gerber #pressure #still

6 days ago
Over the last seven years, I've **** yzed hundreds of stocks and cryptocurrencies to see if they might be worth an investment. At the end of the day, I only end up buying a select few, like two of my longtime favorites, Costco Wholesale (NASDAQ: COST) and Apple (NASDAQ: AAPL).
Here's an abridged version of my research process -- hopefully it'll contain something useful to adapt as your own.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
I typically start by getting the lay of the land regarding the company in question.
Step zero is comparing the stock's total returns to the S&P 500 over a range of different periods, starting from one month and extending to five years. Ideally, like both Apple and Costco, the company being evaluated will have outperformed the index over the last five years.
#NASDAQ #flashing #total
Here's an abridged version of my research process -- hopefully it'll contain something useful to adapt as your own.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
I typically start by getting the lay of the land regarding the company in question.
Step zero is comparing the stock's total returns to the S&P 500 over a range of different periods, starting from one month and extending to five years. Ideally, like both Apple and Costco, the company being evaluated will have outperformed the index over the last five years.
#NASDAQ #flashing #total


6 days ago
Sept 16, 2026, 12:53 pm EDT
Earnings from Costco
COST
+0.02%
Wholesale next week could fall short of Wall Street forecasts, but an upcoming announcement from the retailer could be an enticement t0 investors.
COST
+0.02%
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#wholesale #wall #jones #company
Earnings from Costco
COST
+0.02%
Wholesale next week could fall short of Wall Street forecasts, but an upcoming announcement from the retailer could be an enticement t0 investors.
COST
+0.02%
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#wholesale #wall #jones #company

6 days ago
On the September 11 episode of Mad Money, Jim Cramer expressed strong optimism for Brinker International, Inc. (NYSE:EAT) ahead of its upcoming **** yst presentation, as he said:
Thursday, we have two important **** yst meetings. Brinker... We have them all the time on the show. Brinker, you know, is Chili's, and the company never fails to wow me. I think this meeting will be no exception.
Brinker International, Inc. (NYSE:EAT) continues to demonstrate operational strength across the casual dining sector, driven by sustained customer traffic and menu innovation at Chili's Grill & Bar. In its fourth quarter of fiscal 2026, the company generated $1.54 billion in total revenue, bringing full-year revenues to $5.81 billion. Adjusted earnings per share for the quarter reached $3.07, representing a 23% year-over-year increase.
Chili's reported a 5.6% increase in comparable store sales, marking its 21st consecutive quarter of positive same-store sales growth. The sustained momentum has been supported by the ongoing success of the $10.99 "3 for Me" everyday value platform as well as targeted menu launches, including the Big Crispy Chicken Sandwich, which helped support traffic as Chili's continued positioning its value proposition against fast-food offerings. According to the company's CEO Kevin Hochman, the Big Crispy Chicken Sandwich "overdelivered" on the management's estimates.
Despite consistent top-line momentum, Brinker International, Inc. (NYSE:EAT) faces ongoing execution risks **** ociated with sticky cost inflation and broader macroeconomic pressures on consumer spending. Elevated wholesale prices for core commodities, especially beef and produce, continue to weigh on restaurant operating costs, while wage growth across regional markets keeps labor expenses elevated.
#elevated #analyst
Thursday, we have two important **** yst meetings. Brinker... We have them all the time on the show. Brinker, you know, is Chili's, and the company never fails to wow me. I think this meeting will be no exception.
Brinker International, Inc. (NYSE:EAT) continues to demonstrate operational strength across the casual dining sector, driven by sustained customer traffic and menu innovation at Chili's Grill & Bar. In its fourth quarter of fiscal 2026, the company generated $1.54 billion in total revenue, bringing full-year revenues to $5.81 billion. Adjusted earnings per share for the quarter reached $3.07, representing a 23% year-over-year increase.
Chili's reported a 5.6% increase in comparable store sales, marking its 21st consecutive quarter of positive same-store sales growth. The sustained momentum has been supported by the ongoing success of the $10.99 "3 for Me" everyday value platform as well as targeted menu launches, including the Big Crispy Chicken Sandwich, which helped support traffic as Chili's continued positioning its value proposition against fast-food offerings. According to the company's CEO Kevin Hochman, the Big Crispy Chicken Sandwich "overdelivered" on the management's estimates.
Despite consistent top-line momentum, Brinker International, Inc. (NYSE:EAT) faces ongoing execution risks **** ociated with sticky cost inflation and broader macroeconomic pressures on consumer spending. Elevated wholesale prices for core commodities, especially beef and produce, continue to weigh on restaurant operating costs, while wage growth across regional markets keeps labor expenses elevated.
#elevated #analyst


6 days ago
Uber Technologies (NYSE:UBER) and Costco Wholesale (NASDAQ:COST) have expanded their US delivery partnership to 47 states, up from 17, making nearly 600 Costco locations available through the Uber Eats platform.
The companies said the expanded service allows Costco members to place orders for on-demand or scheduled delivery through the Uber Eats app.
Customers can purchase fresh produce, bulk groceries and household products, link their Costco membership during checkout and track their deliveries in real time.
The expansion increases the geographic reach of Costco's delivery service through Uber Eats, giving members access to products from participating warehouses.
Nearly 600 Costco locations are now available on the platform, according to the companies' joint statement.
#costco #expanded #available #platform
The companies said the expanded service allows Costco members to place orders for on-demand or scheduled delivery through the Uber Eats app.
Customers can purchase fresh produce, bulk groceries and household products, link their Costco membership during checkout and track their deliveries in real time.
The expansion increases the geographic reach of Costco's delivery service through Uber Eats, giving members access to products from participating warehouses.
Nearly 600 Costco locations are now available on the platform, according to the companies' joint statement.
#costco #expanded #available #platform

6 days ago
Cardinal Health, Inc. (CAH), headquartered in Dublin, Ohio, operates as a healthcare services and products company. Valued at $54.6 billion by market cap, the company's services include pharmaceutical distribution, health-care product manufacturing, distribution and consulting services, drug delivery systems development, pharmaceutical packaging, automated dispensing systems manufacturing, and retail pharmacy franchising.
Companies worth $10 billion or more are generally described as "large-cap stocks," and CAH perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the medical distribution industry. As one of the top three U.S. pharma wholesalers, CAH holds a commanding market position. Its diversified pharmaceutical and medical distribution portfolio, broadens its customer base, adds resilience to market swings, and creates multiple revenue streams with cross-selling opportunities.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#market #Health #Manufacturing #systems
Companies worth $10 billion or more are generally described as "large-cap stocks," and CAH perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the medical distribution industry. As one of the top three U.S. pharma wholesalers, CAH holds a commanding market position. Its diversified pharmaceutical and medical distribution portfolio, broadens its customer base, adds resilience to market swings, and creates multiple revenue streams with cross-selling opportunities.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#market #Health #Manufacturing #systems


7 days ago
The U.S. fuel crisis stemming from the ongoing war in Iran has now reached the retail shelf, with Costco Wholesale (COST) nearly doubling the price of its Kirkland Signature full-synthetic motor oil from roughly $30 to $58 per 5-quart two-pack, while simultaneously capping purchases at two units per membership every seven days.
It's an extraordinary move for a retailer whose entire brand identity rests on bulk buying at deep discounts, and it signals that severe supply chain disruptions are spreading well beyond the gasoline pump.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#supply #wholesale
It's an extraordinary move for a retailer whose entire brand identity rests on bulk buying at deep discounts, and it signals that severe supply chain disruptions are spreading well beyond the gasoline pump.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#supply #wholesale


8 days ago
On the September 11 episode of Mad Money, Jim Cramer expressed strong optimism for Brinker International, Inc. (NYSE:EAT) ahead of its upcoming **** yst presentation, as he said:
Thursday, we have two important **** yst meetings. Brinker... We have them all the time on the show. Brinker, you know, is Chili's, and the company never fails to wow me. I think this meeting will be no exception.
Brinker International, Inc. (NYSE:EAT) continues to demonstrate operational strength across the casual dining sector, driven by sustained customer traffic and menu innovation at Chili's Grill & Bar. In its fourth quarter of fiscal 2026, the company generated $1.54 billion in total revenue, bringing full-year revenues to $5.81 billion. Adjusted earnings per share for the quarter reached $3.07, representing a 23% year-over-year increase.
Chili's reported a 5.6% increase in comparable store sales, marking its 21st consecutive quarter of positive same-store sales growth. The sustained momentum has been supported by the ongoing success of the $10.99 "3 for Me" everyday value platform as well as targeted menu launches, including the Big Crispy Chicken Sandwich, which helped support traffic as Chili's continued positioning its value proposition against fast-food offerings. According to the company's CEO Kevin Hochman, the Big Crispy Chicken Sandwich "overdelivered" on the management's estimates.
Despite consistent top-line momentum, Brinker International, Inc. (NYSE:EAT) faces ongoing execution risks **** ociated with sticky cost inflation and broader macroeconomic pressures on consumer spending. Elevated wholesale prices for core commodities, especially beef and produce, continue to weigh on restaurant operating costs, while wage growth across regional markets keeps labor expenses elevated.
#NYSE
Thursday, we have two important **** yst meetings. Brinker... We have them all the time on the show. Brinker, you know, is Chili's, and the company never fails to wow me. I think this meeting will be no exception.
Brinker International, Inc. (NYSE:EAT) continues to demonstrate operational strength across the casual dining sector, driven by sustained customer traffic and menu innovation at Chili's Grill & Bar. In its fourth quarter of fiscal 2026, the company generated $1.54 billion in total revenue, bringing full-year revenues to $5.81 billion. Adjusted earnings per share for the quarter reached $3.07, representing a 23% year-over-year increase.
Chili's reported a 5.6% increase in comparable store sales, marking its 21st consecutive quarter of positive same-store sales growth. The sustained momentum has been supported by the ongoing success of the $10.99 "3 for Me" everyday value platform as well as targeted menu launches, including the Big Crispy Chicken Sandwich, which helped support traffic as Chili's continued positioning its value proposition against fast-food offerings. According to the company's CEO Kevin Hochman, the Big Crispy Chicken Sandwich "overdelivered" on the management's estimates.
Despite consistent top-line momentum, Brinker International, Inc. (NYSE:EAT) faces ongoing execution risks **** ociated with sticky cost inflation and broader macroeconomic pressures on consumer spending. Elevated wholesale prices for core commodities, especially beef and produce, continue to weigh on restaurant operating costs, while wage growth across regional markets keeps labor expenses elevated.
#NYSE


8 days ago
New vehicle sales in Indonesia surged by a further 32% year-on-year to 81,756 units in August 2026, up from weak year-earlier sales of 61,771 units, according to wholesale data compiled by the local automotive industry ***** ociation, Gaikindo. The market last month was driven higher by strong demand for trucks and battery electric vehicles (BEVs).
In the first eight months of 2026, the country's vehicle market expanded by 20% to 599,491 units, after declining by 11% to 499,315 units a year earlier, with sales of light passenger vehicles rising by over 13% to 437,374 units, while commercial vehicle sales increased by 42% to 162,117 units, driven by a 54% surge in light- and medium-duty trucks to 131,813 units.
The truck market this year has been supported by government plans to procure vehicles to support the development of rural cooperatives and improve local logistics networks nationwide.
Sales of BEVs almost doubled to 103,300 units year-to-date, up from 53,100 units in the same period a year earlier, driven by Chinese brands and supported by government tax incentives.
GDP growth moderated to 5.3% year-on-year in the second quarter of 2026, down from a peak of 5.6% in the first quarter, underpinned mainly by strong government spending and investment. Private consumption growth slowed to 5.1% from 5.5%, after the central bank hiked its benchmark interest rate by 100 basis points to 5.75% in the second quarter to support the rupiah and rein in rising inflation. Government spending grew by 16%, down from a peak of 22%, driven by social programmes and rising fuel subsidy costs.
#year
In the first eight months of 2026, the country's vehicle market expanded by 20% to 599,491 units, after declining by 11% to 499,315 units a year earlier, with sales of light passenger vehicles rising by over 13% to 437,374 units, while commercial vehicle sales increased by 42% to 162,117 units, driven by a 54% surge in light- and medium-duty trucks to 131,813 units.
The truck market this year has been supported by government plans to procure vehicles to support the development of rural cooperatives and improve local logistics networks nationwide.
Sales of BEVs almost doubled to 103,300 units year-to-date, up from 53,100 units in the same period a year earlier, driven by Chinese brands and supported by government tax incentives.
GDP growth moderated to 5.3% year-on-year in the second quarter of 2026, down from a peak of 5.6% in the first quarter, underpinned mainly by strong government spending and investment. Private consumption growth slowed to 5.1% from 5.5%, after the central bank hiked its benchmark interest rate by 100 basis points to 5.75% in the second quarter to support the rupiah and rein in rising inflation. Government spending grew by 16%, down from a peak of 22%, driven by social programmes and rising fuel subsidy costs.
#year

9 days ago
On September 10, Copart (NASDAQ:CPRT) held its fourth-quarter earnings call and used it to unveil a deal that could reshape its business: an all-cash agreement to acquire ACV, a digital auto marketplace that moved roughly $10 billion of vehicles last year without owning a single lot. The announcement landed alongside a quarter that captured the company's central tension. Revenue rose, but net income fell, and management is now betting that pairing its junkyards with someone else's software can fix that.
The ACV deal is the headline, and for good reason. ACV brings more than 22,000 active buyers and inspection and valuation technology, while Copart contributes over 275 locations, roughly 4 million vehicles sold annually, and about 1 million members across more than 185 countries. Management structured it as an all-cash tender offer funded from cash on hand, with a close targeted by the end of the calendar year and earnings accretion expected in fiscal 2028. Executives framed the fit as physical scale meeting digital liquidity, giving dealers, banks, and fleet sellers a single partner for disposing of vehicles.
That diversification push is already showing up in the numbers. International revenue grew 11.7% to $222.1 million on 15% service revenue growth, and international buyers accounted for 45.7% of total US sales dollars despite making up only 38.2% of units, a sign they are chasing pricier vehicles. Domestically, non-insurance units returned to growth of 0.2% in the quarter after a full-year decline, dealer units rose 5.8%, and BluCar, which serves banks and fleets, expanded nearly 20%. Global average selling prices climbed 3.5%, evidence that Copart's auctions still command pricing power even as volumes soften.
The quarter's numbers show where the strain is. Consolidated revenue grew 2.4% to $1.2 billion, yet net income dropped 17.4% to $327.4 million and diluted earnings per share fell 14.6% to $0.35. Operating expense per car jumped 12.7% year over year as the company poured money into long-haul delivery, **** leExpress, and dedicated wholesale facilities, and US facility costs alone rose 7.7% in the quarter. Lower interest income, a byproduct of the $1.63 billion spent on buybacks earlier in the fiscal year, added to the squeeze.
The core insurance business is also cooling. Global insurance units fell 4.2%, with domestic insurance **** ignments down 7.5%, though management noted that figure would have been up 2.3% excluding the loss of a single customer. Collision claim frequency declined 3.4% even as total loss frequency hit a record 23.3% for a second quarter and severity topped $6,300 per claim, up 8.8%. And the ACV deal itself carries integration risk, since management expects only breakeven results before accretion arrives in fiscal 2028.
#quarter #vehicles #insurance
The ACV deal is the headline, and for good reason. ACV brings more than 22,000 active buyers and inspection and valuation technology, while Copart contributes over 275 locations, roughly 4 million vehicles sold annually, and about 1 million members across more than 185 countries. Management structured it as an all-cash tender offer funded from cash on hand, with a close targeted by the end of the calendar year and earnings accretion expected in fiscal 2028. Executives framed the fit as physical scale meeting digital liquidity, giving dealers, banks, and fleet sellers a single partner for disposing of vehicles.
That diversification push is already showing up in the numbers. International revenue grew 11.7% to $222.1 million on 15% service revenue growth, and international buyers accounted for 45.7% of total US sales dollars despite making up only 38.2% of units, a sign they are chasing pricier vehicles. Domestically, non-insurance units returned to growth of 0.2% in the quarter after a full-year decline, dealer units rose 5.8%, and BluCar, which serves banks and fleets, expanded nearly 20%. Global average selling prices climbed 3.5%, evidence that Copart's auctions still command pricing power even as volumes soften.
The quarter's numbers show where the strain is. Consolidated revenue grew 2.4% to $1.2 billion, yet net income dropped 17.4% to $327.4 million and diluted earnings per share fell 14.6% to $0.35. Operating expense per car jumped 12.7% year over year as the company poured money into long-haul delivery, **** leExpress, and dedicated wholesale facilities, and US facility costs alone rose 7.7% in the quarter. Lower interest income, a byproduct of the $1.63 billion spent on buybacks earlier in the fiscal year, added to the squeeze.
The core insurance business is also cooling. Global insurance units fell 4.2%, with domestic insurance **** ignments down 7.5%, though management noted that figure would have been up 2.3% excluding the loss of a single customer. Collision claim frequency declined 3.4% even as total loss frequency hit a record 23.3% for a second quarter and severity topped $6,300 per claim, up 8.8%. And the ACV deal itself carries integration risk, since management expects only breakeven results before accretion arrives in fiscal 2028.
#quarter #vehicles #insurance
9 days ago
On September 10, IBEX Limited (NASDAQ:IBEX) held its fourth-quarter and full fiscal year 2026 earnings call, and the numbers backed up a message management has been building toward for months. The company posted record full-year revenue, adjusted EBITDA, and free cash flow, all while pitching itself as a business that has flipped the AI narrative in its favor rather than becoming its next casualty. For a sector that has spent the last two years bracing for automation to gut it, that is a notable claim to back with actual client wins.
Full-year revenue hit $644.1 million, up 15.4% organically, and fourth-quarter revenue reached $164.3 million, up 11.6% from a year earlier. That marked the sixth straight quarter of double-digit growth, a streak that suggests the momentum is not a one-off. HealthTech led the charge, climbing 38.5% to $114 million for the year and blowing past the $100 million target management had set for the segment, driven largely by demand from large insurance payers. Technology grew 27.4% in the quarter, while travel and logistics added 17.8%, helped by a new AI agent partnership with Philippine Airlines.
That Philippine Airlines deal is the clearest evidence that IBEX's Sierra AI partnership, formalized in January and announced publicly in May, is more than a slide in an investor deck. During the proof of concept, the AI agent handled interactions in English, Tagalog, and Taglish, hit resolution rates above 20%, and scored a 4.7 out of 5.0 on customer satisfaction, on par with human agents. A separate deployment for BJ's Wholesale pushed resolution rates above 40% and matched that same satisfaction score, beating the marks the client's prior BPO vendor had put up with human agents alone. The company added 17 new trophy logo clients across the year, and its top five clients now make up 33% of revenue, down from 36%, a sign the business is not leaning on a shrinking handful of accounts to carry it.
Not every line moved in the right direction. Fourth quarter GAAP net income slipped to $8.7 million from $9.6 million a year earlier, and diluted EPS fell to $0.59 from $0.66. Management pointed to training costs tied to all those new client wins, a temporary hit from shifting work out of nearshore centers into offshore ones, and higher fuel prices hitting utility and transportation costs, particularly offshore. Adjusted EBITDA margin for the quarter slipped to 12.3% from 13.9%, the same set of pressures showing up in the profitability line rather than just net income.
#revenue #fourth
Full-year revenue hit $644.1 million, up 15.4% organically, and fourth-quarter revenue reached $164.3 million, up 11.6% from a year earlier. That marked the sixth straight quarter of double-digit growth, a streak that suggests the momentum is not a one-off. HealthTech led the charge, climbing 38.5% to $114 million for the year and blowing past the $100 million target management had set for the segment, driven largely by demand from large insurance payers. Technology grew 27.4% in the quarter, while travel and logistics added 17.8%, helped by a new AI agent partnership with Philippine Airlines.
That Philippine Airlines deal is the clearest evidence that IBEX's Sierra AI partnership, formalized in January and announced publicly in May, is more than a slide in an investor deck. During the proof of concept, the AI agent handled interactions in English, Tagalog, and Taglish, hit resolution rates above 20%, and scored a 4.7 out of 5.0 on customer satisfaction, on par with human agents. A separate deployment for BJ's Wholesale pushed resolution rates above 40% and matched that same satisfaction score, beating the marks the client's prior BPO vendor had put up with human agents alone. The company added 17 new trophy logo clients across the year, and its top five clients now make up 33% of revenue, down from 36%, a sign the business is not leaning on a shrinking handful of accounts to carry it.
Not every line moved in the right direction. Fourth quarter GAAP net income slipped to $8.7 million from $9.6 million a year earlier, and diluted EPS fell to $0.59 from $0.66. Management pointed to training costs tied to all those new client wins, a temporary hit from shifting work out of nearshore centers into offshore ones, and higher fuel prices hitting utility and transportation costs, particularly offshore. Adjusted EBITDA margin for the quarter slipped to 12.3% from 13.9%, the same set of pressures showing up in the profitability line rather than just net income.
#revenue #fourth

12 days ago
Oxford Industries, Inc. (NYSE:OXM) reported fiscal second-quarter net sales of $394.4 million, down 2.2%. Full-price direct-to-consumer sales declined 1%, while wholesale sales fell 14%, primarily reflecting lower off-price sales.
GAAP gross margin increased to 73.8% from 61.4% after Oxford Industries, Inc. (NYSE:OXM) recognized approximately $42 million of tariff refund claims as a reduction of cost of goods sold. Company-defined non-GAAP adjusted gross margin, excluding tariff refunds and LIFO effects, still improved to 63.1% from 61.7%. Updated **** ortment, sourcing, and pricing strategies increased initial markups, while lower off-price wholesale sales improved the sales mix.
Oxford Industries, Inc. (NYSE:OXM) lowered full-year sales guidance to $1.43 billion to $1.47 billion from $1.475 billion to $1.505 billion. Company-defined non-GAAP adjusted EPS guidance fell to $1.60 to $2.00 from $2.30 to $2.70, reducing the midpoint by 28%. Adjusted EPS excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, distribution-center relocation costs, merchandising initiatives, store-closure impairments and related taxes.
Underlying margin expansion suggests Oxford Industries, Inc. (NYSE:OXM) improved product economics beyond the one-time refund. Company-defined non-GAAP adjusted operating income, which excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, and specified distribution-center, merchandising, and store-closure costs, increased to $29.3 million from $28.3 million. Adjusted operating margin rose to 7.4% from 7.0%.
Tommy Bahama remained the strongest major brand for Oxford Industries, Inc. (NYSE:OXM), with sales increasing 0.8% and adjusted gross margin rising to 63.6% from 60.7%. FIFO inventory fell $9 million, or 4%, from one year earlier, reducing markdown exposure.
#gaap
GAAP gross margin increased to 73.8% from 61.4% after Oxford Industries, Inc. (NYSE:OXM) recognized approximately $42 million of tariff refund claims as a reduction of cost of goods sold. Company-defined non-GAAP adjusted gross margin, excluding tariff refunds and LIFO effects, still improved to 63.1% from 61.7%. Updated **** ortment, sourcing, and pricing strategies increased initial markups, while lower off-price wholesale sales improved the sales mix.
Oxford Industries, Inc. (NYSE:OXM) lowered full-year sales guidance to $1.43 billion to $1.47 billion from $1.475 billion to $1.505 billion. Company-defined non-GAAP adjusted EPS guidance fell to $1.60 to $2.00 from $2.30 to $2.70, reducing the midpoint by 28%. Adjusted EPS excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, distribution-center relocation costs, merchandising initiatives, store-closure impairments and related taxes.
Underlying margin expansion suggests Oxford Industries, Inc. (NYSE:OXM) improved product economics beyond the one-time refund. Company-defined non-GAAP adjusted operating income, which excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, and specified distribution-center, merchandising, and store-closure costs, increased to $29.3 million from $28.3 million. Adjusted operating margin rose to 7.4% from 7.0%.
Tommy Bahama remained the strongest major brand for Oxford Industries, Inc. (NYSE:OXM), with sales increasing 0.8% and adjusted gross margin rising to 63.6% from 60.7%. FIFO inventory fell $9 million, or 4%, from one year earlier, reducing markdown exposure.
#gaap


13 days ago
Casey's General Stores Inc. (NASDAQ:CASY), the third-largest convenience chain and fifth-biggest pizza brand within the U.S., released its first quarter results, showing early traction from the company's recently announced three-year strategic plan. For the recent quarter, inside same-store sales jumped 3.2% year-over-year, and 7.7% on a two-year stacked basis, leading to inside margins of 42.2%. Total inside gross profit stood at $749.8 million, rising 6.3% compared to the same period last year. The company posted net income of $273.7 million, exhibiting a 27.1% increase relative to Q1 last year. This translated into a 27.7% jump in diluted EPS which rose to $7.37.
Foodio/Shutterstock.com
Casey's is building on its three-year roadmap which rests on three core pillars. These include acceleration of growth across food and beverage, scaling up its store footprint, and elevating its operational efficiency.
Food remains a major growth enabler for the broader business, with prepared foods and nonalcoholic beverages currently driving the expansion of inside sales. Wings sales within Des Moines market also posted a 20% year-over-year sales jump. This positions the company to benefit from a larger opportunity of ramping up the offerings across roughly 3,000 stores, and cements Casey's reputation as a food destination.
The retailer also plans to expand its operations with at least 400 stores through a mix of acquisitions, and ground-up development of new stores. The integration of Fikes Wholesale, owner of CEFCO Convenience Stores and Casey's largest acquisition to date, demonstrates its capacity to expand through dealmaking. Management said the integration remains ahead of schedule.
#stores #largest
Foodio/Shutterstock.com
Casey's is building on its three-year roadmap which rests on three core pillars. These include acceleration of growth across food and beverage, scaling up its store footprint, and elevating its operational efficiency.
Food remains a major growth enabler for the broader business, with prepared foods and nonalcoholic beverages currently driving the expansion of inside sales. Wings sales within Des Moines market also posted a 20% year-over-year sales jump. This positions the company to benefit from a larger opportunity of ramping up the offerings across roughly 3,000 stores, and cements Casey's reputation as a food destination.
The retailer also plans to expand its operations with at least 400 stores through a mix of acquisitions, and ground-up development of new stores. The integration of Fikes Wholesale, owner of CEFCO Convenience Stores and Casey's largest acquisition to date, demonstrates its capacity to expand through dealmaking. Management said the integration remains ahead of schedule.
#stores #largest


13 days ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributed the significant improvement in adjusted operating income to tariff claim refunds received during the quarter, while also noting gross profit expansion driven by elevated ****** ortment, disciplined sourcing, and improved markdown management.
Retail segment softness was primarily driven by a 200 basis point headwind from seasonal sandals, which suffered from early weather-related challenges and failed to rebound.
The company achieved 150 basis points of core gross margin expansion through disciplined markdown management and elevated ****** ortments, despite operating in a highly promotional market environment.
Brand portfolio growth of 18% was fueled by double-digit wholesale increases, demonstrating the successful scaling of exclusive brands like Topo and Jessica Simpson across multiple distribution channels.
#operating #gross #expansion
Management attributed the significant improvement in adjusted operating income to tariff claim refunds received during the quarter, while also noting gross profit expansion driven by elevated ****** ortment, disciplined sourcing, and improved markdown management.
Retail segment softness was primarily driven by a 200 basis point headwind from seasonal sandals, which suffered from early weather-related challenges and failed to rebound.
The company achieved 150 basis points of core gross margin expansion through disciplined markdown management and elevated ****** ortments, despite operating in a highly promotional market environment.
Brand portfolio growth of 18% was fueled by double-digit wholesale increases, demonstrating the successful scaling of exclusive brands like Topo and Jessica Simpson across multiple distribution channels.
#operating #gross #expansion

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
13 days ago
US stocks sank on Thursday morning as oil prices and Treasury yields continued to climb and investors ******* sed fresh wholesale inflation data.
The Dow Jones Industrial Average (^DJI) fell 0.5%, while the S&P 500 (^GSPC) fell 0.4%. The tech-heavy Nasdaq Composite (^IXIC) dropped 0.5%, with all three indexes deepening losses from the past three days.
Stocks have cooled this week as oil prices topped $105 per barrel after Iran targeted US Navy warships in the latest escalation in the Middle East conflict. The move higher in oil has helped support rising Treasury yields. The 10-year yield (^TNX) hit a three-year high on Wednesday after the Treasury Department announced it would buy up to $6 billion in longer-term debt.
President Trump said Wednesday that oil prices may not come down until after the midterm elections two months away. The ongoing US-Iran war and disruptions in the Strait of Hormuz have raised concerns that an energy shock could flow into broader inflation and all but force the Federal Reserve to raise interest rates.
On Thursday, wholesale inflation data showed producer prices rose on a monthly and yearly basis, largely in line with expectations, setting the stage for the government's consumer inflation report, due out Friday. The Producer Price Index rose 5.4% year-on-year, and 4.6% on a core basis.
#three
The Dow Jones Industrial Average (^DJI) fell 0.5%, while the S&P 500 (^GSPC) fell 0.4%. The tech-heavy Nasdaq Composite (^IXIC) dropped 0.5%, with all three indexes deepening losses from the past three days.
Stocks have cooled this week as oil prices topped $105 per barrel after Iran targeted US Navy warships in the latest escalation in the Middle East conflict. The move higher in oil has helped support rising Treasury yields. The 10-year yield (^TNX) hit a three-year high on Wednesday after the Treasury Department announced it would buy up to $6 billion in longer-term debt.
President Trump said Wednesday that oil prices may not come down until after the midterm elections two months away. The ongoing US-Iran war and disruptions in the Strait of Hormuz have raised concerns that an energy shock could flow into broader inflation and all but force the Federal Reserve to raise interest rates.
On Thursday, wholesale inflation data showed producer prices rose on a monthly and yearly basis, largely in line with expectations, setting the stage for the government's consumer inflation report, due out Friday. The Producer Price Index rose 5.4% year-on-year, and 4.6% on a core basis.
#three


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

16 days ago
On August 6, Xponential Fitness (NYSE:XPOF) reported results for the second quarter ended June 30, and the numbers came in well short of where the boutique-fitness franchisor wanted to be. Revenue fell 13% year over year to $66 million, and the company swung to a net loss of $4.8 million after posting net income in the same period last year. CEO Mike Nuzzo said the quarter came in "below expectations." The bigger story sits in the outlook section, where the company trimmed nearly every full-year target it had set.
Despite the weak headline numbers, Xponential kept adding to its network. The company opened 67 gross new studios and sold 53 franchise licenses during the quarter, a sign that franchisee demand for its brands hasn't disappeared. North America system-wide sales held essentially flat at $437.3 million, which means new locations are offsetting some of the softness at existing studios rather than the whole system contracting. Even after cutting its 2026 targets, the company still expects to open roughly 150 net new studios for the year and generate North America system-wide sales of $1.7 billion to $1.75 billion. Full-year adjusted EBITDA guidance, while lowered, still points to $91 million to $97 million, meaning the business is still projected to be solidly profitable on that measure.
The details underneath the topline number are worse than the revenue decline alone suggests. North America same-store sales fell 6.8%, a sharp reversal from 2.4% growth in the same period a year earlier, and the quarterly run-rate average unit volume dropped to $659,000 from $686,000. Franchise revenue slipped 3% to $44 million on that same-store weakness plus brand divestitures completed in 2025, while equipment revenue dropped 26% to $7.1 million as fewer studio openings and license sales meant fewer installations. Merchandise revenue nearly vanished, falling 90% to $0.5 million as the company shifted from an in-house wholesale model to an outsourced retail arrangement, a transition it admitted came with its own challenges.
Costs moved the wrong direction too, with selling, general and administrative expenses up 33% to $32 million on higher legal expenses, and marketing fund expenses up 29% to $11.4 million. Adjusted EBITDA fell 22% to $21.9 million, and adjusted net income collapsed to $0.8 million from $14.5 million a year earlier. The balance sheet adds another concern, with just $25 million in cash, cash equivalents, and restricted cash against $522.4 million in total long-term debt, and $25.7 million in cash used in operating activities during the quarter. Management responded by cutting full-year revenue guidance to $250 million to $260 million, a 19% decline at the midpoint from 2025 and down from a prior forecast of $260 million to $270 million.
#million #quarter #north #sales
Despite the weak headline numbers, Xponential kept adding to its network. The company opened 67 gross new studios and sold 53 franchise licenses during the quarter, a sign that franchisee demand for its brands hasn't disappeared. North America system-wide sales held essentially flat at $437.3 million, which means new locations are offsetting some of the softness at existing studios rather than the whole system contracting. Even after cutting its 2026 targets, the company still expects to open roughly 150 net new studios for the year and generate North America system-wide sales of $1.7 billion to $1.75 billion. Full-year adjusted EBITDA guidance, while lowered, still points to $91 million to $97 million, meaning the business is still projected to be solidly profitable on that measure.
The details underneath the topline number are worse than the revenue decline alone suggests. North America same-store sales fell 6.8%, a sharp reversal from 2.4% growth in the same period a year earlier, and the quarterly run-rate average unit volume dropped to $659,000 from $686,000. Franchise revenue slipped 3% to $44 million on that same-store weakness plus brand divestitures completed in 2025, while equipment revenue dropped 26% to $7.1 million as fewer studio openings and license sales meant fewer installations. Merchandise revenue nearly vanished, falling 90% to $0.5 million as the company shifted from an in-house wholesale model to an outsourced retail arrangement, a transition it admitted came with its own challenges.
Costs moved the wrong direction too, with selling, general and administrative expenses up 33% to $32 million on higher legal expenses, and marketing fund expenses up 29% to $11.4 million. Adjusted EBITDA fell 22% to $21.9 million, and adjusted net income collapsed to $0.8 million from $14.5 million a year earlier. The balance sheet adds another concern, with just $25 million in cash, cash equivalents, and restricted cash against $522.4 million in total long-term debt, and $25.7 million in cash used in operating activities during the quarter. Management responded by cutting full-year revenue guidance to $250 million to $260 million, a 19% decline at the midpoint from 2025 and down from a prior forecast of $260 million to $270 million.
#million #quarter #north #sales


19 days ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Zegna brand performance is driven by 'high-quality growth,' capturing market share through a unique position in China and strength in core categories like knitwear and shoes.
The group is aggressively shifting toward a Direct-to-Consumer (DTC) model, with DTC now representing 86% of branded revenues, which supports higher gross margins despite currency headwinds.
Thom Browne is undergoing a structural transformation from a wholesale-driven model to a retail-oriented culture, involving a significant reduction and upgrade of the wholesale network.
TOM FORD Fashion is seeing improved fixed-cost absorption through revenue growth and disciplined cost management as it builds brand awareness.
#driven #model #NVIDIA #zegna
Zegna brand performance is driven by 'high-quality growth,' capturing market share through a unique position in China and strength in core categories like knitwear and shoes.
The group is aggressively shifting toward a Direct-to-Consumer (DTC) model, with DTC now representing 86% of branded revenues, which supports higher gross margins despite currency headwinds.
Thom Browne is undergoing a structural transformation from a wholesale-driven model to a retail-oriented culture, involving a significant reduction and upgrade of the wholesale network.
TOM FORD Fashion is seeing improved fixed-cost absorption through revenue growth and disciplined cost management as it builds brand awareness.
#driven #model #NVIDIA #zegna

19 days ago
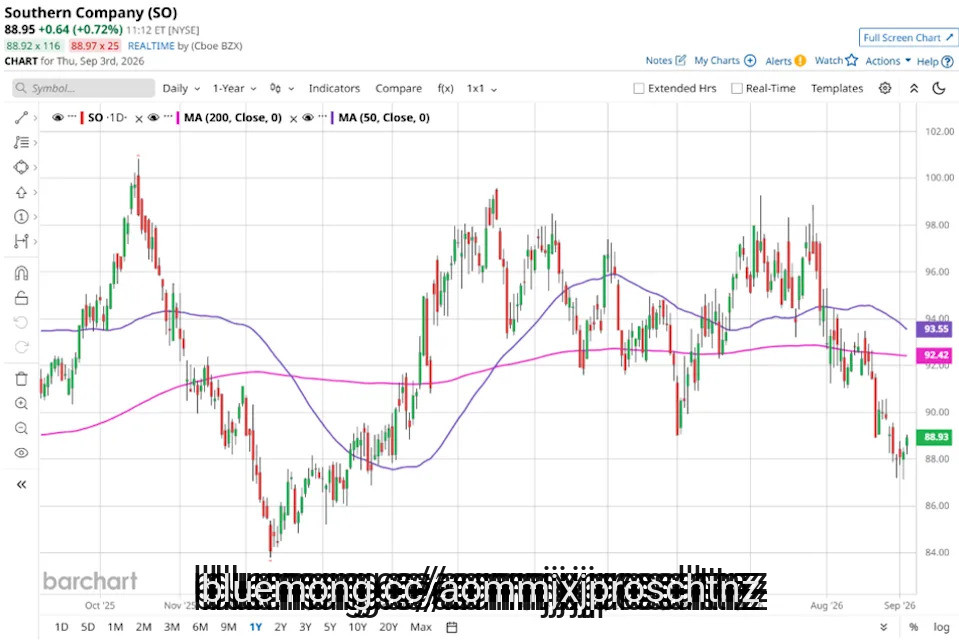
Atlanta, Georgia-based The Southern Company (SO) generates, transmits, and distributes electricity. Valued at $101.6 billion by market cap, the company also offers wireless telecommunications services, provides businesses with two-way radio, telephone, paging, and internet access services, and wholesales fiber optic solutions.
Companies worth $10 billion or more are generally described as "large-cap stocks," and SO definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the utilities - regulated electric industry. SO has a robust foundation, with strong finances, a skilled workforce, and extensive infrastructure, including power plants and transmission lines. The company's expertise in navigating complex regulatory environments and influencing energy policy is a key ***** et.
A Potential ***** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
Fears of an Extended US-Iran Conflict Boost Crude Oil Prices
Nat-Gas Prices Rise on Hotter US Weather and Expectations of Smaller Storage
#company #market #Services #atlanta
Companies worth $10 billion or more are generally described as "large-cap stocks," and SO definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the utilities - regulated electric industry. SO has a robust foundation, with strong finances, a skilled workforce, and extensive infrastructure, including power plants and transmission lines. The company's expertise in navigating complex regulatory environments and influencing energy policy is a key ***** et.
A Potential ***** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
Fears of an Extended US-Iran Conflict Boost Crude Oil Prices
Nat-Gas Prices Rise on Hotter US Weather and Expectations of Smaller Storage
#company #market #Services #atlanta


19 days ago
With a market cap of $138.2 billion, Bristol-Myers Squibb Company (BMY) is a global biopharmaceutical company that discovers, develops, manufactures, and markets innovative medicines worldwide. Its portfolio spans key therapeutic areas including oncology, hematology, immunology, cardiovascular disease, and neuroscience, with well-known products such as Opdivo, Eliquis, Revlimid, and Yervoy.
Companies valued at $10 billion or more are generally classified as "large-cap" stocks, and Bristol-Myers Squibb fits this criterion perfectly. The company serves patients through a broad commercial network that includes wholesalers, distributors, specialty pharmacies, hospitals, clinics, and government agencies.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ***** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#company #bristol #squibb #Stock
Companies valued at $10 billion or more are generally classified as "large-cap" stocks, and Bristol-Myers Squibb fits this criterion perfectly. The company serves patients through a broad commercial network that includes wholesalers, distributors, specialty pharmacies, hospitals, clinics, and government agencies.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ***** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#company #bristol #squibb #Stock


19 days ago
Revolution Medicines, Inc. (NASDAQ:RVMD) received FDA approval for Rasonque, or daraxonrasib, following an expedited review. The once-daily oral RAS inhibitor is approved for adults with metastatic pancreatic adenocarcinoma who have received at least one prior systemic therapy or are not candidates for multiagent systemic therapy.
Revolution Medicines, Inc. (NASDAQ:RVMD) set a wholesale acquisition cost (WAC) of $39,800 for a 30-day supply. Twelve 30-day supplies would total $477,600 at WAC before discounts, rebates, or ******* istance. Rasonque is available in the United States, with (ON)Path offering insurance navigation and financial-assistance resources, including copay support for eligible commercially insured patients.
The approval was based on RASolute 302, a randomized Phase 3 trial involving 500 patients with previously treated metastatic pancreatic adenocarcinoma. In the overall population, median overall survival reached 13.2 months with Rasonque versus 6.7 months with chemotherapy. The hazard ratio of 0.40 represented a 60% lower hazard of death during trial follow-up. Median progression-free survival was 7.2 months versus 3.6 months, while objective response rates were 30% and 11%, respectively.
The survival benefit gives Rasonque a strong clinical argument for reimbursement. Pancreatic cancer is aggressive, treatment options after progression are limited, and Rasonque improved overall survival, progression-free survival, and response rates in a randomized comparison. Oral dosing may also reduce the burden of intravenous chemotherapy.
The approved population is broader than a single mutation-defined subgroup. Rasonque can be prescribed with or without an identified RAS tumor mutation and does not require a companion diagnostic. That reduces testing friction within the approved treatment setting.
#months #pancreatic #progression #medicines
Revolution Medicines, Inc. (NASDAQ:RVMD) set a wholesale acquisition cost (WAC) of $39,800 for a 30-day supply. Twelve 30-day supplies would total $477,600 at WAC before discounts, rebates, or ******* istance. Rasonque is available in the United States, with (ON)Path offering insurance navigation and financial-assistance resources, including copay support for eligible commercially insured patients.
The approval was based on RASolute 302, a randomized Phase 3 trial involving 500 patients with previously treated metastatic pancreatic adenocarcinoma. In the overall population, median overall survival reached 13.2 months with Rasonque versus 6.7 months with chemotherapy. The hazard ratio of 0.40 represented a 60% lower hazard of death during trial follow-up. Median progression-free survival was 7.2 months versus 3.6 months, while objective response rates were 30% and 11%, respectively.
The survival benefit gives Rasonque a strong clinical argument for reimbursement. Pancreatic cancer is aggressive, treatment options after progression are limited, and Rasonque improved overall survival, progression-free survival, and response rates in a randomized comparison. Oral dosing may also reduce the burden of intravenous chemotherapy.
The approved population is broader than a single mutation-defined subgroup. Rasonque can be prescribed with or without an identified RAS tumor mutation and does not require a companion diagnostic. That reduces testing friction within the approved treatment setting.
#months #pancreatic #progression #medicines

19 days ago
On September 3, Ermenegildo Zegna Group (NYSE:ZGN) reported first-half revenues of €987.3 million, up 6.4% year over year and 9.3% on an organic basis. Direct-to-consumer sales did nearly all the work, climbing 15.8% organically and now making up 86% of branded revenue. But headline profit told a rougher story, sliding to €28.4 million from €47.9 million a year earlier. The gap between a business growing almost everywhere that matters and a bottom line moving the other direction is what investors now have to untangle.
The clearest strength in the first half of 2026 is how much of Zegna's growth is coming from channels it controls directly. Direct-to-consumer revenue grew 12.1% as reported and 15.8% organically, while the Group deliberately shrank its wholesale business by 14.6% as it keeps trimming third-party accounts. The Zegna segment, which houses the flagship ZEGNA brand along with Textile, generated €724.3 million in revenue, up 9.7% year over year, with the ZEGNA brand itself growing 13.9% organically to €634.6 million. That segment's Adjusted EBIT Margin rose 50 basis points to 14.8%, driven by higher sales per square meter and better sell-through in its own stores.
Group-wide Adjusted EBIT rose to €74.5 million from €68.7 million, pushing the margin to 7.5%. The balance sheet moved in the right direction too, with the net cash surplus climbing to €59.6 million at June 30 from €52.1 million at December 31, 2025. Free cash flow flipped to a positive €19.2 million, compared with a negative €23.1 million a year earlier, helped by stronger operating cash flow and tighter working capital management. Even Tom Ford Fashion, still unprofitable, cut its Adjusted EBIT loss to €12.1 million from €19.4 million, a sign the newer brand is moving toward breakeven rather than away from it.
The drop in profit isn't just optics. H1 2025's €47.9 million figure included a €27.8 million non-cash gain from remeasuring non-controlling interest put option liabilities, a boost that didn't repeat this year. On top of that, the effective tax rate jumped to 38.8% from 29.6%, and the combined swing in financial expenses and foreign exchange moved to a negative €22.7 million from a positive €6.0 million. Together, those items explain most of the gap between a profit margin of 2.9% this year and 5.2% last year, even as operating profit itself improved to €68.5 million from €61.3 million.
Thom Browne is the segment causing the most concern. Revenue there fell 4.9% year over year to €123.1 million, and Adjusted EBIT swung to a loss of €8.3 million from a profit of €4.5 million, which the company attributed to foreign exchange pressure and investment in shifting the brand toward a retail-first model. Capital expenditure also climbed to €64 million from €54 million, largely tied to a new shoe production plant in Parma, and corporate costs rose to €12 million from €10.7 million as the Group builds out its structure.
#million
The clearest strength in the first half of 2026 is how much of Zegna's growth is coming from channels it controls directly. Direct-to-consumer revenue grew 12.1% as reported and 15.8% organically, while the Group deliberately shrank its wholesale business by 14.6% as it keeps trimming third-party accounts. The Zegna segment, which houses the flagship ZEGNA brand along with Textile, generated €724.3 million in revenue, up 9.7% year over year, with the ZEGNA brand itself growing 13.9% organically to €634.6 million. That segment's Adjusted EBIT Margin rose 50 basis points to 14.8%, driven by higher sales per square meter and better sell-through in its own stores.
Group-wide Adjusted EBIT rose to €74.5 million from €68.7 million, pushing the margin to 7.5%. The balance sheet moved in the right direction too, with the net cash surplus climbing to €59.6 million at June 30 from €52.1 million at December 31, 2025. Free cash flow flipped to a positive €19.2 million, compared with a negative €23.1 million a year earlier, helped by stronger operating cash flow and tighter working capital management. Even Tom Ford Fashion, still unprofitable, cut its Adjusted EBIT loss to €12.1 million from €19.4 million, a sign the newer brand is moving toward breakeven rather than away from it.
The drop in profit isn't just optics. H1 2025's €47.9 million figure included a €27.8 million non-cash gain from remeasuring non-controlling interest put option liabilities, a boost that didn't repeat this year. On top of that, the effective tax rate jumped to 38.8% from 29.6%, and the combined swing in financial expenses and foreign exchange moved to a negative €22.7 million from a positive €6.0 million. Together, those items explain most of the gap between a profit margin of 2.9% this year and 5.2% last year, even as operating profit itself improved to €68.5 million from €61.3 million.
Thom Browne is the segment causing the most concern. Revenue there fell 4.9% year over year to €123.1 million, and Adjusted EBIT swung to a loss of €8.3 million from a profit of €4.5 million, which the company attributed to foreign exchange pressure and investment in shifting the brand toward a retail-first model. Capital expenditure also climbed to €64 million from €54 million, largely tied to a new shoe production plant in Parma, and corporate costs rose to €12 million from €10.7 million as the Group builds out its structure.
#million

20 days ago
Yes, there is such a thing as a good 5-5 start – at least for now, considering how insane it is to try figuring out all these teams with mostly new players.
What's so good about it? Going 3-2 yesterday was fine, and over the first two runs, one loss was that horrific Hawaii beat against Stanford, another came in the final seconds of Illinois-UAB, and then there's the whopper – thinking Rutgers would destroy UMass. Historically shocking whiff, cap tipped, moving on.
There aren't many options for the Friday games, but let's force down an appetizer before the smorgasbord on Saturday.
Last Week's Results: 5-5
– All the Week 1 Picks
– Week 1 Expert Picks
Line: Point Total 46.5
ATS Pick: Under
This is one of those picks to see if we have our in-season game legs early on. Seriously, feel free to ignore this one, because it's a little dangerous.
Both teams have new coaching staffs, new ideas, and wholesale personnel changes. That, and 46.5 isn't all that hard to hit – the original call to make this one of the games was when the total was 49.5.
Again, I'm flying a bit blind here, but it's Pat Fitzgerald with a pieced-together team. It'll be about the defense and running game. Mike Jacobs' Toledo side will keep the chains moving and the clock rolling. This should be a good, tough fight.
– Toledo vs Michigan State Game Preview
Line: Kansas -41.5
ATS Pick: Kansas
It's a small sample size, but one key mini-trend isn't shocking – with the exception of Buffalo against Albany, FBS teams are annihilating the FCSers.
Utah 66, Idaho 14
UCF 73, Bethune-Cookman 6
Missouri 54, UAPB 14
Delaware 42, Merrimack 7
Kennesaw State 47, West Georgia 0 (I LOVED this and chickened out yesterday, not making this one of the five best picks)
Minnesota 59, Eastern Illinois 7
I never change our call on the predicted final score in our game previews unless something insane happens, but Kansas big at home against LIU – partly because it'll likely go full throttle for a full 60 minutes – was the call from the start. If anything, we were probably too conservative on what the Jayhawks will do.
– LIU vs Kansas Game Preview
Sticking with that FBS blowout over FCS thing …
Line: Purdue -35.5, o/u: 55.5
ATS Pick: Purdue
There's no need to do a deep dive here. Purdue has a brutal schedule ahead, it's been a rough run over the last few years, and the coaches will keep pushing because the program has to set a new tone. Purdue beat Indiana State 49-0 in 2024, and Indiana slipped past the Sycamores by 73 last year.
– Indiana State vs Purdue Game Preview
Line: Point Total 47.5
ATS Pick: Over
Two things are in play here. First, the Stanford defense didn't look like anything special once the Hawaii offense got rolling in the 37-27 Cardinal win. There's a real chance Miami takes care of most of the total on its own.
Here's the second part – the line is 24.5. In the six games last year when Miami won by more than that, all but the 38-7 win over Pi
What's so good about it? Going 3-2 yesterday was fine, and over the first two runs, one loss was that horrific Hawaii beat against Stanford, another came in the final seconds of Illinois-UAB, and then there's the whopper – thinking Rutgers would destroy UMass. Historically shocking whiff, cap tipped, moving on.
There aren't many options for the Friday games, but let's force down an appetizer before the smorgasbord on Saturday.
Last Week's Results: 5-5
– All the Week 1 Picks
– Week 1 Expert Picks
Line: Point Total 46.5
ATS Pick: Under
This is one of those picks to see if we have our in-season game legs early on. Seriously, feel free to ignore this one, because it's a little dangerous.
Both teams have new coaching staffs, new ideas, and wholesale personnel changes. That, and 46.5 isn't all that hard to hit – the original call to make this one of the games was when the total was 49.5.
Again, I'm flying a bit blind here, but it's Pat Fitzgerald with a pieced-together team. It'll be about the defense and running game. Mike Jacobs' Toledo side will keep the chains moving and the clock rolling. This should be a good, tough fight.
– Toledo vs Michigan State Game Preview
Line: Kansas -41.5
ATS Pick: Kansas
It's a small sample size, but one key mini-trend isn't shocking – with the exception of Buffalo against Albany, FBS teams are annihilating the FCSers.
Utah 66, Idaho 14
UCF 73, Bethune-Cookman 6
Missouri 54, UAPB 14
Delaware 42, Merrimack 7
Kennesaw State 47, West Georgia 0 (I LOVED this and chickened out yesterday, not making this one of the five best picks)
Minnesota 59, Eastern Illinois 7
I never change our call on the predicted final score in our game previews unless something insane happens, but Kansas big at home against LIU – partly because it'll likely go full throttle for a full 60 minutes – was the call from the start. If anything, we were probably too conservative on what the Jayhawks will do.
– LIU vs Kansas Game Preview
Sticking with that FBS blowout over FCS thing …
Line: Purdue -35.5, o/u: 55.5
ATS Pick: Purdue
There's no need to do a deep dive here. Purdue has a brutal schedule ahead, it's been a rough run over the last few years, and the coaches will keep pushing because the program has to set a new tone. Purdue beat Indiana State 49-0 in 2024, and Indiana slipped past the Sycamores by 73 last year.
– Indiana State vs Purdue Game Preview
Line: Point Total 47.5
ATS Pick: Over
Two things are in play here. First, the Stanford defense didn't look like anything special once the Hawaii offense got rolling in the 37-27 Cardinal win. There's a real chance Miami takes care of most of the total on its own.
Here's the second part – the line is 24.5. In the six games last year when Miami won by more than that, all but the 38-7 win over Pi
21 days ago
Shell has agreed to take full control of U.S. convenience store operator and fuel distributor Tri Star Energy, in a transaction that will more than double the energy major's company-owned convenience retail footprint in the United States.
Equilon Enterprises, which operates as Shell Oil Products US, will increase its ownership of Nashville-based Tri Star from 33% to 100%. The acquisition includes 320 fuel and convenience retail sites in Tennessee and surrounding states, along with fuel-supply agreements covering another 552 dealer-owned locations. Financial terms were not disclosed.
Shell is acquiring the remaining interest from The Parman Corporation, Kimbro Oil Company and their subsidiaries. The deal is expected to close by the end of 2026, subject to regulatory approval and customary closing conditions.
The transaction represents a substantial expansion of Shell's directly controlled retail operations. While Shell already has around 12,000 branded fuel and convenience sites across 49 U.S. states, the vast majority are operated by wholesalers or dealers rather than owned directly by the company. Shell says its U.S. network serves more than 7 million customers per day.
Following completion, Tri Star will be operated by Texas Petroleum Group, a wholly owned unit of Shell Mobility & Convenience US. Shell expects the combined business to have nearly 550 company-owned convenience retail locations and supply agreements with around 650 dealer-owned sites across the southern United States.
Tri Star, founded in 2000, operates convenience-store brands including Twice Daily, Sudden Service and Little General and also owns the White Bison Coffee brand. Its wholesale fuel operation reaches multiple states, giving Shell additional exposure to both fuel distribution and higher-margin convenience and food-and-beverage sales.
#shell #convenience #retail
Equilon Enterprises, which operates as Shell Oil Products US, will increase its ownership of Nashville-based Tri Star from 33% to 100%. The acquisition includes 320 fuel and convenience retail sites in Tennessee and surrounding states, along with fuel-supply agreements covering another 552 dealer-owned locations. Financial terms were not disclosed.
Shell is acquiring the remaining interest from The Parman Corporation, Kimbro Oil Company and their subsidiaries. The deal is expected to close by the end of 2026, subject to regulatory approval and customary closing conditions.
The transaction represents a substantial expansion of Shell's directly controlled retail operations. While Shell already has around 12,000 branded fuel and convenience sites across 49 U.S. states, the vast majority are operated by wholesalers or dealers rather than owned directly by the company. Shell says its U.S. network serves more than 7 million customers per day.
Following completion, Tri Star will be operated by Texas Petroleum Group, a wholly owned unit of Shell Mobility & Convenience US. Shell expects the combined business to have nearly 550 company-owned convenience retail locations and supply agreements with around 650 dealer-owned sites across the southern United States.
Tri Star, founded in 2000, operates convenience-store brands including Twice Daily, Sudden Service and Little General and also owns the White Bison Coffee brand. Its wholesale fuel operation reaches multiple states, giving Shell additional exposure to both fuel distribution and higher-margin convenience and food-and-beverage sales.
#shell #convenience #retail
21 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Why we like it: Our top Bank of America card pick excels across several categories. It has no annual fee and a great 0% introductory APR period, which you can use for both new purchases and balance transfers. But it's also an all-around solid cash-back card. You can earn 3% cash back on your choice category (6% for the first year) plus 2% cash back at grocery stores and wholesale clubs, up to a combined $2,500 spent each quarter. Everything else earns 1% cash back.
Choice category options cover plenty of common purchases: gas and EV charging stations, online shopping (including cable, internet, phone plans, and streaming), dining, travel, drugstores and pharmacies, or home improvement and furnishings. Having multiple rewards category options can give you more flexibility, especially as your spending habits change over time.
Read our full review of the Bank of America Customized Cash Rewards credit card.
#bank #choice #rewards
Why we like it: Our top Bank of America card pick excels across several categories. It has no annual fee and a great 0% introductory APR period, which you can use for both new purchases and balance transfers. But it's also an all-around solid cash-back card. You can earn 3% cash back on your choice category (6% for the first year) plus 2% cash back at grocery stores and wholesale clubs, up to a combined $2,500 spent each quarter. Everything else earns 1% cash back.
Choice category options cover plenty of common purchases: gas and EV charging stations, online shopping (including cable, internet, phone plans, and streaming), dining, travel, drugstores and pharmacies, or home improvement and furnishings. Having multiple rewards category options can give you more flexibility, especially as your spending habits change over time.
Read our full review of the Bank of America Customized Cash Rewards credit card.
#bank #choice #rewards



21 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Why we like it: Our top Bank of America card pick excels across several categories. It has no annual fee and a great 0% introductory APR period, which you can use for both new purchases and balance transfers. But it's also an all-around solid cash-back card. You can earn 3% cash back on your choice category (6% for the first year) plus 2% cash back at grocery stores and wholesale clubs, up to a combined $2,500 spent each quarter. Everything else earns 1% cash back.
Choice category options cover plenty of common purchases: gas and EV charging stations, online shopping (including cable, internet, phone plans, and streaming), dining, travel, drugstores and pharmacies, or home improvement and furnishings. Having multiple rewards category options can give you more flexibility, especially as your spending habits change over time.
Read our full review of the Bank of America Customized Cash Rewards credit card.
#cash #bank #rewards #options
Why we like it: Our top Bank of America card pick excels across several categories. It has no annual fee and a great 0% introductory APR period, which you can use for both new purchases and balance transfers. But it's also an all-around solid cash-back card. You can earn 3% cash back on your choice category (6% for the first year) plus 2% cash back at grocery stores and wholesale clubs, up to a combined $2,500 spent each quarter. Everything else earns 1% cash back.
Choice category options cover plenty of common purchases: gas and EV charging stations, online shopping (including cable, internet, phone plans, and streaming), dining, travel, drugstores and pharmacies, or home improvement and furnishings. Having multiple rewards category options can give you more flexibility, especially as your spending habits change over time.
Read our full review of the Bank of America Customized Cash Rewards credit card.
#cash #bank #rewards #options



22 days ago
Peter Lynch built an impressive track record as the fund manager for Fidelity's Magellan Fund. Under his stewardship, from 1977 to 1990, the fund beat the S&P 500 index in 11 out of the 13 years. And it produced an impressive 29% average annual return.
Fortunately, Lynch shares his wisdom in a book called One Up on Wall Street. He describes his philosophy, which is buy what you know, research the company's fundamentals, and plan to make a long-term commitment.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
With this in mind, here are two consumer goods companies that fit the bill.
Many people continue to shop at Costco Wholesale's (NASDAQ: COST) giant warehouses. If you've ever gone into one, you can usually see a crowd.
#NVIDIA #fund #flashing #years
Fortunately, Lynch shares his wisdom in a book called One Up on Wall Street. He describes his philosophy, which is buy what you know, research the company's fundamentals, and plan to make a long-term commitment.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
With this in mind, here are two consumer goods companies that fit the bill.
Many people continue to shop at Costco Wholesale's (NASDAQ: COST) giant warehouses. If you've ever gone into one, you can usually see a crowd.
#NVIDIA #fund #flashing #years

22 days ago
Juno Beach, Florida-based NextEra Energy, Inc. (NEE) generates, stores, transmits, distributes, and sells electric power to retail and wholesale customers in North America. The company has a market cap of $170.7 billion and operates through Florida Power & Light Company (FPL) and NEER segments. NextEra generates electricity from wind, solar, nuclear, natural gas, and other clean energy ******* ets.
Companies with a market cap of $10 billion or more are typically referred to as "large-cap stocks." NEE fits squarely into that category, with its market cap exceeding this threshold and reflecting its substantial size and influence in the regulated electric utilities industry.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#Florida #fans #palantir
Companies with a market cap of $10 billion or more are typically referred to as "large-cap stocks." NEE fits squarely into that category, with its market cap exceeding this threshold and reflecting its substantial size and influence in the regulated electric utilities industry.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#Florida #fans #palantir

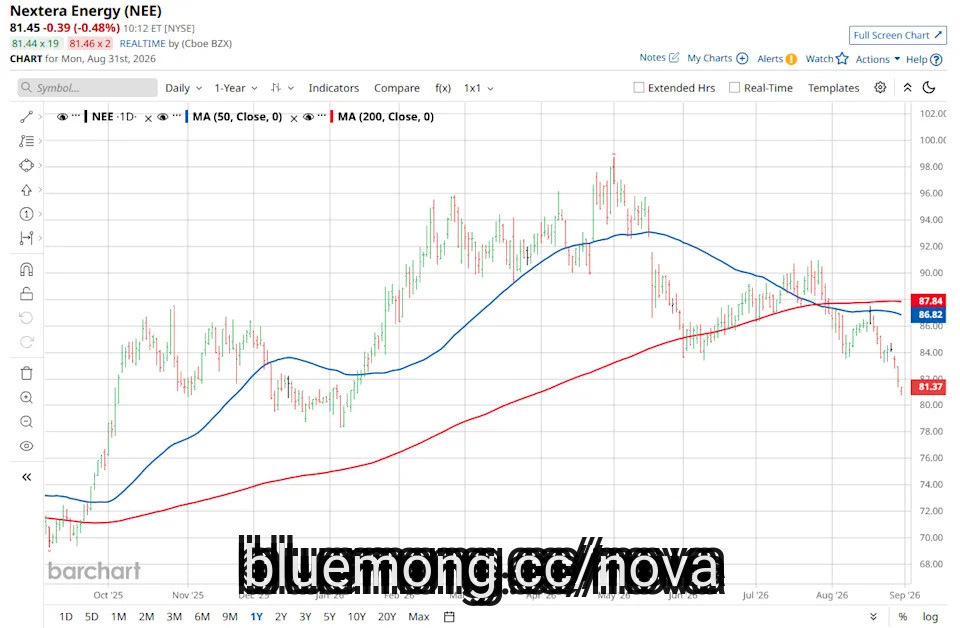
22 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Why we like it: Our top Bank of America card pick excels across several categories. It has no annual fee and a great 0% introductory APR period, which you can use for both new purchases and balance transfers. But it's also an all-around solid cash-back card. You can earn 3% cash back on your choice category (6% for the first year) plus 2% cash back at grocery stores and wholesale clubs, up to a combined $2,500 spent each quarter. Everything else earns 1% cash back.
Choice category options cover plenty of common purchases: gas and EV charging stations, online shopping (including cable, internet, phone plans, and streaming), dining, travel, drugstores and pharmacies, or home improvement and furnishings. Having multiple rewards category options can give you more flexibility, especially as your spending habits change over time.
Read our full review of the Bank of America Customized Cash Rewards credit card.
#cash #back #America #rewards
Why we like it: Our top Bank of America card pick excels across several categories. It has no annual fee and a great 0% introductory APR period, which you can use for both new purchases and balance transfers. But it's also an all-around solid cash-back card. You can earn 3% cash back on your choice category (6% for the first year) plus 2% cash back at grocery stores and wholesale clubs, up to a combined $2,500 spent each quarter. Everything else earns 1% cash back.
Choice category options cover plenty of common purchases: gas and EV charging stations, online shopping (including cable, internet, phone plans, and streaming), dining, travel, drugstores and pharmacies, or home improvement and furnishings. Having multiple rewards category options can give you more flexibility, especially as your spending habits change over time.
Read our full review of the Bank of America Customized Cash Rewards credit card.
#cash #back #America #rewards


23 days ago
NEW DELHI: Former Pakistan captain Misbah-ul-Haq has offered his resignation from the Pakistan Cricket Board's (PCB) national selection committee, adding another dramatic twist to the turmoil surrounding the Test side after a sweeping overhaul of the squad and coaching staff.
According to Geo News, sources close to Misbah said the former cricketer had informed the PCB of his decision and would serve a notice period before formally stepping down. Cricinfo also reported that Misbah had offered his resignation, although the PCB is yet to accept it.
The development comes just a day after the PCB announced wholesale changes to the Pakistan Test squad and coaching staff following the team's heavy 194-run defeat to England at Lord's.
The timing of Misbah's decision has raised questions over the selection committee's role in the PCB's latest overhaul. According to the reports, Misbah was apparently not consulted despite being part of the national selection committee when the board decided to make major changes to the squad and coaching staff.
The PCB released seven players from the Test squad ahead of the third Test against England at Edgbaston, starting September 9. Mohammad Rizwan, Imam-ul-Haq, Salman Ali Agha, Ali Usman, Aamer Jamal, Awais Zafar and Khurram Shahzad were among those released.
Sarfaraz Ahmed and Umar Gul were also removed as head coach and bowling coach respectively.
The PCB subsequently brought in white-ball head coach Mike Hesson and bowling coach Ashley Noffke to work with the Test side for the remainder of the England tour.
Cricinfo further reported that Misbah has decided to step down from his role as a batting consultant at the National Cricket Academy in Lahore, where his contract required him to work for 180 days a year.
The extent of Pakistan's overhaul was further highlighted by the inclusion of five uncapped players in the squad for the third Test.
Arafat Minhas, Mohammad Imran Jnr, Saad Baig, Mohammad Imran Randhawa and Razaullah have been added, while Saim Ayub and Abdullah Fazal have also been brought into the group. The latter two have a combined experience of only 10 Test matches.
The sweeping changes followed Pakistan's innings-and-103-run defeat in the first Test before England won the second by 194 runs. The back-to-back defeats left Pakistan 0-2 down in the three-match series and staring at a potential 3-0 clean sweep.
Misbah was appointed to the four-member national selection committee in March alongside Aaqib Javed, Sarfaraz Ahmed and Asad Shafiq.
The former captain has previously held several senior positions within the PCB. He was appointed head coach and chief selector in 2019, before stepping down as chief selector in October 2020 and eventually leaving the head coach's position in 2021.
He returned to the PCB setup as an adviser in 2023 under the then ad hoc management committee headed by Zaka Ashraf. He was later appointed one of five mentors for the men's Champions Cup and al
According to Geo News, sources close to Misbah said the former cricketer had informed the PCB of his decision and would serve a notice period before formally stepping down. Cricinfo also reported that Misbah had offered his resignation, although the PCB is yet to accept it.
The development comes just a day after the PCB announced wholesale changes to the Pakistan Test squad and coaching staff following the team's heavy 194-run defeat to England at Lord's.
The timing of Misbah's decision has raised questions over the selection committee's role in the PCB's latest overhaul. According to the reports, Misbah was apparently not consulted despite being part of the national selection committee when the board decided to make major changes to the squad and coaching staff.
The PCB released seven players from the Test squad ahead of the third Test against England at Edgbaston, starting September 9. Mohammad Rizwan, Imam-ul-Haq, Salman Ali Agha, Ali Usman, Aamer Jamal, Awais Zafar and Khurram Shahzad were among those released.
Sarfaraz Ahmed and Umar Gul were also removed as head coach and bowling coach respectively.
The PCB subsequently brought in white-ball head coach Mike Hesson and bowling coach Ashley Noffke to work with the Test side for the remainder of the England tour.
Cricinfo further reported that Misbah has decided to step down from his role as a batting consultant at the National Cricket Academy in Lahore, where his contract required him to work for 180 days a year.
The extent of Pakistan's overhaul was further highlighted by the inclusion of five uncapped players in the squad for the third Test.
Arafat Minhas, Mohammad Imran Jnr, Saad Baig, Mohammad Imran Randhawa and Razaullah have been added, while Saim Ayub and Abdullah Fazal have also been brought into the group. The latter two have a combined experience of only 10 Test matches.
The sweeping changes followed Pakistan's innings-and-103-run defeat in the first Test before England won the second by 194 runs. The back-to-back defeats left Pakistan 0-2 down in the three-match series and staring at a potential 3-0 clean sweep.
Misbah was appointed to the four-member national selection committee in March alongside Aaqib Javed, Sarfaraz Ahmed and Asad Shafiq.
The former captain has previously held several senior positions within the PCB. He was appointed head coach and chief selector in 2019, before stepping down as chief selector in October 2020 and eventually leaving the head coach's position in 2021.
He returned to the PCB setup as an adviser in 2023 under the then ad hoc management committee headed by Zaka Ashraf. He was later appointed one of five mentors for the men's Champions Cup and al


