

18 hours ago
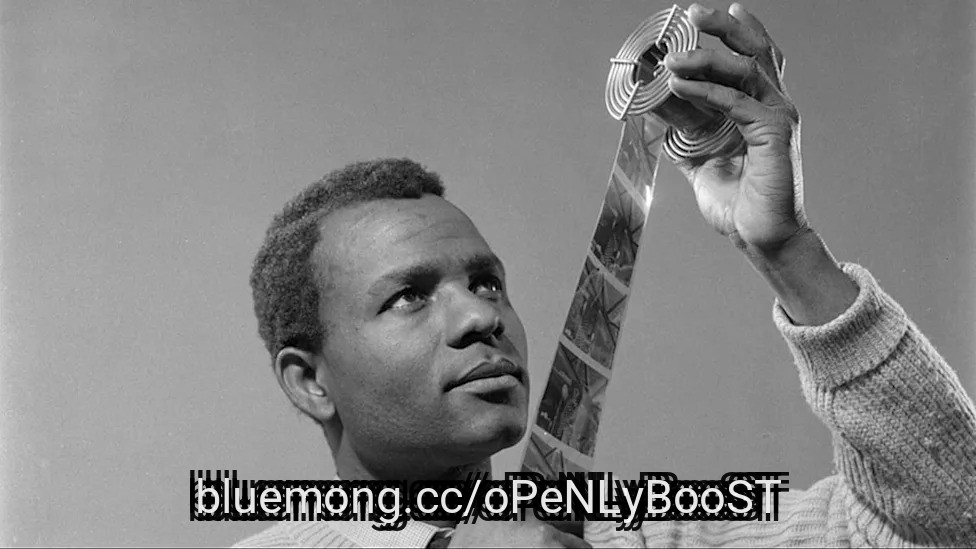
James Barnor is no stranger to big moments.
When Ghana declared independence in 1957, he was there with his camera. In 1960s London, he challenged stereotypes of Black models and artists with photographs for Drum magazine. In 1970, he established Ghana's first colour-processing laboratory.
Now aged 97, he is receiving one of photography's top honours.
The World Photography Organisation has revealed that Barnor will receive the Outstanding Contribution to Photography award at the 2027 Sony World Photography Awards.
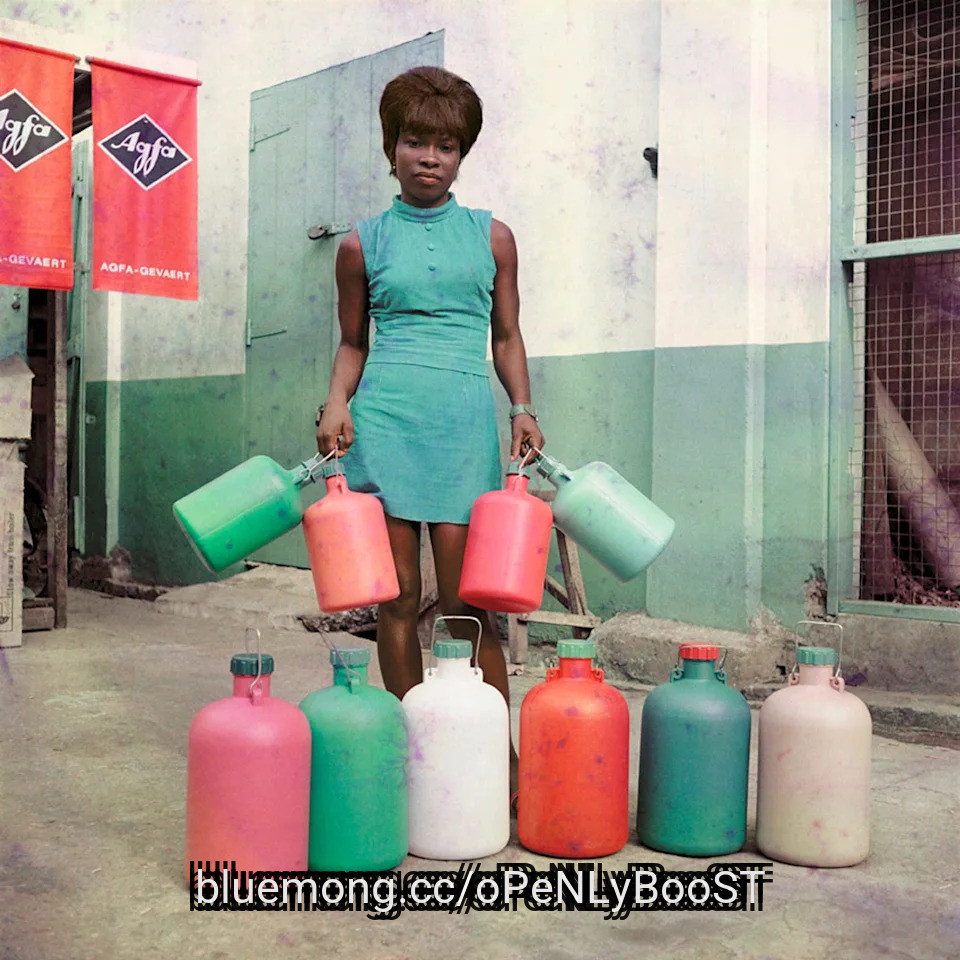
James Barnor, Untitled #2 , Two friends dressed for a church celebration, Accra, 1970s - James Barnor / Courtesy Galerie Clémentine de la Féronnière
#World #ghana #black #outstanding
When Ghana declared independence in 1957, he was there with his camera. In 1960s London, he challenged stereotypes of Black models and artists with photographs for Drum magazine. In 1970, he established Ghana's first colour-processing laboratory.
Now aged 97, he is receiving one of photography's top honours.
The World Photography Organisation has revealed that Barnor will receive the Outstanding Contribution to Photography award at the 2027 Sony World Photography Awards.
James Barnor, Untitled #2 , Two friends dressed for a church celebration, Accra, 1970s - James Barnor / Courtesy Galerie Clémentine de la Féronnière
#World #ghana #black #outstanding

1 month ago
Three decades ago, the advent and proliferation of the internet lit a fire under Wall Street's major indexes. Today, the artificial intelligence (AI) infrastructure build-out is stoking the same enthusiasm and fueling a multitrillion-dollar addressable opportunity.
Though dozens of tech-driven companies are benefiting from the AI revolution, Nvidia (NASDAQ:NVDA), Palantir Technologies (NASDAQ:PLTR), and Google parent Alphabet (NASDAQ:GOOGL)(NASDAQ:GOOG) are at the forefront of this game-changing technology.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nvidia's graphics processing units hold a virtual monopoly in AI-accelerated data centers, making it one of the most widely held stocks among retail investors.
Image source: Getty Images.
#NVIDIA #three #nvda
Though dozens of tech-driven companies are benefiting from the AI revolution, Nvidia (NASDAQ:NVDA), Palantir Technologies (NASDAQ:PLTR), and Google parent Alphabet (NASDAQ:GOOGL)(NASDAQ:GOOG) are at the forefront of this game-changing technology.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nvidia's graphics processing units hold a virtual monopoly in AI-accelerated data centers, making it one of the most widely held stocks among retail investors.
Image source: Getty Images.
#NVIDIA #three #nvda


1 month ago
The FDA said two samples tested positive for the parasite.
The Food and Drug Administration (FDA) said on Friday it has found a potential source of the cyclosporiasis outbreak that was tied to lettuce over the summer.
The agency collected samples during its onsite inspections of Taylor Farms de Mexico facilities, it said.
Two samples tested positive for the parasite, Cyclospora, according to the FDA. One positive sample was from a tank that held outgoing wastewater from a processing facility, the agency said. The second positive sample was from a drainage ditch of an iceberg lettuce grower, it noted.
"While there is currently not enough evidence to conclusively determine how contamination occurred in this outbreak, the positive samples show that Cyclospora was present in the environment where lettuce was grown and processed,” the FDA wrote in an update on its website.
#lettuce #tested #Food
The Food and Drug Administration (FDA) said on Friday it has found a potential source of the cyclosporiasis outbreak that was tied to lettuce over the summer.
The agency collected samples during its onsite inspections of Taylor Farms de Mexico facilities, it said.
Two samples tested positive for the parasite, Cyclospora, according to the FDA. One positive sample was from a tank that held outgoing wastewater from a processing facility, the agency said. The second positive sample was from a drainage ditch of an iceberg lettuce grower, it noted.
"While there is currently not enough evidence to conclusively determine how contamination occurred in this outbreak, the positive samples show that Cyclospora was present in the environment where lettuce was grown and processed,” the FDA wrote in an update on its website.
#lettuce #tested #Food


1 month ago
The winning entry of a prestigious scientific photography competition is being re-evaluated following criticism from other scientists that it was made with AI.
Nikon's annual Small World In Motion contest accepts photos and video taken using powerful microscopes, and has run annually for the last 15 years.
The winner was a short video submitted by Dr Ning Xu, a researcher at Tsinghua University in China, which claims to be footage of tiny, hair-like structures called cilia moving inside the airways of a child with a rare disease.
Xu did not respond to the BBC's request for comment, but has posted online denying he broke the competition rules.
In a response to a post by Nikon on LinkedIn, he did not dispute using AI within the image processing but said he remained within the rules of the contest.
#within
Nikon's annual Small World In Motion contest accepts photos and video taken using powerful microscopes, and has run annually for the last 15 years.
The winner was a short video submitted by Dr Ning Xu, a researcher at Tsinghua University in China, which claims to be footage of tiny, hair-like structures called cilia moving inside the airways of a child with a rare disease.
Xu did not respond to the BBC's request for comment, but has posted online denying he broke the competition rules.
In a response to a post by Nikon on LinkedIn, he did not dispute using AI within the image processing but said he remained within the rules of the contest.
#within



2 months ago
On September 9, 2026, ****** og Devices, Inc. (NASDAQ:ADI) agreed to acquire privately held Alif Semiconductor for $1.35 billion in cash, with up to $200 million in additional contingent payments. It adds Alif's low-power, AI-native microcontrollers and fusion processors to ADI's portfolio of sensing, signal-processing and power-management technology. ADI CEO Vincent Roche described the deal as advancing "Physical Intelligence," letting systems sense, reason and act locally in real time. The acquisition is expected to close by the end of 2026 pending U.S. antitrust review.
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition

2 months ago
Targa Resources Corp. (NYSE:TRGP) has significantly outperformed the wider market this year, posting gains of over 56% since the beginning of 2026. A major catalyst behind this growth was the 20-year fee-based agreement that the company signed with ExxonMobil last month.
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
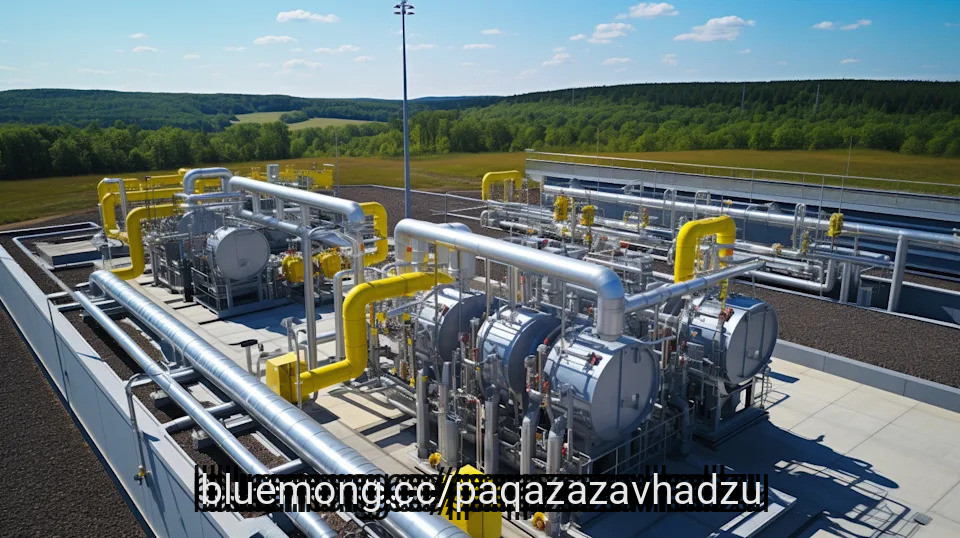
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda

2 months ago
On August 6, Targa Resources Corp. (NYSE:TRGP) reported a record second quarter. Adjusted EBITDA reached $1.60 billion, a 38% jump from the same period a year earlier, and management now expects full-year results near the top of its guidance range. Targa moves and processes natural gas and natural gas liquids out of the Permian Basin, and these numbers suggest that system is running fuller than ever.
The strength came from volume, not just price. Adjusted EBITDA also climbed 14% from the first quarter, helped by Permian gas volumes that added over 450 million cubic feet of daily throughput. Some producers held back output because Waha gas prices went negative, and Targa still set a volume record. Volumes for NGL pipelines, fractionation, and LPG exports also hit records, helped by Train 11, a new fractionator in Mont Belvieu, Texas, that started up early in the quarter.
Construction is also landing on time. East Driver, a new processing plant serving the Midland side of the Permian, started up late in the quarter and ahead of schedule, and the other gathering and logistics projects are tracking their plans. Shareholders get a cut too. On July 16, Targa declared a $1.25 per share quarterly dividend, 25% above the payout for the second quarter of 2025, payable August 14 to holders of record on July 31. It also spent $80 million buying back shares during the quarter.
Growth at this pace costs real money. Targa plans about $4.5 billion in net growth spending this year, and its consolidated debt stood at $19,578 million on June 30. About $3.2 billion of liquidity gives it a cushion. In July, it also extended its receivables securitization facility to July 30, 2027 and raised the size to as much as $800 million. More borrowing capacity helps, but it is still borrowing.
Not every dollar of the profit surge is as steady as a pipeline volume. Management tied the higher outlook partly to strong marketing margin and optimization work in the first two quarters, and the quarter's jump in marketing margin came from greater optimization opportunities. That kind of income can be lumpy. Meanwhile, lower natural gas prices trimmed margins in the gathering business, and the Waha curtailments showed that producers can pull back when local prices turn ugly.
#record
The strength came from volume, not just price. Adjusted EBITDA also climbed 14% from the first quarter, helped by Permian gas volumes that added over 450 million cubic feet of daily throughput. Some producers held back output because Waha gas prices went negative, and Targa still set a volume record. Volumes for NGL pipelines, fractionation, and LPG exports also hit records, helped by Train 11, a new fractionator in Mont Belvieu, Texas, that started up early in the quarter.
Construction is also landing on time. East Driver, a new processing plant serving the Midland side of the Permian, started up late in the quarter and ahead of schedule, and the other gathering and logistics projects are tracking their plans. Shareholders get a cut too. On July 16, Targa declared a $1.25 per share quarterly dividend, 25% above the payout for the second quarter of 2025, payable August 14 to holders of record on July 31. It also spent $80 million buying back shares during the quarter.
Growth at this pace costs real money. Targa plans about $4.5 billion in net growth spending this year, and its consolidated debt stood at $19,578 million on June 30. About $3.2 billion of liquidity gives it a cushion. In July, it also extended its receivables securitization facility to July 30, 2027 and raised the size to as much as $800 million. More borrowing capacity helps, but it is still borrowing.
Not every dollar of the profit surge is as steady as a pipeline volume. Management tied the higher outlook partly to strong marketing margin and optimization work in the first two quarters, and the quarter's jump in marketing margin came from greater optimization opportunities. That kind of income can be lumpy. Meanwhile, lower natural gas prices trimmed margins in the gathering business, and the Waha curtailments showed that producers can pull back when local prices turn ugly.
#record
2 months ago
Nvidia (NASDAQ:NVDA) has constructed an artificial intelligence (AI) empire over the past few years. The company sells the world's most powerful AI chips, known as graphics processing units (GPUs), and an entire portfolio of related tools that are generating triple-digit growth and record levels of revenue.
Investors have piled into Nvidia stock to gain access to this incredible growth story, and so far, they've scored a major win. The stock has soared about 800% over the past five years. But, in recent times, investors have worried about one particular challenge: competition. Though Nvidia remains in the lead, a number of companies also sell AI chips -- and these products are becoming more powerful with each update.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
These players include chip companies like Advanced Micro Devices as well as broader tech giants like Amazon (NASDAQ:AMZN). All of this has prompted some investors to pause before getting in on Nvidia stock at this stage of the AI story. Nvidia stock has climbed about 14% this year, which isn't a big leap for this stock.
Just recently, however, some bright news emerged during Amazon's earning call. In fact, these 15 words from Amazon chief Andy Jassy may eliminate Nvidia's biggest risk.
#chips
Investors have piled into Nvidia stock to gain access to this incredible growth story, and so far, they've scored a major win. The stock has soared about 800% over the past five years. But, in recent times, investors have worried about one particular challenge: competition. Though Nvidia remains in the lead, a number of companies also sell AI chips -- and these products are becoming more powerful with each update.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
These players include chip companies like Advanced Micro Devices as well as broader tech giants like Amazon (NASDAQ:AMZN). All of this has prompted some investors to pause before getting in on Nvidia stock at this stage of the AI story. Nvidia stock has climbed about 14% this year, which isn't a big leap for this stock.
Just recently, however, some bright news emerged during Amazon's earning call. In fact, these 15 words from Amazon chief Andy Jassy may eliminate Nvidia's biggest risk.
#chips

2 months ago
Applied Materials (NASDAQ:AMAT) primarily generates its revenue by designing, developing, manufacturing, and selling the critical fabrication equipment, specialized factory automation software, and materials engineering solutions utilized to produce integrated circuits for customers globally.
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily


2 months ago
SEIC provides investment processing, management, and operational platforms for private banks, financial advisors, institutional investors, and financial managers. SEIC's second-quarter fiscal 2026 report showed revenue of $641.6 million (a 14.7% year-over-year gain), adjusted per-share earnings of $1.66 (a 38% rise), $207 million in operating income (a 36% jump) – all of which were quarterly records – and the company has nearly $400 million in cash for more growth ahead.
It's no wonder SEIC shares are up 28% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock
Institutional volumes reveal plenty. Over the last year, SEIC has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in SEIC shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of financials names are under accumulation right now. But there's a powerful fundamental story happening with SEI.
#institutional #investors #Stock
It's no wonder SEIC shares are up 28% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock
Institutional volumes reveal plenty. Over the last year, SEIC has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in SEIC shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of financials names are under accumulation right now. But there's a powerful fundamental story happening with SEI.
#institutional #investors #Stock



2 months ago
Quantum computers can be better at processing data-heavy workloads in areas like science and cryptography, because they can use a concept called superposition to simulate multiple solutions to a problem at the same time. However, even the best quantum systems today are still making far too many errors to solve complex real-world problems.
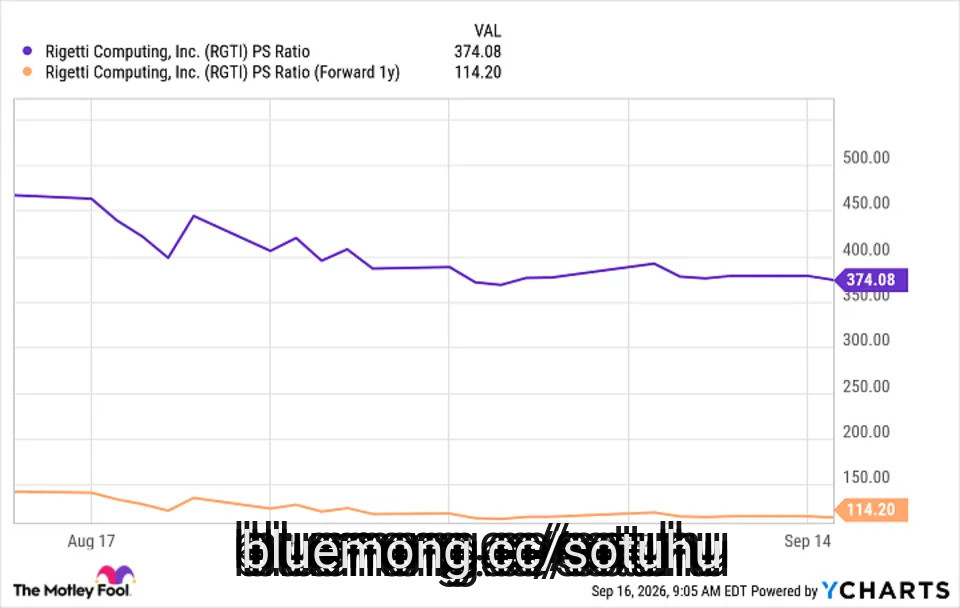
Rigetti Computing (NASDAQ: RGTI) is one of the industry leaders right now, and it's making genuine progress. But considering even the company's most powerful quantum computers aren't overly useful yet, it's struggling to generate meaningful sales, so it's burning through truckloads of cash while it continues to conduct research and development.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That creates a problem for shareholders, because Rigetti stock is trading at a sky-high valuation, which opens the door to potential downside if the company can't find a way to bring in significantly more revenue in the near future. Here's why I predict the stock will plummet over the next 12 months.
Rigetti built its own fabrication facility to produce chips, developed its own quantum programming language, and even created its own cloud platform, which it can rent to other businesses, thereby monetizing quantum computing capacity. By effectively operating its own end-to-end supply chain, the company can bring new systems to market much faster than many of its competitors.
#quantum #signal #even #company
Rigetti Computing (NASDAQ: RGTI) is one of the industry leaders right now, and it's making genuine progress. But considering even the company's most powerful quantum computers aren't overly useful yet, it's struggling to generate meaningful sales, so it's burning through truckloads of cash while it continues to conduct research and development.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That creates a problem for shareholders, because Rigetti stock is trading at a sky-high valuation, which opens the door to potential downside if the company can't find a way to bring in significantly more revenue in the near future. Here's why I predict the stock will plummet over the next 12 months.
Rigetti built its own fabrication facility to produce chips, developed its own quantum programming language, and even created its own cloud platform, which it can rent to other businesses, thereby monetizing quantum computing capacity. By effectively operating its own end-to-end supply chain, the company can bring new systems to market much faster than many of its competitors.
#quantum #signal #even #company

2 months ago
Guardian Metal Resources PLC (NYSEAMERICAN:GMTL) reported its first Good Hope drilling results on September 14, adding exploration potential to the Pilot Mountain tungsten project in Nevada. Hole GH26-01 returned a 12.95-meter downhole interval grading 0.79% tungsten trioxide, or WO3, starting at 12.19 meters. GH26-02 intersected 13.11 meters at 0.42% WO3 from 2.13 meters.
The holes were twinned, with GH26-02 redrilling the upper portion where core had not been recovered. Good Hope and the separate Tremor discovery remain outside the resource base supporting the existing pre-feasibility study. The investment question is whether additional mineralization can improve project returns without slowing development.
Shallow mineralization offers a potential route to additional feed that could be accessible early in a future mining sequence. Good Hope sits approximately 1.1 to 1.3 kilometers from the existing resource areas, making its possible integration worth evaluating alongside the planned operation.
The June pre-feasibility study models an eight-year open-pit operation based on Desert Scheelite and Garnet. If further work establishes economic resources at Good Hope or Tremor, additional feed could extend that operating life or improve the sequence in which material reaches the processing plant.
For Guardian Metal Resources PLC (NYSEAMERICAN:GMTL), the potential benefit is better use of infrastructure already contemplated for Pilot Mountain. That would depend on recoverable metal, processing compatibility, and the additional capital required to bring the new zones into production.
#hope #resources #guardian
The holes were twinned, with GH26-02 redrilling the upper portion where core had not been recovered. Good Hope and the separate Tremor discovery remain outside the resource base supporting the existing pre-feasibility study. The investment question is whether additional mineralization can improve project returns without slowing development.
Shallow mineralization offers a potential route to additional feed that could be accessible early in a future mining sequence. Good Hope sits approximately 1.1 to 1.3 kilometers from the existing resource areas, making its possible integration worth evaluating alongside the planned operation.
The June pre-feasibility study models an eight-year open-pit operation based on Desert Scheelite and Garnet. If further work establishes economic resources at Good Hope or Tremor, additional feed could extend that operating life or improve the sequence in which material reaches the processing plant.
For Guardian Metal Resources PLC (NYSEAMERICAN:GMTL), the potential benefit is better use of infrastructure already contemplated for Pilot Mountain. That would depend on recoverable metal, processing compatibility, and the additional capital required to bring the new zones into production.
#hope #resources #guardian
2 months ago
Nebius Group (NASDAQ: NBIS) stock surged sharply higher Thursday morning, gaining as much as 11.2%. As of 2:27 p.m. ET, the stock had given back most of those gains, but was still up 2.1%.
The catalyst that sent the artificial intelligence (AI) and neocloud specialist higher was a report that the company is raising some prices.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is one of several neocloud operators that stockpile graphics processing units (GPUs) and provide on-demand AI processing. The company announced that it will raise the price for access to on-demand Nvidia (NASDAQ: NVDA) GPUs by roughly 20%, effective Oct. 1.
H100 chips -- $4.50 per GPU hour, up 17%
#Stock #neocloud
The catalyst that sent the artificial intelligence (AI) and neocloud specialist higher was a report that the company is raising some prices.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is one of several neocloud operators that stockpile graphics processing units (GPUs) and provide on-demand AI processing. The company announced that it will raise the price for access to on-demand Nvidia (NASDAQ: NVDA) GPUs by roughly 20%, effective Oct. 1.
H100 chips -- $4.50 per GPU hour, up 17%
#Stock #neocloud


2 months ago
Exodus Movement, Inc. (NYSEAMERICAN:EXOD) reported on September 11 that August payment-processing gross transaction volume reached $356.8 million, up from $338.0 million in July. Monthly active cards declined to 757,900 from 783,600.
Separately, Web3 exchange-provider processed volume increased to $376.8 million from $314.8 million, while reported monthly active users remained at 1.4 million. The figures show stronger transaction activity alongside fewer active cards and a stable reported user count.
The question is whether that activity produces enough revenue to improve profitability while Exodus Movement, Inc. (NYSEAMERICAN:EXOD) integrates Monavate and reduces costs.
Payment growth persists after adjusting for currency translation. Exodus Movement, Inc. (NYSEAMERICAN:EXOD) converted sterling payment volumes into dollars using average rates of $1.35 per pound for August and $1.34 for July. Reversing those conversions implies approximately 4.8% growth in underlying sterling volume, compared with 5.6% in reported dollars. Both calculations use rounded disclosed figures.
Web3 exchange-provider volume increased approximately 19.7%. XO Swap partners contributed 23% of volume in both months. The unchanged reported share suggests both the partner channel and the remaining business contributed to growth.
#reported #exodus #nyseamerican
Separately, Web3 exchange-provider processed volume increased to $376.8 million from $314.8 million, while reported monthly active users remained at 1.4 million. The figures show stronger transaction activity alongside fewer active cards and a stable reported user count.
The question is whether that activity produces enough revenue to improve profitability while Exodus Movement, Inc. (NYSEAMERICAN:EXOD) integrates Monavate and reduces costs.
Payment growth persists after adjusting for currency translation. Exodus Movement, Inc. (NYSEAMERICAN:EXOD) converted sterling payment volumes into dollars using average rates of $1.35 per pound for August and $1.34 for July. Reversing those conversions implies approximately 4.8% growth in underlying sterling volume, compared with 5.6% in reported dollars. Both calculations use rounded disclosed figures.
Web3 exchange-provider volume increased approximately 19.7%. XO Swap partners contributed 23% of volume in both months. The unchanged reported share suggests both the partner channel and the remaining business contributed to growth.
#reported #exodus #nyseamerican

2 months ago
Semiconductor rivalries rarely move stock prices the way headlines suggest they should. MediaTek unveiled a new flagship smartphone processor on Tuesday, Sept. 15, built to challenge Qualcomm directly in the premium handset market.
Qualcomm Inc (QCOM)'s stock rose anyway, closing up 4.25% at $187.80.
That is not a new pattern. MediaTek's market value first surpassed Qualcomm's earlier this year, according to Reuters. The new chip was meant to widen that lead, not just defend it.
The gap is real money. MediaTek's market capitalization stood near $223 billion on Sept. 15, PitchBook noted. Even after Qualcomm's 4.25% rally that same day, its market cap reached $200.6 billion, according to CompaniesMarketCap, leaving it about $22 billion behind MediaTek.
MediaTek said the Dimensity 9600 Pro is its first mobile processor built on TSMC's 2-nanometer process. Its neural processing unit delivers 51% faster prompt handling for on-device AI models than the prior generation. That lets phones run generative AI tasks without sending data to the cloud.
#market #qualcomm #built #according
Qualcomm Inc (QCOM)'s stock rose anyway, closing up 4.25% at $187.80.
That is not a new pattern. MediaTek's market value first surpassed Qualcomm's earlier this year, according to Reuters. The new chip was meant to widen that lead, not just defend it.
The gap is real money. MediaTek's market capitalization stood near $223 billion on Sept. 15, PitchBook noted. Even after Qualcomm's 4.25% rally that same day, its market cap reached $200.6 billion, according to CompaniesMarketCap, leaving it about $22 billion behind MediaTek.
MediaTek said the Dimensity 9600 Pro is its first mobile processor built on TSMC's 2-nanometer process. Its neural processing unit delivers 51% faster prompt handling for on-device AI models than the prior generation. That lets phones run generative AI tasks without sending data to the cloud.
#market #qualcomm #built #according

2 months ago
Nvidia (NVDA) has been powering the ongoing artificial intelligence (AI) boom. Its graphics processing units (GPUs), central processing units (CPUs), networking products, and increasingly integrated AI systems continue to benefit from enormous investments in data center infrastructure. As a result, NVDA has continued to deliver impressive financial results.
Notably, concerns about a potential slowdown in AI development have weighed on semiconductor stocks, raising fears that the enormous spending on AI infrastructure could eventually moderate. However, demand for Nvidia's products is unlikely to slow, and the company could continue delivering extraordinary growth.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#nvda #processing #units #infrastructure
Notably, concerns about a potential slowdown in AI development have weighed on semiconductor stocks, raising fears that the enormous spending on AI infrastructure could eventually moderate. However, demand for Nvidia's products is unlikely to slow, and the company could continue delivering extraordinary growth.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#nvda #processing #units #infrastructure


2 months ago
Interested in Qualcomm Incorporated? Here are five stocks we like better.
Qualcomm trades at a price-to-earnings ratio of just 22, well below rivals like NVIDIA, Broadcom, and AMD, despite its ties to the AI boom.
Analysts, including Rosenblatt Securities with a $235 price target, see upside from Qualcomm's expansion into AI data centers, automotive chips, and on-device AI processing.
Apple's shift to in-house modem chips and a sluggish Android market in China threaten to offset Qualcomm's diversification gains, keeping its consensus rating at Hold.
There's a certain irony in a stock that has just rallied hard still being written off, yet that's exactly where chipmaker Qualcomm Inc. (NASDAQ: QCOM) finds itself right now. After a brutal 44% slide through much of the summer, its shares staged an impressive comeback, climbing around 30% since the start of August.
#incorporated
Qualcomm trades at a price-to-earnings ratio of just 22, well below rivals like NVIDIA, Broadcom, and AMD, despite its ties to the AI boom.
Analysts, including Rosenblatt Securities with a $235 price target, see upside from Qualcomm's expansion into AI data centers, automotive chips, and on-device AI processing.
Apple's shift to in-house modem chips and a sluggish Android market in China threaten to offset Qualcomm's diversification gains, keeping its consensus rating at Hold.
There's a certain irony in a stock that has just rallied hard still being written off, yet that's exactly where chipmaker Qualcomm Inc. (NASDAQ: QCOM) finds itself right now. After a brutal 44% slide through much of the summer, its shares staged an impressive comeback, climbing around 30% since the start of August.
#incorporated

2 months ago
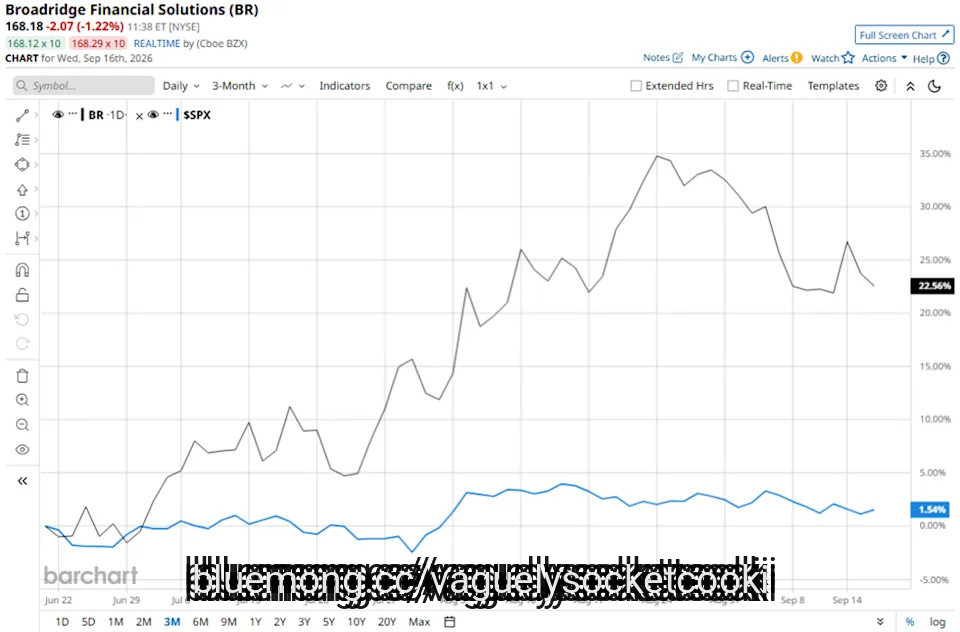
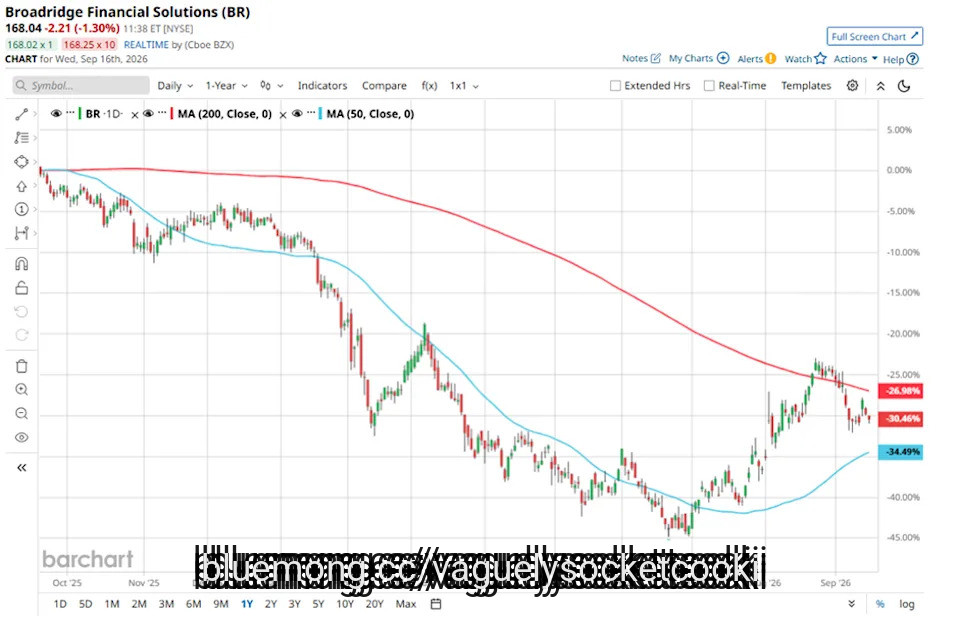
With a market cap of $19.4 billion, Broadridge Financial Solutions, Inc. (BR) is a global financial technology leader that provides investor communications and technology-driven solutions to banks, broker-dealers, ***** et managers, corporate issuers, and other financial institutions. Broadridge plays a critical role in enhancing transparency, efficiency, and engagement across the financial services industry.
Companies valued at $10 billion or more are generally classified as "large-cap" stocks, and Broadridge Financial fits this criterion perfectly. Through its two segments: Investor Communication Solutions and Global Technology & Operations, the company delivers services ranging from regulatory and shareholder communications to front-to-back securities processing and data-driven solutions.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Why It's Time to Load Up on Nvidia Stock
#financial #broadridge
Companies valued at $10 billion or more are generally classified as "large-cap" stocks, and Broadridge Financial fits this criterion perfectly. Through its two segments: Investor Communication Solutions and Global Technology & Operations, the company delivers services ranging from regulatory and shareholder communications to front-to-back securities processing and data-driven solutions.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Why It's Time to Load Up on Nvidia Stock
#financial #broadridge

2 months ago
On August 25, Aptiv (NYSE:APTV) said it will support NVIDIA's newly announced Jetson Orin Nano 2 processor, extending a partnership that already covers the more powerful Jetson Thor platform. The move puts Aptiv squarely inside the buildout of "physical AI," the term for machines like drones, robots, and industrial systems that need to sense and react to the real world in real time. For a company still just months removed from spinning off its electrical distribution business, betting on edge robotics is a statement about where it thinks the next decade of growth actually lives.
NVIDIA's Jetson Orin Nano 2 packs 78 TOPS of processing power into an 8GB, 8-core Arm chip that doubles the inference speed of its predecessor while cutting power draw by 40% at equivalent performance. That kind of efficiency gain matters for battery-powered devices like delivery drones and mobile robots, where every watt saved extends run time. Aptiv isn't just supplying compute support; it is layering in its PULSE surround-view camera and radar system for 360-degree sensing, its Gen 8 radar for object detection in tough conditions, and Wind River software to handle the unglamorous but essential work of long-term maintenance and security updates. That full-stack approach is the pitch: instead of stitching together sensors, chips, and software from separate vendors, customers get one partner who can carry a device from prototype to a fleet running in the field.
The timing lines up with what Aptiv reported in its second-quarter results on August 4, 2026. Revenue reached $3.3 billion, up 2%, while adjusted EBITDA climbed to $613 million from $547 million a year earlier, pushing margins to 18.7% from 17.1%. CEO Kevin Clark pointed to double-digit growth in non-automotive revenue, progress moving robotics from partnership talks to actual commercial deployments, and a major drone industry win secured in early July. North America sales rose 10% and Asia Pacific grew 6%, including 5% growth in China, giving the company some geographic momentum to lean on as it chases this new business line.
The quarter wasn't clean underneath the headline numbers. Free cash flow came in at just $12 million in the second quarter, down from $219 million a year earlier, and the first half of 2026 actually posted negative free cash flow of $196 million versus a positive $264 million a year ago. Operating cash flow from continuing operations fell to $82 million for the first half, down sharply from $531 million. Management also flagged automotive demand and customer mix as an incremental headwind, a reminder that Aptiv's legacy business still carries real weight even as it chases robotics and drones. EMEA revenue dropped 8%, and South America fell 4% in the quarter, both drags even as North America and Asia Pacific grew.
#jetson #robotics
NVIDIA's Jetson Orin Nano 2 packs 78 TOPS of processing power into an 8GB, 8-core Arm chip that doubles the inference speed of its predecessor while cutting power draw by 40% at equivalent performance. That kind of efficiency gain matters for battery-powered devices like delivery drones and mobile robots, where every watt saved extends run time. Aptiv isn't just supplying compute support; it is layering in its PULSE surround-view camera and radar system for 360-degree sensing, its Gen 8 radar for object detection in tough conditions, and Wind River software to handle the unglamorous but essential work of long-term maintenance and security updates. That full-stack approach is the pitch: instead of stitching together sensors, chips, and software from separate vendors, customers get one partner who can carry a device from prototype to a fleet running in the field.
The timing lines up with what Aptiv reported in its second-quarter results on August 4, 2026. Revenue reached $3.3 billion, up 2%, while adjusted EBITDA climbed to $613 million from $547 million a year earlier, pushing margins to 18.7% from 17.1%. CEO Kevin Clark pointed to double-digit growth in non-automotive revenue, progress moving robotics from partnership talks to actual commercial deployments, and a major drone industry win secured in early July. North America sales rose 10% and Asia Pacific grew 6%, including 5% growth in China, giving the company some geographic momentum to lean on as it chases this new business line.
The quarter wasn't clean underneath the headline numbers. Free cash flow came in at just $12 million in the second quarter, down from $219 million a year earlier, and the first half of 2026 actually posted negative free cash flow of $196 million versus a positive $264 million a year ago. Operating cash flow from continuing operations fell to $82 million for the first half, down sharply from $531 million. Management also flagged automotive demand and customer mix as an incremental headwind, a reminder that Aptiv's legacy business still carries real weight even as it chases robotics and drones. EMEA revenue dropped 8%, and South America fell 4% in the quarter, both drags even as North America and Asia Pacific grew.
#jetson #robotics
2 months ago
On August 5, Kinetik Holdings Inc. (NYSE:KNTK) reported the strongest quarterly results in company history and raised its full-year 2026 guidance. The Permian-focused midstream operator posted net income, including noncontrolling interest, of $123.1 million for the quarter ended June 30, while Adjusted EBITDA climbed to $280.8 million. Management didn't stop at celebrating the number. It used the quarter as the launchpad for a string of expansion decisions that stretch out to 2028.
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter


2 months ago
An **** ysis of recent filings from American politicians shows that Accenture (NYSE: ACN) and Boston Scientific (NYSE: BSX) saw an uptick in purchases from notable politicians. Rep. Gilbert Ray Cisneros, Jr. (D-CA) bought Boston Scientific shares, according to a filing earlier this month. The trade was made on August 18, 2026. Rep. Ro Khanna (D-CA) also bought the stock twice, on August 3 and August 10, 2026, according to a filing filed on September 4, 2026. Neither politician sold Boston Scientific shares in the same period. Cisneros and Khanna were also the two buyers of Accenture shares in July and August.
This is based on data from Quiver Quantitative, a platform that tracks congressional stock trades from politicians.
Let's focus on BSX in this article.
BSX is down about 50% so far this year amid a cyberattack that disrupted manufacturing, order processing and shipments, forcing the company to withdraw its previous third-quarter and full-year outlook. Bulls say the market has priced in too severe an outcome. By Sept. 8, the company said its major distribution centers were shipping at or above normal levels, sterilization facilities were operating, and manufacturing had restarted at most plants. Bulls believe much of the disrupted revenue could be delayed rather than permanently lost as hospitals wait for products, reschedule procedures and the company works through its backlog.
Bulls also point to a business that was still growing. Second-quarter revenue rose 7.5% year over year and organic growth was 7%. Several core franchises delivered double-digit organic growth, including Interventional Cardiology and Vascular Therapies, Interventional Oncology and Embolization, and Neuromodulation.
#august #NYSE
This is based on data from Quiver Quantitative, a platform that tracks congressional stock trades from politicians.
Let's focus on BSX in this article.
BSX is down about 50% so far this year amid a cyberattack that disrupted manufacturing, order processing and shipments, forcing the company to withdraw its previous third-quarter and full-year outlook. Bulls say the market has priced in too severe an outcome. By Sept. 8, the company said its major distribution centers were shipping at or above normal levels, sterilization facilities were operating, and manufacturing had restarted at most plants. Bulls believe much of the disrupted revenue could be delayed rather than permanently lost as hospitals wait for products, reschedule procedures and the company works through its backlog.
Bulls also point to a business that was still growing. Second-quarter revenue rose 7.5% year over year and organic growth was 7%. Several core franchises delivered double-digit organic growth, including Interventional Cardiology and Vascular Therapies, Interventional Oncology and Embolization, and Neuromodulation.
#august #NYSE

2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) is a leading professional services company that provides consulting, industry X, song, and technology and operation services. On September 15, 2026, Accenture plc (NYSE:ACN) closed at $193.40 per share. Over the past month, Accenture plc (NYSE:ACN) was up 3.11%, and its shares lost 21.71% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $118.33 billion.
Weitz Multi Cap Equity Fund stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"IT services and management consultant Accenture plc (NYSE:ACN) reported results in mid-June that did little to quell investor fears of AI-disintermediation. Accenture has a long history of helping clients navigate technological transformation, and we believe it will again play a role as AI permeates businesses. To date, however, we have maintained a smaller position given the higher-than-usual degree of uncertainty."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#investor
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) is a leading professional services company that provides consulting, industry X, song, and technology and operation services. On September 15, 2026, Accenture plc (NYSE:ACN) closed at $193.40 per share. Over the past month, Accenture plc (NYSE:ACN) was up 3.11%, and its shares lost 21.71% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $118.33 billion.
Weitz Multi Cap Equity Fund stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"IT services and management consultant Accenture plc (NYSE:ACN) reported results in mid-June that did little to quell investor fears of AI-disintermediation. Accenture has a long history of helping clients navigate technological transformation, and we believe it will again play a role as AI permeates businesses. To date, however, we have maintained a smaller position given the higher-than-usual degree of uncertainty."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#investor


2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#communications #quarter #investor
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#communications #quarter #investor


2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted CoStar Group, Inc. (NASDAQ:CSGP). CoStar Group, Inc. (NASDAQ:CSGP), an information, ****** ytics, and online marketplace services provider for commercial and residential property markets. On September 15, 2026, CoStar Group, Inc. (NASDAQ:CSGP) closed at $31.56 per share, reflecting a market capitalization of $12.79 billion. CoStar Group, Inc. (NASDAQ:CSGP) posted a one-month return of -6.43%, while its shares lost 64.08% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding CoStar Group, Inc. (NASDAQ:CSGP) in its Q2 2026 investor letter:
"CoStar Group, Inc.'s (NASDAQ:CSGP) management prevailed in its struggle with an activist investor and remains undeterred in its residential real estate strategy. Investors are clearly skeptical of management's plan, but at current prices, we believe the punishment has gone too far."
CoStar Group, Inc. (NASDAQ:CSGP) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 58 hedge fund portfolios held CoStar Group, Inc. (NASDAQ:CSGP) at the end of the second quarter, down from 62 in the previous quarter. While we acknowledge the potential of CoStar Group, Inc. (NASDAQ:CSGP) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#group #NASDAQ #fund #weitz
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted CoStar Group, Inc. (NASDAQ:CSGP). CoStar Group, Inc. (NASDAQ:CSGP), an information, ****** ytics, and online marketplace services provider for commercial and residential property markets. On September 15, 2026, CoStar Group, Inc. (NASDAQ:CSGP) closed at $31.56 per share, reflecting a market capitalization of $12.79 billion. CoStar Group, Inc. (NASDAQ:CSGP) posted a one-month return of -6.43%, while its shares lost 64.08% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding CoStar Group, Inc. (NASDAQ:CSGP) in its Q2 2026 investor letter:
"CoStar Group, Inc.'s (NASDAQ:CSGP) management prevailed in its struggle with an activist investor and remains undeterred in its residential real estate strategy. Investors are clearly skeptical of management's plan, but at current prices, we believe the punishment has gone too far."
CoStar Group, Inc. (NASDAQ:CSGP) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 58 hedge fund portfolios held CoStar Group, Inc. (NASDAQ:CSGP) at the end of the second quarter, down from 62 in the previous quarter. While we acknowledge the potential of CoStar Group, Inc. (NASDAQ:CSGP) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#group #NASDAQ #fund #weitz

2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX) as a newly added postion. Netflix, Inc. (NASDAQ:NFLX) is a leading subscription-based streaming entertainment platform. On September 15, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of -2.89%, while its shares lost 36.59% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"We initiated two new positions during the second quarter. Most will be familiar with global streaming giant, Netflix, Inc. (NASDAQ:NFLX). The company made headlines as it tried to acquire Warner Bros. from Warner Bros. Discovery before ultimately walking away from a bidding war for the company. Some investors feared its bid signaled stagnation in its streaming business. At the time of this writing, the 2026 FIFA World Cup is also captivating audiences and draining attention and engagement from Netflix's service. Despite these near-term perception headwinds, we are optimistic that Netflix's introduction of an ad-supported tier is a savvy strategy to extend its growth runway: Netflix will not only participate in the large, multi-billion-dollar global advertising market, but a lower-price ad-tier broadens its potential customer base while simultaneously enhancing the pricing power of its premium, ad free tier."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#second
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX) as a newly added postion. Netflix, Inc. (NASDAQ:NFLX) is a leading subscription-based streaming entertainment platform. On September 15, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of -2.89%, while its shares lost 36.59% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"We initiated two new positions during the second quarter. Most will be familiar with global streaming giant, Netflix, Inc. (NASDAQ:NFLX). The company made headlines as it tried to acquire Warner Bros. from Warner Bros. Discovery before ultimately walking away from a bidding war for the company. Some investors feared its bid signaled stagnation in its streaming business. At the time of this writing, the 2026 FIFA World Cup is also captivating audiences and draining attention and engagement from Netflix's service. Despite these near-term perception headwinds, we are optimistic that Netflix's introduction of an ad-supported tier is a savvy strategy to extend its growth runway: Netflix will not only participate in the large, multi-billion-dollar global advertising market, but a lower-price ad-tier broadens its potential customer base while simultaneously enhancing the pricing power of its premium, ad free tier."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#second

2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Mettler-Toledo International Inc. (NYSE:MTD). Mettler-Toledo International Inc. (NYSE:MTD) manufactures and supplies precision instruments and services in the Americas, Europe, Asia, and internationally. On September 15, 2026, Mettler-Toledo International Inc. (NYSE:MTD) closed at $1,330.40 per share. Over the past month, Mettler-Toledo International Inc. (NYSE:MTD) declined 6.64%, and its shares gained 4.43% over the past 52 weeks. Mettler-Toledo International Inc. (NYSE:MTD) has a market capitalization of $26.66 billion.
Weitz Multi Cap Equity Fund stated the following regarding Mettler-Toledo International Inc. (NYSE:MTD) in its Q2 2026 investor letter:
"Less familiar to shareholders may be our new position in Mettler-Toledo International Inc. (NYSE:MTD), a global supplier of precision measurement instruments across laboratory, industrial and food retailing applications where accuracy, reliability and regulatory compliance are vital. Its highly specialized sales and service organization is a key competitive advantage, working collaboratively with customers to optimize their workflows and improve productivity, reinforcing long-term customer relationships. We have long admired Mettler's business and purchased a small position during a brief period of price dislocation during the quarter."
Mettler-Toledo International Inc. (NYSE:MTD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 48 hedge fund portfolios held Mettler-Toledo International Inc. (NYSE:MTD) at the end of the second quarter, down from 50 in the previous quarter. While we acknowledge the potential of Mettler-Toledo International Inc. (NYSE:MTD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mettler #quarter
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Mettler-Toledo International Inc. (NYSE:MTD). Mettler-Toledo International Inc. (NYSE:MTD) manufactures and supplies precision instruments and services in the Americas, Europe, Asia, and internationally. On September 15, 2026, Mettler-Toledo International Inc. (NYSE:MTD) closed at $1,330.40 per share. Over the past month, Mettler-Toledo International Inc. (NYSE:MTD) declined 6.64%, and its shares gained 4.43% over the past 52 weeks. Mettler-Toledo International Inc. (NYSE:MTD) has a market capitalization of $26.66 billion.
Weitz Multi Cap Equity Fund stated the following regarding Mettler-Toledo International Inc. (NYSE:MTD) in its Q2 2026 investor letter:
"Less familiar to shareholders may be our new position in Mettler-Toledo International Inc. (NYSE:MTD), a global supplier of precision measurement instruments across laboratory, industrial and food retailing applications where accuracy, reliability and regulatory compliance are vital. Its highly specialized sales and service organization is a key competitive advantage, working collaboratively with customers to optimize their workflows and improve productivity, reinforcing long-term customer relationships. We have long admired Mettler's business and purchased a small position during a brief period of price dislocation during the quarter."
Mettler-Toledo International Inc. (NYSE:MTD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 48 hedge fund portfolios held Mettler-Toledo International Inc. (NYSE:MTD) at the end of the second quarter, down from 50 in the previous quarter. While we acknowledge the potential of Mettler-Toledo International Inc. (NYSE:MTD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mettler #quarter


2 months ago
The choice between established ****** ans and digital-first challengers defines many modern portfolios. In the financial realm, investors must decide if JPMorgan Chase (NYSE:JPM) or SoFi Technologies (NASDAQ:SOFI) is the better buy for long-term growth.
JPMorgan Chase operates as a global financial heavyweight, offering everything from wealth management to retail branches. Conversely, SoFi Technologies focuses on an integrated mobile app to help members borrow, save, and invest. While one relies on massive scale, the other bets on fintech innovation to capture a younger, tech-savvy demographic.
JPMorgan Chase functions as a cornerstone of the global economy, managing a vast array of services including ****** et management and investment banking. In its latest annual report, filed for 2025, the firm highlighted its reach through more than 5,000 branches across the 48 contiguous states. It serves a diverse client base ranging from individual consumers and small businesses to large corporations and governments. The firm provides a comprehensive range of financial services, including transaction processing and commercial banking on a global scale.
Financial performance remained robust in FY 2025, with revenue reaching nearly $182.4 billion. This represented a growth rate of approximately 3.3% compared to the previous year, contributing to a net income of close to $57.0 billion. The net margin, which measures the percentage of revenue kept as profit after all expenses, sat at roughly 20.4% for the period. This consistent profitability underscores the scale of its operations across diverse global markets.
As of its December 2025 balance sheet, the firm reported a debt-to-equity ratio of nearly 2.6x. This ratio measures total debt against shareholder equity, with a higher number indicating more reliance on borrowed funds to finance growth. The current ratio, which compares short-term ****** ets to short-term liabilities, was approximately 0.5x, while free cash flow reached a negative $147.8 billion. Free cash flow is the cash a company generates after accounting for cash outflows to support operations and maintain its capital ****** ets.
#sofi #global #term
JPMorgan Chase operates as a global financial heavyweight, offering everything from wealth management to retail branches. Conversely, SoFi Technologies focuses on an integrated mobile app to help members borrow, save, and invest. While one relies on massive scale, the other bets on fintech innovation to capture a younger, tech-savvy demographic.
JPMorgan Chase functions as a cornerstone of the global economy, managing a vast array of services including ****** et management and investment banking. In its latest annual report, filed for 2025, the firm highlighted its reach through more than 5,000 branches across the 48 contiguous states. It serves a diverse client base ranging from individual consumers and small businesses to large corporations and governments. The firm provides a comprehensive range of financial services, including transaction processing and commercial banking on a global scale.
Financial performance remained robust in FY 2025, with revenue reaching nearly $182.4 billion. This represented a growth rate of approximately 3.3% compared to the previous year, contributing to a net income of close to $57.0 billion. The net margin, which measures the percentage of revenue kept as profit after all expenses, sat at roughly 20.4% for the period. This consistent profitability underscores the scale of its operations across diverse global markets.
As of its December 2025 balance sheet, the firm reported a debt-to-equity ratio of nearly 2.6x. This ratio measures total debt against shareholder equity, with a higher number indicating more reliance on borrowed funds to finance growth. The current ratio, which compares short-term ****** ets to short-term liabilities, was approximately 0.5x, while free cash flow reached a negative $147.8 billion. Free cash flow is the cash a company generates after accounting for cash outflows to support operations and maintain its capital ****** ets.
#sofi #global #term

2 months ago
STERIS plc (STE), with a market capitalization of approximately $20.8 billion, is a global healthcare company focused on infection prevention and patient care. The Mentor, Ohio-based company provides consumable products, capital equipment, maintenance and repair services, sterilization solutions, laboratory testing, outsourced reprocessing, and operating room connectivity solutions.
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and STERIS fits this description, with its market capitalization reflecting its substantial size and established position within the healthcare sector. STERIS stands out by combining a leading position in infection prevention with a broad range of healthcare and sterilization products and services. Its trusted brand, loyal customer base, strong financial position, and strategic acquisitions strengthen its competitive position while supporting continued expansion and innovation.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#steris #position
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and STERIS fits this description, with its market capitalization reflecting its substantial size and established position within the healthcare sector. STERIS stands out by combining a leading position in infection prevention with a broad range of healthcare and sterilization products and services. Its trusted brand, loyal customer base, strong financial position, and strategic acquisitions strengthen its competitive position while supporting continued expansion and innovation.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#steris #position

2 months ago
Between 2023 and 2025, Nvidia (NASDAQ: NVDA) was the market's most obvious artificial intelligence (AI) trade. During this period, the stock went parabolic, surging by 1,180% and turning the chipmaker into the world's most valuable company by market cap. On a split-adjusted basis, that was a climb from about $14 per share to $186 by the end of 2025.
Currently, Nvidia stock sits around $218, up another 17% year to date. This is what it looks like when a company owns a scarce product that's in heavy demand -- in this case, graphics processing units (GPUs).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron Technology's (NASDAQ: MU) rocket-like move came a bit later, but hit much harder. Memory chips were an afterthought during the initial GPU gold rush. But as training clusters got larger and inference workloads got hungrier, supplies of high bandwidth memory (HBM) started running short. Prices for HBM soared, and Micron stock responded epically -- rising 239% in 2025 and another 242% so far this year. This type of price action indicates the market has recognized that memory is no longer just another tech commodity -- its supply is one of the key bottlenecks dictating the pace at which data centers can be built.
Nvidia and Micron are not the same bet. While Nvidia sells engines, Micron is selling the tanks for the fuel these engines cannot operate without. This begs the question: At this point, which of these AI chip stocks would be the better one to buy and hold for the next five years?
#signal #Stock #chipmaker
Currently, Nvidia stock sits around $218, up another 17% year to date. This is what it looks like when a company owns a scarce product that's in heavy demand -- in this case, graphics processing units (GPUs).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron Technology's (NASDAQ: MU) rocket-like move came a bit later, but hit much harder. Memory chips were an afterthought during the initial GPU gold rush. But as training clusters got larger and inference workloads got hungrier, supplies of high bandwidth memory (HBM) started running short. Prices for HBM soared, and Micron stock responded epically -- rising 239% in 2025 and another 242% so far this year. This type of price action indicates the market has recognized that memory is no longer just another tech commodity -- its supply is one of the key bottlenecks dictating the pace at which data centers can be built.
Nvidia and Micron are not the same bet. While Nvidia sells engines, Micron is selling the tanks for the fuel these engines cannot operate without. This begs the question: At this point, which of these AI chip stocks would be the better one to buy and hold for the next five years?
#signal #Stock #chipmaker

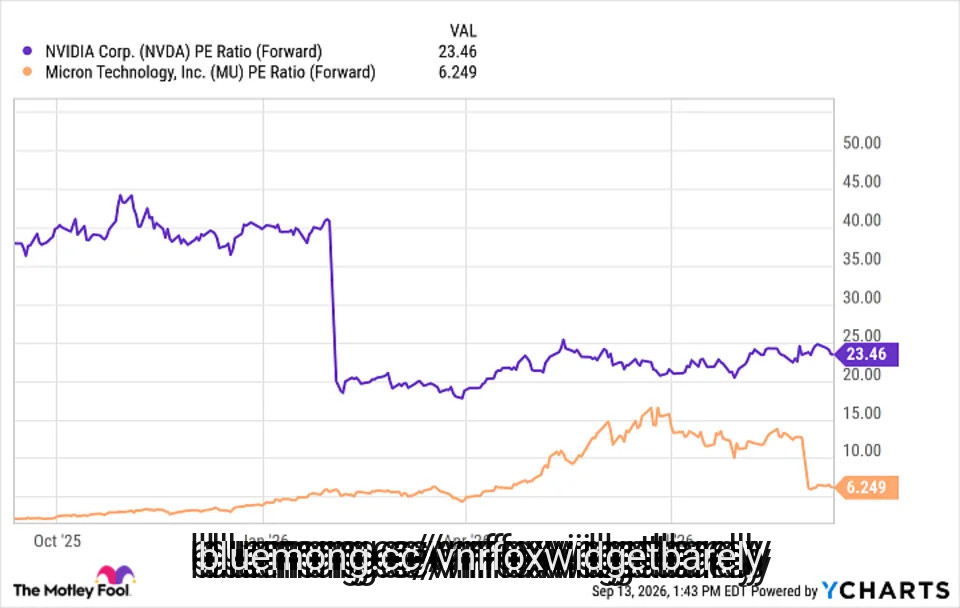

2 months ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend



