20 hours ago
Energy Transfer LP (NYSE:ET) is set to move the primary listing of its common and Series I preferred units from the New York Stock Exchange to the Texas Stock Exchange in early October, making it the first major company to make such a switch from the NYSE to the newly established Dallas exchange. Reuters said the companies moving to TXSE, including Energy Transfer and related energy businesses, represent nearly $100 billion in combined market value, giving the fledgling exchange an important early credibility boost.
For Energy Transfer LP (NYSE:ET), however, the more important question is whether the move can eventually translate into better investor visibility or valuation rather than simply giving the company a stronger Texas identity. WSJ reported that Energy Transfer is worth roughly $75 billion and that Executive Chairman Kelcy Warren is a major backer of TXSE, owning about 30% of its parent company. That relationship makes the listing particularly significant, but it also means investors may scrutinize whether the decision creates a tangible benefit for Energy Transfer unitholders rather than primarily helping establish the new exchange.
The strongest bull argument is that Energy Transfer LP (NYSE:ET) is positioning itself ahead of a potentially important shift in the U.S. energy infrastructure market. TXSE is backed by major financial institutions including BlackRock, Citadel Securities, and Charles Schwab, and winning a roughly $75 billion company gives the exchange substantially more credibility with institutional investors. If TXSE attracts additional large energy companies, Energy Transfer could benefit from becoming one of the exchange's anchor names and gaining greater visibility among investors already focused on Texas-based energy infrastructure.
More importantly, the listing decision fits the underlying environment in which Energy Transfer LP (NYSE:ET) operates. Reuters has highlighted continued investment in U.S. gas-fired generation, LNG infrastructure, and pipeline networks as electricity demand rises and countries seek reliable energy supplies. The U.S. is also building substantial additional LNG export capacity. That matters because Energy Transfer's extensive midstream network can benefit from higher volumes of natural gas, crude oil, and NGLs without taking the same direct commodity-price exposure as upstream producers. If rising power demand from data centers and continued LNG development drive greater demand for U.S. gas transportation, Energy Transfer could see expanding opportunities to place additional infrastructure into service and lock in long-duration cash flows.
#transfer #company #infrastructure #listing
For Energy Transfer LP (NYSE:ET), however, the more important question is whether the move can eventually translate into better investor visibility or valuation rather than simply giving the company a stronger Texas identity. WSJ reported that Energy Transfer is worth roughly $75 billion and that Executive Chairman Kelcy Warren is a major backer of TXSE, owning about 30% of its parent company. That relationship makes the listing particularly significant, but it also means investors may scrutinize whether the decision creates a tangible benefit for Energy Transfer unitholders rather than primarily helping establish the new exchange.
The strongest bull argument is that Energy Transfer LP (NYSE:ET) is positioning itself ahead of a potentially important shift in the U.S. energy infrastructure market. TXSE is backed by major financial institutions including BlackRock, Citadel Securities, and Charles Schwab, and winning a roughly $75 billion company gives the exchange substantially more credibility with institutional investors. If TXSE attracts additional large energy companies, Energy Transfer could benefit from becoming one of the exchange's anchor names and gaining greater visibility among investors already focused on Texas-based energy infrastructure.
More importantly, the listing decision fits the underlying environment in which Energy Transfer LP (NYSE:ET) operates. Reuters has highlighted continued investment in U.S. gas-fired generation, LNG infrastructure, and pipeline networks as electricity demand rises and countries seek reliable energy supplies. The U.S. is also building substantial additional LNG export capacity. That matters because Energy Transfer's extensive midstream network can benefit from higher volumes of natural gas, crude oil, and NGLs without taking the same direct commodity-price exposure as upstream producers. If rising power demand from data centers and continued LNG development drive greater demand for U.S. gas transportation, Energy Transfer could see expanding opportunities to place additional infrastructure into service and lock in long-duration cash flows.
#transfer #company #infrastructure #listing

20 hours ago
Vale S.A. (NYSE:VALE) is considering making its debut in China's domestic bond market as soon as this year, with CFO Marcelo Bacci saying the company is preparing for a potential Panda bond issuance. The move would be strategically significant because China accounts for roughly half of Vale's revenue, making renminbi financing a natural extension of its relationship with its largest market. Bloomberg reported that Vale is still ****** sing the market, including whether it can obtain a maturity longer than the typical two-, three-, or five-year terms available to international issuers.
The timing is also favorable for Vale because China's Panda bond market is expanding rapidly. Reuters reported that foreign issuers have increasingly turned to Asian bond markets to diversify funding sources, while Chinese yuan bond issuance has reached record levels in 2026. For Vale S.A. (NYSE:VALE), the potential transaction therefore looks less like a necessity for raising capital and more like an effort to diversify its investor base, potentially lower funding costs, and build a longer-term financing relationship with Chinese investors.
The strongest bullish argument is that Vale S.A. (NYSE:VALE) could potentially lower and diversify its cost of capital by accessing a large pool of Chinese investors at a time when renminbi funding remains relatively inexpensive. Reuters noted that Chinese onshore and offshore yuan bond markets have experienced record issuance this year, with foreign borrowers increasingly using these markets to diversify away from traditional funding currencies. If Vale can achieve competitive pricing, a Panda bond could provide an additional funding channel alongside its established dollar financing, reducing its dependence on a single market.
The move could also create a better natural match between Vale's revenues and its financing currency. Because China represents approximately half of Vale's revenue, raising at least some debt in renminbi could provide a degree of currency alignment with its Chinese business exposure. More importantly, establishing itself as a repeat issuer could strengthen Vale's relationships with Chinese banks and institutional investors, potentially giving it access to another source of capital when global dollar markets become less attractive.
There is also a broader strategic benefit. China is actively expanding the Panda bond market and encouraging international companies to use it. Official Chinese data showed that more than 160 billion yuan of Panda bonds were issued during the first half of 2026, up 69% year over year, demonstrating that the market is becoming more established and liquid. Vale entering this market could therefore position the company early in a growing financing ecosystem rather than waiting until it becomes more crowded.
#chinese #bond #panda #China
The timing is also favorable for Vale because China's Panda bond market is expanding rapidly. Reuters reported that foreign issuers have increasingly turned to Asian bond markets to diversify funding sources, while Chinese yuan bond issuance has reached record levels in 2026. For Vale S.A. (NYSE:VALE), the potential transaction therefore looks less like a necessity for raising capital and more like an effort to diversify its investor base, potentially lower funding costs, and build a longer-term financing relationship with Chinese investors.
The strongest bullish argument is that Vale S.A. (NYSE:VALE) could potentially lower and diversify its cost of capital by accessing a large pool of Chinese investors at a time when renminbi funding remains relatively inexpensive. Reuters noted that Chinese onshore and offshore yuan bond markets have experienced record issuance this year, with foreign borrowers increasingly using these markets to diversify away from traditional funding currencies. If Vale can achieve competitive pricing, a Panda bond could provide an additional funding channel alongside its established dollar financing, reducing its dependence on a single market.
The move could also create a better natural match between Vale's revenues and its financing currency. Because China represents approximately half of Vale's revenue, raising at least some debt in renminbi could provide a degree of currency alignment with its Chinese business exposure. More importantly, establishing itself as a repeat issuer could strengthen Vale's relationships with Chinese banks and institutional investors, potentially giving it access to another source of capital when global dollar markets become less attractive.
There is also a broader strategic benefit. China is actively expanding the Panda bond market and encouraging international companies to use it. Official Chinese data showed that more than 160 billion yuan of Panda bonds were issued during the first half of 2026, up 69% year over year, demonstrating that the market is becoming more established and liquid. Vale entering this market could therefore position the company early in a growing financing ecosystem rather than waiting until it becomes more crowded.
#chinese #bond #panda #China

20 hours ago
Queen Camilla has reportedly put the royal ambitions of Prince Harry and Meghan Markle on notice. The report came after the Sussexes made a striking return to the UK with their two kids, Prince Archie and Princess Lilibet, last month. The return came six years after the Sussex couple started living in the US after stepping down from their roles as working royals.
Queen Camilla has allegedly pushed her husband, King Charles, to draw a line with his youngest son, Prince Harry, and his wife, Meghan Markle, after they moved back to the UK. As reported by RadarOnline, sources reported that the Queen consort of the United Kingdom had concerns that the Duke and ***** ss of Sussex's return to Britain could blur the boundaries between the monarch and the Sussexes.
In the meantime, a royal insider claimed that Queen Camilla knows how the idea about the monarchy can turn complex very fast. Thus, she reportedly felt "determined" that Prince Harry and Meghan Markle's UK move should not be seen as the start of any "restoration" of their previous royal positions. According to the insider, Queen Camilla's "feeling was that everyone – the Sussexes, officials and the public – needed absolute clarity from the outset."
The source also explained that no one should "underestimate" the "influence" Queen Camilla has on her husband, King Charles. The source then said, "She is somebody whose judgment he trusts enormously, particularly when difficult family questions risk becoming institutional problems. Camilla believed allowing uncertainty to linger would simply store up a much bigger confrontation later."
Meanwhile, another insider told the news outlet that Queen Camilla's move is not about stopping the King from having a relationship with Prince Harry and his kids. "The distinction Camilla was concerned about was between the private family and the public monarchy," the insider added.
#prince #royal
Queen Camilla has allegedly pushed her husband, King Charles, to draw a line with his youngest son, Prince Harry, and his wife, Meghan Markle, after they moved back to the UK. As reported by RadarOnline, sources reported that the Queen consort of the United Kingdom had concerns that the Duke and ***** ss of Sussex's return to Britain could blur the boundaries between the monarch and the Sussexes.
In the meantime, a royal insider claimed that Queen Camilla knows how the idea about the monarchy can turn complex very fast. Thus, she reportedly felt "determined" that Prince Harry and Meghan Markle's UK move should not be seen as the start of any "restoration" of their previous royal positions. According to the insider, Queen Camilla's "feeling was that everyone – the Sussexes, officials and the public – needed absolute clarity from the outset."
The source also explained that no one should "underestimate" the "influence" Queen Camilla has on her husband, King Charles. The source then said, "She is somebody whose judgment he trusts enormously, particularly when difficult family questions risk becoming institutional problems. Camilla believed allowing uncertainty to linger would simply store up a much bigger confrontation later."
Meanwhile, another insider told the news outlet that Queen Camilla's move is not about stopping the King from having a relationship with Prince Harry and his kids. "The distinction Camilla was concerned about was between the private family and the public monarchy," the insider added.
#prince #royal

2 days ago
James Rodríguez's arrival at Atlético Nacional continues to draw major reactions in Colombian football. This time, the club's legendary former goalkeeper and idol, René Higuita, dedicated an emotional welcome message to him, full of affection and verdolaga mystique.
Through his words, the iconic goalkeeper highlighted the institutional weight of the jersey the midfielder from Cúcuta will wear. "This jersey has history, it has heart, and it has fans who are always with us. We love you, welcome to our beloved Atlético Nacional," the former player said.
Higuita ended his greeting by wishing the Colombia national team midfielder the greatest success in this new stage of his professional career: "May the victories come, my brother. Welcome to green," he concluded, reaffirming the enormous excitement this signing has generated among Antioquia's fans.
This article was translated into English by Artificial Intelligence. You can read the original version in 🇪🇸 here.
#tico #fans
Through his words, the iconic goalkeeper highlighted the institutional weight of the jersey the midfielder from Cúcuta will wear. "This jersey has history, it has heart, and it has fans who are always with us. We love you, welcome to our beloved Atlético Nacional," the former player said.
Higuita ended his greeting by wishing the Colombia national team midfielder the greatest success in this new stage of his professional career: "May the victories come, my brother. Welcome to green," he concluded, reaffirming the enormous excitement this signing has generated among Antioquia's fans.
This article was translated into English by Artificial Intelligence. You can read the original version in 🇪🇸 here.
#tico #fans


2 days ago
Block, Inc. (NYSE:XYZ) is taking another step toward consolidating its digital **** et operations under a federal regulatory framework. On September 8, it filed an application with the Office of the Comptroller of the Currency (OCC) to charter Builders Bank & Trust, N.A.
If chartered, the Builders Bank & Trust could become an important part of Block's digital **** et custody infrastructure, giving the company a federally supervised framework for custody and related services involving bitcoin and stablecoins.
Builders Bank & Trust would be an uninsured national trust bank, meaning it would not accept deposits or make traditional loans. Instead, its focus would be on fiduciary and custody services, allowing Block to build specialized infrastructure for safeguarding digital **** ets.
The structure could be particularly valuable as Block, Inc. (NYSE:XYZ) seeks to expand its institutional customer base. A federally supervised custody operation could give larger financial institutions greater confidence in Block's ability to safeguard Bitcoin and other digital **** ets.
Stablecoins represent a potentially important opportunity for Block, particularly through its Cash App ecosystem. A regulated custody infrastructure could eventually support broader stablecoin-related products and payments if Block chooses to expand further in this area.
#Bitcoin
If chartered, the Builders Bank & Trust could become an important part of Block's digital **** et custody infrastructure, giving the company a federally supervised framework for custody and related services involving bitcoin and stablecoins.
Builders Bank & Trust would be an uninsured national trust bank, meaning it would not accept deposits or make traditional loans. Instead, its focus would be on fiduciary and custody services, allowing Block to build specialized infrastructure for safeguarding digital **** ets.
The structure could be particularly valuable as Block, Inc. (NYSE:XYZ) seeks to expand its institutional customer base. A federally supervised custody operation could give larger financial institutions greater confidence in Block's ability to safeguard Bitcoin and other digital **** ets.
Stablecoins represent a potentially important opportunity for Block, particularly through its Cash App ecosystem. A regulated custody infrastructure could eventually support broader stablecoin-related products and payments if Block chooses to expand further in this area.
#Bitcoin


3 days ago
Conagra Brands, Inc. (NYSE:CAG) faces a governance test alongside its turnaround. Reuters reported on September 7 that Institutional Shareholder Services, or ISS, recommended opposing executive compensation, citing weak financial performance and inadequately explained incentive targets.
The September 23 non-binding advisory vote covers fiscal 2026 named-executive compensation. It does not separately approve new CEO John Brase's package. Brase succeeded Sean Connolly on June 1, after fiscal 2026 ended, separating his compensation arrangements from the prior year's pay decisions.
The proxy lists Brase's annual base salary at $1.15 million, his annual incentive target at 150% of eligible salary, and annual long-term incentives of $7.3 million, split 60% into performance shares and 40% into restricted stock units. Incentive opportunities are not guaranteed realized pay.
Conagra Brands, Inc. (NYSE:CAG) needs executives willing to work through changes whose benefits may take several years to appear. Brase's priorities include restoring margins, investing in brands and the supply chain, simplifying operations, and rebalancing capital allocation.
A mix of performance awards and service-based equity can support that effort. Performance shares link rewards to results, while restricted units help retain leaders through disruption. Retention has value if it allows management to complete difficult changes instead of optimizing the next quarterly result.
#performance
The September 23 non-binding advisory vote covers fiscal 2026 named-executive compensation. It does not separately approve new CEO John Brase's package. Brase succeeded Sean Connolly on June 1, after fiscal 2026 ended, separating his compensation arrangements from the prior year's pay decisions.
The proxy lists Brase's annual base salary at $1.15 million, his annual incentive target at 150% of eligible salary, and annual long-term incentives of $7.3 million, split 60% into performance shares and 40% into restricted stock units. Incentive opportunities are not guaranteed realized pay.
Conagra Brands, Inc. (NYSE:CAG) needs executives willing to work through changes whose benefits may take several years to appear. Brase's priorities include restoring margins, investing in brands and the supply chain, simplifying operations, and rebalancing capital allocation.
A mix of performance awards and service-based equity can support that effort. Performance shares link rewards to results, while restricted units help retain leaders through disruption. Retention has value if it allows management to complete difficult changes instead of optimizing the next quarterly result.
#performance

4 days ago
Stablecoin issuer Tether is expanding into the realm of private credit.
The company behind USDT coin (CRYPTO: $USDT) is partnering with British ******* et manager Fasanara Capital and putting $400 million U.S. into a fund that plans to use its stablecoin to move money globally.
Specifically, Tether and Fasanara Capital are joining forces to support StableFund, a private credit vehicle that aims to raise as much as $3 billion U.S. from institutional investors.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#stablecoin #credit
The company behind USDT coin (CRYPTO: $USDT) is partnering with British ******* et manager Fasanara Capital and putting $400 million U.S. into a fund that plans to use its stablecoin to move money globally.
Specifically, Tether and Fasanara Capital are joining forces to support StableFund, a private credit vehicle that aims to raise as much as $3 billion U.S. from institutional investors.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#stablecoin #credit

4 days ago
Options traders can spend hours searching for the right stock, studying charts, comparing fundamentals and trying to predict the market's next move.
But Barchart expert Rick Orford argues there's another question worth answering before any of that:
Options Flow Alert: Institutional Money Piles Into AMD Stock
Volatility Insurance for Applied Optoelectronics (AAOI) Stock Potentially Inspires a Contrarian Outlook
Unusual Options Activity Points to Big Institutional Bets on These 3 Industries
#options #institutional #money
But Barchart expert Rick Orford argues there's another question worth answering before any of that:
Options Flow Alert: Institutional Money Piles Into AMD Stock
Volatility Insurance for Applied Optoelectronics (AAOI) Stock Potentially Inspires a Contrarian Outlook
Unusual Options Activity Points to Big Institutional Bets on These 3 Industries
#options #institutional #money


4 days ago
Renowned Argentine journalist and influencer Flavio Azzaro has once again shaken up the world of sports media after openly stating his greatest institutional ambition: to become president of Racing Club.
During a live broadcast on his Azz Stream channel, the commentator expressed how firmly he views this life goal. "Everything I do in my life, consciously or unconsciously, is to become president of Racing," he stated categorically.
The statements from the Avellaneda journalist reaffirm his ambition to jump from media debate into the internal politics of "La Academia." The idea is for him to be able to run in the 2032 elections.
This article was translated into English by Artificial Intelligence. You can read the original version in 🇪🇸 here.
#journalist #argentine
During a live broadcast on his Azz Stream channel, the commentator expressed how firmly he views this life goal. "Everything I do in my life, consciously or unconsciously, is to become president of Racing," he stated categorically.
The statements from the Avellaneda journalist reaffirm his ambition to jump from media debate into the internal politics of "La Academia." The idea is for him to be able to run in the 2032 elections.
This article was translated into English by Artificial Intelligence. You can read the original version in 🇪🇸 here.
#journalist #argentine

4 days ago
Volatility has picked up in recent days as the market digests rising yields and oil prices along with seasonal headwinds. With everything going on, volatility could rear its ugly head again at any time.
The VIX Index closed at 16.46 yesterday after briefly dropping below 14 last week.
Unusual Options Activity Points to Big Institutional Bets on These 3 Industries
Volatility Insurance for Applied Optoelectronics (AAOI) Stock Potentially Inspires a Contrarian Outlook
A Rare Quant Signal Just Flashed for Contrarian Options Traders in Home Depot Stock
#Stock #index #points #bets
The VIX Index closed at 16.46 yesterday after briefly dropping below 14 last week.
Unusual Options Activity Points to Big Institutional Bets on These 3 Industries
Volatility Insurance for Applied Optoelectronics (AAOI) Stock Potentially Inspires a Contrarian Outlook
A Rare Quant Signal Just Flashed for Contrarian Options Traders in Home Depot Stock
#Stock #index #points #bets


4 days ago
On September 8, 2026, GE Aerospace (NYSE:GE) agreed to buy Consolidated Precision Products (CPP) for $11.75 billion. The acquisition marks the company's largest bet yet on precision engine castings, a constraint that has been capping GE's growth. Trading already at roughly 40x earnings, the company has now attacked one of its genuine bottlenecks through the deal. But has it paid too much to do it?
Castings, including the superalloy and ******* anium hot-section parts inside the jet engines, have constrained GE's engine production, including programs such as LEAP and GEnx, as well as its high-margin aftermarket. Without these castings, the company can neither build nor service its engines. If the acquisition closes, the company will gain access to CPP's 20-plus plants and about 6,600 workers, which are essential for making those components. The deal would therefore enable GE to control the constraint as well as defend its margins. CEO Larry Culp characterized the move as securing manufacturing capacity to meet simultaneous demand across commercial engines, aftermarket services, and defense contracts.
The valuation is where bulls should slow down. GE is paying roughly 18x 2027 EBITDA including synergies (26x without synergies). The sellers are private equity firms Warburg Pincus and Berkshire Partners. They have basically offloaded a cyclical business near the peak of the aerospace cycle. This is smart money selling to GE instead of the other way around. The real tell is that GE felt compelled to buy its way past this capacity bottleneck instead of scaling organically, which reveals how tight its prized aftermarket really was. Also, CPP also supplies other major aerospace and defense companies such as Pratt & Whitney, Honeywell, and Lockheed Martin, and through the vertical tie-up, the company invites antitrust scrutiny before it closes in late 2027.
GE's 40x multiple rests on its high-margin razor-and-blade business model that services a huge installed base. And the casting supply shortages quietly constrain this aftermarket. Hence, more than merely fixing a supply chain issue, the CPP acquisition defends the company's high margin and multiple. Financially, the transaction is accretive to adjusted EPS and free cash flow in the first year, funded through $7 billion in cash alongside newly issued debt. Insider Monkey data shows 113 hedge funds held GE in Q2 2026, down modestly from 119 in Q1, reflecting firm institutional positioning. Short interest is just 1.3% of float, below peers like Honeywell International (1.6%). Almost no one bets against it.
#aftermarket #acquisition #including
Castings, including the superalloy and ******* anium hot-section parts inside the jet engines, have constrained GE's engine production, including programs such as LEAP and GEnx, as well as its high-margin aftermarket. Without these castings, the company can neither build nor service its engines. If the acquisition closes, the company will gain access to CPP's 20-plus plants and about 6,600 workers, which are essential for making those components. The deal would therefore enable GE to control the constraint as well as defend its margins. CEO Larry Culp characterized the move as securing manufacturing capacity to meet simultaneous demand across commercial engines, aftermarket services, and defense contracts.
The valuation is where bulls should slow down. GE is paying roughly 18x 2027 EBITDA including synergies (26x without synergies). The sellers are private equity firms Warburg Pincus and Berkshire Partners. They have basically offloaded a cyclical business near the peak of the aerospace cycle. This is smart money selling to GE instead of the other way around. The real tell is that GE felt compelled to buy its way past this capacity bottleneck instead of scaling organically, which reveals how tight its prized aftermarket really was. Also, CPP also supplies other major aerospace and defense companies such as Pratt & Whitney, Honeywell, and Lockheed Martin, and through the vertical tie-up, the company invites antitrust scrutiny before it closes in late 2027.
GE's 40x multiple rests on its high-margin razor-and-blade business model that services a huge installed base. And the casting supply shortages quietly constrain this aftermarket. Hence, more than merely fixing a supply chain issue, the CPP acquisition defends the company's high margin and multiple. Financially, the transaction is accretive to adjusted EPS and free cash flow in the first year, funded through $7 billion in cash alongside newly issued debt. Insider Monkey data shows 113 hedge funds held GE in Q2 2026, down modestly from 119 in Q1, reflecting firm institutional positioning. Short interest is just 1.3% of float, below peers like Honeywell International (1.6%). Almost no one bets against it.
#aftermarket #acquisition #including


4 days ago
XRP trades at $1.44, up 40% in 30 days, but remains down 23% year-to-date and needs $1.84 to break even for 2026.
A Senate cloture vote on the CLARITY Act and an FOMC rate decision converge mid-month, but the House canceled September votes, pushing final crypto legislation into a lame-duck session.
The XRP Ledger earned BIS approval for recording official statistics hashes, adding long-term institutional demand context without predicting near-term price moves.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
XRP (CRYPTO:XRP) trades at about $1.42 on September 9, 2026, up roughly 38% from its $1.03 close a month ago and about 5.3% from its September 2 close. The move comes just ahead of two major U.S. events: a September 15 Senate cloture vote on the CLARITY Act and the Federal Reserve's September 15–16 policy meeting.
#september #vote
A Senate cloture vote on the CLARITY Act and an FOMC rate decision converge mid-month, but the House canceled September votes, pushing final crypto legislation into a lame-duck session.
The XRP Ledger earned BIS approval for recording official statistics hashes, adding long-term institutional demand context without predicting near-term price moves.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
XRP (CRYPTO:XRP) trades at about $1.42 on September 9, 2026, up roughly 38% from its $1.03 close a month ago and about 5.3% from its September 2 close. The move comes just ahead of two major U.S. events: a September 15 Senate cloture vote on the CLARITY Act and the Federal Reserve's September 15–16 policy meeting.
#september #vote


4 days ago
Answering a caller's query about Box, Inc. (NYSE:BOX) during the lightning round of Mad Money on September 3, Jim Cramer commented:
Box is finally, after multiple years, it is finally breaking out. It has good storage. People like storage. It's got a good CEO in Aaron Levie. It's just never been exciting to people. It's finally starting to get some mojo. I think it's okay to own. It's done nothing for years.
Cramer's perspective highlights a shifting narrative for a cloud pioneer that has historically traded in a tight range. In its fiscal second-quarter 2027 report, Box, Inc. (NYSE:BOX) posted revenue of $321.1 million, marking a 9.2% year-over-year increase that topped Wall Street expectations by over $2 million. Adjusted earnings per share reached $0.40, in line with consensus forecasts, while management raised full-year revenue guidance to approximately $1.29 billion. The core demand is supported by expanding adoption of higher-tier Box Suites, which now account for 69% of revenue, along with early traction in AI-driven document tools that help enterprises modernize legacy storage workflows.
Despite recent top-line acceleration, Box, Inc. (NYSE:BOX) operates in a fiercely competitive market dominated by massive tech ecosystems like Microsoft OneDrive and Google Drive, and other specialized rivals such as Dropbox. While quarterly growth has stabilized, Box's multi-year annual growth rate has historically lagged behind high-flying software peers. Furthermore, Box still needs to sustain its recent growth acceleration while investing in AI capabilities.
As per Insider Monkey's data of over 1000 hedge funds, 37 hedge funds had a stake in Box, Inc. (NYSE:BOX) in Q2 compared to 36 in Q1, highlighting steady institutional backing from long-term ***** et managers. Arrowstreet Capital remained the company's top hedge fund holder in Q2 with 4.3 million shares. Additionally, it is worth noting that another significant shareholder, Citadel Investment Group increased its position in the stock by 60% to over 3.7 million shares. The short percentage of float sits at 14.26%, which shows a notable segment of the market remains unconvinced about the sustainability of the breakout.
#NYSE #year #people
Box is finally, after multiple years, it is finally breaking out. It has good storage. People like storage. It's got a good CEO in Aaron Levie. It's just never been exciting to people. It's finally starting to get some mojo. I think it's okay to own. It's done nothing for years.
Cramer's perspective highlights a shifting narrative for a cloud pioneer that has historically traded in a tight range. In its fiscal second-quarter 2027 report, Box, Inc. (NYSE:BOX) posted revenue of $321.1 million, marking a 9.2% year-over-year increase that topped Wall Street expectations by over $2 million. Adjusted earnings per share reached $0.40, in line with consensus forecasts, while management raised full-year revenue guidance to approximately $1.29 billion. The core demand is supported by expanding adoption of higher-tier Box Suites, which now account for 69% of revenue, along with early traction in AI-driven document tools that help enterprises modernize legacy storage workflows.
Despite recent top-line acceleration, Box, Inc. (NYSE:BOX) operates in a fiercely competitive market dominated by massive tech ecosystems like Microsoft OneDrive and Google Drive, and other specialized rivals such as Dropbox. While quarterly growth has stabilized, Box's multi-year annual growth rate has historically lagged behind high-flying software peers. Furthermore, Box still needs to sustain its recent growth acceleration while investing in AI capabilities.
As per Insider Monkey's data of over 1000 hedge funds, 37 hedge funds had a stake in Box, Inc. (NYSE:BOX) in Q2 compared to 36 in Q1, highlighting steady institutional backing from long-term ***** et managers. Arrowstreet Capital remained the company's top hedge fund holder in Q2 with 4.3 million shares. Additionally, it is worth noting that another significant shareholder, Citadel Investment Group increased its position in the stock by 60% to over 3.7 million shares. The short percentage of float sits at 14.26%, which shows a notable segment of the market remains unconvinced about the sustainability of the breakout.
#NYSE #year #people


4 days ago
On September 3, a caller mentioned that they are unsure whether to buy, sell, or hold Intel Corporation (NASDAQ:INTC). In response, Mad Money host Jim Cramer said:
Okay, now, let's own this right up front. I got too excited about Intel because I knew it was going to have a good quarter. It had an unbelievable quarter, and the stock went down anyway... Here's the problem: The government has a huge position in it, and they're supposed to be able to sell it if they want to, and we're all waiting for the government to sell the stake, and that's why the stock's been going down. And I have been saying, listen, I may just have to go in and buy more right here, get a better average, and have it come back. I understand it is mixed, but my belief in Intel is 100%. I just need to see the government get out of the stock or just go buy it anyway.
Intel Corporation's (NASDAQ:INTC) fundamental business is finally turning a corner. The company blew past Wall Street estimates with $16.1 billion in second-quarter revenue, fueled by heavy demand for its Xeon data center chips and solid progress on its 18A manufacturing technology. For patient investors who watched management pour billions into rebuilding the company's chip-making muscle, these results offer encouraging signs that Intel's long-term comeback and push into AI hardware are starting to pay off.
Even with those solid numbers, the stock faces a major psychological roadblock: the federal government's massive equity stake. As Cramer noted, investors are sitting on their hands, worried about when and how that big block of shares might be sold off, creating a potential overhang on the stock. Adding to this narrative are structural headwinds in the foundry segment, which continues to report operating losses as it scales up capital-intensive fabrication infrastructure, leaving the stock vulnerable to sentiment-driven pullbacks.
Institutional interest reflects growing engagement along with the company's operational recovery. According to Insider Monkey's tracking data, 138 hedge funds held positions in Intel Corporation (NASDAQ:INTC) during the second quarter, marking an increase from 112 funds in the prior quarter. Short interest stands at 2.57% of the public float, showing a measured level of skepticism without aggressive bearish shorting.
#Intel #quarter #government #right
Okay, now, let's own this right up front. I got too excited about Intel because I knew it was going to have a good quarter. It had an unbelievable quarter, and the stock went down anyway... Here's the problem: The government has a huge position in it, and they're supposed to be able to sell it if they want to, and we're all waiting for the government to sell the stake, and that's why the stock's been going down. And I have been saying, listen, I may just have to go in and buy more right here, get a better average, and have it come back. I understand it is mixed, but my belief in Intel is 100%. I just need to see the government get out of the stock or just go buy it anyway.
Intel Corporation's (NASDAQ:INTC) fundamental business is finally turning a corner. The company blew past Wall Street estimates with $16.1 billion in second-quarter revenue, fueled by heavy demand for its Xeon data center chips and solid progress on its 18A manufacturing technology. For patient investors who watched management pour billions into rebuilding the company's chip-making muscle, these results offer encouraging signs that Intel's long-term comeback and push into AI hardware are starting to pay off.
Even with those solid numbers, the stock faces a major psychological roadblock: the federal government's massive equity stake. As Cramer noted, investors are sitting on their hands, worried about when and how that big block of shares might be sold off, creating a potential overhang on the stock. Adding to this narrative are structural headwinds in the foundry segment, which continues to report operating losses as it scales up capital-intensive fabrication infrastructure, leaving the stock vulnerable to sentiment-driven pullbacks.
Institutional interest reflects growing engagement along with the company's operational recovery. According to Insider Monkey's tracking data, 138 hedge funds held positions in Intel Corporation (NASDAQ:INTC) during the second quarter, marking an increase from 112 funds in the prior quarter. Short interest stands at 2.57% of the public float, showing a measured level of skepticism without aggressive bearish shorting.
#Intel #quarter #government #right


4 days ago
A cryptocurrency ETF is an exchange-traded fund that gives investors exposure to cryptocurrency through a regular brokerage account with no crypto wallet, exchange, or private keys required. The most important type is the spot ETF, which holds the actual cryptocurrency (Bitcoin, Ether, etc.) in secure custody, so the fund's price tracks the real-time price of the coin. When you buy a share, you're getting direct exposure to the underlying **** et, wrapped in the familiar, regulated ETF structure. One technical note: U.S. spot crypto funds are structured as exchange-traded products — grantor trusts registered under the Securities Act of 1933 — rather than as 1940 Act ETFs, so they trade just like ETFs but do not carry all of the same investor protections.
This is a big deal because it removes the biggest barriers to crypto investing: custody risk, exchange hacks, and technical complexity. It also brings crypto into tax-advantaged accounts and lets investors hold it alongside their stocks and bonds in one place.
Spot Bitcoin ETFs launched in the U.S. in January 2024 and have become the fastest-growing ETF category ever. In 2026 they dominate the crypto ETF landscape.
IBIT (iShares Bitcoin Trust) was one of the first to market and is the runaway leader, with roughly $71 billion in **** ets — well over half of the entire spot Bitcoin ETF market. BlackRock's fund has become the default vehicle for institutional and retail Bitcoin exposure alike, prized for its deep liquidity and low cost. FBTC (Fidelity Wise Origin Bitcoin Fund) is second with about $18 billion, and GBTC (Grayscale Bitcoin Trust), the converted legacy fund, holds around $15 billion despite its higher fee. For most investors seeking Bitcoin exposure, IBIT and FBTC are the go-to, low-cost choices.
Spot Ethereum ETFs followed in July 2024 and form the second pillar of the crypto ETF world. ETHA (iShares Ethereum Trust) leads with roughly $11 billion in **** ets, followed by FETH (Fidelity Ethereum Fund) at about $2.3 billion. Ethereum offers a different investment thesis than Bitcoin as it's the backbone of decentralized applications, smart contracts, and much of the tokenization trend. This means ether ETFs give investors exposure to a distinct part of the digital-asset ecosystem.
#Bitcoin
This is a big deal because it removes the biggest barriers to crypto investing: custody risk, exchange hacks, and technical complexity. It also brings crypto into tax-advantaged accounts and lets investors hold it alongside their stocks and bonds in one place.
Spot Bitcoin ETFs launched in the U.S. in January 2024 and have become the fastest-growing ETF category ever. In 2026 they dominate the crypto ETF landscape.
IBIT (iShares Bitcoin Trust) was one of the first to market and is the runaway leader, with roughly $71 billion in **** ets — well over half of the entire spot Bitcoin ETF market. BlackRock's fund has become the default vehicle for institutional and retail Bitcoin exposure alike, prized for its deep liquidity and low cost. FBTC (Fidelity Wise Origin Bitcoin Fund) is second with about $18 billion, and GBTC (Grayscale Bitcoin Trust), the converted legacy fund, holds around $15 billion despite its higher fee. For most investors seeking Bitcoin exposure, IBIT and FBTC are the go-to, low-cost choices.
Spot Ethereum ETFs followed in July 2024 and form the second pillar of the crypto ETF world. ETHA (iShares Ethereum Trust) leads with roughly $11 billion in **** ets, followed by FETH (Fidelity Ethereum Fund) at about $2.3 billion. Ethereum offers a different investment thesis than Bitcoin as it's the backbone of decentralized applications, smart contracts, and much of the tokenization trend. This means ether ETFs give investors exposure to a distinct part of the digital-asset ecosystem.
#Bitcoin


4 days ago
Wall Street has bid up defense contractors on geopolitical tensions alongside expanded missile-defense funding, but Northrop Grumman Corporation (NYSE:NOC) remains an outlier. On September 4, 2026, the company secured a $508.5 million Missile Defense Agency contract for ICBM and IRBM target flight-test support running through 2035. The non-competitive contract follows the $3 billion (approx.) in framework agreements to expand solid-rocket-motor production for PAC-3 and THAAD interceptors. Despite these bookings, stock slipped 2.5% to $515. The stock is trading near 16 times earnings and 33% below its peak, making Northrop one of the lowest-multiple prime defense contractors.
Northrop is one of the largest-cap defense contractors with exposure to Golden Dome through ******* e sensors and interceptors, while the Sentinel ICBM and the B-21 bomber provide additional exposure to broader U.S. strategic modernization. The recent bookings back that up: the $508.5 million MDA award, the ~$3 billion PAC-3 and THAAD agreements that will double and triple solid-rocket-motor capacity, and $1.4 billion of IBCS-related U.S. and Polish air-and-missile-defense awards announced in 2025. The latest MDA contract includes cost-plus, cost-reimbursable, and fixed-price-incentive elements, which reduce some financial exposure compared with purely fixed-price development work. Long-term missile-shield funding, however, remains tied to both political and defense bets. Legislative approval introduces timing risk, but the bull thesis is already working.
Execution problems explain the valuation discount. The Sentinel ICBM program triggered a critical Nunn-McCurdy breach after projected costs rose 81% to roughly $141 billion, forcing a Pentagon program restructuring. Concurrently, low-rate initial production on the B-21 bomber generated approximately $2 billion in pre-tax charges on fixed-price commitments. Management must demonstrate that these losses have ceased. Till then, multiple expansion will remain limited. Lockheed trades at roughly 19 times earnings compared with Northrop at about 16 times.
Institutional positioning does not point to aggressiveness in short trades. Our Insider Monkey database tracked 59 hedge funds holding NOC in the second quarter of 2026, compared to 62 in the first quarter. Short interest sits at 1.7% of the float, representing a low number of bets against the stock. Paired with -0.11 beta and a 1.9% dividend yield, the stock offers portfolio diversification at a discounted entry multiple.
#northrop
Northrop is one of the largest-cap defense contractors with exposure to Golden Dome through ******* e sensors and interceptors, while the Sentinel ICBM and the B-21 bomber provide additional exposure to broader U.S. strategic modernization. The recent bookings back that up: the $508.5 million MDA award, the ~$3 billion PAC-3 and THAAD agreements that will double and triple solid-rocket-motor capacity, and $1.4 billion of IBCS-related U.S. and Polish air-and-missile-defense awards announced in 2025. The latest MDA contract includes cost-plus, cost-reimbursable, and fixed-price-incentive elements, which reduce some financial exposure compared with purely fixed-price development work. Long-term missile-shield funding, however, remains tied to both political and defense bets. Legislative approval introduces timing risk, but the bull thesis is already working.
Execution problems explain the valuation discount. The Sentinel ICBM program triggered a critical Nunn-McCurdy breach after projected costs rose 81% to roughly $141 billion, forcing a Pentagon program restructuring. Concurrently, low-rate initial production on the B-21 bomber generated approximately $2 billion in pre-tax charges on fixed-price commitments. Management must demonstrate that these losses have ceased. Till then, multiple expansion will remain limited. Lockheed trades at roughly 19 times earnings compared with Northrop at about 16 times.
Institutional positioning does not point to aggressiveness in short trades. Our Insider Monkey database tracked 59 hedge funds holding NOC in the second quarter of 2026, compared to 62 in the first quarter. Short interest sits at 1.7% of the float, representing a low number of bets against the stock. Paired with -0.11 beta and a 1.9% dividend yield, the stock offers portfolio diversification at a discounted entry multiple.
#northrop

4 days ago
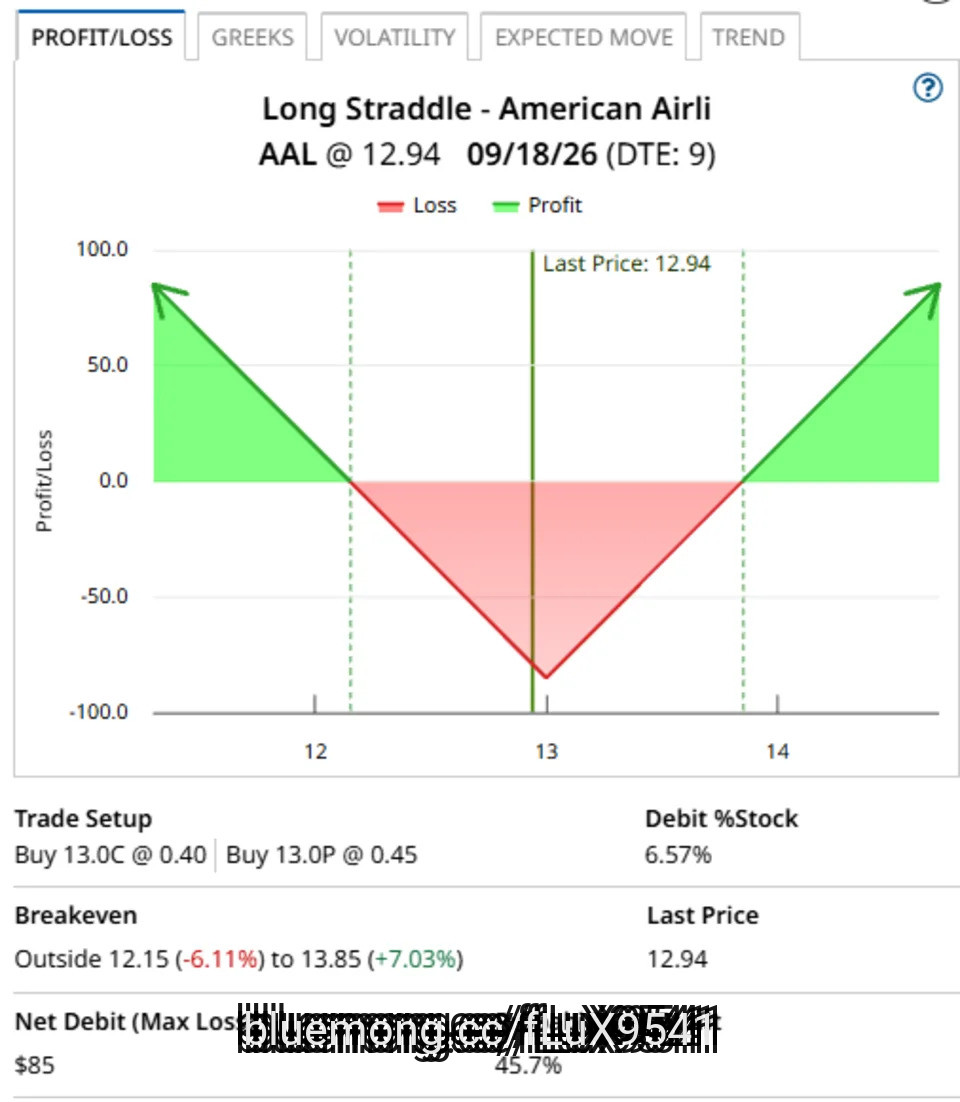
Heavy out-of-the-money put option volume in Shoe Station Group (SHOE) today, ahead of tomorrow's earnings, suggests investors expect a dip in SHOE stock. However, SHOE stock is cheap, and shorting puts yields over 7.7% over the next month.
SHOE is at $13.29 in midday trading, well off its recent peak of $16.11 a month ago on Aug. 10. This may be selling ahead of earnings.
Micron Price Targets Are Rising - Bull Put Credit Spreads in MU Are Attractive for Investors with Limited Funds
Options Flow Alert: Institutional Money Piles Into AMD Stock
Unusual Call Options Activity in Takeover Target GFL Environmental Stock
#Stock
SHOE is at $13.29 in midday trading, well off its recent peak of $16.11 a month ago on Aug. 10. This may be selling ahead of earnings.
Micron Price Targets Are Rising - Bull Put Credit Spreads in MU Are Attractive for Investors with Limited Funds
Options Flow Alert: Institutional Money Piles Into AMD Stock
Unusual Call Options Activity in Takeover Target GFL Environmental Stock
#Stock



5 days ago
Let's just get this out of the way: Mark Wahlberg is as A-list as it gets. He broke out in 1997's "Boogie Nights," and in the nearly three decades since, he's built one of the highest-wattage careers in Hollywood: two Academy Award nominations, a Golden Globe nod for "The Fighter," multiple Emmy nominations as a producer (HBO's "Entourage" among them), and a filmography that spans crime dramas, comedies, and action blockbusters. Right now, he's back on screen in "By Any Means," a manhunt thriller set during the 1966 Mississippi civil rights killings.
He's also signaling where he's increasingly turning his attention. Wahlberg will sit down with Bruce K. Lee, Founder and CEO of Keebeck Wealth Management, on the main stage at TechCrunch Disrupt 2026 to talk about his own progression. Grab your ticket here so you don't miss a moment of this session and Disrupt 2026. Ticket prices increase on September 25.
Image Credits:TechCrunch
His acting career is really just part of the picture. Over the past two decades, Wahlberg has built a production company, a restaurant chain, apparel and fitness ventures, a slate of angel investments, and the now 25-year-old Mark Wahlberg Youth Foundation, which supports inner-city kids and teens. He's used his Hollywood success to launch big projects well outside the movie business — and in a fireside chat at this year's Disrupt, he's going to give us a peek into how.
Wahlberg, who's leaned almost entirely on entrepreneurial instinct about people, culture, products, and markets, is now someone who's been building institutional-level investing discipline, with Lee as his guide, and with a growing focus on healthcare and wellness startups. It's a rare, unvarnished look at how someone with Wahlberg's cultural intelligence has worked his way into some of the most sophisticated rooms in business and finance.
#techcrunch #ticket #decades #nominations
He's also signaling where he's increasingly turning his attention. Wahlberg will sit down with Bruce K. Lee, Founder and CEO of Keebeck Wealth Management, on the main stage at TechCrunch Disrupt 2026 to talk about his own progression. Grab your ticket here so you don't miss a moment of this session and Disrupt 2026. Ticket prices increase on September 25.
Image Credits:TechCrunch
His acting career is really just part of the picture. Over the past two decades, Wahlberg has built a production company, a restaurant chain, apparel and fitness ventures, a slate of angel investments, and the now 25-year-old Mark Wahlberg Youth Foundation, which supports inner-city kids and teens. He's used his Hollywood success to launch big projects well outside the movie business — and in a fireside chat at this year's Disrupt, he's going to give us a peek into how.
Wahlberg, who's leaned almost entirely on entrepreneurial instinct about people, culture, products, and markets, is now someone who's been building institutional-level investing discipline, with Lee as his guide, and with a growing focus on healthcare and wellness startups. It's a rare, unvarnished look at how someone with Wahlberg's cultural intelligence has worked his way into some of the most sophisticated rooms in business and finance.
#techcrunch #ticket #decades #nominations


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

5 days ago
IG Wealth Management and Goldman Sachs ******* et Management have entered a partnership, covering a range of investment portfolios.
The arrangement links IG's financial planning operations with Goldman Sachs ******* et Management's investment management capabilities.
The firms are intended to give IG clients and retail investors in Canada access to diversified strategies spanning equities, fixed income and alternative ******* ets, using approaches previously used by institutional investors.
Goldman Sachs ******* et Management global head and multi-asset solutions co-chief investment officer and portfolio manager Alexandra Wilson-Elizondo said: "We believe a modern approach to ******* et allocation, dynamic investment strategies, robust risk management processes and well-diversified portfolios help clients achieve their objectives across market environments.
"We are excited to partner with IG to bring the capabilities of our Multi-Asset Solutions team to IG's clients across Canada."
#goldman #sachs #canada #portfolios
The arrangement links IG's financial planning operations with Goldman Sachs ******* et Management's investment management capabilities.
The firms are intended to give IG clients and retail investors in Canada access to diversified strategies spanning equities, fixed income and alternative ******* ets, using approaches previously used by institutional investors.
Goldman Sachs ******* et Management global head and multi-asset solutions co-chief investment officer and portfolio manager Alexandra Wilson-Elizondo said: "We believe a modern approach to ******* et allocation, dynamic investment strategies, robust risk management processes and well-diversified portfolios help clients achieve their objectives across market environments.
"We are excited to partner with IG to bring the capabilities of our Multi-Asset Solutions team to IG's clients across Canada."
#goldman #sachs #canada #portfolios

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

5 days ago
ZETA combines data, AI, automation, and execution into a single platform to turn data into strategic decisions with measurable outcomes – and its initial marketing focus is broadening. The company's second-quarter 2026 report showed $443 million in revenue (a 44% year-over-year gain), adjusted EBITDA of $92 million (a 56% jump), net income of $8.2 million or $0.03 per share (after a loss of nearly $13 million the prior quarter), and offered full-year EPS guidance of $0.11.
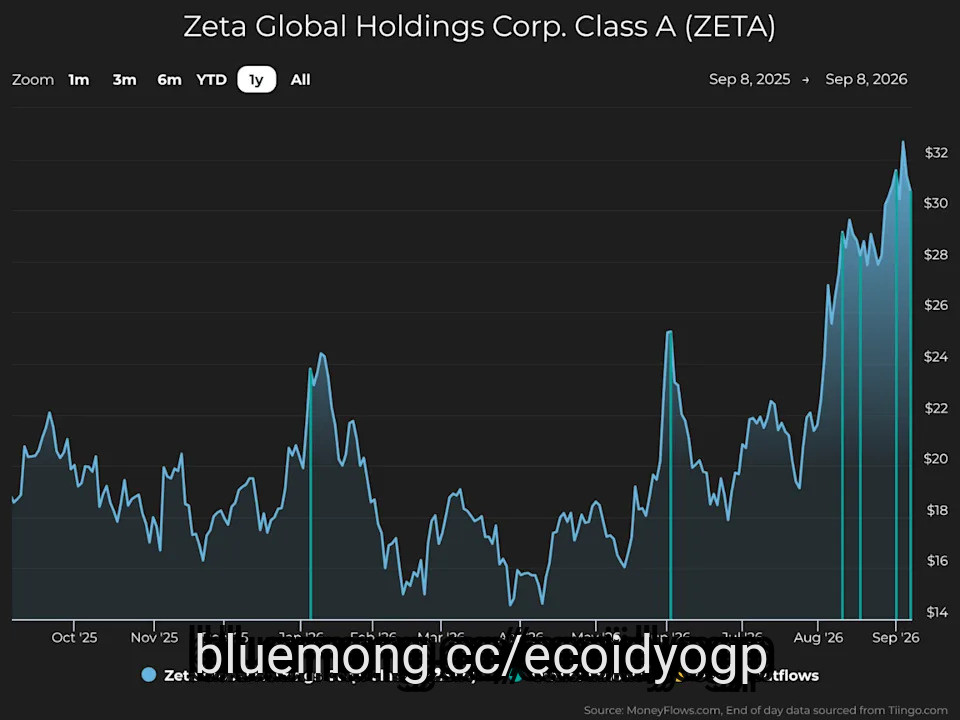
It's no wonder ZETA shares are up 51% this year – and they could rise more. MoneyFlows data shows how Big Money investors are once again betting heavily on the forward picture of the stock.
Institutional volumes reveal plenty. In the last year, ZETA has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in ZETA shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of technology names are under accumulation right now. But there's a powerful fundamental story happening with Zeta Global.
#million #data #institutional #quarter
It's no wonder ZETA shares are up 51% this year – and they could rise more. MoneyFlows data shows how Big Money investors are once again betting heavily on the forward picture of the stock.
Institutional volumes reveal plenty. In the last year, ZETA has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in ZETA shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of technology names are under accumulation right now. But there's a powerful fundamental story happening with Zeta Global.
#million #data #institutional #quarter

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

5 days ago
OKTA offers an enterprise identity management platform, including single sign-on, multi-factor authentication, access gateway, API access management, authentication, adaptive MFA, lifecycle management, and AI agent security. OKTA's second-quarter 2027 report showed $805 million in revenue (an 11% year-over-year gain), per-share earnings of $1.05 (a 15.4% sequential gain), and offered full-year revenue and operating margin guidance of up to $3.226 billion and 26%, respectively.
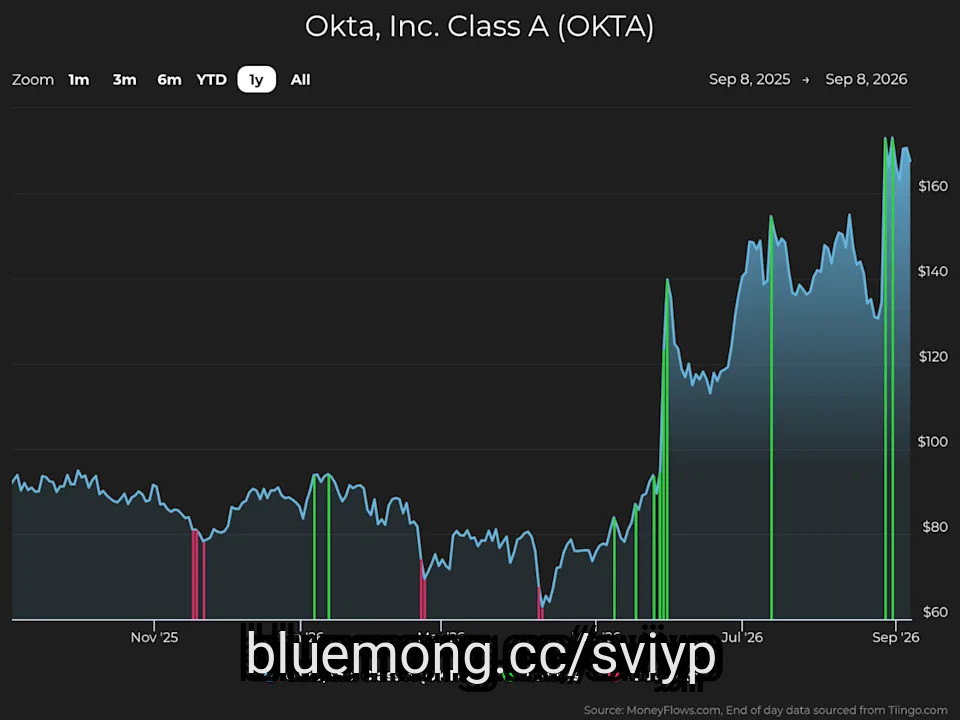
No wonder OKTA shares are up 94% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock.
Institutional volumes reveal plenty. In the last year, OKTA has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in OKTA shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of technology names are under accumulation right now. But there's a powerful fundamental story happening with Okta.
#year #plenty #authentication
No wonder OKTA shares are up 94% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock.
Institutional volumes reveal plenty. In the last year, OKTA has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in OKTA shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of technology names are under accumulation right now. But there's a powerful fundamental story happening with Okta.
#year #plenty #authentication
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
5 days ago
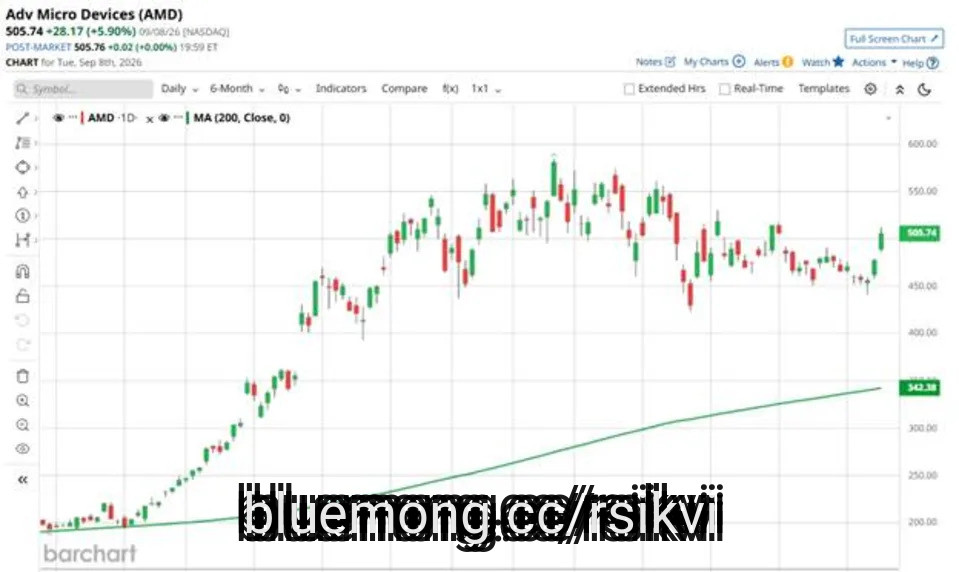
Advanced Micro Devices (AMD) has been one of the standout performers of 2026, already up around 136% year-to-date as the market rewards its accelerating push into AI data center chips.
The options flow from today suggests institutional traders are positioning for this AI-driven rally to keep running.
Micron Price Targets Are Rising - Bull Put Credit Spreads in MU Are Attractive for Investors with Limited Funds
Unusual Call Options Activity in Takeover Target GFL Environmental Stock
Get Paid to Wait: Buy OXY at a Discount or Earn Options Income
#micro #rising #credit
The options flow from today suggests institutional traders are positioning for this AI-driven rally to keep running.
Micron Price Targets Are Rising - Bull Put Credit Spreads in MU Are Attractive for Investors with Limited Funds
Unusual Call Options Activity in Takeover Target GFL Environmental Stock
Get Paid to Wait: Buy OXY at a Discount or Earn Options Income
#micro #rising #credit

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

5 days ago
Newark, New Jersey-based Prudential Financial, Inc. (PRU) is a diversified global financial services company that helps individuals and institutions protect wealth, prepare for retirement and pursue long-term financial goals. Valued at a market cap of $41.2 billion, its businesses span life insurance, annuities, retirement solutions, group insurance and investment management through PGIM, its global ****** et-management arm.
Companies with a market cap of $10 billion or more are typically referred to as "big-cap stocks." PRU fits right into that category. Prudential dominates the market due to its diversified insurance, retirement and investment-management businesses, which provide multiple sources of earnings and reduce reliance on any single market or product. Its established brand, extensive distribution network, large institutional and individual customer base and PGIM ****** et-management platform support scale, recurring fee income and cross-selling opportunities.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ****** ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#management #financial #prudential #Stock
Companies with a market cap of $10 billion or more are typically referred to as "big-cap stocks." PRU fits right into that category. Prudential dominates the market due to its diversified insurance, retirement and investment-management businesses, which provide multiple sources of earnings and reduce reliance on any single market or product. Its established brand, extensive distribution network, large institutional and individual customer base and PGIM ****** et-management platform support scale, recurring fee income and cross-selling opportunities.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ****** ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#management #financial #prudential #Stock


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
5 days ago
GFL Environmental Inc. (NYSE:GFL) completed its acquisition of SECURE Waste Infrastructure, adding a specialized waste and energy-infrastructure platform across Western Canada and North Dakota. At the announcement, the transaction had a C$6.4 billion enterprise value, with shareholder consideration comprising 80% GFL shares and 20% cash.
Closing required the issuance of 75,126,306 subordinate voting shares, capacity under the revolving credit facility, and a new US$1 billion senior secured term loan. The loan matures in August 2033 and carries interest at the Secured Overnight Financing Rate plus 200 basis points. GFL Environmental Inc. (NYSE:GFL) estimates an interest rate of approximately 5% after its cross-currency interest-rate swaps.
SECURE brings a difficult-to-replicate network spanning more than 80 locations, including landfills, waste-treatment and recycling facilities, injection wells and transfer stations. It also operates crude oil terminals, storage facilities and pipeline-connected infrastructure. The ****** ets broaden services and operating density in Western Canada.
More than 2,000 SECURE employees are joining the combined company. SECURE President and Chief Executive Officer Allen Gransch and other managers will continue leading the acquired operations as employees and shareholders. Retaining the operating team should help preserve customer relationships and institutional knowledge during integration.
The acquisition cost is spread across debt and equity. The 2033 maturity provides time for cash generation, while management said the term-loan transaction did not affect the company's credit rating.
#secure
Closing required the issuance of 75,126,306 subordinate voting shares, capacity under the revolving credit facility, and a new US$1 billion senior secured term loan. The loan matures in August 2033 and carries interest at the Secured Overnight Financing Rate plus 200 basis points. GFL Environmental Inc. (NYSE:GFL) estimates an interest rate of approximately 5% after its cross-currency interest-rate swaps.
SECURE brings a difficult-to-replicate network spanning more than 80 locations, including landfills, waste-treatment and recycling facilities, injection wells and transfer stations. It also operates crude oil terminals, storage facilities and pipeline-connected infrastructure. The ****** ets broaden services and operating density in Western Canada.
More than 2,000 SECURE employees are joining the combined company. SECURE President and Chief Executive Officer Allen Gransch and other managers will continue leading the acquired operations as employees and shareholders. Retaining the operating team should help preserve customer relationships and institutional knowledge during integration.
The acquisition cost is spread across debt and equity. The 2033 maturity provides time for cash generation, while management said the term-loan transaction did not affect the company's credit rating.
#secure

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

7 days ago
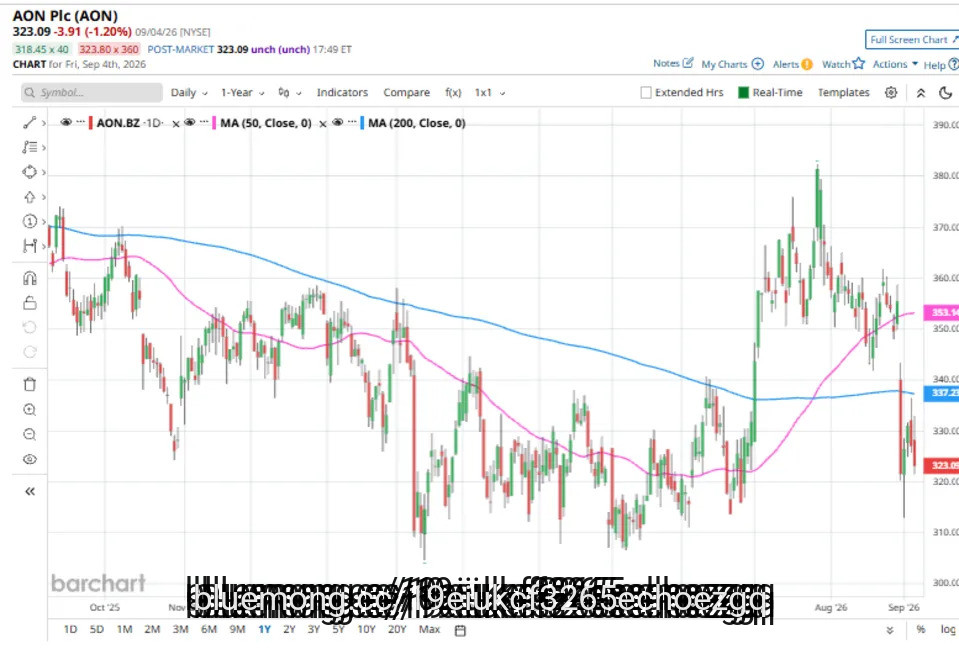
Dublin, Ireland-based Aon plc (AON) is a global professional services firm that helps businesses manage two critical challenges: risk and people. Valued at a market cap of $68.5 billion, the company delivers data-driven solutions to corporate, institutional, and commercial clients to reduce operational volatility and optimize workforce performance.
Companies valued at $10 billion or more are typically classified as "large-cap stocks," and AON fits the label perfectly, with its market cap exceeding this threshold, underscoring its size, influence, and dominance within the insurance brokers industry. Aon's competitive advantage lies in its global scale, proprietary data and ****** ytics, and broad risk and human capital expertise. Its presence across more than 120 countries, combined with a diversified client base, supports a strong international network and helps it serve complex, multinational clients.
How to Play SNPS Stock as Layoffs Hit Synopsys
Micron Stock More Than Tripled in 2026. Now Taiwan Strike Threat Could Shake the AI Boom.
Dear Adobe Stock Fans, Mark Your Calendars for September 10
#risk #market
Companies valued at $10 billion or more are typically classified as "large-cap stocks," and AON fits the label perfectly, with its market cap exceeding this threshold, underscoring its size, influence, and dominance within the insurance brokers industry. Aon's competitive advantage lies in its global scale, proprietary data and ****** ytics, and broad risk and human capital expertise. Its presence across more than 120 countries, combined with a diversified client base, supports a strong international network and helps it serve complex, multinational clients.
How to Play SNPS Stock as Layoffs Hit Synopsys
Micron Stock More Than Tripled in 2026. Now Taiwan Strike Threat Could Shake the AI Boom.
Dear Adobe Stock Fans, Mark Your Calendars for September 10
#risk #market


7 days ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and ******* ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
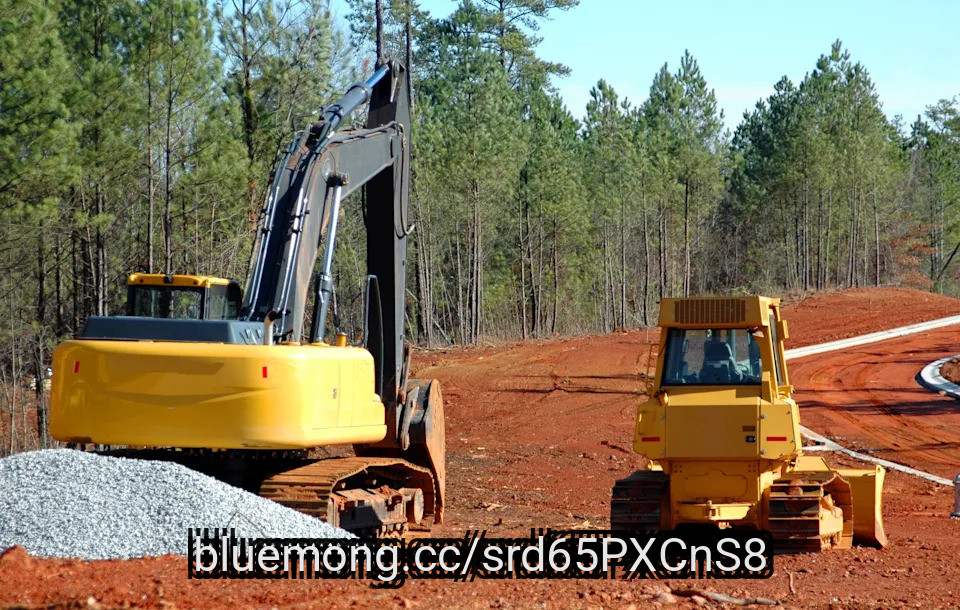
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like CNH Industrial N.V. (NYSE:CNH). CNH Industrial N.V. manufactures and sells specialized machines and services for the farming and construction industries. The one-month return of CNH Industrial N.V. (NYSE:CNH) was 30.96% while its shares traded between $9.00 and $14.46 over the last 52 weeks. On September 7, 2026, CNH Industrial N.V. (NYSE:CNH) stock closed at approximately $14.40 per share, with a market capitalization of about $22.02 billion.
Moerus Worldwide Fund stated the following regarding CNH Industrial N.V. (NYSE:CNH) in its Q2 2026 investor letter:
"We also initiated a position in shares of CNH Industrial N.V. (NYSE:CNH) in H1. CNH Industrial manufactures and sells specialized machines and services for the farming and construction industries under the Case IH and New Holland brands. The production of high horsepower agricultural equipment (i.e. tractors, combines, etc.) for professional farmers is an oligopoly, of which CNH is the second largest original equipment manufacturer behind John Deere."
#NYSE #investor #letter
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like CNH Industrial N.V. (NYSE:CNH). CNH Industrial N.V. manufactures and sells specialized machines and services for the farming and construction industries. The one-month return of CNH Industrial N.V. (NYSE:CNH) was 30.96% while its shares traded between $9.00 and $14.46 over the last 52 weeks. On September 7, 2026, CNH Industrial N.V. (NYSE:CNH) stock closed at approximately $14.40 per share, with a market capitalization of about $22.02 billion.
Moerus Worldwide Fund stated the following regarding CNH Industrial N.V. (NYSE:CNH) in its Q2 2026 investor letter:
"We also initiated a position in shares of CNH Industrial N.V. (NYSE:CNH) in H1. CNH Industrial manufactures and sells specialized machines and services for the farming and construction industries under the Case IH and New Holland brands. The production of high horsepower agricultural equipment (i.e. tractors, combines, etc.) for professional farmers is an oligopoly, of which CNH is the second largest original equipment manufacturer behind John Deere."
#NYSE #investor #letter

7 days ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and **** ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Douglas Elliman Inc. (NYSE:DOUG). Douglas Elliman Inc. is a residential real estate brokerage company with a strong presence in high-end U.S. housing markets. The one-month return of Douglas Elliman Inc. (NYSE:DOUG) was -2.19% while its shares traded between $1.5300 and $3.1900 over the last 52 weeks. On September 7, 2026, Douglas Elliman Inc. (NYSE:DOUG) stock closed at approximately $1.8100 per share, with a market capitalization of about $162.69 million.
Moerus Worldwide Fund stated the following regarding Douglas Elliman Inc. (NYSE:DOUG) in its Q2 2026 investor letter:
"Outside of Materials, other meaningful detractors from H1 came from different industries but were similarly impacted by various concerns related to the war and its effects in various areas, including real estate activity (Douglas Elliman Inc. (NYSE:DOUG)) given heightened inflation concerns and increased interest rate expectations. We would argue that the current valuations of each of these holdings are unusually modest, belying the formidable, leading presence that each boasts in its respective markets."
#douglas #NYSE
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Douglas Elliman Inc. (NYSE:DOUG). Douglas Elliman Inc. is a residential real estate brokerage company with a strong presence in high-end U.S. housing markets. The one-month return of Douglas Elliman Inc. (NYSE:DOUG) was -2.19% while its shares traded between $1.5300 and $3.1900 over the last 52 weeks. On September 7, 2026, Douglas Elliman Inc. (NYSE:DOUG) stock closed at approximately $1.8100 per share, with a market capitalization of about $162.69 million.
Moerus Worldwide Fund stated the following regarding Douglas Elliman Inc. (NYSE:DOUG) in its Q2 2026 investor letter:
"Outside of Materials, other meaningful detractors from H1 came from different industries but were similarly impacted by various concerns related to the war and its effects in various areas, including real estate activity (Douglas Elliman Inc. (NYSE:DOUG)) given heightened inflation concerns and increased interest rate expectations. We would argue that the current valuations of each of these holdings are unusually modest, belying the formidable, leading presence that each boasts in its respective markets."
#douglas #NYSE


7 days ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and ****** ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Tidewater Inc. (NYSE:TDW). Tidewater Inc. is an offshore supply vessel operator that provides support services to the offshore energy industry. Moerus identified Tidewater as one of the Fund's five most significant positive contributors during the first half of 2026. The one-month return of Tidewater Inc. (NYSE:TDW) was 3.68% while its shares traded between $46.65 and $101.58 over the last 52 weeks. On September 7, 2026, Tidewater Inc. (NYSE:TDW) stock closed at approximately $94.26 per share, with a market capitalization of about $4.61 billion.
Moerus Worldwide Fund stated the following regarding Tidewater Inc. (NYSE:TDW) in its Q2 2026 investor letter:
"Similarly, we'd argue that offshore supply vessel (OSV) operator Tidewater Inc. (NYSE:TDW) has grown the per share value of its business dramatically since 2018 through a combination of a relentless focus on costs, share repurchases, and most notably, the utilization of its OSV industry-leading balance sheet to make three acquisitions of ****** ets (with a fourth pending) from distressed and/or motivated sellers at deep discounts to replacement costs during a years-long industry depression."
#tidewater #fund #energy #second
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Tidewater Inc. (NYSE:TDW). Tidewater Inc. is an offshore supply vessel operator that provides support services to the offshore energy industry. Moerus identified Tidewater as one of the Fund's five most significant positive contributors during the first half of 2026. The one-month return of Tidewater Inc. (NYSE:TDW) was 3.68% while its shares traded between $46.65 and $101.58 over the last 52 weeks. On September 7, 2026, Tidewater Inc. (NYSE:TDW) stock closed at approximately $94.26 per share, with a market capitalization of about $4.61 billion.
Moerus Worldwide Fund stated the following regarding Tidewater Inc. (NYSE:TDW) in its Q2 2026 investor letter:
"Similarly, we'd argue that offshore supply vessel (OSV) operator Tidewater Inc. (NYSE:TDW) has grown the per share value of its business dramatically since 2018 through a combination of a relentless focus on costs, share repurchases, and most notably, the utilization of its OSV industry-leading balance sheet to make three acquisitions of ****** ets (with a fourth pending) from distressed and/or motivated sellers at deep discounts to replacement costs during a years-long industry depression."
#tidewater #fund #energy #second
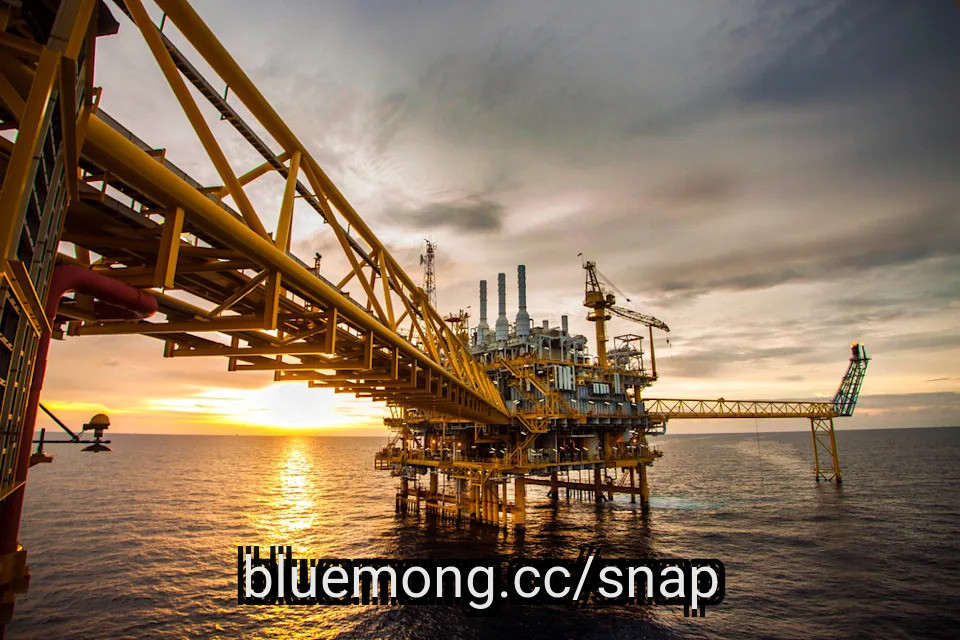

7 days ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and ******* ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Transocean Ltd. (NYSE:RIG) while discussing its investment in Valaris. Transocean Ltd. is an offshore drilling contractor. Moerus discussed the company in connection with its agreement to acquire Valaris in an all-stock transaction, which it said helped surface significant latent value in Valaris. The one-month return of Transocean Ltd. (NYSE:RIG) was 2.53% while its shares traded between $3.01 and $7.66 over the last 52 weeks. On September 7, 2026, Transocean Ltd. (NYSE:RIG) stock closed at approximately $5.85 per share, with a market capitalization of about $6.56 billion.
Moerus Worldwide Fund stated the following regarding Transocean Ltd. (NYSE:RIG) in its Q2 2026 investor letter:
"Shares of this U.S.-based provider of offshore drilling services surged in response to the February 9th announcement that the company had agreed to be acquired by Transocean Ltd. (NYSE:RIG) in an all-stock transaction, which was priced at a roughly 32% premium to Valaris' stock price (based on the previous day's closing price of each stock)."
#valaris
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Transocean Ltd. (NYSE:RIG) while discussing its investment in Valaris. Transocean Ltd. is an offshore drilling contractor. Moerus discussed the company in connection with its agreement to acquire Valaris in an all-stock transaction, which it said helped surface significant latent value in Valaris. The one-month return of Transocean Ltd. (NYSE:RIG) was 2.53% while its shares traded between $3.01 and $7.66 over the last 52 weeks. On September 7, 2026, Transocean Ltd. (NYSE:RIG) stock closed at approximately $5.85 per share, with a market capitalization of about $6.56 billion.
Moerus Worldwide Fund stated the following regarding Transocean Ltd. (NYSE:RIG) in its Q2 2026 investor letter:
"Shares of this U.S.-based provider of offshore drilling services surged in response to the February 9th announcement that the company had agreed to be acquired by Transocean Ltd. (NYSE:RIG) in an all-stock transaction, which was priced at a roughly 32% premium to Valaris' stock price (based on the previous day's closing price of each stock)."
#valaris
7 days ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and ****** ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Valaris Limited (NYSE:VAL). Valaris Limited is a U.S.-based provider of offshore drilling services. Moerus described Valaris as its largest individual contributor to performance in the first half of 2026. The one-month return of Valaris Limited (NYSE:VAL) was 1.62% while its shares traded between $46.70 and $114.12 over the last 52 weeks. On September 7, 2026, Valaris Limited (NYSE:VAL) stock closed at approximately $86.74 per share, with a market capitalization of about $6.03 billion.
Moerus Worldwide Fund stated the following regarding Valaris Limited (NYSE:VAL) in its Q2 2026 investor letter:
"For example, consider Valaris Limited (NYSE:VAL), the largest individual contributor to performance in H1. Shares of this U.S.-based provider of offshore drilling services surged in response to the February 9th announcement that the company had agreed to be acquired by Transocean in an all-stock transaction, which was priced at a roughly 32% premium to Valaris' stock price (based on the previous day's closing price of each stock). Valaris was added to the Fund in early 2025 following a slide in its share price, amid then-subdued oil prices and what we believed to be a temporary lull in offshore drilling activity caused by support infrastructure constraints (among other factors)."
#worldwide #Stock
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Valaris Limited (NYSE:VAL). Valaris Limited is a U.S.-based provider of offshore drilling services. Moerus described Valaris as its largest individual contributor to performance in the first half of 2026. The one-month return of Valaris Limited (NYSE:VAL) was 1.62% while its shares traded between $46.70 and $114.12 over the last 52 weeks. On September 7, 2026, Valaris Limited (NYSE:VAL) stock closed at approximately $86.74 per share, with a market capitalization of about $6.03 billion.
Moerus Worldwide Fund stated the following regarding Valaris Limited (NYSE:VAL) in its Q2 2026 investor letter:
"For example, consider Valaris Limited (NYSE:VAL), the largest individual contributor to performance in H1. Shares of this U.S.-based provider of offshore drilling services surged in response to the February 9th announcement that the company had agreed to be acquired by Transocean in an all-stock transaction, which was priced at a roughly 32% premium to Valaris' stock price (based on the previous day's closing price of each stock). Valaris was added to the Fund in early 2025 following a slide in its share price, amid then-subdued oil prices and what we believed to be a temporary lull in offshore drilling activity caused by support infrastructure constraints (among other factors)."
#worldwide #Stock