6 days ago
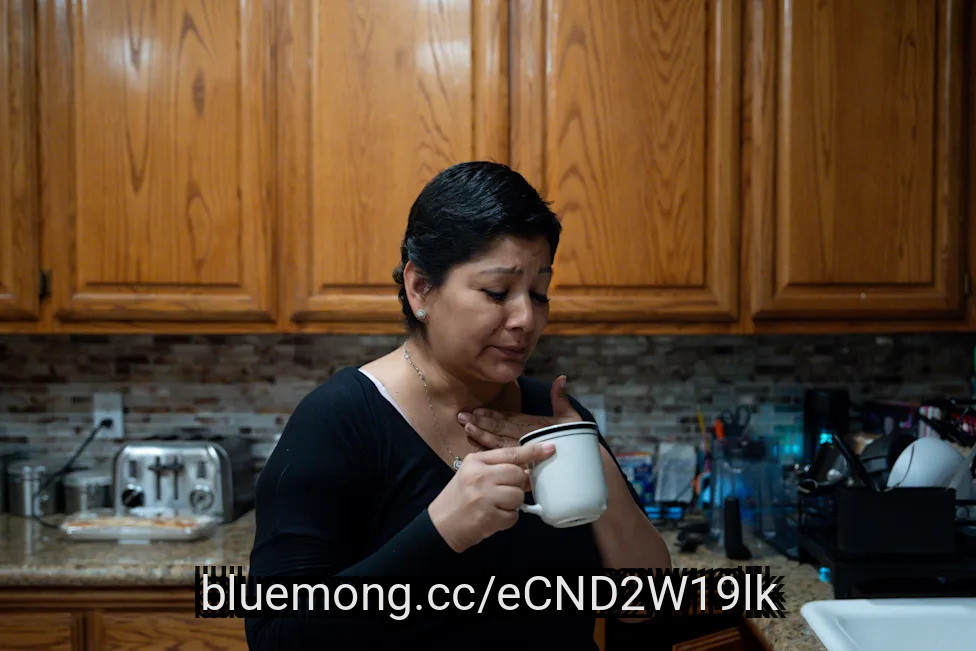
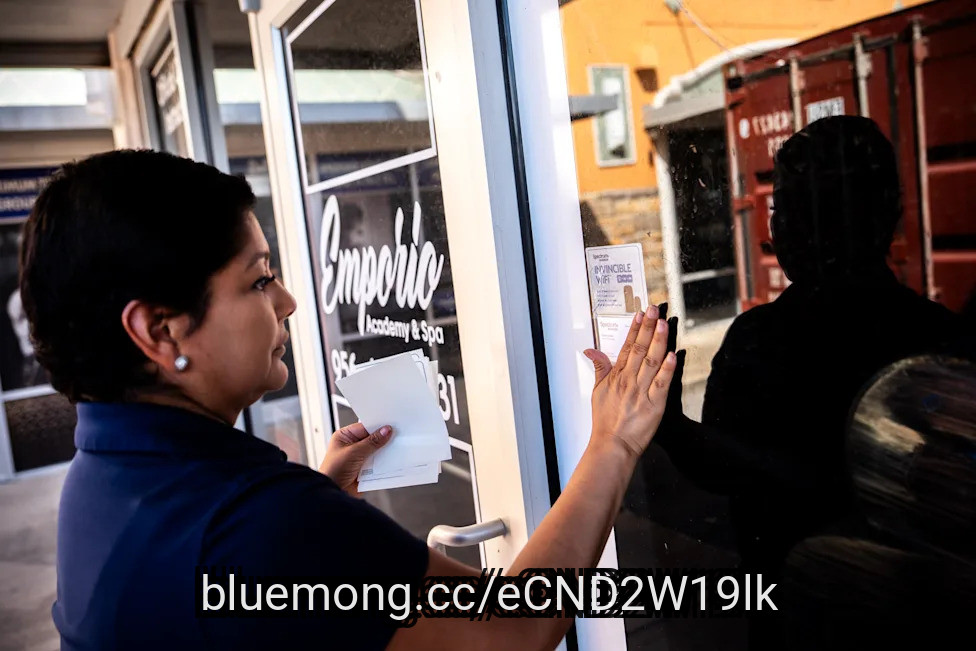
McALLEN, Texas (AP) — The Ford Expedition rumbled to a stop and Cindy Banda's bedazzled flip-flops landed on the asphalt of the Houston cancer center's vast parking lot. She threaded through the rows of cars, a tally of patients who gather here to sit with chemotherapy needles or lie on radiation machines.
The elevator dinged open. A year ago in this building, surgeons removed Banda's right breast, and she still didn't know whether treatment had expunged the cancer from her body. Doctors had told her it would be tough to beat.
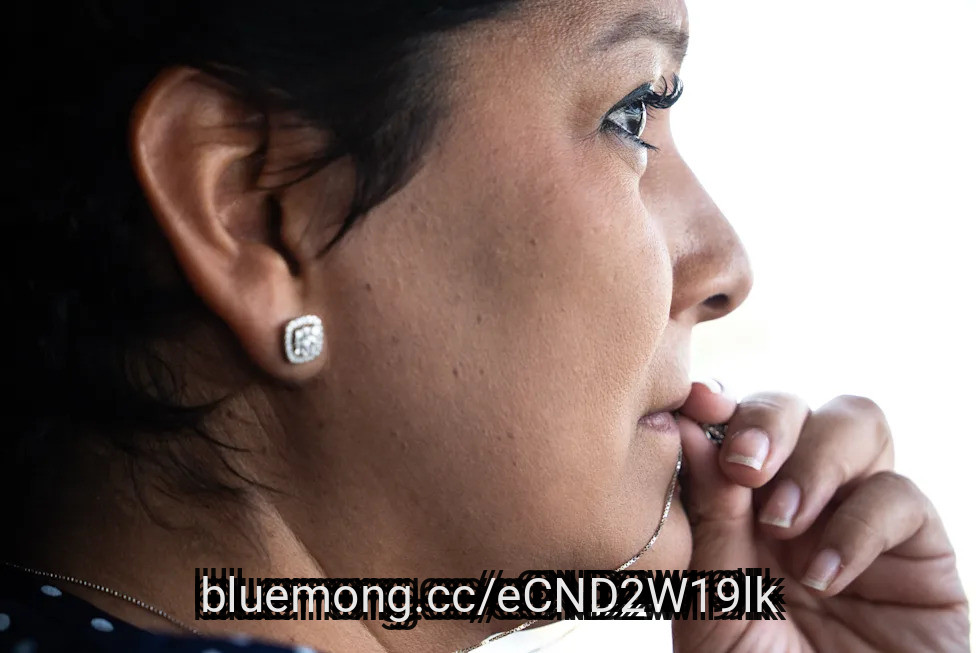
"I'm more of a positive person myself," Banda said, now sitting with a white wristband in a dim waiting room. But the bills are harder to dismiss, and the single mother with six children in her care repeated something like a mantra. "Keep the house. Keep the cars. And just keep the kids stable."
That's true for many Americans, as rising healthcare costs leave more families with a sinking feeling after seeing the bill for surgery or medication. Heading into the Nov. 3 midterm elections, about half of registered voters said healthcare costs are a major problem for them and their families, up from a little more than one-third four years ago, according to a Fox News poll from September.
With party control of Congress at stake, registered voters are nearly twice as likely to say they trust Democrats over Republicans to handle healthcare, according to an ******* ociated Press-NORC Center for Public Affairs Research poll from the same month. Those frustrations, combined with broader concerns over rising prices, have sapped support for President Donald Trump and his Republican Party.
#keep #cancer #rising #families

1 month ago
On September 8, 2026, Reuters reported that ASML Holding N.V. (NASDAQ:ASML) plans to work with major customers. It includes Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM), Nvidia, Intel, Samsung, and SK Hynix to adapt its next-generation "High NA" extreme ultraviolet lithography tools so they can print larger data-center chips. It addresses a current limitation where the newer machines use a smaller mask than ASML's widely deployed standard EUV tools.
ASML targets a pilot production line using the larger masks by 2031 and high-volume manufacturing readiness by 2033. Chief technology officer Marco Pieters said these changes could lift the productivity of these systems by roughly 40%.
The larger-mask project could create a new growth opportunity for ASML Holding N.V. (NASDAQ:ASML) while helping TSMC manufacture larger AI chips more efficiently. ASML plans to use its High NA EUV tools to handle chips as large as today's biggest data-center processors. The business expects the larger masks to increase system productivity by 40%. It could scale up demand for its next-generation equipment and help TSMC improve the economics of producing increasingly large and complex chips.
Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM)'s planned use gives ASML a clear path toward commercializing the technology. TSMC plans to introduce High NA EUV into advanced-node high-volume production from 2030. ASML aims to show its larger-mask technology through a pilot line in 2031. TSMC's commitment could give ASML greater visibility into future equipment demand. Early use could help TSMC maintain its advanced-chip manufacturing advantage.
The collaboration could solidify both companies' positions as chipmakers develop larger and more powerful processors. ASML can extend its High NA roadmap beyond its current chip-size limitation. TSMC can prepare its manufacturing processes for the next generation of AI chips. The partnership gives ASML an opportunity to deepen its relationship with one of its largest customers and gives TSMC access to a technology that could support future advanced-chip production.
#asml #technology #plans #next


1 month ago
ResMed Inc. (NYSE:RMD) is well positioned to benefit from the long-term growth of the global obstructive sleep apnea (OSA) treatment market. Likewise, the company remains well positioned to benefit from growing awareness and penetration in the global market, backed by a robust product portfolio.
The company's OSA portfolio includes CPAP and APAP machines, led by the AirSense platform. The AirSense 10 series is one of the most widely used CPAP and APAP machine series. Beyond sleep therapy machines, it also offers nasal, nasal-pillow, and full-face masks, along with a wide range of accessories and related products.
The broad product portfolio offers multiple avenues for generating recurring revenue beyond the initial sale of a sleep therapy device.
Monkey Business Images/Shutterstock.com
In the fourth quarter of fiscal 2026, ResMed's revenue increased 9% year over year to $1.5 billion, supported by strong demand for sleep devices, masks, and accessories. Americas device revenue increased 6%, while total Americas Sleep and Breathing Health revenue rose 8%. Americas masks and other revenue increased 10%. The stronger performance is particularly important as it highlights the ability to monetize the installed patient base beyond the initial device purchase.
#sleep #increased

1 month ago
International Business Machines (IBM) has secured a landmark $1 billion federal award from the U.S. Department of Commerce under the CHIPS and Science Act. The deal finalized non-dilutive funding to accelerate quantum wafer manufacturing at Anderon, a dedicated quantum foundry company spun out by IBM.
At the time of writing, IBM shares are down about 17% versus the start of this year.
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#international #commerce
At the time of writing, IBM shares are down about 17% versus the start of this year.
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#international #commerce


1 month ago
On August 25, Aptiv (NYSE:APTV) said it will support NVIDIA's newly announced Jetson Orin Nano 2 processor, extending a partnership that already covers the more powerful Jetson Thor platform. The move puts Aptiv squarely inside the buildout of "physical AI," the term for machines like drones, robots, and industrial systems that need to sense and react to the real world in real time. For a company still just months removed from spinning off its electrical distribution business, betting on edge robotics is a statement about where it thinks the next decade of growth actually lives.
NVIDIA's Jetson Orin Nano 2 packs 78 TOPS of processing power into an 8GB, 8-core Arm chip that doubles the inference speed of its predecessor while cutting power draw by 40% at equivalent performance. That kind of efficiency gain matters for battery-powered devices like delivery drones and mobile robots, where every watt saved extends run time. Aptiv isn't just supplying compute support; it is layering in its PULSE surround-view camera and radar system for 360-degree sensing, its Gen 8 radar for object detection in tough conditions, and Wind River software to handle the unglamorous but essential work of long-term maintenance and security updates. That full-stack approach is the pitch: instead of stitching together sensors, chips, and software from separate vendors, customers get one partner who can carry a device from prototype to a fleet running in the field.
The timing lines up with what Aptiv reported in its second-quarter results on August 4, 2026. Revenue reached $3.3 billion, up 2%, while adjusted EBITDA climbed to $613 million from $547 million a year earlier, pushing margins to 18.7% from 17.1%. CEO Kevin Clark pointed to double-digit growth in non-automotive revenue, progress moving robotics from partnership talks to actual commercial deployments, and a major drone industry win secured in early July. North America sales rose 10% and Asia Pacific grew 6%, including 5% growth in China, giving the company some geographic momentum to lean on as it chases this new business line.
The quarter wasn't clean underneath the headline numbers. Free cash flow came in at just $12 million in the second quarter, down from $219 million a year earlier, and the first half of 2026 actually posted negative free cash flow of $196 million versus a positive $264 million a year ago. Operating cash flow from continuing operations fell to $82 million for the first half, down sharply from $531 million. Management also flagged automotive demand and customer mix as an incremental headwind, a reminder that Aptiv's legacy business still carries real weight even as it chases robotics and drones. EMEA revenue dropped 8%, and South America fell 4% in the quarter, both drags even as North America and Asia Pacific grew.
#jetson #robotics

1 month ago
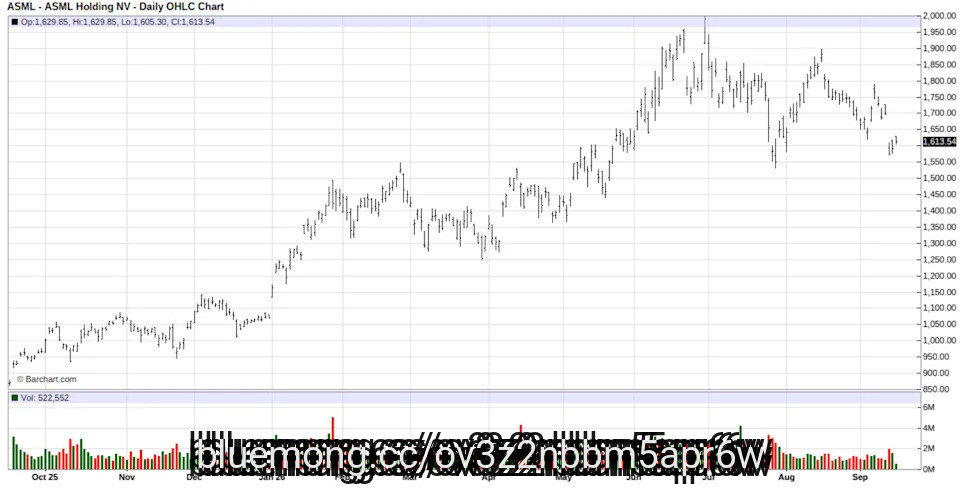
The U.S. has between 3,000 and 4,700 active data centers, with plans to build another 1,500. Globally, there are about 11,800, with plans to add about 100 gigawatts of new capacity by 2030. All of which creates substantial opportunity for beaten-down stocks such as ASML Holding (ASML). However, to run all of those data centers, the world needs advanced AI chips. Today's most advanced data-center AI processors, manufactured on 4nm, 5nm, and certain 7nm processes, depend heavily on ASML's lithography technology. And as the industry moves toward 2nm production, that dependence on ASML's EUV systems will become even more important.
Some of those companies include Samsung Electronics (SMSN.L.IX), Taiwan Semiconductor Manufacturing (TSM), and Intel (INTC). All of which are moving forward with ASML's High-Numerical Aperture extreme ultraviolet lithography systems, better known as High-NA EUV. In short, AI must have powerful chips to run. And those chips are becoming much harder to manufacture, with ASML producing the machines that make their production possible.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#asml #advanced #lithography


2 months ago
International Business Machines (IBM) has risen 6.0% over the last five trading days while the S&P 500 fell 1.3%. A run like that in a weak market pulls money in, but the five-day move is not the question worth answering. What matters is what IBM does to your money when the market moves. Most of what IBM does has little to do with the market.
On days the S&P 500 rose over the past year, IBM captured about 83% of the gain. On days the index fell, IBM took about 102% of the loss. That is a one-year reading of daily moves. For investors evaluating a recent breakout, an asymmetric downside capture ratio warrants closer inspection.
IBM is not a quiet stock. Over the past five years it ran 30.3% annualized volatility against 17.2% for the S&P 500. Its daily moves have tracked the index with a correlation of only 0.36 across those five years, so most of that movement is IBM's own. Independence like that comes from what IBM sells, and when its customers buy.
Software is nearly 45% of IBM's revenue, and about 80% of that software revenue is recurring, coming from subscription and consumption products like Red Hat, HashiCorp and Confluent. The other 20% is transactional. Large clients buy the mainframe and its software stack on enterprise license agreements, generally treated as capital spending.
That last 20% is what slipped in the second quarter of 2026. Management says many clients redirected spending toward servers, storage and memory to secure supply-constrained infrastructure ahead of expected price increases. Tens of large deals did not close on time, and transaction processing revenue fell 9% while data grew 18%.
#revenue
2 months ago
ASML Holding N.V. (NASDAQ:ASML) is examining ways to produce more than 110 EUV lithography systems in 2028, according to JPMorgan ***** ysts following a meeting with CFO Roger Dassen. The company is already nearly sold out for 2027 and expects to produce at least 80 EUV systems that year, meaning output above 110 in 2028 would represent at least a 37.5% increase from the 2027 level. JPMorgan said the main constraint has shifted toward ***** embly speed rather than the availability of critical components, suggesting ASML believes additional capacity can be unlocked through manufacturing and ***** embly improvements.
The potential increase is being driven primarily by AI-related demand. ASML's existing EUV machines, which cost roughly $200 million each, are essential for manufacturing leading-edge AI processors, while customers including TSMC, Samsung, SK Hynix and Intel are expanding advanced-chip capacity. Reuters reported separately that virtually all of ASML's EUV production capacity is booked through 2027, while the company has begun construction of a new Eindhoven facility designed to accelerate tool ***** embly and eventually accommodate up to 20,000 workers.
The strongest bullish implication is that ASML Holding N.V. (NASDAQ:ASML) may be able to convert exceptionally strong demand into higher unit volumes rather than simply relying on price increases. Moving from at least 80 EUV systems in 2027 to more than 110 in 2028 would materially expand the number of high-value systems ASML can monetize. This comes after the company already raised its 2026 revenue outlook to €43 billion–€45 billion, compared with its previous €36 billion–€40 billion range, while targeting a 54%–56% gross margin. Reuters also reported that second-quarter revenue reached €9.3 billion with a 54% gross margin, demonstrating that stronger AI-driven demand is already translating into financial performance.
The longer-term competitive position is particularly favorable because ASML Holding N.V. (NASDAQ:ASML) effectively has no commercial competitor in EUV. JPMorgan estimates that ASML held 94% of the overall lithography market in 2025, while Reuters describes the company as having maintained a monopoly in EUV since the late 2010s. At the same time, customers are committing to ASML's next-generation High-NA technology: the machines cost approximately $400 million, can print features about 40% smaller than existing EUV systems, and TSMC, Samsung, and SK Hynix have all established plans for production adoption. If AI chip demand remains strong enough to support both higher low-NA volumes and eventual High-NA adoption, ASML could see a multi-year increase in system shipments, revenue, and potentially cash generation while strengthening its already exceptional competitive moat.
#company

2 months ago
On August 25, Aptiv (NYSE:APTV) said it will support NVIDIA's newly announced Jetson Orin Nano 2 processor, extending a partnership that already covers the more powerful Jetson Thor platform. The move puts Aptiv squarely inside the buildout of "physical AI," the term for machines like drones, robots, and industrial systems that need to sense and react to the real world in real time. For a company still just months removed from spinning off its electrical distribution business, betting on edge robotics is a statement about where it thinks the next decade of growth actually lives.
NVIDIA's Jetson Orin Nano 2 packs 78 TOPS of processing power into an 8GB, 8-core Arm chip that doubles the inference speed of its predecessor while cutting power draw by 40% at equivalent performance. That kind of efficiency gain matters for battery-powered devices like delivery drones and mobile robots, where every watt saved extends run time. Aptiv isn't just supplying compute support; it is layering in its PULSE surround-view camera and radar system for 360-degree sensing, its Gen 8 radar for object detection in tough conditions, and Wind River software to handle the unglamorous but essential work of long-term maintenance and security updates. That full-stack approach is the pitch: instead of stitching together sensors, chips, and software from separate vendors, customers get one partner who can carry a device from prototype to a fleet running in the field.
The timing lines up with what Aptiv reported in its second-quarter results on August 4, 2026. Revenue reached $3.3 billion, up 2%, while adjusted EBITDA climbed to $613 million from $547 million a year earlier, pushing margins to 18.7% from 17.1%. CEO Kevin Clark pointed to double-digit growth in non-automotive revenue, progress moving robotics from partnership talks to actual commercial deployments, and a major drone industry win secured in early July. North America sales rose 10% and Asia Pacific grew 6%, including 5% growth in China, giving the company some geographic momentum to lean on as it chases this new business line.
The quarter wasn't clean underneath the headline numbers. Free cash flow came in at just $12 million in the second quarter, down from $219 million a year earlier, and the first half of 2026 actually posted negative free cash flow of $196 million versus a positive $264 million a year ago. Operating cash flow from continuing operations fell to $82 million for the first half, down sharply from $531 million. Management also flagged automotive demand and customer mix as an incremental headwind, a reminder that Aptiv's legacy business still carries real weight even as it chases robotics and drones. EMEA revenue dropped 8%, and South America fell 4% in the quarter, both drags even as North America and Asia Pacific grew.
#America #real


2 months ago
Choosing between Advance Auto Parts (NYSE:AAP) and Intuitive Machines (NASDAQ:LUNR) requires balancing the steady but challenged automotive retail sector against the high-stakes, high-growth arena of ******* e infrastructure.
Advance Auto Parts operates as a massive retailer for vehicle maintenance, while Intuitive Machines focuses on lunar landers and orbital services. These two businesses represent very different risk-to-reward profiles for 2026 portfolios.
Advance Auto Parts operates as an automotive aftermarket parts retailer, serving both everyday do-it-yourselfers and professional installers like garages or dealerships. In its latest annual report, filed for the fiscal year ended January 3, 2026, the company noted it operates over 4,000 stores across North America. As an established player among retail stocks, its strategy relies on balancing these two customer bases, with professional sales accounting for nearly 50% of its total revenue.
In FY 2025, revenue reached $8.6 billion, representing a revenue decline of roughly 5.4% compared to the previous year. Despite this decline, the company reported a net income of $44.0 million. This resulted in a thin net margin, a measure of how much profit a company keeps from its total sales, of about 0.5%.
As of its January 2026 balance sheet, the debt-to-equity ratio was 2.4x. This ratio measures total debt against shareholder equity, with a higher number suggesting more reliance on borrowing. The so-called current ratio, which tracks the ability to pay short-term debts with short-term ******* ets, was 1.7x. Free cash flow, defined as cash from operations minus capital expenditures, was negative $298.0 million for the year.
#parts #operates #total #ratio
2 months ago
International Business Machines (IBM) is building a rather interesting corner of the enterprise artificial intelligence (AI) market. The company has combined its hybrid-cloud expertise with foundation models and deep government and scientific partnerships, while its Prithvi family of open models now spans weather, geospatial, and lunar data.
That gives IBM a credible position in domain-specific AI, particularly where the stakes are too high for generic models to wing it. The latest example is the NASA IBM Lunar Foundation Model, open-sourced on Thursday, Sept. 10, which brings decades of multi-instrument lunar observations into a unified, machine-learning-ready dataset and model.
Dear ******* eX Stock Fans, Mark Your Calendars for September 21
Google Just Dropped a Bombshell on AI Spending — Alphabet's $200 Billion AI Bet Is Starting to Pay Off Big
Dear Nike Stock Fans, Mark Your Calendars for September 21
#lunar



2 months ago
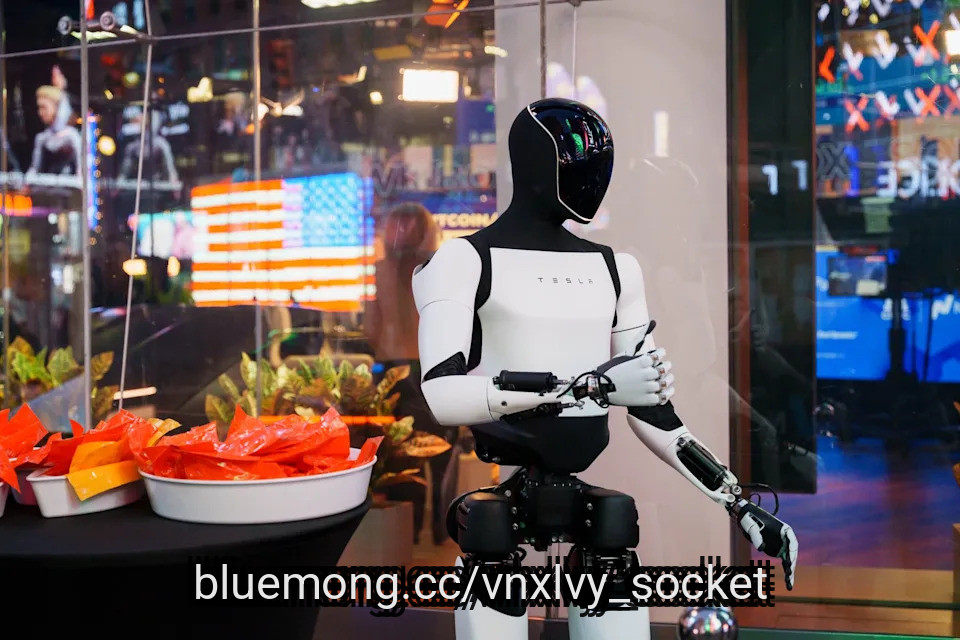
Goldman Sachs raised its 2035 humanoid robot forecast nearly 5x to 6.5 million units, now valuing the market at $138 billion.
Each humanoid robot carries between $3,000 and $6,000 in semiconductor content, potentially generating up to $39 billion in annual chip demand at full scale.
Picks-and-shovels suppliers like semiconductor and automation companies offer a smarter entry than betting on which humanoid robot manufacturer wins.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA made the cut. Enter your email to see the other nine names and why NVDA earned its spot. The report is free. Enter your email and see the full list.
Artificial intelligence is moving out of the data center and into the physical world. Autonomous vehicles, warehouse robots, and increasingly capable machines are giving AI a body, creating what Goldman Sachs calls "physical AI." The investment opportunity could be much larger than the market for humanoid robots themselves. Every machine needs processors, memory, sensors, motors, and software, creating a new demand stream for companies already supplying the AI economy.
#robot #sachs
2 months ago
High-performance computing is currently undergoing a massive generational shift. Deciding between Astera Labs Inc (NASDAQ:ALAB) and Applied Materials Inc (NASDAQ:AMAT) means choosing between a fast-growing connectivity specialist and an established ******* an of manufacturing equipment.
Astera Labs focuses on the internal plumbing of data centers, providing chips that move data between processors. Applied Materials builds the actual machines that make those chips possible. While both benefit from artificial intelligence, they occupy very different rungs on the technology ladder.
Astera Labs sells high-speed connectivity hardware and software designed for AI-heavy data centers. Its primary products include PCIe and Ethernet solutions that help hyperscale cloud providers manage massive data workloads. In its latest annual report, filed for the period ending December 31, 2025, the company noted that one end customer represented more than 70% of its revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached nearly $853 million, which is an increase of approximately 115% over the prior year. This growth resulted in a net income of roughly $219 million, compared to a net loss in the previous fiscal year. The company recorded a net margin of close to 26% during this period. Such expansion is notable among semiconductor stocks catering to the cloud market.
The company carries no debt, resulting in a debt-to-equity ratio of 0.0x. This metric compares total debt to shareholder equity to show how a firm finances its ******* ets. As of its December 2025 balance sheet, the so-called current ratio was nearly 10.2x, indicating a strong ability to cover short-term debts. Free cash flow was roughly $282 million. Note that stock-based compensation represented just about 50% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#million #flow #NASDAQ

2 months ago
Railroad retirement coverage follows the employer, not the work, so independent locomotive manufacturers' workers earn zero creditable railroad service regardless of their job.
Paycheck deductions reveal which system applies. Railroad employees pay Tier I and Tier II taxes, while Social Security-covered workers see only standard withholding.
Workers should confirm RRB employer coverage, check payroll records for Tier II deductions, and review their Social Security earnings record before building any retirement plan.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
In February, Union Pacific signed a $1.2 billion deal with Wabtec to modernize locomotives, a reminder that the companies building the machines and the railroads running them can sit on opposite sides of a surprisingly important retirement line.
#railroad


2 months ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
The phrase 'AI weapons' often conjures images of machines making life-and-death decisions without human oversight. Xtend AI Robotics, Inc. Common Stock CEO Aviv Shapira believes that narrative has outpaced reality. While autonomy is advancing rapidly across modern defense systems, he argues the industry's trajectory is not about removing humans from the battlefield, but enabling them to make better decisions by letting AI handle speed, complexity and dangerous tasks.
Shapira rejected the idea that autonomous weapons are headed toward fully independent lethal decision-making. "That is a misconception, at least in terms of where the industry is today," he told Benzinga in an exclusive email interview.
Don't Miss:
A single bad hire can set a startup back years. Here are the 5 hires founders most often misjudge — and why
#benzinga #shapira #weapons #decisions


2 months ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and ******* ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like CNH Industrial N.V. (NYSE:CNH). CNH Industrial N.V. manufactures and sells specialized machines and services for the farming and construction industries. The one-month return of CNH Industrial N.V. (NYSE:CNH) was 30.96% while its shares traded between $9.00 and $14.46 over the last 52 weeks. On September 7, 2026, CNH Industrial N.V. (NYSE:CNH) stock closed at approximately $14.40 per share, with a market capitalization of about $22.02 billion.
Moerus Worldwide Fund stated the following regarding CNH Industrial N.V. (NYSE:CNH) in its Q2 2026 investor letter:
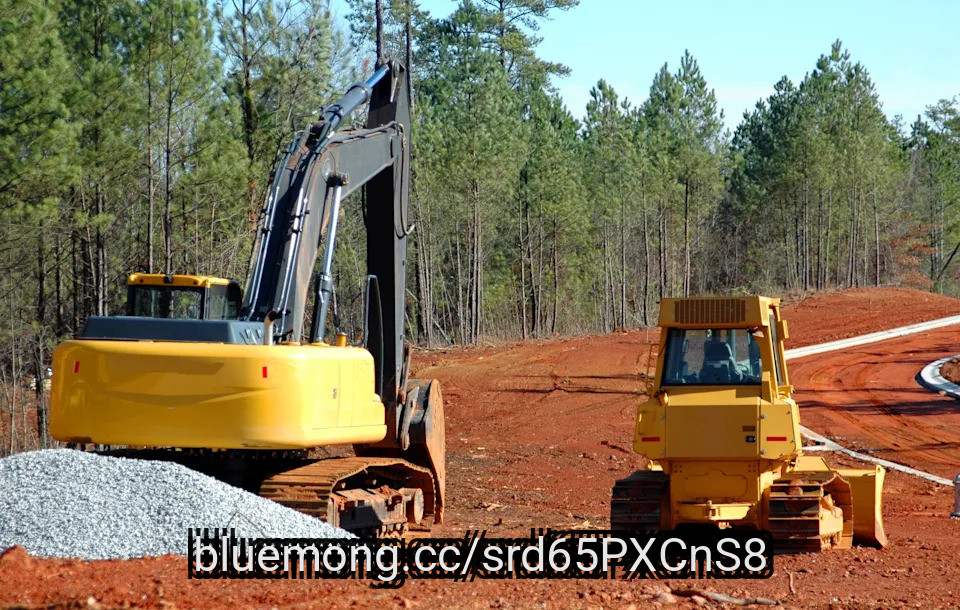
"We also initiated a position in shares of CNH Industrial N.V. (NYSE:CNH) in H1. CNH Industrial manufactures and sells specialized machines and services for the farming and construction industries under the Case IH and New Holland brands. The production of high horsepower agricultural equipment (i.e. tractors, combines, etc.) for professional farmers is an oligopoly, of which CNH is the second largest original equipment manufacturer behind John Deere."
#NYSE #investor #letter

2 months ago
On August 18, Austin Moeller from Canaccord Genuity reiterated his Buy rating for Intuitive Machines (NASDAQ:LUNR). Despite cutting his price target from $41 to $39, his estimates result in almost 165% upside potential as of September 1 closing. Moeller's stance is based on the company's second quarter announcement on August 13. The management reiterated its full-year 2026 guidance, projecting topline figures between $900 million and $1 billion, along with positive adjusted EBITDA. Chief Executive Officer, Steve Altemus, reflected on the company's performance by stating:
"We delivered a strong quarter, highlighted by revenue over four times Q2 2025 as we executed across our programs, recorded unprecedented bookings and backlog, and positioned the Company for the next phase of growth."
Sergey Nivens/Shutterstock.com
The second quarter saw Intuitive Machines (NASDAQ:LUNR) posting record quarterly revenue figures of $206.17 million. This equates to a 310% growth compared to a $50.31 million topline during the same period last year. This can be attributed to execution across the company's commercial lunar payload services, omnibus multidisciplinary engineering services, near ****** e network services, and ****** ecraft production programs. During the second quarter, it booked additional $920 million of awards and ended the quarter with an order backlog of $1.8 billion. This represented a substantial jump compared with December-end backlog of $213.1 million. It is pertinent to highlight that $612.8 million of the total order backlog is linked to the company's acquisition of Lanteris, earlier in 2026.
The business mix exhibited a material shift during the second quarter. National security programs saw a notable jump in revenue contribution, accounting for roughly 30% of the topline compared to just 3% in Q2 2025. The company has been actively pursuing opportunities to expand its pipeline of defense and satellite communication programs. It recently received authorization to proceed on a $600 million multi-satellite communications infrastructure program. The company will leverage its IM 1300 satellite platform to design, manufacture, integrate, and support multiple ****** ecraft. This award validates the Intuitive Machines' IM 1300 platform for large-scale procurements, and strengthens its footprint in satellite communications infrastructure.
#intuitive #machines #company
2 months ago
Brian Joseph Hoff, the Chief Financial Officer of Unusual Machines (NYSEMKT:UMAC), sold 11,413 shares of common stock on Aug. 20, 2026, according to a recent SEC Form 4 filing.
Metric
Value
Shares sold
11,413
#joseph #chief #financial
Metric
Value
Shares sold
11,413
#joseph #chief #financial

2 months ago
Intuitive Machines (NASDAQ: LUNR), a developer of lunar landers and exploration vehicles, doesn't usually get as much attention as bigger ***** e stocks like ***** eX (NASDAQ: SPCX). But over the past two years, Intuitive's stock has nearly tripled.
Most of that rally was driven by the expansion of its partnership with NASA, which now includes seven lunar, orbital satellite, and science missions. Let's take a closer look at that manifest -- and see if its stock is still worth chasing after its astronomical gains.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Intuitive Machines' manifest for NASA includes five lunar surface delivery missions (IM-1 to IM-5) and the production of two satellite buses (IM 300 and IM 500) for orbital science missions.
It has launched two lunar lander missions for NASA so far: IM-1 in 2024 and IM-2 in 2025. Both landers tipped over after arriving on the moon, but they successfully transmitted some data back to NASA before their solar panels ran out of power. Though imperfect, IM-1 marked NASA's first successful moon landing since 1972, and it strengthened Intuitive's relationship with NASA.
#NVIDIA #intuitive #landers


2 months ago
This marks the first time an all-electric manufacturer will take part in the Australian Supercross series.
Begin press release:
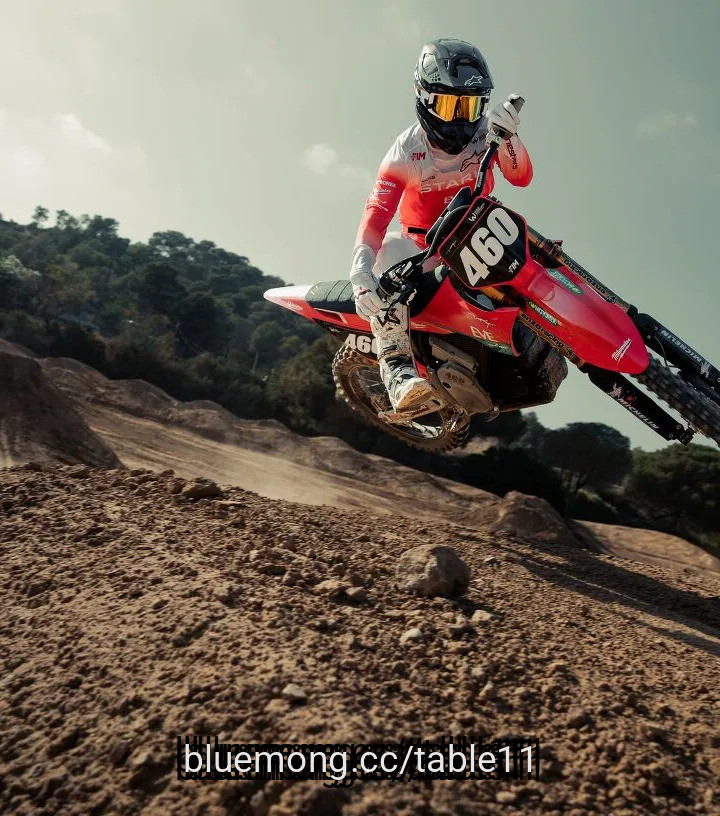
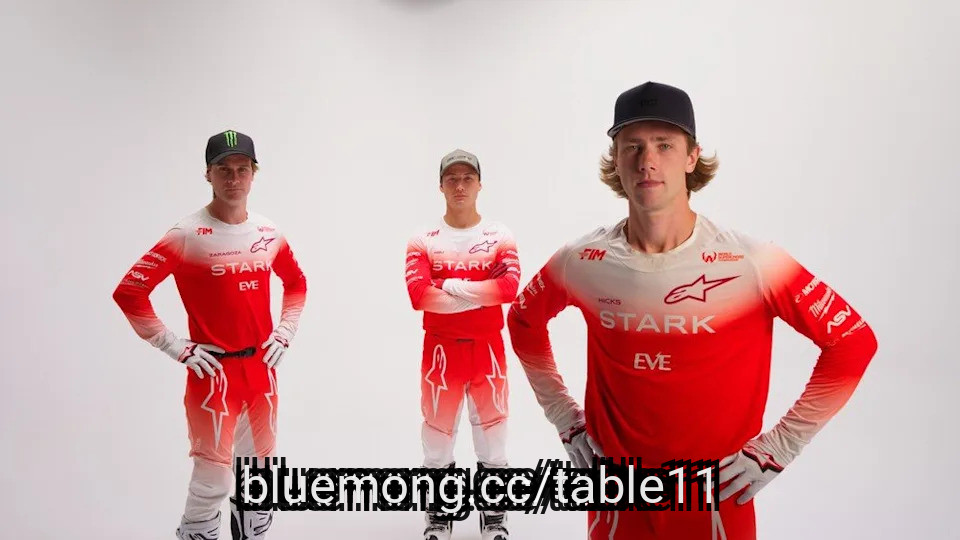
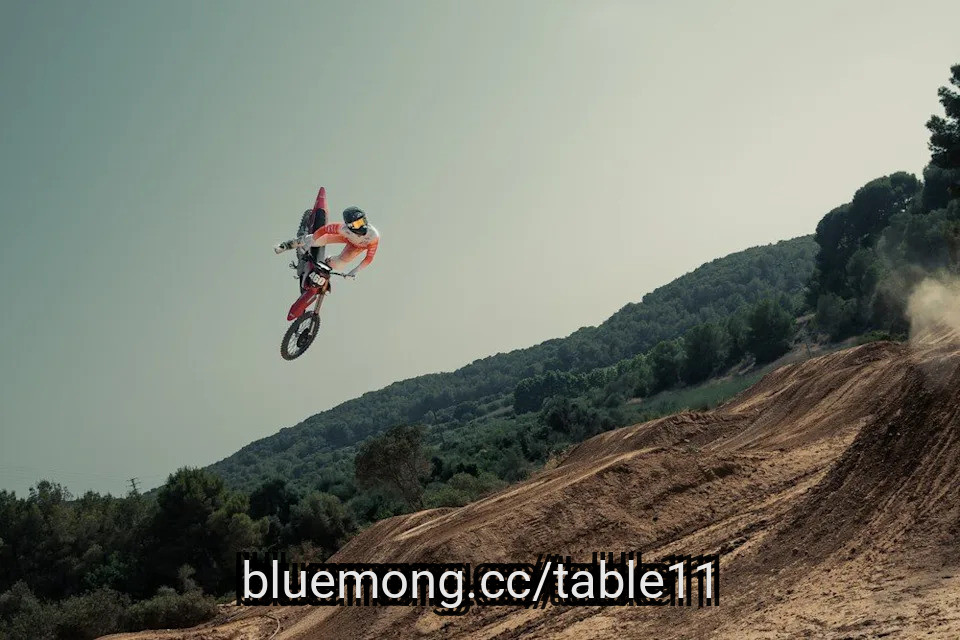
Stark Future will race the full 2026 Boost Mobile AUSX Supercross Championship, presented by Monster Energy. It is the company's first season in Australia, and the first time an electric motorcycle manufacturer takes the start gate in the series.
The Stark factory team will compete across all five rounds, starting in October, with riders in both the SX1 and SX2 classes.
The announcement coincides with a landmark development for Australian Supercross: Motorcycling Australia (MA) has approved eligible electric motorcycles to compete, opening the door for electric and combustion machines to race alongside each other within the appropriate competition classes. Subject to technical regulations and approval from Motorcycling Australia (MA), AUSX has permitted eligible machines to enter directly into the relevant established classes, mirroring a global shift in the sport. This initiative was made possible through close collaboration between Stark, the federation, and AUSX promoters.
#classes #australian #motorcycling #time

2 months ago
The market is flooded with names that claim to be AI companies. The word "AI-powered" is enough to get the attention of the Street, but some believe those days are going to be history soon as investors become jittery about massive CapEx and ROI-related fears.
To find out where retail investors are actually putting money for the long haul, we scoured Reddit threads and discussions on the r/stockstobuytoday community and picked two stocks retail investors on Reddit said they are buying for the next five years. These are International Business Machines Corporation (NYSE:IBM) and Alphabet Inc. (NASDAQ:GOOG). In this article, we will focus on IBM.
Retail investors on Reddit say they like IBM because they believe small quantum startups won't be able to raise enough development money or handle regulation, while IBM is already embedded in enterprise accounts with a strong reputation. They also like the stock's valuation and dividend.
Valuation
IBM has a forward non-GAAP P/E of 19.12, which is 15.72% below the sector median of 22.69 and 5.85% above IBM's own five-year average of 18.07. Forward GAAP P/E of 23.13 sits 21.10% under the sector and 17.03% below IBM's five-year average of 27.88. Forward EV/EBITDA of 13.85 is 5.46% under the sector median and 5.86% above IBM's own history.
#retail #enough #believe


2 months ago
Summers Value Partners, a boutique investment firm, noted in its Q2 2026 investor update that The Summers Value Fund delivered strong results in the quarter, returning 41.7% net, outperforming the Russell 2000 Index ETF (IWM), which returned 21.4%, and the Russell 2000 Value Index ETF (IWN), which returned 17.1%. The letter can be downloaded here. The Fund experienced its best quarter since inception, achieving profitability on both long and short positions. Favorable market conditions, particularly in small-cap and healthcare stocks, led to attractive investment opportunities. The Fund maintained a cash position of approximately 13%. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, The Summers Value Fund highlighted Consensus Cloud Solutions, Inc. (NASDAQ:CCSI). Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) is a leading information delivery services provider through a software-as-a-service platform. On August 31, 2026, Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) closed at $38.25 per share. Over the past month, Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) declined 0.65%, but its shares are up 44.39% over the past year. Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) has a market capitalization of $700.93 million.
The Summers Value Fund stated the following regarding Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) in its Q2 2026 investor letter:
Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) - $695 million market cap. Consensus Cloud Solutions is a leading provider of cloud-based fax services to the healthcare sector under its well-recognized eFax brand. Faxing remains an important means of communication in the healthcare ecosystem with billions of pages sent each year. Faxing, while a legacy technology, allows industry participants to communicate in a HIPAA-compliant manner. Many hospitals and clinics still rely on physical fax machines while Consensus' cloud-based service feels more like sending an email.
Consensus was a busted spin-off from J2 Global when we started buying shares two years ago. The stock had declined from $65 to a low of $12 following missed expectations and an accounting restatement. At its low, the stock traded at 2.5x GAAP earnings. We began building our position at $16, or 3.5x GAAP earnings. Despite selling legacy technology into an industry in secular decline, the company had several attributes we found appealing: high margins, low customer churn, and strong free cash flow generation. After years of a declining share price, investor expectations and sell-side coverage were almost non-existent, which helped create the mispricing..." (Click here to read the full text)
#solutions
2 months ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management deliberately scaled back mining operations to prioritize economic returns over pure scale, resulting in a sequential revenue decline.
The company transitioned a portion of its capacity to a leasing model, shifting direct operating costs and variable risk to lessees.
Operational efficiency was improved by phasing out older S19 series mining machines in favor of newer, more efficient hardware.
A new Bitcoin hedging program was implemented to mitigate price volatility and enhance the predictability of operating cash flows.
#tell #identified

2 months ago
Summers Value Partners, a boutique investment firm, noted in its Q2 2026 investor update that The Summers Value Fund delivered strong results in the quarter, returning 41.7% net, outperforming the Russell 2000 Index ETF (IWM), which returned 21.4%, and the Russell 2000 Value Index ETF (IWN), which returned 17.1%. The letter can be downloaded here. The Fund experienced its best quarter since inception, achieving profitability on both long and short positions. Favorable market conditions, particularly in small-cap and healthcare stocks, led to attractive investment opportunities. The Fund maintained a cash position of approximately 13%. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, The Summers Value Fund highlighted Consensus Cloud Solutions, Inc. (NASDAQ:CCSI). Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) is a leading information delivery services provider through a software-as-a-service platform. On August 31, 2026, Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) closed at $38.25 per share. Over the past month, Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) declined 0.65%, but its shares are up 44.39% over the past year. Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) has a market capitalization of $700.93 million.
The Summers Value Fund stated the following regarding Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) in its Q2 2026 investor letter:
Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) - $695 million market cap. Consensus Cloud Solutions is a leading provider of cloud-based fax services to the healthcare sector under its well-recognized eFax brand. Faxing remains an important means of communication in the healthcare ecosystem with billions of pages sent each year. Faxing, while a legacy technology, allows industry participants to communicate in a HIPAA-compliant manner. Many hospitals and clinics still rely on physical fax machines while Consensus' cloud-based service feels more like sending an email.
Consensus was a busted spin-off from J2 Global when we started buying shares two years ago. The stock had declined from $65 to a low of $12 following missed expectations and an accounting restatement. At its low, the stock traded at 2.5x GAAP earnings. We began building our position at $16, or 3.5x GAAP earnings. Despite selling legacy technology into an industry in secular decline, the company had several attributes we found appealing: high margins, low customer churn, and strong free cash flow generation. After years of a declining share price, investor expectations and sell-side coverage were almost non-existent, which helped create the mispricing..." (Click here to read the full text)
#cloud #solutions #quarter
2 months ago
CrowdStrike Holdings (NASDAQ:CRWD) just posted the best quarter in its history, and the numbers back that up. Net new annual recurring revenue hit $333 million on August 26, accelerating to 51% growth and beating the high end of guidance by more than $45 million. Total revenue climbed 26% to $1.47 billion, a fifth straight quarter of accelerating growth. Buried in the same earnings call, though, was a guide for the current quarter that points to a much slower pace ahead.
The clearest story here is Falcon Flex, the bundled subscription model that lets customers consolidate security modules under one contract. Ending ARR tied to Flex reached $2.29 billion, up 101% year over year, and the company added more than 935 new Flex accounts in the quarter, over ten a day. Customers who converted from a standard subscription to Flex boosted spending by an average of 40%, and new logos signing directly onto Flex made up a record 34% of net new ARR. That bundling machine is now feeding a new category of demand.
Artificial Intelligence Detection and Response, built to police rogue AI agents, saw its ending ARR nearly triple versus the prior quarter, while identity products like Falcon Shield and privileged account protection grew more than 185% and more than 35 times year over year. Endpoint security, the original business, accelerated for a fourth straight quarter as customers locked down AI tools running on their machines. None of this came at the expense of profit. Non-GAAP operating income rose 46% to $372 million, a 25% margin, and free cash flow grew 33% to $377 million. Management raised its full-year net new ARR guidance by 1.15 thousand basis points from its initial outlook, to $1.35 billion to $1.36 billion.
Look past the headline print and the picture gets more complicated. CrowdStrike earned just $5 million in GAAP net income for the quarter, only its third straight quarter in the black on that basis, a reminder that the far larger non-GAAP profit figures still lean on add-backs like stock-based compensation. The company's own outlook for the next quarter cools things off too. Third quarter net new ARR is guided to grow 29% to 31% year over year, roughly half the 51% pace just posted, and revenue growth is guided to slow to 23% to 24% from the 26% delivered in the second quarter. Some of that is routine caution, but it still means the acceleration does not carry forward unchanged.
#year #flex #gaap
2 months ago
HP Inc. (NYSE:HPQ) delivered an unusual combination in its fiscal third quarter: Personal Systems revenue rose 18% year over year to $11.8 billion even though unit shipments fell 16%. The divergence drew scrutiny after the company reported record third-quarter revenue and raised its fiscal 2026 outlook.
Mechanically, the reported changes imply that Personal Systems revenue per unit increased about 40%. However, that is not a clean measure of like-for-like PC pricing. The segment includes services and other attached offerings, while the quarter's mix shifted toward commercial, premium, and AI-enabled machines. HP Inc. (NYSE:HPQ) did not disclose a precise bridge.
The mix shift has substance. AI PCs accounted for 46% of Personal Systems shipment mix, while HP Inc. (NYSE:HPQ) gained 2.6 percentage points of share sequentially in premium categories and 1.8 points sequentially in workstations. Commercial products, which generally carry higher configurations than consumer PCs, generated more than 70% of segment revenue. Revenue rose 22% in commercial Personal Systems and 10% in consumer Personal Systems.
The company is also selling more around the device. Management said peripherals, collaboration products and services such as its Workforce Experience Platform contributed one-third of Personal Systems gross profit. These offerings help explain why segment revenue can rise faster than hardware units without relying entirely on price increases.
Cash generation strengthened the bull case. HP Inc. (NYSE:HPQ) produced $1.7 billion of operating cash flow and $1.6 billion of company-defined free cash flow, after adjustments for lease-related investment and capital spending. The company raised its fiscal-year free-cash-flow outlook to $3.0 billion to $3.2 billion.
#personal #systems #cash
2 months ago
Nvidia (NVDA) delivered a commanding second-quarter fiscal 2027 performance after the close on Wednesday, Aug. 26, with revenue of $96.2 billion more than doubling from the year-ago period and comfortably exceeding the Wall Street consensus of approximately $92.2 billion.
Adjusted earnings per share came in at $2.22, well above the $2.09 ******* ysts had projected, while GAAP net income surged 126% year-over-year to $59.69 billion, or $2.46 per diluted share. The data center segment, which now represents over 92% of total revenue, generated $89 billion in quarterly sales, up 117% from a year earlier and roughly $3 billion above consensus expectations.
HP, Inc. Results Today - Huge, Unusual Options Activity in Long-Dated HPQ Puts
Extreme Speculators Should Keep Close Tabs on Intuitive Machines (LUNR) Stock
Bearish Outlook? Try These 2 Bear Call Spread Trades on Wednesday
#wednesday #revenue #Share #above

2 months ago
International Business Machines (IBM) is a global technology and consulting leader headquartered in Armonk, New York, with roots dating back more than a century. IBM's diversified portfolio spans hybrid cloud computing, artificial intelligence software, enterprise consulting, and next-generation infrastructure, including mainframe systems and quantum computing. IBM has repositioned itself around AI-driven productivity, Red Hat's hybrid cloud platform, and its ambitious quantum computing roadmap targeting a large-scale fault-tolerant quantum computer by 2029. With a client base spanning global enterprises and governments, IBM continues investing heavily in AI, automation, and open-source innovation to drive long-term growth.
IBM stock is currently trading around $230, well below its all-time and 52-week high of $332.46 set in June, though comfortably above its 52-week low of $199.19. Shares tumbled sharply after IBM's second-quarter earnings miss in July, falling more than 7% in a single session to around $206 before staging a partial recovery in the following weeks.
Walmart Stock Is More Expensive Than Nvidia Amid Earnings Miss
SpaceX Stock Just Crashed Below Its IPO Price: Here's the Bull Case ****** ody Can Ignore
A Major Bitcoin Short Squeeze Is Taking MicroStrategy Stock Higher. What Comes Next.
#Stock #quantum #around #miss



2 months ago
On August 11, 2026, Sony Group Corporation (NYSE:SONY) and Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) agreed to form a $4.7 billion joint venture to develop and manufacture next-generation image sensors for smartphones. Mass production is expected to begin in 2029.
Why This Matters
Sony is trying to limit its own capital spending on next-generation chip manufacturing while still capturing AI-era demand for camera "eyes" in machines.
So does partnering with TSMC give Sony the best of both worlds, or does it mean sharing a strategic manufacturing edge with a partner that also serves every other chip customer in the world?
Sony Group Corporation (NYSE:SONY) will be the venture's sole controlling shareholder and will lead development of core image-sensor technology and product design, contributing about $2.92 billion partly by transferring its newly built **** amoto chip factory. The structure is designed specifically to limit Sony's own capital spending while positioning it to capture rising demand for the "eyes" of machines as AI adoption grows. The companies are also counting on **** anese government support to help fund the venture's full planned capacity.
#NYSE #corporation #next #generation


2 months ago
Artificial intelligence has spent years fueling fears that machines could replace American workers. But the AI boom is creating another problem altogether: the U.S. may not have enough people to power it.
As tech companies race to build data centers and utilities expand the transmission lines and power plants needed to keep them running, demand is surging for electricians, engineers and construction workers. The trouble is that many of those workers are already in short supply and a sizable share are nearing retirement.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#ramsey #americans