

6 hours ago
BECKLEY, WV (WVNS) - Volunteers have started planning for the return of the Beckley 5k and Half Marathon event.
Community groups get involved at Beckley's Kids Classic Festival
Members of Active Southern West Virginia have partnered with the Beckley-Raleigh County Chamber of Commerce to present the race.
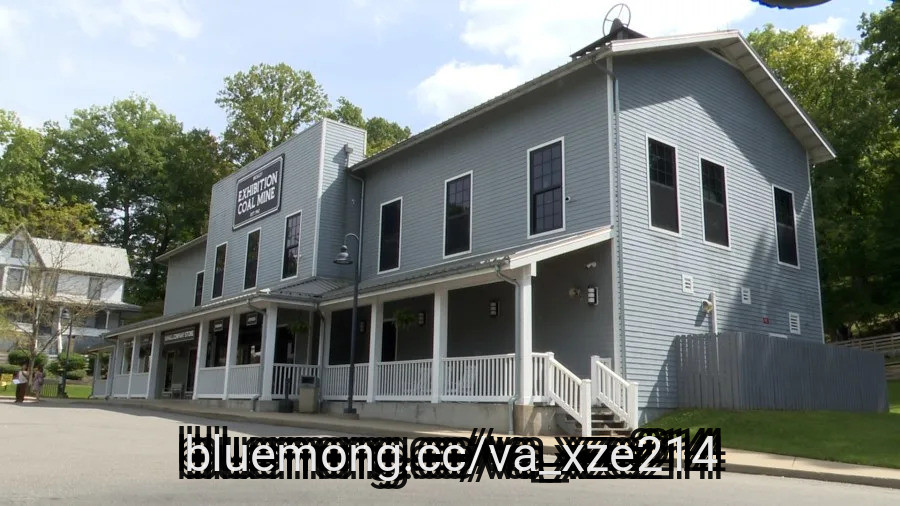
Participants will start and finish at the Beckley Exhibition Coal Mine. Top place finishers could even walk away with a medal for their efforts! Organizers said all proceeds raised will go to a good cause.
"All the funds raised from this and other Active Southern West Virginia events help us to offer free community activities - things like workplace wellness, our kids' run club in schools," said Jenni Canterbury, Development Director with Active Southern West Virginia."
The half marathon is scheduled to kick off at 8:00 the morning of Saturday, September 26th, while the 5k will get started at 8:30 the same morning.
Those interested can go online for more details including information on how to register and how to get involved with volunteering on event day.
#beckley #southern
Community groups get involved at Beckley's Kids Classic Festival
Members of Active Southern West Virginia have partnered with the Beckley-Raleigh County Chamber of Commerce to present the race.
Participants will start and finish at the Beckley Exhibition Coal Mine. Top place finishers could even walk away with a medal for their efforts! Organizers said all proceeds raised will go to a good cause.
"All the funds raised from this and other Active Southern West Virginia events help us to offer free community activities - things like workplace wellness, our kids' run club in schools," said Jenni Canterbury, Development Director with Active Southern West Virginia."
The half marathon is scheduled to kick off at 8:00 the morning of Saturday, September 26th, while the 5k will get started at 8:30 the same morning.
Those interested can go online for more details including information on how to register and how to get involved with volunteering on event day.
#beckley #southern

9 hours ago
A few weeks ago, I used Uber Eats to deliver me a case of bottled water, a dozen Starbucks iced coffee bottles, and a 12-pack of Gatorade Zero.
It cost a little more than going to the store less than two miles from our house, but instead of having to lug those bulky items from the store to my car and then my kitchen, I only had to bring them in from the front door.
That was either a lazy choice or evidence of excellent time management skills, but it's a solid example of how people use the internet. Because while people generally think it's much higher (I've asked the question to thousands of people on various podcasts and live shows over the years), digital sales are still a relatively small percentage of total retail sales.
"E-commerce sales in the second quarter of 2026 accounted for 17.1 percent of total sales," United States Census Bureau data showed.
Consumers have shifted some of their purchases online, and they're looking for convenience.
#people #zero
It cost a little more than going to the store less than two miles from our house, but instead of having to lug those bulky items from the store to my car and then my kitchen, I only had to bring them in from the front door.
That was either a lazy choice or evidence of excellent time management skills, but it's a solid example of how people use the internet. Because while people generally think it's much higher (I've asked the question to thousands of people on various podcasts and live shows over the years), digital sales are still a relatively small percentage of total retail sales.
"E-commerce sales in the second quarter of 2026 accounted for 17.1 percent of total sales," United States Census Bureau data showed.
Consumers have shifted some of their purchases online, and they're looking for convenience.
#people #zero

10 hours ago
On September 10, Shoe Station Group (NASDAQ:SHOE) held its first earnings call under its new name, and the numbers told a story of a company still finding its footing. Second quarter net sales fell 7.2% to $284.3 million from $306.4 million a year earlier, with comparable sales down 7.1%. But buried in the report was a sharper signal: August comparable sales improved to a 2.7% decline, a real jump from the second quarter's pace, and management is pointing to store-by-store product changes as the reason why.
Shoe Station's turnaround argument rests on giving up the idea that every store should look the same. Interim CEO Clifton Sifford said the company had been running nearly identical ***** ortments across its stores even though its two banners serve very different customers, and that approach stopped working. The shift already shows up in the numbers. Once the company localized its athletic ***** ortments ahead of back-to-school, adult athletic sales moved from a low single-digit decline in the second quarter to a low single-digit increase in August.
Running shoes comped positive in both men's and women's categories, and men's work boots, a replenishment category with loyal repeat buyers, grew 2%. Management believes this fall's boot lineup is the best it has fielded in years, heading into what Sifford expects to be a bigger nonathletic fashion cycle. E-commerce sales grew 18.8% even as store traffic fell, and in-store conversion actually improved, evidence that customers who show up are buying; they just are not showing up in the same numbers yet. The company also ended the quarter debt-free with $131.6 million in cash, up $39.7 million from a year ago, giving it room to fund the localized rollout without straining the balance sheet.
The flip side is that the entire second quarter was ugly across the board. Shoe Carnival branded stores, still 63% of revenue, saw sales fall 6.5%, while the newly converted Shoe Station banner dropped 8.4%. Gross profit margin fell 690 basis points to 31.9%, a mix of a promotional footwear market and management's decision to accelerate liquidation of aged inventory, trading margin for cash. That combination cut net income to $6.3 million, or $0.23 per diluted share, down from $19.2 million and $0.70 a year earlier.
Management is not projecting relief anytime soon. Sifford said plainly, "We are not ***** uming the environment improves," and CFO Kerry Jackson noted that gross margins in fiscal August were still running below last year's levels at a pace comparable to the second quarter. Full-year gross margin guidance of 32.5% to 32.7% implies 390 to 410 basis points of compression for the year. Store impairment charges reached $6.7 million on 11 stores year to date, and management has already conceded that the core problem is not price, since conversion rates rose while total customer visits kept falling. That points to a marketing and trust problem rather than a demand problem, and fixing it will take more tha
Shoe Station's turnaround argument rests on giving up the idea that every store should look the same. Interim CEO Clifton Sifford said the company had been running nearly identical ***** ortments across its stores even though its two banners serve very different customers, and that approach stopped working. The shift already shows up in the numbers. Once the company localized its athletic ***** ortments ahead of back-to-school, adult athletic sales moved from a low single-digit decline in the second quarter to a low single-digit increase in August.
Running shoes comped positive in both men's and women's categories, and men's work boots, a replenishment category with loyal repeat buyers, grew 2%. Management believes this fall's boot lineup is the best it has fielded in years, heading into what Sifford expects to be a bigger nonathletic fashion cycle. E-commerce sales grew 18.8% even as store traffic fell, and in-store conversion actually improved, evidence that customers who show up are buying; they just are not showing up in the same numbers yet. The company also ended the quarter debt-free with $131.6 million in cash, up $39.7 million from a year ago, giving it room to fund the localized rollout without straining the balance sheet.
The flip side is that the entire second quarter was ugly across the board. Shoe Carnival branded stores, still 63% of revenue, saw sales fall 6.5%, while the newly converted Shoe Station banner dropped 8.4%. Gross profit margin fell 690 basis points to 31.9%, a mix of a promotional footwear market and management's decision to accelerate liquidation of aged inventory, trading margin for cash. That combination cut net income to $6.3 million, or $0.23 per diluted share, down from $19.2 million and $0.70 a year earlier.
Management is not projecting relief anytime soon. Sifford said plainly, "We are not ***** uming the environment improves," and CFO Kerry Jackson noted that gross margins in fiscal August were still running below last year's levels at a pace comparable to the second quarter. Full-year gross margin guidance of 32.5% to 32.7% implies 390 to 410 basis points of compression for the year. Store impairment charges reached $6.7 million on 11 stores year to date, and management has already conceded that the core problem is not price, since conversion rates rose while total customer visits kept falling. That points to a marketing and trust problem rather than a demand problem, and fixing it will take more tha


12 hours ago
This summer, a 28-year-old digital content marketer packed up his suitcases and duct-taped boxes and fled Russia, leaving behind his family and friends and not knowing when he'll be able to return.
"It is very sad to leave Russia," he said in the southern city of Krasnodar before heading for the border with Georgia.
He blamed "the political situation" in Russia and complications over authorities restricting internet access as his reasons for leaving. Otherwise, "I never would have left for more than several months," he told The ******* ociated Press, speaking on condition of anonymity because of security concerns.
He is one of a number of people who either left or are contemplating a move amid recent Ukrainian drone attacks inside Russia and persistent rumors of a coming mobilization of troops for the 4 1/2-year-old war.
The attacks this summer caused an unprecedented fuel crisis and dealt crippling blows to the booming e-commerce sector. Since last year, the government has cited the attacks to justify harsh restrictions on connecting to the internet.
#Russia #year #otherwise
"It is very sad to leave Russia," he said in the southern city of Krasnodar before heading for the border with Georgia.
He blamed "the political situation" in Russia and complications over authorities restricting internet access as his reasons for leaving. Otherwise, "I never would have left for more than several months," he told The ******* ociated Press, speaking on condition of anonymity because of security concerns.
He is one of a number of people who either left or are contemplating a move amid recent Ukrainian drone attacks inside Russia and persistent rumors of a coming mobilization of troops for the 4 1/2-year-old war.
The attacks this summer caused an unprecedented fuel crisis and dealt crippling blows to the booming e-commerce sector. Since last year, the government has cited the attacks to justify harsh restrictions on connecting to the internet.
#Russia #year #otherwise


16 hours ago
Walmart Inc. (NASDAQ:WMT) is expanding its restaurant-delivery business through a partnership with Papa John's, allowing customers in select U.S. markets to order pizzas, sides, and desserts through Walmart's app and website. The service is expected to launch this fall before expanding to thousands of participating Papa John's locations nationwide. Customers will be able to order restaurant food either separately or alongside Walmart groceries and household products, with Walmart's delivery network handling fulfillment.
The move builds on Walmart's broader push into fast delivery. The company recently reported that U.S. e-commerce sales increased 24% in its latest quarter, while fast-delivery services for groceries and general merchandise grew 48%. Walmart also said 30-minute-or-less delivery was available in 38 U.S. markets, highlighting the infrastructure it can potentially leverage for restaurant orders.
The Papa John's partnership could strengthen Walmart Inc. (NASDAQ:WMT)'s position as a broader consumer-delivery platform rather than simply a retailer. Adding restaurant meals gives shoppers another reason to open Walmart's app, while the ability to combine a pizza order with groceries and household products creates an opportunity to increase basket sizes and order frequency. This is particularly attractive because Walmart already has a large store network that increasingly functions as a last-mile fulfillment system; roughly 80% of its e-commerce orders are fulfilled from stores.
The deal could also improve the economics of Walmart's existing delivery infrastructure. Instead of building a completely separate restaurant-delivery network, Walmart can utilize its established fulfillment capabilities and Spark driver network to serve incremental demand. The Papa John's relationship also expands Walmart's restaurant offering beyond earlier partnerships, helping the company build a more comprehensive alternative to dedicated delivery platforms such as DoorDash and Uber Eats.
More importantly, restaurant delivery could become another engagement tool for Walmart Inc. (NASDAQ:WMT)'s increasingly digital customer base. With e-commerce approaching a quarter of Walmart's overall sales and growing substantially faster than traditional store sales, initiatives that increase digital traffic could support Walmart's broader ecosystem of e-commerce, memberships and advertising.
#walmart #network #fulfillment
The move builds on Walmart's broader push into fast delivery. The company recently reported that U.S. e-commerce sales increased 24% in its latest quarter, while fast-delivery services for groceries and general merchandise grew 48%. Walmart also said 30-minute-or-less delivery was available in 38 U.S. markets, highlighting the infrastructure it can potentially leverage for restaurant orders.
The Papa John's partnership could strengthen Walmart Inc. (NASDAQ:WMT)'s position as a broader consumer-delivery platform rather than simply a retailer. Adding restaurant meals gives shoppers another reason to open Walmart's app, while the ability to combine a pizza order with groceries and household products creates an opportunity to increase basket sizes and order frequency. This is particularly attractive because Walmart already has a large store network that increasingly functions as a last-mile fulfillment system; roughly 80% of its e-commerce orders are fulfilled from stores.
The deal could also improve the economics of Walmart's existing delivery infrastructure. Instead of building a completely separate restaurant-delivery network, Walmart can utilize its established fulfillment capabilities and Spark driver network to serve incremental demand. The Papa John's relationship also expands Walmart's restaurant offering beyond earlier partnerships, helping the company build a more comprehensive alternative to dedicated delivery platforms such as DoorDash and Uber Eats.
More importantly, restaurant delivery could become another engagement tool for Walmart Inc. (NASDAQ:WMT)'s increasingly digital customer base. With e-commerce approaching a quarter of Walmart's overall sales and growing substantially faster than traditional store sales, initiatives that increase digital traffic could support Walmart's broader ecosystem of e-commerce, memberships and advertising.
#walmart #network #fulfillment


18 hours ago
Founded in 1977 and headquartered in South Korea, LX Pantos has grown into a global logistics provider spanning freight forwarding, contract logistics, e-commerce fulfillment, last-mile delivery and installation, and supply chain management consulting. The company now operates more than 380 locations worldwide with a workforce of approximately 8,500 employees, moving more than 1.6 million TEUs of ocean freight and over 120,000 tons of air freight annually. In 2025, LX Pantos recorded revenue of approximately $5.85 billion.
For President and CEO Lee Yong-ho, those figures mark a foundation rather than a destination.
"Since **** uming the role of CEO, I have set a clear vision for LX Pantos: to build the company into a 'Korea-born, global logistics company,' and we have been pursuing that goal with unwavering commitment," Lee said.
That vision marks a departure from the model that carried LX Pantos for decades on domestic corporate freight volumes.
"For many years, LX Pantos grew rapidly by leveraging freight volumes from domestic corporate customers. However, we have also recognized that growth driven primarily by the domestic market has its limitations," Lee said. "It is now time for LX Pantos to evolve into a truly global logistics company — one that is not confined to any single country or customer segment, but is capable of delivering comprehensive logistics solutions to customers worldwide."
#pantos #Logistics
For President and CEO Lee Yong-ho, those figures mark a foundation rather than a destination.
"Since **** uming the role of CEO, I have set a clear vision for LX Pantos: to build the company into a 'Korea-born, global logistics company,' and we have been pursuing that goal with unwavering commitment," Lee said.
That vision marks a departure from the model that carried LX Pantos for decades on domestic corporate freight volumes.
"For many years, LX Pantos grew rapidly by leveraging freight volumes from domestic corporate customers. However, we have also recognized that growth driven primarily by the domestic market has its limitations," Lee said. "It is now time for LX Pantos to evolve into a truly global logistics company — one that is not confined to any single country or customer segment, but is capable of delivering comprehensive logistics solutions to customers worldwide."
#pantos #Logistics



2 days ago
VICTORIA, British Columbia (AP) — Kyle Cottam set a PGA Tour Americas record Saturday when he holed out from 108 yards for eagle on the 16th hole on his way to a 12-under 58 in the Digital Commerce Group Open.
It was the second straight year for a sub-60 round at Uplands Golf Club. A.J. Ewart shot 59 a year ago in the Victoria Open.
Cottam had six birdies in a seven-hole stretch for a 29 on the front nine, and he played the final four holes in 4 under with the eagle on the 16th He got up-and-down for par from just off the green on the 18th hole.
"I was absolutely surprised," Cottam said. "Obviously, you don't wake up in the morning and think you're going to shoot 58."
Cottam had the sixth sub-60 round on the PGA Tour Americas since 2024. There were two sub-60 rounds on the Canadian Tour, including a 58 by Jason Bohn in 2001.
#hole
It was the second straight year for a sub-60 round at Uplands Golf Club. A.J. Ewart shot 59 a year ago in the Victoria Open.
Cottam had six birdies in a seven-hole stretch for a 29 on the front nine, and he played the final four holes in 4 under with the eagle on the 16th He got up-and-down for par from just off the green on the 18th hole.
"I was absolutely surprised," Cottam said. "Obviously, you don't wake up in the morning and think you're going to shoot 58."
Cottam had the sixth sub-60 round on the PGA Tour Americas since 2024. There were two sub-60 rounds on the Canadian Tour, including a 58 by Jason Bohn in 2001.
#hole



3 days ago
Lil Durk has been cleared of every charge in the federal murder-for-hire trial that drew packed courtrooms, celebrity spectators and crowds of supporters to downtown Los Angeles.
A federal jury found the 33-year-old Chicago rapper, whose legal name is Durk Banks, not guilty on September 11 after three days of deliberations. The case centered on an August 2022 attack targeting rapper Quando Rondo that instead killed Rondo's 24-year-old cousin, Saviay'a Robinson, according to The ******* ociated Press.
Prosecutors accused Durk of financing and directing the attack in retaliation for the 2020 killing of his close friend Dayvon "King Von" Bennett. Durk's lawyers argued that former ******* istant Kavon Grant organized the plot without the rapper's knowledge and attacked the credibility of cooperating witnesses who had reached plea agreements with the government.
Durk was not released after the verdict. He remains in federal custody because he faces a separate trial involving murder-related racketeering and firearms allegations, with jury selection currently scheduled to begin October 5.
Durk had faced five counts: conspiracy to commit stalking, stalking using a dangerous weapon, stalking resulting in death, conspiracy to use interstate commerce facilities to commit murder-for-hire resulting in death and use of interstate commerce facilities to commit murder-for-hire resulting in death.
#commit #stalking
A federal jury found the 33-year-old Chicago rapper, whose legal name is Durk Banks, not guilty on September 11 after three days of deliberations. The case centered on an August 2022 attack targeting rapper Quando Rondo that instead killed Rondo's 24-year-old cousin, Saviay'a Robinson, according to The ******* ociated Press.
Prosecutors accused Durk of financing and directing the attack in retaliation for the 2020 killing of his close friend Dayvon "King Von" Bennett. Durk's lawyers argued that former ******* istant Kavon Grant organized the plot without the rapper's knowledge and attacked the credibility of cooperating witnesses who had reached plea agreements with the government.
Durk was not released after the verdict. He remains in federal custody because he faces a separate trial involving murder-related racketeering and firearms allegations, with jury selection currently scheduled to begin October 5.
Durk had faced five counts: conspiracy to commit stalking, stalking using a dangerous weapon, stalking resulting in death, conspiracy to use interstate commerce facilities to commit murder-for-hire resulting in death and use of interstate commerce facilities to commit murder-for-hire resulting in death.
#commit #stalking


3 days ago
WASHINGTON, Sept 9 (Reuters) - Three U.S. lawmakers have called on the American government to blacklist a set of Indian IT firms over what they describe as "more than fifteen years of targeted espionage against U.S. citizens, businesses, and the lawyers representing them."
In a letter issued Wednesday, Democratic Senators Ron Wyden and Sheldon Whitehouse, along with Republican Representative Pat Harrigan, asked the Commerce Department to add BellTroX, CyberRoot, and Sunkissed Organic Farms Pvt. Ltd. (formerly known as "Appin Technology Pvt. Ltd.") and its subsidiaries, to the Commerce Department's Entity List. Such a designation would cut them off from U.S. software, cloud infrastructure, and cybersecurity tools.
Sunkissed representatives, CyberRoot and the Commerce Department did not respond to requests for comment. BellTroX could not be reached for comment.
All three companies have been described in media coverage and in reports published by major tech firms as being fronts for hack-for-hire activities.
In 2022, Reuters named CyberRoot and BellTroX as key players in the cybermercenary industry, saying they were frequently tapped by Western lawyers and private investigators to spy on one another during legal and business disputes. A 2023 Reuters report identified Appin as a pioneer in the field, saying the company grew from an educational startup to a hack-for-hire powerhouse that stole secrets from executives, politicians, military officials and wealthy elites around the globe.
#three
In a letter issued Wednesday, Democratic Senators Ron Wyden and Sheldon Whitehouse, along with Republican Representative Pat Harrigan, asked the Commerce Department to add BellTroX, CyberRoot, and Sunkissed Organic Farms Pvt. Ltd. (formerly known as "Appin Technology Pvt. Ltd.") and its subsidiaries, to the Commerce Department's Entity List. Such a designation would cut them off from U.S. software, cloud infrastructure, and cybersecurity tools.
Sunkissed representatives, CyberRoot and the Commerce Department did not respond to requests for comment. BellTroX could not be reached for comment.
All three companies have been described in media coverage and in reports published by major tech firms as being fronts for hack-for-hire activities.
In 2022, Reuters named CyberRoot and BellTroX as key players in the cybermercenary industry, saying they were frequently tapped by Western lawyers and private investigators to spy on one another during legal and business disputes. A 2023 Reuters report identified Appin as a pioneer in the field, saying the company grew from an educational startup to a hack-for-hire powerhouse that stole secrets from executives, politicians, military officials and wealthy elites around the globe.
#three

4 days ago
Shopify (SHOP) stock opened higher on Wednesday after the e-commerce firm said it has acquired Tailwind Labs, the company behind the widely used Tailwind CSS. The announcement is significant for SHOP, given that Tailwind CSS is installed more than 110 million times per week and is used by prominent names like ChatGPT, Cloudflare (NET), Reddit (RDDT), and X.
That said, Shopify shares have reversed their intraday gains in recent hours and are now headed to end the Sept. 9 session down more than 5%.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ******* e
#tailwind #chatgpt
That said, Shopify shares have reversed their intraday gains in recent hours and are now headed to end the Sept. 9 session down more than 5%.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ******* e
#tailwind #chatgpt


4 days ago
Nvidia (NVDA) Jensen Huang was seated next to US Commerce Secretary Howard Lutnick on a G20 stage on Sept. 2, recalling the first time the two of them met, when he put a number on what the world is about to spend. "You recognize that the infrastructure buildout is not going to be in the tens of billions, but is going to be in the tens of trillions," Huang said. "That supply chain security is going to be necessary."
The venue was the US-hosted G20 innovation ministerial in Chapel Hill, NC, and the chief executive was in a fireside conversation with the Commerce secretary. Sam Altman appeared at the same event. The exchange was carried live and the "tens of trillions" line went out the same afternoon across the wires.
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ***** e
Ahead of Oracle Earnings, Here's What Barchart Data Says Comes Next for ORCL Stock
#next #trillions
The venue was the US-hosted G20 innovation ministerial in Chapel Hill, NC, and the chief executive was in a fireside conversation with the Commerce secretary. Sam Altman appeared at the same event. The exchange was carried live and the "tens of trillions" line went out the same afternoon across the wires.
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ***** e
Ahead of Oracle Earnings, Here's What Barchart Data Says Comes Next for ORCL Stock
#next #trillions


4 days ago
Chinese e-commerce giants such as Shein and Temu have reshaped the retail landscape amid economic uncertainty, higher prices, and cautious consumer spending by offering shoppers a wide range of products at extremely low prices.
Their growth has prompted established companies such as Amazon, Target, and Walmart to invest in strategies like third-party marketplaces, supply chain infrastructure, and digital tools to keep pace with changing consumer habits.
Now, one online-first fashion retailer is taking a different approach. While many established brands have been reassessing their physical footprints and closing underperforming stores, this e-commerce fashion company is moving in the opposite direction by expanding its brick-and-mortar presence in the U.S.
Founded in 2020 as an online-first womenswear brand, Cider has built its business around affordable, trend-driven fashion and a digital-focused shopping experience.
Cider opened its second permanent U.S. retail location on September 4, 2026, at Westfield Valley Fair in San Jose, California. The 11,269-square-foot store is located at 2855 Stevens Creek Blvd., ****** e No. 2411.
#fashion #cider #prices #first
Their growth has prompted established companies such as Amazon, Target, and Walmart to invest in strategies like third-party marketplaces, supply chain infrastructure, and digital tools to keep pace with changing consumer habits.
Now, one online-first fashion retailer is taking a different approach. While many established brands have been reassessing their physical footprints and closing underperforming stores, this e-commerce fashion company is moving in the opposite direction by expanding its brick-and-mortar presence in the U.S.
Founded in 2020 as an online-first womenswear brand, Cider has built its business around affordable, trend-driven fashion and a digital-focused shopping experience.
Cider opened its second permanent U.S. retail location on September 4, 2026, at Westfield Valley Fair in San Jose, California. The 11,269-square-foot store is located at 2855 Stevens Creek Blvd., ****** e No. 2411.
#fashion #cider #prices #first

4 days ago
Etsy Inc (NASDAQ:ETSY) stock is down 2.6% to trade at $70.20 today amid broader market pressure, though Argus reiterated its "buy" rating and lifted its price target to $89 from $67. The $70 level has served as both support and resistance in recent months and could provide a potential pivot point for the shares. What's more, the e-commerce name is now within striking distance of a historically bullish trendline.
According to Schaeffer's Senior Quantitative ***** yst Rocky White, Etsy stock is trading within 0.75 times the 100-day moving averages' 20-day average true range (ATR), after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above that trendline. This setup has appeared 13 other times over the last decade, after which the stock was higher one month later 77% of the time, averaging a 10.3% gain.
Short interest represents 10.8% of the stock's available float, and would take shorts over three days to cover at the stock's average pace of trading. A move higher could pressure some of these bearish bettors to exit their positions, creating additional buying power.
Now also looks like a good time to weigh in on ETSY's next move with options. The stock's Schaeffer's Volatility Index (SVI) of 49% sits in the low 10th percentile of its annual range, suggesting options traders are pricing in relatively low volatility expectations at the moment.
#trading #volatility #within
According to Schaeffer's Senior Quantitative ***** yst Rocky White, Etsy stock is trading within 0.75 times the 100-day moving averages' 20-day average true range (ATR), after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above that trendline. This setup has appeared 13 other times over the last decade, after which the stock was higher one month later 77% of the time, averaging a 10.3% gain.
Short interest represents 10.8% of the stock's available float, and would take shorts over three days to cover at the stock's average pace of trading. A move higher could pressure some of these bearish bettors to exit their positions, creating additional buying power.
Now also looks like a good time to weigh in on ETSY's next move with options. The stock's Schaeffer's Volatility Index (SVI) of 49% sits in the low 10th percentile of its annual range, suggesting options traders are pricing in relatively low volatility expectations at the moment.
#trading #volatility #within


4 days ago
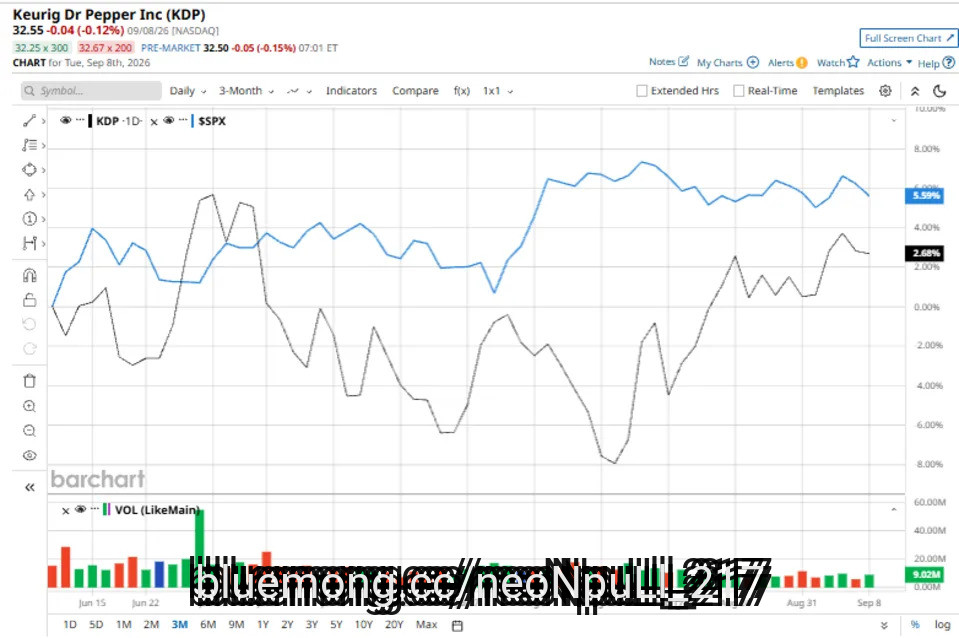
Keurig Dr Pepper Inc. (KDP) is a leading beverage company headquartered in Frisco, Texas, with more than 150 owned, licensed, and partner brands. With a market capitalization of $44.4 billion, the company manufactures, markets, and distributes soft drinks, coffee, water, tea, and other beverages through an extensive distribution network serving consumers across retail, e-commerce, convenience, and foodservice channels worldwide.
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Keurig Dr Pepper comfortably fits this category. Its substantial market capitalization reflects its size, influence, and established presence in the non-alcoholic beverages industry.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ******* ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#keurig #pepper
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Keurig Dr Pepper comfortably fits this category. Its substantial market capitalization reflects its size, influence, and established presence in the non-alcoholic beverages industry.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ******* ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#keurig #pepper

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

7 days ago
Cash App segment is becoming a major driver of the growth story for Block Inc. (NYSE:XYZ) in 2026, as the underlying lending operations within the segment standout as key determinants of management's outlook for the remainder of the year. Recent initiatives around the company's proprietary credit signal support the narrative and broaden the company's lending reach. For the first time, Block will open its Cash App Score for external lenders by collaborating with Nova Credit's Cash Flow Intelligence Platform.
Photo by Clay Banks on Unsplash
Cash App Score was previously limited to internal use by the company for its consumer lending offerings such as the Cash App Borrow. This latest development could pave way for the monetization of company's data infrastructure, resulting in an additional revenue source.
During the second quarter, Block exceeded its prior guidance, reporting $3.17 billion in gross profit and $864 million in adjusted operating income. Revenue reached $6.62 billion, up 9.3% year over year. Gross profit expanded by 25% relative to the same period last year, and the company posted record 27% adjusted operating margins. Adjusted EPS clocked in at $1.02, exhibiting year-over-year growth of 65%.
Block's impressive second quarter print was driven by strong consumer spending, along with Cash App gross profit expansion of 31% year-over-year increase. This can be attributed to significant expansion in consumer lending, driven by Cash App Borrow. Block said Financial Solutions gross profit growth was driven primarily by Cash App Borrow. It reflects favorably on broader user engagement, who are utilizing Cash App for short-term credit financing instead of just a savings or payment mechanism. Despite a nominal 3% growth in monthly transacting actives, volumetric growth within Cash App was impressive. There was a 59% year-over-year jump in Cash App Consumer Lending origination volume, and 17% increase in Cash App Commerce Enablement volume.
#cash #Consumer
Photo by Clay Banks on Unsplash
Cash App Score was previously limited to internal use by the company for its consumer lending offerings such as the Cash App Borrow. This latest development could pave way for the monetization of company's data infrastructure, resulting in an additional revenue source.
During the second quarter, Block exceeded its prior guidance, reporting $3.17 billion in gross profit and $864 million in adjusted operating income. Revenue reached $6.62 billion, up 9.3% year over year. Gross profit expanded by 25% relative to the same period last year, and the company posted record 27% adjusted operating margins. Adjusted EPS clocked in at $1.02, exhibiting year-over-year growth of 65%.
Block's impressive second quarter print was driven by strong consumer spending, along with Cash App gross profit expansion of 31% year-over-year increase. This can be attributed to significant expansion in consumer lending, driven by Cash App Borrow. Block said Financial Solutions gross profit growth was driven primarily by Cash App Borrow. It reflects favorably on broader user engagement, who are utilizing Cash App for short-term credit financing instead of just a savings or payment mechanism. Despite a nominal 3% growth in monthly transacting actives, volumetric growth within Cash App was impressive. There was a 59% year-over-year jump in Cash App Consumer Lending origination volume, and 17% increase in Cash App Commerce Enablement volume.
#cash #Consumer

7 days ago
Baidu announced on September 4 that its Hong Kong Class A shares are now included in both the Shanghai-Hong Kong and Shenzhen-Hong Kong Stock Connect programs, effective September 7.. The change gives eligible mainland investors direct access to the Hong Kong listing, potentially widening liquidity and the shareholder base. It does not alter the operating competition between Baidu, Inc. (NASDAQ:BIDU) and Alibaba Group Holding Limited (NYSE:BABA), which are pursuing AI through different mixes of models, cloud infrastructure, chips, and consumer distribution.
Baidu's bull case combines search traffic, its Ernie ecosystem, cloud services, and Kunlunxin chips. Stock Connect can make that story easier for mainland investors to own, while its dual-primary Hong Kong listing broadens access. The bear case is that improved trading access does not repair weak advertising, guarantee cloud share, or remove geopolitical and regulatory risk. The catalyst affects liquidity more directly than earnings.
Insider Monkey counted 49 hedge funds holding Baidu, Inc. (NASDAQ:BIDU) at June 30, down from 50 at March 31. David Tepper's Appaloosa Management disclosed 1,295,000 shares, 87% more than in Q1. That increase shows one manager's conviction, not a broad rise in fund participation.
Alibaba's June-quarter AI Cloud and Compute Services revenue reached $7.1 billion, up 45% year over year, while segment adjusted EBITA rose 133% to $830 million. Its bull case is a full stack spanning Qwen models, cloud, proprietary chips, and commerce distribution. The bear case is capital intensity, fierce domestic competition, exposure to consumer spending, and the possibility that fast AI growth remains too small to transform the larger group's valuation.
Ninety-seven hedge funds held Alibaba Group Holding Limited (NYSE:BABA) in Q2, down from 102 in Q1. Ken Fisher's Fisher **** et Management disclosed 5,096,418 shares after trimming the position by 0.5%.
#kong #holding
Baidu's bull case combines search traffic, its Ernie ecosystem, cloud services, and Kunlunxin chips. Stock Connect can make that story easier for mainland investors to own, while its dual-primary Hong Kong listing broadens access. The bear case is that improved trading access does not repair weak advertising, guarantee cloud share, or remove geopolitical and regulatory risk. The catalyst affects liquidity more directly than earnings.
Insider Monkey counted 49 hedge funds holding Baidu, Inc. (NASDAQ:BIDU) at June 30, down from 50 at March 31. David Tepper's Appaloosa Management disclosed 1,295,000 shares, 87% more than in Q1. That increase shows one manager's conviction, not a broad rise in fund participation.
Alibaba's June-quarter AI Cloud and Compute Services revenue reached $7.1 billion, up 45% year over year, while segment adjusted EBITA rose 133% to $830 million. Its bull case is a full stack spanning Qwen models, cloud, proprietary chips, and commerce distribution. The bear case is capital intensity, fierce domestic competition, exposure to consumer spending, and the possibility that fast AI growth remains too small to transform the larger group's valuation.
Ninety-seven hedge funds held Alibaba Group Holding Limited (NYSE:BABA) in Q2, down from 102 in Q1. Ken Fisher's Fisher **** et Management disclosed 5,096,418 shares after trimming the position by 0.5%.
#kong #holding

8 days ago
In the quarter ended 31 July 2026, the company's gross profit was $157.0m compared with $143.4m in the same period last year.
Gross margin increased by approximately 320 basis points to 52.0%, primarily due to International Emergency Economic Powers Act (IEEPA) tariff refunds, partly offset by costs related to a new joint venture royalty structure and temporary expenses from the warehouse management system rollout.
During the quarter, Lands' End posted $302m in net revenue, marking a 2.7% increase year-on-year. Its US e-commerce segment saw the strongest growth, with revenues up 9.0% to $182.4m.
This rebound followed earlier disruption related to the implementation of a new warehouse management system, with carryover shipments contributing to the quarterly rise.
Revenue of Lands' End Outfitters business rose by 4.4% to $69.3m, led by enterprise accounts, which offset ongoing challenges in the school uniform business caused by service processing delays.
#related #Warehouse #management #system
Gross margin increased by approximately 320 basis points to 52.0%, primarily due to International Emergency Economic Powers Act (IEEPA) tariff refunds, partly offset by costs related to a new joint venture royalty structure and temporary expenses from the warehouse management system rollout.
During the quarter, Lands' End posted $302m in net revenue, marking a 2.7% increase year-on-year. Its US e-commerce segment saw the strongest growth, with revenues up 9.0% to $182.4m.
This rebound followed earlier disruption related to the implementation of a new warehouse management system, with carryover shipments contributing to the quarterly rise.
Revenue of Lands' End Outfitters business rose by 4.4% to $69.3m, led by enterprise accounts, which offset ongoing challenges in the school uniform business caused by service processing delays.
#related #Warehouse #management #system

8 days ago
Baidu announced on September 4 that its Hong Kong Class A shares are now included in both the Shanghai-Hong Kong and Shenzhen-Hong Kong Stock Connect programs, effective September 7.. The change gives eligible mainland investors direct access to the Hong Kong listing, potentially widening liquidity and the shareholder base. It does not alter the operating competition between Baidu, Inc. (NASDAQ:BIDU) and Alibaba Group Holding Limited (NYSE:BABA), which are pursuing AI through different mixes of models, cloud infrastructure, chips, and consumer distribution.
Baidu's bull case combines search traffic, its Ernie ecosystem, cloud services, and Kunlunxin chips. Stock Connect can make that story easier for mainland investors to own, while its dual-primary Hong Kong listing broadens access. The bear case is that improved trading access does not repair weak advertising, guarantee cloud share, or remove geopolitical and regulatory risk. The catalyst affects liquidity more directly than earnings.
Insider Monkey counted 49 hedge funds holding Baidu, Inc. (NASDAQ:BIDU) at June 30, down from 50 at March 31. David Tepper's Appaloosa Management disclosed 1,295,000 shares, 87% more than in Q1. That increase shows one manager's conviction, not a broad rise in fund participation.
Alibaba's June-quarter AI Cloud and Compute Services revenue reached $7.1 billion, up 45% year over year, while segment adjusted EBITA rose 133% to $830 million. Its bull case is a full stack spanning Qwen models, cloud, proprietary chips, and commerce distribution. The bear case is capital intensity, fierce domestic competition, exposure to consumer spending, and the possibility that fast AI growth remains too small to transform the larger group's valuation.
Ninety-seven hedge funds held Alibaba Group Holding Limited (NYSE:BABA) in Q2, down from 102 in Q1. Ken Fisher's Fisher **** et Management disclosed 5,096,418 shares after trimming the position by 0.5%.
#kong #cloud
Baidu's bull case combines search traffic, its Ernie ecosystem, cloud services, and Kunlunxin chips. Stock Connect can make that story easier for mainland investors to own, while its dual-primary Hong Kong listing broadens access. The bear case is that improved trading access does not repair weak advertising, guarantee cloud share, or remove geopolitical and regulatory risk. The catalyst affects liquidity more directly than earnings.
Insider Monkey counted 49 hedge funds holding Baidu, Inc. (NASDAQ:BIDU) at June 30, down from 50 at March 31. David Tepper's Appaloosa Management disclosed 1,295,000 shares, 87% more than in Q1. That increase shows one manager's conviction, not a broad rise in fund participation.
Alibaba's June-quarter AI Cloud and Compute Services revenue reached $7.1 billion, up 45% year over year, while segment adjusted EBITA rose 133% to $830 million. Its bull case is a full stack spanning Qwen models, cloud, proprietary chips, and commerce distribution. The bear case is capital intensity, fierce domestic competition, exposure to consumer spending, and the possibility that fast AI growth remains too small to transform the larger group's valuation.
Ninety-seven hedge funds held Alibaba Group Holding Limited (NYSE:BABA) in Q2, down from 102 in Q1. Ken Fisher's Fisher **** et Management disclosed 5,096,418 shares after trimming the position by 0.5%.
#kong #cloud

8 days ago
Cash App segment is becoming a major driver of the growth story for Block Inc. (NYSE:XYZ) in 2026, as the underlying lending operations within the segment standout as key determinants of management's outlook for the remainder of the year. Recent initiatives around the company's proprietary credit signal support the narrative and broaden the company's lending reach. For the first time, Block will open its Cash App Score for external lenders by collaborating with Nova Credit's Cash Flow Intelligence Platform.
Photo by Clay Banks on Unsplash
Cash App Score was previously limited to internal use by the company for its consumer lending offerings such as the Cash App Borrow. This latest development could pave way for the monetization of company's data infrastructure, resulting in an additional revenue source.
During the second quarter, Block exceeded its prior guidance, reporting $3.17 billion in gross profit and $864 million in adjusted operating income. Revenue reached $6.62 billion, up 9.3% year over year. Gross profit expanded by 25% relative to the same period last year, and the company posted record 27% adjusted operating margins. Adjusted EPS clocked in at $1.02, exhibiting year-over-year growth of 65%.
Block's impressive second quarter print was driven by strong consumer spending, along with Cash App gross profit expansion of 31% year-over-year increase. This can be attributed to significant expansion in consumer lending, driven by Cash App Borrow. Block said Financial Solutions gross profit growth was driven primarily by Cash App Borrow. It reflects favorably on broader user engagement, who are utilizing Cash App for short-term credit financing instead of just a savings or payment mechanism. Despite a nominal 3% growth in monthly transacting actives, volumetric growth within Cash App was impressive. There was a 59% year-over-year jump in Cash App Consumer Lending origination volume, and 17% increase in Cash App Commerce Enablement volume.
#year #Growth #gross #profit
Photo by Clay Banks on Unsplash
Cash App Score was previously limited to internal use by the company for its consumer lending offerings such as the Cash App Borrow. This latest development could pave way for the monetization of company's data infrastructure, resulting in an additional revenue source.
During the second quarter, Block exceeded its prior guidance, reporting $3.17 billion in gross profit and $864 million in adjusted operating income. Revenue reached $6.62 billion, up 9.3% year over year. Gross profit expanded by 25% relative to the same period last year, and the company posted record 27% adjusted operating margins. Adjusted EPS clocked in at $1.02, exhibiting year-over-year growth of 65%.
Block's impressive second quarter print was driven by strong consumer spending, along with Cash App gross profit expansion of 31% year-over-year increase. This can be attributed to significant expansion in consumer lending, driven by Cash App Borrow. Block said Financial Solutions gross profit growth was driven primarily by Cash App Borrow. It reflects favorably on broader user engagement, who are utilizing Cash App for short-term credit financing instead of just a savings or payment mechanism. Despite a nominal 3% growth in monthly transacting actives, volumetric growth within Cash App was impressive. There was a 59% year-over-year jump in Cash App Consumer Lending origination volume, and 17% increase in Cash App Commerce Enablement volume.
#year #Growth #gross #profit

9 days ago
Michael Burry, the investor famous for his subprime mortgage bets detailed in "The Big Short," said on August 23 that he has sold his stake in Alibaba Group Holding Limited (NYSE:BABA), calling the Chinese e-commerce and cloud giant's shares overvalued. Burry stated in a Substack article that he had intended to reinvest the majority of his investment in Alibaba within a month or two, but changed his mind. "No longer," he said, adding that the stock's price would need to "fall by half" before he became interested again.
Burry's statements came after Alibaba Group Holding Limited (NYSE:BABA) announced and subsequently completed an approximately HK$80 billion, or $10.2 billion, share placement, through a share offering to fund its artificial intelligence goals. The company has stated that all net proceeds will go into developing its "full stack" AI capabilities.
That funding structure prompted Burry to abandon his plan to reinvest in the stock. "I cannot bless share issuances," he said, adding that Burry objected to the dilution from the financing and said he expects Alibaba's return on invested capital to continue declining. In another post on X, he stated clearly that he wouldn't change his view on Alibaba, referring to share issuance as the company's "new paradigm."
Burry had acquired a new Alibaba Group Holding Limited (NYSE:BABA) stake in April, stating at the time that it comprised just over 6% of his portfolio according to his disclosures at the time. However, in late June, he reversed direction, stating that he had sold the entire holding and invested the proceeds in JD.com, Inc. (NASDAQ:JD), Alibaba's main domestic e-commerce rival. He subsequently described his JD.com position as large and argued that easing competition in China's delivery market could support higher margins.
Institutional opinions regarding the two companies have shifted in distinct directions. Alibaba Group Holding Limited (NYSE:BABA) saw hedge fund holdings decrease marginally, from 102 funds in the first quarter to 97 in the second quarter. JD.com, Inc. (NASDAQ:JD), by comparison, saw hedge fund ownership move up little, from 43 funds to 44 over the same period.
#burry #Share #fund
Burry's statements came after Alibaba Group Holding Limited (NYSE:BABA) announced and subsequently completed an approximately HK$80 billion, or $10.2 billion, share placement, through a share offering to fund its artificial intelligence goals. The company has stated that all net proceeds will go into developing its "full stack" AI capabilities.
That funding structure prompted Burry to abandon his plan to reinvest in the stock. "I cannot bless share issuances," he said, adding that Burry objected to the dilution from the financing and said he expects Alibaba's return on invested capital to continue declining. In another post on X, he stated clearly that he wouldn't change his view on Alibaba, referring to share issuance as the company's "new paradigm."
Burry had acquired a new Alibaba Group Holding Limited (NYSE:BABA) stake in April, stating at the time that it comprised just over 6% of his portfolio according to his disclosures at the time. However, in late June, he reversed direction, stating that he had sold the entire holding and invested the proceeds in JD.com, Inc. (NASDAQ:JD), Alibaba's main domestic e-commerce rival. He subsequently described his JD.com position as large and argued that easing competition in China's delivery market could support higher margins.
Institutional opinions regarding the two companies have shifted in distinct directions. Alibaba Group Holding Limited (NYSE:BABA) saw hedge fund holdings decrease marginally, from 102 funds in the first quarter to 97 in the second quarter. JD.com, Inc. (NASDAQ:JD), by comparison, saw hedge fund ownership move up little, from 43 funds to 44 over the same period.
#burry #Share #fund


10 days ago
OTTAWA, Sept 3 (Reuters) - Canadian Prime Minister Mark Carney said on Thursday his government was ready to sign a trade deal with the U.S. that benefits both countries, adding any agreement would need to have stability and credibility.
"The deal that's possible, that's in the interests of Canadian workers, families and businesses, is also the deal that is in the interests of American families, American businesses, American consumers, and ... we're ready to sit down and strike that deal when the Americans are ready," Carney told reporters in Thunder Bay, Ontario.
Carney dismissed recent comments by U.S. Commerce Secretary Howard Lutnick and Treasury Secretary Scott Bessent that Canada walked away from a trade deal because of domestic politics, saying in response to a question, "I don't think, with all respect, appointed, unelected cabinet members in the United States are experts on Canadian politics."
Carney suggested there had been a recent softening in the U.S. approach to any trade deal that could spur further discussions.
"There were a few issues that the United States was arguing right up to the last hour," he said, describing it as an "our way or the highway" attitude before talks broke down last month. "Now, they're not," he said. "So all of a sudden, they don't care about Canadian language or culture and those elements. Well, if they didn't care, they shouldn't have kept them in the deal," Carney said. "It's good. We welcome that."
#carney #canadian #ready #interests
"The deal that's possible, that's in the interests of Canadian workers, families and businesses, is also the deal that is in the interests of American families, American businesses, American consumers, and ... we're ready to sit down and strike that deal when the Americans are ready," Carney told reporters in Thunder Bay, Ontario.
Carney dismissed recent comments by U.S. Commerce Secretary Howard Lutnick and Treasury Secretary Scott Bessent that Canada walked away from a trade deal because of domestic politics, saying in response to a question, "I don't think, with all respect, appointed, unelected cabinet members in the United States are experts on Canadian politics."
Carney suggested there had been a recent softening in the U.S. approach to any trade deal that could spur further discussions.
"There were a few issues that the United States was arguing right up to the last hour," he said, describing it as an "our way or the highway" attitude before talks broke down last month. "Now, they're not," he said. "So all of a sudden, they don't care about Canadian language or culture and those elements. Well, if they didn't care, they shouldn't have kept them in the deal," Carney said. "It's good. We welcome that."
#carney #canadian #ready #interests


10 days ago
Small and midsize shippers are often forced to stitch together various tools for parcel labels, freight quotes, tracking, and much more. The fragmentation gets more expensive as a business grows past pure e-commerce, since the moment a merchant needs to move inventory between warehouses or ship a pallet instead of a box, they're forced out of whatever platform runs their day-to-day shipping and into unfamiliar territory.
ShipStation Global CEO Tom Madine has built the company's post-merger strategy around closing that gap, knowing that the same merchants who came to the platform for parcel labels are increasingly buying freight, too, and would rather not leave the software to do it.
The LTL rollout is the first major product integration since Thoma Bravo acquired WWEX Group (parent of Worldwide Express, GlobalTranz, Unishippers, JEAR Logistics and BLX Logistics) and merged it with Auctane, the parent company of ShipStation, this past June. The combination created ShipStation Global, a company now valued at roughly $12 billion. CEO Tom Madine described the logic of putting the two businesses together as less about scale for its own sake and more about closing a gap both companies kept running into with customers.
"If you think about an e-commerce merchant that's selling through multiple channels, using multiple carriers with inventory in multiple places, it makes that a much more seamless and stress-free process for them, and allows them to manage everything through a single pane of glass," Madine said of the legacy ShipStation product, before pointing to what it had been missing. "There's nothing else like it on the market."
According to Madine, that gap had shown up repeatedly in customer surveys. "One of the most common requests that ShipStation would get in the legacy Auctane world was, 'When are you going to add other modes to the platform?'" he said. "Prior to today, if you were a ShipStation user, you were managing your entire workflow in ShipStation, except when you needed to move freight." Merchants who needed to move inventory between warehouses had to leave the platform entirely, log into a separate freight system, and reconcile the two.
#freight #inventory #multiple #auctane
ShipStation Global CEO Tom Madine has built the company's post-merger strategy around closing that gap, knowing that the same merchants who came to the platform for parcel labels are increasingly buying freight, too, and would rather not leave the software to do it.
The LTL rollout is the first major product integration since Thoma Bravo acquired WWEX Group (parent of Worldwide Express, GlobalTranz, Unishippers, JEAR Logistics and BLX Logistics) and merged it with Auctane, the parent company of ShipStation, this past June. The combination created ShipStation Global, a company now valued at roughly $12 billion. CEO Tom Madine described the logic of putting the two businesses together as less about scale for its own sake and more about closing a gap both companies kept running into with customers.
"If you think about an e-commerce merchant that's selling through multiple channels, using multiple carriers with inventory in multiple places, it makes that a much more seamless and stress-free process for them, and allows them to manage everything through a single pane of glass," Madine said of the legacy ShipStation product, before pointing to what it had been missing. "There's nothing else like it on the market."
According to Madine, that gap had shown up repeatedly in customer surveys. "One of the most common requests that ShipStation would get in the legacy Auctane world was, 'When are you going to add other modes to the platform?'" he said. "Prior to today, if you were a ShipStation user, you were managing your entire workflow in ShipStation, except when you needed to move freight." Merchants who needed to move inventory between warehouses had to leave the platform entirely, log into a separate freight system, and reconcile the two.
#freight #inventory #multiple #auctane
10 days ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance was driven by a recovery in U.S. e-commerce following the resolution of warehouse management system (WMS) issues that had previously disrupted shipments.
Management prioritized high-margin sales and brand integrity over promotional volume in third-party marketplaces, resulting in a 500 basis point gross margin improvement despite lower revenue.
New customer acquisition was fueled by 'iconic' franchises, specifically totes and swim, which served as entry points for younger demographics and new-to-brand shoppers.
The Europe business pivoted toward a 'franchise-first' ******* ortment to simplify operations and improve product margins, resulting in flat revenue but enhanced profitability.
#Margin #brand #performance #Europe
Performance was driven by a recovery in U.S. e-commerce following the resolution of warehouse management system (WMS) issues that had previously disrupted shipments.
Management prioritized high-margin sales and brand integrity over promotional volume in third-party marketplaces, resulting in a 500 basis point gross margin improvement despite lower revenue.
New customer acquisition was fueled by 'iconic' franchises, specifically totes and swim, which served as entry points for younger demographics and new-to-brand shoppers.
The Europe business pivoted toward a 'franchise-first' ******* ortment to simplify operations and improve product margins, resulting in flat revenue but enhanced profitability.
#Margin #brand #performance #Europe


10 days ago
Sept 03, 2026, 10:53 am EDT
The Trump administration is determined to bring manufacturing activity back to the U.S., and tariffs are one of its important tools. The levies should help domestic makers of things, and it has with cars.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
A new bill aims to secure U.S. supply chains and elevate the Commerce Department to lead national quantum policy.
#jones #commerce
The Trump administration is determined to bring manufacturing activity back to the U.S., and tariffs are one of its important tools. The levies should help domestic makers of things, and it has with cars.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
A new bill aims to secure U.S. supply chains and elevate the Commerce Department to lead national quantum policy.
#jones #commerce

10 days ago
Ro Khanna is a Democratic congressman known for being one of the most active stock traders in Congress, with hundreds of disclosed transactions. Khanna says the trades sit in family accounts he does not control.
His disclosures show he has been buying NCR Voyix (NYSE:VYX), a small-cap company that sells checkout technology to retailers and restaurants.
The most recent trade was a buy in June. There were about seven purchases of this stock from Khanna in 2026.
NCR Voyix sells the checkout technology that grocery stores, convenience chains and restaurants run on. The business splits into two segments, Retail and Restaurants, with retail accounting for a major chunk of sales.
The company is in the middle of a rebuild. It handed hardware manufacturing to an ODM partner at the end of the first quarter of fiscal 2026, so hardware now shows up as commission instead of full product revenue. Management is pushing customers onto the Voyix Commerce Platform, a cloud system sold on multiyear subscription contracts, and onto Voyix Connect, its payments gateway.
#khanna #retail #checkout
His disclosures show he has been buying NCR Voyix (NYSE:VYX), a small-cap company that sells checkout technology to retailers and restaurants.
The most recent trade was a buy in June. There were about seven purchases of this stock from Khanna in 2026.
NCR Voyix sells the checkout technology that grocery stores, convenience chains and restaurants run on. The business splits into two segments, Retail and Restaurants, with retail accounting for a major chunk of sales.
The company is in the middle of a rebuild. It handed hardware manufacturing to an ODM partner at the end of the first quarter of fiscal 2026, so hardware now shows up as commission instead of full product revenue. Management is pushing customers onto the Voyix Commerce Platform, a cloud system sold on multiyear subscription contracts, and onto Voyix Connect, its payments gateway.
#khanna #retail #checkout
10 days ago
On August 5, LiveRamp (NYSE:RAMP) reported first-quarter fiscal 2027 results for the period ended June 30, and the numbers looked less like a company coasting toward a sale than one hitting its stride. Revenue rose 10% to $214 million, but the more striking move was further down the income statement, where operating income more than doubled. LiveRamp skipped its usual earnings call this quarter, a direct result of its pending acquisition by Publicis Groupe, but that silence has not slowed the underlying business.
GAAP operating income jumped to $20 million from $7 million a year earlier, pushing operating margin up six points to 9%. Non-GAAP operating income rose 41% to $50 million, with margin expanding five points to 24%, meaning more of every new revenue dollar is dropping to profit rather than being spent to chase it. Diluted earnings per share more than doubled on a GAAP basis to $0.28 from $0.12, while operating cash flow flipped from a $16 million outflow a year ago to $17 million generated this quarter.
LiveRamp is also positioning itself inside the AI advertising buildout rather than at its edges. The company launched LiveRamp Agent Builders, a program pulling outside AI agents into its network for planning and measurement work, and added integrations tied to OpenAI's advertising tools, Databricks' new Agentic Customer Data Platform, and Adobe's commerce content pipeline, alongside a measurement partnership with DoorDash. None of that shows up in a revenue line yet, but customer behavior already reflects some payoff. LiveRamp ended the quarter with 132 customers paying more than $1 million a year, up from 127, and subscription net retention held at 103%. Annualized recurring revenue grew 7% to $539 million, and Data Marketplace revenue climbed 13% to $40 million.
None of that operational improvement changes the number shareholders actually care about: $38.50 a share, the all-cash price Publicis Groupe agreed to pay when the deal was announced on May 17, 2026. However much operating income grows from here, the merger agreement fixes what LiveRamp holders collect if the transaction closes, so this quarter's beat does not translate into upside for anyone holding the stock for the buyout. LiveRamp also confirmed it will not hold a conference call or issue guidance while the deal is pending, which limits how much investors can independently verify beyond what is in this release.
The transaction still has to clear a shareholder vote scheduled for August 17, and closing remains subject to customary conditions even though management called it on track for before the end of calendar 2026. That leaves a few weeks of real, if narrow, uncertainty. The growth numbers are also decelerating slightly at the edges: total revenue grew 10% this quarter versus 11% in the prior year period, and subscription revenue growth slowed to 8% from 10%. Marketplace and Other revenue, the more variable, usage-driven part of the business, is doing more of the work
GAAP operating income jumped to $20 million from $7 million a year earlier, pushing operating margin up six points to 9%. Non-GAAP operating income rose 41% to $50 million, with margin expanding five points to 24%, meaning more of every new revenue dollar is dropping to profit rather than being spent to chase it. Diluted earnings per share more than doubled on a GAAP basis to $0.28 from $0.12, while operating cash flow flipped from a $16 million outflow a year ago to $17 million generated this quarter.
LiveRamp is also positioning itself inside the AI advertising buildout rather than at its edges. The company launched LiveRamp Agent Builders, a program pulling outside AI agents into its network for planning and measurement work, and added integrations tied to OpenAI's advertising tools, Databricks' new Agentic Customer Data Platform, and Adobe's commerce content pipeline, alongside a measurement partnership with DoorDash. None of that shows up in a revenue line yet, but customer behavior already reflects some payoff. LiveRamp ended the quarter with 132 customers paying more than $1 million a year, up from 127, and subscription net retention held at 103%. Annualized recurring revenue grew 7% to $539 million, and Data Marketplace revenue climbed 13% to $40 million.
None of that operational improvement changes the number shareholders actually care about: $38.50 a share, the all-cash price Publicis Groupe agreed to pay when the deal was announced on May 17, 2026. However much operating income grows from here, the merger agreement fixes what LiveRamp holders collect if the transaction closes, so this quarter's beat does not translate into upside for anyone holding the stock for the buyout. LiveRamp also confirmed it will not hold a conference call or issue guidance while the deal is pending, which limits how much investors can independently verify beyond what is in this release.
The transaction still has to clear a shareholder vote scheduled for August 17, and closing remains subject to customary conditions even though management called it on track for before the end of calendar 2026. That leaves a few weeks of real, if narrow, uncertainty. The growth numbers are also decelerating slightly at the edges: total revenue grew 10% this quarter versus 11% in the prior year period, and subscription revenue growth slowed to 8% from 10%. Marketplace and Other revenue, the more variable, usage-driven part of the business, is doing more of the work


11 days ago
On August 26, Movado Group (NYSE:MOV) reported second-quarter fiscal 2027 results that pushed adjusted earnings per share to $0.54 from $0.23 a year earlier, while net sales climbed 4.9% to $169.8 million. The jewelry and watch company also confirmed it will stop issuing annual financial guidance going forward, choosing instead to focus commentary on near-term trends. For a business built on Swiss craftsmanship and a stable of licensed fashion brands, the quarter marked a fifth straight period of positive momentum, and it came with a few surprises tucked inside the numbers.
Some of the headline strength came from a one-time source: $3.2 million in IEEPA duty refunds tied to tariffs paid between February 2025 and May 2026, which lifted GAAP gross margin to 59.4% from 54.1%. But strip that out and adjusted gross margin still rose 340 basis points to 57.5%, driven by favorable channel and product mix, strategic pricing, and less discounting. Growth was broad rather than concentrated in one line item. US net sales rose 4.9%, international sales rose 4.9% as well (4.1% in constant currency), and Latin America and India posted particularly strong results.
Movado.com sales jumped 8%, and Olivia Burton sales grew 23%, powered by small-shaped watches focused on the U.K. and US markets. The company also flagged a resurgence in traditional watch interest among younger buyers, pointing to the Baby Face mini strap watch, which sold out more than 400 units on movado.com in under a month. Looking ahead, Movado is expanding its Tapestry partnership to launch Kate Spade watches starting next fiscal year. The balance sheet backs up the momentum, with $211.6 million in cash, no debt, and $16.6 million already returned to shareholders through dividends this year.
Not every piece of this quarter travels into the second half. Management was explicit that the favorable mix of lower duty rate inventory that padded margins is temporary and is not expected to continue, and second-half gross margin guidance of 55% to 56% reflects that normalization. Sallie DeMarsilis also noted that gross margin gains were partially offset by higher shipping costs tied to fuel surcharges and rising e-commerce volume.
Geographically, the Middle East remains a soft spot, with Efraim Grinberg citing tourism-related headwinds in a region still affected by regional conflict. Operating expenses rose to $85.7 million from $80.6 million, largely on higher performance-based compensation and marketing spend. There is also a smaller but notable item: a $0.2 million pretax charge tied to a misconduct investigation within a Dubai-based Swiss subsidiary branch. And while Movado expects to recover another $6.8 million in IEEPA duties, it has chosen not to recognize that gain until the cash actually arrives, a reminder that not all of this quarter's tailwind is guaranteed to repeat.
#second
Some of the headline strength came from a one-time source: $3.2 million in IEEPA duty refunds tied to tariffs paid between February 2025 and May 2026, which lifted GAAP gross margin to 59.4% from 54.1%. But strip that out and adjusted gross margin still rose 340 basis points to 57.5%, driven by favorable channel and product mix, strategic pricing, and less discounting. Growth was broad rather than concentrated in one line item. US net sales rose 4.9%, international sales rose 4.9% as well (4.1% in constant currency), and Latin America and India posted particularly strong results.
Movado.com sales jumped 8%, and Olivia Burton sales grew 23%, powered by small-shaped watches focused on the U.K. and US markets. The company also flagged a resurgence in traditional watch interest among younger buyers, pointing to the Baby Face mini strap watch, which sold out more than 400 units on movado.com in under a month. Looking ahead, Movado is expanding its Tapestry partnership to launch Kate Spade watches starting next fiscal year. The balance sheet backs up the momentum, with $211.6 million in cash, no debt, and $16.6 million already returned to shareholders through dividends this year.
Not every piece of this quarter travels into the second half. Management was explicit that the favorable mix of lower duty rate inventory that padded margins is temporary and is not expected to continue, and second-half gross margin guidance of 55% to 56% reflects that normalization. Sallie DeMarsilis also noted that gross margin gains were partially offset by higher shipping costs tied to fuel surcharges and rising e-commerce volume.
Geographically, the Middle East remains a soft spot, with Efraim Grinberg citing tourism-related headwinds in a region still affected by regional conflict. Operating expenses rose to $85.7 million from $80.6 million, largely on higher performance-based compensation and marketing spend. There is also a smaller but notable item: a $0.2 million pretax charge tied to a misconduct investigation within a Dubai-based Swiss subsidiary branch. And while Movado expects to recover another $6.8 million in IEEPA duties, it has chosen not to recognize that gain until the cash actually arrives, a reminder that not all of this quarter's tailwind is guaranteed to repeat.
#second
11 days ago
On September 1, Rezolve AI (NASDAQ:RZLV) reported first-half revenue of $130.8 million, up from just $6.3 million a year earlier, a jump of roughly 1,970%. The AI commerce and payments company also said its enterprise customer base grew to 1,640 accounts. Numbers like that demand attention, but the same report showed losses widening even faster than sales. Here's what's really going on underneath the headline growth rate.
Rezolve's enterprise base grew from 950 customers at the end of the prior fiscal year to 1,640 by June 30, and management is leaning on partnerships with Microsoft, Google, Tata Consultancy Services, and Tech Mahindra to keep that pipeline filling without building out its own global sales force. That distribution strategy got a notable vote of confidence after the quarter closed: Google selected Rezolve's proprietary distributed database technology following a technical evaluation of 24 competing companies, and the system is now indexing roughly 100 terabytes of data across 10 blockchain networks inside Google Cloud's infrastructure.
The platform also proved it can handle real traffic. During the FIFA 2026 World Cup measurement window from June 1 through July 31, Rezolve's technology logged about 103 million app opens from 9.86 million unique devices across 16 stadiums, along with 5.84 million geofence events. On the loyalty and payments side, the recently completed acquisition of Reward Loyalty expanded Rezolve's footprint to more than 15 markets, and a partnership with Zilch now touches almost 6 million customers, driving over $3.3 billion a year to partner merchants. Management reaffirmed guidance for approximately $360 million in full-year 2026 revenue, implying second-half sales near $229 million, and reiterated a target of at least $500 million in annual recurring revenue by year-end.
Growth this fast has come at a steep price. Rezolve's operating loss widened to $128.1 million in the first half of 2026, compared with $32.4 million a year earlier, and net loss grew to $139.5 million from $57.9 million. Some of that reflects noncash items, including $41.5 million in share-based compensation and $20.4 million in depreciation and amortization, but cash is also going out the door faster. Net cash used in operating activities jumped to $96.1 million from $19.8 million in the prior-year period, and investing activities consumed another $148.3 million, largely tied to acquisitions and platform development.
#million #revenue #grew #june
Rezolve's enterprise base grew from 950 customers at the end of the prior fiscal year to 1,640 by June 30, and management is leaning on partnerships with Microsoft, Google, Tata Consultancy Services, and Tech Mahindra to keep that pipeline filling without building out its own global sales force. That distribution strategy got a notable vote of confidence after the quarter closed: Google selected Rezolve's proprietary distributed database technology following a technical evaluation of 24 competing companies, and the system is now indexing roughly 100 terabytes of data across 10 blockchain networks inside Google Cloud's infrastructure.
The platform also proved it can handle real traffic. During the FIFA 2026 World Cup measurement window from June 1 through July 31, Rezolve's technology logged about 103 million app opens from 9.86 million unique devices across 16 stadiums, along with 5.84 million geofence events. On the loyalty and payments side, the recently completed acquisition of Reward Loyalty expanded Rezolve's footprint to more than 15 markets, and a partnership with Zilch now touches almost 6 million customers, driving over $3.3 billion a year to partner merchants. Management reaffirmed guidance for approximately $360 million in full-year 2026 revenue, implying second-half sales near $229 million, and reiterated a target of at least $500 million in annual recurring revenue by year-end.
Growth this fast has come at a steep price. Rezolve's operating loss widened to $128.1 million in the first half of 2026, compared with $32.4 million a year earlier, and net loss grew to $139.5 million from $57.9 million. Some of that reflects noncash items, including $41.5 million in share-based compensation and $20.4 million in depreciation and amortization, but cash is also going out the door faster. Net cash used in operating activities jumped to $96.1 million from $19.8 million in the prior-year period, and investing activities consumed another $148.3 million, largely tied to acquisitions and platform development.
#million #revenue #grew #june


11 days ago
The TJX Companies, Inc. (TJX), headquartered in Framingham, Massachusetts, operates as an off-price apparel and home fashions retailer. With a market cap of $147.9 billion, the company operates off-price retail concepts and e-commerce sites in the U.S., Canada, and Europe that offer a wide range of brand name and designer merchandise.
Companies worth $10 billion or more are generally described as "large-cap stocks," and TJX definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the apparel retail industry. TJX has cemented its leadership in off-price retail by leveraging strong vendor relationships and efficient procurement to offer branded merchandise at significantly lower prices than traditional channels. Its treasure-hunt shopping experience, driven by a diverse and ever-changing ****** ortment, continues to resonate with cost-conscious consumers and build a loyal customer base, while strategic investments in Multibrand Outlet Stores in Mexico and Brands for Less in the Middle East underscore its focus on international expansion and geographic diversification.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why ****** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#price #Companies #market #billion
Companies worth $10 billion or more are generally described as "large-cap stocks," and TJX definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the apparel retail industry. TJX has cemented its leadership in off-price retail by leveraging strong vendor relationships and efficient procurement to offer branded merchandise at significantly lower prices than traditional channels. Its treasure-hunt shopping experience, driven by a diverse and ever-changing ****** ortment, continues to resonate with cost-conscious consumers and build a loyal customer base, while strategic investments in Multibrand Outlet Stores in Mexico and Brands for Less in the Middle East underscore its focus on international expansion and geographic diversification.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why ****** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#price #Companies #market #billion
11 days ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Shopify Inc. (NASDAQ:SHOP). Shopify Inc. (NASDAQ:SHOP), a Canada-based e-commerce technology company that provides a cloud-based platform for individuals and companies to create and manage their operations, detracted from performance in the quarter. On September 01, 2026, Shopify Inc. (NASDAQ:SHOP) closed at $139.82 per share. Over the past month, Shopify Inc. (NASDAQ:SHOP) declined 3.06%, and its shares are down 0.29% over the past year. Shopify Inc. (NASDAQ:SHOP) has a market capitalization of $181.44 billion, and its stock has traded within a 52-week range of $94.00 to $182.19.
Sands Capital Select Growth Fund stated the following regarding Shopify Inc. (NASDAQ:SHOP) in its Q2 2026 investor letter:
"Shopify Inc. (NASDAQ:SHOP) is a leading global ecommerce platform enabling the next generation of retail. Shares declined as concerns around AI-related expenses and forward guidance overshadowed strong quarterly results. Revenue grew 32 percent, the company's fastest growth rate since 2021, supported by strength in North America and higher payments penetration. Investors focused on rising LLM costs ***** ociated with Sidekick, Shopify's AI ***** istant, and second-quarter guidance that implied sequential deceleration. In our view, these concerns are manageable. Shopify is embedding AI into its platform to improve merchant productivity, product discovery, conversion, and win rates, creating potential latent pricing power over time. Early traction is encouraging, with Sidekick usage up 400 percent and Campaigns usage up 300 percent year over year. We maintain conviction in Shopify's long-term growth, supported by enterprise adoption, international expansion, rising take rate, and AI-driven discovery and product enhancements."
#shop
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Shopify Inc. (NASDAQ:SHOP). Shopify Inc. (NASDAQ:SHOP), a Canada-based e-commerce technology company that provides a cloud-based platform for individuals and companies to create and manage their operations, detracted from performance in the quarter. On September 01, 2026, Shopify Inc. (NASDAQ:SHOP) closed at $139.82 per share. Over the past month, Shopify Inc. (NASDAQ:SHOP) declined 3.06%, and its shares are down 0.29% over the past year. Shopify Inc. (NASDAQ:SHOP) has a market capitalization of $181.44 billion, and its stock has traded within a 52-week range of $94.00 to $182.19.
Sands Capital Select Growth Fund stated the following regarding Shopify Inc. (NASDAQ:SHOP) in its Q2 2026 investor letter:
"Shopify Inc. (NASDAQ:SHOP) is a leading global ecommerce platform enabling the next generation of retail. Shares declined as concerns around AI-related expenses and forward guidance overshadowed strong quarterly results. Revenue grew 32 percent, the company's fastest growth rate since 2021, supported by strength in North America and higher payments penetration. Investors focused on rising LLM costs ***** ociated with Sidekick, Shopify's AI ***** istant, and second-quarter guidance that implied sequential deceleration. In our view, these concerns are manageable. Shopify is embedding AI into its platform to improve merchant productivity, product discovery, conversion, and win rates, creating potential latent pricing power over time. Early traction is encouraging, with Sidekick usage up 400 percent and Campaigns usage up 300 percent year over year. We maintain conviction in Shopify's long-term growth, supported by enterprise adoption, international expansion, rising take rate, and AI-driven discovery and product enhancements."
#shop





