

1 day ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
Feeling wealthy in retirement is often just that — a feeling. Having an active social life, a solid purpose and enough cash in the bank to never worry about monthly bills might be all you need to describe yourself as a "rich" retiree.
Feelings aside, what do the cold, hard numbers show? Most Americans agree you need at least $2.2 million (1) to be considered wealthy in America. But they might be surprised to see that you actually need considerably more than that to land in the top 10% of U.S. retirees.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#need #actually #moneywise #feelings

24 days ago
For a subset of young workers, the name of the game is to squirrel away enough savings and investments so retirement can come early, substituting strategic personal finance for a lifetime of labor. (FIRE!)
It turns out that the post-pandemic boom and explosion of stock prices has already gifted many older Americans with a version of that lifestyle, according to Bank of America — and it's affecting the economy.
Labor force participation — which measures the share of people employed or seeking work among the total population — never recovered after the shock of the pandemic.
According to BofA's economics team, led by Aditya Bhave, the biggest driver behind the decline in overall labor force participation has been workers over age 55 leaving the workforce.
"This debunks a popular bearish narrative on the labor market: 'the u-rate would have been higher if participation hadn't fallen,'" Bhave wrote.
#according #workers #FIRE #americans


1 month ago
Sept 18, 2026, 2:55 pm EDT
“It takes a lot of money to look this cheap” was one of Dolly Parton’s most famous quips. It also takes a lot of investment to offer cheap prices. That’s why not all discounters are succeeding, even as inflation has sent most consumers scrambling to find the best value.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
“We will not in any way hinder or stifle the Growth of this incredible Industry,” he wrote in a Truth Social post.
#reserved #Growth

1 month ago
Autodesk (ADSK) stock has 23.6% of room above it before it meets a ceiling that has turned it back three times, and 5% below it before the reason to be there stops being true. In dollars: $272.34 overhead, $220.31 Wednesday, $209.29 underneath. The stock has lost about 31% over the past twelve months, so the easy read is that the business broke. Its own numbers say it did not.
Would You Have Made Money Buying Autodesk Here Before?
Buyers have stepped in at this price zone eight times before. Three of those eight produced a completed advance, averaging a 34.3% gain to the peak that followed, with a median of 459 days from the defense to that peak. The other five have not yet risen above their own starting price, so they are not in that average at all. The ceiling overhead asks for less than that average of the three that paid.
The last two years are the problem. Autodesk entered this price band on five separate occasions over the last twenty-four months, and counting only a 20% gain before any 5% fall as a defense, one held and four broke 5% lower first. The path up is not clear either: the stock has to get through $248.16 and $261.04, both pauses rather than proven ceilings.
Is Autodesk In Better Shape Than The Last Time It Sat Here?
#last #Stock #above #times

1 month ago
You might not be impressed by a stock with a 2% dividend yield as long-term interest rates have been rising quickly in the bond market. But a screen of the S&P 500 shows that companies that have raised their payouts the most have tended to be strong overall performers for long-term investors.
Wednesday afternoon, 10-year U.S. Treasury notes BX:TMUBMUSD10Y were yielding 4.96%, up from 4.47% at the end of June and from 4.17% at the end of last year. Investors has been selling off bonds (which drives up market yields) in anticipation of the Federal Reserve's decision on Wednesday to raise its target range for the federal-funds rate.
What happens if you never buy a house? What renters are gaining — and giving up.
The smartest money moves to make now that interest rates are going up
Read: The Fed could raise interest rates three times. Here's where the market could face the stiffest test.
#investors #federal
1 month ago
Alluvium **** et Management, an **** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Liberty Capital Corporation (NASDAQ:GLIBK). Liberty Capital Corporation (NASDAQ:GLIBK) is a communication services company that provides a range of data, wireless, video, voice, and managed services. GCI Liberty, Inc. rebranded to Liberty Capital Corporation (NASDAQ:GLIBK) in May 2026. On September 15, 2026, Liberty Capital Corporation (NASDAQ:GLIBK) closed at $25.55 per share. Over the past month, Liberty Capital Corporation (NASDAQ:GLIBK) declined 1.50% and its shares lost 27.02% over the past 52 weeks. Liberty Capital Corporation (NASDAQ:GLIBK) has a market capitalization of $1.02 billion, and its stock trades within a 52-week range of $19.30 and $41.18.
Conventum – Alluvium Global Fund stated the following regarding Liberty Capital Corporation (NASDAQ:GLIBK) in its Q2 2026 investor letter:
"GCI Liberty, the Alaskan cable business that was spun out of Liberty Broadband, has been renamed Liberty Capital Corporation (NASDAQ:GLIBK) (to reflect a future which is expected to include a broader array of businesses, and with its legacy GCI Alaska cable business being the solid "cash cow"). It fell 40.6%. There was plenty of news. Most notable was its USD 360m acquisition of Quintillion, which owns around 3,000 kilometres of fibre cable and plans to expand it by a further 2,500 kilometres or so. This perfectly aligns with Liberty's GCI operations. We understand Quintillion generates around USD 55-60m in revenue and USD 30m in free cash. We would expect significant synergies (reportedly around USD 20m) so we have little doubt that the deal adds value. And in fact, when we incorporate it into our model, the valuation uplift is around 35%. Management also decided to retreat from the competitive and low margin video business. And finally, Liberty Capital had intended to acquire an interest in Liberty Latin America by striking a deal for an initial 6% stake and building on that by buying John Malone's interest. For some reason this did not proceed which perhaps spooked the market. With the share price falling (to levels approximating half our valuation), and encouraged by its CEO buying shares, we increased our
2 months ago
The most talked about and market moving research calls around Wall Street are now in one place. Here are today's research calls that investors need to know, as compiled by The Fly.
Top 5 Upgrades:
Wells Fargo upgraded Ulta Beauty (ULTA) to Equal Weight from Underweight with a price target of $525, up from $450, after meeting with management. The firm says the company is navigating industry headwinds better than expected.
Oppenheimer upgraded Etsy (ETSY) to Outperform from Perform with a $90 price target. The firm cites the company's AI search benefits, product improvements, and app engagement for the upgrade.
Berenberg upgraded Eli Lilly (LLY) to Buy from Hold with a price target of $1,400, up from $1,220. The firm says its 2026 return on investment **** ysis confirms Eli Lilly's "strong track record of delivering best-in-class returns on investment."
Bernstein upgraded Agilon Health (AGL) to Outperform from Market Perform with a price target of $125, up from $86. The company is undergoing a turnaround focused on risk-taking discipline and incremental medical cost improvements, the firm tells investors in a research note.
#firm #outperform #perform
2 months ago
Oxford Industries, Inc. (NYSE:OXM) reported fiscal second-quarter net sales of $394.4 million, down 2.2%. Full-price direct-to-consumer sales declined 1%, while wholesale sales fell 14%, primarily reflecting lower off-price sales.
GAAP gross margin increased to 73.8% from 61.4% after Oxford Industries, Inc. (NYSE:OXM) recognized approximately $42 million of tariff refund claims as a reduction of cost of goods sold. Company-defined non-GAAP adjusted gross margin, excluding tariff refunds and LIFO effects, still improved to 63.1% from 61.7%. Updated **** ortment, sourcing, and pricing strategies increased initial markups, while lower off-price wholesale sales improved the sales mix.
Oxford Industries, Inc. (NYSE:OXM) lowered full-year sales guidance to $1.43 billion to $1.47 billion from $1.475 billion to $1.505 billion. Company-defined non-GAAP adjusted EPS guidance fell to $1.60 to $2.00 from $2.30 to $2.70, reducing the midpoint by 28%. Adjusted EPS excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, distribution-center relocation costs, merchandising initiatives, store-closure impairments and related taxes.
Underlying margin expansion suggests Oxford Industries, Inc. (NYSE:OXM) improved product economics beyond the one-time refund. Company-defined non-GAAP adjusted operating income, which excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, and specified distribution-center, merchandising, and store-closure costs, increased to $29.3 million from $28.3 million. Adjusted operating margin rose to 7.4% from 7.0%.
Tommy Bahama remained the strongest major brand for Oxford Industries, Inc. (NYSE:OXM), with sales increasing 0.8% and adjusted gross margin rising to 63.6% from 60.7%. FIFO inventory fell $9 million, or 4%, from one year earlier, reducing markdown exposure.
#gaap

2 months ago
Oklo (OKLO) and X-Energy (XE) each fell 5% as markets sold the nuclear group on X-Energy's Sell rating, ignoring Oklo's concurrent Buy initiation.
URA dropped 3% while SPY fell just 0.4%, confirming Thursday's pressure was a sector-specific nuclear selloff, not a broad market event.
Analyst Dimple Gosai argues that financing structure, rather than reactor technology, is what decides which SMR developers can build a first plant and win customers.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and X-Energy, Inc. Class A Common Stock didn't make the cut. Enter your email to see the names that beat XE. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of Oklo (NYSE:OKLO), NuScale Power (NYSE:SMR) and X-Energy (NASDAQ:XE) are sliding together in Thursday afternoon trading after Piper Sandler issued a split rating action across advanced nuclear. Oklo stock is down 5% to $40.50, with the year-to-date (YTD) decline now at 44%.
#enter #NYSE
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Lam Research Corporation (NASDAQ:LRCX), a leading semiconductor equipment company that supplies semiconductor processing equipment. Lam Research Corporation (NASDAQ:LRCX), with a 4.7% portfolio weight, contributed 2.2% to the Fund's performance this quarter. On September 1, 2026, Lam Research Corporation (NASDAQ:LRCX) closed at $290.20 per share. Over the past month, Lam Research Corporation (NASDAQ:LRCX) declined 5.60%, but its shares are up 196.91% over the past year. Lam Research Corporation (NASDAQ:LRCX) has a market capitalization of $363.13 billion.
Sands Capital Select Growth Fund stated the following regarding Lam Research Corporation (NASDAQ:LRCX) in its Q2 2026 investor letter:
"Lam Research Corporation (NASDAQ:LRCX) is a leading global provider of semiconductor fabrication equipment. Shares of the business benefited from renewed confidence in semiconductor capital spending and the rising complexity of chip manufacturing. In the first quarter, revenue grew 24 percent and adjusted earnings per share grew 42 percent year over year, while June-quarter guidance exceeded consensus expectations. The company is a critical supplier of etch and deposition equipment, both of which become increasingly important as memory architectures and leading-edge semiconductor manufacturing grow more complex. We believe Lam's exposure to high-bandwidth memory, advanced NAND, and a recovering memory investment cycle gives it a differentiated role within the AI infrastructure supply chain."
#NASDAQ #fund #select

2 months ago
The dollar index (DXY00) rose by +0.27% on Tuesday. Soaring T-note yields on Tuesday strengthened the dollar's interest rate differentials and pushed the dollar higher. Also, Tuesday's +5% surge in WTI crude oil to a 6-week high raised inflation expectations, which could potentially persuade the Fed to raise interest rates, a supportive factor for the dollar. In addition, Tuesday's stock slump boosted liquidity demand for the dollar.
Gains in the dollar were limited on Tuesday amid weaker-than-expected US economic news, including Aug ISM manufacturing, July construction spending, and July JOLTS job openings.
August's Top Commodity Performers and Underperformers
Dollar Supported by Rising T-Note Yields and Falling Stocks
Our exclusive Barchart Brief newsletter is your FREE midday guide to what's moving stocks, sectors, and investor sentiment - delivered right when you need the info most. Subscribe today!
#july #note

2 months ago
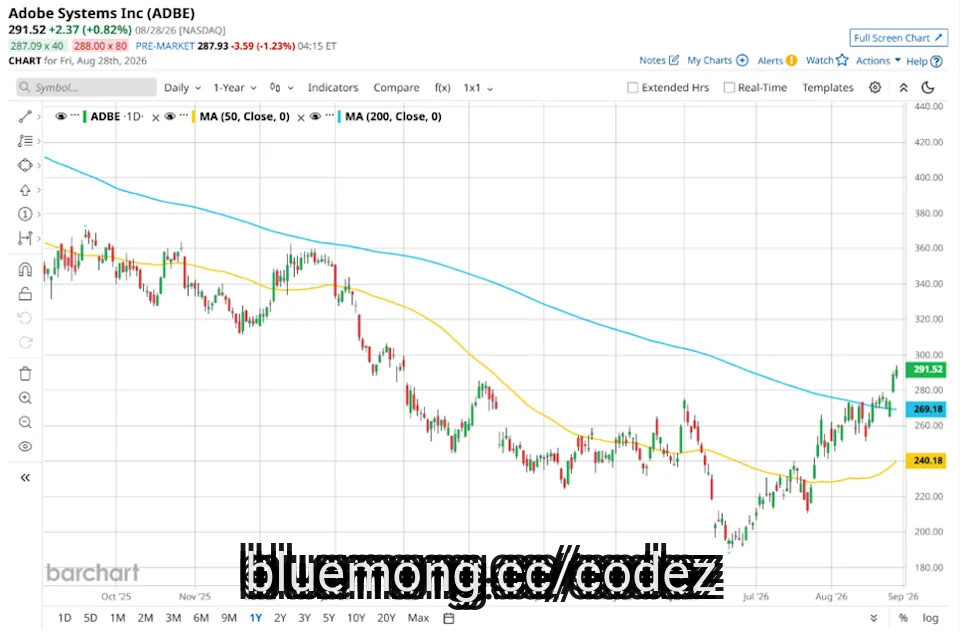
Adobe Inc. (ADBE), headquartered in San Jose, California, provides digital marketing and media solutions. Valued at $115.9 billion by market cap, the computer software company offers a line of application software products, type products, and content for creating, distributing, and managing information.
Companies worth $10 billion or more are generally described as "large-cap stocks," and ADBE fits right into that category with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the software - application industry. Adobe's strength is its Creative Cloud lock-in tools like Photoshop dominate creative workflows, backed by a sticky subscription model and AI-powered Firefly. Strong brand and expansion into marketing and document software keep it central for creatives and enterprises alike.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#Stock #palantir #creative

2 months ago
International Business Machines (IBM) is a global technology and consulting leader headquartered in Armonk, New York, with roots dating back more than a century. IBM's diversified portfolio spans hybrid cloud computing, artificial intelligence software, enterprise consulting, and next-generation infrastructure, including mainframe systems and quantum computing. IBM has repositioned itself around AI-driven productivity, Red Hat's hybrid cloud platform, and its ambitious quantum computing roadmap targeting a large-scale fault-tolerant quantum computer by 2029. With a client base spanning global enterprises and governments, IBM continues investing heavily in AI, automation, and open-source innovation to drive long-term growth.
IBM stock is currently trading around $230, well below its all-time and 52-week high of $332.46 set in June, though comfortably above its 52-week low of $199.19. Shares tumbled sharply after IBM's second-quarter earnings miss in July, falling more than 7% in a single session to around $206 before staging a partial recovery in the following weeks.
Walmart Stock Is More Expensive Than Nvidia Amid Earnings Miss
SpaceX Stock Just Crashed Below Its IPO Price: Here's the Bull Case ****** ody Can Ignore
A Major Bitcoin Short Squeeze Is Taking MicroStrategy Stock Higher. What Comes Next.
#Stock #quantum #around #miss


2 months ago
Boliden has signed an agreement with Votorantim to acquire all of the latter's shares in Nexa Resources, representing a 64.68% stake in the mining company with operations in Brazil and Peru.
The agreement values Votorantim's Nexa shares at $15.29 per share. The offer price reflects a 14.2% premium to Nexa's 20-day average price as of 1 July 2026.
The total implied consideration for the transaction is $1.31bn.
The deal gives Nexa an equity value of approximately $2.02bn (€1.73bn) and an enterprise value of $3.66bn.
Under the terms of the agreement, Boliden will exchange 0.250 newly issued Boliden shares for each Nexa share held by Votorantim.
#nexa #Share #value #Brazil

2 months ago
You can find original article here WealthManagement. Subscribe to our free daily WealthManagement newsletters.
With this year's crop of superstar IPO filings, including ***** eX and Anthropic, there has been a greater focus on the role venture capital plays in investors' portfolios. The stage at which promising companies go public has moved much later in their evolution, meaning that investors seeking the outsized returns of betting on the next Apple, Amazon, or ***** eX must do so while the companies are still private.
Traditionally, that has not been an avenue open to many individual investors, as venture capital funds have tended to come with qualified purchaser requirements, hefty investment minimums, 15-plus-year payoff horizons and limited liquidity mechanisms. A new crop of players, however, is promising mass-affluent investors that they can enter the venture capital business as well, often without the need for accreditation or investment minimums. Whether they can succeed in doing so without making investors take on outsized risks relative to returns is an open question.
One of the first companies to launch a venture-capital fund marketed to retail investors was Destiny XYZ Inc. in the spring of 2024. Called Destiny Tech100 (DXYZ), the fund focuses on "late-stage venture-backed companies," with Destiny XYZ viewing them as a more stable investment than fresh start-ups. Destiny Tech100, which today has a market cap of about $1 billion, comes with a 2.5% annual management fee—roughly in line with what a traditional venture capital fund would charge—but requires no accreditation or minimum investment, since it's structured as an exchange-listed closed-end fund (CEF).
Today, the fund lists 36 companies among its holdings, including ***** eX and OpenAI. Over a 52-week period, DXYZ posted total returns of 21.02%. Over the most recent three-month period, its total returns fell by 44.16%, with its shares trading at $32.94 apiece as of Monday afternoon, down from their 52-week high of $72.87 per share.
#destiny #SpaceX

2 months ago
The recent surge in Bitcoin's (CRYPTO: $BTC) price has given Strategy (NASDAQ: $MSTR) a $1.4 billion U.S. profit on its cryptocurrency holdings.
Bitcoin was trading at $77,300 U.S. early on Aug. 21, up 23% from $62,800 U.S. at the start of the week.
The price of BTC has taken off after the U.S. Treasury intervened in the bond market to lower yields and U.S. President Donald Trump called on Congress to pass the Clarity Act legislation.
More From Cryptoprowl:
Canadian Defense Tech Firm Jumps 92% as Government Revenue Boosts Margins
#Crypto #Bitcoin #treasury #president
2 months ago
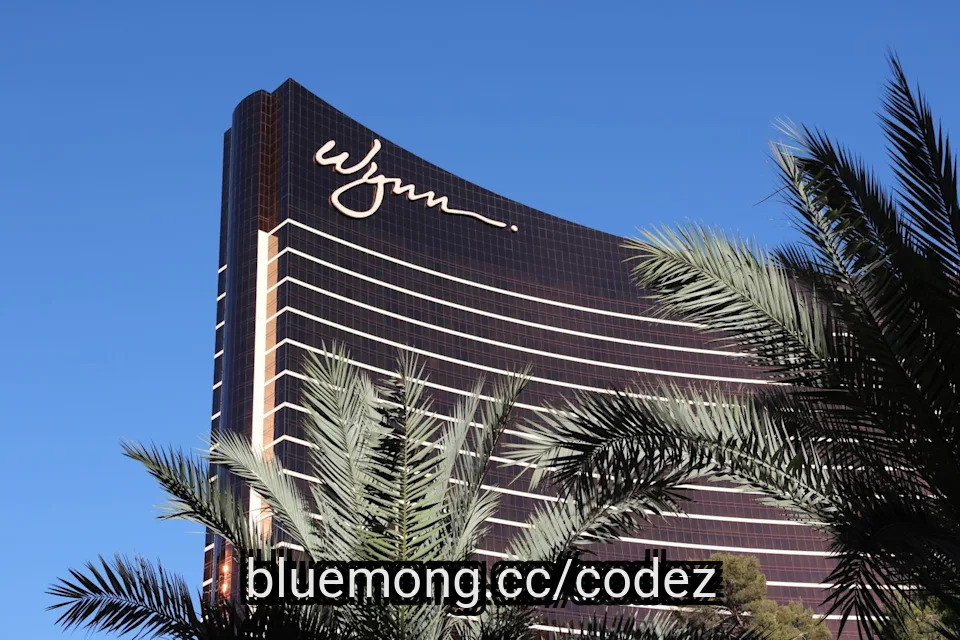
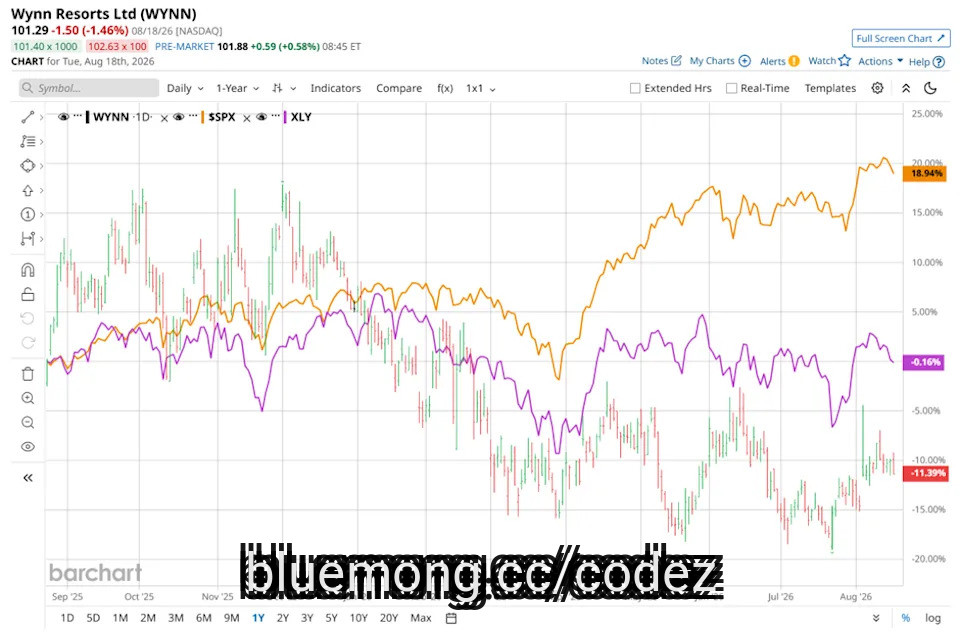
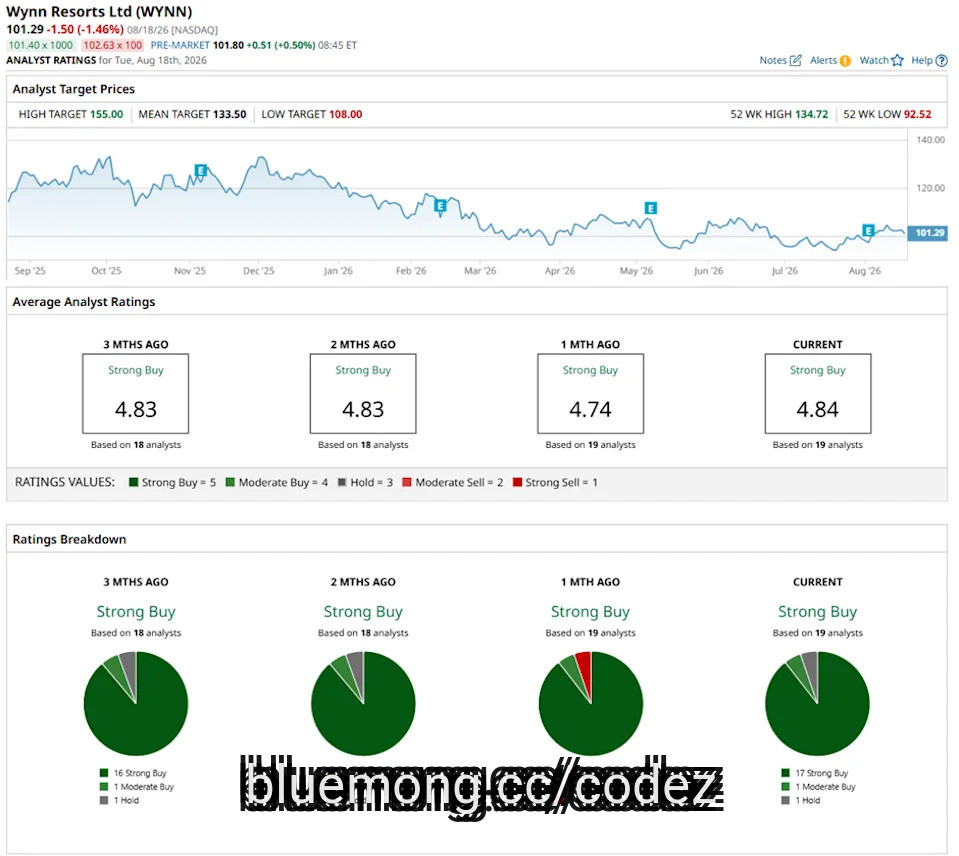
Las Vegas, Nevada-based Wynn Resorts, Limited (WYNN) designs, develops, and operates integrated resorts. Valued at $10.4 billion by market cap, the company offers amenities such as guest rooms and suites, restaurants, golf course, spa, bars, meeting and convention ****** e, night clubs, and recreation and leisure facilities.
Shares of this luxury resort and casino company have underperformed the broader market over the past year. WYNN has declined 9.8% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 19.3%. In 2026, WYNN stock is down 15.4%, compared to the SPX's 12.4% rise on a YTD basis.
Barron Trump, 20, Now Worth $150 Million — More Than Mom, Melania — From Crypto And $39 Energy Drink
Billionaire Michael Saylor Warns Against Buying a House Because 'Every 36 Years You Actually Pay the Cost of the House in Tax to the Government'
QQQ Just 'Gamma Flipped' as Market Makers Were Forced to Sell. Here's What Our Top Chart Expert is Tracking Next.
#wynn #resorts #company #limited
2 months ago
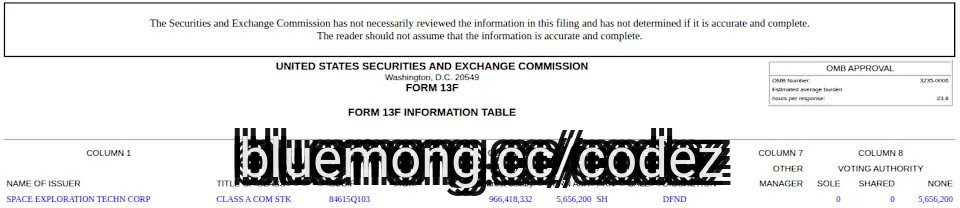
Intesa Sanpaolo, Italy's largest bank, disclosed a $966.42 million stake in ****** eX just weeks after slashing its exposure to BlackRock's Bitcoin ETF.
The shift marks a clear pivot from direct crypto exposure toward an indirect bet through traditional equities.
According to the filing submitted on August 4, Intesa acquired 5.66 million ****** eX shares. The position became the largest in the bank's entire US portfolio.
Follow us on X to get the latest news as it happens.
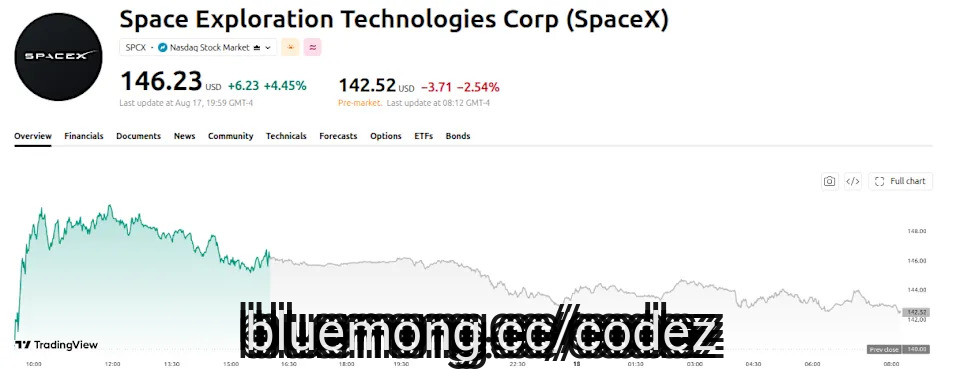
The stake represents roughly 33% of the $2.92 billion the bank holds in US-listed ****** ets. ****** eX went public on June 12. Elon Musk's company holds 18,712 BTC on its corporate balance sheet.
#bank #million #stake
2 months ago
Generation Income Properties (NASDAQ:GIPR) narrowed its second-quarter 2026 net loss attributable to common shareholders by 76% year over year and regained compliance with Nasdaq's stockholders' equity requirement as ******* et sales, capital raising and preferred equity restructuring strengthened its balance sheet.
The Q2 results show measurable progress in GIPR's deleveraging strategy, but near-term risks remain, including a $7.96 million preferred equity redemption obligation, debt maturities, a going-concern disclosure and an unresolved Nasdaq minimum bid-price and market-value issue.
Generation Income Properties (NASDAQ:GIPR) reduced its Q2 net loss attributable to common shareholders to $1.08 million from $4.42 million a year earlier.
Nasdaq confirmed that GIPR regained compliance with its stockholders' equity requirement effective August 10, although compliance will be monitored for one year.
The Loci preferred equity redemption obligation has fallen from a peak of approximately $20 million to $7.96 million as of August 1.
#NASDAQ #compliance #generation

3 months ago
Dimension Energy has raised $857m in additional capital to accelerate the expansion of its distributed solar operations in the US.
The investment includes a $200m increase to Dimension Energy's corporate credit facility, led by Nuveen Energy Infrastructure Credit and funds and accounts managed by HPS Investment Partners.
The upsizing brings Dimension Energy's total corporate credit facility to $650m. It provides the company with further flexibility to advance its pipeline of distributed solar projects and move developments into the construction phase.
A further $657m in construction-to-term debt and tax equity financing has also been secured to support the buildout of 29 solar projects across New York, Illinois, Pennsylvania, New Jersey and Virginia. The combined capacity of these projects is 149MW.
Advantage Capital acted as tax equity investor, with the debt package coordinated primarily by First Citizens Bank, ING Capital, MUFG Bank and the National Bank of Canada. Fifth Third Bank participated as joint lead arranger.
#capital #credit #projects

3 months ago
Lactalis has entered a "definitive" agreement to acquire the UK business of Canadian peer Saputo in the French dairy giant's fourth deal in two months.
While the privately-owned company did not reveal the purchase price in a statement today (14 August), Saputo tagged the transaction at around £988m ($1.33bn).
The deal is expected to close by the end of the first quarter next year, subject to regulatory approval, Toronto-listed Saputo added.
Lactalis said in its own announcement that Saputo UK, which generated revenue in its latest financial year of £800m, comes with five production facilities, along with a host of cheese brands such as Cathedral City and Davidstow.
The sites are located in Hawes (Yorkshire), Davidstow (Cornwall), Nuneaton (Warwickshire), Kirkby (Merseyside) and the Isle of Bute (Scotland), employing around 1,300 people, Lactalis said.
#davidstow #around #august #toronto

3 months ago
World Bank Group member IFC has extended a loan of up to $20m to Novatex, a plastic resin manufacturer in Pakistan.
The loan will fund imports of key raw materials and machinery for packaging.
According to IFC, the financing is aimed at helping local manufacturing while supporting employment, export income and the stability of domestic supply chains.
The move is expected to limit dependence on imported packaging supplies and reduce the risk of disruption for manufacturers that rely on them.
The transaction is also tied to IFC's environmental priorities.
#novatex #member

3 months ago
Cameco (NYSE: CCJ) recently reported ugly second-quarter results. The nuclear fuel supplier's revenue fell 7%, while its adjusted earnings per share missed the ******* ysts' consensus estimate by a mile (0.18 Canadian dollars per share vs. CA$0.36 per share, or $0.13 to $0.26).
However, things for the uranium company weren't as bad as they initially looked. The earnings miss was almost entirely due to lower equity earnings from its investment in Westinghouse Electric, which it co-owns with Brookfield Renewable. That trend could quickly reverse as its owners are preparing to take Westinghouse public, which could unlock significant value for Cameco.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Cameco bought a 49% interest in Westinghouse in late 2023, with Brookfield Renewable purchasing the remaining 51% stake. The deal valued Westinghouse at CA$8.2 billion ($5.9 billion) at the time of its closing.
As a co-owner of Westinghouse, Cameco accounts for its interest in the business on its financial results using the equity method of accounting in Canadian dollars. During the second quarter, Cameco reported a CA$10 million ($7.2 million) loss attributable to its Westinghouse share. That was down from CA$126 million ($90.4 million) in earnings in the year-ago period. However, that was entirely due to some lumpiness in Westinghouse's business. Cameco's equity earnings from Westinghouse were higher in 2025 due to its participation in the construction of two nuclear reactors at a power plant in the Czech Republic.
#earnings #NVIDIA

3 months ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
CNBC's Jim Cramer said Monday that Amazon.Com Inc CEO Andy Jassy's explanation of the company's artificial intelligence (AI) spending during its latest earnings call changed how Wall Street views Big Tech's multibillion-dollar AI investments.
Cramer said investors had questioned for months whether hyperscalers' massive AI infrastructure spending would generate meaningful returns.
He said Jassy's earnings call gave Wall Street the visibility it had been seeking into how those investments are expected to produce long-term cash flow, CNBC reported Monday.
Don't Miss:
#Monday #wall #earnings #Investments

3 months ago
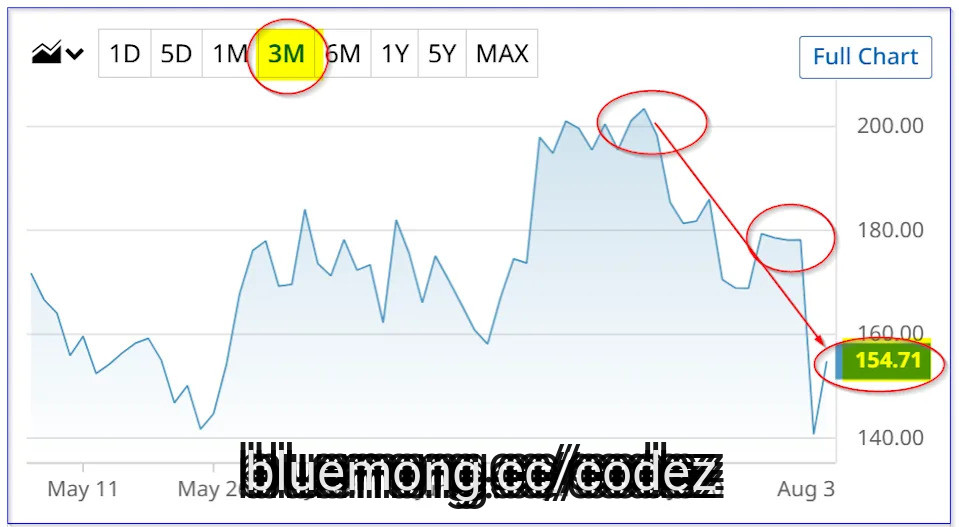
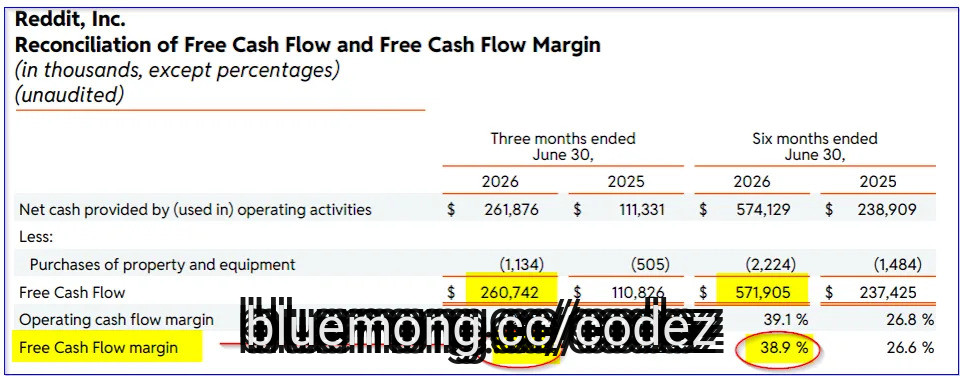
Reddit, Inc. (RDDT) generated a strong Q2 FCF margin (32.4%) - see page 21 of its shareholder letter. And for the trailing 12-month (TTM) period, its FCF margin was 36.7%, with very little capex.
So why did RDDT stock tumble 20% on Friday? That was too much, and value investors knew this. So, on Monday it was up 10%. It could still be worth over 40% more.
Investors Pile Into Long-Dated Microsoft Call Options in Unusual Volume - Bullish on MSFT Stock
Option Volatility And Earnings Report For Aug 3 - 7
Covered Call Screener Results for August 4th
#investors #Margin #reddit #long
3 months ago
Access to this page has been denied because we believe you are using automation tools to browse the website.
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #4c96affd -8c73-11f1-ae7b-7048bdc7e737
#javascript #automation
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #4c96affd -8c73-11f1-ae7b-7048bdc7e737
#javascript #automation
3 months ago
Access to this page has been denied because we believe you are using automation tools to browse the website.
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #87eb1c12 -8bf5-11f1-b316-5dc17de1ecc8
#please
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #87eb1c12 -8bf5-11f1-b316-5dc17de1ecc8
#please
3 months ago
The AI boom is forcing some of technology's biggest cash machines to behave more like utilities. On July 22, Reuters reported that Microsoft Corporation (NASDAQ:MSFT), Oracle Corporation (NYSE:ORCL), and three other hyperscalers are expected to spend more on capital expenditures than they generate in combined free cash flow by 2027. From 2025 through 2027, their annual operating cash flow is projected to rise by $340 billion, versus a $534 billion increase in capex. Microsoft and Oracle, however, are not carrying the same risk.
Microsoft showed the squeeze in fiscal Q2. Operating cash flow was $35.8 billion, while capex including finance leases reached $37.5 billion. That does not mean the company burned cash: Microsoft reported $5.9 billion of conventional free cash flow because that measure deducts cash property and equipment purchases, not newly originated finance leases.
Carol Gauthier/Shutterstock.com
Fiscal Q3, however, was stronger. Operating cash flow rose to $46.7 billion and free cash flow reached $15.8 billion, even after $30.9 billion of cash property and equipment spending. Its AI business also passed a $37 billion annual revenue run rate. Microsoft can finance the buildout. The question is whether Azure and Copilot can generate nice returns before expensive GPUs depreciate or become obsolete.
Oracle has a more immediate cash problem. In fiscal 2026, it spent $55.7 billion on capex against $32 billion of operating cash flow, leaving free cash flow at negative $23.7 billion. Demand is real: cloud revenue grew 39% to $34 billion, and remaining performance obligations reached $638 billion. But backlog is not cash. Oracle must construct capacity before much of that revenue arrives, and plans to raise $45 billion to $50 billion through debt and equity.
#operating #free

3 months ago
XLU trades at 23x earnings, which is above its 17x historical norm, as Constellation and Vistra add direct AI data center power pricing exposure.
VPU delivers similar returns to XLU with broader diversification, while RSPU prevents any one stock from dominating the way NextEra does at 14%.
Don't wait: the **** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
Utility stocks returned to focus in 2026 as artificial intelligence data center demand strained the power grid. That backdrop has pushed investors back into sector funds like the Utilities Select Sector SPDR Fund (NYSEARCA:XLU), the Vanguard Utilities ETF (NYSEARCA:VPU), the Invesco S&P 500 Equal Weight Utilities ETF (NYSEARCA:RSPU), and the actively managed Virtus Reaves Utilities ETF (NYSEARCA:UTES).
XLU sits at the center of the conversation. The fund carries a 0.08% net expense ratio, has climbed roughly 8% year to date, and pays a 2.6% dividend yield. The question for investors is whether that combination still offers the stability the sector is known for after a re-rating driven more by AI narratives than by regulated returns.
4 months ago
Artisan Partners, an investment management firm, issued its first-quarter 2026 investor letter for the "Artisan Mid Cap Value Fund". A copy of this letter is available for download here. In Q1 2026, the portfolio underperformed the benchmark Russell Midcap Value Index as the market favored momentum-driven stocks over quality factors. Some holdings faced company-specific setbacks and negative sentiment. The Fund's Investor Class: ARTQX returned -4.93%, Advisor Class: APDQX declined by -4.90%, and Institutional Class: APHQX fell by -4.97%, all trailing the Index's 3.68% gain. The equity market in the quarter was mixed, with mid- and small-cap indices showing resilience despite lagging large-cap growth stocks. Volatility increased, initially fueled by interest in AI and private credit, but escalated after the outbreak of war in Iran, leading to rising oil prices. Sector performance varied, with energy leading the gains. The Fund continues to seek companies capable of value growth during market dislocations at attractive entry points. Also, review the Fund's top five holdings to see its best picks for 2026.
In its first-quarter 2026 investor letter, Artisan Mid Cap Value Fund highlighted Brown & Brown, Inc. (NYSE:BRO) as a newly added position. Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm that operates through Retail and Specialty Distribution segments. On July 7, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $69.27 per share, reflecting a market capitalization of $23.48 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one-month return of 15.10%, while its shares lost 35.94% over the past 52 weeks.
Artisan Mid Cap Value Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q1 2026 investor letter:
"We initiated six new positions in Q1, representing an above-average rate of new purchase activity. Increased market volatility and greater dispersion in US equities during the quarter created more opportunities to add new names that meet our three margin-of-safety criteria: attractive business economics, sound financial condition and attractive valuation. Additionally, we sought to use recent volatility to upgrade the portfolio's quality. Our three largest new buys by position size were Brown & Brown, Inc. (NYSE:BRO), Veralto and IQVIA Holdings.
Brown & Brown is a leading US insurance broker focused on the middle market. The shares have come under pressure alongside the broader broker group, as investors recalibrated expectations following a period of elevated growth driven by a hard insurance market. As pricing and growth have begun to normalize, valuations have compressed, creating what we believe is a more attractive entry point. From a business economics perspective, insurance brokerage is a compelling model. Brokers act as intermediaries without taking underwriting risk, resulting in high margins, low capital intensity and strong free cash flow conversion, supported by high customer retention. Brown & B




