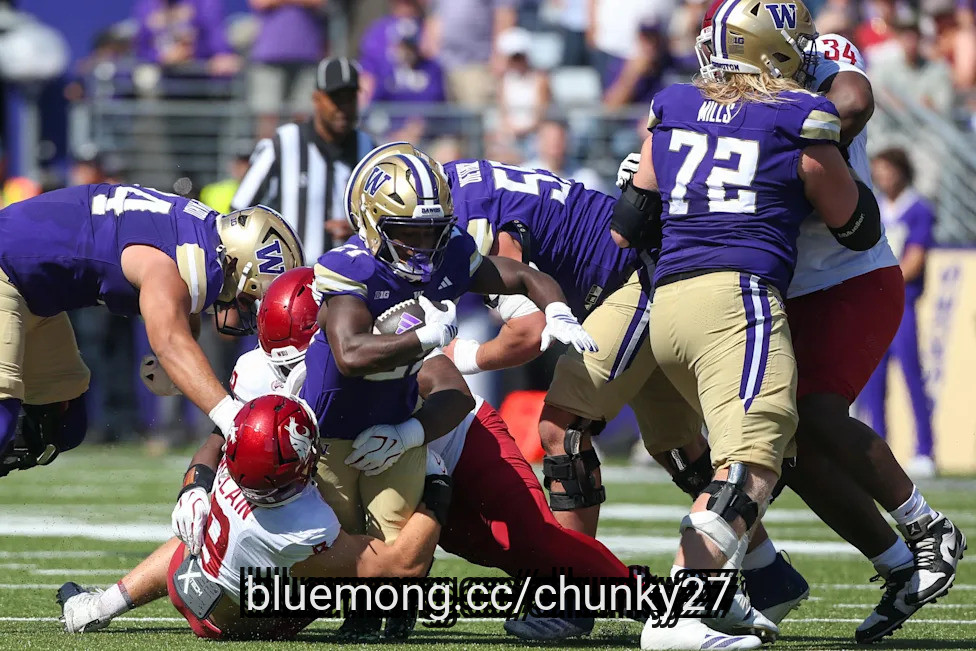
17 hours ago
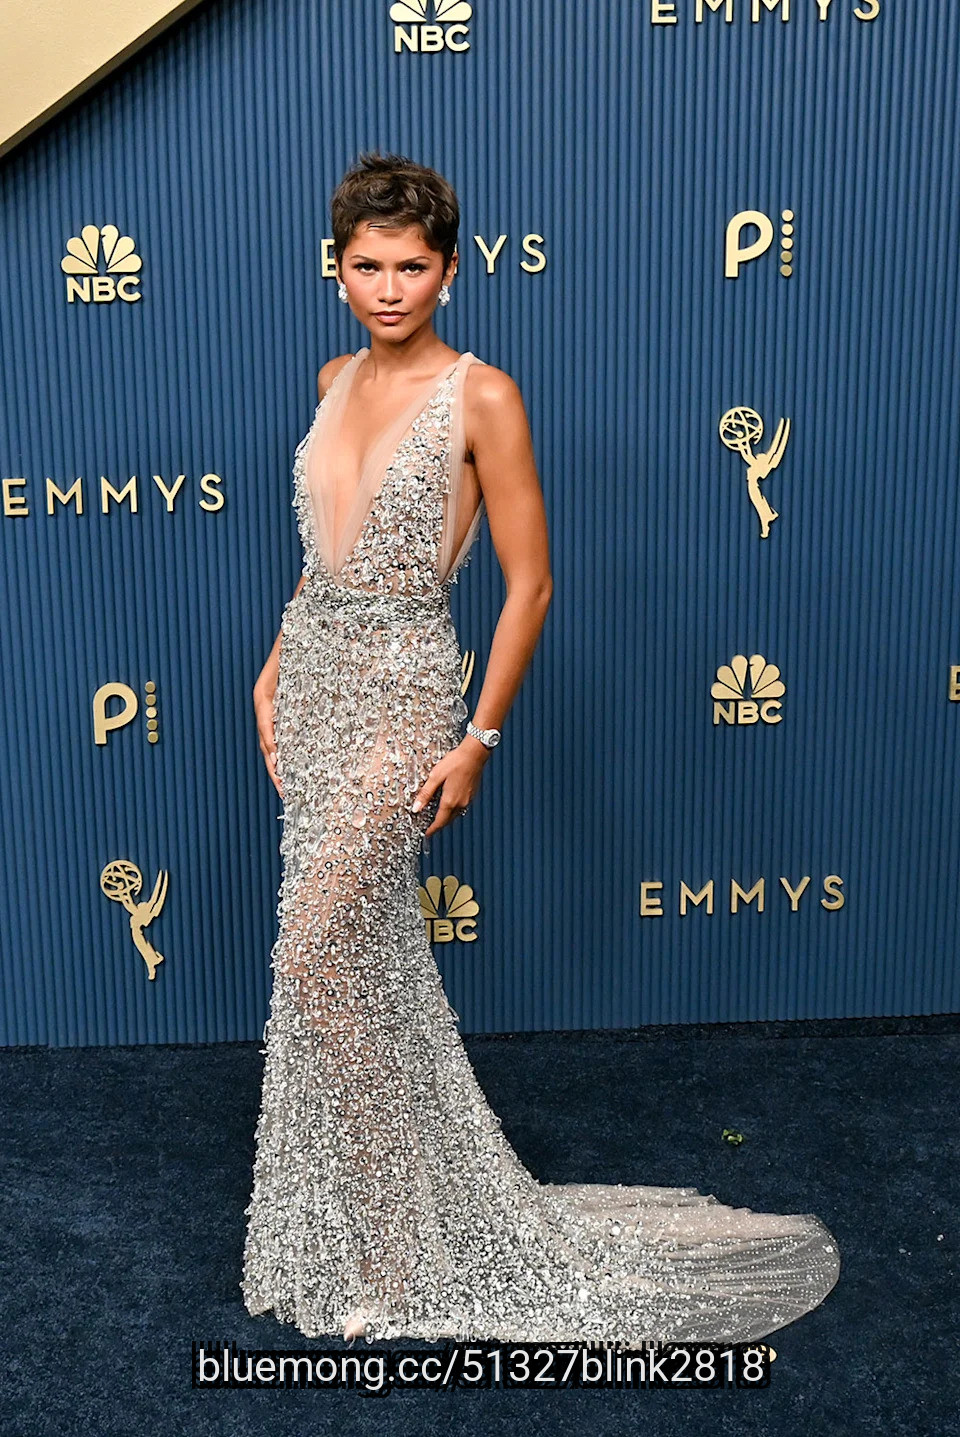
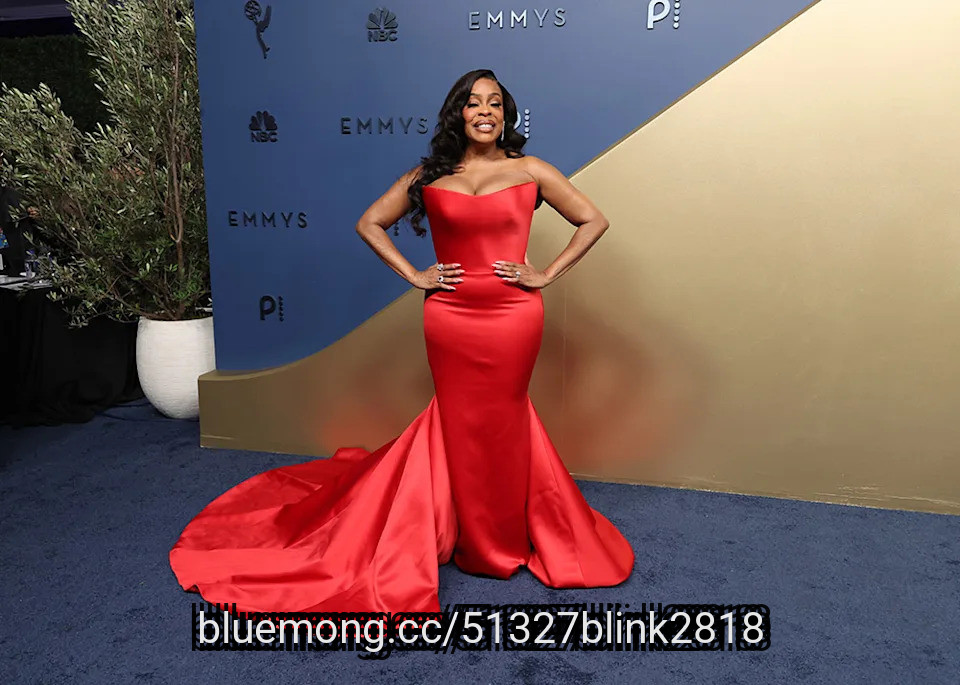
Amid a wealth of style choices at the 2026 Emmys, one color ruled above all: a bold crimson in its best look-at-me hue, seen on women happy to embrace its powerful psychology. From Cailee Spaeny in custom Miu Miu to Hassie Harrison in Monique Lhuillier, Rhea Seehorn in Louis Vuitton and Emmys host Mariska Hargitay in Monse on the red carpet, the choice was just the beginning of an evening that acquitted itself well on the style spectrum.
Among the more touching elements of the night's fashion conversations were the remembrances of legendary designer Bob Mackie, whose death in Palm Springs at the age of 87 was announced mere hours before the 78th Primetime Emmys kicked off at the Peacock Theater in downtown Los Angeles. During the pre-show, E! News host Keltie Knight took a moment to honor Mackie, calling him "one of the most prolific and celebrated costume designers of all time … [who] created some of the most iconic looks of all time for stars like Cher, Carol Burnett, Elton John, Diana Ross, Marilyn Monroe, Barbra Streisand, Dolly Parton and so many others. His impact on the world of fashion is really hard to put into words, and his legacy absolutely lives on." E! News finished the segment with a moment of silence and a black screen.
More from The Hollywood Reporter
Apple TV Reigns at Emmys With 'Widow's Bay' and 'Pluribus' Breakthroughs
Emmys: Chuck Norris, Patrick Muldoon, Daveigh Chase Omitted From In Memoriam Tributes
#spaeny
Among the more touching elements of the night's fashion conversations were the remembrances of legendary designer Bob Mackie, whose death in Palm Springs at the age of 87 was announced mere hours before the 78th Primetime Emmys kicked off at the Peacock Theater in downtown Los Angeles. During the pre-show, E! News host Keltie Knight took a moment to honor Mackie, calling him "one of the most prolific and celebrated costume designers of all time … [who] created some of the most iconic looks of all time for stars like Cher, Carol Burnett, Elton John, Diana Ross, Marilyn Monroe, Barbra Streisand, Dolly Parton and so many others. His impact on the world of fashion is really hard to put into words, and his legacy absolutely lives on." E! News finished the segment with a moment of silence and a black screen.
More from The Hollywood Reporter
Apple TV Reigns at Emmys With 'Widow's Bay' and 'Pluribus' Breakthroughs
Emmys: Chuck Norris, Patrick Muldoon, Daveigh Chase Omitted From In Memoriam Tributes
#spaeny

24 hours ago
September's debate over Chinese and American AI spending puts Alibaba Group Holding Limited (NYSE:BABA) and Amazon.com, Inc. (NASDAQ:AMZN) on opposite sides of the same investment question. Both report strong demand for computing services. Shareholders still need that demand to justify the infrastructure bill.
September 7 coverage of Jefferies' ***** ysis highlighted differences in spending intensity. The companies' own results suggest a more useful test than choosing a winner from headline capital expenditures: distinguish operating progress from cash committed ahead of future growth.
Alibaba's August 20 report showed June-quarter AI Cloud and Compute Services revenue increasing 45% to RMB48.44 billion. Segment adjusted EBITA reached RMB5.63 billion. The reporting group now combines its former Cloud Intelligence Group with T-Head, so investors should use the company's recast comparisons.
That operating improvement supports the case that computing demand can generate returns. It does not mean the spending cycle has already paid for itself. Group capital expenditures reached RMB67.68 billion, while free cash flow, a non-GAAP liquidity measure, was negative RMB44.67 billion for the quarter.
The opportunity is to keep expanding customer demand and utilization as new infrastructure becomes available. The risk is that cash outlays remain elevated while weaker returns elsewhere in the group reduce the room for error. Cloud growth alone cannot settle the value of the entire business.
#spending #cash #Services
September 7 coverage of Jefferies' ***** ysis highlighted differences in spending intensity. The companies' own results suggest a more useful test than choosing a winner from headline capital expenditures: distinguish operating progress from cash committed ahead of future growth.
Alibaba's August 20 report showed June-quarter AI Cloud and Compute Services revenue increasing 45% to RMB48.44 billion. Segment adjusted EBITA reached RMB5.63 billion. The reporting group now combines its former Cloud Intelligence Group with T-Head, so investors should use the company's recast comparisons.
That operating improvement supports the case that computing demand can generate returns. It does not mean the spending cycle has already paid for itself. Group capital expenditures reached RMB67.68 billion, while free cash flow, a non-GAAP liquidity measure, was negative RMB44.67 billion for the quarter.
The opportunity is to keep expanding customer demand and utilization as new infrastructure becomes available. The risk is that cash outlays remain elevated while weaker returns elsewhere in the group reduce the room for error. Cloud growth alone cannot settle the value of the entire business.
#spending #cash #Services


1 day ago
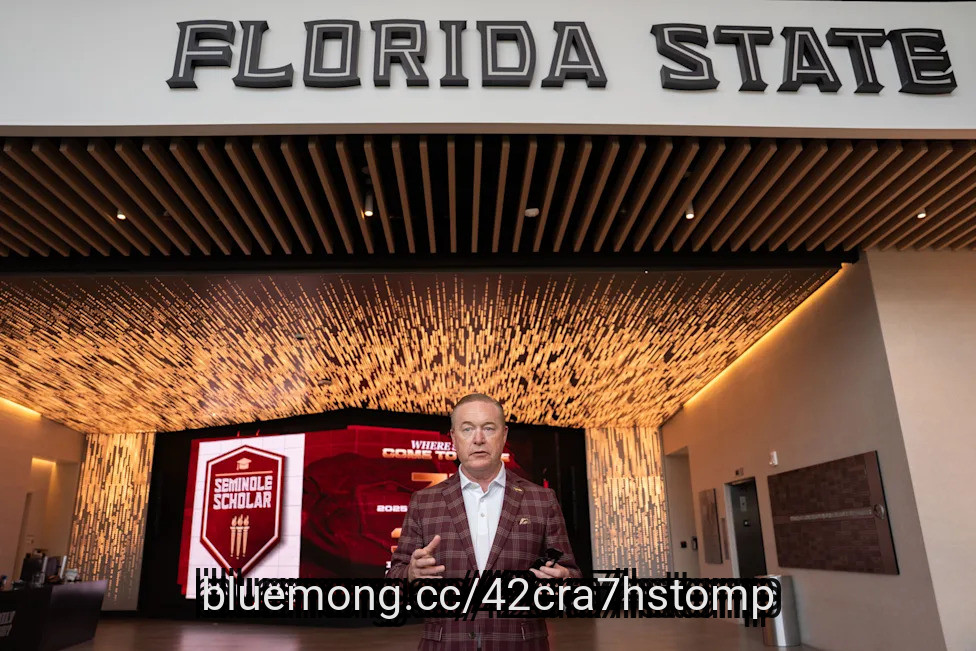
Florida State is in search of a new athletic director after the university fired Michael Alford on Monday, Sep. 14, four years after he was hired.
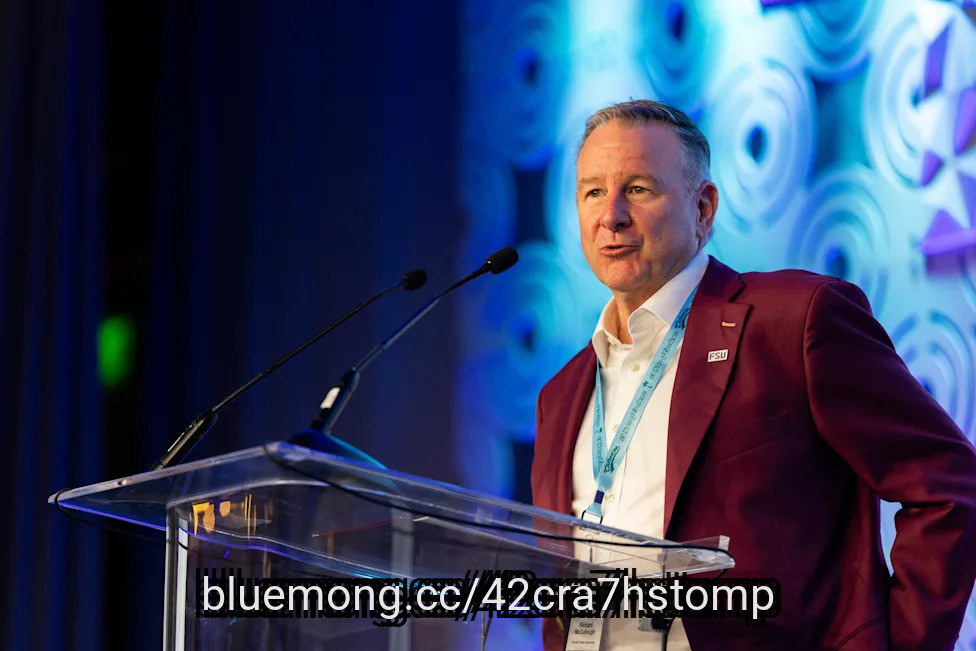
The move was made by FSU president Richard McCullough, who said the Seminoles' athletic program needs to better position itself for the future of collegiate athletics. When he spoke with the media Monday morning, McCullough gave insight into what FSU is looking for in its next athletic director.
He placed a value on business acumen and cited the need for success in revenue generation, while also being savvy enough to navigate the complexities of modern collegiate sports, particularly football.
While no move is imminent, here are a few names that make our initial FSU AD hot board.
Dickey has led the Broncos since 2021, and during his time as the program's athletic director, ***** ey has had a huge impact on revenue generation for the program. That's an area that McCullough highlighted as being important to the Seminoles next AD when speaking to the media after Alford's firing. ***** ey, named the 2025 National ***** ociation of Collegiate Directors of Athletics AD of the year, has overseen Boise State's transition from the Mountain West into the reimagined Pac-12, which would suit FSU and the university's potential interest in departing the ACC.
#Athletic #collegiate
The move was made by FSU president Richard McCullough, who said the Seminoles' athletic program needs to better position itself for the future of collegiate athletics. When he spoke with the media Monday morning, McCullough gave insight into what FSU is looking for in its next athletic director.
He placed a value on business acumen and cited the need for success in revenue generation, while also being savvy enough to navigate the complexities of modern collegiate sports, particularly football.
While no move is imminent, here are a few names that make our initial FSU AD hot board.
Dickey has led the Broncos since 2021, and during his time as the program's athletic director, ***** ey has had a huge impact on revenue generation for the program. That's an area that McCullough highlighted as being important to the Seminoles next AD when speaking to the media after Alford's firing. ***** ey, named the 2025 National ***** ociation of Collegiate Directors of Athletics AD of the year, has overseen Boise State's transition from the Mountain West into the reimagined Pac-12, which would suit FSU and the university's potential interest in departing the ACC.
#Athletic #collegiate

1 day ago
On August 6, The RealReal (NASDAQ:REAL) reported second quarter results that beat its own outlook and pushed the resale luxury marketplace to raise its full year guidance. Gross merchandise value hit an all time high of $617 million, up 22% from a year earlier, and management pointed to four straight quarters of GMV growth above 20%. But a wider net loss sitting next to those record numbers complicates the story for anyone weighing the stock today.
The headline number is GMV of $617 million for the quarter ended June 30, up 22% year over year, with total revenue climbing 17% to $193 million. Consignment revenue grew 15% while Direct Revenue, the company's owned inventory channel, grew 26%, showing both sides of the business contributing to the acceleration. Profitability moved in the same direction. Gross margin reached 74.4%, up 10 basis points from a year ago, and Adjusted EBITDA margin jumped to 7%, a 290 basis point improvement that management called nearly 300 basis points of expansion.
The buyer base backs up the growth story rather than just the pricing. Trailing twelve-month active buyers rose 11% to 1,107,000, and average order value climbed 13% to $659, meaning existing shoppers are spending meaningfully more per transaction, not just showing up more often. That combination gave management enough confidence to raise full-year guidance to $2.54 billion to $2.57 billion in GMV and $788 million to $797 million in total revenue, alongside third-quarter Adjusted EBITDA guidance of $13.5 million to $14.5 million.
Despite the operating improvements, GAAP losses widened. Net loss came in at $27 million, or 14.1% of total revenue, compared to $11 million, or 6.9% of total revenue, a year earlier. GAAP basic net loss per share was $0.23 versus $0.10 in the prior year period, and diluted net loss per share was $0.23 versus $0.13. Much of that swing traces to a $(18.6) million non-cash adjustment tied to the change in fair value of warrant liability, a factor unrelated to how the underlying business performed. On a non-GAAP basis, basic and diluted net loss per share actually narrowed to $0.01 from $0.06, underscoring how much of the GAAP gap is accounting rather than operations.
There is also a transparency wrinkle in the guidance itself. The RealReal said it has not reconciled its forward-looking Adjusted EBITDA figures to GAAP net income or loss, citing components like payroll tax expense on employee stock transactions that it cannot predict with reasonable certainty. That leaves investors trusting a non-GAAP target without the usual bridge back to the bottom line.
#adjusted
The headline number is GMV of $617 million for the quarter ended June 30, up 22% year over year, with total revenue climbing 17% to $193 million. Consignment revenue grew 15% while Direct Revenue, the company's owned inventory channel, grew 26%, showing both sides of the business contributing to the acceleration. Profitability moved in the same direction. Gross margin reached 74.4%, up 10 basis points from a year ago, and Adjusted EBITDA margin jumped to 7%, a 290 basis point improvement that management called nearly 300 basis points of expansion.
The buyer base backs up the growth story rather than just the pricing. Trailing twelve-month active buyers rose 11% to 1,107,000, and average order value climbed 13% to $659, meaning existing shoppers are spending meaningfully more per transaction, not just showing up more often. That combination gave management enough confidence to raise full-year guidance to $2.54 billion to $2.57 billion in GMV and $788 million to $797 million in total revenue, alongside third-quarter Adjusted EBITDA guidance of $13.5 million to $14.5 million.
Despite the operating improvements, GAAP losses widened. Net loss came in at $27 million, or 14.1% of total revenue, compared to $11 million, or 6.9% of total revenue, a year earlier. GAAP basic net loss per share was $0.23 versus $0.10 in the prior year period, and diluted net loss per share was $0.23 versus $0.13. Much of that swing traces to a $(18.6) million non-cash adjustment tied to the change in fair value of warrant liability, a factor unrelated to how the underlying business performed. On a non-GAAP basis, basic and diluted net loss per share actually narrowed to $0.01 from $0.06, underscoring how much of the GAAP gap is accounting rather than operations.
There is also a transparency wrinkle in the guidance itself. The RealReal said it has not reconciled its forward-looking Adjusted EBITDA figures to GAAP net income or loss, citing components like payroll tax expense on employee stock transactions that it cannot predict with reasonable certainty. That leaves investors trusting a non-GAAP target without the usual bridge back to the bottom line.
#adjusted


1 day ago
On September 10, LightPath Technologies (NASDAQ:LPTH) reported fiscal fourth-quarter and full-year results that turned a multiyear strategic bet into a financial statement. Revenue nearly doubled for the year, margins expanded, and the company walked away from its last manufacturing ties to China. For a small-cap optics supplier that spent years explaining a strategy, this was the quarter the strategy started explaining itself.
Annual revenue climbed 92.7% to $71.7 million from $37.2 million, and the fourth quarter alone hit a record $21.2 million, up 73.8% year over year. That growth is not just volume. Full-year gross margin expanded to 36% from 27.2%, and the fourth quarter came in even higher at 39.4%, because ****** emblies, modules and cameras now make up 44% of annual sales instead of being sold as raw components.
CEO Sam Rubin said the shift reflects both a change in what LightPath sells and better execution on what it already made, noting every one of its four product groups improved margin for the year. Backlog finished at $110.9 million, up 197% from $37.4 million a year earlier, with $85.6 million of it scheduled for delivery within 12 months. Weeks after the fiscal year closed, the company booked another $24 million in counter-UAS orders, and some of those programs have already moved to monthly delivery cadences of tens of units.
LightPath also completed its exit from China, selling its subsidiary there for $4.5 million paid out over five years, leaving the company with no manufacturing footprint in a country that increasingly can't supply the defense primes it depends on. That matters because defense programs face a deadline this decade to source optics away from covered nations, and qualification cycles run two to three years, meaning the sourcing decisions being made now will determine who wins contracts in 2029 and 2030.
The company's fourth-quarter net loss narrowed to $4.1 million from $7.1 million a year earlier, but full-year operating expenses jumped to $45.5 million from $22 million, and $15.6 million of that was a noncash charge tied to G5 Infrared outperforming the earnout targets set at acquisition. Management called that charge mostly behind the business now that the final G5 payout has been accrued for January 2027, but it is a reminder that acquisition accounting can swing the income statement even when operations are healthy.
#year #quarter #China
Annual revenue climbed 92.7% to $71.7 million from $37.2 million, and the fourth quarter alone hit a record $21.2 million, up 73.8% year over year. That growth is not just volume. Full-year gross margin expanded to 36% from 27.2%, and the fourth quarter came in even higher at 39.4%, because ****** emblies, modules and cameras now make up 44% of annual sales instead of being sold as raw components.
CEO Sam Rubin said the shift reflects both a change in what LightPath sells and better execution on what it already made, noting every one of its four product groups improved margin for the year. Backlog finished at $110.9 million, up 197% from $37.4 million a year earlier, with $85.6 million of it scheduled for delivery within 12 months. Weeks after the fiscal year closed, the company booked another $24 million in counter-UAS orders, and some of those programs have already moved to monthly delivery cadences of tens of units.
LightPath also completed its exit from China, selling its subsidiary there for $4.5 million paid out over five years, leaving the company with no manufacturing footprint in a country that increasingly can't supply the defense primes it depends on. That matters because defense programs face a deadline this decade to source optics away from covered nations, and qualification cycles run two to three years, meaning the sourcing decisions being made now will determine who wins contracts in 2029 and 2030.
The company's fourth-quarter net loss narrowed to $4.1 million from $7.1 million a year earlier, but full-year operating expenses jumped to $45.5 million from $22 million, and $15.6 million of that was a noncash charge tied to G5 Infrared outperforming the earnout targets set at acquisition. Management called that charge mostly behind the business now that the final G5 payout has been accrued for January 2027, but it is a reminder that acquisition accounting can swing the income statement even when operations are healthy.
#year #quarter #China

1 day ago
On September 10, Copart (NASDAQ:CPRT) held its fourth-quarter earnings call and used it to unveil a deal that could reshape its business: an all-cash agreement to acquire ACV, a digital auto marketplace that moved roughly $10 billion of vehicles last year without owning a single lot. The announcement landed alongside a quarter that captured the company's central tension. Revenue rose, but net income fell, and management is now betting that pairing its junkyards with someone else's software can fix that.
The ACV deal is the headline, and for good reason. ACV brings more than 22,000 active buyers and inspection and valuation technology, while Copart contributes over 275 locations, roughly 4 million vehicles sold annually, and about 1 million members across more than 185 countries. Management structured it as an all-cash tender offer funded from cash on hand, with a close targeted by the end of the calendar year and earnings accretion expected in fiscal 2028. Executives framed the fit as physical scale meeting digital liquidity, giving dealers, banks, and fleet sellers a single partner for disposing of vehicles.
That diversification push is already showing up in the numbers. International revenue grew 11.7% to $222.1 million on 15% service revenue growth, and international buyers accounted for 45.7% of total US sales dollars despite making up only 38.2% of units, a sign they are chasing pricier vehicles. Domestically, non-insurance units returned to growth of 0.2% in the quarter after a full-year decline, dealer units rose 5.8%, and BluCar, which serves banks and fleets, expanded nearly 20%. Global average selling prices climbed 3.5%, evidence that Copart's auctions still command pricing power even as volumes soften.
The quarter's numbers show where the strain is. Consolidated revenue grew 2.4% to $1.2 billion, yet net income dropped 17.4% to $327.4 million and diluted earnings per share fell 14.6% to $0.35. Operating expense per car jumped 12.7% year over year as the company poured money into long-haul delivery, **** leExpress, and dedicated wholesale facilities, and US facility costs alone rose 7.7% in the quarter. Lower interest income, a byproduct of the $1.63 billion spent on buybacks earlier in the fiscal year, added to the squeeze.
The core insurance business is also cooling. Global insurance units fell 4.2%, with domestic insurance **** ignments down 7.5%, though management noted that figure would have been up 2.3% excluding the loss of a single customer. Collision claim frequency declined 3.4% even as total loss frequency hit a record 23.3% for a second quarter and severity topped $6,300 per claim, up 8.8%. And the ACV deal itself carries integration risk, since management expects only breakeven results before accretion arrives in fiscal 2028.
#quarter #vehicles #insurance
The ACV deal is the headline, and for good reason. ACV brings more than 22,000 active buyers and inspection and valuation technology, while Copart contributes over 275 locations, roughly 4 million vehicles sold annually, and about 1 million members across more than 185 countries. Management structured it as an all-cash tender offer funded from cash on hand, with a close targeted by the end of the calendar year and earnings accretion expected in fiscal 2028. Executives framed the fit as physical scale meeting digital liquidity, giving dealers, banks, and fleet sellers a single partner for disposing of vehicles.
That diversification push is already showing up in the numbers. International revenue grew 11.7% to $222.1 million on 15% service revenue growth, and international buyers accounted for 45.7% of total US sales dollars despite making up only 38.2% of units, a sign they are chasing pricier vehicles. Domestically, non-insurance units returned to growth of 0.2% in the quarter after a full-year decline, dealer units rose 5.8%, and BluCar, which serves banks and fleets, expanded nearly 20%. Global average selling prices climbed 3.5%, evidence that Copart's auctions still command pricing power even as volumes soften.
The quarter's numbers show where the strain is. Consolidated revenue grew 2.4% to $1.2 billion, yet net income dropped 17.4% to $327.4 million and diluted earnings per share fell 14.6% to $0.35. Operating expense per car jumped 12.7% year over year as the company poured money into long-haul delivery, **** leExpress, and dedicated wholesale facilities, and US facility costs alone rose 7.7% in the quarter. Lower interest income, a byproduct of the $1.63 billion spent on buybacks earlier in the fiscal year, added to the squeeze.
The core insurance business is also cooling. Global insurance units fell 4.2%, with domestic insurance **** ignments down 7.5%, though management noted that figure would have been up 2.3% excluding the loss of a single customer. Collision claim frequency declined 3.4% even as total loss frequency hit a record 23.3% for a second quarter and severity topped $6,300 per claim, up 8.8%. And the ACV deal itself carries integration risk, since management expects only breakeven results before accretion arrives in fiscal 2028.
#quarter #vehicles #insurance

1 day ago
On September 10, IBEX Limited (NASDAQ:IBEX) held its fourth-quarter and full fiscal year 2026 earnings call, and the numbers backed up a message management has been building toward for months. The company posted record full-year revenue, adjusted EBITDA, and free cash flow, all while pitching itself as a business that has flipped the AI narrative in its favor rather than becoming its next casualty. For a sector that has spent the last two years bracing for automation to gut it, that is a notable claim to back with actual client wins.
Full-year revenue hit $644.1 million, up 15.4% organically, and fourth-quarter revenue reached $164.3 million, up 11.6% from a year earlier. That marked the sixth straight quarter of double-digit growth, a streak that suggests the momentum is not a one-off. HealthTech led the charge, climbing 38.5% to $114 million for the year and blowing past the $100 million target management had set for the segment, driven largely by demand from large insurance payers. Technology grew 27.4% in the quarter, while travel and logistics added 17.8%, helped by a new AI agent partnership with Philippine Airlines.
That Philippine Airlines deal is the clearest evidence that IBEX's Sierra AI partnership, formalized in January and announced publicly in May, is more than a slide in an investor deck. During the proof of concept, the AI agent handled interactions in English, Tagalog, and Taglish, hit resolution rates above 20%, and scored a 4.7 out of 5.0 on customer satisfaction, on par with human agents. A separate deployment for BJ's Wholesale pushed resolution rates above 40% and matched that same satisfaction score, beating the marks the client's prior BPO vendor had put up with human agents alone. The company added 17 new trophy logo clients across the year, and its top five clients now make up 33% of revenue, down from 36%, a sign the business is not leaning on a shrinking handful of accounts to carry it.
Not every line moved in the right direction. Fourth quarter GAAP net income slipped to $8.7 million from $9.6 million a year earlier, and diluted EPS fell to $0.59 from $0.66. Management pointed to training costs tied to all those new client wins, a temporary hit from shifting work out of nearshore centers into offshore ones, and higher fuel prices hitting utility and transportation costs, particularly offshore. Adjusted EBITDA margin for the quarter slipped to 12.3% from 13.9%, the same set of pressures showing up in the profitability line rather than just net income.
#revenue #fourth
Full-year revenue hit $644.1 million, up 15.4% organically, and fourth-quarter revenue reached $164.3 million, up 11.6% from a year earlier. That marked the sixth straight quarter of double-digit growth, a streak that suggests the momentum is not a one-off. HealthTech led the charge, climbing 38.5% to $114 million for the year and blowing past the $100 million target management had set for the segment, driven largely by demand from large insurance payers. Technology grew 27.4% in the quarter, while travel and logistics added 17.8%, helped by a new AI agent partnership with Philippine Airlines.
That Philippine Airlines deal is the clearest evidence that IBEX's Sierra AI partnership, formalized in January and announced publicly in May, is more than a slide in an investor deck. During the proof of concept, the AI agent handled interactions in English, Tagalog, and Taglish, hit resolution rates above 20%, and scored a 4.7 out of 5.0 on customer satisfaction, on par with human agents. A separate deployment for BJ's Wholesale pushed resolution rates above 40% and matched that same satisfaction score, beating the marks the client's prior BPO vendor had put up with human agents alone. The company added 17 new trophy logo clients across the year, and its top five clients now make up 33% of revenue, down from 36%, a sign the business is not leaning on a shrinking handful of accounts to carry it.
Not every line moved in the right direction. Fourth quarter GAAP net income slipped to $8.7 million from $9.6 million a year earlier, and diluted EPS fell to $0.59 from $0.66. Management pointed to training costs tied to all those new client wins, a temporary hit from shifting work out of nearshore centers into offshore ones, and higher fuel prices hitting utility and transportation costs, particularly offshore. Adjusted EBITDA margin for the quarter slipped to 12.3% from 13.9%, the same set of pressures showing up in the profitability line rather than just net income.
#revenue #fourth


1 day ago
On September 10, Designer Brands (NYSE:DBI) reported second-quarter results that pushed full-year earnings guidance sharply higher, even as net sales slipped 1% year over year to $730.6 million. Adjusted operating income reached $39.4 million for the quarter, and management raised its adjusted diluted earnings per share outlook to a range of $0.47 to $0.52, up from $0.28 to $0.38. That kind of upward revision usually calms skeptics. Here, more than a third of the float is still sold short.
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands


1 day ago
On September 10, 1-800-Flowers.com Inc. (NASDAQ:FLWS) reported fiscal 2026 results that read like a company still finding its footing after a hard year. Full year revenue fell 10.8% to $1.5 billion, and the fourth quarter alone dropped 12.9% to $293.1 million, as consumers stayed selective with discretionary spending on gifts and gourmet food. Buried under those declines, though, is a different story: inventory shrank, free cash flow improved by $55 million, and the company hit a two-year cost savings target a full year early. The question now is whether that discipline can outrun the sales slide.
1-800-Flowers spent fiscal 2026 tearing down the walls between its brands. Instead of separate teams running each brand in silos, the company shifted to functional teams built around marketing, merchandising, and the digital shopping experience, with one team now acting as store manager for every website. That shift already shows up in products: the floral business combined its florist-fulfilled and direct-ship merchandising teams, so the same popular arrangements are available either way, instead of competing against itself on one landing page. Harry & David rolled out a redesigned, mobile-first website with AI-powered search that is currently in A/B testing, and several low-traffic standalone sites were folded into harryanddavid.com to concentrate traffic rather than split it.
The financial discipline behind that reorganization is real. The company reached its $50 million cost savings run rate a full year ahead of schedule and has already lined up another $15 million to $20 million in savings for fiscal 2027, with the full benefit landing in fiscal 2028. That, combined with tighter working capital management, pushed free cash flow up $55 million year over year and cut inventory to $153 million from $177 million. Average order value rose 5.5%, third-party marketplace sales through Amazon, Walmart, and DoorDash are growing at double-to-triple-digit rates and are already contribution margin positive, and BloomNet grew 1.9% on the back of local delivery partnerships with apps like DoorDash and Instacart.
The rest of the story is bleaker. Total transactions fell 17.6% for the year, and the fourth quarter's decline was broad-based: consumer floral and gifts dropped 13.4% to $182.8 million as the company pulled back on promotional discounting, and gourmet foods and gift baskets fell 15.4% to $85.8 million, a decline made worse by the timing of Easter. Adjusted EBITDA for the year collapsed to $2.9 million from $29.2 million, and adjusted gross margin slipped 110 basis points to 38%. Even the fourth quarter's 34.7% gross margin leaned on a one-time $7 million tariff refund.
#fiscal
1-800-Flowers spent fiscal 2026 tearing down the walls between its brands. Instead of separate teams running each brand in silos, the company shifted to functional teams built around marketing, merchandising, and the digital shopping experience, with one team now acting as store manager for every website. That shift already shows up in products: the floral business combined its florist-fulfilled and direct-ship merchandising teams, so the same popular arrangements are available either way, instead of competing against itself on one landing page. Harry & David rolled out a redesigned, mobile-first website with AI-powered search that is currently in A/B testing, and several low-traffic standalone sites were folded into harryanddavid.com to concentrate traffic rather than split it.
The financial discipline behind that reorganization is real. The company reached its $50 million cost savings run rate a full year ahead of schedule and has already lined up another $15 million to $20 million in savings for fiscal 2027, with the full benefit landing in fiscal 2028. That, combined with tighter working capital management, pushed free cash flow up $55 million year over year and cut inventory to $153 million from $177 million. Average order value rose 5.5%, third-party marketplace sales through Amazon, Walmart, and DoorDash are growing at double-to-triple-digit rates and are already contribution margin positive, and BloomNet grew 1.9% on the back of local delivery partnerships with apps like DoorDash and Instacart.
The rest of the story is bleaker. Total transactions fell 17.6% for the year, and the fourth quarter's decline was broad-based: consumer floral and gifts dropped 13.4% to $182.8 million as the company pulled back on promotional discounting, and gourmet foods and gift baskets fell 15.4% to $85.8 million, a decline made worse by the timing of Easter. Adjusted EBITDA for the year collapsed to $2.9 million from $29.2 million, and adjusted gross margin slipped 110 basis points to 38%. Even the fourth quarter's 34.7% gross margin leaned on a one-time $7 million tariff refund.
#fiscal


1 day ago
Cowboys news: Dallas praying Malik Hooker's injury isn't as bad as it could be after Week 1 debacle appeared first on ClutchPoints. Add ClutchPoints as a Preferred Source by clicking here.
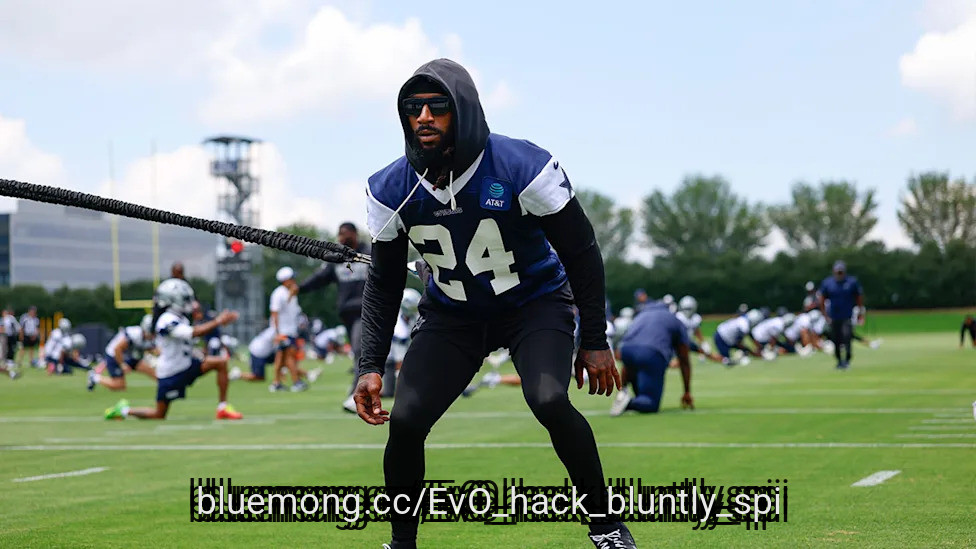
On Sunday evening, the Dallas Cowboys kicked off their season with an ugly 28-20 road loss to the New York Giants. The Cowboys' new-look defense, which had received considerable hype from fans and pundits alike heading into this year, fell flat on its face in this one, finding itself unable to get off the field in the second half against New York.
Things went from bad to worse when Malik Hooker went down with an injury, and on Monday, the team got the latest update on his potential recovery process.
"#Cowboys S Malik Hooker fractured a bone in his forearm and he's consulting with a hand specialist to learn his recovery time, sources say. While some breaks can mean a player is out six weeks, the hope is based on the specific bone and break, it's quicker than that," reported NFL insider Ian Rapoport of the NFL Network on X, formerly Twitter.
Watch sports LIVE with fuboTV (free trial)
#cowboys #recovery
On Sunday evening, the Dallas Cowboys kicked off their season with an ugly 28-20 road loss to the New York Giants. The Cowboys' new-look defense, which had received considerable hype from fans and pundits alike heading into this year, fell flat on its face in this one, finding itself unable to get off the field in the second half against New York.
Things went from bad to worse when Malik Hooker went down with an injury, and on Monday, the team got the latest update on his potential recovery process.
"#Cowboys S Malik Hooker fractured a bone in his forearm and he's consulting with a hand specialist to learn his recovery time, sources say. While some breaks can mean a player is out six weeks, the hope is based on the specific bone and break, it's quicker than that," reported NFL insider Ian Rapoport of the NFL Network on X, formerly Twitter.
Watch sports LIVE with fuboTV (free trial)
#cowboys #recovery


1 day ago
Azure crossed $100B annually with 43% growth, and Microsoft's commercial backlog surged 84% to $678B, explaining why markets shrugged off AI safety calls.
Progressive fell 5% and Sherwin-Williams dropped 12% over the past year as housing starts slid 12% and consumer sentiment hit a recessionary 55.
Trump's 'whoever wins, AI wins' framing directly counters Manchin's push for an executive order freezing AI IPOs until federal safeguards are established.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Microsoft didn't make the cut. Enter your email to see the names that beat MSFT. The report is free. Enter your email and see if any of your stocks made the cut.
Monday morning, hours after public radio spent its morning walking through an open letter asking the AI industry to slow itself down, President Trump told CNBC the opposite: "We're leading China in AI. We're the most sophisticated country in the world. And frankly, I want to keep it that way because whoever wins, AI wins." Ninety minutes later, shares of Microsoft (NASDAQ:MSFT) were changing hands at $498.70, and Polymarket bettors were pricing 84.5% odds that the stock would close green.
#msft #whoever #stocks #morning
Progressive fell 5% and Sherwin-Williams dropped 12% over the past year as housing starts slid 12% and consumer sentiment hit a recessionary 55.
Trump's 'whoever wins, AI wins' framing directly counters Manchin's push for an executive order freezing AI IPOs until federal safeguards are established.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Microsoft didn't make the cut. Enter your email to see the names that beat MSFT. The report is free. Enter your email and see if any of your stocks made the cut.
Monday morning, hours after public radio spent its morning walking through an open letter asking the AI industry to slow itself down, President Trump told CNBC the opposite: "We're leading China in AI. We're the most sophisticated country in the world. And frankly, I want to keep it that way because whoever wins, AI wins." Ninety minutes later, shares of Microsoft (NASDAQ:MSFT) were changing hands at $498.70, and Polymarket bettors were pricing 84.5% odds that the stock would close green.
#msft #whoever #stocks #morning


1 day ago
Energy Transfer LP (NYSE:ET) is set to move the primary listing of its common and Series I preferred units from the New York Stock Exchange to the Texas Stock Exchange in early October, making it the first major company to make such a switch from the NYSE to the newly established Dallas exchange. Reuters said the companies moving to TXSE, including Energy Transfer and related energy businesses, represent nearly $100 billion in combined market value, giving the fledgling exchange an important early credibility boost.
For Energy Transfer LP (NYSE:ET), however, the more important question is whether the move can eventually translate into better investor visibility or valuation rather than simply giving the company a stronger Texas identity. WSJ reported that Energy Transfer is worth roughly $75 billion and that Executive Chairman Kelcy Warren is a major backer of TXSE, owning about 30% of its parent company. That relationship makes the listing particularly significant, but it also means investors may scrutinize whether the decision creates a tangible benefit for Energy Transfer unitholders rather than primarily helping establish the new exchange.
The strongest bull argument is that Energy Transfer LP (NYSE:ET) is positioning itself ahead of a potentially important shift in the U.S. energy infrastructure market. TXSE is backed by major financial institutions including BlackRock, Citadel Securities, and Charles Schwab, and winning a roughly $75 billion company gives the exchange substantially more credibility with institutional investors. If TXSE attracts additional large energy companies, Energy Transfer could benefit from becoming one of the exchange's anchor names and gaining greater visibility among investors already focused on Texas-based energy infrastructure.
More importantly, the listing decision fits the underlying environment in which Energy Transfer LP (NYSE:ET) operates. Reuters has highlighted continued investment in U.S. gas-fired generation, LNG infrastructure, and pipeline networks as electricity demand rises and countries seek reliable energy supplies. The U.S. is also building substantial additional LNG export capacity. That matters because Energy Transfer's extensive midstream network can benefit from higher volumes of natural gas, crude oil, and NGLs without taking the same direct commodity-price exposure as upstream producers. If rising power demand from data centers and continued LNG development drive greater demand for U.S. gas transportation, Energy Transfer could see expanding opportunities to place additional infrastructure into service and lock in long-duration cash flows.
#transfer #company #infrastructure #listing
For Energy Transfer LP (NYSE:ET), however, the more important question is whether the move can eventually translate into better investor visibility or valuation rather than simply giving the company a stronger Texas identity. WSJ reported that Energy Transfer is worth roughly $75 billion and that Executive Chairman Kelcy Warren is a major backer of TXSE, owning about 30% of its parent company. That relationship makes the listing particularly significant, but it also means investors may scrutinize whether the decision creates a tangible benefit for Energy Transfer unitholders rather than primarily helping establish the new exchange.
The strongest bull argument is that Energy Transfer LP (NYSE:ET) is positioning itself ahead of a potentially important shift in the U.S. energy infrastructure market. TXSE is backed by major financial institutions including BlackRock, Citadel Securities, and Charles Schwab, and winning a roughly $75 billion company gives the exchange substantially more credibility with institutional investors. If TXSE attracts additional large energy companies, Energy Transfer could benefit from becoming one of the exchange's anchor names and gaining greater visibility among investors already focused on Texas-based energy infrastructure.
More importantly, the listing decision fits the underlying environment in which Energy Transfer LP (NYSE:ET) operates. Reuters has highlighted continued investment in U.S. gas-fired generation, LNG infrastructure, and pipeline networks as electricity demand rises and countries seek reliable energy supplies. The U.S. is also building substantial additional LNG export capacity. That matters because Energy Transfer's extensive midstream network can benefit from higher volumes of natural gas, crude oil, and NGLs without taking the same direct commodity-price exposure as upstream producers. If rising power demand from data centers and continued LNG development drive greater demand for U.S. gas transportation, Energy Transfer could see expanding opportunities to place additional infrastructure into service and lock in long-duration cash flows.
#transfer #company #infrastructure #listing
1 day ago
Vale S.A. (NYSE:VALE) is considering making its debut in China's domestic bond market as soon as this year, with CFO Marcelo Bacci saying the company is preparing for a potential Panda bond issuance. The move would be strategically significant because China accounts for roughly half of Vale's revenue, making renminbi financing a natural extension of its relationship with its largest market. Bloomberg reported that Vale is still ****** sing the market, including whether it can obtain a maturity longer than the typical two-, three-, or five-year terms available to international issuers.
The timing is also favorable for Vale because China's Panda bond market is expanding rapidly. Reuters reported that foreign issuers have increasingly turned to Asian bond markets to diversify funding sources, while Chinese yuan bond issuance has reached record levels in 2026. For Vale S.A. (NYSE:VALE), the potential transaction therefore looks less like a necessity for raising capital and more like an effort to diversify its investor base, potentially lower funding costs, and build a longer-term financing relationship with Chinese investors.
The strongest bullish argument is that Vale S.A. (NYSE:VALE) could potentially lower and diversify its cost of capital by accessing a large pool of Chinese investors at a time when renminbi funding remains relatively inexpensive. Reuters noted that Chinese onshore and offshore yuan bond markets have experienced record issuance this year, with foreign borrowers increasingly using these markets to diversify away from traditional funding currencies. If Vale can achieve competitive pricing, a Panda bond could provide an additional funding channel alongside its established dollar financing, reducing its dependence on a single market.
The move could also create a better natural match between Vale's revenues and its financing currency. Because China represents approximately half of Vale's revenue, raising at least some debt in renminbi could provide a degree of currency alignment with its Chinese business exposure. More importantly, establishing itself as a repeat issuer could strengthen Vale's relationships with Chinese banks and institutional investors, potentially giving it access to another source of capital when global dollar markets become less attractive.
There is also a broader strategic benefit. China is actively expanding the Panda bond market and encouraging international companies to use it. Official Chinese data showed that more than 160 billion yuan of Panda bonds were issued during the first half of 2026, up 69% year over year, demonstrating that the market is becoming more established and liquid. Vale entering this market could therefore position the company early in a growing financing ecosystem rather than waiting until it becomes more crowded.
#chinese #bond #panda #China
The timing is also favorable for Vale because China's Panda bond market is expanding rapidly. Reuters reported that foreign issuers have increasingly turned to Asian bond markets to diversify funding sources, while Chinese yuan bond issuance has reached record levels in 2026. For Vale S.A. (NYSE:VALE), the potential transaction therefore looks less like a necessity for raising capital and more like an effort to diversify its investor base, potentially lower funding costs, and build a longer-term financing relationship with Chinese investors.
The strongest bullish argument is that Vale S.A. (NYSE:VALE) could potentially lower and diversify its cost of capital by accessing a large pool of Chinese investors at a time when renminbi funding remains relatively inexpensive. Reuters noted that Chinese onshore and offshore yuan bond markets have experienced record issuance this year, with foreign borrowers increasingly using these markets to diversify away from traditional funding currencies. If Vale can achieve competitive pricing, a Panda bond could provide an additional funding channel alongside its established dollar financing, reducing its dependence on a single market.
The move could also create a better natural match between Vale's revenues and its financing currency. Because China represents approximately half of Vale's revenue, raising at least some debt in renminbi could provide a degree of currency alignment with its Chinese business exposure. More importantly, establishing itself as a repeat issuer could strengthen Vale's relationships with Chinese banks and institutional investors, potentially giving it access to another source of capital when global dollar markets become less attractive.
There is also a broader strategic benefit. China is actively expanding the Panda bond market and encouraging international companies to use it. Official Chinese data showed that more than 160 billion yuan of Panda bonds were issued during the first half of 2026, up 69% year over year, demonstrating that the market is becoming more established and liquid. Vale entering this market could therefore position the company early in a growing financing ecosystem rather than waiting until it becomes more crowded.
#chinese #bond #panda #China

1 day ago
Eli Willits has made his primary goal crystal clear ever since he joined the Nationals organization. He wants to be a big leaguer by the time he is 20 years old. For most players, that is a pipe dream. However, Eli Willits is not most players and he made that very obvious this season.
The 18 year old just finished his first professional season in style. Willits got promoted to Double-A for the last week of the season. While he only got to play three games, the last one was legendary. Willits had a four hit game which included his first AA home run and two stolen bases. It was an amazing final act to a wonderful season.
With Willits finishing the season in AA, he is putting himself in position to make a debut late in 2027. Despite being such a young player, Willits is remarkably polished. This comes from being the son of a big leaguer and being obsessed with the game ever since he could walk.
When I talked to Willits earlier this season, it was very clear that three things truly mattered to him. Eli Willits is all about family, faith and baseball. You will be hard pressed to find a more business-like 18 year old out there. As Willits put it, he grew up in an MLB clubhouse and it is easy to see that.
That baseball IQ manifests itself on the field. When I watched Willits for the first time in Low-A, the thing that stuck out to me most was how natural he looked. Willits looked like a big league caliber defender at shortstop already. While many young shortstops, even the defensively gifted ones make a lot of errors, Willits is already so secure. He only made 8 errors all season as an 18 year old.
#season #year
The 18 year old just finished his first professional season in style. Willits got promoted to Double-A for the last week of the season. While he only got to play three games, the last one was legendary. Willits had a four hit game which included his first AA home run and two stolen bases. It was an amazing final act to a wonderful season.
With Willits finishing the season in AA, he is putting himself in position to make a debut late in 2027. Despite being such a young player, Willits is remarkably polished. This comes from being the son of a big leaguer and being obsessed with the game ever since he could walk.
When I talked to Willits earlier this season, it was very clear that three things truly mattered to him. Eli Willits is all about family, faith and baseball. You will be hard pressed to find a more business-like 18 year old out there. As Willits put it, he grew up in an MLB clubhouse and it is easy to see that.
That baseball IQ manifests itself on the field. When I watched Willits for the first time in Low-A, the thing that stuck out to me most was how natural he looked. Willits looked like a big league caliber defender at shortstop already. While many young shortstops, even the defensively gifted ones make a lot of errors, Willits is already so secure. He only made 8 errors all season as an 18 year old.
#season #year


1 day ago
Howmet Aerospace Inc. (NYSE:HWM) is facing a mixed outlook after GE Aerospace agreed to acquire Consolidated Precision Products (CPP) for about $11.75 billion to secure more control over critical engine castings and expand production capacity. The announcement initially hit Howmet shares, which fell about 10%, as investors worried that GE could eventually rely less on outside suppliers such as Howmet.
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial



1 day ago
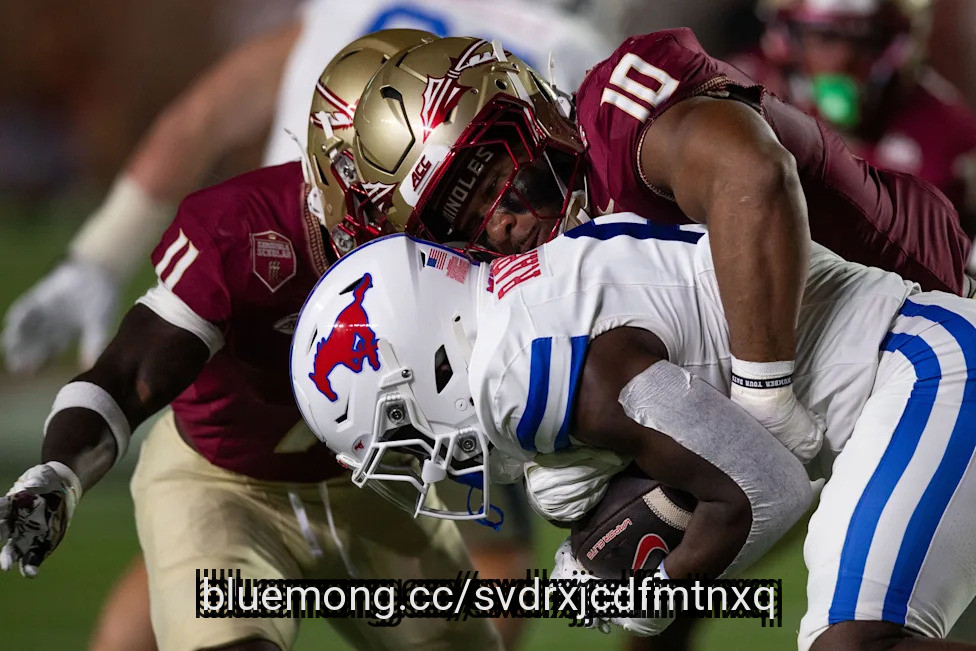
Florida State Athletics has moved on from Athletic Director Michael Alford after four years leading the program, and the news has taken the Seminoles fanbase by surprise.
While Alford's dismissal itself isn't a surprise given the recent underperformance of the Seminoles football program under head coach Mike Norvell, the timing of the firing was a shock. His firing was announced Monday morning, and it comes the week of FSU's trip to face No. 10 Alabama, a game of significance for the future of Norvell.
Alford's tenure included significant accomplishments across FSU athletics and several marquee coaching hires. Yet the struggles of the football program under Norvell since 2024, an 8-18 record, have overshadowed much of that success, emerging as the most prominent challenge of his time as athletics director.
He also faced scrutiny regarding the department's handling of Name, Image, and Likeness (NIL) and roster funding, particularly in football, and the department's massive debt.
(Current Record 1-1, 0-1 ACC)
#record #surprise
While Alford's dismissal itself isn't a surprise given the recent underperformance of the Seminoles football program under head coach Mike Norvell, the timing of the firing was a shock. His firing was announced Monday morning, and it comes the week of FSU's trip to face No. 10 Alabama, a game of significance for the future of Norvell.
Alford's tenure included significant accomplishments across FSU athletics and several marquee coaching hires. Yet the struggles of the football program under Norvell since 2024, an 8-18 record, have overshadowed much of that success, emerging as the most prominent challenge of his time as athletics director.
He also faced scrutiny regarding the department's handling of Name, Image, and Likeness (NIL) and roster funding, particularly in football, and the department's massive debt.
(Current Record 1-1, 0-1 ACC)
#record #surprise


1 day ago
NEW YORK — Forget the Honey Deuces and the celebrities-in-the-audience shots. The finest element of the U.S. Open — the Grand Slam held in the largest tennis stadium in the world — will always be the tennis itself. The trick, in 2026 and beyond, is how to get audiences to actually care about, you know, that tennis.
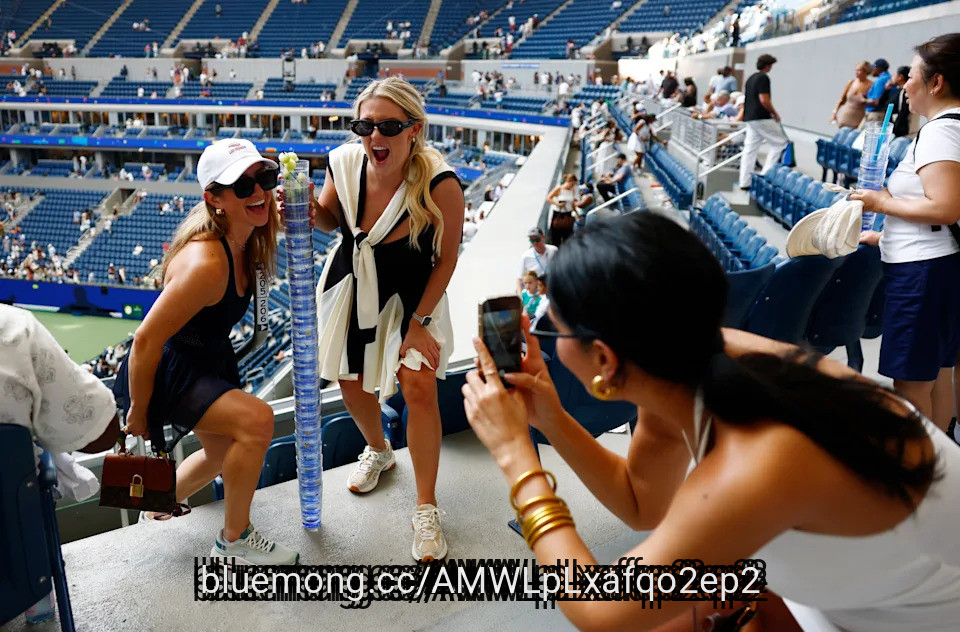
Ben Shelton and Alexander Zverev did their very best on Sunday, bringing both narrative and firepower to the four-set men's final. Yes, the influencers were posing at every aisle on every changeover, and more than a few fans appeared unclear on the basic concept of "sit your ******* down while the point is going on." But when Shelton and Zverev locked in, unleashing serves that nearly hit 150 mph or lashing shots that skipped a fingernail's width in bounds, the crowd was right there with them, rising and falling, a living thing that pulsed with energy unlike any other stadium in tennis.
Less than 24 hours earlier on the same court, Elena Rybakina finished off Aryna Sabalenka in a three-set triumph of resolve and willpower over emotion and firepower. Sabalenka, who had won the previous two Opens, entered as the crowd favorite. But the fans in the stands at Arthur Ashe love hard-fought on-court battles as much as they love the endless scroll of celebrity cameos on the video boards. So after a couple dozen Hollywood and music stars took their turns to varying volumes of applause, the crowd focused in on the match. Sabalenka drew motivational cheers, and then, once the result was clear, Rybakina inspired celebratory ones.
The two matches ended this year's U.S. Open on a triumphant note. At last, the tennis tournament centered on actual tennis, not ticket prices or runway-style entrances to Arthur Ashe Stadium or hundred-dollar chicken nuggets. (Yes, I admit it, I was part of the problem with that last one.)
The influencers' presence dominated the early coverage of the U.S. Open, in large part because they did their job of drawing attention to themselves. But by the time the tournament reached its final crescendo, the influencers had moved on. Two hours before the men's final, the cheapest tickets to get in the stadium could be had for less than $400, suggesting that tennis for tennis' sake isn't the primary motivator for many attending the U.S. Open.
#crowd #shelton
Ben Shelton and Alexander Zverev did their very best on Sunday, bringing both narrative and firepower to the four-set men's final. Yes, the influencers were posing at every aisle on every changeover, and more than a few fans appeared unclear on the basic concept of "sit your ******* down while the point is going on." But when Shelton and Zverev locked in, unleashing serves that nearly hit 150 mph or lashing shots that skipped a fingernail's width in bounds, the crowd was right there with them, rising and falling, a living thing that pulsed with energy unlike any other stadium in tennis.
Less than 24 hours earlier on the same court, Elena Rybakina finished off Aryna Sabalenka in a three-set triumph of resolve and willpower over emotion and firepower. Sabalenka, who had won the previous two Opens, entered as the crowd favorite. But the fans in the stands at Arthur Ashe love hard-fought on-court battles as much as they love the endless scroll of celebrity cameos on the video boards. So after a couple dozen Hollywood and music stars took their turns to varying volumes of applause, the crowd focused in on the match. Sabalenka drew motivational cheers, and then, once the result was clear, Rybakina inspired celebratory ones.
The two matches ended this year's U.S. Open on a triumphant note. At last, the tennis tournament centered on actual tennis, not ticket prices or runway-style entrances to Arthur Ashe Stadium or hundred-dollar chicken nuggets. (Yes, I admit it, I was part of the problem with that last one.)
The influencers' presence dominated the early coverage of the U.S. Open, in large part because they did their job of drawing attention to themselves. But by the time the tournament reached its final crescendo, the influencers had moved on. Two hours before the men's final, the cheapest tickets to get in the stadium could be had for less than $400, suggesting that tennis for tennis' sake isn't the primary motivator for many attending the U.S. Open.
#crowd #shelton

1 day ago
This offseason, the Heat witnessed a complete change in its roster. From superstar acquisitions through trade exchanges to top players leaving impressive salaries to join the roster, they saw a major upheaval. However, two players who were unaffected by these events were Andrew Wiggins and Simone Fontecchio.
Both players not only get to continue on the team but were also offered retention; a lifeline offered to only a handful this time. Now, with the next season approaching, the players have to meet high expectations to justify their contracts.
Earlier in the summer, Wiggins exercised the $30.1 million player option for the final year of his contract with Miami. But on June 29, the Heat decided to hand him a two-year, $34 million extension, bringing his term to a three-year, $64 million contract with them overall. He will be getting $16.5 million in 2027-28 and will have the player-option season worth $17.5 million in 2028-29. This is a huge financial security for any player, especially in a team that is aggressively looking to reinvent itself at the cost of its roster.
Wiggins was a dependable starter and brought stability last season,which he needs to continue this year. Wiggins averaged 15.4 points, 4.8 rebounds, and 2.7 ****** ists per game across 68 appearances. Maintaining his distance from defense, the 31-year-old needs to focus on being a high-efficiency 3-and-D wing, a role that saw him shine last year. He knocked down two threes a game at a career-best 41.4% clip in 2025-26.
At his rate, he could surely increase his average and show improvement. For the upcoming season, Wiggins should get perimeter shooting help from Klay Thompson, who he was teammates with in Golden State.
#wiggins #players #heat #continue
Both players not only get to continue on the team but were also offered retention; a lifeline offered to only a handful this time. Now, with the next season approaching, the players have to meet high expectations to justify their contracts.
Earlier in the summer, Wiggins exercised the $30.1 million player option for the final year of his contract with Miami. But on June 29, the Heat decided to hand him a two-year, $34 million extension, bringing his term to a three-year, $64 million contract with them overall. He will be getting $16.5 million in 2027-28 and will have the player-option season worth $17.5 million in 2028-29. This is a huge financial security for any player, especially in a team that is aggressively looking to reinvent itself at the cost of its roster.
Wiggins was a dependable starter and brought stability last season,which he needs to continue this year. Wiggins averaged 15.4 points, 4.8 rebounds, and 2.7 ****** ists per game across 68 appearances. Maintaining his distance from defense, the 31-year-old needs to focus on being a high-efficiency 3-and-D wing, a role that saw him shine last year. He knocked down two threes a game at a career-best 41.4% clip in 2025-26.
At his rate, he could surely increase his average and show improvement. For the upcoming season, Wiggins should get perimeter shooting help from Klay Thompson, who he was teammates with in Golden State.
#wiggins #players #heat #continue



1 day ago
Intel's 7% drop and AMD's 6% slide outpace NVIDIA's 3% pullback, an order that is the reverse of AI exposure ranking, suggesting a positioning unwind rather than a demand shift.
SOXX falling 6% against QQQ's 2% drop confirms the sell-off is chip-specific, not a broad Nasdaq retreat.
Amodei explicitly ruled out halting AI training, and Anthropic itself committed to deploying AMD's MI450 GPUs in a disclosed partnership.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA made the cut. Enter your email to see the other nine names and why NVDA earned its spot. The report is free. Enter your email and see the full list.
Chip stocks are sliding in early Monday trading after an AI pacing appeal over the weekend rippled beyond memory suppliers and into logic and accelerator names. Intel (NASDAQ:INTC) stock is falling 7% to $95.96, AMD (NASDAQ:AMD) stock is down 6% to $486.80, and NVIDIA (NASDAQ:NVDA) stock is declining 3% to $212.50. Intel is falling hardest of the three, NVIDIA is falling the least, and AMD sits in the middle, an ordering that runs opposite to each name's exposure to AI accelerator demand.
#nvda
SOXX falling 6% against QQQ's 2% drop confirms the sell-off is chip-specific, not a broad Nasdaq retreat.
Amodei explicitly ruled out halting AI training, and Anthropic itself committed to deploying AMD's MI450 GPUs in a disclosed partnership.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA made the cut. Enter your email to see the other nine names and why NVDA earned its spot. The report is free. Enter your email and see the full list.
Chip stocks are sliding in early Monday trading after an AI pacing appeal over the weekend rippled beyond memory suppliers and into logic and accelerator names. Intel (NASDAQ:INTC) stock is falling 7% to $95.96, AMD (NASDAQ:AMD) stock is down 6% to $486.80, and NVIDIA (NASDAQ:NVDA) stock is declining 3% to $212.50. Intel is falling hardest of the three, NVIDIA is falling the least, and AMD sits in the middle, an ordering that runs opposite to each name's exposure to AI accelerator demand.
#nvda

1 day ago
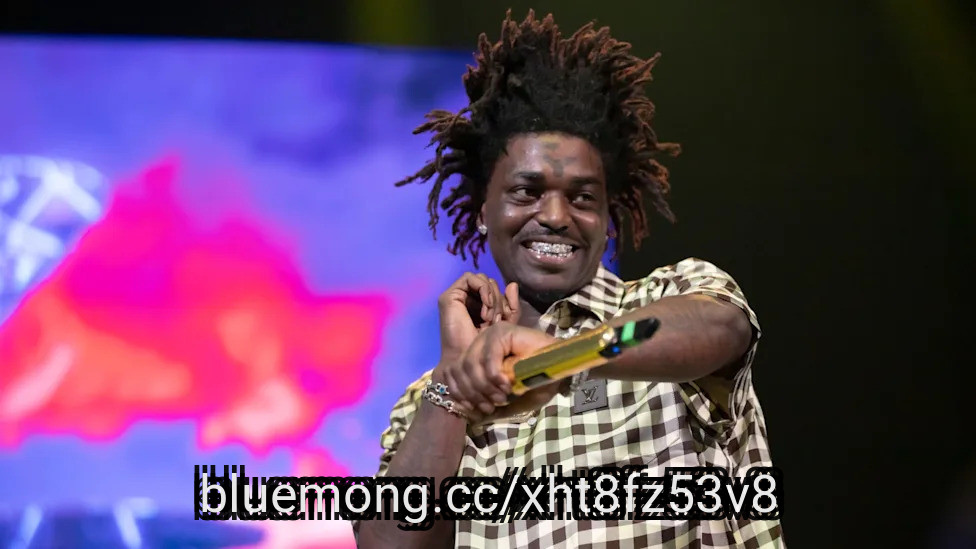
Kodak Black is seen trying to quickly finish up a meal before being turned over to authorities in footage making the rounds on social media this week, though it's worth pointing out that the footage itself does not depict a recent incident.
Instead, the body camera footage in question, which has been widely shared in recent days, stems from May 14 of this year. Annoyingly, much of the posts zeroing in on the food-focused moment from the Pompano Beach, Florida-set video have been shared without context, which may have led some to falsely believe that the Kodak The Blessing artist had been arrested in recent days. This is not true.
Posts have also circulated positing that Kodak "made" officials wait for him to finish his meal "before they arrested him," which is also misleading.
Kodak Black had one last thing to handle before going into custody — finishing his spaghetti. 😭🍝 pic.twitter.com/wbAoIQsSNp
— NineT6ix 🦅 (Salih9t6) September 7, 2026
#kodak #black #shared
Instead, the body camera footage in question, which has been widely shared in recent days, stems from May 14 of this year. Annoyingly, much of the posts zeroing in on the food-focused moment from the Pompano Beach, Florida-set video have been shared without context, which may have led some to falsely believe that the Kodak The Blessing artist had been arrested in recent days. This is not true.
Posts have also circulated positing that Kodak "made" officials wait for him to finish his meal "before they arrested him," which is also misleading.
Kodak Black had one last thing to handle before going into custody — finishing his spaghetti. 😭🍝 pic.twitter.com/wbAoIQsSNp
— NineT6ix 🦅 (Salih9t6) September 7, 2026
#kodak #black #shared


3 days ago
Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) could be positioning itself for its next major phase of growth following its roughly $10 billion acquisition of Crinetics Pharmaceuticals. The deal gives the company immediate exposure to the endocrinology market and provides a new commercial platform beyond its established cystic fibrosis franchise.
On September 3, Citigroup **** yst Geoff Meacham highlighted the strategic importance of the Crinetics acquisition, arguing it could diversify Vertex's business while complementing its existing cystic fibrosis franchise and newer businesses in renal disease, hematology, and pain.
Through the transaction, Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) gains access to Palsonify (paltusotine), an oral treatment for acromegaly that has already received regulatory approval in Europe. Paltusotine is also in Phase 3 development for carcinoid syndrome **** ociated with neuroendocrine tumors.
Palsonify is particularly important because it provides an immediate commercial revenue opportunity, rather than requiring the company to wait several years for an entirely new drug to reach the market.
Early uptake of Palsonify has been encouraging, supported by expanding physician adoption and improving reimbursement coverage. If that momentum continues, the drug could become an important contributor to Vertex's revenue growth.
#palsonify
On September 3, Citigroup **** yst Geoff Meacham highlighted the strategic importance of the Crinetics acquisition, arguing it could diversify Vertex's business while complementing its existing cystic fibrosis franchise and newer businesses in renal disease, hematology, and pain.
Through the transaction, Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) gains access to Palsonify (paltusotine), an oral treatment for acromegaly that has already received regulatory approval in Europe. Paltusotine is also in Phase 3 development for carcinoid syndrome **** ociated with neuroendocrine tumors.
Palsonify is particularly important because it provides an immediate commercial revenue opportunity, rather than requiring the company to wait several years for an entirely new drug to reach the market.
Early uptake of Palsonify has been encouraging, supported by expanding physician adoption and improving reimbursement coverage. If that momentum continues, the drug could become an important contributor to Vertex's revenue growth.
#palsonify


3 days ago
Tennessee football's pass defense distinguished itself with crucial first-half interceptions, and its running game too often was too much for Georgia Tech on Sept. 12 at Bobby Dodd Stadium in Atlanta.
That combination proved decisive as the No. 18 Vols improved to 2-0 with a 45-24 victory over upset-minded Georgia Tech (0-2). But that one-two punch wasn't enough to produce a runaway comparable to the Vols' 56-9 victory over Furman in the season opener.
If you were familiar with Georgia Tech's history under fourth-year coach Brent Key, you might have thought the Vols were catching the Yellow Jackets at the wrong time. His teams have been at their best as underdogs and have upended at least one nationally ranked opponent in each of the past four seasons.
Georgia Tech showed its resolve just when the Vols seemed blowout bound after taking a 31-10 lead early in the third quarter.
The Yellow Jackets sprung to life behind the passing of quarterback Alberto Mendoza, who led them 75 yards for a touchdown and had them on the brink of another score when UT defensive back Dejuan Lane broke up a fourth-down pass in the end zone.
#georgia
That combination proved decisive as the No. 18 Vols improved to 2-0 with a 45-24 victory over upset-minded Georgia Tech (0-2). But that one-two punch wasn't enough to produce a runaway comparable to the Vols' 56-9 victory over Furman in the season opener.
If you were familiar with Georgia Tech's history under fourth-year coach Brent Key, you might have thought the Vols were catching the Yellow Jackets at the wrong time. His teams have been at their best as underdogs and have upended at least one nationally ranked opponent in each of the past four seasons.
Georgia Tech showed its resolve just when the Vols seemed blowout bound after taking a 31-10 lead early in the third quarter.
The Yellow Jackets sprung to life behind the passing of quarterback Alberto Mendoza, who led them 75 yards for a touchdown and had them on the brink of another score when UT defensive back Dejuan Lane broke up a fourth-down pass in the end zone.
#georgia



3 days ago
The Washington Huskies have a problem on offense.
Jedd Fisch's unit has now scored 40 points in their first two games combined, ten fewer points than the Huskies were favored to win those two games by (23.5 against Washington State, 26.5 against Utah State). Washington has finished with more than 350 yards of offense in both of those games, but has found itself completely unable to move the ball consistently or score points efficiently through the first two games.
Quarterback Demond Williams Jr. has struggled to throw the ball in rhythm, often opting to scramble and utilize his talent as a runner to keep the offense on track. Washington has needed that from him, too: Williams has been the Huskies' leading rusher in both games as the running back depth has been decimated by injuries to Jordan Washington, Quaid Carr, and Jayden Limar.
But there has also been opportunity for Williams to throw the ball more effectively. He's missed several what should have been easy throws in the flat and placed longer throws into the end zone out of reach of his receivers more often than he's found those plays. It hasn't been all on Williams, however: starting X receiver Christian Moss left after two snaps in the Apple Cup, and starting Z receiver Rashid Williams left early on Saturday against Utah State, thrusting true freshmen Jordan Clay and Trez Davis into action. Dezmen Roebuck and running back Trey Cooley both also dropped passes that could have easily been touchdowns on Saturday, further putting the offense behind schedule and making for a messy operation.
"As an offense, we shot ourselves in the foot a lot," Williams told the media after the game.
#utah
Jedd Fisch's unit has now scored 40 points in their first two games combined, ten fewer points than the Huskies were favored to win those two games by (23.5 against Washington State, 26.5 against Utah State). Washington has finished with more than 350 yards of offense in both of those games, but has found itself completely unable to move the ball consistently or score points efficiently through the first two games.
Quarterback Demond Williams Jr. has struggled to throw the ball in rhythm, often opting to scramble and utilize his talent as a runner to keep the offense on track. Washington has needed that from him, too: Williams has been the Huskies' leading rusher in both games as the running back depth has been decimated by injuries to Jordan Washington, Quaid Carr, and Jayden Limar.
But there has also been opportunity for Williams to throw the ball more effectively. He's missed several what should have been easy throws in the flat and placed longer throws into the end zone out of reach of his receivers more often than he's found those plays. It hasn't been all on Williams, however: starting X receiver Christian Moss left after two snaps in the Apple Cup, and starting Z receiver Rashid Williams left early on Saturday against Utah State, thrusting true freshmen Jordan Clay and Trez Davis into action. Dezmen Roebuck and running back Trey Cooley both also dropped passes that could have easily been touchdowns on Saturday, further putting the offense behind schedule and making for a messy operation.
"As an offense, we shot ourselves in the foot a lot," Williams told the media after the game.
#utah
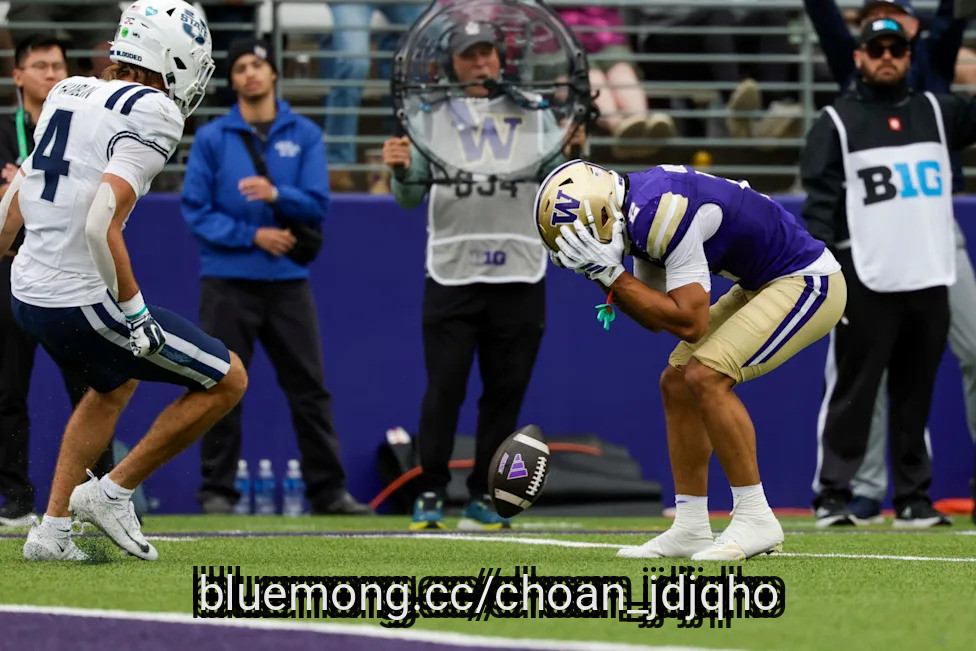

3 days ago
Oregon survived a scare against Boise State in Week 1, overcoming an upset to open the season with a win.
A week later at Oklahoma State, Oregon found itself in a similar position — only this time Dan Lanning's squad couldn't deliver the same ending: Oklahoma State defeated No. 6 Oregon 39-31 at Boone Pickens Stadium in Stillwater, Oklahoma on Saturday, Sept. 12.
REQUIRED READING: Oregon stunned by Oklahoma State by running and throwing of Drew Mestemaker
The Ducks fought all the way back and briefly took a 31-30 lead when Dante Moore connected with Evan Stewart for a 38-yard touchdown. But Oklahoma State answered right back, as quarterback Drew Mestemaker scored on a 10-yard rushing touchdown to permanently put the Cowboys back in front.
Oregon then made a bold decision with 6:48 remaining in the fourth quarter, going for it on fourth-and-8 from its own 33-yard line. The gamble did not pay off, as Moore's pass to Dierre Hill Jr. on the right side fell incomplete, resulting in a turnover on downs. The failed conversion gave Oklahoma State prime field position and put the Ducks' comeback hopes in serious jeopardy when the Cowboys tacked on a 31-yard field goal from Sam Keltner.
#ducks
A week later at Oklahoma State, Oregon found itself in a similar position — only this time Dan Lanning's squad couldn't deliver the same ending: Oklahoma State defeated No. 6 Oregon 39-31 at Boone Pickens Stadium in Stillwater, Oklahoma on Saturday, Sept. 12.
REQUIRED READING: Oregon stunned by Oklahoma State by running and throwing of Drew Mestemaker
The Ducks fought all the way back and briefly took a 31-30 lead when Dante Moore connected with Evan Stewart for a 38-yard touchdown. But Oklahoma State answered right back, as quarterback Drew Mestemaker scored on a 10-yard rushing touchdown to permanently put the Cowboys back in front.
Oregon then made a bold decision with 6:48 remaining in the fourth quarter, going for it on fourth-and-8 from its own 33-yard line. The gamble did not pay off, as Moore's pass to Dierre Hill Jr. on the right side fell incomplete, resulting in a turnover on downs. The failed conversion gave Oklahoma State prime field position and put the Ducks' comeback hopes in serious jeopardy when the Cowboys tacked on a 31-yard field goal from Sam Keltner.
#ducks


3 days ago
A serious team requires serious stats by which they'll be evaluated. Over the last calendar year, the Chicago Bears have become a serious team led by a serious head coach in Ben Johnson and a serious quarterback in Caleb Williams. Which means that the world of ****** ytics in football will be more relevant for them in 2026 than we have perhaps seen in years past.
While not as robust (or widely utilized) as their counterparts in the baseball world, advanced stats have progressively become more relevant for the NFL and its players in recent years. Pro Football Focus is sort of a driver of this increase, and it's here that we begin our journey into this world.
PFF, as it's known colloquially, ****** igns a grade for every action that a player completes on the field. These grades occur on a scale from +2 to -2, with zero representing the average in between the two ends of the spectrum. These grades don't just occur in a vacuum, either. Positional context and the game situation itself are each taken into account as part of where a given play lands on the scale.
#stats #grades
While not as robust (or widely utilized) as their counterparts in the baseball world, advanced stats have progressively become more relevant for the NFL and its players in recent years. Pro Football Focus is sort of a driver of this increase, and it's here that we begin our journey into this world.
PFF, as it's known colloquially, ****** igns a grade for every action that a player completes on the field. These grades occur on a scale from +2 to -2, with zero representing the average in between the two ends of the spectrum. These grades don't just occur in a vacuum, either. Positional context and the game situation itself are each taken into account as part of where a given play lands on the scale.
#stats #grades


3 days ago
Elon Musk, who owns X, is the platform's most-followed person, with 242 million followers.
Musk has more followers than Barack Obama and Cristiano Ronaldo, the next two largest accounts, combined.
Politicians and musicians dominate the ranking, alongside several of the world's biggest athletes.
There are many ways to grow a social media following. When looking to outperform world leaders, however, it helps to own the platform itself.
This visualization ranks the 15 most-followed people on X (formerly Twitter) as of September 2026. Accounts belonging to brands or companies, including X itself, have been excluded.
#accounts #followers #itself #obama
Musk has more followers than Barack Obama and Cristiano Ronaldo, the next two largest accounts, combined.
Politicians and musicians dominate the ranking, alongside several of the world's biggest athletes.
There are many ways to grow a social media following. When looking to outperform world leaders, however, it helps to own the platform itself.
This visualization ranks the 15 most-followed people on X (formerly Twitter) as of September 2026. Accounts belonging to brands or companies, including X itself, have been excluded.
#accounts #followers #itself #obama


3 days ago
India's next Test **** ignment will take them to New Zealand for a two-match series beginning November 19, and former Kiwi fast bowler Trent Boult believes KL Rahul will be one of the Indian batters worth watching closely.
The two Tests will form part of India's marathon New Zealand tour, which begins on October 22 and features 12 matches across the three formats. With India needing a strong result to remain in contention for the World Test Championship (WTC) final, the spotlight is expected to fall on several key players, including captain Shubman Gill and pace spearhead Jasprit **** rah.
Boult, however, has picked Rahul and his opening partner Yashasvi Jaiswal as the two Indian batters he is particularly looking forward to seeing in action.
"I'm always a big fan of KL Rahul and his style of batsmanship. So he's a big player at the top of the order for the Indian side. And yeah, I believe Jaiswal is there as well. Two classy batters to see bat. So yeah, be interesting to see," Boult said in an interview to PTI.
The timing of the series could make conditions particularly interesting. Unlike India's previous Test tours of New Zealand, which have often taken place in the February-March window, this series will be played in late October and November.
Boult feels the timing could bring colder weather into play, while he is hoping the New Zealand pitches retain some grass and offer **** istance to the home attack.
"It's always an exciting chance when the Indian team comes down to play Test cricket in New Zealand," Boult said.
"The only thing I can see happening is it's going to be late October. I believe, just coming out of winter. So it's going to be quite cold. Hopefully, there's a bit of greenness in the wickets for some of our bowlers. It's going to be a good series, I'm sure," the star former Kiwi pacer added.
Boult also backed the current New Zealand bowling unit to make an impact against India, pointing to the variety available to the team.
Kyle Jamieson, Matt Henry, Nathan Smith and Will O'Rourke bring different qualities to the attack, and Boult believes that gives New Zealand enough options to develop its own identity.
"I think the bowling is very well balanced. It's got bases covered in terms of a good pace, obviously, with Will O'Rourke. Obviously, a bit of swing and a bit of bounce from Kyle Jamieson and Matt Henry with his accuracy.
"So yeah, I think the way me, Tim (Southee) and Wags (Neil Wagner) did it over the years was a unique way in itself. But there's other strengths and other game plans that our younger bowlers can follow," Boult further said.
134121390
#test
The two Tests will form part of India's marathon New Zealand tour, which begins on October 22 and features 12 matches across the three formats. With India needing a strong result to remain in contention for the World Test Championship (WTC) final, the spotlight is expected to fall on several key players, including captain Shubman Gill and pace spearhead Jasprit **** rah.
Boult, however, has picked Rahul and his opening partner Yashasvi Jaiswal as the two Indian batters he is particularly looking forward to seeing in action.
"I'm always a big fan of KL Rahul and his style of batsmanship. So he's a big player at the top of the order for the Indian side. And yeah, I believe Jaiswal is there as well. Two classy batters to see bat. So yeah, be interesting to see," Boult said in an interview to PTI.
The timing of the series could make conditions particularly interesting. Unlike India's previous Test tours of New Zealand, which have often taken place in the February-March window, this series will be played in late October and November.
Boult feels the timing could bring colder weather into play, while he is hoping the New Zealand pitches retain some grass and offer **** istance to the home attack.
"It's always an exciting chance when the Indian team comes down to play Test cricket in New Zealand," Boult said.
"The only thing I can see happening is it's going to be late October. I believe, just coming out of winter. So it's going to be quite cold. Hopefully, there's a bit of greenness in the wickets for some of our bowlers. It's going to be a good series, I'm sure," the star former Kiwi pacer added.
Boult also backed the current New Zealand bowling unit to make an impact against India, pointing to the variety available to the team.
Kyle Jamieson, Matt Henry, Nathan Smith and Will O'Rourke bring different qualities to the attack, and Boult believes that gives New Zealand enough options to develop its own identity.
"I think the bowling is very well balanced. It's got bases covered in terms of a good pace, obviously, with Will O'Rourke. Obviously, a bit of swing and a bit of bounce from Kyle Jamieson and Matt Henry with his accuracy.
"So yeah, I think the way me, Tim (Southee) and Wags (Neil Wagner) did it over the years was a unique way in itself. But there's other strengths and other game plans that our younger bowlers can follow," Boult further said.
134121390
#test
3 days ago
Afghanistan are about to make history as they are for the first time, a team will technically host India on Indian soil, with all three matches scheduled at the Arun Jaitley Stadium.
Afghanistan have been playing their home international fixtures in India for several years, using venues in Lucknow, Dehradun and Greater Noida to host matches against various opponents. But they've never done it against India itself until now.
The series wraps up just ahead of the Asian Games, which kick off on September 24, giving the squad a final chance to settle combinations before heading to **** an.
India arrive with mixed white-ball form that doesn't quite match their status as reigning T20 World Cup champions. The problems began in late June with back-to-back T20I defeats to Ireland in Belfast.
England then handed India a 4-0 T20I series loss, and the ODIs followed with another setback, as India went down 2-1. The team was in Zimbabwe for another white-ball **** ignment, and they recovered some lost pride at Harare.
#India #series #white
Afghanistan have been playing their home international fixtures in India for several years, using venues in Lucknow, Dehradun and Greater Noida to host matches against various opponents. But they've never done it against India itself until now.
The series wraps up just ahead of the Asian Games, which kick off on September 24, giving the squad a final chance to settle combinations before heading to **** an.
India arrive with mixed white-ball form that doesn't quite match their status as reigning T20 World Cup champions. The problems began in late June with back-to-back T20I defeats to Ireland in Belfast.
England then handed India a 4-0 T20I series loss, and the ODIs followed with another setback, as India went down 2-1. The team was in Zimbabwe for another white-ball **** ignment, and they recovered some lost pride at Harare.
#India #series #white

4 days ago
CHESTNUT HILL, Mass. — There is no coming back from this for Rutgers — and maybe its head coach.
The Scarlet Knights still have 10 more games on their schedule this fall, but the 2026 season effectively came to an end after they suffered a devastating 28-21 loss to Boston College on Friday night.
Any flicker of hope remaining following a season-opening 37-21 loss to UMass — the worst loss in modern program history — were dashed at Alumni Stadium, where Rutgers showed more life than its pathetic showing against the Minutemen, but not enough to secure a win it desperately needed — and easily could have gotten.
The Scarlet Knights (0-2) were blitzed from the beginning by the Eagles (1-1), who jumped out to a 17-0 lead through the opening 17 minutes and led the rest of the way.
Rutgers was not ready to play — it was forced to call a timeout on the third play of the game when it sent two players on the field with the same jersey number (#56) — and while it came agonizingly close to stealing a game that was there for the taking, it could not stop shooting itself in the foot.
#rutgers #scarlet
The Scarlet Knights still have 10 more games on their schedule this fall, but the 2026 season effectively came to an end after they suffered a devastating 28-21 loss to Boston College on Friday night.
Any flicker of hope remaining following a season-opening 37-21 loss to UMass — the worst loss in modern program history — were dashed at Alumni Stadium, where Rutgers showed more life than its pathetic showing against the Minutemen, but not enough to secure a win it desperately needed — and easily could have gotten.
The Scarlet Knights (0-2) were blitzed from the beginning by the Eagles (1-1), who jumped out to a 17-0 lead through the opening 17 minutes and led the rest of the way.
Rutgers was not ready to play — it was forced to call a timeout on the third play of the game when it sent two players on the field with the same jersey number (#56) — and while it came agonizingly close to stealing a game that was there for the taking, it could not stop shooting itself in the foot.
#rutgers #scarlet
4 days ago
Washington hosts Utah State tomorrow but before we transition to Saturday's gameday coverage. Here is the Week 1 mailbag!
Chicken Little: Is it time to panic?
I wouldn't say the sky is falling, but there is certainly plenty of reason to be concerned. The Huskies' struggles on offense are excusable, but they make you seriously consider a complete shift in expectations now that their two best running backs will miss time. Washington is in desperate need of a hot start to stay as healthy as possible for the toughest games on the schedule, which come in the second half of the season. I get that rivalry games can be funky, but there is zero reason why the Apple Cup should've been as close as it was. Wazzu's offense was horrid, and Washington's was equally so until the fourth quarter. For a team wanting to compete with the Big Ten elite… that's bad. I'm not panicking just yet, but I am considering lowering my win total because I'm not sure if UW will be healthy enough to be the best version of itself.
iadawg: Ellinneus Davis was supposed to be the best defensive lineman but he only had the third most snaps of defensive linemen. Can you explain this? Thanks.
Definitely strange, but I wouldn't spend too much time thinking about it unless it happens against Utah State and Eastern Washington. There's a good chance he had a minor injury bugging him, or head coach Jedd Fisch and defensive coordinator Ryan Walters saw opportunities with other lineman and took advantage. In the end, it worked out for the Huskies. His lower-than-expected usage rate is not a trend that I think will continue through the remainder of September.
#washington #time #defensive #offense
Chicken Little: Is it time to panic?
I wouldn't say the sky is falling, but there is certainly plenty of reason to be concerned. The Huskies' struggles on offense are excusable, but they make you seriously consider a complete shift in expectations now that their two best running backs will miss time. Washington is in desperate need of a hot start to stay as healthy as possible for the toughest games on the schedule, which come in the second half of the season. I get that rivalry games can be funky, but there is zero reason why the Apple Cup should've been as close as it was. Wazzu's offense was horrid, and Washington's was equally so until the fourth quarter. For a team wanting to compete with the Big Ten elite… that's bad. I'm not panicking just yet, but I am considering lowering my win total because I'm not sure if UW will be healthy enough to be the best version of itself.
iadawg: Ellinneus Davis was supposed to be the best defensive lineman but he only had the third most snaps of defensive linemen. Can you explain this? Thanks.
Definitely strange, but I wouldn't spend too much time thinking about it unless it happens against Utah State and Eastern Washington. There's a good chance he had a minor injury bugging him, or head coach Jedd Fisch and defensive coordinator Ryan Walters saw opportunities with other lineman and took advantage. In the end, it worked out for the Huskies. His lower-than-expected usage rate is not a trend that I think will continue through the remainder of September.
#washington #time #defensive #offense