56 mins. ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
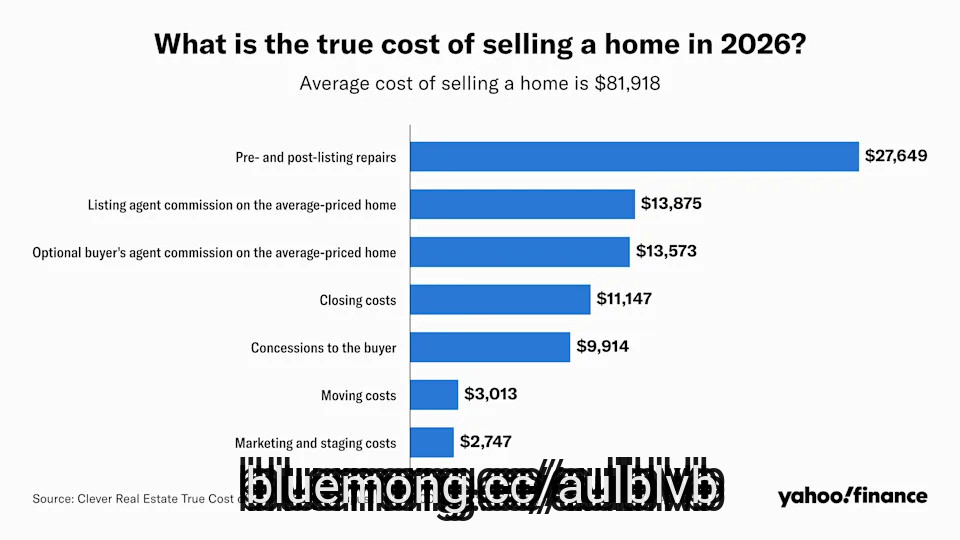
Homeowners are spending more to sell their home, and many underestimate what it will cost to prep, market, and close a deal. Factor in a growing number of buyer's markets, and sellers' profits are being squeezed too.
Owners who put their house on the market in the past three years shelled out an average of nearly $82,000 to sell their home, up 22% from 2025, according to new research by Clever Real Estate.
Here are the numbers sellers will want to consider before listing.
Read more: Is it a good time to sell your house?
#House #advertiser #homeowners #factor
Homeowners are spending more to sell their home, and many underestimate what it will cost to prep, market, and close a deal. Factor in a growing number of buyer's markets, and sellers' profits are being squeezed too.
Owners who put their house on the market in the past three years shelled out an average of nearly $82,000 to sell their home, up 22% from 2025, according to new research by Clever Real Estate.
Here are the numbers sellers will want to consider before listing.
Read more: Is it a good time to sell your house?
#House #advertiser #homeowners #factor

4 days ago
A Michigan retiree couple needs roughly $927,000 invested at a 4% withdrawal rate, versus $1.07 million in Florida.
Florida homeowners pay $8,471 yearly for insurance versus $2,415 in Michigan, a $6,000 gap that requires $151,000 in extra savings.
Michigan exempts Social Security and offers married couples a $128,080 retirement deduction, potentially zeroing state tax on a $37,000 IRA withdrawal.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Retiring to a lake town in Michigan or Wisconsin often raises questions about snow and winter conditions compared with a move to Florida. Winter is one factor in that comparison, but the rest of the picture gets mentioned less often: insurance, taxes, housing, and summers. This piece runs the numbers for a couple at full retirement age.
#often
Florida homeowners pay $8,471 yearly for insurance versus $2,415 in Michigan, a $6,000 gap that requires $151,000 in extra savings.
Michigan exempts Social Security and offers married couples a $128,080 retirement deduction, potentially zeroing state tax on a $37,000 IRA withdrawal.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Retiring to a lake town in Michigan or Wisconsin often raises questions about snow and winter conditions compared with a move to Florida. Winter is one factor in that comparison, but the rest of the picture gets mentioned less often: insurance, taxes, housing, and summers. This piece runs the numbers for a couple at full retirement age.
#often

4 days ago
About 42% of top-10% income families have seven-figure retirement accounts, compared with just 1% of middle-income families.
Married, college-educated homeowners make up about 20% of families but nearly 75% of retirement-account millionaires.
Nearly a third of retirement-account millionaires are families headed by someone ages 55 to 64.
Only about 7% of U.S. families have $1 million or more in retirement accounts. But that milestone is much more common among families that share several key traits.
Among the roughly 9.4 million families with $1 million or more in retirement accounts, about 97% own their homes, 84% are headed by someone with a bachelor's degree, and 61% are in the top 10% by income. That's according to an Investopedia ***** ysis of the Federal Reserve's Survey of Consumer Finances, released earlier this month. All figures are in 2025 dollars.
#million #nearly #millionaires
Married, college-educated homeowners make up about 20% of families but nearly 75% of retirement-account millionaires.
Nearly a third of retirement-account millionaires are families headed by someone ages 55 to 64.
Only about 7% of U.S. families have $1 million or more in retirement accounts. But that milestone is much more common among families that share several key traits.
Among the roughly 9.4 million families with $1 million or more in retirement accounts, about 97% own their homes, 84% are headed by someone with a bachelor's degree, and 61% are in the top 10% by income. That's according to an Investopedia ***** ysis of the Federal Reserve's Survey of Consumer Finances, released earlier this month. All figures are in 2025 dollars.
#million #nearly #millionaires



9 days ago
In a housing market where affordability is increasingly out of reach for many buyers, Vic Bulbon is looking at a type of property that's becoming less expensive: condominiums.
With national home prices near record highs and mortgage rates topping 7% in recent weeks, buying a home remains out of reach for many Americans. Condos appear to offer a rare bright spot, with prices falling across the country.
But even with cheaper sales prices, rising homeowners' **** ociation (HOA) fees and one-time special **** sments are driving up ownership costs.
Now, guidelines released this year by Fannie Mae and Freddie Mac, the government-sponsored agencies that back nearly half of all US home purchases, aim to reduce the financial and structural risks of condo buildings. Real estate agents told CNN that the changes could add pressure to the condo market by further driving up HOA fees, increasing the total monthly bill for condo owners, and potentially eroding the savings of a lower purchase price.
As of mid-October, condo sales prices lagged behind single-family home prices in 99 of the 100 largest markets in the United States, according to data from financial services company Intercontinental Exchange provided to CNN. Nationally, single-family home prices rose 1.5% from a year earlier, while condo prices fell 1.1%.
#prices #home #sales #year
With national home prices near record highs and mortgage rates topping 7% in recent weeks, buying a home remains out of reach for many Americans. Condos appear to offer a rare bright spot, with prices falling across the country.
But even with cheaper sales prices, rising homeowners' **** ociation (HOA) fees and one-time special **** sments are driving up ownership costs.
Now, guidelines released this year by Fannie Mae and Freddie Mac, the government-sponsored agencies that back nearly half of all US home purchases, aim to reduce the financial and structural risks of condo buildings. Real estate agents told CNN that the changes could add pressure to the condo market by further driving up HOA fees, increasing the total monthly bill for condo owners, and potentially eroding the savings of a lower purchase price.
As of mid-October, condo sales prices lagged behind single-family home prices in 99 of the 100 largest markets in the United States, according to data from financial services company Intercontinental Exchange provided to CNN. Nationally, single-family home prices rose 1.5% from a year earlier, while condo prices fell 1.1%.
#prices #home #sales #year

29 days ago
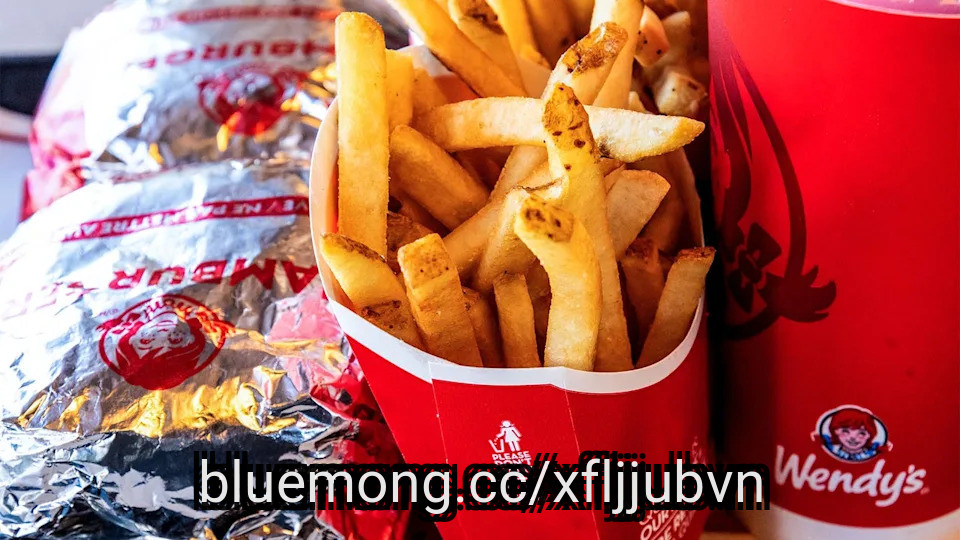
Fast food giant Wendy's faced a fresh wave of permanent store closures on Friday for the second weekend in a row as one of its biggest franchisees scrambled to restructure operations in the aftermath of a Chapter 11 bankruptcy filing.
Most Read from Fast Company
Emotionally intelligent people use 3 short phrases to stop getting defensive and strengthen their relationships
Wendy's is facing more store closures: See an updated list of shuttered locations from franchise bankruptcy
Panda Express's founders built a $7 billion empire. Now they're helping 55,000 employees become homeowners
#fast #closures #Friday
Most Read from Fast Company
Emotionally intelligent people use 3 short phrases to stop getting defensive and strengthen their relationships
Wendy's is facing more store closures: See an updated list of shuttered locations from franchise bankruptcy
Panda Express's founders built a $7 billion empire. Now they're helping 55,000 employees become homeowners
#fast #closures #Friday

29 days ago
U.S. homeowners paid about $633 more on average in property taxes in 2024 compared to 2019, according to the latest U.S. Census Bureau data. Here's what's driving the increase and which states are hit the hardest.
Property taxes are largely determined by a home's ***** sed value and the local tax rate.
The ***** sed value is a dollar amount ***** igned to your home by your local county ***** sor to help determine the property tax. It's not the same as the market value, but it incorporates it.
A higher home market value can mean a higher ***** sed value, which would directly increase its property taxes. And the average market value for a single-family home in the U.S. is $362,210 according to February Zillow estimates — a nearly 55% increase since 2019.
Higher property tax rates may also be behind an increase in real estate taxes. Local governments can raise the rate to cover increases in operational and service costs.
#local #home #average
Property taxes are largely determined by a home's ***** sed value and the local tax rate.
The ***** sed value is a dollar amount ***** igned to your home by your local county ***** sor to help determine the property tax. It's not the same as the market value, but it incorporates it.
A higher home market value can mean a higher ***** sed value, which would directly increase its property taxes. And the average market value for a single-family home in the U.S. is $362,210 according to February Zillow estimates — a nearly 55% increase since 2019.
Higher property tax rates may also be behind an increase in real estate taxes. Local governments can raise the rate to cover increases in operational and service costs.
#local #home #average


1 month ago
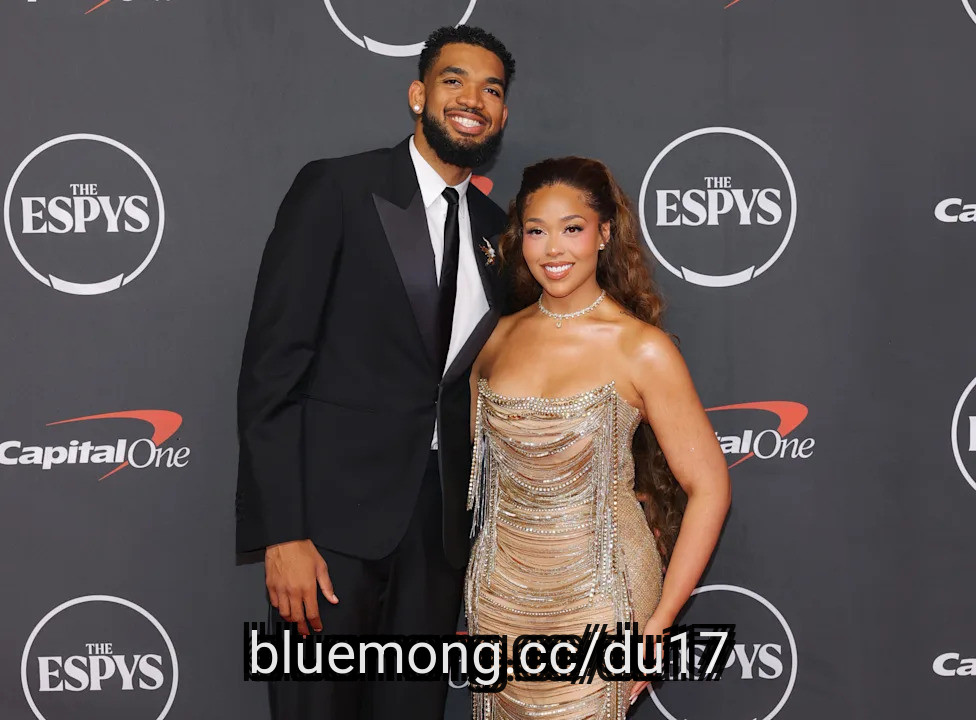
Jordyn Woods has spent much of her life in the spotlight, first as Kylie Jenner's longtime best friend and later as a model, entrepreneur and celebrity in her own right. From her Hollywood connections and family background to her relationship with NBA star Karl-Anthony Towns, Woods has built a life that extends far beyond her former ties to the Kardashian-Jenner family.
But how much do we really know about the life Woods has created for herself? From whether she grew up wealthy and where she lives today to the eye-catching engagement ring she received from Towns and her estimated net worth, here's everything to know about Jordyn Woods' life, career and finances.
Despite her close ties to the Kardashian-Jenner and Smith families, Jordyn Woods did not grow up in a wealthy celebrity household. Her father, John Woods, was a television sound engineer who worked on "The Fresh Prince of Bel-Air", while her mother, Elizabeth Woods, worked as a talent and brand manager. Her parents' careers gave Jordyn an early connection to Hollywood, and her family became particularly close with Will Smith and Jada Pinkett Smith through her father's work, according to People.
Jordyn has acknowledged that she had certain privileges growing up in California and being surrounded by successful people, but she has also pushed back against the idea that her family was wealthy. In a 2025 interview with Crystal Renee Hayslett, she explained that her father worked extremely hard to provide for their family and said that they "definitely struggled," emphasizing that being around wealthy people did not mean her family had the same financial resources.
Jordyn Woods currently lives in Los Angeles, California, with her husband, NBA star Karl-Anthony Towns. TMZ reports the couple purchased a $14 million home in the Los Angeles area, putting them among the city's many celebrity homeowners. Their move into the luxury property came as Woods continued to expand her career beyond social media, while Towns built his fortune through his NBA career.
#woods #jordyn #towns #smith
But how much do we really know about the life Woods has created for herself? From whether she grew up wealthy and where she lives today to the eye-catching engagement ring she received from Towns and her estimated net worth, here's everything to know about Jordyn Woods' life, career and finances.
Despite her close ties to the Kardashian-Jenner and Smith families, Jordyn Woods did not grow up in a wealthy celebrity household. Her father, John Woods, was a television sound engineer who worked on "The Fresh Prince of Bel-Air", while her mother, Elizabeth Woods, worked as a talent and brand manager. Her parents' careers gave Jordyn an early connection to Hollywood, and her family became particularly close with Will Smith and Jada Pinkett Smith through her father's work, according to People.
Jordyn has acknowledged that she had certain privileges growing up in California and being surrounded by successful people, but she has also pushed back against the idea that her family was wealthy. In a 2025 interview with Crystal Renee Hayslett, she explained that her father worked extremely hard to provide for their family and said that they "definitely struggled," emphasizing that being around wealthy people did not mean her family had the same financial resources.
Jordyn Woods currently lives in Los Angeles, California, with her husband, NBA star Karl-Anthony Towns. TMZ reports the couple purchased a $14 million home in the Los Angeles area, putting them among the city's many celebrity homeowners. Their move into the luxury property came as Woods continued to expand her career beyond social media, while Towns built his fortune through his NBA career.
#woods #jordyn #towns #smith

1 month ago
Striking a blow to Mayor Mamdani’s rollout of his signature pied-à-terre tax, a New York City judge on Tuesday ruled in favor of owners of pricey second homes and ordered the city to restart the process.
Staten Island Supreme Court Justice Wayne Ozzi found that notices the city mailed to homeowners informing them that they may be subject to the surcharge were unlawful and had to be canceled and re-sent. He also ruled that a supplemental property tax roll posted online must be taken down.
“No crime is involved here, but homeowners are being substantially harmed and penalized needlessly,” Ozzi wrote in his 22-page decision, referring to the city’s controversial rollout of the tax on high-value second homes.
#second #striking #mamdani
Staten Island Supreme Court Justice Wayne Ozzi found that notices the city mailed to homeowners informing them that they may be subject to the surcharge were unlawful and had to be canceled and re-sent. He also ruled that a supplemental property tax roll posted online must be taken down.
“No crime is involved here, but homeowners are being substantially harmed and penalized needlessly,” Ozzi wrote in his 22-page decision, referring to the city’s controversial rollout of the tax on high-value second homes.
#second #striking #mamdani



2 months ago
When developers hand governance to residents at build-out, HOA fees spike as homeowners absorb true amenity costs and cover reserve underfunding through special ****** sments.
HOA fee increases in post-transition communities routinely outpace the 2027 Social Security COLA of roughly 3%, squeezing retirees on fixed incomes.
Demand the reserve study, CC&Rs, and community development district bond balance before signing. If the sales office stalls, the pitch was rehearsed, not substantiated.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
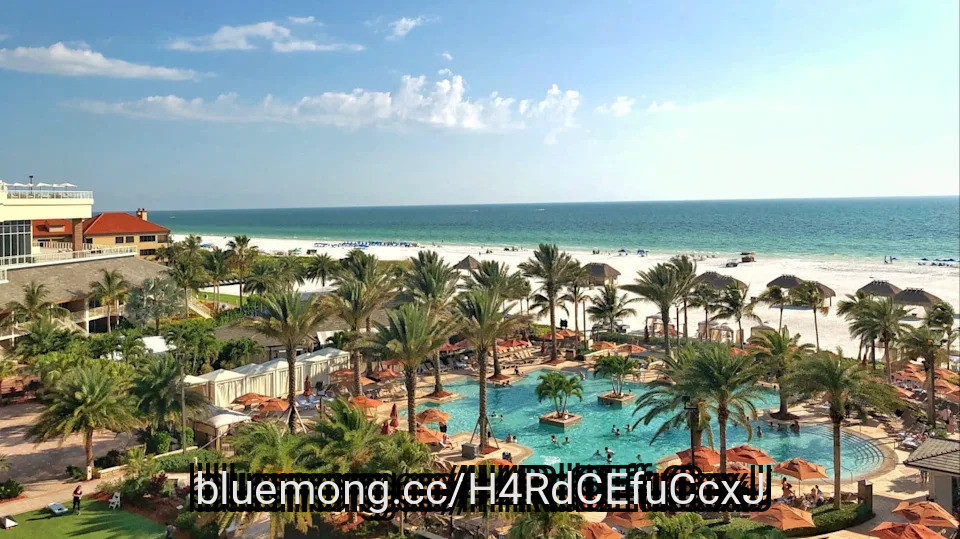
Readers in their late fifties and early sixties ask weekly: Can I retire to a Margaritaville community, and what will it cost over twenty or thirty years? The brochure sells one version, while the sales center sells another. The real question a retiree should ask is what happens once marketing wears off and the structural issue the sales presentation almost never covers emerges.
#retirees #community #years #sells
HOA fee increases in post-transition communities routinely outpace the 2027 Social Security COLA of roughly 3%, squeezing retirees on fixed incomes.
Demand the reserve study, CC&Rs, and community development district bond balance before signing. If the sales office stalls, the pitch was rehearsed, not substantiated.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Readers in their late fifties and early sixties ask weekly: Can I retire to a Margaritaville community, and what will it cost over twenty or thirty years? The brochure sells one version, while the sales center sells another. The real question a retiree should ask is what happens once marketing wears off and the structural issue the sales presentation almost never covers emerges.
#retirees #community #years #sells
2 months ago
Sunny, low-tax states like Florida, South Carolina and Nevada have become a magnet for U.S. retirees, with Florida alone placing four cities in the top 10 WalletHub's Best Places to Retir survey. Scottsdale, Arizona and Las Vegas, Nevada also placed in the top 12 slots in the survey.
Relocation and family finance experts say retirees are drawn to sunnier, usually southern U.S. locales not only due to the warmer climate, but for a lower, or no, tax-rate. Now, data is showing that many retirees are finding their new states bring countering cost of living issues to the buffet table, most notably homeowners ****** ociation fees and sky-high home insurance rates.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#retirees #nevada #sunny
Relocation and family finance experts say retirees are drawn to sunnier, usually southern U.S. locales not only due to the warmer climate, but for a lower, or no, tax-rate. Now, data is showing that many retirees are finding their new states bring countering cost of living issues to the buffet table, most notably homeowners ****** ociation fees and sky-high home insurance rates.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#retirees #nevada #sunny

2 months ago
Imagine purchasing a house for $449,328 and losing it over an unpaid $977 debt to your homeowners ****** ociation. This sounds like the stuff of nightmares, but it's reality for Toby Newton, a 53-year-old who used to own a home in Mesa's Superstition Springs community until his HOA foreclosed over a small amount of debt from missed ****** sments.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
The Mesa Tribune reported on Newton's tragic situation, which Edward Susolik, CEO & President of Callahan & Blaine, PC, told Moneywise was "pretty extreme." Here's how Newton lost his home, along with expert advice on what homeowners should do to avoid the same fate.
#like
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
The Mesa Tribune reported on Newton's tragic situation, which Edward Susolik, CEO & President of Callahan & Blaine, PC, told Moneywise was "pretty extreme." Here's how Newton lost his home, along with expert advice on what homeowners should do to avoid the same fate.
#like


2 months ago
As high mortgage rates and elevated home prices continue to crimp housing affordability, Federal Housing Finance Agency's Bill Pulte is seeking cuts to a common "hidden cost" of homeownership.
Targeting private mortgage insurance, which around 800,000 borrowers used to buy homes last year, Pulte is aligning policies between mortgage giants Fannie Mae and Freddie Mac to allow loan servicers to proactively call borrowers when they're eligible to drop their mortgage insurance. Previously, only Freddie Mac allowed servicers to do so.
"If your Home is worth more, or you have paid the loan down far enough, you should be able to drop EXTRA Mortgage Insurance," Pulte wrote in a post on X on Tuesday.
"Right now Fannie Mae will not let your loan company call and tell you that you may qualify because your home has gone up in value! You have to know to ask. Freddie Mac will let them call. That is crazy. We are fixing that. Fannie Mae will follow Freddie's rule: if you may qualify to drop unnecessary extra insurance because your home has gained value, they can contact you and walk you through how to cancel your PMI. You can stop paying for coverage you do not need and keep the money."
Read more: What is private mortgage insurance (PMI)? Definition, cost, and how to avoid it
#freddie #loan #call
Targeting private mortgage insurance, which around 800,000 borrowers used to buy homes last year, Pulte is aligning policies between mortgage giants Fannie Mae and Freddie Mac to allow loan servicers to proactively call borrowers when they're eligible to drop their mortgage insurance. Previously, only Freddie Mac allowed servicers to do so.
"If your Home is worth more, or you have paid the loan down far enough, you should be able to drop EXTRA Mortgage Insurance," Pulte wrote in a post on X on Tuesday.
"Right now Fannie Mae will not let your loan company call and tell you that you may qualify because your home has gone up in value! You have to know to ask. Freddie Mac will let them call. That is crazy. We are fixing that. Fannie Mae will follow Freddie's rule: if you may qualify to drop unnecessary extra insurance because your home has gained value, they can contact you and walk you through how to cancel your PMI. You can stop paying for coverage you do not need and keep the money."
Read more: What is private mortgage insurance (PMI)? Definition, cost, and how to avoid it
#freddie #loan #call


2 months ago
In some markets, it costs less to rent than to buy — by a lot. And it could be a great way to save a ton of money during your retirement years.
Mortgage and financial consultant Cody Schuiteboer of Best Interest Financial said many retirees never even consider renting as a serious option.
"There is an unshakeable mentality that buying is always the right choice, but the opposite is often true in retirement," he said. "If renting is actually cheaper in that market, renting lets retirees stretch their nest egg further."
MoneyLion ran the rent-versus-ownership numbers in the top retirement destinations along the East Coast and found the cities offering the greatest savings to renters. The homeownership numbers ****** umed a 10% down payment and a 6.53% interest rate, using average home price and rent numbers from Zillow.
Best of all, the following retirement hubs all have a total monthly expenditure cost under $4,000 according to BLS data, and adults over 65 make up at least 20% of the population.
#rent
Mortgage and financial consultant Cody Schuiteboer of Best Interest Financial said many retirees never even consider renting as a serious option.
"There is an unshakeable mentality that buying is always the right choice, but the opposite is often true in retirement," he said. "If renting is actually cheaper in that market, renting lets retirees stretch their nest egg further."
MoneyLion ran the rent-versus-ownership numbers in the top retirement destinations along the East Coast and found the cities offering the greatest savings to renters. The homeownership numbers ****** umed a 10% down payment and a 6.53% interest rate, using average home price and rent numbers from Zillow.
Best of all, the following retirement hubs all have a total monthly expenditure cost under $4,000 according to BLS data, and adults over 65 make up at least 20% of the population.
#rent

2 months ago
Imagine purchasing a house for $449,328 and losing it over an unpaid $977 debt to your homeowners ******* ociation. This sounds like the stuff of nightmares, but it's reality for Toby Newton, a 53-year-old who used to own a home in Mesa's Superstition Springs community until his HOA foreclosed over a small amount of debt from missed ******* sments.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
The Mesa Tribune reported on Newton's tragic situation, which Edward Susolik, CEO & President of Callahan & Blaine, PC, told Moneywise was "pretty extreme." Here's how Newton lost his home, along with expert advice on what homeowners should do to avoid the same fate.
#like #home
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
The Mesa Tribune reported on Newton's tragic situation, which Edward Susolik, CEO & President of Callahan & Blaine, PC, told Moneywise was "pretty extreme." Here's how Newton lost his home, along with expert advice on what homeowners should do to avoid the same fate.
#like #home
2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
With mortgage rates pushing 7%, the timing of a "rate sale" couldn't be better. Chase Home Loans is once again hosting a limited-time interest rate discount promotion.
The national lender launched its first weeks-only offer just over a year ago. Apparently, it's been enough of a success that Chase is bringing the rate sale back for its third encore.
The rate discount is available for three weeks only, from Monday, Sept. 14, through Sunday, Oct. 4. Chase Home Loans will offer homebuyers and homeowners discounted rates on all new mortgage purchase and refinance loans. The sale is available for both new and existing customers.
While offers vary by state, Chase says qualified buyers can receive up to 0.25% off their loan interest rate. For example, an offered rate of 6.75% could be cut to 6.50%. That would save a borrower over $23,800 in interest on a $400,000 loan with a fixed-interest 30-year term — and reduce the payment by more than $65 a month.
#offers #rates
With mortgage rates pushing 7%, the timing of a "rate sale" couldn't be better. Chase Home Loans is once again hosting a limited-time interest rate discount promotion.
The national lender launched its first weeks-only offer just over a year ago. Apparently, it's been enough of a success that Chase is bringing the rate sale back for its third encore.
The rate discount is available for three weeks only, from Monday, Sept. 14, through Sunday, Oct. 4. Chase Home Loans will offer homebuyers and homeowners discounted rates on all new mortgage purchase and refinance loans. The sale is available for both new and existing customers.
While offers vary by state, Chase says qualified buyers can receive up to 0.25% off their loan interest rate. For example, an offered rate of 6.75% could be cut to 6.50%. That would save a borrower over $23,800 in interest on a $400,000 loan with a fixed-interest 30-year term — and reduce the payment by more than $65 a month.
#offers #rates


2 months ago
Extreme weather is creating a more demanding environment for property owners, insurers, and communities. According to the National Centers for Environmental Information (NCEI), the United States recorded 27 confirmed billion-dollar weather and climate disasters in 2024, resulting in a total cost of $182.7 billion. These events spanned a wide range of extremes, including severe storm events, tropical cyclones, wildfires, drought/heat waves, and winter storm/cold wave events. Over the last decade, ***** ulative losses from these disasters have exceeded $1.4 trillion, driven significantly by population growth, material wealth, and increased development in hazard-prone areas. These figures suggest that the financial consequences of extreme events may increasingly depend on how accurately the value of exposed property is understood before a loss occurs.
That question becomes especially consequential during reconstruction. A 2026 report from Bloomberg, featured in Claims Journal, noted that surveys conducted by United Policyholders since 2007 found an average of two-thirds of wildfire survivors reporting that they were underinsured, with an average shortfall of $200,000 or more. The Insurance Information Institute has similarly estimated that two-thirds of American homeowners may be underinsured for wildfire losses, typically by about 20%, and in some cases by as much as 60%. These findings illustrate how the presence of an insurance policy can still leave a substantial difference between available coverage and the resources required to rebuild, particularly when construction costs rise after a catastrophe.
The financial implications can extend across the broader insurance ecosystem. Aon's 2026 Climate and Catastrophe Insight reported approximately $260 billion in global economic losses from natural catastrophes during 2025, compared with $127 billion in insured losses. For property stakeholders, such a figure may place greater attention on the relationship between the value ***** igned to an ***** et, the cost of restoring it, and the capital available when a loss occurs.
Frequency can add another layer to that calculation. Data from NCEI indicate that the average interval between U.S. billion-dollar disaster events was approximately 16 days during 2020–2024, compared with 82 days during the 1980s. NCEI notes that shorter intervals can leave less time and fewer resources for response, recovery, and preparation for subsequent events. As the time between major events contracts, property valuations may require more frequent attention because construction costs, labor conditions, materials, and local economic circumstances can change between policy reviews.
#property #losses #insurance #information
That question becomes especially consequential during reconstruction. A 2026 report from Bloomberg, featured in Claims Journal, noted that surveys conducted by United Policyholders since 2007 found an average of two-thirds of wildfire survivors reporting that they were underinsured, with an average shortfall of $200,000 or more. The Insurance Information Institute has similarly estimated that two-thirds of American homeowners may be underinsured for wildfire losses, typically by about 20%, and in some cases by as much as 60%. These findings illustrate how the presence of an insurance policy can still leave a substantial difference between available coverage and the resources required to rebuild, particularly when construction costs rise after a catastrophe.
The financial implications can extend across the broader insurance ecosystem. Aon's 2026 Climate and Catastrophe Insight reported approximately $260 billion in global economic losses from natural catastrophes during 2025, compared with $127 billion in insured losses. For property stakeholders, such a figure may place greater attention on the relationship between the value ***** igned to an ***** et, the cost of restoring it, and the capital available when a loss occurs.
Frequency can add another layer to that calculation. Data from NCEI indicate that the average interval between U.S. billion-dollar disaster events was approximately 16 days during 2020–2024, compared with 82 days during the 1980s. NCEI notes that shorter intervals can leave less time and fewer resources for response, recovery, and preparation for subsequent events. As the time between major events contracts, property valuations may require more frequent attention because construction costs, labor conditions, materials, and local economic circumstances can change between policy reviews.
#property #losses #insurance #information


2 months ago
A 24-year-old man accused of taking part in a series of high-end home break-ins in the Philadelphia suburbs appeared in a Montgomery County courtroom Thursday.
Jabir Hanif Parker is accused of burglarizing homes from June through August, focusing on master bedrooms and closets in search of expensive jewelry, watches and other valuables.
Investigators say the cases involve three residential burglaries and an attempted burglary at the home of Eagles star Saquon Barkley in Malvern.
Two homeowners were home during the incidents, including Barkley and his family, while two were not.
Authorities say the crimes were sophisticated and appeared to involve planning.
#home #barkley #accused #philadelphia
Jabir Hanif Parker is accused of burglarizing homes from June through August, focusing on master bedrooms and closets in search of expensive jewelry, watches and other valuables.
Investigators say the cases involve three residential burglaries and an attempted burglary at the home of Eagles star Saquon Barkley in Malvern.
Two homeowners were home during the incidents, including Barkley and his family, while two were not.
Authorities say the crimes were sophisticated and appeared to involve planning.
#home #barkley #accused #philadelphia

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
Selling a home for $890,000 leaves roughly $328,000 taxable after the $500,000 joint exclusion, adding $9,240 in Medicare surcharges two years later.
Section 121's $500,000 joint exclusion ceiling hasn't risen with inflation since 1997, leaving longtime homeowners exposed to large taxable gains on ordinary homes.
Rebuilding cost basis with documented improvements, deferring optional IRA withdrawals, and budgeting for the Medicare surcharge from proceeds reduces the sale's financial impact.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
For more than 40 years, the house did exactly what its owners hoped it would do. A couple who paid $62,000 for their home in 1984 closes on the sale this year at $890,000. The IRS lets them exclude up to $500,000 of gain under Internal Revenue Code Section 121. Any taxable gain left after the exclusion, basis adjustments and selling expenses flows into adjusted gross income (AGI). That figure helps determine the modified adjusted gross income (MAGI) Social Security uses to calculate Medicare's income-related monthly adjustment amount (IRMAA) two years later. The sale closes in 2026. The Medicare bill arrives in 2028.
#medicare #years #selling #later
Section 121's $500,000 joint exclusion ceiling hasn't risen with inflation since 1997, leaving longtime homeowners exposed to large taxable gains on ordinary homes.
Rebuilding cost basis with documented improvements, deferring optional IRA withdrawals, and budgeting for the Medicare surcharge from proceeds reduces the sale's financial impact.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
For more than 40 years, the house did exactly what its owners hoped it would do. A couple who paid $62,000 for their home in 1984 closes on the sale this year at $890,000. The IRS lets them exclude up to $500,000 of gain under Internal Revenue Code Section 121. Any taxable gain left after the exclusion, basis adjustments and selling expenses flows into adjusted gross income (AGI). That figure helps determine the modified adjusted gross income (MAGI) Social Security uses to calculate Medicare's income-related monthly adjustment amount (IRMAA) two years later. The sale closes in 2026. The Medicare bill arrives in 2028.
#medicare #years #selling #later


2 months ago
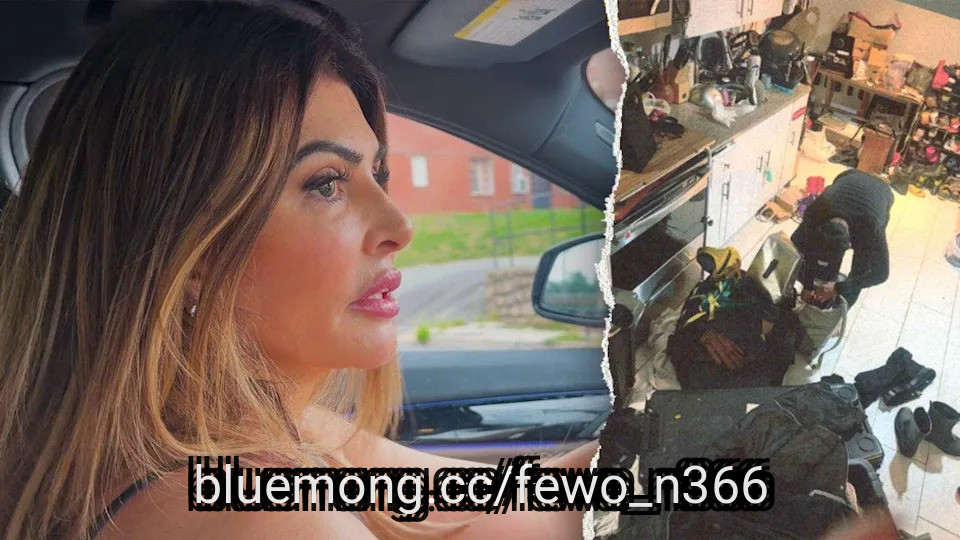
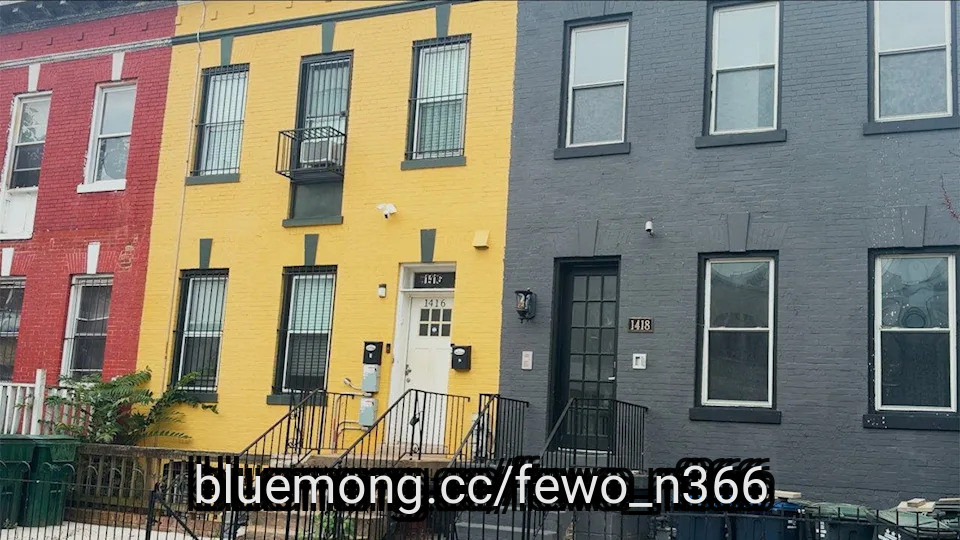
WASHINGTON, D.C. — FIRST ON FOX: As Washington, D.C., grapples with a persistent squatting problem, one resident in the nation's capital is speaking out about how unwelcome tenants have turned her life upside down, terrorizing her neighborhood while the city stands by and does nothing.
"I lived in several countries, including Third World countries, but it seems to me that I'm living in a Fourth World country in D.C.," Tatyana Day Velasquez, who owns a small three-unit building in Columbia Heights, told Fox News Digital.
"I've never seen something like it. There's no accountability for what goes on. Everybody just throws the ball to each other, and there's no help. So how can somebody resolve a problem like mine if you don't get help?"
For a tumultuous eight months, Velasquez said her property's basement apartment has been overrun by strangers who refuse to leave and live rent-free with no consequences in sight.
Homeowners Terrorized By Pro Squatters Turning Dreams Into Nightmares In Palm-lined Paradise, Experts Say
#World #velasquez #like #first
"I lived in several countries, including Third World countries, but it seems to me that I'm living in a Fourth World country in D.C.," Tatyana Day Velasquez, who owns a small three-unit building in Columbia Heights, told Fox News Digital.
"I've never seen something like it. There's no accountability for what goes on. Everybody just throws the ball to each other, and there's no help. So how can somebody resolve a problem like mine if you don't get help?"
For a tumultuous eight months, Velasquez said her property's basement apartment has been overrun by strangers who refuse to leave and live rent-free with no consequences in sight.
Homeowners Terrorized By Pro Squatters Turning Dreams Into Nightmares In Palm-lined Paradise, Experts Say
#World #velasquez #like #first

2 months ago
On August 18, Himax Technologies (NASDAQ:HIMX) said its WiseEye palm vein biometric technology now powers the WAFERLOCK L322, a smart lock built by Taiwan-based WAFERLOCK Corporation that just went on sale. Instead of scanning a fingerprint or a face, the lock reads the vein pattern under a user's palm, a method Himax says still works when hands are wet, dirty, or full of groceries. The announcement lands less than two weeks after Himax posted a second quarter that beat its own guidance on revenue, margin, and profit, giving the palm vein rollout a stronger financial backdrop than it might otherwise have had.
The WAFERLOCK deal shows what Himax has been building toward with WiseEye, an ultralow-power AI platform that pairs an image sensor and processor to capture, match, and verify a palm vein image directly on the device, without sending anything to the cloud. That matters for a smart lock, where sending biometric data offsite would be a hard sell to homeowners. The L322 pairs palm vein recognition with RFID cards, PIN codes, mechanical keys, and compatibility with EasyCard, iPASS, and MIFARE, so the biometric layer sits on top of access methods people already use.
Himax said the underlying palm vein modules earned TÜV Rheinland verification during the quarter, validating their recognition accuracy, response speed, and liveness detection, and that the technology also complies with GDPR, one of the world's strictest privacy standards. Design-in activity is already spreading beyond locks into workforce management, computer monitors, and smart office equipment.
Automotive remains the larger story sitting underneath it. Automotive display drivers, timing controllers, and touch controllers made up well over half of Himax's revenue in the quarter ended June 30, and the company expects full-year 2026 automotive IC sales to grow by double digits from a year earlier as automakers pack more, larger, and higher-resolution screens into vehicle interiors.
Alongside that base, Himax pointed to two newer bets: a leading global brand launched smart glasses powered by WiseEye during the quarter, and the company's co-packaged optics products entered engineering production ramps in the third quarter, with 2027 shipments expected to significantly exceed 2026. Neither business moves the revenue needle yet, but together they give Himax more than one lever to pull.
#himax #wiseeye #waferlock #lock
The WAFERLOCK deal shows what Himax has been building toward with WiseEye, an ultralow-power AI platform that pairs an image sensor and processor to capture, match, and verify a palm vein image directly on the device, without sending anything to the cloud. That matters for a smart lock, where sending biometric data offsite would be a hard sell to homeowners. The L322 pairs palm vein recognition with RFID cards, PIN codes, mechanical keys, and compatibility with EasyCard, iPASS, and MIFARE, so the biometric layer sits on top of access methods people already use.
Himax said the underlying palm vein modules earned TÜV Rheinland verification during the quarter, validating their recognition accuracy, response speed, and liveness detection, and that the technology also complies with GDPR, one of the world's strictest privacy standards. Design-in activity is already spreading beyond locks into workforce management, computer monitors, and smart office equipment.
Automotive remains the larger story sitting underneath it. Automotive display drivers, timing controllers, and touch controllers made up well over half of Himax's revenue in the quarter ended June 30, and the company expects full-year 2026 automotive IC sales to grow by double digits from a year earlier as automakers pack more, larger, and higher-resolution screens into vehicle interiors.
Alongside that base, Himax pointed to two newer bets: a leading global brand launched smart glasses powered by WiseEye during the quarter, and the company's co-packaged optics products entered engineering production ramps in the third quarter, with 2027 shipments expected to significantly exceed 2026. Neither business moves the revenue needle yet, but together they give Himax more than one lever to pull.
#himax #wiseeye #waferlock #lock


2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
A housing market crash happens when home values plummet due to a lack of demand for or an oversupply of homes. The factors leading to a housing market crash are varied, ranging from economic recessions to high mortgage rates that make it less affordable to buy a home. A housing crash can have upsides (low home prices) and downsides (losing built-up equity and tighter finances).
So, what's ahead for the housing market in 2026?
Read more: Want to buy a house in 2026? Here's what you need to know.
Despite 58% of Gen Z wanting a housing market crash, according to Clever, experts don't foresee one in 2026. If anything, they see a greater sense of normalcy following multiple years of twists and turns.
"We're not heading toward a housing crash; we're in a market correction defined by stability, not volatility," Hoby Hanna, CEO of Howard Hanna Real Estate Services, said via email. "Today's housing environment is fundamentally different from 2008. Homeowners have record levels of equity, lending standards are sound, and inventory remains constrained. What we're seeing now is a normalization, not a collapse, as the market adjusts to new economic realities. For buyers and sellers, this is a market filled with opportunity and resilience, not instability or uncertainty."
#we 're #hanna #Equity #disclosure
A housing market crash happens when home values plummet due to a lack of demand for or an oversupply of homes. The factors leading to a housing market crash are varied, ranging from economic recessions to high mortgage rates that make it less affordable to buy a home. A housing crash can have upsides (low home prices) and downsides (losing built-up equity and tighter finances).
So, what's ahead for the housing market in 2026?
Read more: Want to buy a house in 2026? Here's what you need to know.
Despite 58% of Gen Z wanting a housing market crash, according to Clever, experts don't foresee one in 2026. If anything, they see a greater sense of normalcy following multiple years of twists and turns.
"We're not heading toward a housing crash; we're in a market correction defined by stability, not volatility," Hoby Hanna, CEO of Howard Hanna Real Estate Services, said via email. "Today's housing environment is fundamentally different from 2008. Homeowners have record levels of equity, lending standards are sound, and inventory remains constrained. What we're seeing now is a normalization, not a collapse, as the market adjusts to new economic realities. For buyers and sellers, this is a market filled with opportunity and resilience, not instability or uncertainty."
#we 're #hanna #Equity #disclosure

2 months ago
California's cost-of-living index of 111 versus Texas's 97 drives real savings, but only for retirees drawing heavily from IRAs and 401(k)s.
California exempts Social Security from state income tax and Prop 13 caps property tax growth, but both benefits are permanently surrendered the day you sell.
Proposition 19 lets homeowners 55-plus transfer their existing Prop 13 ******* sed value to any California replacement home before listing on the market.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Every few months, a friend or cousin sends the same message: they sold the California house, cashed out the equity, and moved somewhere the mortgage, insurance, and gas stop hurting. The savings are described in a tone between relief and vindication. This piece examines whether the promised savings survive a full retirement budget, or whether a long-time Californian is quietly giving up more than the moving truck can carry.
#whether #Social #learn
California exempts Social Security from state income tax and Prop 13 caps property tax growth, but both benefits are permanently surrendered the day you sell.
Proposition 19 lets homeowners 55-plus transfer their existing Prop 13 ******* sed value to any California replacement home before listing on the market.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Every few months, a friend or cousin sends the same message: they sold the California house, cashed out the equity, and moved somewhere the mortgage, insurance, and gas stop hurting. The savings are described in a tone between relief and vindication. This piece examines whether the promised savings survive a full retirement budget, or whether a long-time Californian is quietly giving up more than the moving truck can carry.
#whether #Social #learn


2 months ago
I keep hearing people say they want to own Tesla (NASDAQ: TSLA) stock but are waiting for a better price, and I understand the instinct, because the stock has swung between $297.38 to $498.83 over the past year. The problem is that Tesla is already 30% off its high while deliveries grew 25% and energy storage jumped 40%, so the discount everyone is waiting for may already be here.
Tesla is down roughly 17% over the past four weeks, and I think that pullback is the entry point rather than a reason to wait for a deeper one.
Tesla trades today roughly 25% below its 52-week high, and about 23% above its 52-week low. Over the past 12 months, the stock has risen by 9.5%, meaning a year of operational progress has produced half the average price appreciation of the S&P 500, which is up by about 19%. Tesla's forward price-to-earnings ratio sits near 207, with a trailing multiple of about 340, so ***** ody is buying the stock based on its current earnings math. If you're buying it at all, you're doing so based on your view of what the company is building.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Second-quarter deliveries hit 480,126 electric vehicles (EVs), up 25% year over year, compared with 451,758 vehicles produced. The energy storage business deployed 13.5 GWh of capacity in the quarter, up 40% from 9.6 GWh in the prior-year quarter and up 53% from the 8.8 GWh it deployed in 2026's first quarter. It was Tesla's second-largest quarterly increase in storage ever, behind only the 14.2 GWh it added in the fourth quarter of 2025. ***** ulative deployments now exceed 132 GWh since 2016, with 22.3 GWh in the first half of 2026 alone.
Tesla's network of Powerwalls -- rechargeable home batteries that store electricity for later use, including during power outages -- supported more than 89,000 virtual power plant events across over 1 million installed units, saving homeowners more than $1 billion on electricity bills. Megapack 3 and Megablock production are starting at Megafactory Houston this year.
#tesla #signal #past #storage
Tesla is down roughly 17% over the past four weeks, and I think that pullback is the entry point rather than a reason to wait for a deeper one.
Tesla trades today roughly 25% below its 52-week high, and about 23% above its 52-week low. Over the past 12 months, the stock has risen by 9.5%, meaning a year of operational progress has produced half the average price appreciation of the S&P 500, which is up by about 19%. Tesla's forward price-to-earnings ratio sits near 207, with a trailing multiple of about 340, so ***** ody is buying the stock based on its current earnings math. If you're buying it at all, you're doing so based on your view of what the company is building.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Second-quarter deliveries hit 480,126 electric vehicles (EVs), up 25% year over year, compared with 451,758 vehicles produced. The energy storage business deployed 13.5 GWh of capacity in the quarter, up 40% from 9.6 GWh in the prior-year quarter and up 53% from the 8.8 GWh it deployed in 2026's first quarter. It was Tesla's second-largest quarterly increase in storage ever, behind only the 14.2 GWh it added in the fourth quarter of 2025. ***** ulative deployments now exceed 132 GWh since 2016, with 22.3 GWh in the first half of 2026 alone.
Tesla's network of Powerwalls -- rechargeable home batteries that store electricity for later use, including during power outages -- supported more than 89,000 virtual power plant events across over 1 million installed units, saving homeowners more than $1 billion on electricity bills. Megapack 3 and Megablock production are starting at Megafactory Houston this year.
#tesla #signal #past #storage

2 months ago
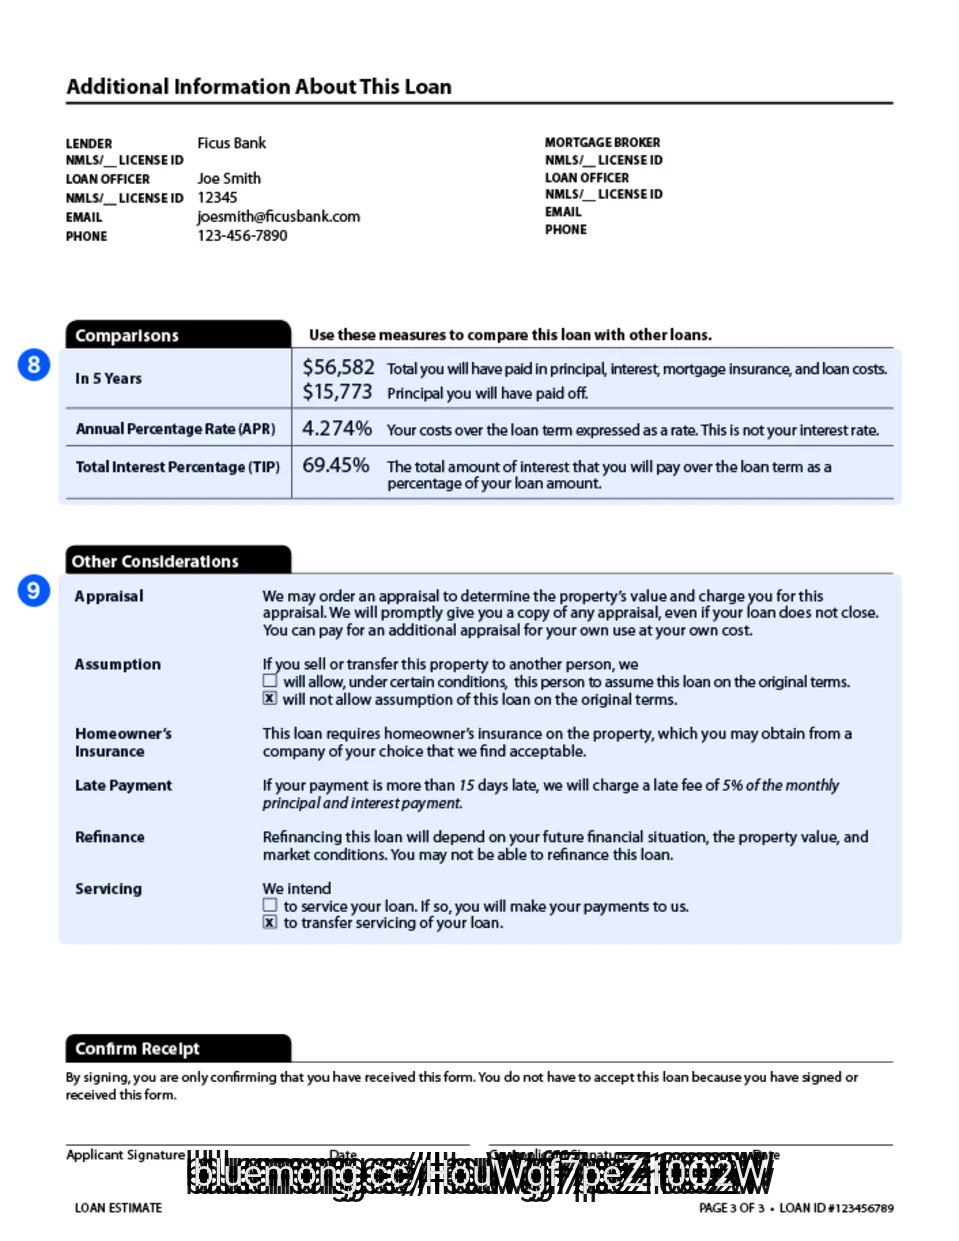
A loan estimate looks like a done deal. It isn't. Some of the numbers on it can legally change by up to 10% before closing, and a few can change by any amount.
Shopping around for a mortgage is crucial, and it starts with the loan estimate, a three-page document detailing the interest rate, estimated costs and other loan terms.
87% of 2025 borrowers paid above the most competitive rate available to them simply because they didn't compare offers, according to Bankrate's Hidden Homeownership Tax research. The typical cost of not shopping: $3,343 a year, or $278 a month.
A mortgage loan estimate is a standardized, three-page document that a lender must send you within three business days of receiving your mortgage application. It lists your rate, monthly payment, closing costs and other terms — but none of these numbers are final. Think of it as a detailed price quote: close enough to compare lenders and build an accurate budget, but not enough to guarantee what you'll actually pay at closing.
When you compare loan estimates from more than one lender, you're more likely to uncover the lowest rate you actually qualify for. Freddie Mac found that borrowers who obtained two rate quotes during the high-rate months of October and November 2022, when average rates topped 7%, could have saved up to $600 a year. Borrowers who obtained at least four quotes could have saved more than $1,200 a year.
#estimate #compare #year
Shopping around for a mortgage is crucial, and it starts with the loan estimate, a three-page document detailing the interest rate, estimated costs and other loan terms.
87% of 2025 borrowers paid above the most competitive rate available to them simply because they didn't compare offers, according to Bankrate's Hidden Homeownership Tax research. The typical cost of not shopping: $3,343 a year, or $278 a month.
A mortgage loan estimate is a standardized, three-page document that a lender must send you within three business days of receiving your mortgage application. It lists your rate, monthly payment, closing costs and other terms — but none of these numbers are final. Think of it as a detailed price quote: close enough to compare lenders and build an accurate budget, but not enough to guarantee what you'll actually pay at closing.
When you compare loan estimates from more than one lender, you're more likely to uncover the lowest rate you actually qualify for. Freddie Mac found that borrowers who obtained two rate quotes during the high-rate months of October and November 2022, when average rates topped 7%, could have saved up to $600 a year. Borrowers who obtained at least four quotes could have saved more than $1,200 a year.
#estimate #compare #year


2 months ago
Listen and subscribe to Power Players with Brian Sozzi on Apple Podcasts, Amazon Music, Spotify, YouTube, or wherever you find your favorite podcasts.
With roots dating back to 1868, Scotts Miracle-Gro (SMG) faces a future that hinges on getting a nonchalant Gen Z crowd to pay to fertilize their lawns, just like their proud green-lawn-owning parents.
New CEO Nate Baxter realizes the hill to climb is steep and chock-full of roadblocks, such as more people buying Astroturf for lawns or putting stones where grass once lived — and needing water to do so.
"So our core consumer that has been with us for decades. They're homeowners or renters who care about their lawn. They are dedicated. And they care about weeds — they don't want them. They want the perfect lawn story," Baxter said in a new episode of the Power Players with Brian Sozzi podcast (watch above; listen in below). "What we are seeing with the next generation of consumer is a real interest in going natural. They don't mind an occasional dandelion in their lawn."
Baxter said Scotts has released new fertilizer in recyclable paper bags and all-natural lawn food to cater to this finicky crowd. He promises a push into products that could help people connect with the health of their lawn's soil.
#players #scotts #listen #crowd
With roots dating back to 1868, Scotts Miracle-Gro (SMG) faces a future that hinges on getting a nonchalant Gen Z crowd to pay to fertilize their lawns, just like their proud green-lawn-owning parents.
New CEO Nate Baxter realizes the hill to climb is steep and chock-full of roadblocks, such as more people buying Astroturf for lawns or putting stones where grass once lived — and needing water to do so.
"So our core consumer that has been with us for decades. They're homeowners or renters who care about their lawn. They are dedicated. And they care about weeds — they don't want them. They want the perfect lawn story," Baxter said in a new episode of the Power Players with Brian Sozzi podcast (watch above; listen in below). "What we are seeing with the next generation of consumer is a real interest in going natural. They don't mind an occasional dandelion in their lawn."
Baxter said Scotts has released new fertilizer in recyclable paper bags and all-natural lawn food to cater to this finicky crowd. He promises a push into products that could help people connect with the health of their lawn's soil.
#players #scotts #listen #crowd



2 months ago
Listen and subscribe to Power Players with Brian Sozzi on Apple Podcasts, Amazon Music, Spotify, YouTube, or wherever you find your favorite podcasts.
With roots dating back to 1868, Scotts Miracle-Gro (SMG) faces a future that hinges on getting a nonchalant Gen Z crowd to pay to fertilize their lawns, just like their proud green-lawn-owning parents.
New CEO Nate Baxter realizes the hill to climb is steep and chock-full of roadblocks, such as more people buying Astroturf for lawns or putting stones where grass once lived — and needing water to do so.
"So our core consumer that has been with us for decades. They're homeowners or renters who care about their lawn. They are dedicated. And they care about weeds — they don't want them. They want the perfect lawn story," Baxter said in a new episode of the Power Players with Brian Sozzi podcast (watch above; listen in below). "What we are seeing with the next generation of consumer is a real interest in going natural. They don't mind an occasional dandelion in their lawn."
Baxter said Scotts has released new fertilizer in recyclable paper bags and all-natural lawn food to cater to this finicky crowd. He promises a push into products that could help people connect with the health of their lawn's soil.
#crowd
With roots dating back to 1868, Scotts Miracle-Gro (SMG) faces a future that hinges on getting a nonchalant Gen Z crowd to pay to fertilize their lawns, just like their proud green-lawn-owning parents.
New CEO Nate Baxter realizes the hill to climb is steep and chock-full of roadblocks, such as more people buying Astroturf for lawns or putting stones where grass once lived — and needing water to do so.
"So our core consumer that has been with us for decades. They're homeowners or renters who care about their lawn. They are dedicated. And they care about weeds — they don't want them. They want the perfect lawn story," Baxter said in a new episode of the Power Players with Brian Sozzi podcast (watch above; listen in below). "What we are seeing with the next generation of consumer is a real interest in going natural. They don't mind an occasional dandelion in their lawn."
Baxter said Scotts has released new fertilizer in recyclable paper bags and all-natural lawn food to cater to this finicky crowd. He promises a push into products that could help people connect with the health of their lawn's soil.
#crowd

2 months ago
Tennessee's 9.55% combined sales tax and surging homeowners insurance drain fixed-income retirees faster than its zero income tax saves them.
Bowling Green, Kentucky fully exempts Social Security, ranks 18th in sales tax nationally, and offers housing untouched by Tennessee's migration-driven price surge.
A $600,000 portfolio at 4% withdrawal closes a $22,000 income gap after Social Security covers $48,000 of a $70,000 annual retirement budget.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Every few months, somebody brings up Tennessee as the obvious retirement move. No state income tax, mild winters, Nashville has a fun scene, and the mountains are nice to look at. It has become the default answer for anyone trying to stretch a retirement portfolio. But here is the question **** ody seems to ask.
#Retirement #learn
Bowling Green, Kentucky fully exempts Social Security, ranks 18th in sales tax nationally, and offers housing untouched by Tennessee's migration-driven price surge.
A $600,000 portfolio at 4% withdrawal closes a $22,000 income gap after Social Security covers $48,000 of a $70,000 annual retirement budget.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Every few months, somebody brings up Tennessee as the obvious retirement move. No state income tax, mild winters, Nashville has a fun scene, and the mountains are nice to look at. It has become the default answer for anyone trying to stretch a retirement portfolio. But here is the question **** ody seems to ask.
#Retirement #learn
2 months ago
On August 19, Lowe's Companies (NYSE:LOW) reported second-quarter sales of $26 billion, up 8.3% from a year earlier, even though comparable sales inched up just 0.2%. The headline number hides a split personality inside the business. Pro contractors, online shoppers and Do-It-For-Me customers kept spending, while everyday DIY homeowners pulled back hard enough that management trimmed its full-year guidance. That gap between who is still spending and who isn't is the real story in this quarter.
Pro sales grew again, and management credited small and medium-sized contractors responding to the company's digital planning tools and the MyLowe's Pro Rewards loyalty program, which lets Pros quote, plan, and manage jobs inside Lowe's own platform. Online sales jumped 15.7%, helped by expanded visualization tools and the Mylow AI agent, which has fielded more than 25 million customer and ******* ociate questions since launch.
Notably, CEO Marvin Ellison said the conversion rate for online shoppers who use Mylow runs triple that of shoppers who don't, a sign the tool is doing more than answering questions. Appliances delivered a seventh straight quarter of positive comparable sales, aided by next-day delivery in virtually every US ZIP code and a push into premium products like Traeger grills and a GE Profile refrigerator that scans groceries for an Instacart shopping list. Loyalty is compounding too: MyLowe's Rewards has crossed 30 million members who shop more often and spend more per visit than nonmembers, giving the company a growing base to sell that premium ******* ortment into even while the broader housing market stalls.
Comparable transactions fell 2.1% during the quarter, offset only by a 2.3% rise in average ticket, and management pinned the weakness on weather-sensitive and seasonal categories where DIY shoppers dominate. Executive Vice President Joe McFarland said Pro customers themselves are noticing it, describing homeowners who are "more cautious about their spending" and shifting toward smaller repair jobs instead of full remodels.
That caution pushed Lowe's to guide toward the bottom of its prior range, now targeting roughly $92 billion in sales and $12.25 in adjusted earnings per share for the full year. Margins felt it too. Adjusted operating margin slipped 62 basis points to 14%, and CFO Brandon Sink noted that an $80 million tariff refund benefit was largely wiped out by elevated fuel and transportation costs. The company's Foundation Building Materials and Artisan Design Group acquisitions add another layer of risk, since Sink flagged "softer-for-longer new home construction" pressuring demand in both segments. Inventory climbed to $17.7 billion, up $1.4 billion year over year, and adjusted debt to EBITDA sits at 3.0x against a 2.75x target management doesn't expect to hit until mid-2027. Third quarter earnings are guided to come in roughly 7% below last year's adjusted EPS.
#sales #billion #shoppers #online
Pro sales grew again, and management credited small and medium-sized contractors responding to the company's digital planning tools and the MyLowe's Pro Rewards loyalty program, which lets Pros quote, plan, and manage jobs inside Lowe's own platform. Online sales jumped 15.7%, helped by expanded visualization tools and the Mylow AI agent, which has fielded more than 25 million customer and ******* ociate questions since launch.
Notably, CEO Marvin Ellison said the conversion rate for online shoppers who use Mylow runs triple that of shoppers who don't, a sign the tool is doing more than answering questions. Appliances delivered a seventh straight quarter of positive comparable sales, aided by next-day delivery in virtually every US ZIP code and a push into premium products like Traeger grills and a GE Profile refrigerator that scans groceries for an Instacart shopping list. Loyalty is compounding too: MyLowe's Rewards has crossed 30 million members who shop more often and spend more per visit than nonmembers, giving the company a growing base to sell that premium ******* ortment into even while the broader housing market stalls.
Comparable transactions fell 2.1% during the quarter, offset only by a 2.3% rise in average ticket, and management pinned the weakness on weather-sensitive and seasonal categories where DIY shoppers dominate. Executive Vice President Joe McFarland said Pro customers themselves are noticing it, describing homeowners who are "more cautious about their spending" and shifting toward smaller repair jobs instead of full remodels.
That caution pushed Lowe's to guide toward the bottom of its prior range, now targeting roughly $92 billion in sales and $12.25 in adjusted earnings per share for the full year. Margins felt it too. Adjusted operating margin slipped 62 basis points to 14%, and CFO Brandon Sink noted that an $80 million tariff refund benefit was largely wiped out by elevated fuel and transportation costs. The company's Foundation Building Materials and Artisan Design Group acquisitions add another layer of risk, since Sink flagged "softer-for-longer new home construction" pressuring demand in both segments. Inventory climbed to $17.7 billion, up $1.4 billion year over year, and adjusted debt to EBITDA sits at 3.0x against a 2.75x target management doesn't expect to hit until mid-2027. Third quarter earnings are guided to come in roughly 7% below last year's adjusted EPS.
#sales #billion #shoppers #online

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
A housing market crash happens when home values plummet due to a lack of demand for or an oversupply of homes. The factors leading to a housing market crash are varied, ranging from economic recessions to high mortgage rates that make it less affordable to buy a home. A housing crash can have upsides (low home prices) and downsides (losing built-up equity and tighter finances).
So, what's ahead for the housing market in 2026?
Read more: Want to buy a house in 2026? Here's what you need to know.
Despite 58% of Gen Z wanting a housing market crash, according to Clever, experts don't foresee one in 2026. If anything, they see a greater sense of normalcy following multiple years of twists and turns.
"We're not heading toward a housing crash; we're in a market correction defined by stability, not volatility," Hoby Hanna, CEO of Howard Hanna Real Estate Services, said via email. "Today's housing environment is fundamentally different from 2008. Homeowners have record levels of equity, lending standards are sound, and inventory remains constrained. What we're seeing now is a normalization, not a collapse, as the market adjusts to new economic realities. For buyers and sellers, this is a market filled with opportunity and resilience, not instability or uncertainty."
#economic #disclosure
A housing market crash happens when home values plummet due to a lack of demand for or an oversupply of homes. The factors leading to a housing market crash are varied, ranging from economic recessions to high mortgage rates that make it less affordable to buy a home. A housing crash can have upsides (low home prices) and downsides (losing built-up equity and tighter finances).
So, what's ahead for the housing market in 2026?
Read more: Want to buy a house in 2026? Here's what you need to know.
Despite 58% of Gen Z wanting a housing market crash, according to Clever, experts don't foresee one in 2026. If anything, they see a greater sense of normalcy following multiple years of twists and turns.
"We're not heading toward a housing crash; we're in a market correction defined by stability, not volatility," Hoby Hanna, CEO of Howard Hanna Real Estate Services, said via email. "Today's housing environment is fundamentally different from 2008. Homeowners have record levels of equity, lending standards are sound, and inventory remains constrained. What we're seeing now is a normalization, not a collapse, as the market adjusts to new economic realities. For buyers and sellers, this is a market filled with opportunity and resilience, not instability or uncertainty."
#economic #disclosure
2 months ago
In 2025, 87% of all mortgage borrowers paid above the most competitive rate available to them, and 78.7% of refinance borrowers overpaid, typically costing them $3,343 a year, or $278 a month, according to Bankrate's Hidden Homeownership Tax research.
Refinancing isn't free. Expect closing costs of 2% to 5% of your new loan amount, and the savings only outweigh that cost once you cross your break-even point.
While a lower interest rate sounds tempting, keep an eye on fees – they can overwhelm your savings from lower monthly payments.
Despite the rise in interest rates in the last few years, refinancing may still make sense for some homeowners. If you're a first-time refinancer, though, you might have a lot of questions about what the process is like — and might also have picked up some misinformation. Let's dispel some common myths about mortgage refinancing.
Myth
#savings
Refinancing isn't free. Expect closing costs of 2% to 5% of your new loan amount, and the savings only outweigh that cost once you cross your break-even point.
While a lower interest rate sounds tempting, keep an eye on fees – they can overwhelm your savings from lower monthly payments.
Despite the rise in interest rates in the last few years, refinancing may still make sense for some homeowners. If you're a first-time refinancer, though, you might have a lot of questions about what the process is like — and might also have picked up some misinformation. Let's dispel some common myths about mortgage refinancing.
Myth
#savings