


6 days ago
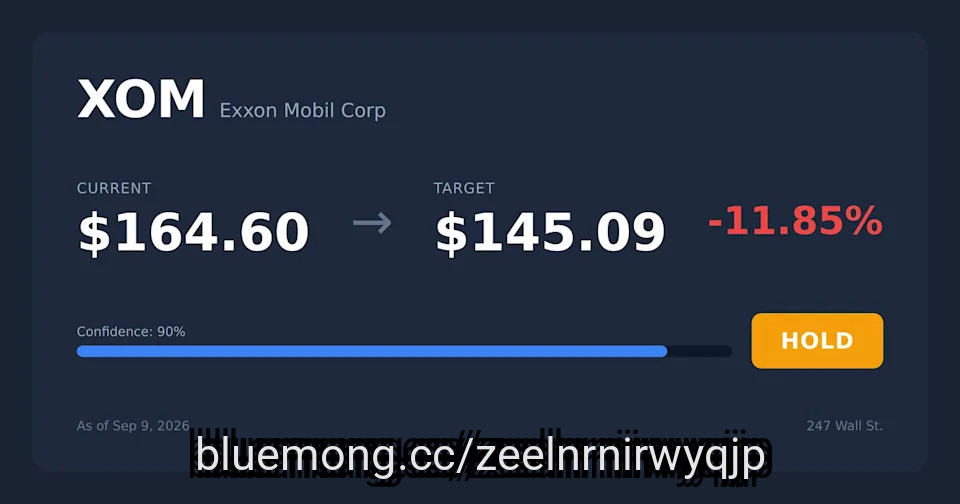
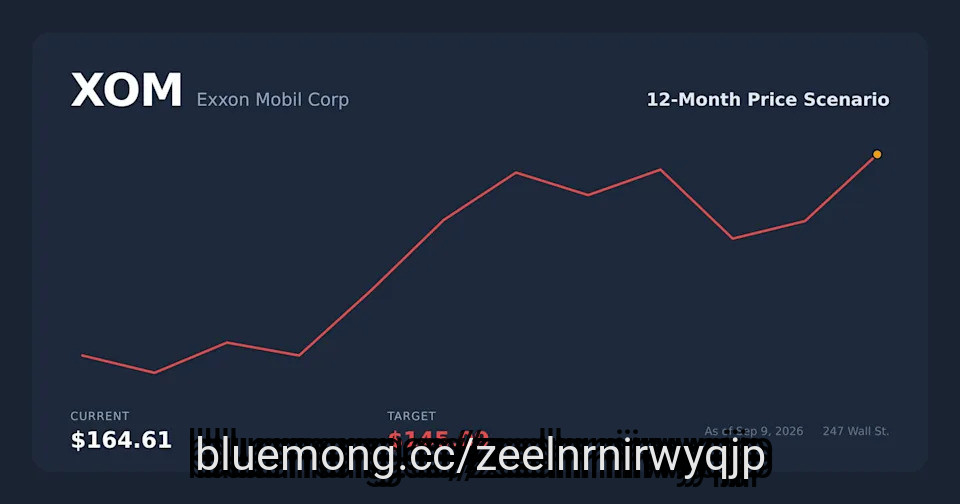
ExxonMobil (XOM) is up 40% in 2026 to $164.83, powered by Brent crude surging from the low $60s to $96, delivering $14.5B in Q2 earnings.
Chevron (CVX) and the XLE ETF outpaced XOM with gains of 44% and 48% respectively, leaving the biggest U.S. major trailing its own sector.
Reaching $200 is possible but depends on crude holding near $96, while the EIA projects Brent falling to $79 by 2027.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Exxon Mobil didn't make the cut. Enter your email to see the names that beat XOM. The report is free. Enter your email and see if any of your stocks made the cut.
ExxonMobil (NYSE:XOM) stock is climbing Wednesday afternoon, extending a strong year for U.S. oil majors. ExxonMobil shares are up 3% in the current session to $164.83, carrying a 40% year-to-date gain. WTI crude oil has done much of the heavy lifting, and today it's up 3.29% over the past 24 hours to $96.09 per barrel.
#exxonmobil #crude
Chevron (CVX) and the XLE ETF outpaced XOM with gains of 44% and 48% respectively, leaving the biggest U.S. major trailing its own sector.
Reaching $200 is possible but depends on crude holding near $96, while the EIA projects Brent falling to $79 by 2027.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Exxon Mobil didn't make the cut. Enter your email to see the names that beat XOM. The report is free. Enter your email and see if any of your stocks made the cut.
ExxonMobil (NYSE:XOM) stock is climbing Wednesday afternoon, extending a strong year for U.S. oil majors. ExxonMobil shares are up 3% in the current session to $164.83, carrying a 40% year-to-date gain. WTI crude oil has done much of the heavy lifting, and today it's up 3.29% over the past 24 hours to $96.09 per barrel.
#exxonmobil #crude

6 days ago
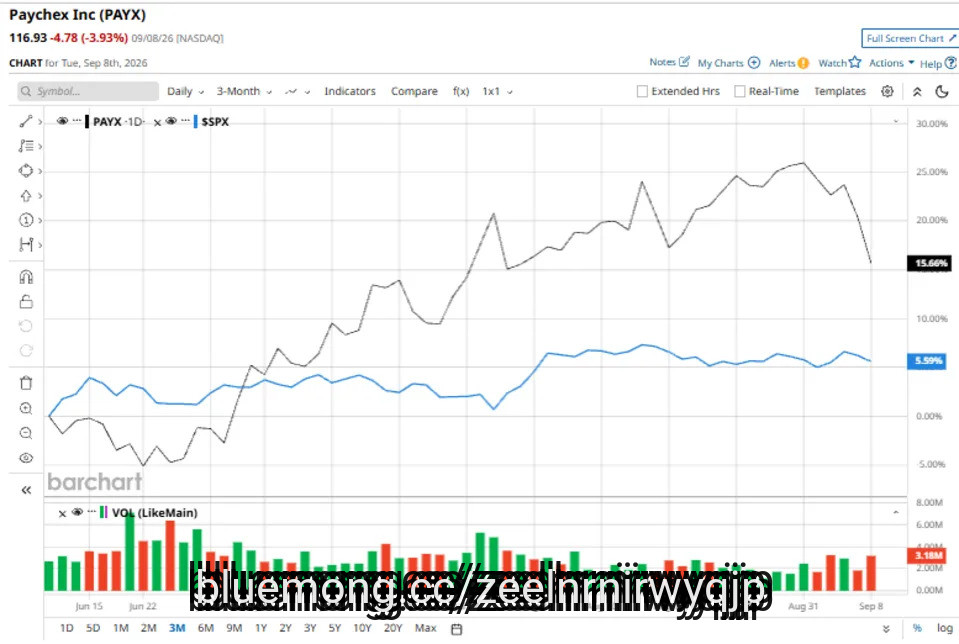
Rochester, New York-based Paychex, Inc. (PAYX) is a leading human capital management company. Its cloud-based platforms, including Paychex Flex, Paycor and SurePayroll, serve businesses across the employee lifecycle, from hiring and onboarding to payroll administration and benefits management.
Companies with a market cap of $10 billion or more are typically referred to as "big-cap stocks." PAYX, with a market cap of $36 billion, fits right into that category. Its competitive position is supported by its broad, integrated payroll and HR platform, deep compliance expertise, personalized service and scalable solutions for small and mid-sized businesses. Its large customer base and recurring payroll relationships create opportunities to cross-sell benefits, retirement, insurance and HR outsourcing services, while its Paychex Flex and Paycor platforms expand its reach across business sizes. Investments in AI, workforce ***** ytics and automation further strengthen its technology offering.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ***** ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#based
Companies with a market cap of $10 billion or more are typically referred to as "big-cap stocks." PAYX, with a market cap of $36 billion, fits right into that category. Its competitive position is supported by its broad, integrated payroll and HR platform, deep compliance expertise, personalized service and scalable solutions for small and mid-sized businesses. Its large customer base and recurring payroll relationships create opportunities to cross-sell benefits, retirement, insurance and HR outsourcing services, while its Paychex Flex and Paycor platforms expand its reach across business sizes. Investments in AI, workforce ***** ytics and automation further strengthen its technology offering.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ***** ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#based


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
12 days ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ****** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Mastercard Incorporated (NYSE:MA). Mastercard Incorporated (NYSE:MA) is a leading global payment technology company that provides transaction processing and other payment-related products and services. On September 02, 2026, Mastercard Incorporated (NYSE:MA) closed at $588.14 per share. Over the past month, Mastercard Incorporated (NYSE:MA) returned 2.12% while its shares lost 1.26% over the past 52 weeks. Mastercard Incorporated (NYSE:MA) has a market capitalization of $515.22 billion.
Eagle Capital Management stated the following regarding Mastercard Incorporated (NYSE:MA) in its Q2 2026 investor letter:
High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global, Mastercard Incorporated (NYSE:MA), A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ****** ets, network effects, or regulatory moats. Mastercard operates as part of a global duopoly of payment rails and standards.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. However, as earnings in the economy normalize back towards m
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Mastercard Incorporated (NYSE:MA). Mastercard Incorporated (NYSE:MA) is a leading global payment technology company that provides transaction processing and other payment-related products and services. On September 02, 2026, Mastercard Incorporated (NYSE:MA) closed at $588.14 per share. Over the past month, Mastercard Incorporated (NYSE:MA) returned 2.12% while its shares lost 1.26% over the past 52 weeks. Mastercard Incorporated (NYSE:MA) has a market capitalization of $515.22 billion.
Eagle Capital Management stated the following regarding Mastercard Incorporated (NYSE:MA) in its Q2 2026 investor letter:
High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global, Mastercard Incorporated (NYSE:MA), A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ****** ets, network effects, or regulatory moats. Mastercard operates as part of a global duopoly of payment rails and standards.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. However, as earnings in the economy normalize back towards m
13 days ago
New York Federal Reserve President John Williams signaled Wednesday that he is open to raising interest rates at the Federal Open Market Committee's September 15-16 meeting, a shift from his previous stance favoring a hold on rates.
"There's no clear signs right now whether monetary policy currently is sufficient to make sure we bring inflation back to target in the next year or two, or whether you need to see further action to do that," Williams said in a "Squawk Box" appearance on CNBC, speaking with anchor Steve Liesman from the New York Fed's headquarters. He added that recent inflation data had been "encouraging" but that policymakers needed to consider a fuller picture of incoming information. He rounded out the thought by saying, "We've got to get a full picture and look at all the different pieces of information we have."
Williams, who holds a permanent seat on the FOMC, had until recently been among the Fed's most vocal defenders of keeping rates steady, according to MarketWatch. His comments Wednesday represented a notable shift in tone ahead of what markets consider a pivotal policy decision.
Williams also addressed the recent rise in Treasury yields, attributing it to economic strength rather than market dysfunction. "What's driving it, in large part, is really a strong U.S. economy and a strong economic outlook fueled by big investments in AI and data centers and technology in general," he said. He described inflation expectations as "well anchored" despite price pressures tied to tariffs and the Iran war.
Markets were pricing in roughly a two-in-three chance of a rate hike at the September meeting as of Wednesday morning, per CME Group figures cited by CNBC.
#wednesday #open
"There's no clear signs right now whether monetary policy currently is sufficient to make sure we bring inflation back to target in the next year or two, or whether you need to see further action to do that," Williams said in a "Squawk Box" appearance on CNBC, speaking with anchor Steve Liesman from the New York Fed's headquarters. He added that recent inflation data had been "encouraging" but that policymakers needed to consider a fuller picture of incoming information. He rounded out the thought by saying, "We've got to get a full picture and look at all the different pieces of information we have."
Williams, who holds a permanent seat on the FOMC, had until recently been among the Fed's most vocal defenders of keeping rates steady, according to MarketWatch. His comments Wednesday represented a notable shift in tone ahead of what markets consider a pivotal policy decision.
Williams also addressed the recent rise in Treasury yields, attributing it to economic strength rather than market dysfunction. "What's driving it, in large part, is really a strong U.S. economy and a strong economic outlook fueled by big investments in AI and data centers and technology in general," he said. He described inflation expectations as "well anchored" despite price pressures tied to tariffs and the Iran war.
Markets were pricing in roughly a two-in-three chance of a rate hike at the September meeting as of Wednesday morning, per CME Group figures cited by CNBC.
#wednesday #open
15 days ago
Markiplier's 8.5% GPRO stake, worth $9 million, ignited a two-day surge topping 128% and pushed shares back above the Nasdaq's $1 minimum bid threshold.
SONY and GRMN stayed flat while GPRO's rally masks a 31% revenue decline, a going-concern warning, and an $800 million share dilution overhang.
Act now: the ****** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and GoPro didn't make the cut. Grab the names FREE today.
GoPro (NASDAQ:GPRO) is back in focus this morning as the Markiplier stake disclosure that surfaced Monday extends into a second day of aggressive buying. Shares are up 78% to $1.56 in Tuesday morning trading, pushing the stock back above the $1 line for the first time in weeks.
The move builds on a wild prior session for GoPro. GoPro stock closed Monday's regular session up 46% at $0.88, its best day on record, then added 55% after hours to $1.37, for a combined Monday gain of more than 128%.
#million
SONY and GRMN stayed flat while GPRO's rally masks a 31% revenue decline, a going-concern warning, and an $800 million share dilution overhang.
Act now: the ****** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and GoPro didn't make the cut. Grab the names FREE today.
GoPro (NASDAQ:GPRO) is back in focus this morning as the Markiplier stake disclosure that surfaced Monday extends into a second day of aggressive buying. Shares are up 78% to $1.56 in Tuesday morning trading, pushing the stock back above the $1 line for the first time in weeks.
The move builds on a wild prior session for GoPro. GoPro stock closed Monday's regular session up 46% at $0.88, its best day on record, then added 55% after hours to $1.37, for a combined Monday gain of more than 128%.
#million

19 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
A housing market crash happens when home values plummet due to a lack of demand for or an oversupply of homes. The factors leading to a housing market crash are varied, ranging from economic recessions to high mortgage rates that make it less affordable to buy a home. A housing crash can have upsides (low home prices) and downsides (losing built-up equity and tighter finances).
So, what's ahead for the housing market in 2026?
Read more: Want to buy a house in 2026? Here's what you need to know.
Despite 58% of Gen Z wanting a housing market crash, according to Clever, experts don't foresee one in 2026. If anything, they see a greater sense of normalcy following multiple years of twists and turns.
"We're not heading toward a housing crash; we're in a market correction defined by stability, not volatility," Hoby Hanna, CEO of Howard Hanna Real Estate Services, said via email. "Today's housing environment is fundamentally different from 2008. Homeowners have record levels of equity, lending standards are sound, and inventory remains constrained. What we're seeing now is a normalization, not a collapse, as the market adjusts to new economic realities. For buyers and sellers, this is a market filled with opportunity and resilience, not instability or uncertainty."
#economic #disclosure
A housing market crash happens when home values plummet due to a lack of demand for or an oversupply of homes. The factors leading to a housing market crash are varied, ranging from economic recessions to high mortgage rates that make it less affordable to buy a home. A housing crash can have upsides (low home prices) and downsides (losing built-up equity and tighter finances).
So, what's ahead for the housing market in 2026?
Read more: Want to buy a house in 2026? Here's what you need to know.
Despite 58% of Gen Z wanting a housing market crash, according to Clever, experts don't foresee one in 2026. If anything, they see a greater sense of normalcy following multiple years of twists and turns.
"We're not heading toward a housing crash; we're in a market correction defined by stability, not volatility," Hoby Hanna, CEO of Howard Hanna Real Estate Services, said via email. "Today's housing environment is fundamentally different from 2008. Homeowners have record levels of equity, lending standards are sound, and inventory remains constrained. What we're seeing now is a normalization, not a collapse, as the market adjusts to new economic realities. For buyers and sellers, this is a market filled with opportunity and resilience, not instability or uncertainty."
#economic #disclosure
21 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
When it comes to the relationship one has with their car, you come first; The car comes second.
That's the advice financial guru Dave Ramsey offered Carl from New York when the 29-year-old father called into The Ramsey Show (1).
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Get your free guide from Priority Gold
#ramsey #wealth #carl
When it comes to the relationship one has with their car, you come first; The car comes second.
That's the advice financial guru Dave Ramsey offered Carl from New York when the 29-year-old father called into The Ramsey Show (1).
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Get your free guide from Priority Gold
#ramsey #wealth #carl

21 days ago
I think David Tepper made a mistake selling UnitedHealth Group (NYSE: UNH), and not a small mistake either. When I look at what this company is doing and where healthcare is headed, I would rather buy the stock than walk away.
For context, here's what happened: Tepper is a billionaire hedge fund manager, the founder and president of Appaloosa Management. Tepper didn't trim his stake in UnitedHealth. He sold every share, about 90,000 in total, refocusing his portfolio toward artificial intelligence (AI) with purchases of Amazon (NASDAQ: AMZN), Micron (NASDAQ: MU), and Taiwan Semiconductor (NYSE: TSM), which now account for nearly 40% of his fund. That tells me his move was about concentrating on a narrower theme, not about UnitedHealth losing its edge. In earlier filings, UnitedHealth ranked among his top positions, accounting for more than 10% of the portfolio, indicating he once saw it as a core holding.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
So what changed? The obvious worry is medical cost pressure, especially from GLP‑1 weight loss drugs and broader inflation in care. UnitedHealth's Q2 2026 numbers show medical costs of $75.36 billion and a medical care ratio of 86.7%, down from 89.4% a year earlier but still above the mid-80s range the company had framed as its target (lower is better). Some investors see that as a sign that margins will stay under pressure and that insurers will never fully catch up to medical care's rising cost curve. Tepper may have decided that the headache was not worth the trouble.
When I dig into the details, I see something different. UnitedHealth is not sitting still and hoping costs fall. It's reshaping how care is delivered across its UnitedHealthcare insurance arm and Optum pharmacy management services. On GLP‑1 drugs, the company has drawn a clear line, covering them for diabetes and cardiovascular risk under tight medical necessity rules and restricting coverage for weight loss alone. It has launched programs like Total Weight Support to combine medication with coaching and digital tools, which gives it a way to manage outcomes rather than paying for pills without structure. That kind of strategy matters when drug costs can top $1,000 per member each month.
#medical #costs
For context, here's what happened: Tepper is a billionaire hedge fund manager, the founder and president of Appaloosa Management. Tepper didn't trim his stake in UnitedHealth. He sold every share, about 90,000 in total, refocusing his portfolio toward artificial intelligence (AI) with purchases of Amazon (NASDAQ: AMZN), Micron (NASDAQ: MU), and Taiwan Semiconductor (NYSE: TSM), which now account for nearly 40% of his fund. That tells me his move was about concentrating on a narrower theme, not about UnitedHealth losing its edge. In earlier filings, UnitedHealth ranked among his top positions, accounting for more than 10% of the portfolio, indicating he once saw it as a core holding.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
So what changed? The obvious worry is medical cost pressure, especially from GLP‑1 weight loss drugs and broader inflation in care. UnitedHealth's Q2 2026 numbers show medical costs of $75.36 billion and a medical care ratio of 86.7%, down from 89.4% a year earlier but still above the mid-80s range the company had framed as its target (lower is better). Some investors see that as a sign that margins will stay under pressure and that insurers will never fully catch up to medical care's rising cost curve. Tepper may have decided that the headache was not worth the trouble.
When I dig into the details, I see something different. UnitedHealth is not sitting still and hoping costs fall. It's reshaping how care is delivered across its UnitedHealthcare insurance arm and Optum pharmacy management services. On GLP‑1 drugs, the company has drawn a clear line, covering them for diabetes and cardiovascular risk under tight medical necessity rules and restricting coverage for weight loss alone. It has launched programs like Total Weight Support to combine medication with coaching and digital tools, which gives it a way to manage outcomes rather than paying for pills without structure. That kind of strategy matters when drug costs can top $1,000 per member each month.
#medical #costs

22 days ago
Loomis Sayles, an investment management company, released its "Global Growth Fund" investor letter for Q2 2026. You can download a copy of the letter here. The fund returned 6.43%, underperforming the MSCI ACWI Index's 14.93% return. The fund employs a long-term private equity investment strategy, focusing on high-quality businesses with sustainable competitive advantages, investing at significant discounts to intrinsic value. At quarter-end, the fund maintained an overweight in communication services, consumer discretionary and healthcare sectors, and an underweight in information technology, financials, industrials, and consumer staples sectors. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its Q2 2026 investor letter, Loomis Sayles Global Growth Fund highlighted Trip.com Group Limited (NASDAQ:TCOM). Trip.com Group Limited (NASDAQ:TCOM), a leading online travel services company, detracted from performance during the quarter. On August 21, 2026, Trip.com Group Limited (NASDAQ:TCOM) closed at $46.11 per share, reflecting a market capitalization of $29.04 billion. Trip.com Group Limited (NASDAQ:TCOM) posted a one‑month return of 2.99%, while its shares lost 30.06% over the past 52 weeks.
Loomis Sayles Global Growth Fund stated the following regarding Trip.com Group Limited (NASDAQ:TCOM) in its Q2 2026 investor letter:
"China-based Trip.com Group Limited (NASDAQ:TCOM), formerly known as Ctrip, is among the world's largest global travel platform. Founded in 1999, the company offers a comprehensive, integrated platform on which travelers can make arrangements for lodging, transportation, packaged tours and other related services, including online advertising and financial services, as well as providing corporate travel management services. The company provides its services in China through its Ctrip and Qunar platforms and serves non-Chinese customers primarily thorough Trip.com and Skyscanner. China-related travel accounts for over 85% of revenue, but Trip.com is available in 24 languages and 35 local currencies while Skyscanner is available in over 50 countries and over 35 languages. Trip.com also holds equity interests in other leading travel sites, including Tongcheng-Elong, China's third largest online travel agent (OTA), and MakeMyTrip, the largest OTA in India.…" (Click here to read the full text)
Trip.com Group Limited (NASDAQ:TCOM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 38 hedge fund portfolios held Trip.com Group Limited (NASDAQ:TCOM) at the end of the first quarter, which was 46 in the previous quarter. While we acknowledge the potential of Trip.com Group Limited (NASDAQ:TCOM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on
In its Q2 2026 investor letter, Loomis Sayles Global Growth Fund highlighted Trip.com Group Limited (NASDAQ:TCOM). Trip.com Group Limited (NASDAQ:TCOM), a leading online travel services company, detracted from performance during the quarter. On August 21, 2026, Trip.com Group Limited (NASDAQ:TCOM) closed at $46.11 per share, reflecting a market capitalization of $29.04 billion. Trip.com Group Limited (NASDAQ:TCOM) posted a one‑month return of 2.99%, while its shares lost 30.06% over the past 52 weeks.
Loomis Sayles Global Growth Fund stated the following regarding Trip.com Group Limited (NASDAQ:TCOM) in its Q2 2026 investor letter:
"China-based Trip.com Group Limited (NASDAQ:TCOM), formerly known as Ctrip, is among the world's largest global travel platform. Founded in 1999, the company offers a comprehensive, integrated platform on which travelers can make arrangements for lodging, transportation, packaged tours and other related services, including online advertising and financial services, as well as providing corporate travel management services. The company provides its services in China through its Ctrip and Qunar platforms and serves non-Chinese customers primarily thorough Trip.com and Skyscanner. China-related travel accounts for over 85% of revenue, but Trip.com is available in 24 languages and 35 local currencies while Skyscanner is available in over 50 countries and over 35 languages. Trip.com also holds equity interests in other leading travel sites, including Tongcheng-Elong, China's third largest online travel agent (OTA), and MakeMyTrip, the largest OTA in India.…" (Click here to read the full text)
Trip.com Group Limited (NASDAQ:TCOM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 38 hedge fund portfolios held Trip.com Group Limited (NASDAQ:TCOM) at the end of the first quarter, which was 46 in the previous quarter. While we acknowledge the potential of Trip.com Group Limited (NASDAQ:TCOM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on

23 days ago
While it's still early in its turnaround efforts, Target has begun shifting the narrative away from its recent controversies and back toward its actual stores.
That's evident from the headlines on recent major stories covering its second-quarter earnings.
"A new look and fresh merch are winning customers back at Target as sales rebound," reported the ******* ociated Press.
Reuters took a similar, business-first approach. "Target lifts annual forecasts again as Fiddelke's turnaround takes root," the news agency shared.
That's a change from the narrative that surrounded the chain's recent struggles.
#narrative #associated
That's evident from the headlines on recent major stories covering its second-quarter earnings.
"A new look and fresh merch are winning customers back at Target as sales rebound," reported the ******* ociated Press.
Reuters took a similar, business-first approach. "Target lifts annual forecasts again as Fiddelke's turnaround takes root," the news agency shared.
That's a change from the narrative that surrounded the chain's recent struggles.
#narrative #associated


27 days ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
The federal government mailed nearly identical checks to Walmart and Target this quarter. One of them got applauded. The other got sent to the penalty box.
Walmart's check came to roughly $2.9 billion in tariff refunds, which helped push gross margin to 25.4% and helped the company beat on both revenue and adjusted earnings Thursday. None of that saved the stock, which fell more than 8% the moment investors found comparable sales at 2.6% against the 3.5% the Street wanted. CFO John David Rainey called the business strong. The market called it a miss and moved on.
Target cashed a $994 million version of the same check Wednesday and walked away with the opposite verdict. The refund added $1.65 to a headline EPS of $4.11 that doubled year over year, but strip it out entirely and adjusted EPS still landed at $2.46 against a $2.33 estimate, with comparable sales at 3.8% against 2.4% expected. Target beat with the crutch kicked away. Walmart did not.
One stock. Nvidia-level potential. 30M+ investors trust Moby to find it first. Get the pick. Tap here.
#Stock #walmart #pick #check
The federal government mailed nearly identical checks to Walmart and Target this quarter. One of them got applauded. The other got sent to the penalty box.
Walmart's check came to roughly $2.9 billion in tariff refunds, which helped push gross margin to 25.4% and helped the company beat on both revenue and adjusted earnings Thursday. None of that saved the stock, which fell more than 8% the moment investors found comparable sales at 2.6% against the 3.5% the Street wanted. CFO John David Rainey called the business strong. The market called it a miss and moved on.
Target cashed a $994 million version of the same check Wednesday and walked away with the opposite verdict. The refund added $1.65 to a headline EPS of $4.11 that doubled year over year, but strip it out entirely and adjusted EPS still landed at $2.46 against a $2.33 estimate, with comparable sales at 3.8% against 2.4% expected. Target beat with the crutch kicked away. Walmart did not.
One stock. Nvidia-level potential. 30M+ investors trust Moby to find it first. Get the pick. Tap here.
#Stock #walmart #pick #check

29 days ago
On August 7, Kodiak Gas Services (NYSE:KGS) held its second-quarter 2026 earnings call, and the numbers backed up the excitement. Revenue climbed 21% year-over-year to $391 million, while adjusted EBITDA hit a company record of $217 million, up 22% from a year earlier. Adjusted net income landed at $54 million, or $0.55 per diluted share. Management used the call to lay out how Kodiak plans to turn a compression business already running near full capacity into a much bigger power infrastructure company by 2030.
Kodiak's core contract compression business kept climbing. The company ended the quarter with 4.4 million revenue-generating horsepower and fleet utilization of 98.2%, and it priced that equipment at $23.80 per horsepower, a 4.5% increase from a year ago. Compression infrastructure adjusted gross margin reached 70% for a second straight quarter, up 170 basis points year-over-year, even as the company absorbed higher lube oil costs tied to the war in Iran. Kodiak has already locked in large horsepower compressor packages for 2027 through 2029 and is roughly 50% contracted for next year's deliveries, giving it unusual visibility into future revenue.
The bigger story is power. Kodiak signed a multiyear turbine supply deal with Baker Hughes for 1 gigawatt of capacity by 2030, with an option to grow that to 1.8 gigawatts, and it has secured about 1.8 gigawatts of power generation overall toward its 2-gigawatt target. The current power fleet is about 90% utilized, and the company executed a limited notice to proceed on a West Texas data center project tied to a hyperscaler, invoicing an initial deposit while it negotiates a long-term contract to begin supplying power in early 2027. Total capital spending among the top four hyperscalers rose roughly 80% year over year in the quarter, a demand backdrop Kodiak is positioning to serve.
Power infrastructure remains far less profitable than compression for now. The segment generated $33 million in revenue with an adjusted gross margin of 65%, well below compression's 70%, and building it out is expensive: Kodiak estimates roughly $1.2 million per megawatt before balance of plant costs. Power infrastructure growth capital spending alone was $134 million in the quarter. Net debt stood at about $2.6 billion at quarter-end, and while an $836 million equity raise in May pushed leverage down to 3.1 times, a company-record low, that debt load will grow as gigawatt-scale turbine and power projects come online through 2030. The West Texas data center deal, still under negotiation, also underscores how much of Kodiak's power growth depends on locking in long-term contracts with a small number of hyperscale counterparties.
#million #company #compression
Kodiak's core contract compression business kept climbing. The company ended the quarter with 4.4 million revenue-generating horsepower and fleet utilization of 98.2%, and it priced that equipment at $23.80 per horsepower, a 4.5% increase from a year ago. Compression infrastructure adjusted gross margin reached 70% for a second straight quarter, up 170 basis points year-over-year, even as the company absorbed higher lube oil costs tied to the war in Iran. Kodiak has already locked in large horsepower compressor packages for 2027 through 2029 and is roughly 50% contracted for next year's deliveries, giving it unusual visibility into future revenue.
The bigger story is power. Kodiak signed a multiyear turbine supply deal with Baker Hughes for 1 gigawatt of capacity by 2030, with an option to grow that to 1.8 gigawatts, and it has secured about 1.8 gigawatts of power generation overall toward its 2-gigawatt target. The current power fleet is about 90% utilized, and the company executed a limited notice to proceed on a West Texas data center project tied to a hyperscaler, invoicing an initial deposit while it negotiates a long-term contract to begin supplying power in early 2027. Total capital spending among the top four hyperscalers rose roughly 80% year over year in the quarter, a demand backdrop Kodiak is positioning to serve.
Power infrastructure remains far less profitable than compression for now. The segment generated $33 million in revenue with an adjusted gross margin of 65%, well below compression's 70%, and building it out is expensive: Kodiak estimates roughly $1.2 million per megawatt before balance of plant costs. Power infrastructure growth capital spending alone was $134 million in the quarter. Net debt stood at about $2.6 billion at quarter-end, and while an $836 million equity raise in May pushed leverage down to 3.1 times, a company-record low, that debt load will grow as gigawatt-scale turbine and power projects come online through 2030. The West Texas data center deal, still under negotiation, also underscores how much of Kodiak's power growth depends on locking in long-term contracts with a small number of hyperscale counterparties.
#million #company #compression

1 month ago
Retail investors were steadfast for nearly eight weeks after ******* e Exploration Technologies Corp (NASDAQ:SPCX) went public. Despite a 67% post-IPO rise, a sharp return to earth, and a stock that spent weeks trading below its debut price, mom-and-pop traders continued to buy. On August 7, that streak was finally broken.
According to data quoted by Reuters, individual investors sold a net $4.5 million in ******* e Exploration Technologies Corp (NASDAQ:SPCX) shares on August 7, marking the first day of net negative retail flows since the company's stock market debut on June 12. The timing is what makes the transition interesting. Just two days earlier, on August 5, ******* eX shares fell 13.6% following the company's first quarterly financial report as a publicly traded company, and retail investors responded by buying heavily, marking the fourth-largest single day of net retail purchases since the IPO. That earnings announcement was a mixed bag: ******* eX highlighted faster-than-expected returns from its AI infrastructure spending, though investors were concerned about how long the company's thriving Starlink satellite-internet operation would be able to fund those costly AI ambitions.
While Wall Street expressed concern about Starlink's financial flows supporting long-term AI objectives, Morgan Stanley ******* yst Adam Jonas reiterated an Overweight rating and a $300 price target on ******* e Exploration Technologies Corp (NASDAQ:SPCX). Jonas claimed that public markets undervalue ******* eX's broader AI ecosystem, citing early synergies between Grok and the Cursor as evidence of a combined real-time data, compute, and intelligence platform.
So the trend went as follows: stock plummets on earnings-day AI expenditure fears, retail buys the dip heavily, and then sells when the stock recovers to its IPO price. Sam North, an eToro market ******* yst, described the sequencing as telling. He observed that a shift from persistent buying to selling is rarely due to a single event, but rather to a combination of profit-taking, position fatigue, and investors reevaluating risk-reward. He said that the sale on August 7 appeared to be retail taking advantage of a share price rebound to take some money off the table, instead of a panicked withdrawal.
None of this indicates that retailers have abandoned ******* e Exploration Technologies Corp (NASDAQ:SPCX). The stock was still up around 2.4% in premarket trading on August 10 following the selling milestone, and one day of moderately negative flows after nearly two months of feverish buying is hardly a disaster. That said, for a company whose short public life has been defined almost completely by retail conviction outlasting institutional skepticism, the first break in that conviction, no matter how little, is worth monitoring.
#august #technologies #NASDAQ #investors
According to data quoted by Reuters, individual investors sold a net $4.5 million in ******* e Exploration Technologies Corp (NASDAQ:SPCX) shares on August 7, marking the first day of net negative retail flows since the company's stock market debut on June 12. The timing is what makes the transition interesting. Just two days earlier, on August 5, ******* eX shares fell 13.6% following the company's first quarterly financial report as a publicly traded company, and retail investors responded by buying heavily, marking the fourth-largest single day of net retail purchases since the IPO. That earnings announcement was a mixed bag: ******* eX highlighted faster-than-expected returns from its AI infrastructure spending, though investors were concerned about how long the company's thriving Starlink satellite-internet operation would be able to fund those costly AI ambitions.
While Wall Street expressed concern about Starlink's financial flows supporting long-term AI objectives, Morgan Stanley ******* yst Adam Jonas reiterated an Overweight rating and a $300 price target on ******* e Exploration Technologies Corp (NASDAQ:SPCX). Jonas claimed that public markets undervalue ******* eX's broader AI ecosystem, citing early synergies between Grok and the Cursor as evidence of a combined real-time data, compute, and intelligence platform.
So the trend went as follows: stock plummets on earnings-day AI expenditure fears, retail buys the dip heavily, and then sells when the stock recovers to its IPO price. Sam North, an eToro market ******* yst, described the sequencing as telling. He observed that a shift from persistent buying to selling is rarely due to a single event, but rather to a combination of profit-taking, position fatigue, and investors reevaluating risk-reward. He said that the sale on August 7 appeared to be retail taking advantage of a share price rebound to take some money off the table, instead of a panicked withdrawal.
None of this indicates that retailers have abandoned ******* e Exploration Technologies Corp (NASDAQ:SPCX). The stock was still up around 2.4% in premarket trading on August 10 following the selling milestone, and one day of moderately negative flows after nearly two months of feverish buying is hardly a disaster. That said, for a company whose short public life has been defined almost completely by retail conviction outlasting institutional skepticism, the first break in that conviction, no matter how little, is worth monitoring.
#august #technologies #NASDAQ #investors
1 month ago
According to a recent report from the Financial Industry Regulatory Authority (FINRA), 61% of social media users and "finfluencer" followers aged 18 to 34 have made an investment decision based on recommendations from a social media personality -- and these folks also reported "substantially higher fraud exposure and victimization."
A lot of financial advice found on social media is worth what you paid for it -- nothing. Here's a look at several bits of advice I've run across that are simply wrong or misleading.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
One social media pontificator said: "The stock market is one of the best tools to grow your wealth." That's very true. Over decades, it beats most other alternatives. They added that a 10% return doubles your money every 7.2 years, and a 20% return doubles your money every 3.6 years. That, too, is true -- it's the classic "Rule of 72."
The problem, though, is the suggestion that you can expect stock market returns of 20% annually. The stock market has averaged annual returns of close to 10% over many decades, not 20%. There are some years with massive gains, and some with sharp drops. But overall, expectations should be tempered.
#advice
A lot of financial advice found on social media is worth what you paid for it -- nothing. Here's a look at several bits of advice I've run across that are simply wrong or misleading.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
One social media pontificator said: "The stock market is one of the best tools to grow your wealth." That's very true. Over decades, it beats most other alternatives. They added that a 10% return doubles your money every 7.2 years, and a 20% return doubles your money every 3.6 years. That, too, is true -- it's the classic "Rule of 72."
The problem, though, is the suggestion that you can expect stock market returns of 20% annually. The stock market has averaged annual returns of close to 10% over many decades, not 20%. There are some years with massive gains, and some with sharp drops. But overall, expectations should be tempered.
#advice

1 month ago
Entrepreneur Media LLC and Yahoo Finance LLC may earn commission or revenue on some products and services through the links below.
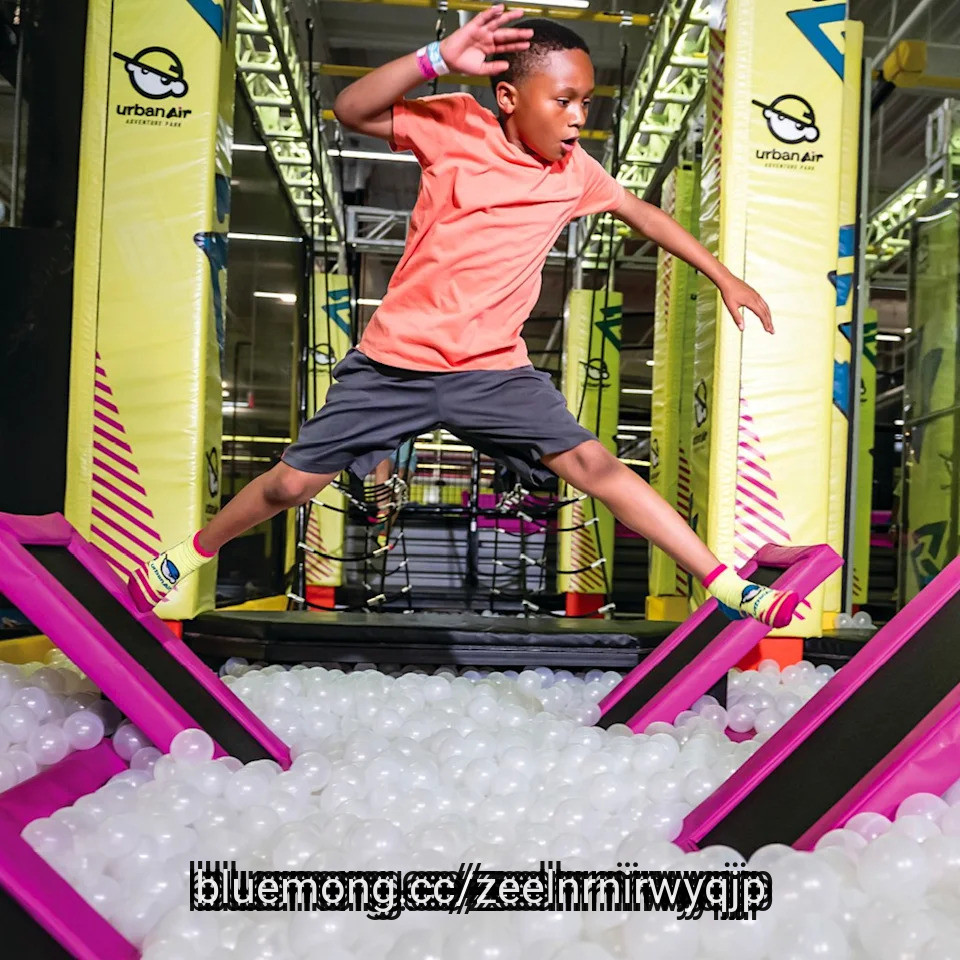
Michael Browning Jr. is the founder and CEO of Unleashed Brands, the $1 billion youth enrichment platform company that includes Urban Air, The Little Gym and Sylvan Learning.
Unleashed Brands has more than 1,600 locations nationwide and serves more than 25 million people.
In 2025, Unleashed Brands opened 133 new franchise locations with more than 200 franchises in development.
When Michael Browning Jr. tried to launch a trampoline park in 2011, every bank and investor rejected him. His age was a factor — he was 26 years old at the time. Investors said he was too young and that his idea would never work.
#unleashed #browning #finance #little
Michael Browning Jr. is the founder and CEO of Unleashed Brands, the $1 billion youth enrichment platform company that includes Urban Air, The Little Gym and Sylvan Learning.
Unleashed Brands has more than 1,600 locations nationwide and serves more than 25 million people.
In 2025, Unleashed Brands opened 133 new franchise locations with more than 200 franchises in development.
When Michael Browning Jr. tried to launch a trampoline park in 2011, every bank and investor rejected him. His age was a factor — he was 26 years old at the time. Investors said he was too young and that his idea would never work.
#unleashed #browning #finance #little


1 month ago
If history is any helpful guide, then ***** eX (SPCX) shares haven't bottomed yet.
Looking at major IPOs over the past 15 years, 19 of the 31 (61%) saw a maximum drawdown of more than 50% in their first year of trading, per Truist chief markets strategist Keith Lerner. The largest first-year drop belongs to Robinhood (HOOD), with a decline of 90%.
SpaceX is already worse relative to the averages.
The stock finished its first week down 4% and its first month off by 16%, both severe underperformance versus the average for each period. The max drawdown on the stock so far this year has amounted to 46%, better than the average decline of 55%.
SpaceX did its part in sparking this debate today.
#spcx
Looking at major IPOs over the past 15 years, 19 of the 31 (61%) saw a maximum drawdown of more than 50% in their first year of trading, per Truist chief markets strategist Keith Lerner. The largest first-year drop belongs to Robinhood (HOOD), with a decline of 90%.
SpaceX is already worse relative to the averages.
The stock finished its first week down 4% and its first month off by 16%, both severe underperformance versus the average for each period. The max drawdown on the stock so far this year has amounted to 46%, better than the average decline of 55%.
SpaceX did its part in sparking this debate today.
#spcx


1 month ago
After making several moves this year to win back customers, Home Depot is making headlines again over a lawsuit that alleges it violated customers' rights.
In 2025, the home-improvement giant had a ******* py year, marked by several consumer boycotts over its decision to cut its diversity, equity, and inclusion policies; its alleged cooperation with ICE's immigration crackdown; and price hikes to address tariff pressures.
In 2026, it turned a new leaf by making several moves to lure shoppers back to its stores and offerings. Home Depot made a major expansion of its "Pro" ecosystem with high-tech tools such as an AI-powered Material List Builder and a first-of-its-kind real-time GPS delivery tracker for bulky materials. It also improved the physical store experience with Wahlburger's food trailers and expanded its rewards program.
Now, the home improvement retailer is facing legal challenges after being accused of using its customers' personal data without their consent.
A new class action lawsuit accuses Home Depot of selling customers' personally identifiable information (PII) to third parties without providing notice or obtaining their consent.
#year
In 2025, the home-improvement giant had a ******* py year, marked by several consumer boycotts over its decision to cut its diversity, equity, and inclusion policies; its alleged cooperation with ICE's immigration crackdown; and price hikes to address tariff pressures.
In 2026, it turned a new leaf by making several moves to lure shoppers back to its stores and offerings. Home Depot made a major expansion of its "Pro" ecosystem with high-tech tools such as an AI-powered Material List Builder and a first-of-its-kind real-time GPS delivery tracker for bulky materials. It also improved the physical store experience with Wahlburger's food trailers and expanded its rewards program.
Now, the home improvement retailer is facing legal challenges after being accused of using its customers' personal data without their consent.
A new class action lawsuit accuses Home Depot of selling customers' personally identifiable information (PII) to third parties without providing notice or obtaining their consent.
#year

1 month ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Rising gas prices has helped electric vehicle sales in the United States and globally. New data shows just how much demand there is for electric vehicles, especially outside the U.S.
Global electric vehicle sales were up 35% in the second quarter, compared to the first quarter, according to newly released data from the International Energy Agency (IEA).
Data, shared by Electrek, shows that EV sales dominated in the second quarter while overall global car sales were down 5% year-over-year in the first half of the year.
Don't Miss:
#sales #second
Rising gas prices has helped electric vehicle sales in the United States and globally. New data shows just how much demand there is for electric vehicles, especially outside the U.S.
Global electric vehicle sales were up 35% in the second quarter, compared to the first quarter, according to newly released data from the International Energy Agency (IEA).
Data, shared by Electrek, shows that EV sales dominated in the second quarter while overall global car sales were down 5% year-over-year in the first half of the year.
Don't Miss:
#sales #second

2 months ago
Vertiv (NYSE:VRT) primarily generates revenue by designing, manufacturing, and servicing critical power and thermal management systems for data centers and communication networks.
It recently acquired ThermoKey and Strategic Thermal Labs to expand its liquid cooling capabilities, and it reported a 15% net income margin for the quarter ended June 30, 2026.
BWX Technologies (NYSE:BWXT) primarily generates revenue by producing precision naval and critical nuclear components for the United States government and commercial power sectors.
While securing contracts exceeding $1.4 billion from the United States Naval Nuclear Propulsion Program, it recorded an 11% net income margin for the quarter ended March 31, 2026.
Revenue gives investors insight into the total demand for a company's products and services before expenses are deducted. Tracking this figure helps investors understand the scale and top-line growth trajectory of a business.
#revenue #NYSE #naval #critical
It recently acquired ThermoKey and Strategic Thermal Labs to expand its liquid cooling capabilities, and it reported a 15% net income margin for the quarter ended June 30, 2026.
BWX Technologies (NYSE:BWXT) primarily generates revenue by producing precision naval and critical nuclear components for the United States government and commercial power sectors.
While securing contracts exceeding $1.4 billion from the United States Naval Nuclear Propulsion Program, it recorded an 11% net income margin for the quarter ended March 31, 2026.
Revenue gives investors insight into the total demand for a company's products and services before expenses are deducted. Tracking this figure helps investors understand the scale and top-line growth trajectory of a business.
#revenue #NYSE #naval #critical

2 months ago
By Lucia Mutikani
WASHINGTON, July 28 (Reuters) - The U.S. trade deficit in goods narrowed in June amid a broad decline in imports, but the improvement was probably insufficient to prevent trade from again subtracting from economic growth in the second quarter.
The report from the Commerce Department on Tuesday also showed exports dropping to a five-month low, pulled down by a sharp decline in shipments of industrial supplies, which include petroleum. The decrease likely reflected a pullback in crude oil prices amid a fragile ceasefire between the U.S. and Iran.
With businesses ramping up investment in artificial intelligence and consumer spending resilient, last month's drop in imports could be temporary. The AI build-out is reliant on imports. The government on Monday reported a strong increase in orders and shipments for non-defense capital goods in June.
"Our model mapping the trade data onto the national accounts now points to net trade subtracting around one percentage point from second-quarter GDP growth," said Oliver Allen, senior U.S. economist at Pantheon Macroeconomics.
#goods
WASHINGTON, July 28 (Reuters) - The U.S. trade deficit in goods narrowed in June amid a broad decline in imports, but the improvement was probably insufficient to prevent trade from again subtracting from economic growth in the second quarter.
The report from the Commerce Department on Tuesday also showed exports dropping to a five-month low, pulled down by a sharp decline in shipments of industrial supplies, which include petroleum. The decrease likely reflected a pullback in crude oil prices amid a fragile ceasefire between the U.S. and Iran.
With businesses ramping up investment in artificial intelligence and consumer spending resilient, last month's drop in imports could be temporary. The AI build-out is reliant on imports. The government on Monday reported a strong increase in orders and shipments for non-defense capital goods in June.
"Our model mapping the trade data onto the national accounts now points to net trade subtracting around one percentage point from second-quarter GDP growth," said Oliver Allen, senior U.S. economist at Pantheon Macroeconomics.
#goods

2 months ago
If you hold shares in the AI software firm, you're already carrying the full weight of a market pricing an exceptionally broad range of futures for the company.
Palantir Technologies (PLTR) is a stock that inspires fierce debate. But what if you could see a price tag on that very uncertainty? The options market provides just that, and right now, it's pricing a remarkably wide field of possibilities for PLTR over the coming year. If you own the stock, you own this risk, whether you trade options or not.
How the Market Is Pricing Both A Steep Drop And A Sharp Rally
Based on its options, the market is pricing a 68% probability that Palantir stock, trading today around $124.57, will end up somewhere between a floor near $70 and a ceiling near $221 over the next year. That's not a prediction, but a measure of the risk you're carrying. A move to that ceiling would represent a 77% gain from here. A drop to the floor would be a 44% loss. The key takeaway for a shareholder is the sheer size of that two-sided swing.
Why the Market Is Pricing More Risk Than Usual
#drop
Palantir Technologies (PLTR) is a stock that inspires fierce debate. But what if you could see a price tag on that very uncertainty? The options market provides just that, and right now, it's pricing a remarkably wide field of possibilities for PLTR over the coming year. If you own the stock, you own this risk, whether you trade options or not.
How the Market Is Pricing Both A Steep Drop And A Sharp Rally
Based on its options, the market is pricing a 68% probability that Palantir stock, trading today around $124.57, will end up somewhere between a floor near $70 and a ceiling near $221 over the next year. That's not a prediction, but a measure of the risk you're carrying. A move to that ceiling would represent a 77% gain from here. A drop to the floor would be a 44% loss. The key takeaway for a shareholder is the sheer size of that two-sided swing.
Why the Market Is Pricing More Risk Than Usual
#drop

2 months ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
In 2025, victims lost $3.5 billion to imposter scams (1). Now, CBS News chief correspondent Matt Gutman nearly became a victim of one of those scams.
"I just got SCAMMED," Matt Gutman posted in a video on X on July 10 (2).
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan still sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Learn more with a free guide from Priority Gold
#Gold #scammed
In 2025, victims lost $3.5 billion to imposter scams (1). Now, CBS News chief correspondent Matt Gutman nearly became a victim of one of those scams.
"I just got SCAMMED," Matt Gutman posted in a video on X on July 10 (2).
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan still sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Learn more with a free guide from Priority Gold
#Gold #scammed

2 months ago
Visa (V) trades at $360.57 per share on a $651.9B market cap and 29.3x trailing earnings. Under a conservative 3-year scenario, the math points to roughly 42% of upside. Revenue compounding does most of the work in our scenario. Here is the picture the math sits on top of:
Where V Stands Today
Valuation: P/E of 29.3 versus a 3-year average of 29.8 and a 3-year high of 33.9.
Revenue: Revenue grew 14.4% over the last twelve months, with a 3-year CAGR of 11.6%.
Net Margin: Running at 52% LTM, against a 3-year average of 53% and a 3-year peak of 55%.
#Visa
Where V Stands Today
Valuation: P/E of 29.3 versus a 3-year average of 29.8 and a 3-year high of 33.9.
Revenue: Revenue grew 14.4% over the last twelve months, with a 3-year CAGR of 11.6%.
Net Margin: Running at 52% LTM, against a 3-year average of 53% and a 3-year peak of 55%.
#Visa

2 months ago
What happened: AMC Entertainment (AMC) stock jumped more than 20% on Monday.
What's behind the move: The movie theater chain reported quarterly record revenue of of $1.6 billion along with an all-time high Adjusted EBITDA, a measure of core operating earnings and cash-generating strength.
"In AMC's entire 106-year history, there has never been a quarter like this one," said AMC CEO Adam Aron during the company's earnings call on Monday morning.
Aron also pushed against "the prognosticators of doom who have continued to vastly underestimate the will and the skill of AMC" as the company navigated six years of challenges.
The quarter benefited from major releases that brought moviegoers back into theaters, including The Super Mario Galaxy Movie and The Odyssey.
What's behind the move: The movie theater chain reported quarterly record revenue of of $1.6 billion along with an all-time high Adjusted EBITDA, a measure of core operating earnings and cash-generating strength.
"In AMC's entire 106-year history, there has never been a quarter like this one," said AMC CEO Adam Aron during the company's earnings call on Monday morning.
Aron also pushed against "the prognosticators of doom who have continued to vastly underestimate the will and the skill of AMC" as the company navigated six years of challenges.
The quarter benefited from major releases that brought moviegoers back into theaters, including The Super Mario Galaxy Movie and The Odyssey.


2 months ago
Intuitive Surgical, Inc. (NASDAQ:ISRG) is one of the 8 Worst Blue Chip Stocks to Buy Now.
On July 9, 2026, BMO Capital ****** yst Vik Chopra initiated coverage of Intuitive Surgical, Inc. (NASDAQ:ISRG) with an Outperform rating and $518 price target. Chopra said the da Vinci 5 upgrade cycle remains in the early innings, procedure growth is broadening into new specialties and geographies, and the earnings stream is "durable and visible."
On July 6, Evercore ISI lowered the firm's price target on Intuitive Surgical to $430 from $480 and kept an In Line rating on the shares. Evercore ISI said its Q2 preview for MedTech, Life Sciences Tools, and Diagnostics highlights generally healthy procedure volumes and capital expenditure trends across the sector.
Last month, BofA ****** yst Travis Steed lowered the firm's price target on Intuitive Surgical to $515 from $520 and kept a Buy rating on the shares. Steed noted that BofA's services team continues to highlight a lower utilization environment and took a more conservative view on 2027 medtech company estimates, given that valuations already reflect utilization risk. Steed also ****** umed inflation will be more of a headwind in 2027, with less margin expansion for medtech, and lowered 2027 estimates across the firm's larger-cap coverage with exposure to utilization and inflation.
Intuitive Surgical, Inc. (NASDAQ:ISRG) develops, manufactures, and markets products that enable physicians and healthcare providers to enhance the quality of and access to minimally invasive care in the United States and internationally.
On July 9, 2026, BMO Capital ****** yst Vik Chopra initiated coverage of Intuitive Surgical, Inc. (NASDAQ:ISRG) with an Outperform rating and $518 price target. Chopra said the da Vinci 5 upgrade cycle remains in the early innings, procedure growth is broadening into new specialties and geographies, and the earnings stream is "durable and visible."
On July 6, Evercore ISI lowered the firm's price target on Intuitive Surgical to $430 from $480 and kept an In Line rating on the shares. Evercore ISI said its Q2 preview for MedTech, Life Sciences Tools, and Diagnostics highlights generally healthy procedure volumes and capital expenditure trends across the sector.
Last month, BofA ****** yst Travis Steed lowered the firm's price target on Intuitive Surgical to $515 from $520 and kept a Buy rating on the shares. Steed noted that BofA's services team continues to highlight a lower utilization environment and took a more conservative view on 2027 medtech company estimates, given that valuations already reflect utilization risk. Steed also ****** umed inflation will be more of a headwind in 2027, with less margin expansion for medtech, and lowered 2027 estimates across the firm's larger-cap coverage with exposure to utilization and inflation.
Intuitive Surgical, Inc. (NASDAQ:ISRG) develops, manufactures, and markets products that enable physicians and healthcare providers to enhance the quality of and access to minimally invasive care in the United States and internationally.

2 months ago
By
Updated July 16, 2026 9:05 am ET
Listen
(1 min)
GE Aerospace GE 1.87%
increase; up pointing triangle
raised its outlook for the full year, but said supply-chain issues are still resulting in slower production and delivery delays.
Updated July 16, 2026 9:05 am ET
Listen
(1 min)
GE Aerospace GE 1.87%
increase; up pointing triangle
raised its outlook for the full year, but said supply-chain issues are still resulting in slower production and delivery delays.

2 months ago
With a market cap of $78.9 billion, Illinois Tool Works Inc. (ITW) is a global multi-industrial manufacturing company, recognized for delivering innovative, customer-focused solutions across seven industry-leading business segments. Guided by the ITW Business Model, the company empowers approximately 43,000 employees worldwide to drive sustainable growth, industry-leading margins, and strong returns through its decentralized and entrepreneurial culture.
The Glenview, Illinois-based company is expected to release its fiscal Q2 2026 results soon. Ahead of this event, ***** ysts project Illinois Tool Works to report an EPS of $2.80, an 8.5% rise from $2.58 in the year-ago quarter. It has exceeded Wall Street's bottom-line estimates in each of the last four quarters.
Broadcom's Largest AI Customer Is Fleeing to MediaTek. AVGO Stock Is Still a Buy.
Nasdaq Futures Plunge as Samsung Sparks Chip Selloff
Mark Cuban Asks What If You Didn't Need Health Insurance — And Hospitals Just Treated You, Then Took 10% of Your Pay?
The Glenview, Illinois-based company is expected to release its fiscal Q2 2026 results soon. Ahead of this event, ***** ysts project Illinois Tool Works to report an EPS of $2.80, an 8.5% rise from $2.58 in the year-ago quarter. It has exceeded Wall Street's bottom-line estimates in each of the last four quarters.
Broadcom's Largest AI Customer Is Fleeing to MediaTek. AVGO Stock Is Still a Buy.
Nasdaq Futures Plunge as Samsung Sparks Chip Selloff
Mark Cuban Asks What If You Didn't Need Health Insurance — And Hospitals Just Treated You, Then Took 10% of Your Pay?


3 months ago
Lennox International Inc. (LII), headquartered in Richardson, Texas, designs, manufactures, and markets products for the heating, ventilation, air conditioning, and refrigeration markets. Valued at $19.8 billion by market cap, the company sells its products and services through direct sales, distributors, and company-owned parts and supplies stores. The leader in energy-efficient climate-control solutions is expected to announce its fiscal second-quarter earnings for 2026 in the near term.
Ahead of the event, ***** ysts expect LII to report a profit of $7.60 per share on a diluted basis, down 2.8% from $7.82 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
Dear Microsoft Stock Fans, Mark Your Calendars for August 1
Heavy Advanced Micro Devices Call Options Volume Today - Is AMD Undervalued?
From Zero to $15 Billion, Qualcomm's AI Roadmap Gets a Boost From Modular Acquisition
Ahead of the event, ***** ysts expect LII to report a profit of $7.60 per share on a diluted basis, down 2.8% from $7.82 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
Dear Microsoft Stock Fans, Mark Your Calendars for August 1
Heavy Advanced Micro Devices Call Options Volume Today - Is AMD Undervalued?
From Zero to $15 Billion, Qualcomm's AI Roadmap Gets a Boost From Modular Acquisition






