

3 days ago
Extreme weather is creating a more demanding environment for property owners, insurers, and communities. According to the National Centers for Environmental Information (NCEI), the United States recorded 27 confirmed billion-dollar weather and climate disasters in 2024, resulting in a total cost of $182.7 billion. These events spanned a wide range of extremes, including severe storm events, tropical cyclones, wildfires, drought/heat waves, and winter storm/cold wave events. Over the last decade, ***** ulative losses from these disasters have exceeded $1.4 trillion, driven significantly by population growth, material wealth, and increased development in hazard-prone areas. These figures suggest that the financial consequences of extreme events may increasingly depend on how accurately the value of exposed property is understood before a loss occurs.
That question becomes especially consequential during reconstruction. A 2026 report from Bloomberg, featured in Claims Journal, noted that surveys conducted by United Policyholders since 2007 found an average of two-thirds of wildfire survivors reporting that they were underinsured, with an average shortfall of $200,000 or more. The Insurance Information Institute has similarly estimated that two-thirds of American homeowners may be underinsured for wildfire losses, typically by about 20%, and in some cases by as much as 60%. These findings illustrate how the presence of an insurance policy can still leave a substantial difference between available coverage and the resources required to rebuild, particularly when construction costs rise after a catastrophe.
The financial implications can extend across the broader insurance ecosystem. Aon's 2026 Climate and Catastrophe Insight reported approximately $260 billion in global economic losses from natural catastrophes during 2025, compared with $127 billion in insured losses. For property stakeholders, such a figure may place greater attention on the relationship between the value ***** igned to an ***** et, the cost of restoring it, and the capital available when a loss occurs.
Frequency can add another layer to that calculation. Data from NCEI indicate that the average interval between U.S. billion-dollar disaster events was approximately 16 days during 2020–2024, compared with 82 days during the 1980s. NCEI notes that shorter intervals can leave less time and fewer resources for response, recovery, and preparation for subsequent events. As the time between major events contracts, property valuations may require more frequent attention because construction costs, labor conditions, materials, and local economic circumstances can change between policy reviews.
#property #losses #insurance #information
That question becomes especially consequential during reconstruction. A 2026 report from Bloomberg, featured in Claims Journal, noted that surveys conducted by United Policyholders since 2007 found an average of two-thirds of wildfire survivors reporting that they were underinsured, with an average shortfall of $200,000 or more. The Insurance Information Institute has similarly estimated that two-thirds of American homeowners may be underinsured for wildfire losses, typically by about 20%, and in some cases by as much as 60%. These findings illustrate how the presence of an insurance policy can still leave a substantial difference between available coverage and the resources required to rebuild, particularly when construction costs rise after a catastrophe.
The financial implications can extend across the broader insurance ecosystem. Aon's 2026 Climate and Catastrophe Insight reported approximately $260 billion in global economic losses from natural catastrophes during 2025, compared with $127 billion in insured losses. For property stakeholders, such a figure may place greater attention on the relationship between the value ***** igned to an ***** et, the cost of restoring it, and the capital available when a loss occurs.
Frequency can add another layer to that calculation. Data from NCEI indicate that the average interval between U.S. billion-dollar disaster events was approximately 16 days during 2020–2024, compared with 82 days during the 1980s. NCEI notes that shorter intervals can leave less time and fewer resources for response, recovery, and preparation for subsequent events. As the time between major events contracts, property valuations may require more frequent attention because construction costs, labor conditions, materials, and local economic circumstances can change between policy reviews.
#property #losses #insurance #information

11 days ago
On August 10, Joe Gomes from ***** le Capital reiterated his Outperform rating on CoreCivic Inc. (NYSE:CXW). In the process, the ***** yst increased his target price on the stock from $35 to $42, resulting in a revised upside potential in excess of 24% based on stock's closing price on August 27. This upward adjustment in price target came after an impressive second quarter print above management estimates. Let's explore the underlying drivers of this outperformance, and which additional factors are expected to shape up investor sentiment toward the stock.
Earlier in August, the company reported its second quarter results which exceeded management's expectations. Topline figures were recorded at $684.9 million, up by 27.3% compared to Q2 2025. Adjusted EBITDA of $109.4 million exhibited 5.9% year-on-year growth, while adjusted diluted EPS of $0.38 reflected a 5.6% growth compared to the same period last year. Such expansion in adjusted diluted EPS was supported by lower operating costs and slightly higher ICE populations, while strong federal revenue also contributed to growth. Following the quarter and subsequent facility sales, management raised its full-year 2026 guidance.
During 2026, CoreCivic has been focusing on strengthening its financial position while expanding its footprint as a federal detention operator. The company generated $734 million in gross proceeds from sales of Prairie Correctional Facility and Midwest Regional Reception Center, to the Department of Homeland Security. It expects to continue to operate both facilities under current arrangements, and was also awarded a new ICE contract to operate the 1,600 bed Prairie Correctional Facility till August 2031. The contract award offers potential for $75 million in revenue boost in the future once fully activated, with no material impact expected during 2026.
CoreCivic can benefit from this demand tailwind without the time and capital required to construct entirely new facilities, although activating idle sites still involves staffing and start-up costs. It also strengthens the company's position as a trusted partner for federal detention requirements, and might create potential opportunities for more contracts in the future.
The company has also taken an aggressive approach toward debt reduction and returning capital to shareholders. On August 10, it entered a $500 million accelerated share repurchase agreement, supported by the proceeds from recent facility sales. A portion of those sale proceeds was also utilized for $608.5 million debt repayment, which included early redemption of senior notes that were due in 2027.
#price
Earlier in August, the company reported its second quarter results which exceeded management's expectations. Topline figures were recorded at $684.9 million, up by 27.3% compared to Q2 2025. Adjusted EBITDA of $109.4 million exhibited 5.9% year-on-year growth, while adjusted diluted EPS of $0.38 reflected a 5.6% growth compared to the same period last year. Such expansion in adjusted diluted EPS was supported by lower operating costs and slightly higher ICE populations, while strong federal revenue also contributed to growth. Following the quarter and subsequent facility sales, management raised its full-year 2026 guidance.
During 2026, CoreCivic has been focusing on strengthening its financial position while expanding its footprint as a federal detention operator. The company generated $734 million in gross proceeds from sales of Prairie Correctional Facility and Midwest Regional Reception Center, to the Department of Homeland Security. It expects to continue to operate both facilities under current arrangements, and was also awarded a new ICE contract to operate the 1,600 bed Prairie Correctional Facility till August 2031. The contract award offers potential for $75 million in revenue boost in the future once fully activated, with no material impact expected during 2026.
CoreCivic can benefit from this demand tailwind without the time and capital required to construct entirely new facilities, although activating idle sites still involves staffing and start-up costs. It also strengthens the company's position as a trusted partner for federal detention requirements, and might create potential opportunities for more contracts in the future.
The company has also taken an aggressive approach toward debt reduction and returning capital to shareholders. On August 10, it entered a $500 million accelerated share repurchase agreement, supported by the proceeds from recent facility sales. A portion of those sale proceeds was also utilized for $608.5 million debt repayment, which included early redemption of senior notes that were due in 2027.
#price
12 days ago
Broadcom (AVGO) reported fiscal third-quarter results after the close on Wednesday, September 2, delivering a beat on both revenue and earnings but failing to impress investors with its forward outlook.
The stock fell more than 3% in after-hours trading, extending what has been a disappointing year for shareholders, with AVGO up only about 1% year-to-date against a 64% gain for the broader PHLX Semiconductor Index.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ******* eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#wednesday #phlx
The stock fell more than 3% in after-hours trading, extending what has been a disappointing year for shareholders, with AVGO up only about 1% year-to-date against a 64% gain for the broader PHLX Semiconductor Index.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ******* eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#wednesday #phlx

13 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Why we like it: The Discover it Cash Back is our top choice because it was the highest-ranking Discover card in the cash-back, 0% APR, balance transfer, and rewards categories. This is definitely due to its high-quality benefits and features, such as 0% intro APR offers, a generous welcome bonus, and an elevated rewards rate — all with a $0 annual fee.
Read our full Discover it Cash Back Credit Card review
Why we like it: The Discover it Miles is a straightforward travel rewards card that makes earning miles on any eligible purchase easy. You don't have to worry about different spending categories since you get 1.5x miles on all qualifying purchases. As a new cardholder, you can also take advantage of the generous Discover Match welcome bonus.
Read our full Discover it Miles review
#discover #card #rewards #offers
Why we like it: The Discover it Cash Back is our top choice because it was the highest-ranking Discover card in the cash-back, 0% APR, balance transfer, and rewards categories. This is definitely due to its high-quality benefits and features, such as 0% intro APR offers, a generous welcome bonus, and an elevated rewards rate — all with a $0 annual fee.
Read our full Discover it Cash Back Credit Card review
Why we like it: The Discover it Miles is a straightforward travel rewards card that makes earning miles on any eligible purchase easy. You don't have to worry about different spending categories since you get 1.5x miles on all qualifying purchases. As a new cardholder, you can also take advantage of the generous Discover Match welcome bonus.
Read our full Discover it Miles review
#discover #card #rewards #offers

22 days ago
Madison Investments, an investment advisor, released its second-quarter 2026 investor letter for the "Madison Large Cap Fund". A copy of the letter can be downloaded here. In the second quarter, U.S. stock market indices achieved their best performance since 2020, driven largely by a narrow group of Artificial Intelligence-related stocks. As in the pandemic's early days, investors are fixated on who will benefit from AI, reminiscent of the late 1990s internet bubble. Against this backdrop, The Madison Large Cap Fund (class I) returned 8.4% in the second quarter of 2026, compared to a 15.2% increase in the S&P 500 Index. The current market's extreme narrowness is concerning, and history suggests this won't persist. While AI is reshaping society and the economy, today's winners may not remain so, and booms could lead to busts. Additionally, factors such as a volatile federal administration, growing budget deficits, inflation, high interest rates, and strained consumer finances will significantly impact the economy and stock market in the future. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Madison Large Cap Fund highlighted Honeywell Aerospace Inc. (NASDAQ:HONA) as a new holding. Honeywell Aerospace Inc. (NASDAQ:HONA), spun off from Honeywell International in June 2026, manufactures and supplies aircraft components, avionics, engines, and systems. On August 21, 2026, Honeywell Aerospace Inc. (NASDAQ:HONA) closed at $164.73 per share, reflecting a market capitalization of $52.21 billion. Honeywell Aerospace Inc. (NASDAQ:HONA) posted a one‑month return of ‑21.87%.
Madison Large Cap Fund stated the following regarding Honeywell Aerospace Inc. (NASDAQ:HONA) in its Q2 2026 investor letter:
"Honeywell Aerospace Inc. (NASDAQ:HONA) is a leading aerospace and defense supplier, supporting OEM, government, and aircraft operator customers. The company's products sit on a wide variety of aerospace programs with approximately 90% of in-service aircraft today having Honeywell Aerospace content. The separation from Honeywell International should enhance an already high-quality business as management compensation and capital allocation will be better tailored to the specific needs of the business. We believe the combination of attractive growth outlook, improved incentives, and optimized capital allocation is underappreciated."
Honeywell Aerospace Inc. (NASDAQ:HONA) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. While we acknowledge the potential of Honeywell Aerospace Inc. (NASDAQ:HONA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#honeywell #fund
In its Q2 2026 investor letter, Madison Large Cap Fund highlighted Honeywell Aerospace Inc. (NASDAQ:HONA) as a new holding. Honeywell Aerospace Inc. (NASDAQ:HONA), spun off from Honeywell International in June 2026, manufactures and supplies aircraft components, avionics, engines, and systems. On August 21, 2026, Honeywell Aerospace Inc. (NASDAQ:HONA) closed at $164.73 per share, reflecting a market capitalization of $52.21 billion. Honeywell Aerospace Inc. (NASDAQ:HONA) posted a one‑month return of ‑21.87%.
Madison Large Cap Fund stated the following regarding Honeywell Aerospace Inc. (NASDAQ:HONA) in its Q2 2026 investor letter:
"Honeywell Aerospace Inc. (NASDAQ:HONA) is a leading aerospace and defense supplier, supporting OEM, government, and aircraft operator customers. The company's products sit on a wide variety of aerospace programs with approximately 90% of in-service aircraft today having Honeywell Aerospace content. The separation from Honeywell International should enhance an already high-quality business as management compensation and capital allocation will be better tailored to the specific needs of the business. We believe the combination of attractive growth outlook, improved incentives, and optimized capital allocation is underappreciated."
Honeywell Aerospace Inc. (NASDAQ:HONA) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. While we acknowledge the potential of Honeywell Aerospace Inc. (NASDAQ:HONA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#honeywell #fund

23 days ago
Berkshire Hathaway's (BRK.A, BRK.B) second 13F filing of the Greg Abel CEO era came with a big surprise in a massive expansion of its Alphabet (GOOG) stake.
Warren Buffett's investing juggernaut raised its position by 83% to nearly 106 million shares worth $38 billion, making Google's parent its third-largest stock holding behind Apple (AAPL) and American Express (AXP).
Tucked inside that Alphabet bet is an unexpected connection to Elon Musk's ****** eX (SPCX).
Buffett never invested in ****** eX or Tesla (TSLA), despite Musk courting his backing for years.
On the flip side, Alphabet has been a major investor in ****** eX since 2015, and as of June 30, it owned nearly 4% of ****** eX, a position valued at $94 billion, according to Reuters.
#abel #goog
Warren Buffett's investing juggernaut raised its position by 83% to nearly 106 million shares worth $38 billion, making Google's parent its third-largest stock holding behind Apple (AAPL) and American Express (AXP).
Tucked inside that Alphabet bet is an unexpected connection to Elon Musk's ****** eX (SPCX).
Buffett never invested in ****** eX or Tesla (TSLA), despite Musk courting his backing for years.
On the flip side, Alphabet has been a major investor in ****** eX since 2015, and as of June 30, it owned nearly 4% of ****** eX, a position valued at $94 billion, according to Reuters.
#abel #goog

25 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Gold (GC=F) December futures opened at $4,577 per troy ounce on Friday, August 21, 2026, up 0.1% from Thursday's closing price. The price of gold is up this morning at $4,633.90 per troy ounce as of 9 a.m. ET.
Gold continued to rise Friday morning amid concerns about U.S. debt. Earlier in the week, the national debt hit a record high of $40 trillion, five months after eclipsing $39 trillion.
For context, the U.S. debt balance was $28.4 trillion in late 2021. Fast-rising national debt erodes trust in the U.S. dollar and raises borrowing costs. As the debt balance grows, higher yields are required to compensate investors for the risk the government will take inflationary measures, like printing money, to service the debt. At the current debt level, interest costs exceed defense spending.
These dynamics can prompt higher demand for gold as a safe haven from the dollar, both for investors and central banks around the world.
#Friday #troy #price #balance
Gold (GC=F) December futures opened at $4,577 per troy ounce on Friday, August 21, 2026, up 0.1% from Thursday's closing price. The price of gold is up this morning at $4,633.90 per troy ounce as of 9 a.m. ET.
Gold continued to rise Friday morning amid concerns about U.S. debt. Earlier in the week, the national debt hit a record high of $40 trillion, five months after eclipsing $39 trillion.
For context, the U.S. debt balance was $28.4 trillion in late 2021. Fast-rising national debt erodes trust in the U.S. dollar and raises borrowing costs. As the debt balance grows, higher yields are required to compensate investors for the risk the government will take inflationary measures, like printing money, to service the debt. At the current debt level, interest costs exceed defense spending.
These dynamics can prompt higher demand for gold as a safe haven from the dollar, both for investors and central banks around the world.
#Friday #troy #price #balance


26 days ago
(Bloomberg) -- Fractile, a startup developing chips tailored for artificial intelligence use that has a deal to supply Anthropic PBC, is in advanced talks to notch a valuation more than six times higher than the price it landed in May.
Most Read from Bloomberg
Bessent Deploys Debt Buybacks in Sign of Concern Over Yield Rise
Natalie Harp, Trump's Gatekeeper, Is at Center of Senator Jon Ossoff Clash
Trump Delays Canada Tariffs at 11th Hour, Saying Deal Close
#anthropic #deploys
Most Read from Bloomberg
Bessent Deploys Debt Buybacks in Sign of Concern Over Yield Rise
Natalie Harp, Trump's Gatekeeper, Is at Center of Senator Jon Ossoff Clash
Trump Delays Canada Tariffs at 11th Hour, Saying Deal Close
#anthropic #deploys
27 days ago
Industrial automation may appear to be on the back burner for the artificial intelligence trade, which has lifted chip and memory names rather than robotics gear makers. Yet it may well be the next frontier as AI pushes into the physical world, making machine vision niche player Cognex (CGNX) an IBD 50 Stocks To Watch pick. Shares rallied into earnings on…
#watch #burner
#watch #burner
1 month ago
Ben Reitzes raised his SNDK price target to $3,600, arguing SanDisk could return $100 billion to shareholders via buybacks over three years.
SanDisk's 8 hyperscaler contracts guarantee $93.9 billion in minimum revenue over 4-plus years, signaling memory is shedding its commodity discount.
With $11.5 billion in fiscal 2026 free cash flow and $15.5 billion in buyback authorization, SanDisk's $100 billion repurchase math is credible.
Act now: the ******* yst who called NVIDIA in 2010 just named his top 10 AI stocks — and SanDisk didn't make the cut. Grab the names FREE today.
Memory has historically been the worst business in the semiconductor industry. Brutal cycles, no pricing power, capacity built at exactly the wrong moment. So when Melius Research's head of technology tells CNBC that a memory company can hand back roughly its entire pre-2026 market cap in buybacks over three years, the reflex is skepticism. The claim deserves better than a reflex.
#billion #buybacks #three
SanDisk's 8 hyperscaler contracts guarantee $93.9 billion in minimum revenue over 4-plus years, signaling memory is shedding its commodity discount.
With $11.5 billion in fiscal 2026 free cash flow and $15.5 billion in buyback authorization, SanDisk's $100 billion repurchase math is credible.
Act now: the ******* yst who called NVIDIA in 2010 just named his top 10 AI stocks — and SanDisk didn't make the cut. Grab the names FREE today.
Memory has historically been the worst business in the semiconductor industry. Brutal cycles, no pricing power, capacity built at exactly the wrong moment. So when Melius Research's head of technology tells CNBC that a memory company can hand back roughly its entire pre-2026 market cap in buybacks over three years, the reflex is skepticism. The claim deserves better than a reflex.
#billion #buybacks #three


1 month ago
As the clichéd warning goes, "past performance is no guarantee of future results." Nevertheless, past performance is usually a pretty good indication of what the future likely holds.
To this end, while continued dividend growth is never guaranteed, once a stock's achieved the ******* le of Dividend King by virtue of at least 50 consecutive years of annual dividend increases, it's clear the underlying company's got some serious staying power.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
And there's one such name right now that's a particularly compelling prospect, and not just for its dividend pedigree. That company is brick-and-mortar retailing ******* an Walmart (NASDAQ: WMT). Here are the top three reasons to buy it right now with plans on holding onto it indefinitely, and one ironic reason not to.
With 53 consecutive annual dividend increases under its belt, Walmart's got nothing left to prove in terms of being a reliable dividend payer and grower.
#past
To this end, while continued dividend growth is never guaranteed, once a stock's achieved the ******* le of Dividend King by virtue of at least 50 consecutive years of annual dividend increases, it's clear the underlying company's got some serious staying power.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
And there's one such name right now that's a particularly compelling prospect, and not just for its dividend pedigree. That company is brick-and-mortar retailing ******* an Walmart (NASDAQ: WMT). Here are the top three reasons to buy it right now with plans on holding onto it indefinitely, and one ironic reason not to.
With 53 consecutive annual dividend increases under its belt, Walmart's got nothing left to prove in terms of being a reliable dividend payer and grower.
#past

1 month ago
Amazon became the fifth company to reach a $3 trillion market cap on August 3, and its founder quickly moved to capitalize on the moment.
Jeff Bezos filed to sell roughly 15 million shares worth about $4.07 billion through Morgan Stanley, the second-largest single Form 144 he has filed by dollar value, behind the $5.4 billion filing he submitted on his wedding day in June 2025.
The disclosure is Bezos's first major sale since a separate 25-million-share program that generated nearly $5.7 billion between his June 2025 wedding day and late July 2025, when the earlier plan was completed.
The filing itself states he had no reportable sales in the prior three months.
Together, the two programs put his combined dispositions since mid-2025 at roughly $9.7 billion, still short of the $13.5 billion he sold across all of 2024, which was his personal annual record.
#billion #june #wedding #amazon
Jeff Bezos filed to sell roughly 15 million shares worth about $4.07 billion through Morgan Stanley, the second-largest single Form 144 he has filed by dollar value, behind the $5.4 billion filing he submitted on his wedding day in June 2025.
The disclosure is Bezos's first major sale since a separate 25-million-share program that generated nearly $5.7 billion between his June 2025 wedding day and late July 2025, when the earlier plan was completed.
The filing itself states he had no reportable sales in the prior three months.
Together, the two programs put his combined dispositions since mid-2025 at roughly $9.7 billion, still short of the $13.5 billion he sold across all of 2024, which was his personal annual record.
#billion #june #wedding #amazon

1 month ago
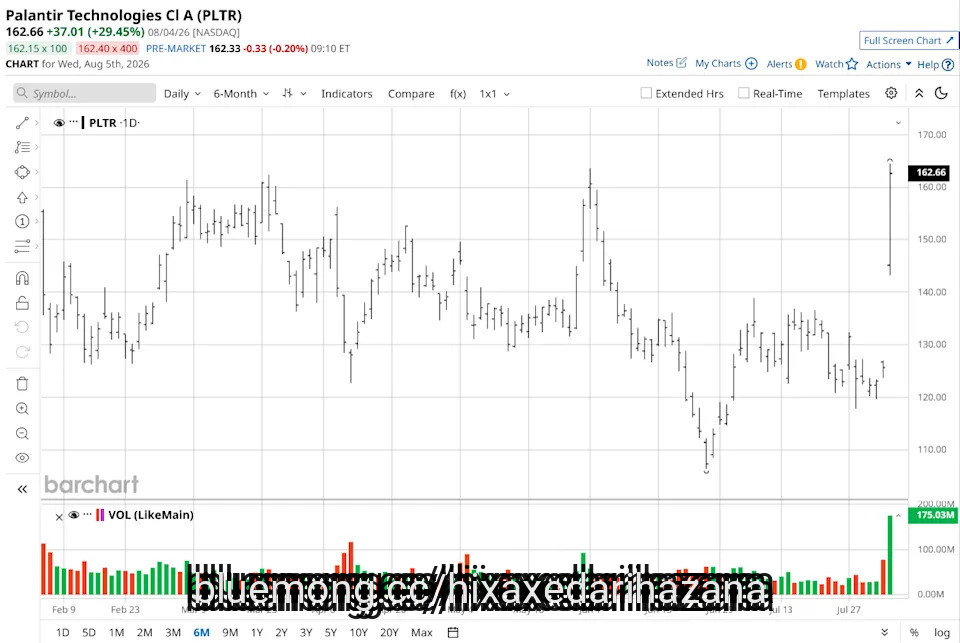
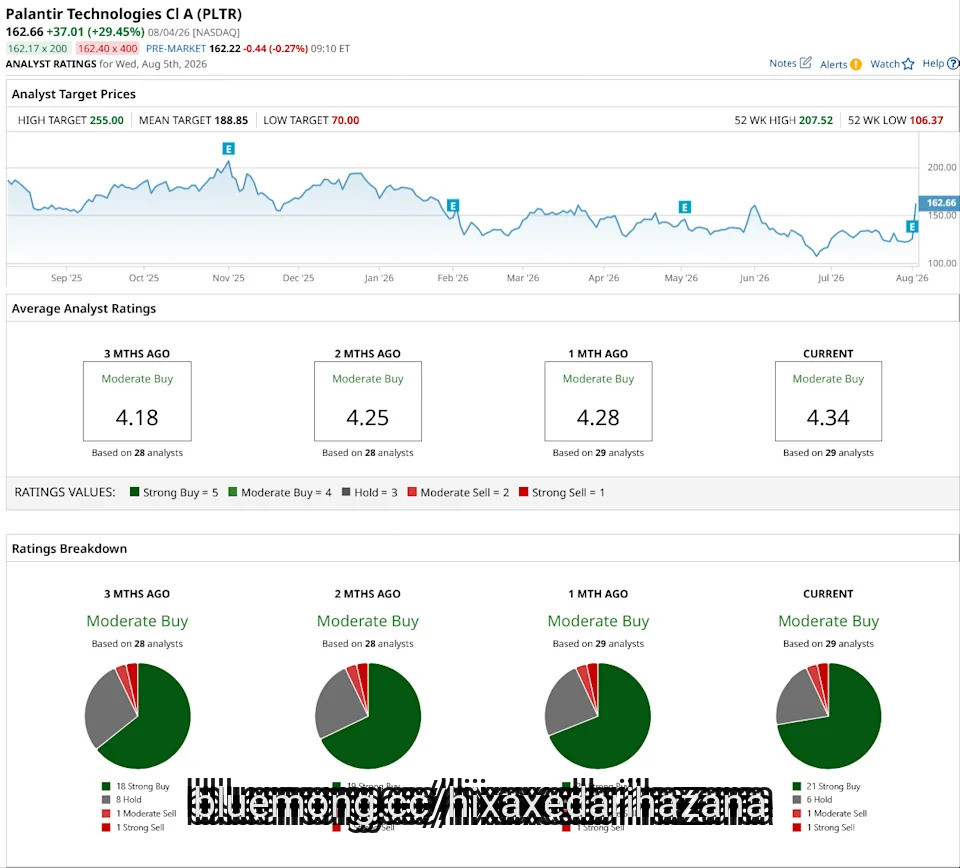
Palantir Technologies (PLTR) is a leading enterprise AI and data **** ytics company that builds operating systems for modern data-driven decision-making. Headquartered in Miami, Florida, Palantir serves both government and commercial clients through its flagship platforms, Gotham and Foundry, which integrate disparate, sensitive data sources while preserving privacy and security.
The company's Artificial Intelligence Platform (AIP) has become a cornerstone of its growth strategy, enabling organizations to deploy large language models (LLMs) against structured and unstructured data. Palantir's client base spans defense, intelligence, healthcare, energy, manufacturing, and financial services, positioning it as a key beneficiary of the enterprise AI adoption wave sweeping global boardrooms.
Jeff Bezos Says He's Selling $1 Billion In Amazon Stock Every Year to Fund Blue Origin — 'It's The Most Important Work I'm Doing'
Apple's New CEO Is Bringing a Familiar Face Back From Retirement. The Shift Is Happening.
Nasdaq Futures Climb as Tech Rally Continues on Palantir Boost, U.S. JOLTS Report and **** eX Earnings on Tap
#data #pltr
The company's Artificial Intelligence Platform (AIP) has become a cornerstone of its growth strategy, enabling organizations to deploy large language models (LLMs) against structured and unstructured data. Palantir's client base spans defense, intelligence, healthcare, energy, manufacturing, and financial services, positioning it as a key beneficiary of the enterprise AI adoption wave sweeping global boardrooms.
Jeff Bezos Says He's Selling $1 Billion In Amazon Stock Every Year to Fund Blue Origin — 'It's The Most Important Work I'm Doing'
Apple's New CEO Is Bringing a Familiar Face Back From Retirement. The Shift Is Happening.
Nasdaq Futures Climb as Tech Rally Continues on Palantir Boost, U.S. JOLTS Report and **** eX Earnings on Tap
#data #pltr
1 month ago
Hotchkis & Wiley, an investment management company, released its second-quarter 2026 investor letter for the "Hotchkis & Wiley Mid-Cap Value Fund." A copy of the letter can be downloaded here. Equity markets posted strong returns in the second quarter of 2026, with the Russell Midcap Index rising 13.8% and the Russell Midcap Value Index returning 13.4%, despite concerns about inflation, a hawkish Federal Reserve, and rising oil prices due to the Iran conflict. Narrow market leadership was evident, particularly semiconductor stocks and other stocks in the AI sector, which saw returns exceeding 100%. The Firm favors quality businesses with attractive valuations, believing that fears regarding AI's impact are overstated. The Hotchkis & Wiley Mid-Cap Value Fund lagged the Russell Midcap Value Index, achieving a 4.74% return in the second quarter, primarily due to underperformance in technology and energy sectors, while stock selection in healthcare contributed positively. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Hotchkis & Wiley Mid-Cap Value Fund highlighted Kosmos Energy Ltd. (NYSE:KOS). Kosmos Energy Ltd. (NYSE:KOS), a deepwater oil and gas exploration and production company, detracted from the Fund's performance during the quarter due to crude oil price weakness. On August 3, 2026, Kosmos Energy Ltd. (NYSE:KOS) closed at $2.53 per share. One-month return of Kosmos Energy Ltd. (NYSE:KOS) was 14.48%, and its shares gained 37.50% over the past 52 weeks. Kosmos Energy Ltd. (NYSE:KOS) has a market capitalization of $1.50 billion.
Hotchkis & Wiley Mid-Cap Value Fund stated the following regarding Kosmos Energy Ltd. (NYSE:KOS) in its Q2 2026 investor letter:
"Kosmos Energy Ltd. (NYSE:KOS) is an independent offshore E&P company with producing ******* ets in the US Gulf of Mexico and Ghana. We own it because its offshore operating expertise, quality ******* ets, attractive reinvestment economics, and compelling valuation create a favorable risk/reward profile. The stock declined during Q2 due to broader crude oil price weakness following the reopening of the Strait of Hormuz. We believe oil undersupply could continue for months and that prices could remain above normal levels, even if the reopening progresses smoothly. Given the company's strong ******* ets, high returns on investment, attractive valuation, and reduced liquidity concerns, our investment thesis remains intact."
Kosmos Energy Ltd. (NYSE:KOS) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 43 hedge fund portfolios held Kosmos Energy Ltd. (NYSE:KOS) at the end of the first quarter, up from 21 in the previous quarter. While we acknowledge the potential of Kosmos Energy Ltd. (NYSE:KOS) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that al
In its Q2 2026 investor letter, Hotchkis & Wiley Mid-Cap Value Fund highlighted Kosmos Energy Ltd. (NYSE:KOS). Kosmos Energy Ltd. (NYSE:KOS), a deepwater oil and gas exploration and production company, detracted from the Fund's performance during the quarter due to crude oil price weakness. On August 3, 2026, Kosmos Energy Ltd. (NYSE:KOS) closed at $2.53 per share. One-month return of Kosmos Energy Ltd. (NYSE:KOS) was 14.48%, and its shares gained 37.50% over the past 52 weeks. Kosmos Energy Ltd. (NYSE:KOS) has a market capitalization of $1.50 billion.
Hotchkis & Wiley Mid-Cap Value Fund stated the following regarding Kosmos Energy Ltd. (NYSE:KOS) in its Q2 2026 investor letter:
"Kosmos Energy Ltd. (NYSE:KOS) is an independent offshore E&P company with producing ******* ets in the US Gulf of Mexico and Ghana. We own it because its offshore operating expertise, quality ******* ets, attractive reinvestment economics, and compelling valuation create a favorable risk/reward profile. The stock declined during Q2 due to broader crude oil price weakness following the reopening of the Strait of Hormuz. We believe oil undersupply could continue for months and that prices could remain above normal levels, even if the reopening progresses smoothly. Given the company's strong ******* ets, high returns on investment, attractive valuation, and reduced liquidity concerns, our investment thesis remains intact."
Kosmos Energy Ltd. (NYSE:KOS) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 43 hedge fund portfolios held Kosmos Energy Ltd. (NYSE:KOS) at the end of the first quarter, up from 21 in the previous quarter. While we acknowledge the potential of Kosmos Energy Ltd. (NYSE:KOS) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that al

1 month ago
Shares of Sprouts Farmers Market (NASDAQ: SFM) climbed more than 16% this past week after the natural and organic grocery chain delivered healthier-than-expected financial results in its most recent quarter.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Sprouts' net sales grew 5% year over year to $2.3 billion in its fiscal second quarter, which ended on June 28.
The retailer opened 7 new stores during the quarter, bringing its total to 490 locations across 25 states.
However, Sprouts' comparable sales, which include revenue from stores open for at least 60 weeks, declined by 1%. Sprouts faced difficult comparisons to the prior-year quarter, when its competitors' supply chain disruptions drove additional traffic to its stores.
#sprouts #NVIDIA #signal
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Sprouts' net sales grew 5% year over year to $2.3 billion in its fiscal second quarter, which ended on June 28.
The retailer opened 7 new stores during the quarter, bringing its total to 490 locations across 25 states.
However, Sprouts' comparable sales, which include revenue from stores open for at least 60 weeks, declined by 1%. Sprouts faced difficult comparisons to the prior-year quarter, when its competitors' supply chain disruptions drove additional traffic to its stores.
#sprouts #NVIDIA #signal

1 month ago
Autonomous trucking developer Aurora Innovation (NASDAQ: AUR) reported a second-quarter net loss of $270 million on $2 million in revenue Wednesday. Executives restated the driverless truck rates behind the two business models the company is selling to carriers and shippers.
Chief Financial Officer David Maday said Aurora's transportation-as-a-service offering carries a per-mile revenue outlook in the $2-plus-per-mile range, while its driver-as-a-service subscription targets $0.85+ per mile. Maday said the company had put both figures out previously. Aurora plans to begin moving customers from the first model to the second in 2027.
The gap between those two numbers is the practical question for any fleet weighing autonomous capacity. Under TaaS, Aurora holds a U.S. Department of Transportation operating authority, controls the truck, carries the insurance, and bills a full-service rate. Under DaaS, according to the company's Form 10-Q, customers "acquire, manage, and maintain fleets directly, while subscribing to the Aurora Driver and a suite of related services."
Aurora's loss amounted to 14 cents a share, wider than the 12-cent average of ****** ysts' estimates. Revenue rose 100% from $1 million a year earlier, which the company attributed in its Form 10-Q to increased utilization, geographical expansion, and higher fuel surcharges.
"Obviously the TaaS deals have a higher per mile revenue outlook because it's the full service," Maday said. "As we've said before, kind of in that $2 plus range, whereas DaaS is targeting the $0.85 plus. There's a substantial difference in TaaS versus DaaS on a revenue side, but there's also a substantial difference on the cost side and on the margin side."
#taas #plus
Chief Financial Officer David Maday said Aurora's transportation-as-a-service offering carries a per-mile revenue outlook in the $2-plus-per-mile range, while its driver-as-a-service subscription targets $0.85+ per mile. Maday said the company had put both figures out previously. Aurora plans to begin moving customers from the first model to the second in 2027.
The gap between those two numbers is the practical question for any fleet weighing autonomous capacity. Under TaaS, Aurora holds a U.S. Department of Transportation operating authority, controls the truck, carries the insurance, and bills a full-service rate. Under DaaS, according to the company's Form 10-Q, customers "acquire, manage, and maintain fleets directly, while subscribing to the Aurora Driver and a suite of related services."
Aurora's loss amounted to 14 cents a share, wider than the 12-cent average of ****** ysts' estimates. Revenue rose 100% from $1 million a year earlier, which the company attributed in its Form 10-Q to increased utilization, geographical expansion, and higher fuel surcharges.
"Obviously the TaaS deals have a higher per mile revenue outlook because it's the full service," Maday said. "As we've said before, kind of in that $2 plus range, whereas DaaS is targeting the $0.85 plus. There's a substantial difference in TaaS versus DaaS on a revenue side, but there's also a substantial difference on the cost side and on the margin side."
#taas #plus

2 months ago
Access to this page has been denied because we believe you are using automation tools to browse the website.
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #38adf9d8 -8b74-11f1-aa82-1ccb12bb2c30
#please #page #tools
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #38adf9d8 -8b74-11f1-aa82-1ccb12bb2c30
#please #page #tools
2 months ago
By
Updated July 27, 2026 6:24 am ET
Listen
(2 min)
Confidence among German firms picked up a little this month as expectations for business climbed, though the roller-coaster ride of oil prices in recent weeks suggests that the recovery could be fragile.
#listen
Updated July 27, 2026 6:24 am ET
Listen
(2 min)
Confidence among German firms picked up a little this month as expectations for business climbed, though the roller-coaster ride of oil prices in recent weeks suggests that the recovery could be fragile.
#listen

2 months ago
SpaceX (SPCX) is poised to sink further after the stock hit a new all-time low Monday, days after a successful test of its Starship rocket. The surprising drop indicates that investor caution toward the newly public company persists, despite hitting an important launch milestone.
SpaceX shares are down nearly 4% in pre-market trade, this after dropping to $109.53 on Monday, before closing down 1.4% at $113.50. Shares have shed nearly 30% from the stock's $150 market debut last month, and are down an astounding 50% from its all-time high of $225.64.
Concern seems to be growing ahead of **** eX's big second quarter earnings report set for August 4th, with a big share unlock happening on August 6th. Per **** eX's lock-up period plan, as many as 20% of shares are eligible to be sold.
The rising angst among **** eX investors comes after Starship launched Friday evening from Starbase, Texas, on its 13th test flight, the first since **** eX's June IPO. Starship deployed all 20 of its next-generation Starlink V3 satellites, relit an engine in **** e, and made what **** eX called its softest ocean splashdown yet.
"I'm a little over the moon right now," **** eX spokesperson Dan Huot said on the company's livestream. "Lucky number 13."
#Monday #time #nearly
SpaceX shares are down nearly 4% in pre-market trade, this after dropping to $109.53 on Monday, before closing down 1.4% at $113.50. Shares have shed nearly 30% from the stock's $150 market debut last month, and are down an astounding 50% from its all-time high of $225.64.
Concern seems to be growing ahead of **** eX's big second quarter earnings report set for August 4th, with a big share unlock happening on August 6th. Per **** eX's lock-up period plan, as many as 20% of shares are eligible to be sold.
The rising angst among **** eX investors comes after Starship launched Friday evening from Starbase, Texas, on its 13th test flight, the first since **** eX's June IPO. Starship deployed all 20 of its next-generation Starlink V3 satellites, relit an engine in **** e, and made what **** eX called its softest ocean splashdown yet.
"I'm a little over the moon right now," **** eX spokesperson Dan Huot said on the company's livestream. "Lucky number 13."
#Monday #time #nearly






