2 hours ago
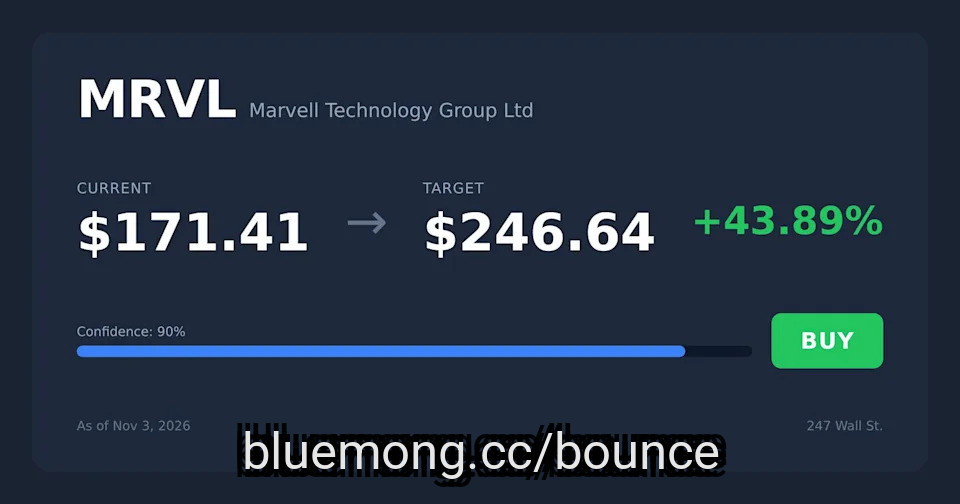
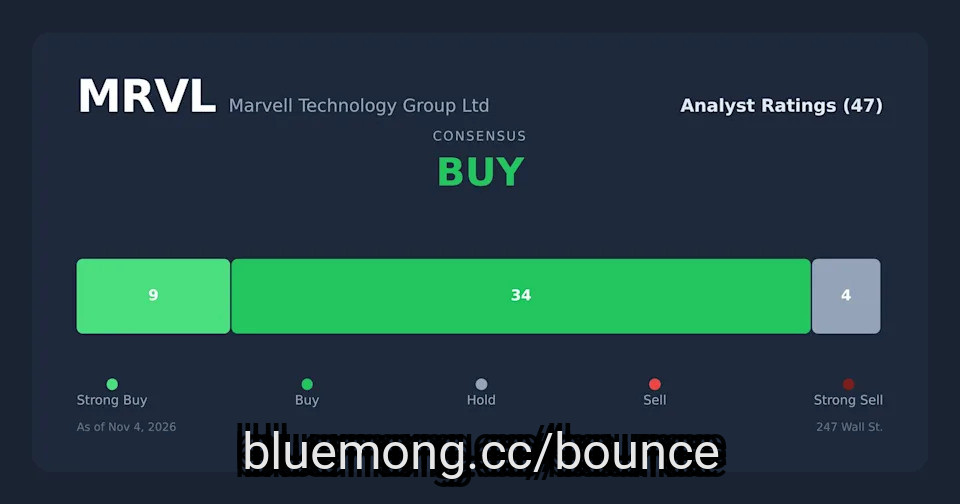
MRVL's base case turns $1,000 into ~$1,549 by 2030, while 40 Wall Street ******* ysts hold buy ratings with zero sells.
The potential LITE acquisition triggered an 11.4% selloff today, and Morningstar warned the deal risks a steep overpay.
Google's expanded custom silicon deal with Marvell includes a warrant to acquire up to 7% of shares tied to revenue milestones.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Marvell Technology didn't make the cut. Enter your email to see the names that beat MRVL. The report is free. Enter your email and see if any of your stocks made the cut.
Marvell Technology (NASDAQ:MRVL) shares traded at $222.97 at midday, a decline of 11.4% on the session. The drop followed reports that the chipmaker is close to a megadeal for Lumentum (NASDAQ:LITE) as part of an AI push.
#enter #stocks
The potential LITE acquisition triggered an 11.4% selloff today, and Morningstar warned the deal risks a steep overpay.
Google's expanded custom silicon deal with Marvell includes a warrant to acquire up to 7% of shares tied to revenue milestones.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Marvell Technology didn't make the cut. Enter your email to see the names that beat MRVL. The report is free. Enter your email and see if any of your stocks made the cut.
Marvell Technology (NASDAQ:MRVL) shares traded at $222.97 at midday, a decline of 11.4% on the session. The drop followed reports that the chipmaker is close to a megadeal for Lumentum (NASDAQ:LITE) as part of an AI push.
#enter #stocks

4 days ago
Two years ago, it seemed like ******* ody wanted to touch Intel (NASDAQ: INTC). The company that basically invented the modern chip industry had turned into its own cautionary tale, posting an $18.8 billion net loss for 2024 while it fell behind Nvidia in artificial intelligence (AI) and behind Taiwan's foundries in manufacturing.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Then something strange happened. The U.S. government bought a stake in Intel. So did Nvidia. So did SoftBank. Companies and governments don't usually hand over billions to a business they think is finished, and that's the real reason I think the next 14 months matter more for this stock than almost any stretch in Intel's recent history.
Turnarounds aren't real until a real, working product ships, and Intel is finally shipping. In July, the company said its newest Arizona fab had entered high-volume manufacturing on a subset of its Core Ultra Series 3 chips, known as Panther Lake, the first processor built on Intel 18A, which Intel calls the most advanced semiconductor process ever developed and manufactured in the United States. Its second-quarter 2026 release adds that the next node behind it, 18A-P, had already entered risk production, meaning Intel isn't just trying to catch up on one generation, it's trying to stay on pace for the one after. On the data center side, that same release says Intel also launched Xeon 6+, its first server chip built on 18A.
Money talks, and in 2025 three very different yet massive buyers said the same thing with their wallets. The U.S. government invested $8.9 billion in Intel common stock, structured largely out of unpaid CHIPS Act and Secure Enclave funding, in exchange for roughly 275 million shares and warrants for up to 241 million more. Nvidia added $5 billion, and SoftBank put in another $2 billion, both also in Intel common stock. None of this money really guarantees Panther Lake sells well, or that Intel's foundry business ever turns a real profit. But I think it's an odd thing to do if you think a company is circling the drain, and you don't have any faith in it.
#signal #first
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Then something strange happened. The U.S. government bought a stake in Intel. So did Nvidia. So did SoftBank. Companies and governments don't usually hand over billions to a business they think is finished, and that's the real reason I think the next 14 months matter more for this stock than almost any stretch in Intel's recent history.
Turnarounds aren't real until a real, working product ships, and Intel is finally shipping. In July, the company said its newest Arizona fab had entered high-volume manufacturing on a subset of its Core Ultra Series 3 chips, known as Panther Lake, the first processor built on Intel 18A, which Intel calls the most advanced semiconductor process ever developed and manufactured in the United States. Its second-quarter 2026 release adds that the next node behind it, 18A-P, had already entered risk production, meaning Intel isn't just trying to catch up on one generation, it's trying to stay on pace for the one after. On the data center side, that same release says Intel also launched Xeon 6+, its first server chip built on 18A.
Money talks, and in 2025 three very different yet massive buyers said the same thing with their wallets. The U.S. government invested $8.9 billion in Intel common stock, structured largely out of unpaid CHIPS Act and Secure Enclave funding, in exchange for roughly 275 million shares and warrants for up to 241 million more. Nvidia added $5 billion, and SoftBank put in another $2 billion, both also in Intel common stock. None of this money really guarantees Panther Lake sells well, or that Intel's foundry business ever turns a real profit. But I think it's an odd thing to do if you think a company is circling the drain, and you don't have any faith in it.
#signal #first

27 days ago
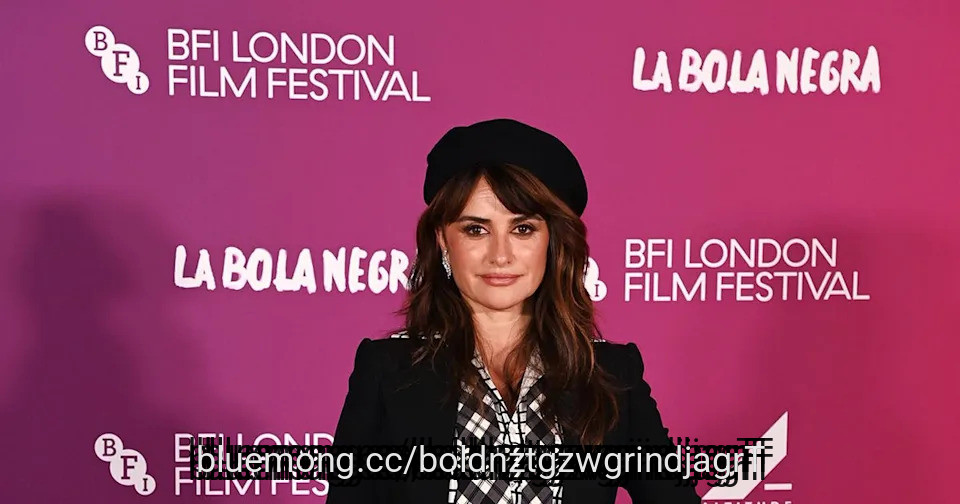
Penélope Cruz continued her La Bola Negra press tour at the 2026 BFI London Film Festival, held at the Royal Festival Hall this evening.
Alan Chapman/Dave Benett/WireImage
The Chanel ambassador has been having plenty of fun experimenting with different styles and labels throughout this press tour. We saw it at TIFF and San Sebastián, and now London has given us another welcome change of direction.
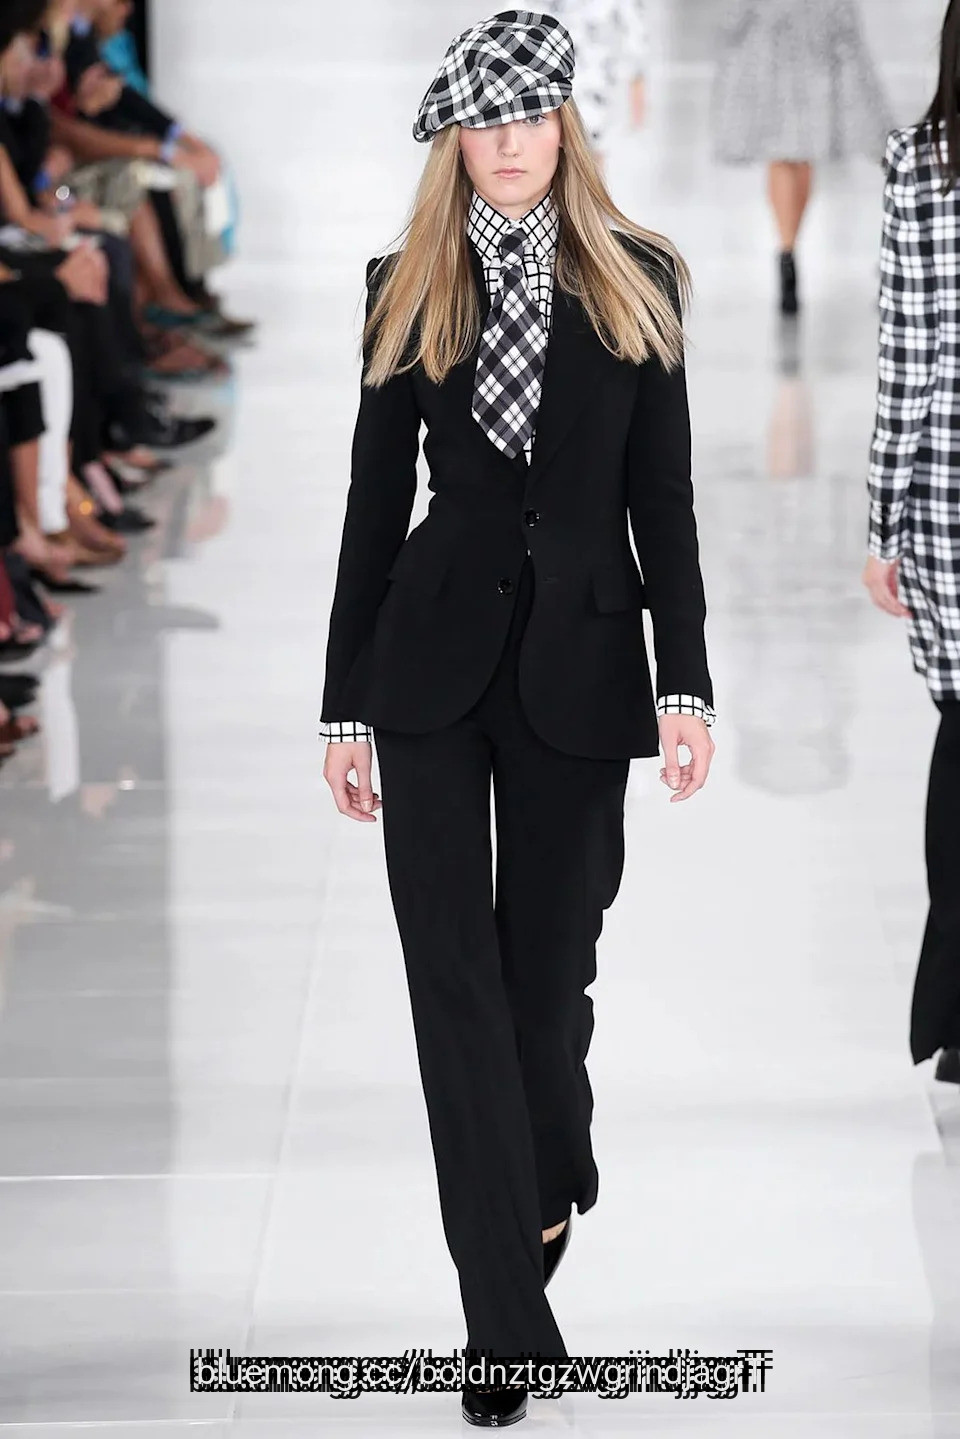
This time, Penélope dipped into the archives for a Ralph Lauren Collection Spring 2014 suit.
The tailoring is impeccable, but it's the pattern play that really sells this look to me. The contrasting checks of the shirt and tie, alongside the dominate cuffs, add plenty of charm and personality to the classic black suit without making the combination feel too busy.
#cruz
Alan Chapman/Dave Benett/WireImage
The Chanel ambassador has been having plenty of fun experimenting with different styles and labels throughout this press tour. We saw it at TIFF and San Sebastián, and now London has given us another welcome change of direction.
This time, Penélope dipped into the archives for a Ralph Lauren Collection Spring 2014 suit.
The tailoring is impeccable, but it's the pattern play that really sells this look to me. The contrasting checks of the shirt and tie, alongside the dominate cuffs, add plenty of charm and personality to the classic black suit without making the combination feel too busy.
#cruz

28 days ago
When a farm sells for a lump sum, IRS rules split proceeds across five ******* et types, and only market cattle profits count as Social Security self-employment earnings.
In a hypothetical sale generating $500,000 in gains, only $100,000 from market cattle counts toward Social Security's earnings test, while land and equipment gains register $0.
Land gains escape the Social Security earnings test but still raise adjusted gross income, potentially making up to 85% of benefits taxable.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Freeman Family Ranches covered 87,953 acres across the North Texas and Oklahoma panhandles. The three properties, in the family for four generations, sold in late July after being listed at nearly $128 million.
#Social #gains #family #market
In a hypothetical sale generating $500,000 in gains, only $100,000 from market cattle counts toward Social Security's earnings test, while land and equipment gains register $0.
Land gains escape the Social Security earnings test but still raise adjusted gross income, potentially making up to 85% of benefits taxable.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Freeman Family Ranches covered 87,953 acres across the North Texas and Oklahoma panhandles. The three properties, in the family for four generations, sold in late July after being listed at nearly $128 million.
#Social #gains #family #market

28 days ago
Selling appreciated stock and donating cash still leaves the full capital gain in Medicare's MAGI, potentially triggering IRMAA surcharges two years later.
A couple adding a $90,000 gain to $200,000 in normal income can face $5,770 in extra annual Medicare premiums, even after donating every dollar to charity.
Donating appreciated shares held over a year directly to charity keeps the gain out of MAGI entirely, avoiding IRMAA; those over 70.5 can also use a QCD up to $111,000.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
A 72-year-old retiree has held Berkshire Hathaway (NYSE:BRK-B) shares for decades. This fall he sells $100,000 worth of stock he bought for $10,000, then writes a check for the full amount to his church's building fund. He ***** umes the gift wipes out the income Medicare sees. For his income tax bill, the gift helps. For Medicare, the $90,000 gain stays on his return, and it will raise his premiums two years from now.
#medicare #magi #Stock
A couple adding a $90,000 gain to $200,000 in normal income can face $5,770 in extra annual Medicare premiums, even after donating every dollar to charity.
Donating appreciated shares held over a year directly to charity keeps the gain out of MAGI entirely, avoiding IRMAA; those over 70.5 can also use a QCD up to $111,000.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
A 72-year-old retiree has held Berkshire Hathaway (NYSE:BRK-B) shares for decades. This fall he sells $100,000 worth of stock he bought for $10,000, then writes a check for the full amount to his church's building fund. He ***** umes the gift wipes out the income Medicare sees. For his income tax bill, the gift helps. For Medicare, the $90,000 gain stays on his return, and it will raise his premiums two years from now.
#medicare #magi #Stock

1 month ago
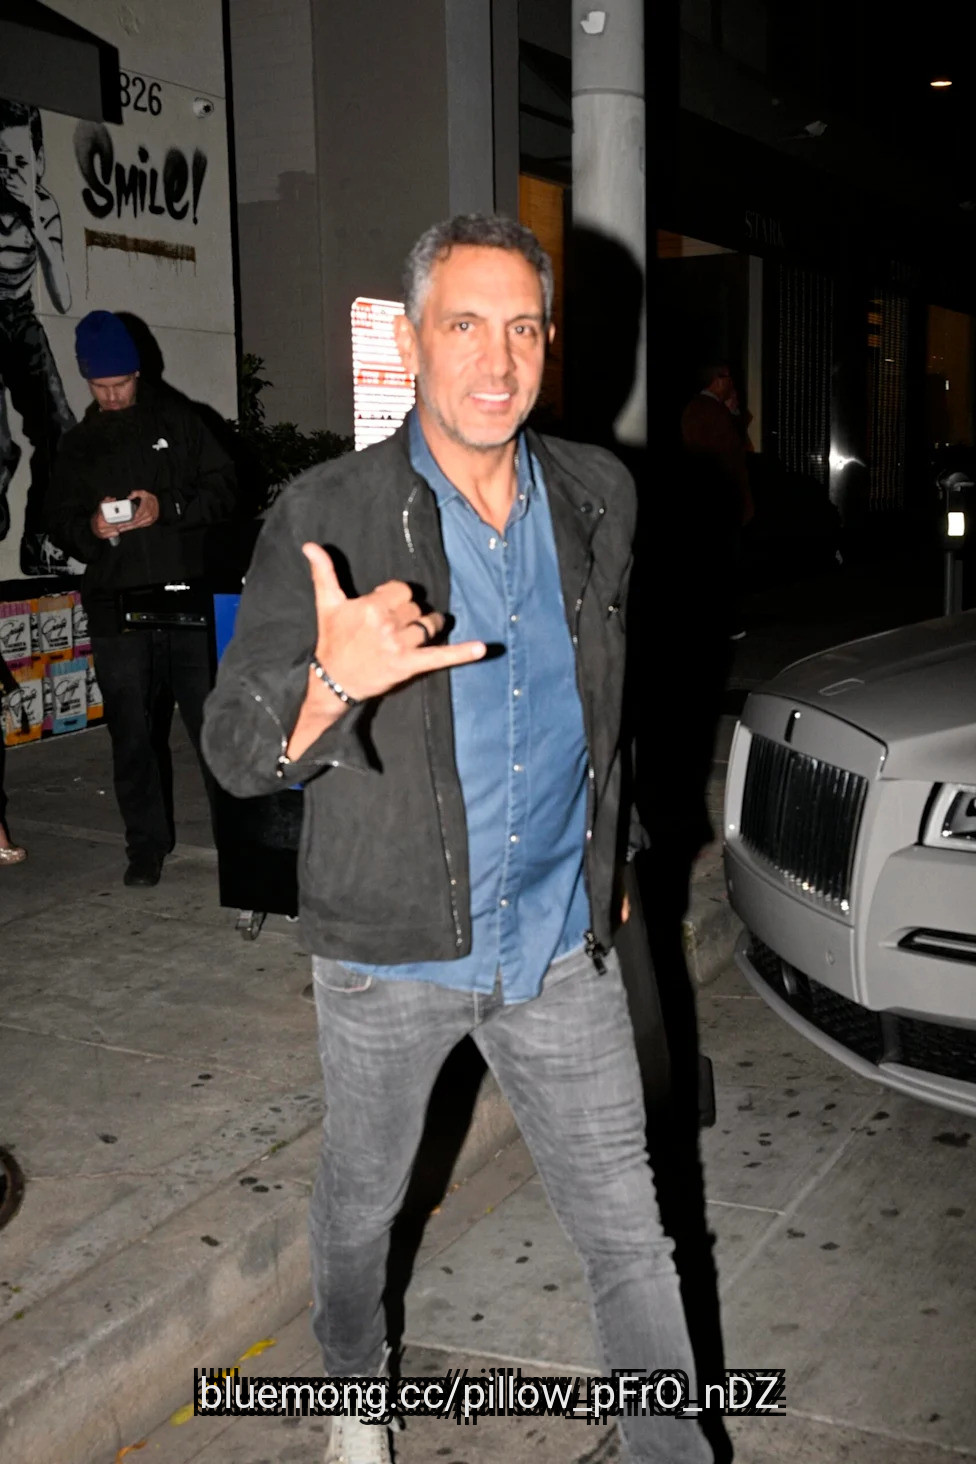
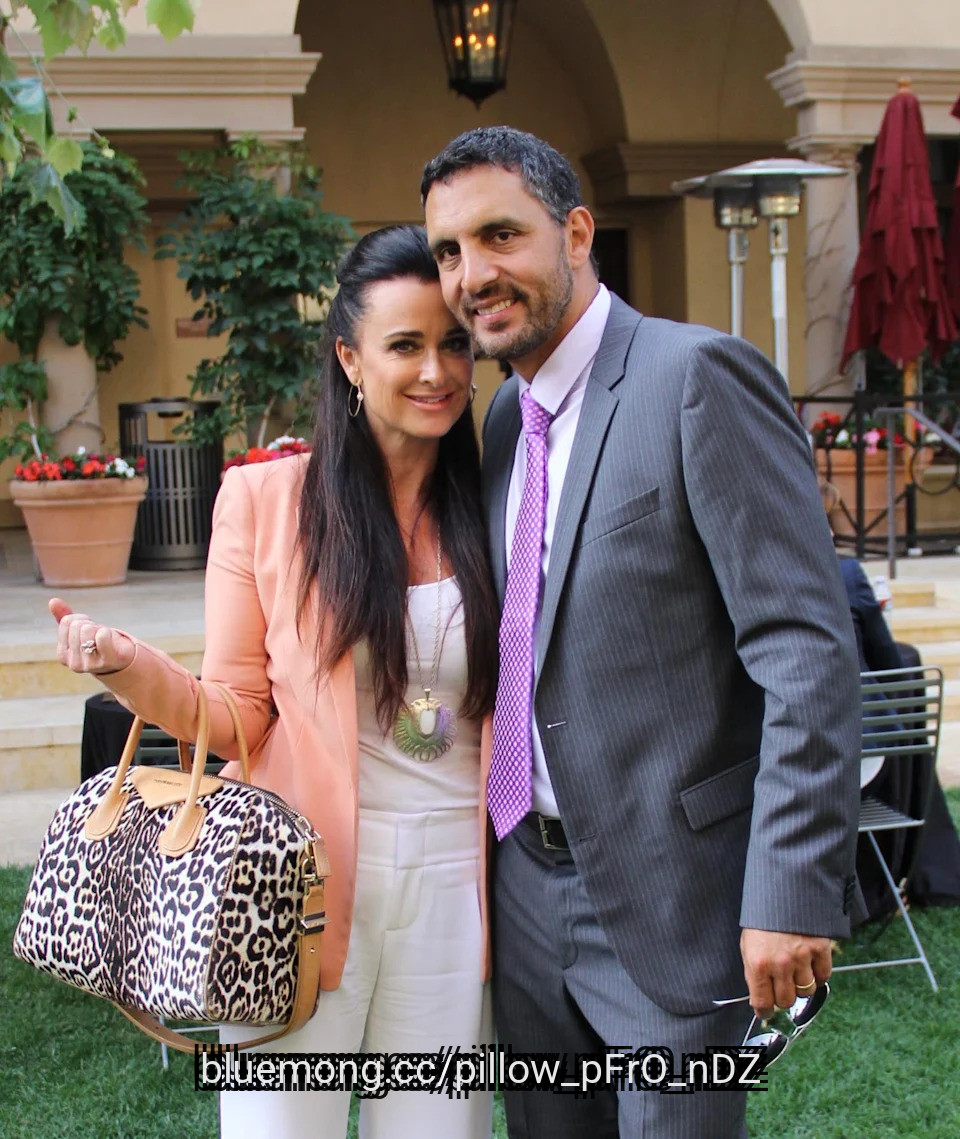
Mauricio Umansky has already made a name for himself. In addition to being the husband of "The Real Housewives of Beverly Hills" star Kyle Richards, Umansky is also a real estate mogul who sells luxury properties worldwide. And if that wasn't enough, Umansky also spent two seasons starring in his own Netflix show, "Buying Beverly Hills," alongside his daughters, Alexia and Farrah. So, what's next for the 56-year-old? He says he's considering a jump into politics, starting with a mayoral run in the coming years.
MEGA
Umansky recently spoke with USA Today about his growing interest in politics and said he's considered running for mayor of LA.
"I'm definitely into potentially running for mayor," he said, with his daughter confirming, "He's been talking about that."
MEGA
#hills #Politics #running #mauricio
MEGA
Umansky recently spoke with USA Today about his growing interest in politics and said he's considered running for mayor of LA.
"I'm definitely into potentially running for mayor," he said, with his daughter confirming, "He's been talking about that."
MEGA
#hills #Politics #running #mauricio

1 month ago
Former Intel CEO Pat Gelsinger is backing a startup that thinks AI's next bottleneck is not the accelerator. It is everything waiting for data to arrive.
Delos Data announced on September 15 that it raised more than $100 million to develop networking chips and software for increasingly heterogeneous AI data centers. Playground Global, where Gelsinger is a general partner, joined the round. Reuters reported that Delos is designing the network to work across different types of compute hardware rather than **** uming every accelerator comes from NVIDIA Corporation (NASDAQ:NVDA).
That makes Advanced Micro Devices, Inc. (NASDAQ:AMD) an important read-through even though AMD is not an investor in Delos.
For illustration purposes only. Photo by Brett Sayles on Pexels
Nvidia does not dominate AI simply because its GPUs are fast. NVIDIA Corporation (NASDAQ:NVDA) sells a tightly integrated system of accelerators, networking, interconnects and software. That makes large clusters easier to deploy and gives customers fewer reasons to mix architectures.
#delos #data #Networking #software
Delos Data announced on September 15 that it raised more than $100 million to develop networking chips and software for increasingly heterogeneous AI data centers. Playground Global, where Gelsinger is a general partner, joined the round. Reuters reported that Delos is designing the network to work across different types of compute hardware rather than **** uming every accelerator comes from NVIDIA Corporation (NASDAQ:NVDA).
That makes Advanced Micro Devices, Inc. (NASDAQ:AMD) an important read-through even though AMD is not an investor in Delos.
For illustration purposes only. Photo by Brett Sayles on Pexels
Nvidia does not dominate AI simply because its GPUs are fast. NVIDIA Corporation (NASDAQ:NVDA) sells a tightly integrated system of accelerators, networking, interconnects and software. That makes large clusters easier to deploy and gives customers fewer reasons to mix architectures.
#delos #data #Networking #software

1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
2 months ago
Nvidia (NASDAQ:NVDA) has constructed an artificial intelligence (AI) empire over the past few years. The company sells the world's most powerful AI chips, known as graphics processing units (GPUs), and an entire portfolio of related tools that are generating triple-digit growth and record levels of revenue.
Investors have piled into Nvidia stock to gain access to this incredible growth story, and so far, they've scored a major win. The stock has soared about 800% over the past five years. But, in recent times, investors have worried about one particular challenge: competition. Though Nvidia remains in the lead, a number of companies also sell AI chips -- and these products are becoming more powerful with each update.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
These players include chip companies like Advanced Micro Devices as well as broader tech giants like Amazon (NASDAQ:AMZN). All of this has prompted some investors to pause before getting in on Nvidia stock at this stage of the AI story. Nvidia stock has climbed about 14% this year, which isn't a big leap for this stock.
Just recently, however, some bright news emerged during Amazon's earning call. In fact, these 15 words from Amazon chief Andy Jassy may eliminate Nvidia's biggest risk.
#chips
Investors have piled into Nvidia stock to gain access to this incredible growth story, and so far, they've scored a major win. The stock has soared about 800% over the past five years. But, in recent times, investors have worried about one particular challenge: competition. Though Nvidia remains in the lead, a number of companies also sell AI chips -- and these products are becoming more powerful with each update.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
These players include chip companies like Advanced Micro Devices as well as broader tech giants like Amazon (NASDAQ:AMZN). All of this has prompted some investors to pause before getting in on Nvidia stock at this stage of the AI story. Nvidia stock has climbed about 14% this year, which isn't a big leap for this stock.
Just recently, however, some bright news emerged during Amazon's earning call. In fact, these 15 words from Amazon chief Andy Jassy may eliminate Nvidia's biggest risk.
#chips

2 months ago
Super Micro Computer (SMCI) stock rose 9.5% on Thursday, September 17, closing just over $40. The move followed a bullish call on how big the market for AI servers gets. That call may well be right. But it answers a question Super Micro's own results never raised. That is why one big session tells you less than it looks like it does.
Analysts at Goldman Sachs said the addressable market for AI servers will expand aggressively through the end of the decade. That is a forecast about an industry rather than about one manufacturer. Another account of Thursday morning's climb credited a broader equity rebound after Wednesday afternoon's Federal Reserve rate decision, not the forecast. Hewlett Packard Enterprise (HPE) jumped 8.0% the same day against the S&P 500's 1.1% gain, showing that capital was rotating heavily into primary AI server makers.
Company-specific headlines that day ran the other way: after the close, a shareholder rights law firm issued a press release soliciting clients for a potential investigation into company management.
A bigger market is not what this company is short of. In its fiscal fourth quarter, ended June 2026, Super Micro booked over $60 billion of new orders. That backlog underpins management's fiscal 2027 revenue guidance of $65 billion to $72 billion—up sharply from the $39 billion booked over the prior twelve months, but spread out as delivery and deployment constraints allow customers to take delivery.
What it is short of is customers ready to take delivery. Super Micro sells data center building block solutions, which bundle the servers with the power, cooling, networking and software around them. The company's manufacturing capability is on track to include more than 3,000 direct liquid-cooled racks a month.
#forecast
Analysts at Goldman Sachs said the addressable market for AI servers will expand aggressively through the end of the decade. That is a forecast about an industry rather than about one manufacturer. Another account of Thursday morning's climb credited a broader equity rebound after Wednesday afternoon's Federal Reserve rate decision, not the forecast. Hewlett Packard Enterprise (HPE) jumped 8.0% the same day against the S&P 500's 1.1% gain, showing that capital was rotating heavily into primary AI server makers.
Company-specific headlines that day ran the other way: after the close, a shareholder rights law firm issued a press release soliciting clients for a potential investigation into company management.
A bigger market is not what this company is short of. In its fiscal fourth quarter, ended June 2026, Super Micro booked over $60 billion of new orders. That backlog underpins management's fiscal 2027 revenue guidance of $65 billion to $72 billion—up sharply from the $39 billion booked over the prior twelve months, but spread out as delivery and deployment constraints allow customers to take delivery.
What it is short of is customers ready to take delivery. Super Micro sells data center building block solutions, which bundle the servers with the power, cooling, networking and software around them. The company's manufacturing capability is on track to include more than 3,000 direct liquid-cooled racks a month.
#forecast


2 months ago
Merck (MRK) stock returned about 87% over the past twelve months, climbing from roughly $79 to about $147. Nothing in the year's results looks like that. The medicines Merck sells today grew at their usual pace. Investors spent the year repricing what comes next.
Revenue over the trailing twelve months was $66.6 billion, up 4.6% and in line with its own three-year pace. Profitability did not follow. Its operating margin over the same twelve months was 10.5%, versus a three-year average of 22.4%.
Most of that gap is one purchase. Merck took a $5.7 billion charge in the second quarter of 2026, about 9% of a year's sales. It bought Terns Pharmaceuticals, and with it MK-4208, a candidate for chronic myeloid leukemia. The bill hits earnings now and the medicine arrives later.
The proof matters because of the risk hanging over this stock. The KEYTRUDA family was just over half of Merck's revenue in the second quarter of 2026. The company is openly planning for the end of that exclusivity when Keytruda loses primary U.S. patent protection in 2028. Management describes the stretch as more of a hill than a cliff, with a shallow dip and a fast return to growth.
Johnson & Johnson (JNJ) returned 56% over the same twelve months and Pfizer (PFE) 23%, so a good year for pharmaceuticals explains some of this but not Merck's lead. What separated Merck was evidence. The FDA approved LIPFENDRA, the first and only oral PCSK9 inhibitor. In the CORALreef Lipids trial it lowered LDL cholesterol by up to 60% when added to a statin.
#year #johnson
Revenue over the trailing twelve months was $66.6 billion, up 4.6% and in line with its own three-year pace. Profitability did not follow. Its operating margin over the same twelve months was 10.5%, versus a three-year average of 22.4%.
Most of that gap is one purchase. Merck took a $5.7 billion charge in the second quarter of 2026, about 9% of a year's sales. It bought Terns Pharmaceuticals, and with it MK-4208, a candidate for chronic myeloid leukemia. The bill hits earnings now and the medicine arrives later.
The proof matters because of the risk hanging over this stock. The KEYTRUDA family was just over half of Merck's revenue in the second quarter of 2026. The company is openly planning for the end of that exclusivity when Keytruda loses primary U.S. patent protection in 2028. Management describes the stretch as more of a hill than a cliff, with a shallow dip and a fast return to growth.
Johnson & Johnson (JNJ) returned 56% over the same twelve months and Pfizer (PFE) 23%, so a good year for pharmaceuticals explains some of this but not Merck's lead. What separated Merck was evidence. The FDA approved LIPFENDRA, the first and only oral PCSK9 inhibitor. In the CORALreef Lipids trial it lowered LDL cholesterol by up to 60% when added to a statin.
#year #johnson


2 months ago
Corning (GLW) stock took a sharp hit this week after the company opened the door to a potential $2 billion equity offering that could dilute existing shareholders. The stock dropped 13.7% on Sept. 14, marking its worst one-day decline in years. At the same time, Corning is expanding its capacity and signing major deals with some of the world's biggest tech companies, including Nvidia (NVDA) and Amazon (AMZN). Its latest Verizon (VZ) agreement alone covers over 80 million miles of optical fiber and connectivity products through 2032. Corning shares have since recovered, shifting attention away from dilution fear to whether the capital raise was a sensible decision, how much stock Corning actually sells, how quickly Optical Communications grows, and whether new capacity generates the returns management expects.
Let's find out more on what matters for investors now.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#Stock #sept
Let's find out more on what matters for investors now.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#Stock #sept


2 months ago
Choosing between a niche equipment provider and a diversified industry **** an requires balancing high growth potential against established stability. Here is how Aehr Test Systems (NASDAQ:AEHR) and KLA (NASDAQ:KLAC) compare for investors.
Aehr Test Systems focuses on specific stress-testing solutions for power semiconductors and memory, while KLA provides broad process control tools used across the entire chip-making industry. While they both operate in the same sector, their scale and risk profiles differ significantly, making them attractive to different types of portfolios.
Aehr Test Systems designs and sells specialized equipment for the testing and stabilization of semiconductor products in various forms, including wafers and singulated dies. The company focuses on the high-growth silicon carbide market for electric vehicles and high-bandwidth memory for artificial intelligence infrastructure. In its 2026 fiscal year (FY), which ended May 29, its five largest customers accounted for nearly 70% of net sales, and customer concentration like this adds a layer of risk to the business.
In FY 2026, revenue reached $50.0 million, representing a decline of 15.2% compared to the previous year. This contraction followed a period of higher operating costs, resulting in a net loss of $7.1 million for the period. The net margin, which represents the percentage of revenue remaining as profit after all expenses, was -14.3% in the latest fiscal year.
As of its May 2026 balance sheet, the debt-to-equity ratio is zero, indicating that the company has no debt relative to its shareholder equity. The current ratio, which measures a company's ability to cover short-term liabilities with short-term **** ets, is 10.3x. Free cash flow, defined as cash from operations minus capital expenditures, was a negative $5.4 million for the fiscal year ended in May.
#year #equipment
Aehr Test Systems focuses on specific stress-testing solutions for power semiconductors and memory, while KLA provides broad process control tools used across the entire chip-making industry. While they both operate in the same sector, their scale and risk profiles differ significantly, making them attractive to different types of portfolios.
Aehr Test Systems designs and sells specialized equipment for the testing and stabilization of semiconductor products in various forms, including wafers and singulated dies. The company focuses on the high-growth silicon carbide market for electric vehicles and high-bandwidth memory for artificial intelligence infrastructure. In its 2026 fiscal year (FY), which ended May 29, its five largest customers accounted for nearly 70% of net sales, and customer concentration like this adds a layer of risk to the business.
In FY 2026, revenue reached $50.0 million, representing a decline of 15.2% compared to the previous year. This contraction followed a period of higher operating costs, resulting in a net loss of $7.1 million for the period. The net margin, which represents the percentage of revenue remaining as profit after all expenses, was -14.3% in the latest fiscal year.
As of its May 2026 balance sheet, the debt-to-equity ratio is zero, indicating that the company has no debt relative to its shareholder equity. The current ratio, which measures a company's ability to cover short-term liabilities with short-term **** ets, is 10.3x. Free cash flow, defined as cash from operations minus capital expenditures, was a negative $5.4 million for the fiscal year ended in May.
#year #equipment


2 months ago
On September 15, Arthur J. Gallagher & Co. (NYSE:AJG) announced that it had bought McMillan Insurance & Bonding Inc., an Englewood, Colorado, firm that operates as Innovise Business Consultants. Gallagher did not say what it paid. On its own, the deal is a footnote. But it is one of many, and the way those deals show up in earnings is where the debate over this stock really lives.
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth


2 months ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august


2 months ago
When developers hand governance to residents at build-out, HOA fees spike as homeowners absorb true amenity costs and cover reserve underfunding through special ****** sments.
HOA fee increases in post-transition communities routinely outpace the 2027 Social Security COLA of roughly 3%, squeezing retirees on fixed incomes.
Demand the reserve study, CC&Rs, and community development district bond balance before signing. If the sales office stalls, the pitch was rehearsed, not substantiated.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Readers in their late fifties and early sixties ask weekly: Can I retire to a Margaritaville community, and what will it cost over twenty or thirty years? The brochure sells one version, while the sales center sells another. The real question a retiree should ask is what happens once marketing wears off and the structural issue the sales presentation almost never covers emerges.
#retirees #community #years #sells
HOA fee increases in post-transition communities routinely outpace the 2027 Social Security COLA of roughly 3%, squeezing retirees on fixed incomes.
Demand the reserve study, CC&Rs, and community development district bond balance before signing. If the sales office stalls, the pitch was rehearsed, not substantiated.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Readers in their late fifties and early sixties ask weekly: Can I retire to a Margaritaville community, and what will it cost over twenty or thirty years? The brochure sells one version, while the sales center sells another. The real question a retiree should ask is what happens once marketing wears off and the structural issue the sales presentation almost never covers emerges.
#retirees #community #years #sells
2 months ago
Elon Musk is getting serious about putting artificial intelligence (AI) into orbit. The ***** eX (SPCX) CEO is reportedly confident the company can launch Nvidia (NVDA) powered AI systems into ***** e in 2027. ***** eX and Nvidia are working on a ***** e-optimized version of Nvidia's Vera Rubin NVL72 platform, and Musk says the system should be lighter, denser, and cheaper than a traditional data-center rack. That matters because ***** eX is trying to turn orbital computing into a major business, while Nvidia could gain another market for its AI hardware.
The opportunity is much bigger than a headline. ***** eX could eventually sell computing capacity from satellites just as it sells broadband through Starlink. Meanwhile, Nvidia could supply the chips behind that infrastructure. Investors should still remember that this is an emerging business, and commercial scale is not expected immediately. Still, the plan gives both companies another way to capitalize on the AI spending boom.
Why It's Time to Load Up on Nvidia Stock
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
#NVIDIA #SpaceX #much #still
The opportunity is much bigger than a headline. ***** eX could eventually sell computing capacity from satellites just as it sells broadband through Starlink. Meanwhile, Nvidia could supply the chips behind that infrastructure. Investors should still remember that this is an emerging business, and commercial scale is not expected immediately. Still, the plan gives both companies another way to capitalize on the AI spending boom.
Why It's Time to Load Up on Nvidia Stock
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
#NVIDIA #SpaceX #much #still

2 months ago
PepsiCo (PEP) has gone nowhere for a year, down 1.8% over the past twelve months while the S&P 500 returned 16.6%. At about $135 a share it trades at 17.7 times earnings, against an S&P 500 median of 22.5. A big cash generator priced below the market is what value buyers hunt for, so is this discount impatience or a verdict?
PepsiCo sells snacks and drinks everywhere consumer staples get sold: grocery aisles, convenience and gas stations, and the away-from-home locations it keeps adding. That reach turns into cash: free cash flow over the trailing twelve months was $9.28 billion, a 5.0% yield.
None of the recent numbers look like a business in trouble. Revenue over the trailing twelve months grew 5.6%, and the operating margin is holding at 15.0% against an S&P 500 median of 18.6%. Management says global volumes grew in both foods and beverages in the first half of 2026, the fastest growth in volume since 2022.
Widen the window and the picture changes. PepsiCo's revenue grew 5.6% over the trailing twelve months against an S&P 500 median of 8.3%, and its three-year average is just 2.5% a year. The trailing twelve months ran hotter, but one window is not a pace, and the pace is what the market pays for.
The company lowered prices in the U.S. early in 2026 to get volume moving. Management says salty snacks went from falling volume to rising volume and PepsiCo gained share, but volume in the second quarter of 2026 fell short of what it expected, which it blames on a consumer hurt by higher gas prices and on delays executing the price investment at some customers. None of this is lost on the market: it is pricing a company that grows slowly and has just spent money trying to grow faster. The problem sits in North America, while the international business stayed strong.
#months #trailing
PepsiCo sells snacks and drinks everywhere consumer staples get sold: grocery aisles, convenience and gas stations, and the away-from-home locations it keeps adding. That reach turns into cash: free cash flow over the trailing twelve months was $9.28 billion, a 5.0% yield.
None of the recent numbers look like a business in trouble. Revenue over the trailing twelve months grew 5.6%, and the operating margin is holding at 15.0% against an S&P 500 median of 18.6%. Management says global volumes grew in both foods and beverages in the first half of 2026, the fastest growth in volume since 2022.
Widen the window and the picture changes. PepsiCo's revenue grew 5.6% over the trailing twelve months against an S&P 500 median of 8.3%, and its three-year average is just 2.5% a year. The trailing twelve months ran hotter, but one window is not a pace, and the pace is what the market pays for.
The company lowered prices in the U.S. early in 2026 to get volume moving. Management says salty snacks went from falling volume to rising volume and PepsiCo gained share, but volume in the second quarter of 2026 fell short of what it expected, which it blames on a consumer hurt by higher gas prices and on delays executing the price investment at some customers. None of this is lost on the market: it is pricing a company that grows slowly and has just spent money trying to grow faster. The problem sits in North America, while the international business stayed strong.
#months #trailing
2 months ago
On August 5, Kinetik Holdings Inc. (NYSE:KNTK) reported the strongest quarterly results in company history and raised its full-year 2026 guidance. The Permian-focused midstream operator posted net income, including noncontrolling interest, of $123.1 million for the quarter ended June 30, while Adjusted EBITDA climbed to $280.8 million. Management didn't stop at celebrating the number. It used the quarter as the launchpad for a string of expansion decisions that stretch out to 2028.
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter


2 months ago
On August 4, Westlake Corporation (NYSE:WLK) reported second-quarter results that erased two consecutive quarterly losses in a single swing. Net income landed at $260 million, or $2.01 per share, compared with a $169 million loss just three months earlier and a $142 million loss a year ago. EBITDA nearly tripled from the second quarter of 2025. The numbers mark a sharp reversal for a company whose chemicals business had been bleeding red ink.
The turnaround centers on Performance and Essential Materials, the segment that makes chlorovinyls and other basic chemicals. PEM swung from a $318 million operating loss in the second quarter of 2025 to $185 million in income this quarter, while EBITDA excluding identified items jumped from a 3% margin to 21%. The driver was pricing: average sales prices across PEM rose 14% year over year, more than offsetting a 3% price decline in the Housing and Infrastructure Products segment. Combined with a 7% increase in companywide sales volume, excluding the effects of plant shutdowns and an acquisition, the pricing recovery pushed companywide EBITDA to $679 million from $210 million a year earlier.
Westlake is also working the balance sheet alongside the market recovery. The company reduced debt by $500 million during the quarter and returned $99 million to shareholders through dividends and share repurchases. Management says its three-pillar profitability improvement plan remains on track to deliver a $600 million operating income benefit, a target that, if it holds, would layer structural cost savings on top of whatever the market gives back in pricing.
Not every part of the story improved together. Housing and Infrastructure Products, the segment tied to home construction and building products, saw its EBITDA margin slip to 22% from 24% a year earlier, even as volume rose 6% excluding the ACI acquisition. Average sales prices in that segment fell 3% year over year, a sign that pricing power in housing products has softened even as the company sells more of it.
The improvement in the core chemicals business also leans heavily on price rather than volume. PEM's turnaround came from a 14% jump in average sales price, a figure that can move in either direction with commodity cycles. The first quarter of 2026 was a reminder of how quickly conditions shift: Westlake posted a $169 million net loss just three months before this result, weighed down by $85 million in identified items, including a $67 million charge to settle litigation over PVC pipe and fittings and $18 million tied to facility shutdowns. A year earlier, in the second quarter of 2025, the company absorbed another $130 million in shutdown-related charges. Restructuring and legal charges showed up in two of the last three reported quarters.
#million #year #quarter #loss
The turnaround centers on Performance and Essential Materials, the segment that makes chlorovinyls and other basic chemicals. PEM swung from a $318 million operating loss in the second quarter of 2025 to $185 million in income this quarter, while EBITDA excluding identified items jumped from a 3% margin to 21%. The driver was pricing: average sales prices across PEM rose 14% year over year, more than offsetting a 3% price decline in the Housing and Infrastructure Products segment. Combined with a 7% increase in companywide sales volume, excluding the effects of plant shutdowns and an acquisition, the pricing recovery pushed companywide EBITDA to $679 million from $210 million a year earlier.
Westlake is also working the balance sheet alongside the market recovery. The company reduced debt by $500 million during the quarter and returned $99 million to shareholders through dividends and share repurchases. Management says its three-pillar profitability improvement plan remains on track to deliver a $600 million operating income benefit, a target that, if it holds, would layer structural cost savings on top of whatever the market gives back in pricing.
Not every part of the story improved together. Housing and Infrastructure Products, the segment tied to home construction and building products, saw its EBITDA margin slip to 22% from 24% a year earlier, even as volume rose 6% excluding the ACI acquisition. Average sales prices in that segment fell 3% year over year, a sign that pricing power in housing products has softened even as the company sells more of it.
The improvement in the core chemicals business also leans heavily on price rather than volume. PEM's turnaround came from a 14% jump in average sales price, a figure that can move in either direction with commodity cycles. The first quarter of 2026 was a reminder of how quickly conditions shift: Westlake posted a $169 million net loss just three months before this result, weighed down by $85 million in identified items, including a $67 million charge to settle litigation over PVC pipe and fittings and $18 million tied to facility shutdowns. A year earlier, in the second quarter of 2025, the company absorbed another $130 million in shutdown-related charges. Restructuring and legal charges showed up in two of the last three reported quarters.
#million #year #quarter #loss


2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre


2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #fund #quarter #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #fund #quarter #parnassus

2 months ago
PulteGroup, Inc. (PHM) is one of America's largest homebuilders, headquartered in Atlanta, Georgia. It acquires and develops land for residential use and constructs and sells single-family detached homes, townhomes, condominiums, and duplexes. Operating in U.S. markets, the company serves diverse homebuyers through brands including Centex, Pulte Homes, Del Webb, and DiVosta Homes. The company has a market capitalization of $22.76 billion, which makes it a "large-cap" stock.
PulteGroup's shares reached a 52-week low of $108.49 on May 19, but are up 10.1% from that level. Over the past three months, the stock has dropped 2.7%, as investors weigh persistent housing-market headwinds. Meanwhile, the broader S&P 500 Index ($SPX) is up marginally over the past three months. Therefore, PHM has clearly underperformed over this period.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#Stock #months #atlanta
PulteGroup's shares reached a 52-week low of $108.49 on May 19, but are up 10.1% from that level. Over the past three months, the stock has dropped 2.7%, as investors weigh persistent housing-market headwinds. Meanwhile, the broader S&P 500 Index ($SPX) is up marginally over the past three months. Therefore, PHM has clearly underperformed over this period.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#Stock #months #atlanta


2 months ago
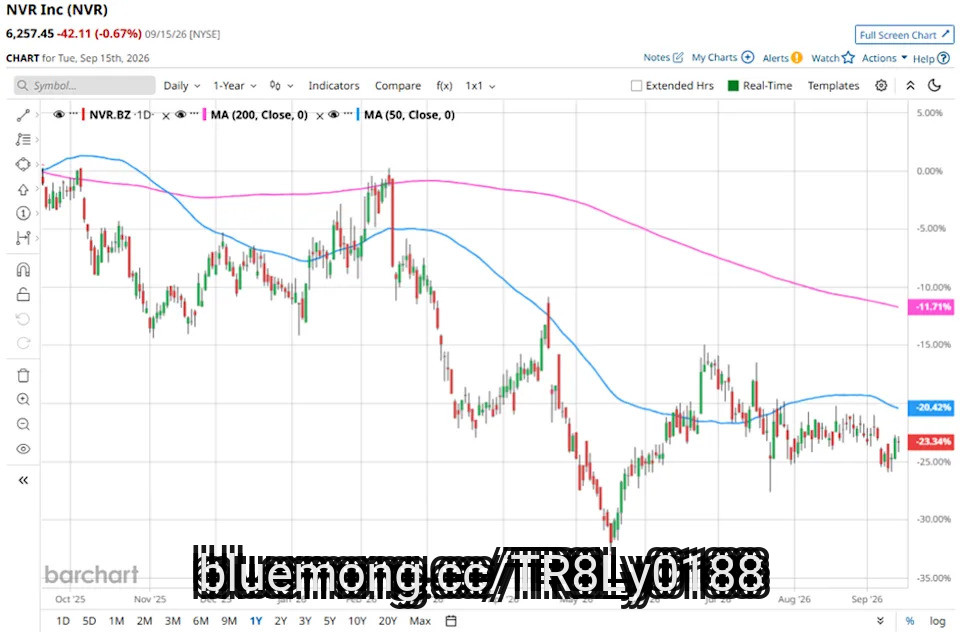
With a market cap of $16.7 billion, NVR, Inc. (NVR) is a leading company operating through two primary business segments: homebuilding and mortgage banking. Its homebuilding segment constructs and sells homes under the Ryan Homes, NVHomes, and Heartland Homes brands.
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and NVR fits this criterion perfectly. The company serves customers across 37 metropolitan areas in 16 states and Washington, D.C.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#Companies
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and NVR fits this criterion perfectly. The company serves customers across 37 metropolitan areas in 16 states and Washington, D.C.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#Companies


2 months ago
Wasatch Global Investors, an ****** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Bloom Energy Corporation (NYSE:BE). Bloom Energy Corporation (NYSE:BE), designs and manufactures solid-oxide fuel cell systems for clean, reliable, on-site power generation. On September 15, 2026, Bloom Energy Corporation closed at $259.35 per share. Over the past month, Bloom Energy Corporation returned 25.51%, and its shares are up 225.53% over the past year. Bloom Energy Corporation has a market capitalization of $76.39 billion, and its stock has traded within a 52-week range of $61.37 to $351.28.
Wasatch Long/Short Alpha Fund stated the following regarding Bloom Energy Corporation (NYSE:BE) in its Q2 2026 investor letter:
"Turning to short positions, detractors from Fund performance were those stocks that rose in price. One of the largest detractors was Bloom Energy Corporation (NYSE:BE). Bloom Energy sells natural, gas-powered fuel cells that help data centers generate power on-site before the centers can connect to the electrical grid. Bloom's stock price has increased significantly in recent months, and we believe it is representative of some of the AI-related exuberance in the small cap market."
Bloom Energy Corporation (NYSE:BE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 116 hedge fund portfolios held Bloom Energy Corporation (NYSE:BE) at the end of the second quarter, up from 91 in the previous quarter. While we acknowledge the potential of Bloom Energy Corporation (NYSE:BE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Bloom Energy Corporation (NYSE:BE). Bloom Energy Corporation (NYSE:BE), designs and manufactures solid-oxide fuel cell systems for clean, reliable, on-site power generation. On September 15, 2026, Bloom Energy Corporation closed at $259.35 per share. Over the past month, Bloom Energy Corporation returned 25.51%, and its shares are up 225.53% over the past year. Bloom Energy Corporation has a market capitalization of $76.39 billion, and its stock has traded within a 52-week range of $61.37 to $351.28.
Wasatch Long/Short Alpha Fund stated the following regarding Bloom Energy Corporation (NYSE:BE) in its Q2 2026 investor letter:
"Turning to short positions, detractors from Fund performance were those stocks that rose in price. One of the largest detractors was Bloom Energy Corporation (NYSE:BE). Bloom Energy sells natural, gas-powered fuel cells that help data centers generate power on-site before the centers can connect to the electrical grid. Bloom's stock price has increased significantly in recent months, and we believe it is representative of some of the AI-related exuberance in the small cap market."
Bloom Energy Corporation (NYSE:BE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 116 hedge fund portfolios held Bloom Energy Corporation (NYSE:BE) at the end of the second quarter, up from 91 in the previous quarter. While we acknowledge the potential of Bloom Energy Corporation (NYSE:BE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund


2 months ago
Rocket Lab (RKLB) stock has traded between $39.48 and $150.23 over the past 52 weeks. It now sits about 58% below its 52-week high, and anyone who bought twelve months ago is still up about 19%. None of that tells you what you would be buying today. Rocket Lab sells two quite different things, and the one its name points at is the smaller of them.
In Q2 2026 the ****** e Systems segment brought in $189.5 million. Launch Services brought in $44.6 million, down 30% from the previous quarter despite a similar number of launches. Management attributes that drop to accounting rather than lost work, because revenue from those launches is recognized over time and much of it had already been booked.
So Rocket Lab earns most of its revenue building satellites and their parts. Electron flew its 16th mission of 2026 in September. Launch is a real franchise, and it is not where most of the money comes from.
The stock trades at 52 times sales, against 3.1 for the S&P 500, on revenue of about $0.8 billion over the trailing twelve months. At this valuation, investors are largely pricing in future execution on the Neutron medium-lift rocket and the financial impact of the pending Iridium acquisition, rather than current satellite production alone. Management targets delivery to the pad in Q4 2026, and says the window for a launch before the end of 2026 is narrowing.
And you are paying for Iridium, which Rocket Lab has agreed to buy and expects to close in mid-2027. Iridium, a global satellite communications network, serves more than 2.5 million subscribers and delivered over $870 million of revenue in its past year. That is more than Rocket Lab's whole trailing twelve months. Management calls it a relatively slow-growing business that brings profit rather than a hole in the income statement.
#million #management #revenue
In Q2 2026 the ****** e Systems segment brought in $189.5 million. Launch Services brought in $44.6 million, down 30% from the previous quarter despite a similar number of launches. Management attributes that drop to accounting rather than lost work, because revenue from those launches is recognized over time and much of it had already been booked.
So Rocket Lab earns most of its revenue building satellites and their parts. Electron flew its 16th mission of 2026 in September. Launch is a real franchise, and it is not where most of the money comes from.
The stock trades at 52 times sales, against 3.1 for the S&P 500, on revenue of about $0.8 billion over the trailing twelve months. At this valuation, investors are largely pricing in future execution on the Neutron medium-lift rocket and the financial impact of the pending Iridium acquisition, rather than current satellite production alone. Management targets delivery to the pad in Q4 2026, and says the window for a launch before the end of 2026 is narrowing.
And you are paying for Iridium, which Rocket Lab has agreed to buy and expects to close in mid-2027. Iridium, a global satellite communications network, serves more than 2.5 million subscribers and delivered over $870 million of revenue in its past year. That is more than Rocket Lab's whole trailing twelve months. Management calls it a relatively slow-growing business that brings profit rather than a hole in the income statement.
#million #management #revenue

2 months ago
Exton, Pennsylvania-based West Pharmaceutical Services, Inc. (WST) designs, manufactures, and sells containment and delivery systems for injectable drugs and healthcare products. Valued at $25.7 billion by market cap, the company's technologies include the design and manufacture of packaging components, research and development of drug delivery systems, and contract laboratory services and other services.
Companies worth $10 billion or more are generally described as "large-cap stocks," and WST perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the medical instruments & supplies industry. WST stands out as a market leader with a diversified portfolio serving pharma and healthcare.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#Stock #billion
Companies worth $10 billion or more are generally described as "large-cap stocks," and WST perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the medical instruments & supplies industry. WST stands out as a market leader with a diversified portfolio serving pharma and healthcare.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#Stock #billion



2 months ago
Between 2023 and 2025, Nvidia (NASDAQ: NVDA) was the market's most obvious artificial intelligence (AI) trade. During this period, the stock went parabolic, surging by 1,180% and turning the chipmaker into the world's most valuable company by market cap. On a split-adjusted basis, that was a climb from about $14 per share to $186 by the end of 2025.
Currently, Nvidia stock sits around $218, up another 17% year to date. This is what it looks like when a company owns a scarce product that's in heavy demand -- in this case, graphics processing units (GPUs).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron Technology's (NASDAQ: MU) rocket-like move came a bit later, but hit much harder. Memory chips were an afterthought during the initial GPU gold rush. But as training clusters got larger and inference workloads got hungrier, supplies of high bandwidth memory (HBM) started running short. Prices for HBM soared, and Micron stock responded epically -- rising 239% in 2025 and another 242% so far this year. This type of price action indicates the market has recognized that memory is no longer just another tech commodity -- its supply is one of the key bottlenecks dictating the pace at which data centers can be built.
Nvidia and Micron are not the same bet. While Nvidia sells engines, Micron is selling the tanks for the fuel these engines cannot operate without. This begs the question: At this point, which of these AI chip stocks would be the better one to buy and hold for the next five years?
#signal #Stock #chipmaker
Currently, Nvidia stock sits around $218, up another 17% year to date. This is what it looks like when a company owns a scarce product that's in heavy demand -- in this case, graphics processing units (GPUs).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron Technology's (NASDAQ: MU) rocket-like move came a bit later, but hit much harder. Memory chips were an afterthought during the initial GPU gold rush. But as training clusters got larger and inference workloads got hungrier, supplies of high bandwidth memory (HBM) started running short. Prices for HBM soared, and Micron stock responded epically -- rising 239% in 2025 and another 242% so far this year. This type of price action indicates the market has recognized that memory is no longer just another tech commodity -- its supply is one of the key bottlenecks dictating the pace at which data centers can be built.
Nvidia and Micron are not the same bet. While Nvidia sells engines, Micron is selling the tanks for the fuel these engines cannot operate without. This begs the question: At this point, which of these AI chip stocks would be the better one to buy and hold for the next five years?
#signal #Stock #chipmaker

2 months ago
Chemical manufacturer OXEA has selected Uber Freight as its strategic logistics provider across the U.S., Canada, Mexico and Europe as the company moves to consolidate regional transportation operations into a more unified global network.
Houston-based OXEA said Uber Freight will manage day-to-day transportation execution across truckload, rail and ocean freight, using technology, data and logistics services to provide greater visibility across the chemical manufacturer's supply chain.
The agreement represents Uber Freight's (NYSE: UBER) first managed transportation engagement designed from the outset to span the U.S., Canada, Mexico and Europe, according to the companies.
OXEA manufactures oxo intermediates and oxo performance chemicals used in products including coatings, lubricants, cosmetics, pharmaceuticals, flavors and fragrances, printing inks and plastics. The company employs more than 1,200 people and sells chemicals in more than 60 countries.
The partnership is intended to replace a more regionally segmented approach to transportation management with an integrated operation connecting OXEA's plants, carriers and customers.
#Mexico #chemical #Logistics
Houston-based OXEA said Uber Freight will manage day-to-day transportation execution across truckload, rail and ocean freight, using technology, data and logistics services to provide greater visibility across the chemical manufacturer's supply chain.
The agreement represents Uber Freight's (NYSE: UBER) first managed transportation engagement designed from the outset to span the U.S., Canada, Mexico and Europe, according to the companies.
OXEA manufactures oxo intermediates and oxo performance chemicals used in products including coatings, lubricants, cosmetics, pharmaceuticals, flavors and fragrances, printing inks and plastics. The company employs more than 1,200 people and sells chemicals in more than 60 countries.
The partnership is intended to replace a more regionally segmented approach to transportation management with an integrated operation connecting OXEA's plants, carriers and customers.
#Mexico #chemical #Logistics


2 months ago
Daytona Beach, Florida-based Brown & Brown, Inc. (BRO) markets and sells insurance products and services in the United States and internationally. Valued at a market cap of $22.9 billion, the company operates through Retail and Specialty Distribution segments and provides property and casualty insurance, employee benefits insurance, personal insurance, specialty insurance, and more.
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." BRO fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the insurance brokers industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#market #Stock #daytona #united
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." BRO fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the insurance brokers industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#market #Stock #daytona #united