15 hours ago
Generating $1,000 a month in dividends is a simple process but it usually requires a substantial capital outlay. The Schwab U.S. Dividend Equity ETF (NYSEMKT: SCHD) is perhaps the best dividend ETF for accomplishing this. Not only does it offer a much-above-average yield, but it's also backed by a portfolio of durable, high-quality companies.
That's exactly what you want in your portfolio, so let's run through the path for how to get there.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The Schwab U.S. Dividend Equity ETF tracks the Dow Jones U.S. Dividend 100 Index. It starts with a universe of U.S. equities that have paid dividends for at least 10 consecutive years. From there, it examines the stock's dividend growth rate, yield, and several fundamental metrics, including return on equity (ROE) and cash flow-to-debt ratio. The 100 stocks with the best combination of these factors make the cut for the portfolio.
It's the combination of dividend yield and dividend quality that makes this fund so effective. The screens act as cross-checks on each other, so investors can get the best of both worlds. Choosing stocks based solely on yield can leave investors vulnerable to yield traps or potential dividend cuts. The quality screen here helps steer clear of that and gives people a sustainable high yield along with the quality portfolio.
#Dividend


19 hours ago
Welltower (WELL) pays out only 52% of normalized FFO, while Ventas (VTR) raised its dividend 8% and improved leverage to a decade-low 4.4x.
Baby boomers turning 80 now number nearly 70 million, yet builders started only 1,000 new senior housing units last quarter.
Sabra's 6% yield comes with a dividend flat since 2020 and a $102 million non-cash loan loss provision recorded in Q2.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Welltower didn't make the cut. Enter your email to see the names that beat WELL. The report is free. Enter your email and see if any of your stocks made the cut.
Senior housing has one of the clearest demand stories in real estate. On its third-quarter call, Ventas (NYSE:VTR) noted that the baby boomer generation, a cohort of nearly 70 million individuals, began turning 80 this year. Builders started only 1,000 units of new senior housing in the quarter. More 80-year-olds and very few new buildings push occupancy and rents higher, but operator health, labor costs, and government reimbursement decide how much of that reaches shareholders. The four REITs below are all equity REITs that own buildings. None is a mortgage REIT. Dividend safety is measured on FFO, FAD, or AFFO coverage, the cash-flow figures REITs actually pay dividends from.
#senior #million #housing #ventas

24 days ago
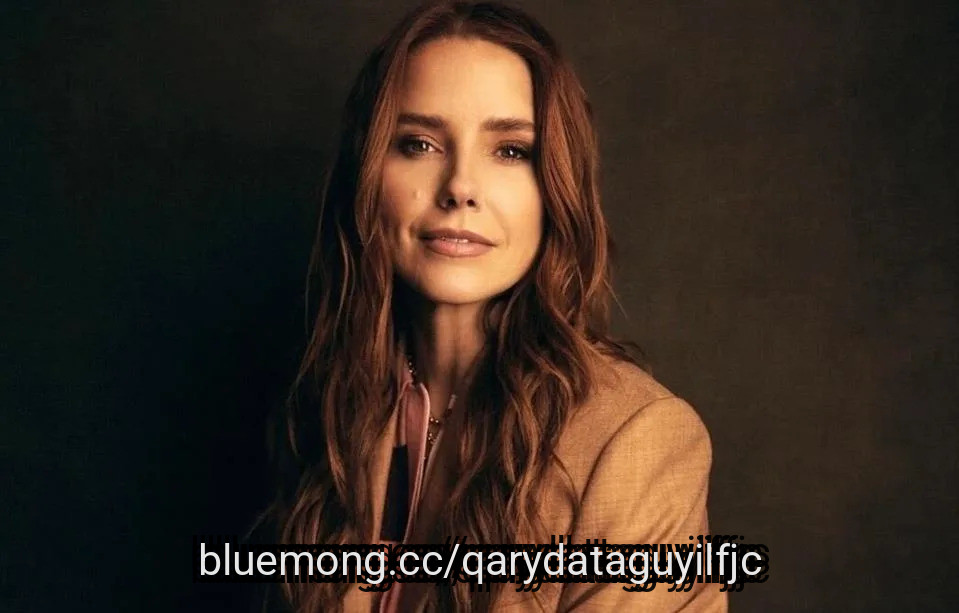
Sophia Bush
The dichotomous trap of women needing to achieve absolute, contradictory perfectionism rang loud and clear in America Ferrera's now iconic speech in the 2023 Barbie movie and it certainly continues to resonate with Sophia Bush, who has never shied from speaking about mental health challenges.
"I think there's a lot of reasons we're still having this conversation," says Bush, who currently stars in Hulu psychological thriller Count My Lies and Grey's Anatomy (ABC), and is attached to reprise her role as Brooke Davis in Netflix's One Tree Hill sequel series.
"First and foremost, society only functions at the level it does because of women's unrecognized and unpaid labor. So the world is not exactly motivated to shift things in our favor because people feel like it'll come at a cost," she says. "But now we understand because of the data around those things… that if you could snap your fingers and create pay equity across gender lines—everyone would be doing better if women were doing better."
Bush cites a litany of women's rights that have been or are being rolled back. "They overturned Roe. Christian nationalism is on the rise and they don't think women should vote," she says. She points to the SAVE (Safeguard American Voter Eligibility) Act and the tens of millions of married women in the U.S. the legislation would block from voting.
#things

24 days ago
Investing.com -- Shares of Chipotle Mexican Grill (NYSE: CMG) and Starbucks (NASDAQ: SBUX) swung sharply Thursday following a Financial Times report that Starbucks has explored a potential acquisition of the burrito chain.
Before you buy NVIDIA: our AI model's stock picks are beating the market by 120%+. See the list now »
Chipotle shares initially jumped as much as 8% following the report, while Starbucks fell as much as 6%. Both stocks later pared those moves as investors weighed the potential implications of a deal.
Whispers of a potential tie-up had circulated previously, including a report from Semafor, but the speculation was largely dismissed by the market at the time. The Financial Times report carries greater weight, indicating that Starbucks has worked with advisers in recent months on a potential proposal for Chipotle, which currently has a market value of nearly $39 billion.
The sharp divergence in the stocks, however, could complicate the financial mechanics of a potential transaction. Starbucks' declining share price would reduce the value of any equity used as consideration, while Chipotle's rally increases the price Starbucks would need to pay for the company. The status of Starbucks' plans, including whether it has made a formal offer, remains unclear.
#starbucks #market #shares


24 days ago
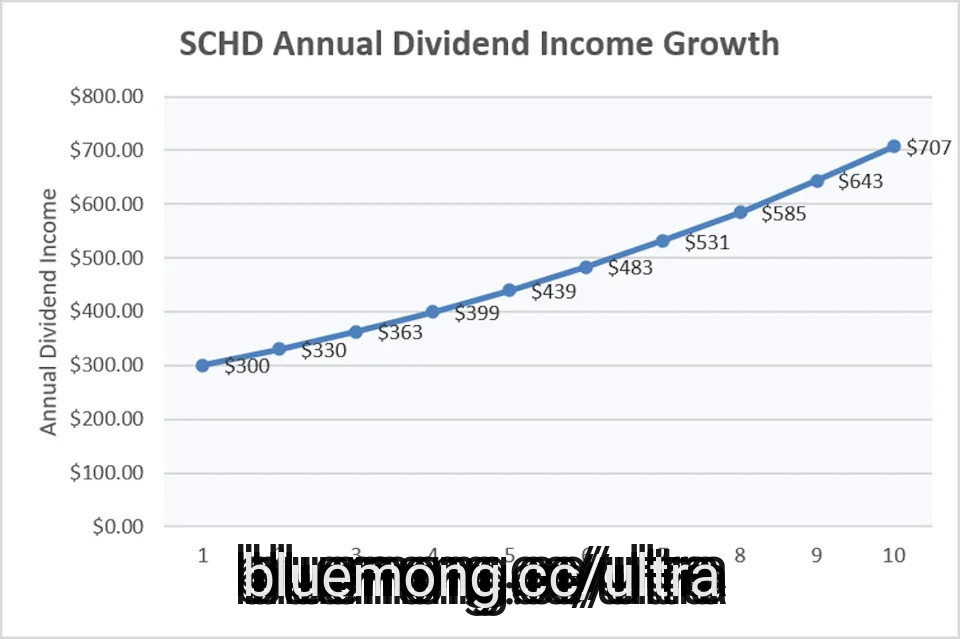
The 10-year Treasury yield recently hit its highest level in 24 years at 5.3%. That high yield has income-seeking investors wondering whether to load up on Treasuries while they're at a historically high level.
Here's a look at how much passive income you can generate over the next 10 years on Treasury bonds compared to another popular income-focused investment: the Schwab U.S. Dividend Equity ETF (NYSEMKT:SCHD).
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: Getty Images.
A 10-year Treasury bond is a fixed-income investment backed by the full faith and credit of the U.S. government. It's a global financial benchmark that influences the rates of almost all consumer and corporate credit, including mortgages.
#treasury #missed #year #investors


24 days ago
It's common for new investors to want to hit home runs in their first at-bats. That situation is arguably amplified at a time when major equity indexes are regularly hitting record highs.
With glamorous, high-octane growth stocks leading the charge, some market participants may be losing sight of the value of the singles-and-doubles approach to dividend investing. Those investors shouldn't ignore history. Though the percentage trended lower over the past decade due to the prominence of low-yield and non-dividend tech darlings, dividends accounted for about a third of the S&P 500's total returns over the past century.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Most investors don't think in 100-year increments, and that's understandable, but when it comes to dividend investing, history and long-term perspectives matter. And the Schwab U.S. Dividend Equity ETF (NYSEMKT: SCHD) is a prime example of a dividend exchange-traded fund (ETF) with a compelling history for long-term investors.
Locked in a seemingly daily battle with the Vanguard Dividend Appreciation ETF for the ******* le of the largest dividend ETF, the $108 billion Schwab fund has a nearly unmatched track record. Two weeks shy of its 15th birthday, this ETF, which tracks the Dow Jones U.S. Dividend 100 Index, has returned 532% since its launch.
#investors

25 days ago
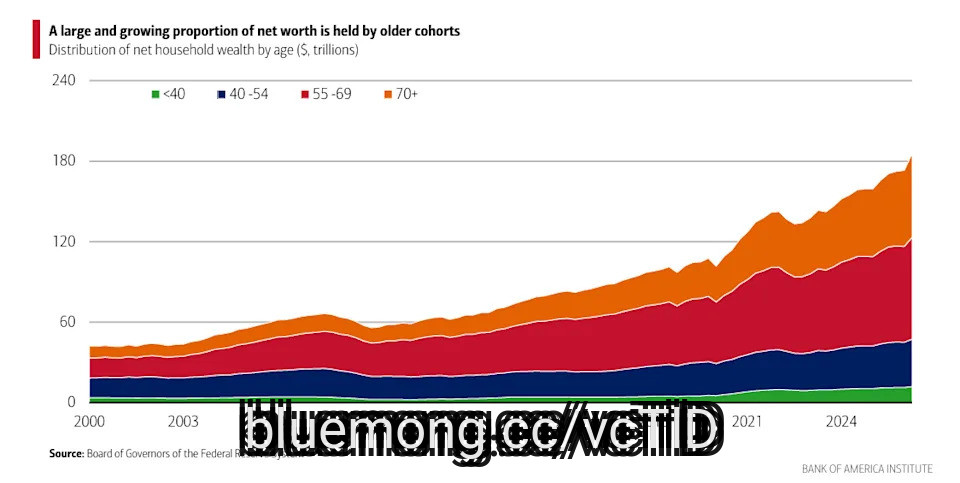
America's older households sit on nearly $140 trillion in wealth, and much of it showed up recently.
Households age 55 and over held around three-quarters of the nation's total net worth in the second quarter of 2026, according to an Oct. 1 report from Bank of America Institute, based on ******* ysis of Federal Reserve data. "With equity markets rising strongly," wrote senior economist David Michael Tinsley, those households have seen "a more than 20% increase in their net worth over the past two years."
That rally has run on AI. The Magnificent Seven accounted for more than half of the S&P 500's gains last year, Fortune reported in April, and Goldman Sachs strategists found technology stocks drove 85% of the index's return through mid-May this year. "AI-driven return has been the single most important structural driver of equity performance," Capgemini's Luca Russignan told Yahoo Finance in June. Boomers own 54% of all U.S. stocks.
That's a lopsided split. Americans 55 and over make up about 31% of the population, according to Census Bureau estimates, but control roughly 75% of its net worth.
The pile gives many older Americans what the institute calls "considerable capacity to spend on travel and other leisure categories." Add their growing share of the population and their extra free time, and they become an increasingly influential market for businesses chasing consumer dollars. The BofA report focused mainly on the economic implications of a growing mass of older consumers, but the generational wealth composition was striking.
#households #institute #according #report

25 days ago
The 2020s will go down in history as one of the best times to be a stock market investor. After a brief dip in 2022, the benchmark S&P 500 (SNPINDEX: ^GSPC) has soared by an average of roughly 21% per year -- double its 100-year average annual return of 10%.
That said, history shows us that significant drawdowns often follow periods of unusually elevated stock market gains as the market reverts to its long-running mean. Let's discuss some of the challenges facing this bull market to try to figure out what might come next.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
By now, most investors have probably heard about the cyclically adjusted price-to-earnings (CAPE) ratio. This metric compares the price of the S&P 500 with its average inflation-adjusted earnings over the past decade. The long time frame smooths out short-term fluctuations, providing a clearer picture of the market's value relative to historical norms.
Right now, the CAPE ratio stands at 40.5, which is well above its average of 17.4. The other two major peaks occurred before the Great Depression in 1929 and during the dot-com bubble in 1999, when it hit its all-time high of 44.19. Both milestones were followed by substantial declines in equity prices over the subsequent years as the speculative bubbles deflated.
#missed #Stock #long #investors
25 days ago
AGNC's Q2 spread income of 40 cents per share covered its 36-cent dividend, but the payout has been cut three times since 2015.
Annaly raised its quarterly dividend from $0.70 to $0.75, while Dynex rebounded to 6.4% economic return after both posted Q1 losses.
If Q3 spread income falls below 36 cents or book value drops below $8.38, shareholders' own capital funds the dividend and a cut becomes likely.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
AGNC Investment (NASDAQ:AGNC) is a mortgage REIT that borrows short-term money in the repo market, buys agency mortgage-backed securities, and keeps the spread between bond yields and borrowing costs. Leverage of 7.4 times tangible equity magnifies both gains and losses.
#times

25 days ago
AGNC Investment has seen a mix of setbacks and gains in recent years, which raises a straightforward question for anyone looking at the stock today: Is the current share price meaningfully supported by the returns the business earns on its capital base?
Over the past 3 years, AGNC Investment has delivered a total return of about 48.1%, which puts real weight on whether those past gains are grounded in sustainable returns on the equity it deploys.
The mortgage REIT model relies on how efficiently AGNC Investment can fund and reinvest its portfolio. The valuation story therefore hinges on whether that capital structure can keep generating attractive excess returns after funding costs and hedging.
What if you looked at AGNC Investment through its earnings instead? See what AGNC Investment's 4.9x P/E says about the price.
For investors, the debate is whether AGNC Investment's current price fairly reflects the level and quality of the returns it earns on its capital.
#investment #returns #whether #earns

26 days ago
A $300,000 investment in SCHD grew to $468,150 over five years versus $573,900 in VOO, leaving a $105,750 gap driven by missing big tech.
SCHD's dividend quality screen kept out the tech giants that led the market, yet that same tilt powered its 23.86% one-year return.
SCHD suits retirees drawing income today, but younger investors should know the yield cost a $300,000 account over $100,000 in five years.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Putting $300,000 into the Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD) on October 1, 2021 left a holder with $468,150 by October 5, 2026. The same money in the Vanguard S&P 500 ETF (NYSEARCA:VOO) grew to $573,900. That leaves a shortfall of $105,750.
#nysearca #Dividend #income #same

26 days ago
FYEE beat JEPI on a $100,000 investment in 2026, paying $7,023 versus $6,070, but FYEE's quarterly payout has fallen from $0.82 to $0.56 per share.
JEPI's monthly distributions better match recurring expenses for retirees, while FYEE's quarterly schedule suits investors who reinvest or can wait between payments.
FYEE's lower share price ($30 vs. JEPI's $56) means $100,000 buys nearly twice as many shares, which is why it delivers more cash despite lower per-share payouts.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
The JPMorgan Equity Premium Income ETF (NYSEARCA:JEPI) built its following on a simple promise. It holds lower-volatility U.S. stocks, adds income from S&P 500 call-option premium, and sends a check every month. JEPI holders value that rhythm, and JEPI remains the default name in covered-call income. On an identical $100,000 investment this year, though, the Fidelity Yield Enhanced Equity ETF (CBOE:FYEE) has paid more cash while writing far fewer checks.
#income #quarterly

26 days ago
(Bloomberg) -- McKesson Corp. and the private equity firm Clayton Dubilier & Rice will buy Option Care Health Inc. for an enterprise value of about $5.8 billion, expanding into the medical infusion ***** e.
Most Read from Bloomberg
New Hazard for Treasuries Hides in Bond Futures' Fine Print
Manchester City Verdict Strains UK-UAE Diplomatic Relations
As Thailand Cracks Down on Foreigners, a Tourist Paradise Reconsiders Its Welcome
#care
Most Read from Bloomberg
New Hazard for Treasuries Hides in Bond Futures' Fine Print
Manchester City Verdict Strains UK-UAE Diplomatic Relations
As Thailand Cracks Down on Foreigners, a Tourist Paradise Reconsiders Its Welcome
#care


26 days ago
Burry is mitigating near-term tax selling in underperforming holdings.
The investor foresees an early end to the artificial intelligence boom, positioning for a 2000–2003 style value equity revival.
Significant capital is being directed into discounted Chinese equities like BYD, while maintaining a cautious stance on Alibaba amidst its infrastructure spending.
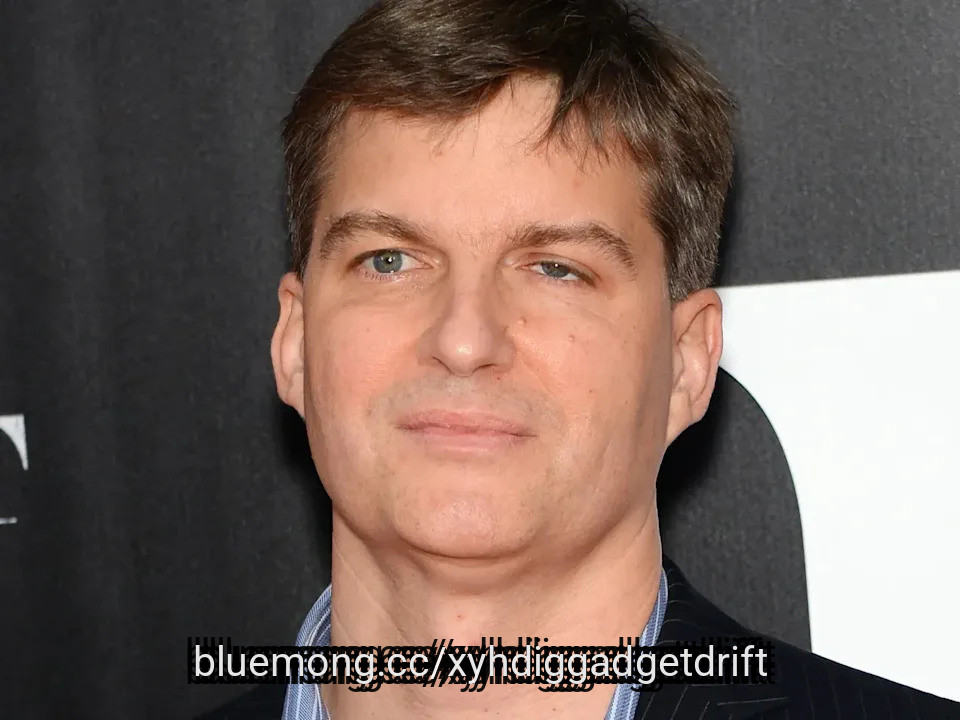
Renowned value investor Michael Burry outlined his fourth-quarter portfolio maneuvers in an update on his Cassandra Unchained Substack platform on Monday, revealing how he is positioning around tax-loss harvesting headwinds while building long-term exposure to deeply discounted sectors.
Burry noted that the final quarter routinely brings heightened selling pressure on underperforming equities as investors sell underperforming ***** ets at a loss to offset capital gains.
#burry #positioning #capital #equities

29 days ago
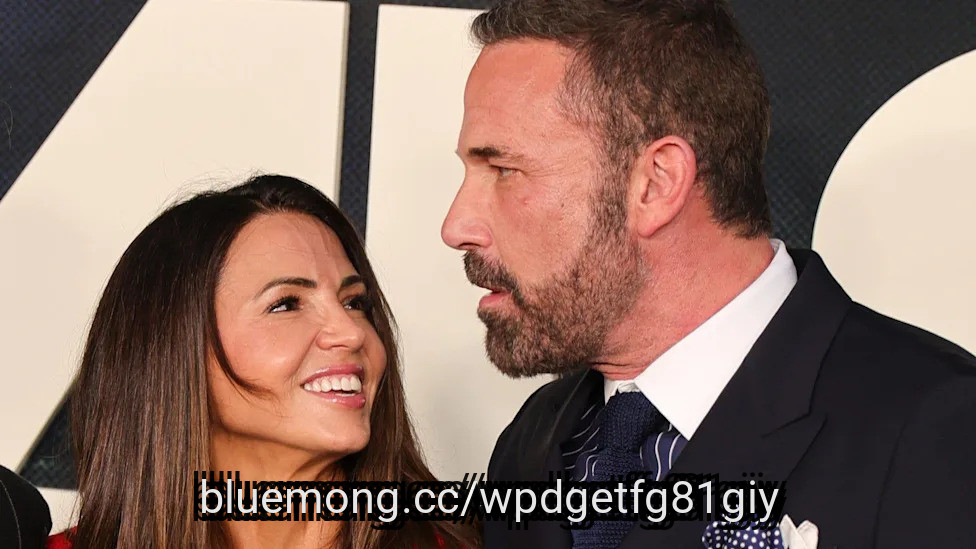
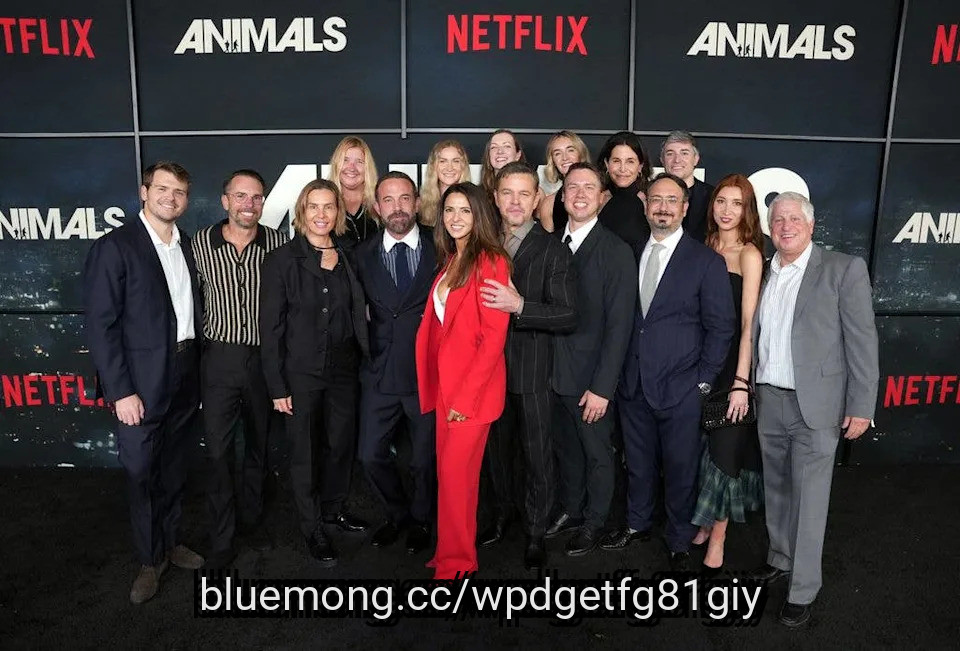
In a sea of black, Matt Damon's wife, Luciana Barroso, boldly stood out from the crowd in a red hot pantsuit as she attended the LA premiere of the new movie, Animals.
Luciana, a partner in Artists Equity, the independent, artist-led production studio co-founded by Matt and Ben Affleck in November 2022, was joined by her husband and Ben on the red carpet, with the mom-of-four giggling away as she posed between the best friends.
The producer paired the vibrant red Gabriela Hearst suit – which featured high rise pleated pants and a matching blazer with large lapels – with a chic cream camisole.
She wore her hair loose around her shoulders, and let her natural beauty shine through with minimal makeup, and accessorized with simple pearl drop earrings.
Luciana is known for her timeless red carpet fashion.
#luciana #matt #carpet #artists




1 month ago
Like every job in Hollywood, managers have grappled with plenty of change in their work in the last decade. Luckily for Range Media Partners' Cora Olson and Michael Diamond, they have each other.
The duo has worked as a unit for 10 years, since being brought together at Mgmt Entertainment and eventually grew to run the lit division. They joined Range as partners in 2024 with a desire to evolve alongside the modern talent management firm, founded during the pandemic by a collective of former CAA, UTA and WME agents hoping to shake things up in the entertainment marketplace. The management company operates its talent representation business alongside an in-house production studio, allowing the operation to finance, develop and build equity in intellectual property.
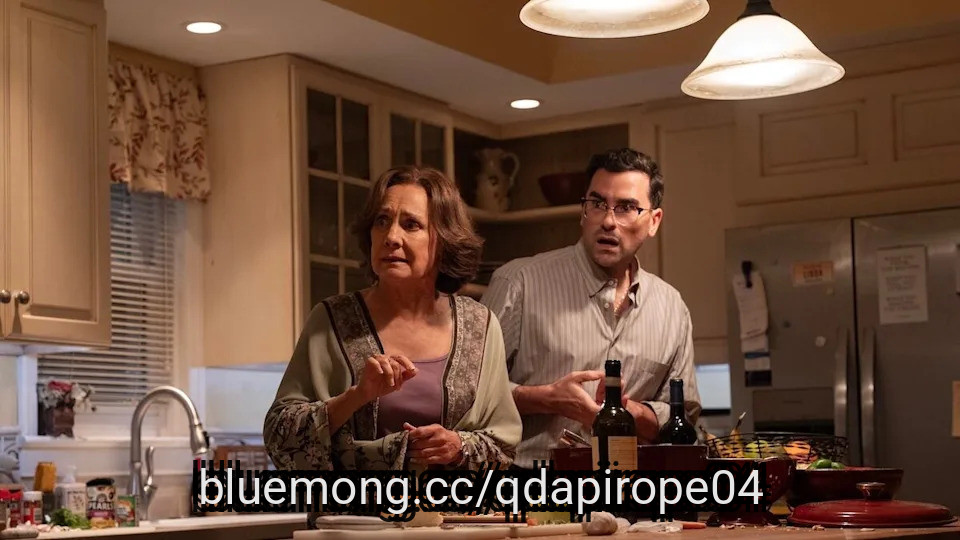
All those contributing factors can help when putting together the right package to get a film or TV project off the ground in today's precarious Hollywood model — one with fewer greenlit projects and a reliance on safer bets from major distributors. But Olson and Diamond, who represent Hollywood big shots like "Schitt's Creek" Emmy winner Dan Levy, actress-producer-director Kyra Sedgwick and "Pig" filmmaker Michael Sarnoski, counter the ****** umption that original ideas are a tougher sell.
It just takes more work to get there.
"You're not just marrying this actor with this part, or this writer with this ****** ignment. It's not as much mix-and-match as it used to be, because there isn't that same amount of volume," Olson told Office With a View. "If you look at the shows and movies that are breaking through right now, it's those really fresh points of view that seem to resonate with audiences."
#diamond #partners

1 month ago
On September 9, 2026, Independence Realty Trust, Inc. (NYSE:IRT) and Centerspace announced a definitive all-stock merger agreement. It creates a combined middle-market apartment REIT with a pro forma equity market capitalization of about $5.0 billion and a total enterprise value of approximately $8.1 billion, encompassing more than 44,000 units.
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management

1 month ago
The transition toward renewable energy is creating massive opportunities for infrastructure providers. Eos Energy Enterprises (NASDAQ:EOSE) and GE Vernova (NYSE:GEV) represent two distinct ways to play this trend in 2026.
Eos focuses on specialized zinc-based batteries for long-duration energy storage. GE Vernova is a diversified giant that services a massive portion of the world's electricity grid. Comparing these two helps clarify whether you prefer a high-growth disruptor or an established power leader.
Eos Energy Enterprises produces aqueous zinc batteries designed as a safer, scalable alternative to lithium-ion. It operates primarily within the industrial stocks **** e, targeting utilities and commercial developers. Customer concentration like this adds a layer of risk to the business, as two clients accounted for approximately 70% of total revenue in 2025.
In FY 2025, revenue reached approximately $114.2 million. This represents growth of nearly 631.8% compared to the prior fiscal year. The company reported a pre-tax net loss of roughly $969.6 million, resulting in a negative net margin of approximately 849.1%.
As of its December 2025 balance sheet, the company had a debt-to-equity ratio of -1.0x. This value indicates that total liabilities exceed shareholder equity. The current ratio, which measures the ability to cover short term obligations with short term **** ets, was approximately 4.9x, while free cash flow was nearly negative $265.0 million.
#enterprises #massive #Growth

1 month ago
Morgan Stanley met privately with Gilead Sciences (GILD) leadership at its 2026 Global Healthcare Conference this month, and the feedback strengthened the bank's positive view on the stock.
Morgan Stanley's biopharma team hosted a meeting and a management dinner with Gilead Chairman and CEO Daniel O'Day and Chief Commercial and Corporate Affairs Officer Johanna Mercier. According to a Morgan Stanley research note shared with me, the discussion reinforced its Overweight rating on Gilead and singled out one franchise as the biggest reason to stay positive.
Gilead trades around $150.89, up about 24% year to date and roughly 111% over five years. That kind of run in a biotech stock usually needs a catalyst, and Morgan Stanley points to HIV prevention. The bigger question for investors now is whether the new HIV prevention business built around Yeztugo can keep growing at the pace of the last few quarters.
Terence Flynn, a Morgan Stanley equity **** yst who covers Gilead and other healthcare stocks has held an Overweight rating on the stock since January 2025.
According to the note, Gilead management described the company as being at "an important inflection point, supported by what it views as the most robust portfolio in the company's history," with no patent expiring until 2036.
#gilead #healthcare #management #note

1 month ago
Enbridge Inc. (NYSE:ENB) has declined by around 17% since hitting its record high in May, likely as a result of rising bond yields, lack of visibility on the company's 5% growth guidance through the end of the decade, and the recently closed equity offering intended to fund the midstream operator's strategic acquisitions.
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target


1 month ago
Interested in Apollo Global Management Inc.? Here are five stocks we like better.
Apollo expects interest rates to remain higher for longer, while estimating only a 10%–20% chance of a recession over the next year. Consumer spending, inflation and AI infrastructure investment are supporting economic activity, though geopolitical and energy risks remain.
The firm views AI primarily as a large-scale financing opportunity, providing structured capital to investment-grade companies involved in digital infrastructure, energy, logistics and defense rather than betting on individual technology winners.
Apollo reported strong institutional fundraising, including a $12 billion first close for its Fund XI, and expects private-equity industry consolidation as smaller or overexpanded managers struggle to return capital. Its high-grade capital-solutions business has completed more than 200 transactions totaling roughly $150 billion.
Baggage Claim: Apollo's $7.7 Billion Bid to Acquire easyJet
#apollo #infrastructure #energy #grade

1 month ago
GDEV Inc. (NASDAQ:GDEV) saw a year-on-year drop in bookings from both its in-app purchases and advertising, during the second quarter fiscal 2026. Consequently, the quarterly revenue figure of $94 million was down 22% compared to Q2 FY25. On the flip side, SG&A expenses and costs related to platform commissions were lower relative to the corresponding period last year. Along with other factors, the lower cost base helped GDEV report $20 million in net profit, up from $17 million in the second quarter of 2025.
Copyright: artush / 123RF Stock Photo
Breaking down the expenses, selling and marketing costs came down by 38% compared to the same quarter last year, clocking in at $33 million. It reflects on management's continued focus on deploying an efficient approach for its user acquisition initiatives. The approach is based on a more targeted performance marketing across certain channels that lead to durable high-value users, instead of broader campaigns for near-term benefits.
The reported quarter marked a turnaround related to the equity accounted ******* ociates. These contributed a $2 million profit share, which was a reversal from a $2 million loss share in Q2 FY25. Most notably, cash flows from operating activities turned from negative $10 million in Q2 FY25 to positive $10 million in the reported period.
Several operating metrics weakened during the reported quarter. Monthly paying users dropped by 23% year-over-year, along with a 15% decline for the entire first half. This was the major underlying reason for a sluggish performance in bookings, which stood at $73 million and $156 million for the second quarter and first half of the year, respectively. These fell short in comparison to $92 million and $173 million recorded in the corresponding periods last year. GDEV also said the decline in first-half platform commissions was driven by lower revenues recognized from PC platforms, while PC's share of bookings fell to 36% from 39%.
#million #lower

1 month ago
Super Micro Computer (SMCI) stock rose 9.5% on Thursday, September 17, closing just over $40. The move followed a bullish call on how big the market for AI servers gets. That call may well be right. But it answers a question Super Micro's own results never raised. That is why one big session tells you less than it looks like it does.
Analysts at Goldman Sachs said the addressable market for AI servers will expand aggressively through the end of the decade. That is a forecast about an industry rather than about one manufacturer. Another account of Thursday morning's climb credited a broader equity rebound after Wednesday afternoon's Federal Reserve rate decision, not the forecast. Hewlett Packard Enterprise (HPE) jumped 8.0% the same day against the S&P 500's 1.1% gain, showing that capital was rotating heavily into primary AI server makers.
Company-specific headlines that day ran the other way: after the close, a shareholder rights law firm issued a press release soliciting clients for a potential investigation into company management.
A bigger market is not what this company is short of. In its fiscal fourth quarter, ended June 2026, Super Micro booked over $60 billion of new orders. That backlog underpins management's fiscal 2027 revenue guidance of $65 billion to $72 billion—up sharply from the $39 billion booked over the prior twelve months, but spread out as delivery and deployment constraints allow customers to take delivery.
What it is short of is customers ready to take delivery. Super Micro sells data center building block solutions, which bundle the servers with the power, cooling, networking and software around them. The company's manufacturing capability is on track to include more than 3,000 direct liquid-cooled racks a month.
#forecast


1 month ago
SCHD delivers nearly double VIG's forward yield at roughly 3% compared to 1.7%, making it the stronger cash anchor for retirees funding withdrawals today.
Despite radically different portfolios, both funds produced nearly identical 10-year returns: VIG at 243% versus SCHD's 237%.
With the 10-year Treasury at 5%, rising rates are punishing VIG's growth tilt, and SCHD leads year-to-date by a wide margin of 25% to 8%.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Retirees weighing a dividend anchor keep landing on the same two funds: Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD) and Vanguard Dividend Appreciation ETF (NYSEARCA:VIG). They look like siblings but diverge sharply under the hood. SCHD screens hard for cash-flow quality and pays a meaningfully higher current yield. VIG buys only companies with 10-plus consecutive years of dividend increases and explicitly kicks out the highest-yielding quartile. That single rule sends the two funds toward very different portfolios, and it is showing up in the returns.
#Dividend #same #nearly #cash

1 month ago
The federal government is preparing to cash out a chunk of its stake in GlobalFoundries (GFS). A new filing shows Washington plans to sell as many as 9.9 million shares of the semiconductor firm, months after agreeing to take an equity position in the company.
For investors watching GFS stock, the move raises questions about what comes next, even as GlobalFoundries lands new government-backed deals in quantum computing and silicon photonics. Here is what the filing means, and why the government owned shares of GlobalFoundries stock in the first place.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#globalfoundries #months #filing



1 month ago
Corning (GLW) stock took a sharp hit this week after the company opened the door to a potential $2 billion equity offering that could dilute existing shareholders. The stock dropped 13.7% on Sept. 14, marking its worst one-day decline in years. At the same time, Corning is expanding its capacity and signing major deals with some of the world's biggest tech companies, including Nvidia (NVDA) and Amazon (AMZN). Its latest Verizon (VZ) agreement alone covers over 80 million miles of optical fiber and connectivity products through 2032. Corning shares have since recovered, shifting attention away from dilution fear to whether the capital raise was a sensible decision, how much stock Corning actually sells, how quickly Optical Communications grows, and whether new capacity generates the returns management expects.
Let's find out more on what matters for investors now.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#Stock #sept

1 month ago
On August 19, Ferrovial (NASDAQ:FER) announced it had been selected to deliver the I-24 Southeast Choice Lanes, a 26-mile project running between Nashville and Murfreesboro. It is the largest single capital investment in Tennessee's history and the state's first public-private partnership. The price tag is $9.2 billion, though Ferrovial isn't carrying it alone, since its DriveTN consortium also counts Transurban and Tikehau Star Infra as partners.
Choice lanes are familiar ground for Ferrovial, which has replicated the model in Washington, D.C., Charlotte and Dallas-Fort Worth. On Virginia's 66 Express corridor, similar lanes shaved up to 50% off peak-hour travel times. That is the pitch for I-24, a stretch of highway that already ranks among the region's most jammed: drivers who opt in get steadier speeds, and those in the free lanes should see less traffic too.
The business behind the bid looks healthy, too. Ferrovial's July 28 results showed adjusted EBITDA up 21.6% on a like-for-like basis to €746 million over the first six months of the year, with U.S. highways doing most of the lifting. Those roads are sending cash home as well, since Ferrovial received €357 million in dividends from North America. And the construction order book reached an all-time high of €18 billion, so plenty of work is already in hand. The pipeline keeps filling: Ferrovial bid on I-285 East in Georgia in July, and its D35 Highway bid in the Czech Republic was the most cost-effective submitted, with technical evaluation still underway.
Beyond the roads, the balance sheet looks sturdy. Ferrovial ended the first half with €1.3 billion in net cash, excluding infrastructure projects, meaning cash outweighs debt outside those projects. The airport arm is progressing too: Ferrovial has finished funding the $1.1 billion in equity it pledged for New Terminal One at JFK, and construction there is 92% complete.
Start with the line that looks worst on the page. Net profit for the first half of 2026 came in at €258 million, versus €540 million for the same period of 2025. That earlier figure included capital gains from ******* et rotation, which makes the comparison harsh, but the mismatch is still there: EBITDA climbed while reported profit fell.
#first #million #choice


1 month ago
Choosing between a niche equipment provider and a diversified industry **** an requires balancing high growth potential against established stability. Here is how Aehr Test Systems (NASDAQ:AEHR) and KLA (NASDAQ:KLAC) compare for investors.
Aehr Test Systems focuses on specific stress-testing solutions for power semiconductors and memory, while KLA provides broad process control tools used across the entire chip-making industry. While they both operate in the same sector, their scale and risk profiles differ significantly, making them attractive to different types of portfolios.
Aehr Test Systems designs and sells specialized equipment for the testing and stabilization of semiconductor products in various forms, including wafers and singulated dies. The company focuses on the high-growth silicon carbide market for electric vehicles and high-bandwidth memory for artificial intelligence infrastructure. In its 2026 fiscal year (FY), which ended May 29, its five largest customers accounted for nearly 70% of net sales, and customer concentration like this adds a layer of risk to the business.
In FY 2026, revenue reached $50.0 million, representing a decline of 15.2% compared to the previous year. This contraction followed a period of higher operating costs, resulting in a net loss of $7.1 million for the period. The net margin, which represents the percentage of revenue remaining as profit after all expenses, was -14.3% in the latest fiscal year.
As of its May 2026 balance sheet, the debt-to-equity ratio is zero, indicating that the company has no debt relative to its shareholder equity. The current ratio, which measures a company's ability to cover short-term liabilities with short-term **** ets, is 10.3x. Free cash flow, defined as cash from operations minus capital expenditures, was a negative $5.4 million for the fiscal year ended in May.
#year #equipment


1 month ago
First Phosphate Corp. (CSE:PHOS, NASDAQ:PHOS, FRA:KD0, OTCQX:FRSPF) earlier this week highlighted Swiss government support for financing linked to its Bégin-Lamarche mine, as CEO John Passalacqua outlined the company's efforts to ***** emble a capital stack designed to limit shareholder dilution.
Proactive: Really big news out from the company today. It really jumps off the page: a guarantee of $212.5 million for CapEx for First Phosphate, coming from the Swiss government. Tell me a little bit about this, John.
John Passalacqua: Yeah, so this is the Swiss government that's guaranteeing up to 85% of exports from Switzerland that are aimed towards the mine at Bégin-Lamarche. So you've got a very nice debt-to-equity ratio there. 85% is almost unheard of in the industry. And it's obviously based on the credibility of the mine, based on the fact that we've been endorsed by the G7, based on the fact that we have other export credit agencies at the table.
EIFO from Denmark was there already, if you remember, for €170 million. So little by little, we're putting together the whole capital stack here for the project, which can be done quite non-dilutively.
And that's a key to this because they're looking at about 85% of the cost, and potentially more if that happens. But it does get to the point where your shareholders are very well protected here.
#john #government #little #first


1 month ago
Are you worried enough about rising interest rates jump-starting a recession that you're looking for ways of sidestepping the effect of such an economic headwind? It's not a terrible idea to at least start making a mental plan for that possibility.
You may have considered Berkshire Hathaway (NYSE: BRKA) (NYSE: BRKB) to fill that role. Its wholly owned, private businesses generate plenty of cash flow regardless of the economic backdrop, after all.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
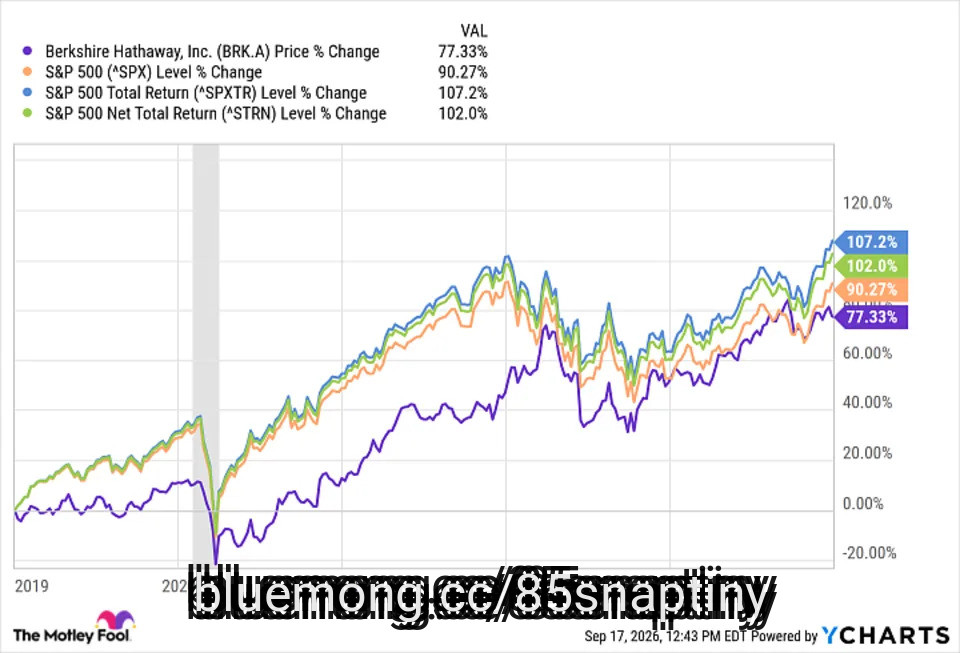
But how do Berkshire shares actually perform during recessions? It's not like the data doesn't exist.
You probably know Berkshire Hathaway best by its stock picks. Although they're not built to be an actively managed mutual fund, its equity holdings -- and changes to these holdings -- are closely followed by investors looking for some new ideas for their own portfolios.
#berkshire #signal #NYSE #flashing