

5 days ago
In a housing market where affordability is increasingly out of reach for many buyers, Vic Bulbon is looking at a type of property that's becoming less expensive: condominiums.
With national home prices near record highs and mortgage rates topping 7% in recent weeks, buying a home remains out of reach for many Americans. Condos appear to offer a rare bright spot, with prices falling across the country.
But even with cheaper sales prices, rising homeowners' **** ociation (HOA) fees and one-time special **** sments are driving up ownership costs.
Now, guidelines released this year by Fannie Mae and Freddie Mac, the government-sponsored agencies that back nearly half of all US home purchases, aim to reduce the financial and structural risks of condo buildings. Real estate agents told CNN that the changes could add pressure to the condo market by further driving up HOA fees, increasing the total monthly bill for condo owners, and potentially eroding the savings of a lower purchase price.
As of mid-October, condo sales prices lagged behind single-family home prices in 99 of the 100 largest markets in the United States, according to data from financial services company Intercontinental Exchange provided to CNN. Nationally, single-family home prices rose 1.5% from a year earlier, while condo prices fell 1.1%.
#prices #home #sales #year

13 days ago
On this day in 1988, it was announced that Sunderland made more than £250,000 in profit during the previous year on the way to clinching the Third Division Championship.
The year before saw a loss of around £125,000 – when the club was relegated from the Second Division for the first time in its history – the accounts released on this day in 1989 showed a turnaround of £375,000.
Increased match receipts of £450,482 and an interest-free loan of £600,000 by chairman Bob Murray were mostly responsible for the club showing a profit for the first time since 1985.
Average gates increased by around 4,000 to 17,426 to provide match receipts of £1,212,118, and though transfer fees were down on the previous year, the turnover increased by £233,273. The **** ets of the club stood at £39,224, the first positive figure since 1974, and this was a far healthier position than the previous year when net liabilities stood at £860,818. This pleased the chairman:
It's been worked for. There is still a long way to go despite turning a £½m loss in a period of 13 months ago into a profit of £250,000. I don't want to see Sunderland Football Club financially embarrassed again. I have been there when the hotel bill had to be paid before the players arrived. I don't want the club to be **** ociated with that sort of thing.
#year #increased #first

25 days ago
An XRP holder proposed raising XRP Ledger fees 100x, but even that hike would cost only $0.0015 per transaction, which amounts to a negligible dent across 63 billion circulating tokens.
David Schwartz called higher fees 'truly bizarre,' warning they would drive away payment processors and undermine XRP Ledger's core advantage of cheap, fast settlement.
Higher fees would force active users to subsidize passive holders, and any fee change requires validator approval, which is a threshold this proposal hasn't reached.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Recently, an XRP (CRYPTO:XRP) holder made a bold proposal on X, suggesting that XRP Ledger fees be raised 10 to 100 times to enable a larger XRP burn with each transaction. Burning tokens reduces the total supply, a move many holders support because it could increase the value of their remaining tokens.
#tokens #ledger



25 days ago
A federal judge has granted final approval to AT&T's $177 million settlement resolving lawsuits over two 2024 data breaches that exposed personal information belonging to millions of customers.
U.S. District Judge Sidney Fitzwater in Dallas approved the settlement Oct. 2, along with $59 million in attorneys' fees for lawyers who negotiated the deal, according to Reuters. The settlement faced dozens of objections, including arguments that the amount was inadequate compared to a $350 million settlement in separate litigation involving T-Mobile.
For AT&T customers who filed valid claims, the amount they receive depends on which data breach affected them, what information was exposed and whether they can document financial losses. Most customers receiving the tiered cash payments are expected to get far less than the settlement's advertised maximums.
Customers could receive between about $6.50 and $40 through the tiered payment system, according to court documents. Here's what to know.
The settlement has two funds totaling $177 million: $149 million for customers affected by the first data incident, known as AT&T 1, and $28 million for customers affected by the second incident, known as AT&T 2.
#million #settlement #information

25 days ago
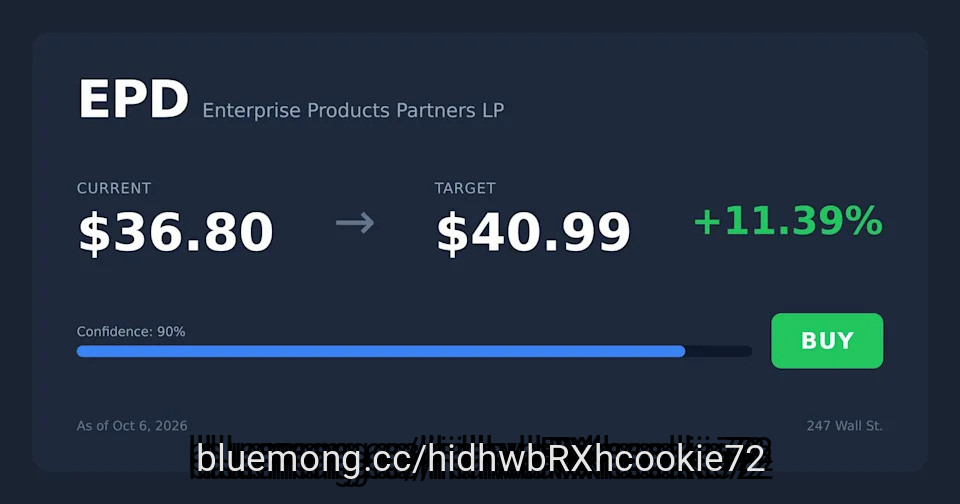
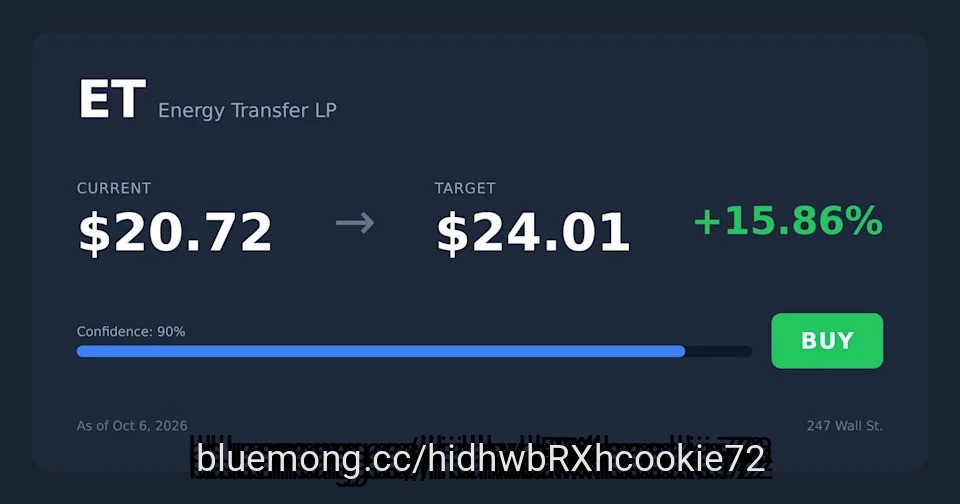
EPD yields 6.19% and ET yields 6.64%, turning a $100,000 equal split into $6,413 in annual passive income.
Energy Transfer cut its distribution 50% in 2020, while Enterprise has grown its payout for 27 consecutive years without a cut.
Energy Transfer is supplying roughly 900 MMcf/d to Oracle-run data centers, making AI power demand a key growth driver.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Energy pays some of the highest yields in the market, and it carries a risk most income sectors avoid: commodity prices. When crude falls, an integrated major can lean on its refining business. A pure producer sees its cash flow rise and fall with oil and gas prices. A midstream operator collects fees on the volumes moving through its pipelines, plants and export docks, so its cash flow holds up better in a downturn.
#energy #income #yields

26 days ago
Warren Buffett stepped down from his role as the chief executive officer of Berkshire Hathaway (NYSE: BRKA)(NYSE: BRKB) at the end of 2025. During his 60-year tenure, he grew the company into a $1 trillion conglomerate with multiple wholly owned subsidiaries, a $350 billion stock portfolio, and over $350 billion in cash.
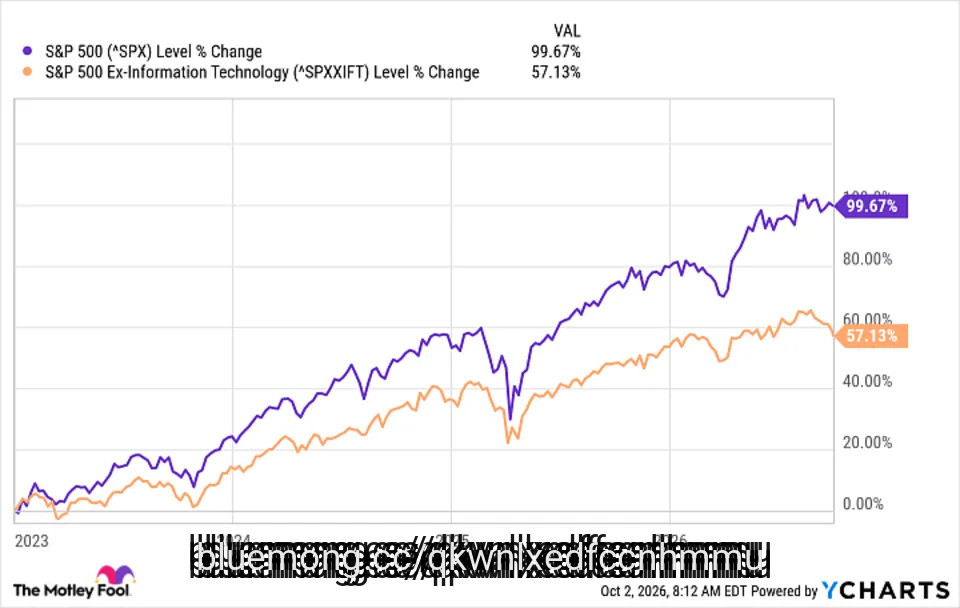
Had an investor purchased $500 worth of Berkshire shares when Buffett took the helm in 1965, thatr person would have been sitting on a whopping $24 million by the time Buffett stepped down. However, Buffett was a full-time professional investor, so he always knew the average person would struggle to replicate his results. That's why he regularly advocated for exchange-traded funds (ETF) that track a diversified index like the S&P 500 (SNPINDEX: ^GSPC).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In his 2013 annual letter to shareholders (published in February 2014), Buffett specifically recommended the Vanguard S&P 500 ETF (NYSEMKT: VOO) because of its exceptionally low fees. While young investors in their 20s and 30s can afford to take more risks, those in their 40s who want to achieve financial security heading into retirement might want to heed Buffett's advice. Here's why I'd buy the Vanguard ETF if I were in that age group.
The S&P 500 is made up of 500 American companies from 11 different sectors of the economy. It has a very strict entry criteria, requiring its members to maintain a market capitalization of at least $22.7 billion, and they must also generate positive earnings. But even after meeting those conditions, a special committee still has the final say over which companies make the cut.
#NVIDIA #signal #flashing


1 month ago
On September 8, 2026, Reuters reported that Paramount Skydance Corporation (NASDAQ:PSKY) said California Attorney General Rob Bonta made television statements that contradict his own legal arguments against Paramount's request for a $1.88 billion bond in the ongoing court fight over its roughly $110 billion acquisition of Warner Bros. Discovery, Inc. (NASDAQ:WBD).
Bonta's office has argued the bond is unnecessary because Paramount voluntarily agreed to pause the deal's closing rather than wait for a court injunction. But Paramount described that same pause as equivalent to an injunction in media interviews, which it argues legally requires the states to post a bond under antitrust law. A hearing is scheduled for September 24.
Paramount Skydance Corporation (NASDAQ:PSKY) could protect a significant portion of its financial position if the court grants its $1.88 billion bond request. Paramount says the delay could cost it about $1.3 billion in fees to Warner Bros. Discovery shareholders by the time the case concludes in April 2027. A bond would give Paramount a potential path to recover those losses if it ultimately defeats the states' challenge. It reduces the financial damage from a prolonged legal process.
Warner Bros. Discovery, Inc. (NASDAQ:WBD) is receiving financial protection from the transaction's delay through Paramount's ticking fees. Paramount agreed to pay WBD shareholders approximately $7 million per day starting October 1 if the transaction does not close, creating a growing payment obligation for Paramount. It is also providing WBD shareholders with compensation for waiting. The arrangement gives WBD a financial benefit from the prolonged closing process even as the companies await a final legal resolution.
The legal dispute has not eliminated the strategic rationale for combining the two media companies. Paramount argues that the merger would strengthen the film and television industry and lead to more content while giving the combined company greater scale to compete with Netflix and Disney. For Paramount, completing the acquisition would speed up David Ellison's plan to build a larger media competitor. WBD shareholders would receive the transaction consideration rather than remain exposed to the company's standalone turnaround.
#paramount


1 month ago
FleetCor and CEO Ronald Clarke agreed to a $100 million payment resolving Federal Trade Commission litigation. The settlement follows years of court action over hidden charges involving commercial fuel cards. Harm reached tens of thousands among small-business customers seeking lower operating costs. Regulators say promised savings disappeared beneath undisclosed billing practices.
Federal regulators accused FleetCor, which now operates as Corpay, of imposing unauthorized fees totaling hundreds of millions. Investigators found improper late penalties despite timely remittance or company barriers that prevented payment. Officials cited misleading claims about gas savings, fraud controls, plus card-related expenses. Those practices harmed operators across the United States, according to a 2019 complaint.
Regulators found FleetCor often waited several billing cycles before adding many charges. Delayed timing made extra costs harder for customers to notice. Invoices omitted fee disclosures, pushing account holders toward separate management reports. Even those documents obscured some amounts among unrelated details or excluded them entirely.
"FleetCor deceived its small business customers by promising fuel savings that never materialized," Christopher Mufarrige said. He directs FTC's Bureau of Consumer Protection. Agency officials also criticized hidden and unauthorized charges. Settlement terms channel restitution toward harmed account holders.
In 2023, one federal district court granted summary judgment to the FTC on every count. Its ruling found hidden charges and false representations involving savings, fees, plus fraud-control features. Permanent injunction terms barred FleetCor from billing without informed consent alongside clear disclosures. That order also prohibited deceptive fuel-card claims or hiding material information behind hyperlinks.
#fleetcor #savings



1 month ago
One of the challenges for nontraditional fintech lenders has been the expense **** ociated with lending.
Because most of them do not have bank charters, they must partner with a traditional third-party bank to fund their loans. However, they must pay a fee or provide a cut of interest income earned on every loan they make using a third party. That eats into their profits.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
A federal bank charter would allow the fintechs to take deposits, because without one, they cannot. The deposits serve as an internal funding source, as loans can be made from the deposit base. With an internal funding source, these fintechs do not have to get third-party funding for loans, which, in turn, allows them to save on fees and collect all of the interest income.
Since fintechs started popping up more frequently over the past five or six years, federal regulators have been reluctant to grant bank charters to fintechs, imposing stringent requirements. But that has changed over the past couple of years as restrictions have eased. There has been a surge in the number of fintechs applying for, and getting, bank charters.
#Fintechs #missed #interest


1 month ago
On September 15, Arthur J. Gallagher & Co. (NYSE:AJG) announced that it had bought McMillan Insurance & Bonding Inc., an Englewood, Colorado, firm that operates as Innovise Business Consultants. Gallagher did not say what it paid. On its own, the deal is a footnote. But it is one of many, and the way those deals show up in earnings is where the debate over this stock really lives.
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth


1 month ago
When developers hand governance to residents at build-out, HOA fees spike as homeowners absorb true amenity costs and cover reserve underfunding through special ****** sments.
HOA fee increases in post-transition communities routinely outpace the 2027 Social Security COLA of roughly 3%, squeezing retirees on fixed incomes.
Demand the reserve study, CC&Rs, and community development district bond balance before signing. If the sales office stalls, the pitch was rehearsed, not substantiated.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Readers in their late fifties and early sixties ask weekly: Can I retire to a Margaritaville community, and what will it cost over twenty or thirty years? The brochure sells one version, while the sales center sells another. The real question a retiree should ask is what happens once marketing wears off and the structural issue the sales presentation almost never covers emerges.
#retirees #community #years #sells
1 month ago
Sunny, low-tax states like Florida, South Carolina and Nevada have become a magnet for U.S. retirees, with Florida alone placing four cities in the top 10 WalletHub's Best Places to Retir survey. Scottsdale, Arizona and Las Vegas, Nevada also placed in the top 12 slots in the survey.
Relocation and family finance experts say retirees are drawn to sunnier, usually southern U.S. locales not only due to the warmer climate, but for a lower, or no, tax-rate. Now, data is showing that many retirees are finding their new states bring countering cost of living issues to the buffet table, most notably homeowners ****** ociation fees and sky-high home insurance rates.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#retirees #nevada #sunny

1 month ago
Financially challenged fast-food franchisees have been lining up to file for bankruptcy protection in 2026 to reorganize their businesses and restructure debt.
Hardee's Phoenix-based restaurant franchisee Superior Star LLC , filed for Chapter 11 bankruptcy protection on July 9, facing an alleged seller financing dispute, according to court papers. A burger chain rival, Checkers Drive-In franchisee C.S. Holdings of Tampa LLC, which operates two locations in Tampa, Fla., filed for Chapter 11 bankruptcy protection to reorganize its business on July 14.
Another Hardee's franchisee, ARC Burger LLC, filed for Chapter 7 bankruptcy liquidation on April 20, 2026, after franchisor Hardee's Restaurants LLC sued the restaurant operator for alleged breach of contract, seeking to recover over $6.5 million in unpaid franchise fees and other obligations, according to Law.com.
And now, major Wendy's restaurant franchisee Meritage Hospitality Group Inc., which operates over 350 locations in 15 states, filed for Chapter 11 bankruptcy to reorganize its business and restructure its debt, almost 11 months after defaulting on its franchise agreements for failing to remit payments.
Meritage Hospitality and 14 affiliates filed their petition in the U.S. Bankruptcy Court for the Western District of Michigan on Sept. 17, 2026, listing $10 million to $50 million in **** ets and debts.
#chapter


1 month ago
Burford Capital Limited (NYSE:BUR) announced on September 14 that its indirect, wholly owned subsidiary, Burford Capital Global Finance LLC, priced $300 million of 8% senior secured notes due 2029. Closing is expected September 17, subject to customary conditions.
Net proceeds and existing cash are intended to redeem the subsidiary's 6.25% unsecured notes due in 2028. The transaction would move this maturity into 2029, with a coupon 175 basis points higher.
The September 14 offering announcement confirmed $400 million of outstanding 2028 notes, making the cash contribution central to the refinancing. Burford Capital Limited (NYSE:BUR) said it expected to issue a conditional notice targeting September 24, 2026, for redemption of all $400 million, subject to successful completion of the $300 million financing.
For Burford Capital Limited (NYSE:BUR), refinancing ahead of maturity creates more room for litigation investments to generate cash. Court proceedings, settlements, and collections follow uncertain schedules. Reducing dependence on a particular realization date could help management preserve investment value.
Redeeming the confirmed $400 million balance with $300 million of replacement notes would reduce gross principal by $100 million. Calculated annual coupons would fall from $25 million to $24 million, before fees and other financing costs.
#capital #september #NYSE

1 month ago
Realty Income Corporation (NYSE:O) announced on September 14 a European property venture in which capital accounts advised by KKR & Co. Inc. (NYSE:KKR) intend to invest €528 million for a 49% interest. Closing is expected September 30, subject to customary conditions.
Realty Income Corporation (NYSE:O) would receive approximately €528 million in gross proceeds while retaining 51% ownership and day-to-day ******* et management. The contributed portfolio carries a 5.9% effective initial capitalization rate after recurring management fees. The question is whether redeploying the capital and earning fees can more than offset the rental economics transferred to the partner.
The venture could provide another funding source for acquisitions. Selling a minority interest in existing properties can release capital while preserving operational continuity. It also gives management an alternative when public equity or debt financing offers less attractive terms.
Management fees add a second source of income alongside retained property earnings. Realty Income Corporation (NYSE:O) could use its existing European operating platform to manage the venture, potentially spreading overhead across a broader pool of investor capital. The benefit depends on fee revenue exceeding the incremental costs of providing those services.
The structure includes a further source of potential upside. Realty Income Corporation (NYSE:O) would have an option to redeem the partner's interest after year 10 and through year 17. The redemption price would provide a capped internal rate of return, an annualized return accounting for cash-flow timing, expected at 6.3% to 6.5% and finalized at closing.
#NYSE #corporation #management #source

1 month ago
Alcoa Corporation (NYSE:AA) priced $2.6 billion of acquisition financing on September 9, 2026, through two wholly owned subsidiaries. Alumina Pty Ltd will issue $1.5 billion of 6.625% notes due 2034, while Alcoa Nederland Holding B.V. will issue $1.1 billion of 6.875% notes due 2036. Alcoa Corporation (NYSE:AA) and certain subsidiaries will guarantee the notes on a senior unsecured basis.
The tranches imply annual coupons of $99.375 million and $75.625 million, respectively, totaling exactly $175 million. Settlement is expected on September 23. Net proceeds and cash on hand would fund the approximately $3.1 billion cash portion of the South32 Limited (ASX:S32) ****** et acquisition, plus related fees and expenses.
For Alcoa Corporation (NYSE:AA), successful settlement would secure longer-dated funding and allow termination of the remaining 364-day bridge commitments. Maturities in 2034 and 2036 give management time to integrate the ****** ets before principal comes due.
The operating opportunity lies in linking additional bauxite resources, alumina refining and aluminum production. Better coordination could strengthen feedstock security and improve purchasing, logistics and plant economics. Acquired earnings and operating improvements could produce recurring cash to service the debt while funding reinvestment.
Fixed coupons also make the interest burden predictable. Strong ****** et performance could support debt reduction and give shareholders a growing share of incremental cash generation.
#notes #september

1 month ago
Hawaiian Electric Industries, Inc. (NYSE:HE) has a potential valuation benchmark for its retained American Savings Bank investment. IPO terms reported September 9 imply approximately $1 billion of equity value at the midpoint. The proposed offering comprises approximately 7.5 million shares at $15 to $17 each.
Hawaiian Electric Industries, Inc. (NYSE:HE) sold 90.1% of the bank in December 2024 and retained 9.9%. Mechanically, a 9.9% holding at a $1 billion valuation would be worth approximately $99 million, ****** uming that ownership percentage remains unchanged.
The base offering would total approximately $120 million at the $16 midpoint before fees. That amount represents shares being sold across the offering, not proceeds automatically attributable to the retained investment.
A public listing could make the minority ****** et easier to value. For Hawaiian Electric Industries, Inc. (NYSE:HE), an observable trading price would give investors a clearer reference for estimating the holding's contribution to overall equity value.
The proposed transaction is entirely secondary, according to the detailed offering report. Existing shareholders are selling shares, so the offering itself does not dilute ownership through newly issued stock. Any change in the retained stake would depend on shareholder sales or other capital changes.
#value #million


1 month ago
When a spouse dies, Social Security drops to one check, but fixed costs like taxes, amenity fees, and utilities do not drop at all.
A surviving single filer's standard deduction drops from $31,500 to $15,750 and Medicare surcharges kick in at half the income threshold.
Run the survivor math now: fixed costs minus survivor income, divided by 3.5% withdrawal rate, reveals if the portfolio actually covers it.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
People often ask about retiring to a place like The Villages in central Florida, and the math usually works for a healthy couple. What almost **** ody asks, until it is too late to plan for, is what happens when the couple becomes one person in the same house. Widowhood, divorce, a spouse moving into memory care. One of you will almost certainly face it. Here is what the numbers actually look like on the other side of that day.
#income


1 month ago
Amazon raised minimum starting pay for its U.S. full-time core operations employees to $20 an hour on Wednesday, a $1-per-hour increase for front-line workers who sort, pack, and transport orders.
Amazon said the typical hourly rate for those workers climbs to nearly $24, and that when benefits are counted, total compensation comes out to more than $32 an hour. Amazon said its minimum starting pay has risen more than 17% over the past three years.
The announcement arrives as Amazon approaches the peak holiday shopping season. According to The Wall Street Journal, Amazon hired 250,000 full-time, part-time, and seasonal workers in advance of last year's holiday period.
Along with the pay increase, Amazon announced two new benefits. Beginning Oct. 1, all U.S. Amazon employees will receive a grocery discount — 10% off eligible groceries and everyday essentials on Amazon.com and Whole Foods Market online, and 20% off in-store at Whole Foods. The discount can be combined with existing Prime member discounts, the company said.
Amazon also said it is launching a banking benefit called Day 1 Financial, through which qualified employees and their families can obtain a lifelong membership in First Tech Federal Credit Union. The benefit includes accounts with no overdraft fees, no monthly maintenance fees, and no account minimums, as well as access to credit cards, auto loans, and home loans for those who qualify. The company said the rollout will start in late 2026, with broad availability expected in 2027.
#time #employees #credit #starting

1 month ago
Autonomous vehicle company May Mobility is merging with a special purpose acquisition company (SPAC) and will become a publicly traded company. It's a deal that could raise more than $300 million for May Mobility at a valuation of $1.4 billion, the company said Wednesday.
Once the merger is complete, May Mobility said it will be the first public company in the U.S. that is focused entirely on autonomous ride-hailing vehicles. This is meant to differentiate it from a number of other public companies working on autonomy, including Tesla, Rivian, Alphabet (with Waymo), and trucking-focused Aurora and Kodiak.
The move sets up May Mobility to be a test of the stock market's appetite for pure-play robotaxi ventures.
It will also be a test of May Mobility's approach to autonomy, which it pitches as "asset-light" and "partnership-first." Instead of owning and operating the robotaxis, May Mobility's business revolves around selling its autonomous vehicles to its fleet partners over time while maintaining control of any remote supervision and software updates. In exchange, May Mobility receives either fixed fees or per-trip licensing fees.
Founded in 2017, May Mobility currently operates autonomous Toyota Siennas in three locations in the U.S. It has a partnership with Lyft in Atlanta, and offers rides in two cities — Eden Prairie and Grand Rapids — in Minnesota.
#company #autonomous #focused


1 month ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre


1 month ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter
1 month ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus
1 month ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus
1 month ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #NASDAQ #fund #parnassus


1 month ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #fund #quarter #parnassus
1 month ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands

1 month ago
The House Ways and Means Committee will consider legislation Wednesday that would exempt some crypto transaction fees from capital-gains calculations and apply new federal tax rules to stablecoins, staking, mining and digital ***** et trading.
Committee Chairman Jason Smith, R-Mo., introduced the 114-page Digital ***** et Tax Certainty Act, or H.R. 10357. The committee has scheduled its markup for 10 a.m. Eastern on Sept. 16.
During a markup, committee members debate a bill, propose amendments, and decide whether to advance it to the full House.
The legislation would create a "de minimis" exemption for qualifying network or transaction fees of $10 or less. De minimis refers to an amount considered too small to require standard tax treatment.
Paying a blockchain fee with crypto can create a taxable event because the IRS treats digital ***** ets as property. The exemption would allow taxpayers to disregard gains or losses on eligible fees.
#committee #digital #asset

1 month ago
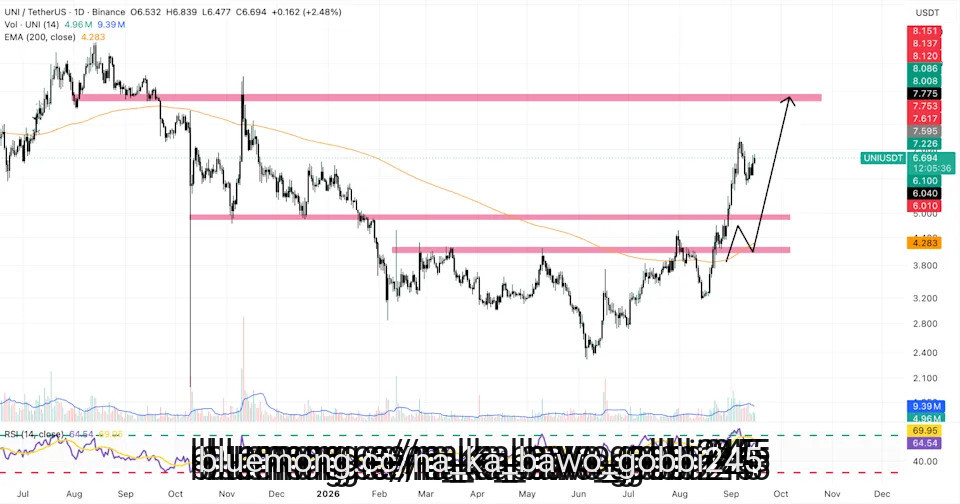
Uniswap (UNI) has jumped by more than 6% in the past 24 hours, and it is the best-performing token in the top 20, as on-chain data shows that protocol fees have exploded in September.
In the past 30 days alone, this token has doubled its value, primarily amid the success of its launch on the Robinhood Chain.
Trading volumes in the past 24 hours have surged by 80%, to nearly $640 million. At those levels, they account for almost 15% of the ****** et's circulating market cap.
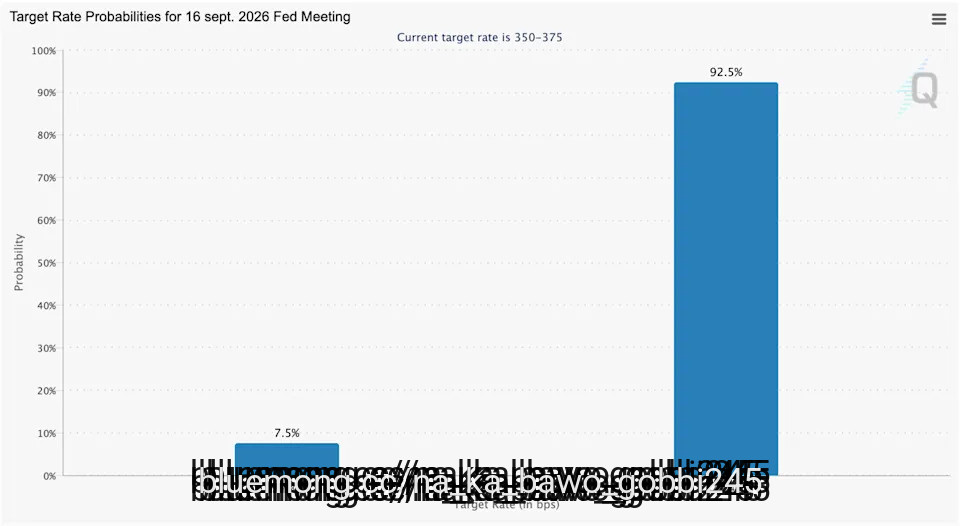
UNI has managed to defy a challenging macroeconomic backdrop marked by expectations of multiple upcoming rate hikes.
According to data from FedWatch, the Federal Reserve will increase interest rates by 25 basis points tomorrow. Meanwhile, it appears that ****** ysts are leaning toward a second rate increase in December, as high inflation in the United States persists.
#past #token #increase

1 month ago
Bank of America Corporation (NYSE:BAC) expects third-quarter investment banking fees to fall by at least 10% year over year, which highlights a broader normalization across capital markets after an unusually strong first half of 2026. BofA expects investment banking fees of roughly $1.6 billion to $1.8 billion in the third quarter, compared with $2 billion a year earlier. CEO Brian Moynihan said the broader investment banking market is also down around 10%, suggesting that the softer quarter reflects a cooling in industry activity rather than a company-specific breakdown.
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#billion #year #rather

