

2 months ago
Morgan Stanley met privately with Gilead Sciences (GILD) leadership at its 2026 Global Healthcare Conference this month, and the feedback strengthened the bank's positive view on the stock.
Morgan Stanley's biopharma team hosted a meeting and a management dinner with Gilead Chairman and CEO Daniel O'Day and Chief Commercial and Corporate Affairs Officer Johanna Mercier. According to a Morgan Stanley research note shared with me, the discussion reinforced its Overweight rating on Gilead and singled out one franchise as the biggest reason to stay positive.
Gilead trades around $150.89, up about 24% year to date and roughly 111% over five years. That kind of run in a biotech stock usually needs a catalyst, and Morgan Stanley points to HIV prevention. The bigger question for investors now is whether the new HIV prevention business built around Yeztugo can keep growing at the pace of the last few quarters.
Terence Flynn, a Morgan Stanley equity **** yst who covers Gilead and other healthcare stocks has held an Overweight rating on the stock since January 2025.
According to the note, Gilead management described the company as being at "an important inflection point, supported by what it views as the most robust portfolio in the company's history," with no patent expiring until 2036.
#gilead #healthcare #management #note
Morgan Stanley's biopharma team hosted a meeting and a management dinner with Gilead Chairman and CEO Daniel O'Day and Chief Commercial and Corporate Affairs Officer Johanna Mercier. According to a Morgan Stanley research note shared with me, the discussion reinforced its Overweight rating on Gilead and singled out one franchise as the biggest reason to stay positive.
Gilead trades around $150.89, up about 24% year to date and roughly 111% over five years. That kind of run in a biotech stock usually needs a catalyst, and Morgan Stanley points to HIV prevention. The bigger question for investors now is whether the new HIV prevention business built around Yeztugo can keep growing at the pace of the last few quarters.
Terence Flynn, a Morgan Stanley equity **** yst who covers Gilead and other healthcare stocks has held an Overweight rating on the stock since January 2025.
According to the note, Gilead management described the company as being at "an important inflection point, supported by what it views as the most robust portfolio in the company's history," with no patent expiring until 2036.
#gilead #healthcare #management #note

2 months ago
Xenon Pharmaceuticals (XENE) shares crashed on Friday after the biopharmaceutical firm said it has paused new patient enrollment in its clinical trials evaluating azetukalner. As investors responded to the setback involving XENE's lead drug candidate for major depressive disorder, its relative strength index (RSI) slipped into the early teens, indicating extremely oversold conditions.
Following today's decline, Xenon Pharmaceuticals stock is trading nearly 40% below its year-to-date high.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#xene #following #America
Following today's decline, Xenon Pharmaceuticals stock is trading nearly 40% below its year-to-date high.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#xene #following #America



2 months ago
Avantor (AVTR) exhibits strong technical momentum, recently setting a new year-to-date high.
Shares are up more than 22% over the past year.
AVTR maintains a 100% "Buy" technical opinion from Barchart.
Most ******* ysts see AVTR as undervalued, but I recommend a tight stop loss given its volatility and only moderate fundamental outlook.
Valued at $10.44 billion, Avantor (AVTR) is a provider of critical products and services primarily to the biopharma, healthcare, education, government, advanced technologies, and applied materials industries.
#avantor #year #exhibits
Shares are up more than 22% over the past year.
AVTR maintains a 100% "Buy" technical opinion from Barchart.
Most ******* ysts see AVTR as undervalued, but I recommend a tight stop loss given its volatility and only moderate fundamental outlook.
Valued at $10.44 billion, Avantor (AVTR) is a provider of critical products and services primarily to the biopharma, healthcare, education, government, advanced technologies, and applied materials industries.
#avantor #year #exhibits



2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ******* ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ******* ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth


2 months ago
American Century Investments, an investment management company, released its second-quarter 2026 investor letter for the "American Century Investments Focused Dynamic Growth Fund". The letter can be downloaded here. U.S. stocks advanced sharply with double-digit quarterly gains largely due to robust earnings, resilient economic data, and momentum in AI-related stocks. However, there was a slight pullback in June as momentum waned and investors anticipated potential interest rate hikes by the Federal Reserve. Growth and AI stocks outperformed value stocks, while large-cap companies generally surpassed small- and mid-cap stocks. Underperformance was noted in healthcare and communication services, while industrials, particularly in aerospace and defense, contributed positively to performance. The fund's investor class returned 16.38%, slightly below the Russell 1000 Growth Index's 16.74%. The investment approach focuses on bottom-up financial ***** ysis to identify large-cap companies with long-term earnings growth potential, while aiming to mitigate non-financial risks. Please review the Fund's top five holdings to gain insights into its key selections for 2026.
In its second-quarter 2026 investor letter, American Century Investments Focused Dynamic Growth Fund highlighted Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY). Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY), a biopharmaceutical company that discovers and commercializes therapeutics based on ribonucleic acid interference, detracted from the Fund's performance this quarter. On September 09, 2026, Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) closed at $258.00 per share. Over the past month, Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) returned 13.60%, but its shares are down 44.94% over the past year. Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) has a market capitalization of $34.52 billion, and its stock has traded within a 52-week range of $197.81 to $495.55.
American Century Investments Focused Dynamic Growth Fund stated the following regarding Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) in its Q2 2026 investor letter:
"Stock choices and a sector overweight relative to the benchmark detracted as many biotechnology stocks, including Alnylam Pharmaceuticals and Insmed, underperformed the market. Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY). The biotechnology company's stock underperformed amid concerns of its upcoming late-stage clinical trial readouts despite what we believed was its otherwise strong recent financial performance."
#alny #century
In its second-quarter 2026 investor letter, American Century Investments Focused Dynamic Growth Fund highlighted Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY). Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY), a biopharmaceutical company that discovers and commercializes therapeutics based on ribonucleic acid interference, detracted from the Fund's performance this quarter. On September 09, 2026, Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) closed at $258.00 per share. Over the past month, Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) returned 13.60%, but its shares are down 44.94% over the past year. Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) has a market capitalization of $34.52 billion, and its stock has traded within a 52-week range of $197.81 to $495.55.
American Century Investments Focused Dynamic Growth Fund stated the following regarding Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) in its Q2 2026 investor letter:
"Stock choices and a sector overweight relative to the benchmark detracted as many biotechnology stocks, including Alnylam Pharmaceuticals and Insmed, underperformed the market. Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY). The biotechnology company's stock underperformed amid concerns of its upcoming late-stage clinical trial readouts despite what we believed was its otherwise strong recent financial performance."
#alny #century


2 months ago
By Karen Roman
Veraxa Biotech AG (Nasdaq: VRXA) said it appointed Raju Willener as Chief Financial Officer, having previously served as Director of Corporate Development at Exentis Group AG, before becoming its CFO in 2025.
Mr. Willener has more than three decades of international financial leadership experience in global capital markets and all aspects of the biopharmaceutical development process, the company stated.
"As we advance our proprietary BiTAC technology platform and growing oncology pipeline, Raju's expertise will be highly valuable in optimizing our capital strategy, evaluating strategic opportunities and supporting disciplined execution and long-term shareholder value creation," said Christoph Antz, Ph.D., VERAXA's CEO and co-founder.
Contact:
#willener #roman #NASDAQ
Veraxa Biotech AG (Nasdaq: VRXA) said it appointed Raju Willener as Chief Financial Officer, having previously served as Director of Corporate Development at Exentis Group AG, before becoming its CFO in 2025.
Mr. Willener has more than three decades of international financial leadership experience in global capital markets and all aspects of the biopharmaceutical development process, the company stated.
"As we advance our proprietary BiTAC technology platform and growing oncology pipeline, Raju's expertise will be highly valuable in optimizing our capital strategy, evaluating strategic opportunities and supporting disciplined execution and long-term shareholder value creation," said Christoph Antz, Ph.D., VERAXA's CEO and co-founder.
Contact:
#willener #roman #NASDAQ


2 months ago
Biopharmaceutical leader Kiniksa Pharmaceuticals (KNSA) is approaching a new buy point in the wake of a strong quarterly sales report. That makes Kiniksa stock Thursday's pick for IBD 50 Growth Stocks To Watch from Investor's Business Daily.
Kiniksa develops and commercializes medicines for cardiovascular, autoimmune and autoinflammatory diseases. Its only drug, Arcalyst, treats recurrent pericarditis, a condition in which the sac protecting the heart, the pericardium, becomes inflamed. The risk of recurrence increases with each subsequent flare-up of pericarditis, according to the Arcalyst website.
The company expects to replace Arcalyst with a next-generation version, now called KPL-387, in 2028 or 2029.
While Arcalyst requires a weekly under-the-skin shot, KPL-387 is a monthly injection. KPL-387 sales are expected to start slow at $21.7 million in 2028, growing to $173.7 million, $486.3 million and $1.03 billion over the next three years.
During the second quarter, Arcalyst generated $243.6 million in sales, growing 55% year over year. That crushed estimates from FactSet that called for $227.7 million.
#next #biopharmaceutical
Kiniksa develops and commercializes medicines for cardiovascular, autoimmune and autoinflammatory diseases. Its only drug, Arcalyst, treats recurrent pericarditis, a condition in which the sac protecting the heart, the pericardium, becomes inflamed. The risk of recurrence increases with each subsequent flare-up of pericarditis, according to the Arcalyst website.
The company expects to replace Arcalyst with a next-generation version, now called KPL-387, in 2028 or 2029.
While Arcalyst requires a weekly under-the-skin shot, KPL-387 is a monthly injection. KPL-387 sales are expected to start slow at $21.7 million in 2028, growing to $173.7 million, $486.3 million and $1.03 billion over the next three years.
During the second quarter, Arcalyst generated $243.6 million in sales, growing 55% year over year. That crushed estimates from FactSet that called for $227.7 million.
#next #biopharmaceutical
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
Jim Cramer openly shares his opinions about various stocks, and on September 3, 2026, during an episode of CNBC's Mad Money, he gave his two cents on Nuvation Bio (NUVB).
A caller asked about the surging biopharma name, and Cramer answered in five plain words: "This is a pure spec."
That is short for pure speculation, which implies a stock that trades on what a drug might do someday, not on the money the company is making right now.
His warning came as the stock climbed on real news, which is exactly what makes Nuvation such a tricky call for investors.
Cramer has hosted Mad Money since 2005 and ran a hedge fund for years before that, so when he flags a stock as too risky for most people, it carries weight.
#cramer #nuvation #pure #shares
A caller asked about the surging biopharma name, and Cramer answered in five plain words: "This is a pure spec."
That is short for pure speculation, which implies a stock that trades on what a drug might do someday, not on the money the company is making right now.
His warning came as the stock climbed on real news, which is exactly what makes Nuvation such a tricky call for investors.
Cramer has hosted Mad Money since 2005 and ran a hedge fund for years before that, so when he flags a stock as too risky for most people, it carries weight.
#cramer #nuvation #pure #shares
2 months ago
Reuters reported that McKesson Corporation (NYSE:MCK) said it would buy privately held Precision Medicine Group in a deal valued at about $2.25 billion as part of a "years-long effort to strengthen its higher-growth businesses."
McKesson has been reshaping its portfolio by exiting non-core **** ets and streamlining its operations while investing in businesses such as oncology and specialty care. Precision Medicine Group, based in Bethesda, Maryland, provides clinical research, laboratory testing, and commercialization services that help biopharma companies develop and launch new medicines. It will become part of McKesson's Oncology & Multispecialty segment once the deal closes, though McKesson gave no completion timeline. CEO Brian Tyler said the acquisition would "enhance our clinical research and commercialization services, strengthen clinical trial execution, and broaden our clinical service offerings."
The deal fits neatly into a growth strategy McKesson Corporation (NYSE:MCK) has already been executing, not a scattershot bet. The company has spent recent years exiting non-core **** ets while specifically building out oncology and specialty care. It means this acquisition extends a strategy management has already proven willing to follow through on.
McKesson is adding Precision Medicine to its strongest-performing division rather than using the acquisition to revive a struggling business. Revenue in the Oncology & Multispecialty segment jumped 33% to $14.2 billion in the first quarter of fiscal 2026, while JP Morgan **** yst Lisa Gill said the acquisition will likely strengthen McKesson's biopharma offerings.
The purchase reflects disciplined capital recycling, not new debt-fueled expansion. McKesson said in April it would sell a minority stake in its medical-surgical solutions business to Apollo Funds for $1.25 billion while pursuing an IPO for that unit, showing the company is actively shedding slower-growth **** ets to help fund investments like this one.
#medicine #acquisition #deal
McKesson has been reshaping its portfolio by exiting non-core **** ets and streamlining its operations while investing in businesses such as oncology and specialty care. Precision Medicine Group, based in Bethesda, Maryland, provides clinical research, laboratory testing, and commercialization services that help biopharma companies develop and launch new medicines. It will become part of McKesson's Oncology & Multispecialty segment once the deal closes, though McKesson gave no completion timeline. CEO Brian Tyler said the acquisition would "enhance our clinical research and commercialization services, strengthen clinical trial execution, and broaden our clinical service offerings."
The deal fits neatly into a growth strategy McKesson Corporation (NYSE:MCK) has already been executing, not a scattershot bet. The company has spent recent years exiting non-core **** ets while specifically building out oncology and specialty care. It means this acquisition extends a strategy management has already proven willing to follow through on.
McKesson is adding Precision Medicine to its strongest-performing division rather than using the acquisition to revive a struggling business. Revenue in the Oncology & Multispecialty segment jumped 33% to $14.2 billion in the first quarter of fiscal 2026, while JP Morgan **** yst Lisa Gill said the acquisition will likely strengthen McKesson's biopharma offerings.
The purchase reflects disciplined capital recycling, not new debt-fueled expansion. McKesson said in April it would sell a minority stake in its medical-surgical solutions business to Apollo Funds for $1.25 billion while pursuing an IPO for that unit, showing the company is actively shedding slower-growth **** ets to help fund investments like this one.
#medicine #acquisition #deal


2 months ago
With a market cap of $138.2 billion, Bristol-Myers Squibb Company (BMY) is a global biopharmaceutical company that discovers, develops, manufactures, and markets innovative medicines worldwide. Its portfolio spans key therapeutic areas including oncology, hematology, immunology, cardiovascular disease, and neuroscience, with well-known products such as Opdivo, Eliquis, Revlimid, and Yervoy.
Companies valued at $10 billion or more are generally classified as "large-cap" stocks, and Bristol-Myers Squibb fits this criterion perfectly. The company serves patients through a broad commercial network that includes wholesalers, distributors, specialty pharmacies, hospitals, clinics, and government agencies.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ***** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#company #bristol #squibb #Stock
Companies valued at $10 billion or more are generally classified as "large-cap" stocks, and Bristol-Myers Squibb fits this criterion perfectly. The company serves patients through a broad commercial network that includes wholesalers, distributors, specialty pharmacies, hospitals, clinics, and government agencies.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ***** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#company #bristol #squibb #Stock


2 months ago
Can-Fite BioPharma Ltd. (NYSE:CANF) reported extended survival trends in a key late-stage cancer trial alongside a $4 million warrant exercise agreement to fund ongoing clinical operations.
• Can Fite Biopharma stock is at significant support. What is going on with CANF?
The clinical-stage biotechnology company observed longer-than-expected blinded overall survival in its ongoing pivotal Phase 3 trial evaluating Namodenoson for advanced hepatocellular carcinoma (HCC).
The study focuses on HCC patients with Child-Pugh B7 cirrhosis, utilizing overall survival as its primary efficacy endpoint.
Because the observed data reflect a pooled, blinded population across both treatment arms, the company cannot draw conclusions regarding drug efficacy or comparative differences yet.
#biopharma #clinical
• Can Fite Biopharma stock is at significant support. What is going on with CANF?
The clinical-stage biotechnology company observed longer-than-expected blinded overall survival in its ongoing pivotal Phase 3 trial evaluating Namodenoson for advanced hepatocellular carcinoma (HCC).
The study focuses on HCC patients with Child-Pugh B7 cirrhosis, utilizing overall survival as its primary efficacy endpoint.
Because the observed data reflect a pooled, blinded population across both treatment arms, the company cannot draw conclusions regarding drug efficacy or comparative differences yet.
#biopharma #clinical


2 months ago
On August 26, Biohaven (NYSE:BHVN) and SK Biopharmaceuticals announced a global licensing agreement covering opakalim, Biohaven's lead epilepsy candidate, in a deal worth up to $795 million plus royalties. SK Biopharmaceuticals picks up exclusive worldwide rights to Biohaven's Kv7 ion channel platform, while Biohaven walks away with $400 million in near-term cash. The timing lines up with an August 10, 2026 earnings report that showed Biohaven still losing well over $100 million a quarter, and the gap between those two dates explains a lot about why this deal happened now.
SK Biopharmaceuticals will pay up to $795 million in upfront and milestone payments connected to the Kv7 platform, on top of tiered royalties on US net sales of opakalim that range from the mid-teens to low twenties. Biohaven collects $350 million at closing and another $50 million in 2027, with as much as $150 million more available through development and regulatory milestones plus royalties on global sales. SK Biopharmaceuticals is also taking over Kv7 program costs going forward, including certain Knopp Biosciences obligations. CEO Vlad Coric described the structure as proof Biohaven can monetize its pipeline through partnerships rather than leaning on public markets for cash.
The deal only makes sense because opakalim looks like it works. In a proof-of-concept study in idiopathic generalized epilepsy, the median time to a second generalized tonic-clonic seizure stretched to 141 days on opakalim versus 47 days on placebo, and a third of patients made it through the full 24 weeks without a second seizure. In focal epilepsy, 54% of patients in an open-label extension study saw at least a 50% drop in seizure frequency over any six months, in a group of more than 100 patients.
Opakalim is also designed as a once-daily pill with no ******* ration required, a real edge over older antiseizure drugs. Pairing that data with SK Biopharmaceuticals, the company behind XCOPRI and the only firm to bring a new focal-seizure drug to the US market since 2016, gives Opakalim a commercial path Biohaven would have struggled to build alone. The cash also buys runway for the rest of the pipeline, including protein degraders BHV-1300 and BHV-1400, which have shown rapid, selective reductions in disease-driving antibodies in Graves' disease and IgA nephropathy with clean safety data across nearly 200 patients dosed.
Biohaven is giving up full ownership of an ******* et it now believes could be a major seller. Royalties in the mid-teens to low twenties are real money, but they are a fraction of what outright ownership of an approved epilepsy drug would be worth, and $50 million of the $400 million upfront does not arrive until 2027. The Knopp Biosciences obligations SK Biopharmaceuticals is absorbing, worth up to $245 million plus mid-single-digit royalties, are a reminder that other parties already have claims on opakalim's future revenue before Biohaven sees a dollar of profit from it.
#ro
SK Biopharmaceuticals will pay up to $795 million in upfront and milestone payments connected to the Kv7 platform, on top of tiered royalties on US net sales of opakalim that range from the mid-teens to low twenties. Biohaven collects $350 million at closing and another $50 million in 2027, with as much as $150 million more available through development and regulatory milestones plus royalties on global sales. SK Biopharmaceuticals is also taking over Kv7 program costs going forward, including certain Knopp Biosciences obligations. CEO Vlad Coric described the structure as proof Biohaven can monetize its pipeline through partnerships rather than leaning on public markets for cash.
The deal only makes sense because opakalim looks like it works. In a proof-of-concept study in idiopathic generalized epilepsy, the median time to a second generalized tonic-clonic seizure stretched to 141 days on opakalim versus 47 days on placebo, and a third of patients made it through the full 24 weeks without a second seizure. In focal epilepsy, 54% of patients in an open-label extension study saw at least a 50% drop in seizure frequency over any six months, in a group of more than 100 patients.
Opakalim is also designed as a once-daily pill with no ******* ration required, a real edge over older antiseizure drugs. Pairing that data with SK Biopharmaceuticals, the company behind XCOPRI and the only firm to bring a new focal-seizure drug to the US market since 2016, gives Opakalim a commercial path Biohaven would have struggled to build alone. The cash also buys runway for the rest of the pipeline, including protein degraders BHV-1300 and BHV-1400, which have shown rapid, selective reductions in disease-driving antibodies in Graves' disease and IgA nephropathy with clean safety data across nearly 200 patients dosed.
Biohaven is giving up full ownership of an ******* et it now believes could be a major seller. Royalties in the mid-teens to low twenties are real money, but they are a fraction of what outright ownership of an approved epilepsy drug would be worth, and $50 million of the $400 million upfront does not arrive until 2027. The Knopp Biosciences obligations SK Biopharmaceuticals is absorbing, worth up to $245 million plus mid-single-digit royalties, are a reminder that other parties already have claims on opakalim's future revenue before Biohaven sees a dollar of profit from it.
#ro

2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Stevanato Group S.p.A. (NYSE:STVN) as a new holding. Stevanato Group S.p.A. (NYSE:STVN) is an Italian company that designs and distributes products and processes that offer integrated solutions for the biopharma and healthcare industries. On August 31, 2026, Stevanato Group S.p.A. (NYSE:STVN) closed at $21.03 per share. Stevanato Group S.p.A. (NYSE:STVN) gained 9.06% in the past month while its shares lost 5.39% over the past 52 weeks. Stevanato Group S.p.A. (NYSE:STVN) has a market capitalization of $5.85 billion and its stock has traded within a 52-week range of $12.89 to $28.00.
Riverwater Partners Small Cap Strategy stated the following regarding Stevanato Group S.p.A. (NYSE:STVN) in its Q2 2026 investor letter:
"In addition, we initiated positions in Stevanato Group S.p.A. (NYSE:STVN), a leading global provider of drug containment, drug delivery, and diagnostic solutions to the pharmaceutical, biotechnology, and life sciences industries. The stock sold off following the launch of oral GLP-1s, which many believe will end the need for injectable forms. Experts believe an expanding GLP-1 TAM, coupled with varying use cases, will necessitate ongoing need for injectable forms. Indeed, 25% of drugs approved in 2025 were biologics which will require injectable devices. This market overreaction offered an attractive entry valuation of 12.5x FY2026E EBITDA vs. STVN's historic multiple of 20X and its nearest comp West Pharmaceutical (WST) at approximately 22–25x."
#stevanato #partners #investor
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Stevanato Group S.p.A. (NYSE:STVN) as a new holding. Stevanato Group S.p.A. (NYSE:STVN) is an Italian company that designs and distributes products and processes that offer integrated solutions for the biopharma and healthcare industries. On August 31, 2026, Stevanato Group S.p.A. (NYSE:STVN) closed at $21.03 per share. Stevanato Group S.p.A. (NYSE:STVN) gained 9.06% in the past month while its shares lost 5.39% over the past 52 weeks. Stevanato Group S.p.A. (NYSE:STVN) has a market capitalization of $5.85 billion and its stock has traded within a 52-week range of $12.89 to $28.00.
Riverwater Partners Small Cap Strategy stated the following regarding Stevanato Group S.p.A. (NYSE:STVN) in its Q2 2026 investor letter:
"In addition, we initiated positions in Stevanato Group S.p.A. (NYSE:STVN), a leading global provider of drug containment, drug delivery, and diagnostic solutions to the pharmaceutical, biotechnology, and life sciences industries. The stock sold off following the launch of oral GLP-1s, which many believe will end the need for injectable forms. Experts believe an expanding GLP-1 TAM, coupled with varying use cases, will necessitate ongoing need for injectable forms. Indeed, 25% of drugs approved in 2025 were biologics which will require injectable devices. This market overreaction offered an attractive entry valuation of 12.5x FY2026E EBITDA vs. STVN's historic multiple of 20X and its nearest comp West Pharmaceutical (WST) at approximately 22–25x."
#stevanato #partners #investor

2 months ago
By Karen Roman
Inventiva S.A. (Nasdaq: IVA) said it designated Chris Benecchi as Chief Operating Officer, having previously served as Chief Executive Officer of Motric Bio (an Aditum Bio company).
Mr. Benecchi will lead the company's operational side as Inventiva comes close to its NATiV3 Phase 3 study results of lanifibranor in MASH, expected for the last quarter of 2026, and also prepare for potential commercialization, it stated.
"As we approach our Phase 3 readout, we are preparing the company for the next stage of its evolution," said Andrew Obenshain, Inventiva's CEO. "Chris brings a valuable combination of commercial, operational and launch experience, with a proven track record of helping organizations bring promising medicines to patients."
Mr. Benecchi has 30 years of biopharmaceutical leadership experience across commercial, operational and enterprise roles, with a record of building organizations, preparing investigational medicines for launch, and leading cross-functional execution in competitive and access-challenged markets, Inventiva said.
#chris #chief #commercial
Inventiva S.A. (Nasdaq: IVA) said it designated Chris Benecchi as Chief Operating Officer, having previously served as Chief Executive Officer of Motric Bio (an Aditum Bio company).
Mr. Benecchi will lead the company's operational side as Inventiva comes close to its NATiV3 Phase 3 study results of lanifibranor in MASH, expected for the last quarter of 2026, and also prepare for potential commercialization, it stated.
"As we approach our Phase 3 readout, we are preparing the company for the next stage of its evolution," said Andrew Obenshain, Inventiva's CEO. "Chris brings a valuable combination of commercial, operational and launch experience, with a proven track record of helping organizations bring promising medicines to patients."
Mr. Benecchi has 30 years of biopharmaceutical leadership experience across commercial, operational and enterprise roles, with a record of building organizations, preparing investigational medicines for launch, and leading cross-functional execution in competitive and access-challenged markets, Inventiva said.
#chris #chief #commercial

2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Stevanato Group S.p.A. (NYSE:STVN) as a new holding. Stevanato Group S.p.A. (NYSE:STVN) is an Italian company that designs and distributes products and processes that offer integrated solutions for the biopharma and healthcare industries. On August 31, 2026, Stevanato Group S.p.A. (NYSE:STVN) closed at $21.03 per share. Stevanato Group S.p.A. (NYSE:STVN) gained 9.06% in the past month while its shares lost 5.39% over the past 52 weeks. Stevanato Group S.p.A. (NYSE:STVN) has a market capitalization of $5.85 billion and its stock has traded within a 52-week range of $12.89 to $28.00.
Riverwater Partners Small Cap Strategy stated the following regarding Stevanato Group S.p.A. (NYSE:STVN) in its Q2 2026 investor letter:
"In addition, we initiated positions in Stevanato Group S.p.A. (NYSE:STVN), a leading global provider of drug containment, drug delivery, and diagnostic solutions to the pharmaceutical, biotechnology, and life sciences industries. The stock sold off following the launch of oral GLP-1s, which many believe will end the need for injectable forms. Experts believe an expanding GLP-1 TAM, coupled with varying use cases, will necessitate ongoing need for injectable forms. Indeed, 25% of drugs approved in 2025 were biologics which will require injectable devices. This market overreaction offered an attractive entry valuation of 12.5x FY2026E EBITDA vs. STVN's historic multiple of 20X and its nearest comp West Pharmaceutical (WST) at approximately 22–25x."
#NYSE #strategy #market #riverwater
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Stevanato Group S.p.A. (NYSE:STVN) as a new holding. Stevanato Group S.p.A. (NYSE:STVN) is an Italian company that designs and distributes products and processes that offer integrated solutions for the biopharma and healthcare industries. On August 31, 2026, Stevanato Group S.p.A. (NYSE:STVN) closed at $21.03 per share. Stevanato Group S.p.A. (NYSE:STVN) gained 9.06% in the past month while its shares lost 5.39% over the past 52 weeks. Stevanato Group S.p.A. (NYSE:STVN) has a market capitalization of $5.85 billion and its stock has traded within a 52-week range of $12.89 to $28.00.
Riverwater Partners Small Cap Strategy stated the following regarding Stevanato Group S.p.A. (NYSE:STVN) in its Q2 2026 investor letter:
"In addition, we initiated positions in Stevanato Group S.p.A. (NYSE:STVN), a leading global provider of drug containment, drug delivery, and diagnostic solutions to the pharmaceutical, biotechnology, and life sciences industries. The stock sold off following the launch of oral GLP-1s, which many believe will end the need for injectable forms. Experts believe an expanding GLP-1 TAM, coupled with varying use cases, will necessitate ongoing need for injectable forms. Indeed, 25% of drugs approved in 2025 were biologics which will require injectable devices. This market overreaction offered an attractive entry valuation of 12.5x FY2026E EBITDA vs. STVN's historic multiple of 20X and its nearest comp West Pharmaceutical (WST) at approximately 22–25x."
#NYSE #strategy #market #riverwater
2 months ago
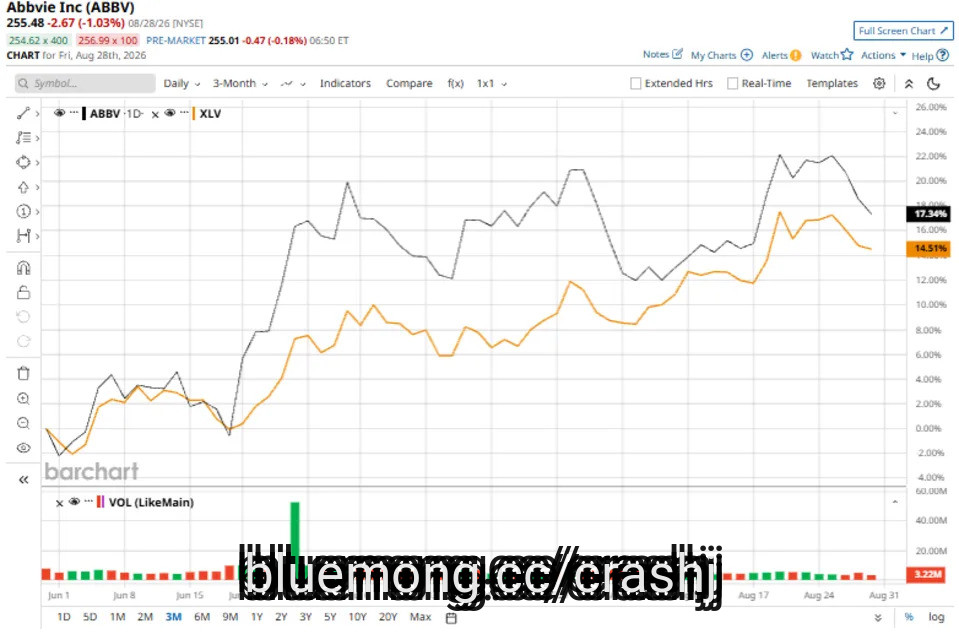
North Chicago, Illinois-based AbbVie Inc. (ABBV) is a global, research-driven biopharmaceutical company focused on developing and commercializing medicines for complex and serious diseases. Valued at a market cap of $386.3 billion, its key therapeutic areas include immunology, neuroscience, oncology and aesthetics, with operations spanning more than 75 countries.
Companies with a market capitalization of $200 billion or more are typically referred to as "mega-cap stocks." ABBV fits right into that category, with its market cap exceeding this threshold, reflecting its substantial size and influence in the general drug manufacturers industry. AbbVie combines a large established pharmaceutical portfolio with a rapidly expanding immunology franchise and a broad pipeline.
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Tesla Just Killed Its Solar Roof After Years of Struggling to Scale. What It Means for TSLA Stock.
Tesla Stock Could Benefit as Trump Locks Down the U.S. Power Grid
#abbvie #abbv #billion
Companies with a market capitalization of $200 billion or more are typically referred to as "mega-cap stocks." ABBV fits right into that category, with its market cap exceeding this threshold, reflecting its substantial size and influence in the general drug manufacturers industry. AbbVie combines a large established pharmaceutical portfolio with a rapidly expanding immunology franchise and a broad pipeline.
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Tesla Just Killed Its Solar Roof After Years of Struggling to Scale. What It Means for TSLA Stock.
Tesla Stock Could Benefit as Trump Locks Down the U.S. Power Grid
#abbvie #abbv #billion


2 months ago
Rahway, New Jersey-based Merck & Co., Inc. (MRK) is a global research-driven biopharmaceutical company focused on developing medicines, vaccines, and animal-health products. Known as MSD outside the U.S. and Canada, Merck operates through two main businesses: Pharmaceuticals and Animal Health. Valued at a market cap of $297 billion, its pharmaceutical portfolio spans oncology, vaccines, cardiometabolic disease, infectious diseases, and other therapeutic areas.
Companies with a market cap of $200 billion or more are typically referred to as "mega-cap stocks." It fits right into that category, with its market cap exceeding this threshold, reflecting its substantial size and influence in the general drug manufacturers industry. Merck combines a dominant oncology franchise, a broad vaccine portfolio, an expanding pipeline of newer medicines, and a large animal-health business. Its key investment consideration is balancing the continued strength of Keytruda and newer products against pressure on mature franchises such as Gardasil and the eventual impact of Keytruda's patent expiry.
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Tesla Just Killed Its Solar Roof After Years of Struggling to Scale. What It Means for TSLA Stock.
Tesla Stock Could Benefit as Trump Locks Down the U.S. Power Grid
#animal #medicines #products
Companies with a market cap of $200 billion or more are typically referred to as "mega-cap stocks." It fits right into that category, with its market cap exceeding this threshold, reflecting its substantial size and influence in the general drug manufacturers industry. Merck combines a dominant oncology franchise, a broad vaccine portfolio, an expanding pipeline of newer medicines, and a large animal-health business. Its key investment consideration is balancing the continued strength of Keytruda and newer products against pressure on mature franchises such as Gardasil and the eventual impact of Keytruda's patent expiry.
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Tesla Just Killed Its Solar Roof After Years of Struggling to Scale. What It Means for TSLA Stock.
Tesla Stock Could Benefit as Trump Locks Down the U.S. Power Grid
#animal #medicines #products


2 months ago
Tempus AI, Inc. (NASDAQ:TEM) rallied following a melanoma breakthrough reported by Moderna and Merck. The companies said their Phase 3 INTerpath-001 trial met its recurrence-free survival endpoint for the personalized cancer therapy intismeran autogene, also known as V940, combined with Keytruda. Detailed trial data remain pending. The read-through came from Personalis, which has supported the V940 clinical-development program since its inception. Tempus agreed in July to a pending acquisition of Personalis at a $1.5 billion enterprise value, net of Tempus's existing stake. The question for Tempus AI, Inc. (NASDAQ:TEM) is whether the result validates the acquisition or merely confirms that one Personalis platform is strategically relevant to personalized cancer therapy.
Personalis uses ImmunoID NeXT to sequence tumor information for personalized vaccine development. That technology is distinct from NeXT Personal, the company's tumor-informed molecular residual disease test and the central strategic target of the acquisition. For Tempus AI, Inc. (NASDAQ:TEM), the clinical result validates Personalis's sequencing capabilities without establishing the economics of either product.
Tempus AI, Inc. (NASDAQ:TEM) is acquiring a company that has supported the V940 program from its beginning. A successful Phase 3 endpoint could strengthen Personalis's credibility with biopharma customers and create additional sequencing opportunities as drugmakers pursue individualized therapies across more tumor types.
The acquisition also reaches beyond vaccine sequencing. Tempus AI, Inc. (NASDAQ:TEM) has commercialized NeXT Personal since 2023. The MRD test searches for small traces of circulating tumor DNA after treatment, helping clinicians monitor response and identify possible recurrence before it becomes visible through conventional imaging.
Tempus AI, Inc. (NASDAQ:TEM) reported 9,000 total MRD tests in the second quarter, up from 6,500 sequentially. Personalis generated finalized quarterly revenue of $22.357 million and delivered 10,384 clinical tests, with volume rising 33% sequentially. NeXT Personal also has Medicare coverage in three indications, giving the pending transaction a commercial foundation independent of V940.
#v940 #acquisition #tumor
Personalis uses ImmunoID NeXT to sequence tumor information for personalized vaccine development. That technology is distinct from NeXT Personal, the company's tumor-informed molecular residual disease test and the central strategic target of the acquisition. For Tempus AI, Inc. (NASDAQ:TEM), the clinical result validates Personalis's sequencing capabilities without establishing the economics of either product.
Tempus AI, Inc. (NASDAQ:TEM) is acquiring a company that has supported the V940 program from its beginning. A successful Phase 3 endpoint could strengthen Personalis's credibility with biopharma customers and create additional sequencing opportunities as drugmakers pursue individualized therapies across more tumor types.
The acquisition also reaches beyond vaccine sequencing. Tempus AI, Inc. (NASDAQ:TEM) has commercialized NeXT Personal since 2023. The MRD test searches for small traces of circulating tumor DNA after treatment, helping clinicians monitor response and identify possible recurrence before it becomes visible through conventional imaging.
Tempus AI, Inc. (NASDAQ:TEM) reported 9,000 total MRD tests in the second quarter, up from 6,500 sequentially. Personalis generated finalized quarterly revenue of $22.357 million and delivered 10,384 clinical tests, with volume rising 33% sequentially. NeXT Personal also has Medicare coverage in three indications, giving the pending transaction a commercial foundation independent of V940.
#v940 #acquisition #tumor

2 months ago
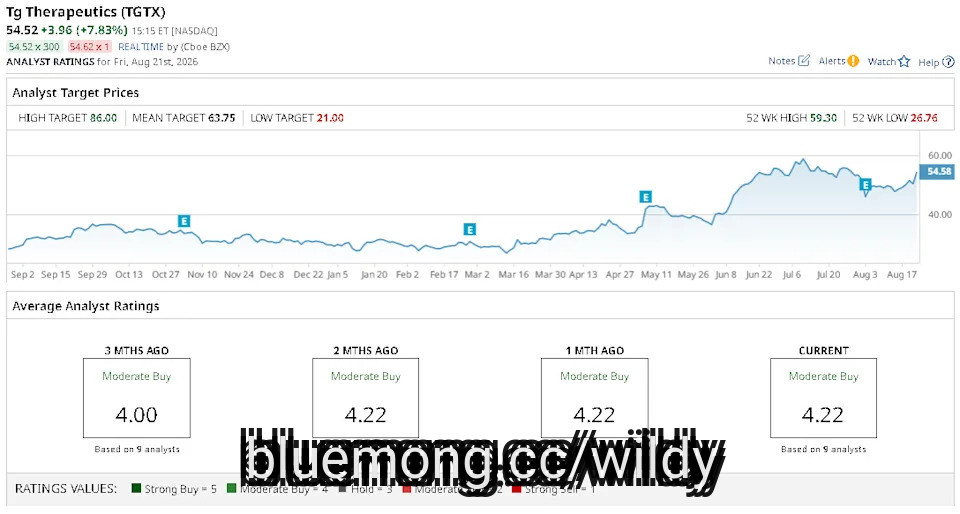
TG Therapeutics (TGTX) shares soared on Aug 21 as speculation emerged that the biotech firm could be the target of a potential takeover. Investors cheered TGTX following an "uncooked" alert from Betaville, suggesting a U.S. biopharma company with a market cap between $20 billion and $40 billion may be interested in acquiring TG Therapeutics.
Following the meteoric rally on Friday, TG Therapeutics stock is up about 85% versus the start of this year.
Microsoft vs. Broadcom: One Has 85% Upside, But I'm Picking the Other
Google Lost About $186 Billion After 4 of Its Top AI Researchers Left, but Sundar Pichai Says Google Will Be 'A Founding Investor' Anyway
Rocket Lab and AST ******* eMobile Are Priced for the Big Bang. One ******* e Stock Already Delivered.
#billion #investors #betaville #Friday
Following the meteoric rally on Friday, TG Therapeutics stock is up about 85% versus the start of this year.
Microsoft vs. Broadcom: One Has 85% Upside, But I'm Picking the Other
Google Lost About $186 Billion After 4 of Its Top AI Researchers Left, but Sundar Pichai Says Google Will Be 'A Founding Investor' Anyway
Rocket Lab and AST ******* eMobile Are Priced for the Big Bang. One ******* e Stock Already Delivered.
#billion #investors #betaville #Friday


2 months ago
Drugmaker Bristol-Myers Squibb Company (NYSE:BMY) is putting real money behind its confidence in American manufacturing. On August 10, the company said it will spend about $2.3 billion on a new plant in Houston, part of a larger $40 billion U.S. investment pledge.
On the very same day, British regulators cleared Eli Lilly and Company (NYSE:LLY)'s weight-loss pill Foundayo for both weight management and type 2 diabetes, making the UK the first country in Europe to approve the drug.
Bristol-Myers Squibb Company (NYSE:BMY)'s new Houston campus, roughly 600,000 square feet, will churn out everything from small-molecule medicines to more complex biologics and antibody-drug conjugates. It is expected to create close to 500 skilled jobs and about 2,000 construction jobs between 2027 and 2030. CEO Christopher Boerner framed it as a vote of confidence in America's biopharma future. The timing lines up with a broader industry trend: drugmakers from Lilly to Johnson & Johnson to Pfizer are all racing to build more in the U.S. as tariff pressure from the Trump administration ramps up.
Eli Lilly took the opposite direction this week, expanding outward instead of inward. Foundayo's UK approval opens a major new market, even though the pill isn't covered by the National Health Service yet and still trails Novo Nordisk's Wegovy pill there.
So which strategy actually serves shareholders better, building strength at home or chasing growth abroad?
#NYSE #myers #squibb #confidence
On the very same day, British regulators cleared Eli Lilly and Company (NYSE:LLY)'s weight-loss pill Foundayo for both weight management and type 2 diabetes, making the UK the first country in Europe to approve the drug.
Bristol-Myers Squibb Company (NYSE:BMY)'s new Houston campus, roughly 600,000 square feet, will churn out everything from small-molecule medicines to more complex biologics and antibody-drug conjugates. It is expected to create close to 500 skilled jobs and about 2,000 construction jobs between 2027 and 2030. CEO Christopher Boerner framed it as a vote of confidence in America's biopharma future. The timing lines up with a broader industry trend: drugmakers from Lilly to Johnson & Johnson to Pfizer are all racing to build more in the U.S. as tariff pressure from the Trump administration ramps up.
Eli Lilly took the opposite direction this week, expanding outward instead of inward. Foundayo's UK approval opens a major new market, even though the pill isn't covered by the National Health Service yet and still trails Novo Nordisk's Wegovy pill there.
So which strategy actually serves shareholders better, building strength at home or chasing growth abroad?
#NYSE #myers #squibb #confidence

3 months ago
Interested in Alpha Teknova, Inc.? Here are five stocks we like better.
Alpha Teknova reported record Q2 revenue of $12.2 million, up 18% year over year, and raised full-year revenue guidance to $45 million–$47 million from $42 million–$44 million.
The company sees significant growth potential as customers advance from catalog products to custom and GMP offerings: GMP customers spend 44 times more than catalog-only buyers, and Teknova expects its first commercial-therapy customer by the end of 2027.
Teknova expects to become adjusted EBITDA-positive in 2027 at annual revenue of $52 million–$57 million, supported by improving biopharma funding, new commercial investments, AI-enabled product configuration and potential bolt-on acquisitions.
Alpha Teknova (NASDAQ:TKNO) Chief Financial Officer Matt Lowell said the provider of laboratory and bioprocessing reagents is seeing renewed growth, reporting record second-quarter revenue and raising its full-year outlook as biopharma funding and life-science end markets improve.
#teknova #revenue #Growth
Alpha Teknova reported record Q2 revenue of $12.2 million, up 18% year over year, and raised full-year revenue guidance to $45 million–$47 million from $42 million–$44 million.
The company sees significant growth potential as customers advance from catalog products to custom and GMP offerings: GMP customers spend 44 times more than catalog-only buyers, and Teknova expects its first commercial-therapy customer by the end of 2027.
Teknova expects to become adjusted EBITDA-positive in 2027 at annual revenue of $52 million–$57 million, supported by improving biopharma funding, new commercial investments, AI-enabled product configuration and potential bolt-on acquisitions.
Alpha Teknova (NASDAQ:TKNO) Chief Financial Officer Matt Lowell said the provider of laboratory and bioprocessing reagents is seeing renewed growth, reporting record second-quarter revenue and raising its full-year outlook as biopharma funding and life-science end markets improve.
#teknova #revenue #Growth


3 months ago
On August 11, Cardinal Health (NYSE:CAH) reported fourth-quarter fiscal 2026 results that on the surface look almost too good to be true. Non-GAAP diluted EPS jumped 40% year over year to $2.91, and full-year adjusted free cash flow hit $5 billion. But a large piece of that quarterly jump came from a one-time tariff refund, and the company's own guidance for the year ahead points to a much more normal pace of growth. That gap between the headline number and what's actually repeatable is where this story gets interesting.
Cardinal Health's fiscal 2026 was broad, not lucky. Operational growth was broad-based across segments, with fourth-quarter total revenue reaching $63.7 billion (up 6% year over year) driven by solid demand in Pharmaceutical and Specialty Solutions. Non-GAAP earnings per share have more than doubled since fiscal 2022, from $5.07 to $11.26, and adjusted free cash flow grew from $2.3 billion to $5 billion over that same four-year stretch, funding $7 billion returned to shareholders.
Pharmaceutical and Specialty Solutions did the heavy lifting again in the fourth quarter, with revenue up 6% to $58.8 billion and segment profit up 21% to $645 million on strength in both brand and Specialty. BioPharma Solutions landed two additional gene therapy 3PL commercialization agreements, with Cardinal Health now exclusively servicing nearly half the cell and gene therapy market and supporting approximately three-fourths of the total market overall. The smaller growth businesses continue to compound rapidly: Nuclear PET and Theranostics revenue grew 20% and 30% respectively in the fourth quarter, while at-Home Solutions posted a 99% total fill rate with its best quarter ever for on-time departures. The board also just authorized a $5 billion increase to the buyback program, pushing total authorization to $6.4 billion, and locked in a long-term Kroger contract extension along with a renewal of its largest medical products customer.
Look closer at that 40% EPS jump, though, and a chunk of it isn't repeatable. About $0.31 of the $2.91 in quarterly diluted earnings per share, roughly 15 percentage points of the 40% growth, came from a one-time $100 million net benefit tied to IEEPA tariff refunds landing in the Global Medical Products and Distribution segment. Strip that out and GMPD's fourth-quarter profit was just $50 million, and the company says it continues to incur ongoing costs from the tariffs that replaced IEEPA. Reported GMPD revenue actually fell 2% for the quarter.
#quarter #specialty
Cardinal Health's fiscal 2026 was broad, not lucky. Operational growth was broad-based across segments, with fourth-quarter total revenue reaching $63.7 billion (up 6% year over year) driven by solid demand in Pharmaceutical and Specialty Solutions. Non-GAAP earnings per share have more than doubled since fiscal 2022, from $5.07 to $11.26, and adjusted free cash flow grew from $2.3 billion to $5 billion over that same four-year stretch, funding $7 billion returned to shareholders.
Pharmaceutical and Specialty Solutions did the heavy lifting again in the fourth quarter, with revenue up 6% to $58.8 billion and segment profit up 21% to $645 million on strength in both brand and Specialty. BioPharma Solutions landed two additional gene therapy 3PL commercialization agreements, with Cardinal Health now exclusively servicing nearly half the cell and gene therapy market and supporting approximately three-fourths of the total market overall. The smaller growth businesses continue to compound rapidly: Nuclear PET and Theranostics revenue grew 20% and 30% respectively in the fourth quarter, while at-Home Solutions posted a 99% total fill rate with its best quarter ever for on-time departures. The board also just authorized a $5 billion increase to the buyback program, pushing total authorization to $6.4 billion, and locked in a long-term Kroger contract extension along with a renewal of its largest medical products customer.
Look closer at that 40% EPS jump, though, and a chunk of it isn't repeatable. About $0.31 of the $2.91 in quarterly diluted earnings per share, roughly 15 percentage points of the 40% growth, came from a one-time $100 million net benefit tied to IEEPA tariff refunds landing in the Global Medical Products and Distribution segment. Strip that out and GMPD's fourth-quarter profit was just $50 million, and the company says it continues to incur ongoing costs from the tariffs that replaced IEEPA. Reported GMPD revenue actually fell 2% for the quarter.
#quarter #specialty

3 months ago
Greenhaven Road Capital, an investment management company, released its second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund achieved an approximate 11% net return in the second quarter, indicating progress from the first quarter. Key changes to the portfolio will include lower concentration and increased investments with near-term catalysts, alongside a proactive stance on profit-taking. The focus will remain on owning strong businesses and conducting research that challenges consensus views, as several major investments are poised for significant events within the year. Despite declines in market multiples, underlying businesses continue to grow, suggesting a favorable positioning for returns. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Greenhaven Road Capital highlighted Liquidia Corporation (NASDAQ:LQDA). Liquidia Corporation (NASDAQ:LQDA) is a biopharmaceutical company, focusing on developing therapies for rare cardiopulmonary diseases. On August 14, 2026, Liquidia Corporation (NASDAQ:LQDA) closed at $74.44 per share. One-month return of Liquidia Corporation (NASDAQ:LQDA) was 0.26% and its shares gained 178.79% over the past 52 weeks. Liquidia Corporation (NASDAQ:LQDA) has a market capitalization of $6.66 billion.
Greenhaven Road Capital stated the following regarding Liquidia Corporation (NASDAQ:LQDA) in its Q2 2026 investor letter:
"Liquidia Corporation (NASDAQ:LQDA) — This is another special situation. The company has launched a successful drug but remains in a patent dispute that will determine how large their market can be. We purchased shares below where I believed they would settle even after an adverse trial outcome. The shares appreciated more than 30% before a verdict, so we realized a short-term gain and will revisit the investment after the decision."
Liquidia Corporation (NASDAQ:LQDA) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 41 hedge fund portfolios held Liquidia Corporation (NASDAQ:LQDA) at the end of the first quarter which was 44 in the previous quarter. While we acknowledge the potential of Liquidia Corporation (NASDAQ:LQDA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#corporation
In its Q2 2026 investor letter, Greenhaven Road Capital highlighted Liquidia Corporation (NASDAQ:LQDA). Liquidia Corporation (NASDAQ:LQDA) is a biopharmaceutical company, focusing on developing therapies for rare cardiopulmonary diseases. On August 14, 2026, Liquidia Corporation (NASDAQ:LQDA) closed at $74.44 per share. One-month return of Liquidia Corporation (NASDAQ:LQDA) was 0.26% and its shares gained 178.79% over the past 52 weeks. Liquidia Corporation (NASDAQ:LQDA) has a market capitalization of $6.66 billion.
Greenhaven Road Capital stated the following regarding Liquidia Corporation (NASDAQ:LQDA) in its Q2 2026 investor letter:
"Liquidia Corporation (NASDAQ:LQDA) — This is another special situation. The company has launched a successful drug but remains in a patent dispute that will determine how large their market can be. We purchased shares below where I believed they would settle even after an adverse trial outcome. The shares appreciated more than 30% before a verdict, so we realized a short-term gain and will revisit the investment after the decision."
Liquidia Corporation (NASDAQ:LQDA) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 41 hedge fund portfolios held Liquidia Corporation (NASDAQ:LQDA) at the end of the first quarter which was 44 in the previous quarter. While we acknowledge the potential of Liquidia Corporation (NASDAQ:LQDA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#corporation


3 months ago
Waltham, Massachusetts-based Thermo Fisher Scientific Inc. (TMO) provides life sciences solutions, ****** ytical instruments, specialty diagnostics, and laboratory products and biopharma services internationally. The company has a market cap of $217.5 billion and operates through four segments: Life Sciences Solutions, ****** ytical Instruments, Specialty Diagnostics, and Laboratory Products and Biopharma Services.
Shares of Thermo Fisher have slightly lagged behind the broader market over the past year, surging 20.3% compared to the S&P 500 Index's ($SPX) 20.4% surge. Moreover, in 2026, the stock has grown by nearly 1.5%, also underperforming SPX's 13.7% gain.
A $210 Billion Reason to Buy AMD Stock Here
CoreWeave vs Nebius: Both Companies Reported Strong Earnings, But Here's the Stock You Should Buy
As Oracle Deepens Its Partnership with AWS, Here's How You Should Play ORCL Stock
#specialty
Shares of Thermo Fisher have slightly lagged behind the broader market over the past year, surging 20.3% compared to the S&P 500 Index's ($SPX) 20.4% surge. Moreover, in 2026, the stock has grown by nearly 1.5%, also underperforming SPX's 13.7% gain.
A $210 Billion Reason to Buy AMD Stock Here
CoreWeave vs Nebius: Both Companies Reported Strong Earnings, But Here's the Stock You Should Buy
As Oracle Deepens Its Partnership with AWS, Here's How You Should Play ORCL Stock
#specialty



3 months ago
Two biopharma giants, Merck & Co., Inc. (NYSE:MRK) and Gilead Sciences, Inc. (NASDAQ:GILD), are proving that in modern drug development, the biggest catalyst isn't always competing head-to-head; it is knowing when to join forces. While both companies reported their first-quarter 2026 earnings earlier this year, their recent double dose of clinical and regulatory breakthroughs across oncology and virology shows how strategic alliances can reshape two massive therapeutic markets at once.
Merck & Co., Inc. delivered $16.3 billion in total sales for the first quarter of 2026, up 5% year-over-year (3% excluding foreign exchange). Top-line growth continued to be anchored by its flagship oncology therapy, Keytruda, which, alongside its sub-formulations, brought in $8.0 billion in sales, representing an 8% ex-exchange increase. Pulmonary arterial hypertension treatment Winrevair also contributed strongly with $525 million in quarterly revenue, up 87% ex-exchange. GAAP and non-GAAP bottom-line metrics reflected net losses per share of $1.72 and $1.28, respectively, largely driven by upfront charges tied to the strategic acquisition of Cidara Therapeutics. Despite those acquisition-related charges, Merck narrowed and raised the midpoint of its full-year worldwide sales guidance to between $65.8 billion and $67.0 billion.
Merck's growth story remains heavily reliant on expanding Keytruda's reach into earlier-stage treatments and novel combination regimens. With key patent expirations approaching toward the end of the decade, management has aggressively pursued business development and combination therapies to diversify its revenue base and maintain its dominance in immuno-oncology.
Gilead Sciences, Inc. reported $7.0 billion in total revenue for the first quarter of 2026, posting 5% year-over-year product sales growth. Gilead's base business, excluding COVID-19 treatment Veklury, rose 8% year-over-year to $6.8 billion, powered by its market-leading HIV franchise, which generated $5.0 billion in sales (up 10% year-over-year). Biktarvy remained the primary growth driver, while newly launched therapies like Yeztugo (lenacapavir) for HIV pre-exposure prophylaxis provided fresh momentum. The corporation's adjusted diluted earnings per share reached $2.03.
Backed by strong demand across its core virology portfolio, Gilead Sciences, Inc. raised its full-year 2026 total product sales guidance range by $400 million, targeting $30.0 billion to $30.4 billion.
#billion #merck #sciences #oncology
Merck & Co., Inc. delivered $16.3 billion in total sales for the first quarter of 2026, up 5% year-over-year (3% excluding foreign exchange). Top-line growth continued to be anchored by its flagship oncology therapy, Keytruda, which, alongside its sub-formulations, brought in $8.0 billion in sales, representing an 8% ex-exchange increase. Pulmonary arterial hypertension treatment Winrevair also contributed strongly with $525 million in quarterly revenue, up 87% ex-exchange. GAAP and non-GAAP bottom-line metrics reflected net losses per share of $1.72 and $1.28, respectively, largely driven by upfront charges tied to the strategic acquisition of Cidara Therapeutics. Despite those acquisition-related charges, Merck narrowed and raised the midpoint of its full-year worldwide sales guidance to between $65.8 billion and $67.0 billion.
Merck's growth story remains heavily reliant on expanding Keytruda's reach into earlier-stage treatments and novel combination regimens. With key patent expirations approaching toward the end of the decade, management has aggressively pursued business development and combination therapies to diversify its revenue base and maintain its dominance in immuno-oncology.
Gilead Sciences, Inc. reported $7.0 billion in total revenue for the first quarter of 2026, posting 5% year-over-year product sales growth. Gilead's base business, excluding COVID-19 treatment Veklury, rose 8% year-over-year to $6.8 billion, powered by its market-leading HIV franchise, which generated $5.0 billion in sales (up 10% year-over-year). Biktarvy remained the primary growth driver, while newly launched therapies like Yeztugo (lenacapavir) for HIV pre-exposure prophylaxis provided fresh momentum. The corporation's adjusted diluted earnings per share reached $2.03.
Backed by strong demand across its core virology portfolio, Gilead Sciences, Inc. raised its full-year 2026 total product sales guidance range by $400 million, targeting $30.0 billion to $30.4 billion.
#billion #merck #sciences #oncology
3 months ago
On August 6, Jim Cramer highlighted Becton, **** inson and Company (NYSE:BDX) on CNBC's Mad Money following its third-quarter fiscal 2026 financial report and said:
This morning, we got a very strong quarter from BD. That's the big medical technology and supply play... That was formerly known as Becton, **** son. This was the first full quarter after they split off their biosciences and diagnostics business, something we loved. They posted a 9-cent earnings beat off a $3.14 basis, higher-than-expected revenue, up 5.4% year-over-year.
They also said their full-year revenue growth would be toward the high end of their previously issued guidance, raised the low end of the earnings per share outlook, and that's why the stock jumped almost 4%. Even after this move, though, BD still trades at roughly 14 times forward earnings estimates, which is pretty darn cheap… This is one that is going to bring out a lot of value. I love this part of tech and… you don't have to worry about memory and memory shortage.
The fiscal third-quarter results represented the initial full operational cycle following the February spin-off of the biosciences and diagnostic solutions business. Top-line revenue reached $4.98 billion, which shows a 4.4% expansion on a constant-currency basis. Adjusted diluted EPS reached $3.23. It is worth noting that decoupling the diagnostics unit allowed management to streamline capital allocation toward high-margin medical devices and automated dispensing systems.
Broad-based demand across all four operating divisions proved to be a catalyst in the quarter, led by Medical Essentials at $1.68 billion and Connected Care at $1.22 billion, which grew 4.4% on a constant-currency basis behind double-digit dispensing gains. BioPharma Systems generated $670 million, which was powered by double-digit biologics volume in GLP-1 auto-injector programs. Furthermore, year-to-date free cash flow surged 44.6% to $1.7 billion, which provided balance sheet strength to absorb approximately 110 basis points of international tariff headwinds.
#quarter #full #earnings
This morning, we got a very strong quarter from BD. That's the big medical technology and supply play... That was formerly known as Becton, **** son. This was the first full quarter after they split off their biosciences and diagnostics business, something we loved. They posted a 9-cent earnings beat off a $3.14 basis, higher-than-expected revenue, up 5.4% year-over-year.
They also said their full-year revenue growth would be toward the high end of their previously issued guidance, raised the low end of the earnings per share outlook, and that's why the stock jumped almost 4%. Even after this move, though, BD still trades at roughly 14 times forward earnings estimates, which is pretty darn cheap… This is one that is going to bring out a lot of value. I love this part of tech and… you don't have to worry about memory and memory shortage.
The fiscal third-quarter results represented the initial full operational cycle following the February spin-off of the biosciences and diagnostic solutions business. Top-line revenue reached $4.98 billion, which shows a 4.4% expansion on a constant-currency basis. Adjusted diluted EPS reached $3.23. It is worth noting that decoupling the diagnostics unit allowed management to streamline capital allocation toward high-margin medical devices and automated dispensing systems.
Broad-based demand across all four operating divisions proved to be a catalyst in the quarter, led by Medical Essentials at $1.68 billion and Connected Care at $1.22 billion, which grew 4.4% on a constant-currency basis behind double-digit dispensing gains. BioPharma Systems generated $670 million, which was powered by double-digit biologics volume in GLP-1 auto-injector programs. Furthermore, year-to-date free cash flow surged 44.6% to $1.7 billion, which provided balance sheet strength to absorb approximately 110 basis points of international tariff headwinds.
#quarter #full #earnings

3 months ago
Aspire Biopharma Holdings Inc. (NASDAQ:ASBP) said Monday it completed its $30 million acquisition of Dura Driver Control Systems, expanding the biopharmaceutical company into the automotive and mobility-control market.
The deal, first announced in June, gives Aspire 100% ownership of Dura Driver Control Systems, or DCS, which is now a wholly owned subsidiary. Aspire paid about $30 million in cash.
DCS is a tier-one automotive supplier focused on electronic driver controls and systems supporting vehicle electrification, safety, lightweighting and sustainability. Aspire said the acquisition is expected to add revenue, earnings and cash flow while diversifying its business.
The company also entered into a $22.5 million senior secured revolving credit facility in connection with the transaction. The company said it will use borrowings from the facility, along with cash on hand, to finance the acquisition.
"Closing the DCS acquisition is a cash-flow-positive milestone that structurally enhances Aspire's valuation," CEO and Board Chair Kraig Higginson said.
#aspire #company
The deal, first announced in June, gives Aspire 100% ownership of Dura Driver Control Systems, or DCS, which is now a wholly owned subsidiary. Aspire paid about $30 million in cash.
DCS is a tier-one automotive supplier focused on electronic driver controls and systems supporting vehicle electrification, safety, lightweighting and sustainability. Aspire said the acquisition is expected to add revenue, earnings and cash flow while diversifying its business.
The company also entered into a $22.5 million senior secured revolving credit facility in connection with the transaction. The company said it will use borrowings from the facility, along with cash on hand, to finance the acquisition.
"Closing the DCS acquisition is a cash-flow-positive milestone that structurally enhances Aspire's valuation," CEO and Board Chair Kraig Higginson said.
#aspire #company


3 months ago
Interested in Zai Lab Limited Unsponsored ADR? Here are five stocks we like better.
Q2 net product revenue rose 11% sequentially to $105.8 million, supported by VYVGART volume growth, steady ZEJULA sales, XACDURO strength and the early KarXT launch. Management expects revenue to stabilize in late 2026 before returning to meaningful year-over-year growth in 2027, with $717.5 million in cash at quarter-end.
Zoci development is expanding toward potential U.S. approval. Zai Lab expects three registrational programs by the end of 2026, plans to complete a Phase III small-cell lung cancer enrollment in the first half of 2027 and anticipates a possible accelerated-approval filing later that year, with potential approval in 2028.
The company continues advancing its global pipeline, including ZL-1503 for atopic dermatitis, ZL-6201 for solid tumors and ZL-1311 for gastrointestinal cancers. Zai Lab also expects its first U.S. regulatory submission next year as it transitions from a China-focused business into a global biopharmaceutical company.
Zai Lab Stock Has Fallen to Value Levels
#expects #Potential #global
Q2 net product revenue rose 11% sequentially to $105.8 million, supported by VYVGART volume growth, steady ZEJULA sales, XACDURO strength and the early KarXT launch. Management expects revenue to stabilize in late 2026 before returning to meaningful year-over-year growth in 2027, with $717.5 million in cash at quarter-end.
Zoci development is expanding toward potential U.S. approval. Zai Lab expects three registrational programs by the end of 2026, plans to complete a Phase III small-cell lung cancer enrollment in the first half of 2027 and anticipates a possible accelerated-approval filing later that year, with potential approval in 2028.
The company continues advancing its global pipeline, including ZL-1503 for atopic dermatitis, ZL-6201 for solid tumors and ZL-1311 for gastrointestinal cancers. Zai Lab also expects its first U.S. regulatory submission next year as it transitions from a China-focused business into a global biopharmaceutical company.
Zai Lab Stock Has Fallen to Value Levels
#expects #Potential #global

3 months ago
Baron Capital, an investment management company, released its Q2 2026 investor letter for the "Baron Health Care Fund". A copy of the letter is available to download here. The Fund gained 11.99% during the quarter, compared with the 10.48% gain for the Russell 3000 Health Care Index and the 15.44% gain for the Russell 3000 Index. Since inception, the Fund appreciated 10.61% on an annualized basis, compared with 10.02% for the Benchmark and 14.83% for the Index. Strong stock selection in pharmaceuticals, biotechnology, health care equipment, and life sciences tools and services supported the Fund's outperformance, although limited exposure to managed care stocks reduced relative returns. The Fund remains positive on health care due to improving biotechnology funding, strong acquisition activity, recovering managed care margins, and growth from an aging population, chronic disease, medical innovation, and higher health care spending. In addition, please check the Fund's top five holdings to know the best picks in 2026.
In its second-quarter 2026 investor letter, Baron Health Care Fund highlighted argenx SE (NASDAQ:ARGX). argenx SE (NASDAQ:ARGX) is a commercial-stage biopharma company that develops various therapies for the treatment of autoimmune diseases in the United States and internationally. On August 03, 2026, argenx SE (NASDAQ:ARGX) closed at $830.79 per share. The one-month return of argenx SE (NASDAQ:ARGX) was -9.69% and its shares gained 23.10% over the past 52 weeks. argenx SE (NASDAQ:ARGX) has a market capitalization of $51.66 billion with a 52-week trading range between $631.47 - $953.58.
Baron Health Care Fund stated the following regarding argenx SE (NASDAQ:ARGX) in its Q2 2026 investor letter:
"Biotechnology company argenx SE (NASDAQ:ARGX) is best known for developing Vyvgart, the leading FcRn inhibitor for the treatment of autoimmune conditions. Shares rose after a period of prior weakness, which may have been partly driven by the retirement of longtime CEO Tim Van Hauwermeiren in early 2026. We view the transition to Karen Massey, who previously led the company's operations, as largely non-disruptive and believe she is well positioned to continue executing the company's strategy. Shares also benefited from optimism ahead of several clinical readouts, including data from studies of Vyvgart in immune-mediated necrotizing myopathy and dermatomyositis, expected in the third quarter of 2026, as well as empasibrupart in multifocal motor neuropathy, expected in the fourth quarter of 2026. Vyvgart continues to launch well in generalized myasthenia gravis and chronic inflammatory demyelinating polyneuropathy, where we believe it has established itself as an important treatment option. We expect Vyvgart to demonstrate efficacy across an expanding range of autoantibody-driven autoimmune conditions over time and remain encouraged by argenx's pipeline progress."
#care #argx #baron #vyvgart
In its second-quarter 2026 investor letter, Baron Health Care Fund highlighted argenx SE (NASDAQ:ARGX). argenx SE (NASDAQ:ARGX) is a commercial-stage biopharma company that develops various therapies for the treatment of autoimmune diseases in the United States and internationally. On August 03, 2026, argenx SE (NASDAQ:ARGX) closed at $830.79 per share. The one-month return of argenx SE (NASDAQ:ARGX) was -9.69% and its shares gained 23.10% over the past 52 weeks. argenx SE (NASDAQ:ARGX) has a market capitalization of $51.66 billion with a 52-week trading range between $631.47 - $953.58.
Baron Health Care Fund stated the following regarding argenx SE (NASDAQ:ARGX) in its Q2 2026 investor letter:
"Biotechnology company argenx SE (NASDAQ:ARGX) is best known for developing Vyvgart, the leading FcRn inhibitor for the treatment of autoimmune conditions. Shares rose after a period of prior weakness, which may have been partly driven by the retirement of longtime CEO Tim Van Hauwermeiren in early 2026. We view the transition to Karen Massey, who previously led the company's operations, as largely non-disruptive and believe she is well positioned to continue executing the company's strategy. Shares also benefited from optimism ahead of several clinical readouts, including data from studies of Vyvgart in immune-mediated necrotizing myopathy and dermatomyositis, expected in the third quarter of 2026, as well as empasibrupart in multifocal motor neuropathy, expected in the fourth quarter of 2026. Vyvgart continues to launch well in generalized myasthenia gravis and chronic inflammatory demyelinating polyneuropathy, where we believe it has established itself as an important treatment option. We expect Vyvgart to demonstrate efficacy across an expanding range of autoantibody-driven autoimmune conditions over time and remain encouraged by argenx's pipeline progress."
#care #argx #baron #vyvgart




