

24 days ago
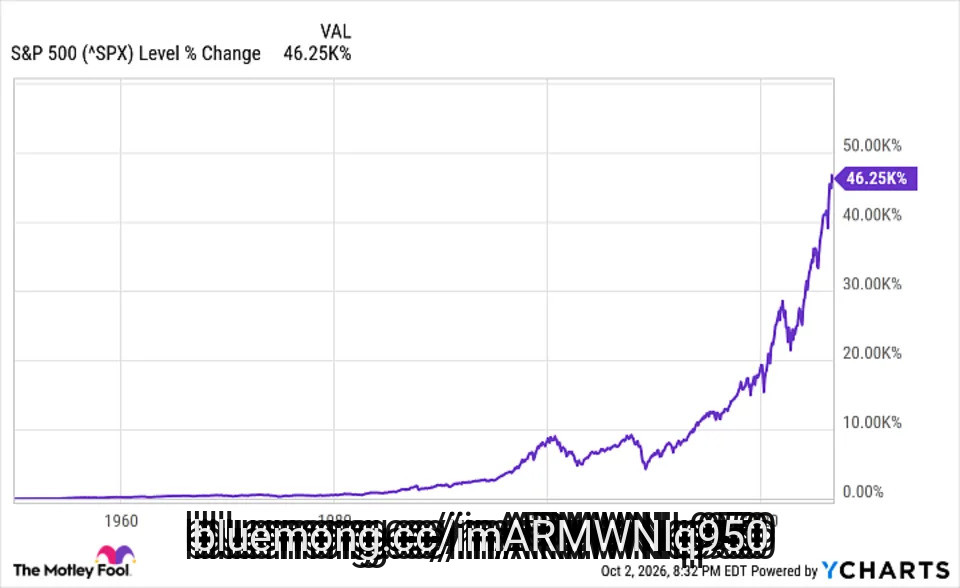
For decades, no investment portfolio has been more closely watched by investors than Berkshire Hathaway's (NYSE:BRKA)(NYSE:BRKB). Now-retired CEO Warren Buffett always had a knack for spotting amazing deals hiding in plain sight, leading to a greater-than-6,000,000% outperformance of the S&P 500 (SNPINDEX:^GSPC) since the mid-1960s.
But investors might not realize that a "secret" Buffett portfolio exists within Berkshire Hathaway. In the June-ended quarter, this $863 million portfolio sent shares of artificial intelligence (AI) superstars Alphabet (NASDAQ:GOOGL)(NASDAQ:GOOG) and Broadcom (NASDAQ:AVGO) packing. Meanwhile, this under-the-radar fund has built up a significant position in two S&P 500 index funds: the State Street SPDR S&P 500 ETF Trust (NYSEMKT:SPY) and the Vanguard S&P 500 ETF (NYSEMKT:VOO).
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: Getty Images.
In 1998, Buffett's Berkshire acquired reinsurance company General Re for about $22 billion in an all-stock deal. While the reinsurance operations were the crown jewel of this buyout, General Re also owned a specialty investment firm, New England ****** et Management (NEAM). When the deal closed in December 1998, NEAM became a subsidiary of Berkshire Hathaway.
#Portfolio #buffett #general #neam

1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august

1 month ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

1 month ago
LifeMD, Inc. (NASDAQ:LFMD) announced an exclusive healthcare collaboration on September 15 that initially makes virtual-health membership benefits available to approximately 29 million eligible AT&T wireless and fiber customers across 11 states. Customers must be 18 or older, and some services have additional eligibility and state restrictions. A nationwide expansion planned for January 2027 would extend eligibility beyond 100 million customers.
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services


1 month ago
Barclays ******* yst Simon Coles says the recent pullback in Tower Semiconductor (TSEM) shares is an opportunity to load up on a quality name at a meaningful discount. In a research note this morning, Coles ******* umed coverage of the independent specialty foundry with an "Overweight" rating and a $310 price target that signals potential upside of nearly 40% from here.
Tower Semiconductor stock has been in a sharp downtrend in recent months, currently trading about 30% below its June high.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#tower #recent #simon #tsem



1 month ago
Interested in Cardinal Health, Inc.? Here are five stocks we like better.
Cardinal Health expects growth to normalize in fiscal 2027 after fiscal 2026 benefited from unusually strong specialty growth, customer onboarding, acquisitions and solid healthcare utilization. Management said all five operating segments delivered double-digit earnings growth in fiscal 2026.
The company is expanding its specialty and at-home healthcare strategy through MSO platforms, bolt-on acquisitions and diabetes-related deals. Strive Medical has closed, while the AdaptHealth diabetes acquisition is expected to close in the second half of fiscal 2027, strengthening Cardinal's continuous glucose monitoring business.
Cardinal is prioritizing automated, small-parcel distribution of higher-value at-home products and plans to add three more automated distribution centers. Management also said cash flow was strong in fiscal 2026, putting the company about 90% of the way toward its previously announced $10 billion objective.
Cardinal Health Earnings: Can Perfection Get Priced In Twice?
#acquisitions

1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august


1 month ago
Fenimore ***** et Management, an investment management company, released its Q2 2026 investor letter. The letter can be downloaded here. U.S. equity markets saw broad gains in Q2, driven by strong corporate earnings, economic resilience, and enthusiasm for artificial intelligence (AI). Major indices reached all-time highs, though the energy sector declined. Continued earnings growth, especially among AI-related investments, supported the rally. Technology, particularly semiconductors, led performance as demand for AI infrastructure surged. Despite macroeconomic uncertainties and interest rate influences, Fenimore remains committed to investing in high-quality businesses. The Fenimore Small Cap Strategy returned 9.51% in the quarter, lagging the Russell 2000 Index's 21.49% gain. The underperformance was largely driven by avoiding lower-quality tech stocks linked to data center expansions. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Fenimore ***** et Management highlighted Ryan Specialty Holdings, Inc. (NYSE:RYAN). Ryan Specialty Holdings, Inc. (NYSE:RYAN) is a specialty insurance services company that provides distribution, underwriting, product development, administration, and risk management services. On September 17, 2026, Ryan Specialty Holdings, Inc. (NYSE:RYAN) closed at $40.03 per share. The one-month return of Ryan Specialty Holdings, Inc. (NYSE:RYAN) was -8.32%, and its shares lost 25.53% over the past 52 weeks. Ryan Specialty Holdings, Inc. (NYSE:RYAN) has a market capitalization of $10.15 billion.
Fenimore ***** et Management stated the following regarding Ryan Specialty Holdings, Inc. (NYSE:RYAN) in its Q2 2026 investor letter:
"We initiated a position in Ryan Specialty Holdings, Inc. (NYSE:RYAN), which we had previously owned after its initial public offering. The insurance industry has seen softness in rates. While RYAN's model differs from traditional retail brokerage, the company released results citing a volatile environment which led to a decrease in their earnings outlook for the year. We're encouraged by the business's long-term prospects and, in our opinion, its legendary leader Pat Ryan. He is also purchasing shares of RYAN's stock during this weakness."
Ryan Specialty Holdings, Inc. (NYSE:RYAN) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 32 hedge fund portfolios held Ryan Specialty Holdings, Inc. (NYSE:RYAN) at the end of the second quarter, compared to 35 in the previous quarter. While we acknowledge the potential of Ryan Specialty Holdings, Inc. (NYSE:RYAN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.


1 month ago
Sunbelt Rentals Holdings, Inc. (NYSE:SUNB) reported on September 9 that fiscal first-quarter revenue increased 11.2% to $3.115 billion, including $2.927 billion of rental revenue, up 12.5%. The quarter ended July 31, 2026.
Management raised fiscal 2027 rental-revenue growth guidance to 7% through 10%, while increasing planned net rental-equipment capital expenditures to $2.4 billion through $2.8 billion. Demand supports expansion, but investors need to ****** s how much cash remains after funding the fleet.
North America Specialty rental revenue grew 25.3%, giving Sunbelt Rentals Holdings, Inc. (NYSE:SUNB) a strong source of growth beyond general equipment rentals. Specialized services can deepen customer relationships and create opportunities to supply several needs on the same project.
The company estimated that the FIFA World Cup contributed 2.5 percentage points to quarterly rental-revenue growth. Serving complex events demonstrates the commercial value of a broad equipment network. The investment opportunity is to turn that capability into recurring work across industrial, energy and construction customers.
Adjusted EBITDA increased 8.7% to $1.315 billion. This company-defined non-GAAP measure adds taxes, net interest, depreciation, amortization, stock-based compensation and specified restructuring costs to net income. Its margin is adjusted EBITDA divided by revenue.
#rentals


1 month ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
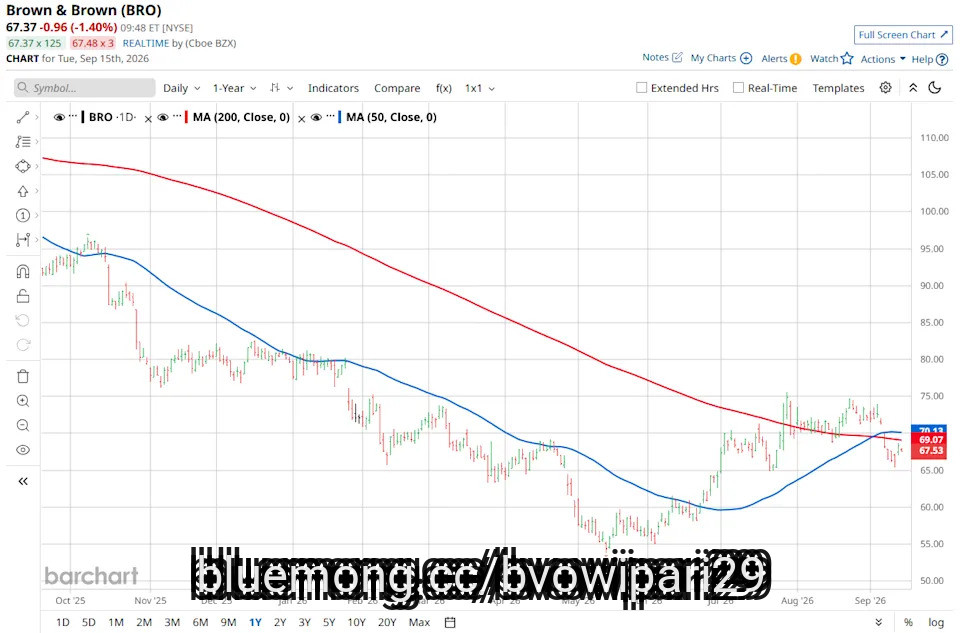
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter
1 month ago
Portsmouth-based Iron Mountain Incorporated (IRM) is a global leader in information management services, trusted by more than 240,000 customers in 61 countries. The company has a market cap of $33.4 billion and offers solutions for information management, digital transformation, information security, data centers, and ******* et lifecycle management (ALM).
Companies with a market cap of $10 billion or more are typically referred to as "large-cap stocks." IRM fits perfectly into that category, with its market cap exceeding this threshold and reflecting its substantial size and influence in the specialty REIT industry.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#information #incorporated #Companies



1 month ago
International Flavors & Fragrances Inc. (IFF), headquartered in New York, produces and markets cosmetic active and natural health ingredients for use in various consumer products. Valued at $21.3 billion by market cap, the company flavors and fragrances are individual ingredients and compounds of a large number of ingredients that are blended, mixed, and reacted together to produce proprietary formulas.
Companies worth $10 billion or more are generally described as "large-cap stocks," and IFF perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the specialty chemicals industry. IFF is a preeminent player in global flavors and fragrances, with 35,000+ products spanning food, beverage, personal care, and health & wellness. Its scale, innovation focus, and alignment with natural, sustainable, and customized ingredient trends support a competitive edge, while operations in 60+ countries provide access to emerging markets and evolving consumer preferences.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#ingredients #markets #Health #products



1 month ago
MiKargo247 is expanding its spot cargo insurance coverage to include strategic cargo theft under a new partnership with Verified Carrier.
The coverage is designed to address a growing category of freight fraud involving double brokering, carrier identity theft and fictitious pickups. Under the partnership, brokers using Verified Carrier can purchase MiKargo247 spot cargo insurance and have the strategic theft exclusion removed when the load is hauled by an eligible verified carrier. The companies announced the partnership Sept. 1.
Strategic cargo theft accounted for about 30% of reported U.S. cargo theft incidents in 2025, according to a June report from Munich Re Specialty and BSI Consulting. The report found that criminals are increasingly using deception, impersonation and other fraud-based methods to obtain freight rather than relying solely on physically stealing cargo from trucks or facilities.
The shift creates a challenge for brokers and insurers because fraudulent actors can make it difficult to determine who is actually hauling a load.
The FBI warned in April that cyber-enabled strategic cargo theft is increasing, with criminals using compromised accounts, fictitious companies and double-brokering schemes to divert legitimate freight. The agency recommended that transportation companies independently verify shipment requests and pickups before releasing loads.
#carrier #partnership #Companies


1 month ago
GameStop (GME) is a Grapevine, Texas-based specialty retailer operating stores and e-commerce platforms under the GameStop, EB Games, and Micromania banners across the U.S., Canada, Australia, and Europe. Once known primarily as a video game and electronics retailer, GameStop has diversified aggressively under Executive Chairman Ryan Cohen, expanding into collectibles, trading cards, pop culture merchandise, and even cryptocurrency and equity investments. The company has become a prominent "meme stock," attracting substantial retail investor attention while pursuing an unconventional capital allocation strategy that includes bitcoin holdings and a sizable equity stake in eBay (EBAY), positioning GameStop as much an investment vehicle as a traditional retailer.
GameStop stock recently traded around $21.15, near the bottom of its 52-week range of $17.79 to $28.10 and below its 200-day moving average. Shares have pulled back significantly from their 2025 meme-stock highs, weighed down by declining video game sales, ongoing store closures, and investor skepticism toward the company's diversification into digital ***** ets and equity investments. The stock did see brief bursts of retail-trader enthusiasm this year, including renewed meme-stock speculation tied to its proposed eBay acquisition, though shares have remained volatile and range-bound as GameStop's core retail business continues shrinking alongside its growing collectibles and investment segments.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#shares


1 month ago
Daytona Beach, Florida-based Brown & Brown, Inc. (BRO) markets and sells insurance products and services in the United States and internationally. Valued at a market cap of $22.9 billion, the company operates through Retail and Specialty Distribution segments and provides property and casualty insurance, employee benefits insurance, personal insurance, specialty insurance, and more.
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." BRO fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the insurance brokers industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#market #Stock #daytona #united

1 month ago
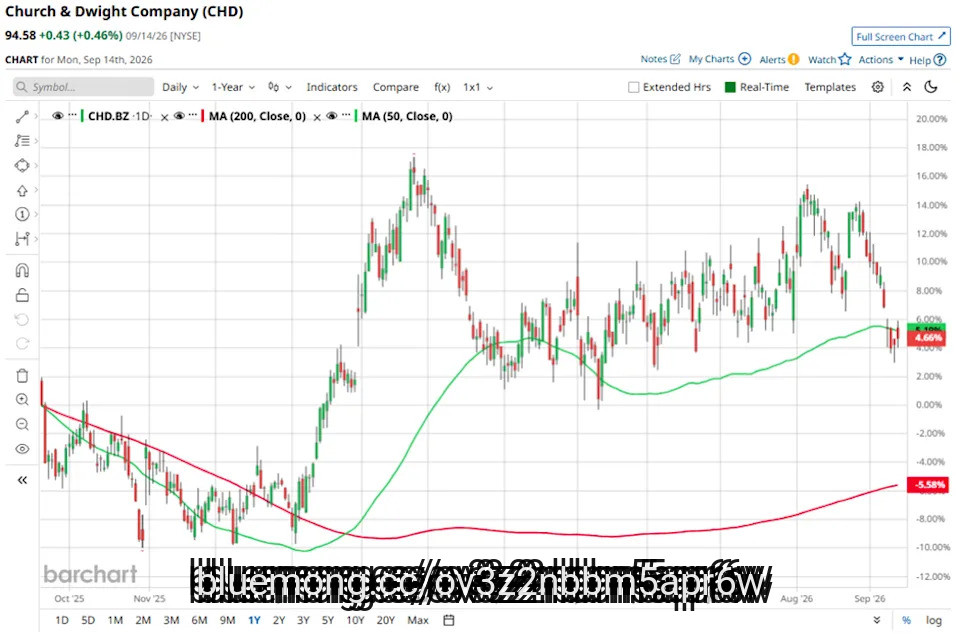
With a market cap of $22.4 billion, Church & Dwight Co., Inc. (CHD) is a leading developer, manufacturer, and marketer of household, personal care, and specialty products. Best known as the U.S. leader in sodium bicarbonate production, the company's portfolio includes iconic power brands such as ARM & HAMMER, Trojan, OxiClean, Waterpik, and Vitafusion.
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Church & Dwight fits this criterion perfectly. Operating across domestic, international, and specialty product segments, Church & Dwight serves consumers worldwide through retail, e-commerce, and industrial distribution channels.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#hammer #oxiclean

1 month ago
GameStop (GME) is a Grapevine, Texas-based specialty retailer operating stores and e-commerce platforms under the GameStop, EB Games, and Micromania banners across the U.S., Canada, Australia, and Europe. Once known primarily as a video game and electronics retailer, GameStop has diversified aggressively under Executive Chairman Ryan Cohen, expanding into collectibles, trading cards, pop culture merchandise, and even cryptocurrency and equity investments. The company has become a prominent "meme stock," attracting substantial retail investor attention while pursuing an unconventional capital allocation strategy that includes bitcoin holdings and a sizable equity stake in eBay (EBAY), positioning GameStop as much an investment vehicle as a traditional retailer.
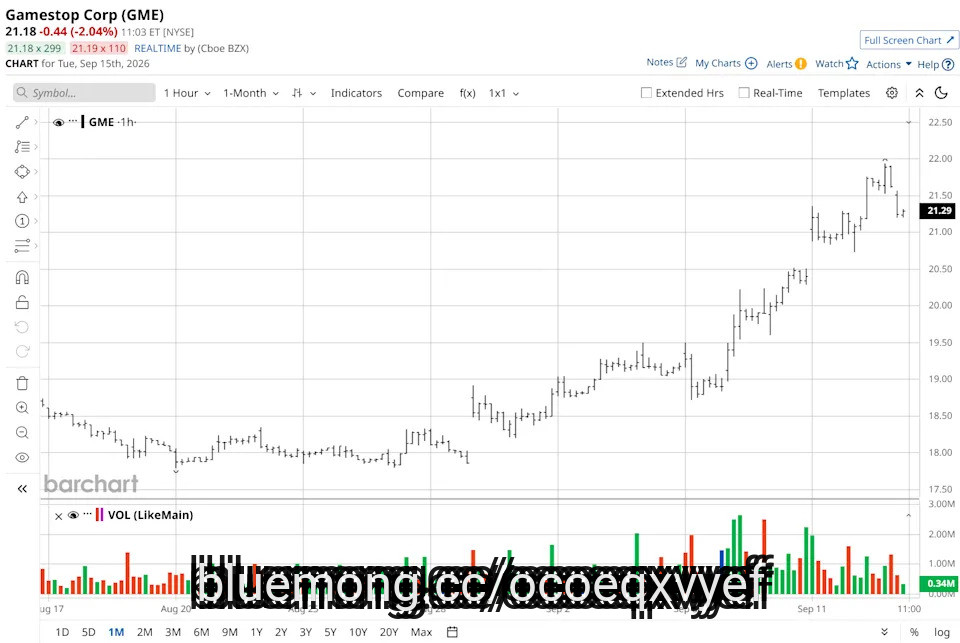
GameStop stock recently traded around $21.15, near the bottom of its 52-week range of $17.79 to $28.10 and below its 200-day moving average. Shares have pulled back significantly from their 2025 meme-stock highs, weighed down by declining video game sales, ongoing store closures, and investor skepticism toward the company's diversification into digital **** ets and equity investments. The stock did see brief bursts of retail-trader enthusiasm this year, including renewed meme-stock speculation tied to its proposed eBay acquisition, though shares have remained volatile and range-bound as GameStop's core retail business continues shrinking alongside its growing collectibles and investment segments.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#Equity

1 month ago
Daytona Beach, Florida-based Brown & Brown, Inc. (BRO) markets and sells insurance products and services in the United States and internationally. Valued at a market cap of $22.9 billion, the company operates through Retail and Specialty Distribution segments and provides property and casualty insurance, employee benefits insurance, personal insurance, specialty insurance, and more.
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." BRO fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the insurance brokers industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#brown #beach #united

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
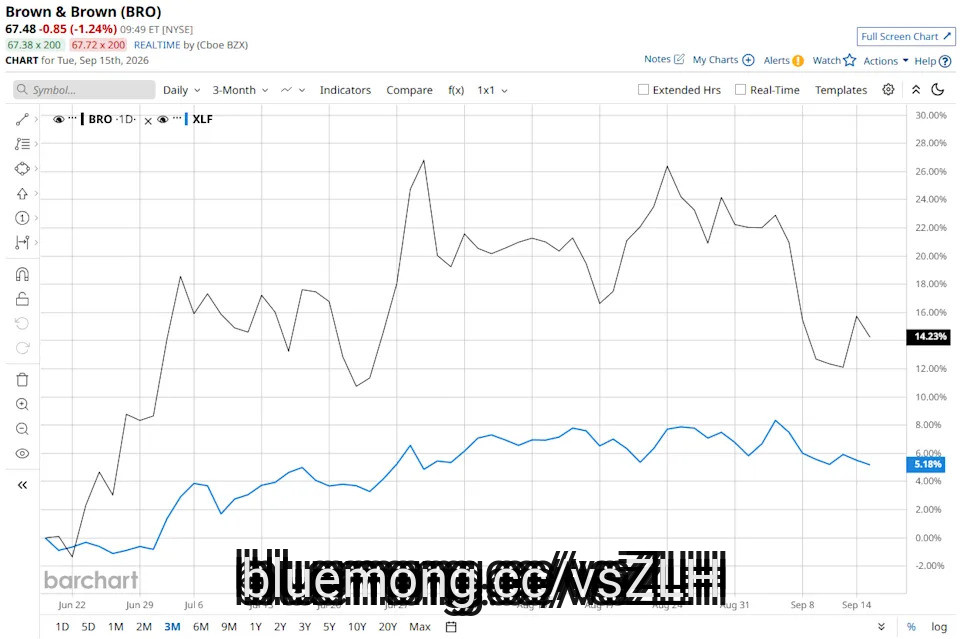
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund #letter


2 months ago
Horizon Technology Finance Corp., an affiliate of Monroe Capital, on September 10 said that the RoHo Capital Opportunity Fund LLC, a joint venture formed by Horizon and CR Financial Holdings, Inc., the holding company for Roth Capital Partners, LLC, has provided a $20-million senior credit facility to NeoVolta, Inc., with the ability to increase the facility to $30 million upon mutual agreement. An initial $20 million was funded at closing to support NeoVolta's continued growth.NeoVolta is an energy technology company focused on developing and manufacturing domestic battery energy storage systems (BESS). Together with its joint venture partner LONGi, NeoVolta is developing a 210,600-square-foot manufacturing facility in Pendergrass, Georgia, to produce BESS systems designed to meet U.S. domestic content and supply-chain requirements. The facility is expected to have an initial annual production capacity of up to 2 GWh, with the potential to scale to 8 GWh over time."Providing growth capital to innovative companies operating in attractive, high-growth markets is a core focus of RoHo's investment strategy," said Paul Seitz, chief investment officer of Horizon. "Formed by Horizon and Roth Capital, RoHo pairs Horizon's venture lending and structuring expertise with Roth's deep public markets relationships to deliver flexible growth capital to small- and micro-cap public companies. We are pleased to support NeoVolta's growth plans with a tailored financing solution and look forward to continuing to deploy capital through RoHo in support of innovative public companies pursuing significant market opportunities.""Horizon and Roth Capital bring valuable experience and a collaborative approach as we advance NeoVolta's domestic battery energy storage systems manufacturing platform," said Ardes Johnson, CEO of NeoVolta. "As we ramp our Georgia facility and pursue larger commercial and utility-scale opportunities, this relationship supports our ability to execute on our long-term growth strategy."Horizon Technology Finance Corp. is a specialty finance company that provides capital in the form of secured loans to venture capital and private equity-backed companies and publicly traded companies in the technology, life science, healthcare information and services, and sustainability industries. The investment objective of Horizon is to maximize its investment portfolio's return by generating current income from the debt investments it makes and capital appreciation from the warrants it receives when making such debt investments. Horizon is headquartered in Farmington, Connecticut, with a regional office in Pleasanton, California, and investment professionals located throughout the U.S.Monroe Capital is a premier ****** et management firm specializing in private credit markets across various strategies, including direct lending, technology finance, venture debt, opportunistic, structured credit, real estate and equity.CR Financial Holdings, Inc., is a private hol



2 months ago
Farmington, Connecticut-based Otis Worldwide Corporation (OTIS) manufactures, installs, and services building systems. Valued at $26.4 billion by market cap, the company offers elevators, escalators, and other moving products.
Companies worth $10 billion or more are generally described as "large-cap stocks," and OTIS perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the specialty industrial machinery industry. OTIS is the largest global elevator and escalator supplier, known for its innovative safety features dating back to 1854. The company boasts a loyal customer base and competitive edge, with its success lying in commanding premium pricing, securing long-term service contracts, and leveraging its installed base for consistent revenue.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ******* e
#tens #Stock #billion #market



2 months ago
Quanta Services, Inc. (PWR) is a leading specialty infrastructure contractor that designs, builds, upgrades, repairs, and maintains critical energy and communications infrastructure across the U.S., Canada, Australia, and select international markets.
With a market cap of $96.1 billion, Quanta Services fits squarely within the large-cap stock category. It is particularly well positioned to benefit from the surging demand for electricity and grid investment. Data-center expansion, AI infrastructure, manufacturing reshoring, electrification, renewable-energy buildouts, and grid modernization are all driving demand for the infrastructure Quanta provides.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ******* e
#energy


2 months ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Net sales growth of 22% was primarily driven by sustained demand across enterprise, data center, and specialty market sectors, including military applications.
Gross profit margin expansion to 37.4% demonstrates significant manufacturing operating leverage, where fixed costs are distributed over higher production volumes.
Management attributes margin improvements to increased manufacturing efficiencies that naturally occur as production volumes scale.
The company is navigating industry-wide optical fiber shortages and raw material lead time extensions by actively managing supply chain dynamics to protect customer deliveries.
#Margin #Manufacturing #volumes #management
2 months ago
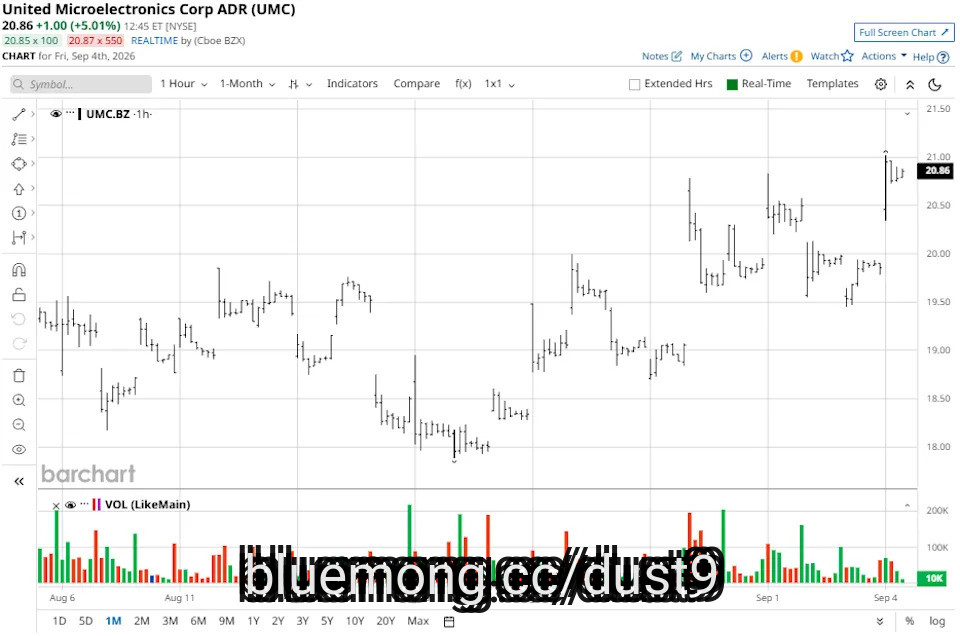
United Microelectronics (UMC) is a leading global semiconductor foundry founded in 1980 and headquartered in Hsinchu, Taiwan. The company specializes in advanced wafer fabrication, offering complementary metal-oxide semiconductor (CMOS) logic, mixed-signal, radiofrequency, embedded memory, high-voltage, and image sensor manufacturing services to a diverse global customer base. The company has increasingly focused on specialty semiconductor solutions spanning power management, connectivity, and advanced packaging, while expanding into silicon photonics to capture emerging demand related to artificial intelligence (AI).
UMC stock currently trades around $22, which is closer to the higher end of its 52-week range of $6.72 to $28.96, reflecting a dramatic rebound from multiyear lows earlier in the year. Shares have been volatile in recent sessions, popping on strong sales figures as investors weigh near-term margin pressures against long-term AI-driven capacity expansion plans.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ***** ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#semiconductor #united #taiwan



2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance was anchored by municipal demand, which remains stable due to the non-discretionary nature of aging water infrastructure repair and evolving regulatory requirements.
Data center development has emerged as a significant growth engine, nearly doubling year-over-year, while treatment plant projects have grown to a mid-single-digit percentage of the total sales mix.
Treatment plant solutions delivered double-digit growth as the company successfully pivots toward higher-value specialty products and technical project support.
Fire protection strength was driven by a combination of market share gains in new geographies and favorable steel pricing dynamics.
#year #tell #FIRE


2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance was driven by the disciplined execution of a value creation strategy, resulting in 27% full-year adjusted EBITDA growth despite reported sales declines from network optimization.
Management attributes underlying sales growth to the $90 billion target addressable market of differentiated retailers, who increased their grocery industry share by 30 basis points.
Operational efficiency improved through the deployment of 'Lean' daily management to 44 distribution centers, resulting in four consecutive quarters of fill rate and throughput gains.
The natural product segment continues to outperform the broader market, reflecting enduring consumer demand for health-forward and specialty products.
#resulting #performance #ebitda #operational
2 months ago
Reuters reported that Solstice Advanced Materials, Inc. (NASDAQ:SOLS) and Element Solutions Inc (NYSE:ESI) mutually agreed to terminate their $14.5 billion merger agreement, the companies said on August 27, citing feedback from shareholders on both sides who preferred each to stay independent. Neither side will pay a termination fee.
Solstice Chairman Rajeev Gautam said the company valued that feedback, including shareholders' "excitement about Solstice's strategy and growth trajectory as an independent company." Solstice's board also authorized its first-ever buyback, up to $500 million, and reaffirmed its recently raised guidance. Solstice shares jumped 15% in after-hours trading, while Element gained 4%. The deal, announced July 6 just 10 months after Solstice's Honeywell spin-off, would have combined Solstice's refrigerants and specialty materials businesses with Element's electronics chemicals operations, paying Element holders $10 cash plus 0.5 Solstice shares per share. The original announcement got a rough welcome: Solstice fell nearly 15% that day, which CEO David Sewell blamed on arbitrage trading, not doubts about the deal.
Both companies continue to perform strongly on their own. Solstice's second-quarter net sales rose 11% to $1.148 billion, and the company raised its full-year sales guidance to $4.125 billion-$4.185 billion. Element delivered an even stronger quarter, with record net sales up 56% to $978 million and full-year adjusted EBITDA guidance raised to $690 million-$710 million.
Solstice Advanced Materials, Inc. (NASDAQ:SOLS) sheds significant deal risk by walking away. The termination removes the financing and merger risks linked to the acquisition and eliminates the need to use the $4.685 billion bridge facility. It also lets Solstice maintain its 1.3x net leverage. Its new $500 million buyback, the company's first ever, also gives Solstice a direct way to return capital to shareholders while it focuses on organic growth.
Element Solutions Inc (NYSE:ESI) also maintains the strengths that its shareholders wanted to preserve. Chairman Ian Ashken said investors valued Element's management team, culture, and existing business portfolio. CEO Benjamin Gliklich said the company's growth remains compelling. Remaining independent allows Element to continue investing in its existing businesses and pursuing its own growth strategy without taking on the risks of a larger combination.
#billion #million #Growth
2 months ago
Reuters reported that McKesson Corporation (NYSE:MCK) said it would buy privately held Precision Medicine Group in a deal valued at about $2.25 billion as part of a "years-long effort to strengthen its higher-growth businesses."
McKesson has been reshaping its portfolio by exiting non-core **** ets and streamlining its operations while investing in businesses such as oncology and specialty care. Precision Medicine Group, based in Bethesda, Maryland, provides clinical research, laboratory testing, and commercialization services that help biopharma companies develop and launch new medicines. It will become part of McKesson's Oncology & Multispecialty segment once the deal closes, though McKesson gave no completion timeline. CEO Brian Tyler said the acquisition would "enhance our clinical research and commercialization services, strengthen clinical trial execution, and broaden our clinical service offerings."
The deal fits neatly into a growth strategy McKesson Corporation (NYSE:MCK) has already been executing, not a scattershot bet. The company has spent recent years exiting non-core **** ets while specifically building out oncology and specialty care. It means this acquisition extends a strategy management has already proven willing to follow through on.
McKesson is adding Precision Medicine to its strongest-performing division rather than using the acquisition to revive a struggling business. Revenue in the Oncology & Multispecialty segment jumped 33% to $14.2 billion in the first quarter of fiscal 2026, while JP Morgan **** yst Lisa Gill said the acquisition will likely strengthen McKesson's biopharma offerings.
The purchase reflects disciplined capital recycling, not new debt-fueled expansion. McKesson said in April it would sell a minority stake in its medical-surgical solutions business to Apollo Funds for $1.25 billion while pursuing an IPO for that unit, showing the company is actively shedding slower-growth **** ets to help fund investments like this one.
#medicine #acquisition #deal

2 months ago
On August 21, Kurt Yinger from DA Davidson initiated his coverage of Everus Construction Group Inc. (NYSE:ECG) with a $168 target price and an upside potential of more than 43%, as of September 4 closing. The **** yst **** igned a Buy rating to the stock based on a highly compelling story that revolves around recent accretive acquisitions, expanding profit margins, lucrative project backlog, and strong order bookings. Kurt anticipated the $295 million Epsilon acquisition to bolster the existing forecasts. Let's explore what fuels this bullish narrative around this specialty contractor.
youssef-abdelwahab-qyzo7TDSVQs-unsplash
Everus finalized its $295 million cash acquisition of Epsilon Industries on September 1. Epsilon is an established designer and manufacturer of mechanical and electrical building infrastructure systems. The transaction was financed using a mix of cash on hand and borrowings under the company's existing credit facilities.
The deal expands Everus' prefabrication and modular construction capabilities, enabling it to cater to high-demand sectors through custom fabrication, design-assist and turnkey installation solutions. These sectors include data centers, advanced manufacturing, and healthcare. Epsilon's numerous strategic centers in the U.S. and Canada will contribute to Everus' nationwide distribution network and augment its current geographic presence within priority growth markets.
By integrating Epsilon's workforce and technical expertise, Everus is well-positioned to meet the increased customer demand, penetrate key end-markets and capitalize on favorable industry trends. With this the company will ultimately reinforce its competitive edge and long-term growth trajectory within the construction sector.
#everus

2 months ago
On the September 2 episode of Mad Money, Jim Cramer called Cardinal Health, Inc. (NYSE:CAH) one of his "absolute favorites" and mentioned its growing exposure to specialty pharmaceuticals and higher-margin healthcare services.
Cardinal's been running circles around McKesson and Cencora. They consistently put up the best numbers because this company has gradually become less of a commoditized service provider and more of a specialized player.
Cardinal Health, Inc.'s (NYSE:CAH) fiscal fourth-quarter revenue rose 6% to $63.7 billion but missed estimates, while adjusted earnings per share came in at $2.91. Excluding a $0.31 per share tariff refund benefit, adjusted EPS was $2.60. Management forecast fiscal 2027 non-GAAP EPS of $12.40 to $12.60, a 13% to 15% growth, while adjusted free cash flow is expected at $3.5 billion to $4 billion.
The revenue miss is less significant if the company continues converting pharmaceutical volume into earnings. Lower branded-drug prices, including those affected by Medicare negotiations, can reduce reported sales without a proportional decline in distributor fees. The shift toward generics can have a similar effect because lower-priced drugs generate less revenue but can support attractive margins and high volumes. As Cramer said:
Remember, volume is where Cardinal really makes the money, volume, okay? That's why I keep shrugging off the revenue misses.
#cardinal #less #billion #NYSE


