

8 mins. ago
On August 5, Kinetik Holdings Inc. (NYSE:KNTK) reported the strongest quarterly results in company history and raised its full-year 2026 guidance. The Permian-focused midstream operator posted net income, including noncontrolling interest, of $123.1 million for the quarter ended June 30, while Adjusted EBITDA climbed to $280.8 million. Management didn't stop at celebrating the number. It used the quarter as the launchpad for a string of expansion decisions that stretch out to 2028.
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#natural
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#natural


3 hours ago
Alluvium **** et Management, an **** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Alphabet Inc. (NASDAQ:GOOG). Alphabet Inc. (NASDAQ:GOOG), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence. On September 15, 2026, Alphabet Inc. (NASDAQ:GOOG) closed at $341.43 per share, reflecting a market capitalization of $4.2 trillion. Alphabet Inc. (NASDAQ:GOOG) posted a one-month return of -0.08%, while its shares gained 36.65% over the past 52 weeks.
Conventum – Alluvium Global Fund stated the following regarding Alphabet Inc. (NASDAQ:GOOG) in its Q2 2026 investor letter:
"Alphabet Inc. (NASDAQ:GOOG) was the Fund's strongest performer over the quarter, up 24.4%. There's little to add from our last report, except that its 22% revenue growth exceeded our expectations, and it seems it can't keep up with demand, hence it has increased, yet again (and somewhat worryingly) its capital expenditure to budget (to USD 190b) and expects further increases next year."
Alphabet Inc. (NASDAQ:GOOG) ranks 7th on our list of 40 Most Popular Stocks Among Hedge Funds. As per our database, 195 hedge fund portfolios held Alphabet Inc. (NASDAQ:GOOG) at the end of the second quarter, which was 201 in the previous quarter. While we acknowledge the potential of Alphabet Inc. (NASDAQ:GOOG) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#goog #fund #conventum
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Alphabet Inc. (NASDAQ:GOOG). Alphabet Inc. (NASDAQ:GOOG), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence. On September 15, 2026, Alphabet Inc. (NASDAQ:GOOG) closed at $341.43 per share, reflecting a market capitalization of $4.2 trillion. Alphabet Inc. (NASDAQ:GOOG) posted a one-month return of -0.08%, while its shares gained 36.65% over the past 52 weeks.
Conventum – Alluvium Global Fund stated the following regarding Alphabet Inc. (NASDAQ:GOOG) in its Q2 2026 investor letter:
"Alphabet Inc. (NASDAQ:GOOG) was the Fund's strongest performer over the quarter, up 24.4%. There's little to add from our last report, except that its 22% revenue growth exceeded our expectations, and it seems it can't keep up with demand, hence it has increased, yet again (and somewhat worryingly) its capital expenditure to budget (to USD 190b) and expects further increases next year."
Alphabet Inc. (NASDAQ:GOOG) ranks 7th on our list of 40 Most Popular Stocks Among Hedge Funds. As per our database, 195 hedge fund portfolios held Alphabet Inc. (NASDAQ:GOOG) at the end of the second quarter, which was 201 in the previous quarter. While we acknowledge the potential of Alphabet Inc. (NASDAQ:GOOG) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#goog #fund #conventum

1 day ago
Starbucks Corporation (NASDAQ:SBUX) is betting $1 billion that leather armchairs, rugs, and bookshelves can turn a recovering coffee business into a more profitable one. The company plans to upgrade as many as 9,000 North American stores into warmer, more comfortable **** es designed to bring back customers who stopped treating Starbucks as a place to sit and stay. The strategy arrives as CEO Brian Niccol's turnaround gains traction, but investors still need to see whether higher traffic can translate into stronger margins.
Pixabay/Public Domain
The store upgrades are part of Niccol's broader "Back to Starbucks" strategy, which has already helped reverse a prolonged sales slump. Global comparable-store sales increased 7.9% in the latest quarter, with transactions up 4.2% and average ticket up 3.5%. U.S. comparable sales also rose 7.9%, indicating that the recovery is being driven by more than higher prices.
Starbucks Corporation (NASDAQ:SBUX) is spending roughly $150,000 per store on the new uplifts, far below the cost of previous renovations, and the work can generally be completed overnight without closing stores. The company expects about 1,500 upgrades to be finished by the end of September and ultimately wants to reach 8,000 to 9,000 company-operated North American locations.
That matters because Starbucks Corporation (NASDAQ:SBUX) has gradually become optimized for transactions rather than lingering. Mobile orders now account for roughly one-third of U.S. transactions, more than twice their share in 2019. The new design is therefore an attempt to restore the "third place" concept without abandoning the convenience that has become central to the business.
#corporation #NASDAQ #sales #transactions
Pixabay/Public Domain
The store upgrades are part of Niccol's broader "Back to Starbucks" strategy, which has already helped reverse a prolonged sales slump. Global comparable-store sales increased 7.9% in the latest quarter, with transactions up 4.2% and average ticket up 3.5%. U.S. comparable sales also rose 7.9%, indicating that the recovery is being driven by more than higher prices.
Starbucks Corporation (NASDAQ:SBUX) is spending roughly $150,000 per store on the new uplifts, far below the cost of previous renovations, and the work can generally be completed overnight without closing stores. The company expects about 1,500 upgrades to be finished by the end of September and ultimately wants to reach 8,000 to 9,000 company-operated North American locations.
That matters because Starbucks Corporation (NASDAQ:SBUX) has gradually become optimized for transactions rather than lingering. Mobile orders now account for roughly one-third of U.S. transactions, more than twice their share in 2019. The new design is therefore an attempt to restore the "third place" concept without abandoning the convenience that has become central to the business.
#corporation #NASDAQ #sales #transactions


2 days ago
The WNBA learned in early September that commissioner Cathy Engelbert has decided to step down and retire from her position following this season. Engelbert has overseen a successful tenure that has helped elevate the WNBA's profile and grow the league's brand.
Now, the league will need to find Engelbert's successor. Several names have already been suggested as potential candidates. However, some of the WNBA's biggest stars may also have a voice in who should succeed Engelbert.
MORE: Sophie Cunningham showered with gifts at NASCAR race
One star has already offered her thoughts on the type of person who should take over. Indiana Fever star Sophie Cunningham was asked what kind of person she expects to be named the next WNBA commissioner.
Aug 23, 2026; Chicago, Illinois, USA; Indiana Fever guard Sophie Cunningham (8) reacts while warming up prior to a game against the Chicago Sky at Wintrust Arena. Mandatory Credit: Patrick Gorski-Imagn Images Credit: IMAGN IMAGES via Reuters Connect (Reuters)
#WNBA #Chicago
Now, the league will need to find Engelbert's successor. Several names have already been suggested as potential candidates. However, some of the WNBA's biggest stars may also have a voice in who should succeed Engelbert.
MORE: Sophie Cunningham showered with gifts at NASCAR race
One star has already offered her thoughts on the type of person who should take over. Indiana Fever star Sophie Cunningham was asked what kind of person she expects to be named the next WNBA commissioner.
Aug 23, 2026; Chicago, Illinois, USA; Indiana Fever guard Sophie Cunningham (8) reacts while warming up prior to a game against the Chicago Sky at Wintrust Arena. Mandatory Credit: Patrick Gorski-Imagn Images Credit: IMAGN IMAGES via Reuters Connect (Reuters)
#WNBA #Chicago



2 days ago
On September 10, Copart (NASDAQ:CPRT) held its fourth-quarter earnings call and used it to unveil a deal that could reshape its business: an all-cash agreement to acquire ACV, a digital auto marketplace that moved roughly $10 billion of vehicles last year without owning a single lot. The announcement landed alongside a quarter that captured the company's central tension. Revenue rose, but net income fell, and management is now betting that pairing its junkyards with someone else's software can fix that.
The ACV deal is the headline, and for good reason. ACV brings more than 22,000 active buyers and inspection and valuation technology, while Copart contributes over 275 locations, roughly 4 million vehicles sold annually, and about 1 million members across more than 185 countries. Management structured it as an all-cash tender offer funded from cash on hand, with a close targeted by the end of the calendar year and earnings accretion expected in fiscal 2028. Executives framed the fit as physical scale meeting digital liquidity, giving dealers, banks, and fleet sellers a single partner for disposing of vehicles.
That diversification push is already showing up in the numbers. International revenue grew 11.7% to $222.1 million on 15% service revenue growth, and international buyers accounted for 45.7% of total US sales dollars despite making up only 38.2% of units, a sign they are chasing pricier vehicles. Domestically, non-insurance units returned to growth of 0.2% in the quarter after a full-year decline, dealer units rose 5.8%, and BluCar, which serves banks and fleets, expanded nearly 20%. Global average selling prices climbed 3.5%, evidence that Copart's auctions still command pricing power even as volumes soften.
The quarter's numbers show where the strain is. Consolidated revenue grew 2.4% to $1.2 billion, yet net income dropped 17.4% to $327.4 million and diluted earnings per share fell 14.6% to $0.35. Operating expense per car jumped 12.7% year over year as the company poured money into long-haul delivery, **** leExpress, and dedicated wholesale facilities, and US facility costs alone rose 7.7% in the quarter. Lower interest income, a byproduct of the $1.63 billion spent on buybacks earlier in the fiscal year, added to the squeeze.
The core insurance business is also cooling. Global insurance units fell 4.2%, with domestic insurance **** ignments down 7.5%, though management noted that figure would have been up 2.3% excluding the loss of a single customer. Collision claim frequency declined 3.4% even as total loss frequency hit a record 23.3% for a second quarter and severity topped $6,300 per claim, up 8.8%. And the ACV deal itself carries integration risk, since management expects only breakeven results before accretion arrives in fiscal 2028.
#quarter #vehicles #insurance
The ACV deal is the headline, and for good reason. ACV brings more than 22,000 active buyers and inspection and valuation technology, while Copart contributes over 275 locations, roughly 4 million vehicles sold annually, and about 1 million members across more than 185 countries. Management structured it as an all-cash tender offer funded from cash on hand, with a close targeted by the end of the calendar year and earnings accretion expected in fiscal 2028. Executives framed the fit as physical scale meeting digital liquidity, giving dealers, banks, and fleet sellers a single partner for disposing of vehicles.
That diversification push is already showing up in the numbers. International revenue grew 11.7% to $222.1 million on 15% service revenue growth, and international buyers accounted for 45.7% of total US sales dollars despite making up only 38.2% of units, a sign they are chasing pricier vehicles. Domestically, non-insurance units returned to growth of 0.2% in the quarter after a full-year decline, dealer units rose 5.8%, and BluCar, which serves banks and fleets, expanded nearly 20%. Global average selling prices climbed 3.5%, evidence that Copart's auctions still command pricing power even as volumes soften.
The quarter's numbers show where the strain is. Consolidated revenue grew 2.4% to $1.2 billion, yet net income dropped 17.4% to $327.4 million and diluted earnings per share fell 14.6% to $0.35. Operating expense per car jumped 12.7% year over year as the company poured money into long-haul delivery, **** leExpress, and dedicated wholesale facilities, and US facility costs alone rose 7.7% in the quarter. Lower interest income, a byproduct of the $1.63 billion spent on buybacks earlier in the fiscal year, added to the squeeze.
The core insurance business is also cooling. Global insurance units fell 4.2%, with domestic insurance **** ignments down 7.5%, though management noted that figure would have been up 2.3% excluding the loss of a single customer. Collision claim frequency declined 3.4% even as total loss frequency hit a record 23.3% for a second quarter and severity topped $6,300 per claim, up 8.8%. And the ACV deal itself carries integration risk, since management expects only breakeven results before accretion arrives in fiscal 2028.
#quarter #vehicles #insurance

2 days ago
On September 10, Shoe Station Group (NASDAQ:SHOE) held its first earnings call under its new name, and the numbers told a story of a company still finding its footing. Second quarter net sales fell 7.2% to $284.3 million from $306.4 million a year earlier, with comparable sales down 7.1%. But buried in the report was a sharper signal: August comparable sales improved to a 2.7% decline, a real jump from the second quarter's pace, and management is pointing to store-by-store product changes as the reason why.
Shoe Station's turnaround argument rests on giving up the idea that every store should look the same. Interim CEO Clifton Sifford said the company had been running nearly identical ***** ortments across its stores even though its two banners serve very different customers, and that approach stopped working. The shift already shows up in the numbers. Once the company localized its athletic ***** ortments ahead of back-to-school, adult athletic sales moved from a low single-digit decline in the second quarter to a low single-digit increase in August.
Running shoes comped positive in both men's and women's categories, and men's work boots, a replenishment category with loyal repeat buyers, grew 2%. Management believes this fall's boot lineup is the best it has fielded in years, heading into what Sifford expects to be a bigger nonathletic fashion cycle. E-commerce sales grew 18.8% even as store traffic fell, and in-store conversion actually improved, evidence that customers who show up are buying; they just are not showing up in the same numbers yet. The company also ended the quarter debt-free with $131.6 million in cash, up $39.7 million from a year ago, giving it room to fund the localized rollout without straining the balance sheet.
The flip side is that the entire second quarter was ugly across the board. Shoe Carnival branded stores, still 63% of revenue, saw sales fall 6.5%, while the newly converted Shoe Station banner dropped 8.4%. Gross profit margin fell 690 basis points to 31.9%, a mix of a promotional footwear market and management's decision to accelerate liquidation of aged inventory, trading margin for cash. That combination cut net income to $6.3 million, or $0.23 per diluted share, down from $19.2 million and $0.70 a year earlier.
Management is not projecting relief anytime soon. Sifford said plainly, "We are not ***** uming the environment improves," and CFO Kerry Jackson noted that gross margins in fiscal August were still running below last year's levels at a pace comparable to the second quarter. Full-year gross margin guidance of 32.5% to 32.7% implies 390 to 410 basis points of compression for the year. Store impairment charges reached $6.7 million on 11 stores year to date, and management has already conceded that the core problem is not price, since conversion rates rose while total customer visits kept falling. That points to a marketing and trust problem rather than a demand problem, and fixing it will take more tha
Shoe Station's turnaround argument rests on giving up the idea that every store should look the same. Interim CEO Clifton Sifford said the company had been running nearly identical ***** ortments across its stores even though its two banners serve very different customers, and that approach stopped working. The shift already shows up in the numbers. Once the company localized its athletic ***** ortments ahead of back-to-school, adult athletic sales moved from a low single-digit decline in the second quarter to a low single-digit increase in August.
Running shoes comped positive in both men's and women's categories, and men's work boots, a replenishment category with loyal repeat buyers, grew 2%. Management believes this fall's boot lineup is the best it has fielded in years, heading into what Sifford expects to be a bigger nonathletic fashion cycle. E-commerce sales grew 18.8% even as store traffic fell, and in-store conversion actually improved, evidence that customers who show up are buying; they just are not showing up in the same numbers yet. The company also ended the quarter debt-free with $131.6 million in cash, up $39.7 million from a year ago, giving it room to fund the localized rollout without straining the balance sheet.
The flip side is that the entire second quarter was ugly across the board. Shoe Carnival branded stores, still 63% of revenue, saw sales fall 6.5%, while the newly converted Shoe Station banner dropped 8.4%. Gross profit margin fell 690 basis points to 31.9%, a mix of a promotional footwear market and management's decision to accelerate liquidation of aged inventory, trading margin for cash. That combination cut net income to $6.3 million, or $0.23 per diluted share, down from $19.2 million and $0.70 a year earlier.
Management is not projecting relief anytime soon. Sifford said plainly, "We are not ***** uming the environment improves," and CFO Kerry Jackson noted that gross margins in fiscal August were still running below last year's levels at a pace comparable to the second quarter. Full-year gross margin guidance of 32.5% to 32.7% implies 390 to 410 basis points of compression for the year. Store impairment charges reached $6.7 million on 11 stores year to date, and management has already conceded that the core problem is not price, since conversion rates rose while total customer visits kept falling. That points to a marketing and trust problem rather than a demand problem, and fixing it will take more tha


2 days ago
On September 10, Designer Brands (NYSE:DBI) reported second-quarter results that pushed full-year earnings guidance sharply higher, even as net sales slipped 1% year over year to $730.6 million. Adjusted operating income reached $39.4 million for the quarter, and management raised its adjusted diluted earnings per share outlook to a range of $0.47 to $0.52, up from $0.28 to $0.38. That kind of upward revision usually calms skeptics. Here, more than a third of the float is still sold short.
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands


2 days ago
Panthers news: Jalen **** er injury update is good news after Week 1 appeared first on ClutchPoints. Add ClutchPoints as a Preferred Source by clicking here.
Jalen **** er gave Carolina Panthers fans a scare after his monster Week 1 performance, but his initial injury update sounds encouraging.
Coker told reporters Monday that he rolled his ankle during the first quarter of Sunday's 59-37 loss to the Chicago Bears but expects to practice Wednesday.
That's tremendous news considering **** er somehow played through the injury and proceeded to torch Chicago's secondary.
The third-year receiver caught eight of his nine targets for a career-high 138 yards and two touchdowns, including a 51-yard score from Bryce Young. It was also the first multi-touchdown performance of **** er's career.
#update
Jalen **** er gave Carolina Panthers fans a scare after his monster Week 1 performance, but his initial injury update sounds encouraging.
Coker told reporters Monday that he rolled his ankle during the first quarter of Sunday's 59-37 loss to the Chicago Bears but expects to practice Wednesday.
That's tremendous news considering **** er somehow played through the injury and proceeded to torch Chicago's secondary.
The third-year receiver caught eight of his nine targets for a career-high 138 yards and two touchdowns, including a 51-yard score from Bryce Young. It was also the first multi-touchdown performance of **** er's career.
#update


2 days ago
Unavailable for the Alabama Crimson Tide's win at Kentucky, could the 2026 season debut of Noah Rogers and AK Dear come this upcoming Saturday against Florida State?
After missing Week 2, Alabama head coach Kalen DeBoer updated the status of both Monday afternoon during his Week 3 press conference, as well as a few other Crimson Tide players currently dealing with injuries.
Among those was also Michael Carroll, Alabama's starting right guard who missed the Kentucky game, his first of the season.
"Michael, we'll continue to work with him," DeBoer said. "I feel confident that we'll get there, and we'll just kind of see how the week goes, but I think he's heading in a good direction, and we hope to get him back."
"AK, making good progress. I think he was getting closer towards the end of the week. Again, reset, and we'll see where he's at today and then tomorrow get out there hopefully more on the practice field. He was doing some light practice, doing some things with us last week already. So, I think he expects, and his mindset's been awesome with what he had injury-wise too, just the recovery and the response, his mindset's helped him come back even quicker."
#week #kentucky
After missing Week 2, Alabama head coach Kalen DeBoer updated the status of both Monday afternoon during his Week 3 press conference, as well as a few other Crimson Tide players currently dealing with injuries.
Among those was also Michael Carroll, Alabama's starting right guard who missed the Kentucky game, his first of the season.
"Michael, we'll continue to work with him," DeBoer said. "I feel confident that we'll get there, and we'll just kind of see how the week goes, but I think he's heading in a good direction, and we hope to get him back."
"AK, making good progress. I think he was getting closer towards the end of the week. Again, reset, and we'll see where he's at today and then tomorrow get out there hopefully more on the practice field. He was doing some light practice, doing some things with us last week already. So, I think he expects, and his mindset's been awesome with what he had injury-wise too, just the recovery and the response, his mindset's helped him come back even quicker."
#week #kentucky


2 days ago
After briefly exiting Sunday's win over the Cleveland Browns, Jacksonville Jaguars' head coach Liam Coen fully expects wide receiver Brian Thomas Jr. to be available in Week 2 against Denver -- although he may be limited during the week of upcoming practices.
"I fully imagine him being able to play this game," Coen said on Monday. "No issues, just might not be able to get hit throughout the week or something."
Thomas Jr. left the Jaguars' Week 1 win in the first half with a shoulder injury. He was initially questionable to return, but did go back into the game.
Thomas Jr. finished the game with three receptions for 40 yards.
He also sustained a shoulder injury in the Jaguars' first joint practice with the Tampa Bay Buccaneers. Whether or not that injury and the current one are related has not been reported.
#fully #able #shoulder
"I fully imagine him being able to play this game," Coen said on Monday. "No issues, just might not be able to get hit throughout the week or something."
Thomas Jr. left the Jaguars' Week 1 win in the first half with a shoulder injury. He was initially questionable to return, but did go back into the game.
Thomas Jr. finished the game with three receptions for 40 yards.
He also sustained a shoulder injury in the Jaguars' first joint practice with the Tampa Bay Buccaneers. Whether or not that injury and the current one are related has not been reported.
#fully #able #shoulder

2 days ago
Interested in Johnson & Johnson? Here are five stocks we like better.
Johnson & Johnson raised its growth ambitions, forecasting 6.5% adjusted operational sales growth and 7.3% adjusted EPS growth in 2026, with revenue expected to surpass $100 billion. Executives see 2027 improving further and aim for double-digit growth by the end of the decade despite STELARA biosimilar competition.
The company plans to detail its long-term growth strategy at an enterprise review in December, highlighting new product launches, a pipeline that includes 12 proof-of-concept molecules in Phase III, and the durability of growth beyond 2030.
Capital spending is focused on Innovative Medicine and MedTech launches, including ICOTYDE, cancer treatments, and the OTTAVA robotic surgical system. J&J also expects continued momentum from its myeloma therapies, ICOTYDE's expanding coverage, and MedTech products, while using acquisitions mainly to support growth beyond the current decade.
5 Defensive Stocks to Watch as CPI and the Fed Put the Rally to the Test
#adjusted #interested
Johnson & Johnson raised its growth ambitions, forecasting 6.5% adjusted operational sales growth and 7.3% adjusted EPS growth in 2026, with revenue expected to surpass $100 billion. Executives see 2027 improving further and aim for double-digit growth by the end of the decade despite STELARA biosimilar competition.
The company plans to detail its long-term growth strategy at an enterprise review in December, highlighting new product launches, a pipeline that includes 12 proof-of-concept molecules in Phase III, and the durability of growth beyond 2030.
Capital spending is focused on Innovative Medicine and MedTech launches, including ICOTYDE, cancer treatments, and the OTTAVA robotic surgical system. J&J also expects continued momentum from its myeloma therapies, ICOTYDE's expanding coverage, and MedTech products, while using acquisitions mainly to support growth beyond the current decade.
5 Defensive Stocks to Watch as CPI and the Fed Put the Rally to the Test
#adjusted #interested


2 days ago
Argentina's state-controlled energy company YPF is close to signing several LNG sales agreements for its planned Argentina LNG project as it races toward a final investment decision later this year.
YPF CEO Horacio Marín said at the Gastech conference in Bangkok that the company expects to sign two or three LNG contracts covering between 0.5 million and 1.5 million tonnes per year each. YPF aims to have the agreements secured before partners make a final investment decision in November.
The $24-billion Argentina LNG development, backed by YPF, Italy's Eni and Abu Dhabi's XRG, is designed to turn the vast Vaca Muerta shale formation into a major source of LNG for international markets.
The initial development will feature two floating LNG facilities with combined capacity of 12 million tonnes per year, with potential expansion to 18 million tonnes. A dedicated 527-kilometer pipeline will transport gas from Vaca Muerta to the Atlantic coast in Río Negro province. YPF says the development will also include gas treatment and liquids infrastructure.
Eni and XRG each hold approximately 32% interests in the upstream blocks feeding the development, with YPF holding 36%.
#development #year #tonnes #muerta
YPF CEO Horacio Marín said at the Gastech conference in Bangkok that the company expects to sign two or three LNG contracts covering between 0.5 million and 1.5 million tonnes per year each. YPF aims to have the agreements secured before partners make a final investment decision in November.
The $24-billion Argentina LNG development, backed by YPF, Italy's Eni and Abu Dhabi's XRG, is designed to turn the vast Vaca Muerta shale formation into a major source of LNG for international markets.
The initial development will feature two floating LNG facilities with combined capacity of 12 million tonnes per year, with potential expansion to 18 million tonnes. A dedicated 527-kilometer pipeline will transport gas from Vaca Muerta to the Atlantic coast in Río Negro province. YPF says the development will also include gas treatment and liquids infrastructure.
Eni and XRG each hold approximately 32% interests in the upstream blocks feeding the development, with YPF holding 36%.
#development #year #tonnes #muerta


2 days ago
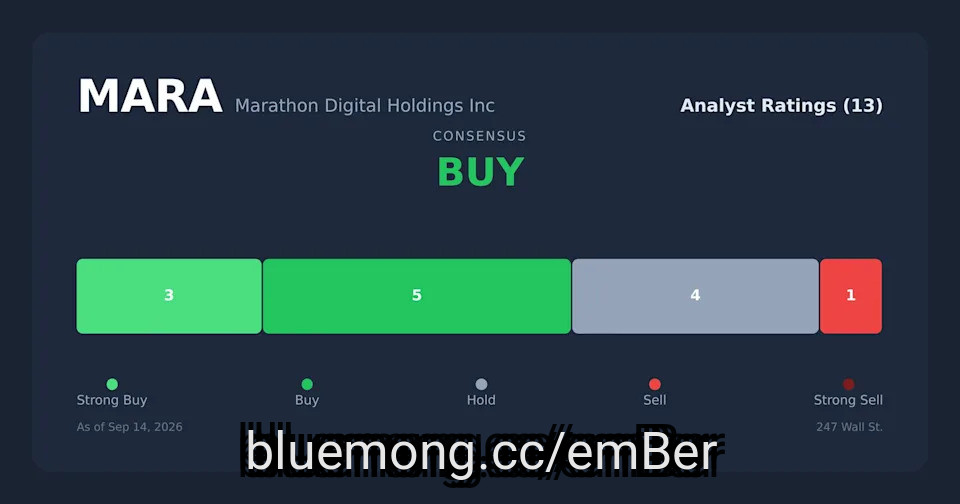
Coinbase jumped 6% on a Compass Point upgrade to Neutral, while MARA slid 2% after JPMorgan cut it to Underweight with an $11 target.
IBIT rose 1% as Bitcoin lifted crypto stocks, while SPY fell 0.8%, splitting crypto-linked equities from the broader AI-led tech selloff.
The Senate's CLARITY Act vote this week is the binary catalyst for Coinbase, though ****** yst Ed Engel expects the bill to fail.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Coinbase didn't make the cut. Enter your email to see the names that beat COIN. The report is free. Enter your email and see if any of your stocks made the cut.
Coinbase Global (NASDAQ:COIN) shares are up 6% to $185.34 Monday morning after Compass Point ****** yst Ed Engel upgraded the exchange operator to Neutral from Sell ahead of a scheduled Senate floor vote on crypto market-structure legislation. The bounce for Coinbase stock trims an 18% year-to-date decline that had made the exchange one of the sector's most bruised names heading into this week.
#Coinbase #engel #vote
IBIT rose 1% as Bitcoin lifted crypto stocks, while SPY fell 0.8%, splitting crypto-linked equities from the broader AI-led tech selloff.
The Senate's CLARITY Act vote this week is the binary catalyst for Coinbase, though ****** yst Ed Engel expects the bill to fail.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Coinbase didn't make the cut. Enter your email to see the names that beat COIN. The report is free. Enter your email and see if any of your stocks made the cut.
Coinbase Global (NASDAQ:COIN) shares are up 6% to $185.34 Monday morning after Compass Point ****** yst Ed Engel upgraded the exchange operator to Neutral from Sell ahead of a scheduled Senate floor vote on crypto market-structure legislation. The bounce for Coinbase stock trims an 18% year-to-date decline that had made the exchange one of the sector's most bruised names heading into this week.
#Coinbase #engel #vote



2 days ago
Enbridge Inc. (NYSE:ENB) has agreed to buy Blackstone-owned Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its presence in the U.S. liquids pipeline market. The deal includes a 75% stake in the 1,050-mile Pony Express Pipeline, a 51% interest in the Powder River Gateway system, around 8.4 million barrels of storage capacity and crude marketing operations.
Pony Express can move roughly 460,000 barrels of crude per day between the Rockies and the Cushing, Oklahoma, hub. The deal also gives Enbridge greater exposure to major producing regions, including the Bakken, Powder River and Denver-Julesburg basins.
The acquisition gives Enbridge Inc. (NYSE:ENB) a stronger position in U.S. crude transportation at a time when domestic oil production is expected to remain important. Pony Express gives the company a larger presence in the Rockies and complements its existing Express-Platte system.
That combination could allow Enbridge to bring the operations together more efficiently and find synergies across its wider liquids network. The deal also gives Enbridge more than additional pipeline capacity. It adds storage infrastructure and crude marketing operations, giving the company more flexibility in how it manages and optimizes volumes. Bringing these parts of the business together could also improve the economics of the acquired **** ets.
Enbridge Inc. (NYSE:ENB) expects the **** ets to generate significant free cash flow. The company also says the transaction should add to distributable cash flow per share in the first full year after closing. The **** ets also offer relatively predictable infrastructure-style cash flows. This means Enbridge does not need higher crude prices to benefit from the acquisition. The deal fits with the company's broader strategy of growing its fee-based energy infrastructure business across North America, backed by its C$41 billion secured growth backlog.
#enbridge #cash #gives #business
Pony Express can move roughly 460,000 barrels of crude per day between the Rockies and the Cushing, Oklahoma, hub. The deal also gives Enbridge greater exposure to major producing regions, including the Bakken, Powder River and Denver-Julesburg basins.
The acquisition gives Enbridge Inc. (NYSE:ENB) a stronger position in U.S. crude transportation at a time when domestic oil production is expected to remain important. Pony Express gives the company a larger presence in the Rockies and complements its existing Express-Platte system.
That combination could allow Enbridge to bring the operations together more efficiently and find synergies across its wider liquids network. The deal also gives Enbridge more than additional pipeline capacity. It adds storage infrastructure and crude marketing operations, giving the company more flexibility in how it manages and optimizes volumes. Bringing these parts of the business together could also improve the economics of the acquired **** ets.
Enbridge Inc. (NYSE:ENB) expects the **** ets to generate significant free cash flow. The company also says the transaction should add to distributable cash flow per share in the first full year after closing. The **** ets also offer relatively predictable infrastructure-style cash flows. This means Enbridge does not need higher crude prices to benefit from the acquisition. The deal fits with the company's broader strategy of growing its fee-based energy infrastructure business across North America, backed by its C$41 billion secured growth backlog.
#enbridge #cash #gives #business

2 days ago
The Cooper Companies, Inc. (NASDAQ:COO) cut its fiscal 2026 profit and revenue forecasts after weaker-than-expected demand for contact lenses weighed on its CooperVision business. The company now expects adjusted earnings of $4.51–$4.55 per share, down from its previous forecast of $4.58–$4.66, while revenue guidance was reduced to $4.23–$4.25 billion from $4.29–$4.32 billion. Third-quarter revenue came in at $1.07 billion, below Wall Street's $1.10 billion estimate, although adjusted EPS of $1.15 beat expectations.
The weakness was concentrated in CooperVision, where revenue fell to $717 million. Cooper said a reduction in U.S. channel inventory hurt results and is expected to continue affecting the fourth quarter. At the same time, the company completed its strategic review and decided to retain CooperSurgical rather than sell the business.
The biggest bullish argument is that some of the current weakness may be temporary rather than a fundamental deterioration in the contact lens market. The Cooper Companies, Inc. (NASDAQ:COO) specifically pointed to U.S. channel inventory reductions, meaning part of the sales pressure reflects distributors and customers working through existing stock rather than consumers permanently abandoning contact lenses. If inventories normalize, CooperVision could see a recovery in sales growth.
Cooper also continues to have a strong position in the global contact lens market. The company is investing in new products, expanding CooperVision's sales and marketing organization and improving inventory and logistics operations. Its strategic review also identified opportunities to reduce costs and improve operational efficiency.
There are encouraging signs beneath the weak headline numbers. Adjusted third-quarter EPS still increased 4% year over year to $1.15, while free cash flow jumped 66% to $273 million. The Cooper Companies, Inc. (NASDAQ:COO) also increased its share-repurchase authorization from $2 billion to $3 billion, giving the company another way to support per-share earnings if the stock remains depressed.
#Companies #revenue #contact #coopervision
The weakness was concentrated in CooperVision, where revenue fell to $717 million. Cooper said a reduction in U.S. channel inventory hurt results and is expected to continue affecting the fourth quarter. At the same time, the company completed its strategic review and decided to retain CooperSurgical rather than sell the business.
The biggest bullish argument is that some of the current weakness may be temporary rather than a fundamental deterioration in the contact lens market. The Cooper Companies, Inc. (NASDAQ:COO) specifically pointed to U.S. channel inventory reductions, meaning part of the sales pressure reflects distributors and customers working through existing stock rather than consumers permanently abandoning contact lenses. If inventories normalize, CooperVision could see a recovery in sales growth.
Cooper also continues to have a strong position in the global contact lens market. The company is investing in new products, expanding CooperVision's sales and marketing organization and improving inventory and logistics operations. Its strategic review also identified opportunities to reduce costs and improve operational efficiency.
There are encouraging signs beneath the weak headline numbers. Adjusted third-quarter EPS still increased 4% year over year to $1.15, while free cash flow jumped 66% to $273 million. The Cooper Companies, Inc. (NASDAQ:COO) also increased its share-repurchase authorization from $2 billion to $3 billion, giving the company another way to support per-share earnings if the stock remains depressed.
#Companies #revenue #contact #coopervision

2 days ago
Howmet Aerospace Inc. (NYSE:HWM) is facing a mixed outlook after GE Aerospace agreed to acquire Consolidated Precision Products (CPP) for about $11.75 billion to secure more control over critical engine castings and expand production capacity. The announcement initially hit Howmet shares, which fell about 10%, as investors worried that GE could eventually rely less on outside suppliers such as Howmet.
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial



2 days ago
Hub Group anticipates receiving a delisting notification from Nasdaq following delays in submitting its financial reports, which stemmed from an accounting error identified earlier this year. The company missed a Monday deadline to comply with Nasdaq's financial reporting requirements. It will ask for a hearing to keep its stock listing intact and plans to seek a further extension of the filing requirements.
The company said receipt of the letter doesn't mean shares will immediately stop trading, and that the hearing request will automatically stay a delisting for 15 calendar days. It will also ask for shares not to be delisted during the hearing process, which can take approximately 30 to 45 days to commence following the request.
"While there can be no ***** urances, the Company expects that the Company's Class A common stock will continue to trade on the Nasdaq Global Select Market during the hearing process," a Monday news release stated. "In addition, the Company expects to present to the Nasdaq Hearings Panel a compelling plan to regain full compliance with Nasdaq's continued listing requirements and to secure sufficient time to execute such plan."
Hub Group (NASDAQ: HUBG) announced in February that it had identified a $77-million understatement in purchased transportation expenses during the first three quarters of 2025, and that it was delaying fourth-quarter and full-year 2025 financial reporting. It said in May that "prematurely or incorrectly recognized" transactions were also discovered during 2023 and 2024, and that those periods, along with the first three quarters of 2025, would need to be restated.
It plans to complete the restatement process and file results for the outstanding periods during the fourth quarter. Shares of HUBG were off 6.2% in early trading on Monday compared to the S&P 500, which was down 0.6%.
#NASDAQ #shares #process
The company said receipt of the letter doesn't mean shares will immediately stop trading, and that the hearing request will automatically stay a delisting for 15 calendar days. It will also ask for shares not to be delisted during the hearing process, which can take approximately 30 to 45 days to commence following the request.
"While there can be no ***** urances, the Company expects that the Company's Class A common stock will continue to trade on the Nasdaq Global Select Market during the hearing process," a Monday news release stated. "In addition, the Company expects to present to the Nasdaq Hearings Panel a compelling plan to regain full compliance with Nasdaq's continued listing requirements and to secure sufficient time to execute such plan."
Hub Group (NASDAQ: HUBG) announced in February that it had identified a $77-million understatement in purchased transportation expenses during the first three quarters of 2025, and that it was delaying fourth-quarter and full-year 2025 financial reporting. It said in May that "prematurely or incorrectly recognized" transactions were also discovered during 2023 and 2024, and that those periods, along with the first three quarters of 2025, would need to be restated.
It plans to complete the restatement process and file results for the outstanding periods during the fourth quarter. Shares of HUBG were off 6.2% in early trading on Monday compared to the S&P 500, which was down 0.6%.
#NASDAQ #shares #process

2 days ago
General Motors is developing a domestic battery supply chain it expects to complete within two to three years, even as the company currently relies on some Chinese-sourced materials for its existing battery production.
Kurt Kelty, GM's vice president of battery and sustainability, told CNBC that the company's near-term goal is full domestic sourcing. "We're developing a supply chain such that, two years from now, three years from now, it will be domestic," Kelty said. "That's what we're aiming for — when we get into market, we've got a domestic source for that."
Kelty's comments center on sodium-ion battery cells that GM is developing with Denver-based startup Peak Energy for use in stationary energy storage systems for homes, businesses, and data centers. GM expects to reach commercial production of those cells around 2029, according to CNBC. A GM spokesperson confirmed to CNBC that the company would apply the same domestic sourcing priority to battery cells for future electric vehicles.
Unlike conventional lithium iron phosphate chemistry, sodium-ion cells are built around sodium from soda ash — a resource the U.S. holds in abundance — sidestepping the lithium and ferrous sulfate supply chains that China currently controls. Kelty added that sodium-ion cells handle a broader span of temperatures, which means they can function without the active thermal management that drives up the cost and complexity of stationary storage installations.
"The better thing to do is try to leapfrog, come up with a different technology that's actually better that we can actually source here," Kelty told CNBC.
#battery #supply #years #we 're
Kurt Kelty, GM's vice president of battery and sustainability, told CNBC that the company's near-term goal is full domestic sourcing. "We're developing a supply chain such that, two years from now, three years from now, it will be domestic," Kelty said. "That's what we're aiming for — when we get into market, we've got a domestic source for that."
Kelty's comments center on sodium-ion battery cells that GM is developing with Denver-based startup Peak Energy for use in stationary energy storage systems for homes, businesses, and data centers. GM expects to reach commercial production of those cells around 2029, according to CNBC. A GM spokesperson confirmed to CNBC that the company would apply the same domestic sourcing priority to battery cells for future electric vehicles.
Unlike conventional lithium iron phosphate chemistry, sodium-ion cells are built around sodium from soda ash — a resource the U.S. holds in abundance — sidestepping the lithium and ferrous sulfate supply chains that China currently controls. Kelty added that sodium-ion cells handle a broader span of temperatures, which means they can function without the active thermal management that drives up the cost and complexity of stationary storage installations.
"The better thing to do is try to leapfrog, come up with a different technology that's actually better that we can actually source here," Kelty told CNBC.
#battery #supply #years #we 're

2 days ago
Princess Diana's iconic "revenge dress" is heading back to auction. Meghan Markle is reportedly interested in buying it, but she could face some serious competition. A source claims Kim Kardashian is among several high-profile names determined to own the famous gown. With its royal history and emotional significance, the upcoming sale could become a closely watched battle.
Meghan Markle is reportedly hoping to get her hands on one of Princess Diana's most famous looks. The black Christina Stambolian dress is set to return to the auction block in December. Sotheby's expects it could sell for up to £220,000 (approxiamately $2,96,000).
The dress has a story almost as famous as its design. Diana wore it to a 1994 fundraising gala, on the same night then-Prince Charles allegedly admitted to infidelity. She stepped out in the daring off-the-shoulder number instead of following the more restrained royal style expected of her. The look soon earned its now-famous "revenge dress" nickname.
Now, according to New Idea, Meghan is supposedly considering a bid. However, she may have to beat some serious competition to take it home. A source claimed that Kim Kardashian is "determined to own this dress." The insider also named Salma Hayek and Lady Gaga as potential contenders. Several collectors from Qatar and Saudi Arabia are allegedly interested, too.
With that kind of competition, the final price could climb quickly. The source claimed Prince Harry and Meghan's budget could become "a huge problem" when the bidding begins. And apparently, the couple may not even agree on whether the dress should be theirs.
#several
Meghan Markle is reportedly hoping to get her hands on one of Princess Diana's most famous looks. The black Christina Stambolian dress is set to return to the auction block in December. Sotheby's expects it could sell for up to £220,000 (approxiamately $2,96,000).
The dress has a story almost as famous as its design. Diana wore it to a 1994 fundraising gala, on the same night then-Prince Charles allegedly admitted to infidelity. She stepped out in the daring off-the-shoulder number instead of following the more restrained royal style expected of her. The look soon earned its now-famous "revenge dress" nickname.
Now, according to New Idea, Meghan is supposedly considering a bid. However, she may have to beat some serious competition to take it home. A source claimed that Kim Kardashian is "determined to own this dress." The insider also named Salma Hayek and Lady Gaga as potential contenders. Several collectors from Qatar and Saudi Arabia are allegedly interested, too.
With that kind of competition, the final price could climb quickly. The source claimed Prince Harry and Meghan's budget could become "a huge problem" when the bidding begins. And apparently, the couple may not even agree on whether the dress should be theirs.
#several
4 days ago
Jim Cramer sees Enterprise Products Partners L.P. (NYSE:EPD) as a major beneficiary of the disruption surrounding the Strait of Hormuz, as he said during the September 8 episode of Mad Money:
When I wrote How to Make Money in Any Market… I didn't know that Enterprise Products Partners was going to be the, maybe the single biggest pipeline winner in this country thanks to the war. I didn't see that war coming. The CEO of Enterprise, Jim Teague, has raised awareness for the company's profit opportunity because of the Hormuz closing. The margins of some of its liquids, like ethane to ethylene, ethylene to polyethylene, have soared. As Teague says, the Houston Ship Channel is now just as important as the Strait of Hormuz. Now, there's an endorsement. Stock yields 5.8%.
Enterprise Products Partners L.P. (NYSE:EPD) reported record second-quarter adjusted EBITDA of $2.8 billion, up 17% year over year, while operational distributable cash flow reached a record $2.3 billion, up 21%. Moreover, pipeline volumes reached a record 14.7 million barrels of oil equivalent per day, up 8%, while marine-terminal volumes increased 33% to 2.8 million barrels per day. Co-Chief Executive Officer James Teague said:
Volumes at our marine terminals have returned to normal levels in June and July after the initial rush to backfill volumes affected by hostilities in the Middle East in April and May.
In July, Enterprise Products Partners L.P. (NYSE:EPD) declared a quarterly distribution of $0.56 per unit, or $2.24 annualized, a 2.8% increase from a year earlier. At EPD's September 8 closing price of $38.83, that equates to a yield of approximately 5.8%. The company has increased its distribution for 27 consecutive years. The company's latest investor materials show $6.5 billion of major capital projects under construction. It expects 2026 organic growth capital spending, net of ***** et-sale proceeds, of $2.9 billion to $3.4 billion. The company retained $1.1 billion of DCF for internally funded growth capital expenditures and buybacks.
#partners #hormuz
When I wrote How to Make Money in Any Market… I didn't know that Enterprise Products Partners was going to be the, maybe the single biggest pipeline winner in this country thanks to the war. I didn't see that war coming. The CEO of Enterprise, Jim Teague, has raised awareness for the company's profit opportunity because of the Hormuz closing. The margins of some of its liquids, like ethane to ethylene, ethylene to polyethylene, have soared. As Teague says, the Houston Ship Channel is now just as important as the Strait of Hormuz. Now, there's an endorsement. Stock yields 5.8%.
Enterprise Products Partners L.P. (NYSE:EPD) reported record second-quarter adjusted EBITDA of $2.8 billion, up 17% year over year, while operational distributable cash flow reached a record $2.3 billion, up 21%. Moreover, pipeline volumes reached a record 14.7 million barrels of oil equivalent per day, up 8%, while marine-terminal volumes increased 33% to 2.8 million barrels per day. Co-Chief Executive Officer James Teague said:
Volumes at our marine terminals have returned to normal levels in June and July after the initial rush to backfill volumes affected by hostilities in the Middle East in April and May.
In July, Enterprise Products Partners L.P. (NYSE:EPD) declared a quarterly distribution of $0.56 per unit, or $2.24 annualized, a 2.8% increase from a year earlier. At EPD's September 8 closing price of $38.83, that equates to a yield of approximately 5.8%. The company has increased its distribution for 27 consecutive years. The company's latest investor materials show $6.5 billion of major capital projects under construction. It expects 2026 organic growth capital spending, net of ***** et-sale proceeds, of $2.9 billion to $3.4 billion. The company retained $1.1 billion of DCF for internally funded growth capital expenditures and buybacks.
#partners #hormuz
4 days ago
Solaris Energy Infrastructure, Inc. (NYSE:SEI), traditionally known as an oil and gas field services and solutions company, has been increasingly shifting toward the data center market. On September 8, the company provided an update to its guidance ranges, which suggests that this shift is working.
The company lifted its adjusted EBITDA guidance for the third and fourth quarters of 2026 and provided its initial outlook for the first quarter of 2027. The company said that the updated expectations reflect stronger contributions from its core power services business, along with better-than-expected performance from recently acquired businesses. Solaris Energy Infrastructure, Inc. (NYSE:SEI) now expects Q3 2026 adjusted EBITDA of $110 million to $130 million, up from its previous range of $90 million to $105 million. At the midpoint, that represents a 23% increase.
For Q4 2026, the company raised its guidance to $145 million to $180 million from $100 million to $120 million, a 48% increase at the midpoint. The company also provided initial Q1 2027 adjusted EBITDA guidance of $200 million to $240 million.
Investors responded positively to the update as the stock rallied following the announcement. Solaris Energy Infrastructure, Inc. (NYSE:SEI) has returned about 150% over the past 12 months. As of September 8, the stock was up more than 25% year to date, compared with a 12% gain for the S&P 500.
The guidance update follows the company's September 2 announcement of its acquisition of Omega Foundation Services, a leader in the specialized engineering, procurement and construction industry with expertise in heavy civil construction across several end markets, including large-scale data centers.
#energy #Services
The company lifted its adjusted EBITDA guidance for the third and fourth quarters of 2026 and provided its initial outlook for the first quarter of 2027. The company said that the updated expectations reflect stronger contributions from its core power services business, along with better-than-expected performance from recently acquired businesses. Solaris Energy Infrastructure, Inc. (NYSE:SEI) now expects Q3 2026 adjusted EBITDA of $110 million to $130 million, up from its previous range of $90 million to $105 million. At the midpoint, that represents a 23% increase.
For Q4 2026, the company raised its guidance to $145 million to $180 million from $100 million to $120 million, a 48% increase at the midpoint. The company also provided initial Q1 2027 adjusted EBITDA guidance of $200 million to $240 million.
Investors responded positively to the update as the stock rallied following the announcement. Solaris Energy Infrastructure, Inc. (NYSE:SEI) has returned about 150% over the past 12 months. As of September 8, the stock was up more than 25% year to date, compared with a 12% gain for the S&P 500.
The guidance update follows the company's September 2 announcement of its acquisition of Omega Foundation Services, a leader in the specialized engineering, procurement and construction industry with expertise in heavy civil construction across several end markets, including large-scale data centers.
#energy #Services


4 days ago
Lululemon Athletica Inc. (NASDAQ:LULU) recently issued its second guidance cut of the year, and investors responded immediately by sending shares down roughly 18%. That selloff came despite an EPS beat, but the headline result was heavily supported by a tariff refund rather than underlying business strength. Brand sentiment, traffic, and leggings sales are all weakening across the company's two largest markets. The key issue for investors is no longer whether the quarter was weak, but whether the stock's low valuation and new CEO can provide the catalyst for a meaningful recovery.
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company
4 days ago
Interested in Lam Research Corporation? Here are five stocks we like better.
Lam Research raised its 2026 wafer-fabrication equipment spending outlook to the low-$150 billion range from $135 billion-$140 billion, driven by sustained AI demand and expectations for eight to 10 new leading-edge fabs through 2027.
AI hardware is increasing equipment intensity, while advanced chip designs and packaging are expanding Lam's addressable market. The company cited growing opportunities in gate-all-around transistors, backside power delivery, advanced packaging and dry-resist technology.
Lam is accelerating capacity expansion, including a second Malaysia facility, as clean-room availability and supply-chain capacity constrain the industry. The company also expects NAND upgrades to accelerate, while targeting mid-50% gross margins and reporting record customer-support revenue.
From High Dividend Growth to High Yield, These 3 Stocks Just Boosted Dividend Payouts
#billion #Research #equipment #advanced
Lam Research raised its 2026 wafer-fabrication equipment spending outlook to the low-$150 billion range from $135 billion-$140 billion, driven by sustained AI demand and expectations for eight to 10 new leading-edge fabs through 2027.
AI hardware is increasing equipment intensity, while advanced chip designs and packaging are expanding Lam's addressable market. The company cited growing opportunities in gate-all-around transistors, backside power delivery, advanced packaging and dry-resist technology.
Lam is accelerating capacity expansion, including a second Malaysia facility, as clean-room availability and supply-chain capacity constrain the industry. The company also expects NAND upgrades to accelerate, while targeting mid-50% gross margins and reporting record customer-support revenue.
From High Dividend Growth to High Yield, These 3 Stocks Just Boosted Dividend Payouts
#billion #Research #equipment #advanced

4 days ago
Updated Sept 11, 2026, 1:55 pm EDT / Original Sept 11, 2026, 7:30 am EDT
The grocery giant now expects same-store sales excluding fuel to rise between 0.2% and 0.8% for the fiscal year, down from a prior range of 1% to 2% growth. The new guidance includes a hit of roughly 140 basis points tied to the Inflation Reduction Act, which lowered prescription drug prices for Medicare beneficiaries and impacted pharmacy revenue. Management separately reaffirmed its earnings guidance of $5.10 to $5.30 a share for the fiscal year.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#inflation #medicare
The grocery giant now expects same-store sales excluding fuel to rise between 0.2% and 0.8% for the fiscal year, down from a prior range of 1% to 2% growth. The new guidance includes a hit of roughly 140 basis points tied to the Inflation Reduction Act, which lowered prescription drug prices for Medicare beneficiaries and impacted pharmacy revenue. Management separately reaffirmed its earnings guidance of $5.10 to $5.30 a share for the fiscal year.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#inflation #medicare

4 days ago
Qualcomm (QCOM) grew revenue just 1.9% over the last twelve months, against a compound pace of about 6.2% a year over five years and 4.5% over three. The quarterly path is worse. Across the last four quarters, year-over-year growth slid from 10.0% to 5.0%, then to declines of 3.5% and 4.0%. That turn to shrinking quarterly sales is the risk to weigh.
Phones Still Bring In About Half The Sales
In fiscal Q3 2026, handset chip revenue was $5.1 billion, about half of the $9.9 billion total. The CEO says unprecedented memory prices, plus supply shortages driven by data center demand, are pulling revenue down across mobile and consumer electronics. Management puts the net effect at a 20% drop in its Android chip revenue in 2026 from 2025.
And Apple Revenue Is Exiting Faster Than Planned
Apple is the second drag. Citing its own supply constraints, Qualcomm said on its fiscal Q3 2026 call that it expects materially lower share in new iPhone launches than its prior 20% estimate. An ****** yst put fiscal 2026 Apple product revenue at about $7.5 billion, and management called that a fair range.
#revenue #Apple #fiscal #management
Phones Still Bring In About Half The Sales
In fiscal Q3 2026, handset chip revenue was $5.1 billion, about half of the $9.9 billion total. The CEO says unprecedented memory prices, plus supply shortages driven by data center demand, are pulling revenue down across mobile and consumer electronics. Management puts the net effect at a 20% drop in its Android chip revenue in 2026 from 2025.
And Apple Revenue Is Exiting Faster Than Planned
Apple is the second drag. Citing its own supply constraints, Qualcomm said on its fiscal Q3 2026 call that it expects materially lower share in new iPhone launches than its prior 20% estimate. An ****** yst put fiscal 2026 Apple product revenue at about $7.5 billion, and management called that a fair range.
#revenue #Apple #fiscal #management

4 days ago
Palo Alto Networks, Inc. (NASDAQ:PANW) is entering its fiscal 2027 with strong momentum, particularly in next-generation security. But investors now demand more from the cybersecurity company after its stock rallied sharply.
On September 7, PhillipCapital downgraded Palo Alto stock to Neutral from Accumulate but raised the price target to $346 from $320.
PhillipCapital's move captures the central investment debate. It's that Palo Alto's opportunities are compelling, but the stock's roughly 160% rise from its February low to its August peak has raised the bar for further gains.
Palo Alto Networks, Inc. (NASDAQ:PANW)'s revenue rose 34% YoY to $3.4 billion in fiscal 2026 fourth quarter. More importantly, Next-Generation Security ARR (NGS ARR) surged 63% to $9.10 billion. The company added nearly $1 billion of net new NGS ARR in the quarter. The company targets $20 billion in NGS ARR by fiscal 2030, as it expects platformization and AI infrastructure investment to continue driving growth.
More than 65% of Palo Alto's NGS ARR comes from platformized customers. Meanwhile, AI is expanding the addressable market. As enterprises deploy agents, Palo Alto offerings such as Prisma AIRS and Cortex, alongside CyberArk's identity-security platform, can address emerging needs.
#palo #company #NASDAQ #PANW
On September 7, PhillipCapital downgraded Palo Alto stock to Neutral from Accumulate but raised the price target to $346 from $320.
PhillipCapital's move captures the central investment debate. It's that Palo Alto's opportunities are compelling, but the stock's roughly 160% rise from its February low to its August peak has raised the bar for further gains.
Palo Alto Networks, Inc. (NASDAQ:PANW)'s revenue rose 34% YoY to $3.4 billion in fiscal 2026 fourth quarter. More importantly, Next-Generation Security ARR (NGS ARR) surged 63% to $9.10 billion. The company added nearly $1 billion of net new NGS ARR in the quarter. The company targets $20 billion in NGS ARR by fiscal 2030, as it expects platformization and AI infrastructure investment to continue driving growth.
More than 65% of Palo Alto's NGS ARR comes from platformized customers. Meanwhile, AI is expanding the addressable market. As enterprises deploy agents, Palo Alto offerings such as Prisma AIRS and Cortex, alongside CyberArk's identity-security platform, can address emerging needs.
#palo #company #NASDAQ #PANW
4 days ago
On September 3, Genesco (NYSE:GCO) reported a second quarter that should not have worked on paper. Revenue fell 3% to $530 million, yet the company nearly halved its adjusted operating loss and raised full-year earnings guidance to the top end of its range. That combination, shrinking sales alongside expanding profit, is the footwear-first strategy showing up in real numbers. Every one of the company's three brands beat internal expectations, and management says the toughest sales pressure ahead is coming from a deliberate choice rather than a weakening business.
Journeys, the company's teen-focused chain, delivered its eighth consecutive quarter of positive comparable sales, up 2%, even while lapping strong growth from a year earlier. The more interesting story sits underneath that number. The Journeys 4.0 store format, a redesigned concept built around a more elevated ***** ortment, is generating a sales lift of 25% or more wherever it opens, and the company expects roughly 180 locations, about a fifth of its fleet, running that format by year-end. That rollout, combined with fleet optimization and more efficient use of selling staff, handed Journeys 180 basis points of expense leverage in the quarter. Comparable sales kept accelerating into August, marking Journeys' ninth straight month of positive comps and a mid-single-digit gain during the back-to-school peak.
Johnston & Murphy is running its own streak, with comparable sales up 4% in its third consecutive positive quarter, helped by a newly extended, multiyear partnership with Peyton Manning and a broader shift in menswear toward more refined, put-together dressing. Companywide, adjusted gross margin expanded 140 basis points to 47.2%, and the adjusted operating loss narrowed to $8 million from $14 million a year ago. Genesco also collected $22.5 million in tariff refunds during the quarter and cut total debt to $15.8 million from $71 million a year earlier, giving a new CFO and a new Schuh president a far healthier balance sheet to work with as they settle into their roles.
The drag comes almost entirely from Schuh, Genesco's UK chain, where comparable sales fell 9% as management deliberately pulled back on discounting to protect margin. Executives were blunt about the cost of that choice. CEO Mimi Vaughn said "the UK consumer market remains challenged and price sensitive," and the Schuh turnaround is expected to take longer than the one already underway at Journeys. That pressure is now baked into guidance. Full-year total sales are expected to fall about 2%, worse than the prior forecast of down 1% to flat, with management incorporating more back-half sales pressure than it originally planned for given how promotional the UK footwear market has become.
#comparable #schuh #management #pressure
Journeys, the company's teen-focused chain, delivered its eighth consecutive quarter of positive comparable sales, up 2%, even while lapping strong growth from a year earlier. The more interesting story sits underneath that number. The Journeys 4.0 store format, a redesigned concept built around a more elevated ***** ortment, is generating a sales lift of 25% or more wherever it opens, and the company expects roughly 180 locations, about a fifth of its fleet, running that format by year-end. That rollout, combined with fleet optimization and more efficient use of selling staff, handed Journeys 180 basis points of expense leverage in the quarter. Comparable sales kept accelerating into August, marking Journeys' ninth straight month of positive comps and a mid-single-digit gain during the back-to-school peak.
Johnston & Murphy is running its own streak, with comparable sales up 4% in its third consecutive positive quarter, helped by a newly extended, multiyear partnership with Peyton Manning and a broader shift in menswear toward more refined, put-together dressing. Companywide, adjusted gross margin expanded 140 basis points to 47.2%, and the adjusted operating loss narrowed to $8 million from $14 million a year ago. Genesco also collected $22.5 million in tariff refunds during the quarter and cut total debt to $15.8 million from $71 million a year earlier, giving a new CFO and a new Schuh president a far healthier balance sheet to work with as they settle into their roles.
The drag comes almost entirely from Schuh, Genesco's UK chain, where comparable sales fell 9% as management deliberately pulled back on discounting to protect margin. Executives were blunt about the cost of that choice. CEO Mimi Vaughn said "the UK consumer market remains challenged and price sensitive," and the Schuh turnaround is expected to take longer than the one already underway at Journeys. That pressure is now baked into guidance. Full-year total sales are expected to fall about 2%, worse than the prior forecast of down 1% to flat, with management incorporating more back-half sales pressure than it originally planned for given how promotional the UK footwear market has become.
#comparable #schuh #management #pressure
4 days ago
After Bayern Munich's 5-0 win against Bodo/Glimt, goal scorer Harry Kane was asked about his ongoing contract negotiations with the club. Though he could not offer any details of the contract or when he expects it to be done, he spoke with a calm confidence that everything would get done in due time.
"We had conversations, a couple of weeks ago and some more this week. As I said before, a contract doesn't happen overnight — it takes time to digest and see how we can make it best case possible for everyone involved. I don't expect it to be done in the next week or two, but hopefully in the next one or two months we should be where we want to be. Right now I'm at a happy place. All I want to do and what the club wants me to do is to focus on the pitch, score the goals and help the team. I'm calm.. It's hard to talk to you guys about it because it's confidential stuff. I'm sure in due time you'll know about the details and get the answers you're looking for. All I can say now is that the conversations are going well. We'll see what happens," Kane said (as captured by iMiaSanMia)
Kane's contract expires at the end of this season, but both sides seem to be confident that a deal will get done to keep the England captain in Bavaria. His comments on Thursday are consistent with updates from Bayern front office officials over the past months.
Where is your confidence level that Kane will remain with Bayern Munich after this season? Let us know in the comments.
Sign up for a user account and get:
#club #calm
"We had conversations, a couple of weeks ago and some more this week. As I said before, a contract doesn't happen overnight — it takes time to digest and see how we can make it best case possible for everyone involved. I don't expect it to be done in the next week or two, but hopefully in the next one or two months we should be where we want to be. Right now I'm at a happy place. All I want to do and what the club wants me to do is to focus on the pitch, score the goals and help the team. I'm calm.. It's hard to talk to you guys about it because it's confidential stuff. I'm sure in due time you'll know about the details and get the answers you're looking for. All I can say now is that the conversations are going well. We'll see what happens," Kane said (as captured by iMiaSanMia)
Kane's contract expires at the end of this season, but both sides seem to be confident that a deal will get done to keep the England captain in Bavaria. His comments on Thursday are consistent with updates from Bayern front office officials over the past months.
Where is your confidence level that Kane will remain with Bayern Munich after this season? Let us know in the comments.
Sign up for a user account and get:
#club #calm


5 days ago
Biohaven (BHVN) stock plummeted Thursday after the company paused enrollment in a midstage study of its seizure treatment due to safety concerns.
The Food and Drug Administration is now requiring Biohaven to ***** s the potential for human toxicity from a metabolite in the drug, opakalim. Opakalim is in testing as a treatment for focal onset seizures. But, in rats, it proved toxic.
Dosing is still ongoing. But the rodent toxicity setback likely delays potential regulatory approval. That's a boon for Xenon Pharmaceuticals (XENE), which is in late-stage testing with its drug, azetukalner. Both drugs work by opening potassium channels in the nervous system to calm overactive brain cells.
On the stock market today, Biohaven stock dropped 14.7% to 12.79. Shares fell below their 21-day and 50-day moving averages on the news, MarketSurge shows. Xenon stock slid a fraction to 58.80.
To ask for FDA approval, Biohaven will need the results of studies called RISE-2 and RISE-3. The hold was placed on the former, but the latter is still ongoing. The company expects to have the results from RISE-3 later this year.
#toxicity
The Food and Drug Administration is now requiring Biohaven to ***** s the potential for human toxicity from a metabolite in the drug, opakalim. Opakalim is in testing as a treatment for focal onset seizures. But, in rats, it proved toxic.
Dosing is still ongoing. But the rodent toxicity setback likely delays potential regulatory approval. That's a boon for Xenon Pharmaceuticals (XENE), which is in late-stage testing with its drug, azetukalner. Both drugs work by opening potassium channels in the nervous system to calm overactive brain cells.
On the stock market today, Biohaven stock dropped 14.7% to 12.79. Shares fell below their 21-day and 50-day moving averages on the news, MarketSurge shows. Xenon stock slid a fraction to 58.80.
To ask for FDA approval, Biohaven will need the results of studies called RISE-2 and RISE-3. The hold was placed on the former, but the latter is still ongoing. The company expects to have the results from RISE-3 later this year.
#toxicity


5 days ago
Zhihu Inc. (NYSE:ZH) disclosed on September 6 that a wholly owned subsidiary had signed a conditional RMB1.5 billion cash commitment to Tianjin Lisi Xingshen Equity Investment Partnership. The agreement, dated September 4, requires shareholder approval, with payments funded internally through capital calls.
Zhihu Inc. (NYSE:ZH) expects to hold no more than 30% of the fund and will have no role in daily management or individual investment decisions. The blind-pool structure asks shareholders to approve a manager and strategy before specific investments are identified. The fund targets early-to-mid-stage private AI and technology companies with significant mainland China connections.
The strategic rationale fits the company's existing capabilities. Zhihu Inc. (NYSE:ZH) is developing AI search, expert-data solutions and AI-enabled content businesses. Exposure to foundation models, infrastructure, robotics and applications could create technology partnerships and help identify emerging customer needs.
A specialist fund also supplies investment research, deal sourcing and portfolio oversight that would require substantial internal resources to replicate. For shareholders, the potential benefit combines investment returns with commercial opportunities for the core content platform. Any cooperation would still require separate **** sment and agreement.
There is an operating business to build around. Second-quarter paid content and intellectual-property operations revenue increased to RMB425.9 million from RMB408.2 million. Zhihu Inc. (NYSE:ZH) also reduced total operating expenses by 13% to RMB469.4 million. These results support a focused approach in which outside technology complements established content and expert relationships.
#content #technology #million
Zhihu Inc. (NYSE:ZH) expects to hold no more than 30% of the fund and will have no role in daily management or individual investment decisions. The blind-pool structure asks shareholders to approve a manager and strategy before specific investments are identified. The fund targets early-to-mid-stage private AI and technology companies with significant mainland China connections.
The strategic rationale fits the company's existing capabilities. Zhihu Inc. (NYSE:ZH) is developing AI search, expert-data solutions and AI-enabled content businesses. Exposure to foundation models, infrastructure, robotics and applications could create technology partnerships and help identify emerging customer needs.
A specialist fund also supplies investment research, deal sourcing and portfolio oversight that would require substantial internal resources to replicate. For shareholders, the potential benefit combines investment returns with commercial opportunities for the core content platform. Any cooperation would still require separate **** sment and agreement.
There is an operating business to build around. Second-quarter paid content and intellectual-property operations revenue increased to RMB425.9 million from RMB408.2 million. Zhihu Inc. (NYSE:ZH) also reduced total operating expenses by 13% to RMB469.4 million. These results support a focused approach in which outside technology complements established content and expert relationships.
#content #technology #million



