19 days ago
California Resources Corporation (NYSE:CRC) announced on September 17 that it had agreed to sell its Uinta Basin **** ets, located mostly in Utah and Colorado, to an undisclosed buyer for $90 million in cash. The company had come to own the Uinta **** ets, which span about 100,000 net acres, after it acquired Berry Corp last year. However, CRC considered them non-core to its operations. The net proceeds from the sale will be used for shareholder returns and other corporate purposes.
Francisco Leon, President and CEO of California Resources Corporation, commented:
"Today's transaction strengthens our business. The monetization of our Uinta Basin **** ets sharpens our focus on California and captures additional value from the Berry merger. This transaction enhances our capital allocation flexibility, allowing us to invest in higher-return opportunities within the Golden State and supports our shareholder return strategy. The sale also helps offset the purchase price of our recent midstream transaction."
The transaction is expected to close by year-end, subject to the receipt of certain third-party consents and other customary conditions.
The sale will allow CRC to redeploy the $90 million toward **** ets that are central to its operating strategy while avoiding additional capital commitments to Uinta. The company already stated in its Q2 earnings call that Uinta has higher capital intensity, higher break-evens, lower crude quality, higher transportation and operating costs, and steeper declines. Therefore, the sale removes a portfolio distraction at a time when CRC is concentrating investment in California infrastructure and production.
#uinta #assets #transaction #capital
19 days ago
Targa Resources Corp. (NYSE:TRGP) has significantly outperformed the wider market this year, posting gains of over 56% since the beginning of 2026. A major catalyst behind this growth was the 20-year fee-based agreement that the company signed with ExxonMobil last month.
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda
19 days ago
Shell plc (NYSE:SHEL) is a global group of energy and petrochemical companies with a presence in over 70 countries. The stock has delivered gains of over 23% since the beginning of 2026 and even hit its all-time high earlier in March, driven primarily by soaring oil prices and solid earnings amid supply disruptions in the Middle East.
Following a slight pullback over the last few months, Shell has started to regain momentum, and Morgan Stanley expects the rally to continue. On September 3, the investment bank upgraded SHEL from 'Equal Weight' to 'Overweight', while also raising its price target from $81.60 to $101.30. The target boost implies an upside of 9% from the current levels and even exceeds Shell's previous record high of almost $95 per share achieved earlier this year.
Morgan Stanley noted that the concerns surrounding Shell's long-term resource longevity have now eased, with the company now positioned to sustain production growth through 2030 and stabilize output thereafter. The ******* yst firm believes that while the stock has been weighed down due to its dividend policy, there is now "potential for a significant acceleration. As a result, Morgan Stanley promoted SHEL to top-pick status.
Shell completed the acquisition of ARC Resources earlier this month, addressing the resource-depletion concerns that have weighed down its valuation. The $16.4 billion deal has significantly expanded the energy giant's gas reserves and will boost its production by 370,000 boed. Additionally, the strategic move expands Shell's exposure to the North American gas market and bolsters its position in a region that is emerging as a key player in the global LNG supply.
Shell's recent upstream investments provide further support to Morgan Stanley's bullish thesis. The company announced earlier this month that it had agreed to acquire a 30% interest in BP's Conifer exploration prospect in the US Gulf, and a 50% stake in the Tupinamba exploration block in Brazil's Santos Basin. Additionally, it also recently signed a preliminary agreement for the acquisition of production rights over Ghana's South Deepwater Tano Cape Three Points oil and gas block.
#shel #production #energy #Stock
19 days ago
Enbridge Inc. (NYSE:ENB) has declined by around 17% since hitting its record high in May, likely as a result of rising bond yields, lack of visibility on the company's 5% growth guidance through the end of the decade, and the recently closed equity offering intended to fund the midstream operator's strategic acquisitions.
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target


19 days ago
On August 6, Targa Resources Corp. (NYSE:TRGP) reported a record second quarter. Adjusted EBITDA reached $1.60 billion, a 38% jump from the same period a year earlier, and management now expects full-year results near the top of its guidance range. Targa moves and processes natural gas and natural gas liquids out of the Permian Basin, and these numbers suggest that system is running fuller than ever.
The strength came from volume, not just price. Adjusted EBITDA also climbed 14% from the first quarter, helped by Permian gas volumes that added over 450 million cubic feet of daily throughput. Some producers held back output because Waha gas prices went negative, and Targa still set a volume record. Volumes for NGL pipelines, fractionation, and LPG exports also hit records, helped by Train 11, a new fractionator in Mont Belvieu, Texas, that started up early in the quarter.
Construction is also landing on time. East Driver, a new processing plant serving the Midland side of the Permian, started up late in the quarter and ahead of schedule, and the other gathering and logistics projects are tracking their plans. Shareholders get a cut too. On July 16, Targa declared a $1.25 per share quarterly dividend, 25% above the payout for the second quarter of 2025, payable August 14 to holders of record on July 31. It also spent $80 million buying back shares during the quarter.
Growth at this pace costs real money. Targa plans about $4.5 billion in net growth spending this year, and its consolidated debt stood at $19,578 million on June 30. About $3.2 billion of liquidity gives it a cushion. In July, it also extended its receivables securitization facility to July 30, 2027 and raised the size to as much as $800 million. More borrowing capacity helps, but it is still borrowing.
Not every dollar of the profit surge is as steady as a pipeline volume. Management tied the higher outlook partly to strong marketing margin and optimization work in the first two quarters, and the quarter's jump in marketing margin came from greater optimization opportunities. That kind of income can be lumpy. Meanwhile, lower natural gas prices trimmed margins in the gathering business, and the Waha curtailments showed that producers can pull back when local prices turn ugly.
#record
20 days ago
On September 16, Evolution Petroleum Corporation (NYSEAMERICAN:EPM) held its fiscal fourth-quarter and full-year 2026 earnings call, and the numbers told a story of a company climbing out of a rough patch. Revenue jumped 20% sequentially to $24.2 million as oil prices realized before hedge settlements shot up 49% year over year to $90.74 a barrel. Adjusted EBITDA more than doubled to $6.5 million. After a bruising third quarter, the fourth quarter finally looked like the recovery management had promised investors back in May.
The fourth-quarter turnaround wasn't just about crude. NGL prices realized $32.49 a barrel, up 27% year over year, and because Evolution leaves its NGL production entirely unhedged, every dollar of that gain flowed straight through. That combination of higher liquids pricing, growing production, and the roll-off of a prior-period transportation adjustment at the Delhi Field pushed operating cash flow to $6.8 million in the quarter, nearly double the $3.5 million generated in the third quarter.
Behind the quarterly numbers sits a longer-term shift in how Evolution makes money. The company closed a roughly $16 million acquisition of mineral and royalty acreage in the Permian's Midland Basin after the fiscal year ended, adding about 3,420 net royalty acres and more than 200 barrels of oil equivalent per day of current production, all without Evolution spending a dime on development. That mirrors what's already happening in the SCOOP/STACK play, where fourth-quarter production climbed 14% year over year to 1,275 BOE per day while unit operating costs fell to $10.33 a barrel. Evolution also replaced more than 100% of the 2.6 million barrels of oil equivalent it produced during the year, ending fiscal 2026 with 27.2 million barrels of proved reserves, an outcome that matters directly to a dividend now in its 52nd consecutive quarter.
Not every part of the business bounced back. Average daily production fell 4% year over year to 6,901 barrels of oil equivalent per day, largely because the flush production from new Chaveroo wells that boosted last year's fourth quarter has since tapered off. Natural gas pricing remained the softest spot in the portfolio, especially at the Jonah Field, where CEO Kelly Loyd said "regional differentials have weighed on realizations" even as broader demand for gas keeps growing. CFO Ryan Stash noted that stronger oil and NGL results helped offset "continued weakness in natural gas realizations, particularly at Jonah."
#barrel

22 days ago
On August 5, Kinetik Holdings Inc. (NYSE:KNTK) reported the strongest quarterly results in company history and raised its full-year 2026 guidance. The Permian-focused midstream operator posted net income, including noncontrolling interest, of $123.1 million for the quarter ended June 30, while Adjusted EBITDA climbed to $280.8 million. Management didn't stop at celebrating the number. It used the quarter as the launchpad for a string of expansion decisions that stretch out to 2028.
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter

22 days ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
French manufacturing giant Vallourec has secured the entire carbon-steel line pipe and external coating scope for Petrobras's Sepia 2 offshore development, covering roughly 130 kilometers of subsea infrastructure.
The contract strengthens its position in Brazil's technically demanding pre-salt market and gives investors another reason to believe the group's offshore order book still has room to grow.
Vallourec shares rose around 6% after the premium pipe manufacturer announced a major contract with Subsea7 for the Sepia 2 project in Brazil's Santos Basin.
The agreement covers roughly 130 kilometers of rigid risers and flowlines, representing more than 15,000 tonnes of carbon-steel seamless line pipe designed for highly corrosive environments.
#roughly
22 days ago
Choosing between a clean energy innovator and a traditional oil giant reflects a core tension in today's market. Investors must decide if Bloom Energy (NYSE:BE) or Diamondback Energy (NASDAQ:FANG) is the better buy.
Bloom Energy manufactures solid oxide fuel cells that provide reliable onsite power, targeting the surging demand from artificial intelligence infrastructure. Diamondback Energy focuses on extracting oil and gas from the Permian Basin, prioritizing operational efficiency and shareholder returns. While both operate in the energy **** e, their business models, risk profiles, and valuation metrics differ significantly for 2026 investors.
Bloom Energy serves as a prominent player among renewable energy stocks, focusing on solid oxide technology for onsite electricity and hydrogen production. The company targets large-load customers in the data center, semiconductor, and industrial sectors where power reliability is critical. Key partnerships include an agreement with American Electric Power (NASDAQ:AEP) to provide up to one gigawatt of fuel cells and a financing framework worth nearly $5.0 billion with Brookfield (NYSE:BN).
In FY 2025, Bloom Energy reported revenue of approximately $2.0 billion, which represents a growth rate of roughly 37.3% compared to the prior year. Despite this robust top-line performance, the company reported a net loss of nearly $88.4 million for the same period. This loss widened from a net loss of approximately $29.2 million in FY 2024, although the net margin of negative 4.4% in FY 2025 was a significant improvement over the negative 22.7% margin seen in FY 2023.
As of its December 2025 balance sheet, Bloom Energy holds a debt-to-equity ratio of 3.9x. This ratio measures total debt against shareholder equity, indicating the company relies moderately on borrowed funds to fuel its expansion. The current ratio, which measures a company's ability to cover short-term debts with its short-term **** ets, stands at a strong 6.0x. For FY 2025, free cash flow reached close to $57.2 million, which is the cash remaining after paying for operating costs and equipment investments.
#bloom #million


23 days ago
On August 5, Kinetik Holdings Inc. (NYSE:KNTK) reported the strongest quarterly results in company history and raised its full-year 2026 guidance. The Permian-focused midstream operator posted net income, including noncontrolling interest, of $123.1 million for the quarter ended June 30, while Adjusted EBITDA climbed to $280.8 million. Management didn't stop at celebrating the number. It used the quarter as the launchpad for a string of expansion decisions that stretch out to 2028.
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#natural

23 days ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
French manufacturing giant Vallourec has secured the entire carbon-steel line pipe and external coating scope for Petrobras's Sepia 2 offshore development, covering roughly 130 kilometers of subsea infrastructure.
The contract strengthens its position in Brazil's technically demanding pre-salt market and gives investors another reason to believe the group's offshore order book still has room to grow.
Vallourec shares rose around 6% after the premium pipe manufacturer announced a major contract with Subsea7 for the Sepia 2 project in Brazil's Santos Basin.
The agreement covers roughly 130 kilometers of rigid risers and flowlines, representing more than 15,000 tonnes of carbon-steel seamless line pipe designed for highly corrosive environments.
#pipe #vallourec #roughly

25 days ago
TotalEnergies SE (NYSE:TTE) plans to invest $10 billion alongside its partners in Angola over the next five years, with the goal of maintaining and potentially increasing its oil production in the country. TotalEnergies currently produces around 450,000 barrels per day in Angola, making it the country's largest oil operator and accounting for more than 40% of its total output.
The investment will go toward existing operations, new exploration, and projects aimed at replacing production from Angola's aging offshore fields. One of the biggest projects in the pipeline is the $6 billion Kaminho development, which is expected to start producing oil in 2028. TotalEnergies SE (NYSE:TTE) is also expanding its exploration efforts after signing agreements for two additional offshore blocks. On top of that, the company recently announced a new discovery in Block 17 that could add roughly 6,000 barrels per day to production.
The investment strengthens TotalEnergies SE (NYSE:TTE)'s position in one of Africa's key oil-producing markets and, perhaps more importantly, helps protect a major source of existing production. With around 450,000 barrels per day already coming from Angola, simply keeping output at current levels could continue to provide a meaningful contribution to the company's upstream cash flow. Any additional production from new discoveries and projects would offer further upside.
The current oil-price environment also works in TotalEnergies' favor. Brent crude recently climbed above $100 a barrel amid supply concerns and geopolitical tensions and is currently trading near this range. If prices remain elevated, projects designed to maintain or increase Angolan production could generate strong returns and make the company's investment more attractive.
There are also signs that TotalEnergies SE (NYSE:TTE) is doing more than just trying to slow production declines. Its recent Acacia-5 discovery in Block 17 could add around 6,000 barrels per day, while the company is expanding its exploration presence through new offshore blocks in the Lower Congo Basin. Angola's efforts to reform its oil sector and attract more exploration investment could also create a more favorable environment for TotalEnergies over the longer term.
#investment #offshore

25 days ago
Enbridge Inc. (NYSE:ENB) has agreed to buy Blackstone-owned Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its presence in the U.S. liquids pipeline market. The deal includes a 75% stake in the 1,050-mile Pony Express Pipeline, a 51% interest in the Powder River Gateway system, around 8.4 million barrels of storage capacity and crude marketing operations.
Pony Express can move roughly 460,000 barrels of crude per day between the Rockies and the Cushing, Oklahoma, hub. The deal also gives Enbridge greater exposure to major producing regions, including the Bakken, Powder River and Denver-Julesburg basins.
The acquisition gives Enbridge Inc. (NYSE:ENB) a stronger position in U.S. crude transportation at a time when domestic oil production is expected to remain important. Pony Express gives the company a larger presence in the Rockies and complements its existing Express-Platte system.
That combination could allow Enbridge to bring the operations together more efficiently and find synergies across its wider liquids network. The deal also gives Enbridge more than additional pipeline capacity. It adds storage infrastructure and crude marketing operations, giving the company more flexibility in how it manages and optimizes volumes. Bringing these parts of the business together could also improve the economics of the acquired **** ets.
Enbridge Inc. (NYSE:ENB) expects the **** ets to generate significant free cash flow. The company also says the transaction should add to distributable cash flow per share in the first full year after closing. The **** ets also offer relatively predictable infrastructure-style cash flows. This means Enbridge does not need higher crude prices to benefit from the acquisition. The deal fits with the company's broader strategy of growing its fee-based energy infrastructure business across North America, backed by its C$41 billion secured growth backlog.
#enbridge #cash #gives #business
26 days ago
During the September 3 episode of Mad Money, Jim Cramer mentioned Microsoft Corporation (NASDAQ:MSFT) for its unconventional approach to powering hyperscale data centers in partnership with Chevron Corporation (NYSE:CVX). He said:
How about Microsoft? Look, Mr. Softee is getting religion. They've realized that by giving us more disclosure on Azure, their cloud infrastructure business, we'll find more things to like. They're right. In the end, I come to praise Microsoft CFO Amy Hood, not bury her. They've been very clever getting power for the data centers, pumping it right out of the Permian. They got this deal with Chevron as a partner… 2.67 gigawatts. No one's talking about it. It's the cleanest behind the meter plan for power I have seen yet. People even, and this is not a stretch, I'm not kidding, people even like Copilot.
CFO Amy Hood provided Wall Street with a much clearer look at actual cloud demand by breaking down detailed Azure growth metrics and data center capacity constraints. At the same time, enterprise adoption of Microsoft 365 Copilot is moving past initial trials, with major corporations deploying the AI ***** istant across workforce segments.
A major highlight of the company's infrastructure strategy is a twenty-year agreement with Chevron Corporation (NYSE:CVX) for a proposed 2.67-gigawatt natural gas power plant in West Texas. Designed to supply dedicated off-grid electricity directly to a hyperscale data center in the Permian Basin, the project bypasses regional grid transmission queues to secure reliable power for continuous AI workloads. Microsoft Corporation's (NASDAQ:MSFT) president of Cloud Operations + Innovation, Noelle Walsh, commented:
Our agreement with Chevron helps ensure we'll have dedicated, large-scale power to support the evolution and reliability of advanced compute. Through this partnership, we're delighted to grow with and become a deeper part of the West Texas community.
#chevron #power #they 've
27 days ago
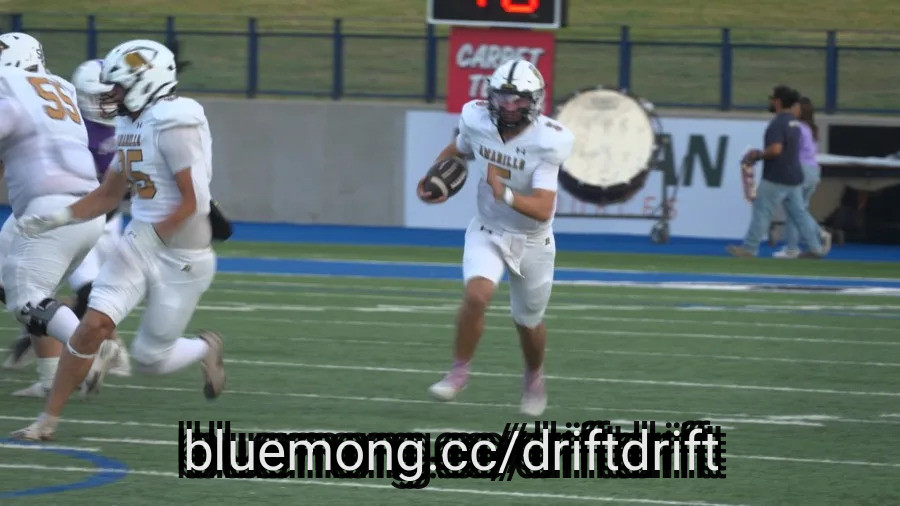
MIDLAND, Texas (KMID/KPEJ) - After a close game that came down to the end, the Midland Bulldogs fell 17-14 to Amarillo. Midland now drops to 0-3 on the season.
Next week, the Bulldogs will look for their first win of the season when they hit the road to face Bastrop.
Watch the video above for the highlights.
Copyright 2026 Nexstar Media, Inc. All rights reserved. This material may not be published, broadcast, rewritten, or redistributed.For the latest news, weather, sports, and streaming video, head to Yourbasin.
#kpej
27 days ago
Tamboran Resources Corporation (NYSE:TBN) announced September 7 that it and Daly Waters Energy, LP had begun gas sales from the Shenandoah South Pilot Project into Australia's Northern Territory network. The deliveries mark the Beetaloo Basin's first gas sales and move the project into revenue generation.
The Sturt Plateau Compression Facility has a capacity of approximately 48.5 million cubic feet per day. Contracted supply of approximately 38.8 million cubic feet per day is expected by early 2027 under a long-term take-or-pay agreement with the Northern Territory Government. These are gross project volumes. Commissioning gas receives a discounted price because supply remains interruptible.
Tamboran Resources Corporation (NYSE:TBN) now has a working route from wells through processing infrastructure to a customer. All five wells on the Shenandoah South 2 pad have been drilled, stimulated and connected to the facility. Initial deliveries reduce uncertainty around the physical connection between the resource and its market.
Contracted demand equals 80% of stated processing capacity, providing a substantial foundation for utilization once production reaches the target. Take-or-pay agreements generally require buyers to pay for committed volumes even if they do not take delivery, subject to contractual conditions.
The gas sales agreement specifies a fixed price with annual adjustments linked to Australia's Consumer Price Index. That structure provides more revenue visibility than relying entirely on spot-market demand, although the price remains confidential.
#corporation

28 days ago
On September 2, Shell Offshore, a subsidiary of Shell plc (NYSE:SHEL), announced the acquisition of a 30% working interest in Conifer, an exploration prospect operated by BP p.l.c. (NYSE:BP) in the U.S. Gulf of Mexico. Located offshore within Keathley Canyon near BP's Kaskida host development, Conifer represents a significant deep-water play. BP retains operatorship, with the initial exploration well expected to spud in 2027. While the deal reflects shared risk and capital efficiency in high-cost offshore basins, comparing the two giants' Q2 2026 earnings shows that Shell is currently executing from a position of superior financial strength.
Shell plc (NYSE:SHEL) delivered an exceptionally clean Q2 2026 report. Adjusted earnings reached $9.8 billion, driven by record upstream production in Brazil and record refinery utilization, which offset Middle East operational outages. Cash flow from operations (CFFO) came in at $21.4 billion, supported by higher realized prices and a $3.4 billion working capital inflow. Shell maintained strict capital discipline, reiterating its full-year capex outlook of $24 billion–$26 billion while completing $5.8 billion in structural cost reductions since 2022. Balance sheet health remains robust, with gearing at 19% and net debt at $42 billion ($12 billion excluding leases).
BP p.l.c. (NYSE:BP) also turned in a solid Q2 recovery, but its headline metrics lag behind Shell's scale. BP reported underlying replacement cost profit (its proxy for net income) of $5.7 billion, a 78% quarter-over-quarter rebound fueled by strong refining margins and oil trading. Operating cash flow reached $10.9 billion after absorbing a $1.0 billion working capital build. BP used strong cash generation to trim net debt down to $22.25 billion, while guiding full-year capex to $13.5 billion–$14.0 billion.
Although BP raised its quarterly dividend by 4% to 8.66 cents, Shell's cash engine allowed it to announce its 19th consecutive quarter of at least $3 billion in share buybacks, distributing 44% of CFFO over the trailing 12 months.
Shell's bull case centers on superior capital allocation, aggressive portfolio high-grading, including the ARC Resources acquisition targeting a 4% production CAGR through 2030, and consistent share buybacks. The bear case focuses on execution risks in integrated gas and LNG amid volatile market conditions, as well as the challenges of integrating large-scale acquisitions.
#cost


1 month ago
On August 5, Southwest Gas Holdings (NYSE:SWX) reported second quarter results for the period ended June 30 and reaffirmed its full year 2026 guidance. Net income attributable to the company reached $42.1 million, a sharp turnaround from a $40.2 million loss in the same quarter of 2025. But the number that stood out was the Great Basin 2028 Expansion Project, where contracted demand has grown enough that management now expects capital costs of $2.3 billion instead of the $1.7 billion baked into current five year guidance.
Southwest Gas's growth story increasingly runs through Nevada. Binding precedent agreements for the Great Basin 2028 Expansion Project have grown to roughly 1 billion cubic feet per day of contracted demand, and the company has fielded another 1.8 billion cubic feet of expressions of interest for phases running from 2029 through 2035. Based on that demand, management now projects an annual margin of $270 million to $300 million once the pipeline is in service, on capital investment of about $2.3 billion.
Regulators have been cooperating too. California's Public Utilities Commission approved the non-cost-of-capital pieces of Southwest Gas's rate case, adding roughly $40 million of incremental annual revenue and triggering recognition of $9.7 million of previously deferred first-quarter income. Nevada regulators approved a Triennial Resource Plan with prudency pre-determinations for about $186 million of capital spending, and the company filed for a general rate case increase of roughly $74 million.
Arizona's new System Integrity Mechanism, effective April 1 this year, lets Southwest Gas recover safety and reliability spending faster, up to a $50 million annual cap. The company put $520 million into its network in the first six months of 2026, including $115 million toward Great Basin, and closed the quarter with $270.5 million in cash and nearly $1 billion in available liquidity.
Look past the headline swing to profit, and the picture gets murkier. The core natural gas distribution segment actually earned less this quarter, with its contribution to net income falling from $45.6 million a year earlier to $40.8 million, and its adjusted net income slipping from $33.7 million to $31 million. Depreciation and amortization rose $8.7 million, or 13%, as gas plant in service grew 7% year over year, a reminder that heavy pipeline spending shows up in expenses well before it shows up in rates.
#million #company #basin


1 month ago
Williams has closed its approximately $5.5 billion acquisition of Momentum Midstream, giving the U.S. pipeline operator a substantially larger position in the Haynesville natural gas basin as Gulf Coast LNG and power demand continue to rise.
The transaction consists of approximately $3.5 billion in cash and debt consideration and around $2 billion in Williams equity.
Momentum brings more than 4,000 miles of pipeline, over 1 million dedicated acres and 6 billion cubic feet per day of gas gathering capacity. The ******* ets also include processing and treating facilities and three pipelines backed by take-or-pay contracts with a combined 4.05 Bcf/d of transportation capacity.
Williams initially announced the acquisition on August 3, valuing the transaction at up to $5.5 billion. At the time, the company said the deal carried an implied valuation of approximately 8.5 times projected 2027 EBITDA and was expected to increase both earnings per share and available funds from operations per share. Williams also raised the midpoint of its 2026 adjusted EBITDA guidance by $200 million to $8.4 billion to reflect the transaction.
The acquisition gives Williams a larger role in moving Haynesville gas toward some of the fastest-growing sources of U.S. gas demand, particularly LNG export facilities and industrial consumers along the Gulf Coast.
#williams #billion #transaction

1 month ago
WestEnd Capital Management, an investment advisor, released its Q2 2026 investor letter. The letter can be downloaded here. WestEnd Capital Management's Core Strategy achieved a 16.3% net return in the quarter, surpassing the S&P 500's 15.0%. This performance stemmed from strong earnings generators and upward earnings revisions, showcasing U.S. companies' efficiency in converting sales into profits. S&P 500 net profit margins reached a decade-high of 14.8% in Q1 and are expected to remain above 14% in Q2 despite challenges like higher interest rates and geopolitical uncertainty. Technology remains a key focus in WestEnd's portfolio, along with investments in infrastructure, demographic shifts, financial innovation, and selective consumer opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, WestEnd Capital Management highlighted WaterBridge Infrastructure LLC (NYSE:WBI). WaterBridge Infrastructure LLC (NYSE:WBI) is a pure-play water infrastructure company. On September 2, 2026, WaterBridge Infrastructure LLC (NYSE:WBI) closed at $32.26 per share. Over the past month, WaterBridge Infrastructure LLC (NYSE:WBI) declined 1.31%, while YTD its shares are up 61.37%. WaterBridge Infrastructure LLC (NYSE:WBI) has a market capitalization of $3.98 billion.
WestEnd Capital Management stated the following regarding WaterBridge Infrastructure LLC (NYSE:WBI) in its Q2 2026 investor letter:
"WaterBridge Infrastructure LLC (NYSE:WBI) owns and operates the largest independent produced-water infrastructure network in the Delaware Basin, providing services that are essential to energy production throughout one of North America's most productive oil basins.
The scale and density of this network would be extremely difficult and expensive to replicate. WaterBridge also generates most of its revenue through long-term contracts that include minimum-volume commitments and inflation-linked pricing.
#waterbridge #investor #quarter #earnings
1 month ago
Shell has completed its acquisition of Canadian oil and gas producer ARC Resources, significantly expanding the supermajor's position in the prolific Montney basin of British Columbia and Alberta.
The transaction has an updated enterprise value of approximately $16.5 billion, including $2.5 billion of net debt and leases. ARC shareholders receive C$8.20 in cash and 0.40247 Shell shares for each ARC share, according to Shell.
The acquisition immediately adds around 370,000 barrels of oil equivalent per day of natural gas and liquids production to Shell's portfolio and more than 1.5 million net acres in the Montney. At the end of 2025, ARC held around 2 billion boe of proved and probable reserves.
The deal also strengthens Shell's Canadian LNG strategy. ARC's gas resources sit close to Shell's existing Montney operations, while Shell owns a 40% interest in LNG Canada. ARC previously said its undeveloped gas properties could help Shell extract additional value through its integrated LNG business, including a potential second phase of LNG Canada.
Shell expects the acquisition to lift production growth across its Integrated Gas and Upstream businesses to around 4% annually through 2030, compared with 2025. The company expects double-digit returns and says the deal should boost free cash flow per share beginning in 2027.
#acquisition #canadian #resources

1 month ago
Plains All American Pipeline (PAA) demonstrates strong technical momentum, with shares up more than 45% over the past year.
The stock is trading at a new 5-year high.
PAA boasts a 6.54% dividend yield, which adds to its appeal.
PAA's crude oil and NGL segments are positioned for volume-driven growth, supported by long-term commitments and increasing throughput.
Valued at $18.2 billion, Plains All American Pipeline (PAA) is a master limited partnership involved in the transportation, storage, terminalling, and marketing of crude oil, natural gas, natural gas liquids, and refined products. The partnership has operations in the Permian Basin, South Texas/Eagle Ford area, Rocky Mountain, and Gulf Coast in the U.S., and Manito, South Saskatchewan, and Rainbow in Canada.
#pipeline #natural

1 month ago
First Eagle Investment Management, an investment management company, released its Q2 2026 investor update for "First Eagle Global Fund". The letter can be downloaded here. Easing tensions in the Middle East led to a strong rally in risk markets in Q2. The S&P 500 Index rose 15.2%, while the MSCI EAFE Index gained 10.8%. Growth stocks outperformed, with the MSCI World Growth Index significantly exceeding value returns. A notable shift in U.S. interest rate expectations followed Kevin Warsh's appointment as chair of the Federal Open Market Committee, pushing Treasury yields higher and strengthening the dollar. Despite the optimistic market environment, concerns about fiscal constraints and limited policy flexibility remain. Tighter credit spreads and elevated equity valuations reflect strong demand for financial ***** ets, with household wealth in equities at a post-WWII high. Earnings expectations are buoyant, driven by AI infrastructure developments. Against this backdrop, Global Fund A Shares returned 2.86% in Q2 2026, with emerging markets and developed Europe as the primary contributors. Developed Asia (excluding ***** an) was the only detractor, and ***** an lagged. Information technology and financials led among equity sectors, while materials and energy detracted. The fund underperformed relative to the MSCI World Index during this period. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, First Eagle Global Fund highlighted ExxonMobil Holdings Corporation (NYSE:XOM). ExxonMobil Holdings Corporation (NYSE:XOM) is a leading US-based crude oil and natural gas exploration and production company. On August 31, 2026, ExxonMobil Holdings Corporation (NYSE:XOM) closed at $160.95 per share. Over the past month, ExxonMobil Holdings Corporation (NYSE:XOM) returned 5.74%, and its shares are up 41.95% over the past year. ExxonMobil Holdings Corporation (NYSE:XOM) has a market capitalization of $661.81 billion.
First Eagle Global Fund stated the following regarding ExxonMobil Holdings Corporation (NYSE:XOM) in its Q2 2026 investor letter:
"Shares of integrated oil and gas giant ExxonMobil Holdings Corporation (NYSE:XOM) traded down alongside easing crude oil prices. Although the company experienced disruptions in its Middle East operations, it reported better-than expected results for its most recent quarter because of improved production from ***** ets in Guyana and the Permian Basin. We continue to view Exxon as a high-quality operator with strong capital discipline, an attractive portfolio of durable ***** ets and a commitment to returning cash to shareholders."
#first

1 month ago
ONEOK, Inc. (NYSE:OKE) has agreed to acquire Brazos Midstream's Permian Midland Basin natural-gas gathering and processing ***** ets for $4.425 billion in cash. The deal is being paired with a $9 billion nonvoting minority equity investment from Apollo, of which ONEOK plans to use about $5 billion to reduce existing debt. ONEOK expects the acquisition to be immediately accretive to earnings and free cash flow per share.
The transaction would more than double ONEOK, Inc. (NYSE:OKE)'s Midland Basin processing capacity to approximately 2.3 Bcf/d, including plants already under construction. The acquired platform includes roughly 700 miles of gathering infrastructure, 1.2 Bcf/d of processing capacity after the Cassidy II plant is completed, and approximately 600,000 dedicated acres backed by fixed-fee contracts with more than 12 years of weighted-average remaining term.
The biggest attraction is the quality and location of the ***** ets. The Permian remains one of the most economically important oil and gas-producing regions in the U.S., and the Brazos system gives ONEOK, Inc. (NYSE:OKE) additional exposure to ***** ociated natural-gas volumes generated by oil production. The acquired ***** ets are supported by 14 active drilling rigs operated by producers including ExxonMobil, Diamondback Energy, and Double Eagle. The long-term contracts provide ONEOK with considerable visibility into future volumes and cash flows. That makes this more than a simple capacity expansion. ONEOK is effectively adding infrastructure that can grow alongside production on the dedicated acreage.
The ***** ets fit closely with ONEOK's existing gathering, processing, NGL transportation and crude infrastructure. That creates an opportunity to extract more value from the same barrels and molecules as they move through ONEOK's network.
The company expects to connect the Brazos system with downstream ***** ets such as its West Texas NGL Pipeline and the Medford NGL fractionation facility. This broader integration could produce commercial and operational efficiencies that an independent owner of the ***** ets might not be able to capture. ONEOK estimates about $80 million of full-year synergies in its 2027 EBITDA calculation and expects additional commercial and capital efficiencies as the systems are integrated.
#cash #expects
1 month ago
First Eagle Investment Management, an investment management company, released its Q2 2026 investor update for "First Eagle Global Fund". The letter can be downloaded here. Easing tensions in the Middle East led to a strong rally in risk markets in Q2. The S&P 500 Index rose 15.2%, while the MSCI EAFE Index gained 10.8%. Growth stocks outperformed, with the MSCI World Growth Index significantly exceeding value returns. A notable shift in U.S. interest rate expectations followed Kevin Warsh's appointment as chair of the Federal Open Market Committee, pushing Treasury yields higher and strengthening the dollar. Despite the optimistic market environment, concerns about fiscal constraints and limited policy flexibility remain. Tighter credit spreads and elevated equity valuations reflect strong demand for financial ***** ets, with household wealth in equities at a post-WWII high. Earnings expectations are buoyant, driven by AI infrastructure developments. Against this backdrop, Global Fund A Shares returned 2.86% in Q2 2026, with emerging markets and developed Europe as the primary contributors. Developed Asia (excluding ***** an) was the only detractor, and ***** an lagged. Information technology and financials led among equity sectors, while materials and energy detracted. The fund underperformed relative to the MSCI World Index during this period. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, First Eagle Global Fund highlighted ExxonMobil Holdings Corporation (NYSE:XOM). ExxonMobil Holdings Corporation (NYSE:XOM) is a leading US-based crude oil and natural gas exploration and production company. On August 31, 2026, ExxonMobil Holdings Corporation (NYSE:XOM) closed at $160.95 per share. Over the past month, ExxonMobil Holdings Corporation (NYSE:XOM) returned 5.74%, and its shares are up 41.95% over the past year. ExxonMobil Holdings Corporation (NYSE:XOM) has a market capitalization of $661.81 billion.
First Eagle Global Fund stated the following regarding ExxonMobil Holdings Corporation (NYSE:XOM) in its Q2 2026 investor letter:
"Shares of integrated oil and gas giant ExxonMobil Holdings Corporation (NYSE:XOM) traded down alongside easing crude oil prices. Although the company experienced disruptions in its Middle East operations, it reported better-than expected results for its most recent quarter because of improved production from ***** ets in Guyana and the Permian Basin. We continue to view Exxon as a high-quality operator with strong capital discipline, an attractive portfolio of durable ***** ets and a commitment to returning cash to shareholders."
#fund #msci

1 month ago
ONEOK has agreed to acquire Brazos Midstream's natural gas gathering and processing ******* ets in the Permian Basin's Midland sub-basin for $4.425 billion in cash, expanding the midstream operator's footprint in one of the largest U.S. oil and gas producing regions.
The acquisition will be funded as part of a separate $9 billion nonvoting minority equity investment from funds and affiliates managed by Apollo Global Management. ONEOK plans to use roughly $5 billion of the Apollo proceeds to extinguish existing debt, while the remainder will fund the Brazos acquisition.
The structure allows ONEOK to finance the transaction without issuing common equity. The company said the combination of the Apollo investment and planned debt reduction is expected to bring its pro forma 2027 debt-to-EBITDA ratio to about 3.25 times.
Brazos' Midland Basin system is supported by roughly 600,000 dedicated acres under fixed-fee contracts with a weighted average remaining term exceeding 12 years, according to ONEOK. Producers operating on the acreage include ExxonMobil, Diamondback Energy and Double Eagle, with 14 active drilling rigs currently supporting the system.
After completion of the Cassidy II processing plant, which ONEOK expects in the third quarter of 2027, the acquired system is expected to comprise about 700 miles of gathering infrastructure and 1.2 billion cubic feet per day of gas processing capacity across seven Midland Basin counties.
#basin

1 month ago
PetroChina reported record first-half operating results for 2026, with profit attributable to shareholders rising 22% year over year to RMB103.94 billion as the Chinese energy giant expanded across natural gas, new materials and lower-carbon businesses.
Revenue increased 5.3% to RMB1.527 trillion, while basic earnings per share reached RMB0.57. PetroChina said it was the first time its attributable profit had exceeded RMB100 billion in a half-year period.
The company's oil, gas and new energies business remained its biggest earnings contributor, generating RMB100.45 billion in operating profit during the first half.
PetroChina reported oil and gas equivalent production of 921 million barrels, domestic crude production of 393 million barrels and marketable natural gas production of 2.66 trillion cubic feet.
The company said it made six new discoveries and advanced 19 new developments during the period. It also established two large gas reserve areas in the Sichuan and Junggar basins and a major deep conventional oil reserve area at Tarim Fuman.
#petrochina #first #production #rmb100

1 month ago
Chevron Corporation (NYSE:CVX) and TotalEnergies SE (NYSE:TTE) are making major moves in Sub-Saharan Africa, underscored by Chevron's August 17 announcement of a significant oil and gas condensate discovery in offshore Angola's Block 0. The 105-4X exploration well in the Lower Congo Basin encountered over 600 meters of column with 90 meters of net pay in the primary Pinda reservoir. Operated by Chevron's subsidiary CABGOC (39.2% interest) alongside Sonangol E&P, Azule Energy, and TotalEnergies, the ****** et will likely be tied back to nearby existing infrastructure for low-cost production. The discovery highlights Chevron's broader Sub-Saharan push, which generates ~300k boed net and includes recent additions in Nigeria, Guinea-Bissau, Equatorial Guinea, and Angola's Blocks 49, 50, 33, and 14/23, alongside the upcoming Nabba-1X well in Namibia.
Photo from Fervo Energy website
Looking at Q2 2026 financial metrics, both energy giants posted robust results, but Chevron outperformed TotalEnergies across absolute top- and bottom-line figures as well as capital efficiency.
Chevron Corporation (NYSE:CVX) generated $70.1 billion in revenue and reported net income of $12.1 billion ($6.11 per share), with adjusted earnings hitting $12.0 billion. Driven by record production of 4.07 million boed (up 20% year-over-year) and strong refining throughput, Chevron produced an impressive $22.6 billion in operating cash flow and $18.1 billion in free cash flow, delivering a return on capital employed (ROCE) of 21.4%.
TotalEnergies SE (NYSE:TTE) also delivered solid top-line cash generation but came in lower in net profitability. Leveraging higher commodity prices during the Middle East conflict, TotalEnergies generated $9.8 billion in cash flow and $6.0 billion in adjusted net income for Q2 2026, with oil and gas production averaging 2.395 Mboe/d. Its Exploration & Production unit posted $3.2 billion in adjusted net operating income and $5.8 billion in cash flow, while Downstream contributed $2.9 billion in cash flow and Integrated Power generated $700 million. Both energy majors maintain strong, identical balance-sheet leverage, with each firm posting a net debt gearing ratio of 13.1% at the close of Q2. Overall, Chevron leads in total profitability, cash flow generation, and return on capital, making it the stronger financial performer this quarter.
#cash #TotalEnergies #flow #well


1 month ago
UT Permian Basin gets an early opportunity to challenge an FCS opponent when the Falcons visit UT Rio Grande Valley on Saturday night in Edinburg, Texas.
Dec 29, 2018; Miami Gardens, FL, USA; a general view of a football on the field in the 2018 Orange Bowl college football playoff semifinal game between the Alabama Crimson Tide and the Oklahoma Sooners at Hard Rock Stadium. Mandatory Credit: Jasen Vinlove-Imagn Images
Date: Saturday, August 29, 2026
Time: 8:00 PM ET
Channel: ESPN+
#saturday #Football #permian

1 month ago
Osasuna and Getafe CF face each other this Monday at the Reyno de Navarra (El Sadar) for round three of the La Liga.
Osasuna have won 4 points to date and are placed in 7th position. In their last fixture, Luis Ramis's team won 1-2 against Celta de Vigo (La Liga 2026/27).
Getafe CF have 3 points to their name this season and occupy 9th position in the table. In their last game, José Bordalás's team lost 2-1 against Partizan (UEFA Conference League (Qual.) 2026/27).
The last meeting between the two teams ended with Getafe CF winning 1-0.
Osasuna ( vs Celta de Vigo 2026-08-27): Sergio Herrera, Íñigo Arguibide, Abel Bretones, Alejandro Catena, Asier Osambela, Jorge Herrando, Jonathan Dubasin, Lucas Torró, Jon Moncayola, Kike Barja, Raúl García
#liga #vigo #team