

2 months ago
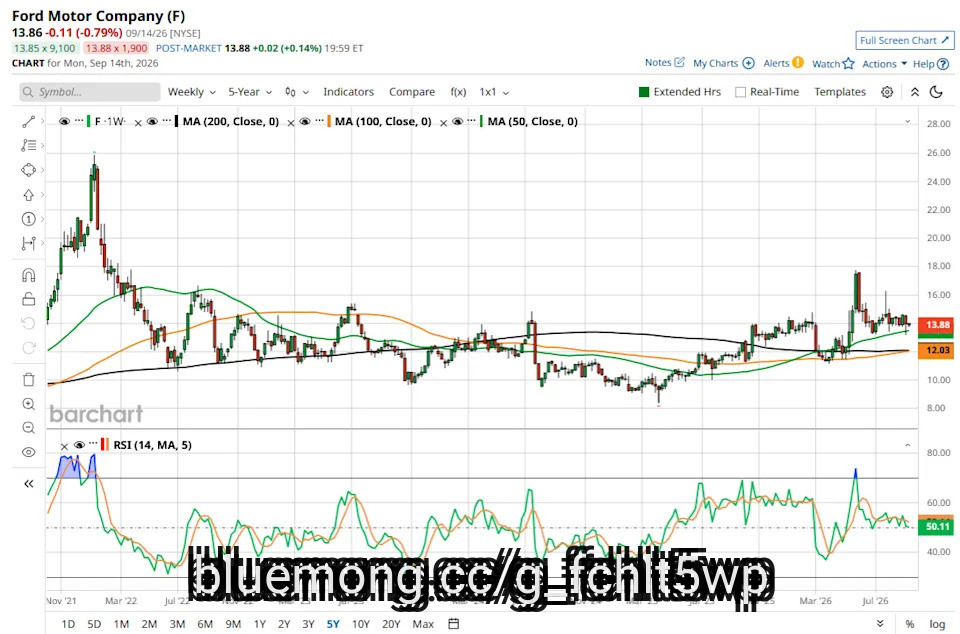
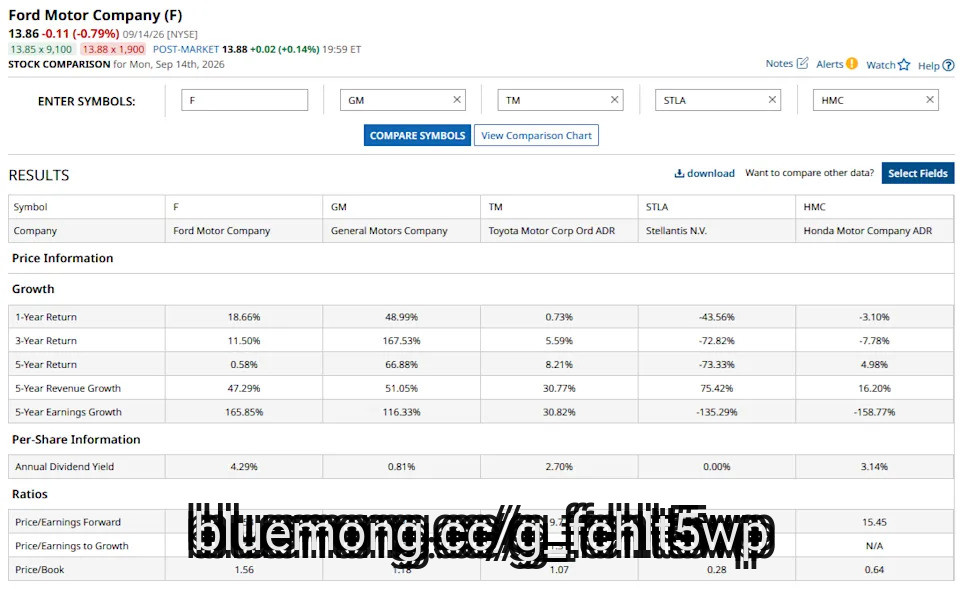
With a dividend yield of 4.3%, Ford (F) is among the highest-yielding constituents of the S&P 500 Index ($SPX). That number would look even more compelling considering Ford's dividend yield is over four times what an average S&P 500 Index constituent pays.
However, a bit of number-crunching tells a different picture. Dividend yield is basically a function of the per-share dividend, which is the numerator in the equation, and the stock price, which is the denominator. Dividend yield rises when the company raises its dividends or the share price falls. More often than not, the latter is true for companies that have a very high dividend yield.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ****** ysis you won't find anywhere else.
The S&P 500's dividend yield is near its historical lows. Two factors can be blamed for the dip in the world's most popular index's dividend yield. First, tech companies' share in the market-cap-weighted index has soared amid the artificial intelligence (AI) driven rally. Mega-cap tech companies are known to be frugal with dividends, and their rising weightage in the index pulls down its dividend yield. Second, while the annualized dividend per share of the S&P 500 has continued to rise over the years, the increase has been much lower compared to the surge in stock prices.
In contrast, Ford's quarterly dividend has been static since July 2022, when the company raised the payout by 50% to $0.15. Notably, while Ford paid special dividends in the preceding three years to reach its payout targets, it hasn't raised its payout for over four years. Its dividend yield is still high because of its underperforming stock, which has essentially gone nowhere in the last five years and trades 46% below its October 2022 highs.
#Dividend #yield #Share #dividends
However, a bit of number-crunching tells a different picture. Dividend yield is basically a function of the per-share dividend, which is the numerator in the equation, and the stock price, which is the denominator. Dividend yield rises when the company raises its dividends or the share price falls. More often than not, the latter is true for companies that have a very high dividend yield.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ****** ysis you won't find anywhere else.
The S&P 500's dividend yield is near its historical lows. Two factors can be blamed for the dip in the world's most popular index's dividend yield. First, tech companies' share in the market-cap-weighted index has soared amid the artificial intelligence (AI) driven rally. Mega-cap tech companies are known to be frugal with dividends, and their rising weightage in the index pulls down its dividend yield. Second, while the annualized dividend per share of the S&P 500 has continued to rise over the years, the increase has been much lower compared to the surge in stock prices.
In contrast, Ford's quarterly dividend has been static since July 2022, when the company raised the payout by 50% to $0.15. Notably, while Ford paid special dividends in the preceding three years to reach its payout targets, it hasn't raised its payout for over four years. Its dividend yield is still high because of its underperforming stock, which has essentially gone nowhere in the last five years and trades 46% below its October 2022 highs.
#Dividend #yield #Share #dividends

2 months ago
The CoinEx crypto exchange is shutting down its operations after nine years, citing a "prolonged" crypto market downturn, shrinking trading activity and rising compliance costs across major jurisdictions.
The exchange said the wind-down will begin on Sep. 15, with services being withdrawn in stages before the platform closes completely on Dec. 22.
Related: Coinbase CEO doubles down on bullish Bitcoin target
CoinEx will immediately stop new user registrations, referral commissions and several new product subscriptions. Futures markets are moving into reduce-only mode, while no new orders will be accepted for margin trading, loans, staking, earn products and several other services.
All non-spot services are scheduled to end on Sep. 22. On-chain deposits will also close that day, with the exception of deposits in CoinEx Token, or CET, which will remain available until Sep. 29.
#Services #exchange #trading
The exchange said the wind-down will begin on Sep. 15, with services being withdrawn in stages before the platform closes completely on Dec. 22.
Related: Coinbase CEO doubles down on bullish Bitcoin target
CoinEx will immediately stop new user registrations, referral commissions and several new product subscriptions. Futures markets are moving into reduce-only mode, while no new orders will be accepted for margin trading, loans, staking, earn products and several other services.
All non-spot services are scheduled to end on Sep. 22. On-chain deposits will also close that day, with the exception of deposits in CoinEx Token, or CET, which will remain available until Sep. 29.
#Services #exchange #trading
2 months ago
Something strange is currently happening with interest rates and inflation.
The United States Federal Funds Rate -- essentially the price banks charge each other to borrow money overnight -- currently sits at 3.75%. The rate has remained at 3.75% throughout 2026.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
For much of 2023 and 2024, the Fed Funds Rate was pegged at 5.5% to battle stubbornly high inflation. As inflation fears eased, the rate was gradually lowered to today's 3.75% level.
Despite a low and stable Fed Funds Rate, however, mortgage interest rates have begun to climb. According to the Wall Street Journal, average U.S. mortgage rates have climbed to a 15-month high of nearly 7%. Treasury yields, meanwhile, are approaching multi-year highs.
#NVIDIA #high
The United States Federal Funds Rate -- essentially the price banks charge each other to borrow money overnight -- currently sits at 3.75%. The rate has remained at 3.75% throughout 2026.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
For much of 2023 and 2024, the Fed Funds Rate was pegged at 5.5% to battle stubbornly high inflation. As inflation fears eased, the rate was gradually lowered to today's 3.75% level.
Despite a low and stable Fed Funds Rate, however, mortgage interest rates have begun to climb. According to the Wall Street Journal, average U.S. mortgage rates have climbed to a 15-month high of nearly 7%. Treasury yields, meanwhile, are approaching multi-year highs.
#NVIDIA #high

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
When your income is limited, scaling back your budget can only get you so far. The good news: Cutting back on spending isn't the only way to improve your finances. You can potentially make big changes by finding a new source of income.
With the right side gig, putting in just a few extra hours of work per week could be enough to help you cover major bills and build up your savings. Follow these tips to ensure your venture is successful.
Finding the right side gig is a bit of an art. You'll need to figure out when you have free time, which skills people are willing to pay you for, and how much money you can realistically make once all of your personal expenses are covered. Here's what you should consider:
There are plenty of websites where you can list your services for hire, such as Lyft, Task Rabbit, and Fiverr, but they don't always pay well. According to a study from Human Rights Watch, people who used gig work platforms earned less than minimum wage after covering all of their work-related expenses.
#only #right
When your income is limited, scaling back your budget can only get you so far. The good news: Cutting back on spending isn't the only way to improve your finances. You can potentially make big changes by finding a new source of income.
With the right side gig, putting in just a few extra hours of work per week could be enough to help you cover major bills and build up your savings. Follow these tips to ensure your venture is successful.
Finding the right side gig is a bit of an art. You'll need to figure out when you have free time, which skills people are willing to pay you for, and how much money you can realistically make once all of your personal expenses are covered. Here's what you should consider:
There are plenty of websites where you can list your services for hire, such as Lyft, Task Rabbit, and Fiverr, but they don't always pay well. According to a study from Human Rights Watch, people who used gig work platforms earned less than minimum wage after covering all of their work-related expenses.
#only #right


2 months ago
The Dow Jones Industrial Average (DJINDICES:^DJI) gained 0.56% to 53,062, the S&P 500 (SNPINDEX:^GSPC) rose 0.47% to 7,667, and the Nasdaq Composite (NASDAQINDEX:^IXIC) added 0.45% to 26,218, as the major indexes snapped multi-day losing streaks despite persistent geopolitical tensions.
Dell Technologies (NYSE:DELL) shares surged after the hardware giant lifted its annual revenue forecast, while Nvidia (NASDAQ:NVDA) helped lead the technology recovery.
Investors also monitored Snowflake (NYSE:SNOW) and Broadcom (NASDAQ:AVGO) as the technology firms prepared to report quarterly results after hours, following a significant year-to-date rally.
Perhaps the biggest news item today in the stock market came from Dell Technologies, which rose 16% after reporting blowout earnings. Sales and adjusted EPS rose 58% and 203% in the quarter, while its AI-Optimized Server business doubled its revenue. Most importantly, the AI unit recorded $61 billion in orders, bringing its backlog to over $95 billion and underscoring the company's growing importance in the AI **** e.
On the other hand, cybersecurity juggernaut Palo Alto Networks (NASDAQ:PANW) dropped 9% today after reporting fine (but not perfect) earnings. This decline is likely nothing for interested or current shareholders to worry about, as PANW stock was trading close to perfection after more than doubling over the last six months.
#PANW #Stock
Dell Technologies (NYSE:DELL) shares surged after the hardware giant lifted its annual revenue forecast, while Nvidia (NASDAQ:NVDA) helped lead the technology recovery.
Investors also monitored Snowflake (NYSE:SNOW) and Broadcom (NASDAQ:AVGO) as the technology firms prepared to report quarterly results after hours, following a significant year-to-date rally.
Perhaps the biggest news item today in the stock market came from Dell Technologies, which rose 16% after reporting blowout earnings. Sales and adjusted EPS rose 58% and 203% in the quarter, while its AI-Optimized Server business doubled its revenue. Most importantly, the AI unit recorded $61 billion in orders, bringing its backlog to over $95 billion and underscoring the company's growing importance in the AI **** e.
On the other hand, cybersecurity juggernaut Palo Alto Networks (NASDAQ:PANW) dropped 9% today after reporting fine (but not perfect) earnings. This decline is likely nothing for interested or current shareholders to worry about, as PANW stock was trading close to perfection after more than doubling over the last six months.
#PANW #Stock
2 months ago
PetroChina reported record first-half operating results for 2026, with profit attributable to shareholders rising 22% year over year to RMB103.94 billion as the Chinese energy giant expanded across natural gas, new materials and lower-carbon businesses.
Revenue increased 5.3% to RMB1.527 trillion, while basic earnings per share reached RMB0.57. PetroChina said it was the first time its attributable profit had exceeded RMB100 billion in a half-year period.
The company's oil, gas and new energies business remained its biggest earnings contributor, generating RMB100.45 billion in operating profit during the first half.
PetroChina reported oil and gas equivalent production of 921 million barrels, domestic crude production of 393 million barrels and marketable natural gas production of 2.66 trillion cubic feet.
The company said it made six new discoveries and advanced 19 new developments during the period. It also established two large gas reserve areas in the Sichuan and Junggar basins and a major deep conventional oil reserve area at Tarim Fuman.
#petrochina #first #production #rmb100
Revenue increased 5.3% to RMB1.527 trillion, while basic earnings per share reached RMB0.57. PetroChina said it was the first time its attributable profit had exceeded RMB100 billion in a half-year period.
The company's oil, gas and new energies business remained its biggest earnings contributor, generating RMB100.45 billion in operating profit during the first half.
PetroChina reported oil and gas equivalent production of 921 million barrels, domestic crude production of 393 million barrels and marketable natural gas production of 2.66 trillion cubic feet.
The company said it made six new discoveries and advanced 19 new developments during the period. It also established two large gas reserve areas in the Sichuan and Junggar basins and a major deep conventional oil reserve area at Tarim Fuman.
#petrochina #first #production #rmb100

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
When you're planning a vacation, you probably aren't thinking about worst-case medical scenarios. Travel insurance, if it comes up at all, is often viewed as a way to protect against a canceled flight or lost baggage.
But a serious medical emergency abroad can wreak havoc on your finances. The U.S. Centers for Disease Control and Prevention estimates an international air ambulance can cost $30,000 to $250,000.
Emergency medical evacuation insurance is designed to protect against that risk. Here's everything you need to know about how this benefit works, what it pays for, and how to choose a plan that actually meets your needs.
Emergency medical evacuation insurance, sometimes called medevac coverage, helps pay for and coordinate transportation if you become seriously ill or injured during a trip.
#emergency #travel
When you're planning a vacation, you probably aren't thinking about worst-case medical scenarios. Travel insurance, if it comes up at all, is often viewed as a way to protect against a canceled flight or lost baggage.
But a serious medical emergency abroad can wreak havoc on your finances. The U.S. Centers for Disease Control and Prevention estimates an international air ambulance can cost $30,000 to $250,000.
Emergency medical evacuation insurance is designed to protect against that risk. Here's everything you need to know about how this benefit works, what it pays for, and how to choose a plan that actually meets your needs.
Emergency medical evacuation insurance, sometimes called medevac coverage, helps pay for and coordinate transportation if you become seriously ill or injured during a trip.
#emergency #travel


2 months ago
Aoris Investment Management, a specialist international equity manager, released its Q2 2026 investor letter for "Aoris International Fund". A copy of the letter can be downloaded here. The fund invests in high-quality, wealth-generating businesses managed by prudent and capable teams, targeting an annual return of 8–12% after fees over a 5–7-year market cycle. During the June quarter, international equity markets, as represented by the MSCI AC World Accumulation Index ex Australia, returned 13.8% in AUD terms. In local currencies, the return 15.1%. The Portfolio's Class A (Unhedged) returned 5.7% after fees, underperforming its benchmark by 8.1%, while the Class C (Hedged) gained 6.7%, 8.4% less than its benchmark. The June quarter continued to reflect an unusual year, marked by significant share price increases among AI infrastructure companies, particularly semiconductor producers and data center suppliers. Economic sectors like banks and commodity producers saw gains, but the firm chose not to invest due to their cyclicality and low growth prospects. Conversely, concerns about enterprise software and data companies, challenged by AI, negatively impacted performance. The letter outlined potential incremental opportunities for portfolio companies through AI. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Aoris Investment Management highlighted RELX PLC (NYSE:RELX). RELX PLC (NYSE:RELX) is a British-based information ****** ytics and decision solutions provider for professional and business customers. On August 21, 2026, RELX PLC (NYSE:RELX) stock closed at $35.91 per share. One-month return of RELX PLC (NYSE:RELX) was 0.73%, and its shares lost 24.86% over the past 52 weeks. RELX PLC (NYSE:RELX) has a market capitalization of $62.03 billion.
Aoris Investment Management stated the following regarding RELX PLC (NYSE:RELX) in its Q2 2026 investor letter:
"RELX PLC (NYSE:RELX) provides data, ****** ytics and decision-making tools for professional users in the science, academia, legal, risk and insurance industries. One-third of its revenue comes from scientific content and research tools, one-third comes from risk management solutions like identity verification and anti-money laundering, 20% comes from content and tools for the legal industry, and 10% comes from running trade exhibitions.
RELX owns and curates large bodies of proprietary and authoritative content, which has become more valuable as the internet is largely exhausted as a training resource for AI models. Legal work is especially well-suited to generative AI because it's language-intensive, but also an area where accuracy matters. RELX's AI products help lawyers research, draft and conduct due diligence faster, while remaining anchored to trusted legal content. Just two and a half years after launch, around half of its legal customers have subscribed to its premium AI offering. AI is also making frau
In its Q2 2026 investor letter, Aoris Investment Management highlighted RELX PLC (NYSE:RELX). RELX PLC (NYSE:RELX) is a British-based information ****** ytics and decision solutions provider for professional and business customers. On August 21, 2026, RELX PLC (NYSE:RELX) stock closed at $35.91 per share. One-month return of RELX PLC (NYSE:RELX) was 0.73%, and its shares lost 24.86% over the past 52 weeks. RELX PLC (NYSE:RELX) has a market capitalization of $62.03 billion.
Aoris Investment Management stated the following regarding RELX PLC (NYSE:RELX) in its Q2 2026 investor letter:
"RELX PLC (NYSE:RELX) provides data, ****** ytics and decision-making tools for professional users in the science, academia, legal, risk and insurance industries. One-third of its revenue comes from scientific content and research tools, one-third comes from risk management solutions like identity verification and anti-money laundering, 20% comes from content and tools for the legal industry, and 10% comes from running trade exhibitions.
RELX owns and curates large bodies of proprietary and authoritative content, which has become more valuable as the internet is largely exhausted as a training resource for AI models. Legal work is especially well-suited to generative AI because it's language-intensive, but also an area where accuracy matters. RELX's AI products help lawyers research, draft and conduct due diligence faster, while remaining anchored to trusted legal content. Just two and a half years after launch, around half of its legal customers have subscribed to its premium AI offering. AI is also making frau

2 months ago
On the hottest of summer days, a natural gas "peaker" usually kicks in to support the wave of air conditioning units turning on at once. It's the electrical grid's lifesaver, a turbine built only for the highest-demand hours of the year, and also one of the most expensive to run. It's what made 7 p.m. electricity so expensive in different parts of the U.S in the first place.
But a shift is taking place. California and Texas are now turning to batteries to power their grids. Power units that were typically used simply to store energy are now being deployed as power sources themselves. California's grid operator has at least 13,000 megawatts of battery capacity, enough to serve several million homes through evening peak hours, and Texas' batteries already power up to 10% of the state's grid at peak.
Electricity customers see the benefits. When batteries set the marginal price instead of gas turbines that cost two to three times as much to run, wholesale power gets cheaper during the hours it used to be most expensive. Gas peakers that already sat idle for more than 86% of the year will eventually lose the few remaining hours that kept them viable, and utilities will likely choose batteries over new gas plants long term.
Unlike gas turbines, batteries don't generate electricity on their own. They move it from the hours when it's cheapest to the hours when it's most valuable. Solar panels flood the grid with power in the middle of the day, pushing wholesale prices close to zero and sometimes below it. Batteries absorb that cheap surplus. When the sun sets and demand surges past what the remaining generation can deliver, they discharge into the gap that gas peakers once filled, offering to do it at a lower price.
In California, the cycle has run at a scale large enough to reshape the wholesale market. In 2024, across the California Independent System Operator's territory, batteries provided an average of 8.6% of all electricity consumed during the highest-demand evening hours, keeping the lights on in roughly three million homes. By 2025, they were regularly delivering more than 6,000 megawatts at peak, six times the roughly 1,000 megawatts they managed three years earlier.
#hours #electricity
But a shift is taking place. California and Texas are now turning to batteries to power their grids. Power units that were typically used simply to store energy are now being deployed as power sources themselves. California's grid operator has at least 13,000 megawatts of battery capacity, enough to serve several million homes through evening peak hours, and Texas' batteries already power up to 10% of the state's grid at peak.
Electricity customers see the benefits. When batteries set the marginal price instead of gas turbines that cost two to three times as much to run, wholesale power gets cheaper during the hours it used to be most expensive. Gas peakers that already sat idle for more than 86% of the year will eventually lose the few remaining hours that kept them viable, and utilities will likely choose batteries over new gas plants long term.
Unlike gas turbines, batteries don't generate electricity on their own. They move it from the hours when it's cheapest to the hours when it's most valuable. Solar panels flood the grid with power in the middle of the day, pushing wholesale prices close to zero and sometimes below it. Batteries absorb that cheap surplus. When the sun sets and demand surges past what the remaining generation can deliver, they discharge into the gap that gas peakers once filled, offering to do it at a lower price.
In California, the cycle has run at a scale large enough to reshape the wholesale market. In 2024, across the California Independent System Operator's territory, batteries provided an average of 8.6% of all electricity consumed during the highest-demand evening hours, keeping the lights on in roughly three million homes. By 2025, they were regularly delivering more than 6,000 megawatts at peak, six times the roughly 1,000 megawatts they managed three years earlier.
#hours #electricity

3 months ago
On August 4, Tenable Holdings (NASDAQ:TENB) announced that it now covers every major AI platform and developer tool through its Tenable One platform, adding Google Gemini to a list that already included Anthropic Claude, OpenAI's ChatGPT Enterprise, and Microsoft Copilot. It is a bet that as companies rush to adopt AI, someone needs to watch where the risk is hiding, and Tenable wants to be the company holding that flashlight.
The scale of the problem Tenable is chasing is hard to ignore. The company said it detected 457 million AI-related security issues across more than 7,000 organizations, averaging 62,000 exposures per organization over 30 days. That is the kind of number that makes the case for exposure management on its own. Tenable One AI Exposure now extends discovery to every major LLM, all major Model Context Protocol deployments, and AI-native development tools like Cursor, Windsurf, and Trae, roughly doubling its coverage of sanctioned and shadow AI in one release. Beyond just finding the exposures, the platform lets security teams act on them directly, creating tickets in Jira or ServiceNow (NYSE:NOW), or firing off alerts through email, Slack, or Teams. That combination of visibility and Tenable's Hexa AI engine, which automates remediation tasks, is what the company is positioning as a full loop rather than another dashboard ******* ody checks.
The business results back up the demand story. Tenable One made up half of the company's new sales in the second quarter, evidence that customers are consolidating onto the full platform instead of buying individual point tools. Second-quarter revenue came in at $268.5 million, ahead of management's guided range of $263 million to $266 million, while operating expenses fell to $195.8 million from $200.3 million a year earlier. That combination flipped a $14.7 million net loss into a $3.8 million net profit, and adjusted profit jumped 40% to $57.9 million. The stock is up more than 40% in 2026 on the back of that improvement, yet Tenable's market capitalization of $3.6 billion is still a fraction of CrowdStrike Holdings (NASDAQ:CRWD) and Palo Alto Networks (NASDAQ:PANW), whose combined market cap tops $450 billion.
That gap shows up in valuation too. Tenable trades at a price-to-sales ratio of 3.7, well below its own historical average of 7.1 since going public in 2018, and far cheaper than Palo Alto Networks at 22.9 times sales or CrowdStrike at 38.1 times. But cheap multiples usually come with a reason attached. Tenable's revenue grew 8.6% year over year in the quarter, modest next to CrowdStrike's annual recurring revenue growth of 24% to $5.5 billion. Some of Tenable's profit turnaround came from cutting costs, including in growth-oriented areas like marketing, rather than from accelerating sales. That is a reasonable way to prove discipline, but it raises the question of whether faster growth is coming or whether the company is simply managing a slower-growth business more efficiently
The scale of the problem Tenable is chasing is hard to ignore. The company said it detected 457 million AI-related security issues across more than 7,000 organizations, averaging 62,000 exposures per organization over 30 days. That is the kind of number that makes the case for exposure management on its own. Tenable One AI Exposure now extends discovery to every major LLM, all major Model Context Protocol deployments, and AI-native development tools like Cursor, Windsurf, and Trae, roughly doubling its coverage of sanctioned and shadow AI in one release. Beyond just finding the exposures, the platform lets security teams act on them directly, creating tickets in Jira or ServiceNow (NYSE:NOW), or firing off alerts through email, Slack, or Teams. That combination of visibility and Tenable's Hexa AI engine, which automates remediation tasks, is what the company is positioning as a full loop rather than another dashboard ******* ody checks.
The business results back up the demand story. Tenable One made up half of the company's new sales in the second quarter, evidence that customers are consolidating onto the full platform instead of buying individual point tools. Second-quarter revenue came in at $268.5 million, ahead of management's guided range of $263 million to $266 million, while operating expenses fell to $195.8 million from $200.3 million a year earlier. That combination flipped a $14.7 million net loss into a $3.8 million net profit, and adjusted profit jumped 40% to $57.9 million. The stock is up more than 40% in 2026 on the back of that improvement, yet Tenable's market capitalization of $3.6 billion is still a fraction of CrowdStrike Holdings (NASDAQ:CRWD) and Palo Alto Networks (NASDAQ:PANW), whose combined market cap tops $450 billion.
That gap shows up in valuation too. Tenable trades at a price-to-sales ratio of 3.7, well below its own historical average of 7.1 since going public in 2018, and far cheaper than Palo Alto Networks at 22.9 times sales or CrowdStrike at 38.1 times. But cheap multiples usually come with a reason attached. Tenable's revenue grew 8.6% year over year in the quarter, modest next to CrowdStrike's annual recurring revenue growth of 24% to $5.5 billion. Some of Tenable's profit turnaround came from cutting costs, including in growth-oriented areas like marketing, rather than from accelerating sales. That is a reasonable way to prove discipline, but it raises the question of whether faster growth is coming or whether the company is simply managing a slower-growth business more efficiently

3 months ago
Shell is set to invest in the next phase of Arrow Energy's Surat Gas Project in Queensland, Australia, to secure ongoing gas supply for both domestic customers and its Queensland Curtis liquefied natural gas (QCLNG) export terminal.
Arrow Energy is an incorporated joint venture (JV) equally owned by Shell and PetroChina.
Shell confirmed that production from the new phase, known as Surat Gas Project Central, is expected to begin in 2028.
The development comprises 143 backfill wells, designed to deliver around 79 million standard cubic feet, or approximately 84 terajoules, of gas per day at peak output.
Gas will be supplied to the Australian domestic market as well as international liquefied natural gas (LNG) clients through the QCLNG facility, operated by Shell on Curtis Island near Gladstone.
#project #qclng #domestic
Arrow Energy is an incorporated joint venture (JV) equally owned by Shell and PetroChina.
Shell confirmed that production from the new phase, known as Surat Gas Project Central, is expected to begin in 2028.
The development comprises 143 backfill wells, designed to deliver around 79 million standard cubic feet, or approximately 84 terajoules, of gas per day at peak output.
Gas will be supplied to the Australian domestic market as well as international liquefied natural gas (LNG) clients through the QCLNG facility, operated by Shell on Curtis Island near Gladstone.
#project #qclng #domestic

3 months ago
Greenskeeper **** et Management, an independent firm that specializes in disciplined value investing, recently released its Q2 2026 scorecard. A copy is available to download here. After a slow start to the year, the Fund gained 10.9% in the quarter, lifting its year-to-date return to 1.9%. The rebound came as markets showed signs of rotating away from momentum stocks and toward companies supported by reasonable valuations. Please review the Fund's top five holdings to gain insights into their key selections for 2026.
In its second-quarter 2026 investor letter, Greenskeeper **** et Management highlighted Lockheed Martin Corporation (NYSE:LMT). Lockheed Martin Corporation (NYSE:LMT) is an aerospace and defense company that engages in the research, design, development, manufacture, integration, and sustainment of technology systems, products, and services. On August 03, 2026, Lockheed Martin Corporation (NYSE:LMT) closed at $586.29 per share. The one-month return of Lockheed Martin Corporation (NYSE:LMT) was 9.51%, and its shares gained 36.91% over the past 52 weeks. Lockheed Martin Corporation (NYSE:LMT) has a market capitalization of $135.32 billion.
Greenskeeper **** et Management stated the following regarding Lockheed Martin Corporation (NYSE:LMT) in its Q2 2026 investor letter:
"Lockheed Martin Corporation (NYSE:LMT) was our second-largest detractor during the quarter, declining 15.7%. The sell-off was primarily driven by execution challenges within its Aeronautics division, which delayed aircraft deliveries and required additional rework on certain fixed-price contracts. These issues weighed on near-term profitability and raised concerns about the company's ability to meet its production targets.
We view these operational headwinds as temporary. Global demand for defence capabilities remains exceptionally strong as governments replenish depleted inventories and navigate an increasingly complex geopolitical backdrop. Anchored by leading positions across critical defence programs, Lockheed Martin remains well-positioned to drive long-term cash generation as execution normalizes and order backlogs convert into deliveries."
#gained
In its second-quarter 2026 investor letter, Greenskeeper **** et Management highlighted Lockheed Martin Corporation (NYSE:LMT). Lockheed Martin Corporation (NYSE:LMT) is an aerospace and defense company that engages in the research, design, development, manufacture, integration, and sustainment of technology systems, products, and services. On August 03, 2026, Lockheed Martin Corporation (NYSE:LMT) closed at $586.29 per share. The one-month return of Lockheed Martin Corporation (NYSE:LMT) was 9.51%, and its shares gained 36.91% over the past 52 weeks. Lockheed Martin Corporation (NYSE:LMT) has a market capitalization of $135.32 billion.
Greenskeeper **** et Management stated the following regarding Lockheed Martin Corporation (NYSE:LMT) in its Q2 2026 investor letter:
"Lockheed Martin Corporation (NYSE:LMT) was our second-largest detractor during the quarter, declining 15.7%. The sell-off was primarily driven by execution challenges within its Aeronautics division, which delayed aircraft deliveries and required additional rework on certain fixed-price contracts. These issues weighed on near-term profitability and raised concerns about the company's ability to meet its production targets.
We view these operational headwinds as temporary. Global demand for defence capabilities remains exceptionally strong as governments replenish depleted inventories and navigate an increasingly complex geopolitical backdrop. Anchored by leading positions across critical defence programs, Lockheed Martin remains well-positioned to drive long-term cash generation as execution normalizes and order backlogs convert into deliveries."
#gained

3 months ago
US stocks steadied on Wednesday after a searing rally as oil declined for the third day in a row amid growing hopes that the Strait of Hormuz could soon reopen.
Futures on the tech-heavy Nasdaq-100 (NQ=F) were little changed in premarket trading. Futures for the S&P 500 (ES=F) and Dow Jones Industrial Average (YM=F) both gained slightly after the indexes closed at record highs.
A rise in Asian markets overnight pointed toward a strong open as global markets cheered diplomatic efforts for another peace deal between the US and Iran — no matter how fragile. South Korea's KOSPI (^KS11) index led gains, rising 4%.
On Tuesday, Qatar said a proposal had been drafted between the US and Iran to reopen the Strait of Hormuz, a critical waterway for a fifth of the world's oil. Iran is also reportedly considering allowing European countries to remove mines from the strait, adding to confidence that shipping traffic in the region could normalize.
Oil prices fell in premarket trading on the news, with the global benchmark Brent crude (BZ=F) declining 1% to $78 per barrel, while WTI crude oil futures (CL=F), the US benchmark, fell below $75 per barrel.
#reopen #premarket #global
Futures on the tech-heavy Nasdaq-100 (NQ=F) were little changed in premarket trading. Futures for the S&P 500 (ES=F) and Dow Jones Industrial Average (YM=F) both gained slightly after the indexes closed at record highs.
A rise in Asian markets overnight pointed toward a strong open as global markets cheered diplomatic efforts for another peace deal between the US and Iran — no matter how fragile. South Korea's KOSPI (^KS11) index led gains, rising 4%.
On Tuesday, Qatar said a proposal had been drafted between the US and Iran to reopen the Strait of Hormuz, a critical waterway for a fifth of the world's oil. Iran is also reportedly considering allowing European countries to remove mines from the strait, adding to confidence that shipping traffic in the region could normalize.
Oil prices fell in premarket trading on the news, with the global benchmark Brent crude (BZ=F) declining 1% to $78 per barrel, while WTI crude oil futures (CL=F), the US benchmark, fell below $75 per barrel.
#reopen #premarket #global

3 months ago
Microsoft (MSFT) just reported the quarter investors wanted to see. While investors punished Meta (META) for its disappointing Q2, they celebrated Microsoft's results. MSFT stock closed 15.51% higher Thursday, even though it is down 4% year-to-date (YTD). Microsoft delivered accelerating AI demand, exceptional financial strength despite high spending, and growing evidence that its massive AI investments are already translating into higher profits.
Here are the three biggest reasons investors rushed to buy MSFT stock.
Cathie Wood Doubles Down on Tesla and **** eX as Wall Street Turns Cautious
Why BlackRock Is Betting Big on Ondas Stock Now
Hoping for Lower Prices at the Gas Pump? After Exxon Doubles Profits, CEO Darren Woods Says 'I Wouldn't Hold My Breath.'
#thursday
Here are the three biggest reasons investors rushed to buy MSFT stock.
Cathie Wood Doubles Down on Tesla and **** eX as Wall Street Turns Cautious
Why BlackRock Is Betting Big on Ondas Stock Now
Hoping for Lower Prices at the Gas Pump? After Exxon Doubles Profits, CEO Darren Woods Says 'I Wouldn't Hold My Breath.'
#thursday


3 months ago
LVS Advisory, a New York City-based full-service investment firm, recently released its second-quarter 2026 investor letter. A copy of the letter can be downloaded here. In the first half of 2026, the LVS Event-Driven Portfolio appreciated 4.6% (net), and the LVS Levered Event-Driven Portfolio gained 6.5% (net) while the LVS Growth Portfolio declined 4.2% (net). The first two portfolios outperformed, while the latter lagged. However, the firm believes that all three strategies are poised for improved performance. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, LVS Advisory highlighted Vistance Networks, Inc. (NASDAQ:VISN). Vistance Networks, Inc. (NASDAQ:VISN) is a global provider of infrastructure solutions for communications, data center, and entertainment networks. On July 27, 2026, Vistance Networks, Inc. (NASDAQ:VISN) closed at $11.85 per share, reflecting a market capitalization of $2.67 billion. Vistance Networks, Inc. (NASDAQ:VISN) posted a one-month return of -7.95%, while its shares gained 38.79% over the past 52 weeks.
LVS Advisory stated the following regarding Vistance Networks, Inc. (NASDAQ:VISN) in its Q2 2026 investor update:
"Vistance Networks, Inc. (NASDAQ:VISN) is a busted roll-up in the telecom infrastructure industry. Formerly known as CommScope, the company sold cables, wires, fiber equipment, and wireless networking systems to data centers, internet service providers, and corporate campuses.
For years, the company employed an aggressive acquisition strategy to roll up the legacy cable and copper wire industry in an effort to become the leading end-to-end provider of wired and wireless communications. Vistance took on an enormous amount of debt to complete the $3 billion acquisition of BNS from TE Connectivity in 2015 and later the $7 billion acquisition of Arris in 2019. At its peak, the company had accumulated a total of $10.5 billion of debt with a net leverage ratio of 7.1x. The debt load became unsustainable, and the stock collapsed from The board ran a sale process in 2025 in a last-ditch effort to save the company from bankruptcy. This resulted in a series of **** et sales that paid down debt and returned capital to shareholders…" (Click here to read the full text)
#NASDAQ #billion #company
In its Q2 2026 investor letter, LVS Advisory highlighted Vistance Networks, Inc. (NASDAQ:VISN). Vistance Networks, Inc. (NASDAQ:VISN) is a global provider of infrastructure solutions for communications, data center, and entertainment networks. On July 27, 2026, Vistance Networks, Inc. (NASDAQ:VISN) closed at $11.85 per share, reflecting a market capitalization of $2.67 billion. Vistance Networks, Inc. (NASDAQ:VISN) posted a one-month return of -7.95%, while its shares gained 38.79% over the past 52 weeks.
LVS Advisory stated the following regarding Vistance Networks, Inc. (NASDAQ:VISN) in its Q2 2026 investor update:
"Vistance Networks, Inc. (NASDAQ:VISN) is a busted roll-up in the telecom infrastructure industry. Formerly known as CommScope, the company sold cables, wires, fiber equipment, and wireless networking systems to data centers, internet service providers, and corporate campuses.
For years, the company employed an aggressive acquisition strategy to roll up the legacy cable and copper wire industry in an effort to become the leading end-to-end provider of wired and wireless communications. Vistance took on an enormous amount of debt to complete the $3 billion acquisition of BNS from TE Connectivity in 2015 and later the $7 billion acquisition of Arris in 2019. At its peak, the company had accumulated a total of $10.5 billion of debt with a net leverage ratio of 7.1x. The debt load became unsustainable, and the stock collapsed from The board ran a sale process in 2025 in a last-ditch effort to save the company from bankruptcy. This resulted in a series of **** et sales that paid down debt and returned capital to shareholders…" (Click here to read the full text)
#NASDAQ #billion #company
3 months ago
Reddit reports second-quarter earnings on July 30. Heading into the print, the stock is down about 27% year to date, and most of that damage came from one story. The Wall Street Journal recently reported that Reddit had internally discussed restricting Google's access to its platform content for AI training, as renewal talks over their data-licensing deal hit friction. The stock dropped roughly 9% that day.
Reddit and Google signed a $60 million-a-year licensing agreement in 2024, letting Google train its AI models on Reddit's content. That's under 2% of Reddit's trailing revenue.
But investors reacted as if the number mattered less than the signal. If Reddit is willing to walk away from a live AI licensing partner, that raises questions about how durable the rest of Reddit's data business really is, and whether Google's AI-powered search results are already cutting into the referral traffic Reddit depends on. Let's break down the case.
The Growth Story Hasn't Slowed
Reddit hasn't missed an **** yst estimate since going public in 2024. Revenue growth has actually sped up: 61% year-over-year in the first quarter of 2025, then 69% in the most recent quarter. Diluted EPS rose 7x during this period. Free cash flow rose 145% year-over-year in the first quarter.
#year #Growth #hasn 't #Stock
Reddit and Google signed a $60 million-a-year licensing agreement in 2024, letting Google train its AI models on Reddit's content. That's under 2% of Reddit's trailing revenue.
But investors reacted as if the number mattered less than the signal. If Reddit is willing to walk away from a live AI licensing partner, that raises questions about how durable the rest of Reddit's data business really is, and whether Google's AI-powered search results are already cutting into the referral traffic Reddit depends on. Let's break down the case.
The Growth Story Hasn't Slowed
Reddit hasn't missed an **** yst estimate since going public in 2024. Revenue growth has actually sped up: 61% year-over-year in the first quarter of 2025, then 69% in the most recent quarter. Diluted EPS rose 7x during this period. Free cash flow rose 145% year-over-year in the first quarter.
#year #Growth #hasn 't #Stock





