

10 days ago
Three months after revealing plans that it would seek a jersey patch sponsorship, Wright State University announced a deal with Premier Health on Thursday, Oct. 29.
"Premier Health has stood alongside Wright State Athletics for years and this partnership is a profound statement of what that relationship means," said Wright State Athletics Director Brad Chandler in a press release. "All 14 Division I programs will now carry Premier Health on its uniform, connecting our student-athletes with the academic health system that cares for the families in our stands and across our community. We worked hard to bring the first jersey patch sponsorship in the Dayton region to life, and we're proud that it's with a partner that has always shown up for Wright State. This is about more than visibility. It's two Dayton institutions putting their names side by side and investing in the next generation."
The NCAA approved the use of jersey patches in January.
According to an NCAA press release, "Effective Aug. 1, all Division I teams will be permitted up to two additional commercial logos on their uniforms and apparel and one additional commercial logo on equipment during the preseason and regular season, with an additional commercial logo on uniforms and apparel for conference championships. The patches will be limited to a maximum of 4 square inches per logo."
The patches will debut on Monday, Nov. 2, when the Wright State men's basketball team plays Air Force in the Stars, Stripes and Flight Classic at the Nutter Center.
#wright #state #premier #patches
"Premier Health has stood alongside Wright State Athletics for years and this partnership is a profound statement of what that relationship means," said Wright State Athletics Director Brad Chandler in a press release. "All 14 Division I programs will now carry Premier Health on its uniform, connecting our student-athletes with the academic health system that cares for the families in our stands and across our community. We worked hard to bring the first jersey patch sponsorship in the Dayton region to life, and we're proud that it's with a partner that has always shown up for Wright State. This is about more than visibility. It's two Dayton institutions putting their names side by side and investing in the next generation."
The NCAA approved the use of jersey patches in January.
According to an NCAA press release, "Effective Aug. 1, all Division I teams will be permitted up to two additional commercial logos on their uniforms and apparel and one additional commercial logo on equipment during the preseason and regular season, with an additional commercial logo on uniforms and apparel for conference championships. The patches will be limited to a maximum of 4 square inches per logo."
The patches will debut on Monday, Nov. 2, when the Wright State men's basketball team plays Air Force in the Stars, Stripes and Flight Classic at the Nutter Center.
#wright #state #premier #patches


2 months ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

2 months ago
On September 8, 2026, Reuters reported that ASML Holding N.V. (NASDAQ:ASML) plans to work with major customers. It includes Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM), Nvidia, Intel, Samsung, and SK Hynix to adapt its next-generation "High NA" extreme ultraviolet lithography tools so they can print larger data-center chips. It addresses a current limitation where the newer machines use a smaller mask than ASML's widely deployed standard EUV tools.
ASML targets a pilot production line using the larger masks by 2031 and high-volume manufacturing readiness by 2033. Chief technology officer Marco Pieters said these changes could lift the productivity of these systems by roughly 40%.
The larger-mask project could create a new growth opportunity for ASML Holding N.V. (NASDAQ:ASML) while helping TSMC manufacture larger AI chips more efficiently. ASML plans to use its High NA EUV tools to handle chips as large as today's biggest data-center processors. The business expects the larger masks to increase system productivity by 40%. It could scale up demand for its next-generation equipment and help TSMC improve the economics of producing increasingly large and complex chips.
Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM)'s planned use gives ASML a clear path toward commercializing the technology. TSMC plans to introduce High NA EUV into advanced-node high-volume production from 2030. ASML aims to show its larger-mask technology through a pilot line in 2031. TSMC's commitment could give ASML greater visibility into future equipment demand. Early use could help TSMC maintain its advanced-chip manufacturing advantage.
The collaboration could solidify both companies' positions as chipmakers develop larger and more powerful processors. ASML can extend its High NA roadmap beyond its current chip-size limitation. TSMC can prepare its manufacturing processes for the next generation of AI chips. The partnership gives ASML an opportunity to deepen its relationship with one of its largest customers and gives TSMC access to a technology that could support future advanced-chip production.
#asml #technology #plans #next
ASML targets a pilot production line using the larger masks by 2031 and high-volume manufacturing readiness by 2033. Chief technology officer Marco Pieters said these changes could lift the productivity of these systems by roughly 40%.
The larger-mask project could create a new growth opportunity for ASML Holding N.V. (NASDAQ:ASML) while helping TSMC manufacture larger AI chips more efficiently. ASML plans to use its High NA EUV tools to handle chips as large as today's biggest data-center processors. The business expects the larger masks to increase system productivity by 40%. It could scale up demand for its next-generation equipment and help TSMC improve the economics of producing increasingly large and complex chips.
Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM)'s planned use gives ASML a clear path toward commercializing the technology. TSMC plans to introduce High NA EUV into advanced-node high-volume production from 2030. ASML aims to show its larger-mask technology through a pilot line in 2031. TSMC's commitment could give ASML greater visibility into future equipment demand. Early use could help TSMC maintain its advanced-chip manufacturing advantage.
The collaboration could solidify both companies' positions as chipmakers develop larger and more powerful processors. ASML can extend its High NA roadmap beyond its current chip-size limitation. TSMC can prepare its manufacturing processes for the next generation of AI chips. The partnership gives ASML an opportunity to deepen its relationship with one of its largest customers and gives TSMC access to a technology that could support future advanced-chip production.
#asml #technology #plans #next


2 months ago
On September 17, B. Riley initiated coverage of Nokia Oyj (NYSE:NOK), giving the stock a Buy rating and setting the price target at $15. The firm pointed to the company's position in telecom infrastructure, cloud software, and hardware networking solutions.
Riley noted that the company's networking businesses are seeing strong growth. In Q2 2026, Optical Networks revenue increased 20% year-over-year, while IP Networks grew 16%. Net sales to AI and cloud customers also surged 105%. The research firm noted that hyperscalers continue to purchase Nokia Oyj's (NYSE:NOK) AI networking products to support large-scale computing clusters.
The company's AI and cloud opportunity is also reflected in its order book. Nokia Oyj (NYSE:NOK) reported EUR 2.8 billion in AI and cloud order intake during the second quarter of 2026. B. Riley pointed out that this provides revenue visibility into 2027. The firm also noted that the carrier inventory correction cycle that had weighed on global capital expenditures has now concluded.
Riley derived its $15 price target using a sum-of-the-parts valuation that separates the company's legacy ****** ets from its data center business. The firm applied a premium hardware multiple to the data center segment, reflecting its view of the potential operating leverage in that business.
Profitability Remains a Concern
#riley #NYSE #firm
Riley noted that the company's networking businesses are seeing strong growth. In Q2 2026, Optical Networks revenue increased 20% year-over-year, while IP Networks grew 16%. Net sales to AI and cloud customers also surged 105%. The research firm noted that hyperscalers continue to purchase Nokia Oyj's (NYSE:NOK) AI networking products to support large-scale computing clusters.
The company's AI and cloud opportunity is also reflected in its order book. Nokia Oyj (NYSE:NOK) reported EUR 2.8 billion in AI and cloud order intake during the second quarter of 2026. B. Riley pointed out that this provides revenue visibility into 2027. The firm also noted that the carrier inventory correction cycle that had weighed on global capital expenditures has now concluded.
Riley derived its $15 price target using a sum-of-the-parts valuation that separates the company's legacy ****** ets from its data center business. The firm applied a premium hardware multiple to the data center segment, reflecting its view of the potential operating leverage in that business.
Profitability Remains a Concern
#riley #NYSE #firm

2 months ago
On September 3, 2026, lululemon athletica inc. (NASDAQ:LULU) reported second-quarter fiscal 2026 results for the period ended August 2, 2026. Net revenue fell 4% to $2.4 billion, missing the $2.46 billion ****** ysts expected, and comparable sales dropped 10% on a constant dollar basis. Management cut full-year revenue guidance to a decline of 5% to 7%, down from a prior forecast of flat to down 1%, and lowered full-year earnings per share guidance to $9.48 to $9.73 from its prior forecast of $10.95 to $11.15, compared with $13.26 earned in fiscal 2025. Shares fell about 18% in extended trading. Incoming CEO Heidi O'Neill was set to start the following week.
Photo by Ian Deng Quddu on Unsplash
Citi's cut to $117 from $130 came with a Neutral rating and the observation that the stock's risk-reward is "slightly more favorable" after the selloff, even though the firm called fiscal 2027 visibility "very unclear." The operational bright spots are real.
lululemon athletica inc. (NASDAQ:LULU) increased its chase volume, the supply chain capability that lets it reorder fast-moving styles quickly, by about 20% this year, and away-from-body styles including the Groove Wide-Leg, Align Foldover Jogger, Breezily, and an updated Dance Studio Pant are trending well as shoppers shift from tight-fitting leggings. The brand's community pull held up too.
The SeaWheeze Half Marathon and Festival returned in August for the first time since 2019, drawing nearly 10,000 runners from 24 countries and roughly 14,000 festival attendees, while more than 85,000 people from 120 countries joined the companion Strava challenge, strong enough that Lululemon already committed to bringing the event back next summer. Rest of World revenue, spanning EMEA and APAC, grew 5% on a reported basis, and the company ended the quarter with $1.4 billion in cash and no outstanding borrowings.
#revenue #billion #NASDAQ
Photo by Ian Deng Quddu on Unsplash
Citi's cut to $117 from $130 came with a Neutral rating and the observation that the stock's risk-reward is "slightly more favorable" after the selloff, even though the firm called fiscal 2027 visibility "very unclear." The operational bright spots are real.
lululemon athletica inc. (NASDAQ:LULU) increased its chase volume, the supply chain capability that lets it reorder fast-moving styles quickly, by about 20% this year, and away-from-body styles including the Groove Wide-Leg, Align Foldover Jogger, Breezily, and an updated Dance Studio Pant are trending well as shoppers shift from tight-fitting leggings. The brand's community pull held up too.
The SeaWheeze Half Marathon and Festival returned in August for the first time since 2019, drawing nearly 10,000 runners from 24 countries and roughly 14,000 festival attendees, while more than 85,000 people from 120 countries joined the companion Strava challenge, strong enough that Lululemon already committed to bringing the event back next summer. Rest of World revenue, spanning EMEA and APAC, grew 5% on a reported basis, and the company ended the quarter with $1.4 billion in cash and no outstanding borrowings.
#revenue #billion #NASDAQ


2 months ago
Sempra (NYSE:SRE) added a long-term customer commitment on September 14, when its infrastructure subsidiary announced a 20-year sales and purchase agreement with Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR). The agreement covers approximately 0.8 million tonnes annually of liquefied natural gas, or LNG.
Supply will come from the subsidiary's contracted liquefaction capacity at Port Arthur LNG Phase 2 in Texas. The project is under construction, with trains 3 and 4 expected to begin commercial operations in 2030 and 2031, respectively. The agreement improves visibility into future sales, while the earnings contribution depends on delivery and contract economics.
Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR) becomes the infrastructure subsidiary's first South American LNG customer. That broadens the geographic base of buyers and establishes a commercial relationship extending over two decades.
For Sempra (NYSE:SRE), the practical benefit is an external buyer for part of the subsidiary's contracted capacity. Securing that relationship before startup could reduce the need to find buyers for the covered volumes as production approaches, while supporting longer-term supply planning.
The annual commitment equals approximately 6.2% of Phase 2's planned 13-million-tonne annual capacity. This provides a measure of scale, although it does not establish the percentage of capacity still available for sale.
#agreement #petr #supply #term
Supply will come from the subsidiary's contracted liquefaction capacity at Port Arthur LNG Phase 2 in Texas. The project is under construction, with trains 3 and 4 expected to begin commercial operations in 2030 and 2031, respectively. The agreement improves visibility into future sales, while the earnings contribution depends on delivery and contract economics.
Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR) becomes the infrastructure subsidiary's first South American LNG customer. That broadens the geographic base of buyers and establishes a commercial relationship extending over two decades.
For Sempra (NYSE:SRE), the practical benefit is an external buyer for part of the subsidiary's contracted capacity. Securing that relationship before startup could reduce the need to find buyers for the covered volumes as production approaches, while supporting longer-term supply planning.
The annual commitment equals approximately 6.2% of Phase 2's planned 13-million-tonne annual capacity. This provides a measure of scale, although it does not establish the percentage of capacity still available for sale.
#agreement #petr #supply #term

2 months ago
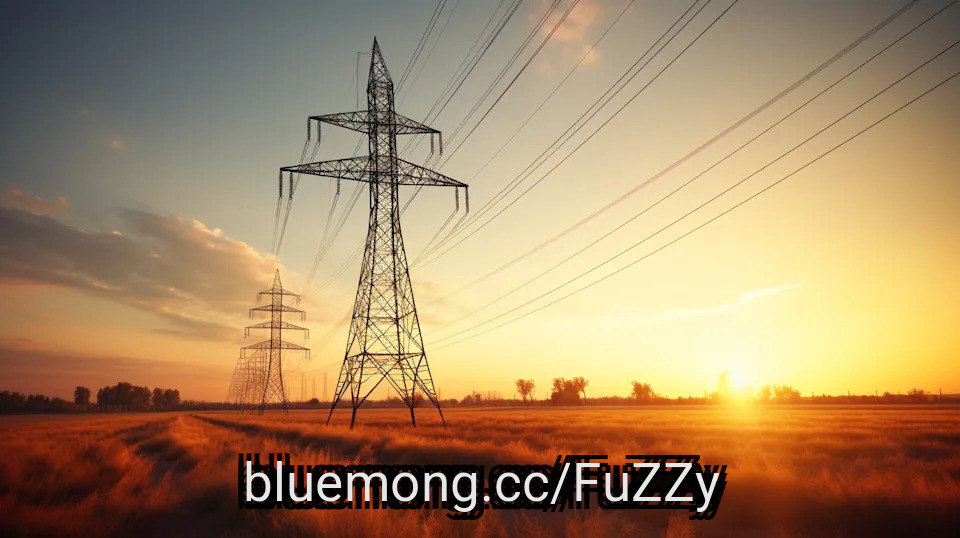
Transocean Ltd. (NYSE:RIG) received a boost on September 15 when the company announced that it had secured an approximately $80 million contract for its Deepwater Conqueror ultra-deepwater drillship in Equatorial Guinea. The estimated 170-day campaign with an undisclosed operator is expected to begin next year, directly following the rig's current contract in the US Gulf.
Built in 2016, the DSME 12000-design Deepwater Conqueror can operate in water depths of up to 12,000 feet and drill to a maximum depth of 40,000 feet.
The $80 million award provides Transocean with additional contract revenue and improves visibility into the company's future revenue base. If the award includes attractive day rates and limited mobilization costs, it could contribute positively to operating margins and cash flows. The company's backlog stood at approximately $6.7 billion as of August 5, 2026.
The contract could also improve the utilization of its high-value drilling rig. Since ultra-deepwater rigs require substantial investment, securing work for an idle or underutilized rig could help spread fixed operating costs over a larger revenue base. Deepwater Conqueror will move directly from its US Gulf contract to Equatorial Guinea, avoiding a gap between the two programs.
The latest award also provides Transocean with an alternative destination for its rigs. The company had already signaled in its Q2 earnings call that the growing demand for new deepwater contracts in Africa would also help offset a decline in awards in the US Gulf.
#deepwater #contract #gulf #equatorial
Built in 2016, the DSME 12000-design Deepwater Conqueror can operate in water depths of up to 12,000 feet and drill to a maximum depth of 40,000 feet.
The $80 million award provides Transocean with additional contract revenue and improves visibility into the company's future revenue base. If the award includes attractive day rates and limited mobilization costs, it could contribute positively to operating margins and cash flows. The company's backlog stood at approximately $6.7 billion as of August 5, 2026.
The contract could also improve the utilization of its high-value drilling rig. Since ultra-deepwater rigs require substantial investment, securing work for an idle or underutilized rig could help spread fixed operating costs over a larger revenue base. Deepwater Conqueror will move directly from its US Gulf contract to Equatorial Guinea, avoiding a gap between the two programs.
The latest award also provides Transocean with an alternative destination for its rigs. The company had already signaled in its Q2 earnings call that the growing demand for new deepwater contracts in Africa would also help offset a decline in awards in the US Gulf.
#deepwater #contract #gulf #equatorial

2 months ago
Targa Resources Corp. (NYSE:TRGP) has significantly outperformed the wider market this year, posting gains of over 56% since the beginning of 2026. A major catalyst behind this growth was the 20-year fee-based agreement that the company signed with ExxonMobil last month.
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda

2 months ago
GE Vernova Inc. (NYSE:GEV) received a boost on September 16 after CEO Scott Strazik stated that the company's backlog could hit the $200 billion mark "very early" in 2027, sooner than Wall Street had expected. The company expects the "strong and durable demand" to drive accelerated growth after its backlog had reached $167 billion at the end of the second quarter of 2026.
GEV has gained by almost 50% over the last year but is down by more than 14% over the last month, reflecting growing investor concerns surrounding the AI trade. The stock also came under pressure on September 14 when GLJ Research slammed it with a 'Sell' rating and a Street-low price target of $470, describing the company as "a cyclical gas turbine manufacturer priced as a secular compounder".
The update builds on extraordinarily strong momentum for GE Vernova, powered by the incredibly strong demand for its power equipment amid the AI data center boom. The company's backlog of $176 billion at the end of Q2 grew $13 billion from the previous quarter and was up 37% YoY, providing it with visibility into earnings well into the 2030s.
Notably, GE Vernova is translating this demand into financial improvement rather than simply a very large order book. The company's revenue grew by 22% YoY to $11.1 billion in the second quarter, while its free cash flow reached $5.1 billion, already exceeding its full-year 2025 level. Given the high demand, GEV raised its 2026 revenue forecast to $45.5 billion-$46.5 billion, up from its previous range of $44.5 billion-$45.5 billion.
The ongoing AI boom has been a major growth catalyst for GE Vernova, as its data center-related orders exceeded $5 billion in the first half of this year, more than double 2025's total. According to Barron's, power availability has become a key constraint for data center operators, and this strong demand has effectively constrained GEV's turbine capacity, which can support pricing and the value of scarce delivery slots.
#billion #year #data #center
GEV has gained by almost 50% over the last year but is down by more than 14% over the last month, reflecting growing investor concerns surrounding the AI trade. The stock also came under pressure on September 14 when GLJ Research slammed it with a 'Sell' rating and a Street-low price target of $470, describing the company as "a cyclical gas turbine manufacturer priced as a secular compounder".
The update builds on extraordinarily strong momentum for GE Vernova, powered by the incredibly strong demand for its power equipment amid the AI data center boom. The company's backlog of $176 billion at the end of Q2 grew $13 billion from the previous quarter and was up 37% YoY, providing it with visibility into earnings well into the 2030s.
Notably, GE Vernova is translating this demand into financial improvement rather than simply a very large order book. The company's revenue grew by 22% YoY to $11.1 billion in the second quarter, while its free cash flow reached $5.1 billion, already exceeding its full-year 2025 level. Given the high demand, GEV raised its 2026 revenue forecast to $45.5 billion-$46.5 billion, up from its previous range of $44.5 billion-$45.5 billion.
The ongoing AI boom has been a major growth catalyst for GE Vernova, as its data center-related orders exceeded $5 billion in the first half of this year, more than double 2025's total. According to Barron's, power availability has become a key constraint for data center operators, and this strong demand has effectively constrained GEV's turbine capacity, which can support pricing and the value of scarce delivery slots.
#billion #year #data #center


2 months ago
Enbridge Inc. (NYSE:ENB) has declined by around 17% since hitting its record high in May, likely as a result of rising bond yields, lack of visibility on the company's 5% growth guidance through the end of the decade, and the recently closed equity offering intended to fund the midstream operator's strategic acquisitions.
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target


2 months ago
On September 17, Ferrari N.V. (NYSE:RACE) announced a partnership with the technology company Rakuten Group, Inc., effective January 1, 2027. The announcement gives no scope and no price tag, so it works better as a signal than as a number. The real substance sits in the results Ferrari posted on July 30, when it raised its 2026 guidance because buyers are ordering more personalization than the company expected.
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari

2 months ago
Intel Corporation (NASDAQ:INTC) is targeting a potentially significant opportunity through its strategic Terafab partnership with companies **** ociated with Elon Musk, including **** eX, Tesla, and xAI. The initiative is part of an ambitious semiconductor manufacturing project focused on producing advanced chips for artificial intelligence (AI), robotics, autonomous vehicles, and other compute-intensive applications.
On September 15, Tigress Financial highlighted the strategic importance of the alliance to Intel's turnaround prospects. The research firm reiterated its Buy rating on Intel and raised its price target to $145 from $118, citing the company's long-term growth opportunity.
The Terafab partnership could provide Intel's foundry business with exposure to customers that have substantial AI and high-performance computing requirements. Securing external customers could help Intel increase manufacturing scale while improving the utilization and economics of its foundry operations.
The partnership could also support Intel Corporation (NASDAQ:INTC)'s efforts to improve its semiconductor manufacturing technology. Greater production volumes and engagement with demanding customers could provide opportunities to improve manufacturing economics, yields, and scalability as Intel works to strengthen its competitive position in advanced chip manufacturing.
Beyond manufacturing scale, Terafab could expand Intel's role in the broader AI semiconductor supply chain. The company has historically been heavily **** ociated with CPUs, but growing its foundry business could give it greater exposure to AI accelerators, custom silicon, and other specialized compute applications. A relationship with major AI-focused customers could also help provide greater visibility into future manufacturing demand.
#Intel
On September 15, Tigress Financial highlighted the strategic importance of the alliance to Intel's turnaround prospects. The research firm reiterated its Buy rating on Intel and raised its price target to $145 from $118, citing the company's long-term growth opportunity.
The Terafab partnership could provide Intel's foundry business with exposure to customers that have substantial AI and high-performance computing requirements. Securing external customers could help Intel increase manufacturing scale while improving the utilization and economics of its foundry operations.
The partnership could also support Intel Corporation (NASDAQ:INTC)'s efforts to improve its semiconductor manufacturing technology. Greater production volumes and engagement with demanding customers could provide opportunities to improve manufacturing economics, yields, and scalability as Intel works to strengthen its competitive position in advanced chip manufacturing.
Beyond manufacturing scale, Terafab could expand Intel's role in the broader AI semiconductor supply chain. The company has historically been heavily **** ociated with CPUs, but growing its foundry business could give it greater exposure to AI accelerators, custom silicon, and other specialized compute applications. A relationship with major AI-focused customers could also help provide greater visibility into future manufacturing demand.
#Intel


2 months ago
On September 4, the U.S. Department of War (DoW) announced a $336,112,000 Navy contract for Huntington Ingalls Industries, Inc. (NYSE:HII) to advance procurement of long-lead materials for the construction of the future USS William J. Clinton (CVN 82).
Work on the program will be executed in Newport News, Virginia, with completion anticipated by March 2039. Shipbuilding and conversion funding from FY 2026 will be obligated at the time of award.
The contract is not just a headline number, but reaffirms the company's status as the sole nuclear carrier builder for the U.S. Navy.
The long lead materials contract has secured Huntington Ingalls Industries, Inc. (NYSE:HII)'s role on the CVN 82 well before construction begins, which has extended revenue visibility to 2039.
According to defense websites, the Navy plans on spending $22.34 billion on its aircraft carrier replacement program over the next five years. This contract can be seen as among the first in a larger sequence, with more awards to come as procurement accelerates.
#navy #contract #ingalls #industries
Work on the program will be executed in Newport News, Virginia, with completion anticipated by March 2039. Shipbuilding and conversion funding from FY 2026 will be obligated at the time of award.
The contract is not just a headline number, but reaffirms the company's status as the sole nuclear carrier builder for the U.S. Navy.
The long lead materials contract has secured Huntington Ingalls Industries, Inc. (NYSE:HII)'s role on the CVN 82 well before construction begins, which has extended revenue visibility to 2039.
According to defense websites, the Navy plans on spending $22.34 billion on its aircraft carrier replacement program over the next five years. This contract can be seen as among the first in a larger sequence, with more awards to come as procurement accelerates.
#navy #contract #ingalls #industries

2 months ago
During the September 14 episode of Mad Money, Jim Cramer addressed the broader tech sector pullback and mentioned Broadcom Inc. (NASDAQ:AVGO) as an attractive option for investors looking past short-term volatility. He stated:
Well, it's a tough time to come out to San Francisco, a day when the whole AI complex is getting hammered because Anthropic and OpenAI seem to be, I don't know… pulling in their horns. Actually, I think there's some real bargains in this group. Take Broadcom, the maker of chips, networking equipment, and tech infrastructure and software with a stock that's down more than 10% over the past month. At the beginning of this month, Broadcom reported a strong set of results, issued a spectacular multi-year forecast, but their guidance for the current quarter was, I don't know, viewed by some as in line.
The stock got slammed. I think Broadcom's still on track to put up some incredible growth because they're at the heart of the AI ecosystem because the company's never let us down in all the years my Charitable Trust has owned it. And down here, roughly 150 points below its June high, the stock may be too cheap to ignore.
Recent financial reports from Broadcom Inc. (NASDAQ:AVGO) highlights the scale of expansion driving its core semiconductor and infrastructure divisions. Total revenue for the fiscal third quarter reached $29.6 billion, representing an 85.5% increase compared to the same period in the previous year. Artificial intelligence semiconductor revenue surged 221% to $16.7 billion, accounting for roughly 56% of total revenue. Remaining performance obligations climbed significantly to $179.2 billion, providing substantial visibility into future contracted revenue. Broadcom also serves major hyperscale AI customers including Alphabet and Meta Platforms.
Management raised its full year guidance to $58 billion from $56 billion in artificial intelligence revenue, while projecting $115 billion for fiscal 2027 and $230 billion for fiscal 2028. The figures highlight a deep integration into the enterprise artificial intelligence ecosystem through custom accelerators and high-speed networking solutions.
#down #year #fiscal #NASDAQ
Well, it's a tough time to come out to San Francisco, a day when the whole AI complex is getting hammered because Anthropic and OpenAI seem to be, I don't know… pulling in their horns. Actually, I think there's some real bargains in this group. Take Broadcom, the maker of chips, networking equipment, and tech infrastructure and software with a stock that's down more than 10% over the past month. At the beginning of this month, Broadcom reported a strong set of results, issued a spectacular multi-year forecast, but their guidance for the current quarter was, I don't know, viewed by some as in line.
The stock got slammed. I think Broadcom's still on track to put up some incredible growth because they're at the heart of the AI ecosystem because the company's never let us down in all the years my Charitable Trust has owned it. And down here, roughly 150 points below its June high, the stock may be too cheap to ignore.
Recent financial reports from Broadcom Inc. (NASDAQ:AVGO) highlights the scale of expansion driving its core semiconductor and infrastructure divisions. Total revenue for the fiscal third quarter reached $29.6 billion, representing an 85.5% increase compared to the same period in the previous year. Artificial intelligence semiconductor revenue surged 221% to $16.7 billion, accounting for roughly 56% of total revenue. Remaining performance obligations climbed significantly to $179.2 billion, providing substantial visibility into future contracted revenue. Broadcom also serves major hyperscale AI customers including Alphabet and Meta Platforms.
Management raised its full year guidance to $58 billion from $56 billion in artificial intelligence revenue, while projecting $115 billion for fiscal 2027 and $230 billion for fiscal 2028. The figures highlight a deep integration into the enterprise artificial intelligence ecosystem through custom accelerators and high-speed networking solutions.
#down #year #fiscal #NASDAQ

2 months ago
Amazon Business is now a $60B operation serving 11 million customers worldwide. In this FreightWaves Today interview, Amazon Business exec Daniel Silverfield breaks down what that scale means for procurement, supplier consolidation, same-day grocery delivery and AI-driven savings.The big takeaway: business buyers want fewer suppliers, better visibility and less waste in purchasing. Silverfield explains how Amazon Business is pitching exactly that to everyone from small companies to Fortune 100s.
Amazon Business has hit $60 billion in annualized gross sales and now serves 11 million customers worldwide, with 1.8 million organizations added this year alone — a growth rate that puts it on par with a Fortune 100 company if it were standalone. The platform, which launched roughly a decade ago after Amazon noticed businesses already shopping on amazon.com, is increasingly central to how companies across sectors manage procurement, from office supplies to same-day groceries.
The scale matters to shippers, carriers, and brokers because Amazon Business is driving a fundamental shift in B2B purchasing behavior — consolidating supplier pools, centralizing data, and moving procurement from quarterly reporting cycles to an always-on, AI-powered model. Every order that migrates to the platform is one fewer touchpoint for traditional distributors and one more shipment flowing through Amazon's own logistics network.
Daniel Silverfield, head of value and selection for Amazon Business, said the platform saved customers $880 million on Prime free shipping last year and $1 billion through business-specific discounts. The company added 30% new items year over year and recently launched same-day grocery delivery across 2,300 U.S. cities in the first half of this year, a capability customers had been requesting for some time.
"The big shift that we're seeing is that people are moving to a continuous, always-on, conversational-powered procurement journey where agents may be looking for the best price while they're asleep, maybe negotiating on their behalf while they're asleep, and then surfacing to them the best product to buy," said Silverfield.
#customers
Amazon Business has hit $60 billion in annualized gross sales and now serves 11 million customers worldwide, with 1.8 million organizations added this year alone — a growth rate that puts it on par with a Fortune 100 company if it were standalone. The platform, which launched roughly a decade ago after Amazon noticed businesses already shopping on amazon.com, is increasingly central to how companies across sectors manage procurement, from office supplies to same-day groceries.
The scale matters to shippers, carriers, and brokers because Amazon Business is driving a fundamental shift in B2B purchasing behavior — consolidating supplier pools, centralizing data, and moving procurement from quarterly reporting cycles to an always-on, AI-powered model. Every order that migrates to the platform is one fewer touchpoint for traditional distributors and one more shipment flowing through Amazon's own logistics network.
Daniel Silverfield, head of value and selection for Amazon Business, said the platform saved customers $880 million on Prime free shipping last year and $1 billion through business-specific discounts. The company added 30% new items year over year and recently launched same-day grocery delivery across 2,300 U.S. cities in the first half of this year, a capability customers had been requesting for some time.
"The big shift that we're seeing is that people are moving to a continuous, always-on, conversational-powered procurement journey where agents may be looking for the best price while they're asleep, maybe negotiating on their behalf while they're asleep, and then surfacing to them the best product to buy," said Silverfield.
#customers

2 months ago
GE Aerospace (GE) has more engine work booked than it can currently perform, and that visibility is much of why people own the shares. The option chain does not treat the stock as settled. At about $307, contracts running twelve months out carry a band from near $216.93 to near $434.6, with roughly a two-in-three chance the stock finishes inside it.
Read that band as money. The ceiling near $434.6 sits about 41.5% above today's price, and the floor near $216.93 sits about 29.4% below it. Whatever money you have in GE, the options market prices about $90 of every $307 coming off, or about $128 going on, inside twelve months.
The two distances are not equal. A share price cannot fall below zero while nothing caps the upside, so the ceiling always sits further out than the floor. That is arithmetic rather than a view on GE.
The floor is the half worth sitting with. Near $216.93, it is well below $272.91, the lowest GE has traded in the past 52 weeks. The chain is not forecasting that price. It prices twelve months as long enough to reach it.
A range is only wide relative to something. The stock's realized volatility over the trailing year, meaning how far it has actually moved, was 33.2%, and the options quote 34.6%. The market is charging about what this stock already delivers.
#near #sits #floor #band
Read that band as money. The ceiling near $434.6 sits about 41.5% above today's price, and the floor near $216.93 sits about 29.4% below it. Whatever money you have in GE, the options market prices about $90 of every $307 coming off, or about $128 going on, inside twelve months.
The two distances are not equal. A share price cannot fall below zero while nothing caps the upside, so the ceiling always sits further out than the floor. That is arithmetic rather than a view on GE.
The floor is the half worth sitting with. Near $216.93, it is well below $272.91, the lowest GE has traded in the past 52 weeks. The chain is not forecasting that price. It prices twelve months as long enough to reach it.
A range is only wide relative to something. The stock's realized volatility over the trailing year, meaning how far it has actually moved, was 33.2%, and the options quote 34.6%. The market is charging about what this stock already delivers.
#near #sits #floor #band

2 months ago
VICTORIA, SEYCHELLES, September 16th, 2026, Chainwire
Bitget has published its August 2026 Proof of Reserves report, marking the 45th consecutive monthly disclosure since the program began in December 2022, with a total reserve ratio of 122% for the month. Separately, Bitget's August 2026 Protection Fund valuation report recorded an average monthly value of $382 million, backed by 5,500 BTC held as a separate protection reserve.
Bitget publishes both monthly Proof of Reserves and monthly Protection Fund valuation reports — two separate disclosures providing visibility into different parts of the platform's **** et-protection framework. The August PoR reserve ratio of 122% means Bitget's reported reserves for tracked **** ets exceeded the corresponding user balances included in the snapshot. A full per-asset breakdown is available on Bitget's Proof of Reserves page.
A reserve ratio above 100% reflects the position captured in a particular reporting snapshot and should not be interpreted as a financial audit or a guarantee of future solvency.
The Protection Fund's August valuation ranged from approximately $345.3 million on Aug 1, 2026 to $441.5 million on Aug 27, 2026, with an average monthly valuation of $382 million. Its dollar value fluctuates with Bitcoin's market price because the fund is backed by 5,500 BTC. Bitget established the fund in 2022 with an initial $300 million commitment, and its valuation remained above that level throughout August.
#proof
Bitget has published its August 2026 Proof of Reserves report, marking the 45th consecutive monthly disclosure since the program began in December 2022, with a total reserve ratio of 122% for the month. Separately, Bitget's August 2026 Protection Fund valuation report recorded an average monthly value of $382 million, backed by 5,500 BTC held as a separate protection reserve.
Bitget publishes both monthly Proof of Reserves and monthly Protection Fund valuation reports — two separate disclosures providing visibility into different parts of the platform's **** et-protection framework. The August PoR reserve ratio of 122% means Bitget's reported reserves for tracked **** ets exceeded the corresponding user balances included in the snapshot. A full per-asset breakdown is available on Bitget's Proof of Reserves page.
A reserve ratio above 100% reflects the position captured in a particular reporting snapshot and should not be interpreted as a financial audit or a guarantee of future solvency.
The Protection Fund's August valuation ranged from approximately $345.3 million on Aug 1, 2026 to $441.5 million on Aug 27, 2026, with an average monthly valuation of $382 million. Its dollar value fluctuates with Bitcoin's market price because the fund is backed by 5,500 BTC. Bitget established the fund in 2022 with an initial $300 million commitment, and its valuation remained above that level throughout August.
#proof

2 months ago
This story was originally published on CFO.com. To receive daily news and insights, subscribe to our free daily CFO.com newsletter.
Is there a disconnect between finance teams and procurement teams? A new survey of 2,005 procurement leaders in the U.S. and the U.K. suggests there is for some companies, and it may ultimately be affecting their bottom lines.
Released Tuesday, the report from California-based contract lifecycle management company Agiloft showed that about one in 10 respondents said they have no shared metrics between chief procurement officers and CFOs. The lack of shared metrics was cited among the biggest obstacles preventing companies from "closing the gap between what procurement negotiates and what finance realizes."
Other barriers cited were lack of contract data visibility, selected by 14% of respondents, along with manual processes that create exceptions that go unseen (23%).
Agiloft's survey included responses gathered from 2,005 chief procurement officers and other procurement leaders Aug. 5-20.
#procurement
Is there a disconnect between finance teams and procurement teams? A new survey of 2,005 procurement leaders in the U.S. and the U.K. suggests there is for some companies, and it may ultimately be affecting their bottom lines.
Released Tuesday, the report from California-based contract lifecycle management company Agiloft showed that about one in 10 respondents said they have no shared metrics between chief procurement officers and CFOs. The lack of shared metrics was cited among the biggest obstacles preventing companies from "closing the gap between what procurement negotiates and what finance realizes."
Other barriers cited were lack of contract data visibility, selected by 14% of respondents, along with manual processes that create exceptions that go unseen (23%).
Agiloft's survey included responses gathered from 2,005 chief procurement officers and other procurement leaders Aug. 5-20.
#procurement


2 months ago
On September 10, a caller outlined a detailed financial thesis showing Micron Technology, Inc. (NASDAQ:MU) reaching $1,400 and asked whether the **** ysis held water. In response, Mad Money host Jim Cramer said:
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry

2 months ago
Pfizer Inc. (NYSE:PFE) and Valneva SE (NASDAQ:VALN) reported on August 14 that the European Medicines Agency has validated the Marketing Authorization Application for PF-07307405, the companies' experimental Lyme disease vaccine candidate, and will now begin the official review.
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#vaccine #pfizer #NYSE
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#vaccine #pfizer #NYSE
2 months ago
Chemical manufacturer OXEA has selected Uber Freight as its strategic logistics provider across the U.S., Canada, Mexico and Europe as the company moves to consolidate regional transportation operations into a more unified global network.
Houston-based OXEA said Uber Freight will manage day-to-day transportation execution across truckload, rail and ocean freight, using technology, data and logistics services to provide greater visibility across the chemical manufacturer's supply chain.
The agreement represents Uber Freight's (NYSE: UBER) first managed transportation engagement designed from the outset to span the U.S., Canada, Mexico and Europe, according to the companies.
OXEA manufactures oxo intermediates and oxo performance chemicals used in products including coatings, lubricants, cosmetics, pharmaceuticals, flavors and fragrances, printing inks and plastics. The company employs more than 1,200 people and sells chemicals in more than 60 countries.
The partnership is intended to replace a more regionally segmented approach to transportation management with an integrated operation connecting OXEA's plants, carriers and customers.
#Mexico #chemical #Logistics
Houston-based OXEA said Uber Freight will manage day-to-day transportation execution across truckload, rail and ocean freight, using technology, data and logistics services to provide greater visibility across the chemical manufacturer's supply chain.
The agreement represents Uber Freight's (NYSE: UBER) first managed transportation engagement designed from the outset to span the U.S., Canada, Mexico and Europe, according to the companies.
OXEA manufactures oxo intermediates and oxo performance chemicals used in products including coatings, lubricants, cosmetics, pharmaceuticals, flavors and fragrances, printing inks and plastics. The company employs more than 1,200 people and sells chemicals in more than 60 countries.
The partnership is intended to replace a more regionally segmented approach to transportation management with an integrated operation connecting OXEA's plants, carriers and customers.
#Mexico #chemical #Logistics


2 months ago
On September 13, Reuters reported that Anthropic is in talks to bring NVIDIA Corporation (NASDAQ:NVDA) in as an anchor investor in what could become one of the largest IPOs in history, potentially raising as much as $100 billion at a valuation of around $2 trillion. Nvidia is reportedly considering an investment of up to $10 billion. Anthropic's annualized revenue run rate has reportedly increased from about $9 billion in 2025 to more than $65 billion by mid-2026, with the company targeting as much as $200 billion of revenue by 2028.
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of ***** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable o
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of ***** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable o


2 months ago
Pfizer Inc. (NYSE:PFE) and Valneva SE (NASDAQ:VALN) reported on August 14 that the European Medicines Agency has validated the Marketing Authorization Application for PF-07307405, the companies' experimental Lyme disease vaccine candidate, and will now begin the official review.
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#disease
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#disease

2 months ago
Chemical manufacturer OXEA has selected Uber Freight as its strategic logistics provider across the U.S., Canada, Mexico and Europe as the company moves to consolidate regional transportation operations into a more unified global network.
Houston-based OXEA said Uber Freight will manage day-to-day transportation execution across truckload, rail and ocean freight, using technology, data and logistics services to provide greater visibility across the chemical manufacturer's supply chain.
The agreement represents Uber Freight's (NYSE: UBER) first managed transportation engagement designed from the outset to span the U.S., Canada, Mexico and Europe, according to the companies.
OXEA manufactures oxo intermediates and oxo performance chemicals used in products including coatings, lubricants, cosmetics, pharmaceuticals, flavors and fragrances, printing inks and plastics. The company employs more than 1,200 people and sells chemicals in more than 60 countries.
The partnership is intended to replace a more regionally segmented approach to transportation management with an integrated operation connecting OXEA's plants, carriers and customers.
#Transportation #Logistics
Houston-based OXEA said Uber Freight will manage day-to-day transportation execution across truckload, rail and ocean freight, using technology, data and logistics services to provide greater visibility across the chemical manufacturer's supply chain.
The agreement represents Uber Freight's (NYSE: UBER) first managed transportation engagement designed from the outset to span the U.S., Canada, Mexico and Europe, according to the companies.
OXEA manufactures oxo intermediates and oxo performance chemicals used in products including coatings, lubricants, cosmetics, pharmaceuticals, flavors and fragrances, printing inks and plastics. The company employs more than 1,200 people and sells chemicals in more than 60 countries.
The partnership is intended to replace a more regionally segmented approach to transportation management with an integrated operation connecting OXEA's plants, carriers and customers.
#Transportation #Logistics
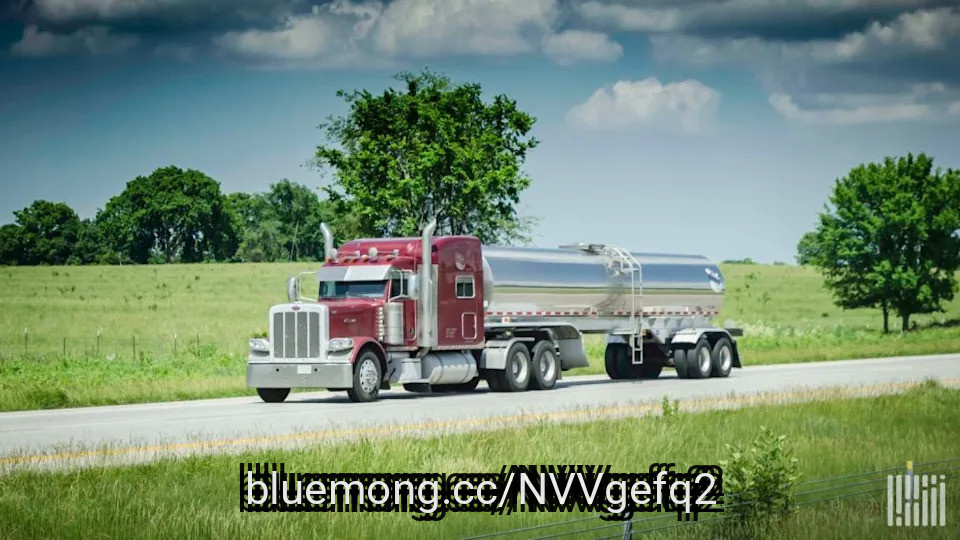

2 months ago
On September 13, Reuters reported that Anthropic is in talks to bring NVIDIA Corporation (NASDAQ:NVDA) in as an anchor investor in what could become one of the largest IPOs in history, potentially raising as much as $100 billion at a valuation of around $2 trillion. Nvidia is reportedly considering an investment of up to $10 billion. Anthropic's annualized revenue run rate has reportedly increased from about $9 billion in 2025 to more than $65 billion by mid-2026, with the company targeting as much as $200 billion of revenue by 2028.
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of **** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable of
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of **** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable of

2 months ago
VICTORIA, SEYCHELLES, September 16th, 2026, Chainwire
Bitget has published its August 2026 Proof of Reserves report, marking the 45th consecutive monthly disclosure since the program began in December 2022, with a total reserve ratio of 122% for the month. Separately, Bitget's August 2026 Protection Fund valuation report recorded an average monthly value of $382 million, backed by 5,500 BTC held as a separate protection reserve.
Bitget publishes both monthly Proof of Reserves and monthly Protection Fund valuation reports — two separate disclosures providing visibility into different parts of the platform's ***** et-protection framework. The August PoR reserve ratio of 122% means Bitget's reported reserves for tracked ***** ets exceeded the corresponding user balances included in the snapshot. A full per-asset breakdown is available on Bitget's Proof of Reserves page.
A reserve ratio above 100% reflects the position captured in a particular reporting snapshot and should not be interpreted as a financial audit or a guarantee of future solvency.
The Protection Fund's August valuation ranged from approximately $345.3 million on Aug 1, 2026 to $441.5 million on Aug 27, 2026, with an average monthly valuation of $382 million. Its dollar value fluctuates with Bitcoin's market price because the fund is backed by 5,500 BTC. Bitget established the fund in 2022 with an initial $300 million commitment, and its valuation remained above that level throughout August.
#valuation
Bitget has published its August 2026 Proof of Reserves report, marking the 45th consecutive monthly disclosure since the program began in December 2022, with a total reserve ratio of 122% for the month. Separately, Bitget's August 2026 Protection Fund valuation report recorded an average monthly value of $382 million, backed by 5,500 BTC held as a separate protection reserve.
Bitget publishes both monthly Proof of Reserves and monthly Protection Fund valuation reports — two separate disclosures providing visibility into different parts of the platform's ***** et-protection framework. The August PoR reserve ratio of 122% means Bitget's reported reserves for tracked ***** ets exceeded the corresponding user balances included in the snapshot. A full per-asset breakdown is available on Bitget's Proof of Reserves page.
A reserve ratio above 100% reflects the position captured in a particular reporting snapshot and should not be interpreted as a financial audit or a guarantee of future solvency.
The Protection Fund's August valuation ranged from approximately $345.3 million on Aug 1, 2026 to $441.5 million on Aug 27, 2026, with an average monthly valuation of $382 million. Its dollar value fluctuates with Bitcoin's market price because the fund is backed by 5,500 BTC. Bitget established the fund in 2022 with an initial $300 million commitment, and its valuation remained above that level throughout August.
#valuation

2 months ago
Sept. 14 (UPI) -- The planned West End revival of Sunday in the Park with George has been delayed to 2028.
Empire Street Productions announced Monday that the musical "will no longer proceed as scheduled" in 2027, with the company to "retain the rights with a view to presenting the production in 2028."
The news follows word that Wicked co-stars Ariana Grande and Jonathan Bailey have dropped out of the production. Grande announced in August that she "will be taking a step back from visibility" after the conclusion of her Eternal Sunshine tour, with Bailey later confirming he has "decided to also step back" from the revival.
Sunday in the Park with George features music and lyrics by famed composer Stephen Sondheim. The musical, inspired by the Georges Seurat painting A Sunday Afternoon on the Island of La Grande Jatte, debuted on Broadway in 1984 and on West End in 2006.
Marianne Elliot was to direct the West End revival, which was originally scheduled to open at London's Barbican Centre in summer 2027.
#grande #musical
Empire Street Productions announced Monday that the musical "will no longer proceed as scheduled" in 2027, with the company to "retain the rights with a view to presenting the production in 2028."
The news follows word that Wicked co-stars Ariana Grande and Jonathan Bailey have dropped out of the production. Grande announced in August that she "will be taking a step back from visibility" after the conclusion of her Eternal Sunshine tour, with Bailey later confirming he has "decided to also step back" from the revival.
Sunday in the Park with George features music and lyrics by famed composer Stephen Sondheim. The musical, inspired by the Georges Seurat painting A Sunday Afternoon on the Island of La Grande Jatte, debuted on Broadway in 1984 and on West End in 2006.
Marianne Elliot was to direct the West End revival, which was originally scheduled to open at London's Barbican Centre in summer 2027.
#grande #musical
2 months ago
Energy Transfer LP (NYSE:ET) is set to move the primary listing of its common and Series I preferred units from the New York Stock Exchange to the Texas Stock Exchange in early October, making it the first major company to make such a switch from the NYSE to the newly established Dallas exchange. Reuters said the companies moving to TXSE, including Energy Transfer and related energy businesses, represent nearly $100 billion in combined market value, giving the fledgling exchange an important early credibility boost.
For Energy Transfer LP (NYSE:ET), however, the more important question is whether the move can eventually translate into better investor visibility or valuation rather than simply giving the company a stronger Texas identity. WSJ reported that Energy Transfer is worth roughly $75 billion and that Executive Chairman Kelcy Warren is a major backer of TXSE, owning about 30% of its parent company. That relationship makes the listing particularly significant, but it also means investors may scrutinize whether the decision creates a tangible benefit for Energy Transfer unitholders rather than primarily helping establish the new exchange.
The strongest bull argument is that Energy Transfer LP (NYSE:ET) is positioning itself ahead of a potentially important shift in the U.S. energy infrastructure market. TXSE is backed by major financial institutions including BlackRock, Citadel Securities, and Charles Schwab, and winning a roughly $75 billion company gives the exchange substantially more credibility with institutional investors. If TXSE attracts additional large energy companies, Energy Transfer could benefit from becoming one of the exchange's anchor names and gaining greater visibility among investors already focused on Texas-based energy infrastructure.
More importantly, the listing decision fits the underlying environment in which Energy Transfer LP (NYSE:ET) operates. Reuters has highlighted continued investment in U.S. gas-fired generation, LNG infrastructure, and pipeline networks as electricity demand rises and countries seek reliable energy supplies. The U.S. is also building substantial additional LNG export capacity. That matters because Energy Transfer's extensive midstream network can benefit from higher volumes of natural gas, crude oil, and NGLs without taking the same direct commodity-price exposure as upstream producers. If rising power demand from data centers and continued LNG development drive greater demand for U.S. gas transportation, Energy Transfer could see expanding opportunities to place additional infrastructure into service and lock in long-duration cash flows.
#transfer #company #infrastructure #listing
For Energy Transfer LP (NYSE:ET), however, the more important question is whether the move can eventually translate into better investor visibility or valuation rather than simply giving the company a stronger Texas identity. WSJ reported that Energy Transfer is worth roughly $75 billion and that Executive Chairman Kelcy Warren is a major backer of TXSE, owning about 30% of its parent company. That relationship makes the listing particularly significant, but it also means investors may scrutinize whether the decision creates a tangible benefit for Energy Transfer unitholders rather than primarily helping establish the new exchange.
The strongest bull argument is that Energy Transfer LP (NYSE:ET) is positioning itself ahead of a potentially important shift in the U.S. energy infrastructure market. TXSE is backed by major financial institutions including BlackRock, Citadel Securities, and Charles Schwab, and winning a roughly $75 billion company gives the exchange substantially more credibility with institutional investors. If TXSE attracts additional large energy companies, Energy Transfer could benefit from becoming one of the exchange's anchor names and gaining greater visibility among investors already focused on Texas-based energy infrastructure.
More importantly, the listing decision fits the underlying environment in which Energy Transfer LP (NYSE:ET) operates. Reuters has highlighted continued investment in U.S. gas-fired generation, LNG infrastructure, and pipeline networks as electricity demand rises and countries seek reliable energy supplies. The U.S. is also building substantial additional LNG export capacity. That matters because Energy Transfer's extensive midstream network can benefit from higher volumes of natural gas, crude oil, and NGLs without taking the same direct commodity-price exposure as upstream producers. If rising power demand from data centers and continued LNG development drive greater demand for U.S. gas transportation, Energy Transfer could see expanding opportunities to place additional infrastructure into service and lock in long-duration cash flows.
#transfer #company #infrastructure #listing

2 months ago
Interested in Intuitive Surgical, Inc.? Here are five stocks we like better.
Global procedure growth remains intact despite a recent U.S. slowdown and Affordable Care Act-related uncertainty; Intuitive Surgical maintained its 13.5%–15.5% global procedure-growth outlook, expecting results near the midpoint.
Ambulatory surgery centers and international markets remain important expansion opportunities, with second-quarter system placements rising in the U.S. and abroad. However, China remains pressured by local competition and slower tenders, with improved visibility not expected until 2027.
Future growth could come from da Vinci 5 upgrades, Force Feedback instruments, new procedures and sites of care, and AI services such as Case Insights. The company also reported strong financial performance, including 21% revenue growth and operating and free-cash-flow margins above historical averages.
This AI ETF Is Missing the Biggest AI Winners
#affordable
Global procedure growth remains intact despite a recent U.S. slowdown and Affordable Care Act-related uncertainty; Intuitive Surgical maintained its 13.5%–15.5% global procedure-growth outlook, expecting results near the midpoint.
Ambulatory surgery centers and international markets remain important expansion opportunities, with second-quarter system placements rising in the U.S. and abroad. However, China remains pressured by local competition and slower tenders, with improved visibility not expected until 2027.
Future growth could come from da Vinci 5 upgrades, Force Feedback instruments, new procedures and sites of care, and AI services such as Case Insights. The company also reported strong financial performance, including 21% revenue growth and operating and free-cash-flow margins above historical averages.
This AI ETF Is Missing the Biggest AI Winners
#affordable

2 months ago
On September 10, Piper Sandler **** yst Bill Carcache initiated coverage of Q2 Holdings, Inc. (NYSE:QTWO), giving the stock an Overweight rating and setting the price target at $82.
The research firm started coverage on companies in the payments and consumer finance group and named Q2 Holdings, Inc. (NYSE:QTWO) as its preferred name in the sector.
According to Piper Sandler, the company offers the "clearest combination" of subscription revenue growth, visibility into annual recurring revenue, and improving free cash flow conversion. The firm also highlighted the company's growing margins and debt-free balance sheet. Piper Sandler said these factors support what it sees as the clearest path toward durable growth among the payments and consumer finance group.
Q2 Holdings, Inc. (NYSE:QTWO) delivered strong financial performance in Q2 2026. The company reported revenue of $219.8 million, an increase of 13% year-over-year and 2% sequentially. GAAP gross margin improved to 59.2% from 53.6% in the prior-year quarter, while GAAP net income rose to $29.9 million from $11.8 million.
Adjusted EBITDA reached a record $62.8 million, up 37% year-over-year. The company said it delivered another quarter of consistent execution, with strong bookings across its solutions.
#year #NYSE #revenue
The research firm started coverage on companies in the payments and consumer finance group and named Q2 Holdings, Inc. (NYSE:QTWO) as its preferred name in the sector.
According to Piper Sandler, the company offers the "clearest combination" of subscription revenue growth, visibility into annual recurring revenue, and improving free cash flow conversion. The firm also highlighted the company's growing margins and debt-free balance sheet. Piper Sandler said these factors support what it sees as the clearest path toward durable growth among the payments and consumer finance group.
Q2 Holdings, Inc. (NYSE:QTWO) delivered strong financial performance in Q2 2026. The company reported revenue of $219.8 million, an increase of 13% year-over-year and 2% sequentially. GAAP gross margin improved to 59.2% from 53.6% in the prior-year quarter, while GAAP net income rose to $29.9 million from $11.8 million.
Adjusted EBITDA reached a record $62.8 million, up 37% year-over-year. The company said it delivered another quarter of consistent execution, with strong bookings across its solutions.
#year #NYSE #revenue


