

1 day ago
Sign up for Semafor Washington, DC: What the White House is reading. Read it now.
In this article:
As soon as Republican Sen. Darline Graham won the GOP nomination to replace her late brother in August, Democrat Annie Andrews made her move.
Andrews immediately began spending more than $5 million on advertising in South Carolina’s Senate race at a moment when she largely had the airwaves to herself as her new opponent struggled to raise money. At the time, Republicans were racing to prioritize other competitive races across the country — and most people in both parties still saw South Carolina as a pipe dream for Democrats.
But by October, when the rest of the country began tuning into South Carolina — and spending money — Andrews quietly became the frontrunner, according to internal campaign details shared with Semafor following her victory on Tuesday.
#semafor #began
In this article:
As soon as Republican Sen. Darline Graham won the GOP nomination to replace her late brother in August, Democrat Annie Andrews made her move.
Andrews immediately began spending more than $5 million on advertising in South Carolina’s Senate race at a moment when she largely had the airwaves to herself as her new opponent struggled to raise money. At the time, Republicans were racing to prioritize other competitive races across the country — and most people in both parties still saw South Carolina as a pipe dream for Democrats.
But by October, when the rest of the country began tuning into South Carolina — and spending money — Andrews quietly became the frontrunner, according to internal campaign details shared with Semafor following her victory on Tuesday.
#semafor #began

5 days ago
Altria has raised its dividend 61 times in 57 years and yields ~6%, while Realty Income has raised its payout 115 consecutive quarters and yields ~6%.
Kinder Morgan carries a $9.6 billion project backlog, over 60% tied to power generation, while AT&T uses just 46% of adjusted EPS to fund its dividend.
VICI Properties yields ~7.5% with 100% portfolio occupancy and 39.6-year average lease terms, but its stock trades well below the average **** yst target of $31.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Altria didn't make the cut. Enter your email to see the names that beat MO. The report is free. Enter your email and see if any of your stocks made the cut.
Retirees need two things from a dividend stock: the check must arrive on schedule, and it must grow faster than the cost of groceries. This month's list covers five cash-generating businesses in five different industries: tobacco, net-lease real estate, gaming real estate, natural gas pipelines, and telecom. In every case, earnings or cash flow will cover the payout, and each company has years of payment history behind it. Several of them pay in November, including Realty Income (NYSE:O), whose next monthly dividend of $0.2715 a share is scheduled to arrive on November 13.
#november #raised
Kinder Morgan carries a $9.6 billion project backlog, over 60% tied to power generation, while AT&T uses just 46% of adjusted EPS to fund its dividend.
VICI Properties yields ~7.5% with 100% portfolio occupancy and 39.6-year average lease terms, but its stock trades well below the average **** yst target of $31.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Altria didn't make the cut. Enter your email to see the names that beat MO. The report is free. Enter your email and see if any of your stocks made the cut.
Retirees need two things from a dividend stock: the check must arrive on schedule, and it must grow faster than the cost of groceries. This month's list covers five cash-generating businesses in five different industries: tobacco, net-lease real estate, gaming real estate, natural gas pipelines, and telecom. In every case, earnings or cash flow will cover the payout, and each company has years of payment history behind it. Several of them pay in November, including Realty Income (NYSE:O), whose next monthly dividend of $0.2715 a share is scheduled to arrive on November 13.
#november #raised


29 days ago
Pfizer (NYSE: PFE) is offering a dividend yield of roughly 6% today. That is well above the roughly 1% yield on offer from the S&P 500 index (SNPINDEX: ^GSPC) and the 1.4% average yield of pharmaceutical stocks. There are good reasons for the negative view of Pfizer, but investors may be ignoring the company's over 100-year history of success. Here's why you may want to consider buying this out-of-favor dividend stock while others are fearful.
Pfizer's stock rocketed higher during the coronavirus pandemic, as investors myopically focused on the company's COVID vaccine. When COVID turned out to be a less serious long-term threat than originally believed, Wall Street dumped Pfizer. At this point, the stock is down more than 50% from its 2021 high. That is a big part of the story behind the high yield.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
However, there's another piece that is more fundamental to the pharmaceutical industry. Like all drug makers, Pfizer's drugs receive time-limited patent protections. When patents expire, generic versions of the medications can be produced. That generally leads to a dramatic decline in revenue from Pfizer's drugs. Right now, Pfizer is facing down some notable patent expirations. This is a completely normal dynamic in the pharmaceutical sector.
Patent expirations are why drug companies are always on the lookout for new drugs. The problem is that patent expirations follow a set schedule, but drug development does not. Pfizer's drug pipeline isn't producing major new drugs right now, and it looks like it may have to work through a period in which new drugs won't fully offset revenue lost to patent expirations. This isn't uncommon, either, but investors are likely focusing on the short term rather than the long term when it comes to Pfizer.
#patent #yield #drug #expirations
Pfizer's stock rocketed higher during the coronavirus pandemic, as investors myopically focused on the company's COVID vaccine. When COVID turned out to be a less serious long-term threat than originally believed, Wall Street dumped Pfizer. At this point, the stock is down more than 50% from its 2021 high. That is a big part of the story behind the high yield.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
However, there's another piece that is more fundamental to the pharmaceutical industry. Like all drug makers, Pfizer's drugs receive time-limited patent protections. When patents expire, generic versions of the medications can be produced. That generally leads to a dramatic decline in revenue from Pfizer's drugs. Right now, Pfizer is facing down some notable patent expirations. This is a completely normal dynamic in the pharmaceutical sector.
Patent expirations are why drug companies are always on the lookout for new drugs. The problem is that patent expirations follow a set schedule, but drug development does not. Pfizer's drug pipeline isn't producing major new drugs right now, and it looks like it may have to work through a period in which new drugs won't fully offset revenue lost to patent expirations. This isn't uncommon, either, but investors are likely focusing on the short term rather than the long term when it comes to Pfizer.
#patent #yield #drug #expirations
29 days ago
$100,000 split across MO and ET alone generates roughly $2,548 annually, backed by 60 and 19 consecutive dividend raises respectively.
Verizon's CFO called its 6.1% dividend "ironclad" after free cash flow surged 27% to $6.43 billion in Q2.
Exxon anchors the basket with 43 straight years of dividend growth and a fortress balance sheet carrying just 0.55x net debt-to-EBITDA.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Exxon Mobil didn't make the cut. Enter your email to see the names that beat XOM. The report is free. Enter your email and see if any of your stocks made the cut.
Split $100,000 equally across five blue-chip dividend payers in tobacco, pipelines, telecom, net-lease real estate and integrated oil, and today's yields produce roughly $5,436 in annual income. That works out to about $20,000 per name. Dividend safety depends on more than yield. These companies back their payouts with long records of raises, real cash generation and a balance sheet that can handle a rough patch. That combination is what turns a one-time investment into a durable income stream.
#across #free #cash #balance
Verizon's CFO called its 6.1% dividend "ironclad" after free cash flow surged 27% to $6.43 billion in Q2.
Exxon anchors the basket with 43 straight years of dividend growth and a fortress balance sheet carrying just 0.55x net debt-to-EBITDA.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Exxon Mobil didn't make the cut. Enter your email to see the names that beat XOM. The report is free. Enter your email and see if any of your stocks made the cut.
Split $100,000 equally across five blue-chip dividend payers in tobacco, pipelines, telecom, net-lease real estate and integrated oil, and today's yields produce roughly $5,436 in annual income. That works out to about $20,000 per name. Dividend safety depends on more than yield. These companies back their payouts with long records of raises, real cash generation and a balance sheet that can handle a rough patch. That combination is what turns a one-time investment into a durable income stream.
#across #free #cash #balance

29 days ago
VICI's 8% yield mostly reflects a stock down 25%, while OHI raised its dividend for the first time since 2020 with coverage at 1.65x.
Energy Transfer has raised its distribution 19 consecutive quarters with 2.3x coverage, while AT&T covers its dividend at just 42% of $18B+ free cash flow.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
The 10-year Treasury yield closed at 5.31% as of October 5, 2026, the high of the past month. Any dividend stock has to clear that bar. The five names below try to clear it with cash flow that comes from contracts: decades-long triple-net leases, monthly wireless and fiber bills, and fee-based pipeline volumes. Dividend safety comes first in each entry. A big yield only counts when the payout is covered, the balance sheet can carry it, and the dividend record shows how management acts under pressure.
VICI Properties (NYSE:VICI) offers a forward dividend of $1.84 annualized. At a share price of $22.62, that works out to a very high yield of 8.13%. Most of that yield comes from the share price. The stock is down 24.93% over the past year, 15.28% year to date and 9.32% in the past month alone. Over the same stretch, the dividend rose only slightly. Investors have been marking the stock down on concerns about a shifting gaming landscape and softer Las Vegas travel .
#past #comes
Energy Transfer has raised its distribution 19 consecutive quarters with 2.3x coverage, while AT&T covers its dividend at just 42% of $18B+ free cash flow.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
The 10-year Treasury yield closed at 5.31% as of October 5, 2026, the high of the past month. Any dividend stock has to clear that bar. The five names below try to clear it with cash flow that comes from contracts: decades-long triple-net leases, monthly wireless and fiber bills, and fee-based pipeline volumes. Dividend safety comes first in each entry. A big yield only counts when the payout is covered, the balance sheet can carry it, and the dividend record shows how management acts under pressure.
VICI Properties (NYSE:VICI) offers a forward dividend of $1.84 annualized. At a share price of $22.62, that works out to a very high yield of 8.13%. Most of that yield comes from the share price. The stock is down 24.93% over the past year, 15.28% year to date and 9.32% in the past month alone. Over the same stretch, the dividend rose only slightly. Investors have been marking the stock down on concerns about a shifting gaming landscape and softer Las Vegas travel .
#past #comes


1 month ago
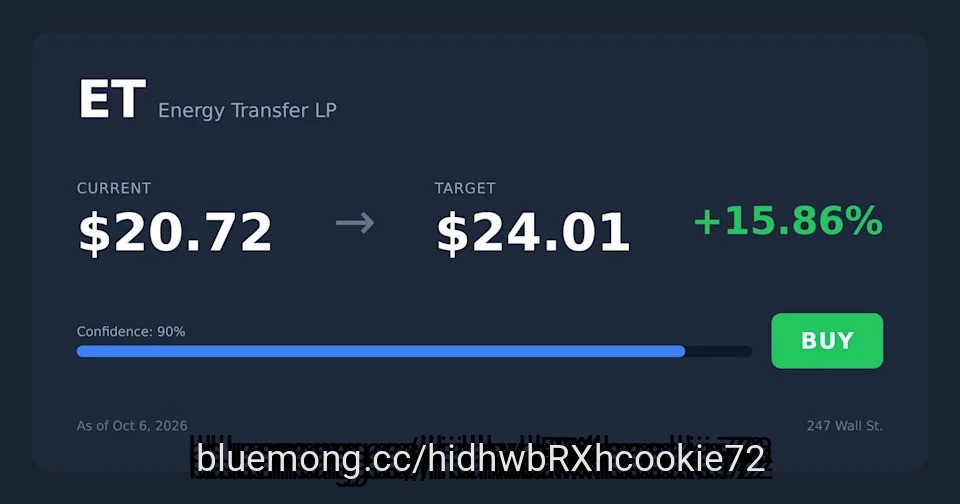
Energy Transfer (NYSE: ET) is one of the largest U.S.-listed master limited partnerships (MLPs) specializing in the ownership of pipelines and other midstream energy ***** ets. Based on current prices, Energy Transfer has a forward distribution yield of 6.64%.
In other words, add up its quarterly cash distributions and divide by the current stock price, and you'll get approximately this figure. Considering this, let's run the numbers and see how many shares of this pipeline stock you'd need to own in order to earn $250 monthly.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Considering the complexities of MLPs and taxation, we will focus on a gross dividend income of $250 per month from an Energy Transfer position, for purposes of our calculation. A monthly payout of $250 comes out to $3,000 per year. Energy Transfer pays $1.36 per share in annual distributions.
Divide $3,000 by $1.36, and you get 2,205 shares, worth around $45,136 based on Energy Transfer's current stock price. From this position, you'd generate around $2,998.80 in dividend income annually, or just under $250 per month.
#transfer #mlps #considering
In other words, add up its quarterly cash distributions and divide by the current stock price, and you'll get approximately this figure. Considering this, let's run the numbers and see how many shares of this pipeline stock you'd need to own in order to earn $250 monthly.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Considering the complexities of MLPs and taxation, we will focus on a gross dividend income of $250 per month from an Energy Transfer position, for purposes of our calculation. A monthly payout of $250 comes out to $3,000 per year. Energy Transfer pays $1.36 per share in annual distributions.
Divide $3,000 by $1.36, and you get 2,205 shares, worth around $45,136 based on Energy Transfer's current stock price. From this position, you'd generate around $2,998.80 in dividend income annually, or just under $250 per month.
#transfer #mlps #considering

1 month ago
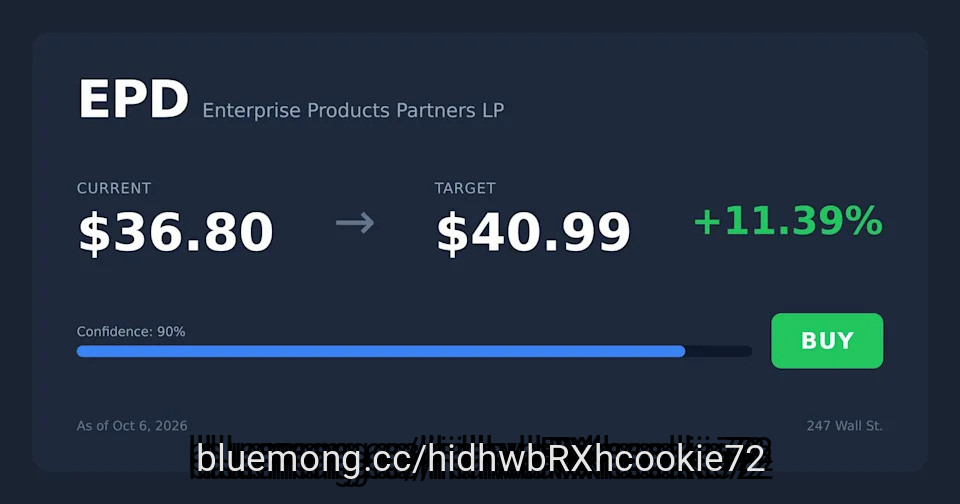
EPD yields 6.19% and ET yields 6.64%, turning a $100,000 equal split into $6,413 in annual passive income.
Energy Transfer cut its distribution 50% in 2020, while Enterprise has grown its payout for 27 consecutive years without a cut.
Energy Transfer is supplying roughly 900 MMcf/d to Oracle-run data centers, making AI power demand a key growth driver.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Energy pays some of the highest yields in the market, and it carries a risk most income sectors avoid: commodity prices. When crude falls, an integrated major can lean on its refining business. A pure producer sees its cash flow rise and fall with oil and gas prices. A midstream operator collects fees on the volumes moving through its pipelines, plants and export docks, so its cash flow holds up better in a downturn.
#energy #income #yields
Energy Transfer cut its distribution 50% in 2020, while Enterprise has grown its payout for 27 consecutive years without a cut.
Energy Transfer is supplying roughly 900 MMcf/d to Oracle-run data centers, making AI power demand a key growth driver.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Energy pays some of the highest yields in the market, and it carries a risk most income sectors avoid: commodity prices. When crude falls, an integrated major can lean on its refining business. A pure producer sees its cash flow rise and fall with oil and gas prices. A midstream operator collects fees on the volumes moving through its pipelines, plants and export docks, so its cash flow holds up better in a downturn.
#energy #income #yields

2 months ago
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral


2 months ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
2 months ago
Americans have paid about $97 billion more for fuel since the Iran war started in late February, roughly $740 extra per household, according to CNN. President Trump says prices will come down after the midterms. The CEO of Chevron just said publicly he does not see how that happens quickly.
Mike Wirth, Chevron's chairman and chief executive, spoke at a University of Texas at Austin energy conference on September 11. He told the audience that the mechanisms that helped absorb the oil supply shock earlier in the conflict have largely been used up, and that prices are more likely to rise than fall over the next few months.
When the U.S.-Iran conflict began, the oil market had several ways to handle the disruption. Countries could release crude from strategic reserves. Commercial inventories could be drawn down. The U.S. eased restrictions on sanctioned crude stored on vessels at sea. Those measures helped limit the initial price spike.
"Those have largely now played out," Wirth said. The energy system no longer has the buffers it had when the war began.
The loss of flexibility became more acute after attacks knocked out a major Saudi crude pipeline that had been bypassing the Strait of Hormuz. That single disruption put an estimated 2.5 million barrels of oil per day in limbo, tightening a market that was already running short on supply.
#crude #prices #energy #conflict
Mike Wirth, Chevron's chairman and chief executive, spoke at a University of Texas at Austin energy conference on September 11. He told the audience that the mechanisms that helped absorb the oil supply shock earlier in the conflict have largely been used up, and that prices are more likely to rise than fall over the next few months.
When the U.S.-Iran conflict began, the oil market had several ways to handle the disruption. Countries could release crude from strategic reserves. Commercial inventories could be drawn down. The U.S. eased restrictions on sanctioned crude stored on vessels at sea. Those measures helped limit the initial price spike.
"Those have largely now played out," Wirth said. The energy system no longer has the buffers it had when the war began.
The loss of flexibility became more acute after attacks knocked out a major Saudi crude pipeline that had been bypassing the Strait of Hormuz. That single disruption put an estimated 2.5 million barrels of oil per day in limbo, tightening a market that was already running short on supply.
#crude #prices #energy #conflict


2 months ago
Targa Resources Corp. (NYSE:TRGP) has significantly outperformed the wider market this year, posting gains of over 56% since the beginning of 2026. A major catalyst behind this growth was the 20-year fee-based agreement that the company signed with ExxonMobil last month.
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda

2 months ago
Enbridge Inc. (NYSE:ENB) has declined by around 17% since hitting its record high in May, likely as a result of rising bond yields, lack of visibility on the company's 5% growth guidance through the end of the decade, and the recently closed equity offering intended to fund the midstream operator's strategic acquisitions.
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target

2 months ago
On September 16, Air Products (NYSE:APD) said it had signed a long-term deal to supply high-purity gases to a leading chipmaker, backed by roughly $250 million of its own money in Arizona. It is the company's second semiconductor supply win, and the two projects together carry more than $900 million of investment. That is a notable turn for a company that has been pulling back from big clean-energy projects.
The Arizona project plays to what Air Products already does. It will build, own, and operate the equipment, from hydrogen generation units and carbon dioxide purification to bulk supply for three gases: helium, hydrogen, and carbon dioxide. That means the customer's gas supply runs through equipment Air Products owns. Supply is targeted to start in phases, so the buildout can move alongside the customer's expansion plans. And this is familiar ground. Air Products has supplied electronics makers for more than 40 years, and its Chandler facility has served the Phoenix chip cluster since 1981, with a pipeline system carrying ultra-high purity nitrogen around the area.
The core business gives the deal a solid floor. In the fiscal third quarter, reported on July 30, adjusted earnings per share rose 12% to $3.47, and management lifted its full-year outlook to an adjusted $13.39 to $13.49 per share. Margins widened as well, so growth is showing up as profit. Chips appear elsewhere in the results too, since the company announced a deal to build four large air separation units to serve a chipmaker's growth in Taiwan.
The cost of the pivot is hard to ignore. On June 30, Air Products announced it would not go ahead with its Louisiana Clean Energy Complex and would discontinue a zero-carbon liquid hydrogen facility in Casa Grande, Arizona, plus other smaller clean energy distribution projects. The exits triggered roughly $2.9 billion in pre-tax charges, which is why the company posted a GAAP loss of $6.47 per share in the third quarter even as its underlying earnings grew. Adjusted results leave that hit out, but the GAAP numbers show what the retreat cost.
Owning the ****** ets also means funding them. Air Products expects about $3.5 billion of capital spending in fiscal 2026, and the Arizona plant alone is a commitment of approximately $250 million, with supply arriving in phases. The release also leaves gaps: it does not name the customer or say how long the contract runs, so the length of the revenue stream is unclear. Elsewhere, Europe's operating income rose only 2% as costs climbed, and management says it is still cautious about the economic backdrop.
#clean #adjusted
The Arizona project plays to what Air Products already does. It will build, own, and operate the equipment, from hydrogen generation units and carbon dioxide purification to bulk supply for three gases: helium, hydrogen, and carbon dioxide. That means the customer's gas supply runs through equipment Air Products owns. Supply is targeted to start in phases, so the buildout can move alongside the customer's expansion plans. And this is familiar ground. Air Products has supplied electronics makers for more than 40 years, and its Chandler facility has served the Phoenix chip cluster since 1981, with a pipeline system carrying ultra-high purity nitrogen around the area.
The core business gives the deal a solid floor. In the fiscal third quarter, reported on July 30, adjusted earnings per share rose 12% to $3.47, and management lifted its full-year outlook to an adjusted $13.39 to $13.49 per share. Margins widened as well, so growth is showing up as profit. Chips appear elsewhere in the results too, since the company announced a deal to build four large air separation units to serve a chipmaker's growth in Taiwan.
The cost of the pivot is hard to ignore. On June 30, Air Products announced it would not go ahead with its Louisiana Clean Energy Complex and would discontinue a zero-carbon liquid hydrogen facility in Casa Grande, Arizona, plus other smaller clean energy distribution projects. The exits triggered roughly $2.9 billion in pre-tax charges, which is why the company posted a GAAP loss of $6.47 per share in the third quarter even as its underlying earnings grew. Adjusted results leave that hit out, but the GAAP numbers show what the retreat cost.
Owning the ****** ets also means funding them. Air Products expects about $3.5 billion of capital spending in fiscal 2026, and the Arizona plant alone is a commitment of approximately $250 million, with supply arriving in phases. The release also leaves gaps: it does not name the customer or say how long the contract runs, so the length of the revenue stream is unclear. Elsewhere, Europe's operating income rose only 2% as costs climbed, and management says it is still cautious about the economic backdrop.
#clean #adjusted


2 months ago
On August 6, Targa Resources Corp. (NYSE:TRGP) reported a record second quarter. Adjusted EBITDA reached $1.60 billion, a 38% jump from the same period a year earlier, and management now expects full-year results near the top of its guidance range. Targa moves and processes natural gas and natural gas liquids out of the Permian Basin, and these numbers suggest that system is running fuller than ever.
The strength came from volume, not just price. Adjusted EBITDA also climbed 14% from the first quarter, helped by Permian gas volumes that added over 450 million cubic feet of daily throughput. Some producers held back output because Waha gas prices went negative, and Targa still set a volume record. Volumes for NGL pipelines, fractionation, and LPG exports also hit records, helped by Train 11, a new fractionator in Mont Belvieu, Texas, that started up early in the quarter.
Construction is also landing on time. East Driver, a new processing plant serving the Midland side of the Permian, started up late in the quarter and ahead of schedule, and the other gathering and logistics projects are tracking their plans. Shareholders get a cut too. On July 16, Targa declared a $1.25 per share quarterly dividend, 25% above the payout for the second quarter of 2025, payable August 14 to holders of record on July 31. It also spent $80 million buying back shares during the quarter.
Growth at this pace costs real money. Targa plans about $4.5 billion in net growth spending this year, and its consolidated debt stood at $19,578 million on June 30. About $3.2 billion of liquidity gives it a cushion. In July, it also extended its receivables securitization facility to July 30, 2027 and raised the size to as much as $800 million. More borrowing capacity helps, but it is still borrowing.
Not every dollar of the profit surge is as steady as a pipeline volume. Management tied the higher outlook partly to strong marketing margin and optimization work in the first two quarters, and the quarter's jump in marketing margin came from greater optimization opportunities. That kind of income can be lumpy. Meanwhile, lower natural gas prices trimmed margins in the gathering business, and the Waha curtailments showed that producers can pull back when local prices turn ugly.
#record
The strength came from volume, not just price. Adjusted EBITDA also climbed 14% from the first quarter, helped by Permian gas volumes that added over 450 million cubic feet of daily throughput. Some producers held back output because Waha gas prices went negative, and Targa still set a volume record. Volumes for NGL pipelines, fractionation, and LPG exports also hit records, helped by Train 11, a new fractionator in Mont Belvieu, Texas, that started up early in the quarter.
Construction is also landing on time. East Driver, a new processing plant serving the Midland side of the Permian, started up late in the quarter and ahead of schedule, and the other gathering and logistics projects are tracking their plans. Shareholders get a cut too. On July 16, Targa declared a $1.25 per share quarterly dividend, 25% above the payout for the second quarter of 2025, payable August 14 to holders of record on July 31. It also spent $80 million buying back shares during the quarter.
Growth at this pace costs real money. Targa plans about $4.5 billion in net growth spending this year, and its consolidated debt stood at $19,578 million on June 30. About $3.2 billion of liquidity gives it a cushion. In July, it also extended its receivables securitization facility to July 30, 2027 and raised the size to as much as $800 million. More borrowing capacity helps, but it is still borrowing.
Not every dollar of the profit surge is as steady as a pipeline volume. Management tied the higher outlook partly to strong marketing margin and optimization work in the first two quarters, and the quarter's jump in marketing margin came from greater optimization opportunities. That kind of income can be lumpy. Meanwhile, lower natural gas prices trimmed margins in the gathering business, and the Waha curtailments showed that producers can pull back when local prices turn ugly.
#record

2 months ago
Interested in Axsome Therapeutics, Inc.? Here are five stocks we like better.
Auvelity remains Axsome's main growth driver: It generated more than $180 million of the company's $218.4 million in second-quarter revenue, while its new Alzheimer's disease agitation indication is supported by an expanded sales force of more than 600 representatives.
The commercial portfolio is expanding: Sunosi continues to grow, and SYMBRAVO revenue increased 30% sequentially in the second quarter as Axsome expanded its migraine sales team.
Pipeline and finances are strengthening: Axsome has several late-stage programs and upcoming clinical milestones, ended the quarter with $320 million in cash, and said it is approaching cash-flow positivity.
Biotech Is Heating Up—These 2 Red-Hot Stocks Stand Out
#second
Auvelity remains Axsome's main growth driver: It generated more than $180 million of the company's $218.4 million in second-quarter revenue, while its new Alzheimer's disease agitation indication is supported by an expanded sales force of more than 600 representatives.
The commercial portfolio is expanding: Sunosi continues to grow, and SYMBRAVO revenue increased 30% sequentially in the second quarter as Axsome expanded its migraine sales team.
Pipeline and finances are strengthening: Axsome has several late-stage programs and upcoming clinical milestones, ended the quarter with $320 million in cash, and said it is approaching cash-flow positivity.
Biotech Is Heating Up—These 2 Red-Hot Stocks Stand Out
#second
2 months ago
On August 19, Ferrovial (NASDAQ:FER) announced it had been selected to deliver the I-24 Southeast Choice Lanes, a 26-mile project running between Nashville and Murfreesboro. It is the largest single capital investment in Tennessee's history and the state's first public-private partnership. The price tag is $9.2 billion, though Ferrovial isn't carrying it alone, since its DriveTN consortium also counts Transurban and Tikehau Star Infra as partners.
Choice lanes are familiar ground for Ferrovial, which has replicated the model in Washington, D.C., Charlotte and Dallas-Fort Worth. On Virginia's 66 Express corridor, similar lanes shaved up to 50% off peak-hour travel times. That is the pitch for I-24, a stretch of highway that already ranks among the region's most jammed: drivers who opt in get steadier speeds, and those in the free lanes should see less traffic too.
The business behind the bid looks healthy, too. Ferrovial's July 28 results showed adjusted EBITDA up 21.6% on a like-for-like basis to €746 million over the first six months of the year, with U.S. highways doing most of the lifting. Those roads are sending cash home as well, since Ferrovial received €357 million in dividends from North America. And the construction order book reached an all-time high of €18 billion, so plenty of work is already in hand. The pipeline keeps filling: Ferrovial bid on I-285 East in Georgia in July, and its D35 Highway bid in the Czech Republic was the most cost-effective submitted, with technical evaluation still underway.
Beyond the roads, the balance sheet looks sturdy. Ferrovial ended the first half with €1.3 billion in net cash, excluding infrastructure projects, meaning cash outweighs debt outside those projects. The airport arm is progressing too: Ferrovial has finished funding the $1.1 billion in equity it pledged for New Terminal One at JFK, and construction there is 92% complete.
Start with the line that looks worst on the page. Net profit for the first half of 2026 came in at €258 million, versus €540 million for the same period of 2025. That earlier figure included capital gains from ******* et rotation, which makes the comparison harsh, but the mismatch is still there: EBITDA climbed while reported profit fell.
#first #million #choice
Choice lanes are familiar ground for Ferrovial, which has replicated the model in Washington, D.C., Charlotte and Dallas-Fort Worth. On Virginia's 66 Express corridor, similar lanes shaved up to 50% off peak-hour travel times. That is the pitch for I-24, a stretch of highway that already ranks among the region's most jammed: drivers who opt in get steadier speeds, and those in the free lanes should see less traffic too.
The business behind the bid looks healthy, too. Ferrovial's July 28 results showed adjusted EBITDA up 21.6% on a like-for-like basis to €746 million over the first six months of the year, with U.S. highways doing most of the lifting. Those roads are sending cash home as well, since Ferrovial received €357 million in dividends from North America. And the construction order book reached an all-time high of €18 billion, so plenty of work is already in hand. The pipeline keeps filling: Ferrovial bid on I-285 East in Georgia in July, and its D35 Highway bid in the Czech Republic was the most cost-effective submitted, with technical evaluation still underway.
Beyond the roads, the balance sheet looks sturdy. Ferrovial ended the first half with €1.3 billion in net cash, excluding infrastructure projects, meaning cash outweighs debt outside those projects. The airport arm is progressing too: Ferrovial has finished funding the $1.1 billion in equity it pledged for New Terminal One at JFK, and construction there is 92% complete.
Start with the line that looks worst on the page. Net profit for the first half of 2026 came in at €258 million, versus €540 million for the same period of 2025. That earlier figure included capital gains from ******* et rotation, which makes the comparison harsh, but the mismatch is still there: EBITDA climbed while reported profit fell.
#first #million #choice


2 months ago
On August 10, Ferguson Enterprises Inc. (NYSE:FERG) reported results for the quarter ended June 30, and the numbers show a company growing straight through a soft housing market. Sales rose 4.6% to $8.8 billion, and management lifted its outlook for the full year. But profit grew more slowly than sales, and that gap is what makes this report worth a closer look.
The strongest engine was non-residential work, where US revenue jumped 8% on share gains in what management called a mixed market. Large capital projects are part of the story, with open order volumes growing and bidding activity strong, so there is a pipeline behind the current numbers. Housing, roughly half of revenue, is the weak spot. Yet residential sales still rose 2% in the US even though new construction is weak and repair work is soft, which means Ferguson is beating its markets rather than riding them.
Capital deployment is the second pillar. Ferguson closed five acquisitions in the quarter, and on July 13, it announced a deal for FWI Holdings, known as FloWorks, an industrial distributor of valves and flow-control products that is expected to close in the third quarter. The eight deals announced this year carry about $1.4 billion in annualized revenue, a second growth path alongside organic sales. Net debt sits at 1.3 times adjusted EBITDA, a level management calls strong. The company also returned cash, buying back $202 million of stock in the quarter and declaring a $0.89 dividend payable October 7 to holders of record on August 21. Management raised its full-year sales outlook to mid-single-digit growth, before counting FloWorks.
Start with the gap between sales and profit. Adjusted operating profit rose 2.9%, behind the 4.6% sales gain, and gross margin slipped 20 basis points to 31.0%. Ferguson notes that last year's gross margin was temporarily lifted by the timing of supplier price increases, which is fair context, but the direction is still down. Reported earnings per share of $3.43 rose 6.9%, while the adjusted figure of $3.39 grew a slower 5.3%.
Then there are the soft spots. About half of revenue comes from residential markets that management describes as subdued, so a 2% gain there is modest. Canada's sales slipped 1.9%, with a business divestment outweighing organic growth, and management calls the market there challenging, especially in residential. Management also describes the economic environment as uncertain, and the margin part of the guidance raise is small. The low end of the adjusted operating margin range moved from 9.4% to 9.5%, while the top stayed at 9.8%. The guidance also leaves out FloWorks, and net debt to adjusted EBITDA is 1.3 times, against 1.2 times a year ago.
#management
The strongest engine was non-residential work, where US revenue jumped 8% on share gains in what management called a mixed market. Large capital projects are part of the story, with open order volumes growing and bidding activity strong, so there is a pipeline behind the current numbers. Housing, roughly half of revenue, is the weak spot. Yet residential sales still rose 2% in the US even though new construction is weak and repair work is soft, which means Ferguson is beating its markets rather than riding them.
Capital deployment is the second pillar. Ferguson closed five acquisitions in the quarter, and on July 13, it announced a deal for FWI Holdings, known as FloWorks, an industrial distributor of valves and flow-control products that is expected to close in the third quarter. The eight deals announced this year carry about $1.4 billion in annualized revenue, a second growth path alongside organic sales. Net debt sits at 1.3 times adjusted EBITDA, a level management calls strong. The company also returned cash, buying back $202 million of stock in the quarter and declaring a $0.89 dividend payable October 7 to holders of record on August 21. Management raised its full-year sales outlook to mid-single-digit growth, before counting FloWorks.
Start with the gap between sales and profit. Adjusted operating profit rose 2.9%, behind the 4.6% sales gain, and gross margin slipped 20 basis points to 31.0%. Ferguson notes that last year's gross margin was temporarily lifted by the timing of supplier price increases, which is fair context, but the direction is still down. Reported earnings per share of $3.43 rose 6.9%, while the adjusted figure of $3.39 grew a slower 5.3%.
Then there are the soft spots. About half of revenue comes from residential markets that management describes as subdued, so a 2% gain there is modest. Canada's sales slipped 1.9%, with a business divestment outweighing organic growth, and management calls the market there challenging, especially in residential. Management also describes the economic environment as uncertain, and the margin part of the guidance raise is small. The low end of the adjusted operating margin range moved from 9.4% to 9.5%, while the top stayed at 9.8%. The guidance also leaves out FloWorks, and net debt to adjusted EBITDA is 1.3 times, against 1.2 times a year ago.
#management
2 months ago
If you are looking for reliable high yields in the energy sector, Energy Transfer (NYSE: ET) is likely to be high up on the list of options. And Wall Street really likes the stock, with 19 of the 21 ***** ysts covering it rating it a buy or strong buy. And yet, I just can't get myself to buy it, instead owning lower-yielding Enbridge (NYSE: ENB). Here's why Energy Transfer's 6.3% yield, despite distribution coverage of 2.2x, isn't enough to get me to buy it.
Before getting to Energy Transfer, I want to highlight some facts about Enbridge, the North American pipeline giant I actually bought. For starters, Enbridge's yield is 5.8%, roughly half a percentage point lower. That's a big difference, as buying Energy Transfer would increase my income stream by nearly 9%.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
I can totally understand where a dividend investor would buy Energy Transfer for the added yield. But there's a big difference when you consider dividend history. Enbridge has increased its dividend annually for 31 consecutive years. Energy Transfer cut its distribution in 2020 during the COVID pandemic, right when most investors would probably have preferred dividend consistency. To Energy Transfer's credit, it lived up to its promise at the time to reduce leverage and return to distribution growth. In fact, the distribution is now above its level prior to the cut. And the cut was probably the right decision to make for the business.
But that distribution cut was a hit for unitholders. And it comes after another questionable situation back during the 1996 energy market downturn. At that point, Energy Transfer agreed to buy peer Williams (NYSE: WMB), but got cold feet. In an effort to scuttle the deal, Energy Transfer issued convertibles that appeared to protect insiders from a dividend cut, if one were made. The Williams deal was canceled, and the convertibles never became an issue, but it raised material trust issues for me.
#distribution #Dividend #yield
Before getting to Energy Transfer, I want to highlight some facts about Enbridge, the North American pipeline giant I actually bought. For starters, Enbridge's yield is 5.8%, roughly half a percentage point lower. That's a big difference, as buying Energy Transfer would increase my income stream by nearly 9%.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
I can totally understand where a dividend investor would buy Energy Transfer for the added yield. But there's a big difference when you consider dividend history. Enbridge has increased its dividend annually for 31 consecutive years. Energy Transfer cut its distribution in 2020 during the COVID pandemic, right when most investors would probably have preferred dividend consistency. To Energy Transfer's credit, it lived up to its promise at the time to reduce leverage and return to distribution growth. In fact, the distribution is now above its level prior to the cut. And the cut was probably the right decision to make for the business.
But that distribution cut was a hit for unitholders. And it comes after another questionable situation back during the 1996 energy market downturn. At that point, Energy Transfer agreed to buy peer Williams (NYSE: WMB), but got cold feet. In an effort to scuttle the deal, Energy Transfer issued convertibles that appeared to protect insiders from a dividend cut, if one were made. The Williams deal was canceled, and the convertibles never became an issue, but it raised material trust issues for me.
#distribution #Dividend #yield

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Silver (SI=F) December futures opened at $65.76 per ounce on Friday, September 18, 2026, down 0.5% from Thursday's close but more than $2 higher than yesterday's opening price. Silver prices surged this morning, reaching $67.47 as of 7:05 a.m. ET.
Until today, silver prices bounced around the $63 to $64 range, but broke out of those bookends by a wide margin this morning. Today's opening price set the highest opening price of the week, and silver is surging this morning, hitting a high of $67.89.
The Fed's decision to raise rates for the first time in three years, combined with the ongoing restoration of Saudi Arabia's key East-West pipeline, has prompted inflation concerns to fade among investors.
And oil prices are responding as well. Wednesday morning, Brent crude (BZ=F) prices were over $107 a barrel. Yesterday at this time, prices were at over $99 a barrel, and this morning, they're $98.51 as of 7:05 a.m. ET.
#disclosure
Silver (SI=F) December futures opened at $65.76 per ounce on Friday, September 18, 2026, down 0.5% from Thursday's close but more than $2 higher than yesterday's opening price. Silver prices surged this morning, reaching $67.47 as of 7:05 a.m. ET.
Until today, silver prices bounced around the $63 to $64 range, but broke out of those bookends by a wide margin this morning. Today's opening price set the highest opening price of the week, and silver is surging this morning, hitting a high of $67.89.
The Fed's decision to raise rates for the first time in three years, combined with the ongoing restoration of Saudi Arabia's key East-West pipeline, has prompted inflation concerns to fade among investors.
And oil prices are responding as well. Wednesday morning, Brent crude (BZ=F) prices were over $107 a barrel. Yesterday at this time, prices were at over $99 a barrel, and this morning, they're $98.51 as of 7:05 a.m. ET.
#disclosure



2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Gold (GC=F) December futures opened at $4,381.60 per troy ounce on Friday, September 18, 2026, down 0.4% from Thursday's closing price. Gold is moving upward this morning at $4,421.40 per troy ounce as of 6:46 a.m. ET.
Gold prices have held in the $4,300 range since last Friday, but this morning they broke above $4,400, hitting a weekly high of $4,439.80.
The Fed's decision to raise rates for the first time in three years, combined with the ongoing restoration of Saudi Arabia's key East-West pipeline, has prompted inflation concerns to fade among investors.
Oil prices continue to move lower as a result. On Wednesday at this time, Brent crude (BZ=F) prices were over $107 a barrel. Yesterday morning, prices were at over $99 a barrel, and this morning, they're $98.46 as of 6:39 a.m. ET.
#morning #prices #ounce #barrel
Gold (GC=F) December futures opened at $4,381.60 per troy ounce on Friday, September 18, 2026, down 0.4% from Thursday's closing price. Gold is moving upward this morning at $4,421.40 per troy ounce as of 6:46 a.m. ET.
Gold prices have held in the $4,300 range since last Friday, but this morning they broke above $4,400, hitting a weekly high of $4,439.80.
The Fed's decision to raise rates for the first time in three years, combined with the ongoing restoration of Saudi Arabia's key East-West pipeline, has prompted inflation concerns to fade among investors.
Oil prices continue to move lower as a result. On Wednesday at this time, Brent crude (BZ=F) prices were over $107 a barrel. Yesterday morning, prices were at over $99 a barrel, and this morning, they're $98.46 as of 6:39 a.m. ET.
#morning #prices #ounce #barrel



2 months ago
On August 6, APA Corporation (NASDAQ:APA) held its second-quarter earnings call, and one number stood out from the rest. The oil and gas producer is now holding its Permian oil production steady with four drilling rigs, half the eight it once estimated it would need. Adjusted production of 347,000 barrels of oil equivalent per day beat management's own guidance, free cash flow kept climbing, and the balance sheet is healing faster than planned. That combination is the story of the quarter.
APA raised its full-year US oil guidance to 123,000 barrels per day, up from an original 120,000, while holding its capital budget at $1.3 billion despite higher diesel and other input costs. Management also lifted its cost-savings target to $500 million in annualized run-rate savings by year-end, up from the $450 million goal it set at the start of the year.
That flexibility is showing up in cash flow. Free cash flow hit $738 million in the second quarter, pushing the first half of 2026 past $1.2 billion, which topped what APA generated in each of the past three full years. The company returned $189 million of that to shareholders through dividends and the repurchase of 2.8 million shares at an average price of $35.26, continuing a streak of returning at least 60% of free cash flow to investors every year since 2021.
The balance sheet is moving just as fast. Net debt stood at $3.3 billion at quarter-end after APA repaid $752 million of bonds in the first half, including $673 million in the second quarter alone, cutting total debt by $2.3 billion since the end of 2024 and lowering annualized interest expense by roughly $175 million. Management now expects to hit its $3 billion net debt target in 2027, well ahead of the three- to four-year window it laid out when the goal was first announced.
Further out, APA is building option value beyond its core Permian and Egypt ****** ets. It agreed to acquire Savant Alaska for $70 million, picking up an airstrip, a dock, and a pipeline connection into the Trans Alaska system to support two exploration wells planned for 2027. In Uruguay, ENI signed on as a partner in Block 6, funding a significant share of the first exploration well while APA keeps 60% ownership. In Suriname, the GranMorgu project remains on budget for first oil in mid-2028.
#billion
APA raised its full-year US oil guidance to 123,000 barrels per day, up from an original 120,000, while holding its capital budget at $1.3 billion despite higher diesel and other input costs. Management also lifted its cost-savings target to $500 million in annualized run-rate savings by year-end, up from the $450 million goal it set at the start of the year.
That flexibility is showing up in cash flow. Free cash flow hit $738 million in the second quarter, pushing the first half of 2026 past $1.2 billion, which topped what APA generated in each of the past three full years. The company returned $189 million of that to shareholders through dividends and the repurchase of 2.8 million shares at an average price of $35.26, continuing a streak of returning at least 60% of free cash flow to investors every year since 2021.
The balance sheet is moving just as fast. Net debt stood at $3.3 billion at quarter-end after APA repaid $752 million of bonds in the first half, including $673 million in the second quarter alone, cutting total debt by $2.3 billion since the end of 2024 and lowering annualized interest expense by roughly $175 million. Management now expects to hit its $3 billion net debt target in 2027, well ahead of the three- to four-year window it laid out when the goal was first announced.
Further out, APA is building option value beyond its core Permian and Egypt ****** ets. It agreed to acquire Savant Alaska for $70 million, picking up an airstrip, a dock, and a pipeline connection into the Trans Alaska system to support two exploration wells planned for 2027. In Uruguay, ENI signed on as a partner in Block 6, funding a significant share of the first exploration well while APA keeps 60% ownership. In Suriname, the GranMorgu project remains on budget for first oil in mid-2028.
#billion

2 months ago
On September 15, Jazz Pharmaceuticals plc (NASDAQ:JAZZ) completed its acquisition of privately held Actio Biosciences for $820 million upfront, adding a clinical-stage epilepsy drug called ABS-1230 to its rare disease pipeline. The deal lands weeks after Jazz posted its highest quarterly revenue ever on August 3, and raised its full-year guidance, so a fresh acquisition now sits on top of a business that was already accelerating. The question for investors is whether that combination adds up to durable growth or just a bigger bill.
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta


2 months ago
On September 8, 2026, CNBC reported that Novartis AG (NYSE:NVS) shares fell about 10% after the company said its experimental drug del-desiran failed to meet its primary goal in a late-stage trial for myotonic dystrophy type 1.
It marked the company's third clinical setback in a week following the earlier failure of cardiovascular drug pelacarsen and a separate pause of eight trials of cell therapy rap-cel after three patient deaths. The decline erased roughly 24 billion Swiss francs, or about $29.6 billion, in market value and put Novartis on pace for one of its worst trading days in company history.
Remibrutinib provides a major remaining pipeline catalyst since Novartis AG (NYSE:NVS) reported successful late-stage results for remibrutinib in multiple sclerosis. It gives investors a credible growth driver after the failures of pelacarsen and del-desiran. The business expects more remibrutinib data later this year, making the drug an important test of whether its remaining pipeline can help long-term growth.
Novartis still expects 5% to 6% annual sales growth through 2030. Management reaffirmed its full-year financial guidance and maintained its target for 5% to 6% compound annual sales growth from 2025 through 2030. That guidance shows the company still expects its overall portfolio and remaining pipeline ******* ets to offset pressure from aging drugs.
The company retains a diversified commercial portfolio. The del-desiran failure removes a potentially important future revenue contributor, but Novartis still makes substantial revenue from its existing medicines. It also retains other pipeline ******* ets. That diversification gives the firm financial capacity to absorb individual clinical failures while it rebuilds investor confidence in its growth pipeline.
#company #remibrutinib
It marked the company's third clinical setback in a week following the earlier failure of cardiovascular drug pelacarsen and a separate pause of eight trials of cell therapy rap-cel after three patient deaths. The decline erased roughly 24 billion Swiss francs, or about $29.6 billion, in market value and put Novartis on pace for one of its worst trading days in company history.
Remibrutinib provides a major remaining pipeline catalyst since Novartis AG (NYSE:NVS) reported successful late-stage results for remibrutinib in multiple sclerosis. It gives investors a credible growth driver after the failures of pelacarsen and del-desiran. The business expects more remibrutinib data later this year, making the drug an important test of whether its remaining pipeline can help long-term growth.
Novartis still expects 5% to 6% annual sales growth through 2030. Management reaffirmed its full-year financial guidance and maintained its target for 5% to 6% compound annual sales growth from 2025 through 2030. That guidance shows the company still expects its overall portfolio and remaining pipeline ******* ets to offset pressure from aging drugs.
The company retains a diversified commercial portfolio. The del-desiran failure removes a potentially important future revenue contributor, but Novartis still makes substantial revenue from its existing medicines. It also retains other pipeline ******* ets. That diversification gives the firm financial capacity to absorb individual clinical failures while it rebuilds investor confidence in its growth pipeline.
#company #remibrutinib
2 months ago
The temporary closure of the key onshore pipeline Saudi Arabia uses to bypass the Strait of Hormuz has added another shock to an oil market already struggling with six months of Middle East supply disruptions.
And the damage now appears to be more extensive than initially believed.
Three pumping stations along Saudi Arabia's East-West pipeline were damaged in last week's attack, Reuters reported on Thursday, citing satellite imagery and industry sources. Earlier ***** sments had identified damage at two stations. Three sources told Reuters that repairs could take five to six weeks, although partial pumping could resume sooner.
Before the attack, the system was moving between 4 million and 5 million barrels per day (bpd), equivalent to roughly 4%–5% of global oil supply. Its total capacity is around 7 million bpd, including approximately 2 million bpd supplied to refineries.
Saudi Arabia shut the pipeline following multiple attacks on September 10. Satellite imagery previously published by MizarVision showed extensive fire and structural damage around pumping stations along the route.
#million #pumping #arabia
And the damage now appears to be more extensive than initially believed.
Three pumping stations along Saudi Arabia's East-West pipeline were damaged in last week's attack, Reuters reported on Thursday, citing satellite imagery and industry sources. Earlier ***** sments had identified damage at two stations. Three sources told Reuters that repairs could take five to six weeks, although partial pumping could resume sooner.
Before the attack, the system was moving between 4 million and 5 million barrels per day (bpd), equivalent to roughly 4%–5% of global oil supply. Its total capacity is around 7 million bpd, including approximately 2 million bpd supplied to refineries.
Saudi Arabia shut the pipeline following multiple attacks on September 10. Satellite imagery previously published by MizarVision showed extensive fire and structural damage around pumping stations along the route.
#million #pumping #arabia
2 months ago
US stocks rebounded on Thursday as oil prices edged lower and a Fed rate hike on Wednesday offered some relief that the central bank was working to contain inflation.
The Dow Jones Industrial Average (^DJI) rose 0.6%, while the S&P 500 (^GSPC) climbed 1.1%. The tech-heavy Nasdaq Composite (^IXIC) jumped 1.7%, rebounding from a post-Fed-hike slump on Wednesday.
Stocks recovered as investors **** sed Federal Reserve Chairman Kevin Warsh's hawkish rhetoric, which **** ysts said helped restore the Fed's credibility on inflation. On Wednesday, the Federal Reserve raised interest rates by 25 basis points for the first time in three years and projected one more rate hike this year.
The decision drew the ire of President Trump, who called for lower interest rates and said he had spoken with Warsh ahead of the FOMC meeting. "You might as well vote with the board because it's not going to matter," Trump said he told Warsh.
Oil prices, meanwhile, ticked lower as US Energy Secretary Chris Wright said Saudi Arabia's East-West pipeline, which has become a key alternative route for oil stuck in the Strait of Hormuz, would be restored soon. Brent crude (BZ=F), the global benchmark, changed hands at $104 per barrel.
#reserve #Trump
The Dow Jones Industrial Average (^DJI) rose 0.6%, while the S&P 500 (^GSPC) climbed 1.1%. The tech-heavy Nasdaq Composite (^IXIC) jumped 1.7%, rebounding from a post-Fed-hike slump on Wednesday.
Stocks recovered as investors **** sed Federal Reserve Chairman Kevin Warsh's hawkish rhetoric, which **** ysts said helped restore the Fed's credibility on inflation. On Wednesday, the Federal Reserve raised interest rates by 25 basis points for the first time in three years and projected one more rate hike this year.
The decision drew the ire of President Trump, who called for lower interest rates and said he had spoken with Warsh ahead of the FOMC meeting. "You might as well vote with the board because it's not going to matter," Trump said he told Warsh.
Oil prices, meanwhile, ticked lower as US Energy Secretary Chris Wright said Saudi Arabia's East-West pipeline, which has become a key alternative route for oil stuck in the Strait of Hormuz, would be restored soon. Brent crude (BZ=F), the global benchmark, changed hands at $104 per barrel.
#reserve #Trump
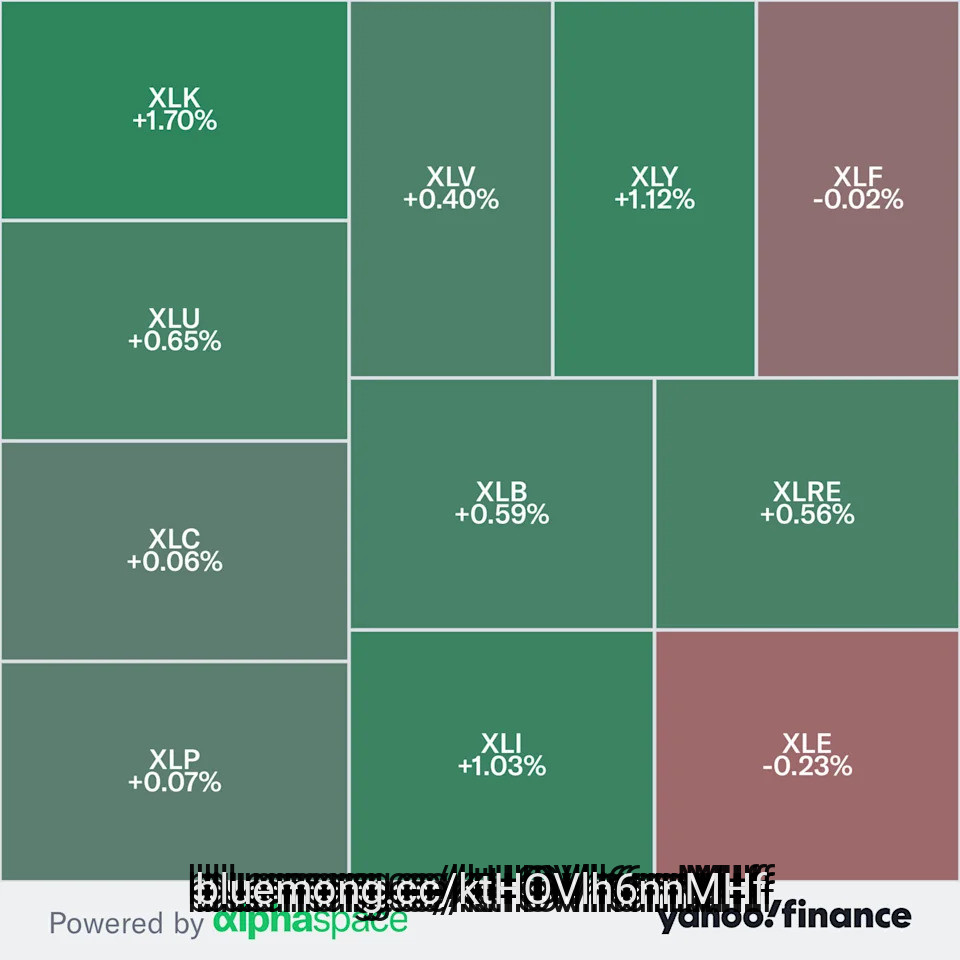

2 months ago
Elon Musk's ***** eX has been talking, internally, about buying the leftover customer files of startups that already went under. Not licensing data from companies that are still operating and can say no. Buying the digital estate of companies that no longer exist to say anything at all.
The discussions are happening inside ***** eXAI, the artificial intelligence division born in February when ***** eX merged with xAI. People familiar with the talks told Bloomberg they're informal and might go nowhere. But the idea makes sense from the perspective of an AI lab racing for the frontier.
The goal is basically cheap fuel for Grok. AI models learn from training data—the text, code, and records an algorithm studies to get better at predicting what comes next—and the good stuff, real business records instead of scraped web pages, is getting expensive. A dead company's file cabinet is apparently a bargain by comparison.
Google already did the same. The search giant paid $10 million in a bankruptcy auction for the internal records of Spirit Airlines, the discount carrier that shut down for good this year. They got around 100 million emails, 500 million Microsoft Teams messages, decades of employee files, all headed into an AI training pipeline.
That data belonged to real employees who signed up for a job, not an AI experiment. A flight attendants' union objected in bankruptcy court, arguing that scrubbing names off records—what companies call "de-identifying" data—doesn't stop someone from piecing together who said what in a decade of internal chats. The court fight is still ongoing.
#million #buying #still #training
The discussions are happening inside ***** eXAI, the artificial intelligence division born in February when ***** eX merged with xAI. People familiar with the talks told Bloomberg they're informal and might go nowhere. But the idea makes sense from the perspective of an AI lab racing for the frontier.
The goal is basically cheap fuel for Grok. AI models learn from training data—the text, code, and records an algorithm studies to get better at predicting what comes next—and the good stuff, real business records instead of scraped web pages, is getting expensive. A dead company's file cabinet is apparently a bargain by comparison.
Google already did the same. The search giant paid $10 million in a bankruptcy auction for the internal records of Spirit Airlines, the discount carrier that shut down for good this year. They got around 100 million emails, 500 million Microsoft Teams messages, decades of employee files, all headed into an AI training pipeline.
That data belonged to real employees who signed up for a job, not an AI experiment. A flight attendants' union objected in bankruptcy court, arguing that scrubbing names off records—what companies call "de-identifying" data—doesn't stop someone from piecing together who said what in a decade of internal chats. The court fight is still ongoing.
#million #buying #still #training
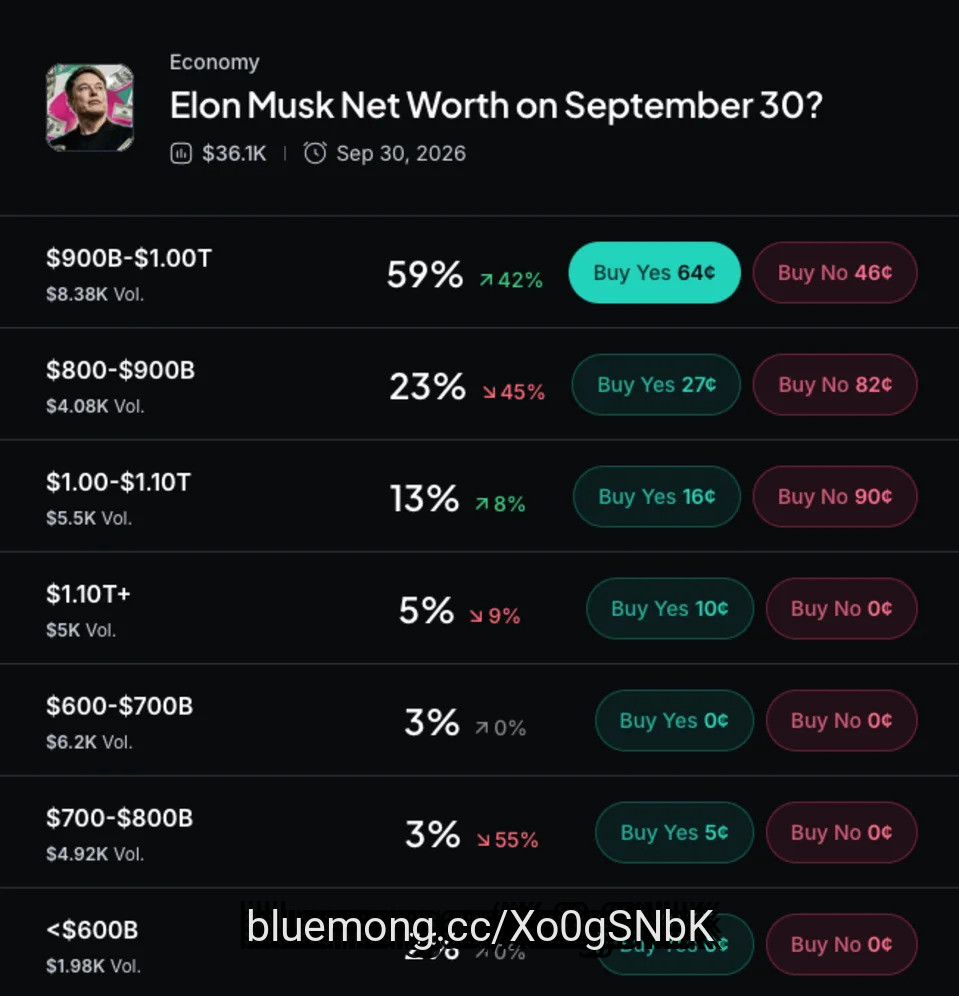
2 months ago
Become a CEO after your MBA: that's the promise some private equity firms are using to recruit top operating talent.
This promise propels the best and brightest into top executive roles without requiring them to climb the corporate ladder, underpinned by the belief that cultivating talent is a better bet than making semi-blind bets on external hires.
Alpine Investors and Shore Capital Partners have each built separate pipelines to funnel operational talent, aiming to equip executives to take charge of their portfolio companies.
Lower-middle-market buyout firm Shore Capital Partners runs what it calls its CXO program, a two-year training scheme that places early- to mid-career talent and recent MBA grads into C-suite-adjacent roles at its portfolio companies—typically chief of staff or vice president of business operations or strategic initiatives.
Top-performing CXO graduates then have the chance to be promoted to C-level positions. So far, Shore has produced four CEOs from the CXO program. This includes Mark Larsen, who has been CEO of medical software business Connexure since 2024.
#Companies
This promise propels the best and brightest into top executive roles without requiring them to climb the corporate ladder, underpinned by the belief that cultivating talent is a better bet than making semi-blind bets on external hires.
Alpine Investors and Shore Capital Partners have each built separate pipelines to funnel operational talent, aiming to equip executives to take charge of their portfolio companies.
Lower-middle-market buyout firm Shore Capital Partners runs what it calls its CXO program, a two-year training scheme that places early- to mid-career talent and recent MBA grads into C-suite-adjacent roles at its portfolio companies—typically chief of staff or vice president of business operations or strategic initiatives.
Top-performing CXO graduates then have the chance to be promoted to C-level positions. So far, Shore has produced four CEOs from the CXO program. This includes Mark Larsen, who has been CEO of medical software business Connexure since 2024.
#Companies


2 months ago
Comments from Anthropic CEO Dario Amodei and OpenAI CEO Sam Altman calling for a more measured approach to frontier AI development contributed to a sharp selloff across neoclouds and data center stocks. Bernstein identified CoreWeave Inc. (NASDAQ:CRWV) as the most exposed name because of its rural footprint and focus on AI training. The concern represents a genuine structural argument. However, it marks the second time this year that the same group of stocks has faced concerns over the sustainability of AI demand. There is also an important tension within Bernstein's own note, which highlights CoreWeave's exposure while acknowledging that most of its backlog remains shielded by contracts.
Bernstein cautioned that a slowdown in AI training could weigh on data center developers. The warning followed Amodei's weekend comments urging the industry to deliberately slow the pace of frontier AI capability gains, along with similar remarks from Sam Altman. According to ****** yst Madison Rezaei, slower training activity would likely reduce demand for rural data center sites designed for latency-insensitive workloads. The ****** yst pointed out that rural and Tier 3 markets account for 70% of the industry's 488GW pipeline. CoreWeave was identified as the most exposed name in the firm's coverage. ****** yst Madison Rezaei remarked:
We estimate that 25% of their existing active U.S. power, with an additional ~74% of their contracted power, is situated in Tier 3 and Tier 4 markets.
However, there is a key counterpoint within Bernstein's own note:
The backlog is primarily comprised of take-or-pay contracts, so we do not anticipate a threat there but could see a pullback in demand for the contracted-not-yet-sold rural power if training development slows.
#training #analyst
Bernstein cautioned that a slowdown in AI training could weigh on data center developers. The warning followed Amodei's weekend comments urging the industry to deliberately slow the pace of frontier AI capability gains, along with similar remarks from Sam Altman. According to ****** yst Madison Rezaei, slower training activity would likely reduce demand for rural data center sites designed for latency-insensitive workloads. The ****** yst pointed out that rural and Tier 3 markets account for 70% of the industry's 488GW pipeline. CoreWeave was identified as the most exposed name in the firm's coverage. ****** yst Madison Rezaei remarked:
We estimate that 25% of their existing active U.S. power, with an additional ~74% of their contracted power, is situated in Tier 3 and Tier 4 markets.
However, there is a key counterpoint within Bernstein's own note:
The backlog is primarily comprised of take-or-pay contracts, so we do not anticipate a threat there but could see a pullback in demand for the contracted-not-yet-sold rural power if training development slows.
#training #analyst

2 months ago
Space Exploration Technologies Corp. (NASDAQ:SPCX) is increasingly confident it can reach a $100 billion annual revenue run rate by year-end. The company's CFO said there is now "even more conviction" around the target. A new AI hosting agreement worth $13 billion on an annualized basis adds significant support to that outlook and reflects how quickly ***** eX's compute business is scaling. But the financial picture behind that growth is less straightforward. The same AI division that management is relying on to help reach that target posted a $1.3 billion loss in the latest quarter alone. The loss wiped out what would have otherwise been a profitable quarter, while the company generated roughly negative $25 billion in free cash flow during the first half of 2026.
CFO Bret Johnsen said ***** eX has "even more conviction" that it can reach a $100 billion annual revenue run rate. The outlook is supported by a newly signed AI hosting agreement worth $1.11 billion per month beginning in December, or roughly $13 billion on an annualized basis. The company plans to end the year with a little over 2 gigawatts of terrestrial AI-computing capacity and scale to between 5 and 10 gigawatts in 2027. Orbital computing remains a longer-term option for overcoming power constraints. Its current agreements include a $6.7 billion cloud-services contract that is scheduled to ramp up in October. Existing arrangements with Google and Anthropic are worth more than $2 billion per month combined. Reaching the $100 billion target would require monthly revenue to more than triple from second-quarter's pace.
SpaceX's rocket and Starlink businesses generated roughly $1.1 billion in combined operating income in the second quarter. But the AI division's $1.3 billion loss more than wiped out that profit. The company also generated roughly negative $25 billion in free cash flow during the first half of 2026. The stock declined more than 5% after the second-quarter results despite a revenue beat.
The AI contract pipeline is clearly expanding and gaining momentum. However, the $100 billion target is a revenue run-rate measure rather than a profitability target. At the same time, the division driving this expansion remains the company's largest contributor to both both operating losses and capital spending, making the growth opportunity financially costly for now.
SpaceX had 119 hedge funds among its institutional holders at the end of the second quarter of fiscal 2026. Meanwhile, short interest stood at just 2.76% of float as of August 31, 2026. The ownership and the short interest figures show that institutional sentiment remains broadly constructive and toward the company's long-term outlook.
#roughly
CFO Bret Johnsen said ***** eX has "even more conviction" that it can reach a $100 billion annual revenue run rate. The outlook is supported by a newly signed AI hosting agreement worth $1.11 billion per month beginning in December, or roughly $13 billion on an annualized basis. The company plans to end the year with a little over 2 gigawatts of terrestrial AI-computing capacity and scale to between 5 and 10 gigawatts in 2027. Orbital computing remains a longer-term option for overcoming power constraints. Its current agreements include a $6.7 billion cloud-services contract that is scheduled to ramp up in October. Existing arrangements with Google and Anthropic are worth more than $2 billion per month combined. Reaching the $100 billion target would require monthly revenue to more than triple from second-quarter's pace.
SpaceX's rocket and Starlink businesses generated roughly $1.1 billion in combined operating income in the second quarter. But the AI division's $1.3 billion loss more than wiped out that profit. The company also generated roughly negative $25 billion in free cash flow during the first half of 2026. The stock declined more than 5% after the second-quarter results despite a revenue beat.
The AI contract pipeline is clearly expanding and gaining momentum. However, the $100 billion target is a revenue run-rate measure rather than a profitability target. At the same time, the division driving this expansion remains the company's largest contributor to both both operating losses and capital spending, making the growth opportunity financially costly for now.
SpaceX had 119 hedge funds among its institutional holders at the end of the second quarter of fiscal 2026. Meanwhile, short interest stood at just 2.76% of float as of August 31, 2026. The ownership and the short interest figures show that institutional sentiment remains broadly constructive and toward the company's long-term outlook.
#roughly


2 months ago
Democrats' wary optimism about the midterms gave way to growing confidence this week.
The party has seen strong post-Labor Day polls in key battlegrounds - and even in traditionally red areas. Recent escalations in the war in Iran, including an attack on a major pipeline in Saudi Arabia, mean the rising gas prices bedeviling Republicans will not be going down anytime soon. Republicans have not been able to bring prices under control more generally. And President Donald Trump's unpopularity is at near-record levels.
Subscribe to The Post Most newsletter for the most important and interesting stories from The Washington Post.
Considering all this, Democrats now think conditions are right for the party to retake control of the House and possibly the Senate later this year.
"If the election were held today, we would win the majority," Senate Minority Leader Chuck Schumer (New York) said in an interview with The Washington Post.
#labor
The party has seen strong post-Labor Day polls in key battlegrounds - and even in traditionally red areas. Recent escalations in the war in Iran, including an attack on a major pipeline in Saudi Arabia, mean the rising gas prices bedeviling Republicans will not be going down anytime soon. Republicans have not been able to bring prices under control more generally. And President Donald Trump's unpopularity is at near-record levels.
Subscribe to The Post Most newsletter for the most important and interesting stories from The Washington Post.
Considering all this, Democrats now think conditions are right for the party to retake control of the House and possibly the Senate later this year.
"If the election were held today, we would win the majority," Senate Minority Leader Chuck Schumer (New York) said in an interview with The Washington Post.
#labor


