

19 hours ago
Ramsey warns that depreciating ****** ets like cars erode wealth, and 84% of millionaires credited ditching car payments as key to building it.
A $30,000 car loses roughly $18,000 in value within five years, and average annual ownership costs hit $11,577, making cars a major wealth drag.
Since Micah maxes retirement accounts, carries zero debt, and pays cash, buying the sports car is defensible if he maintains those financial habits.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A caller to the Dave Ramsey Show recently sparked a pointed conversation about cars, wealth, and what it actually means to earn a solid income. The caller was Micah, a 24-year-old earning $80,000 per year. He maxes out both his 401(k) and IRA and carries zero debt. His question was simple: he has $30,000 in cash and wants to put it toward a 2019 Nissan 370Z as a weekend car, but he wonders whether investing the money instead would serve him better long-term.
#zero
A $30,000 car loses roughly $18,000 in value within five years, and average annual ownership costs hit $11,577, making cars a major wealth drag.
Since Micah maxes retirement accounts, carries zero debt, and pays cash, buying the sports car is defensible if he maintains those financial habits.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A caller to the Dave Ramsey Show recently sparked a pointed conversation about cars, wealth, and what it actually means to earn a solid income. The caller was Micah, a 24-year-old earning $80,000 per year. He maxes out both his 401(k) and IRA and carries zero debt. His question was simple: he has $30,000 in cash and wants to put it toward a 2019 Nissan 370Z as a weekend car, but he wonders whether investing the money instead would serve him better long-term.
#zero
2 days ago
On September 9, 2026, Reuters reported that GE Aerospace (NYSE:GE) agreed to buy castings maker Consolidated Precision Products for $11.75 billion. It is its largest acquisition since becoming a standalone company in 2024, to secure the supply of the precision metal turbine-blade components that have been a persistent bottleneck across the jet engine industry. CPP is the world's third-largest maker of these parts. CEO Larry Culp called the capacity "mission-critical" as the company works through a backlog stretching into the next decade.
GE Aerospace (NYSE:GE) can use the acquisition to convert its massive backlog into revenue faster. The company's backlog exceeded $210 billion after its second-quarter results. It includes roughly $170 billion in commercial services and more than $30 billion in defense. The $11.75 billion acquisition of Consolidated Precision Products directly targets one of the supply-chain bottlenecks that has limited GE's ability to increase engine production. CPP supplies about one-quarter of GE's casting needs. It gives GE greater control over a critical manufacturing process and could help it meet deliveries tied to its long-term backlog.
Bringing CPP in-house could improve GE's production economics while reducing supplier dependence. Spare-parts delinquencies jumped 20% sequentially in the second quarter. It shows the ongoing operational impact of supply constraints. GE plans to apply its Flight Deck lean operating model at CPP to improve factory yields and machine utilization and reduce scrap and rework. The company expects the acquisition to generate about $200 million in net synergies and achieve double-digit return on invested capital by the fifth year. It gives investors a measurable path to stronger returns from the deal.
The acquisition makes GE's position solid in the next generation of engines. GE expects demand for airfoils to increase more than 30% by 2030 from 2026 levels. CPP's casting expertise could help GE bring new airfoil designs into production faster. The business also expects CPP to make roughly $2 billion in revenue in 2027. That combination gives investors a potential path to higher production capacity, faster technology development, and stronger long-term participation in commercial and defense aerospace demand.
GE Aerospace (NYSE:GE) must justify a nearly $12 billion investment, and investors already ******* ign a premium valuation to the stock. GE Aerospace trades at roughly 46 times forward earnings. It leaves investors with limited tolerance for execution problems or weaker-than-expected returns. The company will fund $7 billion of the acquisition with cash and finance the remainder with new debt. So GE needs CPP's earnings and operating improvements to make sufficient returns to support the purchase price and protect shareholder value.
#billion #backlog #supply
GE Aerospace (NYSE:GE) can use the acquisition to convert its massive backlog into revenue faster. The company's backlog exceeded $210 billion after its second-quarter results. It includes roughly $170 billion in commercial services and more than $30 billion in defense. The $11.75 billion acquisition of Consolidated Precision Products directly targets one of the supply-chain bottlenecks that has limited GE's ability to increase engine production. CPP supplies about one-quarter of GE's casting needs. It gives GE greater control over a critical manufacturing process and could help it meet deliveries tied to its long-term backlog.
Bringing CPP in-house could improve GE's production economics while reducing supplier dependence. Spare-parts delinquencies jumped 20% sequentially in the second quarter. It shows the ongoing operational impact of supply constraints. GE plans to apply its Flight Deck lean operating model at CPP to improve factory yields and machine utilization and reduce scrap and rework. The company expects the acquisition to generate about $200 million in net synergies and achieve double-digit return on invested capital by the fifth year. It gives investors a measurable path to stronger returns from the deal.
The acquisition makes GE's position solid in the next generation of engines. GE expects demand for airfoils to increase more than 30% by 2030 from 2026 levels. CPP's casting expertise could help GE bring new airfoil designs into production faster. The business also expects CPP to make roughly $2 billion in revenue in 2027. That combination gives investors a potential path to higher production capacity, faster technology development, and stronger long-term participation in commercial and defense aerospace demand.
GE Aerospace (NYSE:GE) must justify a nearly $12 billion investment, and investors already ******* ign a premium valuation to the stock. GE Aerospace trades at roughly 46 times forward earnings. It leaves investors with limited tolerance for execution problems or weaker-than-expected returns. The company will fund $7 billion of the acquisition with cash and finance the remainder with new debt. So GE needs CPP's earnings and operating improvements to make sufficient returns to support the purchase price and protect shareholder value.
#billion #backlog #supply
3 days ago
Ciena stock rebounds 4% as investors reprice CEO Gary Smith's projection of a $10B backlog by fiscal year-end, despite a 19% monthly slide.
Arista rises just 2% and Cisco barely moves at 0.4%, confirming today's surge is Ciena's own order book story, not a broad networking rally.
CFO Marc Graff guided for at least 30% revenue growth next fiscal year, backed by backlog that extends beyond that period.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Ciena (NYSE:CIEN) stock is climbing early Wednesday, up 4% to $347.60. The advance is a rebound rather than a breakout, since Ciena stock is down 19% over the past month. No fresh company news landed this morning, and the market is re-pricing disclosures Ciena made at the start of September, when the company reported record quarterly results with revenue at the top end of guidance.
#backlog
Arista rises just 2% and Cisco barely moves at 0.4%, confirming today's surge is Ciena's own order book story, not a broad networking rally.
CFO Marc Graff guided for at least 30% revenue growth next fiscal year, backed by backlog that extends beyond that period.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Ciena (NYSE:CIEN) stock is climbing early Wednesday, up 4% to $347.60. The advance is a rebound rather than a breakout, since Ciena stock is down 19% over the past month. No fresh company news landed this morning, and the market is re-pricing disclosures Ciena made at the start of September, when the company reported record quarterly results with revenue at the top end of guidance.
#backlog


4 days ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f

10 days ago
Updated Sept 09, 2026, 2:10 pm EDT / Original Sept 08, 2026, 5:46 pm EDT
Casey General Stores’ solid earnings report, including strong fuel margins and prepared food sales, should be a recipe for a stock rally.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
State Street has an ETF that invests 90% of ******* ets in the S&P 500 and 10% in investment-grade corporate bonds. But it’s a concentrated bet on AI.
#casey #jones #company #rights
Casey General Stores’ solid earnings report, including strong fuel margins and prepared food sales, should be a recipe for a stock rally.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
State Street has an ETF that invests 90% of ******* ets in the S&P 500 and 10% in investment-grade corporate bonds. But it’s a concentrated bet on AI.
#casey #jones #company #rights
10 days ago
The move represents a sharp reversal from the yen's weakness earlier in the summer, when the USD/JPY approached 165 and forced **** anese authorities to intervene in the foreign-exchange market.
The latest appreciation is increasingly being driven by expectations that the Bank of **** an (BoJ) is preparing to raise interest rates at its September meeting, while investors are also reassessing the outlook for US monetary policy. The BoJ is scheduled to meet next Thursday and Friday, with markets now pricing in a high probability of a 25-basis-point increase. More importantly, investors will be looking for guidance on whether the central bank could accelerate the pace of subsequent tightening.
U.S. consumer-price data due on Friday will provide an important signal ahead of the Federal Reserve's September 15-16 meeting. The inflation figures have become particularly significant because the Fed's policy outlook remains unusually divided. Governor Christopher Waller has indicated that he could support keeping rates unchanged if inflation continues to moderate, while Fed Chair Kevin Warsh has stressed that insufficient progress on inflation could warrant tighter policy.
From a technical perspective, the weekly chart points to a clear deterioration in the USD/JPY trend. The pair has broken below its ascending trend structure and is trading beneath both the Tenkan-sen and Kijun-sen lines of the Ichimoku Cloud index. This suggests that the medium-term bullish structure has weakened. The weekly RSI has also fallen below the neutral 50 threshold and is moving lower, indicating that bearish momentum is becoming more established.
The fundamental backdrop is becoming increasingly challenging for the USD/JPY bulls because the interest-rate differential that supported the yen carry trade for years is gradually narrowing.
#Friday #rates
The latest appreciation is increasingly being driven by expectations that the Bank of **** an (BoJ) is preparing to raise interest rates at its September meeting, while investors are also reassessing the outlook for US monetary policy. The BoJ is scheduled to meet next Thursday and Friday, with markets now pricing in a high probability of a 25-basis-point increase. More importantly, investors will be looking for guidance on whether the central bank could accelerate the pace of subsequent tightening.
U.S. consumer-price data due on Friday will provide an important signal ahead of the Federal Reserve's September 15-16 meeting. The inflation figures have become particularly significant because the Fed's policy outlook remains unusually divided. Governor Christopher Waller has indicated that he could support keeping rates unchanged if inflation continues to moderate, while Fed Chair Kevin Warsh has stressed that insufficient progress on inflation could warrant tighter policy.
From a technical perspective, the weekly chart points to a clear deterioration in the USD/JPY trend. The pair has broken below its ascending trend structure and is trading beneath both the Tenkan-sen and Kijun-sen lines of the Ichimoku Cloud index. This suggests that the medium-term bullish structure has weakened. The weekly RSI has also fallen below the neutral 50 threshold and is moving lower, indicating that bearish momentum is becoming more established.
The fundamental backdrop is becoming increasingly challenging for the USD/JPY bulls because the interest-rate differential that supported the yen carry trade for years is gradually narrowing.
#Friday #rates

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
16 days ago
On August 6, PENN Entertainment (NASDAQ:PENN) reported second-quarter results that flipped from a year-ago loss into a profit. Net income came in at $32.6 million, compared with a loss of $18.3 million in the same quarter of 2025. Revenue rose to $1.86 billion from $1.77 billion, and Adjusted EBITDA climbed to $312.6 million from $236.1 million. Diluted earnings per share landed at $0.24, versus a loss per share of $0.12 a year earlier. For a company whose digital business has weighed on results for years, that combination stands out.
The Retail segment, which covers PENN's casino properties across the Northeast, South, West and Midwest, generated $1.5 billion in revenue and $517.2 million in Segment Adjusted EBITDAR, a margin of 34.4%. Nine properties posted their best second quarter ever for both revenue and Adjusted EBITDAR, a sign the strength wasn't confined to one or two markets. June brought two new additions to the portfolio: a hotel tower at Hollywood Columbus and the new Hollywood Casino Aurora, both of which the company said are already drawing strong visitation.
The balance sheet also moved in the right direction. Total liquidity stood at $1.9 billion as of June 30, including $887.2 million in cash. Traditional net debt fell to $1,927.5 million from $2,217.5 million at the end of 2025, pulling traditional net leverage down to 2.9 times from 4.5 times over that span. Capital expenditures dropped to $97.5 million in the quarter from $159.4 million a year earlier. On May 15, PENN repaid the remaining $106.7 million balance of its 2.75% convertible notes, wiping out roughly 4.6 million potentially dilutive shares in the process.
The Interactive segment still lost money, an Adjusted EBITDA loss of $9.5 million, though that's a sharp improvement from the $62.0 million loss posted in the second quarter of 2025. Revenue for the segment reached $349.4 million, but $185.5 million of that figure came from a tax gross-up rather than actual wagering activity, a distinction that matters when sizing up the segment's real growth. PENN also leaned on refinancing to manage its debt load rather than paying it down outright: on April 16, it extended its $1.0 billion revolving credit facility and $446.9 million term loan A to 2031, and on May 28, it repriced and extended its term loan B facility to 2033.
Total traditional debt still sat at $2,814.7 million at quarter's end. Other expenses jumped to $43.0 million for the first six months of 2026 from just $2.2 million a year earlier, driven by transaction costs, severance tied to a corporate reorganization, and settlement costs connected to the company's cooperation agreement with HG Vora Capital Management. Cash rent payments to REIT landlords also remained a heavy recurring cost, $247.1 million for the quarter alone.
#revenue
The Retail segment, which covers PENN's casino properties across the Northeast, South, West and Midwest, generated $1.5 billion in revenue and $517.2 million in Segment Adjusted EBITDAR, a margin of 34.4%. Nine properties posted their best second quarter ever for both revenue and Adjusted EBITDAR, a sign the strength wasn't confined to one or two markets. June brought two new additions to the portfolio: a hotel tower at Hollywood Columbus and the new Hollywood Casino Aurora, both of which the company said are already drawing strong visitation.
The balance sheet also moved in the right direction. Total liquidity stood at $1.9 billion as of June 30, including $887.2 million in cash. Traditional net debt fell to $1,927.5 million from $2,217.5 million at the end of 2025, pulling traditional net leverage down to 2.9 times from 4.5 times over that span. Capital expenditures dropped to $97.5 million in the quarter from $159.4 million a year earlier. On May 15, PENN repaid the remaining $106.7 million balance of its 2.75% convertible notes, wiping out roughly 4.6 million potentially dilutive shares in the process.
The Interactive segment still lost money, an Adjusted EBITDA loss of $9.5 million, though that's a sharp improvement from the $62.0 million loss posted in the second quarter of 2025. Revenue for the segment reached $349.4 million, but $185.5 million of that figure came from a tax gross-up rather than actual wagering activity, a distinction that matters when sizing up the segment's real growth. PENN also leaned on refinancing to manage its debt load rather than paying it down outright: on April 16, it extended its $1.0 billion revolving credit facility and $446.9 million term loan A to 2031, and on May 28, it repriced and extended its term loan B facility to 2033.
Total traditional debt still sat at $2,814.7 million at quarter's end. Other expenses jumped to $43.0 million for the first six months of 2026 from just $2.2 million a year earlier, driven by transaction costs, severance tied to a corporate reorganization, and settlement costs connected to the company's cooperation agreement with HG Vora Capital Management. Cash rent payments to REIT landlords also remained a heavy recurring cost, $247.1 million for the quarter alone.
#revenue

17 days ago
The S&P 500 Index ($SPX) (SPY) is up by +0.50% today, the Dow Jones Industrial Average ($DOWI) (DIA) is up by +0.79%, and the Nasdaq 100 Index ($IUXX) (QQQ) is up by +0.17%. E-mini S&P futures (ESU26) are up +0.49%, and September E-mini Nasdaq futures (NQU26) are up +0.15%.
Stock index futures recovered from overnight losses and are moving higher today as a retreat in crude oil prices knocked bond yields lower. Crude oil prices gave up an overnight advance and turned lower today when US Energy Secretary Wright said that over 17 million bbl of oil went through the Strait of Hormuz on Monday, easing supply concerns. That knocked the 10-year T-note yield down -1 bp to 4.79%, benefiting stocks. Gains in stocks accelerated on dovish comments for New York Fed President Williams, who said inflation is continuing to trend down.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why ***** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#today #futures #mini
Stock index futures recovered from overnight losses and are moving higher today as a retreat in crude oil prices knocked bond yields lower. Crude oil prices gave up an overnight advance and turned lower today when US Energy Secretary Wright said that over 17 million bbl of oil went through the Strait of Hormuz on Monday, easing supply concerns. That knocked the 10-year T-note yield down -1 bp to 4.79%, benefiting stocks. Gains in stocks accelerated on dovish comments for New York Fed President Williams, who said inflation is continuing to trend down.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why ***** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#today #futures #mini

18 days ago
Beaverton, Oregon-based NIKE, Inc. (NKE) designs, produces, markets, and sells athletic footwear, apparel, equipment, accessories, and services. Valued at $57.9 billion by market cap, the company offers products under the trademarks NIKE, Jumpman, Converse, All Star, Star Chevron, and Jack Purcell, along with operating digital platforms with fitness apps, wellness content, and retail services.
Companies worth $10 billion or more are generally described as "large-cap stocks," and NKE perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the footwear & accessories industry. NKE's strong brand and innovation drive its success. The iconic "Just Do It" logo and slogan resonate globally, fostering loyalty. The company invests heavily in demand creation and digital platforms to engage consumers and set trends.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#fans #mark
Companies worth $10 billion or more are generally described as "large-cap stocks," and NKE perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the footwear & accessories industry. NKE's strong brand and innovation drive its success. The iconic "Just Do It" logo and slogan resonate globally, fostering loyalty. The company invests heavily in demand creation and digital platforms to engage consumers and set trends.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#fans #mark


24 days ago
Since succeeding Warren Buffett as CEO of Berkshire Hathaway (NYSE: BRKA) (NYSE: BRKB) last January, Greg Abel has made some major changes to Berkshire's stock portfolio. In the two quarters since taking the helm of the Oracle of Omaha's holding company, Abel has both increased stock holdings and jettisoned many positions, including a few held for many decades.
However, Abel hasn't materially decreased Berkshire's positions in Apple, American Express, Alphabet, Bank of America, and Coca-Cola. During Q2 2026, Berkshire trimmed its BofA stake by 5.9%, while increasing its Alphabet position by 45.2%.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
These five blue chip stocks now account for around 60% of its investments in U.S.-listed equities. Yet while this indeed represents high concentration, is that in itself a major risk? Not necessarily.
It's unfair to call Berkshire Hathaway's stock portfolio concentrated under Greg Abel's watch. After all, it was Warren Buffett's penchant for long-term, high-conviction investments that led to such high concentration in the first place.
#signal #high #greg #alphabet
However, Abel hasn't materially decreased Berkshire's positions in Apple, American Express, Alphabet, Bank of America, and Coca-Cola. During Q2 2026, Berkshire trimmed its BofA stake by 5.9%, while increasing its Alphabet position by 45.2%.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
These five blue chip stocks now account for around 60% of its investments in U.S.-listed equities. Yet while this indeed represents high concentration, is that in itself a major risk? Not necessarily.
It's unfair to call Berkshire Hathaway's stock portfolio concentrated under Greg Abel's watch. After all, it was Warren Buffett's penchant for long-term, high-conviction investments that led to such high concentration in the first place.
#signal #high #greg #alphabet

25 days ago
Trump's "economic D-Day" against Iran is built around one of Washington's most powerful weapons: access to the U.S. financial system. The problem is that the deeper Washington pushes into Iran's remaining trade, the bigger the targets become.
China buys more than 80% of Iran's seaborne crude. Iraq relies on Iranian gas for as much as 40% of its electricity generation. Turkey imported 4.5 bcm of Iranian gas in the first half of this year, while India still maintains a heavily one-sided trade relationship with Tehran. The UAE, once one of Iran's most important commercial and financial conduits, has already suspended dealings with Tehran.
The U.S. Treasury can sanction tankers, traders and small Chinese refiners without creating much collateral damage outside the Iranian trade. Going after the major banks financing that commerce is different, however. The same is true of forcing Baghdad to choose between complying with Washington and keeping Iranian gas flowing to Iraqi power stations.
The Trump administration took a cautious approach on Monday. Its first round targeted nearly 60 individuals, companies and vessels and expanded sanctions across shipping, aviation, technology, gold and digital ***** ets, but left China's major banks untouched.
That leaves the most powerful part of Trump's threat still hanging over Iran's trading partners. If the first round fails to cut Iranian commerce sufficiently, Washington can move from sanctioning the networks built to evade U.S. restrictions to targeting the banks and companies that still have substantial business to lose in the United States.
#still #tehran #built #financial
China buys more than 80% of Iran's seaborne crude. Iraq relies on Iranian gas for as much as 40% of its electricity generation. Turkey imported 4.5 bcm of Iranian gas in the first half of this year, while India still maintains a heavily one-sided trade relationship with Tehran. The UAE, once one of Iran's most important commercial and financial conduits, has already suspended dealings with Tehran.
The U.S. Treasury can sanction tankers, traders and small Chinese refiners without creating much collateral damage outside the Iranian trade. Going after the major banks financing that commerce is different, however. The same is true of forcing Baghdad to choose between complying with Washington and keeping Iranian gas flowing to Iraqi power stations.
The Trump administration took a cautious approach on Monday. Its first round targeted nearly 60 individuals, companies and vessels and expanded sanctions across shipping, aviation, technology, gold and digital ***** ets, but left China's major banks untouched.
That leaves the most powerful part of Trump's threat still hanging over Iran's trading partners. If the first round fails to cut Iranian commerce sufficiently, Washington can move from sanctioning the networks built to evade U.S. restrictions to targeting the banks and companies that still have substantial business to lose in the United States.
#still #tehran #built #financial

26 days ago
By Khushi Malhotra
MUMBAI, Aug 24 (Reuters) - India will launch tokenised corporate bonds next month, as it tests the use of blockchain technology to enable instant settlement of bond transactions, three sources with direct knowledge of the matter said on Monday.
The notes, to be issued for the first time by state-owned power financier REC, would place India alongside markets such as Europe and Hong Kong in using the technology for issuance and settlement.
Tokenised bonds are securities whose ownership, issuance, trading and settlement are recorded digitally on a blockchain or distributed ledger, allowing transactions to be completed almost instantly.
India's markets regulator and central bank are working together on pushing the technology, according to the sources, who spoke on the condition of anonymity as the discussions are ongoing and confidential.
#Blockchain #transactions #sources #issuance
MUMBAI, Aug 24 (Reuters) - India will launch tokenised corporate bonds next month, as it tests the use of blockchain technology to enable instant settlement of bond transactions, three sources with direct knowledge of the matter said on Monday.
The notes, to be issued for the first time by state-owned power financier REC, would place India alongside markets such as Europe and Hong Kong in using the technology for issuance and settlement.
Tokenised bonds are securities whose ownership, issuance, trading and settlement are recorded digitally on a blockchain or distributed ledger, allowing transactions to be completed almost instantly.
India's markets regulator and central bank are working together on pushing the technology, according to the sources, who spoke on the condition of anonymity as the discussions are ongoing and confidential.
#Blockchain #transactions #sources #issuance

1 month ago
Altcoins, which are cryptocurrencies other than Bitcoin (CRYPTO: BTC), are usually considered speculative and volatile investments. But they're also high-risk, high-reward tokens that could have much greater upside potential than Bitcoin.
Two of the market's most closely watched altcoins are XRP (CRYPTO: XRP) and Ether (CRYPTO: ETH). Both altcoins have struggled over the past year as fears of interest rate hikes and other macro headwinds drove investors toward more conservative investments, but will one recover faster than the other when the crypto market warms up again?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
XRP is the native token of the XRP Ledger, a blockchain that was designed to provide fast, low-cost cross-border payments. It was created by the founders of Ripple, a fintech company that specializes in blockchain-based money transfers. It's still primarily used as a bridge currency for fiat transactions on Ripple's platform, but it's being adopted by other financial institutions (especially in **** an) to accelerate cross-border transactions with lower fees. The bulls believe XRP's value will rise as its ledger replaces those legacy financial rails.
Ether is the native token of Ethereum, the world's largest proof-of-stake (PoS) blockchain. As a PoS blockchain, it supports staking (locking up tokens to earn yield) and smart contracts (for developing decentralized apps and other tokenized **** ets). Every time a user makes a transaction on Ethereum, they must pay a "gas fee" in Ether. Therefore, Ether's value is driven by Ethereum's ability to draw more developers and decentralized app users to its ecosystem.
#Crypto #altcoins #flashing #ledger
Two of the market's most closely watched altcoins are XRP (CRYPTO: XRP) and Ether (CRYPTO: ETH). Both altcoins have struggled over the past year as fears of interest rate hikes and other macro headwinds drove investors toward more conservative investments, but will one recover faster than the other when the crypto market warms up again?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
XRP is the native token of the XRP Ledger, a blockchain that was designed to provide fast, low-cost cross-border payments. It was created by the founders of Ripple, a fintech company that specializes in blockchain-based money transfers. It's still primarily used as a bridge currency for fiat transactions on Ripple's platform, but it's being adopted by other financial institutions (especially in **** an) to accelerate cross-border transactions with lower fees. The bulls believe XRP's value will rise as its ledger replaces those legacy financial rails.
Ether is the native token of Ethereum, the world's largest proof-of-stake (PoS) blockchain. As a PoS blockchain, it supports staking (locking up tokens to earn yield) and smart contracts (for developing decentralized apps and other tokenized **** ets). Every time a user makes a transaction on Ethereum, they must pay a "gas fee" in Ether. Therefore, Ether's value is driven by Ethereum's ability to draw more developers and decentralized app users to its ecosystem.
#Crypto #altcoins #flashing #ledger
1 month ago
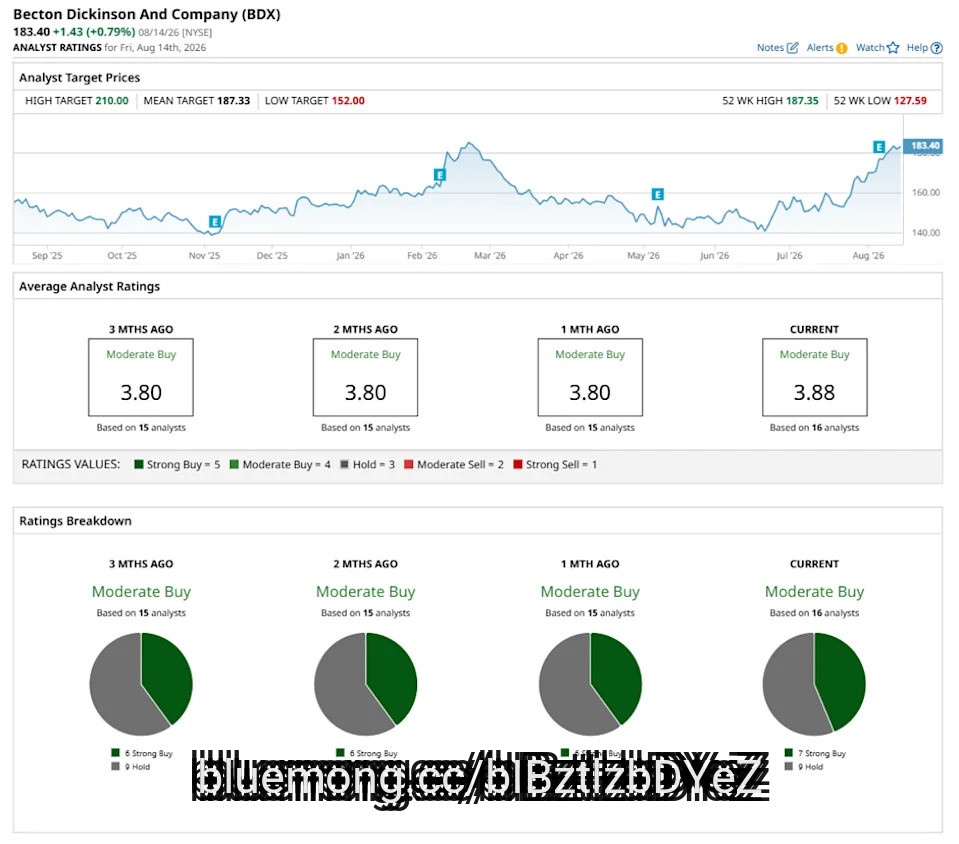
Becton, **** inson and Company (BDX) develops, manufactures, and sells medical supplies, devices, laboratory equipment, and diagnostic products. Valued at $50.5 billion by market cap, the company offers solutions that help advance medical research and genomics, enhance the diagnosis of infectious disease and cancer, improve medication management, and promote infection prevention.
Shares of this global medical technology giant have underperformed the broader market over the past year. BDX has gained 19.6% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 20.4%. However, in 2026, BDX stock is up 20.2%, surpassing the SPX's 13.7% rise on a YTD basis.
CoreWeave vs Nebius: Both Companies Reported Strong Earnings, But Here's the Stock You Should Buy
A $210 Billion Reason to Buy AMD Stock Here
As Oracle Deepens Its Partnership with AWS, Here's How You Should Play ORCL Stock
#medical #billion
Shares of this global medical technology giant have underperformed the broader market over the past year. BDX has gained 19.6% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 20.4%. However, in 2026, BDX stock is up 20.2%, surpassing the SPX's 13.7% rise on a YTD basis.
CoreWeave vs Nebius: Both Companies Reported Strong Earnings, But Here's the Stock You Should Buy
A $210 Billion Reason to Buy AMD Stock Here
As Oracle Deepens Its Partnership with AWS, Here's How You Should Play ORCL Stock
#medical #billion
1 month ago
Albin, Randall & Bennett (ARB), an accounting and business advisory practice based in the US, has promoted Matthew S. Marcoullier and Samantha J. Pedersen to the role of principal.
Together, Marcoullier and Pedersen have accumulated 35 years of service at the company.
Marcoullier joined ARB in 2013. He focuses on accounting, tax, consulting and advisory work for auto dealerships and commercial businesses across New England.
His work includes tax planning, addressing operational issues, organisational planning, compensation strategies and compliance.
Within ARB, Marcoullier oversees annual dealership last in, first out (LIFO) calculations and contributes to the development of training and technical resources that support the company's specialist knowledge.
#albin
Together, Marcoullier and Pedersen have accumulated 35 years of service at the company.
Marcoullier joined ARB in 2013. He focuses on accounting, tax, consulting and advisory work for auto dealerships and commercial businesses across New England.
His work includes tax planning, addressing operational issues, organisational planning, compensation strategies and compliance.
Within ARB, Marcoullier oversees annual dealership last in, first out (LIFO) calculations and contributes to the development of training and technical resources that support the company's specialist knowledge.
#albin
2 months ago
Baron Capital, an investment management company, released its Q2 2026 investor letter for the "Baron Health Care Fund". A copy of the letter is available to download here. The Fund gained 11.99% during the quarter, compared with the 10.48% gain for the Russell 3000 Health Care Index and the 15.44% gain for the Russell 3000 Index. Since inception, the Fund appreciated 10.61% on an annualized basis, compared with 10.02% for the Benchmark and 14.83% for the Index. Strong stock selection in pharmaceuticals, biotechnology, health care equipment, and life sciences tools and services supported the Fund's outperformance, although limited exposure to managed care stocks reduced relative returns. The Fund remains positive on health care due to improving biotechnology funding, strong acquisition activity, recovering managed care margins, and growth from an aging population, chronic disease, medical innovation, and higher health care spending. In addition, please check the Fund's top five holdings to know the best picks in 2026.
In its second-quarter 2026 investor letter, Baron Health Care Fund highlighted Insmed Incorporated (NASDAQ:INSM). Insmed Incorporated (NASDAQ:INSM), which develops and commercializes therapies for patients with serious and rare diseases, detracted from the fund's performance during the quarter. On August 03, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $98.45 per share. The one-month return of Insmed Incorporated (NASDAQ:INSM) was -12.56%, and its shares lost 11.59% over the past 52 weeks. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $21.34 billion.
Baron Health Care Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated is a biotechnology company with three lead pulmonology ******* ets that we believe can collectively generate more than $8 billion in peak sales. We are particularly excited about Brinsupri for non-cystic fibrosis bronchiectasis, which we view as a $5 billion-plus opportunity. Despite what we believe has been a strong start to the launch, shares fell after first quarter Brinsupri sales missed expectations as investors focused on early signs of higher treatment discontinuations. Insmed's exit from the Nasdaq-100 Index created additional technical selling pressure. Long term, we continue to view Brinsupri as an important treatment option for the 500,000-plus bronchiectasis patients in the U.S. We remain bullish on the portfolio's long-term fundamentals, including the opportunity for treprostinil palmitil inhalation powder (TPIP), which is being studied for pulmonary arterial hypertension and pulmonary hypertension ******* ociated with interstitial lung disease. Compared to existing inhaled prostanoids that require four daily treatments, once-daily TPIP is more convenient and can be dosed at significantly higher levels, potentially resulting in meaningfully better efficacy."
#fund #baron
In its second-quarter 2026 investor letter, Baron Health Care Fund highlighted Insmed Incorporated (NASDAQ:INSM). Insmed Incorporated (NASDAQ:INSM), which develops and commercializes therapies for patients with serious and rare diseases, detracted from the fund's performance during the quarter. On August 03, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $98.45 per share. The one-month return of Insmed Incorporated (NASDAQ:INSM) was -12.56%, and its shares lost 11.59% over the past 52 weeks. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $21.34 billion.
Baron Health Care Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated is a biotechnology company with three lead pulmonology ******* ets that we believe can collectively generate more than $8 billion in peak sales. We are particularly excited about Brinsupri for non-cystic fibrosis bronchiectasis, which we view as a $5 billion-plus opportunity. Despite what we believe has been a strong start to the launch, shares fell after first quarter Brinsupri sales missed expectations as investors focused on early signs of higher treatment discontinuations. Insmed's exit from the Nasdaq-100 Index created additional technical selling pressure. Long term, we continue to view Brinsupri as an important treatment option for the 500,000-plus bronchiectasis patients in the U.S. We remain bullish on the portfolio's long-term fundamentals, including the opportunity for treprostinil palmitil inhalation powder (TPIP), which is being studied for pulmonary arterial hypertension and pulmonary hypertension ******* ociated with interstitial lung disease. Compared to existing inhaled prostanoids that require four daily treatments, once-daily TPIP is more convenient and can be dosed at significantly higher levels, potentially resulting in meaningfully better efficacy."
#fund #baron

2 months ago
Starbucks Corp (NASDAQ:SBUX, XETRA:SRB) beat Wall Street estimates for fiscal third-quarter revenue and profit as its turnaround plan drove stronger-than-expected US sales growth.
Adjusted earnings per share came in at $0.85, above the $0.66 ***** yst estimate and up 70% year-over-year. Revenue was $9.3 billion, topping the $9.16 billion consensus though down 1% from a year earlier.
Global comparable sales rose 7.9%, with North America up 8.1% and international sales up 5.7%. US comparable sales climbed 7.9%, driven by a 4.2% rise in traffic and a 3.6% increase in average ticket.
Starbucks raised its full-year guidance, now expecting adjusted EPS of $2.55 to $2.65, above the $2.40 consensus. Global comparable sales growth is expected to near 6% for the year, with non-GAAP operating margin above 11% and 600 to 650 net new coffeehouses planned. Fourth-quarter US comparable sales are guided to grow at least 6.5%.
North America net revenue reached $7.4 billion, up 7%, while International net revenue fell 34% to $1.3 billion. Channel Development revenue rose 22% to $587.9 million.
#revenue #comparable
Adjusted earnings per share came in at $0.85, above the $0.66 ***** yst estimate and up 70% year-over-year. Revenue was $9.3 billion, topping the $9.16 billion consensus though down 1% from a year earlier.
Global comparable sales rose 7.9%, with North America up 8.1% and international sales up 5.7%. US comparable sales climbed 7.9%, driven by a 4.2% rise in traffic and a 3.6% increase in average ticket.
Starbucks raised its full-year guidance, now expecting adjusted EPS of $2.55 to $2.65, above the $2.40 consensus. Global comparable sales growth is expected to near 6% for the year, with non-GAAP operating margin above 11% and 600 to 650 net new coffeehouses planned. Fourth-quarter US comparable sales are guided to grow at least 6.5%.
North America net revenue reached $7.4 billion, up 7%, while International net revenue fell 34% to $1.3 billion. Channel Development revenue rose 22% to $587.9 million.
#revenue #comparable

2 months ago
(The views expressed here are solely those of the author and do not necessarily represent the views of FreightWaves or its affiliates.)
A Dallas County jury last week hit freight broker C.H. Robinson with a share of a $604 million verdict in Peyton Lipe et al. v. Lupus Superior, LLC et al. The case stems from a deadly 2021 crash on Interstate 20 in Mississippi. A tractor-trailer operated by Lupus Superior and driven by Gorgonio Gonzalez plowed into stopped traffic. The wreck sparked a multi-vehicle fire that killed Jennifer Lipe, Benjamin Brewer, and Rhoderick Coleman. Two others were seriously hurt. Gonzalez also died.
The jury found the driver, the motor carrier, and C.H. Robinson all negligent. The jury ******* igned Gonzalez with 45% responsibility, Lupus Superior with 32% responsibility, and C.H. Robinson 23% responsibility. Lupus Superior, a Grand Prairie, TX based motor carrier, holds a satisfactory safety rating with the FMCSA. More importantly, the jurors decided Gonzalez was acting as a "borrowed employee" of C.H. Robinson and was carrying out a mission under the broker's control. That finding opens the door to full vicarious liability for the driver's negligence. C.H. Robinson has said it will appeal.
This verdict lands right after two major court decisions that reshape how courts treat liability in trucking and logistics. Understanding the difference between vicarious liability and negligent hiring is key to seeing what happens next.
Vicarious Liability: When One Party Answers for Another's Mistakes.
#superior
A Dallas County jury last week hit freight broker C.H. Robinson with a share of a $604 million verdict in Peyton Lipe et al. v. Lupus Superior, LLC et al. The case stems from a deadly 2021 crash on Interstate 20 in Mississippi. A tractor-trailer operated by Lupus Superior and driven by Gorgonio Gonzalez plowed into stopped traffic. The wreck sparked a multi-vehicle fire that killed Jennifer Lipe, Benjamin Brewer, and Rhoderick Coleman. Two others were seriously hurt. Gonzalez also died.
The jury found the driver, the motor carrier, and C.H. Robinson all negligent. The jury ******* igned Gonzalez with 45% responsibility, Lupus Superior with 32% responsibility, and C.H. Robinson 23% responsibility. Lupus Superior, a Grand Prairie, TX based motor carrier, holds a satisfactory safety rating with the FMCSA. More importantly, the jurors decided Gonzalez was acting as a "borrowed employee" of C.H. Robinson and was carrying out a mission under the broker's control. That finding opens the door to full vicarious liability for the driver's negligence. C.H. Robinson has said it will appeal.
This verdict lands right after two major court decisions that reshape how courts treat liability in trucking and logistics. Understanding the difference between vicarious liability and negligent hiring is key to seeing what happens next.
Vicarious Liability: When One Party Answers for Another's Mistakes.
#superior

2 months ago
Columbia Threadneedle Investments, an investment management company, released its "Columbia Seligman Global Technology Fund" second quarter 2026 investor letter. A copy of the letter can be downloaded here. During the quarter, the Fund's Institutional Class shares returned 50.34%, outperforming the MSCI World Information Technology Index's 33.65% gain. Stock selection in semiconductors, technology hardware and software, together with an off-benchmark electrical equipment allocation, supported relative performance, while exposure to financials, consumer discretionary and healthcare detracted. Technology stocks rallied as concerns over the Iran conflict eased and AI infrastructure spending boosted demand for semiconductors, memory, networking, servers and power solutions. The Fund expects AI and data-centre investment to remain strong, supported by broadening earnings growth and improving software bookings, cloud consumption and customer spending. However, geopolitical uncertainty, higher interest rates and heavy AI investment could pressure valuations and free cash flow. The strategy holds 50–75 technology companies across market capitalisations and uses bottom-up GARP research to identify misunderstood and undervalued businesses in the technology industry. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Columbia Seligman Global Technology Fund highlighted Bloom Energy Corporation (NYSE:BE) as a leading contributor. Bloom Energy Corporation (NYSE:BE) is an energy company that designs and manufactures solid-oxide fuel cell systems for clean, reliable, on-site power generation. On July 27, 2026, Bloom Energy Corporation (NYSE:BE) closed at $188.18 per share. One-month return of Bloom Energy Corporation (NYSE:BE) was -37.83% and its shares gained 441.53% over the past 52 weeks. Bloom Energy Corporation (NYSE:BE) has a market capitalization of $53.53 billion.
Columbia Seligman Global Technology Fund stated the following regarding Bloom Energy Corporation (NYSE:BE) in its Q2 2026 investor letter:
"The fund continued to hold an off-benchmark position in Bloom Energy Corporation (NYSE:BE). The company manufactures and markets solid-oxide fuel cells that produce electricity and can provide an alternative source of energy compared to traditional supply. Data-center operators have increasingly turned to Bloom's solid-oxide fuel cells to bypass grid constraints and power energy-intensive AI workloads. The optimism around Bloom continued during the quarter, with expectations that accelerating AI data-center construction would drive demand for reliable, onsite power-generation solutions, particularly as utilities struggled to provide sufficient grid capacity in many regions. The stock also benefited from growing recognition of Bloom's fuel-cell technology as a potential bridge solution for powering AI infrastructure, supporting expectations for stronger bookings and long-term
In its second-quarter 2026 investor letter, Columbia Seligman Global Technology Fund highlighted Bloom Energy Corporation (NYSE:BE) as a leading contributor. Bloom Energy Corporation (NYSE:BE) is an energy company that designs and manufactures solid-oxide fuel cell systems for clean, reliable, on-site power generation. On July 27, 2026, Bloom Energy Corporation (NYSE:BE) closed at $188.18 per share. One-month return of Bloom Energy Corporation (NYSE:BE) was -37.83% and its shares gained 441.53% over the past 52 weeks. Bloom Energy Corporation (NYSE:BE) has a market capitalization of $53.53 billion.
Columbia Seligman Global Technology Fund stated the following regarding Bloom Energy Corporation (NYSE:BE) in its Q2 2026 investor letter:
"The fund continued to hold an off-benchmark position in Bloom Energy Corporation (NYSE:BE). The company manufactures and markets solid-oxide fuel cells that produce electricity and can provide an alternative source of energy compared to traditional supply. Data-center operators have increasingly turned to Bloom's solid-oxide fuel cells to bypass grid constraints and power energy-intensive AI workloads. The optimism around Bloom continued during the quarter, with expectations that accelerating AI data-center construction would drive demand for reliable, onsite power-generation solutions, particularly as utilities struggled to provide sufficient grid capacity in many regions. The stock also benefited from growing recognition of Bloom's fuel-cell technology as a potential bridge solution for powering AI infrastructure, supporting expectations for stronger bookings and long-term

2 months ago
Access to this page has been denied because we believe you are using automation tools to browse the website.
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #9317c1d0 -8afe-11f1-9f83-b5213db595c9
#access #please
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #9317c1d0 -8afe-11f1-9f83-b5213db595c9
#access #please
2 months ago
Bristol Gate Capital Partners, an investment management company, published its Q2 2026 investor letter for the "US Equity Strategy". A copy of the letter can be downloaded here. The Strategy lagged the S&P 500 Total Return Index in the quarter in terms of returns, but outperformed in dividend growth. Despite debate over capital cycle returns, AI remained the dominant market theme, expanding from early adoption to broader enterprise adoption. The firm continues to focus on high-dividend-growth companies while maintaining discipline around valuation and earnings durability. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Bristol US Equity Strategy highlighted Howmet Aerospace Inc. (NYSE:HWM) as a newly added position. Howmet Aerospace Inc. (NYSE:HWM) is a leading US-based aerospace and industrial company that operates through Engine Products, Fastening Systems, Engineered Structures, and Forged Wheels segments. On July 22, 2026, Howmet Aerospace Inc. (NYSE:HWM) closed at $280.70 per share. One-month return of Howmet Aerospace Inc. (NYSE:HWM) was 2.77%, and its shares gained 50.27% over the past 52 weeks. Howmet Aerospace Inc. (NYSE:HWM) has a market capitalization of about $112.31 billion.
Bristol US Equity Strategy stated the following regarding Howmet Aerospace Inc. (NYSE:HWM) in its Q2 2026 investor update:
"Howmet Aerospace Inc. (NYSE:HWM) supplies engineered components to the commercial aerospace, defense and industrial markets. Its advantage stems from decades of accumulated R&D in materials science and manufacturing, and it faces limited competition as a US manufacturer for the aerospace industry. Management has demonstrated excellent capital allocation through investments in high-growth projects that leverage the company's strengths."
Howmet Aerospace Inc. (NYSE:HWM) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 75 hedge fund portfolios held Howmet Aerospace Inc. (NYSE:HWM) at the end of the first quarter, up from 71 in the previous quarter. While we acknowledge the potential of Howmet Aerospace Inc. (NYSE:HWM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#bristol
In its Q2 2026 investor letter, Bristol US Equity Strategy highlighted Howmet Aerospace Inc. (NYSE:HWM) as a newly added position. Howmet Aerospace Inc. (NYSE:HWM) is a leading US-based aerospace and industrial company that operates through Engine Products, Fastening Systems, Engineered Structures, and Forged Wheels segments. On July 22, 2026, Howmet Aerospace Inc. (NYSE:HWM) closed at $280.70 per share. One-month return of Howmet Aerospace Inc. (NYSE:HWM) was 2.77%, and its shares gained 50.27% over the past 52 weeks. Howmet Aerospace Inc. (NYSE:HWM) has a market capitalization of about $112.31 billion.
Bristol US Equity Strategy stated the following regarding Howmet Aerospace Inc. (NYSE:HWM) in its Q2 2026 investor update:
"Howmet Aerospace Inc. (NYSE:HWM) supplies engineered components to the commercial aerospace, defense and industrial markets. Its advantage stems from decades of accumulated R&D in materials science and manufacturing, and it faces limited competition as a US manufacturer for the aerospace industry. Management has demonstrated excellent capital allocation through investments in high-growth projects that leverage the company's strengths."
Howmet Aerospace Inc. (NYSE:HWM) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 75 hedge fund portfolios held Howmet Aerospace Inc. (NYSE:HWM) at the end of the first quarter, up from 71 in the previous quarter. While we acknowledge the potential of Howmet Aerospace Inc. (NYSE:HWM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#bristol

2 months ago
Giverny Capital ***** et Management, LLC, an investment management company, recently published its second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The model portfolio returned 13.70% this quarter, compared to the S&P 500's 15.20% return. YTD, the portfolio gained 5.89%, while the index increased by 10.21%. The long-term link between stock appreciation and earnings growth is strong; Benjamin Graham described the market as a "voting machine" in the short term and a "weighing machine" in the long term. Despite the S&P 500's 10.2% rise in the first half of the year, 210 stocks lost value, indicating market anomalies. High-quality earnings compounders that benefit from AI capabilities are likely to maintain their competitive edge. Recently, the market has increasingly chased momentum. Tech giants are taking advantage of the optimism of investors amid fears of an AI bubble. Despite strong profit margins, reliance on "moonshot" investments raises sustainability concerns. The author recommends investing in both emerging tech leaders and established firms. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Giverny Capital ***** et Management highlighted Mastercard Incorporated (NYSE:MA). Mastercard Incorporated (NYSE:MA) is a leading global payment technology company provides transaction processing and other payment-related products and services. On July 20, 2026, Mastercard Incorporated (NYSE:MA) closed at $547.44 per share, reflecting a market capitalization of $483.71 billion. Mastercard Incorporated (NYSE:MA) posted a one-month return of 11.06%, while its shares lost 2.99% over the past 52 weeks.
Giverny Capital ***** et Management stated the following regarding Mastercard Incorporated (NYSE:MA) in its Q2 2026 investor update:
"Roughly 40% of the Index outperforming the average and 60% underperforming is not so unusual, but two-thirds of that lagging group underperforming by more than 10 percentage points seems like a lot. Even this level of dispersion might make sense if most of the earnings growth in the Index was concentrated in the 200 stocks that were up double digits. This is not the case. We own Index constituents such as Charles Schwab, JP Morgan, Mastercard Incorporated (NYSE:MA) and Progressive Corp. that continue to grow their earnings per share at healthy rates and in some cases at higher rates than usual, but whose stock prices are lagging.
Similarly, Wall Street ***** ysts expect Mastercard to compound EPS by 15% over the next few years, roughly the same rate as the past 20 years. The stock was down 10% in the first half of 2026 and has lagged the Index over the past five years."
#incorporated #index #asset
In its Q2 2026 investor letter, Giverny Capital ***** et Management highlighted Mastercard Incorporated (NYSE:MA). Mastercard Incorporated (NYSE:MA) is a leading global payment technology company provides transaction processing and other payment-related products and services. On July 20, 2026, Mastercard Incorporated (NYSE:MA) closed at $547.44 per share, reflecting a market capitalization of $483.71 billion. Mastercard Incorporated (NYSE:MA) posted a one-month return of 11.06%, while its shares lost 2.99% over the past 52 weeks.
Giverny Capital ***** et Management stated the following regarding Mastercard Incorporated (NYSE:MA) in its Q2 2026 investor update:
"Roughly 40% of the Index outperforming the average and 60% underperforming is not so unusual, but two-thirds of that lagging group underperforming by more than 10 percentage points seems like a lot. Even this level of dispersion might make sense if most of the earnings growth in the Index was concentrated in the 200 stocks that were up double digits. This is not the case. We own Index constituents such as Charles Schwab, JP Morgan, Mastercard Incorporated (NYSE:MA) and Progressive Corp. that continue to grow their earnings per share at healthy rates and in some cases at higher rates than usual, but whose stock prices are lagging.
Similarly, Wall Street ***** ysts expect Mastercard to compound EPS by 15% over the next few years, roughly the same rate as the past 20 years. The stock was down 10% in the first half of 2026 and has lagged the Index over the past five years."
#incorporated #index #asset

2 months ago
LightPath Technologies (NASDAQ:LPTH) shares gained 9% after the company announced it had secured an 11 million dollar follow-on order for infrared camera systems from a major global technology customer supporting counter-unmanned aircraft system (counter-UAS) applications.
The latest contract represents another order from one of LightPath's key customers and reinforces ongoing demand for the company's infrared imaging technology across defence and public safety markets.
According to the company, the programme will also include a planned transition from traditional Germanium optics to its proprietary BlackDiamond optical materials.
Chief Executive Officer Sam Rubin said the agreement demonstrates the company's growing partnership with an important customer.
"This order reflects the deepening relationship with one of our most significant customers and the expanding role of our infrared camera systems in public safety applications, where reliability and performance are mission-critical."
The latest contract represents another order from one of LightPath's key customers and reinforces ongoing demand for the company's infrared imaging technology across defence and public safety markets.
According to the company, the programme will also include a planned transition from traditional Germanium optics to its proprietary BlackDiamond optical materials.
Chief Executive Officer Sam Rubin said the agreement demonstrates the company's growing partnership with an important customer.
"This order reflects the deepening relationship with one of our most significant customers and the expanding role of our infrared camera systems in public safety applications, where reliability and performance are mission-critical."

2 months ago
Blue Origin is looking to cash in on the recent hype around ******* e stocks, following ******* eX's IPO last month. Jeff Bezos' rocket company is raising $10 billion, NYT Dealbook reported Wednesday, as Blue Origin plans to ramp up operations while playing an increasingly-critical role in NASA's upcoming missions. ******* e stocks were mixed early Wednesday.
Blue Origin aims to raise $10 billion for a pre-money valuation of $130 billion, according to the New York Times. ******* et management firm Coatue Management is expected to lead the round with a $4 billion commitment. Bezos will personally contribute $2 billion.
The round would mark the first fundraise from outside investors in Blue Origin's nearly 26-year history.
Meanwhile, ******* ysts predict Blue Origin could spend nearly $5 billion this year as it ramps up launches and heavy infrastructure investments, the Financial Times previously reported. Blue Origin has spent about $28 billion since its inception.
The move comes on the heels of ******* eX (SPCX)'s IPO in early June, which raised $85 billion at a nearly $2 trillion valuation. However, Blue Origin is reportedly not yet considering a public debut.
Blue Origin aims to raise $10 billion for a pre-money valuation of $130 billion, according to the New York Times. ******* et management firm Coatue Management is expected to lead the round with a $4 billion commitment. Bezos will personally contribute $2 billion.
The round would mark the first fundraise from outside investors in Blue Origin's nearly 26-year history.
Meanwhile, ******* ysts predict Blue Origin could spend nearly $5 billion this year as it ramps up launches and heavy infrastructure investments, the Financial Times previously reported. Blue Origin has spent about $28 billion since its inception.
The move comes on the heels of ******* eX (SPCX)'s IPO in early June, which raised $85 billion at a nearly $2 trillion valuation. However, Blue Origin is reportedly not yet considering a public debut.

2 months ago
The market has had an up-and-down year, but there are a few stocks that are taking a bigger beating than most. Microsoft (NASDAQ: MSFT) and Meta Platforms (NASDAQ: META) are two major underperformers in the tech realm, and have lost investors' money in 2026. So far, Meta is down around 12%, while Microsoft is nearly down 20%.
That's some poor performance from two stocks that have been historically great investments, and I think each could turn it around and be excellent performers before 2026 is over. Here's why.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
It's hard not to appreciate Microsoft's strategy in the artificial intelligence (AI) era. It has several strategies, and all of them seem to be paying off just fine. The launch of Copilot has been incredibly successful, and this business now has $37 billion in annual revenue, growing at a 123% year-over-year pace. This allows its business productivity tools to integrate seamlessly with AI and boost productivity.
However, if clients turn sour on Copilot, it also has a thriving cloud computing division that's powering AI workflows. Azure grew at a 40% year-over-year pace in its most recent quarter, showcasing strong demand for computing infrastructure. So, even if its own internal AI tools don't pan out, it can benefit from other companies building great AI products on its platform.
That's some poor performance from two stocks that have been historically great investments, and I think each could turn it around and be excellent performers before 2026 is over. Here's why.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
It's hard not to appreciate Microsoft's strategy in the artificial intelligence (AI) era. It has several strategies, and all of them seem to be paying off just fine. The launch of Copilot has been incredibly successful, and this business now has $37 billion in annual revenue, growing at a 123% year-over-year pace. This allows its business productivity tools to integrate seamlessly with AI and boost productivity.
However, if clients turn sour on Copilot, it also has a thriving cloud computing division that's powering AI workflows. Azure grew at a 40% year-over-year pace in its most recent quarter, showcasing strong demand for computing infrastructure. So, even if its own internal AI tools don't pan out, it can benefit from other companies building great AI products on its platform.

2 months ago
By Nate Raymond
BOSTON, July 7 (Reuters) - The founder and chief executive of an AI startup secretly pleaded guilty last year to participating in a vast scheme in which attorneys at major law firms tipped traders about mergers their employers were advising on.
Court records unsealed on Monday show that Arya Bolurfrushan, a former Goldman Sachs banker who founded Abu Dhabi-based AppliedAI, pleaded guilty in June 2025 after striking a deal with federal prosecutors in Boston who were working to build cases against dozens of other people accused of participating in the long-running insider trading scheme.
Those individuals include Nicolo Nourafchan, who had worked at the law firms Sidley Austin, Latham & Watkins and Goodwin Procter before prosecutors in May unveiled charges against him and 29 other people accused of engaging in a scheme to profit from confidential information about mergers underway.
Bolurfrushan pleaded guilty to conspiring to commit securities fraud in a plea agreement where prosecutors agreed to recommend that he be sentenced to two years in prison and forfeit $954,496 he derived from the scheme.
BOSTON, July 7 (Reuters) - The founder and chief executive of an AI startup secretly pleaded guilty last year to participating in a vast scheme in which attorneys at major law firms tipped traders about mergers their employers were advising on.
Court records unsealed on Monday show that Arya Bolurfrushan, a former Goldman Sachs banker who founded Abu Dhabi-based AppliedAI, pleaded guilty in June 2025 after striking a deal with federal prosecutors in Boston who were working to build cases against dozens of other people accused of participating in the long-running insider trading scheme.
Those individuals include Nicolo Nourafchan, who had worked at the law firms Sidley Austin, Latham & Watkins and Goodwin Procter before prosecutors in May unveiled charges against him and 29 other people accused of engaging in a scheme to profit from confidential information about mergers underway.
Bolurfrushan pleaded guilty to conspiring to commit securities fraud in a plea agreement where prosecutors agreed to recommend that he be sentenced to two years in prison and forfeit $954,496 he derived from the scheme.

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Whether you are buying a home or refinancing an existing loan, closing costs will be a sizable expense — think thousands of dollars. In some cases, it's possible to roll those settlement fees into the loan. Here's when and how you can, and also if you should.
A lender may allow closing costs to be rolled into a mortgage if you have enough borrowing power. Here's what that means.
Loan-to-value, or LTV, is the amount you finance compared to the home's appraised value. Say you take out a $300,000 loan on a home with a $400,000 market value. Your loan-to-value is 75%. Here's the formula:
Loan / value = LTV
Whether you are buying a home or refinancing an existing loan, closing costs will be a sizable expense — think thousands of dollars. In some cases, it's possible to roll those settlement fees into the loan. Here's when and how you can, and also if you should.
A lender may allow closing costs to be rolled into a mortgage if you have enough borrowing power. Here's what that means.
Loan-to-value, or LTV, is the amount you finance compared to the home's appraised value. Say you take out a $300,000 loan on a home with a $400,000 market value. Your loan-to-value is 75%. Here's the formula:
Loan / value = LTV

3 months ago
Meta Platforms, Inc. (NASDAQ:META) was among the stocks on Jim Cramer's Mad Money radar as he taught investors how to profit from the upcoming wave of takeovers. Cramer noted how people view the stock, as he said:
Third, Meta, down 11% this month. Meta is going out of style because it's now viewed as nothing more than a pure advertising play… Again, false view, but right now, that does not matter. People do not want to own this stock. It is spending too much money, and we don't know why. It hasn't been explained well. What can Meta do? It has and is building a ton of data center power. I think Meta simply needs to say it's going into the cloud computing Meta web services business. This can give you an instant 100-point gain, maybe more than that.
Photo by Alexander Shatov on Unsplash
Meta Platforms, Inc. (NASDAQ:META) develops technologies and applications that connect people through social networking and messaging. The company's portfolio includes Facebook, Instagram, WhatsApp, Messenger, Threads, and virtual and augmented reality products.
While we acknowledge the risk and potential of META as an investment, our conviction lies in the belief that some AI stocks hold greater promise for delivering higher returns and doing so within a shorter time frame. If you are looking for an AI stock that is more promising than META and that has 10,000% upside potential, check out our report about this cheapest AI stock.
Third, Meta, down 11% this month. Meta is going out of style because it's now viewed as nothing more than a pure advertising play… Again, false view, but right now, that does not matter. People do not want to own this stock. It is spending too much money, and we don't know why. It hasn't been explained well. What can Meta do? It has and is building a ton of data center power. I think Meta simply needs to say it's going into the cloud computing Meta web services business. This can give you an instant 100-point gain, maybe more than that.
Photo by Alexander Shatov on Unsplash
Meta Platforms, Inc. (NASDAQ:META) develops technologies and applications that connect people through social networking and messaging. The company's portfolio includes Facebook, Instagram, WhatsApp, Messenger, Threads, and virtual and augmented reality products.
While we acknowledge the risk and potential of META as an investment, our conviction lies in the belief that some AI stocks hold greater promise for delivering higher returns and doing so within a shorter time frame. If you are looking for an AI stock that is more promising than META and that has 10,000% upside potential, check out our report about this cheapest AI stock.

3 months ago
The "everyday millionaire" has a problem. It's not money. It's math.
In 2025, UBS coined the term EMILLI — Everyday MILLIonaire — to describe the 401(k) maximizer, the dual-income homeowner, the diligent index-fund investor who looked up one day and realized the number on their brokerage statement had crossed seven figures. It became shorthand for a particular brand of accessible aspiration: you didn't have to be a tech founder or a hedge fund manager. You just had to show up, stay invested, and wait.
The 2026 UBS Global Wealth Report, released Tuesday, confirms that the everyday millionaire class is expanding faster than at any point in 17 years. The U.S. added 441,078 new millionaires in 2025 alone — more than 1,200 per day, accounting for nearly half the global total. The millionaire population grew in all 56 of UBS' tracked markets simultaneously for the first time on record.
And yet. The group immediately above the EMILLI tier has been compounding wealth at a rate that makes the everyday millionaire's gains look, by comparison, like standing still.
UBS has a name for the cohort sitting just above the EMILLI tier: the "elder siblings." These are households with between $5 million and $100 million in net wealth—above the everyday millionaire threshold, below the billionaire stratosphere. Too rich to be relatable, not rich enough to be scandalous.
In 2025, UBS coined the term EMILLI — Everyday MILLIonaire — to describe the 401(k) maximizer, the dual-income homeowner, the diligent index-fund investor who looked up one day and realized the number on their brokerage statement had crossed seven figures. It became shorthand for a particular brand of accessible aspiration: you didn't have to be a tech founder or a hedge fund manager. You just had to show up, stay invested, and wait.
The 2026 UBS Global Wealth Report, released Tuesday, confirms that the everyday millionaire class is expanding faster than at any point in 17 years. The U.S. added 441,078 new millionaires in 2025 alone — more than 1,200 per day, accounting for nearly half the global total. The millionaire population grew in all 56 of UBS' tracked markets simultaneously for the first time on record.
And yet. The group immediately above the EMILLI tier has been compounding wealth at a rate that makes the everyday millionaire's gains look, by comparison, like standing still.
UBS has a name for the cohort sitting just above the EMILLI tier: the "elder siblings." These are households with between $5 million and $100 million in net wealth—above the everyday millionaire threshold, below the billionaire stratosphere. Too rich to be relatable, not rich enough to be scandalous.





