1 month ago
Huntington Bancshares Incorporated (NASDAQ:HBAN) dropped 5.55% to $15.82 on September 16, 2026, close to its 52-week low. The price movement was triggered by a profit warning at a Barclays conference. Huntington brought down its 2027 EPS guidance from above $1.90 to the range of $1.75-$1.83, and its 2026 net interest income growth from 39%-43% to roughly 35%. What matters more than these numbers is the reason behind them. Deposit costs are rising, and loan pricing is tightening, and it landed on the day the Fed delivered its first interest rate hike since 2023. The drop therefore raises the question: is this an oversold bank or the opening crack in regional-bank margins?
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth

1 month ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

1 month ago
The State Department's approval of two potential arms sales to Saudi Arabia totaling $5.75 billion, including JDAM-ER munitions and AGT-1500 tank engines, offers a modest but meaningful data point for two very different defense players. For The Boeing Company (NYSE:BA), the potential sale represents an additional international defense opportunity as the company continues working through margin pressure elsewhere. For Honeywell Aerospace Inc. (NASDAQ:HONA), the package reinforces a stable business line while the firm tackles its first quarter as a standalone public company.
The State Department approved a potential $5 billion sale of JDAM-ER guidance kits and bombs to Saudi Arabia, along with a separate potential $750 million deal for AGT-1500 tank engines. The JDAM package consists of 5,004 KMU-572 and 5,000 KMU-556 JDAM guidance kits and 5,004 BLU-111 and 5,000 BLU-117 bombs. Boeing has been identified as the principal contractor for the JDAM-ERs, with Honeywell handling the engines. The State Department said the sales would strengthen Saudi Arabia's airborne defense capabilities and improve interoperability with U.S. and Gulf partner forces.
Boeing stands to gain only modestly from the deal, given its roughly $85 billion Defense, ******* e and Security backlog. International orders already account for 27% of that total. The segment reported a second-quarter operating loss, largely due to charges tied to the VC-25B (Air Force One) program. That makes mature, lower-risk munitions programs such as JDAM-ER a more dependable part of the portfolio, though the deal is unlikely to have a meaningful impact on margins. For Honeywell Aerospace, the contract is smaller, but the AGT-1500 fits within its established defense propulsion business. It also adds to the company's international defence business, which makes up about 30% of its total Defense and ******* e revenue.
Honeywell Aerospace is owned by 74 hedge funds as of Q2 2026, which is consistent with Honeywell (NASDAQ:HON) hedge fund ownership prior to the spinoff. Unlike Honeywell, the number of hedge funds holding Boeing stock dropped from 99 at the end of the first quarter of fiscal 2026 to 90 at the end of Q2 2026.
Neither potential sale is large enough to have a meaningful impact on either company's short-term results by itself. Still, each supports a different investment story. For Boeing, the potential sales add to international defense exposure if finalized, as its defense unit continues dealing with fixed-price losses. For Honeywell, they support the steady flow of high-margin legacy revenue across its broader defense franchise.
#international #saudi

1 month ago
On September 4, RTX Corporation (NYSE:RTX) announced that its Pratt & Whitney business was investing $25 million to expand its manufacturing facility in Niepołomice, Poland.
The site produces complex tubular ****** emblies for both military and commercial engines. The expanded facility will begin operations in 2028 and create over 120 jobs.
Niepołomice already delivers precision components for several engines, including the F135, Pratt & Whitney GTF, and the PW800. The initiative complements the $100 million investment announced in April to boost production and enhance capabilities at the company's facility in Rzeszów, Poland.
The capacity expansion reflects the company's confidence in sustained demand for both commercial and military engine production over the coming years, which is supported by a record backlog of $289 billion at the end of Q2, increasing 22% year-over-year.
This further strengthens RTX Corporation (NYSE:RTX)'s manufacturing footprint in Europe, especially in Poland – which is already the company's largest presence outside the U.S. with more than 9,500 employees. The expansion will enhance its regional supply chain capabilities.
#Manufacturing

1 month ago
GE Aerospace's $11.75 billion purchase of Consolidated Precision Products, announced September 8, is billed as fixing the castings bottleneck behind the company's $170 billion services backlog and a spare-parts delinquency rate that grew 20% sequentially in the second quarter.
The deal will not close until the second half of 2027, covers roughly a quarter of GE's airfoil needs, and CFO Rahul Ghai has told investors twice this month that "broad vertical integration is not the solution," calling CPP a "unique situation."
Sell-side price targets jumped hard after the announcement, with the mean target rising from $350.95 on June 30 to $401.00 by September 16, pushing the target-to-price ratio to 128.2%, the widest gap in over a year.
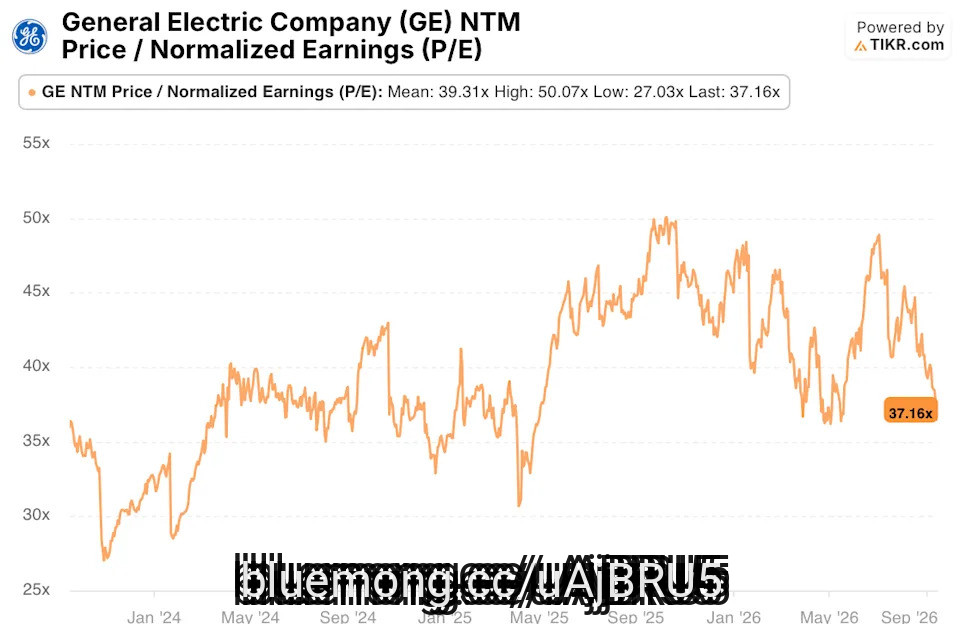
Over that same window, GE's share price fell from $373.73 to $312.90 and its NTM P/E multiple compressed to 37.16x, below its own two-year average of 39.31x and well off the roughly 50x peak reached a year earlier, even as consensus EPS estimates kept climbing smoothly through 2030 with no visible step-up.
GE Aerospace's (GE) own numbers make the case for urgency. Services backlog sits near $170 billion, internal shop visit capacity is running 40% oversubscribed, and spare-parts delinquency, shipments delayed by material shortages, grew 20% sequentially in the second quarter even as revenue rose. Management has said engines removed but not yet inducted into shops are up 60% year over year. That is the backdrop against which GE agreed to buy CPP, the world's third-largest maker of precision castings used in turbine blades and vanes.
#year #billion



1 month ago
On September 9, 2026, Reuters reported that GE Aerospace (NYSE:GE) agreed to buy castings maker Consolidated Precision Products for $11.75 billion. It is its largest acquisition since becoming a standalone company in 2024, to secure the supply of the precision metal turbine-blade components that have been a persistent bottleneck across the jet engine industry. CPP is the world's third-largest maker of these parts. CEO Larry Culp called the capacity "mission-critical" as the company works through a backlog stretching into the next decade.
GE Aerospace (NYSE:GE) can use the acquisition to convert its massive backlog into revenue faster. The company's backlog exceeded $210 billion after its second-quarter results. It includes roughly $170 billion in commercial services and more than $30 billion in defense. The $11.75 billion acquisition of Consolidated Precision Products directly targets one of the supply-chain bottlenecks that has limited GE's ability to increase engine production. CPP supplies about one-quarter of GE's casting needs. It gives GE greater control over a critical manufacturing process and could help it meet deliveries tied to its long-term backlog.
Bringing CPP in-house could improve GE's production economics while reducing supplier dependence. Spare-parts delinquencies jumped 20% sequentially in the second quarter. It shows the ongoing operational impact of supply constraints. GE plans to apply its Flight Deck lean operating model at CPP to improve factory yields and machine utilization and reduce scrap and rework. The company expects the acquisition to generate about $200 million in net synergies and achieve double-digit return on invested capital by the fifth year. It gives investors a measurable path to stronger returns from the deal.
The acquisition makes GE's position solid in the next generation of engines. GE expects demand for airfoils to increase more than 30% by 2030 from 2026 levels. CPP's casting expertise could help GE bring new airfoil designs into production faster. The business also expects CPP to make roughly $2 billion in revenue in 2027. That combination gives investors a potential path to higher production capacity, faster technology development, and stronger long-term participation in commercial and defense aerospace demand.
GE Aerospace (NYSE:GE) must justify a nearly $12 billion investment, and investors already ******* ign a premium valuation to the stock. GE Aerospace trades at roughly 46 times forward earnings. It leaves investors with limited tolerance for execution problems or weaker-than-expected returns. The company will fund $7 billion of the acquisition with cash and finance the remainder with new debt. So GE needs CPP's earnings and operating improvements to make sufficient returns to support the purchase price and protect shareholder value.
#billion #backlog #supply

1 month ago
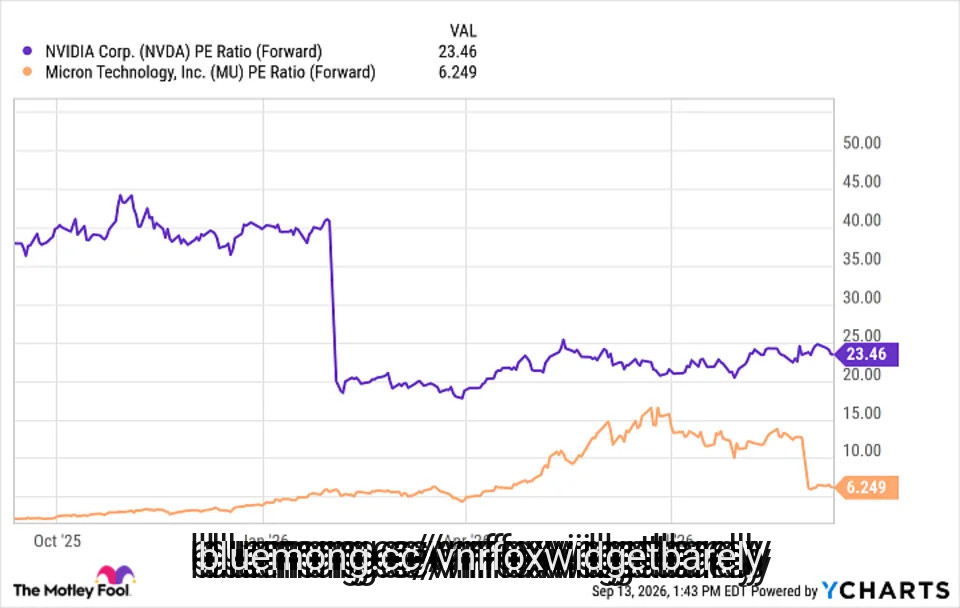
Between 2023 and 2025, Nvidia (NASDAQ: NVDA) was the market's most obvious artificial intelligence (AI) trade. During this period, the stock went parabolic, surging by 1,180% and turning the chipmaker into the world's most valuable company by market cap. On a split-adjusted basis, that was a climb from about $14 per share to $186 by the end of 2025.
Currently, Nvidia stock sits around $218, up another 17% year to date. This is what it looks like when a company owns a scarce product that's in heavy demand -- in this case, graphics processing units (GPUs).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron Technology's (NASDAQ: MU) rocket-like move came a bit later, but hit much harder. Memory chips were an afterthought during the initial GPU gold rush. But as training clusters got larger and inference workloads got hungrier, supplies of high bandwidth memory (HBM) started running short. Prices for HBM soared, and Micron stock responded epically -- rising 239% in 2025 and another 242% so far this year. This type of price action indicates the market has recognized that memory is no longer just another tech commodity -- its supply is one of the key bottlenecks dictating the pace at which data centers can be built.
Nvidia and Micron are not the same bet. While Nvidia sells engines, Micron is selling the tanks for the fuel these engines cannot operate without. This begs the question: At this point, which of these AI chip stocks would be the better one to buy and hold for the next five years?
#signal #Stock #chipmaker


1 month ago
GE Aerospace (GE) trades near $318, up 13.4% over the past twelve months. Behind that price sits a commercial services backlog of roughly $170 billion, work on engines already flying. The easy read is that the good news is in the price, and the coming three years just work that backlog off. A three-year scenario on the company's own numbers puts a size on what is left.
Revenue does most of the work. The scenario grows it 17.4% a year for three years, down from the 21.7% pace of the past twelve months, and net margin recovers some of the ground it has lost. Together they lift earnings about 67%.
The constraint is not demand. Management said in July that what lies ahead is much more a supply-side challenge than a demand one. Spare parts delinquencies, shipments held up for want of material, grew 20% sequentially in the second quarter of 2026.
GE Aerospace agreed in September to buy the castings maker Consolidated Precision Products. The deal shows where the bottleneck sits.
Then the multiple takes its cut. The scenario trims the P/E from 36.8x to 32.9x, because a slower revenue pace will not support what the market pays today. On those ******* umptions the stock would be worth about $475 in three years, roughly 50% above today.
#aerospace #revenue #price


1 month ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ******* et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
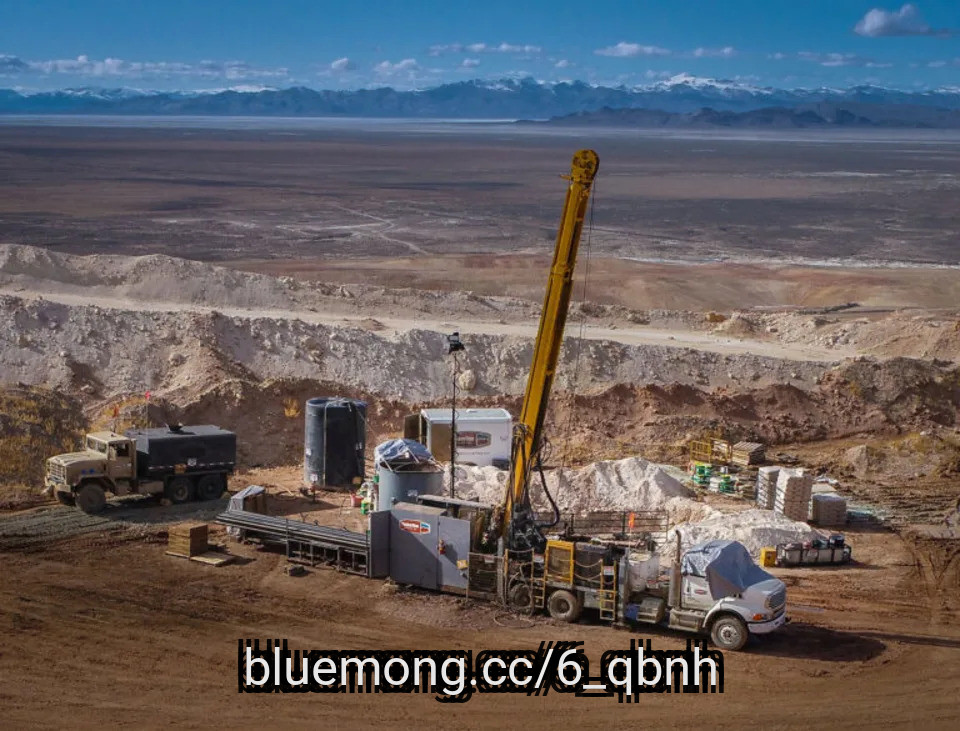
Photo from Hycroft Mining website
#letter

1 month ago
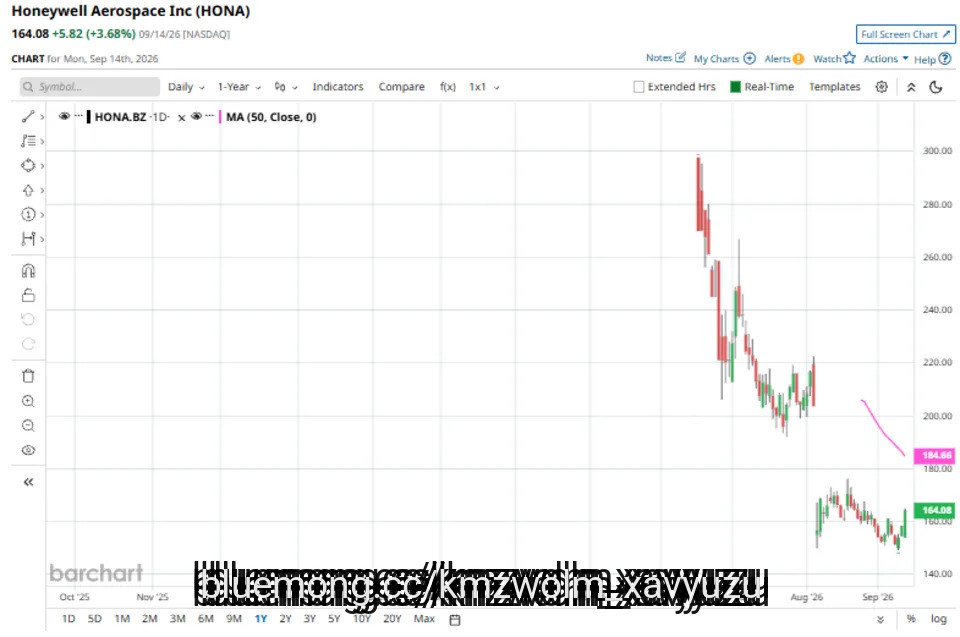
Based in Phoenix, Arizona, Honeywell Aerospace Inc. (HONA), is an aerospace company that develops engines, avionics, flight controls, navigation, sensors, propulsion systems, and other technologies for commercial aviation, defense, business aviation, and **** e applications.
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Honeywell Aerospace, with a market capitalization of approximately $50.2 billion, comfortably fits this category. Its diversified portfolio spanning avionics, engines, power systems, and controls makes it a key player within the aerospace and defense industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#aerospace #systems #aviation

1 month ago
Auxier ****** et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ****** et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ****** et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
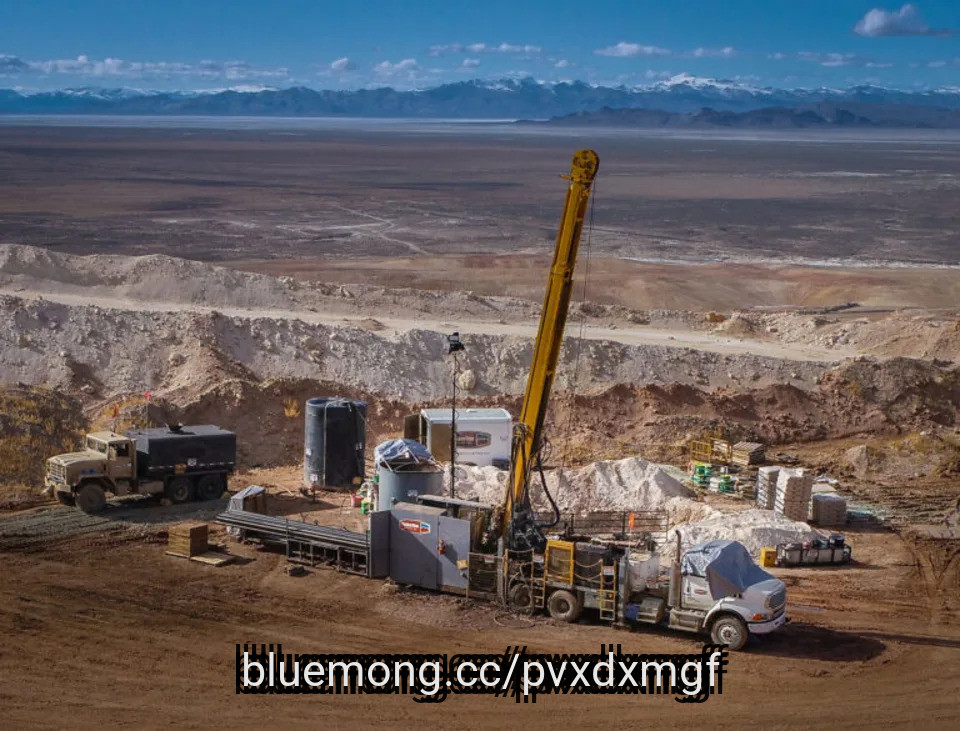
Photo from Hycroft Mining website
#quarter #asset #management #focus

1 month ago
Based in Phoenix, Arizona, Honeywell Aerospace Inc. (HONA), is an aerospace company that develops engines, avionics, flight controls, navigation, sensors, propulsion systems, and other technologies for commercial aviation, defense, business aviation, and ***** e applications.
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Honeywell Aerospace, with a market capitalization of approximately $50.2 billion, comfortably fits this category. Its diversified portfolio spanning avionics, engines, power systems, and controls makes it a key player within the aerospace and defense industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#aerospace



1 month ago
McLaren Automotive has announced a £500m investment programme to expand its UK manufacturing, engineering and operations, enabling it to accelerate the development of its next generation of models.
The investment forms part of a larger commitment from McLaren Automotive shareholder L'IMAD, a sovereign investor of the Government of Abu Dhabi, and reinforces McLaren's commitment to Britain, where Bruce McLaren founded the company in 1963.
Expanding McLaren Automotive in the UK
The company said the investment will enable McLaren Automotive to expand its production capability, increasing vehicle output to ensure the next generation of McLaren Automotive cars are built in Britain 'including a newly confirmed performance SUV'. This will be made possible by a new vehicle ****** embly facility planned in the UK.
For the first time in its history, McLaren Automotive's future powertrains will be designed and built in-house, starting with two new engines and transmissions. This will support the company's hybrid engine strategy, building on McLaren Automotive's use of hybrid technology, which started with the McLaren P1.
#next


1 month ago
On August 4, Willis Lease Finance Corporation (NASDAQ:WLFC) reported second-quarter results that pulled in two directions at once. The lessor of commercial aircraft engines grew its operating business at a healthy clip, yet net income fell by more than half, a split that makes this quarter harder to read than the headline suggests.
Income from operations climbed 20.2% to $34.0 million in the quarter ended June 30, 2026, and the engine underneath that number is lease rent revenue, which rose 6.7% to $77.1 million as the average size of Willis Lease's portfolio expanded from a year earlier. Over the first six months of 2026, lease rent revenue is up 10.4% to $154.5 million, a steadier pace than the quarterly figure alone implies.
The company's trading business added to that. Willis Lease booked a $32.0 million gain on the sale of leased equipment, up 16.2%, after selling 21 engines and other parts and equipment during the quarter, compared with 14 engines and two airframes a year earlier. That kind of turnover matters for a leasing company, since selling ****** ets at a gain confirms that engine values in the market are holding up.
The bigger story sits in how Willis Lease is expanding beyond its own balance sheet. ****** ets under management, which folds in the company's on-balance-sheet fleet along with its Willis Aviation Capital business, grew 21% year over year to $4.4 billion. CEO Austin C. Willis tied that growth directly to building out Willis Aviation Capital, and the fee income backs that up: management and advisory fees jumped 113.4% to $5.5 million in the quarter and 194.9% to $13.4 million over six months. Two new investment fund partnerships, one with Liberty Mutual Investments that began operating in March 2026 and one with Blackstone Credit & Insurance that started in April 2026, are the mechanics behind that shift toward managing other people's capital rather than only deploying its own.
Net income attributable to common shareholders fell 51.2% to $28.7 million, and diluted earnings per share dropped from $2.81 to $1.31. Some of that gap traces to a tough comparison rather than a weaker quarter, since the second quarter of 2025 included a $43.0 million gain from the sale of the BAML business that had no counterpart this year. Willis Lease also recognized a $5.4 million loss on debt extinguishment in the quarter, and $12.4 million over six months, a cost tied to refinancing that simply was not there in 2025.
#lease #capital #months

1 month ago
Costco has raised the price of its Kirkland Signature full-synthetic motor oil and begun limiting how much any one member can purchase, as a global lubricant shortage tied to the ongoing Middle East conflict pushes crude oil toward $100 a barrel.
That 10-quart case — two 5-quart bottles, enough for a typical V6 or V8 oil change — has jumped to $57.99, compared with the roughly $30 price members had grown accustomed to paying, according to The Drive. Stores are capping purchases at two units per customer per week. The retailer has also imposed a five-per-member limit on Mobil 1, with six quarts of that brand running $44.
The rationing reflects pressure from multiple directions. The connection to fuel prices runs through the refinery: base oil shares its crude-oil origins with gasoline and diesel, so when margins on finished fuel are strong, refiners have a financial reason to favor fuel production over lubricant stock, according to The Auto Wire. EIA data showed the gasoline crack spread sitting roughly a dollar per gallon higher than where it stood at the same point in 2025, a gap that has squeezed base oil availability and pushed its price upward.
Regulatory and licensing costs add a separate layer of expense. The Kirkland 5W-30 displays the dexos1 Gen 3 certification, GM's proprietary specification, and earning that mark is not free — manufacturers must put their formulation through GM's independent testing protocol and obtain a license from the automaker, paying separately for each product and each unit sold, according to The Auto Wire. Layered on top of that is an industry-wide burden: when the API SP category took effect around 2020, it introduced seven additional laboratory tests with no equivalent in the previous standard, among them a procedure targeting low-speed pre-ignition, the knock-like detonation problem **** ociated with modern turbocharged, direct-injection engines.
The supply squeeze is unfolding against a backdrop of a worsening global oil deficit. The International Energy Agency cut its 2026 global oil supply forecast to 102 million barrels per day in August, projecting a deficit of 1.8 million barrels per day in the third quarter — more than double its prior estimate. **** ulative global inventory draws since the start of the U.S.-Iran conflict have reached more than 500 million barrels, and Chevron CEO Mike Wirth said last week that the cushions that had softened earlier price increases have been exhausted. U.S. diesel prices crossed $6 per gallon for the first time, sitting at $6.06 as of Monday, an 8-cent increase from Sunday and 21 cents above week-earlier levels, according to AAA.
#barrels #wire

2 months ago
GE Aerospace (NYSE:GE) is making its largest acquisition since becoming a standalone publicly traded company. It agreed to acquire Consolidated Precision Products (CPP) for around $12 billion.
CPP is one of the world's largest precision castings providers. It's a major GE supplier. Precision castings is a major pressure point for the aerospace engines industry. Acquiring CPP would give GE Aerospace greater control over a critical part of its engine supply chain.
And the deal could strengthen GE's ability to meet demand already sitting in its backlog. But the investment case depends on whether additional production capacity generates enough free cash flow to justify the deal's premium price.
rommma/Shutterstock.com
Engine manufacturers like GE Aerospace (NYSE:GE) are struggling to keep pace with surging demand due to supply chain constraints. CPP is a major supplier of precision castings for GE's LEAP and GEnx engines. GE plans to raise CPP's output. It would do that by improving factory yields and machine use. With the CPP deal, GE also sees a path to accelerate production of new engine technologies.
#NYSE #largest #engines #supply


2 months ago
On September 8, 2026, GE Aerospace (NYSE:GE) agreed to buy Consolidated Precision Products (CPP) for $11.75 billion. The acquisition marks the company's largest bet yet on precision engine castings, a constraint that has been capping GE's growth. Trading already at roughly 40x earnings, the company has now attacked one of its genuine bottlenecks through the deal. But has it paid too much to do it?
Castings, including the superalloy and ******* anium hot-section parts inside the jet engines, have constrained GE's engine production, including programs such as LEAP and GEnx, as well as its high-margin aftermarket. Without these castings, the company can neither build nor service its engines. If the acquisition closes, the company will gain access to CPP's 20-plus plants and about 6,600 workers, which are essential for making those components. The deal would therefore enable GE to control the constraint as well as defend its margins. CEO Larry Culp characterized the move as securing manufacturing capacity to meet simultaneous demand across commercial engines, aftermarket services, and defense contracts.
The valuation is where bulls should slow down. GE is paying roughly 18x 2027 EBITDA including synergies (26x without synergies). The sellers are private equity firms Warburg Pincus and Berkshire Partners. They have basically offloaded a cyclical business near the peak of the aerospace cycle. This is smart money selling to GE instead of the other way around. The real tell is that GE felt compelled to buy its way past this capacity bottleneck instead of scaling organically, which reveals how tight its prized aftermarket really was. Also, CPP also supplies other major aerospace and defense companies such as Pratt & Whitney, Honeywell, and Lockheed Martin, and through the vertical tie-up, the company invites antitrust scrutiny before it closes in late 2027.
GE's 40x multiple rests on its high-margin razor-and-blade business model that services a huge installed base. And the casting supply shortages quietly constrain this aftermarket. Hence, more than merely fixing a supply chain issue, the CPP acquisition defends the company's high margin and multiple. Financially, the transaction is accretive to adjusted EPS and free cash flow in the first year, funded through $7 billion in cash alongside newly issued debt. Insider Monkey data shows 113 hedge funds held GE in Q2 2026, down modestly from 119 in Q1, reflecting firm institutional positioning. Short interest is just 1.3% of float, below peers like Honeywell International (1.6%). Almost no one bets against it.
#aftermarket #acquisition #including


2 months ago
During a September 8 episode of Mad Money, Jim Cramer examined the broader aerospace ecosystem following GE Aerospace's (NYSE:GE) nearly $12 billion agreement to acquire castings specialist Consolidated Precision Products (CPP). Commenting on the strategic importance of supply chain control and the enduring strength of commercial and defense aviation despite rising oil prices, Cramer stated:
I still believe in the data center, but I also want to open your eyes to other opportunities. This morning, for example, GE Aerospace spent nearly $12 billion to buy a castings company called Consolidated Precision Products to integrate this key segment into its supply chain. It's vital for both commercial aircraft and particularly defense, both of which are booming. Now, on a day where oil's up, you might not want to focus on anything airline related, but travel's been booming the whole time, the whole time the Iranian war's been going on. This acquisition will pay off quickly for GE, making it more likely that they can accelerate production. This is also good news, therefore, for Boeing, a huge customer of GE that needs to boost its production speed.
GE is relatively close to its highs, deservedly so. Boeing? Nowhere near its high. Yet the order book is full. Last week, there was this negative article about how Boeing is being hurt by the problem-filled Spirit AeroSystems acquisition. It made that one two years ago. But that actually had to be done because Boeing, like GE Aerospace, needs to get better control of its supply chain. Aha, you say, who needs that kind of problem? Boeing just reported its slowest deliveries in 4 months. I come back and say, wait a second. First, the problems from the Spirit deal are now behind them. You know what? The story is actually old news.
Plus, CEO Kelly Ortberg has made it clear that orders would be lumpy. I knew that. And look, I know the high price of oil, particularly jet fuel, is bad news for the airlines. But the higher price of fuel also makes these new engines and airplanes far more valuable than before. Why? They're way more energy efficient. It's a good situation that has nothing to do with the data center. It does require more, better tech that AI can help with.
GE Aerospace (NYSE:GE) and The Boeing Company (NYSE:BA) represent two distinct pillars of the aerospace manufacturing ecosystem, operating at massive commercial scale. GE Aerospace reported second-quarter revenue of $13.3 billion, up 21% year-over-year, driven by strong commercial engine services and record internal shop visit output. Its total order backlog extends past $210 billion, supported by sustained airline demand for propulsion systems and aftermarket maintenance.
#boeing #chain #consolidated


2 months ago
You can find original article here WealthManagement. Subscribe to our free daily WealthManagement newsletters.
Edelman Financial Engines is extending its retirement plan advisory and fiduciary capabilities to the small and mid-sized business market. While the firm has long served business owners through its workplace and wealth businesses, this service focuses on helping smaller business owners offer and manage retirement plans for their employees.
The firm has partnered with ADP for payroll, human capital management and retirement services. Edelman's will provide investment management, 3(38) investment management, plan consulting and personalized financial advice to plan participants. That includes providing one-on-one discretionary advisory services for individual employees.
Employees also gain unlimited access to Edelman's phone-based licensed advisors, who average 10 years of industry tenure, along with on-demand digital planning tools.
"EFE financial wellness and advisory services have been available to employees in eligible workplace retirement plans through the ADP platform since 2018," said Chris Magno, senior vice president and general manager of ADP Retirement Services, in a statement. "The new service expands that relationship by delivering a more comprehensive retirement solution purpose-built for small and mid-sized businesses, offered in combination with the full-service recordkeeping, payroll integration and plan administration capabilities of ADP."
#Services #management #wealthmanagement


2 months ago
On August 6, Nova (NASDAQ:NVMI) reported second-quarter 2026 results for the three months ended June 30, and the numbers marked a new high point for the semiconductor metrology company. Revenue hit $255.0 million, up 8% from the first quarter of 2026 and 16% higher than the second quarter of 2025. GAAP net income reached $75 million, while non-GAAP net income climbed to $86.5 million. For a company built around measuring the tiniest details in chip manufacturing, the quarter itself was anything but small.
The headline figures tell part of the story, but the breakdown underneath is where the quarter gets interesting. GAAP earnings per diluted share reached $2.20 in the second quarter of 2026, up from $2.04 in the first quarter of 2026 and $2.14 a year earlier in the second quarter of 2025. Non-GAAP earnings per diluted share went further, hitting $2.51 in the second quarter of 2026 compared with $2.33 in the first quarter of 2026 and $2.20 in the second quarter of 2025. That is back-to-back sequential growth on both a GAAP and non-GAAP basis, not just a single strong quarter against an easy comparison.
Two product lines did the heavy lifting. Nova posted record revenue from its advanced logic devices business, which it tied to the industry's shift toward Gate-All-Around transistor architecture and rising demand for advanced process nodes. Advanced packaging solutions also hit a record, supported by capacity additions across both logic and memory manufacturing. Those are two distinct growth engines firing in the same quarter, which matters more than a single hot product line would.
Management is not treating this as a one-off. For the third quarter of 2026, the period ending September 30, Nova guided to revenue of $277 million to $287 million, GAAP diluted EPS of $2.46 to $2.61, and non-GAAP diluted EPS of $2.70 to $2.85. At the midpoint, that outlook points to another double-digit sequential jump in sales. President and CEO Gaby Waisman framed the quarter as validation of the company's long-term plan, citing broad-based customer demand, continued market share gains, and deeper engagement across leading-edge device segments as the drivers behind what he described as increased visibility into coming quarters.
The results were not clean across every line. Gross margin came in at 56.5% in the second quarter of 2026, down from 57.7% in the first quarter of 2026 and 57.8% in the second quarter of 2025. That is a decline on both a sequential and year-over-year basis even as revenue set records, which means the mix of what Nova sold this quarter carried lower profitability than what it sold a year ago.
#quarter #gaap

2 months ago
CNBC reported that Chris Churchman, The Goldman Sachs Group, Inc. (NYSE:GS) partner who leads the bank's Marquee digital platform for institutional clients, warned that AI's spread across Wall Street risks eroding the reasoning skills of the next generation of bankers.
Churchman said on Goldman's internal "Exchanges" podcast, "There's a huge danger here that in the era of AI, we outsource our reasoning to these models, and we have cognitive atrophy that stops us being able to reason from first principles ourselves." He compared it to how GPS and search engines eroded navigation skills and said much of banking's knowledge is learned only "by doing." Churchman said the firm has not yet determined how it will manage the transition.
The Goldman Sachs Group, Inc. (NYSE:GS) is surfacing this risk proactively, through its own senior AI leadership, rather than being caught off guard by it later. Having the executive who leads Marquee flag the danger publicly signals internal scrutiny that could help Goldman build safeguards into its AI rollout before problems show up in deal execution. It is an advantage over firms deploying AI without asking the same questions.
The near-term efficiency case for AI remains fully intact regardless of the long-term talent question. CNBC itself framed the tradeoff as a "devil's bargain" that could make the industry more profitable today while potentially eroding the talent it needs for tomorrow. It means Goldman still captures AI's productivity benefits now even as it works out the downstream risk.
Marquee itself is a genuine strategic **** et getting AI investment. The platform, through which hedge funds and other large institutional clients access Goldman's market data, research, **** ytics, and execution tools, is being built out with AI features, which positions it as a differentiated offering for Goldman's most valuable client relationships.
#churchman #marquee #cnbc #sachs
2 months ago
Dorian LPG has agreed an order with South Korean shipbuilder Hanwha Ocean for the construction of three 90,000m³ dual-fuel Panamax very large gas carriers (VLGCs) for a total price of around $345m (Won463.5bn).
The three ships are scheduled for delivery in June, September and December 2030.
Each VLGC will be fitted with dual-fuel engines capable of burning liquefied petroleum gas (LPG) or conventional low-sulphur fuels. They will also feature a shaft generator system that allows power to be produced on board during sea passages.
Hull forms and main engines have been designed to take larger-diameter propellers and energy-saving devices around the propellers, which the company said improves overall energy efficiency.
Dorian LPG said the Panamax dimensions give its charterers commercial flexibility to transit the old Panama Canal locks.
#three #fuel #south

2 months ago
On August 6, Nova (NASDAQ:NVMI) reported second-quarter 2026 results for the three months ended June 30, and the numbers marked a new high point for the semiconductor metrology company. Revenue hit $255.0 million, up 8% from the first quarter of 2026 and 16% higher than the second quarter of 2025. GAAP net income reached $75 million, while non-GAAP net income climbed to $86.5 million. For a company built around measuring the tiniest details in chip manufacturing, the quarter itself was anything but small.
The headline figures tell part of the story, but the breakdown underneath is where the quarter gets interesting. GAAP earnings per diluted share reached $2.20 in the second quarter of 2026, up from $2.04 in the first quarter of 2026 and $2.14 a year earlier in the second quarter of 2025. Non-GAAP earnings per diluted share went further, hitting $2.51 in the second quarter of 2026 compared with $2.33 in the first quarter of 2026 and $2.20 in the second quarter of 2025. That is back-to-back sequential growth on both a GAAP and non-GAAP basis, not just a single strong quarter against an easy comparison.
Two product lines did the heavy lifting. Nova posted record revenue from its advanced logic devices business, which it tied to the industry's shift toward Gate-All-Around transistor architecture and rising demand for advanced process nodes. Advanced packaging solutions also hit a record, supported by capacity additions across both logic and memory manufacturing. Those are two distinct growth engines firing in the same quarter, which matters more than a single hot product line would.
Management is not treating this as a one-off. For the third quarter of 2026, the period ending September 30, Nova guided to revenue of $277 million to $287 million, GAAP diluted EPS of $2.46 to $2.61, and non-GAAP diluted EPS of $2.70 to $2.85. At the midpoint, that outlook points to another double-digit sequential jump in sales. President and CEO Gaby Waisman framed the quarter as validation of the company's long-term plan, citing broad-based customer demand, continued market share gains, and deeper engagement across leading-edge device segments as the drivers behind what he described as increased visibility into coming quarters.
The results were not clean across every line. Gross margin came in at 56.5% in the second quarter of 2026, down from 57.7% in the first quarter of 2026 and 57.8% in the second quarter of 2025. That is a decline on both a sequential and year-over-year basis even as revenue set records, which means the mix of what Nova sold this quarter carried lower profitability than what it sold a year ago.
#second #diluted #advanced


2 months ago
On August 4, Archrock (NYSE:AROC) posted second-quarter results that told two different stories at once. Revenue slipped to $371.2 million from $383.2 million a year earlier, yet net income climbed to $66.7 million, and earnings per share rose to $0.38. That gap between a shrinking top line and a growing bottom line is the puzzle this quarter leaves investors to sort out.
The clearest bull signal came from a new long-term agreement with an existing strategic customer covering roughly 665,000 horsepower, structured with an eight-year base term and a two-year extension option. That kind of commitment locks in cash flow well into the next decade and reinforces management's multi-year growth capital expenditure guidance of $1.4 billion to $1.6 billion **** ulatively from 2027 through 2030. The core contract operations segment backed that confidence with real numbers. Revenue there rose 3% to $329.3 million, and adjusted gross margin improved to 71% from 70%, with period-end utilization at 94.4%.
The balance sheet also moved in the right direction. Archrock's leverage ratio fell to 2.6x as of June 30, down from 3.3x a year earlier, even after the company redeemed its entire $800 million of 6.250% senior notes due 2028 on April 1. The board kept rewarding shareholders through it all, declaring a quarterly dividend of $0.23 per share, about 10% higher than a year ago, marking the fifth increase in two years, with coverage still comfortable at 3.1x.
The softer parts of this quarter center on aftermarket services and forward guidance. That segment's revenue fell to $42.0 million from $64.8 million, as last year's non-recurring sales of overhauled engines did not repeat and maintenance demand skipped its usual mid-year seasonal **** p. Total operating horsepower also declined to 4.5 million from 4.7 million, partly from the sale of about 165,000 non-strategic units.
On the guidance front, Archrock tightened its full-year adjusted EBITDA range to $865 million to $885 million, down from a prior range of $865 million to $915 million, pointing to lube oil cost pressure, higher make-ready spending to reactivate idle equipment, and increased SG&A tied to stock-based incentive compensation. Adjusted net income actually dipped to $66.5 million and adjusted EPS to $0.38, both slightly below last year's $68.4 million and $0.39. Long-term debt still sits at $2.3 billion, and Archrock did not repurchase any shares during the quarter, leaving $113.2 million of buyback capacity untouched.
#million

2 months ago
During the August 31 episode of Mad Money, Jim Cramer examined the sharp rotation back into enterprise software following the forced unwinding of bearish hedge fund positions. Mentioning Veeva Systems Inc. (NYSE:VEEV) and Salesforce, Inc. (NYSE:CRM) as examples of sector leaders, he commented:
Situational Awareness just despised enterprise software and Veeva Systems, number three, up 40%, is enterprise software writ large for the healthcare industry. I think it's bounced back in conjunction with all the other enterprise software companies that Situational Awareness believed would be destroyed by AI that haven't been. Once that hedge fund blew up, the whole group came roaring back as Situational was no longer there to put pressure on them. Hey, Salesforce had a similar rally, up nearly 40%. Now, here's one that openly took on the short sellers first with rhetoric and then with numbers which have not been hurt at all by… the SaaS-pocalypse. His blowout quarter obliterated the shorts. I don't think they still know what hit them.
For months, bearish macro funds aggressively shorted enterprise software providers, on the belief that emerging artificial intelligence platforms would easily replicate proprietary workflows and trigger severe pricing compression.
Salesforce, Inc. (NYSE:CRM) and Veeva Systems Inc. (NYSE:VEEV) proved the exact opposite. Salesforce showed that autonomous enterprise features act as expansion engines. Similarly, Veeva Systems, which powers critical clinical and commercial operations for the heavily regulated life sciences sector, integrated advanced data capabilities directly into its platform. Rather than cannibalizing software licenses, artificial intelligence features reinforced the massive switching costs embedded in both platforms.
Despite solid execution, market skeptics continue to scrutinize the growth limits and valuation multiples of both companies. Salesforce, Inc. (NYSE:CRM) trades at a forward P/E of 19x, showing market hesitation over macroeconomic budget tightening and the necessity for the company to rapidly monetize its heavy artificial intelligence investments.
#salesforce #situational #artificial #intelligence


2 months ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Global Opportunity Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 26.7% (Institutional Shares), exceeding a 14.9% gain for the MSCI ACWI Index (the Index), and a 19.8% gain for the MSCI ACWI Growth Index. YTD, the Fund is up 20.6% compared to gains of 11.3% and 10.6% for the benchmarks, respectively. In mid-2026, market patterns show similarities to the previous year, following three years of over 25% gains driven by a healthy economy and AI investments. Elevated geopolitical risks persisted, with a pullback likely. A tariff-related market dip was followed by a recovery, reflecting a growing market indifference to geopolitical uncertainties. Similarly, airstrikes against Iran and subsequent tension led to an initial market sell-off, yet a lull in hostilities led to a strong market rally. The Fund noted significant outperformance, credited to stock selection and sector allocation, with 1,173bps of overall outperformance relative to the Index. It excelled in developed markets while underperforming in emerging markets, particularly due to a spectacular rise in Korea. The Fund remains optimistic about its investments and seeks attractive opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Global Opportunity Fund highlighted DPC Holdings PLC (NYSE:DPC) as a new addition. DPC Holdings PLC (NYSE:DPC) manufacturers engine products, including complex precision cast components and nickel- and cobalt-based superalloys for aerospace, industrial gas turbine and transportation industries. On September 1, 2026, DPC Holdings PLC (NYSE:DPC) closed at $41.48 per share. Over the past month, DPC Holdings PLC (NYSE:DPC) declined 20.69%. DPC Holdings PLC (NYSE:DPC) has a market capitalization of $6.02 billion.
Baron Global Opportunity Fund stated the following regarding DPC Holdings PLC (NYSE:DPC) in its Q2 2026 investor letter:
We also initiated a new position in DPC Holdings PLC (NYSE:DPC), a leading manufacturer of precision-cast superalloy components – the turbine blades, vanes, and structural castings that must perform under very harsh operating conditions including very high temperatures (1000c) and high pressure. These parts go into both commercial aircraft engines and industrial gas turbines (IGT) that generate electricity. The company occupies a hard-to-replicate market positioning as a critical supplier of the inner parts of an engine that only a handful of qualified manufacturers in the world are capable of producing.
Since the company began its turnaround in 2020 after over a decade under poor ownership, with the leadership of CEO Mike Quinn, who spent over a decade at Precision Castparts, and Co Chairperson of the Board Dirkson Charles, who built and currently is CEO of aerospace and defense proprietary parts provider

2 months ago
Valued at a market cap of $355.4 billion, GE Aerospace (GE) is a global leader in aerospace propulsion, services, and systems, supporting commercial and military aviation worldwide. With a large installed base of aircraft engines and a global workforce, the company builds on more than a century of innovation and industry expertise.
Companies worth more than $10 billion are generally described as "large-cap" stocks, and GE Aerospace fits this criterion perfectly. GE Aerospace is focused on advancing the future of flight while improving safety, performance, and reliability.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
#large
2 months ago
Irving, Texas-based Caterpillar Inc. (CAT) manufactures and sells construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives in the United States and internationally. The company has a market capitalization of $367.9 billion and is one of the world's largest manufacturers of the said equipment.
Companies with a market cap of $200 billion or more are typically referred to as "mega-cap stocks." CAT fits perfectly into that category, with its market cap exceeding this threshold and reflecting its substantial size and influence in the farm and heavy construction machinery industry.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Tesla Stock Could Benefit as Trump Locks Down the U.S. Power Grid
#Stock #construction #Diesel #billion


2 months ago
POET (NASDAQ: POET) secured a $50 million Lumilens purchase order, and our model sees 137% upside to a $17.74 BUY price target.
Lumentum (LITE) generates $1 billion quarterly on the same optical tailwind; Applied Optoelectronics (AAOI) proves hyperscale-qualified 800G suppliers command premium multiples.
POET holds $796 million in cash to fund its Malaysia production ramp, but four of its last five earnings reports missed estimates.
Act now: the ****** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Poet Technologies didn't make the cut. Grab the names FREE today.
POET Technologies (NASDAQ:POET) is a small-cap photonics designer building optical engines for 400G, 800G, and 1.6T data center interconnects, the plumbing hyperscalers need to move AI traffic without melting their power budgets. With a fresh $50 million purchase order from Lumilens in hand, our proprietary model sees room for a sharp re-rating.
#order

2 months ago
The wait for a large gas turbine now runs longer than the time it takes to design, permit, and build the plant it will sit in. Order one today from any of the three largest manufacturers, and the delivery slot lands four or more years out—if a slot is available at all. The queue to connect a new plant to the grid runs about as long. For developers racing to power the data centers hyperscalers are building, the timeline no longer works, and it is pushing the U.S. generation build toward whatever can be constructed without waiting in either line.That dislocation is the backdrop to a quieter story about where capital is moving, and it surfaced in July when a familiar U.S. plant operator changed hands. IHI Power Services Corp., a company with roughly four decades of experience running American power plants, became Kyuden Energy Partners Corp. on completion of its acquisition by Kyuden International Corp., the overseas arm of a company fully owned by **** an's Kyushu Electric Power Co. The rebrand is the news of the day. The more instructive part is what a foreign utility chose to buy: not power plants, but the capability to run them.
Tony Dabbene, who led IHI Power Services through the transition and stays on as CEO, was blunt about the market. "We are seeing the most dynamic environment in decades," he told POWER, pointing to demand tied to the hyperscalers' data center buildout. Major gas turbine manufacturers, he said, are quoting lead times of four-plus years, with interconnection queues running about the same. The manufacturers' own disclosures bear that out: GE Vernova's gas turbine backlog and slot reservations reached 116 GW by mid-2026, and Siemens Energy has described itself as booked into the back half of the decade, treating 2029 delivery slots as near-term availability.What Dabbene described next was the market's response. Rather than wait for an interconnection that may not clear before mid-decade, developers are building behind the meter and on private grids that sidestep the queue entirely. To power them, they're reaching for whatever can be deployed the fastest: reciprocating engines, fuel cells, and battery storage paired with microgrids, engineered to achieve the high-availability targets that around-the-clock computing demands while managing the power-quality swings that come when those loads shift in an instant. "It is a brand-new world in the energy **** e," he said.This is where a multi-fuel operator has the edge. A company that already runs natural gas, hydro, biomass, wind, solar, and storage has done the work developers are now rushing toward—operating mixed generation and meeting high availability targets. The turbine shortage may be a headache for those building facilities, but it's an opportunity for reliable operators.
#corp #runs #plant #four