

2 days ago
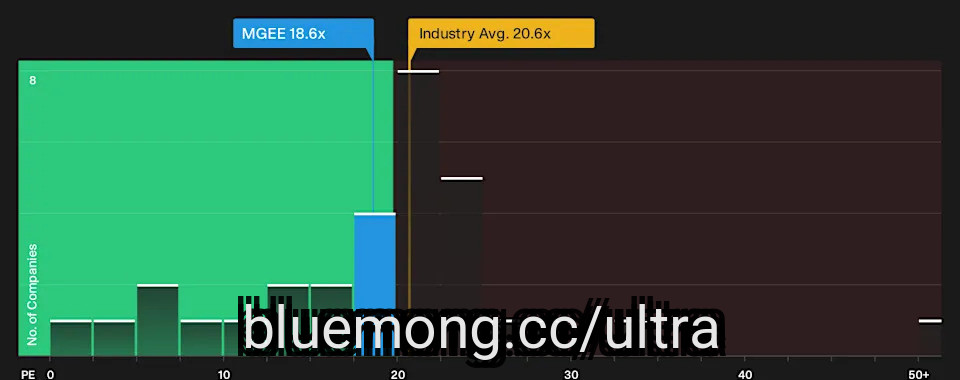
Rates stuck in a holding pattern, inflation still above target and the Fed hinting it may not be done yet. That mix keeps pressure on growth stories and puts steady cash payers back in the spotlight. Investors hunting for resilience and reliable income are watching this closely, because moments like this can reshape portfolios for years. This article walks through 3 dividend stocks exposed to this macro story.
The stocks covered next are just a sample to illustrate the idea. The full screen surfaced 18 more large-cap defensive dividend companies with income profiles and risk characteristics that also fit this tighter brief. If you want to identify and ******* yze your own shortlist of higher-conviction defensive payers right now, head straight into the Large-Cap Defensive Dividend Stocks (US) screener.
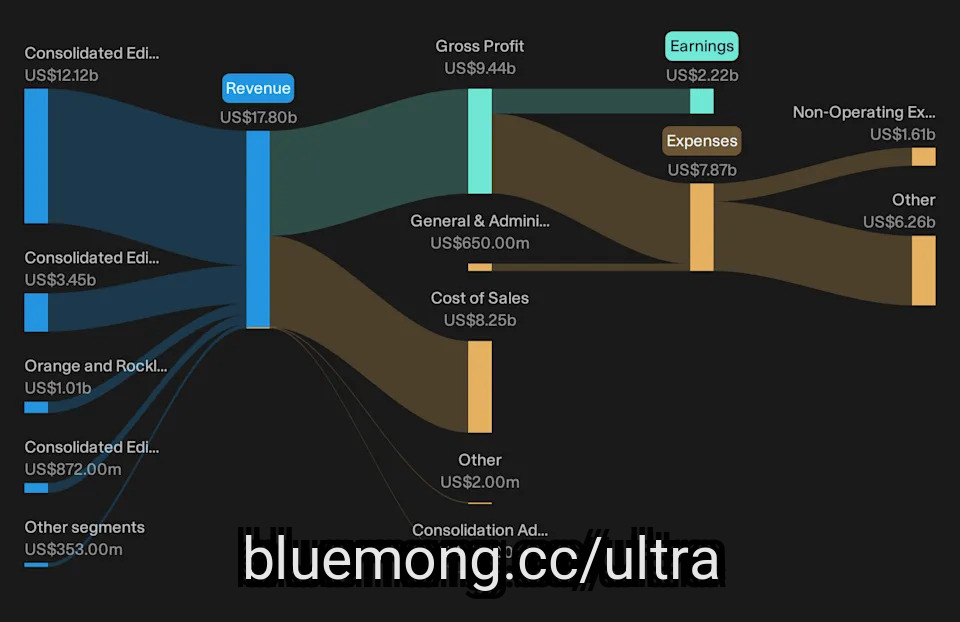
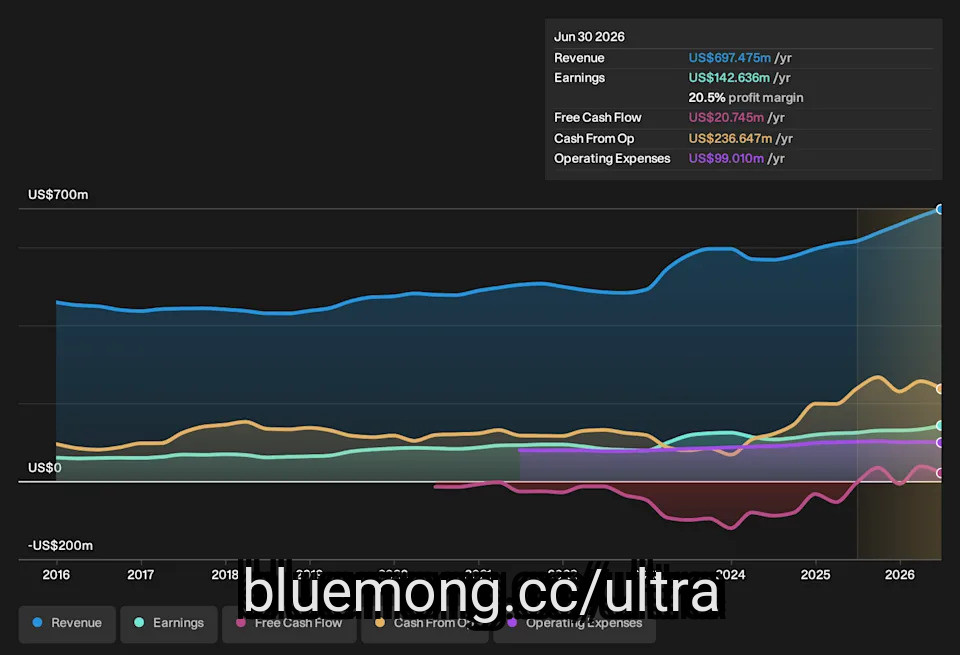
Overview: Consolidated Edison is a regulated utility that delivers electric, gas and steam services to customers across New York and parts of New Jersey.
Operations: Consolidated Edison generates almost all of its roughly US$17.7b revenue from US$12.1b CECONY electric, US$3.4b CECONY gas and US$872 million steam operations in the United States.
#edison #income

1 month ago
SPX Technologies, Inc. (NYSE:SPXC) announced on September 15 that it completed the acquisition of FIS Water, LLC for approximately $410 million in cash, including certain tax attributes. The acquired business is expected to generate approximately $105 million of revenue in 2026.
That is FIS Water's full-year revenue forecast; its contribution to consolidated 2026 results will reflect the ownership period. The stated cash consideration equals approximately 3.9 times expected annual revenue, making profitability and cash conversion central to the investment case.
FIS Water expands the products SPX Technologies, Inc. (NYSE:SPXC) can supply to cooling customers. Its filtration and flow-control products remove solids, maintain water quality, and regulate water movement in commercial and industrial cooling systems, including data centers.
The business has joined the HVAC segment, covering heating, ventilation and air conditioning, within its Cooling operations. Its products complement existing cooling-tower offerings, while its valves and actuators also fit the recently acquired Neptronic controls business.
The strategic attraction is customer overlap. Management identified shared customers, engineering specifications and sales channels, and plans to use its global distribution and equipment-manufacturer relationships to support growth.
#cooling #NYSE

1 month ago
On August 6, Targa Resources Corp. (NYSE:TRGP) reported a record second quarter. Adjusted EBITDA reached $1.60 billion, a 38% jump from the same period a year earlier, and management now expects full-year results near the top of its guidance range. Targa moves and processes natural gas and natural gas liquids out of the Permian Basin, and these numbers suggest that system is running fuller than ever.
The strength came from volume, not just price. Adjusted EBITDA also climbed 14% from the first quarter, helped by Permian gas volumes that added over 450 million cubic feet of daily throughput. Some producers held back output because Waha gas prices went negative, and Targa still set a volume record. Volumes for NGL pipelines, fractionation, and LPG exports also hit records, helped by Train 11, a new fractionator in Mont Belvieu, Texas, that started up early in the quarter.
Construction is also landing on time. East Driver, a new processing plant serving the Midland side of the Permian, started up late in the quarter and ahead of schedule, and the other gathering and logistics projects are tracking their plans. Shareholders get a cut too. On July 16, Targa declared a $1.25 per share quarterly dividend, 25% above the payout for the second quarter of 2025, payable August 14 to holders of record on July 31. It also spent $80 million buying back shares during the quarter.
Growth at this pace costs real money. Targa plans about $4.5 billion in net growth spending this year, and its consolidated debt stood at $19,578 million on June 30. About $3.2 billion of liquidity gives it a cushion. In July, it also extended its receivables securitization facility to July 30, 2027 and raised the size to as much as $800 million. More borrowing capacity helps, but it is still borrowing.
Not every dollar of the profit surge is as steady as a pipeline volume. Management tied the higher outlook partly to strong marketing margin and optimization work in the first two quarters, and the quarter's jump in marketing margin came from greater optimization opportunities. That kind of income can be lumpy. Meanwhile, lower natural gas prices trimmed margins in the gathering business, and the Waha curtailments showed that producers can pull back when local prices turn ugly.
#record

1 month ago
GE Aerospace's $11.75 billion purchase of Consolidated Precision Products, announced September 8, is billed as fixing the castings bottleneck behind the company's $170 billion services backlog and a spare-parts delinquency rate that grew 20% sequentially in the second quarter.
The deal will not close until the second half of 2027, covers roughly a quarter of GE's airfoil needs, and CFO Rahul Ghai has told investors twice this month that "broad vertical integration is not the solution," calling CPP a "unique situation."
Sell-side price targets jumped hard after the announcement, with the mean target rising from $350.95 on June 30 to $401.00 by September 16, pushing the target-to-price ratio to 128.2%, the widest gap in over a year.
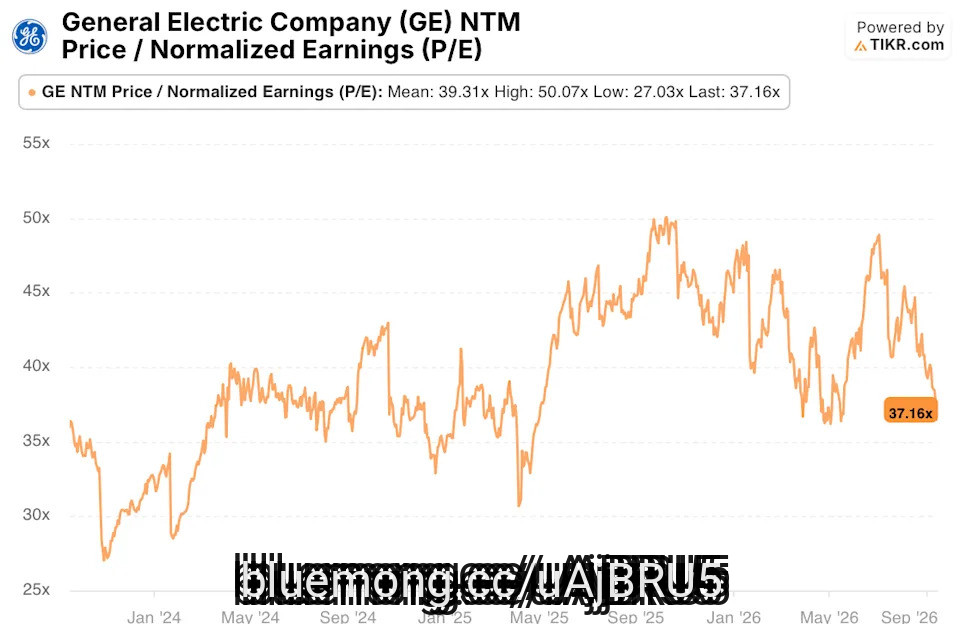
Over that same window, GE's share price fell from $373.73 to $312.90 and its NTM P/E multiple compressed to 37.16x, below its own two-year average of 39.31x and well off the roughly 50x peak reached a year earlier, even as consensus EPS estimates kept climbing smoothly through 2030 with no visible step-up.
GE Aerospace's (GE) own numbers make the case for urgency. Services backlog sits near $170 billion, internal shop visit capacity is running 40% oversubscribed, and spare-parts delinquency, shipments delayed by material shortages, grew 20% sequentially in the second quarter even as revenue rose. Management has said engines removed but not yet inducted into shops are up 60% year over year. That is the backdrop against which GE agreed to buy CPP, the world's third-largest maker of precision castings used in turbine blades and vanes.
#year #billion



1 month ago
On September 9, 2026, Reuters reported that GE Aerospace (NYSE:GE) agreed to buy castings maker Consolidated Precision Products for $11.75 billion. It is its largest acquisition since becoming a standalone company in 2024, to secure the supply of the precision metal turbine-blade components that have been a persistent bottleneck across the jet engine industry. CPP is the world's third-largest maker of these parts. CEO Larry Culp called the capacity "mission-critical" as the company works through a backlog stretching into the next decade.
GE Aerospace (NYSE:GE) can use the acquisition to convert its massive backlog into revenue faster. The company's backlog exceeded $210 billion after its second-quarter results. It includes roughly $170 billion in commercial services and more than $30 billion in defense. The $11.75 billion acquisition of Consolidated Precision Products directly targets one of the supply-chain bottlenecks that has limited GE's ability to increase engine production. CPP supplies about one-quarter of GE's casting needs. It gives GE greater control over a critical manufacturing process and could help it meet deliveries tied to its long-term backlog.
Bringing CPP in-house could improve GE's production economics while reducing supplier dependence. Spare-parts delinquencies jumped 20% sequentially in the second quarter. It shows the ongoing operational impact of supply constraints. GE plans to apply its Flight Deck lean operating model at CPP to improve factory yields and machine utilization and reduce scrap and rework. The company expects the acquisition to generate about $200 million in net synergies and achieve double-digit return on invested capital by the fifth year. It gives investors a measurable path to stronger returns from the deal.
The acquisition makes GE's position solid in the next generation of engines. GE expects demand for airfoils to increase more than 30% by 2030 from 2026 levels. CPP's casting expertise could help GE bring new airfoil designs into production faster. The business also expects CPP to make roughly $2 billion in revenue in 2027. That combination gives investors a potential path to higher production capacity, faster technology development, and stronger long-term participation in commercial and defense aerospace demand.
GE Aerospace (NYSE:GE) must justify a nearly $12 billion investment, and investors already ******* ign a premium valuation to the stock. GE Aerospace trades at roughly 46 times forward earnings. It leaves investors with limited tolerance for execution problems or weaker-than-expected returns. The company will fund $7 billion of the acquisition with cash and finance the remainder with new debt. So GE needs CPP's earnings and operating improvements to make sufficient returns to support the purchase price and protect shareholder value.
#billion #backlog #supply
1 month ago
On September 11, a caller praised The Boeing Company's (NYSE:BA) CEO and asked when the company would overcome the ongoing labor uncertainty and finally move beyond years of sideways stock performance. Mad Money host Jim Cramer replied:
I think that Boeing is ready to go up. But here's the problem. Every time crude goes up a dollar, the stock goes down a dollar. And that, think about it, that was actually the ratio. I did some work on this. And because today crude was down, Boeing went up $5... No, it's so stupid because, in truth, the airlines need more planes because the planes are more fuel-efficient. So they actually do better in this environment, but ******* ody cares. They know that airlines have to borrow money to buy planes and rates are higher, and they think that oil somehow's bad. But what ends up happening is the stock does nothing. I think it's about to go up because I think oil might be peaking unless there's some catastrophe over there.
The Boeing Company's (NYSE:BA) second-quarter results showed improving cash generation, but profitability remained weak. Revenue rose 8% year over year to $24.6 billion, while operating cash flow reached $1.4 billion and free cash flow was $631 million. Its total backlog reached a record $715 billion, including more than 6,200 commercial airplanes. CEO Kelly Ortberg said, "We're ramping up production just as we planned. That's driving higher revenues and improved cash flow." He also said there's more work ahead to ramp production, complete commercial-aircraft certifications and uphold customer commitments. Boeing said the 737-7 and 737-10 had completed flight testing, with deliveries expected to begin in 2027.
The Boeing Company's (NYSE:BA) large backlog has yet to translate into consistent commercial-aircraft profitability, leaving execution and margins as important concerns for investors. Commercial Airplanes delivered 171 aircraft in the second quarter but still posted a $322 million operating loss and a negative 2.7% operating margin. It also reported a $428 million GAAP net loss.
The balance sheet leaves less room for further setbacks. The company ended June with $45.9 billion of consolidated debt against $20 billion of cash and investments in marketable securities. The FAA certified the 737-7 on August 3, while Boeing continues working toward certification of the 737-10. First deliveries of the variants are expected in 2027. The company also recorded $280 million of losses on the VC-25B program in the quarter.
#boeing #cash #commercial

1 month ago
Core & Main, Inc. (NYSE:CNM) reported quarterly sales of $2.145 billion on September 9, up 2.5%. Company-defined non-GAAP adjusted EBITDA reached $274 million. The measure adjusts consolidated net income for interest, taxes, depreciation and amortization, equity compensation, debt modification and extinguishment losses, offering expenses, and specified other income or expenses.
Consolidated net income rose 6.4% to $150 million, while GAAP diluted earnings per share increased 10% to $0.77. Diluted weighted-average shares declined approximately 2.5% to 193.4 million. Buybacks amplified an improvement that also had an operating foundation.
The company repurchased $169 million of equity during the quarter, against $62 million of operating cash flow. The investment question is whether cash generation can sustain capital returns alongside the spending needed to grow.
Core & Main, Inc. (NYSE:CNM) benefits from demand for essential infrastructure products. Management highlighted municipal demand, fire protection, treatment plants, and data centers as areas of strength. These end markets provide several sources of business even when construction demand is uneven.
Expense discipline also helped. Quarterly selling, general and administrative expenses declined to $301 million from $302 million. Controlling overhead allows modest sales growth to contribute more to earnings. Stronger volumes would make further earnings gains easier to sustain.
#income #main #quarterly

1 month ago
GE Aerospace (GE) trades near $318, up 13.4% over the past twelve months. Behind that price sits a commercial services backlog of roughly $170 billion, work on engines already flying. The easy read is that the good news is in the price, and the coming three years just work that backlog off. A three-year scenario on the company's own numbers puts a size on what is left.
Revenue does most of the work. The scenario grows it 17.4% a year for three years, down from the 21.7% pace of the past twelve months, and net margin recovers some of the ground it has lost. Together they lift earnings about 67%.
The constraint is not demand. Management said in July that what lies ahead is much more a supply-side challenge than a demand one. Spare parts delinquencies, shipments held up for want of material, grew 20% sequentially in the second quarter of 2026.
GE Aerospace agreed in September to buy the castings maker Consolidated Precision Products. The deal shows where the bottleneck sits.
Then the multiple takes its cut. The scenario trims the P/E from 36.8x to 32.9x, because a slower revenue pace will not support what the market pays today. On those ******* umptions the stock would be worth about $475 in three years, roughly 50% above today.
#aerospace #revenue #price


1 month ago
Jim Cramer raised concerns about The TJX Companies, Inc. (NYSE:TJX) during the September 10 episode of Mad Money, as he said:
We had our CNBC Investing Club meeting today… I review each of the Charitable Trust positions on the call. This time, it was pretty clinical until I got to TJX, the off-price retailer. Candidly, I lost it on TJX. I've owned the stock for the Trust for as long as I can remember, and I've never felt so worried about this franchise. They have a bunch of divisions, but the biggest one, Marmaxx, consisting of TJ Maxx and Marshalls, really blew it. Management told us that they had figured out what had gone wrong and they've already fixed it, but because of competitive reasons or whatever, they wouldn't tell us what went wrong and they wouldn't tell us how they fixed it. I found that infuriating…
I came close to saying, forget it, Jim, it's retail. Sometimes retail is seductive. I love my local TJ Maxx, and I think Home Goods is a fun place to shop. The company's almost always about the best in the industry, crushing Burlington and Ross Stores. But this time, shockingly, Ross Stores upside surprised. It crushed TJX, much better than expected... So why bother sticking your neck out for something in this group? Simple. Because some of the greatest stories of all time have come from retail. Costco's been an incredible long-term performer. Walmart's been terrific. And TJX, it's been a wonder, one of the best stocks ever.
Could they really suddenly have lost it? Did they go all LULU? I don't think so. What happens, though, is you have to be conscious that TJX is right now being buffeted by its group, which is trading down because of the decline in discretionary income from the tax that is higher gasoline. We can't tell how much of its underperformance comes from that alone or maybe the mistakes that management made and says they've corrected. In other words, these retail stocks are very hard to own, even as they seem so easy to grasp.
TJX Companies, Inc. (NYSE:TJX) reported second-quarter fiscal 2027 sales of $15.18 billion, up 5% year over year, while consolidated comparable sales increased 4%. Adjusted diluted EPS rose 11% to $1.22, and the company raised its full-year diluted EPS outlook to $5.31-$5.36, or $5.15-$5.20 excluding an expected $0.16 net benefit from tariff refunds. The weakness was concentrated in Marmaxx, which includes TJ Maxx, Marshalls and Sierra. Comparable sales increased just 1%, down from 6% in the first quarter, while HomeGoods, TJX Canada and TJX International each posted comparable-sales growth of 6% or more.
#year


1 month ago
Jim Cramer raised concerns about The TJX Companies, Inc. (NYSE:TJX) during the September 10 episode of Mad Money, as he said:
We had our CNBC Investing Club meeting today… I review each of the Charitable Trust positions on the call. This time, it was pretty clinical until I got to TJX, the off-price retailer. Candidly, I lost it on TJX. I've owned the stock for the Trust for as long as I can remember, and I've never felt so worried about this franchise. They have a bunch of divisions, but the biggest one, Marmaxx, consisting of TJ Maxx and Marshalls, really blew it. Management told us that they had figured out what had gone wrong and they've already fixed it, but because of competitive reasons or whatever, they wouldn't tell us what went wrong and they wouldn't tell us how they fixed it. I found that infuriating…
I came close to saying, forget it, Jim, it's retail. Sometimes retail is seductive. I love my local TJ Maxx, and I think Home Goods is a fun place to shop. The company's almost always about the best in the industry, crushing Burlington and Ross Stores. But this time, shockingly, Ross Stores upside surprised. It crushed TJX, much better than expected... So why bother sticking your neck out for something in this group? Simple. Because some of the greatest stories of all time have come from retail. Costco's been an incredible long-term performer. Walmart's been terrific. And TJX, it's been a wonder, one of the best stocks ever.
Could they really suddenly have lost it? Did they go all LULU? I don't think so. What happens, though, is you have to be conscious that TJX is right now being buffeted by its group, which is trading down because of the decline in discretionary income from the tax that is higher gasoline. We can't tell how much of its underperformance comes from that alone or maybe the mistakes that management made and says they've corrected. In other words, these retail stocks are very hard to own, even as they seem so easy to grasp.
TJX Companies, Inc. (NYSE:TJX) reported second-quarter fiscal 2027 sales of $15.18 billion, up 5% year over year, while consolidated comparable sales increased 4%. Adjusted diluted EPS rose 11% to $1.22, and the company raised its full-year diluted EPS outlook to $5.31-$5.36, or $5.15-$5.20 excluding an expected $0.16 net benefit from tariff refunds. The weakness was concentrated in Marmaxx, which includes TJ Maxx, Marshalls and Sierra. Comparable sales increased just 1%, down from 6% in the first quarter, while HomeGoods, TJX Canada and TJX International each posted comparable-sales growth of 6% or more.
#sales #time #NYSE


1 month ago
On August 5, Clear Channel Outdoor Holdings Inc. (NYSE:CCO) reported second-quarter results that showed the billboard and airport advertising company accelerating just as it prepares to leave the public markets. On February 9, Clear Channel agreed to be acquired by an investor consortium advised by Mubadala Capital for $2.43 per share, a deal stockholders approved on May 12, and one expected to close by the end of the third quarter of 2026. Because of the pending Merger, Clear Channel skipped its usual earnings call and offered no forward guidance.
Consolidated revenue climbed 8.7% to $438.0 million in the quarter and 10.2% to $811.9 million over the first half, with the 2026 FIFA World Cup pulling in extra advertising spend across both of Clear Channel's segments. The America division, which houses the roadside billboard and street furniture business, grew revenue 7% to $324.3 million as demand from technology advertisers in the San Francisco/Bay Area market broadened out and digital billboard revenue rose 7.2% to $122 million. Airports revenue jumped 14% to $113.6 million, helped by strong demand at San Francisco
International Airport and digital sales that climbed 15.6% to $73.4 million, with national advertisers now accounting for 57.8% of that segment's revenue. Profitability grew even faster than the top line. Adjusted EBITDA rose 11.6% to $143.4 million for the quarter and 19% to $247.3 million for the first half, while Airports Segment Adjusted EBITDA jumped 22.8% to $29.9 million. Adjusted Funds From Operations climbed 61.6% to $44.9 million in the quarter, and for the first half it went from just $5 million a year ago to $51.5 million. On August 4, Clear Channel also closed the sale of its Spain business for about $132.3 million, proceeds it plans to put toward paying down debt.
The growth did not reach the bottom line. Clear Channel posted a loss from continuing operations of $10 million in the quarter, reversing a $6.3 million profit a year earlier, and the consolidated net loss came to $5 million versus net income of $10.6 million in the same period of 2025. Over six months, the loss from continuing operations widened 21.4% to $59.4 million. Costs rose alongside revenue. Direct operating and SG&A expenses increased 5.9% for the quarter, and Airports site lease expense alone jumped 12.0% to $67.1 million on higher minimum guaranteed payments and the renewed contract with the Metropolitan Washington Airports Authority.
#channel #revenue #airports #operations

1 month ago
On September 10, Copart (NASDAQ:CPRT) held its fourth-quarter earnings call and used it to unveil a deal that could reshape its business: an all-cash agreement to acquire ACV, a digital auto marketplace that moved roughly $10 billion of vehicles last year without owning a single lot. The announcement landed alongside a quarter that captured the company's central tension. Revenue rose, but net income fell, and management is now betting that pairing its junkyards with someone else's software can fix that.
The ACV deal is the headline, and for good reason. ACV brings more than 22,000 active buyers and inspection and valuation technology, while Copart contributes over 275 locations, roughly 4 million vehicles sold annually, and about 1 million members across more than 185 countries. Management structured it as an all-cash tender offer funded from cash on hand, with a close targeted by the end of the calendar year and earnings accretion expected in fiscal 2028. Executives framed the fit as physical scale meeting digital liquidity, giving dealers, banks, and fleet sellers a single partner for disposing of vehicles.
That diversification push is already showing up in the numbers. International revenue grew 11.7% to $222.1 million on 15% service revenue growth, and international buyers accounted for 45.7% of total US sales dollars despite making up only 38.2% of units, a sign they are chasing pricier vehicles. Domestically, non-insurance units returned to growth of 0.2% in the quarter after a full-year decline, dealer units rose 5.8%, and BluCar, which serves banks and fleets, expanded nearly 20%. Global average selling prices climbed 3.5%, evidence that Copart's auctions still command pricing power even as volumes soften.
The quarter's numbers show where the strain is. Consolidated revenue grew 2.4% to $1.2 billion, yet net income dropped 17.4% to $327.4 million and diluted earnings per share fell 14.6% to $0.35. Operating expense per car jumped 12.7% year over year as the company poured money into long-haul delivery, **** leExpress, and dedicated wholesale facilities, and US facility costs alone rose 7.7% in the quarter. Lower interest income, a byproduct of the $1.63 billion spent on buybacks earlier in the fiscal year, added to the squeeze.
The core insurance business is also cooling. Global insurance units fell 4.2%, with domestic insurance **** ignments down 7.5%, though management noted that figure would have been up 2.3% excluding the loss of a single customer. Collision claim frequency declined 3.4% even as total loss frequency hit a record 23.3% for a second quarter and severity topped $6,300 per claim, up 8.8%. And the ACV deal itself carries integration risk, since management expects only breakeven results before accretion arrives in fiscal 2028.
#quarter #vehicles #insurance

1 month ago
On September 10, MasterCraft Boat Holdings (NASDAQ:MCFT) reported a fiscal fourth quarter that looked nothing like the one a year earlier. Adjusted EBITDA more than doubled, margins expanded across the legacy business, and the company closed out a year defined by its May 15 acquisition of Marine Products Corporation. But buried inside those same results was a $10.1 million writedown that tells a very different story about one corner of the business.
MasterCraft's core boat business is the reason the quarter worked at all. Legacy net sales, meaning the business before the acquisition, climbed 21.5% year over year to $96.6 million in the fourth quarter, powered by the next generation X Series lineup and less discounting at the dealer level. That combination of volume and pricing pushed legacy adjusted EBITDA margin up 730 basis points to 19.3%, up from 12% a year earlier. Once the newly acquired Chaparral and Robalo brands are added in, which contributed for only six weeks after the deal closed on May 15, consolidated fourth quarter net sales reached $129.9 million, up 63.4%, and adjusted EBITDA hit $20.5 million, up 114.9%.
The company also cleaned up its channel. Dealer field inventory for the legacy business fell 30% year over year, with turnover now running ahead of pre-pandemic levels, a sign dealers are selling boats rather than sitting on them. Full-year adjusted net income reached $30.2 million, or $1.76 per diluted share, up from $15.1 million, or $0.92 per share, in fiscal 2025. The company generated $22.3 million in free cash flow for the year and, as of June 30, held $43.9 million in cash, zero debt, and a fully available $75 million credit line. MasterCraft's own retail sales grew low single digits for the year even as the broader powerboat industry fell mid to high single digits, and the newer Robalo brand posted high single-digit retail growth in the fishing boat category.
The picture gets murkier once you look past the flagship brand. The Leisure segment, home to the Crest and Balise pontoon boats, saw fourth-quarter sales fall 11.2% year over year to $12.1 million, and the company booked a $10.1 million non-cash impairment against Crest brand ******* ets tied to what management called current category conditions. On a GAAP basis, that charge combined with acquisition costs and purchase accounting adjustments turned the quarter into a net loss of $7 million, or $0.35 per diluted share, compared to net income of $5.5 million a year earlier. Operating expenses rose $23.1 million in the quarter, including $5.9 million in transaction costs tied to the acquisition.
#million #legacy

1 month ago
Howmet Aerospace Inc. (NYSE:HWM) is facing a mixed outlook after GE Aerospace agreed to acquire Consolidated Precision Products (CPP) for about $11.75 billion to secure more control over critical engine castings and expand production capacity. The announcement initially hit Howmet shares, which fell about 10%, as investors worried that GE could eventually rely less on outside suppliers such as Howmet.
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial


2 months ago
GE Aerospace (NYSE:GE) is making its largest acquisition since becoming a standalone publicly traded company. It agreed to acquire Consolidated Precision Products (CPP) for around $12 billion.
CPP is one of the world's largest precision castings providers. It's a major GE supplier. Precision castings is a major pressure point for the aerospace engines industry. Acquiring CPP would give GE Aerospace greater control over a critical part of its engine supply chain.
And the deal could strengthen GE's ability to meet demand already sitting in its backlog. But the investment case depends on whether additional production capacity generates enough free cash flow to justify the deal's premium price.
rommma/Shutterstock.com
Engine manufacturers like GE Aerospace (NYSE:GE) are struggling to keep pace with surging demand due to supply chain constraints. CPP is a major supplier of precision castings for GE's LEAP and GEnx engines. GE plans to raise CPP's output. It would do that by improving factory yields and machine use. With the CPP deal, GE also sees a path to accelerate production of new engine technologies.
#NYSE #largest #engines #supply


2 months ago
First Citizens BancShares, Inc. (NASDAQ:FCNCA), through its First-Citizens Bank & Trust Company subsidiary, completed the acquisition of 138 BMO Bank N.A. branches on September 4. The locations span 11 states across the Midwest, Great Plains and West.
The completion announcement did not disclose final transferred balances. At the announcement, First Citizens BancShares, Inc. (NASDAQ:FCNCA) expected to ****** ume approximately $5.7 billion of deposits and acquire $1.1 billion of loans. Its July 2026 update lowered those estimates to $5.3 billion and $700 million, respectively. Both estimates imply roughly $4.6 billion of net liquidity. That difference represents funding capacity, not transaction income, and remains subject to final balances and acquisition accounting.
The deposit franchise could be the transaction's most valuable ****** et. At announcement, the acquired deposits carried a weighted average rate of 1.43%, with 21% in noninterest-bearing demand accounts. First Citizens BancShares, Inc. (NASDAQ:FCNCA) reported a 2.07% average total deposit cost in the second quarter of 2026. Retaining the acquired accounts near their original pricing could lower the consolidated funding cost.
The 138 branches also establish or deepen a presence across 11 states. The original transaction presentation identified approximately $1.0 billion of wealth ****** ets under management, creating opportunities to cross-sell commercial lending, treasury services, and wealth products. Retaining branch personnel could help preserve local relationships.
First Citizens BancShares, Inc. (NASDAQ:FCNCA) can deploy the surplus funding in several ways. As of June 30, 2026, the company held $151.03 billion of loans and $32.19 billion of borrowings, including a $28.42 billion purchase money note owed to the Federal Deposit Insurance Corporation. The acquired liquidity could support loan growth, replace more expensive funding, or be invested in securities. The original presentation projected immediate earnings-per-share accretion and an approximately 27-basis-point reduction in the Common Equity Tier 1 capital ratio.
#billion #first #citizens


2 months ago
Consolidated Edison Company of New York, Inc., the regulated utility subsidiary of Consolidated Edison, Inc. (NYSE:ED), joined New York regulatory staff and other parties in filing a proposed three-year steam-rate plan covering November 2026 through October 2029. Approval from the New York State Public Service Commission remains required.
The proposal includes headline base-rate changes of $13 million, $42 million and $39 million over the three rate years. A bill-shaping mechanism would instead implement corresponding base-rate increases of $26.6 million, $27.5 million and $28.5 million, producing an approximately 3.5% total customer-bill effect each year. Any revenue shortfall caused by delayed billing after the proposed November 1 effective date would be collected through a surcharge.
For Consolidated Edison, Inc. (NYSE:ED), the attraction is a visible investment and recovery framework. The trade-off is a 9.5% authorized return on common equity and limited room before earnings sharing begins.
The settlement supports $396 million of steam capital spending over three years, comprising $143 million, $127 million, and $126 million annually. The average rate base is projected to increase from $2.118 billion in the first rate year to $2.234 billion in the second and $2.311 billion in the third. That represents approximately 9.1% ***** ulative growth from the first year to the third, providing a larger base on which Consolidated Edison, Inc. (NYSE:ED) can earn its authorized return.
The multiyear structure also improves planning. Consolidated Edison, Inc. (NYSE:ED) would know the principal revenue, capital, and financing ***** umptions through October 2029 rather than returning immediately to a full rate proceeding. The proposed after-tax weighted average cost of capital rises from 7.07% to 7.19% across the plan, reflecting higher ***** umed long-term debt costs.
#million #consolidated #year #three

2 months ago
Saints manager Craig Harrison was sent off as his side consolidated their place at the top of the Cymru Premier table.
The visitors were already two goals ahead - through first-half efforts from Daniel Williams and Rory Holden - by the time Harrison earned the wrath of the match officials early in the second period. Saints stay top while Airbus held on to eighth spot.
The tale of the table did not lie as Caernarfon eased to a thumping victory in south west Wales to move third.
Phillip Mooney and Sion Bradley putting them 2-0 up by the break before Ammanford's Lucas Davies saw red.
Bradley added their third from the penalty spot before Mooney also grabbed a second and Harri Wyn completed their scoring as they left winless Ammanford to lick their wounds and down in 15th place.
#mooney #table #Third #craig


2 months ago
On September 8, 2026, GE Aerospace (NYSE:GE) agreed to buy Consolidated Precision Products (CPP) for $11.75 billion. The acquisition marks the company's largest bet yet on precision engine castings, a constraint that has been capping GE's growth. Trading already at roughly 40x earnings, the company has now attacked one of its genuine bottlenecks through the deal. But has it paid too much to do it?
Castings, including the superalloy and ******* anium hot-section parts inside the jet engines, have constrained GE's engine production, including programs such as LEAP and GEnx, as well as its high-margin aftermarket. Without these castings, the company can neither build nor service its engines. If the acquisition closes, the company will gain access to CPP's 20-plus plants and about 6,600 workers, which are essential for making those components. The deal would therefore enable GE to control the constraint as well as defend its margins. CEO Larry Culp characterized the move as securing manufacturing capacity to meet simultaneous demand across commercial engines, aftermarket services, and defense contracts.
The valuation is where bulls should slow down. GE is paying roughly 18x 2027 EBITDA including synergies (26x without synergies). The sellers are private equity firms Warburg Pincus and Berkshire Partners. They have basically offloaded a cyclical business near the peak of the aerospace cycle. This is smart money selling to GE instead of the other way around. The real tell is that GE felt compelled to buy its way past this capacity bottleneck instead of scaling organically, which reveals how tight its prized aftermarket really was. Also, CPP also supplies other major aerospace and defense companies such as Pratt & Whitney, Honeywell, and Lockheed Martin, and through the vertical tie-up, the company invites antitrust scrutiny before it closes in late 2027.
GE's 40x multiple rests on its high-margin razor-and-blade business model that services a huge installed base. And the casting supply shortages quietly constrain this aftermarket. Hence, more than merely fixing a supply chain issue, the CPP acquisition defends the company's high margin and multiple. Financially, the transaction is accretive to adjusted EPS and free cash flow in the first year, funded through $7 billion in cash alongside newly issued debt. Insider Monkey data shows 113 hedge funds held GE in Q2 2026, down modestly from 119 in Q1, reflecting firm institutional positioning. Short interest is just 1.3% of float, below peers like Honeywell International (1.6%). Almost no one bets against it.
#aftermarket #acquisition #including


2 months ago
During a September 8 episode of Mad Money, Jim Cramer examined the broader aerospace ecosystem following GE Aerospace's (NYSE:GE) nearly $12 billion agreement to acquire castings specialist Consolidated Precision Products (CPP). Commenting on the strategic importance of supply chain control and the enduring strength of commercial and defense aviation despite rising oil prices, Cramer stated:
I still believe in the data center, but I also want to open your eyes to other opportunities. This morning, for example, GE Aerospace spent nearly $12 billion to buy a castings company called Consolidated Precision Products to integrate this key segment into its supply chain. It's vital for both commercial aircraft and particularly defense, both of which are booming. Now, on a day where oil's up, you might not want to focus on anything airline related, but travel's been booming the whole time, the whole time the Iranian war's been going on. This acquisition will pay off quickly for GE, making it more likely that they can accelerate production. This is also good news, therefore, for Boeing, a huge customer of GE that needs to boost its production speed.
GE is relatively close to its highs, deservedly so. Boeing? Nowhere near its high. Yet the order book is full. Last week, there was this negative article about how Boeing is being hurt by the problem-filled Spirit AeroSystems acquisition. It made that one two years ago. But that actually had to be done because Boeing, like GE Aerospace, needs to get better control of its supply chain. Aha, you say, who needs that kind of problem? Boeing just reported its slowest deliveries in 4 months. I come back and say, wait a second. First, the problems from the Spirit deal are now behind them. You know what? The story is actually old news.
Plus, CEO Kelly Ortberg has made it clear that orders would be lumpy. I knew that. And look, I know the high price of oil, particularly jet fuel, is bad news for the airlines. But the higher price of fuel also makes these new engines and airplanes far more valuable than before. Why? They're way more energy efficient. It's a good situation that has nothing to do with the data center. It does require more, better tech that AI can help with.
GE Aerospace (NYSE:GE) and The Boeing Company (NYSE:BA) represent two distinct pillars of the aerospace manufacturing ecosystem, operating at massive commercial scale. GE Aerospace reported second-quarter revenue of $13.3 billion, up 21% year-over-year, driven by strong commercial engine services and record internal shop visit output. Its total order backlog extends past $210 billion, supported by sustained airline demand for propulsion systems and aftermarket maintenance.
#boeing #chain #consolidated


2 months ago
On September 3, a caller asked if UnitedHealth Group Incorporated (NYSE:UNH) has enough profitable growth that they should consider adding it to their portfolio. Mad Money host Jim Cramer replied:
Yes, the answer: it does, it does. You know, I've got to tell you, I thought that last quarter was very, very good. The stock market did not like the quarter as much as I thought it would, but the stock's making a stand here. I think that UNH is good to buy.
Cramer's bullish stance rests on the core strength of the company's financial delivery and improving execution. In its second-quarter 2026 report, UnitedHealth Group Incorporated (NYSE:UNH) posted consolidated revenues of $112 billion and operating earnings of $8 billion. Adjusted diluted earnings per share reached $6.38, outpacing Wall Street expectations by $1.48. Driven by strong performance across both the UnitedHealthcare and Optum divisions, management raised its full-year 2026 adjusted EPS guidance to a range of $19.50 to $20. Furthermore, the medical care ratio improved to 86.7% down from 89.4% a year prior, showing that medical cost trends and pricing are aligning effectively.
On the other hand, Wall Street remains cautious about lingering cost pressures across the managed care landscape. Even though the medical care ratio improved compared to last year, patients continuing to utilize medical services at a high rate keeps expenses heavy. At the same time, commercial insurance margins are taking longer to bounce back. Adding in tighter payment adjustments for government-backed plans along with heavy spending on tech infrastructure, cautious investors could have reasons to wait rather than chasing the stock higher.
Insider Monkey's data tracking over 1000 hedge funds shows accumulation by major ****** et managers. 143 hedge funds had positions in UnitedHealth Group Incorporated (NYSE:UNH) in Q2 compared to 130 in Q1. Of those funds, Fisher ****** et Management was the top shareholder with nearly 9.1 million shares. The firm increased its position in the stock by 74% in the quarter. Additionally, short interest remains low, with the short percentage of the float sitting at 1.92%, showing a general lack of aggressive bearish bets against the stock.
#unitedhealth #funds


2 months ago
GE Aerospace (GE) is acquiring castings supplier Consolidated Precision Products for nearly $12 billion, with Cramer calling it a defense-driven win for the stock.
GE's Defense & Propulsion Technologies segment grew revenue 16% to $3.4 billion in Q2 2026, backed by a $210 billion backlog.
GE's 433% five-year run tempers urgency, but the recent 9.5% monthly pullback gives new investors a better entry point.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and GE Aerospace didn't make the cut. Enter your email to see the names that beat GE. The report is free. Enter your email and see if any of your stocks made the cut.
Jim Cramer used his Mad Dash on September 8, 2026, to press the case for GE Aerospace (NYSE:GE), calling its purchase of Consolidated Precision Products the kind of consolidation the market has been asking for.
#enter #defense #calling


2 months ago
On August 27, ****** an Machinery Inc. (NASDAQ:TITN) reported results for the fiscal second quarter ended July 31, and the numbers point in two different directions at once. Revenue fell to $496.4 million from $546.4 million a year earlier, and the net loss widened to $9.2 million, or $0.40 per diluted share, compared with a $6.0 million loss a year ago. Yet gross margin climbed to 18.6% from 17.1%, and management held its full year profitability targets steady even while cutting its outlook for Europe. Sorting out that mix is the real story of the quarter.
The clearest bright spot is margin. Gross profit margin expanded 150 basis points to 18.6%, which the company attributed to stronger equipment margins as aged inventory keeps shrinking, plus a richer mix of parts and service revenue. That improvement showed up directly in the segments. Agriculture's pretax loss narrowed sharply to $3.3 million from $12.3 million a year ago, even though segment revenue fell to $310.2 million on an 8.4% same-store sales decline. Construction told an even better story, with revenue rising to $78.6 million from $72.0 million on 9.2% same-store growth, and the segment flipped to $0.4 million of pretax income from a $1.2 million pretax loss last year, helped by data center and infrastructure project activity.
Management raised its Construction revenue ****** umption for the year to up 5% to 10%, from flat to up 5% previously. Australia also improved, with revenue up 22.5% once currency effects are stripped out, and its full-year outlook was raised to up 15% to 20% on better moisture levels and farmer sentiment. Floorplan and other interest expense fell to $8.1 million from $11.5 million as interest-bearing inventory levels came down, another sign the cleanup is easing pressure on the business.
The offsetting weakness is just as clear. Consolidated revenue dropped across nearly every line, and Agriculture's same-store decline reflects continued pressure on grower profitability in North America. The bottom line moved the wrong way too, with Adjusted EBITDA slipping to $4.6 million from $5.6 million and operating expenses rising to 19.0% of revenue from 17.0%. Europe was the sharpest problem. Segment revenue fell to $66.1 million from $98.1 million, and once a $1.1 million currency benefit is excluded, revenue was down $33.1 million, or 33.7%. The wind-down of the company's German operations accounted for roughly $11 million of that decline, with the rest coming from softer demand after the boost Romania saw from European Union stimulus programs faded.
#million #once #even

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Transitioned from a brand-centric to a function-based organization to create clear accountability across marketing, merchandising, and digital experience teams.
Achieved the original $50 million two-year cost savings target within one year by improving marketing efficiency and streamlining internal operations.
Prioritized revenue contribution margin over top-line growth in fiscal 2026, intentionally reducing marketing spend that did not meet incrementality or profitability thresholds.
Consolidated the digital ecosystem by moving low-traffic standalone websites into categories within flagship platforms like Harry & David to leverage scale and improve efficiency.
#achieved
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
Featured image by Jenna O'Malley/PitchBook News
European PE add-ons are stuck at decade highs for the obvious reason—sponsors playing it safe—but increasingly also because a consolidated platform is what enhances the chance to exit.
According to PitchBook's Q2 2026 European PE Breakdown, there were 2,121 add-on deals in H1 2026, reaching a decade high of 57.7% of the total European PE deal count. It's the third straight quarter the strategy has held near record levels.
Richard Damming, head of PE investments Europe at Schroders Capital, spoke with PitchBook News about why a consolidated platform may help secure an exit in the subdued market and how to create value in times of low financial leverage.
This interview has been edited for length and clarity.
#according



2 months ago
On September 2, Argan, Inc. (NYSE:AGX) reported strong results for its second quarter of fiscal year 2027. The company posted record revenue of $384 million, a gross margin of 19.3%, record net income of $53 million, and record adjusted EBITDA of $70 million.
Following the strong results, Freedom Broker upgraded its rating on the stock from Hold to Buy with a price target of $700. ****** yst Sergey Glinyanov noted that Argan, Inc.'s (NYSE:AGX) results showed strong execution across major Power projects. Over the last twelve months, the company has delivered strong revenue growth of 29%.
Argan, Inc. (NYSE:AGX) also has an impressive project backlog to support future revenue. As of July 31, 2026, consolidated project backlog stood at approximately $2.5 billion. While this was down from roughly $2.9 billion as of January 31, 2026, the backlog still provides a significant base for future revenue.
The company expects to add several projects over the next 7 to 15 months. Future performance could benefit from ramp-up of gas-fired projects and new contract awards.
"We maintain our $700 target price for AGX and upgrade the rating from Hold to Buy, reflecting the emerging upside potential," Glinyanov wrote.
#strong #future #record

2 months ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ******* umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted UnitedHealth Group Incorporated (NYSE:UNH). UnitedHealth Group Incorporated (NYSE:UNH), a diversified healthcare company, contributed 2.5% to the Fund's performance during the quarter. On September 02, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $399.66 per share. Over the past month UnitedHealth Group Incorporated (NYSE:UNH) was down 1.07%, and its shares gained 28.76% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $358.73 billion and its stock has traded within a 52-week range of $255.97 - $461.62.
Eagle Capital Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"Managed care (13% of capital): UnitedHealth Group Incorporated (NYSE:UNH), Humana, Elevance: These managed care companies have significant scale advantages in a consolidated industry that outgrows the overall economy. The industry moves with its own cycle and, over the last several years, has faced cost/price pressures in Medicare Advantage and Medicaid. Even the largest firms are earning poor margins, and some weaker firms are unprofitable. We believe conditions have bottomed out and that we are transitioning to a multi-year improvement in margins and earnings. Al-driven technology projects can both reduce costs and improve service quality. Since returning as CEO at UnitedHealth last year, Stephen Hemsley and the management team have been correcting some of the company's missteps. Recent results provide growing evidence that the turnaround is well on track. We expect EPS growth of 15-20% over the next several years, driven by moderate revenue growth and significantly e

2 months ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ***** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Humana Inc. (NYSE:HUM). Humana Inc. (NYSE:HUM) is an American insurance company that provides medical and specialty insurance products. On September 02, 2026, Humana Inc. (NYSE:HUM) closed at $400.97 per share. Over the past month, Humana Inc. (NYSE:HUM) returned 9.18%, and its shares gained 28.52% over the past 52 weeks. Humana Inc. (NYSE:HUM) has a market capitalization of $48.15 billion with a 52-week trading range between $163.11 and $428.88.
Eagle Capital Management stated the following regarding Humana Inc. (NYSE:HUM) in its Q2 2026 investor letter:
"Managed care (13% of capital): UnitedHealth Group, Humana Inc. (NYSE:HUM), Elevance: These managed care companies have significant scale advantages in a consolidated industry that outgrows the overall economy. The industry moves with its own cycle and, over the last several years, has faced cost/price pressures in Medicare Advantage and Medicaid. Even the largest firms are earning poor margins, and some weaker firms are unprofitable. We believe conditions have bottomed out and that we are transitioning to a multi-year improvement in margins and earnings. Al-driven technology projects can both reduce costs and improve service quality. Humana is also making good strides, and we expect significantly improved Star ratings for the company later this year. We expect EPS growth of 15-20% over the next several years, driven by moderate revenue growth and significantly expanding margins."
#eagle


2 months ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7% gain. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Micron Technology, Inc. (NASDAQ:MU). Micron Technology, Inc. (NASDAQ:MU) is a leading semiconductor company manufacturing memory and storage products. On September 02, 2026, Micron Technology, Inc. (NASDAQ:MU) closed at $956.08 per share. Over the past month, Micron Technology, Inc. (NASDAQ:MU) returned 8.46%, but its shares are up 669.73% over the past year. Micron Technology, Inc. (NASDAQ:MU) has a market capitalization of $1.08 trillion, and its stock has traded within a 52-week range of $118.52 to $1,255.00.
Sands Capital Select Growth Fund stated the following regarding Micron Technology, Inc. (NASDAQ:MU) in its Q2 2026 investor letter:
"Micron Technology, Inc. (NASDAQ:MU) and SanDisk increased the portfolio's exposure to memory, which has become a critical bottleneck in the AI infrastructure stack. Agentic AI systems require greater context, faster retrieval, and more persistent memory, increasing demand for DRAM, high-bandwidth memory, and NAND. At the same time, advanced memory remains difficult, capital intensive, and time consuming to manufacture. The industry has also become more consolidated and disciplined, which should limit the speed of supply response. We believe this combination of accelerating demand and constrained supply can support stronger pricing, better margins, and a more durable earnings cycle for leading memory providers."
#NASDAQ #fund #sands #investor

2 months ago
On August 5, Clover Health Investments Corp. (NASDAQ:CLOV) reported second-quarter 2026 results that turned a year-ago loss into real profit. GAAP net income came in at $28 million, a $39 million swing from the $10.6 million loss posted in the same quarter last year. Medicare Advantage membership climbed to 157,309, up 48% year over year, and the company raised its full-year guidance across every major line item. For a stock that has spent years chasing profitability, this quarter reads like a turning point.
The headline number is the $28 million in GAAP net income for the quarter, but the six-month picture tells the same story with more weight behind it: $55.3 million in net income through the first half of 2026, compared to an $11.9 million loss over the same stretch last year. Revenue reached $743.2 million in the quarter, up 55.6% year over year, and consolidated gross profit rose 53.6% to $153.0 million. Adjusted EBITDA more than doubled, jumping 139.2% to $40.9 million from $17.1 million a year earlier, which means profitability is scaling faster than revenue itself.
Clover backed those numbers by raising its 2026 outlook on every front. Full-year adjusted EBITDA guidance moved up to $70 million to $85 million from a prior range of $50 million to $70 million, and GAAP net income guidance rose to $20 million to $35 million from $0 million to $20 million. The company also closed the quarter with $443.0 million in cash and investments, up 13.8% year over year, giving it room to keep funding growth. CEO Andrew Toy pointed to the Clover ***** istant platform reaching more physicians and members as the engine behind "better health outcomes" alongside the growth, while Interim CFO Clay Thornton tied the improving cohort economics to the company retaining more of that value under its full-risk model heading into 2027.
The same filing shows that scaling a Medicare Advantage insurer is not cheap. Insurance net medical claims incurred rose 56.1% year over year to $615.4 million, tracking almost in step with revenue growth. The insurance benefits expense ratio, which measures how much of premium revenue goes toward paying medical claims, sat at 87.6% for the quarter, only 80 basis points better than a year ago, and the six-month figure improved by just 20 basis points. That means the cost of caring for members has barely budged as a share of revenue, even as the top line surged.
Spending on overhead grew too. Salaries, benefits, and general and administrative expenses rose 13.3% year over year to $124.4 million, while the adjusted version of that same cost line jumped 35.9% to $112.1 million. And even after the guidance raise, projected full-year GAAP net income of $20 million to $35 million is modest against total revenue guidance of $2.92 billion to $3.00 billion, a thin margin for a business still proving it can convert scale into durable profit.
#quarter #income



