

2 days ago
Phillips 66 (NYSE:PSX) has been on a strong rally this year, posting gains of over 110% since the beginning of 2026. The outperformance has been driven by an unusually sharp surge in global refining margins amid the war in the Middle East, which has significantly tightened the world's refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
Given Phillips 66's substantial outperformance compared to the wider market, investors may be questioning whether the stock's record-setting run has reached its peak. However, the ****** ysts over at BMO Capital see further upside ahead. On September 17, the firm raised its price target on PSX from $260 to $310, while maintaining an 'Outperform' rating on the shares. The target boost implies an upside of 13% from the current levels and even exceeds the stock's all-time high of over $274 achieved earlier this month.
BMO Capital highlighted Phillips 66's integrated business model, noting that it has gained momentum and outperformed its individual segments, supported by strong execution across the portfolio. While Refining and Renewables remain the cyclical leaders, BMO also sees a favorable medium-term growth outlook for the company's Midstream business.
BMO Capital's vote of confidence comes amid a broader optimism surrounding Phillips 66, with ****** ysts from Morgan Stanley, Raymon James, UBS, and several others also improving their respective outlooks on PSX. This suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, particularly following the renewed escalations between Iran and the United States.
The supply disruptions now extend beyond the troubled region, as a recent wave of Ukrainian attacks on Russian refineries has further reduced global refining capacity and provided further support to margins.
#further #margins #amid
Given Phillips 66's substantial outperformance compared to the wider market, investors may be questioning whether the stock's record-setting run has reached its peak. However, the ****** ysts over at BMO Capital see further upside ahead. On September 17, the firm raised its price target on PSX from $260 to $310, while maintaining an 'Outperform' rating on the shares. The target boost implies an upside of 13% from the current levels and even exceeds the stock's all-time high of over $274 achieved earlier this month.
BMO Capital highlighted Phillips 66's integrated business model, noting that it has gained momentum and outperformed its individual segments, supported by strong execution across the portfolio. While Refining and Renewables remain the cyclical leaders, BMO also sees a favorable medium-term growth outlook for the company's Midstream business.
BMO Capital's vote of confidence comes amid a broader optimism surrounding Phillips 66, with ****** ysts from Morgan Stanley, Raymon James, UBS, and several others also improving their respective outlooks on PSX. This suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, particularly following the renewed escalations between Iran and the United States.
The supply disruptions now extend beyond the troubled region, as a recent wave of Ukrainian attacks on Russian refineries has further reduced global refining capacity and provided further support to margins.
#further #margins #amid

2 days ago
Targa Resources Corp. (NYSE:TRGP) has significantly outperformed the wider market this year, posting gains of over 56% since the beginning of 2026. A major catalyst behind this growth was the 20-year fee-based agreement that the company signed with ExxonMobil last month.
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda

2 days ago
Shell plc (NYSE:SHEL) is a global group of energy and petrochemical companies with a presence in over 70 countries. The stock has delivered gains of over 23% since the beginning of 2026 and even hit its all-time high earlier in March, driven primarily by soaring oil prices and solid earnings amid supply disruptions in the Middle East.
Following a slight pullback over the last few months, Shell has started to regain momentum, and Morgan Stanley expects the rally to continue. On September 3, the investment bank upgraded SHEL from 'Equal Weight' to 'Overweight', while also raising its price target from $81.60 to $101.30. The target boost implies an upside of 9% from the current levels and even exceeds Shell's previous record high of almost $95 per share achieved earlier this year.
Morgan Stanley noted that the concerns surrounding Shell's long-term resource longevity have now eased, with the company now positioned to sustain production growth through 2030 and stabilize output thereafter. The ******* yst firm believes that while the stock has been weighed down due to its dividend policy, there is now "potential for a significant acceleration. As a result, Morgan Stanley promoted SHEL to top-pick status.
Shell completed the acquisition of ARC Resources earlier this month, addressing the resource-depletion concerns that have weighed down its valuation. The $16.4 billion deal has significantly expanded the energy giant's gas reserves and will boost its production by 370,000 boed. Additionally, the strategic move expands Shell's exposure to the North American gas market and bolsters its position in a region that is emerging as a key player in the global LNG supply.
Shell's recent upstream investments provide further support to Morgan Stanley's bullish thesis. The company announced earlier this month that it had agreed to acquire a 30% interest in BP's Conifer exploration prospect in the US Gulf, and a 50% stake in the Tupinamba exploration block in Brazil's Santos Basin. Additionally, it also recently signed a preliminary agreement for the acquisition of production rights over Ghana's South Deepwater Tano Cape Three Points oil and gas block.
#shel #production #energy #Stock
Following a slight pullback over the last few months, Shell has started to regain momentum, and Morgan Stanley expects the rally to continue. On September 3, the investment bank upgraded SHEL from 'Equal Weight' to 'Overweight', while also raising its price target from $81.60 to $101.30. The target boost implies an upside of 9% from the current levels and even exceeds Shell's previous record high of almost $95 per share achieved earlier this year.
Morgan Stanley noted that the concerns surrounding Shell's long-term resource longevity have now eased, with the company now positioned to sustain production growth through 2030 and stabilize output thereafter. The ******* yst firm believes that while the stock has been weighed down due to its dividend policy, there is now "potential for a significant acceleration. As a result, Morgan Stanley promoted SHEL to top-pick status.
Shell completed the acquisition of ARC Resources earlier this month, addressing the resource-depletion concerns that have weighed down its valuation. The $16.4 billion deal has significantly expanded the energy giant's gas reserves and will boost its production by 370,000 boed. Additionally, the strategic move expands Shell's exposure to the North American gas market and bolsters its position in a region that is emerging as a key player in the global LNG supply.
Shell's recent upstream investments provide further support to Morgan Stanley's bullish thesis. The company announced earlier this month that it had agreed to acquire a 30% interest in BP's Conifer exploration prospect in the US Gulf, and a 50% stake in the Tupinamba exploration block in Brazil's Santos Basin. Additionally, it also recently signed a preliminary agreement for the acquisition of production rights over Ghana's South Deepwater Tano Cape Three Points oil and gas block.
#shel #production #energy #Stock

2 days ago
Marathon Petroleum Corporation (NYSE:MPC) has substantially outperformed the wider market this year, supported by an unusually sharp surge in global refining margins as the prolonged Iran crisis has significantly tightened global refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
With Marathon up by over 150% since the beginning of 2026, there are now concerns that the stock may have topped out. However, the ****** ysts over at Morgan Stanley are convinced that the rally still has further room to run. On September 14, Morgan Stanley ****** yst Joe Laetsch significantly raised the firm's price target on MPC from $265 to $453, while reaffirming an 'Overweight' rating on the shares.
The target boost reflects an upside of over 9% from the current price level and even exceeds the stock's record high of just under $411 per share achieved earlier this month. The Morgan Stanley update comes amid broader Wall Street optimism surrounding the American refining giant, with ****** ysts from Raymon James, UBS, and several others also improving their respective outlooks on MPC.
Morgan Stanley's vote of confidence suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, especially given the fresh wave of attacks between Washington and Tehran. Even if the conflict in the Middle East subsides, the region's refined fuel output is expected to remain relatively tight, since the damaged or idled refineries in the Middle East are likely to take some time to return to full operations.
As the largest refiner by volume in the United States, Marathon has significant operating leverage to capitalize on the current high-margin environment. The company already demonstrated its ability to translate the high crack spreads into material earnings when it delivered an almost fourfold increase in profits in the second quarter.
#morgan #marathon #stanley #middle
With Marathon up by over 150% since the beginning of 2026, there are now concerns that the stock may have topped out. However, the ****** ysts over at Morgan Stanley are convinced that the rally still has further room to run. On September 14, Morgan Stanley ****** yst Joe Laetsch significantly raised the firm's price target on MPC from $265 to $453, while reaffirming an 'Overweight' rating on the shares.
The target boost reflects an upside of over 9% from the current price level and even exceeds the stock's record high of just under $411 per share achieved earlier this month. The Morgan Stanley update comes amid broader Wall Street optimism surrounding the American refining giant, with ****** ysts from Raymon James, UBS, and several others also improving their respective outlooks on MPC.
Morgan Stanley's vote of confidence suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, especially given the fresh wave of attacks between Washington and Tehran. Even if the conflict in the Middle East subsides, the region's refined fuel output is expected to remain relatively tight, since the damaged or idled refineries in the Middle East are likely to take some time to return to full operations.
As the largest refiner by volume in the United States, Marathon has significant operating leverage to capitalize on the current high-margin environment. The company already demonstrated its ability to translate the high crack spreads into material earnings when it delivered an almost fourfold increase in profits in the second quarter.
#morgan #marathon #stanley #middle

2 days ago
Valero Energy Corporation (NYSE:VLO) has been on a strong rally, posting gains of over 140% since the beginning of 2026. The strong performance is fuelled by an unusually sharp surge in global refining margins as the ongoing disruptions have significantly reduced the world's refining capacity and tightened supplies of gasoline, diesel, and jet fuel.
While there are now investor concerns that the stock may have topped out, Wall Street sees further upside ahead. On September 14, Morgan Stanley ******* yst Joe Laetsch significantly boosted the firm's price target on VLO from $255 to $411, while maintaining an 'Equal Weight' rating on the shares. The revised target implies an upside of almost 4% from the current levels and even exceeds the stock's all-time high of just under $400 per share.
The higher price objective is supported by the possibility that Valero can translate the favorable refining environment into material earnings and cash flows. The company did exactly that in the second quarter, when it posted its highest-ever Q2 profit and topped Wall Street expectations.
It seems like the high-margin environment is here to stay following a fresh wave of attacks between the US and Iran. Even if the attacks stop and a potential peace agreement is achieved, the damaged or idled refineries in the Middle East are likely to take some time to return to full operations, keeping refined-fuel markets relatively tight. Notably, the supply disruptions also extend beyond the troubled region, as a recent series of Ukrainian strikes on Russian refineries has further constrained global refining capacity.
Valero's FCC Unit optimization project at its St. Charles Refinery will allow it to capitalize even further on the high-priced environment. Expected to be completed in the third quarter, the $230 million initiative will help enhance the facility's ability to produce high-value products.
#even #environment #wall #strong
While there are now investor concerns that the stock may have topped out, Wall Street sees further upside ahead. On September 14, Morgan Stanley ******* yst Joe Laetsch significantly boosted the firm's price target on VLO from $255 to $411, while maintaining an 'Equal Weight' rating on the shares. The revised target implies an upside of almost 4% from the current levels and even exceeds the stock's all-time high of just under $400 per share.
The higher price objective is supported by the possibility that Valero can translate the favorable refining environment into material earnings and cash flows. The company did exactly that in the second quarter, when it posted its highest-ever Q2 profit and topped Wall Street expectations.
It seems like the high-margin environment is here to stay following a fresh wave of attacks between the US and Iran. Even if the attacks stop and a potential peace agreement is achieved, the damaged or idled refineries in the Middle East are likely to take some time to return to full operations, keeping refined-fuel markets relatively tight. Notably, the supply disruptions also extend beyond the troubled region, as a recent series of Ukrainian strikes on Russian refineries has further constrained global refining capacity.
Valero's FCC Unit optimization project at its St. Charles Refinery will allow it to capitalize even further on the high-priced environment. Expected to be completed in the third quarter, the $230 million initiative will help enhance the facility's ability to produce high-value products.
#even #environment #wall #strong

3 days ago
Margin debt hit $1.45 trillion in August, up 140% since 2022 and outpacing the S&P 500's 98% gain, which leaves the market carrying far more forced-selling risk.
At roughly 4.5% of GDP, margin debt now exceeds the dot-com bubble's peak, meaning a routine correction could cascade into broker-forced liquidations across the market.
The real danger isn't high leverage itself but the simultaneous forced selling that erupts when overleveraged investors all need cash at once.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
The longer-term comparison is even more striking. Since the end of 2022 -- and the start of the current AI-dominated era -- investor borrowing has increased by $847 billion, or 140%, versus a 98% gain for the S&P 500 over the same period. That means leverage has grown faster than the market value investors have accumulated, presumably as they took on debt to buy into the AI boom.
#market #leverage #investors
At roughly 4.5% of GDP, margin debt now exceeds the dot-com bubble's peak, meaning a routine correction could cascade into broker-forced liquidations across the market.
The real danger isn't high leverage itself but the simultaneous forced selling that erupts when overleveraged investors all need cash at once.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
The longer-term comparison is even more striking. Since the end of 2022 -- and the start of the current AI-dominated era -- investor borrowing has increased by $847 billion, or 140%, versus a 98% gain for the S&P 500 over the same period. That means leverage has grown faster than the market value investors have accumulated, presumably as they took on debt to buy into the AI boom.
#market #leverage #investors

3 days ago
Interested in Keysight Technologies Inc.? Here are five stocks we like better.
AI data-center demand is driving strong growth in Keysight's wireline business, particularly around 1.6T and emerging 3.2T networking, silicon photonics, co-packaged optics and system-level testing.
Demand currently exceeds supply, with Keysight expanding manufacturing capacity, supplier agreements and component sourcing; revenue beyond its typical order-to-revenue window was approaching $100 million.
Keysight expects additional growth from 6G, aerospace and defense, semiconductors and software-defined vehicles. The company anticipates 6G acceleration in the first half of 2028 and plans to maintain investment while targeting incremental margins of at least 40% when growth exceeds 5%.
3 Lesser-Known Quantum Plays the Market May Be Overlooking Right Now
#exceeds #lesser
AI data-center demand is driving strong growth in Keysight's wireline business, particularly around 1.6T and emerging 3.2T networking, silicon photonics, co-packaged optics and system-level testing.
Demand currently exceeds supply, with Keysight expanding manufacturing capacity, supplier agreements and component sourcing; revenue beyond its typical order-to-revenue window was approaching $100 million.
Keysight expects additional growth from 6G, aerospace and defense, semiconductors and software-defined vehicles. The company anticipates 6G acceleration in the first half of 2028 and plans to maintain investment while targeting incremental margins of at least 40% when growth exceeds 5%.
3 Lesser-Known Quantum Plays the Market May Be Overlooking Right Now
#exceeds #lesser
4 days ago
When planning for retirement, most people account for housing, travel, daily living expenses and general healthcare costs. However, it's easy to overlook one retirement expense: the Income-Related Monthly Adjustment Amount, commonly known as IRMAA.
If you have a large pension, substantial tax-deferred retirement accounts, or other variables that may elevate your retirement income, IRMAA is a factor you may encounter starting in your mid-60s. While it is unlikely to derail a well-constructed financial plan, failing to understand IRMAA and how to plan ahead for it can lead to frustrating annual surprises.
In the United States, most adults become eligible for Medicare when they turn 65. Medicare is divided into several parts, but IRMAA specifically applies to two of them: Part B (which covers doctor visits, outpatient care and preventive services) and Part D (prescription drug coverage).
For the average retiree, Medicare Part B carries a standard monthly base premium ($202.90 per month in 2026). Part D coverage varies depending on the specific private plan selected, but carries a national average base premium of roughly $38.99 per month. Combined, a standard retiree pays roughly $242 per month for basic Part B and Part D coverage, per Medicare.
However, Medicare premiums are not one-size-fits-all. If your income exceeds specific threshold limits set by the federal government, you will be required to pay an additional surcharge on top of your base monthly premiums. That additional surcharge is IRMAA.
#income #base
If you have a large pension, substantial tax-deferred retirement accounts, or other variables that may elevate your retirement income, IRMAA is a factor you may encounter starting in your mid-60s. While it is unlikely to derail a well-constructed financial plan, failing to understand IRMAA and how to plan ahead for it can lead to frustrating annual surprises.
In the United States, most adults become eligible for Medicare when they turn 65. Medicare is divided into several parts, but IRMAA specifically applies to two of them: Part B (which covers doctor visits, outpatient care and preventive services) and Part D (prescription drug coverage).
For the average retiree, Medicare Part B carries a standard monthly base premium ($202.90 per month in 2026). Part D coverage varies depending on the specific private plan selected, but carries a national average base premium of roughly $38.99 per month. Combined, a standard retiree pays roughly $242 per month for basic Part B and Part D coverage, per Medicare.
However, Medicare premiums are not one-size-fits-all. If your income exceeds specific threshold limits set by the federal government, you will be required to pay an additional surcharge on top of your base monthly premiums. That additional surcharge is IRMAA.
#income #base

6 days ago
Anthropic is moving forward with plans for an initial public offering that could value the company at $2 trillion, with signs pointing to the listing remaining on track, according to Bloomberg. Nasdaq has been selected as the venue for the listing, and Nvidia is reportedly weighing a contribution of around $10 billion to the offering.
Bloomberg reports Anthropic's annualized revenue at $65 billion, with the company's margins underpinned by investor confidence in where AI capabilities are headed rather than by today's cash generation.
The IPO comes as Anthropic chief executive officer Dario Amodei has published an essay calling on AI companies to manage the pace of frontier model development. Amodei's essay calls on firms "must slow the pace" of capability improvements, yet frames the goal as "a balanced rate" of progress, with the ****** urance that "progress will still seem fast," Bloomberg notes. When CFO Krishna Rao shared the piece on LinkedIn, his commentary centered on the themes of "pacing" and "common standards."
Anthropic is preparing to tell IPO investors that its potential revenue opportunity exceeds $30 trillion, according to The Wall Street Journal. The company more than doubled its revenue to $11.6 billion in the second quarter and could seek to raise as much as $100 billion in its offering — both figures that would surpass what ****** eX achieved when it went public in June at a $1.77 trillion valuation.
Investors have projected that Anthropic's annualized revenue will reach between $100 billion and $120 billion before year's end, representing more than tenfold growth from the $47 billion annualized revenue the company reported in May, according to the Financial Times as cited in earlier reporting. Morgan Stanley, Goldman Sachs, and JPMorgan are leading the offering. The company filed paperwork with the Securities and Exchange Commission in June.
#billion #bloomberg #trillion #according
Bloomberg reports Anthropic's annualized revenue at $65 billion, with the company's margins underpinned by investor confidence in where AI capabilities are headed rather than by today's cash generation.
The IPO comes as Anthropic chief executive officer Dario Amodei has published an essay calling on AI companies to manage the pace of frontier model development. Amodei's essay calls on firms "must slow the pace" of capability improvements, yet frames the goal as "a balanced rate" of progress, with the ****** urance that "progress will still seem fast," Bloomberg notes. When CFO Krishna Rao shared the piece on LinkedIn, his commentary centered on the themes of "pacing" and "common standards."
Anthropic is preparing to tell IPO investors that its potential revenue opportunity exceeds $30 trillion, according to The Wall Street Journal. The company more than doubled its revenue to $11.6 billion in the second quarter and could seek to raise as much as $100 billion in its offering — both figures that would surpass what ****** eX achieved when it went public in June at a $1.77 trillion valuation.
Investors have projected that Anthropic's annualized revenue will reach between $100 billion and $120 billion before year's end, representing more than tenfold growth from the $47 billion annualized revenue the company reported in May, according to the Financial Times as cited in earlier reporting. Morgan Stanley, Goldman Sachs, and JPMorgan are leading the offering. The company filed paperwork with the Securities and Exchange Commission in June.
#billion #bloomberg #trillion #according

8 days ago
SPY surged 11% year-to-date while home prices hit all-time highs, powering a record $12.5 trillion single-quarter wealth gain to $185.7 trillion total.
The personal saving rate collapsed to 2.8% from 5.8% a year ago as Americans spend paper gains concentrated among the wealthiest households.
Household net worth hit 571% of GDP, just shy of the 574% record that previously preceded the Fed's most aggressive rate-hiking cycle in four decades.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
American households just booked the largest quarterly wealth gain in history, and most Americans do not feel any richer. Federal Reserve data released this month shows U.S. household net worth jumped $12.5 trillion in the second quarter of 2026, reaching a record $185.7 trillion. That single-quarter increase exceeds the annual gross domestic product of every country on earth except the United States and China. It is the eleventh straight quarter of gains, a streak that has added $43.4 trillion to household balance sheets and pushed ***** ulative wealth creation since the 2020 pandemic to $83.9 trillion. Yet the University of Michigan's consumer sentiment index came in at 55.2 in July, a level the survey's own interpretation guide classifies as recessionary.
#trillion #quarter #record #year
The personal saving rate collapsed to 2.8% from 5.8% a year ago as Americans spend paper gains concentrated among the wealthiest households.
Household net worth hit 571% of GDP, just shy of the 574% record that previously preceded the Fed's most aggressive rate-hiking cycle in four decades.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
American households just booked the largest quarterly wealth gain in history, and most Americans do not feel any richer. Federal Reserve data released this month shows U.S. household net worth jumped $12.5 trillion in the second quarter of 2026, reaching a record $185.7 trillion. That single-quarter increase exceeds the annual gross domestic product of every country on earth except the United States and China. It is the eleventh straight quarter of gains, a streak that has added $43.4 trillion to household balance sheets and pushed ***** ulative wealth creation since the 2020 pandemic to $83.9 trillion. Yet the University of Michigan's consumer sentiment index came in at 55.2 in July, a level the survey's own interpretation guide classifies as recessionary.
#trillion #quarter #record #year

10 days ago
LAS VEGAS — When the Miami Dolphins open the 2026 season against the Las Vegas Raiders, nearly a quarter of their active roster will consist of rookies. The Dolphins have 13 of them, most in the NFL, all with a story to tell on the road to realize their dreams.
For fullback DJ Herman, his reality exceeds anything he could have dreamed.
"I'm even more stoked than probably some of these other rookies because I'm going back to my hometown, where it all started, in Las Vegas," Herman said.
Herman figures "all the stars aligned" for his big day to be wrapped in a family reunion and personal cheering section about 50 strong.
Buy Miami Dolphins tickets on StubHub
#rookies #season
For fullback DJ Herman, his reality exceeds anything he could have dreamed.
"I'm even more stoked than probably some of these other rookies because I'm going back to my hometown, where it all started, in Las Vegas," Herman said.
Herman figures "all the stars aligned" for his big day to be wrapped in a family reunion and personal cheering section about 50 strong.
Buy Miami Dolphins tickets on StubHub
#rookies #season


11 days ago
Microsoft (MSFT) is coming off the most profitable stretch it has posted in years, and its stock trades at $493.95, about 92% of its 52-week high. Nothing here is broken. The risk is quieter than that. The spending that came with those margins is still climbing, and the company has already told shareholders what it expects that to do to fiscal 2027.
Net margin over the trailing twelve months is 40.3%, the highest in at least five years and well above a 36.8% three-year average. Operating margin runs 46.8% against a 45.3% three-year average, near the top of its multi-year range. Revenue of $331.8 billion grew 17.8% year over year, so none of this came from a shrinking business.
Margins at a peak rarely stay there. This peak arrives with a specific and growing bill, and that bill is the Azure build-out.
Azure revenue grew 43% in fiscal Q4 2026, and management says customer demand still exceeds available capacity. Company-wide, the build-out took $41 billion of capital expenditure in that one quarter (including equipment acquired under leases), roughly two-thirds of it on what management calls short-lived **** ets, primarily CPUs and GPUs. Against $55.4 billion in cash from operations, cash actually paid for property and equipment was $35.8 billion, yielding $19.6 billion in free cash flow.
The bill is already visible in the margin. The company's gross margin was 67% in fiscal Q4 2026, down year over year, and management attributes the decline to the sales mix shift toward Azure and the AI infrastructure spending behind it, offset only partly by efficiency gains. Capital expenditure is guided higher again in fiscal 2027.
#azure #bill #cash
Net margin over the trailing twelve months is 40.3%, the highest in at least five years and well above a 36.8% three-year average. Operating margin runs 46.8% against a 45.3% three-year average, near the top of its multi-year range. Revenue of $331.8 billion grew 17.8% year over year, so none of this came from a shrinking business.
Margins at a peak rarely stay there. This peak arrives with a specific and growing bill, and that bill is the Azure build-out.
Azure revenue grew 43% in fiscal Q4 2026, and management says customer demand still exceeds available capacity. Company-wide, the build-out took $41 billion of capital expenditure in that one quarter (including equipment acquired under leases), roughly two-thirds of it on what management calls short-lived **** ets, primarily CPUs and GPUs. Against $55.4 billion in cash from operations, cash actually paid for property and equipment was $35.8 billion, yielding $19.6 billion in free cash flow.
The bill is already visible in the margin. The company's gross margin was 67% in fiscal Q4 2026, down year over year, and management attributes the decline to the sales mix shift toward Azure and the AI infrastructure spending behind it, offset only partly by efficiency gains. Capital expenditure is guided higher again in fiscal 2027.
#azure #bill #cash


14 days ago
CNBC reported on August 27, 2026, that BitGo Holdings, Inc. (NYSE:BTGO) will acquire the institutional trading business of NYDIG, adding derivatives, structured products, financing, and other capital markets services to its existing custody, settlement, and wallet infrastructure.
About 30 NYDIG employees and roughly 250 institutional client relationships will join BitGo, according to a person close to the matter; a regulatory filing put the deal's total consideration at about $42.5 million, mostly in BitGo stock. BitGo, which went public earlier this year and has a market value under $1 billion, is expanding its institutional capabilities. NYDIG said it will instead focus on power generation, Bitcoin mining, and high-performance computing data centers, where its development pipeline already exceeds 3 gigawatts.
Source: Unsplash
The deal moves BitGo toward a more complete, higher-margin institutional platform. CEO Mike Belshe said institutions want a partner supporting the "full lifecycle of digital ****** ets, from custody and trading to financing and settlement," and adding derivatives and structured products allows BitGo Holdings, Inc. (NYSE:BTGO) to capture more of that lifecycle from each client. This expanded service could help BitGo make more money from its current institutional clients
The timing aligns with a recent crypto market rebound rather than a speculative bet on a future recovery, while BitGo gains an immediate institutional client base. Bitcoin had recently topped $80,000 after months of weak trading volume, while roughly 250 institutional client relationships and about 30 experienced staff will transfer to BitGo. Building that scale organically could take years.
#holdings #adding
About 30 NYDIG employees and roughly 250 institutional client relationships will join BitGo, according to a person close to the matter; a regulatory filing put the deal's total consideration at about $42.5 million, mostly in BitGo stock. BitGo, which went public earlier this year and has a market value under $1 billion, is expanding its institutional capabilities. NYDIG said it will instead focus on power generation, Bitcoin mining, and high-performance computing data centers, where its development pipeline already exceeds 3 gigawatts.
Source: Unsplash
The deal moves BitGo toward a more complete, higher-margin institutional platform. CEO Mike Belshe said institutions want a partner supporting the "full lifecycle of digital ****** ets, from custody and trading to financing and settlement," and adding derivatives and structured products allows BitGo Holdings, Inc. (NYSE:BTGO) to capture more of that lifecycle from each client. This expanded service could help BitGo make more money from its current institutional clients
The timing aligns with a recent crypto market rebound rather than a speculative bet on a future recovery, while BitGo gains an immediate institutional client base. Bitcoin had recently topped $80,000 after months of weak trading volume, while roughly 250 institutional client relationships and about 30 experienced staff will transfer to BitGo. Building that scale organically could take years.
#holdings #adding

15 days ago
Prominent economist Mohamed El-Erian argues hyperscalers and national governments are issuing a flood of bonds to keep up their rapid spending velocity onto fewer buyers. Those straightforward circumstances are pushing bond yields up.
"If you look at the amount of issuance that's coming from governments, from hyperscalers, from companies, it far exceeds what you can count on in terms of reliable buyers, and that's why there's been pressure on interest rates, El-Erian told CNBC in an interview on Friday. "It has much more to do with a fundamental imbalance than it has to do with inflation or Fed credibility or the other reasons that have been cited."
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#governments #Friday
"If you look at the amount of issuance that's coming from governments, from hyperscalers, from companies, it far exceeds what you can count on in terms of reliable buyers, and that's why there's been pressure on interest rates, El-Erian told CNBC in an interview on Friday. "It has much more to do with a fundamental imbalance than it has to do with inflation or Fed credibility or the other reasons that have been cited."
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#governments #Friday


16 days ago
Prominent economist Mohamed El-Erian argues hyperscalers and national governments are issuing a flood of bonds to keep up their rapid spending velocity onto fewer buyers. Those straightforward circumstances are pushing bond yields up.
"If you look at the amount of issuance that's coming from governments, from hyperscalers, from companies, it far exceeds what you can count on in terms of reliable buyers, and that's why there's been pressure on interest rates, El-Erian told CNBC in an interview on Friday. "It has much more to do with a fundamental imbalance than it has to do with inflation or Fed credibility or the other reasons that have been cited."
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#governments #buyers #jeff #bezos
"If you look at the amount of issuance that's coming from governments, from hyperscalers, from companies, it far exceeds what you can count on in terms of reliable buyers, and that's why there's been pressure on interest rates, El-Erian told CNBC in an interview on Friday. "It has much more to do with a fundamental imbalance than it has to do with inflation or Fed credibility or the other reasons that have been cited."
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#governments #buyers #jeff #bezos


18 days ago
Noting that long-held KLA Corporation (NASDAQ:KLAC) shares had pulled back significantly after peaking past $300 in June, a caller on the September 1 episode of Mad Money asked if it is a buy, hold, or sell. In response, Jim Cramer said:
I think it's a great company. It is up 40% for the year. Its price-to-earnings multiple is still too high. It does great intellectual property. I think if you wanted to buy some here, it's fine. But again, I would not put a lot of it on. Why? Because these are all semiconductor capital equipment companies that I've been talking about this evening. They're extremely volatile. You can buy a quarter… and then you have to wait no more than that because we have to see what happens. I don't want you to put on too much money at one level in a stock this volatile.
KLA Corporation (NASDAQ:KLAC) has built an extraordinary business by dominating the semiconductor process control and inspection market. Advanced-node, high-bandwidth-memory and complex logic manufacturing increasingly requires sophisticated inspection and metrology tools, an area where KLA holds a leading position. The deep competitive moat and exceptional intellectual property make it an important player in the semiconductor supply chain. For long-term investors, this technical leadership provides a solid foundation that exceeds routine industry ups and downs.
Even with top-tier technology, KLA Corporation's (NASDAQ:KLAC) sharp climb leaves little room for error. Up nearly 33% year-to-date at the time of writing and trading at a forward multiple of 31.65x, the valuation shows a heavy dose of optimism. Semiconductor capital equipment stocks are notoriously cyclical and ******* e to sharp price swings, meaning that a pullback from recent highs can quickly turn into a deeper correction if market sentiment shifts or fab spending slows down.
Wall Street's major players keep a close watch on KLA Corporation (NASDAQ:KLAC) as a reliable gauge of overall semiconductor capital spending. According to Insider Monkey's database tracking elite hedge funds, 81 funds held a position in the stock during the second quarter, up from 71 in the previous quarter, showing clear institutional interest. Arrowstreet Capital remained the company's top shareholder in the second quarter, despite reducing its position by 41% to 4.7 million shares. At the same time, short interest sits at just 2.16% of the float, indicating that professional bears are largely keeping their distance despite the company's high price tag.
#NASDAQ #klac #quarter
I think it's a great company. It is up 40% for the year. Its price-to-earnings multiple is still too high. It does great intellectual property. I think if you wanted to buy some here, it's fine. But again, I would not put a lot of it on. Why? Because these are all semiconductor capital equipment companies that I've been talking about this evening. They're extremely volatile. You can buy a quarter… and then you have to wait no more than that because we have to see what happens. I don't want you to put on too much money at one level in a stock this volatile.
KLA Corporation (NASDAQ:KLAC) has built an extraordinary business by dominating the semiconductor process control and inspection market. Advanced-node, high-bandwidth-memory and complex logic manufacturing increasingly requires sophisticated inspection and metrology tools, an area where KLA holds a leading position. The deep competitive moat and exceptional intellectual property make it an important player in the semiconductor supply chain. For long-term investors, this technical leadership provides a solid foundation that exceeds routine industry ups and downs.
Even with top-tier technology, KLA Corporation's (NASDAQ:KLAC) sharp climb leaves little room for error. Up nearly 33% year-to-date at the time of writing and trading at a forward multiple of 31.65x, the valuation shows a heavy dose of optimism. Semiconductor capital equipment stocks are notoriously cyclical and ******* e to sharp price swings, meaning that a pullback from recent highs can quickly turn into a deeper correction if market sentiment shifts or fab spending slows down.
Wall Street's major players keep a close watch on KLA Corporation (NASDAQ:KLAC) as a reliable gauge of overall semiconductor capital spending. According to Insider Monkey's database tracking elite hedge funds, 81 funds held a position in the stock during the second quarter, up from 71 in the previous quarter, showing clear institutional interest. Arrowstreet Capital remained the company's top shareholder in the second quarter, despite reducing its position by 41% to 4.7 million shares. At the same time, short interest sits at just 2.16% of the float, indicating that professional bears are largely keeping their distance despite the company's high price tag.
#NASDAQ #klac #quarter

18 days ago
The numbers don't lie: Nvidia (NVDA) has never had more influence on the broader stock market than right now.
Nvidia now accounts for about 8% of the S&P 500's (^GSPC) market cap, near its highest proportion on record per data from Augur Infinity (chart below). At a market cap of $5.4 trillion (and climbing), Nvidia's value is now bigger than that of five of the S&P 500's 11 sectors.
The AI chip darling's market cap also exceeds the combined value of the energy, utilities, real estate, and materials sectors in the S&P 500.
"Nvidia is making history," strategists at The Kobeissi Letter said.
The history is not coming without a host of very good reasons.
Nvidia said after reporting its fiscal second quarter earnings that it sees 70% revenue growth for fiscal year 2028. This was above **** yst forecasts for 45% growth. The sales gain would be larger — think in excess of 100% — if not for memory chip shortages, said Nvidia CEO Jensen Huang.
The company saw adjusted earnings per share of $2.22 on revenue of $96.2 billion in its just-reported quarter. These were better than the $2.09 per share the Street had expected and revenue of $92.3 billion.
#market #history #quarter #earnings
Nvidia now accounts for about 8% of the S&P 500's (^GSPC) market cap, near its highest proportion on record per data from Augur Infinity (chart below). At a market cap of $5.4 trillion (and climbing), Nvidia's value is now bigger than that of five of the S&P 500's 11 sectors.
The AI chip darling's market cap also exceeds the combined value of the energy, utilities, real estate, and materials sectors in the S&P 500.
"Nvidia is making history," strategists at The Kobeissi Letter said.
The history is not coming without a host of very good reasons.
Nvidia said after reporting its fiscal second quarter earnings that it sees 70% revenue growth for fiscal year 2028. This was above **** yst forecasts for 45% growth. The sales gain would be larger — think in excess of 100% — if not for memory chip shortages, said Nvidia CEO Jensen Huang.
The company saw adjusted earnings per share of $2.22 on revenue of $96.2 billion in its just-reported quarter. These were better than the $2.09 per share the Street had expected and revenue of $92.3 billion.
#market #history #quarter #earnings

18 days ago
A crash, a penalty… what next? For a man who's just turned 20, Italian hotshot Kimi Antonelli has already endured a tumultuous relationship with his home grand prix: the electrifying, old-school Monza circuit, long christened Formula 1's Temple of Speed.
Two years ago, on the same weekend that Toto Wolff announced that then-F2 driver Antonelli would have the small shoes of Lewis Hamilton to fill in 2025, Antonelli took part in his first F1 session. On his second flying lap, full-send around the final high-speed Parabolica corner, the teen dumped his car violently into the wall. Then, in 2025, Antonelli crashed again in practice before receiving a penalty for track limits and running Alex Albon off the circuit.
Coming in the midst of a helter-skelter rookie year, Wolff acknowledged that Antonelli's ninth-place performance had been "underwhelming," urging his protege to "just free up." Fast-forward 12 months, Antonelli is potentially 11 races away from becoming F1's youngest-ever world champion. And on Thursday, he acknowledged he feels "very free mentally."
Yet Antonelli's chances of becoming the first home driver to win the Italian Grand Prix since Ferrari's Ludovico Scarfiotti in 1966 are slim, bordering on zero. The championship leader, 59 points clear at the top, will take a 20-place grid penalty this weekend as he exceeds his engine allocation for the season. Mercedes's thinking is that, with Monza's mammoth long straight, overtaking from the back of the grid will be easier come raceday. Still, it feels a shame to lose the budding romance of a potential first Italian winner in 60 years.
"In some ways, it makes me a bit more relaxed going into the weekend," Antonelli said in the FIA press conference. "That's why I'm going to be able to enjoy more the driving and the weekend itself. Also, it's a different opportunity.
#wolff #grand #home
Two years ago, on the same weekend that Toto Wolff announced that then-F2 driver Antonelli would have the small shoes of Lewis Hamilton to fill in 2025, Antonelli took part in his first F1 session. On his second flying lap, full-send around the final high-speed Parabolica corner, the teen dumped his car violently into the wall. Then, in 2025, Antonelli crashed again in practice before receiving a penalty for track limits and running Alex Albon off the circuit.
Coming in the midst of a helter-skelter rookie year, Wolff acknowledged that Antonelli's ninth-place performance had been "underwhelming," urging his protege to "just free up." Fast-forward 12 months, Antonelli is potentially 11 races away from becoming F1's youngest-ever world champion. And on Thursday, he acknowledged he feels "very free mentally."
Yet Antonelli's chances of becoming the first home driver to win the Italian Grand Prix since Ferrari's Ludovico Scarfiotti in 1966 are slim, bordering on zero. The championship leader, 59 points clear at the top, will take a 20-place grid penalty this weekend as he exceeds his engine allocation for the season. Mercedes's thinking is that, with Monza's mammoth long straight, overtaking from the back of the grid will be easier come raceday. Still, it feels a shame to lose the budding romance of a potential first Italian winner in 60 years.
"In some ways, it makes me a bit more relaxed going into the weekend," Antonelli said in the FIA press conference. "That's why I'm going to be able to enjoy more the driving and the weekend itself. Also, it's a different opportunity.
#wolff #grand #home


18 days ago
The scene in Bilbao, in 2024, foreshadowed the change that would come. Michele Kang, the owner of OL Lyonnes, strode around the edge of the pitch in the San Mames to greet the travelling supporters of the women's football powerhouse, who were buoyed by her ambition and intent to invest. Barcelona won 2-0 to lift their third Women's Champions League **** le in four years, thanks to goals from their two Ballon d'Or winners Aitana Bonmati and Alexia Putellas. But while Kang, the South Korean-born American billionaire and philanthropist, vowed that Lyonnes would return stronger, her sphere of influence was also primed to have an impact elsewhere.
As well as the French champions, Kang owned two other teams as part of her multi-club Kynisca group, the US side Washington Spirit and the London City Lionesses, based out of Bromley and playing in the second tier of English women's football. Two years on, driven by Kang's vision and fuelled by her deep pockets, London City have secured promotion and undergone a remarkable makeover. From that Champions League final alone, they have signed not just Putellas, making the Spain international and World Cup winner the biggest overseas signing in Women's Super League history, but two of her Barcelona team-mates in Mapi Leon and Jana Fernandez. From sister club Lyonnes, London City have signed two of their starting forwards in Kadidiatou Diani and Delphine Cascarino, as well as midfielder Danielle van de Donk.
Michele Kang celebrates London City's promotion to the Women's Super League in 2025 (Getty)
Within two years, London City have disrupted women's football and have now set their sights on challenging for the WSL **** le. It has not come cheap: Putellas was a free transfer but is one of the highest-paid women's footballers in the world at around £1m per year. Before the new season, London City have also signed former England goalkeeper Mary Earps from Paris Saint-Germain and have built a team set on challenging **** nal and Chelsea's dominance in the capital. In terms of transfer fees within the WSL, only **** nal and Chelsea have come close to matching the £1m London City paid PSG for midfielder Grace Geyoro last summer. Their position is also a unique one. Of the 14 teams in this season's expanded WSL, London City are the only independent outfit with no affiliation to a men's club, yet their spending comfortably exceeds that of Manchester United and Liverpool, despite the riches that flow from the Premier League.
Kang is the driving force. The 67-year-old, who made her fortune through healthcare technology in the US, is an investor in the true sense of the word, believing in the untapped value and potential of women's sports. Her philanthropy has extended to making $30m and $4m donations to US Soccer and USA Rugby respectively, the latter just hours after watching the US women's rugby sevens team win bronze at the 2024 Paris Olympics. London City are likely to make a financial loss in their second season o
As well as the French champions, Kang owned two other teams as part of her multi-club Kynisca group, the US side Washington Spirit and the London City Lionesses, based out of Bromley and playing in the second tier of English women's football. Two years on, driven by Kang's vision and fuelled by her deep pockets, London City have secured promotion and undergone a remarkable makeover. From that Champions League final alone, they have signed not just Putellas, making the Spain international and World Cup winner the biggest overseas signing in Women's Super League history, but two of her Barcelona team-mates in Mapi Leon and Jana Fernandez. From sister club Lyonnes, London City have signed two of their starting forwards in Kadidiatou Diani and Delphine Cascarino, as well as midfielder Danielle van de Donk.
Michele Kang celebrates London City's promotion to the Women's Super League in 2025 (Getty)
Within two years, London City have disrupted women's football and have now set their sights on challenging for the WSL **** le. It has not come cheap: Putellas was a free transfer but is one of the highest-paid women's footballers in the world at around £1m per year. Before the new season, London City have also signed former England goalkeeper Mary Earps from Paris Saint-Germain and have built a team set on challenging **** nal and Chelsea's dominance in the capital. In terms of transfer fees within the WSL, only **** nal and Chelsea have come close to matching the £1m London City paid PSG for midfielder Grace Geyoro last summer. Their position is also a unique one. Of the 14 teams in this season's expanded WSL, London City are the only independent outfit with no affiliation to a men's club, yet their spending comfortably exceeds that of Manchester United and Liverpool, despite the riches that flow from the Premier League.
Kang is the driving force. The 67-year-old, who made her fortune through healthcare technology in the US, is an investor in the true sense of the word, believing in the untapped value and potential of women's sports. Her philanthropy has extended to making $30m and $4m donations to US Soccer and USA Rugby respectively, the latter just hours after watching the US women's rugby sevens team win bronze at the 2024 Paris Olympics. London City are likely to make a financial loss in their second season o
18 days ago
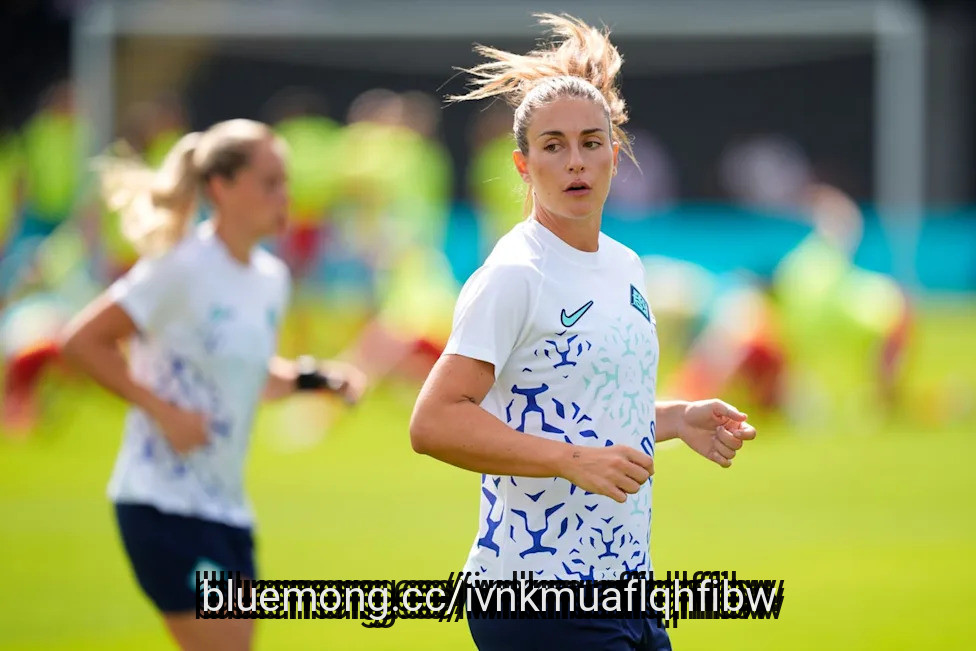
The names just kept coming, one after the other: Alexia Putellas, a two-time Ballon d'Or winner; Mary Earps, named the best women's goalkeeper by FIFA in 2022 and 2023; Mapi Leon, a four-time Champions League winner; and Kadidiatou Diani, who has earned more than 100 caps for France.
But how are the London City Lionesses, owned by American businesswoman Michele Kang, complying with the Women's Super League's financial rules to pay these big-name players?
Invest before revenue.
Kang, a Korean-American businesswoman, bought the club in 2023, helping them win promotion to the WSL in 2025. Finishing sixth in their debut top-flight season was respectable, but this summer, they have gone big. London City have splashed out on star players — albeit mostly on free transfers — for two reasons: they want to qualify for the Champions League and increase their revenue as soon as possible.
Earnings have to rise so they can afford to pay this set of players. London City are banking on marquee names attracting larger sponsorship deals and a new fanbase that will increase revenue down the line. On Thursday they announced a first-of-its-kind multi-year front-of-shirt partnership with Nike. The financial terms of the deal were not disclosed. Kang, however, said the value exceeds some Premier League men's teams' shirt deals and the $4million (£2.9 m) annual value of the NWSL's Atlanta expansion franchise's recent front-of-shirt agreement, believed to be the wealthiest jersey sponsorship in women's sports.
#city
But how are the London City Lionesses, owned by American businesswoman Michele Kang, complying with the Women's Super League's financial rules to pay these big-name players?
Invest before revenue.
Kang, a Korean-American businesswoman, bought the club in 2023, helping them win promotion to the WSL in 2025. Finishing sixth in their debut top-flight season was respectable, but this summer, they have gone big. London City have splashed out on star players — albeit mostly on free transfers — for two reasons: they want to qualify for the Champions League and increase their revenue as soon as possible.
Earnings have to rise so they can afford to pay this set of players. London City are banking on marquee names attracting larger sponsorship deals and a new fanbase that will increase revenue down the line. On Thursday they announced a first-of-its-kind multi-year front-of-shirt partnership with Nike. The financial terms of the deal were not disclosed. Kang, however, said the value exceeds some Premier League men's teams' shirt deals and the $4million (£2.9 m) annual value of the NWSL's Atlanta expansion franchise's recent front-of-shirt agreement, believed to be the wealthiest jersey sponsorship in women's sports.
#city


21 days ago
Cathie Wood's ARK Invest picked up 243,707 Nvidia shares on Friday at a total cost of approximately $53 million, according to Barron's. The buy came after Nvidia stock closed down 4.6% at $217.55 that day, pulling back from a surge driven by the chipmaker's latest earnings report.
The purchase fits a pattern that has emerged over recent months, with Wood adding to ARK's Nvidia holdings at the same time she has been paring back its AMD exposure. ARK sold 156,286 AMD shares on Friday as well.
Nvidia stock was up 0.5% at $218.70 in premarket trading Monday.
Nvidia's second-quarter revenue more than doubled, clearing ****** yst forecasts by the widest margin in two years, and the company projected 70% revenue growth for its fiscal 2028 year. Nvidia stock climbed roughly 7% on Thursday following the report, lifting chip stocks broadly and pushing major indexes higher. The stock's subsequent pullback on Friday set up the entry point for ARK's purchase.
CEO Jensen Huang said demand for the company's products exceeds its ability to supply them.
#Friday #shares #back #cathie
The purchase fits a pattern that has emerged over recent months, with Wood adding to ARK's Nvidia holdings at the same time she has been paring back its AMD exposure. ARK sold 156,286 AMD shares on Friday as well.
Nvidia stock was up 0.5% at $218.70 in premarket trading Monday.
Nvidia's second-quarter revenue more than doubled, clearing ****** yst forecasts by the widest margin in two years, and the company projected 70% revenue growth for its fiscal 2028 year. Nvidia stock climbed roughly 7% on Thursday following the report, lifting chip stocks broadly and pushing major indexes higher. The stock's subsequent pullback on Friday set up the entry point for ARK's purchase.
CEO Jensen Huang said demand for the company's products exceeds its ability to supply them.
#Friday #shares #back #cathie

24 days ago
The Florida State Seminoles will open their 2026 season Saturday night against New Mexico State, and the Aggies are receiving a seven-figure guarantee for making the trip to Tallahassee. According to a contract reported by the Tallahassee Democrat, Florida State agreed to pay New Mexico State $1.4 million for Saturday's game at Doak Campbell Stadium. The agreement called for the payment to be made by July 15.
The matchup is what is commonly referred to as a "buy game," with a larger program paying an opponent to play a one-off contest at its home stadium. Those guarantees can provide important revenue for Group of Six and FCS athletic departments while giving Power Four programs an additional home date.
Florida State's payment to New Mexico State exceeds the guarantees attached to two of its nonconference home games last season. The Seminoles paid Kent State $1.2 million for its trip to Tallahassee in 2025 and East Texas A&M $450,000 for its visit to Doak Campbell Stadium. FSU defeated those teams 66-10 and 77-3, respectively.
Saturday will mark only the second meeting between Florida State and New Mexico State. The programs first played on Oct. 3, 1964, when the Seminoles earned a 36-0 victory in Tallahassee. New Mexico State enters this season after finishing 4-8 in 2025, its second year under head coach Tony Sanchez.
The Aggies represent the first step in a schedule that becomes considerably more challenging for Florida State almost immediately. After Saturday's opener, the Seminoles host te No. 20 SMU Mustangs in their ACC opener before traveling to play the No. 11 Alabama Crimson Tide in Week 3.
#state #tallahassee #stadium
The matchup is what is commonly referred to as a "buy game," with a larger program paying an opponent to play a one-off contest at its home stadium. Those guarantees can provide important revenue for Group of Six and FCS athletic departments while giving Power Four programs an additional home date.
Florida State's payment to New Mexico State exceeds the guarantees attached to two of its nonconference home games last season. The Seminoles paid Kent State $1.2 million for its trip to Tallahassee in 2025 and East Texas A&M $450,000 for its visit to Doak Campbell Stadium. FSU defeated those teams 66-10 and 77-3, respectively.
Saturday will mark only the second meeting between Florida State and New Mexico State. The programs first played on Oct. 3, 1964, when the Seminoles earned a 36-0 victory in Tallahassee. New Mexico State enters this season after finishing 4-8 in 2025, its second year under head coach Tony Sanchez.
The Aggies represent the first step in a schedule that becomes considerably more challenging for Florida State almost immediately. After Saturday's opener, the Seminoles host te No. 20 SMU Mustangs in their ACC opener before traveling to play the No. 11 Alabama Crimson Tide in Week 3.
#state #tallahassee #stadium

25 days ago
Strategy Inc (NASDAQ:MSTR) rallied along with Bitcoin. The cryptocurrency rally followed a White House meeting with industry executives, while the Treasury Department's expanded bond-buyback plans lowered long-term yields and weakened the dollar.
However, Strategy Inc (NASDAQ:MSTR) is not a simple leveraged Bitcoin fund. The company held 843,775 Bitcoin on July 26, sold 1,638 Bitcoin during July 27-August 2, and another 1,690 during August 3-9, leaving 840,447 Bitcoin. That position was worth approximately $57.5 billion at Wednesday's Bitcoin price, but the figure represents gross **** et value rather than value attributable to common shareholders.
Common issuance increases gross Bitcoin per share only when the Bitcoin acquired per incremental **** umed diluted share exceeds the existing ratio. Issuing above net **** et value alone is insufficient because the share denominator and use of proceeds determine the result. Strategy Inc (NASDAQ:MSTR) reported that its company-defined Bitcoin-per-share metric increased 5% during the second quarter to 210,824 satoshis.
Strategy Inc (NASDAQ:MSTR) also had a $4.80 billion reserve as of August 16, including unsettled at-the-market offering proceeds. The reserve provides a buffer for contractual debt interest and preferred dividends when declared, although the preferred series have different terms, including **** ulative provisions for certain securities. This liquidity reduces near-term dependence on favorable Bitcoin or capital-market conditions.
Strategy Inc (NASDAQ:MSTR) reported $6.7 billion of aggregate convertible principal and a $15.5 billion aggregate preferred notional amount in May. At June 30, preferred equity had a $14.44 billion carrying amount and a $15.46 billion liquidation preference; repurchases began after quarter-end. These claims sit ahead of common equity under a basic-share valuation framework.
#NASDAQ
However, Strategy Inc (NASDAQ:MSTR) is not a simple leveraged Bitcoin fund. The company held 843,775 Bitcoin on July 26, sold 1,638 Bitcoin during July 27-August 2, and another 1,690 during August 3-9, leaving 840,447 Bitcoin. That position was worth approximately $57.5 billion at Wednesday's Bitcoin price, but the figure represents gross **** et value rather than value attributable to common shareholders.
Common issuance increases gross Bitcoin per share only when the Bitcoin acquired per incremental **** umed diluted share exceeds the existing ratio. Issuing above net **** et value alone is insufficient because the share denominator and use of proceeds determine the result. Strategy Inc (NASDAQ:MSTR) reported that its company-defined Bitcoin-per-share metric increased 5% during the second quarter to 210,824 satoshis.
Strategy Inc (NASDAQ:MSTR) also had a $4.80 billion reserve as of August 16, including unsettled at-the-market offering proceeds. The reserve provides a buffer for contractual debt interest and preferred dividends when declared, although the preferred series have different terms, including **** ulative provisions for certain securities. This liquidity reduces near-term dependence on favorable Bitcoin or capital-market conditions.
Strategy Inc (NASDAQ:MSTR) reported $6.7 billion of aggregate convertible principal and a $15.5 billion aggregate preferred notional amount in May. At June 30, preferred equity had a $14.44 billion carrying amount and a $15.46 billion liquidation preference; repurchases began after quarter-end. These claims sit ahead of common equity under a basic-share valuation framework.
#NASDAQ

25 days ago
Almonty Industries Inc. (NASDAQ:ALM) began a 36-month share-repurchase authorization on August 24 that permits the company to buy up to 14.4 million common shares, representing approximately 5% of shares outstanding as of August 14, for as much as US$300 million.
The headline amount overstates what Almonty Industries Inc. (NASDAQ:ALM) would spend at its current valuation. At the August 24 closing price of $18.28, repurchasing the full 14.4 million shares would cost approximately $263.2 million before transaction costs. The share limit would become the binding constraint unless the average purchase price exceeds roughly $20.83.
The buyback is financially plausible because Almonty Industries Inc. (NASDAQ:ALM) ended June with C$1.23 billion of cash. First-half operating cash flow reached C$31.6 million, compared with a C$14.9 million outflow a year earlier, while second-quarter revenue increased to C$43.0 million from C$7.2 million.
Sangdong is also moving beyond construction. Almonty Industries Inc. (NASDAQ:ALM) began feeding stockpiled ore into the processing plant in June to produce saleable tungsten concentrate. Phase I is designed for approximately 640,000 tonnes of annual ore throughput, and the planned Phase II expansion could increase capacity to approximately 1.2 million tonnes.
If management is correct that the market undervalues Sangdong's future cash flow, retiring shares before the mine reaches full output could increase each remaining shareholder's participation in that growth. Almonty Industries Inc. (NASDAQ:ALM) also has flexibility to spread purchases across three years rather than committing the entire amount immediately.
#million #phase
The headline amount overstates what Almonty Industries Inc. (NASDAQ:ALM) would spend at its current valuation. At the August 24 closing price of $18.28, repurchasing the full 14.4 million shares would cost approximately $263.2 million before transaction costs. The share limit would become the binding constraint unless the average purchase price exceeds roughly $20.83.
The buyback is financially plausible because Almonty Industries Inc. (NASDAQ:ALM) ended June with C$1.23 billion of cash. First-half operating cash flow reached C$31.6 million, compared with a C$14.9 million outflow a year earlier, while second-quarter revenue increased to C$43.0 million from C$7.2 million.
Sangdong is also moving beyond construction. Almonty Industries Inc. (NASDAQ:ALM) began feeding stockpiled ore into the processing plant in June to produce saleable tungsten concentrate. Phase I is designed for approximately 640,000 tonnes of annual ore throughput, and the planned Phase II expansion could increase capacity to approximately 1.2 million tonnes.
If management is correct that the market undervalues Sangdong's future cash flow, retiring shares before the mine reaches full output could increase each remaining shareholder's participation in that growth. Almonty Industries Inc. (NASDAQ:ALM) also has flexibility to spread purchases across three years rather than committing the entire amount immediately.
#million #phase


26 days ago
Aston Villa are on the verge of signing Chelsea striker Nicolas Jackson, with Fabrizio Romano reporting that personal terms between the player's camp and the club are nearly finalised. Aston Villa have now entered official club-to-club negotiations with Chelsea, with Unai Emery personally pushing the deal forward. The total package on the table exceeds £60 million. Jackson, 25, is not part of new Chelsea head coach Xabi Alonso's plans after returning from a season-long loan at Bayern Munich.
This isn't panic buying. Jackson spent the 2025/26 season at Bayern, scoring 8 goals in 23 Bundesliga appearances and contributing 3 goals and 2 ***** ists across 10 Champions League matches. He also scored twice for Senegal at the 2025 Africa Cup of Nations. A regular in Senegal's 2026 World Cup campaign too. He has proven he can function at the highest level.
Chelsea want him gone. That changes the negotiation entirely.
At £60m, Villa are acquiring a Premier League-tested, Champions League-experienced centre-forward who is 25 years old. The market for that profile is brutal right now, so the fee isn't outrageous; it's the going rate.
MUNICH, GERMANY – SEPTEMBER 17: Nicolas Jackson of Bayern Munich looks on from the bench during the UEFA Champions League 2025/26 League Phase MD1 match between FC Bayern München and Chelsea FC at Football Arena Munich on September 17, 2025 in Munich, Germany. (Photo by Alex Grimm/Getty Images)
#Chelsea #jackson #bayern #champions
This isn't panic buying. Jackson spent the 2025/26 season at Bayern, scoring 8 goals in 23 Bundesliga appearances and contributing 3 goals and 2 ***** ists across 10 Champions League matches. He also scored twice for Senegal at the 2025 Africa Cup of Nations. A regular in Senegal's 2026 World Cup campaign too. He has proven he can function at the highest level.
Chelsea want him gone. That changes the negotiation entirely.
At £60m, Villa are acquiring a Premier League-tested, Champions League-experienced centre-forward who is 25 years old. The market for that profile is brutal right now, so the fee isn't outrageous; it's the going rate.
MUNICH, GERMANY – SEPTEMBER 17: Nicolas Jackson of Bayern Munich looks on from the bench during the UEFA Champions League 2025/26 League Phase MD1 match between FC Bayern München and Chelsea FC at Football Arena Munich on September 17, 2025 in Munich, Germany. (Photo by Alex Grimm/Getty Images)
#Chelsea #jackson #bayern #champions

28 days ago
New reports indicate that artificial intelligence (AI) lab Anthropic could file its S-1 by the end of the month. Below, I'll detail why Anthropic's public debut carries outsize implications for major backers like Amazon (NASDAQ: AMZN), whose growth is intertwined with the start-up's trajectory.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Reports from Bloomberg suggest Anthropic is aiming for an initial public offering (IPO) that matches or exceeds ****** e Exploration Technologies' record raise from earlier this summer. Anthropic has already raised roughly $133 billion to date, most recently in a $65 billion Series H round that valued it at $965 billion. This near-trillion-dollar figure reflects Anthropic's explosive growth, with recent quarterly revenue surpassing $11.5 billion and an annualized run rate approaching $65 billion.
Amazon investors have good reason to monitor the Anthropic offering. Amazon has already invested $13 billion in Anthropic, with commitments for up to an additional $20 billion contingent on commercial milestones.
Beyond simple equity ownership, the partnership between Amazon and Anthropic runs deep through AWS. Anthropic uses Amazon's custom silicon for training and inference, including a massive deployment under Project Rainier that utilizes over 1 million Amazon Trainium chips, complemented by its Graviton processors.
#public
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Reports from Bloomberg suggest Anthropic is aiming for an initial public offering (IPO) that matches or exceeds ****** e Exploration Technologies' record raise from earlier this summer. Anthropic has already raised roughly $133 billion to date, most recently in a $65 billion Series H round that valued it at $965 billion. This near-trillion-dollar figure reflects Anthropic's explosive growth, with recent quarterly revenue surpassing $11.5 billion and an annualized run rate approaching $65 billion.
Amazon investors have good reason to monitor the Anthropic offering. Amazon has already invested $13 billion in Anthropic, with commitments for up to an additional $20 billion contingent on commercial milestones.
Beyond simple equity ownership, the partnership between Amazon and Anthropic runs deep through AWS. Anthropic uses Amazon's custom silicon for training and inference, including a massive deployment under Project Rainier that utilizes over 1 million Amazon Trainium chips, complemented by its Graviton processors.
#public

28 days ago
Anthropic is preparing to tell IPO investors that its potential revenue opportunity exceeds $30 trillion, according to The Wall Street Journal, citing people familiar with the matter. The figure would top the $28.5 trillion estimate **** eX presented to investors ahead of its own offering.
The company is basing its total addressable market, or TAM, on the full scope of work that could be completed using AI models. The metric reflects the maximum annual revenue a company could achieve if it captured every available customer, and is routinely deployed in IPO filings to signal how much upside remains for growth.
Anthropic more than doubled its revenue to $11.6 billion in the second quarter. For comparison, FactSet data cited by the Journal shows that the 191 tech companies in the S&P 1500 collectively generated $2.4 trillion in revenue last year.
The Claude maker could also aim to raise as much as $100 billion in its offering and is targeting a valuation of about $2 trillion. Both marks would surpass what **** eX achieved — the rocket company pulled in $86 billion and debuted at a $1.77 trillion valuation when it went public in June.
None of the figures are final, and the Journal notes that details of Anthropic's plans are still being worked out. Anthropic is expected to publish its IPO prospectus documents shortly, a timeline that would leave the door open for a market debut as early as September or early October.
#anthropic #revenue #billion #SpaceX
The company is basing its total addressable market, or TAM, on the full scope of work that could be completed using AI models. The metric reflects the maximum annual revenue a company could achieve if it captured every available customer, and is routinely deployed in IPO filings to signal how much upside remains for growth.
Anthropic more than doubled its revenue to $11.6 billion in the second quarter. For comparison, FactSet data cited by the Journal shows that the 191 tech companies in the S&P 1500 collectively generated $2.4 trillion in revenue last year.
The Claude maker could also aim to raise as much as $100 billion in its offering and is targeting a valuation of about $2 trillion. Both marks would surpass what **** eX achieved — the rocket company pulled in $86 billion and debuted at a $1.77 trillion valuation when it went public in June.
None of the figures are final, and the Journal notes that details of Anthropic's plans are still being worked out. Anthropic is expected to publish its IPO prospectus documents shortly, a timeline that would leave the door open for a market debut as early as September or early October.
#anthropic #revenue #billion #SpaceX

1 month ago
In my day job, I am an English professor. This is relevant because in my hobby of writing about football, I frequently encounter people who forget that words mean things. ESPN just released a ranking of NFL positional groups that includes this statement: "you would be surprised by what you can learn sitting down and objectively grading and/or ranking each positional unit of all 32 teams."
This is probably true. The author of the article should try it some time. "Objectively," per Merriam-Webster, involves "evaluation with a basis in observable facts rather than feelings or opinions." He then proceeds to just rattle off a bunch of rank lists without actually providing any criteria for how the lists were composed. To be clear–this is an author writing to the standard of "trust me bro" and vibes, and it says a lot about the state of ESPN and sports journalism in general.
Because a detailed ***** ysis of everything wrong with the article would take framing and ***** ysis that exceeds what the low quality of its argumentation deserves, I am simply going to focus on three Bears-centric rankings that make me wonder whether or not the author was even bothering.
ESPN ranks Chicago's running back room as 24th in the NFL. In 2025, Chicago had the 4th-best rushing attack in the league by EPA/run, and it was one of only ten teams in the league that had positive value in EPA per run. Not only was Chicago third in total rushing yards, it was one of only three teams in the league with two running backs (Swift and Monangai) with at least 25 attempts in the top twenty in terms of success rate and EPA per rush. Those two were 12th and 21st in terms of yards per carry in terms for backs with at least 50 rush attempts, and 3rd and 19th in terms of total EPA.
Either would be the basis of a rushing attack above 24th in the league, and Chicago has both of them. By any objective standard, Chicago has a 1-2 punch at running back that is near the top of the league. If the concern is that Chicago's third running back is going to bring down the rest of the group, we would need to believe that 23 teams in the NFL have third-string running backs sufficient to make up the difference over this pairing.
#author
This is probably true. The author of the article should try it some time. "Objectively," per Merriam-Webster, involves "evaluation with a basis in observable facts rather than feelings or opinions." He then proceeds to just rattle off a bunch of rank lists without actually providing any criteria for how the lists were composed. To be clear–this is an author writing to the standard of "trust me bro" and vibes, and it says a lot about the state of ESPN and sports journalism in general.
Because a detailed ***** ysis of everything wrong with the article would take framing and ***** ysis that exceeds what the low quality of its argumentation deserves, I am simply going to focus on three Bears-centric rankings that make me wonder whether or not the author was even bothering.
ESPN ranks Chicago's running back room as 24th in the NFL. In 2025, Chicago had the 4th-best rushing attack in the league by EPA/run, and it was one of only ten teams in the league that had positive value in EPA per run. Not only was Chicago third in total rushing yards, it was one of only three teams in the league with two running backs (Swift and Monangai) with at least 25 attempts in the top twenty in terms of success rate and EPA per rush. Those two were 12th and 21st in terms of yards per carry in terms for backs with at least 50 rush attempts, and 3rd and 19th in terms of total EPA.
Either would be the basis of a rushing attack above 24th in the league, and Chicago has both of them. By any objective standard, Chicago has a 1-2 punch at running back that is near the top of the league. If the concern is that Chicago's third running back is going to bring down the rest of the group, we would need to believe that 23 teams in the NFL have third-string running backs sufficient to make up the difference over this pairing.
#author


1 month ago
Micron (MU) beat Q3 consensus by 18%, expanded gross margin to 85%, and guided Q4 revenue to a record $50B.
Sandisk (SNDK) and Western Digital (WDC) trade at forward P/Es of 26 and 18, versus Micron's strikingly cheap 6, signaling deep value or cycle risk.
Sixteen Strategic Customer Agreements lock in roughly $100B of minimum-priced revenue, giving Micron floor pricing CEO Mehrotra says exceeds any past cycle margin.
Act now: the ******* yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Micron Technology didn't make the cut. Grab the names FREE today.
Micron Technology (NASDAQ:MU) closed the most recent session at $1,011.75, capping a 254.71% year-to-date run driven by an AI memory cycle that CEO Sanjay Mehrotra called a structural transformation of the industry.
#cycle #Margin
Sandisk (SNDK) and Western Digital (WDC) trade at forward P/Es of 26 and 18, versus Micron's strikingly cheap 6, signaling deep value or cycle risk.
Sixteen Strategic Customer Agreements lock in roughly $100B of minimum-priced revenue, giving Micron floor pricing CEO Mehrotra says exceeds any past cycle margin.
Act now: the ******* yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Micron Technology didn't make the cut. Grab the names FREE today.
Micron Technology (NASDAQ:MU) closed the most recent session at $1,011.75, capping a 254.71% year-to-date run driven by an AI memory cycle that CEO Sanjay Mehrotra called a structural transformation of the industry.
#cycle #Margin

1 month ago
You can find original article here WealthManagement. Subscribe to our free daily WealthManagement newsletters.
Schwab on the Hunt for Long-Short Strategies Director "Charles Schwab has recently been on the search for a director to lead the firm's long-short separately managed account initiative, someone responsible for building a team focused specifically on long-short SMAs and creating companywide coordination for the business, according to a job posting. Schwab did not respond to questions, including if the position has been filled." (The Daily Upside)
Morgan Stanley Bolsters UMA Offerings as Advisory ***** ets Soar "Morgan Stanley has expanded the fund options on its Select UMA Program to provide a wider set of investment choices as its investment advisory platform exceeds $3 trillion in ***** ets under management... Amid that momentum, the firm has added tender offer funds and interval funds to the closed-end mutual funds offered in the Select UMA Program, according to a Form ADV disclosure." (FundFire)
U.S. ETF Investors at Odds: Chasing Returns or Playing the Long Game? "All investors seek positive returns, but their time horizons and strategies are dramatically different. The longest-term investors rely on research that points to the odds-on play of buying and holding broad-based, cap-weighted stock and bond ETFs. Other investors extrapolate recent performance with hopes to continue riding a wave." (ETF.com)
Wealth Management Has a $3 Trillion Problem: Investors Are Keeping Too Much Cash "The risk, they argue, is that the yield on cash won't keep pace with inflation. Money-market yields are currently right about at the rate of inflation. Many advisers are pitching alternatives, including corporate bonds, municipal bonds and more exotic offerings such as buffer exchange-traded funds and private credit." (WSJ)
#schwab #short #select
Schwab on the Hunt for Long-Short Strategies Director "Charles Schwab has recently been on the search for a director to lead the firm's long-short separately managed account initiative, someone responsible for building a team focused specifically on long-short SMAs and creating companywide coordination for the business, according to a job posting. Schwab did not respond to questions, including if the position has been filled." (The Daily Upside)
Morgan Stanley Bolsters UMA Offerings as Advisory ***** ets Soar "Morgan Stanley has expanded the fund options on its Select UMA Program to provide a wider set of investment choices as its investment advisory platform exceeds $3 trillion in ***** ets under management... Amid that momentum, the firm has added tender offer funds and interval funds to the closed-end mutual funds offered in the Select UMA Program, according to a Form ADV disclosure." (FundFire)
U.S. ETF Investors at Odds: Chasing Returns or Playing the Long Game? "All investors seek positive returns, but their time horizons and strategies are dramatically different. The longest-term investors rely on research that points to the odds-on play of buying and holding broad-based, cap-weighted stock and bond ETFs. Other investors extrapolate recent performance with hopes to continue riding a wave." (ETF.com)
Wealth Management Has a $3 Trillion Problem: Investors Are Keeping Too Much Cash "The risk, they argue, is that the yield on cash won't keep pace with inflation. Money-market yields are currently right about at the rate of inflation. Many advisers are pitching alternatives, including corporate bonds, municipal bonds and more exotic offerings such as buffer exchange-traded funds and private credit." (WSJ)
#schwab #short #select


