

20 hours ago
Over the last few years, the stock market has become concentrated among a relatively small cohort of technology companies. These companies have an unusually strong influence over the direction of the S&P 500 (SNPINDEX: ^GSPC), making investor sentiment toward artificial intelligence (AI) particularly important to the broader market's performance.
As of Nov. 3, a little more than one-third of the S&P 500 is composed of the "Magnificent Seven" stocks -- Nvidia, Apple, Alphabet, Microsoft, Amazon, Meta Platforms, and Tesla. This concentration is important heading into Friday, Nov. 6, when two potentially market-moving events are scheduled.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The October jobs report is scheduled to publish before the opening bell, while billionaire entrepreneur Elon Musk will take the stage at a major investment conference later that afternoon. Here's why I'm predicting Nov. 6 could become a consequential trading day on Wall Street.
The Bureau of Labor Statistics (BLS) will release the October employment report at 8:30 a.m. ET on Nov. 6. This report provides investors with several important economic indicators, including nonfarm payroll growth, the unemployment rate, and changes in average hourly earnings. These figures can offer clues about the health of the American economy and the Federal Reserve's next moves on interest rates.
#NVIDIA #signal #october #market
As of Nov. 3, a little more than one-third of the S&P 500 is composed of the "Magnificent Seven" stocks -- Nvidia, Apple, Alphabet, Microsoft, Amazon, Meta Platforms, and Tesla. This concentration is important heading into Friday, Nov. 6, when two potentially market-moving events are scheduled.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The October jobs report is scheduled to publish before the opening bell, while billionaire entrepreneur Elon Musk will take the stage at a major investment conference later that afternoon. Here's why I'm predicting Nov. 6 could become a consequential trading day on Wall Street.
The Bureau of Labor Statistics (BLS) will release the October employment report at 8:30 a.m. ET on Nov. 6. This report provides investors with several important economic indicators, including nonfarm payroll growth, the unemployment rate, and changes in average hourly earnings. These figures can offer clues about the health of the American economy and the Federal Reserve's next moves on interest rates.
#NVIDIA #signal #october #market

10 days ago
Colom would be Mississippi’s first Black U.S. senator since Reconstruction.
Why are major Democrats and Republicans flocking to Mississippi in recent weeks?
In a climate where polls show President Donald Trump's approval ratings cratering, Democrats are unusually optimistic about Scott Colom's chances of flipping the Senate seat held by incumbent Republican Cindy Hyde-Smith -- even in deep-red Mississippi.
"We got to have a senator that looks out for Mississippi, that puts Mississippi farmers first, Mississippi small businesses first, represent our values by not allowing corruption to ruin our country and actually delivers on the commitments to put America first," Colom told ABC News in an interview earlier this week.
The incumbent's campaign dismisses the Democratic push as the last-ditch effort of a campaign that will fall short.
#first #black #reconstruction
Why are major Democrats and Republicans flocking to Mississippi in recent weeks?
In a climate where polls show President Donald Trump's approval ratings cratering, Democrats are unusually optimistic about Scott Colom's chances of flipping the Senate seat held by incumbent Republican Cindy Hyde-Smith -- even in deep-red Mississippi.
"We got to have a senator that looks out for Mississippi, that puts Mississippi farmers first, Mississippi small businesses first, represent our values by not allowing corruption to ruin our country and actually delivers on the commitments to put America first," Colom told ABC News in an interview earlier this week.
The incumbent's campaign dismisses the Democratic push as the last-ditch effort of a campaign that will fall short.
#first #black #reconstruction

29 days ago
The 2020s will go down in history as one of the best times to be a stock market investor. After a brief dip in 2022, the benchmark S&P 500 (SNPINDEX: ^GSPC) has soared by an average of roughly 21% per year -- double its 100-year average annual return of 10%.
That said, history shows us that significant drawdowns often follow periods of unusually elevated stock market gains as the market reverts to its long-running mean. Let's discuss some of the challenges facing this bull market to try to figure out what might come next.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
By now, most investors have probably heard about the cyclically adjusted price-to-earnings (CAPE) ratio. This metric compares the price of the S&P 500 with its average inflation-adjusted earnings over the past decade. The long time frame smooths out short-term fluctuations, providing a clearer picture of the market's value relative to historical norms.
Right now, the CAPE ratio stands at 40.5, which is well above its average of 17.4. The other two major peaks occurred before the Great Depression in 1929 and during the dot-com bubble in 1999, when it hit its all-time high of 44.19. Both milestones were followed by substantial declines in equity prices over the subsequent years as the speculative bubbles deflated.
#missed #Stock #long #investors
That said, history shows us that significant drawdowns often follow periods of unusually elevated stock market gains as the market reverts to its long-running mean. Let's discuss some of the challenges facing this bull market to try to figure out what might come next.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
By now, most investors have probably heard about the cyclically adjusted price-to-earnings (CAPE) ratio. This metric compares the price of the S&P 500 with its average inflation-adjusted earnings over the past decade. The long time frame smooths out short-term fluctuations, providing a clearer picture of the market's value relative to historical norms.
Right now, the CAPE ratio stands at 40.5, which is well above its average of 17.4. The other two major peaks occurred before the Great Depression in 1929 and during the dot-com bubble in 1999, when it hit its all-time high of 44.19. Both milestones were followed by substantial declines in equity prices over the subsequent years as the speculative bubbles deflated.
#missed #Stock #long #investors

29 days ago
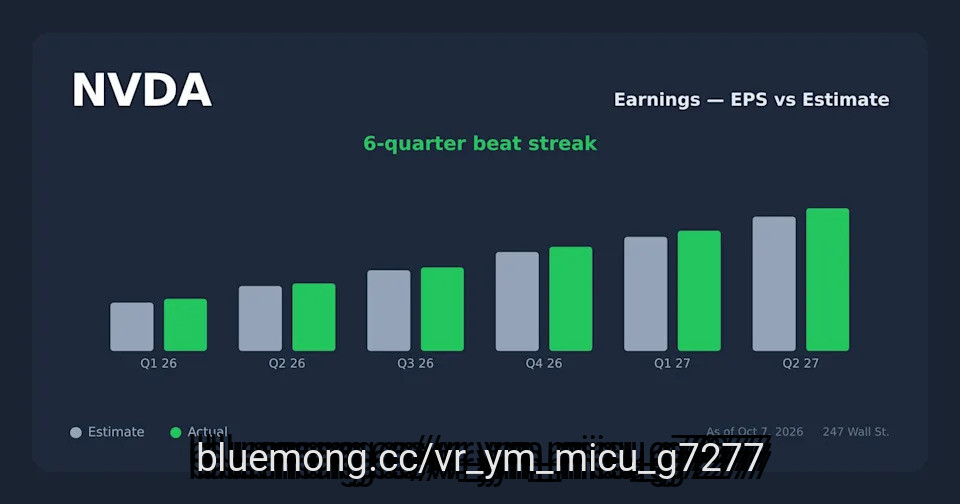
NVDA and AAPL join MSFT to control 21% of the S&P 500, nearly double the prior three-stock record of 13% set in the 1980s.
SPY investors who also hold NVDA, AAPL, or MSFT directly are doubling up; TOPC caps each position at 3% as a concentration alternative.
Only 25% of S&P 500 stocks trade above their 50-day moving average, meaning the index's record high rests on historically thin participation.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
At the close on October 6, 2026, the S&P 500 finished at a record 7,818.93, up 0.58%. Three companies now account for an unusually large share of that level.
#nvda
SPY investors who also hold NVDA, AAPL, or MSFT directly are doubling up; TOPC caps each position at 3% as a concentration alternative.
Only 25% of S&P 500 stocks trade above their 50-day moving average, meaning the index's record high rests on historically thin participation.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
At the close on October 6, 2026, the S&P 500 finished at a record 7,818.93, up 0.58%. Three companies now account for an unusually large share of that level.
#nvda


1 month ago
Ari Kytsya has never pretended that making adult content is all big checks, flexible hours, and glamorous trips. Long before the allegations surrounding the so-called "Cornell 7" case reignited a national conversation about consent, exploitation, and women's safety, the TikTok personality warned that adult creators can face harassment, privacy violations, predatory contracts, and frightening encounters with people who refuse to let their online relationships remain online.
Kytsya has not publicly connected her experiences to the Cornell case. However, her warnings offer another look into the risks women say they face when money, **** , and entitlement collide.
ZUMAPRESS.com / MEGA
Kytsya, who has built an audience of millions across TikTok and other social media platforms, has been unusually open about the realities of working in the adult-content industry. In a video highlighted by Yahoo Entertainment, the OF creator pushed back against the idea that selling explicit content offers an easy path to wealth. "This job is not easy money," she declared, arguing that she works just as hard, or harder, than she did in her previous jobs.
Kytsya also claimed that some creators lie about how much they earn. According to her, those making significant amounts of money generally entered the industry with an established audience rather than building a profitable account from nothing. Even successful creators cannot depend on a consistent paycheck, she explained. One month's income can be extremely high, then fall dramatically the next.
#money #TikTok #case #face
Kytsya has not publicly connected her experiences to the Cornell case. However, her warnings offer another look into the risks women say they face when money, **** , and entitlement collide.
ZUMAPRESS.com / MEGA
Kytsya, who has built an audience of millions across TikTok and other social media platforms, has been unusually open about the realities of working in the adult-content industry. In a video highlighted by Yahoo Entertainment, the OF creator pushed back against the idea that selling explicit content offers an easy path to wealth. "This job is not easy money," she declared, arguing that she works just as hard, or harder, than she did in her previous jobs.
Kytsya also claimed that some creators lie about how much they earn. According to her, those making significant amounts of money generally entered the industry with an established audience rather than building a profitable account from nothing. Even successful creators cannot depend on a consistent paycheck, she explained. One month's income can be extremely high, then fall dramatically the next.
#money #TikTok #case #face

1 month ago
While we have been experiencing unusually mild temperatures this October, it did rain during Paris Fashion Week.
Dragos Sora
Mid-last week saw Rosalía springing forward in a fresh-off-the-runway Dior Spring 2027 look. Now she's falling back in Vaquera.
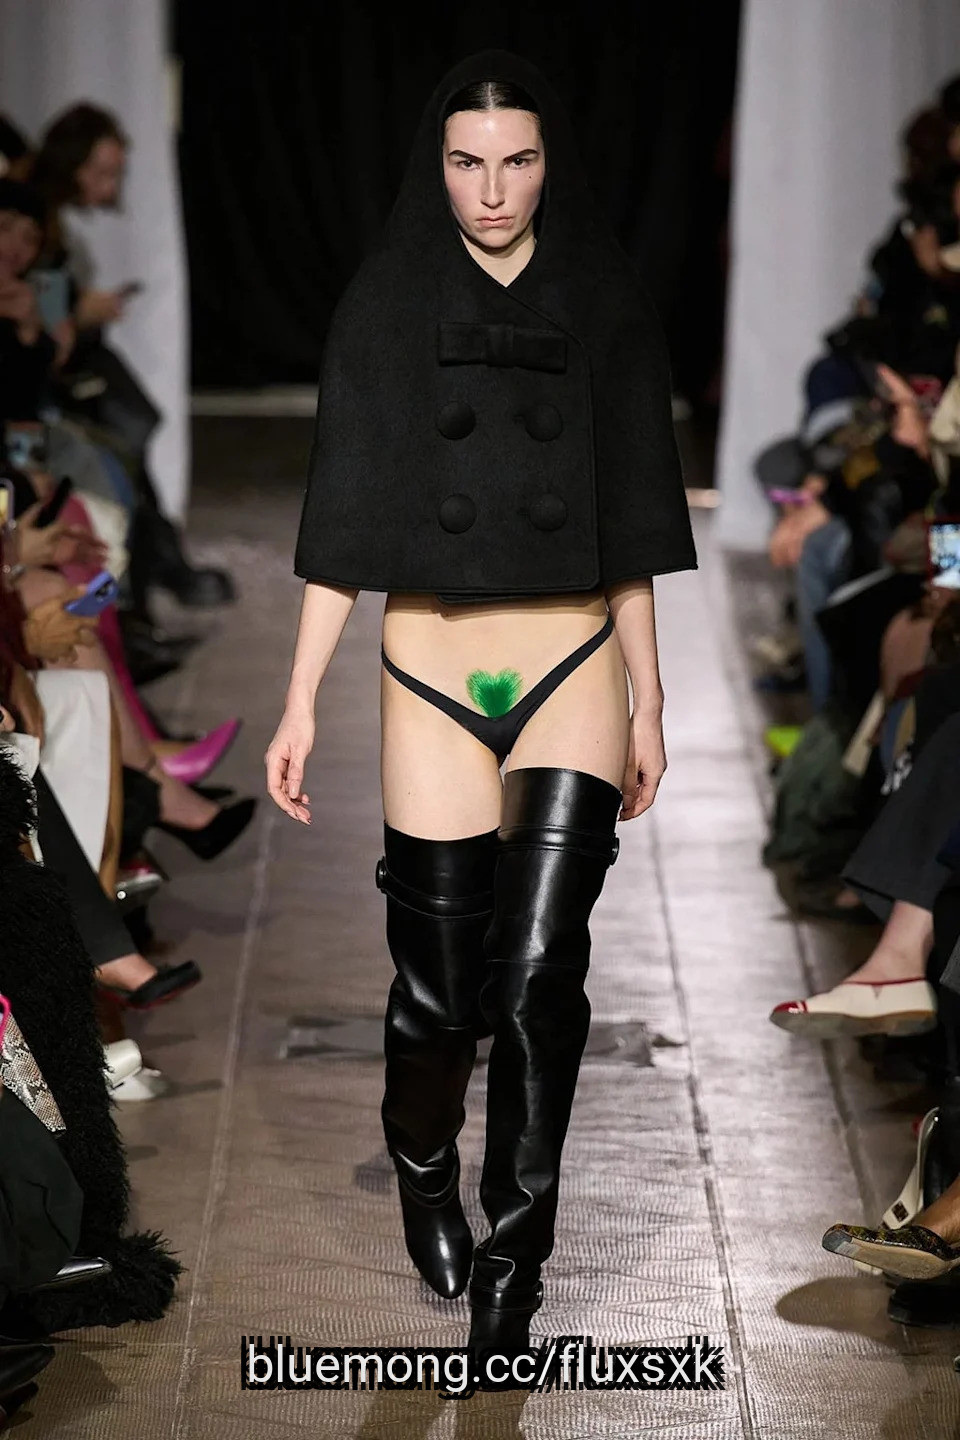
Instead of having a bodyguard follow her around with an umbrella, à la Jennifer Lopez at the Stella McCartney show, Rosalía came prepared for the Paris rain in a hooded cape from the Vaquera Fall 2026 collection, featuring double-breasted ***** ons and a bow fastening.
Dragos Sora
#Paris #vaquera
Dragos Sora
Mid-last week saw Rosalía springing forward in a fresh-off-the-runway Dior Spring 2027 look. Now she's falling back in Vaquera.
Instead of having a bodyguard follow her around with an umbrella, à la Jennifer Lopez at the Stella McCartney show, Rosalía came prepared for the Paris rain in a hooded cape from the Vaquera Fall 2026 collection, featuring double-breasted ***** ons and a bow fastening.
Dragos Sora
#Paris #vaquera


1 month ago
Tate McRae traded stagewear for a softer kind of drama at Schiaparelli, arriving at the fashion house's Spring/Summer 2027 show in Paris in a sweeping champagne-toned satin look.
The 23-year-old singer attended the October 1 presentation in a deeply plunging blazer paired with a matching floor-length slip skirt. Her hair was worn long and loose, while the styling remained relatively spare, allowing the reflective fabric and dramatic neckline to carry most of the look.
CNN Style identified the outfit as a champagne blazer and coordinating slip skirt, clearing up a detail that was easy to miss from photographs because the uninterrupted satin silhouette could initially read as a gown. McRae joined other music figures at the Schiaparelli presentation, including Peggy Gou and JT.
The front-row appearance came during an unusually significant day for McRae away from the concert stage. October 1 also marked the official launch of TATE 01, her debut fragrance and first major move into the beauty business, putting a new entrepreneurial project alongside one of her most prominent Paris Fashion Week appearances.
From a distance, the fluid line of McRae's outfit made the satin ensemble resemble a single dress. CNN Style's Paris Fashion Week coverage, however, described it as a plunging champagne blazer worn with a matching slip skirt.
#champagne #slip #skirt #tate
The 23-year-old singer attended the October 1 presentation in a deeply plunging blazer paired with a matching floor-length slip skirt. Her hair was worn long and loose, while the styling remained relatively spare, allowing the reflective fabric and dramatic neckline to carry most of the look.
CNN Style identified the outfit as a champagne blazer and coordinating slip skirt, clearing up a detail that was easy to miss from photographs because the uninterrupted satin silhouette could initially read as a gown. McRae joined other music figures at the Schiaparelli presentation, including Peggy Gou and JT.
The front-row appearance came during an unusually significant day for McRae away from the concert stage. October 1 also marked the official launch of TATE 01, her debut fragrance and first major move into the beauty business, putting a new entrepreneurial project alongside one of her most prominent Paris Fashion Week appearances.
From a distance, the fluid line of McRae's outfit made the satin ensemble resemble a single dress. CNN Style's Paris Fashion Week coverage, however, described it as a plunging champagne blazer worn with a matching slip skirt.
#champagne #slip #skirt #tate


1 month ago
An Australian woman went viral after sharing a video of an unusually pristine frozen food section at her local supermarket. The clip showcased rows of products stacked with near-perfect uniformity, with the meticulous organization extending across multiple freezers and different types of frozen goods.
Sarah Mae Ahern, or sarahmaeahern on Instagram, is an Australian musician and content creator whose posts primarily focus on her music career, along with occasional glimpses into life with her husband Alex and their child.
Ahern's breakout viral video, however, came from an unexpected trip to the supermarket. While grocery shopping with her husband, the pair encountered a frozen food section where seemingly every item had been arranged perfectly in place.
They filmed the display and shared it online, where the video amassed nearly 11 million views, more than 610,000 likes and roughly 7,500 comments over the following three months.
"We are looking at how perfectly stacked everything is in this freezer section," Alex says, while Ahern films him as she laughs, before she pans over to said freezers, which display frozen desserts, pastries and ice cream, every product in it neatly organized.
#freezers
Sarah Mae Ahern, or sarahmaeahern on Instagram, is an Australian musician and content creator whose posts primarily focus on her music career, along with occasional glimpses into life with her husband Alex and their child.
Ahern's breakout viral video, however, came from an unexpected trip to the supermarket. While grocery shopping with her husband, the pair encountered a frozen food section where seemingly every item had been arranged perfectly in place.
They filmed the display and shared it online, where the video amassed nearly 11 million views, more than 610,000 likes and roughly 7,500 comments over the following three months.
"We are looking at how perfectly stacked everything is in this freezer section," Alex says, while Ahern films him as she laughs, before she pans over to said freezers, which display frozen desserts, pastries and ice cream, every product in it neatly organized.
#freezers


2 months ago
Phillips 66 (NYSE:PSX) has been on a strong rally this year, posting gains of over 110% since the beginning of 2026. The outperformance has been driven by an unusually sharp surge in global refining margins amid the war in the Middle East, which has significantly tightened the world's refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
Given Phillips 66's substantial outperformance compared to the wider market, investors may be questioning whether the stock's record-setting run has reached its peak. However, the ****** ysts over at BMO Capital see further upside ahead. On September 17, the firm raised its price target on PSX from $260 to $310, while maintaining an 'Outperform' rating on the shares. The target boost implies an upside of 13% from the current levels and even exceeds the stock's all-time high of over $274 achieved earlier this month.
BMO Capital highlighted Phillips 66's integrated business model, noting that it has gained momentum and outperformed its individual segments, supported by strong execution across the portfolio. While Refining and Renewables remain the cyclical leaders, BMO also sees a favorable medium-term growth outlook for the company's Midstream business.
BMO Capital's vote of confidence comes amid a broader optimism surrounding Phillips 66, with ****** ysts from Morgan Stanley, Raymon James, UBS, and several others also improving their respective outlooks on PSX. This suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, particularly following the renewed escalations between Iran and the United States.
The supply disruptions now extend beyond the troubled region, as a recent wave of Ukrainian attacks on Russian refineries has further reduced global refining capacity and provided further support to margins.
#further #margins #amid
Given Phillips 66's substantial outperformance compared to the wider market, investors may be questioning whether the stock's record-setting run has reached its peak. However, the ****** ysts over at BMO Capital see further upside ahead. On September 17, the firm raised its price target on PSX from $260 to $310, while maintaining an 'Outperform' rating on the shares. The target boost implies an upside of 13% from the current levels and even exceeds the stock's all-time high of over $274 achieved earlier this month.
BMO Capital highlighted Phillips 66's integrated business model, noting that it has gained momentum and outperformed its individual segments, supported by strong execution across the portfolio. While Refining and Renewables remain the cyclical leaders, BMO also sees a favorable medium-term growth outlook for the company's Midstream business.
BMO Capital's vote of confidence comes amid a broader optimism surrounding Phillips 66, with ****** ysts from Morgan Stanley, Raymon James, UBS, and several others also improving their respective outlooks on PSX. This suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, particularly following the renewed escalations between Iran and the United States.
The supply disruptions now extend beyond the troubled region, as a recent wave of Ukrainian attacks on Russian refineries has further reduced global refining capacity and provided further support to margins.
#further #margins #amid

2 months ago
Marathon Petroleum Corporation (NYSE:MPC) has substantially outperformed the wider market this year, supported by an unusually sharp surge in global refining margins as the prolonged Iran crisis has significantly tightened global refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
With Marathon up by over 150% since the beginning of 2026, there are now concerns that the stock may have topped out. However, the ****** ysts over at Morgan Stanley are convinced that the rally still has further room to run. On September 14, Morgan Stanley ****** yst Joe Laetsch significantly raised the firm's price target on MPC from $265 to $453, while reaffirming an 'Overweight' rating on the shares.
The target boost reflects an upside of over 9% from the current price level and even exceeds the stock's record high of just under $411 per share achieved earlier this month. The Morgan Stanley update comes amid broader Wall Street optimism surrounding the American refining giant, with ****** ysts from Raymon James, UBS, and several others also improving their respective outlooks on MPC.
Morgan Stanley's vote of confidence suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, especially given the fresh wave of attacks between Washington and Tehran. Even if the conflict in the Middle East subsides, the region's refined fuel output is expected to remain relatively tight, since the damaged or idled refineries in the Middle East are likely to take some time to return to full operations.
As the largest refiner by volume in the United States, Marathon has significant operating leverage to capitalize on the current high-margin environment. The company already demonstrated its ability to translate the high crack spreads into material earnings when it delivered an almost fourfold increase in profits in the second quarter.
#morgan #marathon #stanley #middle
With Marathon up by over 150% since the beginning of 2026, there are now concerns that the stock may have topped out. However, the ****** ysts over at Morgan Stanley are convinced that the rally still has further room to run. On September 14, Morgan Stanley ****** yst Joe Laetsch significantly raised the firm's price target on MPC from $265 to $453, while reaffirming an 'Overweight' rating on the shares.
The target boost reflects an upside of over 9% from the current price level and even exceeds the stock's record high of just under $411 per share achieved earlier this month. The Morgan Stanley update comes amid broader Wall Street optimism surrounding the American refining giant, with ****** ysts from Raymon James, UBS, and several others also improving their respective outlooks on MPC.
Morgan Stanley's vote of confidence suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, especially given the fresh wave of attacks between Washington and Tehran. Even if the conflict in the Middle East subsides, the region's refined fuel output is expected to remain relatively tight, since the damaged or idled refineries in the Middle East are likely to take some time to return to full operations.
As the largest refiner by volume in the United States, Marathon has significant operating leverage to capitalize on the current high-margin environment. The company already demonstrated its ability to translate the high crack spreads into material earnings when it delivered an almost fourfold increase in profits in the second quarter.
#morgan #marathon #stanley #middle

2 months ago
Valero Energy Corporation (NYSE:VLO) has been on a strong rally, posting gains of over 140% since the beginning of 2026. The strong performance is fuelled by an unusually sharp surge in global refining margins as the ongoing disruptions have significantly reduced the world's refining capacity and tightened supplies of gasoline, diesel, and jet fuel.
While there are now investor concerns that the stock may have topped out, Wall Street sees further upside ahead. On September 14, Morgan Stanley ******* yst Joe Laetsch significantly boosted the firm's price target on VLO from $255 to $411, while maintaining an 'Equal Weight' rating on the shares. The revised target implies an upside of almost 4% from the current levels and even exceeds the stock's all-time high of just under $400 per share.
The higher price objective is supported by the possibility that Valero can translate the favorable refining environment into material earnings and cash flows. The company did exactly that in the second quarter, when it posted its highest-ever Q2 profit and topped Wall Street expectations.
It seems like the high-margin environment is here to stay following a fresh wave of attacks between the US and Iran. Even if the attacks stop and a potential peace agreement is achieved, the damaged or idled refineries in the Middle East are likely to take some time to return to full operations, keeping refined-fuel markets relatively tight. Notably, the supply disruptions also extend beyond the troubled region, as a recent series of Ukrainian strikes on Russian refineries has further constrained global refining capacity.
Valero's FCC Unit optimization project at its St. Charles Refinery will allow it to capitalize even further on the high-priced environment. Expected to be completed in the third quarter, the $230 million initiative will help enhance the facility's ability to produce high-value products.
#even #environment #wall #strong
While there are now investor concerns that the stock may have topped out, Wall Street sees further upside ahead. On September 14, Morgan Stanley ******* yst Joe Laetsch significantly boosted the firm's price target on VLO from $255 to $411, while maintaining an 'Equal Weight' rating on the shares. The revised target implies an upside of almost 4% from the current levels and even exceeds the stock's all-time high of just under $400 per share.
The higher price objective is supported by the possibility that Valero can translate the favorable refining environment into material earnings and cash flows. The company did exactly that in the second quarter, when it posted its highest-ever Q2 profit and topped Wall Street expectations.
It seems like the high-margin environment is here to stay following a fresh wave of attacks between the US and Iran. Even if the attacks stop and a potential peace agreement is achieved, the damaged or idled refineries in the Middle East are likely to take some time to return to full operations, keeping refined-fuel markets relatively tight. Notably, the supply disruptions also extend beyond the troubled region, as a recent series of Ukrainian strikes on Russian refineries has further constrained global refining capacity.
Valero's FCC Unit optimization project at its St. Charles Refinery will allow it to capitalize even further on the high-priced environment. Expected to be completed in the third quarter, the $230 million initiative will help enhance the facility's ability to produce high-value products.
#even #environment #wall #strong


2 months ago
TIPS held in taxable brokerage accounts generate phantom income from inflation-adjusted principal, potentially pushing up to 85% of Social Security benefits into taxable income.
30-year TIPS currently yield 2.96% above inflation, but account placement determines how much of that real return retirees actually keep after taxes.
Holding TIPS inside a traditional IRA defers inflation-adjustment taxation until withdrawal, shielding annual principal increases from the Social Security provisional income formula.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A 71-year-old retiree did what the textbooks suggest. He built a ladder of Treasury Inflation-Protected Securities in his brokerage account to keep inflation from quietly eating away at retirement. The timing looks unusually attractive. As of August 28, Treasury's real-yield curve put 10-year TIPS at 2.42% and 30-year TIPS at 2.96%. Those are yields above inflation for an investor buying at current market prices and holding to maturity. That 2.96% is a real yield, meaning it sits on top of the inflation adjustment rather than competing with the inflation rate itself.
#real #taxable
30-year TIPS currently yield 2.96% above inflation, but account placement determines how much of that real return retirees actually keep after taxes.
Holding TIPS inside a traditional IRA defers inflation-adjustment taxation until withdrawal, shielding annual principal increases from the Social Security provisional income formula.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A 71-year-old retiree did what the textbooks suggest. He built a ladder of Treasury Inflation-Protected Securities in his brokerage account to keep inflation from quietly eating away at retirement. The timing looks unusually attractive. As of August 28, Treasury's real-yield curve put 10-year TIPS at 2.42% and 30-year TIPS at 2.96%. Those are yields above inflation for an investor buying at current market prices and holding to maturity. That 2.96% is a real yield, meaning it sits on top of the inflation adjustment rather than competing with the inflation rate itself.
#real #taxable

2 months ago
Interested in Cardinal Health, Inc.? Here are five stocks we like better.
Cardinal Health expects growth to normalize in fiscal 2027 after fiscal 2026 benefited from unusually strong specialty growth, customer onboarding, acquisitions and solid healthcare utilization. Management said all five operating segments delivered double-digit earnings growth in fiscal 2026.
The company is expanding its specialty and at-home healthcare strategy through MSO platforms, bolt-on acquisitions and diabetes-related deals. Strive Medical has closed, while the AdaptHealth diabetes acquisition is expected to close in the second half of fiscal 2027, strengthening Cardinal's continuous glucose monitoring business.
Cardinal is prioritizing automated, small-parcel distribution of higher-value at-home products and plans to add three more automated distribution centers. Management also said cash flow was strong in fiscal 2026, putting the company about 90% of the way toward its previously announced $10 billion objective.
Cardinal Health Earnings: Can Perfection Get Priced In Twice?
#acquisitions
Cardinal Health expects growth to normalize in fiscal 2027 after fiscal 2026 benefited from unusually strong specialty growth, customer onboarding, acquisitions and solid healthcare utilization. Management said all five operating segments delivered double-digit earnings growth in fiscal 2026.
The company is expanding its specialty and at-home healthcare strategy through MSO platforms, bolt-on acquisitions and diabetes-related deals. Strive Medical has closed, while the AdaptHealth diabetes acquisition is expected to close in the second half of fiscal 2027, strengthening Cardinal's continuous glucose monitoring business.
Cardinal is prioritizing automated, small-parcel distribution of higher-value at-home products and plans to add three more automated distribution centers. Management also said cash flow was strong in fiscal 2026, putting the company about 90% of the way toward its previously announced $10 billion objective.
Cardinal Health Earnings: Can Perfection Get Priced In Twice?
#acquisitions
2 months ago
SEIC provides investment processing, management, and operational platforms for private banks, financial advisors, institutional investors, and financial managers. SEIC's second-quarter fiscal 2026 report showed revenue of $641.6 million (a 14.7% year-over-year gain), adjusted per-share earnings of $1.66 (a 38% rise), $207 million in operating income (a 36% jump) – all of which were quarterly records – and the company has nearly $400 million in cash for more growth ahead.
It's no wonder SEIC shares are up 28% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock
Institutional volumes reveal plenty. Over the last year, SEIC has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in SEIC shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of financials names are under accumulation right now. But there's a powerful fundamental story happening with SEI.
#institutional #investors #Stock
It's no wonder SEIC shares are up 28% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock
Institutional volumes reveal plenty. Over the last year, SEIC has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in SEIC shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of financials names are under accumulation right now. But there's a powerful fundamental story happening with SEI.
#institutional #investors #Stock



2 months ago
By Michael S. Derby
Sept 16 (Reuters) - Surging government bond yields are raising credit costs across the U.S. economy and could factor into Federal Reserve monetary policy deliberations, but ***** ysts see the central bank resisting any explicit call from the Trump administration to bail out the market.
The focus on the Fed's possible involvement comes as Treasury Secretary Scott Bessent has taken an unusually activist role in trying to tamp down rising yields he considers to be misaligned with the U.S. economic outlook.
Bessent's campaign, which saw the expansion of a key debt buyback operation last week, is foundering, as the 10-year Treasury note rose above 5% to its highest since 2007. He shrugged the move off as owing to "global issues" on Tuesday as he arrived for a congressional hearing.
Treasury's bond market travails are raising questions whether the Fed might be requested to buy government debt to reduce supply, which could cap or lower yields, in turn easing government and private sector borrowing costs.
#government #treasury #bond #debt
Sept 16 (Reuters) - Surging government bond yields are raising credit costs across the U.S. economy and could factor into Federal Reserve monetary policy deliberations, but ***** ysts see the central bank resisting any explicit call from the Trump administration to bail out the market.
The focus on the Fed's possible involvement comes as Treasury Secretary Scott Bessent has taken an unusually activist role in trying to tamp down rising yields he considers to be misaligned with the U.S. economic outlook.
Bessent's campaign, which saw the expansion of a key debt buyback operation last week, is foundering, as the 10-year Treasury note rose above 5% to its highest since 2007. He shrugged the move off as owing to "global issues" on Tuesday as he arrived for a congressional hearing.
Treasury's bond market travails are raising questions whether the Fed might be requested to buy government debt to reduce supply, which could cap or lower yields, in turn easing government and private sector borrowing costs.
#government #treasury #bond #debt

2 months ago
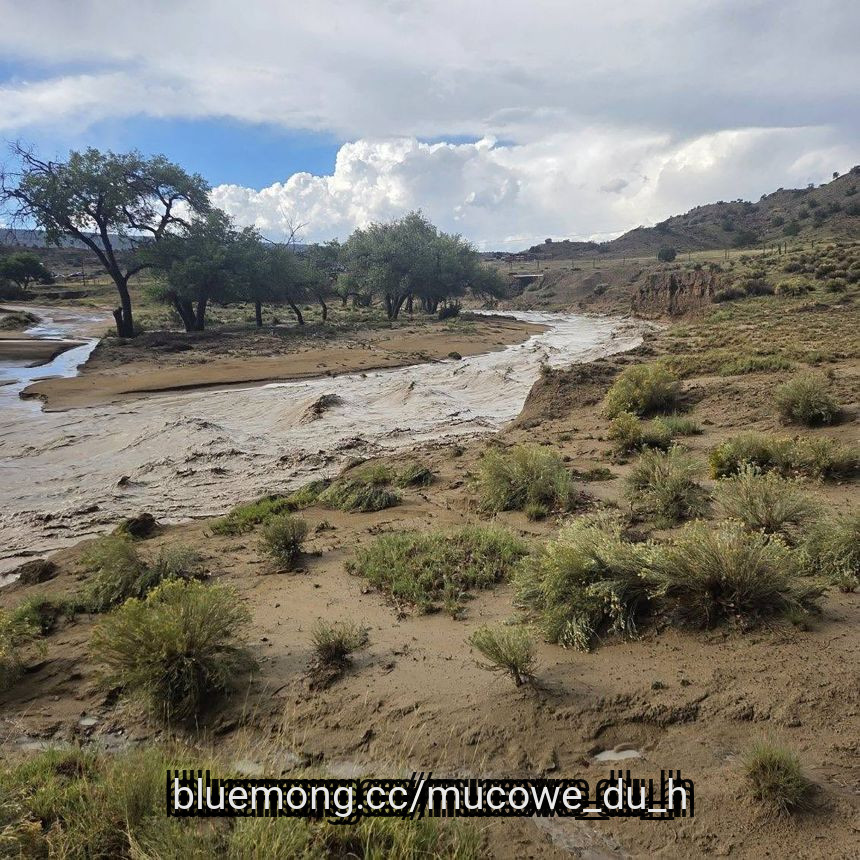
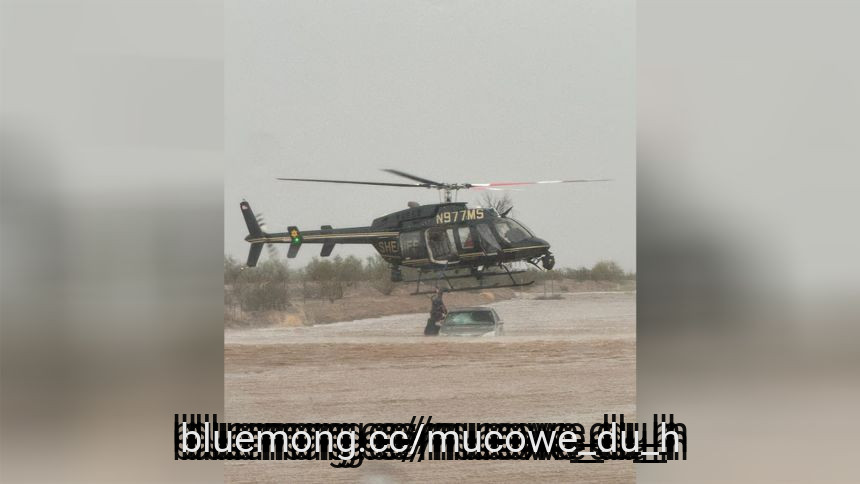
The Southwest faces a barrage of intense rain this week as rounds of storms are tapping into unusually moisture-rich air being pulled north from Baja California, after flash flooding in New Mexico killed three people early Wednesday.
Officers responded at around 12:30 a.m. local time to a report of three people washed away by flooding near Newcomb, New Mexico, on the Navajo Nation. Police discovered two adults and one juvenile on scene, the Navajo Police Department said in a statement. All three were ****** ounced dead. The department declined to provide further details about the deaths when contacted by CNN, citing concern for the family’s privacy.
🌧️ Get your local forecast from the CNN Weather app
Rainfall over Newcomb began Tuesday afternoon around 4:30 p.m. and lingered intermittently until just after midnight. The area saw around 0.5 inches to 1 inch of rain in total, with most of it falling within an hour Tuesday evening.
Wednesday’s storms prompted a rare Level 3 of 4 risk of flooding rainfall for parts of Arizona and New Mexico, including Phoenix and Tucson. Phoenix had not faced a flood risk that high since 2022.
#flooding #around #wednesday #navajo
Officers responded at around 12:30 a.m. local time to a report of three people washed away by flooding near Newcomb, New Mexico, on the Navajo Nation. Police discovered two adults and one juvenile on scene, the Navajo Police Department said in a statement. All three were ****** ounced dead. The department declined to provide further details about the deaths when contacted by CNN, citing concern for the family’s privacy.
🌧️ Get your local forecast from the CNN Weather app
Rainfall over Newcomb began Tuesday afternoon around 4:30 p.m. and lingered intermittently until just after midnight. The area saw around 0.5 inches to 1 inch of rain in total, with most of it falling within an hour Tuesday evening.
Wednesday’s storms prompted a rare Level 3 of 4 risk of flooding rainfall for parts of Arizona and New Mexico, including Phoenix and Tucson. Phoenix had not faced a flood risk that high since 2022.
#flooding #around #wednesday #navajo


2 months ago
Today, Amazon Inc. (AMZN) put options at a $220 strike expiring in 45 days (Oct. 30) have had unusually heavy volume. That strike is 11.5% below today's trading price, and investors collect a 1.45% short-put yield, a bullish play.
AMZN is trading at $248.77 in midday trading on Tuesday, Sept. 15. That's well off its recent peak of $284.02 on Aug. 3, just after its July 30 Q2 earnings release.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart ****** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#week #strike
AMZN is trading at $248.77 in midday trading on Tuesday, Sept. 15. That's well off its recent peak of $284.02 on Aug. 3, just after its July 30 Q2 earnings release.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart ****** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#week #strike



2 months ago
Bank of America Corporation (NYSE:BAC) expects third-quarter investment banking fees to fall by at least 10% year over year, which highlights a broader normalization across capital markets after an unusually strong first half of 2026. BofA expects investment banking fees of roughly $1.6 billion to $1.8 billion in the third quarter, compared with $2 billion a year earlier. CEO Brian Moynihan said the broader investment banking market is also down around 10%, suggesting that the softer quarter reflects a cooling in industry activity rather than a company-specific breakdown.
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#billion #year #rather
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#billion #year #rather


2 months ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700

2 months ago
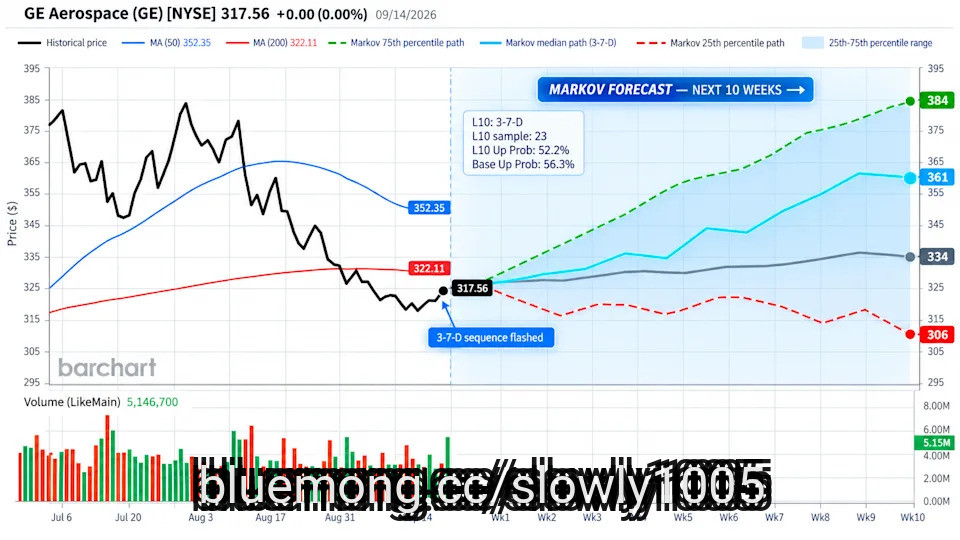
Browsing through the available strike selections for month-of-October bull call spreads, it's impossible to ignore one glaring idea for GE Aerospace (GE). With a maximum payout of 222.58% in exchange for a net debit (cash outlay) of $310, the risk-reward profile seems unusually favorable. Of course, Wall Street isn't in the business of giving traders a free lunch — and that's where the problem with GE stock lies.
While the breakeven price of $333.10 represents "only" a 5% lift from the current spot price, the implied probability of this threshold (derived from the Black-Scholes family of calculations) sits at 29.6%. Again, that's just to break even. If you want to be fully profitable, GE Aerospace stock must trigger the $340 second-leg strike price.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart **** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#price #call #unusually #browsing
While the breakeven price of $333.10 represents "only" a 5% lift from the current spot price, the implied probability of this threshold (derived from the Black-Scholes family of calculations) sits at 29.6%. Again, that's just to break even. If you want to be fully profitable, GE Aerospace stock must trigger the $340 second-leg strike price.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart **** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#price #call #unusually #browsing

2 months ago
Adobe Systems (ADBE) reported strong revenue and free cash flow results for fiscal Q3 on Sept. 10. Free cash flow (FCF) margins were over 40% over the past year. ADBE stock is dirt cheap now at less than 10x earnings and 10x trailing 12-month (TTM) FCF. As a result, shorting ADBE puts and put credit spreads work well for value investors.
ADBE closed at $265.60 on Monday, Sept. 14, up from a recent trough of $248.83 on Sept. 10 before the earnings release. However, the chart below from Barchart shows ADBE has been flat for the past month and a half.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart ****** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#week #cash #flow
ADBE closed at $265.60 on Monday, Sept. 14, up from a recent trough of $248.83 on Sept. 10 before the earnings release. However, the chart below from Barchart shows ADBE has been flat for the past month and a half.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart ****** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#week #cash #flow


2 months ago
Bank of America Corporation (NYSE:BAC) expects third-quarter investment banking fees to fall by at least 10% year over year, which highlights a broader normalization across capital markets after an unusually strong first half of 2026. BofA expects investment banking fees of roughly $1.6 billion to $1.8 billion in the third quarter, compared with $2 billion a year earlier. CEO Brian Moynihan said the broader investment banking market is also down around 10%, suggesting that the softer quarter reflects a cooling in industry activity rather than a company-specific breakdown.
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#investment #banking #year
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#investment #banking #year
2 months ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi

2 months ago
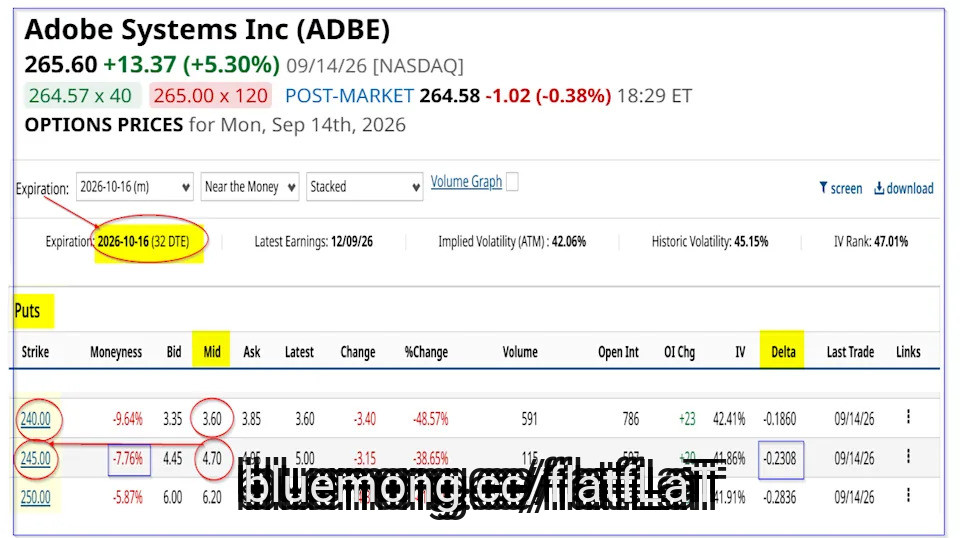
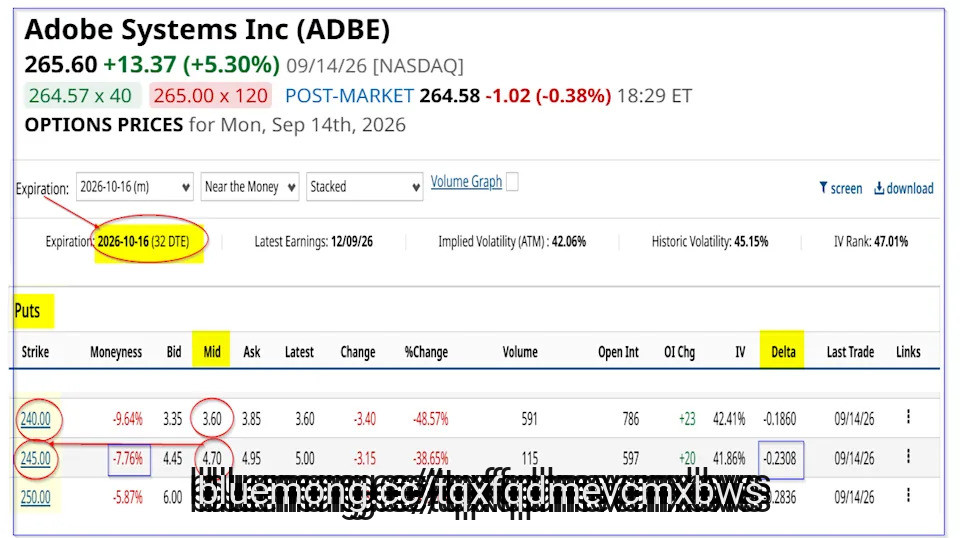
Adobe Systems (ADBE) reported strong revenue and free cash flow results for fiscal Q3 on Sept. 10. Free cash flow (FCF) margins were over 40% over the past year. ADBE stock is dirt cheap now at less than 10x earnings and 10x trailing 12-month (TTM) FCF. As a result, shorting ADBE puts and put credit spreads work well for value investors.
ADBE closed at $265.60 on Monday, Sept. 14, up from a recent trough of $248.83 on Sept. 10 before the earnings release. However, the chart below from Barchart shows ADBE has been flat for the past month and a half.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart ****** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#investors #cash #flow #past
ADBE closed at $265.60 on Monday, Sept. 14, up from a recent trough of $248.83 on Sept. 10 before the earnings release. However, the chart below from Barchart shows ADBE has been flat for the past month and a half.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart ****** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#investors #cash #flow #past


2 months ago
By Michael S. Derby
Sept 16 (Reuters) - Surging government bond yields are raising credit costs across the U.S. economy and could factor into Federal Reserve monetary policy deliberations, but **** ysts see the central bank resisting any explicit call from the Trump administration to bail out the market.
The focus on the Fed's possible involvement comes as Treasury Secretary Scott Bessent has taken an unusually activist role in trying to tamp down rising yields he considers to be misaligned with the U.S. economic outlook.
Bessent's campaign, which saw the expansion of a key debt buyback operation last week, is foundering, as the 10-year Treasury note rose above 5% to its highest since 2007. He shrugged the move off as owing to "global issues" on Tuesday as he arrived for a congressional hearing.
Treasury's bond market travails are raising questions whether the Fed might be requested to buy government debt to reduce supply, which could cap or lower yields, in turn easing government and private sector borrowing costs.
#costs
Sept 16 (Reuters) - Surging government bond yields are raising credit costs across the U.S. economy and could factor into Federal Reserve monetary policy deliberations, but **** ysts see the central bank resisting any explicit call from the Trump administration to bail out the market.
The focus on the Fed's possible involvement comes as Treasury Secretary Scott Bessent has taken an unusually activist role in trying to tamp down rising yields he considers to be misaligned with the U.S. economic outlook.
Bessent's campaign, which saw the expansion of a key debt buyback operation last week, is foundering, as the 10-year Treasury note rose above 5% to its highest since 2007. He shrugged the move off as owing to "global issues" on Tuesday as he arrived for a congressional hearing.
Treasury's bond market travails are raising questions whether the Fed might be requested to buy government debt to reduce supply, which could cap or lower yields, in turn easing government and private sector borrowing costs.
#costs

2 months ago
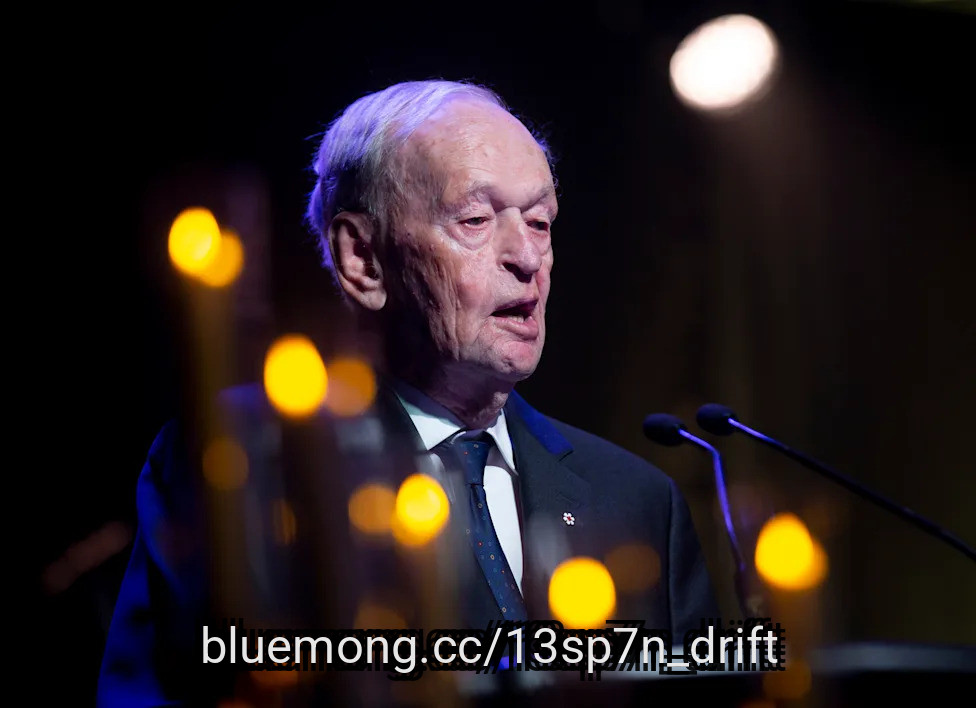
GANDER, Newfoundland (AP) — Standing in the town that sheltered thousands of stranded Americans after the Sept. 11 attacks, former Canadian Prime Minister Jean Chrétien marked the 25th anniversary Friday with a pointed message for the United States: "Never mistake our generosity for weakness."
The 92-year-old former leader, who was prime minister at the time of the attacks, drew a standing ovation after telling his "American friends" that Canadians may be tolerant and kind but "we bow to no one." U.S. Ambassador to Canada Pete Hoekstra rose afterward and hugged him.
"I say that not in anger, but as one friend to another," Chrétien said. "Friends need to be honest with each other."
The unusually blunt remarks came during a solemn ceremony honoring the nearly 3,000 people killed in New York, at the Pentagon and aboard Flight 93, and remembering Gander's extraordinary response to the attacks.
Gander, Newfoundland opened its arms to nearly 6,600 airline passengers diverted there when the U.S. government shut down airspace during 9/11.
#attacks #former #tien #nearly
The 92-year-old former leader, who was prime minister at the time of the attacks, drew a standing ovation after telling his "American friends" that Canadians may be tolerant and kind but "we bow to no one." U.S. Ambassador to Canada Pete Hoekstra rose afterward and hugged him.
"I say that not in anger, but as one friend to another," Chrétien said. "Friends need to be honest with each other."
The unusually blunt remarks came during a solemn ceremony honoring the nearly 3,000 people killed in New York, at the Pentagon and aboard Flight 93, and remembering Gander's extraordinary response to the attacks.
Gander, Newfoundland opened its arms to nearly 6,600 airline passengers diverted there when the U.S. government shut down airspace during 9/11.
#attacks #former #tien #nearly
2 months ago
Focusing on large-cap technology equities that have lagged behind broader market momentum during the September 3 episode of Mad Money, Jim Cramer broke down why Alphabet Inc. (NASDAQ:GOOGL) presents an exceptional opportunity. He said:
Hey, you want a hated stock? How about this Alphabet, up just 9% for the year? There's a big cap stock that's really been left behind. Sure, it's done next to nothing, but when you look at the monster grower that is Google Cloud, you have to wonder, how can you not own the stock? Is it because of Waymo? Now, they're doing terrifically. Maybe you don't like YouTube; wow, biggest entertainment channel on Earth. Search, Gemini, maybe their AI isn't ready? Oh, maybe it will be.
Again, I say everything at a price, and $342 is the price for Alphabet, whether they get it right or not. Amazing that ******* ody cares about… Warren buying a lot of Alphabet. All people care about is that everybody's underwater from that secondary offering they did, 13 points higher from here. I say, so what? I don't care where it went. I care where it's going. It sells for 17 times earnings. It's the price.
Alphabet Inc.'s (NASDAQ:GOOGL) business keeps growing fast as more companies sign up for its cloud infrastructure. In the second quarter, total revenue hit nearly $120 billion. Google Cloud was the main driver behind this growth, as its sales surged 82%, turning it into a major profit source along with core businesses like YouTube. Alphabet leads the global online media market and is steadily expanding Waymo's driverless taxi service. Despite these strengths, the stock trades at roughly 17 times earnings around Cramer's commentary. That multiple is unusually low and understates the valuation of the company's underlying operations.
At the same time, there is a reasonable case for caution due to massive spending. Capital expenditures reached nearly $45 billion in Q2 alone as Alphabet Inc. (NASDAQ:GOOGL) spends aggressively on data centers and AI hardware. If making money from AI takes longer than planned, this heavy investment could hurt short-term cash flow and profit margins. Additionally, recent stock offerings have left some recent buyers holding shares at a loss.
#behind #price
Hey, you want a hated stock? How about this Alphabet, up just 9% for the year? There's a big cap stock that's really been left behind. Sure, it's done next to nothing, but when you look at the monster grower that is Google Cloud, you have to wonder, how can you not own the stock? Is it because of Waymo? Now, they're doing terrifically. Maybe you don't like YouTube; wow, biggest entertainment channel on Earth. Search, Gemini, maybe their AI isn't ready? Oh, maybe it will be.
Again, I say everything at a price, and $342 is the price for Alphabet, whether they get it right or not. Amazing that ******* ody cares about… Warren buying a lot of Alphabet. All people care about is that everybody's underwater from that secondary offering they did, 13 points higher from here. I say, so what? I don't care where it went. I care where it's going. It sells for 17 times earnings. It's the price.
Alphabet Inc.'s (NASDAQ:GOOGL) business keeps growing fast as more companies sign up for its cloud infrastructure. In the second quarter, total revenue hit nearly $120 billion. Google Cloud was the main driver behind this growth, as its sales surged 82%, turning it into a major profit source along with core businesses like YouTube. Alphabet leads the global online media market and is steadily expanding Waymo's driverless taxi service. Despite these strengths, the stock trades at roughly 17 times earnings around Cramer's commentary. That multiple is unusually low and understates the valuation of the company's underlying operations.
At the same time, there is a reasonable case for caution due to massive spending. Capital expenditures reached nearly $45 billion in Q2 alone as Alphabet Inc. (NASDAQ:GOOGL) spends aggressively on data centers and AI hardware. If making money from AI takes longer than planned, this heavy investment could hurt short-term cash flow and profit margins. Additionally, recent stock offerings have left some recent buyers holding shares at a loss.
#behind #price


2 months ago
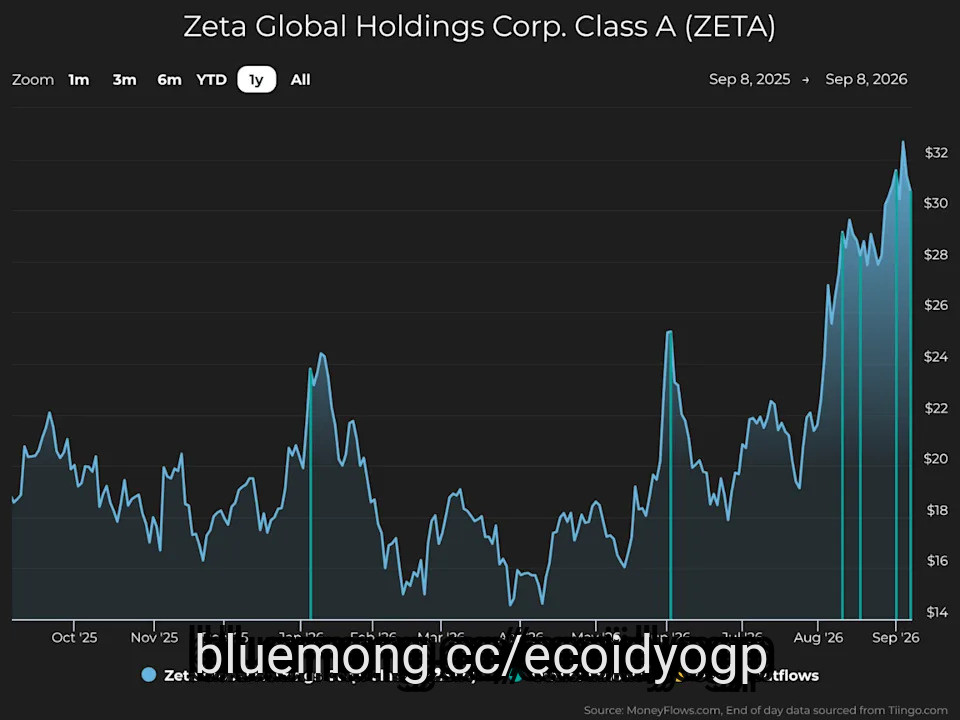
ZETA combines data, AI, automation, and execution into a single platform to turn data into strategic decisions with measurable outcomes – and its initial marketing focus is broadening. The company's second-quarter 2026 report showed $443 million in revenue (a 44% year-over-year gain), adjusted EBITDA of $92 million (a 56% jump), net income of $8.2 million or $0.03 per share (after a loss of nearly $13 million the prior quarter), and offered full-year EPS guidance of $0.11.
It's no wonder ZETA shares are up 51% this year – and they could rise more. MoneyFlows data shows how Big Money investors are once again betting heavily on the forward picture of the stock.
Institutional volumes reveal plenty. In the last year, ZETA has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in ZETA shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of technology names are under accumulation right now. But there's a powerful fundamental story happening with Zeta Global.
#million #data #institutional #quarter
It's no wonder ZETA shares are up 51% this year – and they could rise more. MoneyFlows data shows how Big Money investors are once again betting heavily on the forward picture of the stock.
Institutional volumes reveal plenty. In the last year, ZETA has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in ZETA shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of technology names are under accumulation right now. But there's a powerful fundamental story happening with Zeta Global.
#million #data #institutional #quarter

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
OKTA offers an enterprise identity management platform, including single sign-on, multi-factor authentication, access gateway, API access management, authentication, adaptive MFA, lifecycle management, and AI agent security. OKTA's second-quarter 2027 report showed $805 million in revenue (an 11% year-over-year gain), per-share earnings of $1.05 (a 15.4% sequential gain), and offered full-year revenue and operating margin guidance of up to $3.226 billion and 26%, respectively.
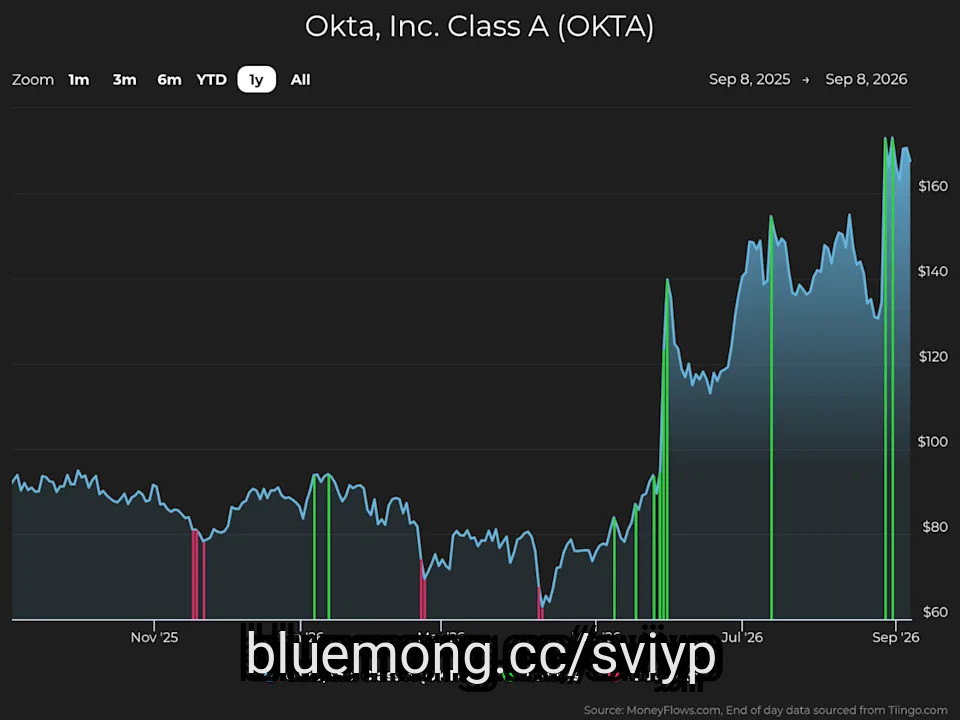
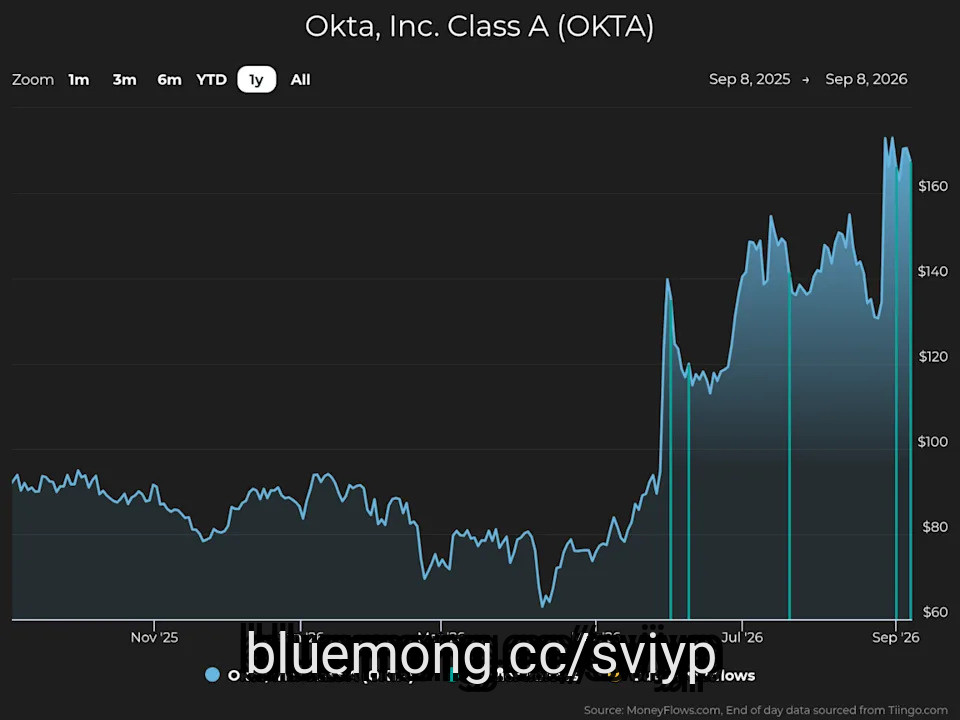
No wonder OKTA shares are up 94% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock.
Institutional volumes reveal plenty. In the last year, OKTA has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in OKTA shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of technology names are under accumulation right now. But there's a powerful fundamental story happening with Okta.
#year #plenty #authentication
No wonder OKTA shares are up 94% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock.
Institutional volumes reveal plenty. In the last year, OKTA has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in OKTA shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of technology names are under accumulation right now. But there's a powerful fundamental story happening with Okta.
#year #plenty #authentication
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
The move represents a sharp reversal from the yen's weakness earlier in the summer, when the USD/JPY approached 165 and forced **** anese authorities to intervene in the foreign-exchange market.
The latest appreciation is increasingly being driven by expectations that the Bank of **** an (BoJ) is preparing to raise interest rates at its September meeting, while investors are also reassessing the outlook for US monetary policy. The BoJ is scheduled to meet next Thursday and Friday, with markets now pricing in a high probability of a 25-basis-point increase. More importantly, investors will be looking for guidance on whether the central bank could accelerate the pace of subsequent tightening.
U.S. consumer-price data due on Friday will provide an important signal ahead of the Federal Reserve's September 15-16 meeting. The inflation figures have become particularly significant because the Fed's policy outlook remains unusually divided. Governor Christopher Waller has indicated that he could support keeping rates unchanged if inflation continues to moderate, while Fed Chair Kevin Warsh has stressed that insufficient progress on inflation could warrant tighter policy.
From a technical perspective, the weekly chart points to a clear deterioration in the USD/JPY trend. The pair has broken below its ascending trend structure and is trading beneath both the Tenkan-sen and Kijun-sen lines of the Ichimoku Cloud index. This suggests that the medium-term bullish structure has weakened. The weekly RSI has also fallen below the neutral 50 threshold and is moving lower, indicating that bearish momentum is becoming more established.
The fundamental backdrop is becoming increasingly challenging for the USD/JPY bulls because the interest-rate differential that supported the yen carry trade for years is gradually narrowing.
#Friday #rates
The latest appreciation is increasingly being driven by expectations that the Bank of **** an (BoJ) is preparing to raise interest rates at its September meeting, while investors are also reassessing the outlook for US monetary policy. The BoJ is scheduled to meet next Thursday and Friday, with markets now pricing in a high probability of a 25-basis-point increase. More importantly, investors will be looking for guidance on whether the central bank could accelerate the pace of subsequent tightening.
U.S. consumer-price data due on Friday will provide an important signal ahead of the Federal Reserve's September 15-16 meeting. The inflation figures have become particularly significant because the Fed's policy outlook remains unusually divided. Governor Christopher Waller has indicated that he could support keeping rates unchanged if inflation continues to moderate, while Fed Chair Kevin Warsh has stressed that insufficient progress on inflation could warrant tighter policy.
From a technical perspective, the weekly chart points to a clear deterioration in the USD/JPY trend. The pair has broken below its ascending trend structure and is trading beneath both the Tenkan-sen and Kijun-sen lines of the Ichimoku Cloud index. This suggests that the medium-term bullish structure has weakened. The weekly RSI has also fallen below the neutral 50 threshold and is moving lower, indicating that bearish momentum is becoming more established.
The fundamental backdrop is becoming increasingly challenging for the USD/JPY bulls because the interest-rate differential that supported the yen carry trade for years is gradually narrowing.
#Friday #rates

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
