4 days ago
Microsoft's (NASDAQ:MSFT) fiscal 2026, which ended June 30, was arguably the strongest year in the software giant's history. Revenue grew 18% to $331.8 billion. Net income jumped 31% year over year, to $133.7 billion.
Micron Technology (NASDAQ:MU) is approaching that number from a different direction. The memory specialist earned $8.5 billion in its fiscal 2025.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But for the fiscal fourth quarter of 2026, which ended in early September, management guided to earnings of $30.73 per diluted share, plus or minus $1.00, on a generally accepted accounting principles (GAAP) basis. On about 1.15 billion diluted shares, the guidance works out to about $35 billion of profit in one quarter (about four times what the whole prior fiscal year produced).
Here's my prediction: In fiscal 2027, Micron will earn more than Microsoft. That means beating the year Microsoft is now in, not the one it just reported. It's a bold call, and it relies almost entirely on the price of memory.
#Microsoft #quarter
Micron Technology (NASDAQ:MU) is approaching that number from a different direction. The memory specialist earned $8.5 billion in its fiscal 2025.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But for the fiscal fourth quarter of 2026, which ended in early September, management guided to earnings of $30.73 per diluted share, plus or minus $1.00, on a generally accepted accounting principles (GAAP) basis. On about 1.15 billion diluted shares, the guidance works out to about $35 billion of profit in one quarter (about four times what the whole prior fiscal year produced).
Here's my prediction: In fiscal 2027, Micron will earn more than Microsoft. That means beating the year Microsoft is now in, not the one it just reported. It's a bold call, and it relies almost entirely on the price of memory.
#Microsoft #quarter

4 days ago
A Wall Street Journal report on September 16 revealed that ExxonMobil Holdings Corporation (NYSE:XOM) is nearing a preliminary agreement with Venezuela's state-owned PDVSA, potentially marking its return to the country almost two decades after its ***** ets were nationalized. According to Reuters, Exxon has shown interest in the large Petromonagas heavy oil project in the Orinoco Belt, as well as in areas in the neighboring Carabobo block.
While the talks are still in their preliminary phase and could still fall apart or be delayed, they mark a major turnaround from Exxon's previous stance on Venezuela. The company's CEO, Darren Woods, stated in January that the country was "uninvestable" without durable investment protections, legal reforms, and changes to its hydrocarbon laws.
The development comes amid a broader push by the Trump administration to open Venezuela's oil industry to American companies and revive the country's dilapidated oil infrastructure. The South American nation is sitting on the largest proven crude oil reserves in the world, accounting for roughly 17% of the global total.
Venezuela could provide Exxon with access to an enormous resource base at a time when the company is actively seeking low-cost and long-duration ***** ets. The fields under consideration are estimated to contain more than 50 billion barrels of oil buried underground.
Exxon already holds an advantage through its previous experience in the country. Petromonagas, formerly called Cerro Negro, was once the energy firm's flagship project in Venezuela, giving it familiarity with the country's vast heavy and extra-heavy crude resources. Petromonagas also remains one of the few Venezuelan projects with an operational upgrader capable of turning the Orinoco's extra-heavy crude into lighter exportable grades.
#heavy #project
While the talks are still in their preliminary phase and could still fall apart or be delayed, they mark a major turnaround from Exxon's previous stance on Venezuela. The company's CEO, Darren Woods, stated in January that the country was "uninvestable" without durable investment protections, legal reforms, and changes to its hydrocarbon laws.
The development comes amid a broader push by the Trump administration to open Venezuela's oil industry to American companies and revive the country's dilapidated oil infrastructure. The South American nation is sitting on the largest proven crude oil reserves in the world, accounting for roughly 17% of the global total.
Venezuela could provide Exxon with access to an enormous resource base at a time when the company is actively seeking low-cost and long-duration ***** ets. The fields under consideration are estimated to contain more than 50 billion barrels of oil buried underground.
Exxon already holds an advantage through its previous experience in the country. Petromonagas, formerly called Cerro Negro, was once the energy firm's flagship project in Venezuela, giving it familiarity with the country's vast heavy and extra-heavy crude resources. Petromonagas also remains one of the few Venezuelan projects with an operational upgrader capable of turning the Orinoco's extra-heavy crude into lighter exportable grades.
#heavy #project

4 days ago
GE Vernova Inc. (NYSE:GEV) is one of Jim Cramer's favorite stocks. Throughout 2025, the CNBC TV host continued to heap praise on the firm. Cramer's praise came at a time when new-age nuclear power and quantum computing stocks were experiencing strong gains. Throughout this period, he continued to **** ert that GE Vernova Inc. (NYSE:GEV) was the only nuclear firm with a stable delivery timeline and the capacity to deliver. In his morning appearance on the 15th, Cramer discussed the recent dip in shares and worries about a slowdown in the AI buildout:
"One company, GE Vernova, which was hit incredibly hard, which actually builds these, was saying they're seeing an order acceleration. So I really doubt the idea there's going to be a decel. Now that stock got hammered yesterday, it's been a horrendous stock since we started getting this political controversy. But again I point out that you just hear no one say anything about pullback."
For GE Vernova Inc. (NYSE:GEV), as perhaps indicated by the share price movement, the narrative is driven by its backlog and overall exposure to AI's power generation demand. On this front, CEO Scott Strazik, another Cramer favorite, outlined during the firm's second quarter earnings that data center orders of $5 billion for H1 2026 had already doubled over the full year 2025 figures. Additionally, during Q2, the firm's total orders touched $24 billion to mark an 88% growth driven by its Power and Electrification segment. As a whole, GE Vernova Inc. (NYSE:GEV)'s Q2 revenue grew by 22% annually, while its overall backlog and electrification backlogs sat at $176 billion and $446 billion.
At the same time, with GE Vernova Inc. (NYSE:GEV) also relying on gas turbines for its business, the debate is also about whether exposure to AI can remove the inherent cyclicality in the business. Additionally, with data centers accounting for 40% of the Electrification business's orders, any slowdown in capex spending by big tech players could generate tailwinds for GE Vernova Inc. (NYSE:GEV). Similarly, while the data center business is booming and the gas generation business remains tied to prices and interest rates, the firm's wind business is a drag and expected to hurt the bottom line throughout 2026.
In Q2, 106 out of the 1,006 funds tracked by Insider Monkey had held a stake in GE Vernova Inc. (NYSE:GEV), which marked a dip over the 118 out of 1,022 funds in Q1. Whether the dip was due to the order mix and AI sentiment or due to profit taking, your guess is as good as ours. On the valuation front, GE Vernova Inc. (NYSE:GEV) trades at a forward P/E ratio of 35, while short interest as a percentage of float is 3.29%.
#vernova #business #throughout #data
"One company, GE Vernova, which was hit incredibly hard, which actually builds these, was saying they're seeing an order acceleration. So I really doubt the idea there's going to be a decel. Now that stock got hammered yesterday, it's been a horrendous stock since we started getting this political controversy. But again I point out that you just hear no one say anything about pullback."
For GE Vernova Inc. (NYSE:GEV), as perhaps indicated by the share price movement, the narrative is driven by its backlog and overall exposure to AI's power generation demand. On this front, CEO Scott Strazik, another Cramer favorite, outlined during the firm's second quarter earnings that data center orders of $5 billion for H1 2026 had already doubled over the full year 2025 figures. Additionally, during Q2, the firm's total orders touched $24 billion to mark an 88% growth driven by its Power and Electrification segment. As a whole, GE Vernova Inc. (NYSE:GEV)'s Q2 revenue grew by 22% annually, while its overall backlog and electrification backlogs sat at $176 billion and $446 billion.
At the same time, with GE Vernova Inc. (NYSE:GEV) also relying on gas turbines for its business, the debate is also about whether exposure to AI can remove the inherent cyclicality in the business. Additionally, with data centers accounting for 40% of the Electrification business's orders, any slowdown in capex spending by big tech players could generate tailwinds for GE Vernova Inc. (NYSE:GEV). Similarly, while the data center business is booming and the gas generation business remains tied to prices and interest rates, the firm's wind business is a drag and expected to hurt the bottom line throughout 2026.
In Q2, 106 out of the 1,006 funds tracked by Insider Monkey had held a stake in GE Vernova Inc. (NYSE:GEV), which marked a dip over the 118 out of 1,022 funds in Q1. Whether the dip was due to the order mix and AI sentiment or due to profit taking, your guess is as good as ours. On the valuation front, GE Vernova Inc. (NYSE:GEV) trades at a forward P/E ratio of 35, while short interest as a percentage of float is 3.29%.
#vernova #business #throughout #data

5 days ago
Anthropic's initial public offering (IPO), expected no earlier than mid-October, will be a test of just how hungry the financial markets still are for exposure to artificial intelligence (AI). The S&P 500 (SNPINDEX: ^GSPC) is going to react depending on how that test goes. Its backers want a valuation of $2 trillion or more, which would top ******* e Exploration Technologies as the biggest IPO ever if it happens.
Don't expect S&P 500 funds to buy it immediately, though. The road for Anthropic entering the S&P 500 is going to be slow, and it could test some nerves along the way.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
By definition, index funds tracking the S&P 500 must buy whatever the S&P 500 adds to its list of stocks.
Anthropic probably won't get special treatment, given that on June 4, S&P Dow Jones Indices declined to loosen its rules for mega-cap listings. Those rules still require 12 months as a public company, at least 10% of shares being publicly held, and reported positive earnings under generally accepted accounting principles (GAAP).
#snpindex
Don't expect S&P 500 funds to buy it immediately, though. The road for Anthropic entering the S&P 500 is going to be slow, and it could test some nerves along the way.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
By definition, index funds tracking the S&P 500 must buy whatever the S&P 500 adds to its list of stocks.
Anthropic probably won't get special treatment, given that on June 4, S&P Dow Jones Indices declined to loosen its rules for mega-cap listings. Those rules still require 12 months as a public company, at least 10% of shares being publicly held, and reported positive earnings under generally accepted accounting principles (GAAP).
#snpindex


5 days ago
During the September 14 episode of Mad Money, Jim Cramer addressed the broader tech sector pullback and mentioned Broadcom Inc. (NASDAQ:AVGO) as an attractive option for investors looking past short-term volatility. He stated:
Well, it's a tough time to come out to San Francisco, a day when the whole AI complex is getting hammered because Anthropic and OpenAI seem to be, I don't know… pulling in their horns. Actually, I think there's some real bargains in this group. Take Broadcom, the maker of chips, networking equipment, and tech infrastructure and software with a stock that's down more than 10% over the past month. At the beginning of this month, Broadcom reported a strong set of results, issued a spectacular multi-year forecast, but their guidance for the current quarter was, I don't know, viewed by some as in line.
The stock got slammed. I think Broadcom's still on track to put up some incredible growth because they're at the heart of the AI ecosystem because the company's never let us down in all the years my Charitable Trust has owned it. And down here, roughly 150 points below its June high, the stock may be too cheap to ignore.
Recent financial reports from Broadcom Inc. (NASDAQ:AVGO) highlights the scale of expansion driving its core semiconductor and infrastructure divisions. Total revenue for the fiscal third quarter reached $29.6 billion, representing an 85.5% increase compared to the same period in the previous year. Artificial intelligence semiconductor revenue surged 221% to $16.7 billion, accounting for roughly 56% of total revenue. Remaining performance obligations climbed significantly to $179.2 billion, providing substantial visibility into future contracted revenue. Broadcom also serves major hyperscale AI customers including Alphabet and Meta Platforms.
Management raised its full year guidance to $58 billion from $56 billion in artificial intelligence revenue, while projecting $115 billion for fiscal 2027 and $230 billion for fiscal 2028. The figures highlight a deep integration into the enterprise artificial intelligence ecosystem through custom accelerators and high-speed networking solutions.
#down #year #fiscal #NASDAQ
Well, it's a tough time to come out to San Francisco, a day when the whole AI complex is getting hammered because Anthropic and OpenAI seem to be, I don't know… pulling in their horns. Actually, I think there's some real bargains in this group. Take Broadcom, the maker of chips, networking equipment, and tech infrastructure and software with a stock that's down more than 10% over the past month. At the beginning of this month, Broadcom reported a strong set of results, issued a spectacular multi-year forecast, but their guidance for the current quarter was, I don't know, viewed by some as in line.
The stock got slammed. I think Broadcom's still on track to put up some incredible growth because they're at the heart of the AI ecosystem because the company's never let us down in all the years my Charitable Trust has owned it. And down here, roughly 150 points below its June high, the stock may be too cheap to ignore.
Recent financial reports from Broadcom Inc. (NASDAQ:AVGO) highlights the scale of expansion driving its core semiconductor and infrastructure divisions. Total revenue for the fiscal third quarter reached $29.6 billion, representing an 85.5% increase compared to the same period in the previous year. Artificial intelligence semiconductor revenue surged 221% to $16.7 billion, accounting for roughly 56% of total revenue. Remaining performance obligations climbed significantly to $179.2 billion, providing substantial visibility into future contracted revenue. Broadcom also serves major hyperscale AI customers including Alphabet and Meta Platforms.
Management raised its full year guidance to $58 billion from $56 billion in artificial intelligence revenue, while projecting $115 billion for fiscal 2027 and $230 billion for fiscal 2028. The figures highlight a deep integration into the enterprise artificial intelligence ecosystem through custom accelerators and high-speed networking solutions.
#down #year #fiscal #NASDAQ

5 days ago
Hub Group, Inc. (NASDAQ:HUBG) disclosed on September 14 that preliminary, unaudited first-half 2026 revenue was expected to reach $1.7 billion to $1.8 billion, near management's expectations. Yet management anticipated an operating loss before one-time charges. This non-GAAP presentation excludes those charges, but neither the loss nor the exclusions were quantified.
Hub Group, Inc. (NASDAQ:HUBG) identified higher fuel, rail, and drayage costs, excess warehouse capacity, and accounting-review and restatement expenses. The central issue is whether pricing and efficiency improvements can restore profitability on the revenue already moving through the business.
Hub Group, Inc. (NASDAQ:HUBG) began implementing rate increases in the third quarter, after transportation costs had pressured first-half results. Relatively stable intermodal volume trends suggest an existing customer base on which better pricing could improve margins. If increases hold without significant volume losses, revenue could become more profitable without requiring a broad freight recovery.
Hub Group, Inc. (NASDAQ:HUBG) also launched additional efficiency initiatives in the second quarter, including warehouse consolidation and improvements in driver and warehouse-worker productivity. These actions address specific weaknesses: underused ***** e spreads fixed costs across fewer orders, while low productivity raises the cost of each shipment or handling task. Better utilization could reinforce the benefit of higher rates.
Hub Group, Inc. (NASDAQ:HUBG) is also targeting order-to-cash processes, which cover the steps from taking orders through billing and collection. Improvements could reduce administrative friction and accelerate cash collection. That would support liquidity while operational changes take effect, although faster collections alone would not repair an operating loss.
#improvements #better
Hub Group, Inc. (NASDAQ:HUBG) identified higher fuel, rail, and drayage costs, excess warehouse capacity, and accounting-review and restatement expenses. The central issue is whether pricing and efficiency improvements can restore profitability on the revenue already moving through the business.
Hub Group, Inc. (NASDAQ:HUBG) began implementing rate increases in the third quarter, after transportation costs had pressured first-half results. Relatively stable intermodal volume trends suggest an existing customer base on which better pricing could improve margins. If increases hold without significant volume losses, revenue could become more profitable without requiring a broad freight recovery.
Hub Group, Inc. (NASDAQ:HUBG) also launched additional efficiency initiatives in the second quarter, including warehouse consolidation and improvements in driver and warehouse-worker productivity. These actions address specific weaknesses: underused ***** e spreads fixed costs across fewer orders, while low productivity raises the cost of each shipment or handling task. Better utilization could reinforce the benefit of higher rates.
Hub Group, Inc. (NASDAQ:HUBG) is also targeting order-to-cash processes, which cover the steps from taking orders through billing and collection. Improvements could reduce administrative friction and accelerate cash collection. That would support liquidity while operational changes take effect, although faster collections alone would not repair an operating loss.
#improvements #better


5 days ago
Realty Income Corporation (NYSE:O) announced on September 14 a European property venture in which capital accounts advised by KKR & Co. Inc. (NYSE:KKR) intend to invest €528 million for a 49% interest. Closing is expected September 30, subject to customary conditions.
Realty Income Corporation (NYSE:O) would receive approximately €528 million in gross proceeds while retaining 51% ownership and day-to-day ******* et management. The contributed portfolio carries a 5.9% effective initial capitalization rate after recurring management fees. The question is whether redeploying the capital and earning fees can more than offset the rental economics transferred to the partner.
The venture could provide another funding source for acquisitions. Selling a minority interest in existing properties can release capital while preserving operational continuity. It also gives management an alternative when public equity or debt financing offers less attractive terms.
Management fees add a second source of income alongside retained property earnings. Realty Income Corporation (NYSE:O) could use its existing European operating platform to manage the venture, potentially spreading overhead across a broader pool of investor capital. The benefit depends on fee revenue exceeding the incremental costs of providing those services.
The structure includes a further source of potential upside. Realty Income Corporation (NYSE:O) would have an option to redeem the partner's interest after year 10 and through year 17. The redemption price would provide a capped internal rate of return, an annualized return accounting for cash-flow timing, expected at 6.3% to 6.5% and finalized at closing.
#NYSE #corporation #management #source
Realty Income Corporation (NYSE:O) would receive approximately €528 million in gross proceeds while retaining 51% ownership and day-to-day ******* et management. The contributed portfolio carries a 5.9% effective initial capitalization rate after recurring management fees. The question is whether redeploying the capital and earning fees can more than offset the rental economics transferred to the partner.
The venture could provide another funding source for acquisitions. Selling a minority interest in existing properties can release capital while preserving operational continuity. It also gives management an alternative when public equity or debt financing offers less attractive terms.
Management fees add a second source of income alongside retained property earnings. Realty Income Corporation (NYSE:O) could use its existing European operating platform to manage the venture, potentially spreading overhead across a broader pool of investor capital. The benefit depends on fee revenue exceeding the incremental costs of providing those services.
The structure includes a further source of potential upside. Realty Income Corporation (NYSE:O) would have an option to redeem the partner's interest after year 10 and through year 17. The redemption price would provide a capped internal rate of return, an annualized return accounting for cash-flow timing, expected at 6.3% to 6.5% and finalized at closing.
#NYSE #corporation #management #source


5 days ago
Logistic Properties of the Americas (NYSEAMERICAN:LPA) moved closer to selling Parque Logístico Lima Sur after Peru's antitrust authority, INDECOPI, approved the transaction on September 11. FIBRA Prime would acquire the entire 1.3-million-square-foot logistics park for $145 million. Customary administrative closing matters remain outstanding.
Management expects approximately $85 million of net proceeds after debt repayment and before taxes, with Mexico the intended destination. Approval advances the financing of that expansion, while the investment case rests on replacing an established income stream.
Lima Sur generated $10.3 million of cash net operating income, or cash NOI, during the 12 months ended March 31, 2026. Cash NOI is a company-defined non-IFRS measure of property income after operating expenses, adjusted to remove straight-line rental accounting. It excludes corporate overhead, financing costs, income taxes, and other non-property items.
Logistic Properties of the Americas (NYSEAMERICAN:LPA) has demonstrated an ability to develop, lease and operate logistics ***** ets. Second-quarter revenue increased 26.1% to $14.7 million, while stabilized portfolio occupancy reached 100% as of June 30.
Mexico already contributes revenue. Two properties acquired in Puebla in August 2025 generated approximately $0.5 million during the second quarter. That provides an operating foothold for deploying proceeds.
#cash #logistic #nyseamerican #Mexico
Management expects approximately $85 million of net proceeds after debt repayment and before taxes, with Mexico the intended destination. Approval advances the financing of that expansion, while the investment case rests on replacing an established income stream.
Lima Sur generated $10.3 million of cash net operating income, or cash NOI, during the 12 months ended March 31, 2026. Cash NOI is a company-defined non-IFRS measure of property income after operating expenses, adjusted to remove straight-line rental accounting. It excludes corporate overhead, financing costs, income taxes, and other non-property items.
Logistic Properties of the Americas (NYSEAMERICAN:LPA) has demonstrated an ability to develop, lease and operate logistics ***** ets. Second-quarter revenue increased 26.1% to $14.7 million, while stabilized portfolio occupancy reached 100% as of June 30.
Mexico already contributes revenue. Two properties acquired in Puebla in August 2025 generated approximately $0.5 million during the second quarter. That provides an operating foothold for deploying proceeds.
#cash #logistic #nyseamerican #Mexico

6 days ago
Cognyte Software Ltd. (NASDAQ:CGNT) reported on September 9 that revenue for the fiscal second quarter ended July 31, 2026, increased 12.0% to $109.2 million. Total software revenue, comprising software and software services, rose 20.9% to $100.8 million.
Company-defined non-GAAP adjusted EBITDA increased 35.7% to $14.9 million. The measure adds depreciation, amortization, stock-based compensation, restructuring costs, and other specified adjustments to GAAP operating income. Yet quarterly billings fell to $76.3 million from $93.0 million. The central question is whether a more profitable revenue mix can produce stronger cash generation while sustaining future growth.
The portfolio transition is visible in the revenue base. Total software revenue represented more than 92% of sales. Recurring revenue, primarily support contracts and subscription offerings, reached $56.2 million, or 51.4% of total revenue.
For Cognyte Software Ltd. (NASDAQ:CGNT), a larger recurring base could make revenue more predictable and support continued product investment. Renewals also create opportunities to expand customer relationships without rebuilding the sales pipeline from scratch. The benefit depends on retention and expansion within those accounts.
Profitability improved under both accounting measures. GAAP operating margin increased to 4.3% from 2.8%, while adjusted EBITDA margin expanded to 13.6% from 11.3%. That combination strengthens the case that the transition is improving operating economics, even after recognizing expenses excluded from adjusted results.
#gaap #NASDAQ
Company-defined non-GAAP adjusted EBITDA increased 35.7% to $14.9 million. The measure adds depreciation, amortization, stock-based compensation, restructuring costs, and other specified adjustments to GAAP operating income. Yet quarterly billings fell to $76.3 million from $93.0 million. The central question is whether a more profitable revenue mix can produce stronger cash generation while sustaining future growth.
The portfolio transition is visible in the revenue base. Total software revenue represented more than 92% of sales. Recurring revenue, primarily support contracts and subscription offerings, reached $56.2 million, or 51.4% of total revenue.
For Cognyte Software Ltd. (NASDAQ:CGNT), a larger recurring base could make revenue more predictable and support continued product investment. Renewals also create opportunities to expand customer relationships without rebuilding the sales pipeline from scratch. The benefit depends on retention and expansion within those accounts.
Profitability improved under both accounting measures. GAAP operating margin increased to 4.3% from 2.8%, while adjusted EBITDA margin expanded to 13.6% from 11.3%. That combination strengthens the case that the transition is improving operating economics, even after recognizing expenses excluded from adjusted results.
#gaap #NASDAQ


6 days ago
AeroVironment, Inc. (NASDAQ:AVAV) reported on September 9, 2026, that revenue for fiscal Q1 2027, ended August 1, 2026, increased 6% to $480.5 million. Funded backlog reached approximately $1.5 billion at quarter-end, up from $1.2 billion at April 30, 2026. This represents remaining work under firm customer orders with funding already appropriated, providing a concrete base for future revenue.
Non-GAAP adjusted diluted earnings were $0.59 per share, excluding acquired-intangible amortization, purchase-accounting adjustments, acquisition expenses, and net gains and losses on equity-method and equity-security investments. Adjusted EPS retains net interest income. The GAAP result was a $5.1 million net loss, or $0.10 per diluted share. The question is whether the expanding order base can produce stronger operating earnings and cash generation.
Bookings reached $683 million, producing a book-to-bill ratio of 1.4, calculated as bookings divided by revenue. Bookings measure authorized contract awards and modifications and can include work whose funding has not yet been obligated. The ratio indicates that new business exceeded revenue recognized during the quarter.
AeroVironment, Inc. (NASDAQ:AVAV) is also translating demand into sales in Autonomous Systems, where revenue rose 21% to $346 million. That provides operating evidence behind the opportunity in unmanned aircraft and precision-strike systems.
Management maintained fiscal 2027 revenue guidance of $2.125 billion to $2.225 billion, and non-GAAP adjusted EBITDA of $305 million to $325 million. Adjusted EBITDA excludes net interest income or expense, taxes, depreciation and amortization from net income and further adjusts for stock compensation, acquisition expenses, cloud-computing amortization, net gains and losses on equity-method and equity-security investments, and other specified items.
#Equity
Non-GAAP adjusted diluted earnings were $0.59 per share, excluding acquired-intangible amortization, purchase-accounting adjustments, acquisition expenses, and net gains and losses on equity-method and equity-security investments. Adjusted EPS retains net interest income. The GAAP result was a $5.1 million net loss, or $0.10 per diluted share. The question is whether the expanding order base can produce stronger operating earnings and cash generation.
Bookings reached $683 million, producing a book-to-bill ratio of 1.4, calculated as bookings divided by revenue. Bookings measure authorized contract awards and modifications and can include work whose funding has not yet been obligated. The ratio indicates that new business exceeded revenue recognized during the quarter.
AeroVironment, Inc. (NASDAQ:AVAV) is also translating demand into sales in Autonomous Systems, where revenue rose 21% to $346 million. That provides operating evidence behind the opportunity in unmanned aircraft and precision-strike systems.
Management maintained fiscal 2027 revenue guidance of $2.125 billion to $2.225 billion, and non-GAAP adjusted EBITDA of $305 million to $325 million. Adjusted EBITDA excludes net interest income or expense, taxes, depreciation and amortization from net income and further adjusts for stock compensation, acquisition expenses, cloud-computing amortization, net gains and losses on equity-method and equity-security investments, and other specified items.
#Equity


7 days ago
Boston, Massachusetts-based State Street Corporation (STT) provides a range of financial products and services to institutional investors. Valued at a market cap of $50.9 billion, it offers custody, accounting, and fund administration services for traditional and alternative ****** ets, as well as multi-asset-class investments, recordkeeping, client reporting, and more.
Companies with a market cap of $10 billion or more are typically referred to as "large-cap stocks." STT fits squarely in that category, with a market cap above this threshold that reflects its size and influence in the ****** et management industry.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#market #street
Companies with a market cap of $10 billion or more are typically referred to as "large-cap stocks." STT fits squarely in that category, with a market cap above this threshold that reflects its size and influence in the ****** et management industry.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#market #street

7 days ago
Rocket Lab (RKLB) stock has traded between $39.48 and $150.23 over the past 52 weeks. It now sits about 58% below its 52-week high, and anyone who bought twelve months ago is still up about 19%. None of that tells you what you would be buying today. Rocket Lab sells two quite different things, and the one its name points at is the smaller of them.
In Q2 2026 the ****** e Systems segment brought in $189.5 million. Launch Services brought in $44.6 million, down 30% from the previous quarter despite a similar number of launches. Management attributes that drop to accounting rather than lost work, because revenue from those launches is recognized over time and much of it had already been booked.
So Rocket Lab earns most of its revenue building satellites and their parts. Electron flew its 16th mission of 2026 in September. Launch is a real franchise, and it is not where most of the money comes from.
The stock trades at 52 times sales, against 3.1 for the S&P 500, on revenue of about $0.8 billion over the trailing twelve months. At this valuation, investors are largely pricing in future execution on the Neutron medium-lift rocket and the financial impact of the pending Iridium acquisition, rather than current satellite production alone. Management targets delivery to the pad in Q4 2026, and says the window for a launch before the end of 2026 is narrowing.
And you are paying for Iridium, which Rocket Lab has agreed to buy and expects to close in mid-2027. Iridium, a global satellite communications network, serves more than 2.5 million subscribers and delivered over $870 million of revenue in its past year. That is more than Rocket Lab's whole trailing twelve months. Management calls it a relatively slow-growing business that brings profit rather than a hole in the income statement.
#million #management #revenue
In Q2 2026 the ****** e Systems segment brought in $189.5 million. Launch Services brought in $44.6 million, down 30% from the previous quarter despite a similar number of launches. Management attributes that drop to accounting rather than lost work, because revenue from those launches is recognized over time and much of it had already been booked.
So Rocket Lab earns most of its revenue building satellites and their parts. Electron flew its 16th mission of 2026 in September. Launch is a real franchise, and it is not where most of the money comes from.
The stock trades at 52 times sales, against 3.1 for the S&P 500, on revenue of about $0.8 billion over the trailing twelve months. At this valuation, investors are largely pricing in future execution on the Neutron medium-lift rocket and the financial impact of the pending Iridium acquisition, rather than current satellite production alone. Management targets delivery to the pad in Q4 2026, and says the window for a launch before the end of 2026 is narrowing.
And you are paying for Iridium, which Rocket Lab has agreed to buy and expects to close in mid-2027. Iridium, a global satellite communications network, serves more than 2.5 million subscribers and delivered over $870 million of revenue in its past year. That is more than Rocket Lab's whole trailing twelve months. Management calls it a relatively slow-growing business that brings profit rather than a hole in the income statement.
#million #management #revenue


7 days ago
The choice between established ****** ans and digital-first challengers defines many modern portfolios. In the financial realm, investors must decide if JPMorgan Chase (NYSE:JPM) or SoFi Technologies (NASDAQ:SOFI) is the better buy for long-term growth.
JPMorgan Chase operates as a global financial heavyweight, offering everything from wealth management to retail branches. Conversely, SoFi Technologies focuses on an integrated mobile app to help members borrow, save, and invest. While one relies on massive scale, the other bets on fintech innovation to capture a younger, tech-savvy demographic.
JPMorgan Chase functions as a cornerstone of the global economy, managing a vast array of services including ****** et management and investment banking. In its latest annual report, filed for 2025, the firm highlighted its reach through more than 5,000 branches across the 48 contiguous states. It serves a diverse client base ranging from individual consumers and small businesses to large corporations and governments. The firm provides a comprehensive range of financial services, including transaction processing and commercial banking on a global scale.
Financial performance remained robust in FY 2025, with revenue reaching nearly $182.4 billion. This represented a growth rate of approximately 3.3% compared to the previous year, contributing to a net income of close to $57.0 billion. The net margin, which measures the percentage of revenue kept as profit after all expenses, sat at roughly 20.4% for the period. This consistent profitability underscores the scale of its operations across diverse global markets.
As of its December 2025 balance sheet, the firm reported a debt-to-equity ratio of nearly 2.6x. This ratio measures total debt against shareholder equity, with a higher number indicating more reliance on borrowed funds to finance growth. The current ratio, which compares short-term ****** ets to short-term liabilities, was approximately 0.5x, while free cash flow reached a negative $147.8 billion. Free cash flow is the cash a company generates after accounting for cash outflows to support operations and maintain its capital ****** ets.
#sofi #global #term
JPMorgan Chase operates as a global financial heavyweight, offering everything from wealth management to retail branches. Conversely, SoFi Technologies focuses on an integrated mobile app to help members borrow, save, and invest. While one relies on massive scale, the other bets on fintech innovation to capture a younger, tech-savvy demographic.
JPMorgan Chase functions as a cornerstone of the global economy, managing a vast array of services including ****** et management and investment banking. In its latest annual report, filed for 2025, the firm highlighted its reach through more than 5,000 branches across the 48 contiguous states. It serves a diverse client base ranging from individual consumers and small businesses to large corporations and governments. The firm provides a comprehensive range of financial services, including transaction processing and commercial banking on a global scale.
Financial performance remained robust in FY 2025, with revenue reaching nearly $182.4 billion. This represented a growth rate of approximately 3.3% compared to the previous year, contributing to a net income of close to $57.0 billion. The net margin, which measures the percentage of revenue kept as profit after all expenses, sat at roughly 20.4% for the period. This consistent profitability underscores the scale of its operations across diverse global markets.
As of its December 2025 balance sheet, the firm reported a debt-to-equity ratio of nearly 2.6x. This ratio measures total debt against shareholder equity, with a higher number indicating more reliance on borrowed funds to finance growth. The current ratio, which compares short-term ****** ets to short-term liabilities, was approximately 0.5x, while free cash flow reached a negative $147.8 billion. Free cash flow is the cash a company generates after accounting for cash outflows to support operations and maintain its capital ****** ets.
#sofi #global #term


7 days ago
If online prediction markets are correct, the Democrats are likely to win back the House and Senate in November. On Polymarket, there's currently a 53% chance of a Democratic sweep.
If you're a crypto investor, that outcome could have important consequences for your portfolio. That's especially the case if Democrats delay, roll back, or block important pro-crypto legislation. With that in mind, here's one crypto to buy and one crypto to sell.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My one crypto to buy is Bitcoin (CRYPTO: BTC). It is still the most popular cryptocurrency, accounting for a whopping 60% of the crypto market's total $2.6 trillion market cap. As Bitcoin goes, so goes the crypto market.
As a result, Bitcoin currently has the support of both Wall Street and the White House, so any political fallout from the midterm elections in the event of a Democratic sweep should be minimal. Regulators already agree that Bitcoin is a commodity, not a security. Thus, even if the Clarity Act does not pass this year, it shouldn't have a direct impact on the regulatory status of Bitcoin and how institutional investors view it.
#NVIDIA #flashing #total
If you're a crypto investor, that outcome could have important consequences for your portfolio. That's especially the case if Democrats delay, roll back, or block important pro-crypto legislation. With that in mind, here's one crypto to buy and one crypto to sell.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My one crypto to buy is Bitcoin (CRYPTO: BTC). It is still the most popular cryptocurrency, accounting for a whopping 60% of the crypto market's total $2.6 trillion market cap. As Bitcoin goes, so goes the crypto market.
As a result, Bitcoin currently has the support of both Wall Street and the White House, so any political fallout from the midterm elections in the event of a Democratic sweep should be minimal. Regulators already agree that Bitcoin is a commodity, not a security. Thus, even if the Clarity Act does not pass this year, it shouldn't have a direct impact on the regulatory status of Bitcoin and how institutional investors view it.
#NVIDIA #flashing #total
7 days ago
GENEVA (AP) — Human rights experts commissioned by the U.N.'s top human rights body say they have found "reasonable grounds" to believe the United States committed war crimes in two strikes in Iran, including on a school in the southern city of Minab.
The international fact-finding mission on Iran says the findings center on a pair of airstrikes that killed at least 178 civilians, including women and children.
At the start of the U.S.-Israeli war against Iran in February, at least one U.S. missile hit the Shajareh Tayyebeh school in Minab, according to an ****** ociated Press investigation. There has been no final accounting of what happened. Iranian state media have said 168 people were killed in the strike, most of them children.
"Following the United States and Israeli attacks on 28 February, the mission found reasonable grounds to believe the United States committed the war crime of launching indiscriminate attacks resulting in the loss of life or injury to civilians or damage to civilian objects," the fact-finding team said in a statement.
The Trump administration has yet to directly accept the blame or release findings of a Pentagon investigation into the school bombing.
#school
The international fact-finding mission on Iran says the findings center on a pair of airstrikes that killed at least 178 civilians, including women and children.
At the start of the U.S.-Israeli war against Iran in February, at least one U.S. missile hit the Shajareh Tayyebeh school in Minab, according to an ****** ociated Press investigation. There has been no final accounting of what happened. Iranian state media have said 168 people were killed in the strike, most of them children.
"Following the United States and Israeli attacks on 28 February, the mission found reasonable grounds to believe the United States committed the war crime of launching indiscriminate attacks resulting in the loss of life or injury to civilians or damage to civilian objects," the fact-finding team said in a statement.
The Trump administration has yet to directly accept the blame or release findings of a Pentagon investigation into the school bombing.
#school
7 days ago
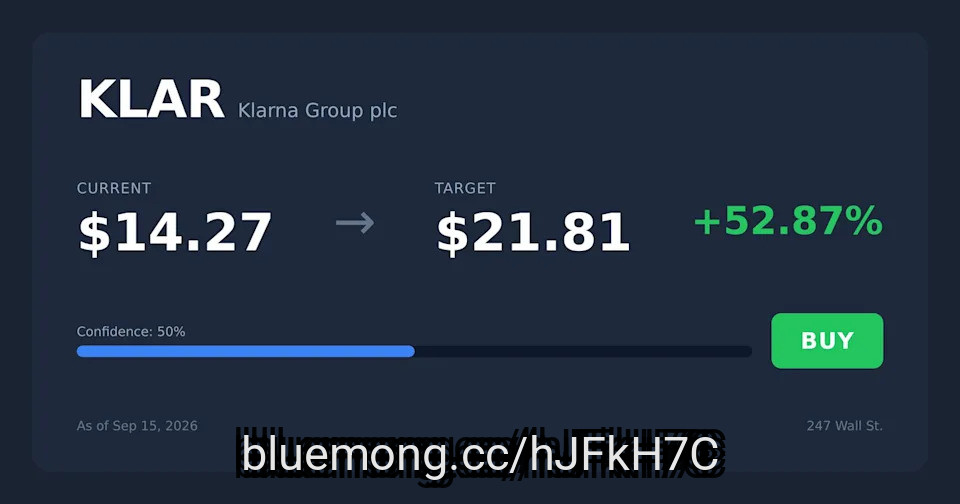
Klarna stock has cratered 51% year to date and 32% in just the past month, trading near its 52-week low of $12.
While KLAR collapsed, Sezzle surged 87% and Affirm slipped just 3%, signaling Klarna's pain is company-specific, not a BNPL sector rout.
Klarna's Q2 showed transaction margin up 42% and a swing to $9M net profit, but a guidance cut and accounting changes cloud the Q3 outlook.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Klarna Group plc didn't make the cut. Enter your email to see the names that beat KLAR. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of Klarna (NYSE:KLAR) are trading at $14.23 on Tuesday afternoon, leaving the buy now, pay later (BNPL) lender down 51% year to date. Klarna stock is also down 32% over the past month, meaning much of the damage has landed recently rather than fading out.
#klar #year #month
While KLAR collapsed, Sezzle surged 87% and Affirm slipped just 3%, signaling Klarna's pain is company-specific, not a BNPL sector rout.
Klarna's Q2 showed transaction margin up 42% and a swing to $9M net profit, but a guidance cut and accounting changes cloud the Q3 outlook.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Klarna Group plc didn't make the cut. Enter your email to see the names that beat KLAR. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of Klarna (NYSE:KLAR) are trading at $14.23 on Tuesday afternoon, leaving the buy now, pay later (BNPL) lender down 51% year to date. Klarna stock is also down 32% over the past month, meaning much of the damage has landed recently rather than fading out.
#klar #year #month



7 days ago
Eli Lilly and Company (NYSE:LLY) says its newly launched oral obesity drug Foundayo has captured more than 30% of new U.S. patients starting oral weight-loss medicines, a notable early gain against Novo Nordisk's Wegovy pill. Reuters reports that Wegovy initially held roughly 90% of the oral market, making Lilly's rapid share capture an important sign that the oral GLP-1 market is becoming a two-player competition rather than a Novo-dominated segment. The broader U.S. obesity-drug market is expected to exceed $100 billion annually by 2030, with oral treatments potentially accounting for more than one-third of GLP-1 use.
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and **** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#patients #weight #c
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and **** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#patients #weight #c


7 days ago
Eli Lilly and Company (NYSE:LLY) says its newly launched oral obesity drug Foundayo has captured more than 30% of new U.S. patients starting oral weight-loss medicines, a notable early gain against Novo Nordisk's Wegovy pill. Reuters reports that Wegovy initially held roughly 90% of the oral market, making Lilly's rapid share capture an important sign that the oral GLP-1 market is becoming a two-player competition rather than a Novo-dominated segment. The broader U.S. obesity-drug market is expected to exceed $100 billion annually by 2030, with oral treatments potentially accounting for more than one-third of GLP-1 use.
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and ***** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#weight
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and ***** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#weight

8 days ago
Choosing between Advance Auto Parts (NYSE:AAP) and Intuitive Machines (NASDAQ:LUNR) requires balancing the steady but challenged automotive retail sector against the high-stakes, high-growth arena of ******* e infrastructure.
Advance Auto Parts operates as a massive retailer for vehicle maintenance, while Intuitive Machines focuses on lunar landers and orbital services. These two businesses represent very different risk-to-reward profiles for 2026 portfolios.
Advance Auto Parts operates as an automotive aftermarket parts retailer, serving both everyday do-it-yourselfers and professional installers like garages or dealerships. In its latest annual report, filed for the fiscal year ended January 3, 2026, the company noted it operates over 4,000 stores across North America. As an established player among retail stocks, its strategy relies on balancing these two customer bases, with professional sales accounting for nearly 50% of its total revenue.
In FY 2025, revenue reached $8.6 billion, representing a revenue decline of roughly 5.4% compared to the previous year. Despite this decline, the company reported a net income of $44.0 million. This resulted in a thin net margin, a measure of how much profit a company keeps from its total sales, of about 0.5%.
As of its January 2026 balance sheet, the debt-to-equity ratio was 2.4x. This ratio measures total debt against shareholder equity, with a higher number suggesting more reliance on borrowing. The so-called current ratio, which tracks the ability to pay short-term debts with short-term ******* ets, was 1.7x. Free cash flow, defined as cash from operations minus capital expenditures, was negative $298.0 million for the year.
#parts #operates #total #ratio
Advance Auto Parts operates as a massive retailer for vehicle maintenance, while Intuitive Machines focuses on lunar landers and orbital services. These two businesses represent very different risk-to-reward profiles for 2026 portfolios.
Advance Auto Parts operates as an automotive aftermarket parts retailer, serving both everyday do-it-yourselfers and professional installers like garages or dealerships. In its latest annual report, filed for the fiscal year ended January 3, 2026, the company noted it operates over 4,000 stores across North America. As an established player among retail stocks, its strategy relies on balancing these two customer bases, with professional sales accounting for nearly 50% of its total revenue.
In FY 2025, revenue reached $8.6 billion, representing a revenue decline of roughly 5.4% compared to the previous year. Despite this decline, the company reported a net income of $44.0 million. This resulted in a thin net margin, a measure of how much profit a company keeps from its total sales, of about 0.5%.
As of its January 2026 balance sheet, the debt-to-equity ratio was 2.4x. This ratio measures total debt against shareholder equity, with a higher number suggesting more reliance on borrowing. The so-called current ratio, which tracks the ability to pay short-term debts with short-term ******* ets, was 1.7x. Free cash flow, defined as cash from operations minus capital expenditures, was negative $298.0 million for the year.
#parts #operates #total #ratio

8 days ago
US-based accounting, tax and advisory practice PKF O'Connor Davies has appointed Mark Goldschmitt as a partner within its commercial tax practice, based at its office in Hauppauge, New York.
Goldschmitt brings close to 30 years of public accounting experience.
His work focuses on tax planning, regulatory compliance and business advisory services for corporate entities, partnerships, privately held enterprises and high-net-worth individuals.
His sector experience spans architecture, legal services, digital media, staffing and recruitment.
The appointment forms part of the company's plans to develop its commercial tax service capabilities across the New York metropolitan region.
#experience #o 'connor
Goldschmitt brings close to 30 years of public accounting experience.
His work focuses on tax planning, regulatory compliance and business advisory services for corporate entities, partnerships, privately held enterprises and high-net-worth individuals.
His sector experience spans architecture, legal services, digital media, staffing and recruitment.
The appointment forms part of the company's plans to develop its commercial tax service capabilities across the New York metropolitan region.
#experience #o 'connor


8 days ago
The Public Company Accounting Oversight Board (PCAOB) in the US has named Addison Scott and Zian Xi as Audit Practitioner Fellows under the newly introduced Audit Practitioner Fellowship Programme.
Based within the regulator's Office of the Chief Auditor, both fellows have begun two-year terms with immediate effect.
Scott and Xi will ****** ist with the board's research and standard-setting priorities, with the aim of bolstering oversight functions and serving the public interest.
Scott joined the PCAOB in September 2026 after more than 11 years with EY.
Her tenure included three years in the company's Professional Practice Group, where she focused on audit methodology and the execution of standards set by the PCAOB, the American Institute of Certified Public Accountants, and international auditing and quality management bodies.
#pcaob #scott
Based within the regulator's Office of the Chief Auditor, both fellows have begun two-year terms with immediate effect.
Scott and Xi will ****** ist with the board's research and standard-setting priorities, with the aim of bolstering oversight functions and serving the public interest.
Scott joined the PCAOB in September 2026 after more than 11 years with EY.
Her tenure included three years in the company's Professional Practice Group, where she focused on audit methodology and the execution of standards set by the PCAOB, the American Institute of Certified Public Accountants, and international auditing and quality management bodies.
#pcaob #scott

9 days ago
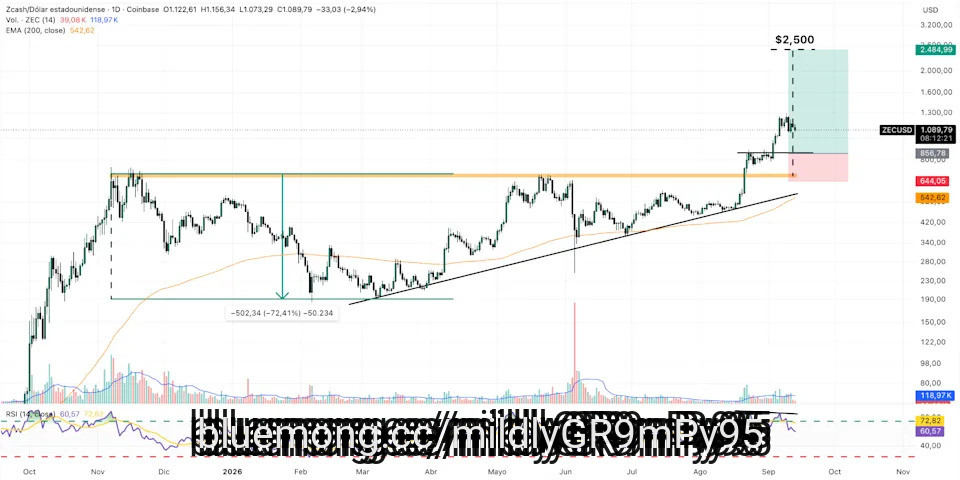
Zcash (ZEC) has dropped by nearly 6% in the past 7 days following a massive rally that pushed the token to its highest levels in a decade.
Trading volumes remain quite high at $1.4 billion, accounting for over 7% of the ******* et's circulating market cap.
The price hit a strong sell wall at $1,300 as macroeconomic conditions in the United States deteriorated.
A stable inflation print on Friday kickstarted a short-lived rally across crypto ******* ets but quickly faded, as odds of a rate hike during the next FOMC meeting rose to nearly 90%.
The Federal Open Market Committee (FOMC) is expected to convene on September 16. Comments from the new Chairman of the central bank, Kevin Warsh, will be scrutinized to get a sense of how the institution plans to curb inflation.
#inflation #zcash #trading #states
Trading volumes remain quite high at $1.4 billion, accounting for over 7% of the ******* et's circulating market cap.
The price hit a strong sell wall at $1,300 as macroeconomic conditions in the United States deteriorated.
A stable inflation print on Friday kickstarted a short-lived rally across crypto ******* ets but quickly faded, as odds of a rate hike during the next FOMC meeting rose to nearly 90%.
The Federal Open Market Committee (FOMC) is expected to convene on September 16. Comments from the new Chairman of the central bank, Kevin Warsh, will be scrutinized to get a sense of how the institution plans to curb inflation.
#inflation #zcash #trading #states

10 days ago
On August 6, The RealReal (NASDAQ:REAL) reported second quarter results that beat its own outlook and pushed the resale luxury marketplace to raise its full year guidance. Gross merchandise value hit an all time high of $617 million, up 22% from a year earlier, and management pointed to four straight quarters of GMV growth above 20%. But a wider net loss sitting next to those record numbers complicates the story for anyone weighing the stock today.
The headline number is GMV of $617 million for the quarter ended June 30, up 22% year over year, with total revenue climbing 17% to $193 million. Consignment revenue grew 15% while Direct Revenue, the company's owned inventory channel, grew 26%, showing both sides of the business contributing to the acceleration. Profitability moved in the same direction. Gross margin reached 74.4%, up 10 basis points from a year ago, and Adjusted EBITDA margin jumped to 7%, a 290 basis point improvement that management called nearly 300 basis points of expansion.
The buyer base backs up the growth story rather than just the pricing. Trailing twelve-month active buyers rose 11% to 1,107,000, and average order value climbed 13% to $659, meaning existing shoppers are spending meaningfully more per transaction, not just showing up more often. That combination gave management enough confidence to raise full-year guidance to $2.54 billion to $2.57 billion in GMV and $788 million to $797 million in total revenue, alongside third-quarter Adjusted EBITDA guidance of $13.5 million to $14.5 million.
Despite the operating improvements, GAAP losses widened. Net loss came in at $27 million, or 14.1% of total revenue, compared to $11 million, or 6.9% of total revenue, a year earlier. GAAP basic net loss per share was $0.23 versus $0.10 in the prior year period, and diluted net loss per share was $0.23 versus $0.13. Much of that swing traces to a $(18.6) million non-cash adjustment tied to the change in fair value of warrant liability, a factor unrelated to how the underlying business performed. On a non-GAAP basis, basic and diluted net loss per share actually narrowed to $0.01 from $0.06, underscoring how much of the GAAP gap is accounting rather than operations.
There is also a transparency wrinkle in the guidance itself. The RealReal said it has not reconciled its forward-looking Adjusted EBITDA figures to GAAP net income or loss, citing components like payroll tax expense on employee stock transactions that it cannot predict with reasonable certainty. That leaves investors trusting a non-GAAP target without the usual bridge back to the bottom line.
#adjusted
The headline number is GMV of $617 million for the quarter ended June 30, up 22% year over year, with total revenue climbing 17% to $193 million. Consignment revenue grew 15% while Direct Revenue, the company's owned inventory channel, grew 26%, showing both sides of the business contributing to the acceleration. Profitability moved in the same direction. Gross margin reached 74.4%, up 10 basis points from a year ago, and Adjusted EBITDA margin jumped to 7%, a 290 basis point improvement that management called nearly 300 basis points of expansion.
The buyer base backs up the growth story rather than just the pricing. Trailing twelve-month active buyers rose 11% to 1,107,000, and average order value climbed 13% to $659, meaning existing shoppers are spending meaningfully more per transaction, not just showing up more often. That combination gave management enough confidence to raise full-year guidance to $2.54 billion to $2.57 billion in GMV and $788 million to $797 million in total revenue, alongside third-quarter Adjusted EBITDA guidance of $13.5 million to $14.5 million.
Despite the operating improvements, GAAP losses widened. Net loss came in at $27 million, or 14.1% of total revenue, compared to $11 million, or 6.9% of total revenue, a year earlier. GAAP basic net loss per share was $0.23 versus $0.10 in the prior year period, and diluted net loss per share was $0.23 versus $0.13. Much of that swing traces to a $(18.6) million non-cash adjustment tied to the change in fair value of warrant liability, a factor unrelated to how the underlying business performed. On a non-GAAP basis, basic and diluted net loss per share actually narrowed to $0.01 from $0.06, underscoring how much of the GAAP gap is accounting rather than operations.
There is also a transparency wrinkle in the guidance itself. The RealReal said it has not reconciled its forward-looking Adjusted EBITDA figures to GAAP net income or loss, citing components like payroll tax expense on employee stock transactions that it cannot predict with reasonable certainty. That leaves investors trusting a non-GAAP target without the usual bridge back to the bottom line.
#adjusted

10 days ago
On August 5, Clear Channel Outdoor Holdings Inc. (NYSE:CCO) reported second-quarter results that showed the billboard and airport advertising company accelerating just as it prepares to leave the public markets. On February 9, Clear Channel agreed to be acquired by an investor consortium advised by Mubadala Capital for $2.43 per share, a deal stockholders approved on May 12, and one expected to close by the end of the third quarter of 2026. Because of the pending Merger, Clear Channel skipped its usual earnings call and offered no forward guidance.
Consolidated revenue climbed 8.7% to $438.0 million in the quarter and 10.2% to $811.9 million over the first half, with the 2026 FIFA World Cup pulling in extra advertising spend across both of Clear Channel's segments. The America division, which houses the roadside billboard and street furniture business, grew revenue 7% to $324.3 million as demand from technology advertisers in the San Francisco/Bay Area market broadened out and digital billboard revenue rose 7.2% to $122 million. Airports revenue jumped 14% to $113.6 million, helped by strong demand at San Francisco
International Airport and digital sales that climbed 15.6% to $73.4 million, with national advertisers now accounting for 57.8% of that segment's revenue. Profitability grew even faster than the top line. Adjusted EBITDA rose 11.6% to $143.4 million for the quarter and 19% to $247.3 million for the first half, while Airports Segment Adjusted EBITDA jumped 22.8% to $29.9 million. Adjusted Funds From Operations climbed 61.6% to $44.9 million in the quarter, and for the first half it went from just $5 million a year ago to $51.5 million. On August 4, Clear Channel also closed the sale of its Spain business for about $132.3 million, proceeds it plans to put toward paying down debt.
The growth did not reach the bottom line. Clear Channel posted a loss from continuing operations of $10 million in the quarter, reversing a $6.3 million profit a year earlier, and the consolidated net loss came to $5 million versus net income of $10.6 million in the same period of 2025. Over six months, the loss from continuing operations widened 21.4% to $59.4 million. Costs rose alongside revenue. Direct operating and SG&A expenses increased 5.9% for the quarter, and Airports site lease expense alone jumped 12.0% to $67.1 million on higher minimum guaranteed payments and the renewed contract with the Metropolitan Washington Airports Authority.
#channel #revenue #airports #operations
Consolidated revenue climbed 8.7% to $438.0 million in the quarter and 10.2% to $811.9 million over the first half, with the 2026 FIFA World Cup pulling in extra advertising spend across both of Clear Channel's segments. The America division, which houses the roadside billboard and street furniture business, grew revenue 7% to $324.3 million as demand from technology advertisers in the San Francisco/Bay Area market broadened out and digital billboard revenue rose 7.2% to $122 million. Airports revenue jumped 14% to $113.6 million, helped by strong demand at San Francisco
International Airport and digital sales that climbed 15.6% to $73.4 million, with national advertisers now accounting for 57.8% of that segment's revenue. Profitability grew even faster than the top line. Adjusted EBITDA rose 11.6% to $143.4 million for the quarter and 19% to $247.3 million for the first half, while Airports Segment Adjusted EBITDA jumped 22.8% to $29.9 million. Adjusted Funds From Operations climbed 61.6% to $44.9 million in the quarter, and for the first half it went from just $5 million a year ago to $51.5 million. On August 4, Clear Channel also closed the sale of its Spain business for about $132.3 million, proceeds it plans to put toward paying down debt.
The growth did not reach the bottom line. Clear Channel posted a loss from continuing operations of $10 million in the quarter, reversing a $6.3 million profit a year earlier, and the consolidated net loss came to $5 million versus net income of $10.6 million in the same period of 2025. Over six months, the loss from continuing operations widened 21.4% to $59.4 million. Costs rose alongside revenue. Direct operating and SG&A expenses increased 5.9% for the quarter, and Airports site lease expense alone jumped 12.0% to $67.1 million on higher minimum guaranteed payments and the renewed contract with the Metropolitan Washington Airports Authority.
#channel #revenue #airports #operations
10 days ago
On September 10, LightPath Technologies (NASDAQ:LPTH) reported fiscal fourth-quarter and full-year results that turned a multiyear strategic bet into a financial statement. Revenue nearly doubled for the year, margins expanded, and the company walked away from its last manufacturing ties to China. For a small-cap optics supplier that spent years explaining a strategy, this was the quarter the strategy started explaining itself.
Annual revenue climbed 92.7% to $71.7 million from $37.2 million, and the fourth quarter alone hit a record $21.2 million, up 73.8% year over year. That growth is not just volume. Full-year gross margin expanded to 36% from 27.2%, and the fourth quarter came in even higher at 39.4%, because ****** emblies, modules and cameras now make up 44% of annual sales instead of being sold as raw components.
CEO Sam Rubin said the shift reflects both a change in what LightPath sells and better execution on what it already made, noting every one of its four product groups improved margin for the year. Backlog finished at $110.9 million, up 197% from $37.4 million a year earlier, with $85.6 million of it scheduled for delivery within 12 months. Weeks after the fiscal year closed, the company booked another $24 million in counter-UAS orders, and some of those programs have already moved to monthly delivery cadences of tens of units.
LightPath also completed its exit from China, selling its subsidiary there for $4.5 million paid out over five years, leaving the company with no manufacturing footprint in a country that increasingly can't supply the defense primes it depends on. That matters because defense programs face a deadline this decade to source optics away from covered nations, and qualification cycles run two to three years, meaning the sourcing decisions being made now will determine who wins contracts in 2029 and 2030.
The company's fourth-quarter net loss narrowed to $4.1 million from $7.1 million a year earlier, but full-year operating expenses jumped to $45.5 million from $22 million, and $15.6 million of that was a noncash charge tied to G5 Infrared outperforming the earnout targets set at acquisition. Management called that charge mostly behind the business now that the final G5 payout has been accrued for January 2027, but it is a reminder that acquisition accounting can swing the income statement even when operations are healthy.
#year #quarter #China
Annual revenue climbed 92.7% to $71.7 million from $37.2 million, and the fourth quarter alone hit a record $21.2 million, up 73.8% year over year. That growth is not just volume. Full-year gross margin expanded to 36% from 27.2%, and the fourth quarter came in even higher at 39.4%, because ****** emblies, modules and cameras now make up 44% of annual sales instead of being sold as raw components.
CEO Sam Rubin said the shift reflects both a change in what LightPath sells and better execution on what it already made, noting every one of its four product groups improved margin for the year. Backlog finished at $110.9 million, up 197% from $37.4 million a year earlier, with $85.6 million of it scheduled for delivery within 12 months. Weeks after the fiscal year closed, the company booked another $24 million in counter-UAS orders, and some of those programs have already moved to monthly delivery cadences of tens of units.
LightPath also completed its exit from China, selling its subsidiary there for $4.5 million paid out over five years, leaving the company with no manufacturing footprint in a country that increasingly can't supply the defense primes it depends on. That matters because defense programs face a deadline this decade to source optics away from covered nations, and qualification cycles run two to three years, meaning the sourcing decisions being made now will determine who wins contracts in 2029 and 2030.
The company's fourth-quarter net loss narrowed to $4.1 million from $7.1 million a year earlier, but full-year operating expenses jumped to $45.5 million from $22 million, and $15.6 million of that was a noncash charge tied to G5 Infrared outperforming the earnout targets set at acquisition. Management called that charge mostly behind the business now that the final G5 payout has been accrued for January 2027, but it is a reminder that acquisition accounting can swing the income statement even when operations are healthy.
#year #quarter #China

10 days ago
On September 10, MasterCraft Boat Holdings (NASDAQ:MCFT) reported a fiscal fourth quarter that looked nothing like the one a year earlier. Adjusted EBITDA more than doubled, margins expanded across the legacy business, and the company closed out a year defined by its May 15 acquisition of Marine Products Corporation. But buried inside those same results was a $10.1 million writedown that tells a very different story about one corner of the business.
MasterCraft's core boat business is the reason the quarter worked at all. Legacy net sales, meaning the business before the acquisition, climbed 21.5% year over year to $96.6 million in the fourth quarter, powered by the next generation X Series lineup and less discounting at the dealer level. That combination of volume and pricing pushed legacy adjusted EBITDA margin up 730 basis points to 19.3%, up from 12% a year earlier. Once the newly acquired Chaparral and Robalo brands are added in, which contributed for only six weeks after the deal closed on May 15, consolidated fourth quarter net sales reached $129.9 million, up 63.4%, and adjusted EBITDA hit $20.5 million, up 114.9%.
The company also cleaned up its channel. Dealer field inventory for the legacy business fell 30% year over year, with turnover now running ahead of pre-pandemic levels, a sign dealers are selling boats rather than sitting on them. Full-year adjusted net income reached $30.2 million, or $1.76 per diluted share, up from $15.1 million, or $0.92 per share, in fiscal 2025. The company generated $22.3 million in free cash flow for the year and, as of June 30, held $43.9 million in cash, zero debt, and a fully available $75 million credit line. MasterCraft's own retail sales grew low single digits for the year even as the broader powerboat industry fell mid to high single digits, and the newer Robalo brand posted high single-digit retail growth in the fishing boat category.
The picture gets murkier once you look past the flagship brand. The Leisure segment, home to the Crest and Balise pontoon boats, saw fourth-quarter sales fall 11.2% year over year to $12.1 million, and the company booked a $10.1 million non-cash impairment against Crest brand ******* ets tied to what management called current category conditions. On a GAAP basis, that charge combined with acquisition costs and purchase accounting adjustments turned the quarter into a net loss of $7 million, or $0.35 per diluted share, compared to net income of $5.5 million a year earlier. Operating expenses rose $23.1 million in the quarter, including $5.9 million in transaction costs tied to the acquisition.
#million #legacy
MasterCraft's core boat business is the reason the quarter worked at all. Legacy net sales, meaning the business before the acquisition, climbed 21.5% year over year to $96.6 million in the fourth quarter, powered by the next generation X Series lineup and less discounting at the dealer level. That combination of volume and pricing pushed legacy adjusted EBITDA margin up 730 basis points to 19.3%, up from 12% a year earlier. Once the newly acquired Chaparral and Robalo brands are added in, which contributed for only six weeks after the deal closed on May 15, consolidated fourth quarter net sales reached $129.9 million, up 63.4%, and adjusted EBITDA hit $20.5 million, up 114.9%.
The company also cleaned up its channel. Dealer field inventory for the legacy business fell 30% year over year, with turnover now running ahead of pre-pandemic levels, a sign dealers are selling boats rather than sitting on them. Full-year adjusted net income reached $30.2 million, or $1.76 per diluted share, up from $15.1 million, or $0.92 per share, in fiscal 2025. The company generated $22.3 million in free cash flow for the year and, as of June 30, held $43.9 million in cash, zero debt, and a fully available $75 million credit line. MasterCraft's own retail sales grew low single digits for the year even as the broader powerboat industry fell mid to high single digits, and the newer Robalo brand posted high single-digit retail growth in the fishing boat category.
The picture gets murkier once you look past the flagship brand. The Leisure segment, home to the Crest and Balise pontoon boats, saw fourth-quarter sales fall 11.2% year over year to $12.1 million, and the company booked a $10.1 million non-cash impairment against Crest brand ******* ets tied to what management called current category conditions. On a GAAP basis, that charge combined with acquisition costs and purchase accounting adjustments turned the quarter into a net loss of $7 million, or $0.35 per diluted share, compared to net income of $5.5 million a year earlier. Operating expenses rose $23.1 million in the quarter, including $5.9 million in transaction costs tied to the acquisition.
#million #legacy
10 days ago
TotalEnergies SE (NYSE:TTE) plans to invest $10 billion alongside its partners in Angola over the next five years, with the goal of maintaining and potentially increasing its oil production in the country. TotalEnergies currently produces around 450,000 barrels per day in Angola, making it the country's largest oil operator and accounting for more than 40% of its total output.
The investment will go toward existing operations, new exploration, and projects aimed at replacing production from Angola's aging offshore fields. One of the biggest projects in the pipeline is the $6 billion Kaminho development, which is expected to start producing oil in 2028. TotalEnergies SE (NYSE:TTE) is also expanding its exploration efforts after signing agreements for two additional offshore blocks. On top of that, the company recently announced a new discovery in Block 17 that could add roughly 6,000 barrels per day to production.
The investment strengthens TotalEnergies SE (NYSE:TTE)'s position in one of Africa's key oil-producing markets and, perhaps more importantly, helps protect a major source of existing production. With around 450,000 barrels per day already coming from Angola, simply keeping output at current levels could continue to provide a meaningful contribution to the company's upstream cash flow. Any additional production from new discoveries and projects would offer further upside.
The current oil-price environment also works in TotalEnergies' favor. Brent crude recently climbed above $100 a barrel amid supply concerns and geopolitical tensions and is currently trading near this range. If prices remain elevated, projects designed to maintain or increase Angolan production could generate strong returns and make the company's investment more attractive.
There are also signs that TotalEnergies SE (NYSE:TTE) is doing more than just trying to slow production declines. Its recent Acacia-5 discovery in Block 17 could add around 6,000 barrels per day, while the company is expanding its exploration presence through new offshore blocks in the Lower Congo Basin. Angola's efforts to reform its oil sector and attract more exploration investment could also create a more favorable environment for TotalEnergies over the longer term.
#investment #offshore
The investment will go toward existing operations, new exploration, and projects aimed at replacing production from Angola's aging offshore fields. One of the biggest projects in the pipeline is the $6 billion Kaminho development, which is expected to start producing oil in 2028. TotalEnergies SE (NYSE:TTE) is also expanding its exploration efforts after signing agreements for two additional offshore blocks. On top of that, the company recently announced a new discovery in Block 17 that could add roughly 6,000 barrels per day to production.
The investment strengthens TotalEnergies SE (NYSE:TTE)'s position in one of Africa's key oil-producing markets and, perhaps more importantly, helps protect a major source of existing production. With around 450,000 barrels per day already coming from Angola, simply keeping output at current levels could continue to provide a meaningful contribution to the company's upstream cash flow. Any additional production from new discoveries and projects would offer further upside.
The current oil-price environment also works in TotalEnergies' favor. Brent crude recently climbed above $100 a barrel amid supply concerns and geopolitical tensions and is currently trading near this range. If prices remain elevated, projects designed to maintain or increase Angolan production could generate strong returns and make the company's investment more attractive.
There are also signs that TotalEnergies SE (NYSE:TTE) is doing more than just trying to slow production declines. Its recent Acacia-5 discovery in Block 17 could add around 6,000 barrels per day, while the company is expanding its exploration presence through new offshore blocks in the Lower Congo Basin. Angola's efforts to reform its oil sector and attract more exploration investment could also create a more favorable environment for TotalEnergies over the longer term.
#investment #offshore


10 days ago
Hub Group anticipates receiving a delisting notification from Nasdaq following delays in submitting its financial reports, which stemmed from an accounting error identified earlier this year. The company missed a Monday deadline to comply with Nasdaq's financial reporting requirements. It will ask for a hearing to keep its stock listing intact and plans to seek a further extension of the filing requirements.
The company said receipt of the letter doesn't mean shares will immediately stop trading, and that the hearing request will automatically stay a delisting for 15 calendar days. It will also ask for shares not to be delisted during the hearing process, which can take approximately 30 to 45 days to commence following the request.
"While there can be no ***** urances, the Company expects that the Company's Class A common stock will continue to trade on the Nasdaq Global Select Market during the hearing process," a Monday news release stated. "In addition, the Company expects to present to the Nasdaq Hearings Panel a compelling plan to regain full compliance with Nasdaq's continued listing requirements and to secure sufficient time to execute such plan."
Hub Group (NASDAQ: HUBG) announced in February that it had identified a $77-million understatement in purchased transportation expenses during the first three quarters of 2025, and that it was delaying fourth-quarter and full-year 2025 financial reporting. It said in May that "prematurely or incorrectly recognized" transactions were also discovered during 2023 and 2024, and that those periods, along with the first three quarters of 2025, would need to be restated.
It plans to complete the restatement process and file results for the outstanding periods during the fourth quarter. Shares of HUBG were off 6.2% in early trading on Monday compared to the S&P 500, which was down 0.6%.
#NASDAQ #shares #process
The company said receipt of the letter doesn't mean shares will immediately stop trading, and that the hearing request will automatically stay a delisting for 15 calendar days. It will also ask for shares not to be delisted during the hearing process, which can take approximately 30 to 45 days to commence following the request.
"While there can be no ***** urances, the Company expects that the Company's Class A common stock will continue to trade on the Nasdaq Global Select Market during the hearing process," a Monday news release stated. "In addition, the Company expects to present to the Nasdaq Hearings Panel a compelling plan to regain full compliance with Nasdaq's continued listing requirements and to secure sufficient time to execute such plan."
Hub Group (NASDAQ: HUBG) announced in February that it had identified a $77-million understatement in purchased transportation expenses during the first three quarters of 2025, and that it was delaying fourth-quarter and full-year 2025 financial reporting. It said in May that "prematurely or incorrectly recognized" transactions were also discovered during 2023 and 2024, and that those periods, along with the first three quarters of 2025, would need to be restated.
It plans to complete the restatement process and file results for the outstanding periods during the fourth quarter. Shares of HUBG were off 6.2% in early trading on Monday compared to the S&P 500, which was down 0.6%.
#NASDAQ #shares #process


10 days ago
Dennis W. Liu, Chief Accounting Officer of Clear Secure, Inc. (NYSE:YOU), disposed of 6,059 shares of Class A Common Stock between September 1, 2026, and September 3, 2026, as disclosed in a recent SEC Form 4 filing.
Metric
Value
Transaction value
~$263,500
#september #dennis #secure
Metric
Value
Transaction value
~$263,500
#september #dennis #secure

10 days ago
Josh Allen's dramatic winning drive sends strong message to rest of AFC originally appeared on The Sporting News. Add The Sporting News as a Preferred Source by clicking here.
The Buffalo Bills needed Josh Allen to rescue them one more time. Their franchise quarterback delivered.
Allen directed a 96-yard touchdown drive late in the fourth quarter to lift Buffalo to a 36-31 victory over the Houston Texans. He completed the comeback by finding Joshua Palmer for a 34-yard touchdown with 1:36 remaining.
Houston still had an opportunity to answer, but Greg Rousseau forced a C.J. Stroud fumble near the Buffalo goal line to secure the victory. It was an early-season reminder that defeating the Bills requires more than taking a late lead. Opponents must finish the job without giving Allen another meaningful possession.
Allen completed 20 of 29 passes for 334 yards and two touchdowns. He also ran for two scores, accounting for four of Buffalo's touchdowns in the win. His final touchdown throw was made possible by a missed opportunity from the Texans.
#drive #yard
The Buffalo Bills needed Josh Allen to rescue them one more time. Their franchise quarterback delivered.
Allen directed a 96-yard touchdown drive late in the fourth quarter to lift Buffalo to a 36-31 victory over the Houston Texans. He completed the comeback by finding Joshua Palmer for a 34-yard touchdown with 1:36 remaining.
Houston still had an opportunity to answer, but Greg Rousseau forced a C.J. Stroud fumble near the Buffalo goal line to secure the victory. It was an early-season reminder that defeating the Bills requires more than taking a late lead. Opponents must finish the job without giving Allen another meaningful possession.
Allen completed 20 of 29 passes for 334 yards and two touchdowns. He also ran for two scores, accounting for four of Buffalo's touchdowns in the win. His final touchdown throw was made possible by a missed opportunity from the Texans.
#drive #yard