4 days ago
On September 9, 2026, Signet Jewelers Limited (NYSE:SIG) reported second-quarter net profit of more than $52 million, reversing a net loss of over $9 million a year earlier, with adjusted earnings per share of $2.19 beating ***** yst estimates of $1.72 by a wide margin. It sent shares up as much as 24% in trading.
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited


4 days ago
On September 9, 2026, Reuters reported that Alphabet Inc. (NASDAQ:GOOGL)'s Google will invest at least €13 billion, or about $15.1 billion, in AI infrastructure in Finland over the next two years, its biggest European investment, including three new data centers and a 22-year deal for up to 50% of the output of one of Finland's two nuclear power plants. The agreement with Finnish utility Fortum is Google's first nuclear energy deal outside the United States, and Fortum's stock jumped as much as 15.5% on the news, its biggest gain in Europe that day.
Finland gives Alphabet Inc. (NASDAQ:GOOGL) a potentially more cost-efficient location for its expanding AI infrastructure. Google plans to invest at least €13 billion ($15.1 billion) in three new data centers and related infrastructure in Finland during 2027 and 2028. The country's cold climate can reduce the need for energy-intensive cooling. The investment will also help grid improvements, clean-energy projects and battery storage.
The 22-year nuclear power agreement gives Google greater control over a critical input for AI infrastructure. Google will purchase up to 50% of the electricity generated by Finland's Loviisa nuclear plant, providing a long-term source of low-carbon power for its data-center operations. The agreement also gives Fortum greater economic certainty to extend and upgrade the plant through 2050. Google and Fortum plan to explore more nuclear and renewable projects.
Alphabet has strong demand drivers that can justify investment in AI capacity. The firm has increased its 2026 global capital investment target to $195 billion-$205 billion as it seeks to capture growing AI computing demand. Google is using the additional infrastructure to support Gemini, Search, Maps, and YouTube. It gives Alphabet multiple major products through which it can monetize greater AI capacity over time.
The Finland project adds another major commitment to Alphabet Inc. (NASDAQ:GOOGL)'s already enormous AI spending program. Alphabet expects to spend $195 billion-$205 billion on capital investment globally in 2026. The Finnish project will require at least another €13 billion during 2027 and 2028. Investors need Alphabet to make enough incremental revenue and cash flow from AI services to justify an infrastructure buildout that is rapidly increasing the company's capital requirements.
#billion #Google #investment #googl
Finland gives Alphabet Inc. (NASDAQ:GOOGL) a potentially more cost-efficient location for its expanding AI infrastructure. Google plans to invest at least €13 billion ($15.1 billion) in three new data centers and related infrastructure in Finland during 2027 and 2028. The country's cold climate can reduce the need for energy-intensive cooling. The investment will also help grid improvements, clean-energy projects and battery storage.
The 22-year nuclear power agreement gives Google greater control over a critical input for AI infrastructure. Google will purchase up to 50% of the electricity generated by Finland's Loviisa nuclear plant, providing a long-term source of low-carbon power for its data-center operations. The agreement also gives Fortum greater economic certainty to extend and upgrade the plant through 2050. Google and Fortum plan to explore more nuclear and renewable projects.
Alphabet has strong demand drivers that can justify investment in AI capacity. The firm has increased its 2026 global capital investment target to $195 billion-$205 billion as it seeks to capture growing AI computing demand. Google is using the additional infrastructure to support Gemini, Search, Maps, and YouTube. It gives Alphabet multiple major products through which it can monetize greater AI capacity over time.
The Finland project adds another major commitment to Alphabet Inc. (NASDAQ:GOOGL)'s already enormous AI spending program. Alphabet expects to spend $195 billion-$205 billion on capital investment globally in 2026. The Finnish project will require at least another €13 billion during 2027 and 2028. Investors need Alphabet to make enough incremental revenue and cash flow from AI services to justify an infrastructure buildout that is rapidly increasing the company's capital requirements.
#billion #Google #investment #googl

4 days ago
On September 9, 2026, Reuters reported that CEO Brian Niccol's first two years as Starbucks Corporation (NASDAQ:SBUX) CEO have succeeded in bringing customers back to the coffee chain. Comparable sales rose 7.9% in the fiscal third quarter for a fourth straight quarter of improvement, but his "Back to Starbucks" restructuring has raised costs and squeezed margins along the way. Global operating margin has fallen to 12.9% from 15.8% two years earlier. Niccol, who marks his second anniversary in the role, now faces pressure to convert the sales recovery into the sustainable profit growth investors are demanding.
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#
5 days ago
Definium Therapeutics, Inc. (NASDAQ:DFTX) has now delivered a third consecutive positive Phase 3 readout for its LSD-based medication, the second in generalized anxiety disorder. The result puts the company on a viable route toward a potential FDA approval of an LSD-based treatment for generalized anxiety disorder, and considering how closely psychedelic stocks have historically traded on each other's data, the reading carries far more weight than Definium's own ticker.
On September 14, Definium Therapeutics, Inc. (NASDAQ:DFTX) announced that its drug DT120, an orally disintegrating tablet formulation of LSD, was successful in Panorama, the company's second late-stage anxiety trial. Over 12 weeks, patients who received a 100-microgram dose experienced a 9.8-point decline on the Hamilton Anxiety Rating Scale, a typical clinical measure, compared to a 4.7-point drop with placebo.
The resulting 5.1-point placebo-adjusted improvement is similar to what the company's first pivotal anxiety trial, Voyage, showed back in August: an 11.6-point improvement versus 6.2 for placebo, a 5.4-point separation that Jefferies called one of the strongest placebo-adjusted efficacy results ever seen in generalized anxiety disorder, and that Stifel simply described as "a clean win."
Psychedelic equities have a history of trading as a group rather than as individual names, and this tendency applies both ways. In February 2026, when Compass Pathways, the sector's other clinical leader developing a psilocybin-based drug for treatment-resistant depression, reported positive late-stage data, shares of Definium Therapeutics, Inc. (NASDAQ:DFTX), Atai Beckley, GH Research, and Helus Pharma all rose, some by double digits.
That correlation is significant here because Definium's win is an independent validation of the broader therapeutic argument on which Compass and others are betting: a single dose of a classic psychedelic, administered in a controlled clinical setting, can produce lasting improvements in serious mental health conditions via pathways different from existing SSRIs and other standard-of-care drugs.
#definium #placebo
On September 14, Definium Therapeutics, Inc. (NASDAQ:DFTX) announced that its drug DT120, an orally disintegrating tablet formulation of LSD, was successful in Panorama, the company's second late-stage anxiety trial. Over 12 weeks, patients who received a 100-microgram dose experienced a 9.8-point decline on the Hamilton Anxiety Rating Scale, a typical clinical measure, compared to a 4.7-point drop with placebo.
The resulting 5.1-point placebo-adjusted improvement is similar to what the company's first pivotal anxiety trial, Voyage, showed back in August: an 11.6-point improvement versus 6.2 for placebo, a 5.4-point separation that Jefferies called one of the strongest placebo-adjusted efficacy results ever seen in generalized anxiety disorder, and that Stifel simply described as "a clean win."
Psychedelic equities have a history of trading as a group rather than as individual names, and this tendency applies both ways. In February 2026, when Compass Pathways, the sector's other clinical leader developing a psilocybin-based drug for treatment-resistant depression, reported positive late-stage data, shares of Definium Therapeutics, Inc. (NASDAQ:DFTX), Atai Beckley, GH Research, and Helus Pharma all rose, some by double digits.
That correlation is significant here because Definium's win is an independent validation of the broader therapeutic argument on which Compass and others are betting: a single dose of a classic psychedelic, administered in a controlled clinical setting, can produce lasting improvements in serious mental health conditions via pathways different from existing SSRIs and other standard-of-care drugs.
#definium #placebo

6 days ago
On September 15, Needham ***** yst James Ricchiuti lifted the firm's price target on Teledyne Technologies Incorporated (NYSE:TDY) to $760 from $750, and reiterated a Buy rating. The revised price target reflected an upside of 27% from the close of the note.
According to TipRanks, the ***** yst told investors that the company was well placed to gain from a broadening short cycle recovery and opportunities in modern defense applications. Needham further added that the stock offers a 2.6-to-1 risk/reward skew at current levels.
The adjustment is largely in line with the broader ***** yst community. As of the close on September 16, TDY is a Moderate Buy based on the consensus of 10 ***** ysts. It has a one-year average share price target of $758.20, representing an upside of 26%.
Needham noted 'broadening' improvements in the company's short cycle businesses, which suggests that momentum is spreading across product lines, rather than being limited to any one particular segment.
During the Q2 earnings call, the management noted that short-cycle commercial markets were beginning to show growth inflections after recent headwinds and lifted its short-cycle portfolio's growth outlook to mid-single-digits for the year, up from earlier estimates of flat to low-single-digit growth.
#cycle #september
According to TipRanks, the ***** yst told investors that the company was well placed to gain from a broadening short cycle recovery and opportunities in modern defense applications. Needham further added that the stock offers a 2.6-to-1 risk/reward skew at current levels.
The adjustment is largely in line with the broader ***** yst community. As of the close on September 16, TDY is a Moderate Buy based on the consensus of 10 ***** ysts. It has a one-year average share price target of $758.20, representing an upside of 26%.
Needham noted 'broadening' improvements in the company's short cycle businesses, which suggests that momentum is spreading across product lines, rather than being limited to any one particular segment.
During the Q2 earnings call, the management noted that short-cycle commercial markets were beginning to show growth inflections after recent headwinds and lifted its short-cycle portfolio's growth outlook to mid-single-digits for the year, up from earlier estimates of flat to low-single-digit growth.
#cycle #september


6 days ago
On September 9, 2026, Reuters reported that GE Aerospace (NYSE:GE) agreed to buy castings maker Consolidated Precision Products for $11.75 billion. It is its largest acquisition since becoming a standalone company in 2024, to secure the supply of the precision metal turbine-blade components that have been a persistent bottleneck across the jet engine industry. CPP is the world's third-largest maker of these parts. CEO Larry Culp called the capacity "mission-critical" as the company works through a backlog stretching into the next decade.
GE Aerospace (NYSE:GE) can use the acquisition to convert its massive backlog into revenue faster. The company's backlog exceeded $210 billion after its second-quarter results. It includes roughly $170 billion in commercial services and more than $30 billion in defense. The $11.75 billion acquisition of Consolidated Precision Products directly targets one of the supply-chain bottlenecks that has limited GE's ability to increase engine production. CPP supplies about one-quarter of GE's casting needs. It gives GE greater control over a critical manufacturing process and could help it meet deliveries tied to its long-term backlog.
Bringing CPP in-house could improve GE's production economics while reducing supplier dependence. Spare-parts delinquencies jumped 20% sequentially in the second quarter. It shows the ongoing operational impact of supply constraints. GE plans to apply its Flight Deck lean operating model at CPP to improve factory yields and machine utilization and reduce scrap and rework. The company expects the acquisition to generate about $200 million in net synergies and achieve double-digit return on invested capital by the fifth year. It gives investors a measurable path to stronger returns from the deal.
The acquisition makes GE's position solid in the next generation of engines. GE expects demand for airfoils to increase more than 30% by 2030 from 2026 levels. CPP's casting expertise could help GE bring new airfoil designs into production faster. The business also expects CPP to make roughly $2 billion in revenue in 2027. That combination gives investors a potential path to higher production capacity, faster technology development, and stronger long-term participation in commercial and defense aerospace demand.
GE Aerospace (NYSE:GE) must justify a nearly $12 billion investment, and investors already ******* ign a premium valuation to the stock. GE Aerospace trades at roughly 46 times forward earnings. It leaves investors with limited tolerance for execution problems or weaker-than-expected returns. The company will fund $7 billion of the acquisition with cash and finance the remainder with new debt. So GE needs CPP's earnings and operating improvements to make sufficient returns to support the purchase price and protect shareholder value.
#billion #backlog #supply
GE Aerospace (NYSE:GE) can use the acquisition to convert its massive backlog into revenue faster. The company's backlog exceeded $210 billion after its second-quarter results. It includes roughly $170 billion in commercial services and more than $30 billion in defense. The $11.75 billion acquisition of Consolidated Precision Products directly targets one of the supply-chain bottlenecks that has limited GE's ability to increase engine production. CPP supplies about one-quarter of GE's casting needs. It gives GE greater control over a critical manufacturing process and could help it meet deliveries tied to its long-term backlog.
Bringing CPP in-house could improve GE's production economics while reducing supplier dependence. Spare-parts delinquencies jumped 20% sequentially in the second quarter. It shows the ongoing operational impact of supply constraints. GE plans to apply its Flight Deck lean operating model at CPP to improve factory yields and machine utilization and reduce scrap and rework. The company expects the acquisition to generate about $200 million in net synergies and achieve double-digit return on invested capital by the fifth year. It gives investors a measurable path to stronger returns from the deal.
The acquisition makes GE's position solid in the next generation of engines. GE expects demand for airfoils to increase more than 30% by 2030 from 2026 levels. CPP's casting expertise could help GE bring new airfoil designs into production faster. The business also expects CPP to make roughly $2 billion in revenue in 2027. That combination gives investors a potential path to higher production capacity, faster technology development, and stronger long-term participation in commercial and defense aerospace demand.
GE Aerospace (NYSE:GE) must justify a nearly $12 billion investment, and investors already ******* ign a premium valuation to the stock. GE Aerospace trades at roughly 46 times forward earnings. It leaves investors with limited tolerance for execution problems or weaker-than-expected returns. The company will fund $7 billion of the acquisition with cash and finance the remainder with new debt. So GE needs CPP's earnings and operating improvements to make sufficient returns to support the purchase price and protect shareholder value.
#billion #backlog #supply

6 days ago
Hub Group, Inc. (NASDAQ:HUBG) disclosed on September 14 that preliminary, unaudited first-half 2026 revenue was expected to reach $1.7 billion to $1.8 billion, near management's expectations. Yet management anticipated an operating loss before one-time charges. This non-GAAP presentation excludes those charges, but neither the loss nor the exclusions were quantified.
Hub Group, Inc. (NASDAQ:HUBG) identified higher fuel, rail, and drayage costs, excess warehouse capacity, and accounting-review and restatement expenses. The central issue is whether pricing and efficiency improvements can restore profitability on the revenue already moving through the business.
Hub Group, Inc. (NASDAQ:HUBG) began implementing rate increases in the third quarter, after transportation costs had pressured first-half results. Relatively stable intermodal volume trends suggest an existing customer base on which better pricing could improve margins. If increases hold without significant volume losses, revenue could become more profitable without requiring a broad freight recovery.
Hub Group, Inc. (NASDAQ:HUBG) also launched additional efficiency initiatives in the second quarter, including warehouse consolidation and improvements in driver and warehouse-worker productivity. These actions address specific weaknesses: underused ***** e spreads fixed costs across fewer orders, while low productivity raises the cost of each shipment or handling task. Better utilization could reinforce the benefit of higher rates.
Hub Group, Inc. (NASDAQ:HUBG) is also targeting order-to-cash processes, which cover the steps from taking orders through billing and collection. Improvements could reduce administrative friction and accelerate cash collection. That would support liquidity while operational changes take effect, although faster collections alone would not repair an operating loss.
#improvements #better
Hub Group, Inc. (NASDAQ:HUBG) identified higher fuel, rail, and drayage costs, excess warehouse capacity, and accounting-review and restatement expenses. The central issue is whether pricing and efficiency improvements can restore profitability on the revenue already moving through the business.
Hub Group, Inc. (NASDAQ:HUBG) began implementing rate increases in the third quarter, after transportation costs had pressured first-half results. Relatively stable intermodal volume trends suggest an existing customer base on which better pricing could improve margins. If increases hold without significant volume losses, revenue could become more profitable without requiring a broad freight recovery.
Hub Group, Inc. (NASDAQ:HUBG) also launched additional efficiency initiatives in the second quarter, including warehouse consolidation and improvements in driver and warehouse-worker productivity. These actions address specific weaknesses: underused ***** e spreads fixed costs across fewer orders, while low productivity raises the cost of each shipment or handling task. Better utilization could reinforce the benefit of higher rates.
Hub Group, Inc. (NASDAQ:HUBG) is also targeting order-to-cash processes, which cover the steps from taking orders through billing and collection. Improvements could reduce administrative friction and accelerate cash collection. That would support liquidity while operational changes take effect, although faster collections alone would not repair an operating loss.
#improvements #better


6 days ago
Kestra Medical Technologies, Ltd. (NASDAQ:KMTS) reported on September 14 that fiscal first-quarter 2027 revenue increased 60% to $31.0 million. Gross margin reached 56.5%, up from 45.7%, for the quarter ended July 31, 2026.
Management raised fiscal 2027 revenue guidance to $141 million from $137 million, implying 48% annual growth. The outlook strengthens the commercial story, but the expanding organization still consumes substantially more than the business generates in gross profit.
Kestra Medical Technologies, Ltd. (NASDAQ:KMTS) attributed revenue growth to wearable cardioverter defibrillator market expansion, competitive share gains, new sales territories, a higher proportion of in-network patients and improvements in revenue cycle management.
These drivers suggest several ways to expand: reach more patients, improve reimbursement outcomes, and collect revenue more effectively. Their investment value depends on sustaining growth without requiring a matching increase in support costs.
Gross profit nearly doubled to $17.5 million from $8.9 million. Management attributed the margin improvement to higher volume, the in-network patient mix, and cost initiatives. The company is retaining more of each revenue dollar to fund selling expenses and product development.
#million #kestra #kmts
Management raised fiscal 2027 revenue guidance to $141 million from $137 million, implying 48% annual growth. The outlook strengthens the commercial story, but the expanding organization still consumes substantially more than the business generates in gross profit.
Kestra Medical Technologies, Ltd. (NASDAQ:KMTS) attributed revenue growth to wearable cardioverter defibrillator market expansion, competitive share gains, new sales territories, a higher proportion of in-network patients and improvements in revenue cycle management.
These drivers suggest several ways to expand: reach more patients, improve reimbursement outcomes, and collect revenue more effectively. Their investment value depends on sustaining growth without requiring a matching increase in support costs.
Gross profit nearly doubled to $17.5 million from $8.9 million. Management attributed the margin improvement to higher volume, the in-network patient mix, and cost initiatives. The company is retaining more of each revenue dollar to fund selling expenses and product development.
#million #kestra #kmts

7 days ago
Seagate Technology Holdings plc (NASDAQ:STX) announced on September 9 that its subsidiary, Seagate HDD Cayman, completed the redemption and exchange of its remaining 3.50% exchangeable senior notes due 2028 on September 8. Approximately $150.7 million of principal was retired through a settlement involving approximately $150.97 million in cash and 1,647,862 ordinary shares.
For notes submitted for exchange, principal was paid in cash, and the exchange obligation above principal was settled in shares, with cash for fractional shares where applicable. The share delivery therefore satisfied an existing contractual obligation.
Seagate Technology Holdings plc (NASDAQ:STX) has removed a 2028 maturity and the remaining settlement uncertainty attached to this instrument. Based on the approximately $150.7 million principal balance and 3.50% coupon, the transaction eliminates roughly $5.3 million of annual stated interest. That is a calculated annualized saving before taxes and any interest income lost on the cash used.
Recent cash generation supports the ability to absorb the payment. As of July 3, 2026, Seagate Technology Holdings plc (NASDAQ:STX) reported $1.704 billion in cash and cash equivalents. Fiscal fourth-quarter free cash flow was $1.118 billion. This company-defined non-GAAP measure is operating cash flow less acquisitions of property, equipment, and leasehold improvements.
The settlement cash payment equals approximately 8.9% of that reported cash balance. Although the July figure predates settlement, it provides a useful measure of the transaction's scale.
#technology #million #exchange
For notes submitted for exchange, principal was paid in cash, and the exchange obligation above principal was settled in shares, with cash for fractional shares where applicable. The share delivery therefore satisfied an existing contractual obligation.
Seagate Technology Holdings plc (NASDAQ:STX) has removed a 2028 maturity and the remaining settlement uncertainty attached to this instrument. Based on the approximately $150.7 million principal balance and 3.50% coupon, the transaction eliminates roughly $5.3 million of annual stated interest. That is a calculated annualized saving before taxes and any interest income lost on the cash used.
Recent cash generation supports the ability to absorb the payment. As of July 3, 2026, Seagate Technology Holdings plc (NASDAQ:STX) reported $1.704 billion in cash and cash equivalents. Fiscal fourth-quarter free cash flow was $1.118 billion. This company-defined non-GAAP measure is operating cash flow less acquisitions of property, equipment, and leasehold improvements.
The settlement cash payment equals approximately 8.9% of that reported cash balance. Although the July figure predates settlement, it provides a useful measure of the transaction's scale.
#technology #million #exchange

7 days ago
Alcoa Corporation (NYSE:AA) priced $2.6 billion of acquisition financing on September 9, 2026, through two wholly owned subsidiaries. Alumina Pty Ltd will issue $1.5 billion of 6.625% notes due 2034, while Alcoa Nederland Holding B.V. will issue $1.1 billion of 6.875% notes due 2036. Alcoa Corporation (NYSE:AA) and certain subsidiaries will guarantee the notes on a senior unsecured basis.
The tranches imply annual coupons of $99.375 million and $75.625 million, respectively, totaling exactly $175 million. Settlement is expected on September 23. Net proceeds and cash on hand would fund the approximately $3.1 billion cash portion of the South32 Limited (ASX:S32) ****** et acquisition, plus related fees and expenses.
For Alcoa Corporation (NYSE:AA), successful settlement would secure longer-dated funding and allow termination of the remaining 364-day bridge commitments. Maturities in 2034 and 2036 give management time to integrate the ****** ets before principal comes due.
The operating opportunity lies in linking additional bauxite resources, alumina refining and aluminum production. Better coordination could strengthen feedstock security and improve purchasing, logistics and plant economics. Acquired earnings and operating improvements could produce recurring cash to service the debt while funding reinvestment.
Fixed coupons also make the interest burden predictable. Strong ****** et performance could support debt reduction and give shareholders a growing share of incremental cash generation.
#notes #september
The tranches imply annual coupons of $99.375 million and $75.625 million, respectively, totaling exactly $175 million. Settlement is expected on September 23. Net proceeds and cash on hand would fund the approximately $3.1 billion cash portion of the South32 Limited (ASX:S32) ****** et acquisition, plus related fees and expenses.
For Alcoa Corporation (NYSE:AA), successful settlement would secure longer-dated funding and allow termination of the remaining 364-day bridge commitments. Maturities in 2034 and 2036 give management time to integrate the ****** ets before principal comes due.
The operating opportunity lies in linking additional bauxite resources, alumina refining and aluminum production. Better coordination could strengthen feedstock security and improve purchasing, logistics and plant economics. Acquired earnings and operating improvements could produce recurring cash to service the debt while funding reinvestment.
Fixed coupons also make the interest burden predictable. Strong ****** et performance could support debt reduction and give shareholders a growing share of incremental cash generation.
#notes #september
7 days ago
This story was originally published on Construction Dive. To receive daily news and insights, subscribe to our free daily Construction Dive newsletter.
The combined application of six artificial intelligence-enabled levers can cut project costs by 17% to 20% while trimming schedules by 22% to 25%, according to an ***** ysis of a sample, 180,000-square-foot multifamily project by Suffolk Construction and the Massachusetts Institute of Technology.
Suffolk and MIT published a white paper that tags six interrelated construction processes where AI can spur productivity gains.
The study's authors cite improvements in AI models, the tech's ability to sift through mounds of construction data and economic pressures to adopt AI as the driving forces behind the industry's increasing focus on AI.
The paper, ***** led "Construction in the Age of AI," defines the six key levers as:
#suffolk #published #levers #institute
The combined application of six artificial intelligence-enabled levers can cut project costs by 17% to 20% while trimming schedules by 22% to 25%, according to an ***** ysis of a sample, 180,000-square-foot multifamily project by Suffolk Construction and the Massachusetts Institute of Technology.
Suffolk and MIT published a white paper that tags six interrelated construction processes where AI can spur productivity gains.
The study's authors cite improvements in AI models, the tech's ability to sift through mounds of construction data and economic pressures to adopt AI as the driving forces behind the industry's increasing focus on AI.
The paper, ***** led "Construction in the Age of AI," defines the six key levers as:
#suffolk #published #levers #institute
8 days ago
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
8 days ago
ASML Holding N.V. (NASDAQ:ASML) is examining ways to produce more than 110 EUV lithography systems in 2028, according to JPMorgan ***** ysts following a meeting with CFO Roger Dassen. The company is already nearly sold out for 2027 and expects to produce at least 80 EUV systems that year, meaning output above 110 in 2028 would represent at least a 37.5% increase from the 2027 level. JPMorgan said the main constraint has shifted toward ***** embly speed rather than the availability of critical components, suggesting ASML believes additional capacity can be unlocked through manufacturing and ***** embly improvements.
The potential increase is being driven primarily by AI-related demand. ASML's existing EUV machines, which cost roughly $200 million each, are essential for manufacturing leading-edge AI processors, while customers including TSMC, Samsung, SK Hynix and Intel are expanding advanced-chip capacity. Reuters reported separately that virtually all of ASML's EUV production capacity is booked through 2027, while the company has begun construction of a new Eindhoven facility designed to accelerate tool ***** embly and eventually accommodate up to 20,000 workers.
The strongest bullish implication is that ASML Holding N.V. (NASDAQ:ASML) may be able to convert exceptionally strong demand into higher unit volumes rather than simply relying on price increases. Moving from at least 80 EUV systems in 2027 to more than 110 in 2028 would materially expand the number of high-value systems ASML can monetize. This comes after the company already raised its 2026 revenue outlook to €43 billion–€45 billion, compared with its previous €36 billion–€40 billion range, while targeting a 54%–56% gross margin. Reuters also reported that second-quarter revenue reached €9.3 billion with a 54% gross margin, demonstrating that stronger AI-driven demand is already translating into financial performance.
The longer-term competitive position is particularly favorable because ASML Holding N.V. (NASDAQ:ASML) effectively has no commercial competitor in EUV. JPMorgan estimates that ASML held 94% of the overall lithography market in 2025, while Reuters describes the company as having maintained a monopoly in EUV since the late 2010s. At the same time, customers are committing to ASML's next-generation High-NA technology: the machines cost approximately $400 million, can print features about 40% smaller than existing EUV systems, and TSMC, Samsung, and SK Hynix have all established plans for production adoption. If AI chip demand remains strong enough to support both higher low-NA volumes and eventual High-NA adoption, ASML could see a multi-year increase in system shipments, revenue, and potentially cash generation while strengthening its already exceptional competitive moat.
#company
The potential increase is being driven primarily by AI-related demand. ASML's existing EUV machines, which cost roughly $200 million each, are essential for manufacturing leading-edge AI processors, while customers including TSMC, Samsung, SK Hynix and Intel are expanding advanced-chip capacity. Reuters reported separately that virtually all of ASML's EUV production capacity is booked through 2027, while the company has begun construction of a new Eindhoven facility designed to accelerate tool ***** embly and eventually accommodate up to 20,000 workers.
The strongest bullish implication is that ASML Holding N.V. (NASDAQ:ASML) may be able to convert exceptionally strong demand into higher unit volumes rather than simply relying on price increases. Moving from at least 80 EUV systems in 2027 to more than 110 in 2028 would materially expand the number of high-value systems ASML can monetize. This comes after the company already raised its 2026 revenue outlook to €43 billion–€45 billion, compared with its previous €36 billion–€40 billion range, while targeting a 54%–56% gross margin. Reuters also reported that second-quarter revenue reached €9.3 billion with a 54% gross margin, demonstrating that stronger AI-driven demand is already translating into financial performance.
The longer-term competitive position is particularly favorable because ASML Holding N.V. (NASDAQ:ASML) effectively has no commercial competitor in EUV. JPMorgan estimates that ASML held 94% of the overall lithography market in 2025, while Reuters describes the company as having maintained a monopoly in EUV since the late 2010s. At the same time, customers are committing to ASML's next-generation High-NA technology: the machines cost approximately $400 million, can print features about 40% smaller than existing EUV systems, and TSMC, Samsung, and SK Hynix have all established plans for production adoption. If AI chip demand remains strong enough to support both higher low-NA volumes and eventual High-NA adoption, ASML could see a multi-year increase in system shipments, revenue, and potentially cash generation while strengthening its already exceptional competitive moat.
#company

8 days ago
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of **** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#NYSE #johnson
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of **** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#NYSE #johnson
8 days ago
The most talked about and market moving research calls around Wall Street are now in one place. Here are today's research calls that investors need to know, as compiled by The Fly.
Top 5 Upgrades:
Wells Fargo upgraded Ulta Beauty (ULTA) to Equal Weight from Underweight with a price target of $525, up from $450, after meeting with management. The firm says the company is navigating industry headwinds better than expected.
Oppenheimer upgraded Etsy (ETSY) to Outperform from Perform with a $90 price target. The firm cites the company's AI search benefits, product improvements, and app engagement for the upgrade.
Berenberg upgraded Eli Lilly (LLY) to Buy from Hold with a price target of $1,400, up from $1,220. The firm says its 2026 return on investment **** ysis confirms Eli Lilly's "strong track record of delivering best-in-class returns on investment."
Bernstein upgraded Agilon Health (AGL) to Outperform from Market Perform with a price target of $125, up from $86. The company is undergoing a turnaround focused on risk-taking discipline and incremental medical cost improvements, the firm tells investors in a research note.
#firm #outperform #perform
Top 5 Upgrades:
Wells Fargo upgraded Ulta Beauty (ULTA) to Equal Weight from Underweight with a price target of $525, up from $450, after meeting with management. The firm says the company is navigating industry headwinds better than expected.
Oppenheimer upgraded Etsy (ETSY) to Outperform from Perform with a $90 price target. The firm cites the company's AI search benefits, product improvements, and app engagement for the upgrade.
Berenberg upgraded Eli Lilly (LLY) to Buy from Hold with a price target of $1,400, up from $1,220. The firm says its 2026 return on investment **** ysis confirms Eli Lilly's "strong track record of delivering best-in-class returns on investment."
Bernstein upgraded Agilon Health (AGL) to Outperform from Market Perform with a price target of $125, up from $86. The company is undergoing a turnaround focused on risk-taking discipline and incremental medical cost improvements, the firm tells investors in a research note.
#firm #outperform #perform

8 days ago
Anthropic is moving forward with plans for an initial public offering that could value the company at $2 trillion, with signs pointing to the listing remaining on track, according to Bloomberg. Nasdaq has been selected as the venue for the listing, and Nvidia is reportedly weighing a contribution of around $10 billion to the offering.
Bloomberg reports Anthropic's annualized revenue at $65 billion, with the company's margins underpinned by investor confidence in where AI capabilities are headed rather than by today's cash generation.
The IPO comes as Anthropic chief executive officer Dario Amodei has published an essay calling on AI companies to manage the pace of frontier model development. Amodei's essay calls on firms "must slow the pace" of capability improvements, yet frames the goal as "a balanced rate" of progress, with the ****** urance that "progress will still seem fast," Bloomberg notes. When CFO Krishna Rao shared the piece on LinkedIn, his commentary centered on the themes of "pacing" and "common standards."
Anthropic is preparing to tell IPO investors that its potential revenue opportunity exceeds $30 trillion, according to The Wall Street Journal. The company more than doubled its revenue to $11.6 billion in the second quarter and could seek to raise as much as $100 billion in its offering — both figures that would surpass what ****** eX achieved when it went public in June at a $1.77 trillion valuation.
Investors have projected that Anthropic's annualized revenue will reach between $100 billion and $120 billion before year's end, representing more than tenfold growth from the $47 billion annualized revenue the company reported in May, according to the Financial Times as cited in earlier reporting. Morgan Stanley, Goldman Sachs, and JPMorgan are leading the offering. The company filed paperwork with the Securities and Exchange Commission in June.
#billion #bloomberg #trillion #according
Bloomberg reports Anthropic's annualized revenue at $65 billion, with the company's margins underpinned by investor confidence in where AI capabilities are headed rather than by today's cash generation.
The IPO comes as Anthropic chief executive officer Dario Amodei has published an essay calling on AI companies to manage the pace of frontier model development. Amodei's essay calls on firms "must slow the pace" of capability improvements, yet frames the goal as "a balanced rate" of progress, with the ****** urance that "progress will still seem fast," Bloomberg notes. When CFO Krishna Rao shared the piece on LinkedIn, his commentary centered on the themes of "pacing" and "common standards."
Anthropic is preparing to tell IPO investors that its potential revenue opportunity exceeds $30 trillion, according to The Wall Street Journal. The company more than doubled its revenue to $11.6 billion in the second quarter and could seek to raise as much as $100 billion in its offering — both figures that would surpass what ****** eX achieved when it went public in June at a $1.77 trillion valuation.
Investors have projected that Anthropic's annualized revenue will reach between $100 billion and $120 billion before year's end, representing more than tenfold growth from the $47 billion annualized revenue the company reported in May, according to the Financial Times as cited in earlier reporting. Morgan Stanley, Goldman Sachs, and JPMorgan are leading the offering. The company filed paperwork with the Securities and Exchange Commission in June.
#billion #bloomberg #trillion #according

10 days ago
On August 6, The RealReal (NASDAQ:REAL) reported second quarter results that beat its own outlook and pushed the resale luxury marketplace to raise its full year guidance. Gross merchandise value hit an all time high of $617 million, up 22% from a year earlier, and management pointed to four straight quarters of GMV growth above 20%. But a wider net loss sitting next to those record numbers complicates the story for anyone weighing the stock today.
The headline number is GMV of $617 million for the quarter ended June 30, up 22% year over year, with total revenue climbing 17% to $193 million. Consignment revenue grew 15% while Direct Revenue, the company's owned inventory channel, grew 26%, showing both sides of the business contributing to the acceleration. Profitability moved in the same direction. Gross margin reached 74.4%, up 10 basis points from a year ago, and Adjusted EBITDA margin jumped to 7%, a 290 basis point improvement that management called nearly 300 basis points of expansion.
The buyer base backs up the growth story rather than just the pricing. Trailing twelve-month active buyers rose 11% to 1,107,000, and average order value climbed 13% to $659, meaning existing shoppers are spending meaningfully more per transaction, not just showing up more often. That combination gave management enough confidence to raise full-year guidance to $2.54 billion to $2.57 billion in GMV and $788 million to $797 million in total revenue, alongside third-quarter Adjusted EBITDA guidance of $13.5 million to $14.5 million.
Despite the operating improvements, GAAP losses widened. Net loss came in at $27 million, or 14.1% of total revenue, compared to $11 million, or 6.9% of total revenue, a year earlier. GAAP basic net loss per share was $0.23 versus $0.10 in the prior year period, and diluted net loss per share was $0.23 versus $0.13. Much of that swing traces to a $(18.6) million non-cash adjustment tied to the change in fair value of warrant liability, a factor unrelated to how the underlying business performed. On a non-GAAP basis, basic and diluted net loss per share actually narrowed to $0.01 from $0.06, underscoring how much of the GAAP gap is accounting rather than operations.
There is also a transparency wrinkle in the guidance itself. The RealReal said it has not reconciled its forward-looking Adjusted EBITDA figures to GAAP net income or loss, citing components like payroll tax expense on employee stock transactions that it cannot predict with reasonable certainty. That leaves investors trusting a non-GAAP target without the usual bridge back to the bottom line.
#adjusted
The headline number is GMV of $617 million for the quarter ended June 30, up 22% year over year, with total revenue climbing 17% to $193 million. Consignment revenue grew 15% while Direct Revenue, the company's owned inventory channel, grew 26%, showing both sides of the business contributing to the acceleration. Profitability moved in the same direction. Gross margin reached 74.4%, up 10 basis points from a year ago, and Adjusted EBITDA margin jumped to 7%, a 290 basis point improvement that management called nearly 300 basis points of expansion.
The buyer base backs up the growth story rather than just the pricing. Trailing twelve-month active buyers rose 11% to 1,107,000, and average order value climbed 13% to $659, meaning existing shoppers are spending meaningfully more per transaction, not just showing up more often. That combination gave management enough confidence to raise full-year guidance to $2.54 billion to $2.57 billion in GMV and $788 million to $797 million in total revenue, alongside third-quarter Adjusted EBITDA guidance of $13.5 million to $14.5 million.
Despite the operating improvements, GAAP losses widened. Net loss came in at $27 million, or 14.1% of total revenue, compared to $11 million, or 6.9% of total revenue, a year earlier. GAAP basic net loss per share was $0.23 versus $0.10 in the prior year period, and diluted net loss per share was $0.23 versus $0.13. Much of that swing traces to a $(18.6) million non-cash adjustment tied to the change in fair value of warrant liability, a factor unrelated to how the underlying business performed. On a non-GAAP basis, basic and diluted net loss per share actually narrowed to $0.01 from $0.06, underscoring how much of the GAAP gap is accounting rather than operations.
There is also a transparency wrinkle in the guidance itself. The RealReal said it has not reconciled its forward-looking Adjusted EBITDA figures to GAAP net income or loss, citing components like payroll tax expense on employee stock transactions that it cannot predict with reasonable certainty. That leaves investors trusting a non-GAAP target without the usual bridge back to the bottom line.
#adjusted


11 days ago
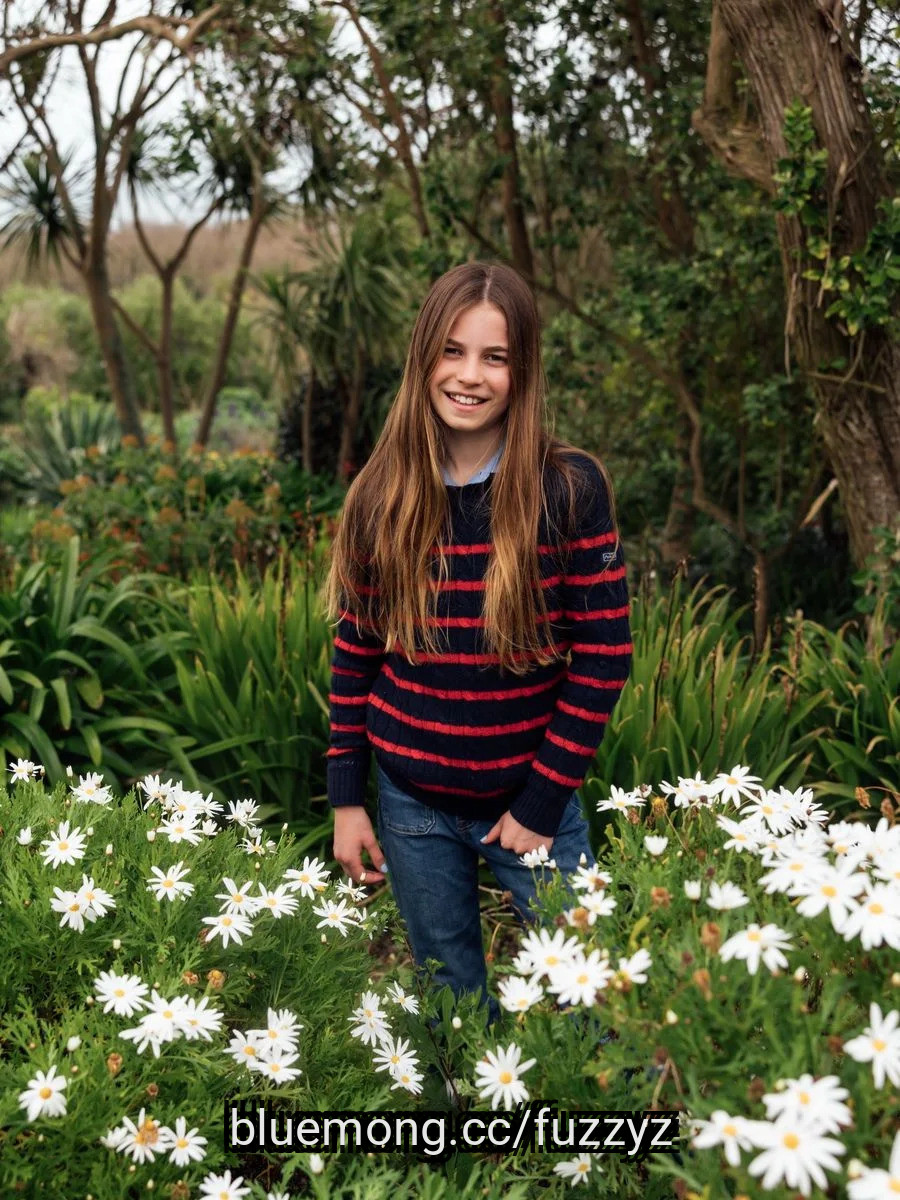
Princess Charlotte has revealed a new sporting passion, and it has a surprisingly strong connection to her royal family history. The 11-year-old princess has been seen showing off her cricket skills in family footage released by the Prince and Princess of Wales, drawing attention to a sport that was once a favorite of her great-grandfather, Prince Philip.
Prince Louis reveals what Princess Charlotte really thinks of his surprising new skill (@ Karwai Tang)
Now cricket is also getting an upgrade at Sandringham, King Charles III's private Norfolk estate, and the location of Anmer Hall, the Prince and Princess of Wales' country home. Plans call for improvements to the estate's cricket ground, creating an intriguing link between Charlotte's newfound enthusiasm, her grandfather's royal estate, and a sporting tradition that stretches back generations.
According to an exclusive report in The Sun, the Sandringham and Dersingham Cricket Club, which has long used the cricket ground on the royal estate, is planning to install an all-weather artificial surface.
A planning application submitted to the Borough Council of King's Lynn and West Norfolk details the £9,000 project, which is designed to extend playing hours and help protect the natural grass during periods of heavy rain or intensive use.
#Cricket #prince #norfolk
Prince Louis reveals what Princess Charlotte really thinks of his surprising new skill (@ Karwai Tang)
Now cricket is also getting an upgrade at Sandringham, King Charles III's private Norfolk estate, and the location of Anmer Hall, the Prince and Princess of Wales' country home. Plans call for improvements to the estate's cricket ground, creating an intriguing link between Charlotte's newfound enthusiasm, her grandfather's royal estate, and a sporting tradition that stretches back generations.
According to an exclusive report in The Sun, the Sandringham and Dersingham Cricket Club, which has long used the cricket ground on the royal estate, is planning to install an all-weather artificial surface.
A planning application submitted to the Borough Council of King's Lynn and West Norfolk details the £9,000 project, which is designed to extend playing hours and help protect the natural grass during periods of heavy rain or intensive use.
#Cricket #prince #norfolk


12 days ago
It was a back-and-forth battle against the Arizona State Sun Devils in the first half, but the Texas A&M Aggies put their foot on the pedal with two massive pick-sixes to seal a Week 2 victory at Kyle Field on Saturday afternoon.
One of the most integral improvements the Aggies wanted to make this offseason was forcing more turnovers. After recording no interceptions against Missouri State in the season opener, Marco Jones and Julio Humphrey took their picks to the house for six.
Meanwhile, electric wide receivers Mario Craver and Isaiah Horton hauled in a touchdown pass apiece, in what was a solid overall outing from the offensive playmakers. While there are still a plethora of adjustments to be made in the trenches, quarterback Marcel Reed still threw for 163 yards and three touchdowns, with just one interception.
In what was a record day for the 12th Man, the Maroon and White came through with a massive 48-20 win over the Big 12 representatives to move to 2-0 in 2026.
Here are some of the best social media reactions from Texas A&M's dominant victory over Arizona State in Week 2:
#state #victory #still #devils
One of the most integral improvements the Aggies wanted to make this offseason was forcing more turnovers. After recording no interceptions against Missouri State in the season opener, Marco Jones and Julio Humphrey took their picks to the house for six.
Meanwhile, electric wide receivers Mario Craver and Isaiah Horton hauled in a touchdown pass apiece, in what was a solid overall outing from the offensive playmakers. While there are still a plethora of adjustments to be made in the trenches, quarterback Marcel Reed still threw for 163 yards and three touchdowns, with just one interception.
In what was a record day for the 12th Man, the Maroon and White came through with a massive 48-20 win over the Big 12 representatives to move to 2-0 in 2026.
Here are some of the best social media reactions from Texas A&M's dominant victory over Arizona State in Week 2:
#state #victory #still #devils


13 days ago
MADRID (AP) — Formula 1 drivers enjoyed the high adrenaline produced by the Madring track at the Spanish Grand Prix while complaining about the lack of overtaking opportunities on the new circuit.
They also called for other improvements such as reducing the pit lane length. Madrid has produced a hybrid urban circuit using existing roads and purpose-built sections for its first grand prix in 45 years.
"In terms of track design I think it can be better," Red Bull's Max Verstappen said on Saturday. "Input from drivers in the future on track design can also help a lot. ... If you want to have better racing, overtaking, I think there can be a few corners that can be changed."
Verstappen added, "There's always a way to find an overtaking opportunity around a track."
There were only a few overtaking maneuvers in the first days of action at Madring across F1, F2 and the F3 series. Some commentators called Madring the Spanish Monaco.
#madring #overtaking #spanish
They also called for other improvements such as reducing the pit lane length. Madrid has produced a hybrid urban circuit using existing roads and purpose-built sections for its first grand prix in 45 years.
"In terms of track design I think it can be better," Red Bull's Max Verstappen said on Saturday. "Input from drivers in the future on track design can also help a lot. ... If you want to have better racing, overtaking, I think there can be a few corners that can be changed."
Verstappen added, "There's always a way to find an overtaking opportunity around a track."
There were only a few overtaking maneuvers in the first days of action at Madring across F1, F2 and the F3 series. Some commentators called Madring the Spanish Monaco.
#madring #overtaking #spanish

14 days ago
The Gophers originally opened as high as 2.5-point betting favorites for this week's game against Mississippi State. According to The Action Network, the consensus odds have continued to flip back and forth throughout the week, with the Bulldogs being favored by as much as 1.5. As of Friday morning, Minnesota is currently a one-point favorite. Could we be looking at a potential classic on Saturday afternoon?
Realistically, the consistent change in betting odds is pretty standard for a nonconference matchup in Week 2. Mississippi State and Minnesota were both viewed as potential wildcard teams with young quarterbacks heading into the season, and blowout wins in Week 1 didn't tell us much. **** ody really knows who should be favored in Saturday's game. But approaching college football with common sense and reason is boring.
Sep 3, 2026; Minneapolis, Minnesota, USA; Minnesota Golden Gophers defensive lineman Anthony Smith (0) and defensive lineman TJ Bush Jr. (3) celebrate during the second half against the Eastern Illinois Panthers at Huntington Bank Stadium. Mandatory Credit: Matt Krohn-Imagn Images
With the current total set at over/under 54.5 points, there's a scenario where Minnesota and Mississippi State easily clear that number, and we see a back-and-forth shootout. Both teams made improvements to their defenses in the offseason after rather disappointing 2025 campaigns.
The Gophers made transfer portal splashes with Cal pass rusher TJ Bush Jr. and Michigan State cornerback Aydan West, while the Bulldogs brought in Zach Arnett as their new defensive coordinator. After Mississippi State opened with a 62-13 win over UL Monroe and the Gophers comfortably beat Eastern Illinois 59-7, their new-look defenses will be tested in Week 2.
#state
Realistically, the consistent change in betting odds is pretty standard for a nonconference matchup in Week 2. Mississippi State and Minnesota were both viewed as potential wildcard teams with young quarterbacks heading into the season, and blowout wins in Week 1 didn't tell us much. **** ody really knows who should be favored in Saturday's game. But approaching college football with common sense and reason is boring.
Sep 3, 2026; Minneapolis, Minnesota, USA; Minnesota Golden Gophers defensive lineman Anthony Smith (0) and defensive lineman TJ Bush Jr. (3) celebrate during the second half against the Eastern Illinois Panthers at Huntington Bank Stadium. Mandatory Credit: Matt Krohn-Imagn Images
With the current total set at over/under 54.5 points, there's a scenario where Minnesota and Mississippi State easily clear that number, and we see a back-and-forth shootout. Both teams made improvements to their defenses in the offseason after rather disappointing 2025 campaigns.
The Gophers made transfer portal splashes with Cal pass rusher TJ Bush Jr. and Michigan State cornerback Aydan West, while the Bulldogs brought in Zach Arnett as their new defensive coordinator. After Mississippi State opened with a 62-13 win over UL Monroe and the Gophers comfortably beat Eastern Illinois 59-7, their new-look defenses will be tested in Week 2.
#state


14 days ago
On August 27, AstraZeneca PLC (NYSE:AZN) and Amgen Inc. (NASDAQ:AMGN) scored a shared clinical victory. Positive high-level results from the Phase III CROSSING trial showed that their co-developed severe asthma drug, TEZSPIRE, achieved statistically significant and clinically meaningful improvements across both co-primary endpoints, histologic remission and the frequency/severity of dysphagia, and all key secondary endpoints at week 24 in patients with eosinophilic esophagitis. These benefits were sustained through week 52 across both tested doses, accompanied by a safety profile consistent with its approved indications. While CROSSING highlights their joint R&D success, a closer look at their standalone financial performance reveals distinct growth trajectories.
Both pharmaceutical giants delivered solid Q2 2026 results, but AstraZeneca is showing stronger overall financial momentum. AstraZeneca PLC (NYSE:AZN)'s Q2 revenue increased 6% year over year to $15.38 billion, supported by its Oncology franchise, which grew 18% in H1 to $14.12 billion, and its Rare Disease portfolio, which increased 13%. Core EPS rose 21% to $2.63, beating expectations, while management reaffirmed its full-year 2026 outlook for mid-to-high single-digit revenue growth and low double-digit Core EPS growth.
Amgen Inc. (NASDAQ:AMGN) reported Q2 revenue of $10.1 billion, up 10% year over year, while non-GAAP EPS increased 4% to $6.29. Although its key growth products advanced 26%, mature products faced significant biosimilar pressure, with Prolia revenue declining 32% and XGEVA falling 34%. Amgen nevertheless raised its 2026 revenue guidance midpoint to $39.4 billion.
Overall, AZN holds the financial edge due to stronger EPS growth, broader portfolio momentum, and less exposure to the biosimilar erosion affecting AMGN's mature products.
Amgen's bull case is supported by robust growth in key products, which increased 26%, and $3.5 billion in Q2 free cash flow, providing substantial capital flexibility. Wells Fargo raised its Amgen price target to $435 from $400 on September 4, citing potential upside from HORIZON and pipeline ****** ets such as olpasiran. New Phase III VESALIUS-CV data also showed Repatha reduced the risk of death by 20% in high-risk adults without a prior heart attack or stroke, with heart attack risk reductions emerging as early as six months. However, accelerating biosimilar competition affecting legacy franchises such as Prolia and XGEVA remains a key risk to sustained margin expansion.
#revenue #astrazeneca #increased #products
Both pharmaceutical giants delivered solid Q2 2026 results, but AstraZeneca is showing stronger overall financial momentum. AstraZeneca PLC (NYSE:AZN)'s Q2 revenue increased 6% year over year to $15.38 billion, supported by its Oncology franchise, which grew 18% in H1 to $14.12 billion, and its Rare Disease portfolio, which increased 13%. Core EPS rose 21% to $2.63, beating expectations, while management reaffirmed its full-year 2026 outlook for mid-to-high single-digit revenue growth and low double-digit Core EPS growth.
Amgen Inc. (NASDAQ:AMGN) reported Q2 revenue of $10.1 billion, up 10% year over year, while non-GAAP EPS increased 4% to $6.29. Although its key growth products advanced 26%, mature products faced significant biosimilar pressure, with Prolia revenue declining 32% and XGEVA falling 34%. Amgen nevertheless raised its 2026 revenue guidance midpoint to $39.4 billion.
Overall, AZN holds the financial edge due to stronger EPS growth, broader portfolio momentum, and less exposure to the biosimilar erosion affecting AMGN's mature products.
Amgen's bull case is supported by robust growth in key products, which increased 26%, and $3.5 billion in Q2 free cash flow, providing substantial capital flexibility. Wells Fargo raised its Amgen price target to $435 from $400 on September 4, citing potential upside from HORIZON and pipeline ****** ets such as olpasiran. New Phase III VESALIUS-CV data also showed Repatha reduced the risk of death by 20% in high-risk adults without a prior heart attack or stroke, with heart attack risk reductions emerging as early as six months. However, accelerating biosimilar competition affecting legacy franchises such as Prolia and XGEVA remains a key risk to sustained margin expansion.
#revenue #astrazeneca #increased #products

14 days ago
Intel Corporation (NASDAQ:INTC) and ASML Holding N.V. (NASDAQ: ASML) have recently provided fresh evidence that High-NA EUV lithography is advancing in commercial manufacturing. At the SPIE Photomask Technology + Extreme Ultraviolet Lithography conference, the two companies announced several updates related to this technology and next-generation chip production.
While the update offers evidence of High-NA's manufacturing readiness, Intel faces a financial test about whether production improvements translate into better foundry returns. For ASML, it is whether greater manufacturing readiness ultimately leads to broader customer adoption and demand.
According to the companies, more than one million wafers have now been processed using High-NA EUV across early tool certification and testing, research and development efforts, and volume production on select layers for a subset of Intel® Core™ Ultra Series 3 processors, code-named Panther Lake.
The products that have been manufactured on Intel 18A using High NA for select layers continue to deliver performance, the companies noted, meeting or exceeding comparable layers patterned using the NXE platform.
This offers Intel early production experience with the technology. Back in July, ASML noted how Intel was the first company to ship a high-volume logic product manufactured using ASML's High NA EUV lithography technology.
#Intel #asml #technology #production
While the update offers evidence of High-NA's manufacturing readiness, Intel faces a financial test about whether production improvements translate into better foundry returns. For ASML, it is whether greater manufacturing readiness ultimately leads to broader customer adoption and demand.
According to the companies, more than one million wafers have now been processed using High-NA EUV across early tool certification and testing, research and development efforts, and volume production on select layers for a subset of Intel® Core™ Ultra Series 3 processors, code-named Panther Lake.
The products that have been manufactured on Intel 18A using High NA for select layers continue to deliver performance, the companies noted, meeting or exceeding comparable layers patterned using the NXE platform.
This offers Intel early production experience with the technology. Back in July, ASML noted how Intel was the first company to ship a high-volume logic product manufactured using ASML's High NA EUV lithography technology.
#Intel #asml #technology #production
14 days ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Net sales growth of 22% was primarily driven by sustained demand across enterprise, data center, and specialty market sectors, including military applications.
Gross profit margin expansion to 37.4% demonstrates significant manufacturing operating leverage, where fixed costs are distributed over higher production volumes.
Management attributes margin improvements to increased manufacturing efficiencies that naturally occur as production volumes scale.
The company is navigating industry-wide optical fiber shortages and raw material lead time extensions by actively managing supply chain dynamics to protect customer deliveries.
#Margin #Manufacturing #volumes #management
Net sales growth of 22% was primarily driven by sustained demand across enterprise, data center, and specialty market sectors, including military applications.
Gross profit margin expansion to 37.4% demonstrates significant manufacturing operating leverage, where fixed costs are distributed over higher production volumes.
Management attributes margin improvements to increased manufacturing efficiencies that naturally occur as production volumes scale.
The company is navigating industry-wide optical fiber shortages and raw material lead time extensions by actively managing supply chain dynamics to protect customer deliveries.
#Margin #Manufacturing #volumes #management

14 days ago
Ollie's Bargain Outlet Holdings Inc.'s (NASDAQ:OLLI) second quarter results were characterized by robust loyalty membership growth, store count expansion, and a notable boost in earnings despite weakness in comparable store sales. During the quarter, the retailer opened 15 new locations and shut down one store because of storm-related damages. This pushed its overall store count to 686 across 36 states, a year-over-year jump of 11.9%. The ongoing growth in its store network continues to be the core focus of Ollie's expansion roadmap, as the management recently confirmed its plans to open 75 new stores by the end of this fiscal year. Such a strategy strongly reflects on the extended growth potential of Ollie's existing business model.
Photo by Franki Chamaki on Unsplash
The company's loyalty program, Ollie's Army, continued to gain momentum during the recent quarter, raising its reach to 18.1 million members. This helped push net sales higher by 9.1% to $741.3 million, with the gain coming mainly from newly opened stores rather than sales at existing locations. Even with comparable sales trending downward, key profitability figures showed clear improvement.
With lower supply chain-related costs, gross margins expanded to 43.5%. A key factor behind this jump was the IEEPA tariff refunds, which contributed 380 basis points to gross margin on their own, in addition to broader reductions in tariff rates. This tariff-related benefit served as a meaningful cushion, helping to overcome the drop in comparable sales.
Together, these factors fueled substantial growth in the bottom line as the adjusted net income climbed 40.3% to $85.4 million, and adjusted net income per diluted share rose 43.4% to $1.42. This represented an outsized growth compared to overall sales growth, which highlights the impact of tariff refunds and margin improvements on the overall results.
#Growth #tariff
Photo by Franki Chamaki on Unsplash
The company's loyalty program, Ollie's Army, continued to gain momentum during the recent quarter, raising its reach to 18.1 million members. This helped push net sales higher by 9.1% to $741.3 million, with the gain coming mainly from newly opened stores rather than sales at existing locations. Even with comparable sales trending downward, key profitability figures showed clear improvement.
With lower supply chain-related costs, gross margins expanded to 43.5%. A key factor behind this jump was the IEEPA tariff refunds, which contributed 380 basis points to gross margin on their own, in addition to broader reductions in tariff rates. This tariff-related benefit served as a meaningful cushion, helping to overcome the drop in comparable sales.
Together, these factors fueled substantial growth in the bottom line as the adjusted net income climbed 40.3% to $85.4 million, and adjusted net income per diluted share rose 43.4% to $1.42. This represented an outsized growth compared to overall sales growth, which highlights the impact of tariff refunds and margin improvements on the overall results.
#Growth #tariff
15 days ago
HELSINKI, Sept 9 (Reuters) - Alphabet's Google will invest at least €13 billion ($15.1 billion) in artificial intelligence infrastructure in Finland over the next two years, it said on Wednesday, calling it the company's single largest investment in Europe.
Finland has become a magnet for data centres as companies including Microsoft and TikTok owner ByteDance seek to reduce energy costs and meet climate goals.
Its cold climate makes coping with the heat produced by data centres cheaper and it also has large amounts of low-carbon electricity.
Alphabet this year increased its global investment to between $195 billion and $205 billion as it seeks to capture growing computing demand.
The investments in Finland will include data centres, electricity grid improvements and clean energy and battery projects driving services such as Gemini, Search, Maps and YouTube, Google said in a statement.
#billion #finland #centres #climate
Finland has become a magnet for data centres as companies including Microsoft and TikTok owner ByteDance seek to reduce energy costs and meet climate goals.
Its cold climate makes coping with the heat produced by data centres cheaper and it also has large amounts of low-carbon electricity.
Alphabet this year increased its global investment to between $195 billion and $205 billion as it seeks to capture growing computing demand.
The investments in Finland will include data centres, electricity grid improvements and clean energy and battery projects driving services such as Gemini, Search, Maps and YouTube, Google said in a statement.
#billion #finland #centres #climate
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
17 days ago
Lucid Group, Inc. (NASDAQ:LCID) is recalling 27,185 of its Air luxury sedans in the U.S. because an exterior lighting circuit could overheat and raise the risk of fire, the National Highway Traffic Safety Administration said on August 28.
NHTSA told owners to park outside and away from structures until a fix is deployed and warned the overheating circuit could also knock out exterior lighting, raising crash risk too. Lucid already released a free over-the-air software update, and NHTSA said 20,719 of the affected vehicles had received it before the announcement.
The recall is Lucid's largest ever, covering more cars than it delivered in all of 2025, when it handed over 15,841 vehicles. It follows a May recall of 2,039 vehicles over lost drive power and a January recall of more than 10,000 vehicles over rearview camera problems.
Lucid Group, Inc. (NASDAQ:LCID)'s top line continues to grow despite its operational challenges, as second-quarter revenue jumped 56% year over year to about $405 million and 44% sequentially. The growth was helped by higher deliveries, a better product mix, a 3.7% increase in average selling price, and $25 million in additional regulatory credit sales. This growth gives Lucid a stronger revenue base as management works to improve the firm's basic economics.
New CEO Silvio Napoli has also introduced a specific turnaround plan with measurable targets. His operational reset plans to generate $1.4 billion in cash-flow improvements this year. It directly addresses problems such as premature product launches, inadequate service investment, and slow responses to quality issues. A more disciplined approach could help Lucid reduce execution problems and rebuild investor confidence.
#lucid #recall #problems #group
NHTSA told owners to park outside and away from structures until a fix is deployed and warned the overheating circuit could also knock out exterior lighting, raising crash risk too. Lucid already released a free over-the-air software update, and NHTSA said 20,719 of the affected vehicles had received it before the announcement.
The recall is Lucid's largest ever, covering more cars than it delivered in all of 2025, when it handed over 15,841 vehicles. It follows a May recall of 2,039 vehicles over lost drive power and a January recall of more than 10,000 vehicles over rearview camera problems.
Lucid Group, Inc. (NASDAQ:LCID)'s top line continues to grow despite its operational challenges, as second-quarter revenue jumped 56% year over year to about $405 million and 44% sequentially. The growth was helped by higher deliveries, a better product mix, a 3.7% increase in average selling price, and $25 million in additional regulatory credit sales. This growth gives Lucid a stronger revenue base as management works to improve the firm's basic economics.
New CEO Silvio Napoli has also introduced a specific turnaround plan with measurable targets. His operational reset plans to generate $1.4 billion in cash-flow improvements this year. It directly addresses problems such as premature product launches, inadequate service investment, and slow responses to quality issues. A more disciplined approach could help Lucid reduce execution problems and rebuild investor confidence.
#lucid #recall #problems #group
17 days ago
Selling a home for $890,000 leaves roughly $328,000 taxable after the $500,000 joint exclusion, adding $9,240 in Medicare surcharges two years later.
Section 121's $500,000 joint exclusion ceiling hasn't risen with inflation since 1997, leaving longtime homeowners exposed to large taxable gains on ordinary homes.
Rebuilding cost basis with documented improvements, deferring optional IRA withdrawals, and budgeting for the Medicare surcharge from proceeds reduces the sale's financial impact.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
For more than 40 years, the house did exactly what its owners hoped it would do. A couple who paid $62,000 for their home in 1984 closes on the sale this year at $890,000. The IRS lets them exclude up to $500,000 of gain under Internal Revenue Code Section 121. Any taxable gain left after the exclusion, basis adjustments and selling expenses flows into adjusted gross income (AGI). That figure helps determine the modified adjusted gross income (MAGI) Social Security uses to calculate Medicare's income-related monthly adjustment amount (IRMAA) two years later. The sale closes in 2026. The Medicare bill arrives in 2028.
#medicare #years #selling #later
Section 121's $500,000 joint exclusion ceiling hasn't risen with inflation since 1997, leaving longtime homeowners exposed to large taxable gains on ordinary homes.
Rebuilding cost basis with documented improvements, deferring optional IRA withdrawals, and budgeting for the Medicare surcharge from proceeds reduces the sale's financial impact.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
For more than 40 years, the house did exactly what its owners hoped it would do. A couple who paid $62,000 for their home in 1984 closes on the sale this year at $890,000. The IRS lets them exclude up to $500,000 of gain under Internal Revenue Code Section 121. Any taxable gain left after the exclusion, basis adjustments and selling expenses flows into adjusted gross income (AGI). That figure helps determine the modified adjusted gross income (MAGI) Social Security uses to calculate Medicare's income-related monthly adjustment amount (IRMAA) two years later. The sale closes in 2026. The Medicare bill arrives in 2028.
#medicare #years #selling #later

18 days ago
Juventus had won their first two games of the season, but it would be entirely fair to say that they had come close to leaving those matches ruing missed opportunities. Each of them could've been put away long time before they were, and indeed one of the major talking points headed into Sunday's matchup against AC Milan was the fact that the Bianconeri had gotten the results without reaching the level of performance they desired. Milan were in the same boat, winning two straight under new manager Ruben Amorim but not convincing in either. It felt as though the team that managed to perform better would be the likelier to come out of the Allianz on top.
It was ultimately Juve that had the better of a game that was equal parts chaotic and sloppy. But once again they failed to take advantage of their performances. They failed to make the most of the chances they made over the game's first 70 minutes before Milan scored on — stop me if you've heard this one before — their first shot on target of the match. It took until the second minute of stoppage time for Juve to finally even things out, when Federico Gatti powered home a Teun Koopmeiners cross from six yards to earn the Old Lady a 1-1 draw.
The problems for Juventus were the same as we've talked about all season so far. The finishing wasn't nearly good enough, the passing was disjointed and often inaccurate, and overall creativity seemed to be lacking. But in spite of all of that, they can honestly say that they were the better of the two sides and deserved victory — even more so when you consider the fact that Milan's goal really should've been disallowed for a foul in the buildup that was never flagged by VAR. Considering they were missing seven players due to injury, several of whom were extremely important, it's far too early to start abandoning hope of a successful year—provided they make the improvements that their play so far suggest is possible.
Luciano Spalletti was missing Kenan Yildiz, Weston McKennie, Khéphren Thuram, Andrea Cambiaso, Jeff Ekhator, Juan Cabal, and Pape Matar Sarr. His 4-2-3-1 formation gave several players their first starts of the year. Guglielmo Vicario started behind the back four of Pierre Kalulu, Bremer, Jhon Lucumí, and Zeki Celik. Manuel Locatelli and Douglas Luiz started in the middle of the park, while Francisco Conceição joined Nico González and Kerim Alajbegovic behind Randal Kolo Muani in attack.
Amorim missed Matteo Gabbia due to an ankle injury, but returned a few players to the starting lineup who had been eased back into things after long World Cup runs. Mike Maignan started in goal, ahead of a 3-4-2-1 setup that was a slight tweak to Amorim's usual 3-4-3. Former Juve prospect Koni De Winter joined Strahinja Pavolovic and Mario Gila in defense. Big-money signing Diego Moreira got his first start of the season opposite Pervis Estupiñán at the wing-back spots, while Luka Modric and Yunis Musah manned the double pivot. Adrien Rabiot joined Alexis Saele
It was ultimately Juve that had the better of a game that was equal parts chaotic and sloppy. But once again they failed to take advantage of their performances. They failed to make the most of the chances they made over the game's first 70 minutes before Milan scored on — stop me if you've heard this one before — their first shot on target of the match. It took until the second minute of stoppage time for Juve to finally even things out, when Federico Gatti powered home a Teun Koopmeiners cross from six yards to earn the Old Lady a 1-1 draw.
The problems for Juventus were the same as we've talked about all season so far. The finishing wasn't nearly good enough, the passing was disjointed and often inaccurate, and overall creativity seemed to be lacking. But in spite of all of that, they can honestly say that they were the better of the two sides and deserved victory — even more so when you consider the fact that Milan's goal really should've been disallowed for a foul in the buildup that was never flagged by VAR. Considering they were missing seven players due to injury, several of whom were extremely important, it's far too early to start abandoning hope of a successful year—provided they make the improvements that their play so far suggest is possible.
Luciano Spalletti was missing Kenan Yildiz, Weston McKennie, Khéphren Thuram, Andrea Cambiaso, Jeff Ekhator, Juan Cabal, and Pape Matar Sarr. His 4-2-3-1 formation gave several players their first starts of the year. Guglielmo Vicario started behind the back four of Pierre Kalulu, Bremer, Jhon Lucumí, and Zeki Celik. Manuel Locatelli and Douglas Luiz started in the middle of the park, while Francisco Conceição joined Nico González and Kerim Alajbegovic behind Randal Kolo Muani in attack.
Amorim missed Matteo Gabbia due to an ankle injury, but returned a few players to the starting lineup who had been eased back into things after long World Cup runs. Mike Maignan started in goal, ahead of a 3-4-2-1 setup that was a slight tweak to Amorim's usual 3-4-3. Former Juve prospect Koni De Winter joined Strahinja Pavolovic and Mario Gila in defense. Big-money signing Diego Moreira got his first start of the season opposite Pervis Estupiñán at the wing-back spots, while Luka Modric and Yunis Musah manned the double pivot. Adrien Rabiot joined Alexis Saele


19 days ago
The newly renovated Memorial Gym on the UTEP campus, home to the university's volleyball team, debuted to a sold-out crowd Sunday, Aug. 30.
Memorial Gym underwent extensive renovations in the offseason as part of the Club Memorial project. The upgrades include new lower-level chairback seating, LED lighting, an upgraded sound system, Taraflex competition flooring, enhanced MinerVision production equipment and several additional fan experience improvements.
The volleyball team is looking for a third consecutive trip to the NCAA tournament.
The Texas Western Miners, now UTEP Miners, gave El Paso fans their first look at the new Memorial Gym at 8 p.m. Saturday, Dec. 8, 1961, when they opened their 1961-62 season in the 4,300-seat gym.
The gym was completed just a few days before the home opener. The Miners returned from their three-game opening road trip, having only a few practice sessions on the new playing surface.
#memorial #sunday
Memorial Gym underwent extensive renovations in the offseason as part of the Club Memorial project. The upgrades include new lower-level chairback seating, LED lighting, an upgraded sound system, Taraflex competition flooring, enhanced MinerVision production equipment and several additional fan experience improvements.
The volleyball team is looking for a third consecutive trip to the NCAA tournament.
The Texas Western Miners, now UTEP Miners, gave El Paso fans their first look at the new Memorial Gym at 8 p.m. Saturday, Dec. 8, 1961, when they opened their 1961-62 season in the 4,300-seat gym.
The gym was completed just a few days before the home opener. The Miners returned from their three-game opening road trip, having only a few practice sessions on the new playing surface.
#memorial #sunday