6 mins. ago
On September 10, Lovesac (NASDAQ:LOVE) reported record second quarter revenue of $161.2 million, its highest Q2 total ever, even as its entry-level furniture shopper kept pulling back. The 0.4% sales increase came almost entirely from showrooms rather than higher-margin online orders, and the quarter's real profit boost was traced to a one-time source. A $20 million tariff refund lifted gross margin by 1,200 basis points to 68.4%, masking an underlying business that actually lost money once that windfall is stripped out.
Configurations priced above $6,000 grew by double digits during the quarter, even against a strong comparison from a year earlier, and management pointed to that segment as the clearest sign the brand's value proposition still resonates. Showroom net sales climbed 4.6% to $114.1 million, helped by 14 net new locations opened over the past year and a double-digit jump in conversion rates that offset softer foot traffic.
The Snugg platform, a smaller and more digitally oriented sofa line, helped push "other products" revenue up 198.2%, with more than half of Snugg sales happening online, giving Lovesac a lower-priced entry point into the brand. The Loved by Lovesac resale program is doing similar work, with 70% of its customers new to the company.
Behind all of this sits a pipeline of four major launches set for the second half: a personalized comfort feature for Sactionals, an entirely new large-format premium seating platform, Snugg accessories including a corner piece and swivel base, and the start of onshore Sactionals seat manufacturing, alongside a national rollout of White Glove and Room of Choice delivery. The balance sheet backs it up, with $68.8 million in cash, no debt, $34 million in unused borrowing capacity, and $7.2 million in buybacks with $46.9 million left under the current authorization.
Omni-channel comparable sales fell 1.9%, driven by demand pressure below $6,000, where management said inflation, higher interest rates, and a spike in gas prices have hit the same buyers for several quarters running. Internet sales dropped 5.3%, Sacs sales fell 8.6%, and the exit of the Best Buy shop-in-shop partnership cut "other" net sales by 23.2%. Strip out the tariff refund and adjusted EBITDA was actually a loss of $1.3 million, compared with income of $0.8 million a year earlier, a sign the core business is less profitable than the headline numbers suggest.
#million #quarter #revenue
Configurations priced above $6,000 grew by double digits during the quarter, even against a strong comparison from a year earlier, and management pointed to that segment as the clearest sign the brand's value proposition still resonates. Showroom net sales climbed 4.6% to $114.1 million, helped by 14 net new locations opened over the past year and a double-digit jump in conversion rates that offset softer foot traffic.
The Snugg platform, a smaller and more digitally oriented sofa line, helped push "other products" revenue up 198.2%, with more than half of Snugg sales happening online, giving Lovesac a lower-priced entry point into the brand. The Loved by Lovesac resale program is doing similar work, with 70% of its customers new to the company.
Behind all of this sits a pipeline of four major launches set for the second half: a personalized comfort feature for Sactionals, an entirely new large-format premium seating platform, Snugg accessories including a corner piece and swivel base, and the start of onshore Sactionals seat manufacturing, alongside a national rollout of White Glove and Room of Choice delivery. The balance sheet backs it up, with $68.8 million in cash, no debt, $34 million in unused borrowing capacity, and $7.2 million in buybacks with $46.9 million left under the current authorization.
Omni-channel comparable sales fell 1.9%, driven by demand pressure below $6,000, where management said inflation, higher interest rates, and a spike in gas prices have hit the same buyers for several quarters running. Internet sales dropped 5.3%, Sacs sales fell 8.6%, and the exit of the Best Buy shop-in-shop partnership cut "other" net sales by 23.2%. Strip out the tariff refund and adjusted EBITDA was actually a loss of $1.3 million, compared with income of $0.8 million a year earlier, a sign the core business is less profitable than the headline numbers suggest.
#million #quarter #revenue


25 mins. ago
Concerned about an AI bubble? Sign up for The Daily Upside for smart and actionable market news, built for investors.
He doesn't get as much media attention as Larry Fink or Bill Ackman, but David Booth, chairman of Dimensional Fund Advisors, has played a foundational role in the creation of the modern ***** et management industry. Working alongside Rex Sinquefield since the early 1980s, Booth has championed the idea that academic research is superior to Wall Street intuition.
During that time, Dimensional has grown from a fledgling business operating out of a spare room of Booth's Brooklyn brownstone to a global investment manager with $1.1 trillion in ***** ets under management. He's no longer running the company, having passed the reins to current co-CEOs Dave Butler and Gerard O'Reilly, but Booth is still intimately involved in setting Dimensional's direction at a time when innovation in the exchange-traded fund market and related trends are driving another sea change in how professional portfolios are built.
Sign up for The Daily Upside at no cost for premium ***** ysis on all your favorite stocks.
READ ALSO: Your Client's Big Tech Company Just IPO'd. Now What? and Investors Need Real Talk About Interval Funds
#company
He doesn't get as much media attention as Larry Fink or Bill Ackman, but David Booth, chairman of Dimensional Fund Advisors, has played a foundational role in the creation of the modern ***** et management industry. Working alongside Rex Sinquefield since the early 1980s, Booth has championed the idea that academic research is superior to Wall Street intuition.
During that time, Dimensional has grown from a fledgling business operating out of a spare room of Booth's Brooklyn brownstone to a global investment manager with $1.1 trillion in ***** ets under management. He's no longer running the company, having passed the reins to current co-CEOs Dave Butler and Gerard O'Reilly, but Booth is still intimately involved in setting Dimensional's direction at a time when innovation in the exchange-traded fund market and related trends are driving another sea change in how professional portfolios are built.
Sign up for The Daily Upside at no cost for premium ***** ysis on all your favorite stocks.
READ ALSO: Your Client's Big Tech Company Just IPO'd. Now What? and Investors Need Real Talk About Interval Funds
#company


4 hours ago
Apple (NASDAQ:AAPL) recently unveiled its new iPhone Duo, a foldable phone priced at a whopping $1,999 — and that's the starting price. The phone is priced at a premium for a company already known for premium-priced products.
If sales for the Duo take off, it could prove to be a massive growth catalyst for the business. But here's why I wouldn't hold my breath, and why I think there could be challenges ahead for the tech company.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
The Duo may look enticing to consumers who love Apple products or foldable phones, but I don't think it'll capture a huge subset of the market, at least not right away. There have been many issues with foldable phones in the past, including screen creases after prolonged use, and repair costs can be high.
#signal #foldable
If sales for the Duo take off, it could prove to be a massive growth catalyst for the business. But here's why I wouldn't hold my breath, and why I think there could be challenges ahead for the tech company.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
The Duo may look enticing to consumers who love Apple products or foldable phones, but I don't think it'll capture a huge subset of the market, at least not right away. There have been many issues with foldable phones in the past, including screen creases after prolonged use, and repair costs can be high.
#signal #foldable

6 hours ago
Marriott International, Inc. (NASDAQ:MAR)'s Middle East business showed a meaningful improvement in July, with revenue per available room (RevPAR) declining 12% year over year, a sharp improvement from the 43% decline in the second quarter. The improvement came despite continued regional conflict, suggesting that demand is proving more resilient than initially feared. More importantly, Marriott's global business remains strong: global room revenue increased 7% in July, with the U.S. and Canada up 8%.
However, the Middle East remains a risk to Marriott International, Inc. (NASDAQ:MAR)'s growth strategy. The region represents only about 3% of Marriott's global fees but 6% of its development pipeline, meaning prolonged conflict can have an outsized impact on future hotel openings. Supply-chain disruptions and restricted capital flows have already delayed projects, pushing Marriott toward the lower end of its full-year net unit growth target.
The biggest positive is that the Middle East headwind appears to be easing faster than expected. Moving from a 43% RevPAR decline in the second quarter to just 12% in July suggests travel demand can recover even as geopolitical risks remain elevated. If the conflict stabilizes, Marriott International, Inc. (NASDAQ:MAR) could see a relatively quick rebound in regional occupancy and room rates.
More importantly, the Middle East is not large enough to overwhelm Marriott's broader global performance. The company generated a 7% increase in global room revenue in July, while U.S. and Canadian room revenue rose 8%. RevPAR growth was also broad-based across luxury, premium/select and mid-scale brands, suggesting that Marriott's strength is not dependent solely on wealthy travelers.
Marriott also benefits from an ***** et-light, fee-driven model, meaning stronger hotel demand can translate into attractive cash generation without requiring the company to own most of the underlying properties. Barron's has highlighted the resilience of this model, alongside the strength of Marriott Bonvoy and additional growth opportunities from its credit-card partnerships.
#marriott #middle #room
However, the Middle East remains a risk to Marriott International, Inc. (NASDAQ:MAR)'s growth strategy. The region represents only about 3% of Marriott's global fees but 6% of its development pipeline, meaning prolonged conflict can have an outsized impact on future hotel openings. Supply-chain disruptions and restricted capital flows have already delayed projects, pushing Marriott toward the lower end of its full-year net unit growth target.
The biggest positive is that the Middle East headwind appears to be easing faster than expected. Moving from a 43% RevPAR decline in the second quarter to just 12% in July suggests travel demand can recover even as geopolitical risks remain elevated. If the conflict stabilizes, Marriott International, Inc. (NASDAQ:MAR) could see a relatively quick rebound in regional occupancy and room rates.
More importantly, the Middle East is not large enough to overwhelm Marriott's broader global performance. The company generated a 7% increase in global room revenue in July, while U.S. and Canadian room revenue rose 8%. RevPAR growth was also broad-based across luxury, premium/select and mid-scale brands, suggesting that Marriott's strength is not dependent solely on wealthy travelers.
Marriott also benefits from an ***** et-light, fee-driven model, meaning stronger hotel demand can translate into attractive cash generation without requiring the company to own most of the underlying properties. Barron's has highlighted the resilience of this model, alongside the strength of Marriott Bonvoy and additional growth opportunities from its credit-card partnerships.
#marriott #middle #room
2 days ago
At about $644.38 a share, Meta Platforms (META) stock carries options that price a range from roughly $418 to $993 for about a year out. The floor of that band would take about a third off a position, and the ceiling would add more than half. Wide as it is, the range carries only a normal premium over how much the shares actually moved in the past year.
What Could That Range Do To Your Shares?
On each share, the ceiling is a gain of about $349 and the floor a loss of about $226. The gap is lopsided because a price can rise without limit but cannot fall below zero. The options put roughly a two-in-three chance on the stock finishing between them.
That leaves roughly a 16% chance of finishing above the ceiling and roughly a 16% chance of finishing below the floor. For a holder, the downside tail is the one to sit with: about one-in-six odds of losing more than a third. The floor also sits more than $100 below $525.23, the lowest price of the past 52 weeks. The shares are already down 15.6% over twelve months, against a 17.9% return for the S&P 500, though they have returned 13.0% over the past three months.
Does Meta Stock Usually Move This Much?
#ceiling #past #below
What Could That Range Do To Your Shares?
On each share, the ceiling is a gain of about $349 and the floor a loss of about $226. The gap is lopsided because a price can rise without limit but cannot fall below zero. The options put roughly a two-in-three chance on the stock finishing between them.
That leaves roughly a 16% chance of finishing above the ceiling and roughly a 16% chance of finishing below the floor. For a holder, the downside tail is the one to sit with: about one-in-six odds of losing more than a third. The floor also sits more than $100 below $525.23, the lowest price of the past 52 weeks. The shares are already down 15.6% over twelve months, against a 17.9% return for the S&P 500, though they have returned 13.0% over the past three months.
Does Meta Stock Usually Move This Much?
#ceiling #past #below


2 days ago
Two retirees with identical $1.65M portfolios face different tax outcomes based solely on withdrawal order and account placement, not holdings.
Drawing down or converting a traditional IRA to Roth before age 73 shrinks future RMDs and keeps income below IRMAA Medicare surcharge thresholds.
VTEB's tax-exempt municipal interest still counts fully toward IRMAA calculations, making it a hidden Medicare cost trap for retirees.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Two retirees, same age, same $1.65 million balance, same seven holdings in identical weights. One will pay a Medicare premium surcharge stacked on top of a rising required withdrawal starting at 73. The other will not. Only the order they draw from, and the accounts those draws come from, separates the outcomes.
#medicare #irmaa #holdings
Drawing down or converting a traditional IRA to Roth before age 73 shrinks future RMDs and keeps income below IRMAA Medicare surcharge thresholds.
VTEB's tax-exempt municipal interest still counts fully toward IRMAA calculations, making it a hidden Medicare cost trap for retirees.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Two retirees, same age, same $1.65 million balance, same seven holdings in identical weights. One will pay a Medicare premium surcharge stacked on top of a rising required withdrawal starting at 73. The other will not. Only the order they draw from, and the accounts those draws come from, separates the outcomes.
#medicare #irmaa #holdings


2 days ago
SCHD (Schwab U.S. Dividend Equity ETF) is a low-cost index fund that owns about 100 high-quality, dividend-growing companies that are built for rising income and long-term total return. JEPI (JPMorgan Equity Premium Income ETF) is an actively managed fund that owns low-volatility stocks and sells call options to generate a high monthly payout, meaning it's built for maximum current income at the cost of upside. In short: SCHD is for growing your income over time; JEPI is for maximizing your income right now.
Feature
JEPI
SCHD
Strategy
#fund #high
Feature
JEPI
SCHD
Strategy
#fund #high

2 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
An option contract's price rarely moves for just one reason. The stock shifts, time keeps passing, expectations for volatility rise and fall, and interest rates maintain their influence in the background. All of that gets folded into the cost of the contract, known as its premium. This makes it hard to tell which force actually moved the number on your screen.
The options Greeks can help you solve that problem. Each one estimates how an option's value would respond to a change in one input, such as the stock price, time, or volatility, with the others held constant.
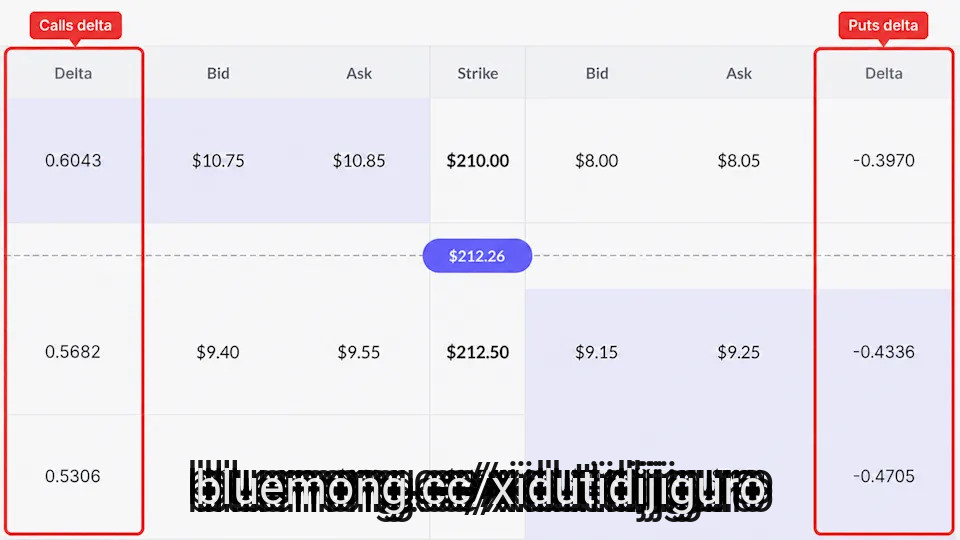
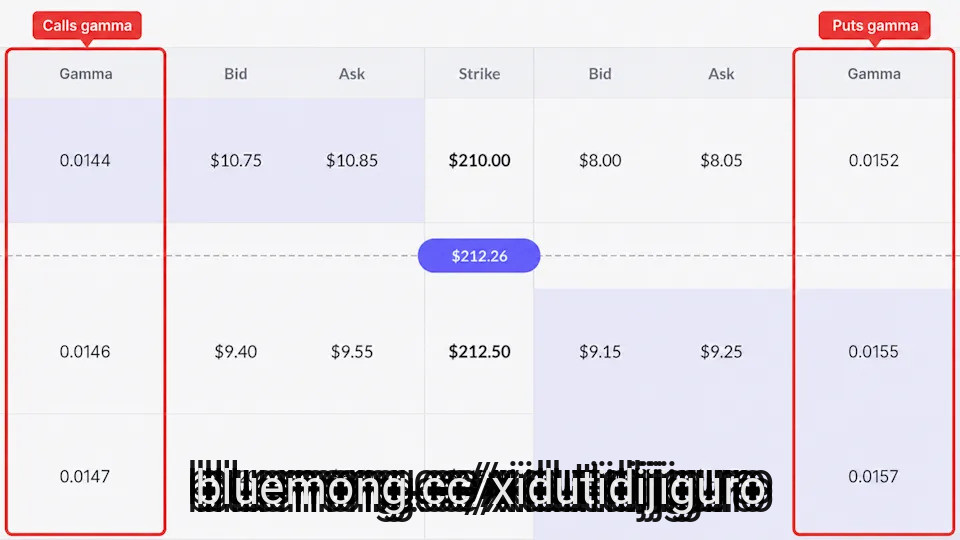
Let's follow a real contract to see how. Nvidia (NVDA) is one of the most actively traded stocks in the options market, which makes its chain a useful place to watch these numbers work. The stock was trading at $212.26 at the time, so we picked a $215 call expiring in 29 days.
Explore options contracts with AlphaSpace
#options #volatility #contract #disclosure
An option contract's price rarely moves for just one reason. The stock shifts, time keeps passing, expectations for volatility rise and fall, and interest rates maintain their influence in the background. All of that gets folded into the cost of the contract, known as its premium. This makes it hard to tell which force actually moved the number on your screen.
The options Greeks can help you solve that problem. Each one estimates how an option's value would respond to a change in one input, such as the stock price, time, or volatility, with the others held constant.
Let's follow a real contract to see how. Nvidia (NVDA) is one of the most actively traded stocks in the options market, which makes its chain a useful place to watch these numbers work. The stock was trading at $212.26 at the time, so we picked a $215 call expiring in 29 days.
Explore options contracts with AlphaSpace
#options #volatility #contract #disclosure

2 days ago
ACV Auctions Inc. (NYSE:ACVA)—one of the leading car auction marketplaces in the US—saw its share price jump by 49 percent week-on-week, taking the first spot in the top-performing stocks in last week's shortened trading session.
This followed an announcement from its Texas-based counterpart, Copart Inc., under which the latter's subsidiary will acquire all of ACVA shares in an all-cash transaction at a price of $10.50 apiece, or for a total of $1.9 billion.
The offer price marked a 45 percent premium over its closing price of $7.22 on Thursday, September 10, prior to the announcement.
The completion of the tender offer is subject to the successful acquisition of a majority stake in ACVA or the expiration of the waiting period.
The transaction is expected to be completed by the end of the year.
#percent
This followed an announcement from its Texas-based counterpart, Copart Inc., under which the latter's subsidiary will acquire all of ACVA shares in an all-cash transaction at a price of $10.50 apiece, or for a total of $1.9 billion.
The offer price marked a 45 percent premium over its closing price of $7.22 on Thursday, September 10, prior to the announcement.
The completion of the tender offer is subject to the successful acquisition of a majority stake in ACVA or the expiration of the waiting period.
The transaction is expected to be completed by the end of the year.
#percent
2 days ago
GE Aerospace (NYSE:GE) is making its largest acquisition since becoming a standalone publicly traded company. It agreed to acquire Consolidated Precision Products (CPP) for around $12 billion.
CPP is one of the world's largest precision castings providers. It's a major GE supplier. Precision castings is a major pressure point for the aerospace engines industry. Acquiring CPP would give GE Aerospace greater control over a critical part of its engine supply chain.
And the deal could strengthen GE's ability to meet demand already sitting in its backlog. But the investment case depends on whether additional production capacity generates enough free cash flow to justify the deal's premium price.
rommma/Shutterstock.com
Engine manufacturers like GE Aerospace (NYSE:GE) are struggling to keep pace with surging demand due to supply chain constraints. CPP is a major supplier of precision castings for GE's LEAP and GEnx engines. GE plans to raise CPP's output. It would do that by improving factory yields and machine use. With the CPP deal, GE also sees a path to accelerate production of new engine technologies.
#NYSE #largest #engines #supply
CPP is one of the world's largest precision castings providers. It's a major GE supplier. Precision castings is a major pressure point for the aerospace engines industry. Acquiring CPP would give GE Aerospace greater control over a critical part of its engine supply chain.
And the deal could strengthen GE's ability to meet demand already sitting in its backlog. But the investment case depends on whether additional production capacity generates enough free cash flow to justify the deal's premium price.
rommma/Shutterstock.com
Engine manufacturers like GE Aerospace (NYSE:GE) are struggling to keep pace with surging demand due to supply chain constraints. CPP is a major supplier of precision castings for GE's LEAP and GEnx engines. GE plans to raise CPP's output. It would do that by improving factory yields and machine use. With the CPP deal, GE also sees a path to accelerate production of new engine technologies.
#NYSE #largest #engines #supply


3 days ago
Concerned about an AI bubble? Sign up for The Daily Upside for smart and actionable market news, built for investors.
Paying off your mortgage used to be something people aspired to. Now, many Americans fantasize about simply getting one.
The National ***** ociation of Realtors said Thursday that US home sales fell 2% month-over-month in August to a 14-month low. The seasonally adjusted annual rate of 3.98 million residences, the lowest since June 2025, was weighed down by stubbornly high mortgage rates and home prices.
Sign up for The Daily Upside at no cost for premium ***** ysis on all your favorite stocks.
READ ALSO: Musk's Boring Company Scores $23 Billion Valuation Despite Slow Progress and Brian Niccol's Two-Year Turnaround Serves Up Sales Growth for Starbucks
#month #sign #sales #paying
Paying off your mortgage used to be something people aspired to. Now, many Americans fantasize about simply getting one.
The National ***** ociation of Realtors said Thursday that US home sales fell 2% month-over-month in August to a 14-month low. The seasonally adjusted annual rate of 3.98 million residences, the lowest since June 2025, was weighed down by stubbornly high mortgage rates and home prices.
Sign up for The Daily Upside at no cost for premium ***** ysis on all your favorite stocks.
READ ALSO: Musk's Boring Company Scores $23 Billion Valuation Despite Slow Progress and Brian Niccol's Two-Year Turnaround Serves Up Sales Growth for Starbucks
#month #sign #sales #paying


3 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Hilton is one of the largest hospitality companies in the world. It operates over 7,000 properties in over 120 countries, so the Hilton Honors American Express Aspire Card — more frequently referred to as simply the Hilton Aspire card — can be an appealing option for frequent travelers looking to maximize rewards.
The Hilton Aspire card is a premium travel card that offers luxurious perks. If you're considering applying for the card, here are seven key details you should know.
Check out our full list of the best travel credit cards
As a premium travel rewards card, the Hilton Aspire card has a high annual fee. As of 2025, the fee is $550, so there's a high cost for simply possessing the card.
#rewards
Hilton is one of the largest hospitality companies in the world. It operates over 7,000 properties in over 120 countries, so the Hilton Honors American Express Aspire Card — more frequently referred to as simply the Hilton Aspire card — can be an appealing option for frequent travelers looking to maximize rewards.
The Hilton Aspire card is a premium travel card that offers luxurious perks. If you're considering applying for the card, here are seven key details you should know.
Check out our full list of the best travel credit cards
As a premium travel rewards card, the Hilton Aspire card has a high annual fee. As of 2025, the fee is $550, so there's a high cost for simply possessing the card.
#rewards


3 days ago
Farmington, Connecticut-based Otis Worldwide Corporation (OTIS) manufactures, installs, and services building systems. Valued at $26.4 billion by market cap, the company offers elevators, escalators, and other moving products.
Companies worth $10 billion or more are generally described as "large-cap stocks," and OTIS perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the specialty industrial machinery industry. OTIS is the largest global elevator and escalator supplier, known for its innovative safety features dating back to 1854. The company boasts a loyal customer base and competitive edge, with its success lying in commanding premium pricing, securing long-term service contracts, and leveraging its installed base for consistent revenue.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ******* e
#tens #Stock #billion #market
Companies worth $10 billion or more are generally described as "large-cap stocks," and OTIS perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the specialty industrial machinery industry. OTIS is the largest global elevator and escalator supplier, known for its innovative safety features dating back to 1854. The company boasts a loyal customer base and competitive edge, with its success lying in commanding premium pricing, securing long-term service contracts, and leveraging its installed base for consistent revenue.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ******* e
#tens #Stock #billion #market



4 days ago
Unlike Medicare Advantage, Medigap offers no recurring annual shopping window, so health conditions can permanently lock policyholders into higher premiums.
The one-time federal Medigap Open Enrollment Period lasts just six months starting at age 65; after that, most states allow medical underwriting.
Never cancel an existing Medigap policy before a replacement is confirmed in writing, since a declined application leaves the original coverage intact.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
A 72-year-old in Ohio opens a December rate notice and finds that her Medigap Plan G premium is rising again in January, the fourth increase in four years. Her broker finds a competitor charging $40 less each month.
#finds #period
The one-time federal Medigap Open Enrollment Period lasts just six months starting at age 65; after that, most states allow medical underwriting.
Never cancel an existing Medigap policy before a replacement is confirmed in writing, since a declined application leaves the original coverage intact.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
A 72-year-old in Ohio opens a December rate notice and finds that her Medigap Plan G premium is rising again in January, the fourth increase in four years. Her broker finds a competitor charging $40 less each month.
#finds #period

4 days ago
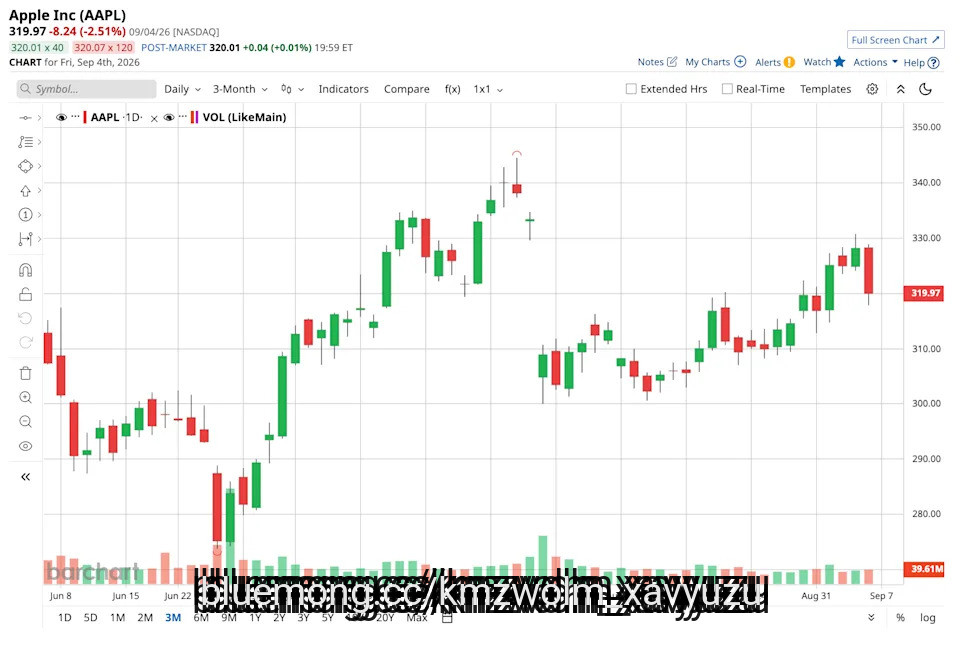
During the episode aired on September 8, Mad Money host Jim Cramer turned his focus to Apple Inc. (NASDAQ:AAPL), breaking down why the tech giant remains his ultimate "fantasy football" quarterback for steady, reliable portfolio performance. He stated:
We know how to draft on Mad Money so, break out your pen and paper and let's get started. Now, we got to start with our quarterback in fantasy… You're typically only playing one quarterback per week. And what you want here is consistent production. That's why for the past several years, I've picked Apple as my fantasy stock football QB. As always, own it, don't trade it. Not only does Apple make the most beloved products in the world, they're playing a very different game from their mega cap peers. Everybody else is spending hundreds of billions of dollars on AI. Apple's spending next to nothing, just partnering with AI companies. They desperately want access to Apple's massive user base.
To me, that makes Apple a lot less risky than the other members of the Magnificent Seven. To put that in NFL terms, Apple reminds me of Josh Allen, the quarterback for the Buffalo Bills. Allen's a known quantity. He was the league MVP two years ago. Then last year, he had 25 passing touchdowns, 14 rushing touchdowns, which, well, it gives you more points in fantasy football. But the main parallel is that both Apple and Allen are now under new management. For the first time in 15 years, Apple has a new CEO, John Ternus, who officially took over from Tim Cook last week. Similarly, at the end of last season, the Buffalo Bills let go of former head coach Sean McDermott, nine seasons, promoting former offensive coordinator Joe Brady to the position.
Cramer's comparison highlights Apple Inc.'s (NASDAQ:AAPL) distinct structural advantage within the Magnificent Seven. While rival mega-cap tech peers sink hundreds of billions of dollars into capital-intensive data center builds and proprietary AI infrastructure, the company has adopted a resource-efficient model. By integrating third-party AI capabilities while guarding its massive, high-intent global user base, the company limits its exposure to heavy upfront capital expenditure and margin compression.
Apple Inc.'s (NASDAQ:AAPL) high user retention continues to drive significant cash flow generation. Its hardware and premium services loop creates deep consumer loyalty, allowing the company to maintain pricing power and high profitability without taking on the aggressive infrastructure risk carried by other major technology players.
#Apple #aapl #last
We know how to draft on Mad Money so, break out your pen and paper and let's get started. Now, we got to start with our quarterback in fantasy… You're typically only playing one quarterback per week. And what you want here is consistent production. That's why for the past several years, I've picked Apple as my fantasy stock football QB. As always, own it, don't trade it. Not only does Apple make the most beloved products in the world, they're playing a very different game from their mega cap peers. Everybody else is spending hundreds of billions of dollars on AI. Apple's spending next to nothing, just partnering with AI companies. They desperately want access to Apple's massive user base.
To me, that makes Apple a lot less risky than the other members of the Magnificent Seven. To put that in NFL terms, Apple reminds me of Josh Allen, the quarterback for the Buffalo Bills. Allen's a known quantity. He was the league MVP two years ago. Then last year, he had 25 passing touchdowns, 14 rushing touchdowns, which, well, it gives you more points in fantasy football. But the main parallel is that both Apple and Allen are now under new management. For the first time in 15 years, Apple has a new CEO, John Ternus, who officially took over from Tim Cook last week. Similarly, at the end of last season, the Buffalo Bills let go of former head coach Sean McDermott, nine seasons, promoting former offensive coordinator Joe Brady to the position.
Cramer's comparison highlights Apple Inc.'s (NASDAQ:AAPL) distinct structural advantage within the Magnificent Seven. While rival mega-cap tech peers sink hundreds of billions of dollars into capital-intensive data center builds and proprietary AI infrastructure, the company has adopted a resource-efficient model. By integrating third-party AI capabilities while guarding its massive, high-intent global user base, the company limits its exposure to heavy upfront capital expenditure and margin compression.
Apple Inc.'s (NASDAQ:AAPL) high user retention continues to drive significant cash flow generation. Its hardware and premium services loop creates deep consumer loyalty, allowing the company to maintain pricing power and high profitability without taking on the aggressive infrastructure risk carried by other major technology players.
#Apple #aapl #last


4 days ago
Apple is skipping the base iPhone 18 this fall in favor of three premium devices: the iPhone 18 Pro, the iPhone 18 Pro Max, and its first foldable — rumored to be called the iPhone Ultra, Duo, or Fold. The foldable is the headline. It's expected to feature a 7.8-inch internal display, a 5.3-inch external screen, an A20 Pro chip, and a thickness of just 4.5mm unfolded, with pricing estimated between $1,999 and $2,399 and limited initial supply. It marks Apple's entry into the foldable category years after rivals — a potentially major new product cycle for one of the world's most valuable companies.
Here's the pattern every ETF investor should understand before today's close. Nearly two decades of data show that Apple tends to "sell the news" on launch day itself. AAPL averages a roughly 0.3% decline on iPhone launch days, with a median drop of about 0.6% — the classic case of anticipation being priced in before the reveal.
But the weakness rarely lasts. Apple has averaged a 0.5% gain the very next session (positive in 15 of 24 releases), and the longer-term picture is decisively bullish: AAPL has gained in the 60 days following an iPhone reveal 17 times since the original 2007 launch. The biggest such move was a 20% gain in the 60 days after the iPhone 11 reveal in 2019. In other words, launch-day dips have historically been buying opportunities, not warning signs. **** ysts have also downplayed fears about the ~$2,000 foldable price tag, arguing a premium halo product is unlikely to dent Apple's overall economics.
Apple is not just a stock — it's one of the largest weights in the entire ETF universe. As one of the biggest companies in the world, it sits near the top of the S&P 500, the Nasdaq-100, and virtually every technology index. That means a move in AAPL ripples through hundreds of funds, and millions of investors have significant Apple exposure without realizing it. When Apple moves on event day, these are the ETFs that move with it.
A handful of funds carry outsized Apple weights and will feel today's move most acutely. GXPT (Global X PureCap MSCI Information Technology ETF) holds roughly 19.2% in Apple — the highest of any diversified fund. FTEC (Fidelity MSCI Information Technology Index ETF) holds about 16.3%, VGT (Vanguard Information Technology ETF) about 16.2%, TRUT (VanEck Technology TruSector ETF) roughly 15.1%, and TOPT (iShares Top 20 U.S. Stocks ETF) around 14.5%. For these funds, Apple is a dominant driver of daily returns.
#iphone #foldable #launch #aapl
Here's the pattern every ETF investor should understand before today's close. Nearly two decades of data show that Apple tends to "sell the news" on launch day itself. AAPL averages a roughly 0.3% decline on iPhone launch days, with a median drop of about 0.6% — the classic case of anticipation being priced in before the reveal.
But the weakness rarely lasts. Apple has averaged a 0.5% gain the very next session (positive in 15 of 24 releases), and the longer-term picture is decisively bullish: AAPL has gained in the 60 days following an iPhone reveal 17 times since the original 2007 launch. The biggest such move was a 20% gain in the 60 days after the iPhone 11 reveal in 2019. In other words, launch-day dips have historically been buying opportunities, not warning signs. **** ysts have also downplayed fears about the ~$2,000 foldable price tag, arguing a premium halo product is unlikely to dent Apple's overall economics.
Apple is not just a stock — it's one of the largest weights in the entire ETF universe. As one of the biggest companies in the world, it sits near the top of the S&P 500, the Nasdaq-100, and virtually every technology index. That means a move in AAPL ripples through hundreds of funds, and millions of investors have significant Apple exposure without realizing it. When Apple moves on event day, these are the ETFs that move with it.
A handful of funds carry outsized Apple weights and will feel today's move most acutely. GXPT (Global X PureCap MSCI Information Technology ETF) holds roughly 19.2% in Apple — the highest of any diversified fund. FTEC (Fidelity MSCI Information Technology Index ETF) holds about 16.3%, VGT (Vanguard Information Technology ETF) about 16.2%, TRUT (VanEck Technology TruSector ETF) roughly 15.1%, and TOPT (iShares Top 20 U.S. Stocks ETF) around 14.5%. For these funds, Apple is a dominant driver of daily returns.
#iphone #foldable #launch #aapl


4 days ago
Trading near $45 a share, Boston Scientific (BSX) sits roughly 58% below its 52-week peak. Instead of buying the dip outright, selling cash-secured put options allows investors to generate immediate income while locking in an even deeper entry point. However, this trade only works if you are comfortable holding the stock through a turnaround, particularly as both of the company's core growth drivers—WATCHMAN and electrophysiology—face sudden operational headwinds.
Sell a put option on BSX expiring 9/17/2027, with a strike price of $30.
Collect roughly $135 in premium per contract (each contract covers 100 shares).
That works out to about 4.4% annualized on the $3,000 of cash you set aside to secure the trade.
Park that collateral in Treasury bills or a Treasury money-market fund yielding roughly 3.9%, boosting your total cash-secured return to about 8.3%.
#secured #works #trading #scientific
Sell a put option on BSX expiring 9/17/2027, with a strike price of $30.
Collect roughly $135 in premium per contract (each contract covers 100 shares).
That works out to about 4.4% annualized on the $3,000 of cash you set aside to secure the trade.
Park that collateral in Treasury bills or a Treasury money-market fund yielding roughly 3.9%, boosting your total cash-secured return to about 8.3%.
#secured #works #trading #scientific


4 days ago
Apple's (AAPL) rivals in China are not waiting for it to make the first move. Just days before Apple's anticipated debut of its first foldable iPhone at its Sept. 9 event, Huawei and Xiaomi (XIACF) rolled out premium foldable devices of their own.
The timing gives both companies a chance to grab attention before Apple's launch. Huawei is launching the Mate XT 2, a trifold device that packs a phone and a tablet-sized screen into one body, while Xiaomi is close behind with the Xiaomi 18 Fold, a passport-style handset that looks a lot like what Apple is expected to show. So, both companies are trying to enter the high-end foldable market before Apple arrives.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ******* ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#xiaomi #huawei #aapl
The timing gives both companies a chance to grab attention before Apple's launch. Huawei is launching the Mate XT 2, a trifold device that packs a phone and a tablet-sized screen into one body, while Xiaomi is close behind with the Xiaomi 18 Fold, a passport-style handset that looks a lot like what Apple is expected to show. So, both companies are trying to enter the high-end foldable market before Apple arrives.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ******* ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#xiaomi #huawei #aapl

4 days ago
Ayyoub Bouaddi has handled everything thrown at him since joining Manchester City with remarkable composure - though his leisurely strolls may need rerouting after recent events.
The Moroccan midfielder has been able to traverse the city center's sidewalks over recent weeks, moving about unnoticed and unrecognized despite sealing an £85 million ($117 million) transfer from Lille. However, the teenager with a distinctive look can't remain incognito much longer after delivering an impressive performance in his maiden start for the Blues.
City shelled out a premium price for Bouaddi - exceeding what rival clubs were prepared to pay - because they were confident he could slot directly into a squad that lost Rodri and Bernardo Silva from their engine room during the summer window. The 18-year-old has been gradually integrated but entered the lineup for the UEFA Champions League fixture in Porto, replacing £116 million ($155.2 million) signing Elliot Anderson.
-Credit:NurPhoto, NurPhoto via Getty Images
While more experienced teammates around him struggled, Bouaddi provided a steadying influence from kickoff and moved effortlessly across the turf to give Enzo Maresca's squad command of proceedings. The manager was all smiles when questioned about the player postgame and joined a growing roster of those who've encountered Bouaddi in praising him as an exceptional prospect.
#manchester #lille
The Moroccan midfielder has been able to traverse the city center's sidewalks over recent weeks, moving about unnoticed and unrecognized despite sealing an £85 million ($117 million) transfer from Lille. However, the teenager with a distinctive look can't remain incognito much longer after delivering an impressive performance in his maiden start for the Blues.
City shelled out a premium price for Bouaddi - exceeding what rival clubs were prepared to pay - because they were confident he could slot directly into a squad that lost Rodri and Bernardo Silva from their engine room during the summer window. The 18-year-old has been gradually integrated but entered the lineup for the UEFA Champions League fixture in Porto, replacing £116 million ($155.2 million) signing Elliot Anderson.
-Credit:NurPhoto, NurPhoto via Getty Images
While more experienced teammates around him struggled, Bouaddi provided a steadying influence from kickoff and moved effortlessly across the turf to give Enzo Maresca's squad command of proceedings. The manager was all smiles when questioned about the player postgame and joined a growing roster of those who've encountered Bouaddi in praising him as an exceptional prospect.
#manchester #lille

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

4 days ago
CVS Health (NYSE: CVS) dealt with significant headwinds after the COVID-19 pandemic. The company's financial results suffered as sales of coronavirus-related products (such as diagnostic tests) declined, while expenses in its insurance business rose substantially, resulting in lower profits and margins. However, CVS Health has done a good job of addressing those problems, and the stock has rebounded. Shares are up 31% over the past 12 months. Wall Street thinks there may be even more upside on the horizon. CVS Health's average price target is $116.04 (according to Yahoo! Finance), implying a meaningful 20% upside from current levels. Is now a great time to buy the stock?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Over the past 18 months (or so), CVS Health has implemented several initiatives that have helped improve its business. For instance, the company closed dozens of stores, many of which were unprofitable. The pharmacy chain specialist also scaled back its insurance division, notably by exiting the Affordable Care Act marketplace. The results have been pretty impressive. Consider the company's second-quarter results. CVS Health's revenue increased by a healthy 7.3% year over year to $106.1 billion.
Adjusted earnings per share were $2.58, 42.5% higher than the year-ago period. Note the improvement in CVS Health's healthcare benefits segment, which offers health insurance services. Operating expenses as a percentage of revenue declined slightly to 12.4%, down from 12.5% in the prior-year quarter, even as revenue grew 3.5% year over year. And operating margins within this unit came in at 5.8%, up from the 2.8% reported in the year-ago period. Also, CVS Health's medical benefits ratio -- the percentage of insurance premiums the company spent on medical care (the lower the better) -- declined to 87.4% in the second quarter, down from 89.9% in Q2 2025.
CVS Health also increased its guidance for the full fiscal year 2026. The company now expects its adjusted EPS to fall between $7.90 and $8.10, up from its previous range of between $7.30 to $7.50. The company is also now projecting cash flow from operations of at least $11.5 billion, up from the previous lower bound of $9.5 billion. These are signs of a much-improved business.
#insurance
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Over the past 18 months (or so), CVS Health has implemented several initiatives that have helped improve its business. For instance, the company closed dozens of stores, many of which were unprofitable. The pharmacy chain specialist also scaled back its insurance division, notably by exiting the Affordable Care Act marketplace. The results have been pretty impressive. Consider the company's second-quarter results. CVS Health's revenue increased by a healthy 7.3% year over year to $106.1 billion.
Adjusted earnings per share were $2.58, 42.5% higher than the year-ago period. Note the improvement in CVS Health's healthcare benefits segment, which offers health insurance services. Operating expenses as a percentage of revenue declined slightly to 12.4%, down from 12.5% in the prior-year quarter, even as revenue grew 3.5% year over year. And operating margins within this unit came in at 5.8%, up from the 2.8% reported in the year-ago period. Also, CVS Health's medical benefits ratio -- the percentage of insurance premiums the company spent on medical care (the lower the better) -- declined to 87.4% in the second quarter, down from 89.9% in Q2 2025.
CVS Health also increased its guidance for the full fiscal year 2026. The company now expects its adjusted EPS to fall between $7.90 and $8.10, up from its previous range of between $7.30 to $7.50. The company is also now projecting cash flow from operations of at least $11.5 billion, up from the previous lower bound of $9.5 billion. These are signs of a much-improved business.
#insurance
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

4 days ago
China's largest new energy vehicle (NEV) manufacturer BYD Auto reported an 18% rise in global sales to 440,293 units in August 2026, marking the fourth consecutive month of growth for the company following eight months of declines. Last month's growth followed a 22% surge in July, as overseas sales continued to strengthen - offsetting continued weak demand and fast-rising competition in its home market.
Domestic sales fell by 14% year-on-year to 250,827 units in August, while overseas sales surged by 134% to 189,466 vehicles, accounting for 43% of the company's global sales.
In the first eight months of 2026, BYD sold a total of 2,668,015 vehicles globally, down by almost 7% from last year's 2,863,876 units, with domestic sales plunging by 33% to 1,505,755 units from 2,233,148 units in the same period last year. Overseas sales surged by 86% to 1,162,260 units year-to-date, after growing by 130% to 630,728 units previously.
BYD is in the process of switching its products to its second-generation Blade Battery, which features flash charging capabilities. The transition has caused some production bottlenecks in recent months, according to local reports. The company is also expanding its presence in the premium BEV segment, with the launch of the Dynasty Da Tang D-segment flagship SUV in July.
BYD has set a target of further increasing its overseas sales to 2.5 million vehicles in 2027, up from an expected 2.0 million units in 2026, helped by an expanded shipping fleet and rising production abroad, with the company's plant in Hungary scheduled to become operational in the fourth quarter of 2026.
#sales
Domestic sales fell by 14% year-on-year to 250,827 units in August, while overseas sales surged by 134% to 189,466 vehicles, accounting for 43% of the company's global sales.
In the first eight months of 2026, BYD sold a total of 2,668,015 vehicles globally, down by almost 7% from last year's 2,863,876 units, with domestic sales plunging by 33% to 1,505,755 units from 2,233,148 units in the same period last year. Overseas sales surged by 86% to 1,162,260 units year-to-date, after growing by 130% to 630,728 units previously.
BYD is in the process of switching its products to its second-generation Blade Battery, which features flash charging capabilities. The transition has caused some production bottlenecks in recent months, according to local reports. The company is also expanding its presence in the premium BEV segment, with the launch of the Dynasty Da Tang D-segment flagship SUV in July.
BYD has set a target of further increasing its overseas sales to 2.5 million vehicles in 2027, up from an expected 2.0 million units in 2026, helped by an expanded shipping fleet and rising production abroad, with the company's plant in Hungary scheduled to become operational in the fourth quarter of 2026.
#sales

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

4 days ago
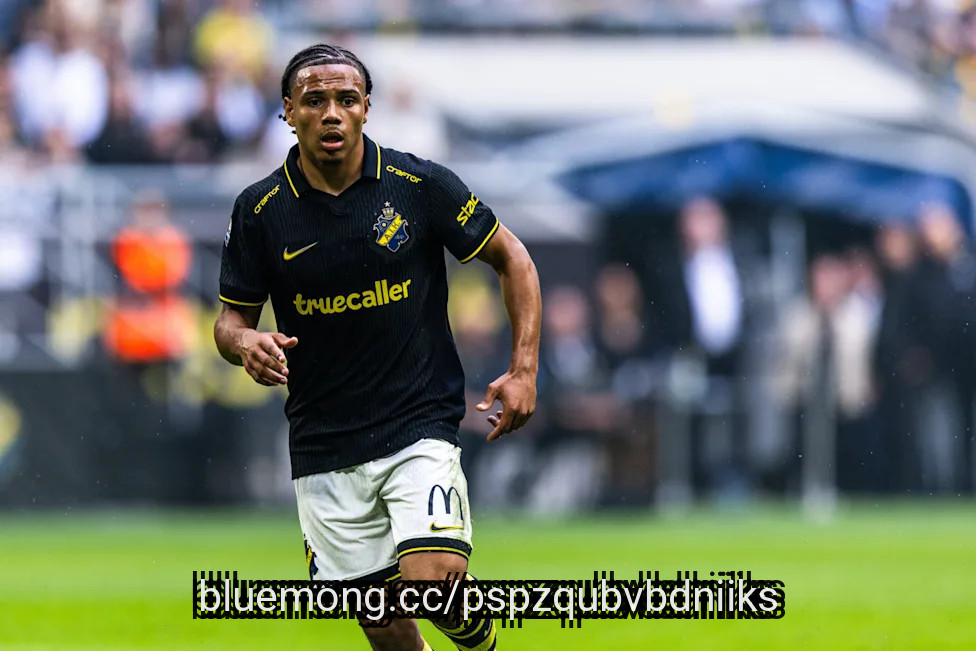
Arsenal are among the clubs keeping a close watch on AIK teenager Kevin Filling, with the 17-year-old increasingly viewed as one of the more intriguing young attacking prospects in Sweden.
According to Caught Offside, **** nal, Chelsea, Liverpool and Juventus have all tracked the forward in recent weeks, with scouts reported to have attended AIK matches in Stockholm. The interest centres on a player described as a potential "project signing", a label that feels particularly relevant in **** nal's case.
Filling has already stepped into senior football and is drawing attention for a profile that clubs value highly. His blend of size, pace and adaptability makes him an attractive option in a market where elite teenage talent can become significantly more expensive in a short **** e of time. Standing at around 1.85m, he can play through the middle or from the left as an inverted winger, while his "physical strength, acceleration and versatility" are understood to be among the key reasons for the growing demand.
There is a clear logic to **** nal's interest. The report states that **** nal "view Filling as a long-term project signing" and that he could be "developed carefully and potentially become part of the first-team picture over the next few seasons". That aligns with a recruitment approach focused on securing premium young talent before it fully explodes in value.
Photo: IMAGO
#filling #young #become
According to Caught Offside, **** nal, Chelsea, Liverpool and Juventus have all tracked the forward in recent weeks, with scouts reported to have attended AIK matches in Stockholm. The interest centres on a player described as a potential "project signing", a label that feels particularly relevant in **** nal's case.
Filling has already stepped into senior football and is drawing attention for a profile that clubs value highly. His blend of size, pace and adaptability makes him an attractive option in a market where elite teenage talent can become significantly more expensive in a short **** e of time. Standing at around 1.85m, he can play through the middle or from the left as an inverted winger, while his "physical strength, acceleration and versatility" are understood to be among the key reasons for the growing demand.
There is a clear logic to **** nal's interest. The report states that **** nal "view Filling as a long-term project signing" and that he could be "developed carefully and potentially become part of the first-team picture over the next few seasons". That aligns with a recruitment approach focused on securing premium young talent before it fully explodes in value.
Photo: IMAGO
#filling #young #become
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

4 days ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance was anchored by the 'Reimagined 200' stores, which outperformed the broader fleet by 80 basis points, validating the strategy of enhanced staffing and curated ***** ortments.
Bloomingdale's achieved its highest second-quarter sales volume in its 154-year history, driven by a 1,700 basis point step-change on a two-year stack as it captures market share in premium and luxury segments.
Management attributed the 9% increase in Average Unit Retail (AUR) to a deliberate shift toward 'fashion authority' positioning, prioritizing better/best brand tiers over high-volume, low-margin units.
The company successfully leveraged enterprise-wide capabilities, such as Macy's is leveraging its marketplace business to fill white-space opportunities, while dermatological skincare brands like SkinCeuticals drove growth at Bluemercury.
#volume #year #management #average
Performance was anchored by the 'Reimagined 200' stores, which outperformed the broader fleet by 80 basis points, validating the strategy of enhanced staffing and curated ***** ortments.
Bloomingdale's achieved its highest second-quarter sales volume in its 154-year history, driven by a 1,700 basis point step-change on a two-year stack as it captures market share in premium and luxury segments.
Management attributed the 9% increase in Average Unit Retail (AUR) to a deliberate shift toward 'fashion authority' positioning, prioritizing better/best brand tiers over high-volume, low-margin units.
The company successfully leveraged enterprise-wide capabilities, such as Macy's is leveraging its marketplace business to fill white-space opportunities, while dermatological skincare brands like SkinCeuticals drove growth at Bluemercury.
#volume #year #management #average
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

4 days ago
If you hold Pfizer (PFE) or Zoetis (ZTS), you hold the same idea: a branded medicine becomes a standard of care and keeps earning for years, in people or in animals. That is where it stops. Pfizer is buying replacements for older drugs losing exclusivity. Zoetis is cutting its effective price to keep the franchises it has. Same bet, two opposite defenses.
Pfizer lifted the midpoint of its 2026 revenue guidance by $500 million while cutting its COVID-19 revenue expectation to about $4 billion from about $5 billion. The rest of the company covered that gap: excluding COVID products, the underlying business grew 5% operationally in the second quarter of 2026, with Eliquis and Padcev among the drivers management named.
Zoetis cut its 2026 outlook and now expects revenue to decline 1% to 3% on an organic operational basis. Management said sales trends through July had not yet indicated market stabilization. Pfizer's raise rests on business it can already see. Zoetis has yet to see visibility on market stabilization.
Pfizer is buying growth and cutting cost, and expects about $9.7 billion in total net savings through 2029. What that funds is an aim, not a guide: a risk-adjusted high single-digit revenue CAGR from year-end 2028 through year-end 2033.
The pipeline behind that aim is expensive to get wrong. A Phase III lung cancer trial that missed its primary endpoint and, to a lesser extent, the removal of revenue projections for Oxbryta led to $4.3 billion of noncash intangible **** et impairments recorded in the second quarter of 2026. While an unadjusted price-to-EBIT comparison puts Pfizer at 23.9 against Zoetis at 9.2, aligning the two on operating income brings them to 9.7x and 9.0x, largely erasing the paying-up premium.
#pfizer #covid
Pfizer lifted the midpoint of its 2026 revenue guidance by $500 million while cutting its COVID-19 revenue expectation to about $4 billion from about $5 billion. The rest of the company covered that gap: excluding COVID products, the underlying business grew 5% operationally in the second quarter of 2026, with Eliquis and Padcev among the drivers management named.
Zoetis cut its 2026 outlook and now expects revenue to decline 1% to 3% on an organic operational basis. Management said sales trends through July had not yet indicated market stabilization. Pfizer's raise rests on business it can already see. Zoetis has yet to see visibility on market stabilization.
Pfizer is buying growth and cutting cost, and expects about $9.7 billion in total net savings through 2029. What that funds is an aim, not a guide: a risk-adjusted high single-digit revenue CAGR from year-end 2028 through year-end 2033.
The pipeline behind that aim is expensive to get wrong. A Phase III lung cancer trial that missed its primary endpoint and, to a lesser extent, the removal of revenue projections for Oxbryta led to $4.3 billion of noncash intangible **** et impairments recorded in the second quarter of 2026. While an unadjusted price-to-EBIT comparison puts Pfizer at 23.9 against Zoetis at 9.2, aligning the two on operating income brings them to 9.7x and 9.0x, largely erasing the paying-up premium.
#pfizer #covid

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

4 days ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Delivered record Q2 sales outside of the holiday period despite a 'K-shaped' economy and aggressive industry-wide promotional activity.
Performance was bifurcated by price point, with double-digit growth in premium configurations over $6,000 while the under-$6,000 segment remained pressured by inflation and interest rates.
Management is pivoting from a single-platform focus to a multi-platform 'Sactionals sofa company' strategy to address broader market segments and aesthetic preferences.
Operational efficiency improved through the 'Fuel for Growth' program and sourcing diversification, helping to insulate the P&L from volatile ocean freight and domestic shipping costs.
#management
Delivered record Q2 sales outside of the holiday period despite a 'K-shaped' economy and aggressive industry-wide promotional activity.
Performance was bifurcated by price point, with double-digit growth in premium configurations over $6,000 while the under-$6,000 segment remained pressured by inflation and interest rates.
Management is pivoting from a single-platform focus to a multi-platform 'Sactionals sofa company' strategy to address broader market segments and aesthetic preferences.
Operational efficiency improved through the 'Fuel for Growth' program and sourcing diversification, helping to insulate the P&L from volatile ocean freight and domestic shipping costs.
#management
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

4 days ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance outperformance was driven by disciplined channel management, with legacy field inventory reduced by approximately 30% year-over-year to improve turns to better than pre-pandemic levels.
The MasterCraft brand's success was anchored by the next-generation X Series rollout, which drove a favorable premium mix and offset lower industry-wide volumes.
Management attributed the 730 basis point expansion in legacy adjusted EBITDA margin to improved fixed cost absorption on higher unit volumes and lower promotional discounting.
The combination with Chaparral and Robalo is framed as a transformational pivot to a larger, more diversified platform spanning inland and coastal markets with broader price points.
#management #lower #NVIDIA
Performance outperformance was driven by disciplined channel management, with legacy field inventory reduced by approximately 30% year-over-year to improve turns to better than pre-pandemic levels.
The MasterCraft brand's success was anchored by the next-generation X Series rollout, which drove a favorable premium mix and offset lower industry-wide volumes.
Management attributed the 730 basis point expansion in legacy adjusted EBITDA margin to improved fixed cost absorption on higher unit volumes and lower promotional discounting.
The combination with Chaparral and Robalo is framed as a transformational pivot to a larger, more diversified platform spanning inland and coastal markets with broader price points.
#management #lower #NVIDIA

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
4 days ago
USAR drops 4% and MP Materials falls 5% as Trump-Xi summit hopes erode the scarcity premium driving domestic rare earth valuations.
REMX sinks 5% versus SPY's 0.5% dip, confirming a targeted sector repricing rather than a broad market risk-off move.
USA Rare Earth broke ground on a $1.2 billion South Carolina facility Wednesday, yet diplomatic headlines overshadowed the milestone the very next day.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and MP Materials didn't make the cut. Enter your email to see the names that beat MP. The report is free. Enter your email and see if any of your stocks made the cut.
Domestic rare earth stocks are sliding Thursday midday as fresh diplomatic warming between Washington and Beijing chips away at the scarcity premium powering the trade. USA Rare Earth (NASDAQ:USAR) stock is down 4% to $16.36, and MP Materials (NYSE:MP) shares are down 5% to $51.85. Both names sit near the front of the U.S. critical-minerals theme and tend to move hard when the geopolitical setup shifts.
#market
REMX sinks 5% versus SPY's 0.5% dip, confirming a targeted sector repricing rather than a broad market risk-off move.
USA Rare Earth broke ground on a $1.2 billion South Carolina facility Wednesday, yet diplomatic headlines overshadowed the milestone the very next day.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and MP Materials didn't make the cut. Enter your email to see the names that beat MP. The report is free. Enter your email and see if any of your stocks made the cut.
Domestic rare earth stocks are sliding Thursday midday as fresh diplomatic warming between Washington and Beijing chips away at the scarcity premium powering the trade. USA Rare Earth (NASDAQ:USAR) stock is down 4% to $16.36, and MP Materials (NYSE:MP) shares are down 5% to $51.85. Both names sit near the front of the U.S. critical-minerals theme and tend to move hard when the geopolitical setup shifts.
#market

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

6 days ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and ******* ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
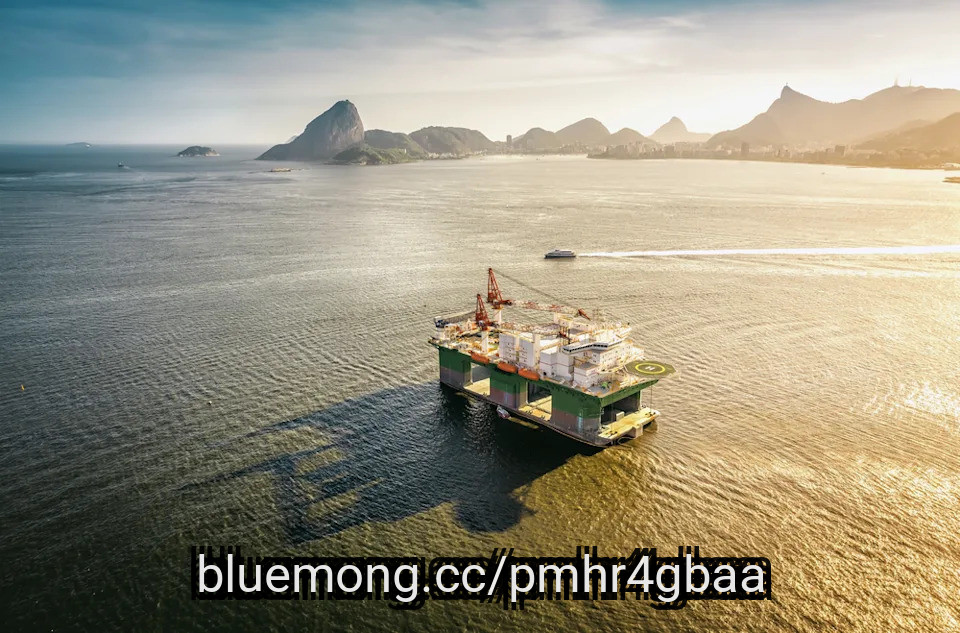
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Transocean Ltd. (NYSE:RIG) while discussing its investment in Valaris. Transocean Ltd. is an offshore drilling contractor. Moerus discussed the company in connection with its agreement to acquire Valaris in an all-stock transaction, which it said helped surface significant latent value in Valaris. The one-month return of Transocean Ltd. (NYSE:RIG) was 2.53% while its shares traded between $3.01 and $7.66 over the last 52 weeks. On September 7, 2026, Transocean Ltd. (NYSE:RIG) stock closed at approximately $5.85 per share, with a market capitalization of about $6.56 billion.
Moerus Worldwide Fund stated the following regarding Transocean Ltd. (NYSE:RIG) in its Q2 2026 investor letter:
"Shares of this U.S.-based provider of offshore drilling services surged in response to the February 9th announcement that the company had agreed to be acquired by Transocean Ltd. (NYSE:RIG) in an all-stock transaction, which was priced at a roughly 32% premium to Valaris' stock price (based on the previous day's closing price of each stock)."
#valaris
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Transocean Ltd. (NYSE:RIG) while discussing its investment in Valaris. Transocean Ltd. is an offshore drilling contractor. Moerus discussed the company in connection with its agreement to acquire Valaris in an all-stock transaction, which it said helped surface significant latent value in Valaris. The one-month return of Transocean Ltd. (NYSE:RIG) was 2.53% while its shares traded between $3.01 and $7.66 over the last 52 weeks. On September 7, 2026, Transocean Ltd. (NYSE:RIG) stock closed at approximately $5.85 per share, with a market capitalization of about $6.56 billion.
Moerus Worldwide Fund stated the following regarding Transocean Ltd. (NYSE:RIG) in its Q2 2026 investor letter:
"Shares of this U.S.-based provider of offshore drilling services surged in response to the February 9th announcement that the company had agreed to be acquired by Transocean Ltd. (NYSE:RIG) in an all-stock transaction, which was priced at a roughly 32% premium to Valaris' stock price (based on the previous day's closing price of each stock)."
#valaris

6 days ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and ****** ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
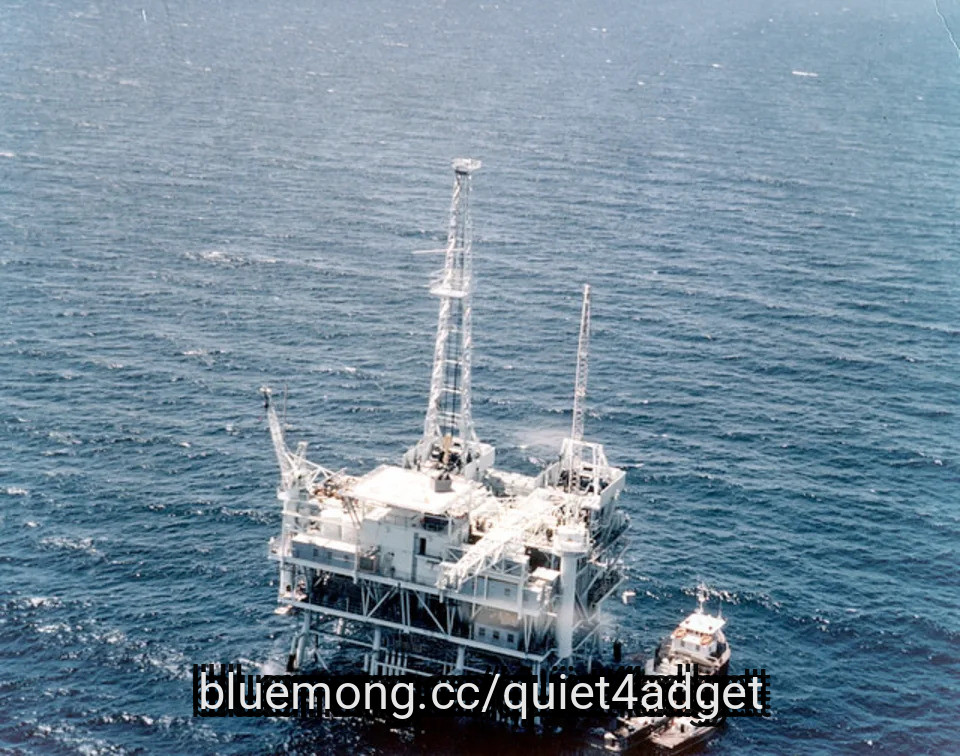
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Valaris Limited (NYSE:VAL). Valaris Limited is a U.S.-based provider of offshore drilling services. Moerus described Valaris as its largest individual contributor to performance in the first half of 2026. The one-month return of Valaris Limited (NYSE:VAL) was 1.62% while its shares traded between $46.70 and $114.12 over the last 52 weeks. On September 7, 2026, Valaris Limited (NYSE:VAL) stock closed at approximately $86.74 per share, with a market capitalization of about $6.03 billion.
Moerus Worldwide Fund stated the following regarding Valaris Limited (NYSE:VAL) in its Q2 2026 investor letter:
"For example, consider Valaris Limited (NYSE:VAL), the largest individual contributor to performance in H1. Shares of this U.S.-based provider of offshore drilling services surged in response to the February 9th announcement that the company had agreed to be acquired by Transocean in an all-stock transaction, which was priced at a roughly 32% premium to Valaris' stock price (based on the previous day's closing price of each stock). Valaris was added to the Fund in early 2025 following a slide in its share price, amid then-subdued oil prices and what we believed to be a temporary lull in offshore drilling activity caused by support infrastructure constraints (among other factors)."
#worldwide #Stock
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Valaris Limited (NYSE:VAL). Valaris Limited is a U.S.-based provider of offshore drilling services. Moerus described Valaris as its largest individual contributor to performance in the first half of 2026. The one-month return of Valaris Limited (NYSE:VAL) was 1.62% while its shares traded between $46.70 and $114.12 over the last 52 weeks. On September 7, 2026, Valaris Limited (NYSE:VAL) stock closed at approximately $86.74 per share, with a market capitalization of about $6.03 billion.
Moerus Worldwide Fund stated the following regarding Valaris Limited (NYSE:VAL) in its Q2 2026 investor letter:
"For example, consider Valaris Limited (NYSE:VAL), the largest individual contributor to performance in H1. Shares of this U.S.-based provider of offshore drilling services surged in response to the February 9th announcement that the company had agreed to be acquired by Transocean in an all-stock transaction, which was priced at a roughly 32% premium to Valaris' stock price (based on the previous day's closing price of each stock). Valaris was added to the Fund in early 2025 following a slide in its share price, amid then-subdued oil prices and what we believed to be a temporary lull in offshore drilling activity caused by support infrastructure constraints (among other factors)."
#worldwide #Stock
6 days ago
Medicare calculates Part B and Part D surcharges using income from two years prior, so a profitable ***** et sale can trigger higher premiums long after the money is spent.
IRMAA resets annually, so a one-time income spike typically raises premiums for only one or two years before fading as normal income returns.
Voluntary ***** et sales don't qualify for SSA-44 relief, making pre-sale income planning the only real tool to minimize Medicare surcharges.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
Picture a longtime fan who bought a personal seat license two decades ago, giving him the right to buy the same season tickets year after year. He has climbed the same stadium stairs every fall, watched his knees start to complain and finally decided the ticket rights were worth more to him as cash than as seats he uses a handful of times each season.
#income #medicare #premiums #tool
IRMAA resets annually, so a one-time income spike typically raises premiums for only one or two years before fading as normal income returns.
Voluntary ***** et sales don't qualify for SSA-44 relief, making pre-sale income planning the only real tool to minimize Medicare surcharges.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
Picture a longtime fan who bought a personal seat license two decades ago, giving him the right to buy the same season tickets year after year. He has climbed the same stadium stairs every fall, watched his knees start to complain and finally decided the ticket rights were worth more to him as cash than as seats he uses a handful of times each season.
#income #medicare #premiums #tool