

1 day ago
During the September 3 episode of Mad Money, Jim Cramer mentioned Microsoft Corporation (NASDAQ:MSFT) for its unconventional approach to powering hyperscale data centers in partnership with Chevron Corporation (NYSE:CVX). He said:
How about Microsoft? Look, Mr. Softee is getting religion. They've realized that by giving us more disclosure on Azure, their cloud infrastructure business, we'll find more things to like. They're right. In the end, I come to praise Microsoft CFO Amy Hood, not bury her. They've been very clever getting power for the data centers, pumping it right out of the Permian. They got this deal with Chevron as a partner… 2.67 gigawatts. No one's talking about it. It's the cleanest behind the meter plan for power I have seen yet. People even, and this is not a stretch, I'm not kidding, people even like Copilot.
CFO Amy Hood provided Wall Street with a much clearer look at actual cloud demand by breaking down detailed Azure growth metrics and data center capacity constraints. At the same time, enterprise adoption of Microsoft 365 Copilot is moving past initial trials, with major corporations deploying the AI ***** istant across workforce segments.
A major highlight of the company's infrastructure strategy is a twenty-year agreement with Chevron Corporation (NYSE:CVX) for a proposed 2.67-gigawatt natural gas power plant in West Texas. Designed to supply dedicated off-grid electricity directly to a hyperscale data center in the Permian Basin, the project bypasses regional grid transmission queues to secure reliable power for continuous AI workloads. Microsoft Corporation's (NASDAQ:MSFT) president of Cloud Operations + Innovation, Noelle Walsh, commented:
Our agreement with Chevron helps ensure we'll have dedicated, large-scale power to support the evolution and reliability of advanced compute. Through this partnership, we're delighted to grow with and become a deeper part of the West Texas community.
#chevron #power #they 've
How about Microsoft? Look, Mr. Softee is getting religion. They've realized that by giving us more disclosure on Azure, their cloud infrastructure business, we'll find more things to like. They're right. In the end, I come to praise Microsoft CFO Amy Hood, not bury her. They've been very clever getting power for the data centers, pumping it right out of the Permian. They got this deal with Chevron as a partner… 2.67 gigawatts. No one's talking about it. It's the cleanest behind the meter plan for power I have seen yet. People even, and this is not a stretch, I'm not kidding, people even like Copilot.
CFO Amy Hood provided Wall Street with a much clearer look at actual cloud demand by breaking down detailed Azure growth metrics and data center capacity constraints. At the same time, enterprise adoption of Microsoft 365 Copilot is moving past initial trials, with major corporations deploying the AI ***** istant across workforce segments.
A major highlight of the company's infrastructure strategy is a twenty-year agreement with Chevron Corporation (NYSE:CVX) for a proposed 2.67-gigawatt natural gas power plant in West Texas. Designed to supply dedicated off-grid electricity directly to a hyperscale data center in the Permian Basin, the project bypasses regional grid transmission queues to secure reliable power for continuous AI workloads. Microsoft Corporation's (NASDAQ:MSFT) president of Cloud Operations + Innovation, Noelle Walsh, commented:
Our agreement with Chevron helps ensure we'll have dedicated, large-scale power to support the evolution and reliability of advanced compute. Through this partnership, we're delighted to grow with and become a deeper part of the West Texas community.
#chevron #power #they 've

1 day ago
Dell Technologies (DELL) stock more than quadrupled over the past year, a 323% gain, against about 18% for the S&P 500, and even Hewlett Packard Enterprise (HPE), up 130.6%, finished far behind. Management had described most of the drivers before the run began: customers sitting on old servers, AI orders that had outrun shipments earlier in the year, and costs falling while sales rose. Those signs could not tell you how far the stock would go.
What Was Dell Seeing In Its Customers' Data Centers?
In February 2025, management said customers still ran a very large base of Dell's 13th and 14th generation servers, ready to be replaced. AI demand, already under discussion then, was exceptionally strong by May 2025, with $12.1 billion of AI server orders in fiscal Q1 2026, more than Dell's AI server shipments for all of fiscal 2025.
In August 2025, management said over 70% of its installed base was running on 14th generation servers or older, and that one 17th generation server could replace six or seven old ones. The results were uneven. In fiscal Q2 2026, traditional server revenue rose again and international demand grew, but demand in North America, its most profitable region, was weak.
Why Were Dell's Costs Falling While Its Sales Rose?
#server
What Was Dell Seeing In Its Customers' Data Centers?
In February 2025, management said customers still ran a very large base of Dell's 13th and 14th generation servers, ready to be replaced. AI demand, already under discussion then, was exceptionally strong by May 2025, with $12.1 billion of AI server orders in fiscal Q1 2026, more than Dell's AI server shipments for all of fiscal 2025.
In August 2025, management said over 70% of its installed base was running on 14th generation servers or older, and that one 17th generation server could replace six or seven old ones. The results were uneven. In fiscal Q2 2026, traditional server revenue rose again and international demand grew, but demand in North America, its most profitable region, was weak.
Why Were Dell's Costs Falling While Its Sales Rose?
#server

1 day ago
Jim Cramer sees Enterprise Products Partners L.P. (NYSE:EPD) as a major beneficiary of the disruption surrounding the Strait of Hormuz, as he said during the September 8 episode of Mad Money:
When I wrote How to Make Money in Any Market… I didn't know that Enterprise Products Partners was going to be the, maybe the single biggest pipeline winner in this country thanks to the war. I didn't see that war coming. The CEO of Enterprise, Jim Teague, has raised awareness for the company's profit opportunity because of the Hormuz closing. The margins of some of its liquids, like ethane to ethylene, ethylene to polyethylene, have soared. As Teague says, the Houston Ship Channel is now just as important as the Strait of Hormuz. Now, there's an endorsement. Stock yields 5.8%.
Enterprise Products Partners L.P. (NYSE:EPD) reported record second-quarter adjusted EBITDA of $2.8 billion, up 17% year over year, while operational distributable cash flow reached a record $2.3 billion, up 21%. Moreover, pipeline volumes reached a record 14.7 million barrels of oil equivalent per day, up 8%, while marine-terminal volumes increased 33% to 2.8 million barrels per day. Co-Chief Executive Officer James Teague said:
Volumes at our marine terminals have returned to normal levels in June and July after the initial rush to backfill volumes affected by hostilities in the Middle East in April and May.
In July, Enterprise Products Partners L.P. (NYSE:EPD) declared a quarterly distribution of $0.56 per unit, or $2.24 annualized, a 2.8% increase from a year earlier. At EPD's September 8 closing price of $38.83, that equates to a yield of approximately 5.8%. The company has increased its distribution for 27 consecutive years. The company's latest investor materials show $6.5 billion of major capital projects under construction. It expects 2026 organic growth capital spending, net of ***** et-sale proceeds, of $2.9 billion to $3.4 billion. The company retained $1.1 billion of DCF for internally funded growth capital expenditures and buybacks.
#partners #hormuz
When I wrote How to Make Money in Any Market… I didn't know that Enterprise Products Partners was going to be the, maybe the single biggest pipeline winner in this country thanks to the war. I didn't see that war coming. The CEO of Enterprise, Jim Teague, has raised awareness for the company's profit opportunity because of the Hormuz closing. The margins of some of its liquids, like ethane to ethylene, ethylene to polyethylene, have soared. As Teague says, the Houston Ship Channel is now just as important as the Strait of Hormuz. Now, there's an endorsement. Stock yields 5.8%.
Enterprise Products Partners L.P. (NYSE:EPD) reported record second-quarter adjusted EBITDA of $2.8 billion, up 17% year over year, while operational distributable cash flow reached a record $2.3 billion, up 21%. Moreover, pipeline volumes reached a record 14.7 million barrels of oil equivalent per day, up 8%, while marine-terminal volumes increased 33% to 2.8 million barrels per day. Co-Chief Executive Officer James Teague said:
Volumes at our marine terminals have returned to normal levels in June and July after the initial rush to backfill volumes affected by hostilities in the Middle East in April and May.
In July, Enterprise Products Partners L.P. (NYSE:EPD) declared a quarterly distribution of $0.56 per unit, or $2.24 annualized, a 2.8% increase from a year earlier. At EPD's September 8 closing price of $38.83, that equates to a yield of approximately 5.8%. The company has increased its distribution for 27 consecutive years. The company's latest investor materials show $6.5 billion of major capital projects under construction. It expects 2026 organic growth capital spending, net of ***** et-sale proceeds, of $2.9 billion to $3.4 billion. The company retained $1.1 billion of DCF for internally funded growth capital expenditures and buybacks.
#partners #hormuz

1 day ago
Fundstrat's Tom Lee took the Future Proof Citywide stage earlier this year with CNBC's Scott Wapner for a session that landed in the middle of a jittery tape that included geopolitical conflict, oil spiking, private credit cracking, and fresh doubts about AI spending. Not too far off where we find ourselves currently, but with an awful lot of volatility and shifting, uncertain outlooks between these six months. While their conversation was a snapshot in time, you can expect more of this kind of sharp, thoughtful ****** ysis next week.
The contrarian take of the session was oil. High crude, Lee argued, is actually constructive for U.S. equities. With the U.S. as a net exporter, our economic competitors are importers, and stalled global growth pushes investors toward growth stocks, which is about 80% of the U.S. market. On AI CapEx, he pushed back on the sticker shock, claiming roughly $700 billion a year is a fraction of the $60 trillion global labor market and small change against daily moves in gold.
Lee also made the case that software had bottomed at the time, that enterprises building their own tools inherit the maintenance burden software companies exist to carry, and that private credit is genuinely bad but not a GFC repeat, with the real fix being taking private companies public rather than pushing private product into retail portfolios. On crypto, his argument shifted from a perspective of digital gold to one of plumbing whereby Wall Street tokenizes ****** ets, and AI agents needing a settlement rail that handles fractions of a penny.
His parting advice was the oldest one in the book, dressed in new clothes: miss the 10 best days of each year and a 16% average return goes to roughly nothing. Danger and opportunity show up together. Staying invested is the perpetual drumbeat of advisors to their clients, but one that needs banging louder when markets feel much less certain.
Future Proof Festival is September 14–17 in Huntington Beach and includes four days on the boardwalk with advisors, ****** et managers, and fintechs building the modern wealth management industry. Find us at the ETF Oasis and don't miss the stellar agenda we've got lined up.
#find #session #credit #time
The contrarian take of the session was oil. High crude, Lee argued, is actually constructive for U.S. equities. With the U.S. as a net exporter, our economic competitors are importers, and stalled global growth pushes investors toward growth stocks, which is about 80% of the U.S. market. On AI CapEx, he pushed back on the sticker shock, claiming roughly $700 billion a year is a fraction of the $60 trillion global labor market and small change against daily moves in gold.
Lee also made the case that software had bottomed at the time, that enterprises building their own tools inherit the maintenance burden software companies exist to carry, and that private credit is genuinely bad but not a GFC repeat, with the real fix being taking private companies public rather than pushing private product into retail portfolios. On crypto, his argument shifted from a perspective of digital gold to one of plumbing whereby Wall Street tokenizes ****** ets, and AI agents needing a settlement rail that handles fractions of a penny.
His parting advice was the oldest one in the book, dressed in new clothes: miss the 10 best days of each year and a 16% average return goes to roughly nothing. Danger and opportunity show up together. Staying invested is the perpetual drumbeat of advisors to their clients, but one that needs banging louder when markets feel much less certain.
Future Proof Festival is September 14–17 in Huntington Beach and includes four days on the boardwalk with advisors, ****** et managers, and fintechs building the modern wealth management industry. Find us at the ETF Oasis and don't miss the stellar agenda we've got lined up.
#find #session #credit #time


1 day ago
By Noel Randewich
Sept 11 (Reuters) - Wall Street ended higher on Friday as oil prices retreated and strong consumer price data reinforced expectations the Federal Reserve will raise interest rates next week to fight inflation.
AI server maker Dell soared 12% to a record high. Hewlett Packard Enterprise jumped 12% and HP gained 8.4% after Oracle's quarterly results topped estimates. Oracle dipped 1.8%.
U.S. consumer prices accelerated last month as the cost of gasoline rebounded after two straight monthly declines, adding pressure on the Fed to tighten monetary policy to fight inflation.
Interest rate futures now reflect a nearly 90% probability that the central bank will raise rates at its policy meeting on Wednesday, according to the CME FedWatch tool. That is up from a 72% likelihood on Thursday.
#raise #rates
Sept 11 (Reuters) - Wall Street ended higher on Friday as oil prices retreated and strong consumer price data reinforced expectations the Federal Reserve will raise interest rates next week to fight inflation.
AI server maker Dell soared 12% to a record high. Hewlett Packard Enterprise jumped 12% and HP gained 8.4% after Oracle's quarterly results topped estimates. Oracle dipped 1.8%.
U.S. consumer prices accelerated last month as the cost of gasoline rebounded after two straight monthly declines, adding pressure on the Fed to tighten monetary policy to fight inflation.
Interest rate futures now reflect a nearly 90% probability that the central bank will raise rates at its policy meeting on Wednesday, according to the CME FedWatch tool. That is up from a 72% likelihood on Thursday.
#raise #rates


1 day ago
Navan Inc. (NASDAQ:NAVN), a global AI-enabled business travel and expense management solutions provider, announced its second quarter results on September 9. The company registered a 45% growth in its gross booking volume (GBV), which reached more than $3 billion. Such growth was fueled by cohort expansion, customer additions and increase in its existing install base. Total revenue for the quarter was $233 million, representing a 35% year-over-year jump. The company's adjusted operating income more than doubled compared to Q2 FY26, and the quarter also saw positive cash flow generation.
Copyright: kentoh / 123RF Stock Photo
Navan delivered robust performance during the recently concluded quarter, driven by a 35% increase in usage revenue which clocked in at $211 million. Subscription revenue was also up 39%, reaching $21 million. Apart from the 45% GBV expansion, a 34% growth was witnessed in Q2 Payment Volume which stood at $1.3 billion. One of the highlights of this quarter was a turnaround in adjusted net income, which jumped from an $8 million loss in Q2 FY26 to a $14 million profit for the reported period.
Enterprise market momentum remained persistent during the period, as the company established partnerships with leading names such as Evotec, Enbridge, ****** mins, and Ingersoll Rand. Significant progress was made around the Navan's proprietary AI agent, Ava, which managed roughly 60% of the total customer interactions. More than 50% of AI calls are now being managed through the company's in-house AI models, compared to 30% for the previous quarter.
Additionally, the company finalized its acquisition of a leading travel management business, Smartrips. This will enable Navan to expand its presence within the swiftly expanding Latin American market. Navan also acquired an AI-led meetings and events management platform, BoomPop.
#volume
Copyright: kentoh / 123RF Stock Photo
Navan delivered robust performance during the recently concluded quarter, driven by a 35% increase in usage revenue which clocked in at $211 million. Subscription revenue was also up 39%, reaching $21 million. Apart from the 45% GBV expansion, a 34% growth was witnessed in Q2 Payment Volume which stood at $1.3 billion. One of the highlights of this quarter was a turnaround in adjusted net income, which jumped from an $8 million loss in Q2 FY26 to a $14 million profit for the reported period.
Enterprise market momentum remained persistent during the period, as the company established partnerships with leading names such as Evotec, Enbridge, ****** mins, and Ingersoll Rand. Significant progress was made around the Navan's proprietary AI agent, Ava, which managed roughly 60% of the total customer interactions. More than 50% of AI calls are now being managed through the company's in-house AI models, compared to 30% for the previous quarter.
Additionally, the company finalized its acquisition of a leading travel management business, Smartrips. This will enable Navan to expand its presence within the swiftly expanding Latin American market. Navan also acquired an AI-led meetings and events management platform, BoomPop.
#volume


1 day ago
Updated Sept 11, 2026, 2:37 pm EDT / Original Sept 11, 2026, 10:54 am EDT
Palantir Technologies
PLTR
+0.83%
is doing a pretty good job of convincing at least one Wall Streeter that businesses will keep adopting its enterprise software—mostly its AI platform—and, in turn, that it will keep growing. Whether the stock will move on the momentum is another question.
PLTR
+0.83%
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#sept #streeter
Palantir Technologies
PLTR
+0.83%
is doing a pretty good job of convincing at least one Wall Streeter that businesses will keep adopting its enterprise software—mostly its AI platform—and, in turn, that it will keep growing. Whether the stock will move on the momentum is another question.
PLTR
+0.83%
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#sept #streeter


1 day ago
SailPoint Inc. (NASDAQ:SAIL), a leading player within the enterprise identity security ***** e, released its fiscal second-quarter 2027 on September 9. The company registered a 25% growth in its annual recurring revenue compared to the same period last year, with figures of $1.231 billion. This was driven by a 36% expansion in SaaS ARR which clocked in at $847 million. SailPoint generated $45 million in operating cash flow during the quarter, along with $37 million in free cash flow.
Burben/Shutterstock.com
Topline for the quarter hit $309 million, exhibiting 17% growth compared to Q2 FY26, amid several underlying factors. The company's subscription revenue reached $295 million, up 19% from a year earlier. SaaS customer base increased by 16%, with net new SaaS ARR jumping 34% year-over-year. It contributed around 97% to overall net new ARR for the business, with AI-driven ARR crossing $70 million mark.
SailPoint's existing customer base showed highly encouraging trends in adopting the company's AI-enabled solutions, with a 60% increase in their annual spend during the second quarter. These solutions were incorporated within more than two-thirds of the completed migrations during the quarter. Quarterly adjusted operating income increased from $54 million a year prior to $63 million, translating into an adjusted margin of 20%.
The quarter also saw key strategic moves by the management. It introduced the SailPoint Identity Security solution, which integrates SailPoint Agentic Fabric with SailPoint Human Fabric to deliver a real-time cycle for discovering and securing intricate digital ecosystems. The company also launched its Cursor Enterprise connector, which enables enterprises to manage both autonomous AI agents and human developers through an integrated control plane.
#year #SaaS #fabric #identity
Burben/Shutterstock.com
Topline for the quarter hit $309 million, exhibiting 17% growth compared to Q2 FY26, amid several underlying factors. The company's subscription revenue reached $295 million, up 19% from a year earlier. SaaS customer base increased by 16%, with net new SaaS ARR jumping 34% year-over-year. It contributed around 97% to overall net new ARR for the business, with AI-driven ARR crossing $70 million mark.
SailPoint's existing customer base showed highly encouraging trends in adopting the company's AI-enabled solutions, with a 60% increase in their annual spend during the second quarter. These solutions were incorporated within more than two-thirds of the completed migrations during the quarter. Quarterly adjusted operating income increased from $54 million a year prior to $63 million, translating into an adjusted margin of 20%.
The quarter also saw key strategic moves by the management. It introduced the SailPoint Identity Security solution, which integrates SailPoint Agentic Fabric with SailPoint Human Fabric to deliver a real-time cycle for discovering and securing intricate digital ecosystems. The company also launched its Cursor Enterprise connector, which enables enterprises to manage both autonomous AI agents and human developers through an integrated control plane.
#year #SaaS #fabric #identity

1 day ago
Palo Alto Networks, Inc. (NASDAQ:PANW) is entering its fiscal 2027 with strong momentum, particularly in next-generation security. But investors now demand more from the cybersecurity company after its stock rallied sharply.
On September 7, PhillipCapital downgraded Palo Alto stock to Neutral from Accumulate but raised the price target to $346 from $320.
PhillipCapital's move captures the central investment debate. It's that Palo Alto's opportunities are compelling, but the stock's roughly 160% rise from its February low to its August peak has raised the bar for further gains.
Palo Alto Networks, Inc. (NASDAQ:PANW)'s revenue rose 34% YoY to $3.4 billion in fiscal 2026 fourth quarter. More importantly, Next-Generation Security ARR (NGS ARR) surged 63% to $9.10 billion. The company added nearly $1 billion of net new NGS ARR in the quarter. The company targets $20 billion in NGS ARR by fiscal 2030, as it expects platformization and AI infrastructure investment to continue driving growth.
More than 65% of Palo Alto's NGS ARR comes from platformized customers. Meanwhile, AI is expanding the addressable market. As enterprises deploy agents, Palo Alto offerings such as Prisma AIRS and Cortex, alongside CyberArk's identity-security platform, can address emerging needs.
#palo #company #NASDAQ #PANW
On September 7, PhillipCapital downgraded Palo Alto stock to Neutral from Accumulate but raised the price target to $346 from $320.
PhillipCapital's move captures the central investment debate. It's that Palo Alto's opportunities are compelling, but the stock's roughly 160% rise from its February low to its August peak has raised the bar for further gains.
Palo Alto Networks, Inc. (NASDAQ:PANW)'s revenue rose 34% YoY to $3.4 billion in fiscal 2026 fourth quarter. More importantly, Next-Generation Security ARR (NGS ARR) surged 63% to $9.10 billion. The company added nearly $1 billion of net new NGS ARR in the quarter. The company targets $20 billion in NGS ARR by fiscal 2030, as it expects platformization and AI infrastructure investment to continue driving growth.
More than 65% of Palo Alto's NGS ARR comes from platformized customers. Meanwhile, AI is expanding the addressable market. As enterprises deploy agents, Palo Alto offerings such as Prisma AIRS and Cortex, alongside CyberArk's identity-security platform, can address emerging needs.
#palo #company #NASDAQ #PANW
1 day ago
NVIDIA Corporation (NASDAQ:NVDA) is expanding its global AI infrastructure ambitions, with Australia emerging as an important new market for its growing portfolio of GPUs, CPUs, networking products, and AI software.
On September 9, it announced strategic partnerships with Australian NVIDIA Cloud Partners (NCPs) and AI infrastructure providers as it works with local partners toward an AI infrastructure buildout of up to 2 gigawatts by 2027.
The initiative will expand the availability of land, power, and data center shell capacity designed to host multiple generations of Nvidia's DSX AI factory infrastructure. While the buildout is designed to meet Australia's growing demand for AI computing, it could also create a significant new source of demand for Nvidia's hardware and software ecosystem.
The Australian buildout could benefit NVIDIA Corporation (NASDAQ:NVDA) beyond the initial sale of GPUs. Nvidia will provide its DSX platform, accelerated computing, networking, software, and ecosystem support to the emerging network of AI factories. DSX is also compatible with Nvidia's CUDA ecosystem.
As enterprises, universities, government agencies, and startups increasingly build AI workloads around Nvidia's architecture, the company could strengthen CUDA's position as the underlying software platform for AI development and deployment.
#NASDAQ #australian
On September 9, it announced strategic partnerships with Australian NVIDIA Cloud Partners (NCPs) and AI infrastructure providers as it works with local partners toward an AI infrastructure buildout of up to 2 gigawatts by 2027.
The initiative will expand the availability of land, power, and data center shell capacity designed to host multiple generations of Nvidia's DSX AI factory infrastructure. While the buildout is designed to meet Australia's growing demand for AI computing, it could also create a significant new source of demand for Nvidia's hardware and software ecosystem.
The Australian buildout could benefit NVIDIA Corporation (NASDAQ:NVDA) beyond the initial sale of GPUs. Nvidia will provide its DSX platform, accelerated computing, networking, software, and ecosystem support to the emerging network of AI factories. DSX is also compatible with Nvidia's CUDA ecosystem.
As enterprises, universities, government agencies, and startups increasingly build AI workloads around Nvidia's architecture, the company could strengthen CUDA's position as the underlying software platform for AI development and deployment.
#NASDAQ #australian

1 day ago
Salesforce Inc. (NYSE:CRM) continues to strengthen its enterprise artificial intelligence offering as it looks to make AI a larger part of its customer relationship management ecosystem. On September 9, reports emerged that the company is prepared to spend as much as $2 billion to acquire Listen Labs, an AI-powered customer research platform.
The potential deal would extend Salesforce's aggressive M&A strategy as the company seeks to expand its generative and agentic AI capabilities. Salesforce recently completed its approximately $3.6 billion acquisition of customer service AI agent provider Fin, formerly Intercom, underscoring management's willingness to use acquisitions to accelerate its AI roadmap.
Listen Labs could add a new layer of customer intelligence to Salesforce's platform. The company uses artificial intelligence to conduct customer interviews through audio and video and ******* yze the resulting responses.
Kritchanut/Shutterstock.com
The potential acquisition could be particularly valuable for Salesforce Agentforce, the company's platform for building and deploying AI agents. Listen Labs could end up providing crucial insights into why customers behave the way they do. Customer interviews and conversations can reveal motivations, preferences, frustrations, and other qualitative information that may not be captured in traditional CRM databases.
#customer #salesforce #platform #artificial
The potential deal would extend Salesforce's aggressive M&A strategy as the company seeks to expand its generative and agentic AI capabilities. Salesforce recently completed its approximately $3.6 billion acquisition of customer service AI agent provider Fin, formerly Intercom, underscoring management's willingness to use acquisitions to accelerate its AI roadmap.
Listen Labs could add a new layer of customer intelligence to Salesforce's platform. The company uses artificial intelligence to conduct customer interviews through audio and video and ******* yze the resulting responses.
Kritchanut/Shutterstock.com
The potential acquisition could be particularly valuable for Salesforce Agentforce, the company's platform for building and deploying AI agents. Listen Labs could end up providing crucial insights into why customers behave the way they do. Customer interviews and conversations can reveal motivations, preferences, frustrations, and other qualitative information that may not be captured in traditional CRM databases.
#customer #salesforce #platform #artificial

1 day ago
AKRON, Ohio (AP) — Marty Whims II got to experience the joy and frustration of being the offensive coordinator for a Football Bowl Subdivision team on Saturday.
Unfortunately, it lasted for only four plays.
Akron was moving the ball on its first possession against Robert Morris when wide receiver Marcel Williams fumbled at the Colonials' 37-yard line. David Johnson recovered the ball after Tasheen Howard and Jake Lopinto forced the fumble.
"We moved the ball, got some first downs. I thought we were going to get a touchdown if we didn't fumble," Whims said shortly after his OC stint ended.
Whims got to call plays as part of Akron's "Offensive Coordinator of the Game" for its home opener. The 46-year-old Whims — a longtime season-ticket holder — graduated from Akron and is the chief financial officer for Stark Enterprises.
#fumble
Unfortunately, it lasted for only four plays.
Akron was moving the ball on its first possession against Robert Morris when wide receiver Marcel Williams fumbled at the Colonials' 37-yard line. David Johnson recovered the ball after Tasheen Howard and Jake Lopinto forced the fumble.
"We moved the ball, got some first downs. I thought we were going to get a touchdown if we didn't fumble," Whims said shortly after his OC stint ended.
Whims got to call plays as part of Akron's "Offensive Coordinator of the Game" for its home opener. The 46-year-old Whims — a longtime season-ticket holder — graduated from Akron and is the chief financial officer for Stark Enterprises.
#fumble


3 days ago
Saint Louis, Missouri-based Centene Corporation (CNC) operates as a healthcare enterprise that provides programs and services to underinsured and uninsured families and commercial organizations in the United States. The company has a market capitalization of $31.6 billion and operates through Medicaid, Medicare, Commercial, and Other segments.
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." CNC fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the healthcare plans industry.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ****** e
#saint
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." CNC fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the healthcare plans industry.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ****** e
#saint


3 days ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted TechTarget, Inc. (NASDAQ:TTGT) as the largest contributor to the portfolio's short book. TechTarget, Inc. (NASDAQ:TTGT) provides sales and support of purchase intent-driven advertising campaigns. On September 9, 2026, TechTarget, Inc. (NASDAQ:TTGT) closed at $3.89 per share. Over the past month, TechTarget, Inc. (NASDAQ:TTGT) returned 1.57% and its shares lost 35.17% over the past 52 weeks. TechTarget, Inc. (NASDAQ:TTGT) has a market capitalization of $281.37 million, and its stock has traded within a 52-week range of $3.37 to $7.15.
Prosper Stars & Stripes stated the following regarding TechTarget, Inc. (NASDAQ:TTGT) in its Q2 2026 investor letter:
"TechTarget, Inc. (NASDAQ:TTGT) was the largest contributor to our short book during the quarter. The company monetizes the purchase research behavior of enterprise IT buyers by operating a network of websites where buyers register to consume technical content, then selling those intent signals as leads to IT vendors. We first shorted the company after it completed a value-destroying acquisition in December 2024 that led to significant impairment charges in Q1 2025 and again in Q1 2026. We believe AI is likely to dismantle search-based discovery and commoditize content, the two pillars of TechTarget's value propositions. Results have validated our concerns, with management describing its market as mature, with 2% to 3% top-line growth, and EBITDA margins that peaked in 2022 falling to 7% in Q1 2026. Notably, revenue growth began deteriorating before ChatGPT launched in November 2022, suggesting that problems run deeper than AI alone. We continue to believe generative AI will weigh on TechTarget's prospects and remain short the company."
#techtarget #NASDAQ
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted TechTarget, Inc. (NASDAQ:TTGT) as the largest contributor to the portfolio's short book. TechTarget, Inc. (NASDAQ:TTGT) provides sales and support of purchase intent-driven advertising campaigns. On September 9, 2026, TechTarget, Inc. (NASDAQ:TTGT) closed at $3.89 per share. Over the past month, TechTarget, Inc. (NASDAQ:TTGT) returned 1.57% and its shares lost 35.17% over the past 52 weeks. TechTarget, Inc. (NASDAQ:TTGT) has a market capitalization of $281.37 million, and its stock has traded within a 52-week range of $3.37 to $7.15.
Prosper Stars & Stripes stated the following regarding TechTarget, Inc. (NASDAQ:TTGT) in its Q2 2026 investor letter:
"TechTarget, Inc. (NASDAQ:TTGT) was the largest contributor to our short book during the quarter. The company monetizes the purchase research behavior of enterprise IT buyers by operating a network of websites where buyers register to consume technical content, then selling those intent signals as leads to IT vendors. We first shorted the company after it completed a value-destroying acquisition in December 2024 that led to significant impairment charges in Q1 2025 and again in Q1 2026. We believe AI is likely to dismantle search-based discovery and commoditize content, the two pillars of TechTarget's value propositions. Results have validated our concerns, with management describing its market as mature, with 2% to 3% top-line growth, and EBITDA margins that peaked in 2022 falling to 7% in Q1 2026. Notably, revenue growth began deteriorating before ChatGPT launched in November 2022, suggesting that problems run deeper than AI alone. We continue to believe generative AI will weigh on TechTarget's prospects and remain short the company."
#techtarget #NASDAQ


3 days ago
On September 2, F5, Inc. (NASDAQ:FFIV) announced a key integration with MuleSoft, a Salesforce, Inc. (NYSE:CRM) company, federating F5 AI Guardrails directly into MuleSoft's Agent Fabric Omni Gateway. As enterprises rapidly scale agentic AI capabilities, security teams face growing governance gaps and risks from prompt injection, data leakage, and toxic outputs. This native integration gives security and platform engineering teams centralized policy enforcement, proactive threat mitigation, and low-touch policy tuning without forcing organizations to re-architect existing infrastructure.
While the partnership strengthens both ecosystems, examining their latest financials reveals two enterprise software giants moving at distinctly different scales and growth trajectories.
F5, Inc. (NASDAQ:FFIV) reported strong Q3 FY26 results, generating $865 million in revenue (up 11% year-over-year). Revenue growth was anchored by a 19% jump in product revenue, led by a 32% surge in systems revenue ($240 million). F5's bottom line remained exceptionally robust, expanding non-GAAP operating margin to 35.0% and delivering non-GAAP net income of $272 million ($4.73 per diluted share, up from $4.16).
Salesforce operated at a much larger scale in its record Q2 FY27, generating $11.3 billion in quarterly revenue (up 11% year-over-year). Growth was fueled by subscription and support revenue of $10.8 billion and expanding adoption of its Agentforce platform, whose annual recurring revenue (ARR) neared $3.9 billion. Salesforce posted a non-GAAP operating margin of 34.1%, and non-GAAP diluted EPS of $5.90, while raising its full-year FY27 revenue guidance to $46.1B–$46.4B.
While both companies run near-identical, highly profitable non-GAAP operating margins (~34%–35%), Salesforce leads overall financial health due to its massive free cash flow generation, cRPO backlog of $33.5 billion, and broader ecosystem dominance.
#Growth
While the partnership strengthens both ecosystems, examining their latest financials reveals two enterprise software giants moving at distinctly different scales and growth trajectories.
F5, Inc. (NASDAQ:FFIV) reported strong Q3 FY26 results, generating $865 million in revenue (up 11% year-over-year). Revenue growth was anchored by a 19% jump in product revenue, led by a 32% surge in systems revenue ($240 million). F5's bottom line remained exceptionally robust, expanding non-GAAP operating margin to 35.0% and delivering non-GAAP net income of $272 million ($4.73 per diluted share, up from $4.16).
Salesforce operated at a much larger scale in its record Q2 FY27, generating $11.3 billion in quarterly revenue (up 11% year-over-year). Growth was fueled by subscription and support revenue of $10.8 billion and expanding adoption of its Agentforce platform, whose annual recurring revenue (ARR) neared $3.9 billion. Salesforce posted a non-GAAP operating margin of 34.1%, and non-GAAP diluted EPS of $5.90, while raising its full-year FY27 revenue guidance to $46.1B–$46.4B.
While both companies run near-identical, highly profitable non-GAAP operating margins (~34%–35%), Salesforce leads overall financial health due to its massive free cash flow generation, cRPO backlog of $33.5 billion, and broader ecosystem dominance.
#Growth


3 days ago
HIVE Digital Technologies, a Canada-based Bitcoin miner and data center operator that trades on the Nasdaq and Toronto Stock Exchange, has appointed Mark Volk as Senior Vice President of Revenue at BUZZ HPC, its wholly owned AI cloud and high-performance computing subsidiary.
Volk's mandate is to build BUZZ HPC's revenue engine and scale it globally. He will lead the company's go-to-market strategy across enterprise, government, sovereign AI, hyperscale, research and academic markets, overseeing commercialization of its GPU-powered infrastructure, including sovereign AI cloud, GPU-as-a-Service, colocation and hybrid AI solutions.
Related: Elon Musk warns 'if the ship of America sinks, we all sink with it'
Volk brings roughly 30 years of experience across AI, high-performance computing, cloud and enterprise infrastructure.
He is not a new face internally, he has worked with HIVE as a consultant for approximately nine months, during which he helped build BUZZ HPC's current GPU cloud demand pipeline.
#buzz #volk #performance #across
Volk's mandate is to build BUZZ HPC's revenue engine and scale it globally. He will lead the company's go-to-market strategy across enterprise, government, sovereign AI, hyperscale, research and academic markets, overseeing commercialization of its GPU-powered infrastructure, including sovereign AI cloud, GPU-as-a-Service, colocation and hybrid AI solutions.
Related: Elon Musk warns 'if the ship of America sinks, we all sink with it'
Volk brings roughly 30 years of experience across AI, high-performance computing, cloud and enterprise infrastructure.
He is not a new face internally, he has worked with HIVE as a consultant for approximately nine months, during which he helped build BUZZ HPC's current GPU cloud demand pipeline.
#buzz #volk #performance #across

3 days ago
On August 31, Advanced Micro Devices, Inc. (NASDAQ:AMD), Cisco Systems, Inc. (NASDAQ:CSCO), and Humain announced that their joint AI infrastructure buildout in Saudi Arabia is officially live. The deployment links AMD's Instinct MI355X GPUs and EPYC CPUs directly with Cisco's Silicon One-based 800G switches, giving Humain a foundation to offer GPU-as-a-service across the Middle East. Beyond this immediate launch, the trio plans to deploy up to 250 MW of capacity powered by next-gen AMD MI400 Series GPUs starting in 2027, staying on track for a massive 1 GW platform by 2030.
The milestone highlights how compute and networking have fused into a single market. But financially, AMD and Cisco present two very different investment profiles.
Advanced Micro Devices, Inc. (NASDAQ:AMD)'s Q2 2026 results demonstrated massive top-line expansion, driven almost entirely by data center demand. Revenue surged 50% year-over-year to $11.5 billion, while non-GAAP EPS rose 82% to $1.66. Its Data Center segment alone more than doubled to $6.7 billion (+107% YoY), accounting for 58% of total revenue as EPYC server chips and Instinct GPUs continue to gain enterprise traction.
Cisco Systems, Inc. (NASDAQ:CSCO)'s Q4 and full-year FY2026 report reflected a mature cash-flow powerhouse capturing an architectural transition. Q4 revenue grew 18% YoY to a record $17.3 billion, pushing full-year revenue up 12% to $63.3 billion. Non-GAAP EPS for Q4 reached $1.22 (+23%), with FY2026 non-GAAP EPS hitting $4.33. Cisco logged $9.3 billion in AI infrastructure orders for the fiscal year (up 4.5x YoY) and maintained a non-GAAP operating margin of 35.9%, generating $14.2 billion in annual operating cash flow.
While AMD clearly leads on top-line growth velocity, Cisco holds the upper hand in raw profitability, structural gross margins (66.3%), and shareholder return via capital repurchases and dividends.
#revenue #advanced
The milestone highlights how compute and networking have fused into a single market. But financially, AMD and Cisco present two very different investment profiles.
Advanced Micro Devices, Inc. (NASDAQ:AMD)'s Q2 2026 results demonstrated massive top-line expansion, driven almost entirely by data center demand. Revenue surged 50% year-over-year to $11.5 billion, while non-GAAP EPS rose 82% to $1.66. Its Data Center segment alone more than doubled to $6.7 billion (+107% YoY), accounting for 58% of total revenue as EPYC server chips and Instinct GPUs continue to gain enterprise traction.
Cisco Systems, Inc. (NASDAQ:CSCO)'s Q4 and full-year FY2026 report reflected a mature cash-flow powerhouse capturing an architectural transition. Q4 revenue grew 18% YoY to a record $17.3 billion, pushing full-year revenue up 12% to $63.3 billion. Non-GAAP EPS for Q4 reached $1.22 (+23%), with FY2026 non-GAAP EPS hitting $4.33. Cisco logged $9.3 billion in AI infrastructure orders for the fiscal year (up 4.5x YoY) and maintained a non-GAAP operating margin of 35.9%, generating $14.2 billion in annual operating cash flow.
While AMD clearly leads on top-line growth velocity, Cisco holds the upper hand in raw profitability, structural gross margins (66.3%), and shareholder return via capital repurchases and dividends.
#revenue #advanced


3 days ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Net sales growth of 22% was primarily driven by sustained demand across enterprise, data center, and specialty market sectors, including military applications.
Gross profit margin expansion to 37.4% demonstrates significant manufacturing operating leverage, where fixed costs are distributed over higher production volumes.
Management attributes margin improvements to increased manufacturing efficiencies that naturally occur as production volumes scale.
The company is navigating industry-wide optical fiber shortages and raw material lead time extensions by actively managing supply chain dynamics to protect customer deliveries.
#Margin #Manufacturing #volumes #management
Net sales growth of 22% was primarily driven by sustained demand across enterprise, data center, and specialty market sectors, including military applications.
Gross profit margin expansion to 37.4% demonstrates significant manufacturing operating leverage, where fixed costs are distributed over higher production volumes.
Management attributes margin improvements to increased manufacturing efficiencies that naturally occur as production volumes scale.
The company is navigating industry-wide optical fiber shortages and raw material lead time extensions by actively managing supply chain dynamics to protect customer deliveries.
#Margin #Manufacturing #volumes #management

3 days ago
Hewlett Packard Enterprise Company (NYSE:HPE) announced an expanded collaboration with Oracle Corporation (NYSE:ORCL) on September 2 to scale Oracle's global AI infrastructure using HPE Juniper Networking across Oracle Cloud Infrastructure (OCI) data centers. The partnership builds on over a decade of joint engineering, leveraging HPE's routing and switching platforms to support OCI's expanding gigawatt-scale GPU superclusters. To align long-term incentives, HPE issued stock warrants to Oracle.
Following the announcement, Wall Street delivered fast price target hikes: Barclays' Tim Long raised HPE's target by $12 to $79 (Overweight), citing server upside and robust margins, while Morgan Stanley's Sanjit Singh boosted Oracle's target by $3 to $210 (Equal Weight), noting a tactically positive setup driven by GPUaaS demand.
Hewlett Packard Enterprise Company (NYSE:HPE) and Oracle both delivered strong results, although Oracle operates at a significantly larger scale. HPE reported record Q3 2026 revenue of $12.2 billion, up 34% year over year, driven by strong server demand and a 74.9% increase in Networking revenue to $2.9 billion. GAAP diluted EPS reached $1.06, while strong execution led management to raise full-year FY26 revenue growth guidance to 34%-37% and its free cash flow target to at least $3.75 billion.
Oracle Corporation (NYSE:ORCL), meanwhile, ended fiscal 2026 with record Q4 revenue of $19.2 billion, up 21% year over year, and full-year revenue of $67.4 billion, up 17%. Q4 Cloud Infrastructure (IaaS) revenue surged 93% to $5.8 billion, while full-year GAAP EPS rose 34% to $5.83 and Remaining Performance Obligations (RPO) jumped 363% to $638 billion.
Overall, ORCL leads in hyper-growth and long-term backlog, reinforcing its position as the stronger software and cloud play, while HPE is demonstrating stronger near-term hardware momentum and attractive cash flow generation for value-oriented investors.
#billion #revenue #infrastructure
Following the announcement, Wall Street delivered fast price target hikes: Barclays' Tim Long raised HPE's target by $12 to $79 (Overweight), citing server upside and robust margins, while Morgan Stanley's Sanjit Singh boosted Oracle's target by $3 to $210 (Equal Weight), noting a tactically positive setup driven by GPUaaS demand.
Hewlett Packard Enterprise Company (NYSE:HPE) and Oracle both delivered strong results, although Oracle operates at a significantly larger scale. HPE reported record Q3 2026 revenue of $12.2 billion, up 34% year over year, driven by strong server demand and a 74.9% increase in Networking revenue to $2.9 billion. GAAP diluted EPS reached $1.06, while strong execution led management to raise full-year FY26 revenue growth guidance to 34%-37% and its free cash flow target to at least $3.75 billion.
Oracle Corporation (NYSE:ORCL), meanwhile, ended fiscal 2026 with record Q4 revenue of $19.2 billion, up 21% year over year, and full-year revenue of $67.4 billion, up 17%. Q4 Cloud Infrastructure (IaaS) revenue surged 93% to $5.8 billion, while full-year GAAP EPS rose 34% to $5.83 and Remaining Performance Obligations (RPO) jumped 363% to $638 billion.
Overall, ORCL leads in hyper-growth and long-term backlog, reinforcing its position as the stronger software and cloud play, while HPE is demonstrating stronger near-term hardware momentum and attractive cash flow generation for value-oriented investors.
#billion #revenue #infrastructure

3 days ago
Dell Technologies (DELL) shares have surged more than 316% so far in 2026, fueled by robust demand for AI infrastructure, increased enterprise investment in modernizing IT systems, and continued expansion of its customer base.
The company is also benefiting from strong demand for its AI-optimized servers, and the momentum is likely sustainable in the coming quarters. At the same time, rising AI demand is also driving demand for traditional servers and networking equipment, further strengthening Dell's long-term growth prospects.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ***** e
#tens
The company is also benefiting from strong demand for its AI-optimized servers, and the momentum is likely sustainable in the coming quarters. At the same time, rising AI demand is also driving demand for traditional servers and networking equipment, further strengthening Dell's long-term growth prospects.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ***** e
#tens



3 days ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance was driven by the compounding power of the identity security platform and rapid adoption of SaaS, which accounted for 97% of net new ARR in Q2.
Management attributes growth to the strategic elevation of identity governance to CISO and Board-level priorities, unlocking larger enterprise budget opportunities.
The acquisition of Entro Security accelerated the product roadmap by expanding discovery capabilities to over 1,200 non-human identity types, providing critical lineage context.
Strategic positioning focuses on a unified control plane, arguing that monitoring alone is insufficient and that proactive governance must link autonomous agents to accountable humans.
#performance #management
Performance was driven by the compounding power of the identity security platform and rapid adoption of SaaS, which accounted for 97% of net new ARR in Q2.
Management attributes growth to the strategic elevation of identity governance to CISO and Board-level priorities, unlocking larger enterprise budget opportunities.
The acquisition of Entro Security accelerated the product roadmap by expanding discovery capabilities to over 1,200 non-human identity types, providing critical lineage context.
Strategic positioning focuses on a unified control plane, arguing that monitoring alone is insufficient and that proactive governance must link autonomous agents to accountable humans.
#performance #management

3 days ago
Netskope Inc. (NASDAQ:NTSK) announced its second quarter results on September 2. The cloud and AI-led security and networking company saw a 27% year-over-year jump in its annual recurring revenue that climbed to $899 million. Total revenue for the recent quarter came in at $220.5 million, equating to a 29% growth compared to the same period last year. The company surpassed management's prior guidance across all metrics.
Gts/Shutterstock.com
The second quarter strength can be attributed to a robust demand for Netskope One platform. This was further supported by the company's continued organic innovation. Netskope is currently positioned right at the convergence of AI, networking, security, and ****** ytics, which makes strengthen its position as enterprises look for secure AI adoption. On the profitability front, the company reported gross profit of $169.1 million on adjusted basis, resulting in a marginal jump in adjusted gross margins to 77%, compared to 75% during the same period last year.
During the quarter, Netskope also introduced some new offerings and advanced features. These include the Netskope One DataSec Command Center, which is a unified platform for tracking and protecting sensitive data across endpoints, cloud, AI environments, and more. The company also brought enhancements to its NewEdge AI Fast Path capability, which, according to company testing, reduced latency by as much as 90% to popular AI destinations.
Following the second quarter, management issued guidance for the upcoming quarter, estimating topline figures between $227 million and $229 million. It has projected full-year revenue between $888 million and $892 million, along with adjusted gross margin of around 77% and a free cash flow margin of nearly 2%.
#second
Gts/Shutterstock.com
The second quarter strength can be attributed to a robust demand for Netskope One platform. This was further supported by the company's continued organic innovation. Netskope is currently positioned right at the convergence of AI, networking, security, and ****** ytics, which makes strengthen its position as enterprises look for secure AI adoption. On the profitability front, the company reported gross profit of $169.1 million on adjusted basis, resulting in a marginal jump in adjusted gross margins to 77%, compared to 75% during the same period last year.
During the quarter, Netskope also introduced some new offerings and advanced features. These include the Netskope One DataSec Command Center, which is a unified platform for tracking and protecting sensitive data across endpoints, cloud, AI environments, and more. The company also brought enhancements to its NewEdge AI Fast Path capability, which, according to company testing, reduced latency by as much as 90% to popular AI destinations.
Following the second quarter, management issued guidance for the upcoming quarter, estimating topline figures between $227 million and $229 million. It has projected full-year revenue between $888 million and $892 million, along with adjusted gross margin of around 77% and a free cash flow margin of nearly 2%.
#second


3 days ago
On September 2, NetApp Inc. (NASDAQ:NTAP) reported its Q1 FY27 results, posting record quarterly net revenue of $2.03 billion. Topline for the Intelligent Data Infrastructure company expanded by 30% compared to the first quarter in FY26. The quarter saw a broad-based growth across its core segments, resulting in a record adjusted earnings per share of $2.58, and a quarterly cash dividend of $0.52 per share. The company also strengthened its existing engagements with major players, covering a range of underlying functions.
During the first quarter, all-flash array net revenue went up 47% year-over-year, hitting a record $1.3 billion mark. This drove the overall net revenue for its Hybrid Cloud segment to $1.8 billion, translating into a 30% year-over-year growth. Public Cloud, which accounts for a smaller chunk of the business, saw its net revenue climb by 28%, also setting a record of $206 million. NetApp's total billings clocked in at $2.06 billion, exhibiting a 36% growth compared to Q1 FY26, while its non-GAAP operating margin reached 31.9%.
During the quarter, NetApp finalized the acquisition of an AI-enabled data infrastructure business, DataPelago. The deal is aimed toward facilitating customers streamline and accelerate large-scale AI deployments. On the product front, the company launched StorageGRID 12.1, to support scaling of AI workload through a federated global namespace. It also introduced Instaclustr for its fully managed Model Context Protocol Gateway, along with enhanced support for Azure NetApp Files up to 64 TiB.
NetApp also revealed new features for NetApp Trident software 26.06. These include deeper integration of OpenShift Virtualization, non-disruptive iSCSI rebalancing, efficient volume placement, and additional cloud support.
Despite encouraging numbers reported during the quarter, the free cash flows settled at $401 million. This was a 35% drop compared to figures reported for Q1 FY26. Additionally, NetApp remains heavily dependent on its Hybrid Cloud business, which generated roughly 90% of quarterly revenue, while Public Cloud still contributes a relatively small fraction of the topline despite growing 28% during the recent quarter. This leads to concerns regarding how much of the company's growth story is truly cloud-native compared to conventional on-premises hardware refresh cycles that are strongly tied to AI infrastructure investments. For the underlying all-flash arrays, such AI-linked demand trend could prove to be front-loaded or cyclical in case enterprise capital expenditure decelerates.
#netapp #Growth
During the first quarter, all-flash array net revenue went up 47% year-over-year, hitting a record $1.3 billion mark. This drove the overall net revenue for its Hybrid Cloud segment to $1.8 billion, translating into a 30% year-over-year growth. Public Cloud, which accounts for a smaller chunk of the business, saw its net revenue climb by 28%, also setting a record of $206 million. NetApp's total billings clocked in at $2.06 billion, exhibiting a 36% growth compared to Q1 FY26, while its non-GAAP operating margin reached 31.9%.
During the quarter, NetApp finalized the acquisition of an AI-enabled data infrastructure business, DataPelago. The deal is aimed toward facilitating customers streamline and accelerate large-scale AI deployments. On the product front, the company launched StorageGRID 12.1, to support scaling of AI workload through a federated global namespace. It also introduced Instaclustr for its fully managed Model Context Protocol Gateway, along with enhanced support for Azure NetApp Files up to 64 TiB.
NetApp also revealed new features for NetApp Trident software 26.06. These include deeper integration of OpenShift Virtualization, non-disruptive iSCSI rebalancing, efficient volume placement, and additional cloud support.
Despite encouraging numbers reported during the quarter, the free cash flows settled at $401 million. This was a 35% drop compared to figures reported for Q1 FY26. Additionally, NetApp remains heavily dependent on its Hybrid Cloud business, which generated roughly 90% of quarterly revenue, while Public Cloud still contributes a relatively small fraction of the topline despite growing 28% during the recent quarter. This leads to concerns regarding how much of the company's growth story is truly cloud-native compared to conventional on-premises hardware refresh cycles that are strongly tied to AI infrastructure investments. For the underlying all-flash arrays, such AI-linked demand trend could prove to be front-loaded or cyclical in case enterprise capital expenditure decelerates.
#netapp #Growth


3 days ago
Answering a caller's query about Box, Inc. (NYSE:BOX) during the lightning round of Mad Money on September 3, Jim Cramer commented:
Box is finally, after multiple years, it is finally breaking out. It has good storage. People like storage. It's got a good CEO in Aaron Levie. It's just never been exciting to people. It's finally starting to get some mojo. I think it's okay to own. It's done nothing for years.
Cramer's perspective highlights a shifting narrative for a cloud pioneer that has historically traded in a tight range. In its fiscal second-quarter 2027 report, Box, Inc. (NYSE:BOX) posted revenue of $321.1 million, marking a 9.2% year-over-year increase that topped Wall Street expectations by over $2 million. Adjusted earnings per share reached $0.40, in line with consensus forecasts, while management raised full-year revenue guidance to approximately $1.29 billion. The core demand is supported by expanding adoption of higher-tier Box Suites, which now account for 69% of revenue, along with early traction in AI-driven document tools that help enterprises modernize legacy storage workflows.
Despite recent top-line acceleration, Box, Inc. (NYSE:BOX) operates in a fiercely competitive market dominated by massive tech ecosystems like Microsoft OneDrive and Google Drive, and other specialized rivals such as Dropbox. While quarterly growth has stabilized, Box's multi-year annual growth rate has historically lagged behind high-flying software peers. Furthermore, Box still needs to sustain its recent growth acceleration while investing in AI capabilities.
As per Insider Monkey's data of over 1000 hedge funds, 37 hedge funds had a stake in Box, Inc. (NYSE:BOX) in Q2 compared to 36 in Q1, highlighting steady institutional backing from long-term ***** et managers. Arrowstreet Capital remained the company's top hedge fund holder in Q2 with 4.3 million shares. Additionally, it is worth noting that another significant shareholder, Citadel Investment Group increased its position in the stock by 60% to over 3.7 million shares. The short percentage of float sits at 14.26%, which shows a notable segment of the market remains unconvinced about the sustainability of the breakout.
#NYSE #year #people
Box is finally, after multiple years, it is finally breaking out. It has good storage. People like storage. It's got a good CEO in Aaron Levie. It's just never been exciting to people. It's finally starting to get some mojo. I think it's okay to own. It's done nothing for years.
Cramer's perspective highlights a shifting narrative for a cloud pioneer that has historically traded in a tight range. In its fiscal second-quarter 2027 report, Box, Inc. (NYSE:BOX) posted revenue of $321.1 million, marking a 9.2% year-over-year increase that topped Wall Street expectations by over $2 million. Adjusted earnings per share reached $0.40, in line with consensus forecasts, while management raised full-year revenue guidance to approximately $1.29 billion. The core demand is supported by expanding adoption of higher-tier Box Suites, which now account for 69% of revenue, along with early traction in AI-driven document tools that help enterprises modernize legacy storage workflows.
Despite recent top-line acceleration, Box, Inc. (NYSE:BOX) operates in a fiercely competitive market dominated by massive tech ecosystems like Microsoft OneDrive and Google Drive, and other specialized rivals such as Dropbox. While quarterly growth has stabilized, Box's multi-year annual growth rate has historically lagged behind high-flying software peers. Furthermore, Box still needs to sustain its recent growth acceleration while investing in AI capabilities.
As per Insider Monkey's data of over 1000 hedge funds, 37 hedge funds had a stake in Box, Inc. (NYSE:BOX) in Q2 compared to 36 in Q1, highlighting steady institutional backing from long-term ***** et managers. Arrowstreet Capital remained the company's top hedge fund holder in Q2 with 4.3 million shares. Additionally, it is worth noting that another significant shareholder, Citadel Investment Group increased its position in the stock by 60% to over 3.7 million shares. The short percentage of float sits at 14.26%, which shows a notable segment of the market remains unconvinced about the sustainability of the breakout.
#NYSE #year #people


3 days ago
Interested in Qualcomm Incorporated? Here are five stocks we like better.
Qualcomm's Amazon agreement gives its data center strategy a major anchor beyond smartphones.
Amazon's warrants are tied to up to $60 billion in potential purchases over a decade, making the deal meaningful but gradual.
Qualcomm's valuation still trails many AI infrastructure peers, but dilution risk and execution timing remain important factors.
Investors continue to seek disciplined strategies to participate in the evolving artificial intelligence (AI) economy without paying inflated multiples for standard graphics hardware. Capital remains focused on businesses positioned to sustain steady enterprise workload expansion while maintaining reasonable valuation metrics.
#interested #qualcomm
Qualcomm's Amazon agreement gives its data center strategy a major anchor beyond smartphones.
Amazon's warrants are tied to up to $60 billion in potential purchases over a decade, making the deal meaningful but gradual.
Qualcomm's valuation still trails many AI infrastructure peers, but dilution risk and execution timing remain important factors.
Investors continue to seek disciplined strategies to participate in the evolving artificial intelligence (AI) economy without paying inflated multiples for standard graphics hardware. Capital remains focused on businesses positioned to sustain steady enterprise workload expansion while maintaining reasonable valuation metrics.
#interested #qualcomm


3 days ago
Qualcomm (QCOM) has spent years telling shareholders it is becoming more than a smartphone chip company. What changed is where the new growth is expected to come from. Two years ago the big non-handset targets were automotive and IoT. Today, the newest leg of the story runs through the data center, and management has already put a number on it.
Qualcomm Once Told You The Laptop Chip Had Redefined Computing
The Snapdragon X Series was the flagship of that older story. Two years ago management said those platforms had redefined personal computing.
Management no longer leads with that story. In the fiscal Q3 2026 call, delivered on July 29, 2026, the PC gets two passing lines: a growing share of design wins in AI-first laptops and Project Solara, a chip-to-cloud platform being built with Microsoft for agent-first enterprise devices. Both are real. Neither carries a revenue figure.
Qualcomm Nearly Doubled Its Non-Handset Target Without Naming The Laptop
#first
Qualcomm Once Told You The Laptop Chip Had Redefined Computing
The Snapdragon X Series was the flagship of that older story. Two years ago management said those platforms had redefined personal computing.
Management no longer leads with that story. In the fiscal Q3 2026 call, delivered on July 29, 2026, the PC gets two passing lines: a growing share of design wins in AI-first laptops and Project Solara, a chip-to-cloud platform being built with Microsoft for agent-first enterprise devices. Both are real. Neither carries a revenue figure.
Qualcomm Nearly Doubled Its Non-Handset Target Without Naming The Laptop
#first

3 days ago
When a caller inquired about IREN Limited (NASDAQ:IREN) during the lightning round on September 3, Mad Money host Jim Cramer said:
If you're going to do neocloud, you got to do, the only one I like is CoreWeave with Michael Intrator. The others I think are too speculative for me.
The two companies are at different stages of building their AI businesses. CoreWeave, Inc. (NASDAQ:CRWV) reported $2.575 billion of second-quarter revenue, up approximately 112% from a year earlier. Its revenue backlog stood at approximately $104 billion as of June 30, excluding more than $25 billion of additional customer commitments secured in early July. Furthermore, active power reached 1.5 gigawatts, while contracted power rose to approximately 3.7 gigawatts. CEO Michael Intrator said on the company's second-quarter earnings call that "our near-term capacity remains effectively sold out." He also described broadening customer demand and rapidly expanding enterprise adoption.
Meanwhile, IREN Limited's (NASDAQ:IREN) AI Cloud Services revenue reached $128.8 million in fiscal 2026, compared with $16.4 million a year earlier. Total fiscal 2026 revenue was $707 million, including $578.2 million from Bitcoin mining. The company reported $4 billion of contracted AI annualized run rate revenue for 2026 capacity, with $1 billion of operating ARR as of August 26. CEO Daniel Roberts said on August 27 that its 2026 capacity was "largely sold out." Roberts said recent three-year contracts represented more than $20 million of revenue per megawatt and that customer prepayments represented 45%-55% of ****** ociated GPU capital expenditures.
CoreWeave, Inc.'s (NASDAQ:CRWV) capital requirements remain substantial. The company spent $9.4 billion on capital expenditures in the second quarter and raised its 2026 CapEx forecast to $35 billion-$39 billion. It also reported $640 million of net interest expense and a $626 million net loss for the quarter. Total debt stood at $35.6 billion as of June 30.
#billion #revenue
If you're going to do neocloud, you got to do, the only one I like is CoreWeave with Michael Intrator. The others I think are too speculative for me.
The two companies are at different stages of building their AI businesses. CoreWeave, Inc. (NASDAQ:CRWV) reported $2.575 billion of second-quarter revenue, up approximately 112% from a year earlier. Its revenue backlog stood at approximately $104 billion as of June 30, excluding more than $25 billion of additional customer commitments secured in early July. Furthermore, active power reached 1.5 gigawatts, while contracted power rose to approximately 3.7 gigawatts. CEO Michael Intrator said on the company's second-quarter earnings call that "our near-term capacity remains effectively sold out." He also described broadening customer demand and rapidly expanding enterprise adoption.
Meanwhile, IREN Limited's (NASDAQ:IREN) AI Cloud Services revenue reached $128.8 million in fiscal 2026, compared with $16.4 million a year earlier. Total fiscal 2026 revenue was $707 million, including $578.2 million from Bitcoin mining. The company reported $4 billion of contracted AI annualized run rate revenue for 2026 capacity, with $1 billion of operating ARR as of August 26. CEO Daniel Roberts said on August 27 that its 2026 capacity was "largely sold out." Roberts said recent three-year contracts represented more than $20 million of revenue per megawatt and that customer prepayments represented 45%-55% of ****** ociated GPU capital expenditures.
CoreWeave, Inc.'s (NASDAQ:CRWV) capital requirements remain substantial. The company spent $9.4 billion on capital expenditures in the second quarter and raised its 2026 CapEx forecast to $35 billion-$39 billion. It also reported $640 million of net interest expense and a $626 million net loss for the quarter. Total debt stood at $35.6 billion as of June 30.
#billion #revenue

3 days ago
During a segment on the September 3 episode, Mad Money host Jim Cramer shared a detailed bullish thesis on Amazon.com, Inc. (NASDAQ:AMZN). He stated:
Let's start with Amazon. Ever since we went out to see Amazon earlier this year, I've been stuck on something that CEO Andy Jassy told me. He said they're going to make an immense amount of money in artificial intelligence. They were going to profit from their gigantic commitment to data centers and next year will be huge for the compute sales. Well, I think it's being pulled forward. I think it may already be huge right now. I also remember Andy talking about the $50 billion semiconductor business that's buried in the company. I like the healthcare initiatives... Amazon Web Services is doing incredibly well. Their grocery delivery business, wow...
Alright, what can I say? All this for a stock that's up just 12% for the year; that's wrong. Amazon's balance sheet isn't as good as it was a year ago; enough already. What if Amazon Web Services is able to make four times what it just paid for 2 million GPUs from NVIDIA? That ratio, by the way, is what NVIDIA CEO Jensen Huang told me companies can expect to get when they buy NVIDIA chips. That makes me think that Amazon is cheap. We've all kind of forgotten that there's a reason why a smart executive like Andy Jassy is willing to wreck Amazon's balance sheet like the old days. It's because they're going to make fortunes with the money they spend. And we are getting closer and closer to seeing huge profits for investments that the Street has hated. You can't wait until next year to buy the stock of Amazon. And that's why it is a screaming buy with the stock trading at about 20 times this year's earnings. That's wrong.
Amazon Web Services remains the primary profit engine for the company. In the second quarter, AWS revenue surged 37% year over year to reach $42.2 billion, putting its annual run rate at roughly $169 billion. Operating income for the cloud unit jumped to $16.6 billion. Companies shifting their operations to handle AI and heavy workloads are turning those massive data center investments into high-margin profits. Aside from basic cloud hosting, Amazon.com, Inc. (NASDAQ:AMZN) is leaning into its own custom chips, like Trainium and Graviton, and growing adoption of the Bedrock platform to keep its revenue streams strong and diversified.
Not everyone on Wall Street shares Cramer's enthusiasm, as it could be pointed out that Amazon.com, Inc.'s (NASDAQ:AMZN) balance sheet is noticeably weaker than it was a year ago as its long-term debt increased from nearly $66 billion at the end of 2025 to nearly $129 billion by mid-2026. Heavy capital commitments and soaring data center expenses, with full-year capital expenditure guidance climbing around $220 billion, have strained cash flow flexibility. Investors could be worried that the company is spending too aggressively. If enterprise demand for artificial intelligence tools slows down or if the massi
Let's start with Amazon. Ever since we went out to see Amazon earlier this year, I've been stuck on something that CEO Andy Jassy told me. He said they're going to make an immense amount of money in artificial intelligence. They were going to profit from their gigantic commitment to data centers and next year will be huge for the compute sales. Well, I think it's being pulled forward. I think it may already be huge right now. I also remember Andy talking about the $50 billion semiconductor business that's buried in the company. I like the healthcare initiatives... Amazon Web Services is doing incredibly well. Their grocery delivery business, wow...
Alright, what can I say? All this for a stock that's up just 12% for the year; that's wrong. Amazon's balance sheet isn't as good as it was a year ago; enough already. What if Amazon Web Services is able to make four times what it just paid for 2 million GPUs from NVIDIA? That ratio, by the way, is what NVIDIA CEO Jensen Huang told me companies can expect to get when they buy NVIDIA chips. That makes me think that Amazon is cheap. We've all kind of forgotten that there's a reason why a smart executive like Andy Jassy is willing to wreck Amazon's balance sheet like the old days. It's because they're going to make fortunes with the money they spend. And we are getting closer and closer to seeing huge profits for investments that the Street has hated. You can't wait until next year to buy the stock of Amazon. And that's why it is a screaming buy with the stock trading at about 20 times this year's earnings. That's wrong.
Amazon Web Services remains the primary profit engine for the company. In the second quarter, AWS revenue surged 37% year over year to reach $42.2 billion, putting its annual run rate at roughly $169 billion. Operating income for the cloud unit jumped to $16.6 billion. Companies shifting their operations to handle AI and heavy workloads are turning those massive data center investments into high-margin profits. Aside from basic cloud hosting, Amazon.com, Inc. (NASDAQ:AMZN) is leaning into its own custom chips, like Trainium and Graviton, and growing adoption of the Bedrock platform to keep its revenue streams strong and diversified.
Not everyone on Wall Street shares Cramer's enthusiasm, as it could be pointed out that Amazon.com, Inc.'s (NASDAQ:AMZN) balance sheet is noticeably weaker than it was a year ago as its long-term debt increased from nearly $66 billion at the end of 2025 to nearly $129 billion by mid-2026. Heavy capital commitments and soaring data center expenses, with full-year capital expenditure guidance climbing around $220 billion, have strained cash flow flexibility. Investors could be worried that the company is spending too aggressively. If enterprise demand for artificial intelligence tools slows down or if the massi

4 days ago
OKTA offers an enterprise identity management platform, including single sign-on, multi-factor authentication, access gateway, API access management, authentication, adaptive MFA, lifecycle management, and AI agent security. OKTA's second-quarter 2027 report showed $805 million in revenue (an 11% year-over-year gain), per-share earnings of $1.05 (a 15.4% sequential gain), and offered full-year revenue and operating margin guidance of up to $3.226 billion and 26%, respectively.
No wonder OKTA shares are up 94% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock.
Institutional volumes reveal plenty. In the last year, OKTA has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in OKTA shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of technology names are under accumulation right now. But there's a powerful fundamental story happening with Okta.
#year #plenty #authentication
No wonder OKTA shares are up 94% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock.
Institutional volumes reveal plenty. In the last year, OKTA has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in OKTA shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of technology names are under accumulation right now. But there's a powerful fundamental story happening with Okta.
#year #plenty #authentication
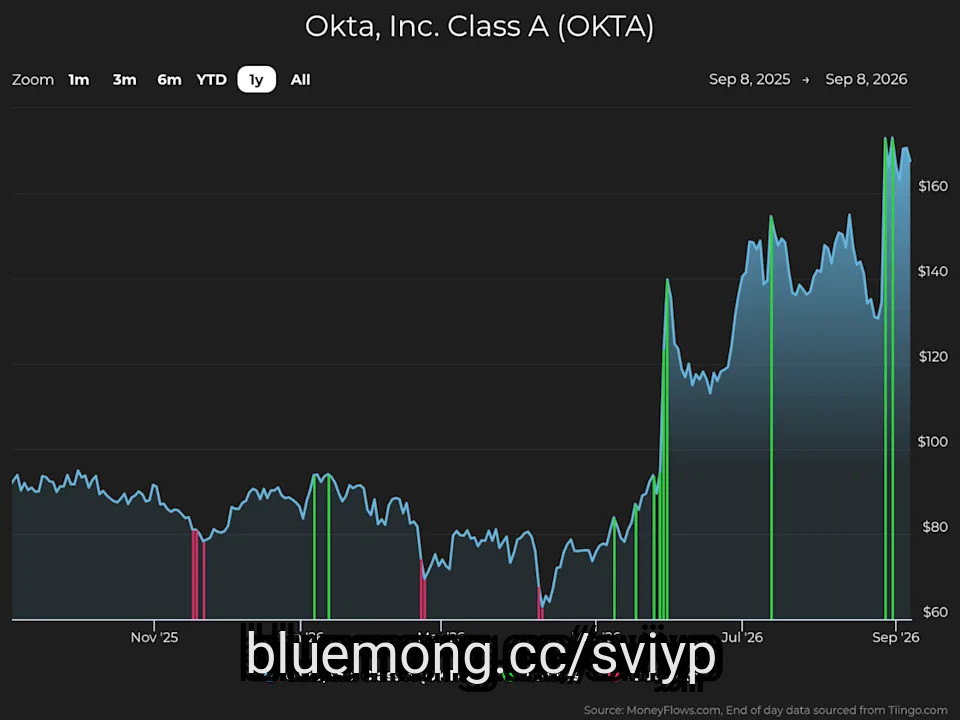
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

4 days ago
The International League T20 (ILT20) Season 5 was officially launched with a glittering event in Dubai, with fast-bowling legends Brett Lee and Shoaib Akhtar among the star attractions on an evening celebrating the league's rapid rise and growing influence across the Gulf region.
The event brought together leading figures from cricket, sport, business and government, with ILT20 chairman Khalid Al Zarooni and league commissioner, ICC board director and ECB general secretary Mubashshir Usmani highlighting the tournament's contribution to the development and expansion of cricket in the UAE and the wider region.
Al Zarooni reflected on the league's growth while thanking its stakeholders and partners.
"What began as a dream has grown into one of the world's leading cricket leagues, bringing together top players and major franchises, while helping grow cricket in the UAE, the region and beyond," he said.
He also acknowledged the support of franchise owners, commercial and strategic partners, with a special mention for Zee Network, while welcoming SPORTFIVE as a new commercial partner.
A special panel discussion hosted by former New Zealand international Simon Doull explored the changing landscape and future of cricket in the region and globally.
The panel featured Usmani, Dr Mohamed Abu Hamra, Eisa Sharif of the Dubai Sports Council, ZEE Entertainment Enterprises Deputy CEO and CFO Mukund Galgali, SportFive President Venu Nair and Bisleri Global Director Sales & Marketing Tushar Malhotra.
Doull later brought Lee and Shoaib together for another engaging discussion, with the two legendary fast bowlers speaking about the ILT20's growing impact on UAE and regional cricket.
The pair also looked back on their playing careers, recalling an era in which their blistering pace made them two of the most feared fast bowlers in world cricket.
The evening also featured a spell-binding performance by celebrity mentalist Karan Singh Magic, while the league unveiled its new brand identity for Season 5.
Season 5 will be played in November and December across the UAE's three iconic venues — Zayed Cricket Stadium in Abu Dhabi, Dubai International Stadium and Sharjah Cricket Stadium.
Defending champions Desert Vipers will enter the fifth season aiming to retain their crown. Gulf Giants won the inaugural season, followed by MI Emirates in Season 2 and Dubai Capitals in Season 3.
#stadium
The event brought together leading figures from cricket, sport, business and government, with ILT20 chairman Khalid Al Zarooni and league commissioner, ICC board director and ECB general secretary Mubashshir Usmani highlighting the tournament's contribution to the development and expansion of cricket in the UAE and the wider region.
Al Zarooni reflected on the league's growth while thanking its stakeholders and partners.
"What began as a dream has grown into one of the world's leading cricket leagues, bringing together top players and major franchises, while helping grow cricket in the UAE, the region and beyond," he said.
He also acknowledged the support of franchise owners, commercial and strategic partners, with a special mention for Zee Network, while welcoming SPORTFIVE as a new commercial partner.
A special panel discussion hosted by former New Zealand international Simon Doull explored the changing landscape and future of cricket in the region and globally.
The panel featured Usmani, Dr Mohamed Abu Hamra, Eisa Sharif of the Dubai Sports Council, ZEE Entertainment Enterprises Deputy CEO and CFO Mukund Galgali, SportFive President Venu Nair and Bisleri Global Director Sales & Marketing Tushar Malhotra.
Doull later brought Lee and Shoaib together for another engaging discussion, with the two legendary fast bowlers speaking about the ILT20's growing impact on UAE and regional cricket.
The pair also looked back on their playing careers, recalling an era in which their blistering pace made them two of the most feared fast bowlers in world cricket.
The evening also featured a spell-binding performance by celebrity mentalist Karan Singh Magic, while the league unveiled its new brand identity for Season 5.
Season 5 will be played in November and December across the UAE's three iconic venues — Zayed Cricket Stadium in Abu Dhabi, Dubai International Stadium and Sharjah Cricket Stadium.
Defending champions Desert Vipers will enter the fifth season aiming to retain their crown. Gulf Giants won the inaugural season, followed by MI Emirates in Season 2 and Dubai Capitals in Season 3.
#stadium
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

