42 mins. ago
Core & Main, Inc. (NYSE:CNM) reported quarterly sales of $2.145 billion on September 9, up 2.5%. Company-defined non-GAAP adjusted EBITDA reached $274 million. The measure adjusts consolidated net income for interest, taxes, depreciation and amortization, equity compensation, debt modification and extinguishment losses, offering expenses, and specified other income or expenses.
Consolidated net income rose 6.4% to $150 million, while GAAP diluted earnings per share increased 10% to $0.77. Diluted weighted-average shares declined approximately 2.5% to 193.4 million. Buybacks amplified an improvement that also had an operating foundation.
The company repurchased $169 million of equity during the quarter, against $62 million of operating cash flow. The investment question is whether cash generation can sustain capital returns alongside the spending needed to grow.
Core & Main, Inc. (NYSE:CNM) benefits from demand for essential infrastructure products. Management highlighted municipal demand, fire protection, treatment plants, and data centers as areas of strength. These end markets provide several sources of business even when construction demand is uneven.
Expense discipline also helped. Quarterly selling, general and administrative expenses declined to $301 million from $302 million. Controlling overhead allows modest sales growth to contribute more to earnings. Stronger volumes would make further earnings gains easier to sustain.
#income #main #quarterly
Consolidated net income rose 6.4% to $150 million, while GAAP diluted earnings per share increased 10% to $0.77. Diluted weighted-average shares declined approximately 2.5% to 193.4 million. Buybacks amplified an improvement that also had an operating foundation.
The company repurchased $169 million of equity during the quarter, against $62 million of operating cash flow. The investment question is whether cash generation can sustain capital returns alongside the spending needed to grow.
Core & Main, Inc. (NYSE:CNM) benefits from demand for essential infrastructure products. Management highlighted municipal demand, fire protection, treatment plants, and data centers as areas of strength. These end markets provide several sources of business even when construction demand is uneven.
Expense discipline also helped. Quarterly selling, general and administrative expenses declined to $301 million from $302 million. Controlling overhead allows modest sales growth to contribute more to earnings. Stronger volumes would make further earnings gains easier to sustain.
#income #main #quarterly


3 hours ago
Evommune, Inc. (NYSE:EVMN) announced on September 8 that EVO756 missed its primary endpoint in a randomized, double-blind, placebo-controlled Phase 2b trial involving 121 adults with moderate-to-severe atopic dermatitis. The primary measure was the percentage change from baseline in Eczema Area and Severity Index, or EASI, at week 12. No tested dose met the primary or secondary endpoints, and development in that indication will stop.
Evommune, Inc. (NYSE:EVMN) had already discontinued EVO756 for chronic spontaneous urticaria following a June trial failure. Development continues in migraine prevention. The setbacks place greater weight on EVO301, which has positive Phase 2a eczema data and a Phase 2b study planned for mid-2027.
Evommune, Inc. (NYSE:EVMN) has clinical evidence supporting its next eczema program. In February, the company reported that EVO301 met the primary endpoint in a randomized, double-blind, placebo-controlled Phase 2a trial involving 70 adults. Participants received two intravenous doses or placebo over a 12-week study.
Evommune, Inc. (NYSE:EVMN) reported a 55% EASI reduction with EVO301 versus 22% with placebo at week 12, a difference of 33 percentage points. The study met its prespecified Bayesian success criterion, and a separate conventional ****** ysis showed statistical significance at p
Evommune, Inc. (NYSE:EVMN) had already discontinued EVO756 for chronic spontaneous urticaria following a June trial failure. Development continues in migraine prevention. The setbacks place greater weight on EVO301, which has positive Phase 2a eczema data and a Phase 2b study planned for mid-2027.
Evommune, Inc. (NYSE:EVMN) has clinical evidence supporting its next eczema program. In February, the company reported that EVO301 met the primary endpoint in a randomized, double-blind, placebo-controlled Phase 2a trial involving 70 adults. Participants received two intravenous doses or placebo over a 12-week study.
Evommune, Inc. (NYSE:EVMN) reported a 55% EASI reduction with EVO301 versus 22% with placebo at week 12, a difference of 33 percentage points. The study met its prespecified Bayesian success criterion, and a separate conventional ****** ysis showed statistical significance at p


3 hours ago
The Williams Companies, Inc. (NYSE:WMB) lost a key New Jersey water-quality certification for Northeast Supply Enhancement, or NESE, after a September 8 federal appeals court ruling reported by Reuters on September 9. The Third Circuit vacated the certification and returned the matter to state regulators. The Williams Companies, Inc. (NYSE:WMB) said that, at this time, it did not expect the ruling to adversely affect construction or the anticipated in-service timeline.
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction


6 hours ago
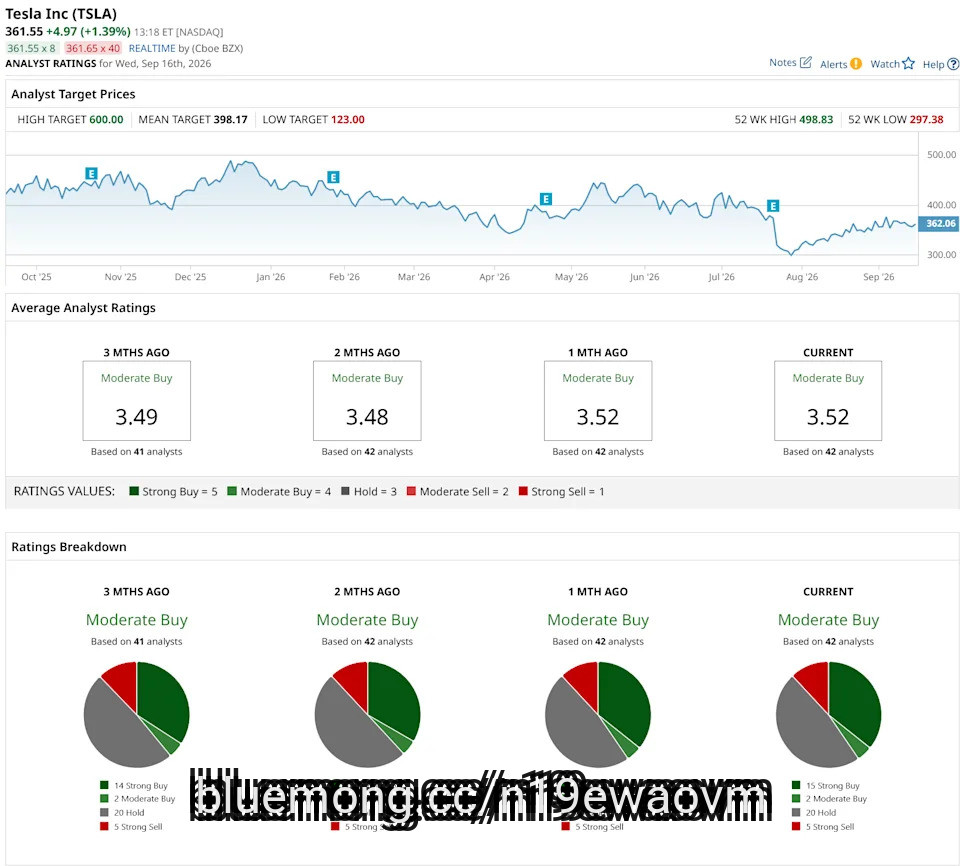
Tesla (TSLA) has had a rough 2026. The stock is down about 20% year-to-date (YTD), falling from $458.34 on the first trading day of the year to $297.38 in late July. That is a decline of more than 27% from peak to trough.
Its much-publicized Cybercab launch also disappointed investors. Tesla launched the robotaxi service in Austin on Sept. 3 with only 45 vehicles registered in Texas. The stock then dropped nearly 6% the next day, wiping out its 5.4% pre-launch gain, after federal safety regulators opened an audit into about 1,000 steering-wheel-free vehicles. Tesla's Model Y-based driverless ride service is still limited to seven U.S. metro areas.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
#tesla #Tsla
Its much-publicized Cybercab launch also disappointed investors. Tesla launched the robotaxi service in Austin on Sept. 3 with only 45 vehicles registered in Texas. The stock then dropped nearly 6% the next day, wiping out its 5.4% pre-launch gain, after federal safety regulators opened an audit into about 1,000 steering-wheel-free vehicles. Tesla's Model Y-based driverless ride service is still limited to seven U.S. metro areas.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
#tesla #Tsla


11 hours ago
By Katharine Jackson and Mike Scarcella
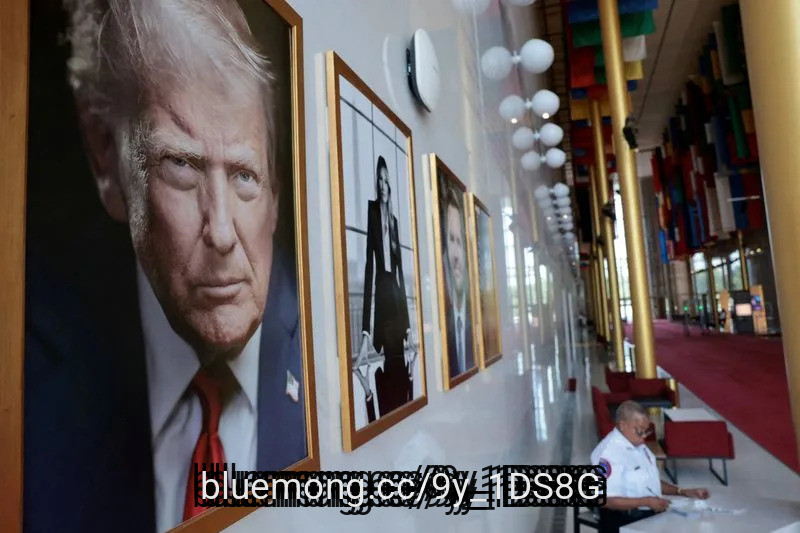
WASHINGTON, Sept 17 (Reuters) - A federal judge ordered President Donald Trump's administration on Thursday to provide at least 30 days' notice before taking any steps to demolish the Kennedy Center, the landmark performing arts venue that has become a flashpoint in his efforts to reshape the U.S. capital.
U.S. District Judge Christopher Cooper issued the order after lawyers for a Democratic congresswoman who is suing to keep the venue open and Trump's name off its facade submitted new evidence citing the Republican president's comments on Wednesday referring to demolishing the Kennedy Center.
"I think that the Trump administration should certainly have recognition. Because frankly, if we don't do that, it's going to close. It'll end up being ripped down," Trump told reporters in North Carolina, referring to putting his name on the facility established by Congress and opened in 1971 as a memorial to slain President John Kennedy.
Matt Floca, the Kennedy Center's Trump-backed executive director, said in a court filing earlier on Thursday that the building was being temporarily closed to ****** s safety risks in areas "exhibiting severe structural deterioration."
#president #venue
WASHINGTON, Sept 17 (Reuters) - A federal judge ordered President Donald Trump's administration on Thursday to provide at least 30 days' notice before taking any steps to demolish the Kennedy Center, the landmark performing arts venue that has become a flashpoint in his efforts to reshape the U.S. capital.
U.S. District Judge Christopher Cooper issued the order after lawyers for a Democratic congresswoman who is suing to keep the venue open and Trump's name off its facade submitted new evidence citing the Republican president's comments on Wednesday referring to demolishing the Kennedy Center.
"I think that the Trump administration should certainly have recognition. Because frankly, if we don't do that, it's going to close. It'll end up being ripped down," Trump told reporters in North Carolina, referring to putting his name on the facility established by Congress and opened in 1971 as a memorial to slain President John Kennedy.
Matt Floca, the Kennedy Center's Trump-backed executive director, said in a court filing earlier on Thursday that the building was being temporarily closed to ****** s safety risks in areas "exhibiting severe structural deterioration."
#president #venue

11 hours ago
On August 5, Kinetik Holdings Inc. (NYSE:KNTK) reported the strongest quarterly results in company history and raised its full-year 2026 guidance. The Permian-focused midstream operator posted net income, including noncontrolling interest, of $123.1 million for the quarter ended June 30, while Adjusted EBITDA climbed to $280.8 million. Management didn't stop at celebrating the number. It used the quarter as the launchpad for a string of expansion decisions that stretch out to 2028.
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter


13 hours ago
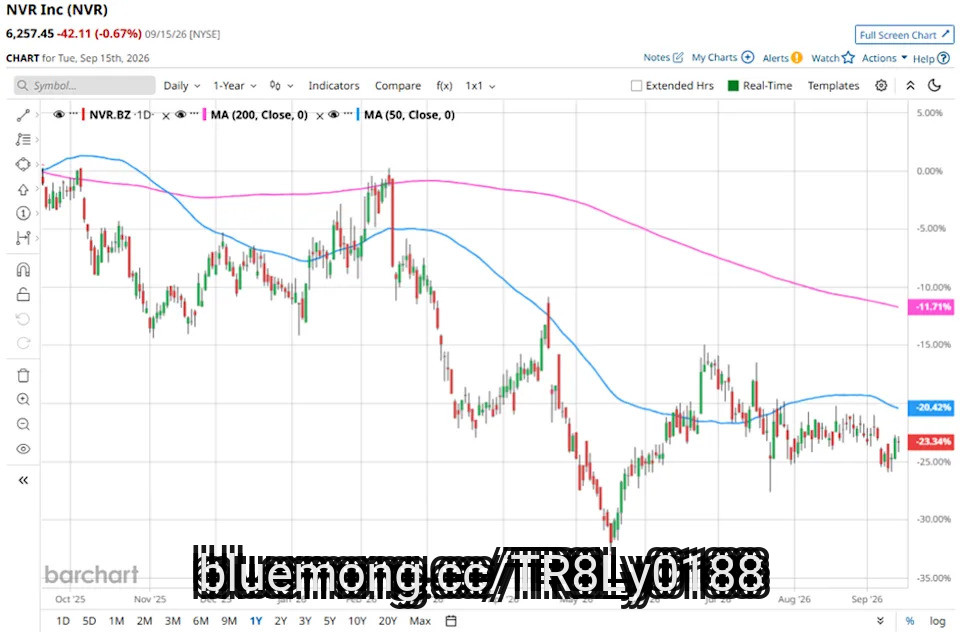
With a market cap of $16.7 billion, NVR, Inc. (NVR) is a leading company operating through two primary business segments: homebuilding and mortgage banking. Its homebuilding segment constructs and sells homes under the Ryan Homes, NVHomes, and Heartland Homes brands.
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and NVR fits this criterion perfectly. The company serves customers across 37 metropolitan areas in 16 states and Washington, D.C.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#Companies
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and NVR fits this criterion perfectly. The company serves customers across 37 metropolitan areas in 16 states and Washington, D.C.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#Companies


13 hours ago
The Nasdaq 100 has rallied slightly to show signs of life as we head toward that crucial Federal Reserve interest rate decision later today. A hike of 25 basis points is expected. This is perhaps the market coming to terms with the new reality as we hold the consolidation.
The question will be whether or not Kevin Warsh sounds extraordinarily hawkish during this press conference, or if it is a situation where it is one and done. I think that probably comes into play here as well. Rates are backing off the 5% level in the 10-year at the moment, at least, but it is worth noting that the market has been extraordinarily resilient.
The Dow Jones 30 is rising a bit in the early part of the session as well. It is in the oversold part of the stochastic oscillator. It is kind of a messy look for the stochastic oscillator at the moment, but it is worth noting that the area right around 52,250 has been important and so far seems to be holding up. The 50-day EMA near the 52,700 level offers pretty significant resistance, so it could be worth watching.
The S&P 500 continues to hang around the 7,600 level. That is an area that had previously been significant resistance and now is offering a significant amount of support over the last 4 or 5 trading sessions. We also have the 50-day EMA there as well. So, a bounce from here and a recovery just means more consolidation.
It will be interesting to watch how this plays out during that press conference. It could be a volatile and ******* py session, but ultimately, the stock market has been rather resilient. The earnings calendar treated us fairly well, and the resiliency of the U.S. economy continues.
#significant #extraordinarily
The question will be whether or not Kevin Warsh sounds extraordinarily hawkish during this press conference, or if it is a situation where it is one and done. I think that probably comes into play here as well. Rates are backing off the 5% level in the 10-year at the moment, at least, but it is worth noting that the market has been extraordinarily resilient.
The Dow Jones 30 is rising a bit in the early part of the session as well. It is in the oversold part of the stochastic oscillator. It is kind of a messy look for the stochastic oscillator at the moment, but it is worth noting that the area right around 52,250 has been important and so far seems to be holding up. The 50-day EMA near the 52,700 level offers pretty significant resistance, so it could be worth watching.
The S&P 500 continues to hang around the 7,600 level. That is an area that had previously been significant resistance and now is offering a significant amount of support over the last 4 or 5 trading sessions. We also have the 50-day EMA there as well. So, a bounce from here and a recovery just means more consolidation.
It will be interesting to watch how this plays out during that press conference. It could be a volatile and ******* py session, but ultimately, the stock market has been rather resilient. The earnings calendar treated us fairly well, and the resiliency of the U.S. economy continues.
#significant #extraordinarily



13 hours ago
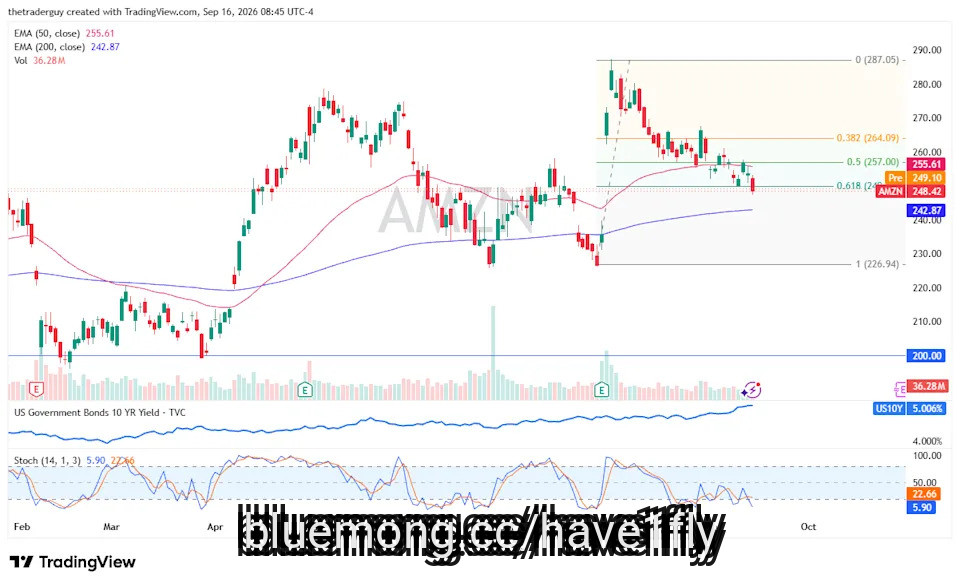
The pre-market for Amazon looks a bit bullish, although I wouldn't call it overly bullish. We are in an area that should be interesting for technical traders, though, as the last earnings call produced a massive gap and we find ourselves at the 61.8% Fibonacci retracement level.
We are getting close to an oversold condition in the stochastic oscillator, and the 10-year yield is now at 5% again, so that has its own part to play here.
I do think we have a situation where traders continue to look at this as a potential value play, but it is also going to be heavily influenced by the U.S. consumer and how it is feeling. Interest rates rising and inflation rising are not good things, but so far it looks like we are at least finding some type of support.
Walmart is doing very little in pre-market trading. It is currently finding the 50-day EMA as a potential barrier, and as a result, it might be worth looking at this through the prism of whether or not we can get above there. We are in the overbought condition in the stochastic oscillator, so maybe a little bit more consolidation. That would not be overly surprising because after all, most of the day is going to be waiting around for the Federal Reserve interest rate decision, and perhaps more important than that will be the press conference.
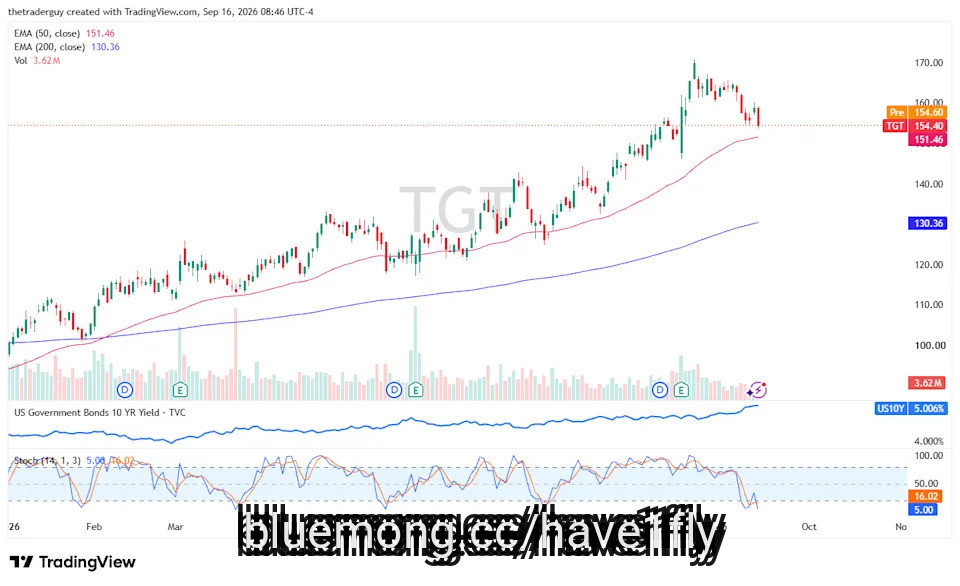
Target looks as if it is going to basically open up where it closed during the previous session, which was pretty ugly for Target. We are sitting just above the 50-day EMA, and it is in a nice uptrend. We are oversold in the stochastic oscillator now, so I'll be looking for some type of bounce.
#looks #overly
We are getting close to an oversold condition in the stochastic oscillator, and the 10-year yield is now at 5% again, so that has its own part to play here.
I do think we have a situation where traders continue to look at this as a potential value play, but it is also going to be heavily influenced by the U.S. consumer and how it is feeling. Interest rates rising and inflation rising are not good things, but so far it looks like we are at least finding some type of support.
Walmart is doing very little in pre-market trading. It is currently finding the 50-day EMA as a potential barrier, and as a result, it might be worth looking at this through the prism of whether or not we can get above there. We are in the overbought condition in the stochastic oscillator, so maybe a little bit more consolidation. That would not be overly surprising because after all, most of the day is going to be waiting around for the Federal Reserve interest rate decision, and perhaps more important than that will be the press conference.
Target looks as if it is going to basically open up where it closed during the previous session, which was pretty ugly for Target. We are sitting just above the 50-day EMA, and it is in a nice uptrend. We are oversold in the stochastic oscillator now, so I'll be looking for some type of bounce.
#looks #overly

15 hours ago
Ethereum's native token, Ether (ETH), is showing signs of underperformance against Bitcoin (BTC), with a bearish double-top setup emerging just as the US Senate's failure to advance the CLARITY Act adds fresh uncertainty to the crypto market.
Ether was trading near 0.03167 BTC on Sept. 16, after failing to sustain its latest advance against Bitcoin.
The ETH/BTC daily chart shows two comparable peaks near 0.03344 BTC, one formed in August and another in September. Together, they resemble a potential double top, a bearish reversal structure that typically develops when buyers repeatedly fail to push price through the same resistance area.
Its neckline sits around 0.03078 BTC, meaning ETH/BTC would need a decisive daily close below that level to validate the breakdown.
If that happens, subtracting the pattern's maximum height from the neckline produces a downside target near 0.0283 BTC. That would represent a decline of roughly 10% from current levels, signaling further Ethereum underperformance relative to Bitcoin.
#Bitcoin #underperformance #daily #neckline
Ether was trading near 0.03167 BTC on Sept. 16, after failing to sustain its latest advance against Bitcoin.
The ETH/BTC daily chart shows two comparable peaks near 0.03344 BTC, one formed in August and another in September. Together, they resemble a potential double top, a bearish reversal structure that typically develops when buyers repeatedly fail to push price through the same resistance area.
Its neckline sits around 0.03078 BTC, meaning ETH/BTC would need a decisive daily close below that level to validate the breakdown.
If that happens, subtracting the pattern's maximum height from the neckline produces a downside target near 0.0283 BTC. That would represent a decline of roughly 10% from current levels, signaling further Ethereum underperformance relative to Bitcoin.
#Bitcoin #underperformance #daily #neckline


1 day ago
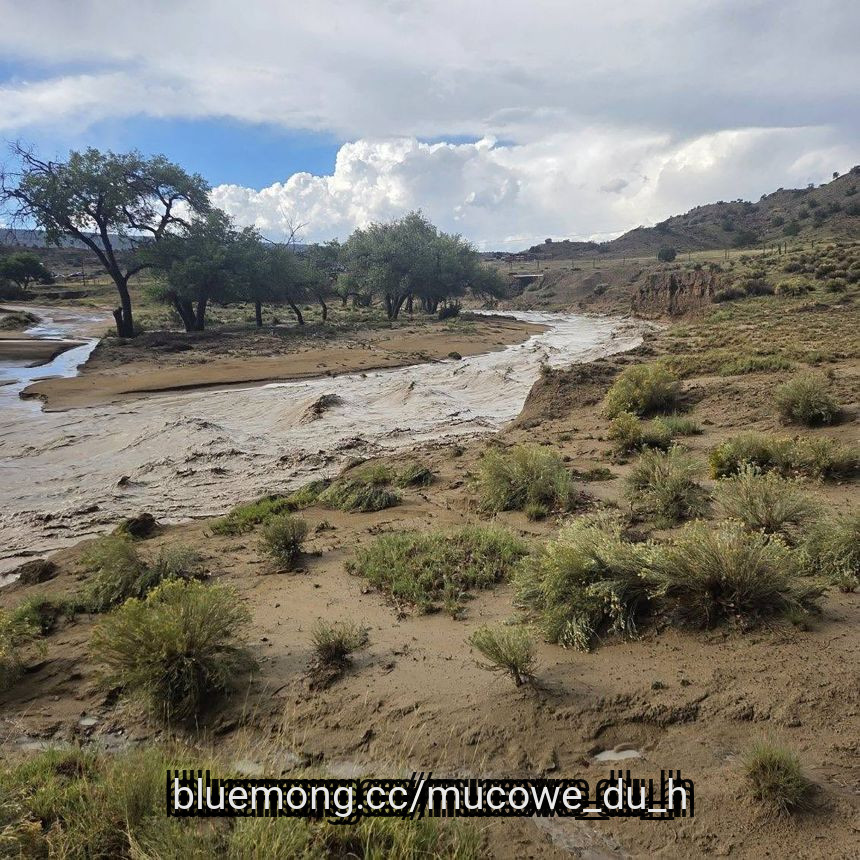
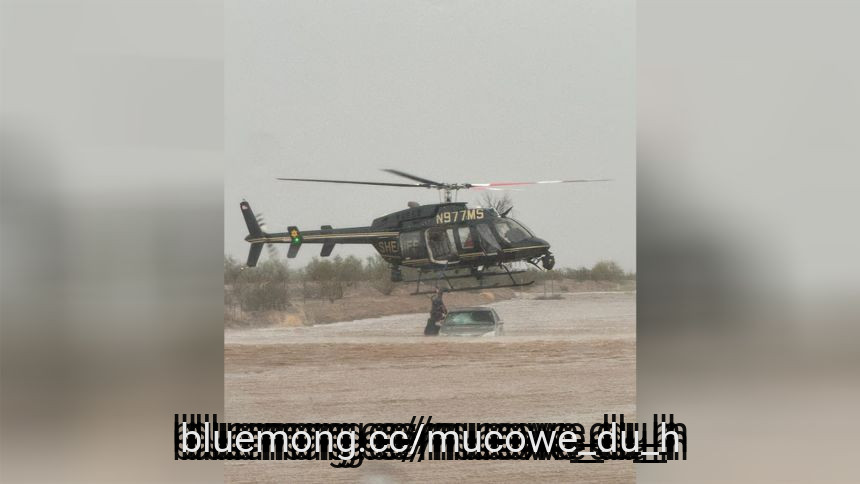
The Southwest faces a barrage of intense rain this week as rounds of storms are tapping into unusually moisture-rich air being pulled north from Baja California, after flash flooding in New Mexico killed three people early Wednesday.
Officers responded at around 12:30 a.m. local time to a report of three people washed away by flooding near Newcomb, New Mexico, on the Navajo Nation. Police discovered two adults and one juvenile on scene, the Navajo Police Department said in a statement. All three were ****** ounced dead. The department declined to provide further details about the deaths when contacted by CNN, citing concern for the family’s privacy.
🌧️ Get your local forecast from the CNN Weather app
Rainfall over Newcomb began Tuesday afternoon around 4:30 p.m. and lingered intermittently until just after midnight. The area saw around 0.5 inches to 1 inch of rain in total, with most of it falling within an hour Tuesday evening.
Wednesday’s storms prompted a rare Level 3 of 4 risk of flooding rainfall for parts of Arizona and New Mexico, including Phoenix and Tucson. Phoenix had not faced a flood risk that high since 2022.
#flooding #around #wednesday #navajo
Officers responded at around 12:30 a.m. local time to a report of three people washed away by flooding near Newcomb, New Mexico, on the Navajo Nation. Police discovered two adults and one juvenile on scene, the Navajo Police Department said in a statement. All three were ****** ounced dead. The department declined to provide further details about the deaths when contacted by CNN, citing concern for the family’s privacy.
🌧️ Get your local forecast from the CNN Weather app
Rainfall over Newcomb began Tuesday afternoon around 4:30 p.m. and lingered intermittently until just after midnight. The area saw around 0.5 inches to 1 inch of rain in total, with most of it falling within an hour Tuesday evening.
Wednesday’s storms prompted a rare Level 3 of 4 risk of flooding rainfall for parts of Arizona and New Mexico, including Phoenix and Tucson. Phoenix had not faced a flood risk that high since 2022.
#flooding #around #wednesday #navajo

1 day ago
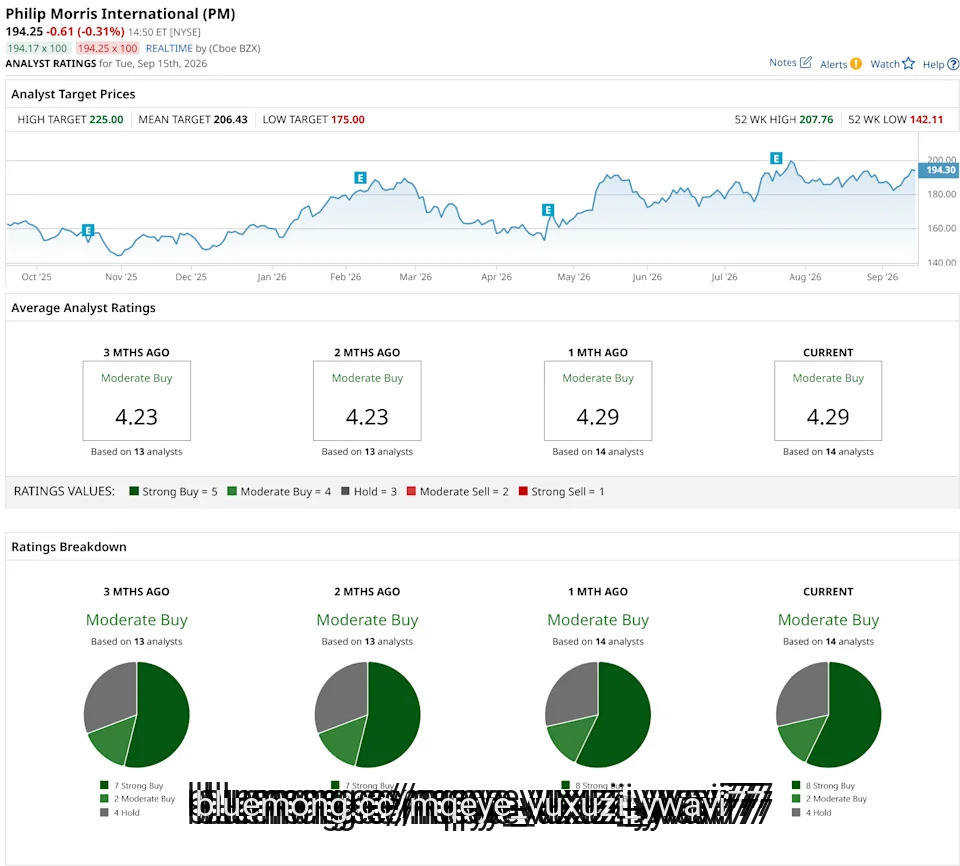
President Trump has nominated Nicole Saphier as Surgeon General, and she has revealed her investment portfolio, which includes tobacco stocks Philip Morris International (PM), Altria Group (MO), and British American Tobacco (BTI). If confirmed in the hearing scheduled for Sept. 16, Saphier would divest these holdings no later than 90 days after her confirmation, as part of an ethics agreement. This clearly avoids conflicts of interest with the role's public health mandate.
Meanwhile, the tobacco market is transforming, with smoke-free products gaining prominence. Bank of America's four‑week scanner data through May 30 showed that most U.S. tobacco categories continued to lose volume, while oral nicotine products remained the sector's strongest growth area.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#philip
Meanwhile, the tobacco market is transforming, with smoke-free products gaining prominence. Bank of America's four‑week scanner data through May 30 showed that most U.S. tobacco categories continued to lose volume, while oral nicotine products remained the sector's strongest growth area.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#philip


1 day ago
On September 10, Imperial Petroleum Inc. (NASDAQ:IMPP), a company involved in seaborne transportation of crude oil, dry bulk, and petroleum products, released its second quarter results. With a topline figure of $87.1 million, the company delivered record quarterly revenue, which also resulted in 139.9% year-over-year growth. Imperial's adjusted EBITDA for the second quarter stood at $41.7 million, while the Q2 adjusted net income of $35.3 million exhibited around 163% growth in comparison with Q2 FY25.
Ralf Gosch/Shutterstock.com
Several factors contributed to the second quarter topline growth. A 6.9 vessel rise in the company's average fleet size was the primary growth enabler. Other factors include encouraging dynamics across the drybulk segment, and higher rates for both drybulk and tankers amid the geopolitical uncertainties. Operating income for the quarter jumped to a near-record level of $33.4 million, which translates into a 307.3% growth relative to Q2 FY25. Imperial posted an adjusted EPS of $0.76 for the reported quarter, which almost doubled compared to the same quarter a year prior.
At the back of efficient fleet management, management remained focus on strengthening its financial position. The company ended the quarter with no debt, and its liquidity position also remained resilient. Cash and cash equivalents, including time deposits, increased from $179.1 million at the end of 2025 to $245.2 million as of June 30, 2026. The company added that its cash base had increased further to approximately $260 million as of the September 10 results release.
Certain areas of weakness warrant a closer examination. During the reported quarter, fleet operational utilization went down from 83.1% in prior year's second quarter to 73.5%. There was a substantial increase in some of the underlying operating expenses. For instance, the vessel operating expense stood at $14.4 million compared to $8.4 million during Q2 FY25. This $6 million rise can be attributed to Imperial's larger fleet size. Similarly, the voyage expenses also jumped from $10.7 million in last year's Q2 to $22.1 million for Q2 FY26. The incremental voyage expenses stemmed from higher bunkers' rates, as well as a 58.4% jump in spot days.
#fleet
Ralf Gosch/Shutterstock.com
Several factors contributed to the second quarter topline growth. A 6.9 vessel rise in the company's average fleet size was the primary growth enabler. Other factors include encouraging dynamics across the drybulk segment, and higher rates for both drybulk and tankers amid the geopolitical uncertainties. Operating income for the quarter jumped to a near-record level of $33.4 million, which translates into a 307.3% growth relative to Q2 FY25. Imperial posted an adjusted EPS of $0.76 for the reported quarter, which almost doubled compared to the same quarter a year prior.
At the back of efficient fleet management, management remained focus on strengthening its financial position. The company ended the quarter with no debt, and its liquidity position also remained resilient. Cash and cash equivalents, including time deposits, increased from $179.1 million at the end of 2025 to $245.2 million as of June 30, 2026. The company added that its cash base had increased further to approximately $260 million as of the September 10 results release.
Certain areas of weakness warrant a closer examination. During the reported quarter, fleet operational utilization went down from 83.1% in prior year's second quarter to 73.5%. There was a substantial increase in some of the underlying operating expenses. For instance, the vessel operating expense stood at $14.4 million compared to $8.4 million during Q2 FY25. This $6 million rise can be attributed to Imperial's larger fleet size. Similarly, the voyage expenses also jumped from $10.7 million in last year's Q2 to $22.1 million for Q2 FY26. The incremental voyage expenses stemmed from higher bunkers' rates, as well as a 58.4% jump in spot days.
#fleet

1 day ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted UnitedHealth Group Incorporated (NYSE:UNH) as a material contributor. UnitedHealth Group Incorporated (NYSE:UNH) is a multinational health benefits company based in Eden Prairie, Minnesota. On September 14, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $383.55 per share. Over the past month, UnitedHealth Group Incorporated (NYSE:UNH) declined 4.38%, while its shares gained 10.86% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $344.27 billion with a 52-week trading range between $255.97 and $461.62.
Auxier ******* et Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"UnitedHealth Group Incorporated (NYSE:UNH) Leads the Way in Reshaping the Insurance Industry with AI UnitedHealth Group is among the companies that have successfully integrated AI into various parts of their operations. One of the most significant benefits has been in administrative functions, where AI has helped save tens of thousands of hours through increased automation and efficiency. As an example, automated transcription of patient encounters has contributed to lower levels of clinician burnout. Management reports that they are generating about $2 of value for every $1 spent on AI due to reductions in manual labor. We like this measured approach to implementing AI where it can provide clear operational benefits and attractive returns, which has been a key strategy of current CEO Stephen Hemsley. UnitedHealth's success in AI use highlights the technology's potential on the user side where companies can benefit without the high upfront cost of building the infrastructure. Cigna Group is projecting $200 million in
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted UnitedHealth Group Incorporated (NYSE:UNH) as a material contributor. UnitedHealth Group Incorporated (NYSE:UNH) is a multinational health benefits company based in Eden Prairie, Minnesota. On September 14, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $383.55 per share. Over the past month, UnitedHealth Group Incorporated (NYSE:UNH) declined 4.38%, while its shares gained 10.86% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $344.27 billion with a 52-week trading range between $255.97 and $461.62.
Auxier ******* et Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"UnitedHealth Group Incorporated (NYSE:UNH) Leads the Way in Reshaping the Insurance Industry with AI UnitedHealth Group is among the companies that have successfully integrated AI into various parts of their operations. One of the most significant benefits has been in administrative functions, where AI has helped save tens of thousands of hours through increased automation and efficiency. As an example, automated transcription of patient encounters has contributed to lower levels of clinician burnout. Management reports that they are generating about $2 of value for every $1 spent on AI due to reductions in manual labor. We like this measured approach to implementing AI where it can provide clear operational benefits and attractive returns, which has been a key strategy of current CEO Stephen Hemsley. UnitedHealth's success in AI use highlights the technology's potential on the user side where companies can benefit without the high upfront cost of building the infrastructure. Cigna Group is projecting $200 million in
1 day ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ******* et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#Growth #asset
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ******* et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#Growth #asset

1 day ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ******* et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
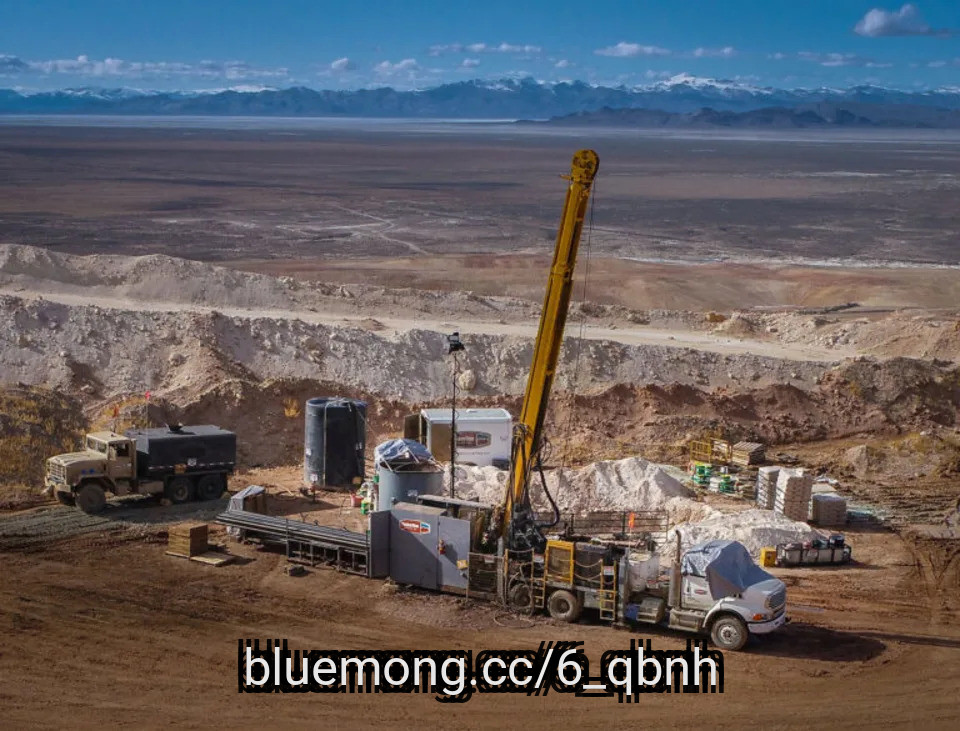
Photo from Hycroft Mining website
#letter
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ******* et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Photo from Hycroft Mining website
#letter

1 day ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Gates Industrial Corporation Ltd. (NYSE:GTES). Gates Industrial Corporation Ltd. (NYSE:GTES) is a leading manufacturer of engineered power transmission and fluid power solutions. On September 14, 2026, Gates Industrial Corporation Ltd. (NYSE:GTES) closed at $25.42 per share. Over the past month, Gates Industrial Corporation Ltd. (NYSE:GTES) declined 6.17%, and its shares gained 0.77% over the past 52 weeks. Gates Industrial Corporation Ltd. (NYSE:GTES) has a market capitalization of $6.44 billion, and its stock has traded within a 52-week range of $20.88 and $30.34.
Auxier ******* et Management stated the following regarding Gates Industrial Corporation Ltd. (NYSE:GTES) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar and Gates Industrial Corporation Ltd. (NYSE:GTES) Ltd. (NYSE:GTES) also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Gates Industrial Corporation Ltd. (NYSE:GTES) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 36 hedge fund portfolios held Gates Industrial Corporation Ltd. (NYSE:GTES) at the end of the second quarter which was 37 in the previous quarter. While we acknowledge the potential of Gates Industrial Corporation Ltd. (NYSE:GTES) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Gates Industrial Corporation Ltd. (NYSE:GTES). Gates Industrial Corporation Ltd. (NYSE:GTES) is a leading manufacturer of engineered power transmission and fluid power solutions. On September 14, 2026, Gates Industrial Corporation Ltd. (NYSE:GTES) closed at $25.42 per share. Over the past month, Gates Industrial Corporation Ltd. (NYSE:GTES) declined 6.17%, and its shares gained 0.77% over the past 52 weeks. Gates Industrial Corporation Ltd. (NYSE:GTES) has a market capitalization of $6.44 billion, and its stock has traded within a 52-week range of $20.88 and $30.34.
Auxier ******* et Management stated the following regarding Gates Industrial Corporation Ltd. (NYSE:GTES) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar and Gates Industrial Corporation Ltd. (NYSE:GTES) Ltd. (NYSE:GTES) also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Gates Industrial Corporation Ltd. (NYSE:GTES) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 36 hedge fund portfolios held Gates Industrial Corporation Ltd. (NYSE:GTES) at the end of the second quarter which was 37 in the previous quarter. While we acknowledge the potential of Gates Industrial Corporation Ltd. (NYSE:GTES) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from


1 day ago
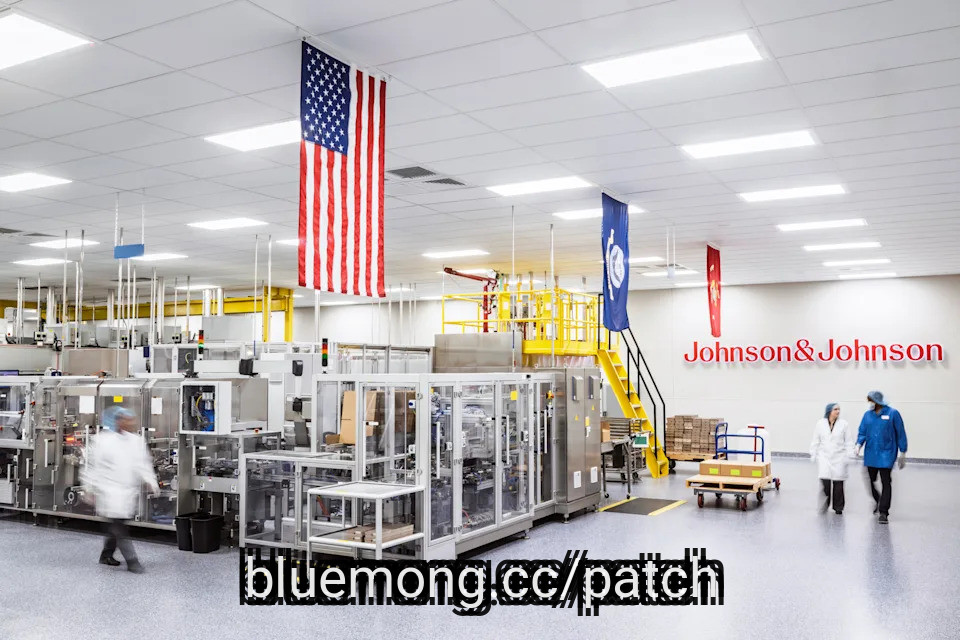
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy

1 day ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio

1 day ago
Elon Musk once again hinted at a possible deepening of collaboration, perhaps even a merger, between his two major companies: Tesla (TSLA) and ****** eX (SPCX).
Speaking at the All-In Summit last night, Musk said it was a great question whether the two companies would remain separate despite several avenues for collaboration.
"With all this collaboration, on so many levels, who can imagine what action one might take when there's so much close collaboration in so many areas," he said.
Yahoo Finance reached out to ****** eX regarding Musk's comments about a possible merger but did not immediately hear back.
#musk #elon
Speaking at the All-In Summit last night, Musk said it was a great question whether the two companies would remain separate despite several avenues for collaboration.
"With all this collaboration, on so many levels, who can imagine what action one might take when there's so much close collaboration in so many areas," he said.
Yahoo Finance reached out to ****** eX regarding Musk's comments about a possible merger but did not immediately hear back.
#musk #elon

1 day ago
The Nasdaq 100 initially pulled back a bit during the early part of the trading session on Tuesday, but showed signs of life and looks very much like a market that is stuck in a range at the moment. This makes a certain amount of sense because we do get the Federal Reserve interest rate decision on Wednesday, but more importantly, we get the press conference.
A hike of 25 basis points is expected. That, in and of itself, probably will not move much. It is the tone of the press conference that will be the real tell.
The Dow Jones 30 initially fell but seems to be finding support at 52,000 again, an area that has previously been both support and resistance. Above, it looks like the 50-day EMA is trying to act as resistance. We are approaching an oversold condition on the stochastic oscillator, but with the 10-year yield at 5%, it makes a certain amount of sense that we struggle a bit.
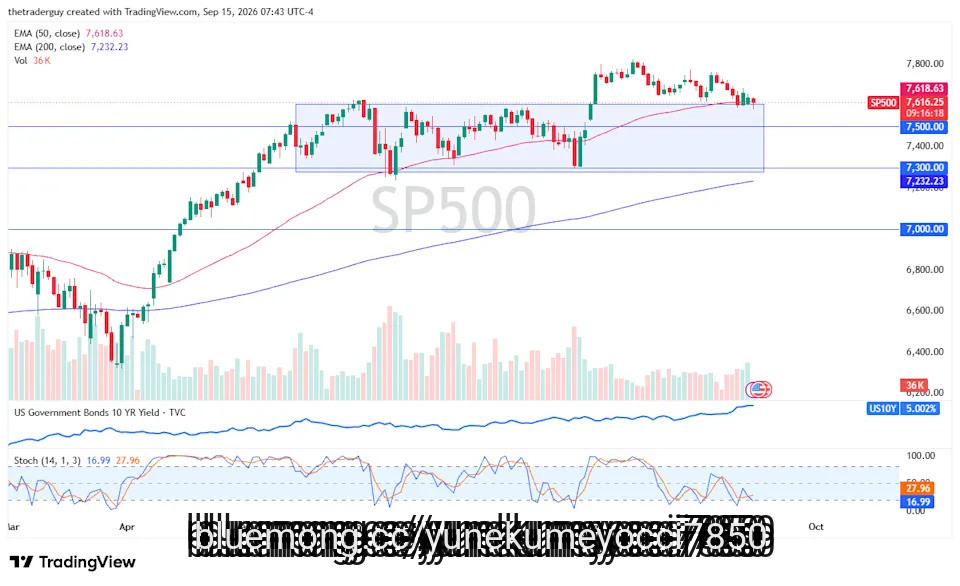
The S&P 500 continues to hang around the 7,600 level. This is an area that previously had been significant resistance. It now looks as if it is trying to offer support yet again. The 50-day EMA is in this neighborhood, and the market almost certainly will be waiting to see what Kevin Warsh has to say tomorrow.
With that being the case, things look somewhat neutral here. Longer term, I am still bullish until something completely changes. At this point, though, I will be looking to see whether or not we get any type of upward momentum.
#looks #makes #certain
A hike of 25 basis points is expected. That, in and of itself, probably will not move much. It is the tone of the press conference that will be the real tell.
The Dow Jones 30 initially fell but seems to be finding support at 52,000 again, an area that has previously been both support and resistance. Above, it looks like the 50-day EMA is trying to act as resistance. We are approaching an oversold condition on the stochastic oscillator, but with the 10-year yield at 5%, it makes a certain amount of sense that we struggle a bit.
The S&P 500 continues to hang around the 7,600 level. This is an area that previously had been significant resistance. It now looks as if it is trying to offer support yet again. The 50-day EMA is in this neighborhood, and the market almost certainly will be waiting to see what Kevin Warsh has to say tomorrow.
With that being the case, things look somewhat neutral here. Longer term, I am still bullish until something completely changes. At this point, though, I will be looking to see whether or not we get any type of upward momentum.
#looks #makes #certain


1 day ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea

1 day ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Logitech International S.A. (NASDAQ:LOGI). Logitech International S.A. (NASDAQ:LOGI) is a Swiss technology company that designs, manufactures, and markets software-enabled hardware solutions. On September 14, 2026, Logitech International S.A. (NASDAQ:LOGI) closed at $100.36 per share. Over the past month, Logitech International S.A. (NASDAQ:LOGI) returned 2.09%, and its shares lost 10.65% over the past 52 weeks. Logitech International S.A. (NASDAQ:LOGI) has a market capitalization of $14.14 billion; its stock has traded within a 52-week trading range of $83.32 to $129.66.
Prosper Stars & Stripes stated the following regarding Logitech International S.A. (NASDAQ:LOGI) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories (DLB), and Logitech International S.A. (NASDAQ:LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to stimulate sales, compounding the pressure."
#na
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Logitech International S.A. (NASDAQ:LOGI). Logitech International S.A. (NASDAQ:LOGI) is a Swiss technology company that designs, manufactures, and markets software-enabled hardware solutions. On September 14, 2026, Logitech International S.A. (NASDAQ:LOGI) closed at $100.36 per share. Over the past month, Logitech International S.A. (NASDAQ:LOGI) returned 2.09%, and its shares lost 10.65% over the past 52 weeks. Logitech International S.A. (NASDAQ:LOGI) has a market capitalization of $14.14 billion; its stock has traded within a 52-week trading range of $83.32 to $129.66.
Prosper Stars & Stripes stated the following regarding Logitech International S.A. (NASDAQ:LOGI) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories (DLB), and Logitech International S.A. (NASDAQ:LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to stimulate sales, compounding the pressure."
#na


1 day ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Dolby Laboratories, Inc. (NYSE:DLB). Dolby Laboratories, Inc. (NYSE:DLB) is a US-based technology company that designs and manufactures audio, imaging, accessibility, and other hardware and software solutions for television, broadcast, and live entertainment industries. On September 14, 2026, Dolby Laboratories, Inc. (NYSE:DLB) closed at $61.91 per share. Over the past month, Dolby Laboratories, Inc. (NYSE:DLB) returned 1.33%, and its shares lost 14.24% over the past 52 weeks. Dolby Laboratories, Inc. (NYSE:DLB) has a market capitalization of $5.79 billion, and its stock has traded within a 52-week range of $48.26 and $73.01.
Prosper Stars & Stripes stated the following regarding Dolby Laboratories, Inc. (NYSE:DLB) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories, Inc. (NYSE:DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to st
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Dolby Laboratories, Inc. (NYSE:DLB). Dolby Laboratories, Inc. (NYSE:DLB) is a US-based technology company that designs and manufactures audio, imaging, accessibility, and other hardware and software solutions for television, broadcast, and live entertainment industries. On September 14, 2026, Dolby Laboratories, Inc. (NYSE:DLB) closed at $61.91 per share. Over the past month, Dolby Laboratories, Inc. (NYSE:DLB) returned 1.33%, and its shares lost 14.24% over the past 52 weeks. Dolby Laboratories, Inc. (NYSE:DLB) has a market capitalization of $5.79 billion, and its stock has traded within a 52-week range of $48.26 and $73.01.
Prosper Stars & Stripes stated the following regarding Dolby Laboratories, Inc. (NYSE:DLB) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories, Inc. (NYSE:DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to st


1 day ago
Auxier ****** et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ****** et Management highlighted UnitedHealth Group Incorporated (NYSE:UNH) as a material contributor. UnitedHealth Group Incorporated (NYSE:UNH) is a multinational health benefits company based in Eden Prairie, Minnesota. On September 14, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $383.55 per share. Over the past month, UnitedHealth Group Incorporated (NYSE:UNH) declined 4.38%, while its shares gained 10.86% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $344.27 billion with a 52-week trading range between $255.97 and $461.62.
Auxier ****** et Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"UnitedHealth Group Incorporated (NYSE:UNH) Leads the Way in Reshaping the Insurance Industry with AI UnitedHealth Group is among the companies that have successfully integrated AI into various parts of their operations. One of the most significant benefits has been in administrative functions, where AI has helped save tens of thousands of hours through increased automation and efficiency. As an example, automated transcription of patient encounters has contributed to lower levels of clinician burnout. Management reports that they are generating about $2 of value for every $1 spent on AI due to reductions in manual labor. We like this measured approach to implementing AI where it can provide clear operational benefits and attractive returns, which has been a key strategy of current CEO Stephen Hemsley. UnitedHealth's success in AI use highlights the technology's potential on the user side where companies can benefit without the high upfront cost of building the infrastructure. Cigna Group is projecting $200 million in me
In its second-quarter 2026 investor letter, Auxier ****** et Management highlighted UnitedHealth Group Incorporated (NYSE:UNH) as a material contributor. UnitedHealth Group Incorporated (NYSE:UNH) is a multinational health benefits company based in Eden Prairie, Minnesota. On September 14, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $383.55 per share. Over the past month, UnitedHealth Group Incorporated (NYSE:UNH) declined 4.38%, while its shares gained 10.86% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $344.27 billion with a 52-week trading range between $255.97 and $461.62.
Auxier ****** et Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"UnitedHealth Group Incorporated (NYSE:UNH) Leads the Way in Reshaping the Insurance Industry with AI UnitedHealth Group is among the companies that have successfully integrated AI into various parts of their operations. One of the most significant benefits has been in administrative functions, where AI has helped save tens of thousands of hours through increased automation and efficiency. As an example, automated transcription of patient encounters has contributed to lower levels of clinician burnout. Management reports that they are generating about $2 of value for every $1 spent on AI due to reductions in manual labor. We like this measured approach to implementing AI where it can provide clear operational benefits and attractive returns, which has been a key strategy of current CEO Stephen Hemsley. UnitedHealth's success in AI use highlights the technology's potential on the user side where companies can benefit without the high upfront cost of building the infrastructure. Cigna Group is projecting $200 million in me

1 day ago
Auxier ***** et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ***** et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ***** et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#NYSE #quarter #Growth #strong
In its second-quarter 2026 investor letter, Auxier ***** et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ***** et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#NYSE #quarter #Growth #strong
1 day ago
Auxier ****** et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ****** et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ****** et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Photo from Hycroft Mining website
#quarter #asset #management #focus
In its second-quarter 2026 investor letter, Auxier ****** et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ****** et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Photo from Hycroft Mining website
#quarter #asset #management #focus

1 day ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Gates Industrial Corporation Ltd. (NYSE:GTES). Gates Industrial Corporation Ltd. (NYSE:GTES) is a leading manufacturer of engineered power transmission and fluid power solutions. On September 14, 2026, Gates Industrial Corporation Ltd. (NYSE:GTES) closed at $25.42 per share. Over the past month, Gates Industrial Corporation Ltd. (NYSE:GTES) declined 6.17%, and its shares gained 0.77% over the past 52 weeks. Gates Industrial Corporation Ltd. (NYSE:GTES) has a market capitalization of $6.44 billion, and its stock has traded within a 52-week range of $20.88 and $30.34.
Auxier ******* et Management stated the following regarding Gates Industrial Corporation Ltd. (NYSE:GTES) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar and Gates Industrial Corporation Ltd. (NYSE:GTES) Ltd. (NYSE:GTES) also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Gates Industrial Corporation Ltd. (NYSE:GTES) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 36 hedge fund portfolios held Gates Industrial Corporation Ltd. (NYSE:GTES) at the end of the second quarter which was 37 in the previous quarter. While we acknowledge the potential of Gates Industrial Corporation Ltd. (NYSE:GTES) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Gates Industrial Corporation Ltd. (NYSE:GTES). Gates Industrial Corporation Ltd. (NYSE:GTES) is a leading manufacturer of engineered power transmission and fluid power solutions. On September 14, 2026, Gates Industrial Corporation Ltd. (NYSE:GTES) closed at $25.42 per share. Over the past month, Gates Industrial Corporation Ltd. (NYSE:GTES) declined 6.17%, and its shares gained 0.77% over the past 52 weeks. Gates Industrial Corporation Ltd. (NYSE:GTES) has a market capitalization of $6.44 billion, and its stock has traded within a 52-week range of $20.88 and $30.34.
Auxier ******* et Management stated the following regarding Gates Industrial Corporation Ltd. (NYSE:GTES) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar and Gates Industrial Corporation Ltd. (NYSE:GTES) Ltd. (NYSE:GTES) also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Gates Industrial Corporation Ltd. (NYSE:GTES) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 36 hedge fund portfolios held Gates Industrial Corporation Ltd. (NYSE:GTES) at the end of the second quarter which was 37 in the previous quarter. While we acknowledge the potential of Gates Industrial Corporation Ltd. (NYSE:GTES) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from


1 day ago
WASHINGTON (AP) — The top Democrat on the House Foreign Affairs Committee said Wednesday that he's going to block a proposed sale of $2.8 billion in heavy weaponry to Israel over concerns that the powerful bombs may not be used in line with U.S. and international law.
Rep. Gregory Meeks of New York said he would withhold approval for the sale because of "grave, unresolved concerns" about how these munitions could be used in densely populated areas of Gaza and Lebanon by Israeli Prime Minister Benjamin Netanyahu's government.
"The Trump administration has not provided sufficient ****** urances that these weapons will be used by the Netanyahu government in accordance with U.S. law and with appropriate protections for civilians," Meeks said in a statement. "I therefore will not clear this sale at this time."
Meeks' objections, however, will not likely affect the sale, which was informally notified to lawmakers on Tuesday. Once it is formally notified to Congress, Secretary of State Marco Rubio can bypass the normal congressional review process by making an emergency determination that the transaction is an urgent national security interest.
Rubio has done so in the past, including bypassing a normal congressional review process to approve a nearly $3 billion sale to Israel last year. The administration then approved a new series of arms sales to Israel totaling $6.67 billion in January.
#used
Rep. Gregory Meeks of New York said he would withhold approval for the sale because of "grave, unresolved concerns" about how these munitions could be used in densely populated areas of Gaza and Lebanon by Israeli Prime Minister Benjamin Netanyahu's government.
"The Trump administration has not provided sufficient ****** urances that these weapons will be used by the Netanyahu government in accordance with U.S. law and with appropriate protections for civilians," Meeks said in a statement. "I therefore will not clear this sale at this time."
Meeks' objections, however, will not likely affect the sale, which was informally notified to lawmakers on Tuesday. Once it is formally notified to Congress, Secretary of State Marco Rubio can bypass the normal congressional review process by making an emergency determination that the transaction is an urgent national security interest.
Rubio has done so in the past, including bypassing a normal congressional review process to approve a nearly $3 billion sale to Israel last year. The administration then approved a new series of arms sales to Israel totaling $6.67 billion in January.
#used

1 day ago
Tributes began pouring in Wednesday after a news helicopter crashed in Los Angeles, leaving three people dead.
The crash occurred just before 7 p.m. local time Tuesday in the Chatsworth area of the San Fernando Valley, as the news chopper was covering a road traffic accident.
Angel City Air operated the helicopter, which was providing news coverage for NBC Los Angeles.
The victims aboard the helicopter were identified as Eliana Moreno, a journalist familiar to viewers of the station and its Spanish-language sister station, Telemundo 52, and pilot George Marciniw. The pair began flying together in 2023.
A pedestrian on the ground was also confirmed to have died at the scene, officials said. Authorities identified the third victim as Edy Gutiérrez Mejia, 29.
#wednesday
The crash occurred just before 7 p.m. local time Tuesday in the Chatsworth area of the San Fernando Valley, as the news chopper was covering a road traffic accident.
Angel City Air operated the helicopter, which was providing news coverage for NBC Los Angeles.
The victims aboard the helicopter were identified as Eliana Moreno, a journalist familiar to viewers of the station and its Spanish-language sister station, Telemundo 52, and pilot George Marciniw. The pair began flying together in 2023.
A pedestrian on the ground was also confirmed to have died at the scene, officials said. Authorities identified the third victim as Edy Gutiérrez Mejia, 29.
#wednesday