8 days ago
Elon Musk has never shied away from ambitious timelines, and his most recent one connects two companies directly together. In a post on X dated September 13, Musk stated that he is "highly confident" that **** e Exploration Technologies Corp. (NASDAQ:SPCX) will transport NVIDIA Corporation (NASDAQ:NVDA) Vera Rubin NVL72 AI computers into orbit next year, repeating a plan that has already moved both companies' stock this year.
The comment strengthens **** eX's Starmind concept, which aims to establish AI data centers in orbit rather than on the ground. The first satellite, named Starmind AI1, will carry a **** e-optimized version of NVIDIA's Vera Rubin NVL72 rack-scale system. The standard terrestrial NVL72 combines 72 Rubin GPUs and 36 Vera CPUs, although **** eX and NVIDIA have not disclosed the final configuration of the orbital version. **** e Exploration Technologies Corp. (NASDAQ:SPCX) plans to launch the satellite in the fourth quarter of 2027 and reach substantial scale by 2028. Musk's plan isn't new; during **** eX's first earnings conference as a public company in August, he stated that the company would build exclusively on NVIDIA hardware in the future, calling the Vera Rubin architecture the best available AI computer design.
Musk's central point is that **** e is, in the long run, the most cost-effective area to develop AI computing. He cites solar power availability in orbit as a crucial advantage, and estimates that within two to three years, **** e might become the lowest-cost place for AI computing in general, describing the orbital architecture as simpler, less expensive, denser, and lighter than a standard data-center rack. Not everyone believes the physics and economics will align on Musk's timeframe. Microsoft President Brad Smith has publicly questioned the broader concept, telling reporters that he would be surprised if companies actually transferred computation from land to low-Earth orbit.
For NVIDIA Corporation (NASDAQ:NVDA), the read-through is simple: **** e-based computing would represent a new, if early-stage and speculative, source of demand for its Vera Rubin platform, on top of the company's strong position in terrestrial AI infrastructure. According to some **** yst models, **** eX accounts for approximately 5% of NVIDIA's revenue.
SpaceX's reasoning is more convoluted. The plan is entirely dependent on the success of Starship, **** eX's next-generation rocket system, which still needs to demonstrate its capacity to handle launch frequency and reliability on the scale Musk describes. When Musk said during **** eX's August earnings call that the company would build its future AI infrastructure exclusively on NVIDIA, NVDA shares rose more than 4%, while **** eX's shares fell more than 10% before paring losses, reflecting investor concerns about execution risk and capital intensity, despite the fact that the NVIDIA relationship was well received.
#Companies
11 days ago
Elon Musk is getting serious about putting artificial intelligence (AI) into orbit. The ***** eX (SPCX) CEO is reportedly confident the company can launch Nvidia (NVDA) powered AI systems into ***** e in 2027. ***** eX and Nvidia are working on a ***** e-optimized version of Nvidia's Vera Rubin NVL72 platform, and Musk says the system should be lighter, denser, and cheaper than a traditional data-center rack. That matters because ***** eX is trying to turn orbital computing into a major business, while Nvidia could gain another market for its AI hardware.
The opportunity is much bigger than a headline. ***** eX could eventually sell computing capacity from satellites just as it sells broadband through Starlink. Meanwhile, Nvidia could supply the chips behind that infrastructure. Investors should still remember that this is an emerging business, and commercial scale is not expected immediately. Still, the plan gives both companies another way to capitalize on the AI spending boom.
Why It's Time to Load Up on Nvidia Stock
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
#NVIDIA #SpaceX #much #still

11 days ago
Spring, Texas-based Hewlett Packard Enterprise Company (HPE) develops intelligent solutions in the United States, the Americas, and internationally. The company has a market cap of $74.2 billion and operates in five segments: Server, Hybrid Cloud, Networking, Financial Services, and Corporate Investments and Other, and offers general-purpose servers, workload-optimized servers, and integrated systems, among others.
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." HPE fits squarely into that category, with its market cap exceeding this threshold and reflecting its substantial size and influence in the communication equipment industry.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#packard


14 days ago
Starbucks Corporation (NASDAQ:SBUX) is betting $1 billion that leather armchairs, rugs, and bookshelves can turn a recovering coffee business into a more profitable one. The company plans to upgrade as many as 9,000 North American stores into warmer, more comfortable **** es designed to bring back customers who stopped treating Starbucks as a place to sit and stay. The strategy arrives as CEO Brian Niccol's turnaround gains traction, but investors still need to see whether higher traffic can translate into stronger margins.
Pixabay/Public Domain
The store upgrades are part of Niccol's broader "Back to Starbucks" strategy, which has already helped reverse a prolonged sales slump. Global comparable-store sales increased 7.9% in the latest quarter, with transactions up 4.2% and average ticket up 3.5%. U.S. comparable sales also rose 7.9%, indicating that the recovery is being driven by more than higher prices.
Starbucks Corporation (NASDAQ:SBUX) is spending roughly $150,000 per store on the new uplifts, far below the cost of previous renovations, and the work can generally be completed overnight without closing stores. The company expects about 1,500 upgrades to be finished by the end of September and ultimately wants to reach 8,000 to 9,000 company-operated North American locations.
That matters because Starbucks Corporation (NASDAQ:SBUX) has gradually become optimized for transactions rather than lingering. Mobile orders now account for roughly one-third of U.S. transactions, more than twice their share in 2019. The new design is therefore an attempt to restore the "third place" concept without abandoning the convenience that has become central to the business.
#corporation #NASDAQ #sales #transactions

18 days ago
On September 3, AbbVie Inc. (NYSE:ABBV) finalized its acquisition of clinical-stage biotech Apogee Therapeutics, Inc. (NASDAQ:APGE) for $135.11 per share in cash. The $10.9 billion buyouts immediately fold Apogee's promising inflammatory and immunology (I&I) pipeline into AbbVie's commercial engine. On the exact same day, AbbVie separately reported positive Phase 3 Cervino trial results for its bispecific T-cell engager, etentamig, in relapsed/refractory multiple myeloma. Together, the dual catalysts emphasize how mega-cap pharmaceutical giants are deploying cash flow from legacy franchises to lock in next-generation immunology and oncology ***** ets.
In Q2 2026, AbbVie Inc. (NYSE:ABBV) posted $16.99 billion in net revenue, up 10.2% year over year, while adjusted diluted EPS increased 22.9% to $3.65. Growth was driven by its immunology blockbusters, Skyrizi and Rinvoq, which generated $5.505 billion and $2.525 billion in revenue, respectively, representing growth of 24.4% and 24.5%. These gains more than offset the continued decline in Humira revenue, which fell 35.9% to $756 million amid biosimilar competition. AbbVie reiterated its full-year 2026 adjusted EPS guidance of $13.87–$14.07, including a $0.14 dilutive impact from the Apogee transaction.
As a clinical-stage biotech, Apogee Therapeutics, Inc. (NASDAQ:APGE) generated no product revenue in Q2 2026, while R&D expenses reached $67.3 million and G&A expenses totaled $24.3 million, resulting in a quarterly net loss of $85.9 million. Despite the cash burn, the company maintained a strong liquidity position, with $1.3 billion in cash and marketable securities, alongside a $1.3 billion non-dilutive credit collaboration with Blackstone Life Sciences to support Phase 3 trials of its lead ***** et, zumilokibart.
Financially, AbbVie is vastly superior in immediate cash generation and profitability, whereas Apogee represented pure clinical optionality backed by robust liquidity.
For AbbVie, acquiring Apogee's optimized antibody portfolio, including zumilokibart for atopic dermatitis, strengthens its post-Humira immunology franchise. Combined with internal R&D advances such as etentamig, which achieved statistically significant overall response rate and progression-free survival results in the Phase 3 Cervino study, along with an 87.9% 12-month overall survival rate, AbbVie demonstrates potential to sustain strong organic growth.
#phase #revenue #Growth

18 days ago
Dell Technologies (DELL) shares have surged more than 316% so far in 2026, fueled by robust demand for AI infrastructure, increased enterprise investment in modernizing IT systems, and continued expansion of its customer base.
The company is also benefiting from strong demand for its AI-optimized servers, and the momentum is likely sustainable in the coming quarters. At the same time, rising AI demand is also driving demand for traditional servers and networking equipment, further strengthening Dell's long-term growth prospects.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ***** e
#tens


18 days ago
Dell Technologies Inc. (NYSE:DELL) reported fiscal second-quarter 2027 revenue of $47.0 billion, up 58% year over year. AI server orders reached $60.9 billion, while recognized AI server revenue totaled $16.4 billion and ending AI server backlog reached $95.0 billion.
Orders and backlog are company-reported operating metrics, not recognized revenue. Orders measure booked demand, while backlog represents orders awaiting conversion. The backlog provides substantial revenue visibility, although Dell Technologies Inc. (NYSE:DELL) did not disclose its conversion schedule.
Dell Technologies Inc. (NYSE:DELL) raised its fiscal 2027 revenue outlook by $25 billion to $192 billion and increased expected AI-optimized server revenue from $60 billion to $74 billion. However, cash flow from operating activities decreased 13% to $2.225 billion. First-half operating cash flow still increased 18% to $6.306 billion.
The company-defined non-GAAP cash measures require a closer look. Free cash flow was $986 million, calculated from $2.225 billion of operating cash flow less $1.239 billion of capital expenditures and capitalized software development costs, net of **** et-sale proceeds. Adjusted free cash flow was $8.149 billion after adding the $6.667 billion operating-cash-flow impact from changes in financing receivables and the $496 million net impact of capital expenditures and depreciation for equipment under operating leases. Dell Technologies Inc. (NYSE:DELL) excludes these Dell Financial Services items because their initial funding is largely replaced by cash inflows from related debt.
Infrastructure Solutions Group revenue increased 89% to $31.8 billion, while operating income rose 225% to $4.8 billion. The company-reported ISG operating income rate, calculated as segment operating income divided by segment revenue, improved to 15.0% from 8.8%. Scale, pricing discipline, and operating leverage are producing stronger segment economics.
#operating #technologies
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
20 days ago
Impax ******* et Management, based in London and specializing in sustainable investing, released its Q2 2026 investor letter for the "Impax US Sustainable Economy Fund". The letter can be downloaded here. The US Sustainable Economy portfolio outperformed the Russell 1000 in Q2 2026, with Institutional Class at 17.96%, Investor Class at 17.95%, and Class A at 17.92%, versus the index's 15.14%. Sector allocation and stock selection drove performance. The sustainability tools, including the Impax Sustainability Lens and Corporate Resilience framework, contributed positively. Equity markets rallied, with both the S&P 500 and Nasdaq reaching new highs before retreating. A key trend was rotation into AI and tech stocks, supported by mega-cap earnings and data center investments (US$750bn to US$1tn). In the second half of 2026, markets may remain volatile amid debates on AI adoption pace and economic momentum. However, growth tied to energy security and efficiency remains compelling, with demand for power, grid, and resource-efficient solutions supporting companies that benefit. The team focuses on businesses with strong growth, sound management, and attractive valuations, adjusting holdings as needed. This approach aims to build well-diversified, differentiated portfolios. Also, please check the fund's top five holdings for its best picks in 2026.
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD) as a key contributor. Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 04, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $477.57 per share, reflecting a market capitalization of $779.62 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 1.71%, but its shares are up 215.42% over the past year.
Impax US Sustainable Economy Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"Advanced Micro Devices, Inc. (NASDAQ:AMD) (Semiconductors, Information Technology) is held for its attractive sustainability opportunity set, particularly in Digital Infrastructure, and for its high Corporate Resilience score across environmental and governance dimensions. The stock rose substantially in the quarter, driven by strong adoption of its AI-optimized GPU (graphics processing unit) and data center processor products. A series of major partnership announcements with cloud computing providers and continued evidence of market share gains in AI accelerator hardware reinforced investor confidence in the company's multi-year earnings growth trajectory."
#NASDAQ #impax #sustainable #letter

21 days ago
Bloomberg reported that Elon Musk said ****** e Exploration Technologies Corp. (NASDAQ:SPCX) first AI satellites, powered exclusively by NVIDIA Corporation (NASDAQ:NVDA) chips, will launch in the fourth quarter of 2027 and reach "significant scale" in 2028, citing a post on X. Musk wrote "SpaceX, in partnership with Nvidia, has designed a ****** e-optimized Vera Rubin NVL72 system for launch to orbit in Q4 next year," describing the satellite data center as "significantly simpler, lower cost, denser, and lighter than a traditional rack."
The timeline has moved up twice since ****** eX's May IPO prospectus, which targeted "as early as 2028," and Musk's August 4 earnings call comments, which said launches would begin "next year." ****** eX COO Gwynne Shotwell told CNBC ahead of the IPO that the firm has already struck deals with Anthropic and Google to rent out orbital compute capacity.
The timeline is moving earlier, not later, which is unusual for a ****** e infrastructure project. ****** e Exploration Technologies Corp. (NASDAQ:SPCX) pulled its target forward from as early as 2028 in its IPO prospectus to a specific Q4 2027 date within a few months. The acceleration shows ****** eX believes development is progressing faster than previously expected and could bring orbital computing revenue online sooner than investors initially anticipated.
Real customers have already committed before ****** eX launches a single satellite. ****** eX President Gwynne Shotwell told CNBC that the company has struck deals with Anthropic and Google to rent orbital compute capacity. It shows that major AI companies already see potential value in the technology. Those early commitments could reduce demand risk if ****** eX delivers the planned capacity.
Wall Street sees a large long-term opportunity if the technology works as described. JPMorgan ****** yst Doug Anmuth projected ****** eX could pursue roughly 75 gigawatts of orbital compute by the end of 2031 at a significantly cheaper cost than could be done on Earth a scale that would make this a meaningful new revenue stream beyond ****** eX's existing launch and Starlink businesses.
#SpaceX #NASDAQ #already #compute
24 days ago
99% of auto-enrollment plans default workers into target-date funds that often carry higher fees and unnecessary bond exposure for 25-year-olds.
VTI, DGRO, and BND together deliver total-market growth, a dividend-quality tilt, and controllable bond stability at costs most 401(k) menus cannot match.
The three-fund portfolio requires annual rebalancing, which means investors who will never log in again are actually better served by the default fund.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
You were auto-enrolled in your 401(k) at 25, checked a box, and moved on. Five years later, you still own whatever target-date fund the plan defaulted you into, and you have never once opened the prospectus. You are not alone. By year-end 2025, 61% of Vanguard defined contribution plans had adopted automatic enrollment, and 99% of automatic enrollment plans used a target-date or other balanced investment strategy as the default fund, with 98% choosing a target-date fund. That default is fine, but it is not optimized. If you want to graduate from "whatever they picked" to a portfolio a grown-up would actually build, three ETFs do the job: Vanguard Total Stock Market ETF (NYSEARCA:VTI), iShares Core Dividend Growth ETF (NYSEARCA:DGRO), and Vanguard Total Bond Market ETF (NASDAQ:BND).
#vanguard #total #market #plans

24 days ago
Jim Cramer broke down Dell Technologies Inc.'s (NYSE:DELL) post-close earnings report on Mad Money's episode aired on September 1, as he declared it one of the best quarters he has ever witnessed. He stated:
You're getting a Dell, specifically, a blowout quarter from Dell Technologies. After the close, this iconic maker of tech hardware reported one of the best quarters I've ever seen thanks to the incredible strength of their AI server business. Dell's revenue grew 58% year-over-year, a 2 billion dollar beat. The company earned $7 and 4 cents per share. That's more than $2 above what Wall Street was looking for and more than triple what they made the year before. And the guidance was even better. They took their full-year earnings per share forecast from just under 18 bucks all the way up to $25.50. Stunning, definition of blowout.
The headline numbers show that the business is operating at extraordinary velocity. Dell Technologies Inc.'s (NYSE:DELL) total revenue reached a record $47 billion, marking a 58% increase year-over-year and beating estimates by more than $2 billion. Non-GAAP diluted earnings per share landed at $7.04, crushing expectations by $2.1. Management backed up the beat by raising full-year revenue guidance to $192 billion and lifted non-GAAP earnings expectations to $25.50 per share.
The main catalyst was the Infrastructure Solutions Group, where revenue surged 89% to $31.8 billion. Dell Technologies Inc. (NYSE:DELL) also booked $60.9 billion in AI-optimized server orders during the quarter, closing the period sitting on a staggering $95 billion AI backlog, proving that enterprise data centers are experiencing a broad modernization cycle. The company's COO and vice chairman, Jeff Clarke commented:
We're seeing broader revenue growth as well, with traditional servers and networking up 122%, storage up 26% and our client solutions up 20% year over year. Our second quarter results underscore the compounding benefits of our competitive advantages, the breadth of our portfolio and the strength of our operating model.
#year #billion #technologies #NYSE

24 days ago
NextEra Energy says an artificial intelligence (AI)–driven dispatch and outage-scheduling tool has saved its customers more than $20 million so far this year. Santee Cooper expects a custom AI weather-forecasting model to help it avoid spot-market purchases that can cost $100,000 an hour during extreme weather. Both utilities say the tools moved from concept to production in a matter of weeks, not years.The two companies detailed their AI deployments during a Sept. 2 virtual media roundtable hosted by Google Cloud, alongside Raiford Smith, the company's global director of power and energy industry. The session focused on Gemini Enterprise, Google Cloud's platform for building and deploying AI agents, and framed both utilities as evidence that AI in the sector has moved beyond generic chatbots and into tools built for specific, high-stakes operational decisions."Utilities are being asked to deliver greater reliability, lower costs, and a grid ready for what comes next," said Rich Argentieri, president of NextEra ***** ytics. Tami Wilson, vice president and chief financial officer of Santee Cooper, described the shift in similar terms, saying her utility is moving away from "legacy, clunky, ***** bersome processes" toward AI-driven financial and load forecasting to save time and money.
Argentieri walked through NextEra's Grid Composer platform, which the company built on the Gemini Enterprise Agent Platform and rolled out across Florida Power and Light's (FPL's) generating fleet. The platform pulls together real-time telemetry, load data, and generation profiles—what Argentieri estimated at roughly half a trillion data points a day—into a single model that compares manual dispatch decisions against an AI-optimized alternative.NextEra built the first version of the tool in less than 12 weeks, according to Argentieri. Since then, he said, the optimized dispatch and outage scheduling it enables have produced "over $20 million of savings to our customers" so far this year. NextEra has since made the underlying tools available to other utilities through a Google Cloud marketplace product it calls Optos, with Optos Composer—the version built for market and ***** et optimization—unifying generation, fuel, maintenance, trading, reserves, and storage decisions that Argentieri said have traditionally been managed by separate, siloed teams."All of those teams very much traditionally siloed. And not only the people, but all the data and the processes that go into that," Argentieri said, describing generation, transmission, and trading functions that rarely shared data before. Bringing those functions onto a single platform, he said, has let the company avoid "suboptimal decisions" and given teams visibility into how choices in one area affect costs elsewhere in the system.Argentieri also pointed to field applications. FPL technicians—he estimated 85% to 90% of the company's workforce—now use voice-activated tools to pull torque specifications or work-order gu
Argentieri walked through NextEra's Grid Composer platform, which the company built on the Gemini Enterprise Agent Platform and rolled out across Florida Power and Light's (FPL's) generating fleet. The platform pulls together real-time telemetry, load data, and generation profiles—what Argentieri estimated at roughly half a trillion data points a day—into a single model that compares manual dispatch decisions against an AI-optimized alternative.NextEra built the first version of the tool in less than 12 weeks, according to Argentieri. Since then, he said, the optimized dispatch and outage scheduling it enables have produced "over $20 million of savings to our customers" so far this year. NextEra has since made the underlying tools available to other utilities through a Google Cloud marketplace product it calls Optos, with Optos Composer—the version built for market and ***** et optimization—unifying generation, fuel, maintenance, trading, reserves, and storage decisions that Argentieri said have traditionally been managed by separate, siloed teams."All of those teams very much traditionally siloed. And not only the people, but all the data and the processes that go into that," Argentieri said, describing generation, transmission, and trading functions that rarely shared data before. Bringing those functions onto a single platform, he said, has let the company avoid "suboptimal decisions" and given teams visibility into how choices in one area affect costs elsewhere in the system.Argentieri also pointed to field applications. FPL technicians—he estimated 85% to 90% of the company's workforce—now use voice-activated tools to pull torque specifications or work-order gu

25 days ago
The Dow Jones Industrial Average (DJINDICES:^DJI) gained 0.56% to 53,062, the S&P 500 (SNPINDEX:^GSPC) rose 0.47% to 7,667, and the Nasdaq Composite (NASDAQINDEX:^IXIC) added 0.45% to 26,218, as the major indexes snapped multi-day losing streaks despite persistent geopolitical tensions.
Dell Technologies (NYSE:DELL) shares surged after the hardware giant lifted its annual revenue forecast, while Nvidia (NASDAQ:NVDA) helped lead the technology recovery.
Investors also monitored Snowflake (NYSE:SNOW) and Broadcom (NASDAQ:AVGO) as the technology firms prepared to report quarterly results after hours, following a significant year-to-date rally.
Perhaps the biggest news item today in the stock market came from Dell Technologies, which rose 16% after reporting blowout earnings. Sales and adjusted EPS rose 58% and 203% in the quarter, while its AI-Optimized Server business doubled its revenue. Most importantly, the AI unit recorded $61 billion in orders, bringing its backlog to over $95 billion and underscoring the company's growing importance in the AI **** e.
On the other hand, cybersecurity juggernaut Palo Alto Networks (NASDAQ:PANW) dropped 9% today after reporting fine (but not perfect) earnings. This decline is likely nothing for interested or current shareholders to worry about, as PANW stock was trading close to perfection after more than doubling over the last six months.
#PANW #Stock
25 days ago
Dell Technologies (NYSE:DELL), a PCs, servers, storage, and enterprise AI infrastructure provider, closed at $492.00, up 15.76%. The company's stronger-than-expected quarter and raised outlook, backed by record AI server orders, drove the move, and investors are now watching AI server demand and margin trends. Trading volume reached 35.0M shares, coming in about 353% above its three-month average of 7.7M shares. Dell Technologies IPO'd in 2016 and has grown 3,976% since going public.
S&P 500 (SNPINDEX:^GSPC) rose 0.47% to 7,667, while the Nasdaq Composite (NASDAQINDEX:^IXIC) gained 0.45% to 26,218. In computer hardware and IT infrastructure, sector rivals HP (NYSE:HPQ) closed at $32.00, up 2.16%, and Hewlett Packard Enterprise (NYSE:HPE) finished at $51.85, up 1.94%, as investors tracked Dell Technologies' AI order momentum and the broader PC margin backdrop.
Dell Technologies' Q2 earnings were a perfect encapsulation of how far the company has come since its "dude, you're getting a Dell" days. Revenue and adjusted EPS spiked 58% and 203% during the quarter, rocketing past Wall Street's expectations. The core driver of Dell's success in Q2 came from its AI-Optimized Server revenue of $16.4 billion, which doubled from last year.
As promising as this revenue growth alone is in its AI unit, its record $60.9 billion of orders and exiting backlog of $95 billion highlight that the best is yet to come and that Q2's excellent results may just be the tip of the iceberg. Powered by the visibility of this backlog, management raised its full-year guidance to 69% sales growth and a 148% rise in adjusted EPS, to $25.50. This leaves DELL stock trading at 19 times forward earnings, which isn't particularly outrageous given the company's AI potential and its steady servers, networking, and PC businesses.
Before you buy stock in Dell Technologies, consider this:
#enterprise #infrastructure

25 days ago
Dell Technologies Inc. (NYSE:DELL) reported stellar fiscal second-quarter earnings, beating Wall Street expectations backed by record demand for artificial intelligence servers. Tripling AI server demand, a 70% revenue growth outlook, and booming traditional server sales should have invited bullish calls from Wall Street, yet one firm chose to stick with a Hold rating.
On September 2, TD Cowen ******* yst Krish Sankar raised the price target on Dell (NYSE: DELL) to $500.00 (from $450.00) while maintaining a Hold rating. TD Cowen chooses to stay on the sidelines despite calling Dell's results "phenomenal" as the firm remains cautious about how much investors should pay for that growth.
For the fiscal second quarter, revenue for Dell surged 58% year-over-year to a record $46.97 billion, beating expectations of $44.92 billion. Adjusted earnings per share of $7.04 topped the expected $4.92 figure.
Soaring demand for its AI servers helped the company boost its annual revenue forecast by $25 billion and also raise its profit outlook for the second time this year. FY27 revenue outlook was raised to $192 billion from $167 billion, an estimated 69% year-over-year growth.
AI servers did most of the heavy lifting for Dell's growth. The company reported $16.4 billion in AI-optimized server revenue, with AI server outlook now sitting at $74 billion for the year, up 200% year over year.
#servers


28 days ago
With a market cap of $760 billion, Advanced Micro Devices, Inc. (AMD) is a high-performance and AI computing company focused on driving innovation across cloud, AI infrastructure, embedded systems, AI PCs and gaming. Its broad portfolio includes AI-optimized CPUs, GPUs, networking and software designed to deliver powerful, scalable computing solutions.
Companies valued at $200 billion or more are generally classified as "mega-cap" stocks, and Advanced Micro Devices fits this criterion perfectly. AMD's full-stack AI technologies are helping enable the next generation of intelligent computing and support billions of experiences worldwide.
Jeff Bezos' Heartfelt Tribute to Dolly Parton Drew Brutal Backlash: 'Nobody Wanted to Hear This From You' — He Once Gave Her $100 Million for Charity
Intel vs. AMD: Why the Market Share Number Is Misleading
A $100 Billion Buildout In Louisiana Is Planned for Starship. What This Means for SPCX Stock.
#market #cpus


1 month ago
Download the Complete Report Here
Scaled ***** et-light appliance platform extending into commercial and health markets. HBB designs, markets and distributes branded household appliances, specialty housewares, commercial foodservice equipment and connected medication-management solutions, generating $606.9 million of revenue and shipping more than 25 million appliances in 2025. The company outsources substantially all manufacturing while retaining product development, engineering, quality ***** urance, marketing and distribution, keeping capex near 1% of revenue. This model combines a scaled consumer foundation with growing Commercial and Health platforms, while preserving capital for brand investment, innovation and adjacent growth opportunities.
A defensible business model built on reinforcing brand strength, category breadth, retailer access and repeatable innovation. Hamilton Beach, Proctor Silex and Weston provide broad mass-market reach, while Lotus and licensed CHI products extend into premium applications. HBB participates in more than 50 categories, ranked second among U.S. national small-kitchen-appliance brands by 2025 unit sales and draws on 300,000+ annual consumer touchpoints to support product development. Established retail relationships and an ***** et-light sourcing network reinforce the platform, making its competitive position broader than any single brand, product or patent.
Five growth pillars broaden mix across premium, commercial, digital and health markets. Recent initiatives include wider Lotus distribution, new core-product placements, Sunkist commercial products, foodservice-chain trials, AI-optimized content across 500 SKUs and expanding specialty-pharmacy partnerships; Health remained on track to grow 2026 sales 50%. Execution now hinges on converting these initiatives and incremental advertising into sustained revenue growth, better mix and profitable sell-through.
A large addressable market provides multiple growth pockets aligned with HBB's positioning. U.S. small-appliance sales grew 1.0% in 2025, while kitchen electrics increased 4.1% and replacement accounted for 52% of 4Q25 purchases. HBB's strong unit position and accessible price points support replacement demand, while its lower dollar share and roughly 1% position in an estimated $4.2 billion premium TAM leave meaningful premiumization headroom. Commercial automation, home-administered therapies and AI-mediated discovery add further growth avenues.
#Growth #Health #appliance



1 month ago
SpaceX's first orbital data center is now due to launch in the fourth quarter of 2027 — about a year earlier than the company told investors when it went public.
The company had earlier noted plans to start deploying satellites "as early as 2028" in its initial May Prospectus. Then on the company's first earnings call on Aug. 4, Musk said launches would start next year. And on Aug. 24 he put a quarter on it: "SpaceX, in partnership with Nvidia, has designed a ******* e-optimized Vera Rubin NVL72 system for launch to orbit in Q4 next year, with significant scale in 2028," he wrote on X.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#next
1 month ago
The World Cup reignited a familiar debate about American youth sports. At the same time, lawmakers from both parties have introduced legislation aimed at curbing predatory private equity practices, reflecting growing concern over rising costs and shrinking access. Those conversations are connected, and they point to a bigger question: What should youth sports actually be optimized for?
As former NFL players, fathers, and people who have spent our lives around youth athletics, we believe the answer is simple: participation.
We understand why this moment has prompted scrutiny. Youth sports have become more expensive. More complicated. Too often, families feel like they're being asked to spend thousands of dollars before a child has even decided whether they love the game.
Those concerns affect far more than the next generation of athletes and deserve addressing head-on.
But as the national conversation continues, we also believe it's important to distinguish between the practices that deserve criticism and the investments that are helping remove barriers for families. The question isn't simply who is investing in youth sports. It's whether those investments are making it easier or harder for kids to play.
#Youth #deserve

1 month ago
Madison Investments, an investment advisor, released its second-quarter 2026 investor letter for the "Madison Large Cap Fund". A copy of the letter can be downloaded here. In the second quarter, U.S. stock market indices achieved their best performance since 2020, driven largely by a narrow group of Artificial Intelligence-related stocks. As in the pandemic's early days, investors are fixated on who will benefit from AI, reminiscent of the late 1990s internet bubble. Against this backdrop, The Madison Large Cap Fund (class I) returned 8.4% in the second quarter of 2026, compared to a 15.2% increase in the S&P 500 Index. The current market's extreme narrowness is concerning, and history suggests this won't persist. While AI is reshaping society and the economy, today's winners may not remain so, and booms could lead to busts. Additionally, factors such as a volatile federal administration, growing budget deficits, inflation, high interest rates, and strained consumer finances will significantly impact the economy and stock market in the future. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Madison Large Cap Fund highlighted Honeywell Aerospace Inc. (NASDAQ:HONA) as a new holding. Honeywell Aerospace Inc. (NASDAQ:HONA), spun off from Honeywell International in June 2026, manufactures and supplies aircraft components, avionics, engines, and systems. On August 21, 2026, Honeywell Aerospace Inc. (NASDAQ:HONA) closed at $164.73 per share, reflecting a market capitalization of $52.21 billion. Honeywell Aerospace Inc. (NASDAQ:HONA) posted a one‑month return of ‑21.87%.
Madison Large Cap Fund stated the following regarding Honeywell Aerospace Inc. (NASDAQ:HONA) in its Q2 2026 investor letter:
"Honeywell Aerospace Inc. (NASDAQ:HONA) is a leading aerospace and defense supplier, supporting OEM, government, and aircraft operator customers. The company's products sit on a wide variety of aerospace programs with approximately 90% of in-service aircraft today having Honeywell Aerospace content. The separation from Honeywell International should enhance an already high-quality business as management compensation and capital allocation will be better tailored to the specific needs of the business. We believe the combination of attractive growth outlook, improved incentives, and optimized capital allocation is underappreciated."
Honeywell Aerospace Inc. (NASDAQ:HONA) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. While we acknowledge the potential of Honeywell Aerospace Inc. (NASDAQ:HONA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#large #letter #stocks


1 month ago
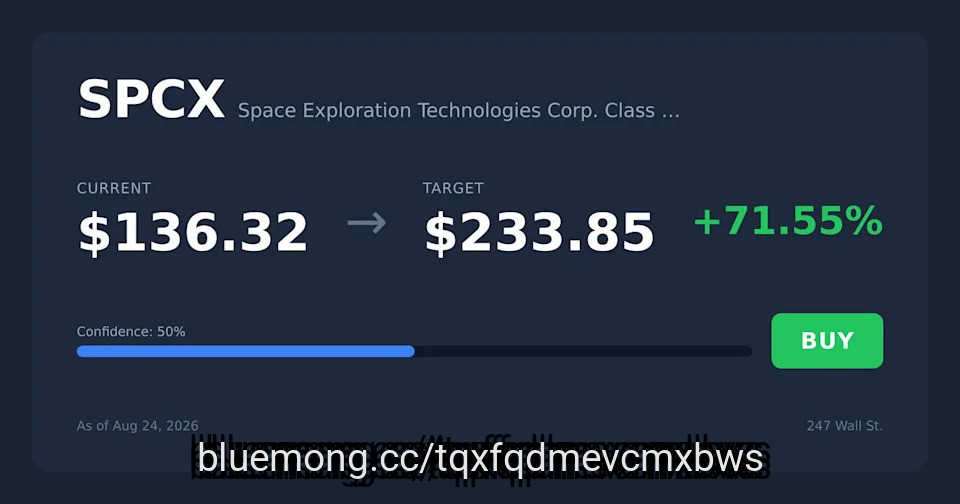
Musk accelerated **** eX's (SPCX) orbital data center launch to Q4 2027, and JPMorgan held its $240 price target, implying roughly 75% upside from current levels.
NVIDIA (NVDA) reports Wednesday, and **** e peers like RKLB sitting out the rally confirm **** eX's surge is a targeted AI-compute repricing, not a sector rotation.
Don't wait: the **** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
SpaceX (NASDAQ:SPCX) stock is up 3% to $139.06 midday Tuesday, breaking from a lukewarm **** e complex that hasn't followed the move. The Procure **** e ETF (NASDAQ:UFO) is up 0.1% to $44.71, well behind the single-name headline **** eX is driving in the sector. Meanwhile, the Invesco QQQ Trust (NASDAQ:QQQ) is up 0.64% to $710.82, a broad-tape backdrop that hardly explains the outsized single-name pop.
The catalyst is twofold. **** eX Founder Elon Musk posted on X Monday afternoon that his company has designed a **** e-optimized Vera Rubin NVL72 system for launch to orbit in Q4 next year, pulling its first orbital data center milestone forward from a previously stated 2028 target. JPMorgan **** yst Doug Anmuth followed Tuesday with a maintained Overweight rating and a $240 price target on **** eX stock, implying substantial upside from current levels.
#NASDAQ #target #NVIDIA #tuesday

1 month ago
Right now, there are two companies dominating the artificial intelligence (AI) memory discussion: Micron Technology (NASDAQ: MU) and Sandisk (NASDAQ: SNDK). ***** ysis of which of these memory specialists deserves a place in your portfolio often centers on the same talking points: soaring demand for high-bandwidth memory (HBM) and flash storage.
What receives far less attention, however, is the architecture of each company's long-term positioning. Examining the lesser-discussed strengths and vulnerabilities of Micron and Sandisk suggests that the smarter choice is not to pick a single winner.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron's competitive advantage stems from the company's history of treating memory as a connected system rather than a commodity. While competitors continue chasing density milestones, Micron spent decades refining its DRAM and NAND portfolios so that the two can be co-optimized. This strategy is paying off as AI workloads increasingly demand both ultra-low latency and massive sequential throughput.
While this cross-pollination is not featured in headlines, smart investors understand that this approach allows Micron to prototype hybrid memory solutions faster than pure-play rivals such as Samsung or SK Hynix. As a result, Micron can respond swiftly to shifts in AI model architecture without waiting for its external partners to catch up.
#flashing #demand
1 month ago
This story was originally published on QSR. To receive daily news and insights, subscribe to our free daily QSR AM Jolt.
In today's challenging restaurant environment, operators are under constant pressure to grow sales while managing rising food, labor, occupancy, and operating costs. While much attention is placed on pricing, promotions, labor optimization, and food costs, one of the most powerful tools for improving restaurant economics is often overlooked: the menuboard.
The menuboard is one of the most important points of communication between a restaurant and its customers. It does more than tell customers what is available and what it costs. A well-designed and strategically optimized menuboard can greatly influence product selection, increase average check, improve throughput, reduce decision friction, and make the operation easier to execute. When these benefits are considered together, the return on investment from menuboard optimization can be substantial.
A menuboard should be viewed as a "silent" salesperson that serves every customer, every day. Unlike a traditional advertising investment, the menuboard goes to work at the precise moment a customer is making a purchase decision.
Its job is to answer three fundamental customer questions quickly: What can I order? What looks appealing? What represents the best value for me?
#menuboard #costs #customer #optimization
1 month ago
Madison Investments, an investment advisor, released its second-quarter 2026 investor letter for the "Madison Large Cap Fund". A copy of the letter can be downloaded here. In the second quarter, U.S. stock market indices achieved their best performance since 2020, driven largely by a narrow group of Artificial Intelligence-related stocks. As in the pandemic's early days, investors are fixated on who will benefit from AI, reminiscent of the late 1990s internet bubble. Against this backdrop, The Madison Large Cap Fund (class I) returned 8.4% in the second quarter of 2026, compared to a 15.2% increase in the S&P 500 Index. The current market's extreme narrowness is concerning, and history suggests this won't persist. While AI is reshaping society and the economy, today's winners may not remain so, and booms could lead to busts. Additionally, factors such as a volatile federal administration, growing budget deficits, inflation, high interest rates, and strained consumer finances will significantly impact the economy and stock market in the future. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Madison Large Cap Fund highlighted Honeywell Aerospace Inc. (NASDAQ:HONA) as a new holding. Honeywell Aerospace Inc. (NASDAQ:HONA), spun off from Honeywell International in June 2026, manufactures and supplies aircraft components, avionics, engines, and systems. On August 21, 2026, Honeywell Aerospace Inc. (NASDAQ:HONA) closed at $164.73 per share, reflecting a market capitalization of $52.21 billion. Honeywell Aerospace Inc. (NASDAQ:HONA) posted a one‑month return of ‑21.87%.
Madison Large Cap Fund stated the following regarding Honeywell Aerospace Inc. (NASDAQ:HONA) in its Q2 2026 investor letter:
"Honeywell Aerospace Inc. (NASDAQ:HONA) is a leading aerospace and defense supplier, supporting OEM, government, and aircraft operator customers. The company's products sit on a wide variety of aerospace programs with approximately 90% of in-service aircraft today having Honeywell Aerospace content. The separation from Honeywell International should enhance an already high-quality business as management compensation and capital allocation will be better tailored to the specific needs of the business. We believe the combination of attractive growth outlook, improved incentives, and optimized capital allocation is underappreciated."
Honeywell Aerospace Inc. (NASDAQ:HONA) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. While we acknowledge the potential of Honeywell Aerospace Inc. (NASDAQ:HONA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#honeywell #fund

2 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Successfully transitioned to a pure-play precision manufacturing business by exiting the wind tower market to focus on high-margin domestic power generation and critical infrastructure.
Positioned to capitalize on a multiyear investment cycle in the electrical grid driven by AI data center load growth, domestic manufacturing reshoring, and general electrification.
Achieved record orders and backlog in Industrial Solutions, supported by robust demand for natural gas turbine components in both new build and aftermarket applications.
Optimized the ******* et base through floor ******* e reconfiguration in Gearing and a 30% facility expansion in North Carolina to enhance throughput velocity and operational efficiency.
#Manufacturing #optimized

2 months ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributes the decision to skew toward organic production growth to a macro view that global oil and product inventories, including Strategic Petroleum Reserves, must be refilled.
Performance outperformance is driven by a 'stacked innovation' framework, combining faster well construction, optimized targeting, and aggressive stimulation techniques to maximize NPV per acre.
The company has successfully transitioned from drilling wells in 30 days to just 5 days, reflecting a continuous improvement culture that offsets inflationary pressures.
Operational efficiency gains, specifically reaching over 21 hours of average pumping time per day, are being utilized to maintain a capital-efficient run rate of approximately $1 billion per quarter.
#management

2 months ago
SummaryView Transcript
The logistics industry has a dirty little secret: trailers sit idle for 30-40% of their lifespan, costing carriers and shippers millions. Chris Hines, CEO of REPOWR, reveals how their new Trailer Optimization Platform (TOP) is transforming this inefficiency into opportunity. Discover how advanced data feeds and an execution layer can automate repositioning, boost utilization, and reduce operational costs. Learn why optimizing your "dumb boxes" is the next frontier in supply chain efficiency.
Trailers sit empty 30% to 40% of their working lives — and sometimes more — while every other link in the freight chain has been optimized. That is the core problem Repower is targeting with its new Trailer Optimization Platform, known as TOP, which automates the repositioning of trailer **** ets from surplus markets to deficit ones. CEO Chris Hines, a 44-year industry veteran, joined the Chattanooga-based startup to push it beyond its origins as a trailer marketplace and into an execution layer that carriers have long lacked.
The stakes are significant. A dry van trailer that cost $10,000 at the dawn of drop-and-hook operations now runs $50,000 depending on tariff conditions, Hines noted. Large carriers routinely run trailer-to-truck ratios of 2.5 to 3 to 1, meaning a fleet of 1,000 trucks could be managing 2,500 or more trailers — often tracked across a patchwork of TMS records, spreadsheets, and whiteboards. "Everything else is optimized in our chain," Hines said. "The gates are optimized, the dock's optimized, the truck's optimized, loads, fuel, but the trailers just lag behind."
"Visibility of the **** et is not enough. You need the execution layer and the automation to move the **** et to its next location." — Chris Hines, CEO, Repower
#optimized #chris #carriers #execution


2 months ago
Alphabet reported earnings on July 22 and the stock dropped more than 7% in a single session. The numbers weren't bad. Cloud grew 82% year over year. Advertising held up. EPS beat. What rattled investors was the spending. Capital expenditure guidance for 2026 came in at $195 billion to $205 billion. Free cash flow went negative for the first time in the company's history. The market looked at that bill and sold first, asked questions later.
Five days later, Phillip Securities ****** yst Serena Lim Yi Qi published a note saying the market got it wrong. On July 27, she upgraded Alphabet to Buy from Accumulate, lowered her price target to $425 from $450, and explained why the combination of those two moves makes sense.
The upgrade from Accumulate to Buy is the meaningful part of the call. Phillip Securities is saying Alphabet's AI momentum has reached the point where sitting on the sidelines no longer makes sense, according to Investing.com.
Lim Yi Qi pointed to Alphabet's vertically integrated AI ecosystem as the core of the bull case. The company controls its own custom silicon through its Tensor Processing Units, runs optimized data centers, and deploys its Gemini models across Search, Cloud, and its broader product suite. That integration, in her view, gives Alphabet a structural advantage that is starting to show up in the numbers in a meaningful way.
The free cash flow picture is more complicated. Alphabet turned negative on free cash flow for the first time this quarter because of the scale of its AI investment. Lim Yi Qi views that as a temporary condition supporting stronger long-term growth rather than a structural problem. The company has also raised its 2026 capex guidance to a range of $195 billion to $205 billion, signaling the buildout is far from over.
#free #flow #first #cloud
2 months ago
This may come as a surprise, but one of the world's biggest winners of the artificial intelligence (AI) revolution isn't actually a technology firm — it's Walmart (WMT), the big-box discount retailer.
Thanks to its early and aggressive bets on AI beginning in the late 2010s, Walmart has transformed its operations, optimized its supply chain, and cut delivery times to as little as 30 minutes while boosting employee productivity.
AI has also helped fuel double-digit share price gains, pushing Walmart's valuation above $1 trillion — the first retailer ever to reach that milestone. In fact, on January 9, 2026, Walmart joined the tech-heavy Nasdaq-100 index as a reflection of its digital transformation, triggering an estimated $19 billion in passive capital inflows and sending shares to new highs.
But these advancements are coming at a human cost. In May 2026, Walmart announced that, as part of a plan to streamline its global operations, it would lay off or relocate about 1,000 corporate workers.
While a company spokesperson told The Wall Street Journal that these changes were "related to organizational structure and alignment, not handing over more tasks to artificial intelligence," Walmart's employees say that the company's AI-fueled initiatives have resulted in a race to meet "impossible deadlines," raising concerns over workplace safety and product quality.
#artificial #wall
2 months ago
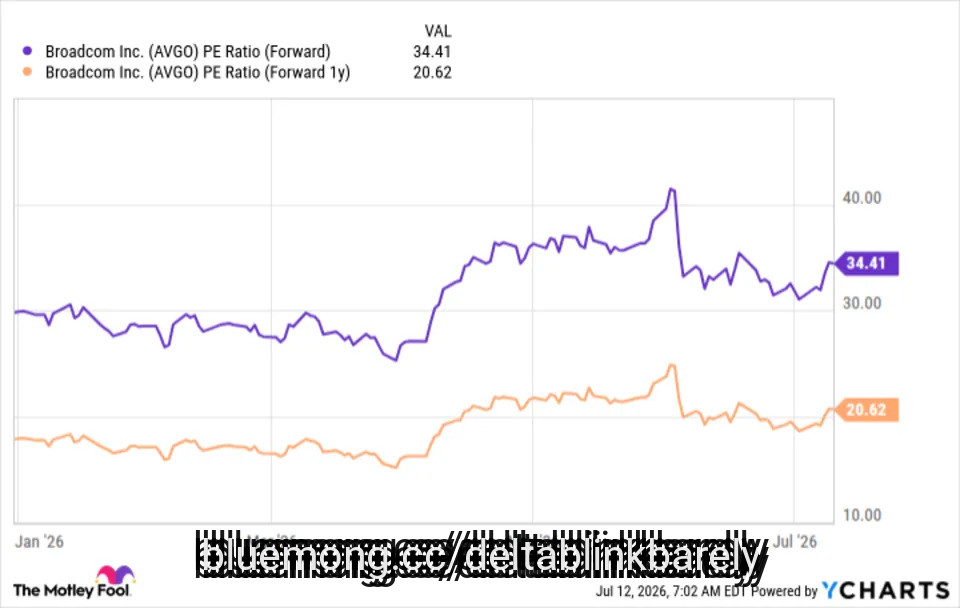
Broadcom (NASDAQ: AVGO) has been a solid stock pick in 2026, rising around 15% so far this year. However, it's down nearly 20% from its all-time high because of a poorly received earnings report. When you dig into why Broadcom's stock fell following that announcement, the reason looks quite silly as bears overreacted to modest guidance. Investors should be looking at this latest sell-off as a golden buying opportunity for a company whose business will explode for the remainder of 2026 and into 2027.
I think this is the most critical reason to buy the stock, as the Broadcom of today is going to look far different from the one at the end of 2027.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Broadcom does a lot as a company, but a highlight now is its custom AI chips. GPU-based computing is highly effective, but it's expensive. GPUs aren't optimized to run a certain workload because they're meant to be able to handle all types of workloads. This unspecialized nature is great for some applications, and poor for others. In AI, several workloads can be streamlined into one type where a specialized computing chip, like the one Broadcom designs, can deliver superior cost performance versus GPU-based training.
Broadcom's customer list is growing, and it now has four major clients, along with some other smaller ones. Highlighting the list are Alphabet (NASDAQ: GOOG) (NASDAQ: GOOGL), Meta Platforms (NASDAQ: META), Anthropic, and OpenAI. Alphabet, which owns Google, is already a leader in this area, as its Tensor Processing Units (TPUs) are quite popular. The other three's custom AI chips will enter production throughout the remainder of 2026 and into 2027, which is why Broadcom has advertised massive growth.