

5 days ago
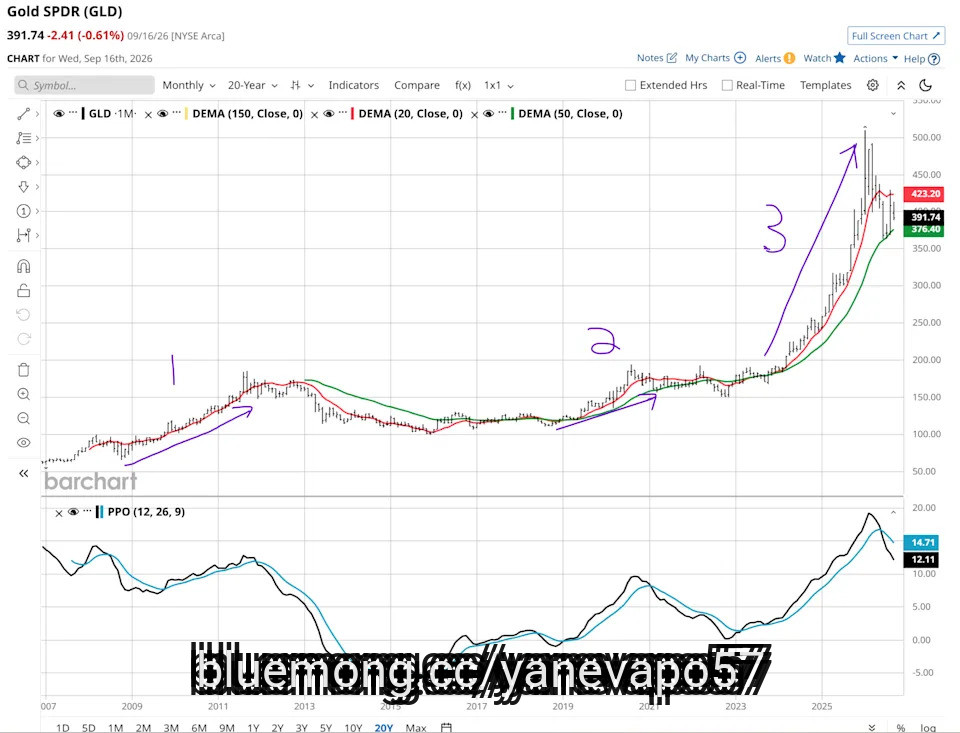
Is there any investment market segment more debated than gold (XAUUSD)? I'm not sure there is. We have "gold bugs," including those who see the yellow metal as the ***** et to own when the world goes haywire.
Then, there are the "we're going back on the gold standard" types. The ones that preceded crypto bros in believing fiat currencies weren't for this world. It follows that gold would return to its former role as the reserve currency.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ***** ysis you won't find anywhere else.
Of course, there are also plenty of investors who don't really think about gold investing very much, and who will simply trade it when there's a good opportunity. I'm in this camp.
Financial media pundits routinely tout gold as some sort of bulletproof allocation. Inflation worries? Own gold. Currency debasement? Own gold. Want your kitchen to be decorated like the Oval Office? You'll need a lot of gold.
#Gold #free #barchart #brief
Then, there are the "we're going back on the gold standard" types. The ones that preceded crypto bros in believing fiat currencies weren't for this world. It follows that gold would return to its former role as the reserve currency.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ***** ysis you won't find anywhere else.
Of course, there are also plenty of investors who don't really think about gold investing very much, and who will simply trade it when there's a good opportunity. I'm in this camp.
Financial media pundits routinely tout gold as some sort of bulletproof allocation. Inflation worries? Own gold. Currency debasement? Own gold. Want your kitchen to be decorated like the Oval Office? You'll need a lot of gold.
#Gold #free #barchart #brief

5 days ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer

5 days ago
On September 9, 2026, Reuters reported that Stellantis N.V. (NYSE:STLA) is recalling 201,976 Jeep vehicles in the U.S., including certain Grand Cherokee, Wagoneer and Grand Wagoneer models. It happened after the National Highway Traffic Safety Administration found a software error that can prevent the tire-pressure monitoring system from detecting low tire pressure or alerting the driver, raising crash risk.
Dealers will update the affected radio-frequency hub software free of charge. The recall is the latest in a year that has already included a 1.5-million-vehicle Ram seat-belt recall, a 955,000-vehicle camera-glitch recall in August, and more than 1 million Wranglers and Gladiators recalled in June for fire risk.
The recall should carry a relatively limited direct financial burden because Stellantis N.V. (NYSE:STLA) can fix the defect with a software update. The recall covers 201,976 Jeep vehicles, but Stellantis does not need to replace a physical component. A software-based remedy should reduce parts and labor costs and allow dealers to complete the repair relatively quickly, limiting the recall's immediate impact on earnings and cash flow.
Stellantis has already begun rebuilding its financial performance, giving investors a stronger foundation to absorb another recall. Second-quarter net profit reached €293 million compared with a €1.87 billion loss a year earlier. Revenue surged 13% to €43.5 billion. The business also generated €1 billion in industrial free cash flow during the quarter, showing real improvement as CEO Antonio Filosa executes his turnaround plan.
Strong North American demand shows the recall has not yet undermined demand for Stellantis' key Jeep and Ram products. Second-quarter North American shipments increased 38% to 445,000 vehicles. It was backed up by refreshed models, including the Jeep Grand Wagoneer and Grand Cherokee and the Ram 1500. So the company enters this recall with improving volumes and strong demand for several of the brands that matter most to its North American turnaround.
#software
Dealers will update the affected radio-frequency hub software free of charge. The recall is the latest in a year that has already included a 1.5-million-vehicle Ram seat-belt recall, a 955,000-vehicle camera-glitch recall in August, and more than 1 million Wranglers and Gladiators recalled in June for fire risk.
The recall should carry a relatively limited direct financial burden because Stellantis N.V. (NYSE:STLA) can fix the defect with a software update. The recall covers 201,976 Jeep vehicles, but Stellantis does not need to replace a physical component. A software-based remedy should reduce parts and labor costs and allow dealers to complete the repair relatively quickly, limiting the recall's immediate impact on earnings and cash flow.
Stellantis has already begun rebuilding its financial performance, giving investors a stronger foundation to absorb another recall. Second-quarter net profit reached €293 million compared with a €1.87 billion loss a year earlier. Revenue surged 13% to €43.5 billion. The business also generated €1 billion in industrial free cash flow during the quarter, showing real improvement as CEO Antonio Filosa executes his turnaround plan.
Strong North American demand shows the recall has not yet undermined demand for Stellantis' key Jeep and Ram products. Second-quarter North American shipments increased 38% to 445,000 vehicles. It was backed up by refreshed models, including the Jeep Grand Wagoneer and Grand Cherokee and the Ram 1500. So the company enters this recall with improving volumes and strong demand for several of the brands that matter most to its North American turnaround.
#software

5 days ago
On September 3, 2026, lululemon athletica inc. (NASDAQ:LULU) reported second-quarter fiscal 2026 results for the period ended August 2, 2026. Net revenue fell 4% to $2.4 billion, missing the $2.46 billion ****** ysts expected, and comparable sales dropped 10% on a constant dollar basis. Management cut full-year revenue guidance to a decline of 5% to 7%, down from a prior forecast of flat to down 1%, and lowered full-year earnings per share guidance to $9.48 to $9.73 from its prior forecast of $10.95 to $11.15, compared with $13.26 earned in fiscal 2025. Shares fell about 18% in extended trading. Incoming CEO Heidi O'Neill was set to start the following week.
Photo by Ian Deng Quddu on Unsplash
Citi's cut to $117 from $130 came with a Neutral rating and the observation that the stock's risk-reward is "slightly more favorable" after the selloff, even though the firm called fiscal 2027 visibility "very unclear." The operational bright spots are real.
lululemon athletica inc. (NASDAQ:LULU) increased its chase volume, the supply chain capability that lets it reorder fast-moving styles quickly, by about 20% this year, and away-from-body styles including the Groove Wide-Leg, Align Foldover Jogger, Breezily, and an updated Dance Studio Pant are trending well as shoppers shift from tight-fitting leggings. The brand's community pull held up too.
The SeaWheeze Half Marathon and Festival returned in August for the first time since 2019, drawing nearly 10,000 runners from 24 countries and roughly 14,000 festival attendees, while more than 85,000 people from 120 countries joined the companion Strava challenge, strong enough that Lululemon already committed to bringing the event back next summer. Rest of World revenue, spanning EMEA and APAC, grew 5% on a reported basis, and the company ended the quarter with $1.4 billion in cash and no outstanding borrowings.
#revenue #billion #NASDAQ
Photo by Ian Deng Quddu on Unsplash
Citi's cut to $117 from $130 came with a Neutral rating and the observation that the stock's risk-reward is "slightly more favorable" after the selloff, even though the firm called fiscal 2027 visibility "very unclear." The operational bright spots are real.
lululemon athletica inc. (NASDAQ:LULU) increased its chase volume, the supply chain capability that lets it reorder fast-moving styles quickly, by about 20% this year, and away-from-body styles including the Groove Wide-Leg, Align Foldover Jogger, Breezily, and an updated Dance Studio Pant are trending well as shoppers shift from tight-fitting leggings. The brand's community pull held up too.
The SeaWheeze Half Marathon and Festival returned in August for the first time since 2019, drawing nearly 10,000 runners from 24 countries and roughly 14,000 festival attendees, while more than 85,000 people from 120 countries joined the companion Strava challenge, strong enough that Lululemon already committed to bringing the event back next summer. Rest of World revenue, spanning EMEA and APAC, grew 5% on a reported basis, and the company ended the quarter with $1.4 billion in cash and no outstanding borrowings.
#revenue #billion #NASDAQ


6 days ago
Nvidia (NVDA) CEO Jensen Huang is challenging the people warning that AI could end humanity, suggesting their alarming predictions may serve another purpose.
Speaking with CBS News, Huang rejected the 'AI apocalypse' debate and questioned the motives behind those spreading that fear, adding a sharper edge to an increasingly public industry split.
OpenAI and Anthropic leaders, alongside Elon Musk, have backed calls to slow advanced AI development over safety concerns and fears that the technology might be advancing quicker than companies can control it, as reported by Financial Times.
For Nvidia investors, that debate carries financial weight. Shares have returned 20% year-to-date and 23% over the six months, according to Seeking Alpha data.
A coordinated slowdown could complicate the spending boom supporting its chip business. Huang's response, however, reaches beyond defending continued investment.
#NVIDIA #anthropic
Speaking with CBS News, Huang rejected the 'AI apocalypse' debate and questioned the motives behind those spreading that fear, adding a sharper edge to an increasingly public industry split.
OpenAI and Anthropic leaders, alongside Elon Musk, have backed calls to slow advanced AI development over safety concerns and fears that the technology might be advancing quicker than companies can control it, as reported by Financial Times.
For Nvidia investors, that debate carries financial weight. Shares have returned 20% year-to-date and 23% over the six months, according to Seeking Alpha data.
A coordinated slowdown could complicate the spending boom supporting its chip business. Huang's response, however, reaches beyond defending continued investment.
#NVIDIA #anthropic


6 days ago
Bloom Energy Corporation (NYSE:BE) garnered significant investor attention after it unveiled a new 800V DC-native fuel-cell power architecture on September 16, designed to supply continuous direct current to the next generation of AI data centers.
These solid-oxide fuel cells can generate continuous 800V DC power natively, rather than producing AC power that then has to be converted into DC that AI computing equipment ultimately consumes. This potentially removes several conversion stages, such as transformers and switchgear, thus lowering capital cost and energy losses.
Bloom claims that its technology can cut non-compute capital expenditures for a 1 GW data center by $3.6 billion, or 27%, and lower five-year total cost of ownership by $5.5 billion, or 9%, compared to traditional AC-based infrastructure.
With this technology, Bloom Energy is targeting one of the biggest bottlenecks in the ongoing AI boom – securing large amounts of reliable power quickly and economically. If 800V DC becomes widely adopted across AI data centers, the company will benefit not only from the soaring power demand, but also from a broader shift in how that power is generated and delivered.
Bloom Energy pointed to Nvidia's planned adoption of 800V DC architecture beginning with Rubin Ultra and Kyber systems as an indication of where data center power infrastructure is heading. In its 2026 Mid-Year Data Center Power Report, Bloom claimed that data center leaders expect DC-based architectures to account for 58% of new deployments by 2030, potentially creating a significant market for technologies designed around direct-current power delivery.
#energy #architecture
These solid-oxide fuel cells can generate continuous 800V DC power natively, rather than producing AC power that then has to be converted into DC that AI computing equipment ultimately consumes. This potentially removes several conversion stages, such as transformers and switchgear, thus lowering capital cost and energy losses.
Bloom claims that its technology can cut non-compute capital expenditures for a 1 GW data center by $3.6 billion, or 27%, and lower five-year total cost of ownership by $5.5 billion, or 9%, compared to traditional AC-based infrastructure.
With this technology, Bloom Energy is targeting one of the biggest bottlenecks in the ongoing AI boom – securing large amounts of reliable power quickly and economically. If 800V DC becomes widely adopted across AI data centers, the company will benefit not only from the soaring power demand, but also from a broader shift in how that power is generated and delivered.
Bloom Energy pointed to Nvidia's planned adoption of 800V DC architecture beginning with Rubin Ultra and Kyber systems as an indication of where data center power infrastructure is heading. In its 2026 Mid-Year Data Center Power Report, Bloom claimed that data center leaders expect DC-based architectures to account for 58% of new deployments by 2030, potentially creating a significant market for technologies designed around direct-current power delivery.
#energy #architecture


6 days ago
Americans have paid about $97 billion more for fuel since the Iran war started in late February, roughly $740 extra per household, according to CNN. President Trump says prices will come down after the midterms. The CEO of Chevron just said publicly he does not see how that happens quickly.
Mike Wirth, Chevron's chairman and chief executive, spoke at a University of Texas at Austin energy conference on September 11. He told the audience that the mechanisms that helped absorb the oil supply shock earlier in the conflict have largely been used up, and that prices are more likely to rise than fall over the next few months.
When the U.S.-Iran conflict began, the oil market had several ways to handle the disruption. Countries could release crude from strategic reserves. Commercial inventories could be drawn down. The U.S. eased restrictions on sanctioned crude stored on vessels at sea. Those measures helped limit the initial price spike.
"Those have largely now played out," Wirth said. The energy system no longer has the buffers it had when the war began.
The loss of flexibility became more acute after attacks knocked out a major Saudi crude pipeline that had been bypassing the Strait of Hormuz. That single disruption put an estimated 2.5 million barrels of oil per day in limbo, tightening a market that was already running short on supply.
#crude #prices #energy #conflict
Mike Wirth, Chevron's chairman and chief executive, spoke at a University of Texas at Austin energy conference on September 11. He told the audience that the mechanisms that helped absorb the oil supply shock earlier in the conflict have largely been used up, and that prices are more likely to rise than fall over the next few months.
When the U.S.-Iran conflict began, the oil market had several ways to handle the disruption. Countries could release crude from strategic reserves. Commercial inventories could be drawn down. The U.S. eased restrictions on sanctioned crude stored on vessels at sea. Those measures helped limit the initial price spike.
"Those have largely now played out," Wirth said. The energy system no longer has the buffers it had when the war began.
The loss of flexibility became more acute after attacks knocked out a major Saudi crude pipeline that had been bypassing the Strait of Hormuz. That single disruption put an estimated 2.5 million barrels of oil per day in limbo, tightening a market that was already running short on supply.
#crude #prices #energy #conflict


6 days ago
Apple's (NASDAQ: AAPL) new iPhones are here, and this could be just the ticket to get the consumer tech ******* an back on top of the market cap throne. It doesn't have far to go to get there.
The stock's recent gains now place it within 2% of hitting a market cap of $5 trillion. Perhaps even more intriguingly, Apple is now less than 10% away from overtaking Nvidia (NASDAQ: NVDA) to become the market's most valuable company by market capitalization.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Apple's business isn't growing as quickly as Nvidia's these days, but it is closing the gap in market cap. Nvidia investors can't feel too bad, with the stock up 26% over the past year. It's just that Apple stock has soared by more than 40% in that time. Momentum is on its side, and that's before a bar-raising device hits the market.
For more than a dozen years, Apple has fallen into a predictable pattern. It delivers double-digit revenue growth in a fiscal year in which it rolls out a revolutionary iPhone model. Then it follows that with two -- and lately more than two -- years of single-digit or negative top-line growth, settling for merely evolutionary smartphone updates.
#NASDAQ
The stock's recent gains now place it within 2% of hitting a market cap of $5 trillion. Perhaps even more intriguingly, Apple is now less than 10% away from overtaking Nvidia (NASDAQ: NVDA) to become the market's most valuable company by market capitalization.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Apple's business isn't growing as quickly as Nvidia's these days, but it is closing the gap in market cap. Nvidia investors can't feel too bad, with the stock up 26% over the past year. It's just that Apple stock has soared by more than 40% in that time. Momentum is on its side, and that's before a bar-raising device hits the market.
For more than a dozen years, Apple has fallen into a predictable pattern. It delivers double-digit revenue growth in a fiscal year in which it rolls out a revolutionary iPhone model. Then it follows that with two -- and lately more than two -- years of single-digit or negative top-line growth, settling for merely evolutionary smartphone updates.
#NASDAQ
6 days ago
On September 15, Digital Realty (NYSE:DLR) made ServiceFabric MCP available, a software layer that lets AI agents design, monitor and troubleshoot network connections across more than 800 data centers, including third-party sites. That nudges a real estate company toward becoming a control panel for enterprise AI. It arrives after second quarter results reported on July 23, when Core FFO per share, the company's preferred earnings yardstick, excluding net promote rose to $2.13 from $1.87 a year earlier. Here is what the launch does, and what it has yet to prove.
The pitch is that enterprise AI needs more than servers. It needs power, cooling, and sovereign placement that software can control. ServiceFabric MCP handles four jobs: designing and provisioning connections, spotting capacity and watching live network health, managing access through OAuth 2, and handing troubleshooting to agents with links into chat and monitoring tools. It is also open by design. Customers do not have to live only in Digital Realty buildings or commit to a single AI model. An IDC research VP argues that public cloud interfaces alone cannot give enterprises enough control over data movement and policy, which favors providers that pair global reach with programmable interconnection. Digital Realty runs the system on its own AI workloads, and See All AI, a medical imaging developer, leans on the Boston campus and ServiceFabric to move large datasets quickly and securely.
The financial engine underneath is running hot. Renewal leases in the second quarter were signed at rates 25.4% higher on a cash basis, which shows customers will pay more to stay put. Signed leases waiting to start added up to a $1.9 billion backlog of annualized base rent at 100% share, so future revenue is already lined up. Management responded by lifting its 2026 Core FFO per share outlook, excluding net promote, to $8.15 to $8.20.
Start with what the launch has not shown yet. Digital Realty itself calls MCP an emerging standard, and ServiceFabric MCP is still being validated across internal, enterprise, and partner deployments. The announcement puts no dollar figure on what it could add to revenue, and the company describes it only as the first programmable surface of a larger architecture that may later stretch into ***** e, power and inventory. Until customers pay for this layer, it is a promising idea more than a line item.
Then there is the bill for the physical side. Digital Realty carried about $18.6 billion of debt at June 30, 2026, and its 2026 development spending outlook, net of partner contributions, now sits at $4.25 billion to $4.75 billion. The outlook also ***** umes new long-term debt priced at 4.5% to 5.5%, up from the earlier 4.0% to 4.5%. To help pay for growth, the company has sold roughly 13.5 million shares this year for about $2.5 billion, which spreads future earnings across more owners. And the quarter's headline flattered a bit: Core FFO per share of $2.65 included a $18
The pitch is that enterprise AI needs more than servers. It needs power, cooling, and sovereign placement that software can control. ServiceFabric MCP handles four jobs: designing and provisioning connections, spotting capacity and watching live network health, managing access through OAuth 2, and handing troubleshooting to agents with links into chat and monitoring tools. It is also open by design. Customers do not have to live only in Digital Realty buildings or commit to a single AI model. An IDC research VP argues that public cloud interfaces alone cannot give enterprises enough control over data movement and policy, which favors providers that pair global reach with programmable interconnection. Digital Realty runs the system on its own AI workloads, and See All AI, a medical imaging developer, leans on the Boston campus and ServiceFabric to move large datasets quickly and securely.
The financial engine underneath is running hot. Renewal leases in the second quarter were signed at rates 25.4% higher on a cash basis, which shows customers will pay more to stay put. Signed leases waiting to start added up to a $1.9 billion backlog of annualized base rent at 100% share, so future revenue is already lined up. Management responded by lifting its 2026 Core FFO per share outlook, excluding net promote, to $8.15 to $8.20.
Start with what the launch has not shown yet. Digital Realty itself calls MCP an emerging standard, and ServiceFabric MCP is still being validated across internal, enterprise, and partner deployments. The announcement puts no dollar figure on what it could add to revenue, and the company describes it only as the first programmable surface of a larger architecture that may later stretch into ***** e, power and inventory. Until customers pay for this layer, it is a promising idea more than a line item.
Then there is the bill for the physical side. Digital Realty carried about $18.6 billion of debt at June 30, 2026, and its 2026 development spending outlook, net of partner contributions, now sits at $4.25 billion to $4.75 billion. The outlook also ***** umes new long-term debt priced at 4.5% to 5.5%, up from the earlier 4.0% to 4.5%. To help pay for growth, the company has sold roughly 13.5 million shares this year for about $2.5 billion, which spreads future earnings across more owners. And the quarter's headline flattered a bit: Core FFO per share of $2.65 included a $18

6 days ago
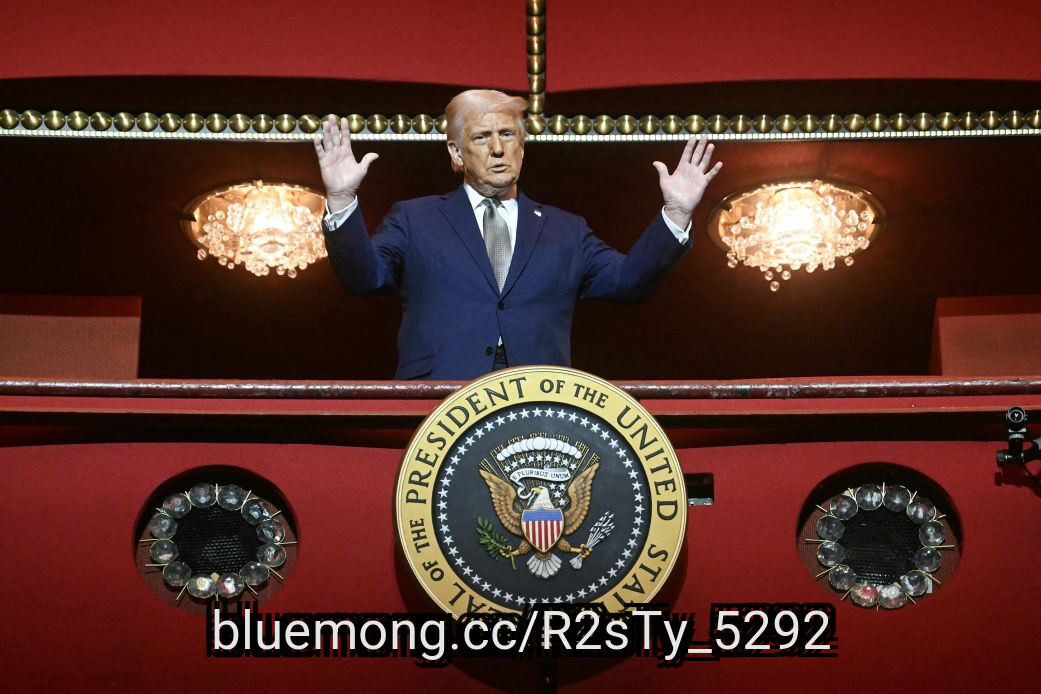
When President Donald Trump’s name was ordered removed from the Kennedy Center this spring, it seemed that an opening to move on from his reign over the performing arts center might have emerged.
“I have instructed the Department of Commerce to make all necessary arrangements with Congress to allow a full and complete transfer of this Institution, giving them the responsibility for its Operation, Maintenance, and Management,” the president wrote in a late-May Truth Social post, seemingly relinquishing the control he’d seized a year prior.
Speculation even bubbled up among some of the more than a dozen “ex-officio,” board members — who don’t get a vote but are not allied with Trump — over whether the former board chairman, billionaire philanthropist David Rubenstein, could be brought back to help restore the center’s fundraising and programming, two sources familiar with the matter told CNN. (CNN has asked Rubenstein for comment.)
But after Trump said he would remain chairman, “it kind of all squelched pretty quickly,” one of the sources said. The hope that his crusade to rename a monument dedicated to the memory of John F. Kennedy had ended turned out to be wishful thinking.
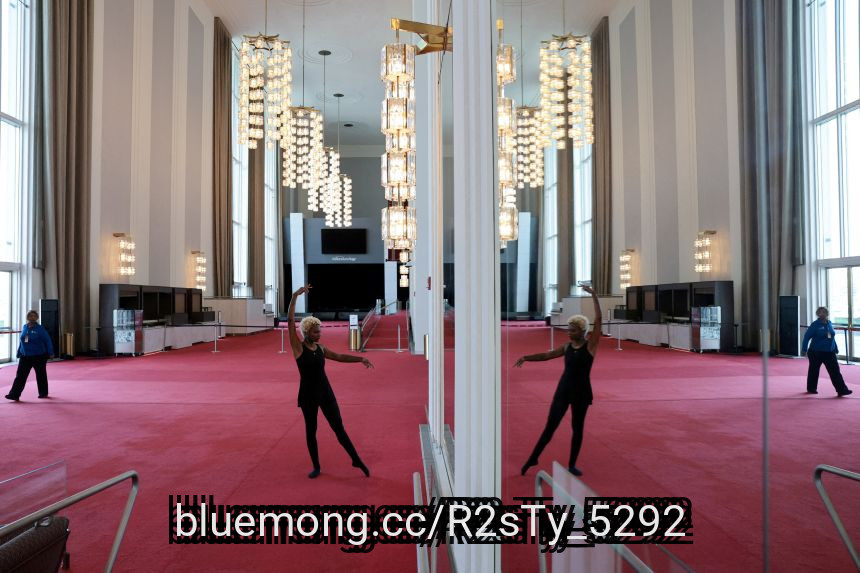
Instead, nine months from a cold December day when cranes first placed Trump’s name on the marble façade, the institution has been brought to the brink by the president still very much engaged in a fight: lights have been turned off inside, infrastructure is crumbling and protests swirl while legal battles mount.
#center
“I have instructed the Department of Commerce to make all necessary arrangements with Congress to allow a full and complete transfer of this Institution, giving them the responsibility for its Operation, Maintenance, and Management,” the president wrote in a late-May Truth Social post, seemingly relinquishing the control he’d seized a year prior.
Speculation even bubbled up among some of the more than a dozen “ex-officio,” board members — who don’t get a vote but are not allied with Trump — over whether the former board chairman, billionaire philanthropist David Rubenstein, could be brought back to help restore the center’s fundraising and programming, two sources familiar with the matter told CNN. (CNN has asked Rubenstein for comment.)
But after Trump said he would remain chairman, “it kind of all squelched pretty quickly,” one of the sources said. The hope that his crusade to rename a monument dedicated to the memory of John F. Kennedy had ended turned out to be wishful thinking.
Instead, nine months from a cold December day when cranes first placed Trump’s name on the marble façade, the institution has been brought to the brink by the president still very much engaged in a fight: lights have been turned off inside, infrastructure is crumbling and protests swirl while legal battles mount.
#center


6 days ago
The price of Bitcoin (CRYPTO: $BTC) and other cryptocurrencies strengthened heading into the weekend after a volatile week dominated by an interest rate hike from the U.S. Federal Reserve
On the afternoon of Sept. 18, Bitcoin was up 6% and trading at $80,850 U.S. The largest cryptocurrency had been trading near $75,000 U.S. on the eve of the U.S. interest rate decision on Sept. 16. Other digital ****** ets were gaining strength at week's end, with Ethereum (CRYPTO: $ETH) also up 6% and Solana's (CRYPTO: $SOL) price rising 11%.
It's proving to be a quick recovery for digital ****** ets after the U.S. central bank raised its trendsetting Fed Funds Rate by 25 basis points, its first hike in three years. Crypto appears to be staging a relief rally as the market welcomes slightly higher interest rates that are used to dampen inflation.
More From Cryptoprowl:
U.S. Regulators Push Crypto Rules As Clarity Act Stalls
#sept #digital
On the afternoon of Sept. 18, Bitcoin was up 6% and trading at $80,850 U.S. The largest cryptocurrency had been trading near $75,000 U.S. on the eve of the U.S. interest rate decision on Sept. 16. Other digital ****** ets were gaining strength at week's end, with Ethereum (CRYPTO: $ETH) also up 6% and Solana's (CRYPTO: $SOL) price rising 11%.
It's proving to be a quick recovery for digital ****** ets after the U.S. central bank raised its trendsetting Fed Funds Rate by 25 basis points, its first hike in three years. Crypto appears to be staging a relief rally as the market welcomes slightly higher interest rates that are used to dampen inflation.
More From Cryptoprowl:
U.S. Regulators Push Crypto Rules As Clarity Act Stalls
#sept #digital
6 days ago
Semiconductor giant Nvidia (NASDAQ: NVDA) has been a hot stock for some time now -- for good reason. It has averaged annualized gains of 52% over the past 15 years. That was enough to turn a single $10,000 investment 15 years ago into a stake worth $5.9 million (with dividends reinvested) or $5.4 million (without the reinvestment of dividends).
What if you buy into it today, though? How big could your stake in it become by, say, 2030? Let's take a look.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Let's start with a caveat: Whatever estimate we come up with will be just that -- an estimate. It will be based on the stock's growth rate -- which over the past three years has averaged nearly 70% per year! Over the past one year, it has gained nearly 20%. (That 20% might seem puny, but remember that over many decades, the stock market has averaged annual gains of close to 10%. So a 20% gain is still pretty good.)
But how quickly will Nvidia grow over the coming four years? Well, let's pick a number between that 20% and the longer-term rate of 52%. Let's say 30%.
#NVIDIA #missed
What if you buy into it today, though? How big could your stake in it become by, say, 2030? Let's take a look.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Let's start with a caveat: Whatever estimate we come up with will be just that -- an estimate. It will be based on the stock's growth rate -- which over the past three years has averaged nearly 70% per year! Over the past one year, it has gained nearly 20%. (That 20% might seem puny, but remember that over many decades, the stock market has averaged annual gains of close to 10%. So a 20% gain is still pretty good.)
But how quickly will Nvidia grow over the coming four years? Well, let's pick a number between that 20% and the longer-term rate of 52%. Let's say 30%.
#NVIDIA #missed
6 days ago
On Sept. 16, the U.S. House of Representatives voted 417 to 3 to pass the Ratepayer Protection Act. Importantly, the bill still needs to pass the Senate and be signed into law by the President.
Given the bill's bipartisan nature and its strong passage in the House, there is a good chance the Ratepayer Protection Act will eventually become law in some form. That could affect several industries, especially certain nuclear stocks.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Before we look at which stocks will benefit, it's important to understand exactly what the bill aims to do.
Data center construction is progressing rapidly as AI companies seek to expand compute capacity as quickly as possible. The current electric grid, however, wasn't designed to handle such a surge in demand.
#NVIDIA #protection #sept
Given the bill's bipartisan nature and its strong passage in the House, there is a good chance the Ratepayer Protection Act will eventually become law in some form. That could affect several industries, especially certain nuclear stocks.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Before we look at which stocks will benefit, it's important to understand exactly what the bill aims to do.
Data center construction is progressing rapidly as AI companies seek to expand compute capacity as quickly as possible. The current electric grid, however, wasn't designed to handle such a surge in demand.
#NVIDIA #protection #sept


6 days ago
Corning (GLW) stock took a sharp hit this week after the company opened the door to a potential $2 billion equity offering that could dilute existing shareholders. The stock dropped 13.7% on Sept. 14, marking its worst one-day decline in years. At the same time, Corning is expanding its capacity and signing major deals with some of the world's biggest tech companies, including Nvidia (NVDA) and Amazon (AMZN). Its latest Verizon (VZ) agreement alone covers over 80 million miles of optical fiber and connectivity products through 2032. Corning shares have since recovered, shifting attention away from dilution fear to whether the capital raise was a sensible decision, how much stock Corning actually sells, how quickly Optical Communications grows, and whether new capacity generates the returns management expects.
Let's find out more on what matters for investors now.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#Stock #sept
Let's find out more on what matters for investors now.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#Stock #sept

7 days ago
Meta Platforms (META) has spent most of 2026 trading near $648 while the business behind it delivered record quarterly revenue. That growing mismatch has drawn a wave of ******* ysts who believe the stock is meaningfully underpriced.
Second-quarter revenue reached $60.8 billion, up 28% year over year, with a 31% operating margin, Meta's earnings press release confirmed.
At a forward price-to-earnings (P/E) ratio of 19, the stock trades below the S&P 500's approximately 22 times forward earnings.
Reaching $900 would require roughly 39% upside from current levels. Whether the target is realistic depends on how quickly Meta's artificial intelligence spending produces revenue beyond its advertising business.
Meta's advertising technology is producing gains that rival any growth story in big tech. Internal model upgrades drove an 8.3% lift in ad clicks and a 15.7% conversion gain on Facebook last quarter, 24/7 Wall St reported.
#business #year
Second-quarter revenue reached $60.8 billion, up 28% year over year, with a 31% operating margin, Meta's earnings press release confirmed.
At a forward price-to-earnings (P/E) ratio of 19, the stock trades below the S&P 500's approximately 22 times forward earnings.
Reaching $900 would require roughly 39% upside from current levels. Whether the target is realistic depends on how quickly Meta's artificial intelligence spending produces revenue beyond its advertising business.
Meta's advertising technology is producing gains that rival any growth story in big tech. Internal model upgrades drove an 8.3% lift in ad clicks and a 15.7% conversion gain on Facebook last quarter, 24/7 Wall St reported.
#business #year

7 days ago
The ******* e Exploration Technologies (NASDAQ: SPCX) IPO was one of the most highly anticipated public offerings in years. Within a few days of going public, ******* eX had a valuation of $2.7 trillion after raising nearly $86 billion in funding.
Then things started going sideways. The stock began falling amid fears that ******* eX is spending too much on artificial intelligence (AI) infrastructure, and shares still trade below their opening price of $150 as of this writing. At one point, the share price fell enough to wipe out more than $1 trillion from ******* eX's valuation over a one-month span.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Another AI company, Anthropic, could go public as soon as next month. Like ******* eX, it's a highly anticipated IPO. But investors would be wise to take the recent ******* eX sell-off as a warning that buying IPO stocks when they first go public is rarely a good move. History shows it's far better to wait before buying -- here's why.
While there was an initial surge in interest for ******* eX, investors quickly turned their attention to the company's massive AI spending spree. The company's capital expenditures (capex) jumped 308% in the first six months of this year, compared to 2025, reaching $28.5 billion. That's a hefty sum, especially when you consider that ******* eX sales were just $12.5 billion over that same period.
#billion #first
Then things started going sideways. The stock began falling amid fears that ******* eX is spending too much on artificial intelligence (AI) infrastructure, and shares still trade below their opening price of $150 as of this writing. At one point, the share price fell enough to wipe out more than $1 trillion from ******* eX's valuation over a one-month span.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Another AI company, Anthropic, could go public as soon as next month. Like ******* eX, it's a highly anticipated IPO. But investors would be wise to take the recent ******* eX sell-off as a warning that buying IPO stocks when they first go public is rarely a good move. History shows it's far better to wait before buying -- here's why.
While there was an initial surge in interest for ******* eX, investors quickly turned their attention to the company's massive AI spending spree. The company's capital expenditures (capex) jumped 308% in the first six months of this year, compared to 2025, reaching $28.5 billion. That's a hefty sum, especially when you consider that ******* eX sales were just $12.5 billion over that same period.
#billion #first


7 days ago
Gov. Abbott says Texas data centers "dug their own grave" by expanding too fast, with fewer than 10% responding to a state electricity demand survey.
Claiming Social Security at 63 instead of 67 permanently locks in just 75% of the full benefit, costing a $2,500 earner roughly $625 monthly.
A long-term ground lease can bridge the income gap to delay Social Security claiming, and passive rental income generally avoids the Social Security earnings test.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Texas spent years courting the data-center boom. Now Gov. Greg Abbott says the industry "dug their own grave" by expanding too quickly without winning over the communities expected to host the projects. The backlash is real.
#texas #grave
Claiming Social Security at 63 instead of 67 permanently locks in just 75% of the full benefit, costing a $2,500 earner roughly $625 monthly.
A long-term ground lease can bridge the income gap to delay Social Security claiming, and passive rental income generally avoids the Social Security earnings test.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Texas spent years courting the data-center boom. Now Gov. Greg Abbott says the industry "dug their own grave" by expanding too quickly without winning over the communities expected to host the projects. The backlash is real.
#texas #grave


7 days ago
Amazon (AMZN) has spent the bulk of 2026 giving investors tons to debate, from its growing cloud business to the enormous bill for its AI ambitions. Now, it's putting another spending decision in the spotlight, one that goes directly into workers' household budgets.
Amazon has announced more than $1.5 billion in higher pay for U.S. operations employees, alongside benefits aimed at everyday expenses.
For workers, the appeal is the obvious, immediate financial breathing room.
For Amazon, the calculation goes further. Keeping experienced employees helps the business built around getting orders to doorsteps a lot quickly. The details point to how Amazon is trying to make those interests meet, even as its broader efficiency push leaves questions about job security.
For perspective, Amazon's pay ******* p adds $2,080 to an eligible worker's annual earnings before taxes, ******* uming 40 paid hours weekly for 52 weeks.
#amazon #goes #employees #amzn
Amazon has announced more than $1.5 billion in higher pay for U.S. operations employees, alongside benefits aimed at everyday expenses.
For workers, the appeal is the obvious, immediate financial breathing room.
For Amazon, the calculation goes further. Keeping experienced employees helps the business built around getting orders to doorsteps a lot quickly. The details point to how Amazon is trying to make those interests meet, even as its broader efficiency push leaves questions about job security.
For perspective, Amazon's pay ******* p adds $2,080 to an eligible worker's annual earnings before taxes, ******* uming 40 paid hours weekly for 52 weeks.
#amazon #goes #employees #amzn

7 days ago
Data center developer Crusoe said Thursday it raised $3.9 billion in a Series F round that pushes its valuation to $30.9 billion. The massive round was co-led by Atreides Management, Mubadala Capital, and Valor Equity Partners. Founders Fund, GIC, Nvidia, Qatar Investment Authority (QIA), Radical Ventures, and TPG also participated, according to Crusoe.
Crusoe also announced three new board members, including Cloudflare CFO Thomas Seifert; Bill Stein, partner and CIO at Primary Digital Infrastructure; and Redwood Materials founder and CEO JB Straubel, who also sits on Tesla's board. Straubel already has ties to Crusoe; he personally invested in the company in 2021, and Crusoe later became the first customer of Redwood's energy storage business.
The eight-year-old company's fresh capital infusion will help finance existing data center projects, including a large site in Abilene, Texas, used by OpenAI, as well as smaller, modular AI factories that can be transported by truck and connected to large power sources almost anywhere.
By manufacturing these modular data centers, called Spark, at its own facilities, Crusoe can deploy compute capacity quickly and without the need for large construction workforces. The smaller centers could also help Crusoe sidestep, at least in part, another major obstacle facing data center developers: backlash from local communities protesting massive complexes near their neighborhoods.
Crusoe co-founder and CEO Chase Lochmiller, who is pictured above, said in a statement he believes AI will usher in an era of abundance, but to get there will mean "controlling the infrastructure from electrons to tokens, and we're grateful to have investors who share that conviction."
#straubel #round
Crusoe also announced three new board members, including Cloudflare CFO Thomas Seifert; Bill Stein, partner and CIO at Primary Digital Infrastructure; and Redwood Materials founder and CEO JB Straubel, who also sits on Tesla's board. Straubel already has ties to Crusoe; he personally invested in the company in 2021, and Crusoe later became the first customer of Redwood's energy storage business.
The eight-year-old company's fresh capital infusion will help finance existing data center projects, including a large site in Abilene, Texas, used by OpenAI, as well as smaller, modular AI factories that can be transported by truck and connected to large power sources almost anywhere.
By manufacturing these modular data centers, called Spark, at its own facilities, Crusoe can deploy compute capacity quickly and without the need for large construction workforces. The smaller centers could also help Crusoe sidestep, at least in part, another major obstacle facing data center developers: backlash from local communities protesting massive complexes near their neighborhoods.
Crusoe co-founder and CEO Chase Lochmiller, who is pictured above, said in a statement he believes AI will usher in an era of abundance, but to get there will mean "controlling the infrastructure from electrons to tokens, and we're grateful to have investors who share that conviction."
#straubel #round

7 days ago
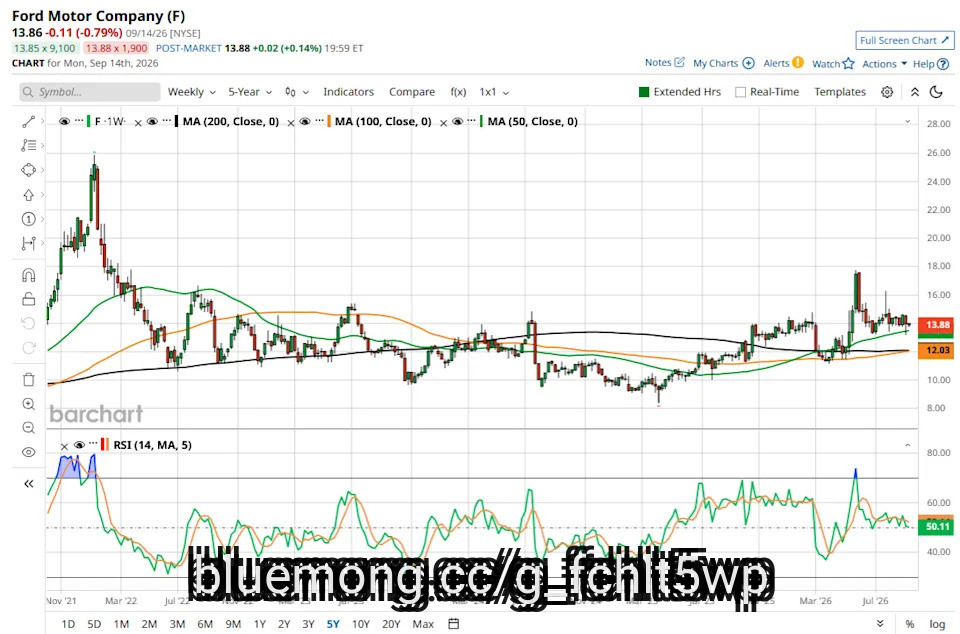
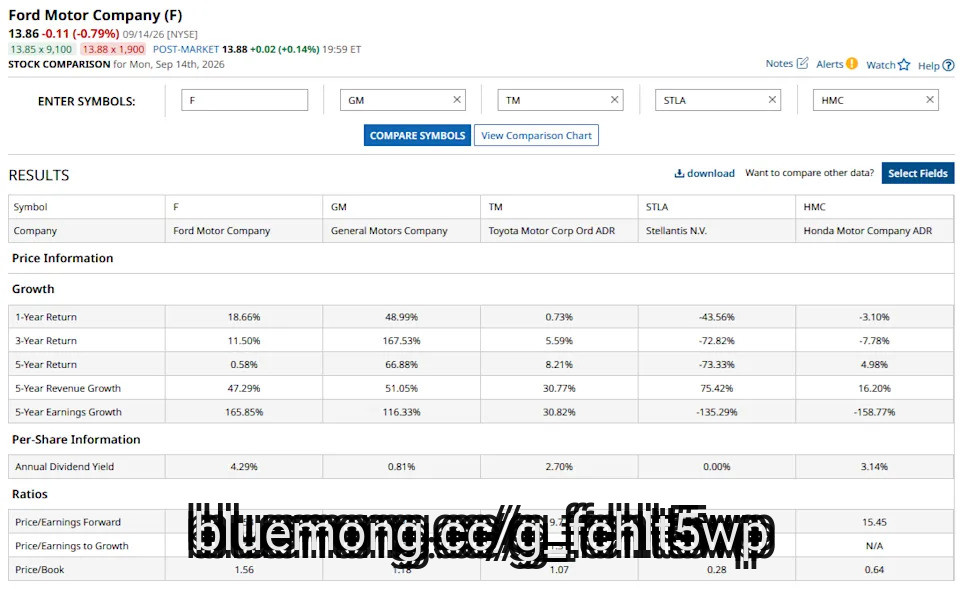
With a dividend yield of 4.3%, Ford (F) is among the highest-yielding constituents of the S&P 500 Index ($SPX). That number would look even more compelling considering Ford's dividend yield is over four times what an average S&P 500 Index constituent pays.
However, a bit of number-crunching tells a different picture. Dividend yield is basically a function of the per-share dividend, which is the numerator in the equation, and the stock price, which is the denominator. Dividend yield rises when the company raises its dividends or the share price falls. More often than not, the latter is true for companies that have a very high dividend yield.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ****** ysis you won't find anywhere else.
The S&P 500's dividend yield is near its historical lows. Two factors can be blamed for the dip in the world's most popular index's dividend yield. First, tech companies' share in the market-cap-weighted index has soared amid the artificial intelligence (AI) driven rally. Mega-cap tech companies are known to be frugal with dividends, and their rising weightage in the index pulls down its dividend yield. Second, while the annualized dividend per share of the S&P 500 has continued to rise over the years, the increase has been much lower compared to the surge in stock prices.
In contrast, Ford's quarterly dividend has been static since July 2022, when the company raised the payout by 50% to $0.15. Notably, while Ford paid special dividends in the preceding three years to reach its payout targets, it hasn't raised its payout for over four years. Its dividend yield is still high because of its underperforming stock, which has essentially gone nowhere in the last five years and trades 46% below its October 2022 highs.
#Dividend #yield #Share #dividends
However, a bit of number-crunching tells a different picture. Dividend yield is basically a function of the per-share dividend, which is the numerator in the equation, and the stock price, which is the denominator. Dividend yield rises when the company raises its dividends or the share price falls. More often than not, the latter is true for companies that have a very high dividend yield.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ****** ysis you won't find anywhere else.
The S&P 500's dividend yield is near its historical lows. Two factors can be blamed for the dip in the world's most popular index's dividend yield. First, tech companies' share in the market-cap-weighted index has soared amid the artificial intelligence (AI) driven rally. Mega-cap tech companies are known to be frugal with dividends, and their rising weightage in the index pulls down its dividend yield. Second, while the annualized dividend per share of the S&P 500 has continued to rise over the years, the increase has been much lower compared to the surge in stock prices.
In contrast, Ford's quarterly dividend has been static since July 2022, when the company raised the payout by 50% to $0.15. Notably, while Ford paid special dividends in the preceding three years to reach its payout targets, it hasn't raised its payout for over four years. Its dividend yield is still high because of its underperforming stock, which has essentially gone nowhere in the last five years and trades 46% below its October 2022 highs.
#Dividend #yield #Share #dividends

7 days ago
Estes Express Lines is investing nearly $56 million to expand its cross-border and offshore freight network, including terminals, equipment and capacity serving Canada, Mexico, Alaska, Hawaii and Puerto Rico.
Alex Peebles, senior director of offshore and international at Estes, said the privately held, family-owned carrier is taking a longer view of the freight market rather than allowing current conditions to dictate its investment strategy.
"We're really looking at all of these investments from a long-term horizon and viewpoint perspective and one that's going to help accommodate growth and capacity into all the offshore international markets that we service," Peebles told FreightWaves.
Estes, which is celebrating its 95th anniversary this year, is North America's largest privately held less-than-truckload (LTL) freight transportation provider. The company operates a network of over 300 terminals and service centers across the U.S., Puerto Rico, Alaska, Hawaii with coverage extending to Canada, Mexico and the Caribbean
Peebles said the company's ownership structure gives it flexibility to move quickly when real estate and equipment opportunities arise.
#rico
Alex Peebles, senior director of offshore and international at Estes, said the privately held, family-owned carrier is taking a longer view of the freight market rather than allowing current conditions to dictate its investment strategy.
"We're really looking at all of these investments from a long-term horizon and viewpoint perspective and one that's going to help accommodate growth and capacity into all the offshore international markets that we service," Peebles told FreightWaves.
Estes, which is celebrating its 95th anniversary this year, is North America's largest privately held less-than-truckload (LTL) freight transportation provider. The company operates a network of over 300 terminals and service centers across the U.S., Puerto Rico, Alaska, Hawaii with coverage extending to Canada, Mexico and the Caribbean
Peebles said the company's ownership structure gives it flexibility to move quickly when real estate and equipment opportunities arise.
#rico


7 days ago
Palantir Technologies (NASDAQ:PLTR) CEO Alex Karp just added a third front to the fight over artificial intelligence (AI) safety on Thursday, arguing that the companies developing the technology -- the Anthropics and OpenAI's of the world -- should face civil and criminal penalties if AI causes the damage their CEOs are warning of.
Speaking with CNBC, Karp said that he agreed that "reasonable guidelines" for the industry should be enforced, but that "you can't do it" and that "the first line of defense" instead should be to hold companies and their leaders responsible for their own actions.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Karp was weighing in on an ongoing and high-profile debate within the industry. After Anthropic CEO Dario Amodei penned an essay warning that AI capabilities were improving too quickly for researchers to understand and control them and that action must be taken to ensure the public's safety, he was joined by several AI leaders with calls for a slowdown and increased oversight.
Here's a look at what they had to say:
#safety #Companies #warning #leaders
Speaking with CNBC, Karp said that he agreed that "reasonable guidelines" for the industry should be enforced, but that "you can't do it" and that "the first line of defense" instead should be to hold companies and their leaders responsible for their own actions.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Karp was weighing in on an ongoing and high-profile debate within the industry. After Anthropic CEO Dario Amodei penned an essay warning that AI capabilities were improving too quickly for researchers to understand and control them and that action must be taken to ensure the public's safety, he was joined by several AI leaders with calls for a slowdown and increased oversight.
Here's a look at what they had to say:
#safety #Companies #warning #leaders
7 days ago
Ascendis Pharma A/S (NASDAQ:ASND) announced on September 14 that it will regain exclusive rights to develop, manufacture, and commercialize TransCon products in metabolic and cardiovascular diseases following the termination of its collaboration with Novo Nordisk A/S (NYSE:NVO).
The rights include once-monthly TransCon Semaglutide, an investigational long-acting prodrug of semaglutide intended for obesity and type 2 diabetes. Neither party will have continuing financial obligations to the other. Once termination becomes effective and the rights revert, management plans to initiate multiple programs across rare and large indications.
The investment question is whether greater control over future products can justify the resources needed to develop them.
Ascendis Pharma A/S (NASDAQ:ASND) would regain flexibility over which indications to pursue, how quickly to advance candidates, and whether to seek another partner. Successful independent development could retain more of a product's commercial economics, while a new collaboration could provide another way to share costs and risk.
Monthly dosing offers a clear development objective. If clinical studies demonstrate effective treatment with acceptable tolerability, fewer injections could make long-term therapy more convenient. That potential benefit would matter most if it helps patients stay on treatment without sacrificing outcomes.
#ascendis #pharma #asnd #regain
The rights include once-monthly TransCon Semaglutide, an investigational long-acting prodrug of semaglutide intended for obesity and type 2 diabetes. Neither party will have continuing financial obligations to the other. Once termination becomes effective and the rights revert, management plans to initiate multiple programs across rare and large indications.
The investment question is whether greater control over future products can justify the resources needed to develop them.
Ascendis Pharma A/S (NASDAQ:ASND) would regain flexibility over which indications to pursue, how quickly to advance candidates, and whether to seek another partner. Successful independent development could retain more of a product's commercial economics, while a new collaboration could provide another way to share costs and risk.
Monthly dosing offers a clear development objective. If clinical studies demonstrate effective treatment with acceptable tolerability, fewer injections could make long-term therapy more convenient. That potential benefit would matter most if it helps patients stay on treatment without sacrificing outcomes.
#ascendis #pharma #asnd #regain

7 days ago
Space Exploration Technologies Corp. (NASDAQ:SPCX) is increasingly confident it can reach a $100 billion annual revenue run rate by year-end. The company's CFO said there is now "even more conviction" around the target. A new AI hosting agreement worth $13 billion on an annualized basis adds significant support to that outlook and reflects how quickly ***** eX's compute business is scaling. But the financial picture behind that growth is less straightforward. The same AI division that management is relying on to help reach that target posted a $1.3 billion loss in the latest quarter alone. The loss wiped out what would have otherwise been a profitable quarter, while the company generated roughly negative $25 billion in free cash flow during the first half of 2026.
CFO Bret Johnsen said ***** eX has "even more conviction" that it can reach a $100 billion annual revenue run rate. The outlook is supported by a newly signed AI hosting agreement worth $1.11 billion per month beginning in December, or roughly $13 billion on an annualized basis. The company plans to end the year with a little over 2 gigawatts of terrestrial AI-computing capacity and scale to between 5 and 10 gigawatts in 2027. Orbital computing remains a longer-term option for overcoming power constraints. Its current agreements include a $6.7 billion cloud-services contract that is scheduled to ramp up in October. Existing arrangements with Google and Anthropic are worth more than $2 billion per month combined. Reaching the $100 billion target would require monthly revenue to more than triple from second-quarter's pace.
SpaceX's rocket and Starlink businesses generated roughly $1.1 billion in combined operating income in the second quarter. But the AI division's $1.3 billion loss more than wiped out that profit. The company also generated roughly negative $25 billion in free cash flow during the first half of 2026. The stock declined more than 5% after the second-quarter results despite a revenue beat.
The AI contract pipeline is clearly expanding and gaining momentum. However, the $100 billion target is a revenue run-rate measure rather than a profitability target. At the same time, the division driving this expansion remains the company's largest contributor to both both operating losses and capital spending, making the growth opportunity financially costly for now.
SpaceX had 119 hedge funds among its institutional holders at the end of the second quarter of fiscal 2026. Meanwhile, short interest stood at just 2.76% of float as of August 31, 2026. The ownership and the short interest figures show that institutional sentiment remains broadly constructive and toward the company's long-term outlook.
#roughly
CFO Bret Johnsen said ***** eX has "even more conviction" that it can reach a $100 billion annual revenue run rate. The outlook is supported by a newly signed AI hosting agreement worth $1.11 billion per month beginning in December, or roughly $13 billion on an annualized basis. The company plans to end the year with a little over 2 gigawatts of terrestrial AI-computing capacity and scale to between 5 and 10 gigawatts in 2027. Orbital computing remains a longer-term option for overcoming power constraints. Its current agreements include a $6.7 billion cloud-services contract that is scheduled to ramp up in October. Existing arrangements with Google and Anthropic are worth more than $2 billion per month combined. Reaching the $100 billion target would require monthly revenue to more than triple from second-quarter's pace.
SpaceX's rocket and Starlink businesses generated roughly $1.1 billion in combined operating income in the second quarter. But the AI division's $1.3 billion loss more than wiped out that profit. The company also generated roughly negative $25 billion in free cash flow during the first half of 2026. The stock declined more than 5% after the second-quarter results despite a revenue beat.
The AI contract pipeline is clearly expanding and gaining momentum. However, the $100 billion target is a revenue run-rate measure rather than a profitability target. At the same time, the division driving this expansion remains the company's largest contributor to both both operating losses and capital spending, making the growth opportunity financially costly for now.
SpaceX had 119 hedge funds among its institutional holders at the end of the second quarter of fiscal 2026. Meanwhile, short interest stood at just 2.76% of float as of August 31, 2026. The ownership and the short interest figures show that institutional sentiment remains broadly constructive and toward the company's long-term outlook.
#roughly


8 days ago
Every time Silicon Valley's biggest names line up behind a single message, someone eventually asks who benefits from such universal agreement. This time, that someone was the investor best known for calling the housing crash before almost anyone else saw it coming.
Michael Burry has spent the past year building a reputation as one of the AI industry's loudest skeptics. His latest target is not a stock but a story. When three of the sector's most powerful executives suddenly agreed the technology needed to slow down, Burry saw the timing as less about caution and more like a self-serving pitch.
Burry has spent much of 2026 building short positions against companies tied to the AI trade, disclosing bets against Nvidia, Tesla, Micron, Applied Materials, Caterpillar and a leading semiconductor ETF, according to TheStreet.
On September 14, Burry published a post on X and on his Substack, Cassandra Unchained, arguing that people should take a moment to understand how self-serving it is for OpenAI, Anthropic and other big hyperscaler executives to talk about slowing things down. The post circulated quickly across financial media, Yahoo Finance reported.
Related: Michael Burry doubles down on his surprising AI bet
#michael #time #someone
Michael Burry has spent the past year building a reputation as one of the AI industry's loudest skeptics. His latest target is not a stock but a story. When three of the sector's most powerful executives suddenly agreed the technology needed to slow down, Burry saw the timing as less about caution and more like a self-serving pitch.
Burry has spent much of 2026 building short positions against companies tied to the AI trade, disclosing bets against Nvidia, Tesla, Micron, Applied Materials, Caterpillar and a leading semiconductor ETF, according to TheStreet.
On September 14, Burry published a post on X and on his Substack, Cassandra Unchained, arguing that people should take a moment to understand how self-serving it is for OpenAI, Anthropic and other big hyperscaler executives to talk about slowing things down. The post circulated quickly across financial media, Yahoo Finance reported.
Related: Michael Burry doubles down on his surprising AI bet
#michael #time #someone

8 days ago
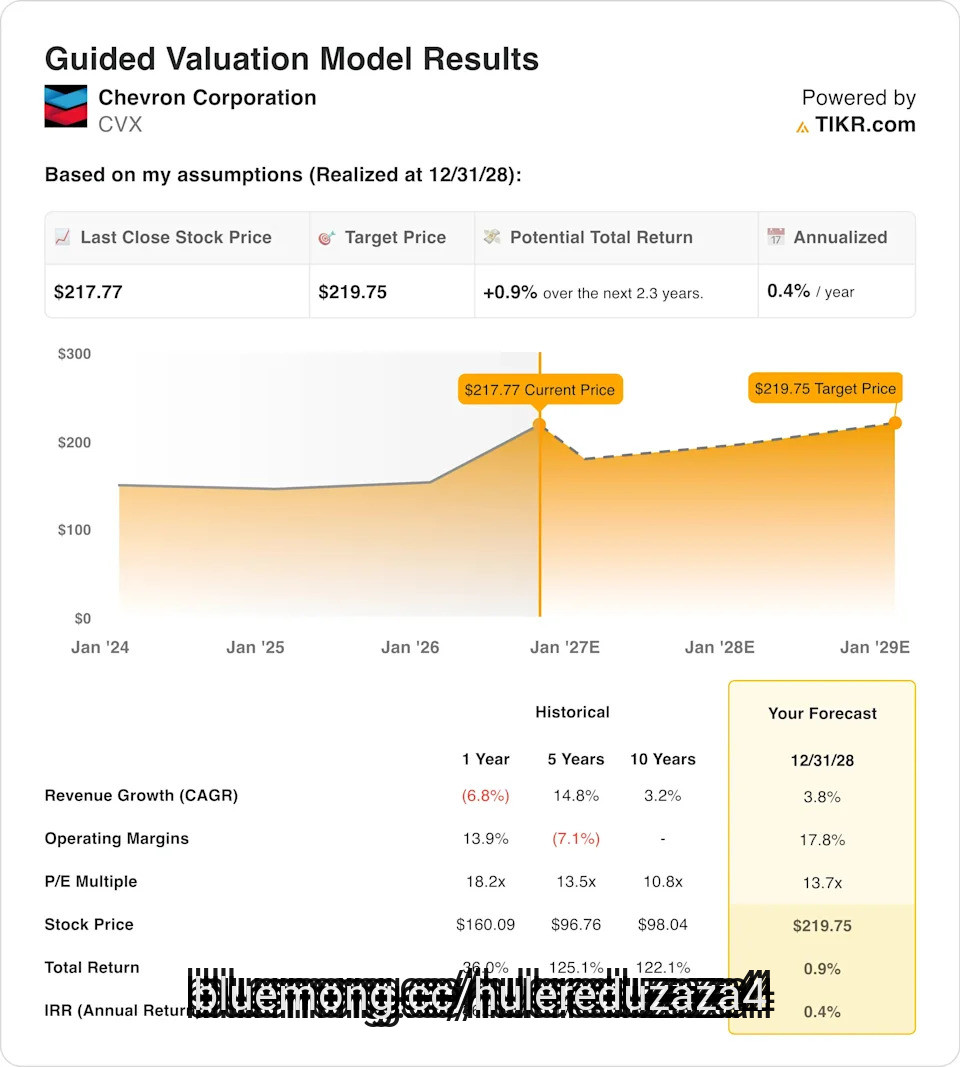
Past week performance: +2.4%
52-week range: $146 to $218
Valuation model target price: $220
Implied upside: 0.9% over 2.3 years
Chevron (CVX) stock barely budged this week, but the commentary coming out of the company was anything but quiet. CEO Mike Wirth told an energy conference that the strategic buffers built up in global crude markets after the recent Iran conflict are now "played out." He added that it's "harder to envision a scenario where prices soften quickly," a notable shift from an executive who typically avoids bold near-term price calls.
#wirth
52-week range: $146 to $218
Valuation model target price: $220
Implied upside: 0.9% over 2.3 years
Chevron (CVX) stock barely budged this week, but the commentary coming out of the company was anything but quiet. CEO Mike Wirth told an energy conference that the strategic buffers built up in global crude markets after the recent Iran conflict are now "played out." He added that it's "harder to envision a scenario where prices soften quickly," a notable shift from an executive who typically avoids bold near-term price calls.
#wirth



8 days ago
The Williams Companies, Inc. (NYSE:WMB) lost a key New Jersey water-quality certification for Northeast Supply Enhancement, or NESE, after a September 8 federal appeals court ruling reported by Reuters on September 9. The Third Circuit vacated the certification and returned the matter to state regulators. The Williams Companies, Inc. (NYSE:WMB) said that, at this time, it did not expect the ruling to adversely affect construction or the anticipated in-service timeline.
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction

8 days ago
You might not be impressed by a stock with a 2% dividend yield as long-term interest rates have been rising quickly in the bond market. But a screen of the S&P 500 shows that companies that have raised their payouts the most have tended to be strong overall performers for long-term investors.
Wednesday afternoon, 10-year U.S. Treasury notes BX:TMUBMUSD10Y were yielding 4.96%, up from 4.47% at the end of June and from 4.17% at the end of last year. Investors has been selling off bonds (which drives up market yields) in anticipation of the Federal Reserve's decision on Wednesday to raise its target range for the federal-funds rate.
What happens if you never buy a house? What renters are gaining — and giving up.
The smartest money moves to make now that interest rates are going up
Read: The Fed could raise interest rates three times. Here's where the market could face the stiffest test.
#investors #federal
Wednesday afternoon, 10-year U.S. Treasury notes BX:TMUBMUSD10Y were yielding 4.96%, up from 4.47% at the end of June and from 4.17% at the end of last year. Investors has been selling off bonds (which drives up market yields) in anticipation of the Federal Reserve's decision on Wednesday to raise its target range for the federal-funds rate.
What happens if you never buy a house? What renters are gaining — and giving up.
The smartest money moves to make now that interest rates are going up
Read: The Fed could raise interest rates three times. Here's where the market could face the stiffest test.
#investors #federal
8 days ago
This story was originally published on CFO Dive. To receive daily news and insights, subscribe to our free daily CFO Dive newsletter.
Business executives consider artificial intelligence a leading tool for decision-making, with 61% citing large language models such as ChatGPT, Claude, Gemini and Copilot among the sources that most influence their strategic decisions, AI enterprise planning platform Board said in a report released Wednesday.
The finding was most ***** ounced among CFOs, with 69% citing LLMs among the resources that inform their decisions, compared with 58% of chief operating officers and 56% of chief information officers.
"CFOs, by nature, are typically a little bit more conservative and skeptical, so I think what this shows is that the AI wave is so strong that it can't be ignored," Board CFO Gordon Pothier said in an interview.
The findings come just a few years after ChatGPT burst onto the market, highlighting how quickly advanced AI tools have reshaped the way businesses operate and make decisions.
#decisions #daily #officers #business
Business executives consider artificial intelligence a leading tool for decision-making, with 61% citing large language models such as ChatGPT, Claude, Gemini and Copilot among the sources that most influence their strategic decisions, AI enterprise planning platform Board said in a report released Wednesday.
The finding was most ***** ounced among CFOs, with 69% citing LLMs among the resources that inform their decisions, compared with 58% of chief operating officers and 56% of chief information officers.
"CFOs, by nature, are typically a little bit more conservative and skeptical, so I think what this shows is that the AI wave is so strong that it can't be ignored," Board CFO Gordon Pothier said in an interview.
The findings come just a few years after ChatGPT burst onto the market, highlighting how quickly advanced AI tools have reshaped the way businesses operate and make decisions.
#decisions #daily #officers #business

8 days ago
On August 4, Westlake Corporation (NYSE:WLK) reported second-quarter results that erased two consecutive quarterly losses in a single swing. Net income landed at $260 million, or $2.01 per share, compared with a $169 million loss just three months earlier and a $142 million loss a year ago. EBITDA nearly tripled from the second quarter of 2025. The numbers mark a sharp reversal for a company whose chemicals business had been bleeding red ink.
The turnaround centers on Performance and Essential Materials, the segment that makes chlorovinyls and other basic chemicals. PEM swung from a $318 million operating loss in the second quarter of 2025 to $185 million in income this quarter, while EBITDA excluding identified items jumped from a 3% margin to 21%. The driver was pricing: average sales prices across PEM rose 14% year over year, more than offsetting a 3% price decline in the Housing and Infrastructure Products segment. Combined with a 7% increase in companywide sales volume, excluding the effects of plant shutdowns and an acquisition, the pricing recovery pushed companywide EBITDA to $679 million from $210 million a year earlier.
Westlake is also working the balance sheet alongside the market recovery. The company reduced debt by $500 million during the quarter and returned $99 million to shareholders through dividends and share repurchases. Management says its three-pillar profitability improvement plan remains on track to deliver a $600 million operating income benefit, a target that, if it holds, would layer structural cost savings on top of whatever the market gives back in pricing.
Not every part of the story improved together. Housing and Infrastructure Products, the segment tied to home construction and building products, saw its EBITDA margin slip to 22% from 24% a year earlier, even as volume rose 6% excluding the ACI acquisition. Average sales prices in that segment fell 3% year over year, a sign that pricing power in housing products has softened even as the company sells more of it.
The improvement in the core chemicals business also leans heavily on price rather than volume. PEM's turnaround came from a 14% jump in average sales price, a figure that can move in either direction with commodity cycles. The first quarter of 2026 was a reminder of how quickly conditions shift: Westlake posted a $169 million net loss just three months before this result, weighed down by $85 million in identified items, including a $67 million charge to settle litigation over PVC pipe and fittings and $18 million tied to facility shutdowns. A year earlier, in the second quarter of 2025, the company absorbed another $130 million in shutdown-related charges. Restructuring and legal charges showed up in two of the last three reported quarters.
#million #year #quarter #loss
The turnaround centers on Performance and Essential Materials, the segment that makes chlorovinyls and other basic chemicals. PEM swung from a $318 million operating loss in the second quarter of 2025 to $185 million in income this quarter, while EBITDA excluding identified items jumped from a 3% margin to 21%. The driver was pricing: average sales prices across PEM rose 14% year over year, more than offsetting a 3% price decline in the Housing and Infrastructure Products segment. Combined with a 7% increase in companywide sales volume, excluding the effects of plant shutdowns and an acquisition, the pricing recovery pushed companywide EBITDA to $679 million from $210 million a year earlier.
Westlake is also working the balance sheet alongside the market recovery. The company reduced debt by $500 million during the quarter and returned $99 million to shareholders through dividends and share repurchases. Management says its three-pillar profitability improvement plan remains on track to deliver a $600 million operating income benefit, a target that, if it holds, would layer structural cost savings on top of whatever the market gives back in pricing.
Not every part of the story improved together. Housing and Infrastructure Products, the segment tied to home construction and building products, saw its EBITDA margin slip to 22% from 24% a year earlier, even as volume rose 6% excluding the ACI acquisition. Average sales prices in that segment fell 3% year over year, a sign that pricing power in housing products has softened even as the company sells more of it.
The improvement in the core chemicals business also leans heavily on price rather than volume. PEM's turnaround came from a 14% jump in average sales price, a figure that can move in either direction with commodity cycles. The first quarter of 2026 was a reminder of how quickly conditions shift: Westlake posted a $169 million net loss just three months before this result, weighed down by $85 million in identified items, including a $67 million charge to settle litigation over PVC pipe and fittings and $18 million tied to facility shutdowns. A year earlier, in the second quarter of 2025, the company absorbed another $130 million in shutdown-related charges. Restructuring and legal charges showed up in two of the last three reported quarters.
#million #year #quarter #loss




