19 days ago
Pfizer (NYSE: PFE) is offering a dividend yield of roughly 6% today. That is well above the roughly 1% yield on offer from the S&P 500 index (SNPINDEX: ^GSPC) and the 1.4% average yield of pharmaceutical stocks. There are good reasons for the negative view of Pfizer, but investors may be ignoring the company's over 100-year history of success. Here's why you may want to consider buying this out-of-favor dividend stock while others are fearful.
Pfizer's stock rocketed higher during the coronavirus pandemic, as investors myopically focused on the company's COVID vaccine. When COVID turned out to be a less serious long-term threat than originally believed, Wall Street dumped Pfizer. At this point, the stock is down more than 50% from its 2021 high. That is a big part of the story behind the high yield.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
However, there's another piece that is more fundamental to the pharmaceutical industry. Like all drug makers, Pfizer's drugs receive time-limited patent protections. When patents expire, generic versions of the medications can be produced. That generally leads to a dramatic decline in revenue from Pfizer's drugs. Right now, Pfizer is facing down some notable patent expirations. This is a completely normal dynamic in the pharmaceutical sector.
Patent expirations are why drug companies are always on the lookout for new drugs. The problem is that patent expirations follow a set schedule, but drug development does not. Pfizer's drug pipeline isn't producing major new drugs right now, and it looks like it may have to work through a period in which new drugs won't fully offset revenue lost to patent expirations. This isn't uncommon, either, but investors are likely focusing on the short term rather than the long term when it comes to Pfizer.
#patent #yield #drug #expirations

21 days ago
A $100,000 split equally across KO, ABBV, and CVX plus two others yields a blended 3.72%, generating $3,715 in annual passive income.
Realty Income (O) leads the group at a 6.04% yield, paying monthly dividends raised for 115 consecutive quarters on 98.8% occupancy.
Five industries fund the income stream, so a weak year in oil, pharma, or ****** et management hits only a fraction of total payouts.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Retirement changes how income works on the day the paychecks stop. Social Security covers part of the monthly bill, and the rest has to come from savings, an annuity, or a portfolio that pays cash on a schedule. Selling shares to cover groceries works fine until a bear market forces those sales at bad prices. Dividends let a retiree collect income and keep the same number of shares.
#income #works #five


24 days ago
PUBLISHED
OCT 03, 2026 AT 07:38 PM EDT
Tennessee officials are still investigating why death row inmate Christa Pike survived an execution attempt after receiving two doses of pentobarbital, a drug intended to render a person unconscious and ultimately cause death.
While the immediate focus has been on what went wrong inside the execution chamber, experts say Pike's case has also renewed scrutiny of a problem that has been building for more than a decade: how states obtain lethal injection drugs after pharmaceutical companies moved aggressively to keep their products from being used in executions. Despite those efforts, pentobarbital remains the primary execution drug used by many death-penalty states, making questions about sourcing, testing and oversight especially significant.
The issue has reshaped how many states carry out executions, forcing them to change drug protocols, seek alternative suppliers and adopt increasingly secretive procurement practices.
#pentobarbital #executions #published #tennessee



1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
1 month ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

1 month ago
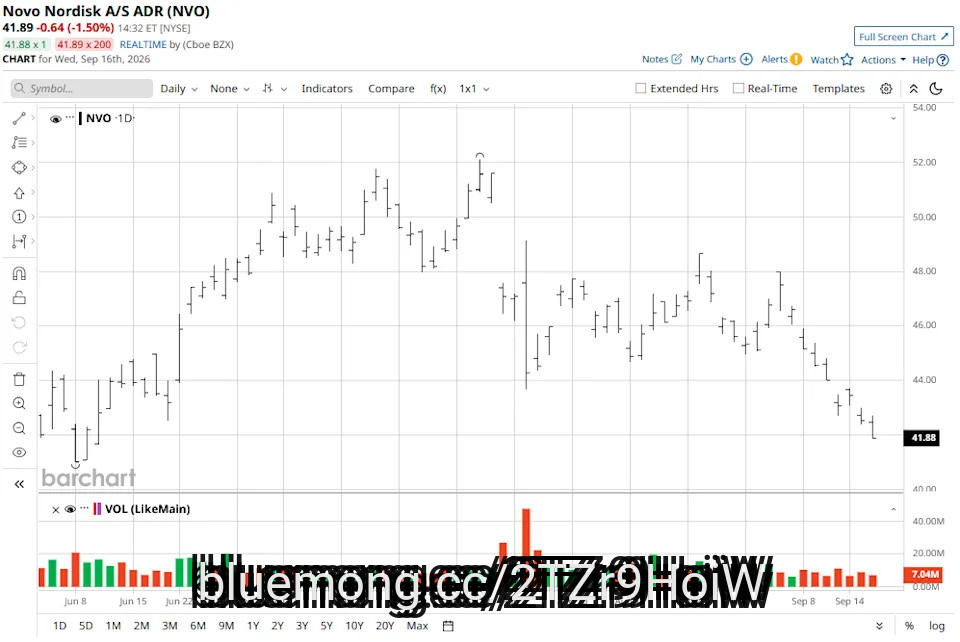
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral


1 month ago
Definium Therapeutics, Inc. (NASDAQ:DFTX) has now delivered a third consecutive positive Phase 3 readout for its LSD-based medication, the second in generalized anxiety disorder. The result puts the company on a viable route toward a potential FDA approval of an LSD-based treatment for generalized anxiety disorder, and considering how closely psychedelic stocks have historically traded on each other's data, the reading carries far more weight than Definium's own ticker.
On September 14, Definium Therapeutics, Inc. (NASDAQ:DFTX) announced that its drug DT120, an orally disintegrating tablet formulation of LSD, was successful in Panorama, the company's second late-stage anxiety trial. Over 12 weeks, patients who received a 100-microgram dose experienced a 9.8-point decline on the Hamilton Anxiety Rating Scale, a typical clinical measure, compared to a 4.7-point drop with placebo.
The resulting 5.1-point placebo-adjusted improvement is similar to what the company's first pivotal anxiety trial, Voyage, showed back in August: an 11.6-point improvement versus 6.2 for placebo, a 5.4-point separation that Jefferies called one of the strongest placebo-adjusted efficacy results ever seen in generalized anxiety disorder, and that Stifel simply described as "a clean win."
Psychedelic equities have a history of trading as a group rather than as individual names, and this tendency applies both ways. In February 2026, when Compass Pathways, the sector's other clinical leader developing a psilocybin-based drug for treatment-resistant depression, reported positive late-stage data, shares of Definium Therapeutics, Inc. (NASDAQ:DFTX), Atai Beckley, GH Research, and Helus Pharma all rose, some by double digits.
That correlation is significant here because Definium's win is an independent validation of the broader therapeutic argument on which Compass and others are betting: a single dose of a classic psychedelic, administered in a controlled clinical setting, can produce lasting improvements in serious mental health conditions via pathways different from existing SSRIs and other standard-of-care drugs.
#definium #placebo


1 month ago
Morgan Stanley met privately with Gilead Sciences (GILD) leadership at its 2026 Global Healthcare Conference this month, and the feedback strengthened the bank's positive view on the stock.
Morgan Stanley's biopharma team hosted a meeting and a management dinner with Gilead Chairman and CEO Daniel O'Day and Chief Commercial and Corporate Affairs Officer Johanna Mercier. According to a Morgan Stanley research note shared with me, the discussion reinforced its Overweight rating on Gilead and singled out one franchise as the biggest reason to stay positive.
Gilead trades around $150.89, up about 24% year to date and roughly 111% over five years. That kind of run in a biotech stock usually needs a catalyst, and Morgan Stanley points to HIV prevention. The bigger question for investors now is whether the new HIV prevention business built around Yeztugo can keep growing at the pace of the last few quarters.
Terence Flynn, a Morgan Stanley equity **** yst who covers Gilead and other healthcare stocks has held an Overweight rating on the stock since January 2025.
According to the note, Gilead management described the company as being at "an important inflection point, supported by what it views as the most robust portfolio in the company's history," with no patent expiring until 2036.
#gilead #healthcare #management #note

1 month ago
Investing in high-yield dividend stocks can be a solid portfolio move and give investors some nice supplemental income. However, not all dividend stocks are created equal. Two dividend stocks I'd be buying now are Energy Transfer (NYSE: ET) and Verizon (NYSE: VZ), while one I would avoid is Pfizer (NYSE: PFE).
Let's take a closer look at each, starting with why I'd avoid investing in Pfizer.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
At one point, Pfizer was as blue chip of a pharmaceutical company as there was. However, the stock's 6.2% yield and cheap valuation reflect a company facing challenges ahead.
Pfizer took on significant debt when it acquired Seagen for $43 billion in December 2023 to strengthen its oncology portfolio. That has left the company with over $60 billion in debt and high interest expenses. The company paid out $9.7 billion in dividends last year while generating $9.1 billion in free cash flow, so it paid out more in dividends than it generated in cash. That has continued through the first six months of 2026.
#NYSE #stocks #missed #high

1 month ago
Xenon Pharmaceuticals (XENE) shares crashed on Friday after the biopharmaceutical firm said it has paused new patient enrollment in its clinical trials evaluating azetukalner. As investors responded to the setback involving XENE's lead drug candidate for major depressive disorder, its relative strength index (RSI) slipped into the early teens, indicating extremely oversold conditions.
Following today's decline, Xenon Pharmaceuticals stock is trading nearly 40% below its year-to-date high.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#xene #following #America


1 month ago
Merck (MRK) stock returned about 87% over the past twelve months, climbing from roughly $79 to about $147. Nothing in the year's results looks like that. The medicines Merck sells today grew at their usual pace. Investors spent the year repricing what comes next.
Revenue over the trailing twelve months was $66.6 billion, up 4.6% and in line with its own three-year pace. Profitability did not follow. Its operating margin over the same twelve months was 10.5%, versus a three-year average of 22.4%.
Most of that gap is one purchase. Merck took a $5.7 billion charge in the second quarter of 2026, about 9% of a year's sales. It bought Terns Pharmaceuticals, and with it MK-4208, a candidate for chronic myeloid leukemia. The bill hits earnings now and the medicine arrives later.
The proof matters because of the risk hanging over this stock. The KEYTRUDA family was just over half of Merck's revenue in the second quarter of 2026. The company is openly planning for the end of that exclusivity when Keytruda loses primary U.S. patent protection in 2028. Management describes the stretch as more of a hill than a cliff, with a shallow dip and a fast return to growth.
Johnson & Johnson (JNJ) returned 56% over the same twelve months and Pfizer (PFE) 23%, so a good year for pharmaceuticals explains some of this but not Merck's lead. What separated Merck was evidence. The FDA approved LIPFENDRA, the first and only oral PCSK9 inhibitor. In the CORALreef Lipids trial it lowered LDL cholesterol by up to 60% when added to a statin.
#year #johnson


1 month ago
For decades, CVS seemed like the perfect business. It was convenient, sold a mix of products people wanted, and everyone was forced to go there (or to one of its rivals) when they needed to pick up a prescription.
Now, however, the company has been fighting a war on many fronts. Consumers can order much of what made the chain convenient for delivery, and various online services, including Amazon, now fill prescriptions.
"At the rear of the store, business at pharmacy counters is being squeezed by stingier drug reimbursement rates and pharmacist wages. In the aisles, sales of everything from greeting cards to cosmetics are feeling the effects of cut-price competition," according to the Financial Times.
It's an evolving situation that has caused CVS rival Rite Aid to shut down all its stores, while CVS and Walgreens have closed thousands of locations between them.
"The whole drugstore four-wall economic model is collapsing on itself, in my opinion," said Josh ****** s, a portfolio manager at Janus Henderson Investors, told the Financial Times.
#business #amazon #walgreens

1 month ago
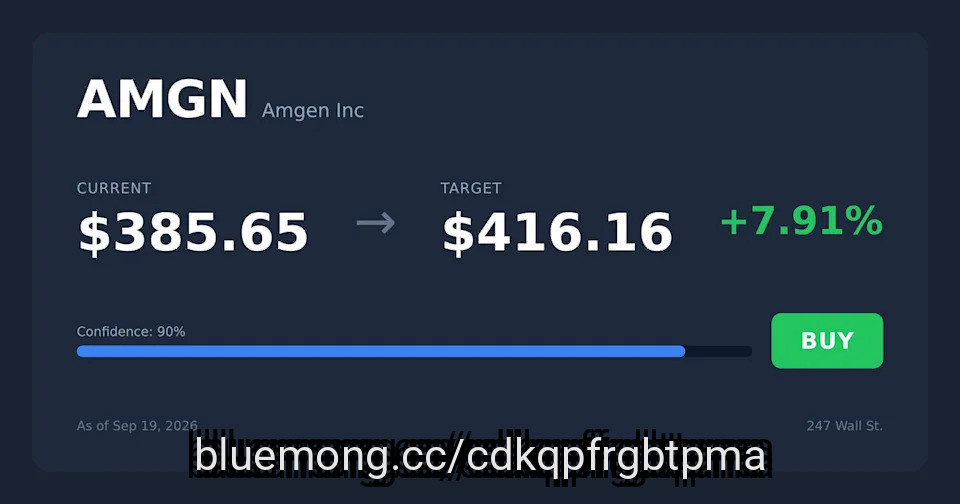
Amgen (AMGN) yields 2.6% with a $10.08 annualized payout, topping Merck (MRK) at 2.29%, and has raised its dividend 6% annually versus Merck's smaller step-ups.
Amgen's 17 billion-dollar products and $3.5B quarterly free cash flow dwarf Merck's reliance on a single Keytruda franchise facing peak penetration.
Merck absorbed a $5.7B acquisition charge that pushed Q2 earnings to a loss, while Amgen raised 2026 EPS guidance to as high as $23.50.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Merck didn't make the cut. Enter your email to see the names that beat MRK. The report is free. Enter your email and see if any of your stocks made the cut.
For a retirement portfolio that leans on pharma dividends, the choice between Amgen (NASDAQ:AMGN) and Merck (NYSE:MRK) comes down to one question: which check is more likely to keep getting bigger through the next wave of patent expirations? Both companies deliver quarterly income today. Only one has the coverage, the growth cadence, and the portfolio breadth to keep raising through the cliff.
#merck #amgen

1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august


1 month ago
On September 15, Jazz Pharmaceuticals plc (NASDAQ:JAZZ) completed its acquisition of privately held Actio Biosciences for $820 million upfront, adding a clinical-stage epilepsy drug called ABS-1230 to its rare disease pipeline. The deal lands weeks after Jazz posted its highest quarterly revenue ever on August 3, and raised its full-year guidance, so a fresh acquisition now sits on top of a business that was already accelerating. The question for investors is whether that combination adds up to durable growth or just a bigger bill.
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta


1 month ago
Ascendis Pharma A/S (NASDAQ:ASND) announced on September 14 that it will regain exclusive rights to develop, manufacture, and commercialize TransCon products in metabolic and cardiovascular diseases following the termination of its collaboration with Novo Nordisk A/S (NYSE:NVO).
The rights include once-monthly TransCon Semaglutide, an investigational long-acting prodrug of semaglutide intended for obesity and type 2 diabetes. Neither party will have continuing financial obligations to the other. Once termination becomes effective and the rights revert, management plans to initiate multiple programs across rare and large indications.
The investment question is whether greater control over future products can justify the resources needed to develop them.
Ascendis Pharma A/S (NASDAQ:ASND) would regain flexibility over which indications to pursue, how quickly to advance candidates, and whether to seek another partner. Successful independent development could retain more of a product's commercial economics, while a new collaboration could provide another way to share costs and risk.
Monthly dosing offers a clear development objective. If clinical studies demonstrate effective treatment with acceptable tolerability, fewer injections could make long-term therapy more convenient. That potential benefit would matter most if it helps patients stay on treatment without sacrificing outcomes.
#ascendis #pharma #asnd #regain


1 month ago
Danish pharmaceutical company Novo Nordisk (NVO) has teamed up with artificial intelligence (AI) leader Anthropic to leverage frontier AI models, including Claude Science, to supercharge its drug discovery and research and development (R&D) operations.
The collaboration aims to address complex biological challenges, streamline software engineering, and compress the timelines required to bring treatments for chronic diseases to market.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
#Stock #danish #science


1 month ago
Avantor (AVTR) exhibits strong technical momentum, recently setting a new year-to-date high.
Shares are up more than 22% over the past year.
AVTR maintains a 100% "Buy" technical opinion from Barchart.
Most ******* ysts see AVTR as undervalued, but I recommend a tight stop loss given its volatility and only moderate fundamental outlook.
Valued at $10.44 billion, Avantor (AVTR) is a provider of critical products and services primarily to the biopharma, healthcare, education, government, advanced technologies, and applied materials industries.
#avantor #year #exhibits


1 month ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus

1 month ago
Walmart and SCAN Health Plan announced a partnership on Wednesday to offer co-branded Medicare Advantage plans in two states, targeting a pool of more than two million Medicare enrollees.
The plans, pending regulatory approval, may include pharmacy, vision, food, and over-the-counter benefits, the companies said. Open enrollment for Medicare Advantage begins Oct. 15, according to MarketWatch.
A central feature of the partnership is Walmart's Everyday Health Signals platform, an AI tool designed to provide personalized nutrition and wellness guidance based on members' shopping preferences and self-reported wellness goals. The companies said they plan to make that capability available to participating plan members as part of broader coaching and wellness support.
"By combining Walmart's technology capabilities and consumer retail expertise with SCAN's Medicare product experience, we have an opportunity to develop products that translate those insights into meaningful support that helps members make more informed choices about their health and well-being," said Zack Myers, national general manager of SCAN Health Plan, in a statement.
Walmart Group Director for Consumer Health and Data Solutions Pravene Nath said the collaboration is distinct because of Walmart's role in customers' everyday lives. "Because customers regularly turn to Walmart for groceries and other everyday essentials, we have an opportunity for those who choose to participate, to use insights from their shopping experiences to make nutrition guidance more relevant and actionable," Nath said in a statement.
#Wellness #members #scan #advantage


1 month ago
Exton, Pennsylvania-based West Pharmaceutical Services, Inc. (WST) designs, manufactures, and sells containment and delivery systems for injectable drugs and healthcare products. Valued at $25.7 billion by market cap, the company's technologies include the design and manufacture of packaging components, research and development of drug delivery systems, and contract laboratory services and other services.
Companies worth $10 billion or more are generally described as "large-cap stocks," and WST perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the medical instruments & supplies industry. WST stands out as a market leader with a diversified portfolio serving pharma and healthcare.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#Stock #billion


1 month ago
Cardinal Health, Inc. (CAH), headquartered in Dublin, Ohio, operates as a healthcare services and products company. Valued at $54.6 billion by market cap, the company's services include pharmaceutical distribution, health-care product manufacturing, distribution and consulting services, drug delivery systems development, pharmaceutical packaging, automated dispensing systems manufacturing, and retail pharmacy franchising.
Companies worth $10 billion or more are generally described as "large-cap stocks," and CAH perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the medical distribution industry. As one of the top three U.S. pharma wholesalers, CAH holds a commanding market position. Its diversified pharmaceutical and medical distribution portfolio, broadens its customer base, adds resilience to market swings, and creates multiple revenue streams with cross-selling opportunities.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#market #Health #Manufacturing #systems



1 month ago
Wolfe Research upgraded two prominent pharmaceutical companies to Outperform on August 13. The firm upgraded both Biogen Inc. (NASDAQ:BIIB) and AbbVie Inc. (NYSE:ABBV)'s ratings from Peer Perform, with Wolfe ***** igning them similar $300 price targets. The firm's logic in each case was based on a comparable set of factors: pipelines that the market appears to undervalue, and valuations that Wolfe believes are too low given each company's growth track.
Wolfe's thesis for Biogen Inc. (NASDAQ:BIIB) is mainly based on late-stage clinical programs, which it believes the stock has yet to reflect. The firm focused on two experimental therapies in particular, both of which have key late-stage clinical readouts expected over the coming year: litifilimab, which Wolfe believes could be the first biologic approved for cutaneous lupus erythematosus, and felzartamab, which the firm claims represents a bigger commercial opportunity in antibody-mediated transplant rejection than Wall Street currently thinks.
Wolfe also cited Biogen's acquisition of Apellis Pharmaceuticals as strengthening its near-term revenue base through the FDA-approved drugs Empaveli and Syfovre. That move is part of an overall pattern of Biogen Inc. (NASDAQ:BIIB) diversifying beyond its core neurology brand, with the company completing its acquisition of RayThera on August 6, adding another early-stage immunology platform to its pipeline.
Wolfe's Biogen Inc. (NASDAQ:BIIB) thesis is incomplete without valuation. The firm believes the stock is trading at a discount to the broader market, despite the company's development on Leqembi, its Alzheimer's medication, and what Wolfe described as solid commercial execution overall.
AbbVie's upgrade is based on a slightly different premise: patent strength and cash generation rather than simple clinical events. Wolfe stated that AbbVie's 2027 earnings multiple of 14.6x seemed too low for a company that forecasts high-single-digit revenue growth for the rest of the decade. AbbVie's patent position, according to Wolfe, sets the company apart from its competitors in a way that the market has yet to completely price in.
#wolfe #firm #market #clinical


1 month ago
Eli Lilly (NYSE: LLY) has been on a historic run over the past five years, outperforming similarly sized peers in the pharmaceutical industry and becoming the first healthcare stock to reach a $1 trillion market cap. The company's diabetes and weight-loss portfolio has been the main engine behind its terrific performance of late, and it remains strong. During the second quarter, Eli Lilly's revenue jumped 48% year over year to $23 billion, while adjusted earnings per share rose 33% year over year to $8.38.
Sales from Eli Lilly's Mounjaro, a diabetes medicine, soared 91% year over year to $9.9 billion, while sales of Zepbound, approved for weight loss and obstructive sleep apnea, grew 46% to $4.9 billion. Can anything stop Eli Lilly's momentum? Here's one thing that might do so.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Eli Lilly generates most of its revenue from Mounjaro and Zepbound, which have the same active ingredient, tirzepatide, a medicine that mimics the action of the GLP-1 and GIP gut hormones. In the second quarter, sales from these two medicines accounted for almost 65% of the company's top line. Eli Lilly also markets Foundayo, an oral GLP-1 approved for weight loss, although it was approved in April and doesn't yet contribute much to its financial results.
Still, the point is that Eli Lilly's lineup is concentrated at the top, with just a couple of brands responsible for most of the recent momentum. Other pharmaceutical giants are well aware of Eli Lilly's GLP-1 success, and they are seeking to launch competing therapies.
#lilly #sales #loss #billion


1 month ago
Pfizer Inc. (NYSE:PFE) and Valneva SE (NASDAQ:VALN) reported on August 14 that the European Medicines Agency has validated the Marketing Authorization Application for PF-07307405, the companies' experimental Lyme disease vaccine candidate, and will now begin the official review.
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#vaccine #pfizer #NYSE

1 month ago
Chemical manufacturer OXEA has selected Uber Freight as its strategic logistics provider across the U.S., Canada, Mexico and Europe as the company moves to consolidate regional transportation operations into a more unified global network.
Houston-based OXEA said Uber Freight will manage day-to-day transportation execution across truckload, rail and ocean freight, using technology, data and logistics services to provide greater visibility across the chemical manufacturer's supply chain.
The agreement represents Uber Freight's (NYSE: UBER) first managed transportation engagement designed from the outset to span the U.S., Canada, Mexico and Europe, according to the companies.
OXEA manufactures oxo intermediates and oxo performance chemicals used in products including coatings, lubricants, cosmetics, pharmaceuticals, flavors and fragrances, printing inks and plastics. The company employs more than 1,200 people and sells chemicals in more than 60 countries.
The partnership is intended to replace a more regionally segmented approach to transportation management with an integrated operation connecting OXEA's plants, carriers and customers.
#Mexico #chemical #Logistics


1 month ago
The Kroger Co. (NYSE:KR) cut its full-year 2026 identical-sales forecast excluding fuel to 0.2%–0.8% from 1%–2%, reflecting a sharper-than-expected slowdown in consumer demand. Second-quarter identical sales rose just 0.2%, down from 3.4% a year earlier and below the 0.9% ****** yst estimate.
The weakness reflects pressure on middle- and lower-income consumers, while a Cyclospora outbreak reduced quarterly identical sales by roughly 35 basis points and Medicare prescription-drug pricing changes created an approximately 140-basis-point headwind for pharmacy revenue. Importantly, Kroger maintained its full-year adjusted FIFO operating-profit forecast of $5.0 billion–$5.2 billion and delivered adjusted EPS of $1.09, ahead of the $1.06 consensus.
The strongest bullish argument is that The Kroger Co. (NYSE:KR) is currently protecting earnings despite the deterioration in sales momentum. Second-quarter adjusted EPS increased 5% year over year to $1.09, while adjusted FIFO operating profit was $1.076 billion. Kroger's gross margin rate actually increased by 13 basis points, although the overall gross-margin percentage was 22.4% versus 22.5% a year earlier, suggesting that pricing, sourcing, and cost-management initiatives are helping offset weaker volumes. The company's higher-margin businesses are also becoming increasingly important: adjusted e-commerce sales grew 20% in the quarter, and Kroger Precision Marketing profit increased 24%. That mix shift gives Kroger an earnings lever even when supermarket traffic and comparable sales are weak.
There is also evidence that management is actively responding to the competitive pressure rather than simply accepting slower growth. CEO Greg Foran has been pursuing tighter sourcing, simpler operations and lower prices, with Reuters reporting plans to cut prices across thousands of products to regain shoppers from Walmart, Costco and Aldi. The Kroger Co. (NYSE:KR)'s balance sheet provides room to fund that strategy: its net debt-to-adjusted-EBITDA ratio was 1.91x, below its stated target range of 2.30x–2.50x, while the company repurchased $1.0 billion of shares in the second quarter and $1.2 billion year to date. It also raised its dividend 11%, marking the 20th consecutive year of increases. If sales stabilize while e-commerce, retail media and cost efficiencies continue expanding, the unchanged $5.0 billion–$5.2 billion operating-profit forecast could prove more important to valuation than the reduced top-line outlook.
#year
1 month ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created ****** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#june
1 month ago
Pfizer Inc. (NYSE:PFE) and Valneva SE (NASDAQ:VALN) reported on August 14 that the European Medicines Agency has validated the Marketing Authorization Application for PF-07307405, the companies' experimental Lyme disease vaccine candidate, and will now begin the official review.
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#disease

1 month ago
Chemical manufacturer OXEA has selected Uber Freight as its strategic logistics provider across the U.S., Canada, Mexico and Europe as the company moves to consolidate regional transportation operations into a more unified global network.
Houston-based OXEA said Uber Freight will manage day-to-day transportation execution across truckload, rail and ocean freight, using technology, data and logistics services to provide greater visibility across the chemical manufacturer's supply chain.
The agreement represents Uber Freight's (NYSE: UBER) first managed transportation engagement designed from the outset to span the U.S., Canada, Mexico and Europe, according to the companies.
OXEA manufactures oxo intermediates and oxo performance chemicals used in products including coatings, lubricants, cosmetics, pharmaceuticals, flavors and fragrances, printing inks and plastics. The company employs more than 1,200 people and sells chemicals in more than 60 countries.
The partnership is intended to replace a more regionally segmented approach to transportation management with an integrated operation connecting OXEA's plants, carriers and customers.
#Transportation #Logistics