4 days ago
On the Sept. 3, 2026 episode of The Ramsey Show, a Houston caller named Nathan asked whether he should use his savings to clear a mortgage he described as a "whatever, 2% mortgage or something." He had about $280,000 left on it and roughly $346,000 in liquid ******* ets, most of it cash and the rest in a taxable brokerage account. Dave Ramsey told him to do it, and to do it that night.
Five months earlier, Ramsey had told a caller in almost the same position the opposite. On April 1, 2026, a web engineer earning around $600,000 a year called in about three weeks after being laid off, sitting on enough cash to clear a San Francisco, California mortgage. "When you're in the middle of a storm, you do temporary things," Ramsey said. "Hold on to the cash. We're not gonna pay off the house because we may not be staying in the house."
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#mortgage #told
Five months earlier, Ramsey had told a caller in almost the same position the opposite. On April 1, 2026, a web engineer earning around $600,000 a year called in about three weeks after being laid off, sitting on enough cash to clear a San Francisco, California mortgage. "When you're in the middle of a storm, you do temporary things," Ramsey said. "Hold on to the cash. We're not gonna pay off the house because we may not be staying in the house."
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#mortgage #told


4 days ago
On September 9, 2026, Apple Inc. (NASDAQ:AAPL) unveiled the iPhone Duo, its first foldable smartphone and the biggest change to the iPhone's design in nearly 20 years, at the first product launch event led by new CEO John Ternus since he succeeded Tim Cook on September 1. The book-style, passport-shaped device opens into a 7.6-inch display, Apple's largest ever, starts at $1,999 for the 256-gigabyte model and rises to $3,199 for 2 terabytes of storage. This makes it the most expensive iPhone Apple has ever sold, with availability set for October 23.
The iPhone Duo gives Apple Inc. (NASDAQ:AAPL) a new premium growth opportunity in a mature smartphone market. Apple entered the foldable market with the $1,999 Duo. It creates a new high-end product category within its largest hardware franchise. ******* ysts expect Apple to take a real share of the foldable market. The firm's brand strength and large installed base could help speed up use of foldable smartphones.
The Duo creates a materially different iPhone experience that could encourage upgrades and attract Android users. The device opens to a 7.6-inch display, supports side-by-side multitasking, and offers a tablet-like experience in a pocketable design. Apple also shows the Duo's ******* anium frame, custom hinge, A20 Pro chip, and Apple Intelligence features. It gives customers several reasons to pay a substantial premium for the new form factor.
The launch solidifies Apple's hardware innovation strategy under new CEO John Ternus. The Duo represents Apple's most significant iPhone redesign since the iPhone X. It gives Ternus an opportunity to reignite enthusiasm around the company's hardware portfolio. The product also expands Apple's ability to monetize its ecosystem through higher-value hardware, services, and accessories as customers spend more time using a larger, more versatile iPhone.
The $1,999 starting price could keep the Duo a niche product. Reuters reported that the global foldable market could account for less than 3% of smartphone sales in 2026. ******* ysts expect only about 6 million Duo units as Apple Inc. (NASDAQ:AAPL) enters the category. Even strong market share would turn into a relatively small contribution compared with Apple's broader iPhone business.
#iphone #aapl
The iPhone Duo gives Apple Inc. (NASDAQ:AAPL) a new premium growth opportunity in a mature smartphone market. Apple entered the foldable market with the $1,999 Duo. It creates a new high-end product category within its largest hardware franchise. ******* ysts expect Apple to take a real share of the foldable market. The firm's brand strength and large installed base could help speed up use of foldable smartphones.
The Duo creates a materially different iPhone experience that could encourage upgrades and attract Android users. The device opens to a 7.6-inch display, supports side-by-side multitasking, and offers a tablet-like experience in a pocketable design. Apple also shows the Duo's ******* anium frame, custom hinge, A20 Pro chip, and Apple Intelligence features. It gives customers several reasons to pay a substantial premium for the new form factor.
The launch solidifies Apple's hardware innovation strategy under new CEO John Ternus. The Duo represents Apple's most significant iPhone redesign since the iPhone X. It gives Ternus an opportunity to reignite enthusiasm around the company's hardware portfolio. The product also expands Apple's ability to monetize its ecosystem through higher-value hardware, services, and accessories as customers spend more time using a larger, more versatile iPhone.
The $1,999 starting price could keep the Duo a niche product. Reuters reported that the global foldable market could account for less than 3% of smartphone sales in 2026. ******* ysts expect only about 6 million Duo units as Apple Inc. (NASDAQ:AAPL) enters the category. Even strong market share would turn into a relatively small contribution compared with Apple's broader iPhone business.
#iphone #aapl

4 days ago
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral


4 days ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer

4 days ago
On September 9, 2026, Reuters reported that Amazon.com, Inc. (NASDAQ:AMZN) raised £4.25 billion, or about $5.76 billion, in its first-ever sterling bond sale, slightly more than initially expected, as part of a four-tranche deal spanning 3 to 19 years. Final investor demand came in at more than £10.65 billion, roughly 2.5 times the amount raised, but that was notably lower than the demand Alphabet saw for its own sterling debut in February, a sign ******* ysts said shows hyperscaler borrowing may be starting to test the limits of investor appetite.
Amazon.com, Inc. (NASDAQ:AMZN)'s first sterling bond sale shows that investors still have a strong appetite for its debt. The firm raised $5.8 billion through the offering, and demand reached roughly 2.5 times the amount available. The sterling market also has relatively limited supply of large technology-company debt. It could back up demand for future Amazon issuance in the currency. Strong demand gives Amazon another funding channel as it finances its large-scale AI and cloud infrastructure investments.
Amazon can put the proceeds toward AWS, its fastest-growing major business. AWS revenue increased 36.7% year over year in the second quarter. It marks its fastest growth rate in 18 quarters as demand for AI infrastructure accelerated. Funding more data centers, computing capacity and related infrastructure could allow Amazon to capture more of that demand. If AWS sustains its growth while making strong operating profits, the additional debt could support investments in one of Amazon's most important long-term earnings drivers.
The sterling offering diversifies Amazon's funding base as its capital requirements grow. Amazon issued four tranches with maturities ranging from three to 19 years. It gives the business access to UK investors while adding sterling financing alongside its existing dollar, euro, Swiss franc and yen debt. This overall investor base gives Amazon greater flexibility to raise capital across different markets and currencies. So diversification could become more valuable as Amazon funds an unprecedented AI infrastructure buildout without relying entirely on one debt market.
Amazon.com, Inc. (NASDAQ:AMZN)'s weaker reception compared with Alphabet signals that investors may demand higher borrowing costs from hyperscalers. Amazon's sterling offering attracted about 2.5 times coverage, below Alphabet's roughly 3.5 times coverage for its recent euro bond sale. The difference shows that demand for hyperscaler debt is not unlimited. If investor appetite continues to weaken, Amazon could face higher yields on future borrowing, increasing the cost of financing its AI infrastructure expansion.
#sterling #infrastructure #NASDAQ #amzn
Amazon.com, Inc. (NASDAQ:AMZN)'s first sterling bond sale shows that investors still have a strong appetite for its debt. The firm raised $5.8 billion through the offering, and demand reached roughly 2.5 times the amount available. The sterling market also has relatively limited supply of large technology-company debt. It could back up demand for future Amazon issuance in the currency. Strong demand gives Amazon another funding channel as it finances its large-scale AI and cloud infrastructure investments.
Amazon can put the proceeds toward AWS, its fastest-growing major business. AWS revenue increased 36.7% year over year in the second quarter. It marks its fastest growth rate in 18 quarters as demand for AI infrastructure accelerated. Funding more data centers, computing capacity and related infrastructure could allow Amazon to capture more of that demand. If AWS sustains its growth while making strong operating profits, the additional debt could support investments in one of Amazon's most important long-term earnings drivers.
The sterling offering diversifies Amazon's funding base as its capital requirements grow. Amazon issued four tranches with maturities ranging from three to 19 years. It gives the business access to UK investors while adding sterling financing alongside its existing dollar, euro, Swiss franc and yen debt. This overall investor base gives Amazon greater flexibility to raise capital across different markets and currencies. So diversification could become more valuable as Amazon funds an unprecedented AI infrastructure buildout without relying entirely on one debt market.
Amazon.com, Inc. (NASDAQ:AMZN)'s weaker reception compared with Alphabet signals that investors may demand higher borrowing costs from hyperscalers. Amazon's sterling offering attracted about 2.5 times coverage, below Alphabet's roughly 3.5 times coverage for its recent euro bond sale. The difference shows that demand for hyperscaler debt is not unlimited. If investor appetite continues to weaken, Amazon could face higher yields on future borrowing, increasing the cost of financing its AI infrastructure expansion.
#sterling #infrastructure #NASDAQ #amzn

4 days ago
California Resources Corporation (NYSE:CRC) announced on September 17 that it had agreed to sell its Uinta Basin **** ets, located mostly in Utah and Colorado, to an undisclosed buyer for $90 million in cash. The company had come to own the Uinta **** ets, which span about 100,000 net acres, after it acquired Berry Corp last year. However, CRC considered them non-core to its operations. The net proceeds from the sale will be used for shareholder returns and other corporate purposes.
Francisco Leon, President and CEO of California Resources Corporation, commented:
"Today's transaction strengthens our business. The monetization of our Uinta Basin **** ets sharpens our focus on California and captures additional value from the Berry merger. This transaction enhances our capital allocation flexibility, allowing us to invest in higher-return opportunities within the Golden State and supports our shareholder return strategy. The sale also helps offset the purchase price of our recent midstream transaction."
The transaction is expected to close by year-end, subject to the receipt of certain third-party consents and other customary conditions.
The sale will allow CRC to redeploy the $90 million toward **** ets that are central to its operating strategy while avoiding additional capital commitments to Uinta. The company already stated in its Q2 earnings call that Uinta has higher capital intensity, higher break-evens, lower crude quality, higher transportation and operating costs, and steeper declines. Therefore, the sale removes a portfolio distraction at a time when CRC is concentrating investment in California infrastructure and production.
#uinta #assets #transaction #capital
Francisco Leon, President and CEO of California Resources Corporation, commented:
"Today's transaction strengthens our business. The monetization of our Uinta Basin **** ets sharpens our focus on California and captures additional value from the Berry merger. This transaction enhances our capital allocation flexibility, allowing us to invest in higher-return opportunities within the Golden State and supports our shareholder return strategy. The sale also helps offset the purchase price of our recent midstream transaction."
The transaction is expected to close by year-end, subject to the receipt of certain third-party consents and other customary conditions.
The sale will allow CRC to redeploy the $90 million toward **** ets that are central to its operating strategy while avoiding additional capital commitments to Uinta. The company already stated in its Q2 earnings call that Uinta has higher capital intensity, higher break-evens, lower crude quality, higher transportation and operating costs, and steeper declines. Therefore, the sale removes a portfolio distraction at a time when CRC is concentrating investment in California infrastructure and production.
#uinta #assets #transaction #capital

4 days ago
Morgan Stanley met privately with Gilead Sciences (GILD) leadership at its 2026 Global Healthcare Conference this month, and the feedback strengthened the bank's positive view on the stock.
Morgan Stanley's biopharma team hosted a meeting and a management dinner with Gilead Chairman and CEO Daniel O'Day and Chief Commercial and Corporate Affairs Officer Johanna Mercier. According to a Morgan Stanley research note shared with me, the discussion reinforced its Overweight rating on Gilead and singled out one franchise as the biggest reason to stay positive.
Gilead trades around $150.89, up about 24% year to date and roughly 111% over five years. That kind of run in a biotech stock usually needs a catalyst, and Morgan Stanley points to HIV prevention. The bigger question for investors now is whether the new HIV prevention business built around Yeztugo can keep growing at the pace of the last few quarters.
Terence Flynn, a Morgan Stanley equity **** yst who covers Gilead and other healthcare stocks has held an Overweight rating on the stock since January 2025.
According to the note, Gilead management described the company as being at "an important inflection point, supported by what it views as the most robust portfolio in the company's history," with no patent expiring until 2036.
#gilead #healthcare #management #note
Morgan Stanley's biopharma team hosted a meeting and a management dinner with Gilead Chairman and CEO Daniel O'Day and Chief Commercial and Corporate Affairs Officer Johanna Mercier. According to a Morgan Stanley research note shared with me, the discussion reinforced its Overweight rating on Gilead and singled out one franchise as the biggest reason to stay positive.
Gilead trades around $150.89, up about 24% year to date and roughly 111% over five years. That kind of run in a biotech stock usually needs a catalyst, and Morgan Stanley points to HIV prevention. The bigger question for investors now is whether the new HIV prevention business built around Yeztugo can keep growing at the pace of the last few quarters.
Terence Flynn, a Morgan Stanley equity **** yst who covers Gilead and other healthcare stocks has held an Overweight rating on the stock since January 2025.
According to the note, Gilead management described the company as being at "an important inflection point, supported by what it views as the most robust portfolio in the company's history," with no patent expiring until 2036.
#gilead #healthcare #management #note
5 days ago
With a market cap. of $13.4 billion, McCormick & Company, Incorporated (MKC) is a global leader in flavor, manufacturing and distributing herbs, spices, seasonings, condiments, and flavors across 150 countries and territories. Its portfolio includes well-known brands such as McCormick, French's, Frank's RedHot, OLD BAY, Cholula, and Gourmet Garden, serving retailers, food manufacturers, and foodservice businesses.
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and McCormick comfortably fits this category. Headquartered in Hunt Valley, Maryland, McCormick operates through its Consumer and Flavor Solutions segments, leveraging its global scale, expertise, and technology to support sustainable growth.
Elon Musk, Who Became the World's First Trillionaire, Still Sleeps in a Tiny $50,000 House Where His Mom Uses the Garage — 'It's Kinda Awesome Though'
How to Play AMZN Stock as Amazon Unveils Project Mercury
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#mccormick #gourmet
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and McCormick comfortably fits this category. Headquartered in Hunt Valley, Maryland, McCormick operates through its Consumer and Flavor Solutions segments, leveraging its global scale, expertise, and technology to support sustainable growth.
Elon Musk, Who Became the World's First Trillionaire, Still Sleeps in a Tiny $50,000 House Where His Mom Uses the Garage — 'It's Kinda Awesome Though'
How to Play AMZN Stock as Amazon Unveils Project Mercury
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#mccormick #gourmet



5 days ago
Gov. Gavin Newsom on Saturday signed legislation to increase security for the state's voting systems and protect Californians' ability to cast ballots in an effort to guard against potential interference in the Nov. 3 election, including by the Trump administration.
Newsom pointed to the Trump administration's recent effort to restrict mail-in voting through the U.S. Postal Service, which was struck down by the U.S. Supreme Court, and the presence of federal monitors at California polls last year as evidence that Trump "will continue his efforts to interfere with the November election."
"Donald Trump won't stop until he can exert dictatorial control over your free vote and disenfranchise millions of people this November. California will stop him at every opportunity," Newsom said in a statement. "We have no bigger task than fighting to protect the right to vote from interference and meddling — the future of democracy is on the line. These bills today build upon the wall California has built to safeguard our electoral process."
The governor signed the package of bills at the ****** anese American National Museum in Little Tokyo, where a year earlier federal agents gathered outside a political rally he was hosting. Then-Border Patrol Sector Chief Gregory Bovino, who had been leading the immigration operations in California, was among those outside the event, joined by agents in helmets, camouflage, masks and holding guns. Newsom described their presence as political intimidation.
One bill Newsom signed Saturday cites efforts to "weaponize law enforcement authority for political purposes," including Republican "Sheriff Chad Bianco's seizure of ballots in Riverside County," and the election monitors sent by the U.S. Justice Department to polling sites in five counties during a 2025 special election on redistricting.
#political
Newsom pointed to the Trump administration's recent effort to restrict mail-in voting through the U.S. Postal Service, which was struck down by the U.S. Supreme Court, and the presence of federal monitors at California polls last year as evidence that Trump "will continue his efforts to interfere with the November election."
"Donald Trump won't stop until he can exert dictatorial control over your free vote and disenfranchise millions of people this November. California will stop him at every opportunity," Newsom said in a statement. "We have no bigger task than fighting to protect the right to vote from interference and meddling — the future of democracy is on the line. These bills today build upon the wall California has built to safeguard our electoral process."
The governor signed the package of bills at the ****** anese American National Museum in Little Tokyo, where a year earlier federal agents gathered outside a political rally he was hosting. Then-Border Patrol Sector Chief Gregory Bovino, who had been leading the immigration operations in California, was among those outside the event, joined by agents in helmets, camouflage, masks and holding guns. Newsom described their presence as political intimidation.
One bill Newsom signed Saturday cites efforts to "weaponize law enforcement authority for political purposes," including Republican "Sheriff Chad Bianco's seizure of ballots in Riverside County," and the election monitors sent by the U.S. Justice Department to polling sites in five counties during a 2025 special election on redistricting.
#political


5 days ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Humanoid robots are showing meaningful progress beyond controlled demonstrations, with advances in autonomy, dexterity, and the ability to perform repetitive real-world tasks. But widespread commercial deployment still remains a work in progress.
After spending a week meeting with leading robotics labs, engineers and investors across the San Francisco Bay Area, researchers found that most humanoid robots remain in development, training, and tele-operated demonstrations. Where real-world deployments exist, they are generally closer to pilots than clear return-on-investment opportunities, according to a report published Wednesday by Citrini Research.
Don't Miss:
A single bad hire can set a startup back years. Here are the 5 hires founders most often misjudge — and why
#robots
Humanoid robots are showing meaningful progress beyond controlled demonstrations, with advances in autonomy, dexterity, and the ability to perform repetitive real-world tasks. But widespread commercial deployment still remains a work in progress.
After spending a week meeting with leading robotics labs, engineers and investors across the San Francisco Bay Area, researchers found that most humanoid robots remain in development, training, and tele-operated demonstrations. Where real-world deployments exist, they are generally closer to pilots than clear return-on-investment opportunities, according to a report published Wednesday by Citrini Research.
Don't Miss:
A single bad hire can set a startup back years. Here are the 5 hires founders most often misjudge — and why
#robots


5 days ago
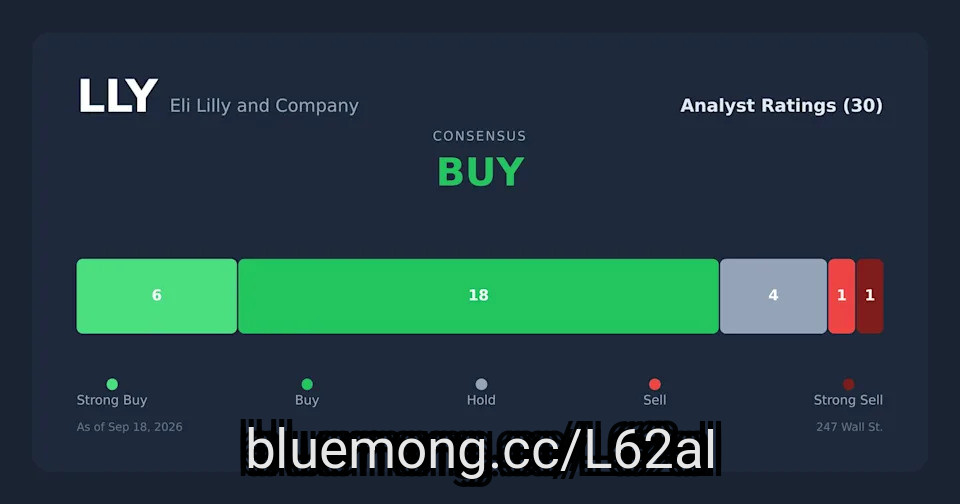
Eli Lilly presents mid-stage eloraTZP data September 30, and LLY stock near $1,152 with a $1 trillion market cap leaves no room for a weak result.
Novo Nordisk's GLP-1 franchise faces headwinds while Viking Therapeutics' VK2735 looms; a convincing eloraTZP win raises the bar for both rivals.
Bearish options positioning shows put/call ratios hitting 4.67 for October 9 expiry, signaling Wall Street is hedging hard against disappointment.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Eli Lilly didn't make the cut. Enter your email to see the names that beat LLY. The report is free. Enter your email and see if any of your stocks made the cut.
Eli Lilly (NYSE:LLY) presents mid-stage data on eloraTZP, a combination of eloralintide and tirzepatide, at a European **** ociation for the Study of Diabetes symposium on September 30.
#eloratzp #september #Stock
Novo Nordisk's GLP-1 franchise faces headwinds while Viking Therapeutics' VK2735 looms; a convincing eloraTZP win raises the bar for both rivals.
Bearish options positioning shows put/call ratios hitting 4.67 for October 9 expiry, signaling Wall Street is hedging hard against disappointment.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Eli Lilly didn't make the cut. Enter your email to see the names that beat LLY. The report is free. Enter your email and see if any of your stocks made the cut.
Eli Lilly (NYSE:LLY) presents mid-stage data on eloraTZP, a combination of eloralintide and tirzepatide, at a European **** ociation for the Study of Diabetes symposium on September 30.
#eloratzp #september #Stock

5 days ago
SailPoint Inc. (NASDAQ:SAIL), a leading player within the enterprise identity security ****** e, recently expanded its strategic alliance with CrowdStrike. As part of the revised arrangement, the company's SailPoint SecOps Identity Intelligence will be integrated with CrowdStrike Falcon Next-Gen SIEM. This will help in expediting threat detection procedures, and will also incorporate access data and identity governance into the overall investigation process. The expanded partnership will facilitate security teams in lining up the identity insights with Falcon's existing security telemetry.
Copyright: franckito / 123RF Stock Photo
The announcement aligns strongly with SailPoint's broader strategic narrative revealed in its Q2 FY27 print. It builds upon several recent initiatives undertaken by the management, such as introduction of the SailPoint Identity Security solution. This is aimed toward integrating SailPoint Agentic Fabric with SailPoint Human Fabric for real-time discovery and security of complex digital ecosystems. The company also launched its Cursor Enterprise connector, which helps organizations to leverage a highly-integrated control plane to manage human developers and autonomous AI agents.
The recently released financials also back this narrative as the company delivered a 25% year-over-year growth in its annual recurring revenue, which stood at $1.231 billion. SailPoint generated $45 million in operating cash flow during the second quarter, along with $37 million in free cash flow.
By weaving SailPoint's identity intelligence into Falcon Next-Gen SIEM, customers gain extra context inside workflows they already rely on, making it easier to probe identity-related risks. The integration augments SailPoint's position at a time when identity threats are on a rise. This leads to an opportunity for SailPoint to cement itself as a leading provider of advanced security solutions.
#sailpoint #falcon #next
Copyright: franckito / 123RF Stock Photo
The announcement aligns strongly with SailPoint's broader strategic narrative revealed in its Q2 FY27 print. It builds upon several recent initiatives undertaken by the management, such as introduction of the SailPoint Identity Security solution. This is aimed toward integrating SailPoint Agentic Fabric with SailPoint Human Fabric for real-time discovery and security of complex digital ecosystems. The company also launched its Cursor Enterprise connector, which helps organizations to leverage a highly-integrated control plane to manage human developers and autonomous AI agents.
The recently released financials also back this narrative as the company delivered a 25% year-over-year growth in its annual recurring revenue, which stood at $1.231 billion. SailPoint generated $45 million in operating cash flow during the second quarter, along with $37 million in free cash flow.
By weaving SailPoint's identity intelligence into Falcon Next-Gen SIEM, customers gain extra context inside workflows they already rely on, making it easier to probe identity-related risks. The integration augments SailPoint's position at a time when identity threats are on a rise. This leads to an opportunity for SailPoint to cement itself as a leading provider of advanced security solutions.
#sailpoint #falcon #next

5 days ago
Volkswagen cut its 2026 operating-margin forecast to no more than 1 per cent, down from a previous range of 4 to 5.5 per cent.
Approximately €10 billion in special charges includes a €6 billion non-cash impairment connected with Porsche.
Volkswagen maintained its cash-flow outlook, but the downgrade highlights deeper pressure from China, restructuring costs and lower-margin electric vehicles.
Volkswagen AG (OTC:VWAGY) shares suffered their sharpest decline in months after the German automaker warned that Porsche's deteriorating outlook and additional restructuring costs would substantially reduce its 2026 profit.
Volkswagen's preferred shares fell as much as 7.5 per cent in Frankfurt on Friday before closing 5.6 per cent lower. Shares of Porsche AG declined 3.3 per cent, while Volkswagen's largest shareholder, Porsche Automobil Holding SE, lost 4.9 per cent.
#volkswagen #Margin #billion
Approximately €10 billion in special charges includes a €6 billion non-cash impairment connected with Porsche.
Volkswagen maintained its cash-flow outlook, but the downgrade highlights deeper pressure from China, restructuring costs and lower-margin electric vehicles.
Volkswagen AG (OTC:VWAGY) shares suffered their sharpest decline in months after the German automaker warned that Porsche's deteriorating outlook and additional restructuring costs would substantially reduce its 2026 profit.
Volkswagen's preferred shares fell as much as 7.5 per cent in Frankfurt on Friday before closing 5.6 per cent lower. Shares of Porsche AG declined 3.3 per cent, while Volkswagen's largest shareholder, Porsche Automobil Holding SE, lost 4.9 per cent.
#volkswagen #Margin #billion
5 days ago
Incredible footage of a tornado scraping along a mountaintop near Fruit Heights, Utah, on Friday surfaced online, with reports of the twister occurring at an elevation of about 7,500 feet (almost 2,300 metres).
When you're living near a mountainside, one of the last things you would expect to see moving fast at higher elevations would be a tornado, but that's what happened in Utah on Friday.
According to the Salt Lake City, Utah, branch of the U.S. National Weather Service (NWS), a rare, strong twister occurred near Fruit Heights, Utah. The funnel first made contact with the ground near a summit along the ridgeline extending west from Francis Peak, at an elevation of about 7,500 feet (almost 2,300 metres).
Tornadoes are uncommon at very high elevation due to drier air and less favourable thunderstorm dynamics.
#elevation #heights #tornado #twister
When you're living near a mountainside, one of the last things you would expect to see moving fast at higher elevations would be a tornado, but that's what happened in Utah on Friday.
According to the Salt Lake City, Utah, branch of the U.S. National Weather Service (NWS), a rare, strong twister occurred near Fruit Heights, Utah. The funnel first made contact with the ground near a summit along the ridgeline extending west from Francis Peak, at an elevation of about 7,500 feet (almost 2,300 metres).
Tornadoes are uncommon at very high elevation due to drier air and less favourable thunderstorm dynamics.
#elevation #heights #tornado #twister

5 days ago
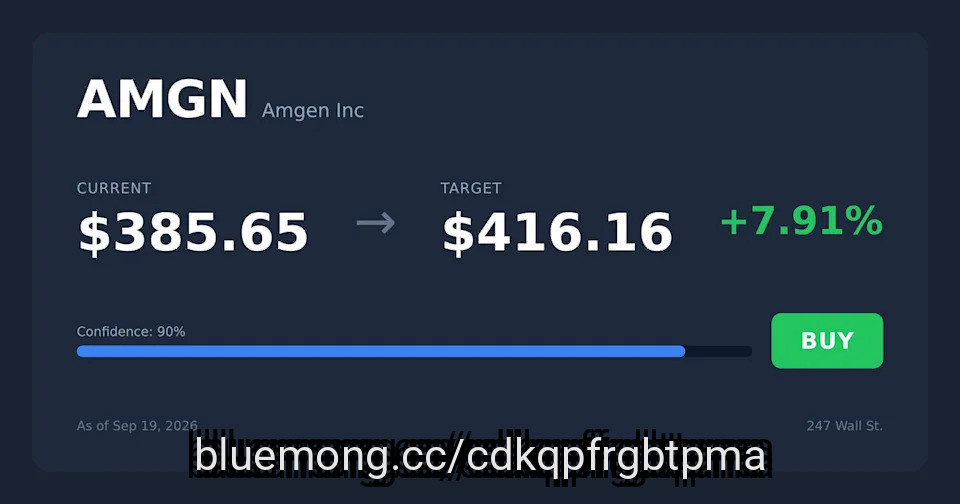
Amgen (AMGN) yields 2.6% with a $10.08 annualized payout, topping Merck (MRK) at 2.29%, and has raised its dividend 6% annually versus Merck's smaller step-ups.
Amgen's 17 billion-dollar products and $3.5B quarterly free cash flow dwarf Merck's reliance on a single Keytruda franchise facing peak penetration.
Merck absorbed a $5.7B acquisition charge that pushed Q2 earnings to a loss, while Amgen raised 2026 EPS guidance to as high as $23.50.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Merck didn't make the cut. Enter your email to see the names that beat MRK. The report is free. Enter your email and see if any of your stocks made the cut.
For a retirement portfolio that leans on pharma dividends, the choice between Amgen (NASDAQ:AMGN) and Merck (NYSE:MRK) comes down to one question: which check is more likely to keep getting bigger through the next wave of patent expirations? Both companies deliver quarterly income today. Only one has the coverage, the growth cadence, and the portfolio breadth to keep raising through the cliff.
#merck #amgen
Amgen's 17 billion-dollar products and $3.5B quarterly free cash flow dwarf Merck's reliance on a single Keytruda franchise facing peak penetration.
Merck absorbed a $5.7B acquisition charge that pushed Q2 earnings to a loss, while Amgen raised 2026 EPS guidance to as high as $23.50.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Merck didn't make the cut. Enter your email to see the names that beat MRK. The report is free. Enter your email and see if any of your stocks made the cut.
For a retirement portfolio that leans on pharma dividends, the choice between Amgen (NASDAQ:AMGN) and Merck (NYSE:MRK) comes down to one question: which check is more likely to keep getting bigger through the next wave of patent expirations? Both companies deliver quarterly income today. Only one has the coverage, the growth cadence, and the portfolio breadth to keep raising through the cliff.
#merck #amgen


5 days ago
The State Department's approval of two potential arms sales to Saudi Arabia totaling $5.75 billion, including JDAM-ER munitions and AGT-1500 tank engines, offers a modest but meaningful data point for two very different defense players. For The Boeing Company (NYSE:BA), the potential sale represents an additional international defense opportunity as the company continues working through margin pressure elsewhere. For Honeywell Aerospace Inc. (NASDAQ:HONA), the package reinforces a stable business line while the firm tackles its first quarter as a standalone public company.
The State Department approved a potential $5 billion sale of JDAM-ER guidance kits and bombs to Saudi Arabia, along with a separate potential $750 million deal for AGT-1500 tank engines. The JDAM package consists of 5,004 KMU-572 and 5,000 KMU-556 JDAM guidance kits and 5,004 BLU-111 and 5,000 BLU-117 bombs. Boeing has been identified as the principal contractor for the JDAM-ERs, with Honeywell handling the engines. The State Department said the sales would strengthen Saudi Arabia's airborne defense capabilities and improve interoperability with U.S. and Gulf partner forces.
Boeing stands to gain only modestly from the deal, given its roughly $85 billion Defense, ******* e and Security backlog. International orders already account for 27% of that total. The segment reported a second-quarter operating loss, largely due to charges tied to the VC-25B (Air Force One) program. That makes mature, lower-risk munitions programs such as JDAM-ER a more dependable part of the portfolio, though the deal is unlikely to have a meaningful impact on margins. For Honeywell Aerospace, the contract is smaller, but the AGT-1500 fits within its established defense propulsion business. It also adds to the company's international defence business, which makes up about 30% of its total Defense and ******* e revenue.
Honeywell Aerospace is owned by 74 hedge funds as of Q2 2026, which is consistent with Honeywell (NASDAQ:HON) hedge fund ownership prior to the spinoff. Unlike Honeywell, the number of hedge funds holding Boeing stock dropped from 99 at the end of the first quarter of fiscal 2026 to 90 at the end of Q2 2026.
Neither potential sale is large enough to have a meaningful impact on either company's short-term results by itself. Still, each supports a different investment story. For Boeing, the potential sales add to international defense exposure if finalized, as its defense unit continues dealing with fixed-price losses. For Honeywell, they support the steady flow of high-margin legacy revenue across its broader defense franchise.
#international #saudi
The State Department approved a potential $5 billion sale of JDAM-ER guidance kits and bombs to Saudi Arabia, along with a separate potential $750 million deal for AGT-1500 tank engines. The JDAM package consists of 5,004 KMU-572 and 5,000 KMU-556 JDAM guidance kits and 5,004 BLU-111 and 5,000 BLU-117 bombs. Boeing has been identified as the principal contractor for the JDAM-ERs, with Honeywell handling the engines. The State Department said the sales would strengthen Saudi Arabia's airborne defense capabilities and improve interoperability with U.S. and Gulf partner forces.
Boeing stands to gain only modestly from the deal, given its roughly $85 billion Defense, ******* e and Security backlog. International orders already account for 27% of that total. The segment reported a second-quarter operating loss, largely due to charges tied to the VC-25B (Air Force One) program. That makes mature, lower-risk munitions programs such as JDAM-ER a more dependable part of the portfolio, though the deal is unlikely to have a meaningful impact on margins. For Honeywell Aerospace, the contract is smaller, but the AGT-1500 fits within its established defense propulsion business. It also adds to the company's international defence business, which makes up about 30% of its total Defense and ******* e revenue.
Honeywell Aerospace is owned by 74 hedge funds as of Q2 2026, which is consistent with Honeywell (NASDAQ:HON) hedge fund ownership prior to the spinoff. Unlike Honeywell, the number of hedge funds holding Boeing stock dropped from 99 at the end of the first quarter of fiscal 2026 to 90 at the end of Q2 2026.
Neither potential sale is large enough to have a meaningful impact on either company's short-term results by itself. Still, each supports a different investment story. For Boeing, the potential sales add to international defense exposure if finalized, as its defense unit continues dealing with fixed-price losses. For Honeywell, they support the steady flow of high-margin legacy revenue across its broader defense franchise.
#international #saudi


5 days ago
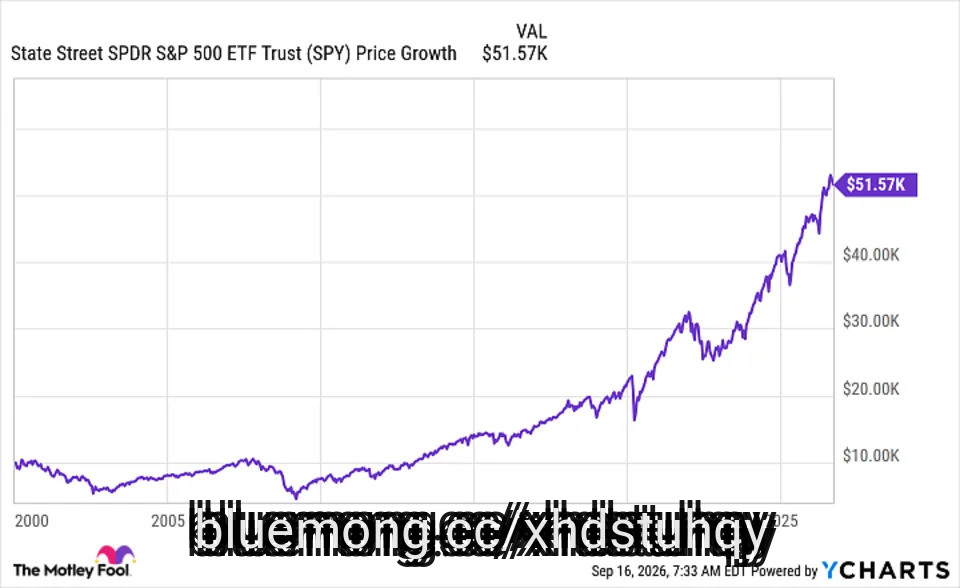
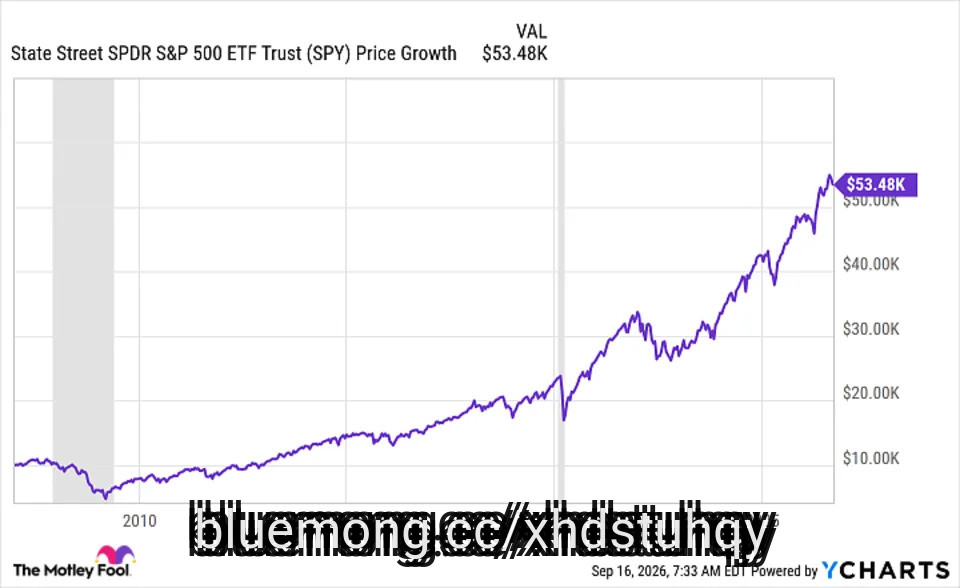
Wall Street pays a huge amount of attention to the price movements of the S&P 500 index (SNPINDEX: ^GSPC). If stocks are in a bull market, everyone wants to know when the next bear market will arrive. If there's a bear market, everyone keeps an eye out for the sign that the next bull market has come along. History shows you should ignore Wall Street and focus on a long-term plan of saving and investing, no matter what the market is doing.
World-famous investor and Wall Street icon Warren Buffett has often said that most investors would be better off buying an S&P 500 index fund, such as SPDR S&P 500 Trust (NYSEMKT: SPY) or Vanguard S&P 500 ETF (NYSEMKT: VOO), than trying to buy individual stocks. The real purpose of this is to create a simple, diversified portfolio that allows the investor to focus their attention on saving money and, frankly, living a happy life.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
That said, a key part of Buffett's investment advice is that you should keep buying the S&P 500 no matter what is happening with the market. That's called dollar-cost averaging. You should also reinvest your dividends, which allows the dividends to compound over time. Both are simple, but powerful wealth-building tools.
SPY data by YCharts
#stocks
World-famous investor and Wall Street icon Warren Buffett has often said that most investors would be better off buying an S&P 500 index fund, such as SPDR S&P 500 Trust (NYSEMKT: SPY) or Vanguard S&P 500 ETF (NYSEMKT: VOO), than trying to buy individual stocks. The real purpose of this is to create a simple, diversified portfolio that allows the investor to focus their attention on saving money and, frankly, living a happy life.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
That said, a key part of Buffett's investment advice is that you should keep buying the S&P 500 no matter what is happening with the market. That's called dollar-cost averaging. You should also reinvest your dividends, which allows the dividends to compound over time. Both are simple, but powerful wealth-building tools.
SPY data by YCharts
#stocks


6 days ago
On September 15, Jazz Pharmaceuticals plc (NASDAQ:JAZZ) completed its acquisition of privately held Actio Biosciences for $820 million upfront, adding a clinical-stage epilepsy drug called ABS-1230 to its rare disease pipeline. The deal lands weeks after Jazz posted its highest quarterly revenue ever on August 3, and raised its full-year guidance, so a fresh acquisition now sits on top of a business that was already accelerating. The question for investors is whether that combination adds up to durable growth or just a bigger bill.
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta

6 days ago
Picture a snowy mountain slope in France or an elite tennis court during a grand slam. Whether it is an Arc'teryx jacket designed for the harshest alpine conditions or a Wilson racket in the hands of a professional, Amer Sports (NYSE:AS) equips the world's most demanding athletes. The company functions as a global powerhouse in athletic gear and apparel, operating a premium multi-brand platform that spans from high-end technical clothing to specialized sports equipment. With its current stock price at $27.26 as of Sept. 16, 2026, the company has seen the stock decline 26% over the past year, reflecting the market's digestion of its rapid post-IPO scaling.
Our proprietary Hidden Gems scoring system **** igns Amer Sports an overall Superscore of 75 out of 100, placing it in the Above Average category. This score ranks the company in the Top ~21% of every company we evaluate, ahead of roughly 79 out of every 100 firms we score. The Superscore serves as a data-driven starting point, and this article examines both the operational momentum fueling its recent success and the structural hurdles that keep the company below top-tier rankings, helping you weigh these signals against your own research.
Strong revenue momentum: The company achieved 27% year-over-year revenue growth in 2025, reaching $6.6 billion as it successfully scaled its brand-led platform across global markets.
Effective channel pivot: Direct-to-consumer revenue surged 43% in 2025, allowing the company to capture higher margins and deepen its direct relationship with premium consumers.
Expanding operational efficiency: Adjusted EBITDA margins widened to 18% in 2025, demonstrating that the company's shared infrastructure strategy is successfully converting scale into bottom-line profitability.
#company #sports #global #premium
Our proprietary Hidden Gems scoring system **** igns Amer Sports an overall Superscore of 75 out of 100, placing it in the Above Average category. This score ranks the company in the Top ~21% of every company we evaluate, ahead of roughly 79 out of every 100 firms we score. The Superscore serves as a data-driven starting point, and this article examines both the operational momentum fueling its recent success and the structural hurdles that keep the company below top-tier rankings, helping you weigh these signals against your own research.
Strong revenue momentum: The company achieved 27% year-over-year revenue growth in 2025, reaching $6.6 billion as it successfully scaled its brand-led platform across global markets.
Effective channel pivot: Direct-to-consumer revenue surged 43% in 2025, allowing the company to capture higher margins and deepen its direct relationship with premium consumers.
Expanding operational efficiency: Adjusted EBITDA margins widened to 18% in 2025, demonstrating that the company's shared infrastructure strategy is successfully converting scale into bottom-line profitability.
#company #sports #global #premium

6 days ago
Financially challenged fast-food franchisees have been lining up to file for bankruptcy protection in 2026 to reorganize their businesses and restructure debt.
Hardee's Phoenix-based restaurant franchisee Superior Star LLC , filed for Chapter 11 bankruptcy protection on July 9, facing an alleged seller financing dispute, according to court papers. A burger chain rival, Checkers Drive-In franchisee C.S. Holdings of Tampa LLC, which operates two locations in Tampa, Fla., filed for Chapter 11 bankruptcy protection to reorganize its business on July 14.
Another Hardee's franchisee, ARC Burger LLC, filed for Chapter 7 bankruptcy liquidation on April 20, 2026, after franchisor Hardee's Restaurants LLC sued the restaurant operator for alleged breach of contract, seeking to recover over $6.5 million in unpaid franchise fees and other obligations, according to Law.com.
And now, major Wendy's restaurant franchisee Meritage Hospitality Group Inc., which operates over 350 locations in 15 states, filed for Chapter 11 bankruptcy to reorganize its business and restructure its debt, almost 11 months after defaulting on its franchise agreements for failing to remit payments.
Meritage Hospitality and 14 affiliates filed their petition in the U.S. Bankruptcy Court for the Western District of Michigan on Sept. 17, 2026, listing $10 million to $50 million in **** ets and debts.
#chapter
Hardee's Phoenix-based restaurant franchisee Superior Star LLC , filed for Chapter 11 bankruptcy protection on July 9, facing an alleged seller financing dispute, according to court papers. A burger chain rival, Checkers Drive-In franchisee C.S. Holdings of Tampa LLC, which operates two locations in Tampa, Fla., filed for Chapter 11 bankruptcy protection to reorganize its business on July 14.
Another Hardee's franchisee, ARC Burger LLC, filed for Chapter 7 bankruptcy liquidation on April 20, 2026, after franchisor Hardee's Restaurants LLC sued the restaurant operator for alleged breach of contract, seeking to recover over $6.5 million in unpaid franchise fees and other obligations, according to Law.com.
And now, major Wendy's restaurant franchisee Meritage Hospitality Group Inc., which operates over 350 locations in 15 states, filed for Chapter 11 bankruptcy to reorganize its business and restructure its debt, almost 11 months after defaulting on its franchise agreements for failing to remit payments.
Meritage Hospitality and 14 affiliates filed their petition in the U.S. Bankruptcy Court for the Western District of Michigan on Sept. 17, 2026, listing $10 million to $50 million in **** ets and debts.
#chapter


6 days ago
On September 8, 2026, CNBC reported that Novartis AG (NYSE:NVS) shares fell about 10% after the company said its experimental drug del-desiran failed to meet its primary goal in a late-stage trial for myotonic dystrophy type 1.
It marked the company's third clinical setback in a week following the earlier failure of cardiovascular drug pelacarsen and a separate pause of eight trials of cell therapy rap-cel after three patient deaths. The decline erased roughly 24 billion Swiss francs, or about $29.6 billion, in market value and put Novartis on pace for one of its worst trading days in company history.
Remibrutinib provides a major remaining pipeline catalyst since Novartis AG (NYSE:NVS) reported successful late-stage results for remibrutinib in multiple sclerosis. It gives investors a credible growth driver after the failures of pelacarsen and del-desiran. The business expects more remibrutinib data later this year, making the drug an important test of whether its remaining pipeline can help long-term growth.
Novartis still expects 5% to 6% annual sales growth through 2030. Management reaffirmed its full-year financial guidance and maintained its target for 5% to 6% compound annual sales growth from 2025 through 2030. That guidance shows the company still expects its overall portfolio and remaining pipeline ******* ets to offset pressure from aging drugs.
The company retains a diversified commercial portfolio. The del-desiran failure removes a potentially important future revenue contributor, but Novartis still makes substantial revenue from its existing medicines. It also retains other pipeline ******* ets. That diversification gives the firm financial capacity to absorb individual clinical failures while it rebuilds investor confidence in its growth pipeline.
#company #remibrutinib
It marked the company's third clinical setback in a week following the earlier failure of cardiovascular drug pelacarsen and a separate pause of eight trials of cell therapy rap-cel after three patient deaths. The decline erased roughly 24 billion Swiss francs, or about $29.6 billion, in market value and put Novartis on pace for one of its worst trading days in company history.
Remibrutinib provides a major remaining pipeline catalyst since Novartis AG (NYSE:NVS) reported successful late-stage results for remibrutinib in multiple sclerosis. It gives investors a credible growth driver after the failures of pelacarsen and del-desiran. The business expects more remibrutinib data later this year, making the drug an important test of whether its remaining pipeline can help long-term growth.
Novartis still expects 5% to 6% annual sales growth through 2030. Management reaffirmed its full-year financial guidance and maintained its target for 5% to 6% compound annual sales growth from 2025 through 2030. That guidance shows the company still expects its overall portfolio and remaining pipeline ******* ets to offset pressure from aging drugs.
The company retains a diversified commercial portfolio. The del-desiran failure removes a potentially important future revenue contributor, but Novartis still makes substantial revenue from its existing medicines. It also retains other pipeline ******* ets. That diversification gives the firm financial capacity to absorb individual clinical failures while it rebuilds investor confidence in its growth pipeline.
#company #remibrutinib
6 days ago
On September 7, 2026, Reuters reported that Novo Nordisk A/S (NYSE:NVO) halted two additional trials of its experimental cardiovascular drug ziltivekimab, further denting the Danish drugmaker's efforts to diversify beyond its blockbuster obesity and diabetes franchise.
The move follows a July disclosure that ziltivekimab failed to reduce major adverse cardiovascular events in a late-stage trial. An independent data monitoring committee found a "low likelihood" that the two additional heart-failure studies would produce a different result from that earlier failure, prompting Novo to end them ahead of schedule.
Novo Nordisk A/S (NYSE:NVO) still has one opportunity to create value from its cardiovascular program. The company will continue testing ziltivekimab in patients recovering from a heart attack, with results expected in the first half of 2027. A successful outcome could give Novo another growth opportunity outside its obesity and diabetes franchise.
Novo's core obesity and diabetes business remains the much larger driver of its financial performance. The oral Wegovy pill has already generated more than 2 million prescriptions shortly after its January 2026 launch. It gives Novo an important growth opportunity as the company competes with Eli Lilly in the oral GLP-1 market.
The company can also preserve capital by ending trials that show limited prospects for success. An independent data monitoring committee found a low likelihood that the two heart-failure studies would produce different results from the earlier failed trial. Novo can redirect the resources it would have spent on those studies toward higher-potential programs.
#obesity #diabetes
The move follows a July disclosure that ziltivekimab failed to reduce major adverse cardiovascular events in a late-stage trial. An independent data monitoring committee found a "low likelihood" that the two additional heart-failure studies would produce a different result from that earlier failure, prompting Novo to end them ahead of schedule.
Novo Nordisk A/S (NYSE:NVO) still has one opportunity to create value from its cardiovascular program. The company will continue testing ziltivekimab in patients recovering from a heart attack, with results expected in the first half of 2027. A successful outcome could give Novo another growth opportunity outside its obesity and diabetes franchise.
Novo's core obesity and diabetes business remains the much larger driver of its financial performance. The oral Wegovy pill has already generated more than 2 million prescriptions shortly after its January 2026 launch. It gives Novo an important growth opportunity as the company competes with Eli Lilly in the oral GLP-1 market.
The company can also preserve capital by ending trials that show limited prospects for success. An independent data monitoring committee found a low likelihood that the two heart-failure studies would produce different results from the earlier failed trial. Novo can redirect the resources it would have spent on those studies toward higher-potential programs.
#obesity #diabetes


6 days ago
During the September 14 episode of Mad Money, Jim Cramer addressed the broader tech sector pullback and mentioned Broadcom Inc. (NASDAQ:AVGO) as an attractive option for investors looking past short-term volatility. He stated:
Well, it's a tough time to come out to San Francisco, a day when the whole AI complex is getting hammered because Anthropic and OpenAI seem to be, I don't know… pulling in their horns. Actually, I think there's some real bargains in this group. Take Broadcom, the maker of chips, networking equipment, and tech infrastructure and software with a stock that's down more than 10% over the past month. At the beginning of this month, Broadcom reported a strong set of results, issued a spectacular multi-year forecast, but their guidance for the current quarter was, I don't know, viewed by some as in line.
The stock got slammed. I think Broadcom's still on track to put up some incredible growth because they're at the heart of the AI ecosystem because the company's never let us down in all the years my Charitable Trust has owned it. And down here, roughly 150 points below its June high, the stock may be too cheap to ignore.
Recent financial reports from Broadcom Inc. (NASDAQ:AVGO) highlights the scale of expansion driving its core semiconductor and infrastructure divisions. Total revenue for the fiscal third quarter reached $29.6 billion, representing an 85.5% increase compared to the same period in the previous year. Artificial intelligence semiconductor revenue surged 221% to $16.7 billion, accounting for roughly 56% of total revenue. Remaining performance obligations climbed significantly to $179.2 billion, providing substantial visibility into future contracted revenue. Broadcom also serves major hyperscale AI customers including Alphabet and Meta Platforms.
Management raised its full year guidance to $58 billion from $56 billion in artificial intelligence revenue, while projecting $115 billion for fiscal 2027 and $230 billion for fiscal 2028. The figures highlight a deep integration into the enterprise artificial intelligence ecosystem through custom accelerators and high-speed networking solutions.
#down #year #fiscal #NASDAQ
Well, it's a tough time to come out to San Francisco, a day when the whole AI complex is getting hammered because Anthropic and OpenAI seem to be, I don't know… pulling in their horns. Actually, I think there's some real bargains in this group. Take Broadcom, the maker of chips, networking equipment, and tech infrastructure and software with a stock that's down more than 10% over the past month. At the beginning of this month, Broadcom reported a strong set of results, issued a spectacular multi-year forecast, but their guidance for the current quarter was, I don't know, viewed by some as in line.
The stock got slammed. I think Broadcom's still on track to put up some incredible growth because they're at the heart of the AI ecosystem because the company's never let us down in all the years my Charitable Trust has owned it. And down here, roughly 150 points below its June high, the stock may be too cheap to ignore.
Recent financial reports from Broadcom Inc. (NASDAQ:AVGO) highlights the scale of expansion driving its core semiconductor and infrastructure divisions. Total revenue for the fiscal third quarter reached $29.6 billion, representing an 85.5% increase compared to the same period in the previous year. Artificial intelligence semiconductor revenue surged 221% to $16.7 billion, accounting for roughly 56% of total revenue. Remaining performance obligations climbed significantly to $179.2 billion, providing substantial visibility into future contracted revenue. Broadcom also serves major hyperscale AI customers including Alphabet and Meta Platforms.
Management raised its full year guidance to $58 billion from $56 billion in artificial intelligence revenue, while projecting $115 billion for fiscal 2027 and $230 billion for fiscal 2028. The figures highlight a deep integration into the enterprise artificial intelligence ecosystem through custom accelerators and high-speed networking solutions.
#down #year #fiscal #NASDAQ
6 days ago
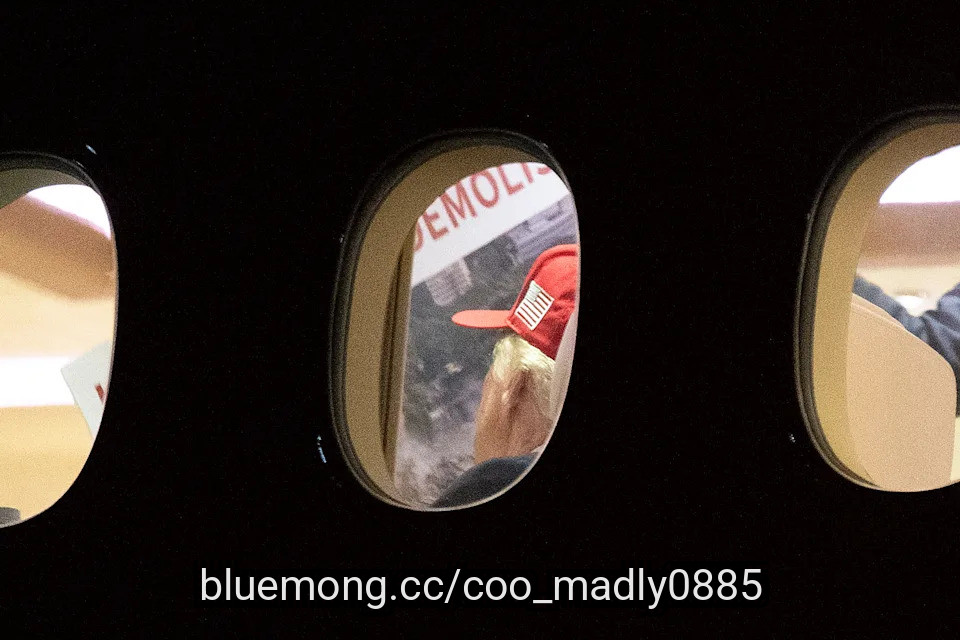
President Trump was photographed this week on board Air Force One examining a large poster with the words "Kennedy Center DEMOLISHED" printed above a rendering of a construction site, heightening concerns that his administration wants to raze Washington, D.C.'s iconic performing arts venue if his name is not added to its facade.
"I think that the Trump administration should certainly have recognition," the president told reporters before he boarded the plane Wednesday in North Carolina. "Because frankly, if we don't do that, it's going to close. It'll end up being ripped down."
Trump's comments and the photographs that followed are the latest developments in a convoluted saga that started when he dismissed the center's trustees in February 2025 — just days after returning to office — and replaced them with loyalists who elected him chairman.
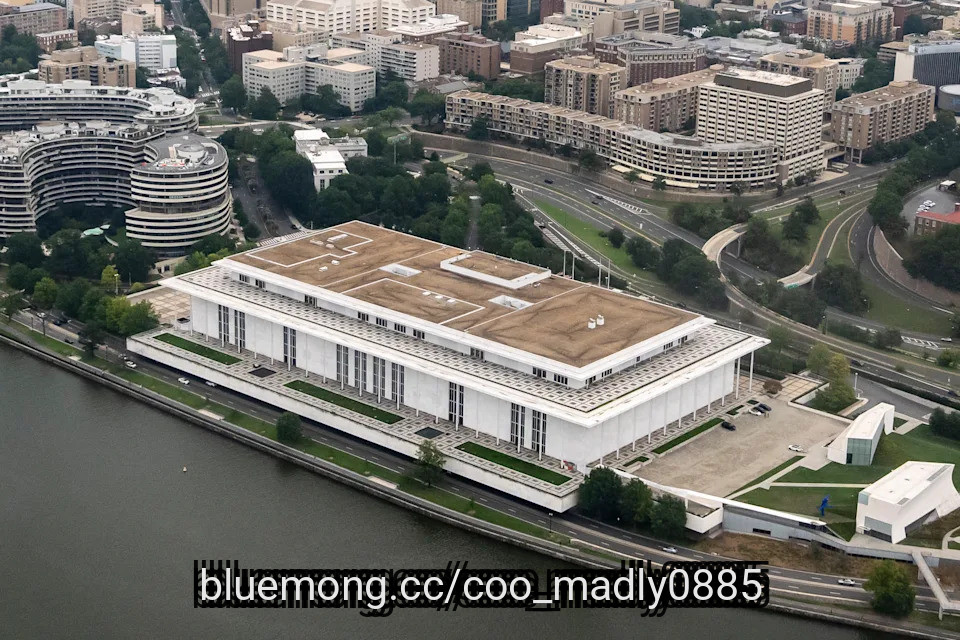
Despite several legal setbacks, Trump's handpicked board has been pushing ever since to rename the John F. Kennedy Center for the Performing Arts, which was built as a "living memorial" to the slain 35th president, after the White House's current occupant.
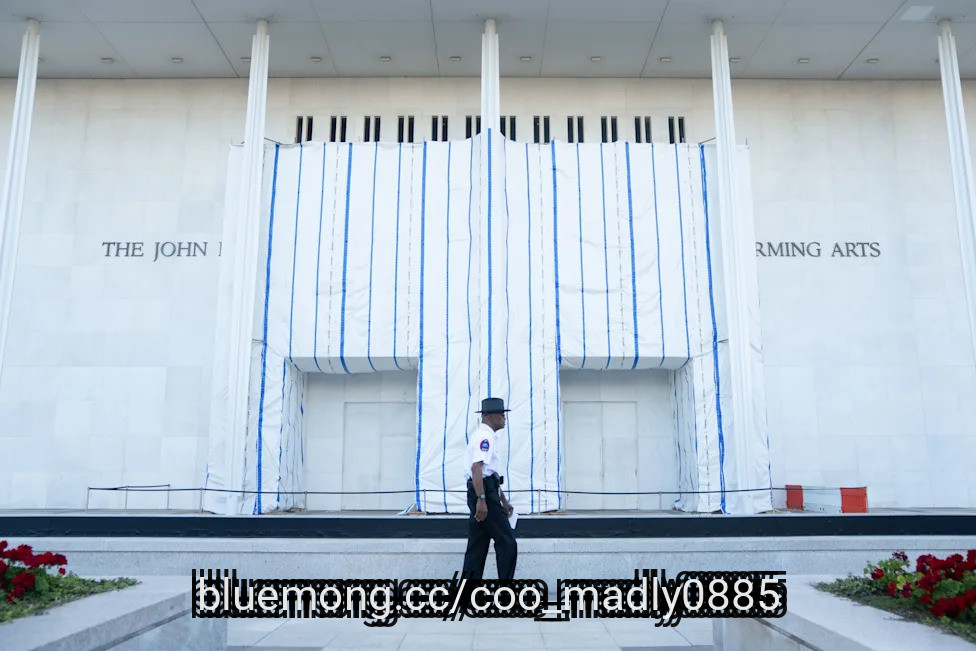
The day before Trump was photographed with the "Kennedy Center DEMOLISHED" poster, his appointees voted to close the center's main building for renovations. Does this mean Trump will bulldoze the Kennedy Center if he doesn't get the "recognition" he wants? Here's what we know — and what we don't.
#performing
"I think that the Trump administration should certainly have recognition," the president told reporters before he boarded the plane Wednesday in North Carolina. "Because frankly, if we don't do that, it's going to close. It'll end up being ripped down."
Trump's comments and the photographs that followed are the latest developments in a convoluted saga that started when he dismissed the center's trustees in February 2025 — just days after returning to office — and replaced them with loyalists who elected him chairman.
Despite several legal setbacks, Trump's handpicked board has been pushing ever since to rename the John F. Kennedy Center for the Performing Arts, which was built as a "living memorial" to the slain 35th president, after the White House's current occupant.
The day before Trump was photographed with the "Kennedy Center DEMOLISHED" poster, his appointees voted to close the center's main building for renovations. Does this mean Trump will bulldoze the Kennedy Center if he doesn't get the "recognition" he wants? Here's what we know — and what we don't.
#performing

6 days ago
Aristotle International Equity Fund, sub-advised by Aristotle Capital Management, LLC, released its second-quarter 2026 investor letter. The letter can be downloaded here. Global equity markets reached record highs in Q2, with the MSCI ACWI Index rising 14.93%, while global fixed income grew modestly by 0.87%. Geopolitical tensions, particularly in the Middle East, affected energy markets and investor sentiment, highlighting volatility and fragility in global supply. Central banks reacted variably to inflationary pressures, with the ECB raising rates amidst concerns of stagflation, while the Fed and Bank of England held rates steady. Despite economic challenges, robust earnings continued in Europe and Asia, driven by AI infrastructure demand. The Aristotle International Equity Fund (Class I-2) recorded an 8.40% return in the quarter, underperforming both the MSCI EAFE Index, which returned 10.82%, and the MSCI ACWI ex USA Index, which returned 14.49%. Going forward, the fund remains focused on quality investments as geopolitical and macroeconomic complexities make forecasting returns challenging. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa
6 days ago
About 13 years ago, “American Idol” contestant Caleb Flynn gushed about his wife Ashley, who he said encouraged him to audition for the 12th season of ABC’s singing competition.
“I love my wife more than anything,” he said in an interview during his brief stint on the show. “She’s very, very pretty, just – woof, I love her.”
Now, Flynn stands trial for her murder, as investigators allege the former music pastor fatally shot his wife of almost 16 years and staged the crime scene to make it appear she was killed by an intruder.
Flynn, 40, was arrested in February, days after he frantically called 911 to report someone broke into their Tipp City, Ohio, home and killed his wife – a beloved middle school volleyball coach – while he was in their daughters’ bedroom.
“We’re looking forward to trying the case,” his defense attorney, Patrick Mulligan, told CNN Tuesday. “We’ve been waiting for this.”
#years
“I love my wife more than anything,” he said in an interview during his brief stint on the show. “She’s very, very pretty, just – woof, I love her.”
Now, Flynn stands trial for her murder, as investigators allege the former music pastor fatally shot his wife of almost 16 years and staged the crime scene to make it appear she was killed by an intruder.
Flynn, 40, was arrested in February, days after he frantically called 911 to report someone broke into their Tipp City, Ohio, home and killed his wife – a beloved middle school volleyball coach – while he was in their daughters’ bedroom.
“We’re looking forward to trying the case,” his defense attorney, Patrick Mulligan, told CNN Tuesday. “We’ve been waiting for this.”
#years



7 days ago
Pharming Group N.V. (NASDAQ:PHAR) announced on September 11 that the U.S. Food and Drug Administration approved Joenja for children aged 4–11 with activated PI3K delta syndrome, or APDS, who weigh at least 27 kilograms. APDS disrupts immune function.
The new 40 mg and 50 mg tablet strengths expand dosing options for Joenja, or leniolisib. The pediatric regimen also includes 70 mg twice daily for children weighing at least 45 kilograms. Pharming Group N.V. (NASDAQ:PHAR) expects the new strengths in October through its existing distribution and patient-support network.
The expansion arrives as the revenue mix shifts. Second-quarter Joenja revenue increased 40% year over year to $17.9 million, while RUCONEST revenue declined 10% to $72.3 million. Total revenue fell 3% to $90.2 million. Joenja's growth is substantial, but the larger franchise still determines much of the overall result.
Pharming Group N.V. (NASDAQ:PHAR) can bring the pediatric doses to market through an established commercial platform. Distribution relationships and patient support are already in place, which could allow additional sales without duplicating the infrastructure required for an entirely new product.
The opportunity is to spread those capabilities across more eligible patients while maintaining support for existing users. Incremental revenue could improve commercial efficiency, although pediatric servicing costs will still matter.
#revenue #NASDAQ #joenja #pediatric
The new 40 mg and 50 mg tablet strengths expand dosing options for Joenja, or leniolisib. The pediatric regimen also includes 70 mg twice daily for children weighing at least 45 kilograms. Pharming Group N.V. (NASDAQ:PHAR) expects the new strengths in October through its existing distribution and patient-support network.
The expansion arrives as the revenue mix shifts. Second-quarter Joenja revenue increased 40% year over year to $17.9 million, while RUCONEST revenue declined 10% to $72.3 million. Total revenue fell 3% to $90.2 million. Joenja's growth is substantial, but the larger franchise still determines much of the overall result.
Pharming Group N.V. (NASDAQ:PHAR) can bring the pediatric doses to market through an established commercial platform. Distribution relationships and patient support are already in place, which could allow additional sales without duplicating the infrastructure required for an entirely new product.
The opportunity is to spread those capabilities across more eligible patients while maintaining support for existing users. Incremental revenue could improve commercial efficiency, although pediatric servicing costs will still matter.
#revenue #NASDAQ #joenja #pediatric

7 days ago
In this episode of Motley Fool Hidden Gems Investing, Motley Fool contributors Jon Quast, Matt Frankel, and Rachel Warren discuss:
Nvidia's potential acquisition of Hugging Face.
Hugging Face's new robot: Microduck.
What is an investment thesis?
Things that break an investment thesis.
#thesis #matt
Nvidia's potential acquisition of Hugging Face.
Hugging Face's new robot: Microduck.
What is an investment thesis?
Things that break an investment thesis.
#thesis #matt


7 days ago
Cadence Design Systems (CDNS) trades at 54.5 times trailing earnings. A multiple that high is a requirement rather than an opinion. The price only works if the business grows into it, and you can work out exactly how much growth it takes. The harder question is whether that calculation deserves your trust here.
What Is Cadence's Price Already ***** uming?
Three things have to be true, and none is a forecast. Each is an ***** umption the price has already made, and each one is worth testing.
First, the market gives Cadence four years to grow into the multiple. Second, the multiple then settles at 28.8 times, where a mature, scaled software franchise usually lands. Third, net margin holds near 24.3%, roughly where Cadence's net margin has run over the past twelve months.
So How Fast Would Cadence Have To Grow?
#times #design
What Is Cadence's Price Already ***** uming?
Three things have to be true, and none is a forecast. Each is an ***** umption the price has already made, and each one is worth testing.
First, the market gives Cadence four years to grow into the multiple. Second, the multiple then settles at 28.8 times, where a mature, scaled software franchise usually lands. Third, net margin holds near 24.3%, roughly where Cadence's net margin has run over the past twelve months.
So How Fast Would Cadence Have To Grow?
#times #design


7 days ago
Lululemon fell 18% after Meghan Frank delivered a second guidance cut, dropping the full-year EPS outlook to roughly $9.60 from last year's $13.26.
Nike fell 10% and On Holding dropped 14% over the same month, suggesting athletic-apparel sector headwinds extend well beyond Lululemon alone.
An 86-cent tariff refund inflated Q2 EPS but won't recur, making Lululemon's reported profit look cleaner than the challenge facing incoming CEO Heidi O'Neill.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Lululemon didn't make the cut. Enter your email to see the names that beat LULU. The report is free. Enter your email and see if any of your stocks made the cut.
Lululemon Athletica (NASDAQ:LULU) stock is under sustained pressure after a September earnings update that lowered management's outlook for the year. Retail broadly softened alongside it, and the broad market held up better, which frames the question of how much of the damage is company-specific and how much is sector-wide. Peer moves are part of that same picture, since athletic-apparel names moved lower together across the past month.
#lululemon #enter #outlook
Nike fell 10% and On Holding dropped 14% over the same month, suggesting athletic-apparel sector headwinds extend well beyond Lululemon alone.
An 86-cent tariff refund inflated Q2 EPS but won't recur, making Lululemon's reported profit look cleaner than the challenge facing incoming CEO Heidi O'Neill.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Lululemon didn't make the cut. Enter your email to see the names that beat LULU. The report is free. Enter your email and see if any of your stocks made the cut.
Lululemon Athletica (NASDAQ:LULU) stock is under sustained pressure after a September earnings update that lowered management's outlook for the year. Retail broadly softened alongside it, and the broad market held up better, which frames the question of how much of the damage is company-specific and how much is sector-wide. Peer moves are part of that same picture, since athletic-apparel names moved lower together across the past month.
#lululemon #enter #outlook