2 hours ago
Pricing alone does not decide where people buy their clothes.
With a number of retail chains competing for the off-price, on-trend fashion crown, it's easy for one brand to fall out of favor. Consumers seem to have an enduring love for Marshalls and TJ Maxx, while the popularity of Ross Dress for Less has grown steadily in recent years.
These brands drive sales by foot traffic, and that's a battle the aforementioned chains have been winning.
"Off-price apparel remained on solid footing in Q2 2026, with Ross leading the segment. Visits to Ross Dress for Less rose 16.4% year over year (YoY), while dd's DISCOUNTS grew 8.4%. TJX's TJ Maxx and Marshalls, meanwhile, saw visits hover around last year's levels — significantly outperforming traditional apparel, which declined 3.5% YoY," according to data from Placer.ai.
In the battle for customers looking for deals on trendy, fashionable clothes, Cato has been struggling, and now plans to close about 15% of its retail stores.
#price
With a number of retail chains competing for the off-price, on-trend fashion crown, it's easy for one brand to fall out of favor. Consumers seem to have an enduring love for Marshalls and TJ Maxx, while the popularity of Ross Dress for Less has grown steadily in recent years.
These brands drive sales by foot traffic, and that's a battle the aforementioned chains have been winning.
"Off-price apparel remained on solid footing in Q2 2026, with Ross leading the segment. Visits to Ross Dress for Less rose 16.4% year over year (YoY), while dd's DISCOUNTS grew 8.4%. TJX's TJ Maxx and Marshalls, meanwhile, saw visits hover around last year's levels — significantly outperforming traditional apparel, which declined 3.5% YoY," according to data from Placer.ai.
In the battle for customers looking for deals on trendy, fashionable clothes, Cato has been struggling, and now plans to close about 15% of its retail stores.
#price

11 hours ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ****** ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total

14 hours ago
The Magnificent 7 stocks are having a tough ride in 2026, and only Apple (AAPL) is outperforming the Nasdaq 100 Index ($IUXX). Digging deeper, Nvidia (NVDA) is the only other constituent that is up in double digits. Despite its recent rally, Tesla (TSLA) is still down over 18% year-to-date (YTD) and is the worst-performing Mag 7 stock.
The price action is not difficult to explain. Investors are now getting increasingly wary of tech companies' ever-rising capex to build artificial intelligence (AI) infrastructure. Apple was an outlier in the AI buildout race and is now sitting pretty as investors realize that waiting it out wasn't exactly a bad move on the iPhone maker's part.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Nvidia, OpenAI, and Oracle's $745B Financing Circle Just Hit Its First Stress Test: A Fed Rate Hike
#aapl #iuxx
The price action is not difficult to explain. Investors are now getting increasingly wary of tech companies' ever-rising capex to build artificial intelligence (AI) infrastructure. Apple was an outlier in the AI buildout race and is now sitting pretty as investors realize that waiting it out wasn't exactly a bad move on the iPhone maker's part.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Nvidia, OpenAI, and Oracle's $745B Financing Circle Just Hit Its First Stress Test: A Fed Rate Hike
#aapl #iuxx



19 hours ago
Concerned about an AI bubble? Sign up for The Daily Upside for smart and actionable market news, built for investors.
There's a lot we can't predict, like the outcome of the midterm elections, who will make it to the Super Bowl or whether Taylor Swift was actually hinting at a new album release in that Emmy's sketch. But when it comes to what our retirement looks like, we can certainly try.
Many retirement plans offer predictive tools that can help savers forecast their future balances, retirement readiness, income replacement rates and more. Participants, however, aren't happy with the options: J.D. Power's recent survey of digital experience satisfaction for retirement plans found that predictive tools were the lowest-performing attribute.
"The technology in the 401(k) is seriously behind what people are used to in their consumer life," said Fred Barstein, CEO of The Retirement Advisor University. When the underlying technology structure is old and **** bersome, it's hard for the tools to be as effective as they could be.
Sign up for The Daily Upside at no cost for premium **** ysis on all your favorite stocks.
#tools #sign #upside #like
There's a lot we can't predict, like the outcome of the midterm elections, who will make it to the Super Bowl or whether Taylor Swift was actually hinting at a new album release in that Emmy's sketch. But when it comes to what our retirement looks like, we can certainly try.
Many retirement plans offer predictive tools that can help savers forecast their future balances, retirement readiness, income replacement rates and more. Participants, however, aren't happy with the options: J.D. Power's recent survey of digital experience satisfaction for retirement plans found that predictive tools were the lowest-performing attribute.
"The technology in the 401(k) is seriously behind what people are used to in their consumer life," said Fred Barstein, CEO of The Retirement Advisor University. When the underlying technology structure is old and **** bersome, it's hard for the tools to be as effective as they could be.
Sign up for The Daily Upside at no cost for premium **** ysis on all your favorite stocks.
#tools #sign #upside #like
21 hours ago
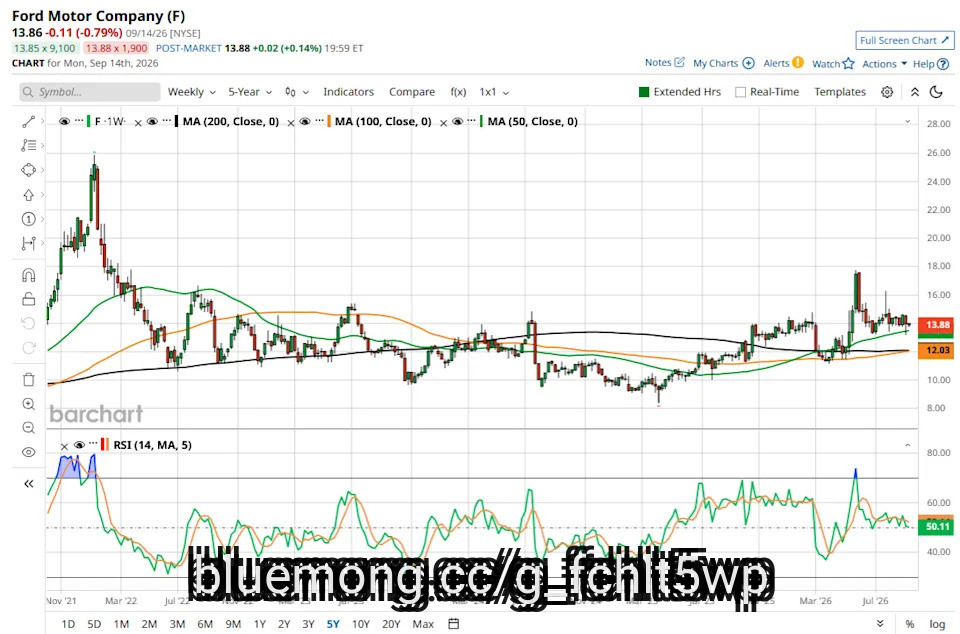
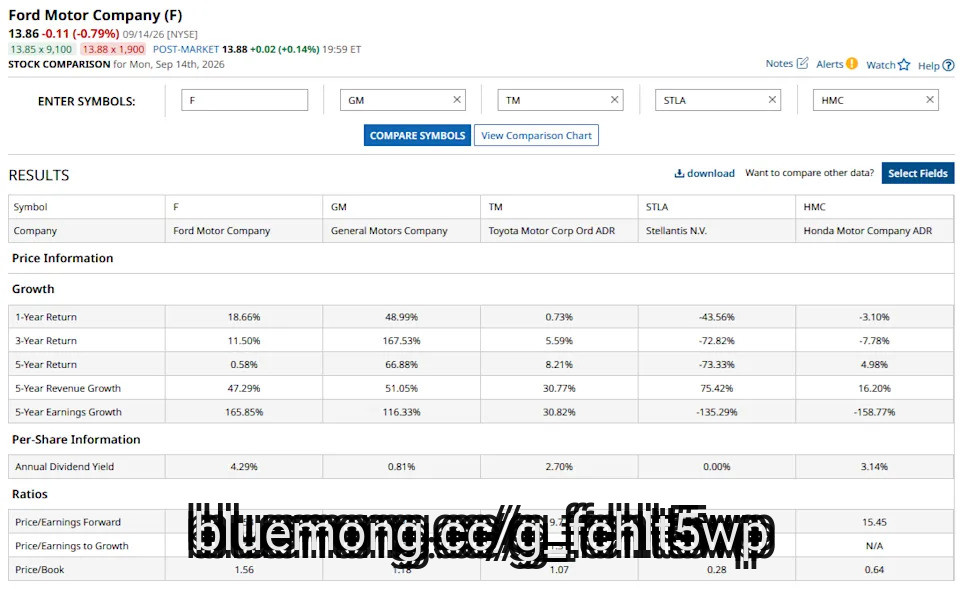
With a dividend yield of 4.3%, Ford (F) is among the highest-yielding constituents of the S&P 500 Index ($SPX). That number would look even more compelling considering Ford's dividend yield is over four times what an average S&P 500 Index constituent pays.
However, a bit of number-crunching tells a different picture. Dividend yield is basically a function of the per-share dividend, which is the numerator in the equation, and the stock price, which is the denominator. Dividend yield rises when the company raises its dividends or the share price falls. More often than not, the latter is true for companies that have a very high dividend yield.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ****** ysis you won't find anywhere else.
The S&P 500's dividend yield is near its historical lows. Two factors can be blamed for the dip in the world's most popular index's dividend yield. First, tech companies' share in the market-cap-weighted index has soared amid the artificial intelligence (AI) driven rally. Mega-cap tech companies are known to be frugal with dividends, and their rising weightage in the index pulls down its dividend yield. Second, while the annualized dividend per share of the S&P 500 has continued to rise over the years, the increase has been much lower compared to the surge in stock prices.
In contrast, Ford's quarterly dividend has been static since July 2022, when the company raised the payout by 50% to $0.15. Notably, while Ford paid special dividends in the preceding three years to reach its payout targets, it hasn't raised its payout for over four years. Its dividend yield is still high because of its underperforming stock, which has essentially gone nowhere in the last five years and trades 46% below its October 2022 highs.
#Dividend #yield #Share #dividends
However, a bit of number-crunching tells a different picture. Dividend yield is basically a function of the per-share dividend, which is the numerator in the equation, and the stock price, which is the denominator. Dividend yield rises when the company raises its dividends or the share price falls. More often than not, the latter is true for companies that have a very high dividend yield.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ****** ysis you won't find anywhere else.
The S&P 500's dividend yield is near its historical lows. Two factors can be blamed for the dip in the world's most popular index's dividend yield. First, tech companies' share in the market-cap-weighted index has soared amid the artificial intelligence (AI) driven rally. Mega-cap tech companies are known to be frugal with dividends, and their rising weightage in the index pulls down its dividend yield. Second, while the annualized dividend per share of the S&P 500 has continued to rise over the years, the increase has been much lower compared to the surge in stock prices.
In contrast, Ford's quarterly dividend has been static since July 2022, when the company raised the payout by 50% to $0.15. Notably, while Ford paid special dividends in the preceding three years to reach its payout targets, it hasn't raised its payout for over four years. Its dividend yield is still high because of its underperforming stock, which has essentially gone nowhere in the last five years and trades 46% below its October 2022 highs.
#Dividend #yield #Share #dividends


21 hours ago
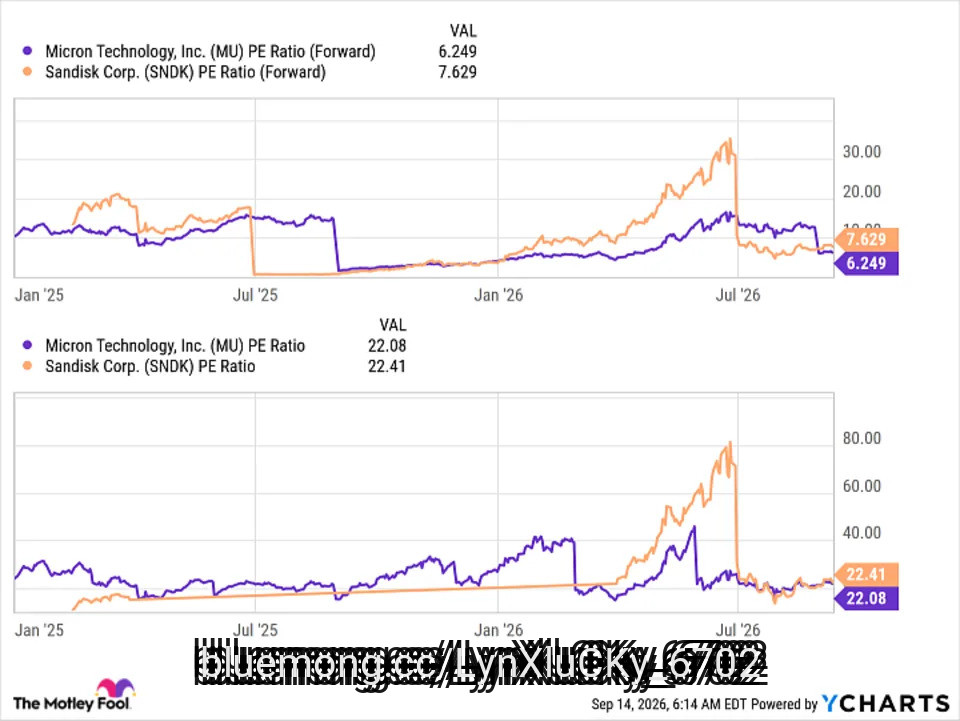
Micron (NASDAQ: MU) and Sandisk (NASDAQ: SNDK) have been two of the best-performing stocks in the S&P 500 (SNPINDEX: ^GSPC) so far this year. Sandisk is leading the way with an incredible 550% gain. Micron is in fourth place, up by over 220%. That means both of these stocks have tripled (or more than tripled in Sandisk's case), but I think that's just the beginning. In fact, if you invested $2,500 in each of these stocks, for a total of $5,000, I think that the combined value of those stakes will rise to $15,000 by the time 2028 arrives.
While that may sound far-fetched, the math backs it up, suggesting that these are two of the best investments you could make in the stock market right now.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The reason these two have done so well in 2026 is that there is no spare memory chip production capacity left. Micron and Sandisk are two of just three big players in this industry, and all of their production is being eaten up by massive demand for additional artificial intelligence computing power. AI processors and servers need heavy volumes of memory to function efficiently, and as a result, there's now a serious shortage of memory, so prices are skyrocketing.
This supply-and-demand imbalance is the culprit behind rising prices for consumer computing hardware, as these devices all require memory chips, too.
#NVIDIA #memory #flashing #best
While that may sound far-fetched, the math backs it up, suggesting that these are two of the best investments you could make in the stock market right now.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The reason these two have done so well in 2026 is that there is no spare memory chip production capacity left. Micron and Sandisk are two of just three big players in this industry, and all of their production is being eaten up by massive demand for additional artificial intelligence computing power. AI processors and servers need heavy volumes of memory to function efficiently, and as a result, there's now a serious shortage of memory, so prices are skyrocketing.
This supply-and-demand imbalance is the culprit behind rising prices for consumer computing hardware, as these devices all require memory chips, too.
#NVIDIA #memory #flashing #best


1 day ago
Become a CEO after your MBA: that's the promise some private equity firms are using to recruit top operating talent.
This promise propels the best and brightest into top executive roles without requiring them to climb the corporate ladder, underpinned by the belief that cultivating talent is a better bet than making semi-blind bets on external hires.
Alpine Investors and Shore Capital Partners have each built separate pipelines to funnel operational talent, aiming to equip executives to take charge of their portfolio companies.
Lower-middle-market buyout firm Shore Capital Partners runs what it calls its CXO program, a two-year training scheme that places early- to mid-career talent and recent MBA grads into C-suite-adjacent roles at its portfolio companies—typically chief of staff or vice president of business operations or strategic initiatives.
Top-performing CXO graduates then have the chance to be promoted to C-level positions. So far, Shore has produced four CEOs from the CXO program. This includes Mark Larsen, who has been CEO of medical software business Connexure since 2024.
#Companies
This promise propels the best and brightest into top executive roles without requiring them to climb the corporate ladder, underpinned by the belief that cultivating talent is a better bet than making semi-blind bets on external hires.
Alpine Investors and Shore Capital Partners have each built separate pipelines to funnel operational talent, aiming to equip executives to take charge of their portfolio companies.
Lower-middle-market buyout firm Shore Capital Partners runs what it calls its CXO program, a two-year training scheme that places early- to mid-career talent and recent MBA grads into C-suite-adjacent roles at its portfolio companies—typically chief of staff or vice president of business operations or strategic initiatives.
Top-performing CXO graduates then have the chance to be promoted to C-level positions. So far, Shore has produced four CEOs from the CXO program. This includes Mark Larsen, who has been CEO of medical software business Connexure since 2024.
#Companies


1 day ago
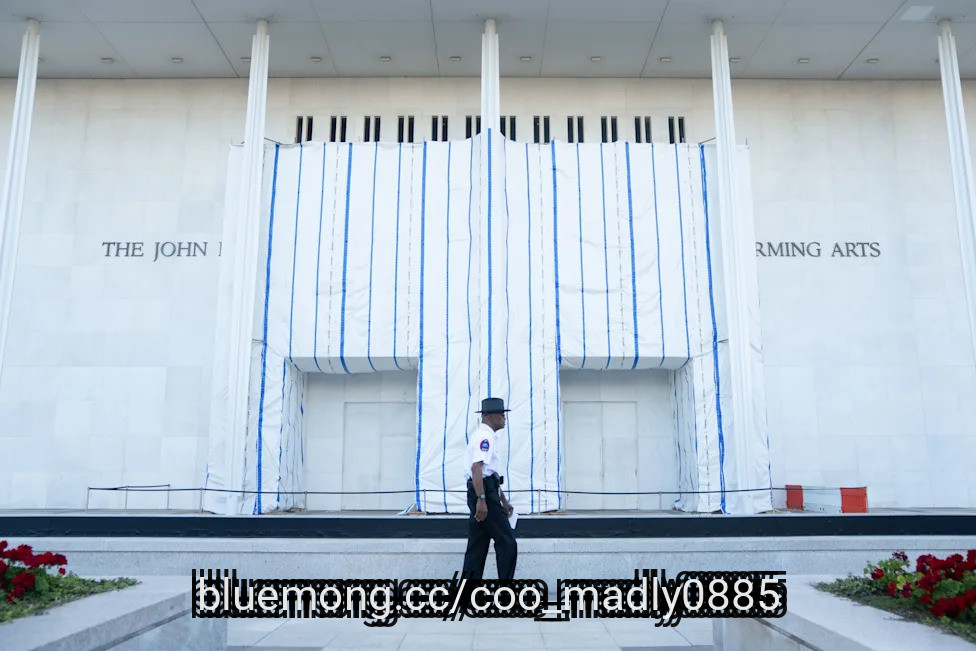
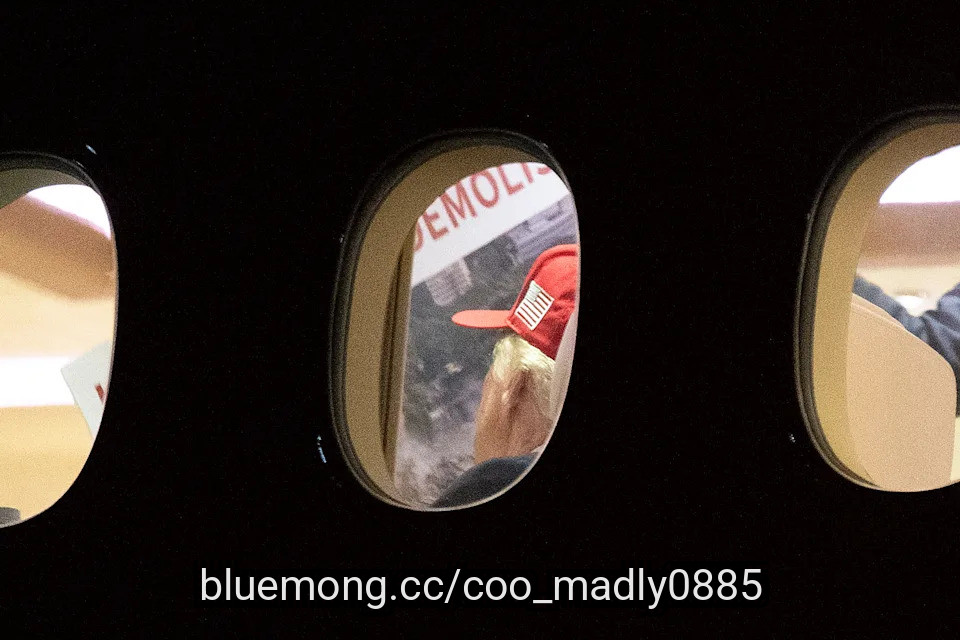
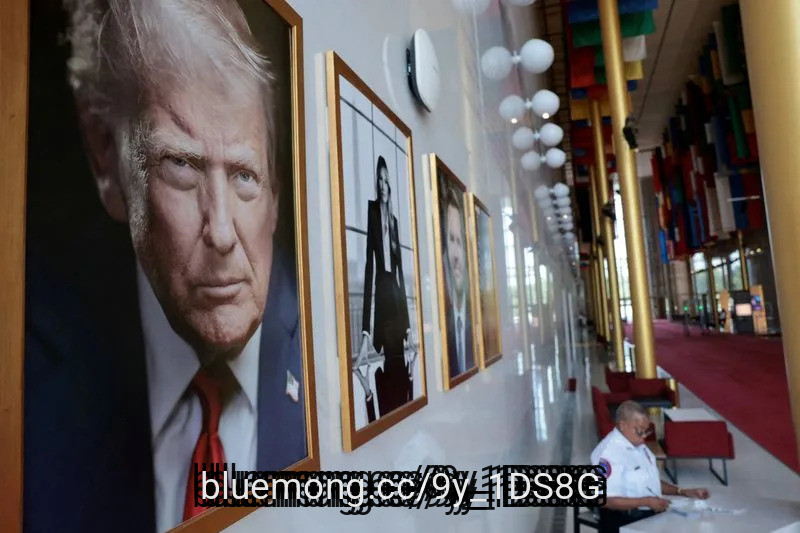
President Trump was photographed this week on board Air Force One examining a large poster with the words "Kennedy Center DEMOLISHED" printed above a rendering of a construction site, heightening concerns that his administration wants to raze Washington, D.C.'s iconic performing arts venue if his name is not added to its facade.
"I think that the Trump administration should certainly have recognition," the president told reporters before he boarded the plane Wednesday in North Carolina. "Because frankly, if we don't do that, it's going to close. It'll end up being ripped down."
Trump's comments and the photographs that followed are the latest developments in a convoluted saga that started when he dismissed the center's trustees in February 2025 — just days after returning to office — and replaced them with loyalists who elected him chairman.
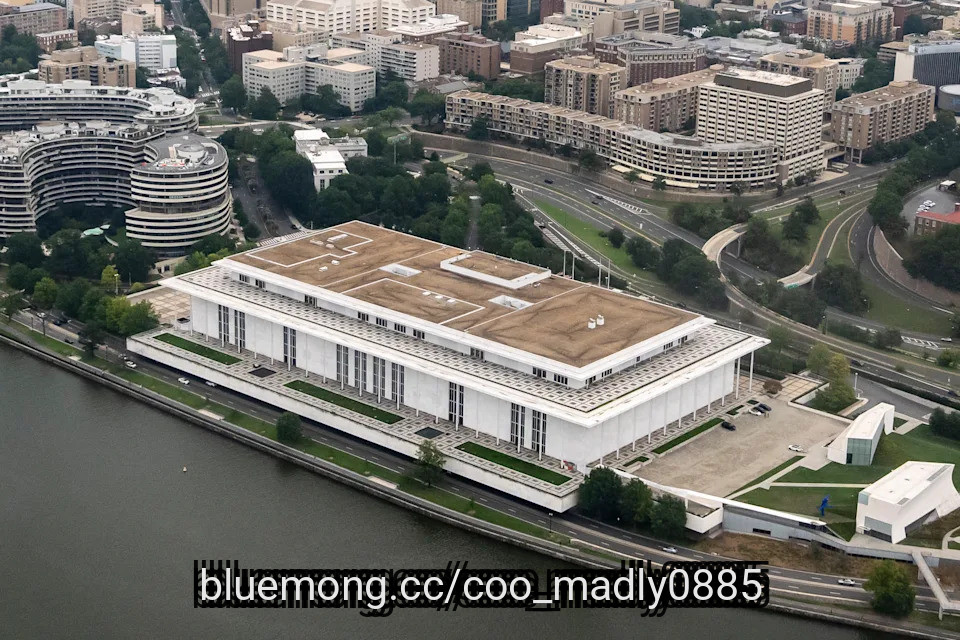
Despite several legal setbacks, Trump's handpicked board has been pushing ever since to rename the John F. Kennedy Center for the Performing Arts, which was built as a "living memorial" to the slain 35th president, after the White House's current occupant.
The day before Trump was photographed with the "Kennedy Center DEMOLISHED" poster, his appointees voted to close the center's main building for renovations. Does this mean Trump will bulldoze the Kennedy Center if he doesn't get the "recognition" he wants? Here's what we know — and what we don't.
#performing
"I think that the Trump administration should certainly have recognition," the president told reporters before he boarded the plane Wednesday in North Carolina. "Because frankly, if we don't do that, it's going to close. It'll end up being ripped down."
Trump's comments and the photographs that followed are the latest developments in a convoluted saga that started when he dismissed the center's trustees in February 2025 — just days after returning to office — and replaced them with loyalists who elected him chairman.
Despite several legal setbacks, Trump's handpicked board has been pushing ever since to rename the John F. Kennedy Center for the Performing Arts, which was built as a "living memorial" to the slain 35th president, after the White House's current occupant.
The day before Trump was photographed with the "Kennedy Center DEMOLISHED" poster, his appointees voted to close the center's main building for renovations. Does this mean Trump will bulldoze the Kennedy Center if he doesn't get the "recognition" he wants? Here's what we know — and what we don't.
#performing

2 days ago
Aristotle International Equity Fund, sub-advised by Aristotle Capital Management, LLC, released its second-quarter 2026 investor letter. The letter can be downloaded here. Global equity markets reached record highs in Q2, with the MSCI ACWI Index rising 14.93%, while global fixed income grew modestly by 0.87%. Geopolitical tensions, particularly in the Middle East, affected energy markets and investor sentiment, highlighting volatility and fragility in global supply. Central banks reacted variably to inflationary pressures, with the ECB raising rates amidst concerns of stagflation, while the Fed and Bank of England held rates steady. Despite economic challenges, robust earnings continued in Europe and Asia, driven by AI infrastructure demand. The Aristotle International Equity Fund (Class I-2) recorded an 8.40% return in the quarter, underperforming both the MSCI EAFE Index, which returned 10.82%, and the MSCI ACWI ex USA Index, which returned 14.49%. Going forward, the fund remains focused on quality investments as geopolitical and macroeconomic complexities make forecasting returns challenging. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa

2 days ago
The biggest return in the U.S. market this year came from the cost of moving oil across the ocean.
The Breakwave Tanker Shipping ETF (BWET) has climbed about 3,600% since the start of the year. That makes it the top-performing non-leveraged fund in the country, ahead of every AI and energy trade that grabbed headlines.
BWET now trades near $726 a share, up from under $20 in January. The huge increase traces back to one event that reshaped global shipping, and it carries a warning for anyone tempted to buy in now.
BWET tracks the price of moving oil by sea. It does that by holding short-dated freight futures, which are contracts that lock in the future cost of renting an oil tanker.
About 90% of the fund follows shipping agreements with the biggest tankers on the route from the Middle East to China. Those agreements lift BWET whenever hiring rates increase.
#cost #agreements
The Breakwave Tanker Shipping ETF (BWET) has climbed about 3,600% since the start of the year. That makes it the top-performing non-leveraged fund in the country, ahead of every AI and energy trade that grabbed headlines.
BWET now trades near $726 a share, up from under $20 in January. The huge increase traces back to one event that reshaped global shipping, and it carries a warning for anyone tempted to buy in now.
BWET tracks the price of moving oil by sea. It does that by holding short-dated freight futures, which are contracts that lock in the future cost of renting an oil tanker.
About 90% of the fund follows shipping agreements with the biggest tankers on the route from the Middle East to China. Those agreements lift BWET whenever hiring rates increase.
#cost #agreements


2 days ago
XLE's put/call ratio hit 2.57, with the most crowded trade being a one-month put that only pays off if energy stocks drop 12%.
USO has surged 126% YTD, but $6 diesel and freight earnings warnings of 5 to 10% signal that high crude is becoming an economic drag.
If energy breaks, defensive rotation candidates XLP (up 10% YTD) and XLV (up 25% over one year) stand to benefit.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Energy is the year's best-performing sector, and on Wednesday the options market bet heavily that it is about to break. Volume in Energy Select Sector SPDR (NYSEARCA:XLE) options ran roughly 70% above normal, with more than twice as many puts as calls changing hands and nine of the ten busiest contracts on the day being puts. The single most crowded trade was a 57-strike put expiring one month out, a structure that only pays off if XLE falls roughly 12% from here. Our own full-chain read on XLE puts a live put/call ratio at 2.57, with ratios above 16 at the Sept. 23 expiration and above 13 at Sept. 25.
#above #call #ratio #trade
USO has surged 126% YTD, but $6 diesel and freight earnings warnings of 5 to 10% signal that high crude is becoming an economic drag.
If energy breaks, defensive rotation candidates XLP (up 10% YTD) and XLV (up 25% over one year) stand to benefit.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Energy is the year's best-performing sector, and on Wednesday the options market bet heavily that it is about to break. Volume in Energy Select Sector SPDR (NYSEARCA:XLE) options ran roughly 70% above normal, with more than twice as many puts as calls changing hands and nine of the ten busiest contracts on the day being puts. The single most crowded trade was a 57-strike put expiring one month out, a structure that only pays off if XLE falls roughly 12% from here. Our own full-chain read on XLE puts a live put/call ratio at 2.57, with ratios above 16 at the Sept. 23 expiration and above 13 at Sept. 25.
#above #call #ratio #trade


2 days ago
Apple (NASDAQ:AAPL) is reportedly considering a big move that could reshape the company. The Information reported on Wednesday that the iPhone maker was considering developing its own artificial intelligence server, which would be Apple's first activity in the enterprise server market since 2011.
The proposal would combine Apple's custom silicon with networking technology supplied by Nvidia (NASDAQ:NVDA) to develop AI servers that could be offered with either two or four M8 Ultra chips, which are Apple's top-performing processors, and geared specifically for AI inference.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Such a move, the first major action under new CEO John Ternus, would signal that Apple is ready to invest in AI architecture to use its custom-made chips in products beyond its consumer devices, which would be a significant shift in company strategy.
Image source: Getty Images.
#flashing
The proposal would combine Apple's custom silicon with networking technology supplied by Nvidia (NASDAQ:NVDA) to develop AI servers that could be offered with either two or four M8 Ultra chips, which are Apple's top-performing processors, and geared specifically for AI inference.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Such a move, the first major action under new CEO John Ternus, would signal that Apple is ready to invest in AI architecture to use its custom-made chips in products beyond its consumer devices, which would be a significant shift in company strategy.
Image source: Getty Images.
#flashing


2 days ago
The casual Mexican restaurant sector has faced a challenging year in 2026, as dining chains have closed underperforming locations, filed for Chapter 11 bankruptcy protection to reorganize their businesses, and in at least one case, filed for Chapter 7 liquidation to shut down all operations.
Once popular Mexican chain On the Border ceased operations in 2026, after closing all of its locations before its operating company, OTB Hospitality, filed for Chapter 7 liquidation on June 19, 2026, the company shared in a press release.
Another chain facing financial distress is Session Taco, a St. Louis-based casual Mexican dining chain, which closed one of its restaurant locations for the second time in seven months. The chain has not filed for bankruptcy.
The Mexican chain, originally branded Mission Taco Joint until a 2023 name change, closed its Sobremesa restaurant in St. Charles, Mo., on Sept. 13 after only three months of operation, according to its Facebook page.
The St. Charles location was previously branded as Session Taco until the company closed the restaurant on Feb. 13 to redesign and rebrand the restaurant as Sobremesa before reopening in June 2026.
#mexican #locations
Once popular Mexican chain On the Border ceased operations in 2026, after closing all of its locations before its operating company, OTB Hospitality, filed for Chapter 7 liquidation on June 19, 2026, the company shared in a press release.
Another chain facing financial distress is Session Taco, a St. Louis-based casual Mexican dining chain, which closed one of its restaurant locations for the second time in seven months. The chain has not filed for bankruptcy.
The Mexican chain, originally branded Mission Taco Joint until a 2023 name change, closed its Sobremesa restaurant in St. Charles, Mo., on Sept. 13 after only three months of operation, according to its Facebook page.
The St. Charles location was previously branded as Session Taco until the company closed the restaurant on Feb. 13 to redesign and rebrand the restaurant as Sobremesa before reopening in June 2026.
#mexican #locations


2 days ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved group-adjusted EBITDA break-even just 15 months post-acquisition by applying Mytheresa's 'secret sauce'—focusing on top-tier customers, full-price selling, and rigorous cost discipline—to the distressed YNAP business.
Mytheresa reached a EUR 1 billion milestone in FY 2026, outperforming the industry through superior customer economics where top customers (4.8% of base) generated 48.4% of total GMV.
NET-A-PORTER and MR PORTER reached a strategic inflection point, returning to top-line growth and positive adjusted EBITDA in Q4 by pivoting from promotional discounting to editorial-led luxury discovery.
YOOX's turnaround is being driven by a deliberate retreat from high-cost overseas markets to focus on a 'healthy core' in Europe, resulting in losses being cut nearly in half compared to the prior year.
#porter #customers #cost #reached
Achieved group-adjusted EBITDA break-even just 15 months post-acquisition by applying Mytheresa's 'secret sauce'—focusing on top-tier customers, full-price selling, and rigorous cost discipline—to the distressed YNAP business.
Mytheresa reached a EUR 1 billion milestone in FY 2026, outperforming the industry through superior customer economics where top customers (4.8% of base) generated 48.4% of total GMV.
NET-A-PORTER and MR PORTER reached a strategic inflection point, returning to top-line growth and positive adjusted EBITDA in Q4 by pivoting from promotional discounting to editorial-led luxury discovery.
YOOX's turnaround is being driven by a deliberate retreat from high-cost overseas markets to focus on a 'healthy core' in Europe, resulting in losses being cut nearly in half compared to the prior year.
#porter #customers #cost #reached

2 days ago
By Katharine Jackson and Mike Scarcella
WASHINGTON, Sept 17 (Reuters) - A federal judge ordered President Donald Trump's administration on Thursday to provide at least 30 days' notice before taking any steps to demolish the Kennedy Center, the landmark performing arts venue that has become a flashpoint in his efforts to reshape the U.S. capital.
U.S. District Judge Christopher Cooper issued the order after lawyers for a Democratic congresswoman who is suing to keep the venue open and Trump's name off its facade submitted new evidence citing the Republican president's comments on Wednesday referring to demolishing the Kennedy Center.
"I think that the Trump administration should certainly have recognition. Because frankly, if we don't do that, it's going to close. It'll end up being ripped down," Trump told reporters in North Carolina, referring to putting his name on the facility established by Congress and opened in 1971 as a memorial to slain President John Kennedy.
Matt Floca, the Kennedy Center's Trump-backed executive director, said in a court filing earlier on Thursday that the building was being temporarily closed to ****** s safety risks in areas "exhibiting severe structural deterioration."
#president #venue
WASHINGTON, Sept 17 (Reuters) - A federal judge ordered President Donald Trump's administration on Thursday to provide at least 30 days' notice before taking any steps to demolish the Kennedy Center, the landmark performing arts venue that has become a flashpoint in his efforts to reshape the U.S. capital.
U.S. District Judge Christopher Cooper issued the order after lawyers for a Democratic congresswoman who is suing to keep the venue open and Trump's name off its facade submitted new evidence citing the Republican president's comments on Wednesday referring to demolishing the Kennedy Center.
"I think that the Trump administration should certainly have recognition. Because frankly, if we don't do that, it's going to close. It'll end up being ripped down," Trump told reporters in North Carolina, referring to putting his name on the facility established by Congress and opened in 1971 as a memorial to slain President John Kennedy.
Matt Floca, the Kennedy Center's Trump-backed executive director, said in a court filing earlier on Thursday that the building was being temporarily closed to ****** s safety risks in areas "exhibiting severe structural deterioration."
#president #venue
2 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre


2 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter

2 days ago
On September 14, Dave & Buster's Entertainment (NASDAQ:PLAY) reported second-quarter fiscal 2026 results that read like two different companies at once. Revenue fell, and the company posted a net loss for the period ended August 4, yet comparable sales, which had been sliding for more than a year, kept getting less bad every month from June through the first five weeks of the third quarter. New CEO Darin Harper is betting that improvement compounds into something bigger.
The clearest evidence is the trend line itself. Comparable store sales fell 5.4% in the first quarter of fiscal 2026, then 2.9% in the second quarter, then just 1.6% in July after a 5% decline in June, and Harper said trends improved further over the first five weeks of the third quarter. Food and beverage sales are moving in the opposite direction entirely, up 7.6% in the quarter and positive for five straight quarters, helped by the Eat & Play Combo, a bundled meal and game credit offer sold through kiosks. Special event sales have now grown for seven consecutive quarters.
Behind that shift sits a rebuilt leadership bench. Dave & Buster's went more than a year without a chief marketing officer, and Harper has since added a CMO, a chief operations officer, a chief technology officer, and a chief legal officer since taking over. The company also leaned on new content, launching 10 games and attractions this year, including tie-ins with Mandalorian and Grogu, John Wick and Stranger Things, after research found more than 70% of guests said new games would bring them back more often. Changes to game pricing pushed play and dwell time up 16% to 20% or more. Six remodeled stores are already outperforming the rest of the chain, and management says the newest remodel template costs less to build than the last one. Net capital spending dropped to $127.6 million through the first half of the year from $155.4 million, and adjusted free cash flow swung to positive $19.5 million from negative $36.5 million, a $56 million improvement.
The headline figures were still rough. Total revenue slipped 2.4% to $544.1 million from $557.4 million a year earlier, and adjusted EBITDA dropped to $98.9 million, an 18.2% margin, from $129.8 million and a 23.3% margin. On a GAAP basis, the company posted a net loss of $12.5 million, or $0.36 per diluted share, versus net income of $11.4 million in the same quarter last year. About $15 million of the EBITDA decline came from items management calls non-normalized, including a $10 million noncash deferral adjustment that did not repeat this year, $3 million in extra preopening costs and $2 million in higher insurance expenses, but even stripped of those, the underlying decline was still roughly $16 million.
#year #first #harper #play
The clearest evidence is the trend line itself. Comparable store sales fell 5.4% in the first quarter of fiscal 2026, then 2.9% in the second quarter, then just 1.6% in July after a 5% decline in June, and Harper said trends improved further over the first five weeks of the third quarter. Food and beverage sales are moving in the opposite direction entirely, up 7.6% in the quarter and positive for five straight quarters, helped by the Eat & Play Combo, a bundled meal and game credit offer sold through kiosks. Special event sales have now grown for seven consecutive quarters.
Behind that shift sits a rebuilt leadership bench. Dave & Buster's went more than a year without a chief marketing officer, and Harper has since added a CMO, a chief operations officer, a chief technology officer, and a chief legal officer since taking over. The company also leaned on new content, launching 10 games and attractions this year, including tie-ins with Mandalorian and Grogu, John Wick and Stranger Things, after research found more than 70% of guests said new games would bring them back more often. Changes to game pricing pushed play and dwell time up 16% to 20% or more. Six remodeled stores are already outperforming the rest of the chain, and management says the newest remodel template costs less to build than the last one. Net capital spending dropped to $127.6 million through the first half of the year from $155.4 million, and adjusted free cash flow swung to positive $19.5 million from negative $36.5 million, a $56 million improvement.
The headline figures were still rough. Total revenue slipped 2.4% to $544.1 million from $557.4 million a year earlier, and adjusted EBITDA dropped to $98.9 million, an 18.2% margin, from $129.8 million and a 23.3% margin. On a GAAP basis, the company posted a net loss of $12.5 million, or $0.36 per diluted share, versus net income of $11.4 million in the same quarter last year. About $15 million of the EBITDA decline came from items management calls non-normalized, including a $10 million noncash deferral adjustment that did not repeat this year, $3 million in extra preopening costs and $2 million in higher insurance expenses, but even stripped of those, the underlying decline was still roughly $16 million.
#year #first #harper #play

2 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus

2 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus

2 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #NASDAQ #fund #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #NASDAQ #fund #parnassus


2 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #fund #quarter #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #fund #quarter #parnassus

2 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands


2 days ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) is a leading professional services company that provides consulting, industry X, song, and technology and operation services. On September 15, 2026, Accenture plc (NYSE:ACN) closed at $193.40 per share. Over the past month, Accenture plc (NYSE:ACN) was up 3.11%, and its shares lost 21.71% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $118.33 billion.
Weitz Multi Cap Equity Fund stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"IT services and management consultant Accenture plc (NYSE:ACN) reported results in mid-June that did little to quell investor fears of AI-disintermediation. Accenture has a long history of helping clients navigate technological transformation, and we believe it will again play a role as AI permeates businesses. To date, however, we have maintained a smaller position given the higher-than-usual degree of uncertainty."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#investor
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) is a leading professional services company that provides consulting, industry X, song, and technology and operation services. On September 15, 2026, Accenture plc (NYSE:ACN) closed at $193.40 per share. Over the past month, Accenture plc (NYSE:ACN) was up 3.11%, and its shares lost 21.71% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $118.33 billion.
Weitz Multi Cap Equity Fund stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"IT services and management consultant Accenture plc (NYSE:ACN) reported results in mid-June that did little to quell investor fears of AI-disintermediation. Accenture has a long history of helping clients navigate technological transformation, and we believe it will again play a role as AI permeates businesses. To date, however, we have maintained a smaller position given the higher-than-usual degree of uncertainty."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#investor


2 days ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#communications #quarter #investor
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#communications #quarter #investor


2 days ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted CoStar Group, Inc. (NASDAQ:CSGP). CoStar Group, Inc. (NASDAQ:CSGP), an information, ****** ytics, and online marketplace services provider for commercial and residential property markets. On September 15, 2026, CoStar Group, Inc. (NASDAQ:CSGP) closed at $31.56 per share, reflecting a market capitalization of $12.79 billion. CoStar Group, Inc. (NASDAQ:CSGP) posted a one-month return of -6.43%, while its shares lost 64.08% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding CoStar Group, Inc. (NASDAQ:CSGP) in its Q2 2026 investor letter:
"CoStar Group, Inc.'s (NASDAQ:CSGP) management prevailed in its struggle with an activist investor and remains undeterred in its residential real estate strategy. Investors are clearly skeptical of management's plan, but at current prices, we believe the punishment has gone too far."
CoStar Group, Inc. (NASDAQ:CSGP) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 58 hedge fund portfolios held CoStar Group, Inc. (NASDAQ:CSGP) at the end of the second quarter, down from 62 in the previous quarter. While we acknowledge the potential of CoStar Group, Inc. (NASDAQ:CSGP) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#group #NASDAQ #fund #weitz
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted CoStar Group, Inc. (NASDAQ:CSGP). CoStar Group, Inc. (NASDAQ:CSGP), an information, ****** ytics, and online marketplace services provider for commercial and residential property markets. On September 15, 2026, CoStar Group, Inc. (NASDAQ:CSGP) closed at $31.56 per share, reflecting a market capitalization of $12.79 billion. CoStar Group, Inc. (NASDAQ:CSGP) posted a one-month return of -6.43%, while its shares lost 64.08% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding CoStar Group, Inc. (NASDAQ:CSGP) in its Q2 2026 investor letter:
"CoStar Group, Inc.'s (NASDAQ:CSGP) management prevailed in its struggle with an activist investor and remains undeterred in its residential real estate strategy. Investors are clearly skeptical of management's plan, but at current prices, we believe the punishment has gone too far."
CoStar Group, Inc. (NASDAQ:CSGP) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 58 hedge fund portfolios held CoStar Group, Inc. (NASDAQ:CSGP) at the end of the second quarter, down from 62 in the previous quarter. While we acknowledge the potential of CoStar Group, Inc. (NASDAQ:CSGP) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#group #NASDAQ #fund #weitz

2 days ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX) as a newly added postion. Netflix, Inc. (NASDAQ:NFLX) is a leading subscription-based streaming entertainment platform. On September 15, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of -2.89%, while its shares lost 36.59% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"We initiated two new positions during the second quarter. Most will be familiar with global streaming giant, Netflix, Inc. (NASDAQ:NFLX). The company made headlines as it tried to acquire Warner Bros. from Warner Bros. Discovery before ultimately walking away from a bidding war for the company. Some investors feared its bid signaled stagnation in its streaming business. At the time of this writing, the 2026 FIFA World Cup is also captivating audiences and draining attention and engagement from Netflix's service. Despite these near-term perception headwinds, we are optimistic that Netflix's introduction of an ad-supported tier is a savvy strategy to extend its growth runway: Netflix will not only participate in the large, multi-billion-dollar global advertising market, but a lower-price ad-tier broadens its potential customer base while simultaneously enhancing the pricing power of its premium, ad free tier."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#second
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX) as a newly added postion. Netflix, Inc. (NASDAQ:NFLX) is a leading subscription-based streaming entertainment platform. On September 15, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of -2.89%, while its shares lost 36.59% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"We initiated two new positions during the second quarter. Most will be familiar with global streaming giant, Netflix, Inc. (NASDAQ:NFLX). The company made headlines as it tried to acquire Warner Bros. from Warner Bros. Discovery before ultimately walking away from a bidding war for the company. Some investors feared its bid signaled stagnation in its streaming business. At the time of this writing, the 2026 FIFA World Cup is also captivating audiences and draining attention and engagement from Netflix's service. Despite these near-term perception headwinds, we are optimistic that Netflix's introduction of an ad-supported tier is a savvy strategy to extend its growth runway: Netflix will not only participate in the large, multi-billion-dollar global advertising market, but a lower-price ad-tier broadens its potential customer base while simultaneously enhancing the pricing power of its premium, ad free tier."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#second
2 days ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Mettler-Toledo International Inc. (NYSE:MTD). Mettler-Toledo International Inc. (NYSE:MTD) manufactures and supplies precision instruments and services in the Americas, Europe, Asia, and internationally. On September 15, 2026, Mettler-Toledo International Inc. (NYSE:MTD) closed at $1,330.40 per share. Over the past month, Mettler-Toledo International Inc. (NYSE:MTD) declined 6.64%, and its shares gained 4.43% over the past 52 weeks. Mettler-Toledo International Inc. (NYSE:MTD) has a market capitalization of $26.66 billion.
Weitz Multi Cap Equity Fund stated the following regarding Mettler-Toledo International Inc. (NYSE:MTD) in its Q2 2026 investor letter:
"Less familiar to shareholders may be our new position in Mettler-Toledo International Inc. (NYSE:MTD), a global supplier of precision measurement instruments across laboratory, industrial and food retailing applications where accuracy, reliability and regulatory compliance are vital. Its highly specialized sales and service organization is a key competitive advantage, working collaboratively with customers to optimize their workflows and improve productivity, reinforcing long-term customer relationships. We have long admired Mettler's business and purchased a small position during a brief period of price dislocation during the quarter."
Mettler-Toledo International Inc. (NYSE:MTD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 48 hedge fund portfolios held Mettler-Toledo International Inc. (NYSE:MTD) at the end of the second quarter, down from 50 in the previous quarter. While we acknowledge the potential of Mettler-Toledo International Inc. (NYSE:MTD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mettler #quarter
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Mettler-Toledo International Inc. (NYSE:MTD). Mettler-Toledo International Inc. (NYSE:MTD) manufactures and supplies precision instruments and services in the Americas, Europe, Asia, and internationally. On September 15, 2026, Mettler-Toledo International Inc. (NYSE:MTD) closed at $1,330.40 per share. Over the past month, Mettler-Toledo International Inc. (NYSE:MTD) declined 6.64%, and its shares gained 4.43% over the past 52 weeks. Mettler-Toledo International Inc. (NYSE:MTD) has a market capitalization of $26.66 billion.
Weitz Multi Cap Equity Fund stated the following regarding Mettler-Toledo International Inc. (NYSE:MTD) in its Q2 2026 investor letter:
"Less familiar to shareholders may be our new position in Mettler-Toledo International Inc. (NYSE:MTD), a global supplier of precision measurement instruments across laboratory, industrial and food retailing applications where accuracy, reliability and regulatory compliance are vital. Its highly specialized sales and service organization is a key competitive advantage, working collaboratively with customers to optimize their workflows and improve productivity, reinforcing long-term customer relationships. We have long admired Mettler's business and purchased a small position during a brief period of price dislocation during the quarter."
Mettler-Toledo International Inc. (NYSE:MTD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 48 hedge fund portfolios held Mettler-Toledo International Inc. (NYSE:MTD) at the end of the second quarter, down from 50 in the previous quarter. While we acknowledge the potential of Mettler-Toledo International Inc. (NYSE:MTD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mettler #quarter


2 days ago
This story was originally published on Restaurant Dive. To receive daily news and insights, subscribe to our free daily Restaurant Dive newsletter.
Chipotle will expand its Apprentice program by placing these employees in over 4,200 company-owned locations by the end of 2027, the chain said in a press release Tuesday.
Apprentices — high-performing employees working toward a management position — are currently in about 75% of its restaurants. Adding more apprentices will create additional opportunities for crew members to advance their careers, while the organization builds a deeper management bench.
These up-and-coming leaders are a key part of the chain's unit growth strategy, particularly as it expands towards 7,000 restaurants in the U.S. and Canada. This year, it expects to open between 350 to 370 company-owned units.
Developing its leadership pipeline is part of the chain's Recipe for Growth strategy, which also includes strengthening its core menu, improving brand messaging and menu innovations, modernizing its business model with technology and expanding its global reach.
#restaurant #dive #employees
Chipotle will expand its Apprentice program by placing these employees in over 4,200 company-owned locations by the end of 2027, the chain said in a press release Tuesday.
Apprentices — high-performing employees working toward a management position — are currently in about 75% of its restaurants. Adding more apprentices will create additional opportunities for crew members to advance their careers, while the organization builds a deeper management bench.
These up-and-coming leaders are a key part of the chain's unit growth strategy, particularly as it expands towards 7,000 restaurants in the U.S. and Canada. This year, it expects to open between 350 to 370 company-owned units.
Developing its leadership pipeline is part of the chain's Recipe for Growth strategy, which also includes strengthening its core menu, improving brand messaging and menu innovations, modernizing its business model with technology and expanding its global reach.
#restaurant #dive #employees