8 days ago
Social Security acts as a financial safety net for many retirees, but it's not enough for most. These government checks were never designed to cover all living expenses. Social Security is a supplemental income source that can keep up with expenses if you combine it with savings.
That's why many people are encouraged to save up before retirement, and the math proves it. Your life in retirement will be very different if you just live on Social Security compared to having $500,000 in savings alongside your government checks. Let's break it all down below.
The average monthly Social Security benefit for retired workers as of mid-2026 was $2,085.98, according to the Social Security Administration (SSA). At that rate, you will not pay any taxes on Social Security, ******* uming you do not have any other income sources. You won't even have to worry about state income taxes.
However, that's where the advantages end if you rely exclusively on Social Security. Per Apartment List data, the national median rent was $1,390 in August. That median rent leaves you with less than $700 for groceries, transportation, healthcare, utilities, insurance, debt and miscellaneous purchases.
For most people, the average Social Security is not enough. High-earners can max out their benefits at $5,181 per month if they earned a high salary for most or all of their 35 highest-earning years and wait until 70 to tap into Social Security, per the SSA. That monthly amount offers more room for financial flexibility, but the average is insufficient for most people unless their spouse earns a similar check or they live very frugally.
#income #financial

9 days ago
SmartAsset and Yahoo Finance LLC may earn commission or revenue through links in the content below.
During most of the decades you are preparing financially for retirement, you are likely focused on saving as close as you can get to the recommended amount, without worrying too much about the details. As you approach retirement, however, it's a good idea to look more closely at what might be a realistic retirement budget. At age 62, with $890,000 in a 401(k) account, $115,000 in a Roth IRA and accounting for Social Security benefits, you can likely generate enough income to cover typical retiree lifestyle expenses. Your individual needs may vary, of course, but there are likely moves you can make now and in retirement to give you the flexibility you'll need to fund a comfortable and secure retirement.
Consider speaking with a financial advisor for help building an effective retirement strategy.
A typical retirement budget starts with the income side and Social Security benefits represent an important part of that for a large majority of retirees. Social Security is lifelong, guaranteed by the U.S. government and includes annual cost-of-living adjustments to keep up with inflation. The amount of your specific benefit is controlled by your work history and age at claiming. ****** uming your current income is $90,000 annually, here are estimates of your annual Social Security benefit based on your age when you start claiming benefits:
Age
#annual

10 days ago
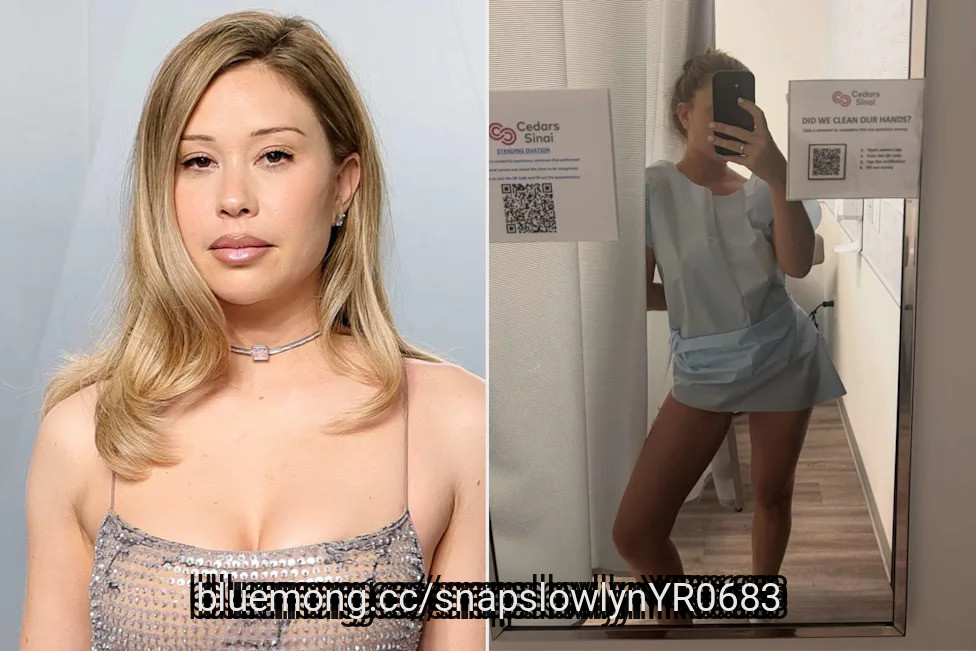
Gabby Windey said she broke her back falling off a vibrating workout plate
The Bachelorette alum, 35, shared photos of her trip to the hospital on Friday, Oct. 2, after injuring her back while using the workout device
Vibrating plates are said to promote strength, flexibility, and circulation and can stimulate muscles
Gabby Windey said she broke her back falling off a vibrating workout plate.
In an Instagram post on Friday, Oct. 2, the 35-year-old Bachelorette alum shared photos of her trip to the hospital after falling from the workout device.
#workout #gabby
18 days ago
Titan International, Inc. (NYSE:TWI) announced a definitive agreement on September 21 to sell its Italtractor ITM undercarriage business to USCO S.p.A. The initial purchase price is approximately $207 million, while the stated total cash value reaches up to approximately $285 million. Understanding that difference is central to ******* sing the financial flexibility the disposal could create.
Titan International, Inc. (NYSE:TWI) expects approximately $23 million from closing adjustments and $11 million in dividends before closing. A further $6 million depends on ITM meeting specified 2026 performance criteria. The headline also includes $38 million in dividends received in earlier years.
Subtracting those historical dividends leaves approximately $247 million in potential future gross receipts, including the earnout, or $241 million without it. These calculations use the announced estimates and span different payment dates. Final adjustments, taxes, and transaction costs will determine how much cash becomes available for deployment.
The disclosed dollar amounts were translated at €1.00 to $1.148, the September 18, 2026 exchange rate. Currency movements could increase or reduce the eventual dollar receipts.
Titan International, Inc. (NYSE:TWI) intends to use part of the proceeds to reduce debt and pursue growth investments, including acquisitions and partnerships. The disposal would also concentrate resources on wheel and tire operations.
#september #announced
25 days ago
On September 9, 2026, Reuters reported that Amazon.com, Inc. (NASDAQ:AMZN) raised £4.25 billion, or about $5.76 billion, in its first-ever sterling bond sale, slightly more than initially expected, as part of a four-tranche deal spanning 3 to 19 years. Final investor demand came in at more than £10.65 billion, roughly 2.5 times the amount raised, but that was notably lower than the demand Alphabet saw for its own sterling debut in February, a sign ******* ysts said shows hyperscaler borrowing may be starting to test the limits of investor appetite.
Amazon.com, Inc. (NASDAQ:AMZN)'s first sterling bond sale shows that investors still have a strong appetite for its debt. The firm raised $5.8 billion through the offering, and demand reached roughly 2.5 times the amount available. The sterling market also has relatively limited supply of large technology-company debt. It could back up demand for future Amazon issuance in the currency. Strong demand gives Amazon another funding channel as it finances its large-scale AI and cloud infrastructure investments.
Amazon can put the proceeds toward AWS, its fastest-growing major business. AWS revenue increased 36.7% year over year in the second quarter. It marks its fastest growth rate in 18 quarters as demand for AI infrastructure accelerated. Funding more data centers, computing capacity and related infrastructure could allow Amazon to capture more of that demand. If AWS sustains its growth while making strong operating profits, the additional debt could support investments in one of Amazon's most important long-term earnings drivers.
The sterling offering diversifies Amazon's funding base as its capital requirements grow. Amazon issued four tranches with maturities ranging from three to 19 years. It gives the business access to UK investors while adding sterling financing alongside its existing dollar, euro, Swiss franc and yen debt. This overall investor base gives Amazon greater flexibility to raise capital across different markets and currencies. So diversification could become more valuable as Amazon funds an unprecedented AI infrastructure buildout without relying entirely on one debt market.
Amazon.com, Inc. (NASDAQ:AMZN)'s weaker reception compared with Alphabet signals that investors may demand higher borrowing costs from hyperscalers. Amazon's sterling offering attracted about 2.5 times coverage, below Alphabet's roughly 3.5 times coverage for its recent euro bond sale. The difference shows that demand for hyperscaler debt is not unlimited. If investor appetite continues to weaken, Amazon could face higher yields on future borrowing, increasing the cost of financing its AI infrastructure expansion.
#sterling #infrastructure #NASDAQ #amzn
25 days ago
On September 9, 2026, Reuters reported that AI music startup Suno launched a new suite of models, including its flagship v6 and exploratory v6-Wild, built in partnership with Warner Music Group Corp. (NASDAQ:WMG) and BMG. It lets users make new music inspired by licensed recordings from participating artists. The launch follows Warner Music's copyright lawsuit settlement with Suno in November 2025, under which artists and songwriters can opt in to have their names, voices, and compositions used in AI-generated music in exchange for compensation.
Warner Music Group Corp. (NASDAQ:WMG) can turn the Suno litigation dispute into a new licensing revenue opportunity. Suno has now launched its v6 models in partnership with Warner Music and BMG. It allows users to make music inspired by licensed works from participating artists. Warner previously sued Suno over copyright issues before reaching a licensing agreement. This gives the label a direct path to monetize AI-generated music rather than relying solely on litigation. The deal could create a new revenue stream as consumers increasingly adopt AI music tools.
Warner enters the AI-music market from a position of financial strength. The firm reported fiscal third-quarter revenue of $5.44 billion, up 9% year over year. Adjusted OIBDA increased 16% to $433 million, and its adjusted OIBDA margin expanded to 23.2%. Warner also said it had met or exceeded its financial targets for five consecutive quarters. That basic growth gives the company greater flexibility to invest in AI initiatives while using licensing agreements to add another potential growth driver to its existing streaming and publishing businesses.
Warner could help establish a more sustainable commercial model for AI-generated music. Suno said future products will include opt-in experiences that allow individual artists to participate and receive payment when users generate music around them. So Warner has an opportunity to help shape licensing and compensation practices as Spotify and other platforms develop their own AI-music products. If the industry increasingly adopts licensed models, Warner's large catalog and relationships with artists could solidify its negotiating position and create recurring AI-related revenue.
Suno's new licensing model does not eliminate the overall legal risks surrounding AI music. Warner Music Group Corp. (NASDAQ:WMG) has reached an agreement with Suno, but other copyright owners are challenging the firm's technology. Independent publisher Round Hill sued Suno in August, alleging that the company used copyrighted songs to train its AI system. Suno also faces separate litigation from Universal Music Group and Sony Music. Hence, lawsuits could increase legal costs and create uncertainty over the licensing framework that Warner hopes to monetize.
#music #licensing #corp #revenue

25 days ago
Americans have paid about $97 billion more for fuel since the Iran war started in late February, roughly $740 extra per household, according to CNN. President Trump says prices will come down after the midterms. The CEO of Chevron just said publicly he does not see how that happens quickly.
Mike Wirth, Chevron's chairman and chief executive, spoke at a University of Texas at Austin energy conference on September 11. He told the audience that the mechanisms that helped absorb the oil supply shock earlier in the conflict have largely been used up, and that prices are more likely to rise than fall over the next few months.
When the U.S.-Iran conflict began, the oil market had several ways to handle the disruption. Countries could release crude from strategic reserves. Commercial inventories could be drawn down. The U.S. eased restrictions on sanctioned crude stored on vessels at sea. Those measures helped limit the initial price spike.
"Those have largely now played out," Wirth said. The energy system no longer has the buffers it had when the war began.
The loss of flexibility became more acute after attacks knocked out a major Saudi crude pipeline that had been bypassing the Strait of Hormuz. That single disruption put an estimated 2.5 million barrels of oil per day in limbo, tightening a market that was already running short on supply.
#crude #prices #energy #conflict

25 days ago
California Resources Corporation (NYSE:CRC) announced on September 17 that it had agreed to sell its Uinta Basin **** ets, located mostly in Utah and Colorado, to an undisclosed buyer for $90 million in cash. The company had come to own the Uinta **** ets, which span about 100,000 net acres, after it acquired Berry Corp last year. However, CRC considered them non-core to its operations. The net proceeds from the sale will be used for shareholder returns and other corporate purposes.
Francisco Leon, President and CEO of California Resources Corporation, commented:
"Today's transaction strengthens our business. The monetization of our Uinta Basin **** ets sharpens our focus on California and captures additional value from the Berry merger. This transaction enhances our capital allocation flexibility, allowing us to invest in higher-return opportunities within the Golden State and supports our shareholder return strategy. The sale also helps offset the purchase price of our recent midstream transaction."
The transaction is expected to close by year-end, subject to the receipt of certain third-party consents and other customary conditions.
The sale will allow CRC to redeploy the $90 million toward **** ets that are central to its operating strategy while avoiding additional capital commitments to Uinta. The company already stated in its Q2 earnings call that Uinta has higher capital intensity, higher break-evens, lower crude quality, higher transportation and operating costs, and steeper declines. Therefore, the sale removes a portfolio distraction at a time when CRC is concentrating investment in California infrastructure and production.
#uinta #assets #transaction #capital
26 days ago
Owning a $400,000 Villages home costs owners roughly 4.5% annually in forgone investment income alone, before taxes, insurance, or CDD bond payments.
Annual rentals run between $2,200 and $3,000 a month, but renting beats owning only for stays under eight years once all costs are counted.
A 75-year-old facing a forced sale in a narrow buyer pool at 3.98 million existing home sales risks losing the flexibility a lease ending provides.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
At the end of the day, renting versus buying in The Villages comes down to one thing: math. More owners are running the numbers and finding that renting wins on the spreadsheet, so here is what the comparison actually looks like when every line is filled in.
#income

27 days ago
On August 6, APA Corporation (NASDAQ:APA) held its second-quarter earnings call, and one number stood out from the rest. The oil and gas producer is now holding its Permian oil production steady with four drilling rigs, half the eight it once estimated it would need. Adjusted production of 347,000 barrels of oil equivalent per day beat management's own guidance, free cash flow kept climbing, and the balance sheet is healing faster than planned. That combination is the story of the quarter.
APA raised its full-year US oil guidance to 123,000 barrels per day, up from an original 120,000, while holding its capital budget at $1.3 billion despite higher diesel and other input costs. Management also lifted its cost-savings target to $500 million in annualized run-rate savings by year-end, up from the $450 million goal it set at the start of the year.
That flexibility is showing up in cash flow. Free cash flow hit $738 million in the second quarter, pushing the first half of 2026 past $1.2 billion, which topped what APA generated in each of the past three full years. The company returned $189 million of that to shareholders through dividends and the repurchase of 2.8 million shares at an average price of $35.26, continuing a streak of returning at least 60% of free cash flow to investors every year since 2021.
The balance sheet is moving just as fast. Net debt stood at $3.3 billion at quarter-end after APA repaid $752 million of bonds in the first half, including $673 million in the second quarter alone, cutting total debt by $2.3 billion since the end of 2024 and lowering annualized interest expense by roughly $175 million. Management now expects to hit its $3 billion net debt target in 2027, well ahead of the three- to four-year window it laid out when the goal was first announced.
Further out, APA is building option value beyond its core Permian and Egypt ****** ets. It agreed to acquire Savant Alaska for $70 million, picking up an airstrip, a dock, and a pipeline connection into the Trans Alaska system to support two exploration wells planned for 2027. In Uruguay, ENI signed on as a partner in Block 6, funding a significant share of the first exploration well while APA keeps 60% ownership. In Suriname, the GranMorgu project remains on budget for first oil in mid-2028.
#billion
27 days ago
On September 8, 2026, the Wall Street Journal reported United Natural Foods, Inc. (NYSE:UNFI)'s fiscal fourth-quarter results, in which adjusted earnings per share of $0.69 beat ***** yst expectations even as revenue of $7.64 billion came in below consensus.
The grocery wholesaler guided for fiscal 2027 net sales of $31.2 billion to $31.8 billion, a return to growth after full-year fiscal 2026 sales declined 2% to $31.2 billion. The business said full-year adjusted EBITDA rose 27% to $701 million and free cash flow hit a record $323 million as it continued executing what CEO Sandy Douglas called its second year of a value-creation strategy.
United Natural Foods, Inc. (NYSE:UNFI)'s turnaround is improving the financial metrics that matter most for a food distributor. Full-year adjusted EBITDA increased 27%. Net debt fell by $295 million and net leverage improved to 2.2 times. The stronger balance sheet gives UNFI more financial flexibility as it works to return to sales growth.
UNFI's natural-products business is providing an important growth engine. Fourth-quarter natural-products sales increased 6.6%, even as conventional-products sales declined 8.6%. The stronger performance in natural products backs up UNFI's strategy of expanding business with customers that can drive growth as the business restructures its operations.
Management also expects fiscal 2027 sales to reach $31.2 billion to $31.8 billion, up from $31.15 billion in fiscal 2026. Adjusted EPS should reach $3.00 to $3.50 versus $2.65 previously. Management anticipates about 10 basis points of margin expansion at the midpoint, which could help UNFI reach its fiscal 2028 margin target a year earlier than planned.
#billion

27 days ago
CoreWeave (NASDAQ: CRWV) stock was rocked on Thursday. The artificial intelligence (AI) cloud company's shares closed down more than 5% on news of two fundraising measures it announced that morning.
CoreWeave announced an at-the-market (ATM) issue of its publicly traded Class A common stock. Up to 35 million shares are to be sold in a public offering by a large syndicate of sales agents.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The company said it will use its share of the proceeds "to provide ongoing financing flexibility and to support CoreWeave's objective of migrating its enterprise credit profile toward investment grade."
The company also announced an issue of convertible senior notes. It will float $3 billion worth of the securities, which mature in 2033 if not converted, in a private offering. The company intends to offer the initial purchasers of the note up to a total of $500 million in additional aggregate principal amount of notes.
#shares
27 days ago
On September 9, 2026, Reuters reported that U.S. Transportation Secretary Sean Duffy sent a letter to Ford Motor Company (NYSE:F) CEO Jim Farley criticizing the automaker's business relationships with Chinese battery maker CATL and Chinese automakers Geely and BYD as raising "profound concern."
It specifically flagged Ford's licensed CATL battery technology at its Marshall, Michigan plant, its joint venture with Geely in Spain, and its decision not to move Lincoln Nautilus production out of China until 2030. Ford responded that Duffy's letter was "a wrongheaded attempt to capture headlines," noting that it owns the Marshall plant, controls its operations, and employs the workforce there, unlike companies that simply import Chinese-made batteries.
Ford Motor Company (NYSE:F) can argue that its CATL partnership still solidifies U.S. battery manufacturing rather than becoming more dependent on Chinese imports. Ford owns and operates its Marshall, Michigan battery plant. It allows the company to manufacture batteries domestically while licensing CATL technology. That structure could help Ford expand its U.S. EV production capacity and reduce the need to import finished Chinese battery packs.
Ford's improving financial performance gives the firm more flexibility to manage the political pressure. The automaker raised its full-year adjusted EBIT guidance to $10 billion-$11 billion after second-quarter results exceeded expectations, with record Bronco sales and a stronger product mix supporting the improvement. Stronger operating earnings could give Ford more resources to adjust its battery strategy if policymakers impose more restrictions on Chinese technology.
The company's existing U.S. manufacturing footprint could become a competitive advantage if Washington tightens restrictions on Chinese automotive technology. Ford has already invested in domestic battery production instead of relying entirely on imported battery packs. Model e losses have narrowed for three consecutive quarters. If policymakers force automakers to cut Chinese supply-chain reliance, Ford can use its existing U.S. factories to adapt faster than rivals that depend heavily on Chinese parts.
#ford #catl #motor

27 days ago
Estes Express Lines is investing nearly $56 million to expand its cross-border and offshore freight network, including terminals, equipment and capacity serving Canada, Mexico, Alaska, Hawaii and Puerto Rico.
Alex Peebles, senior director of offshore and international at Estes, said the privately held, family-owned carrier is taking a longer view of the freight market rather than allowing current conditions to dictate its investment strategy.
"We're really looking at all of these investments from a long-term horizon and viewpoint perspective and one that's going to help accommodate growth and capacity into all the offshore international markets that we service," Peebles told FreightWaves.
Estes, which is celebrating its 95th anniversary this year, is North America's largest privately held less-than-truckload (LTL) freight transportation provider. The company operates a network of over 300 terminals and service centers across the U.S., Puerto Rico, Alaska, Hawaii with coverage extending to Canada, Mexico and the Caribbean
Peebles said the company's ownership structure gives it flexibility to move quickly when real estate and equipment opportunities arise.
#rico


27 days ago
On September 8, 2026, Reuters reported that NIKE, Inc. (NYSE:NKE) shareholders rejected a proposal urging greater transparency on how the company plans to meet its 2030 emissions-reduction targets, despite support from Norway's sovereign wealth fund, Nike's 11th-largest shareholder.
Nike's board had urged a "no" vote, arguing management is "best positioned to determine the targets and related disclosures that are appropriate." Shareholders separately approved the company's executive compensation proposal, including pay for CEO Elliott Hill, in a vote that had faced some opposition.
The failed climate proposal gives NIKE, Inc. (NYSE:NKE)'s management more flexibility to focus on its operational turnaround. Shareholders rejected the request for greater disclosure on how Nike plans to meet its 2030 emissions targets. It allows CEO Elliott Hill and his team to prioritize product innovation, sales recovery, and market-share gains. Nike faces significant operational challenges. So management could benefit from directing more resources toward restoring growth and profitability.
Nike has already made measurable progress toward its environmental targets. It limits the immediate financial impact of the rejected proposal. The company reported an 11% reduction in supply-chain emissions from its 2015 baseline in fiscal 2024, while its 2030 targets call for a 65% reduction in operational emissions and a 30% reduction across its supply chain. This progress gives Nike evidence that it is chasing its climate goals even without expanding its current disclosure.
Shareholders' approval of Elliott Hill's compensation package shows support for Nike's leadership despite the difficult turnaround. Investors approved more than $36 million in total compensation for Hill for fiscal 2026, even though Norway's wealth fund and major proxy advisers opposed the package. Shareholder support gives Hill greater room to execute his strategy as Nike works to stabilize sales, rebuild its market position, and restore long-term earnings growth.
#reduction #elliott #greater

27 days ago
Ascendis Pharma A/S (NASDAQ:ASND) announced on September 14 that it will regain exclusive rights to develop, manufacture, and commercialize TransCon products in metabolic and cardiovascular diseases following the termination of its collaboration with Novo Nordisk A/S (NYSE:NVO).
The rights include once-monthly TransCon Semaglutide, an investigational long-acting prodrug of semaglutide intended for obesity and type 2 diabetes. Neither party will have continuing financial obligations to the other. Once termination becomes effective and the rights revert, management plans to initiate multiple programs across rare and large indications.
The investment question is whether greater control over future products can justify the resources needed to develop them.
Ascendis Pharma A/S (NASDAQ:ASND) would regain flexibility over which indications to pursue, how quickly to advance candidates, and whether to seek another partner. Successful independent development could retain more of a product's commercial economics, while a new collaboration could provide another way to share costs and risk.
Monthly dosing offers a clear development objective. If clinical studies demonstrate effective treatment with acceptable tolerability, fewer injections could make long-term therapy more convenient. That potential benefit would matter most if it helps patients stay on treatment without sacrificing outcomes.
#ascendis #pharma #asnd #regain

28 days ago
Travel credit cards offer points and miles rewards on your spending, which you can use toward travel-related redemptions, such as flights, hotel stays, and car rentals. You'll often earn the highest rewards rate on travel purchases with a travel credit card. However, many also offer boosted rewards on everyday purchases like groceries, gas, and more.
When you're comparing travel credit cards, it's useful to separate them into two distinct types: general travel rewards cards and co-branded airline and hotel credit cards.
With a general travel credit card, you'll have a number of flexible redemption options when you're ready to redeem your points and miles.
Travel card issuers generally have their own travel portals, like Chase Travel or American Express Travel, where you can book flights, hotels, rental cars, and more. These programs also have a number of travel transfer partners to which you can directly transfer points or miles. For example, American Express Membership Rewards points transfer to Delta SkyMiles at a rate of 1:1.
The flexibility of general travel cards means you can use your rewards to travel with different airlines or hotel brands. Each time you're ready to book, simply shop around between the portal or partners and compare the best options for your specific travel plans.
#rewards #points #you 're


28 days ago
Travel credit cards offer points and miles rewards on your spending, which you can use toward travel-related redemptions, such as flights, hotel stays, and car rentals. You'll often earn the highest rewards rate on travel purchases with a travel credit card. However, many also offer boosted rewards on everyday purchases like groceries, gas, and more.
When you're comparing travel credit cards, it's useful to separate them into two distinct types: general travel rewards cards and co-branded airline and hotel credit cards.
With a general travel credit card, you'll have a number of flexible redemption options when you're ready to redeem your points and miles.
Travel card issuers generally have their own travel portals, like Chase Travel or American Express Travel, where you can book flights, hotels, rental cars, and more. These programs also have a number of travel transfer partners to which you can directly transfer points or miles. For example, American Express Membership Rewards points transfer to Delta SkyMiles at a rate of 1:1.
The flexibility of general travel cards means you can use your rewards to travel with different airlines or hotel brands. Each time you're ready to book, simply shop around between the portal or partners and compare the best options for your specific travel plans.
#credit #hotel #general



29 days ago
Agriscience business Corteva (CTVA) is gearing up to spin off its seed operating segment as an independently traded public company, Vylor, trading under the "VYLR" ticker. Shareholders have already approved the separation, and they are expected to receive one Vylor common share for each Corteva common share they hold. VYLR is set to begin trading on Oct. 1. The company is holding an Investor Day webcast on Sept. 15.
Corteva believes this spinoff will give both companies more flexibility. However, ****** ysts have questioned whether it weakens the entities. Meanwhile, CEO Luke Kissam has highlighted a pipeline Corteva values at $11 billion through 2040 and its plan to introduce 12 products over the next decade. Contrarily, competition from generic products remains, and President Donald Trump's administration is exploring whether consolidation among agricultural suppliers has driven up input costs.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
#corteva


29 days ago
Fast-growing stocks and artificial intelligence (AI) seem to go hand in hand, and there are several examples of stocks growing their revenue at 50%, 100%, or even 200%. But none quite touch how rapidly Nebius (NASDAQ: NBIS) is growing. During its most recent quarter, revenue rose by a jaw-dropping 454% year over year. What's even more impressive is that this growth rate is expected to last through the rest of the year, and 2027's will also be elevated.
It's starting to make a lot of sense that Nvidia (NASDAQ: NVDA) is investing in Nebius, and there's still a great buying opportunity here for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is a neocloud business that provides AI-focused cloud computing power to its clients. Among its biggest clients are Meta Platforms and Microsoft, each of which has signed multi-year deals with Nebius to expand capacity. Both Microsoft and Meta have their own data centers, and Microsoft rents out its capacity to others, so why are they renting from Nebius?
Nebius' deal with Nvidia provides it with leading hardware before others, so it's a way to gain early access to the best computing units. Furthermore, these companies like having a bit of flexibility and not having to build too many data centers, as well as getting their hands on as much computing capacity as quickly as possible.
#Microsoft

29 days ago
U.S. stocks fell Tuesday as the 10-year Treasury yield climbed above 5% for the first time since 2007, with investors awaiting a Federal Reserve interest-rate decision expected Wednesday.
The Dow Jones Industrial Average dropped roughly 449 points, or 0.86%. The S&P 500 fell about 0.34% and the Nasdaq Composite declined 0.48%. The 10-year Treasury yield rose as high as 5.041% before pulling back to trade around 5.011%.
Oil prices extended gains after Saudi Arabia shut a key pipeline that bypasses the Strait of Hormuz. Brent crude futures for November delivery rose about 1.6% to trade above $107 a barrel, while West Texas Intermediate futures climbed to above $103.
Fed funds futures point to roughly a 90% to 93% probability that the Fed raises its benchmark rate by a quarter percentage point on Wednesday, which would lift the upper bound of the target range to 4%, according to The Wall Street Journal. That probability was roughly 59% a week ago.
Christopher Hodge, chief economist for the U.S. at Natixis CIB Americas, said in a note that he expects Fed Chair Kevin Warsh to signal the rate move is not a commitment to further hikes. "We also think that he will emphasize that this decision was discrete and does not pre-commit the Fed to any actions in subsequent meetings, giving him and the Committee maximum flexibility to respond to shocks," Hodge said, according to CNBC.
#rate

1 month ago
During the September 10 episode of Mad Money, a caller questioned whether recent vertical integration by industrial competitors and market selloffs warranted a lower valuation for Howmet Aerospace Inc.'s (NYSE:HWM) economic moat, or if demand remained strong enough to make the pullback an overreaction. Jim Cramer replied:
Now, look, I'll tell you, here's the problem… It's a fastener company, and it frankly is, most times, very commodity-oriented business, and it happens to sell at 44 times earnings, and we don't want to pay that for commodities even though the business is strong. I think people are saying, "Wait a second, that's too much to pay, and I'm going to wait till it goes lower." And if you look at the chart, it does seem like it is going lower.
Howmet Aerospace Inc. (NYSE:HWM) occupies a sole-source or primary-supplier position across critical narrowbody and widebody aircraft programs, providing single-crystal turbine blades, advanced structural castings, and **** anium fasteners. Approval and qualification requirements, manufacturing complexity, and a limited supplier base can make alternative sources difficult to establish quickly. That gives the company strong pricing power on both new plane parts and higher-margin replacement spares.
The structural advantages of Howmet Aerospace Inc.'s (NYSE:HWM) business model can be seen in its Q2 financial results. Revenue surged over 24% year-over-year (21% organically) to $2.55 billion, driven by a 28% jump in commercial aerospace revenue, a 38% expansion in industrial gas turbines, and an 11% gain in defense aerospace. The core Engine Products division recorded third-party sales of $1.37 billion, up 32% year-over-year, while segment adjusted EBITDA margins expanded by 470 basis points to 37.7%.
Despite its market positioning, Howmet Aerospace Inc. (NYSE:HWM) carries valuation risks that advise a cautious approach. Trading at elevated EV/EBITDA and forward P/E multiples relative to traditional industrial peers, the stock leaves little margin for operational missteps. Capital expenditures are projected to exceed $500 million in 2026 as the company builds out production capacity for next-generation engine components and gas turbines, reducing near-term free cash conversion flexibility.
#lower #ebitda
1 month ago
The Eagles left their season opener with a victory, but the offensive line's uneven performance has now been followed by a significant personnel change. Philadelphia placed Landon ****** erson on injured reserve after the veteran left guard played through multiple ailments against Washington. Drew Kendall and Willie Lampkin are the leading candidates to replace him, although the Eagles could consider changing more than one position.
Here are four takeaways from the move.
Dickerson rarely looked comfortable against the Commanders. He played all 55 offensive snaps but surrendered three pressures, including a quarterback hit, and was penalized for holding. Those problems were part of a difficult afternoon for Philadelphia's interior protection. Washington repeatedly generated pressure through the middle and finished with three sacks.
Dickerson's performance should be viewed in the context of the physical issues he was trying to manage. He remained on the field for every offensive play, but he did not resemble the powerful and dependable blocker the Eagles have come to expect.
Kendall appears to be one of the most logical candidates to enter the starting lineup. His ability to play both center and guard gives Philadelphia flexibility, especially if the coaching staff wants to limit changes at once. The Eagles could place Kendall directly at left guard and leave Cam Jurgens at center and Tyler Steen at right guard. That would preserve continuity at four of the five starting positions.
#played

1 month ago
Enbridge Inc. (NYSE:ENB) has agreed to buy Blackstone-owned Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its presence in the U.S. liquids pipeline market. The deal includes a 75% stake in the 1,050-mile Pony Express Pipeline, a 51% interest in the Powder River Gateway system, around 8.4 million barrels of storage capacity and crude marketing operations.
Pony Express can move roughly 460,000 barrels of crude per day between the Rockies and the Cushing, Oklahoma, hub. The deal also gives Enbridge greater exposure to major producing regions, including the Bakken, Powder River and Denver-Julesburg basins.
The acquisition gives Enbridge Inc. (NYSE:ENB) a stronger position in U.S. crude transportation at a time when domestic oil production is expected to remain important. Pony Express gives the company a larger presence in the Rockies and complements its existing Express-Platte system.
That combination could allow Enbridge to bring the operations together more efficiently and find synergies across its wider liquids network. The deal also gives Enbridge more than additional pipeline capacity. It adds storage infrastructure and crude marketing operations, giving the company more flexibility in how it manages and optimizes volumes. Bringing these parts of the business together could also improve the economics of the acquired **** ets.
Enbridge Inc. (NYSE:ENB) expects the **** ets to generate significant free cash flow. The company also says the transaction should add to distributable cash flow per share in the first full year after closing. The **** ets also offer relatively predictable infrastructure-style cash flows. This means Enbridge does not need higher crude prices to benefit from the acquisition. The deal fits with the company's broader strategy of growing its fee-based energy infrastructure business across North America, backed by its C$41 billion secured growth backlog.
#enbridge #cash #gives #business
1 month ago
The Detroit Lions now have a substantial cushion in terms of financial stability heading into their first game of the 2026 campaign. This will allow Brad Holmes and the rest of the front office more flexibility in whatever direction they see fit whether that is in-season moves or in preparation for the contracts they will need to negotiate next offseason.
But it is also an indicator of how much faith the team has put into their top two players. Amon-Ra St. Brown and Penei Sewell have each restructured their contracts without changing how vital they are to the squad.
Detroit Lions wide receiver Amon-Ra St. Brown (14) practices during mini camp at Meijer Performance Center in Allen Park on Wednesday, June 17, 2026.
The Lions have restructured the contracts of wideout Brown and offensive tackle Sewell, creating about $35.6 million in salary cap ***** e, per Spotrac. The news was announced on September 12, just one day ahead of the Lions' season opener against the New Orleans Saints.
Lions restructure contracts of Amon-Ra St. Brown and Penei Sewell; create $35.6M in salary cap ***** e, per spotrac.
#brown #detroit #season #restructured


1 month ago
The European Central Bank is likely to deliver a 25 basis-point rate hike at its meeting concluding today. But while the direction of travel may be clear for now, the path beyond September is anything but.
The ECB is likely to keep its powder dry beyond today, with the path thereafter determined by how the economy and, above all, inflation respond to the renewed energy shock. The key message from the Governing Council is therefore likely to be hawkish: further hike(s) may be warranted if inflation risks intensify, but policymakers will want to retain flexibility rather than pre-commit to any specific policy path.
There is only modest evidence so far that inflation expectations are becoming less firmly anchored, although there may be growing concern that second-round effects may eventually turn a temporary energy shock into a more persistent inflation problem. The challenge for the ECB is that the economy has so far proven more resilient than expected, making an upside revision to its growth projections probable. Output rose more than anticipated during the second quarter, and business surveys are suggesting solid momentum ahead.
That resilience matters. A weaker economy would give policymakers more room to look through an energy-driven inflation spike. A more robust economy, by contrast, makes it harder to ***** ume that higher energy prices may simply wash through absent affecting wages, services prices and broader inflation behaviour.
Euro area headline inflation rose to 3.3% year on year last month (Figure 1), although the easing in core inflation to 2.4% does offer some reassurance. Underlying inflation measures have stayed comparatively moderate, wage pressures are still contained and there is, as yet, only sparse evidence that the energy shock is generating widespread second-round effects.
#economy #path #shock #today


1 month ago
Nucor Corporation (NUE) is the largest steel producer and recycler in the U.S., with operations spanning steel mills, steel products, and raw materials. Headquartered in Charlotte, North Carolina, the company produces a broad range of steel, from sheet and structural steel to joists, girders, and tubing, serving critical end markets such as construction, infrastructure, manufacturing, and energy.
With a market capitalization of $58.2 billion, NUE firmly sits in the large-cap category, reflecting its scale, industry influence, and leadership within the U.S. steel sector. Unlike traditional blast-furnace producers, Nucor primarily uses scrap-based electric arc furnaces (EAFs), giving it greater production flexibility and a comparatively lower environmental footprint.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for **** e
#steel #north


1 month ago
On August 27, AstraZeneca PLC (NYSE:AZN) and Amgen Inc. (NASDAQ:AMGN) scored a shared clinical victory. Positive high-level results from the Phase III CROSSING trial showed that their co-developed severe asthma drug, TEZSPIRE, achieved statistically significant and clinically meaningful improvements across both co-primary endpoints, histologic remission and the frequency/severity of dysphagia, and all key secondary endpoints at week 24 in patients with eosinophilic esophagitis. These benefits were sustained through week 52 across both tested doses, accompanied by a safety profile consistent with its approved indications. While CROSSING highlights their joint R&D success, a closer look at their standalone financial performance reveals distinct growth trajectories.
Both pharmaceutical giants delivered solid Q2 2026 results, but AstraZeneca is showing stronger overall financial momentum. AstraZeneca PLC (NYSE:AZN)'s Q2 revenue increased 6% year over year to $15.38 billion, supported by its Oncology franchise, which grew 18% in H1 to $14.12 billion, and its Rare Disease portfolio, which increased 13%. Core EPS rose 21% to $2.63, beating expectations, while management reaffirmed its full-year 2026 outlook for mid-to-high single-digit revenue growth and low double-digit Core EPS growth.
Amgen Inc. (NASDAQ:AMGN) reported Q2 revenue of $10.1 billion, up 10% year over year, while non-GAAP EPS increased 4% to $6.29. Although its key growth products advanced 26%, mature products faced significant biosimilar pressure, with Prolia revenue declining 32% and XGEVA falling 34%. Amgen nevertheless raised its 2026 revenue guidance midpoint to $39.4 billion.
Overall, AZN holds the financial edge due to stronger EPS growth, broader portfolio momentum, and less exposure to the biosimilar erosion affecting AMGN's mature products.
Amgen's bull case is supported by robust growth in key products, which increased 26%, and $3.5 billion in Q2 free cash flow, providing substantial capital flexibility. Wells Fargo raised its Amgen price target to $435 from $400 on September 4, citing potential upside from HORIZON and pipeline ****** ets such as olpasiran. New Phase III VESALIUS-CV data also showed Repatha reduced the risk of death by 20% in high-risk adults without a prior heart attack or stroke, with heart attack risk reductions emerging as early as six months. However, accelerating biosimilar competition affecting legacy franchises such as Prolia and XGEVA remains a key risk to sustained margin expansion.
#revenue #astrazeneca #increased #products
1 month ago
On August 11, Humana Inc. (NYSE:HUM) announced that its Medicaid plan, Humana Healthy Horizons in Indiana, is collaborating with HealthStream, Inc. (NASDAQ:HSTM). The partnership expands access to workforce training for caregivers, aiming to recruit and retain talent in rural and underserved communities. While one provides healthcare coverage and the other builds the software to train healthcare workers, both companies are capitalizing on the industry's critical focus: solving caregiving shortages and optimizing healthcare delivery.
HealthStream emerges as the operationally cleaner, higher-growth performer, while Humana continues to navigate a more complex transition marked by regulatory and profitability pressures. Humana Inc. (NYSE:HUM) reported Q2 2026 GAAP EPS of $5.73 and adjusted EPS of $7.61, with an Insurance segment GAAP benefit ratio of 91.2%. The company reaffirmed its full-year adjusted EPS guidance of at least $9.00 but lowered its FY 2026 GAAP EPS forecast to at least $6.52 from $8.36, reflecting non-cash adjustments and value creation charges. Although individual Medicare Advantage membership is expected to grow approximately 25% in 2026, lower Star Ratings remain a significant drag on profitability.
HealthStream, Inc. (NASDAQ:HSTM), meanwhile, delivered record Q2 2026 results, with revenue rising 12.5% year over year to $83.7 million. Operating income increased 41.4% to $8.3 million, while net income climbed 23.8% to $6.7 million, or $0.23 per diluted share. Adjusted EBITDA also increased 16.9% to $20.6 million. The company's debt-free balance sheet, supported by $66.7 million in cash and cash equivalents, further strengthens its financial flexibility. While Humana operates at substantially greater scale, HealthStream is demonstrating stronger operational leverage, margin expansion, and balance sheet flexibility.
Humana's bull case is supported by strong Medicare Advantage membership growth, with the company targeting a 25% increase in 2026, alongside strategic expansion of its CenterWell primary care business and state Medicaid footprint, including its recent Illinois win. These initiatives could strengthen its long-term recovery and expand its addressable market. However, the bear case centers on elevated medical benefit ratios, which reached 91.2% in Q2, as well as regulatory pressures in Medicaid and continued Medicare Star Ratings headwinds. These factors could further squeeze margins and weigh on net earnings.
#healthcare #year
1 month ago
The Campbell's Company (NASDAQ:CPB) is taking aggressive steps to turn around its fortunes, but the food company faces a difficult test. It's whether the $500 million cost-savings plan can rebuild margins and earnings as weak demand continues to pressure sales.
The company has already cut more than 550 jobs and closed two snack plants as part of the cost-cutting efforts. Moreover, it has reduced its quarterly dividend by 36% to conserve cash. Yet management expects another year of declining sales. That means the turnaround hinges on Campbell's ability to improve efficiency while stabilizing sales.
The need for restructuring became clear in the latest quarter. Sales fell 8% to $2.1 billion, and the company swung to a $69 million loss from a $145 million profit a year ago.
The Campbell's Company (NASDAQ:CPB) now plans to cut $500 million in costs by fiscal 2030. The savings are expected to support margin and allow greater investment in the brands. The cost-cutting program includes the closure of two snack plants and a workforce reduction affecting around 13% of Campbell's salaried employees.
Campbell's strategy has a clear financial logic. Lower costs should improve cash flow, help the company absorb inflationary pressures, and provide greater flexibility to invest in strengthening its brands. But the desired turnaround would only be possible if Campbell's can stabilize its underlying business at the same time.
#sales