

18 hours ago
For the first time in 60 years, Warren Buffett watched someone else lead Berkshire Hathaway's (NYSE: BRKA)(NYSE: BRKB) annual meeting. That doesn't mean Buffett was absent from that May 2 event, though. He was there on the sidelines and had time to field questions in an unofficial capacity.
In a CNBC interview that day, Buffett was asked whether stocks felt expensive. His answer was that he had never seen people more in the mood to gamble and that "prices for an awful lot of things will look very silly."
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Warren Buffett is and always has been a long-term investor. But if things are about to get "silly," should investors adjust their portfolios?
More than 1,000 new exchange-traded funds (ETFs) have launched in 2026 so far. A lot of them involve leverage, ultra-short-term options, and ridiculously high yields. In other words, they're the kinds of products that don't resemble anything that Warren Buffett would consider.
#warren #years
In a CNBC interview that day, Buffett was asked whether stocks felt expensive. His answer was that he had never seen people more in the mood to gamble and that "prices for an awful lot of things will look very silly."
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Warren Buffett is and always has been a long-term investor. But if things are about to get "silly," should investors adjust their portfolios?
More than 1,000 new exchange-traded funds (ETFs) have launched in 2026 so far. A lot of them involve leverage, ultra-short-term options, and ridiculously high yields. In other words, they're the kinds of products that don't resemble anything that Warren Buffett would consider.
#warren #years

2 days ago
Berkshire bought 924,281 SIRI shares across three days, raising its stake to over 125 million shares at roughly $27 million total.
Sirius raised full-year guidance for the second straight quarter, with free cash flow rising 14% and EBITDA margins expanding to 32%.
Pandora monthly users fell 7%, net leverage sits at 3.3x adjusted EBITDA, and management warned of a harder Q4 for subscribers.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Sirius XM didn't make the cut. Enter your email to see the names that beat SIRI. The report is free. Enter your email and see if any of your stocks made the cut.
Berkshire Hathaway (NYSE:BRK-B) disclosed in a Form 4 filed Nov. 3, 2026, that it bought 924,281 shares of Sirius XM (NASDAQ:SIRI) on Oct. 30, Nov. 2, and Nov. 3. The purchases raised its beneficial ownership to 125,731,398 shares. Investing.com estimated the buying at about $26.9 million, with weighted average prices of $28.8913 on Oct. 30 and $30.233 on Nov. 3.
#shares #berkshire #raised #free
Sirius raised full-year guidance for the second straight quarter, with free cash flow rising 14% and EBITDA margins expanding to 32%.
Pandora monthly users fell 7%, net leverage sits at 3.3x adjusted EBITDA, and management warned of a harder Q4 for subscribers.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Sirius XM didn't make the cut. Enter your email to see the names that beat SIRI. The report is free. Enter your email and see if any of your stocks made the cut.
Berkshire Hathaway (NYSE:BRK-B) disclosed in a Form 4 filed Nov. 3, 2026, that it bought 924,281 shares of Sirius XM (NASDAQ:SIRI) on Oct. 30, Nov. 2, and Nov. 3. The purchases raised its beneficial ownership to 125,731,398 shares. Investing.com estimated the buying at about $26.9 million, with weighted average prices of $28.8913 on Oct. 30 and $30.233 on Nov. 3.
#shares #berkshire #raised #free

6 days ago
Welltower (WELL) pays out only 52% of normalized FFO, while Ventas (VTR) raised its dividend 8% and improved leverage to a decade-low 4.4x.
Baby boomers turning 80 now number nearly 70 million, yet builders started only 1,000 new senior housing units last quarter.
Sabra's 6% yield comes with a dividend flat since 2020 and a $102 million non-cash loan loss provision recorded in Q2.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Welltower didn't make the cut. Enter your email to see the names that beat WELL. The report is free. Enter your email and see if any of your stocks made the cut.
Senior housing has one of the clearest demand stories in real estate. On its third-quarter call, Ventas (NYSE:VTR) noted that the baby boomer generation, a cohort of nearly 70 million individuals, began turning 80 this year. Builders started only 1,000 units of new senior housing in the quarter. More 80-year-olds and very few new buildings push occupancy and rents higher, but operator health, labor costs, and government reimbursement decide how much of that reaches shareholders. The four REITs below are all equity REITs that own buildings. None is a mortgage REIT. Dividend safety is measured on FFO, FAD, or AFFO coverage, the cash-flow figures REITs actually pay dividends from.
#senior #million #housing #ventas
Baby boomers turning 80 now number nearly 70 million, yet builders started only 1,000 new senior housing units last quarter.
Sabra's 6% yield comes with a dividend flat since 2020 and a $102 million non-cash loan loss provision recorded in Q2.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Welltower didn't make the cut. Enter your email to see the names that beat WELL. The report is free. Enter your email and see if any of your stocks made the cut.
Senior housing has one of the clearest demand stories in real estate. On its third-quarter call, Ventas (NYSE:VTR) noted that the baby boomer generation, a cohort of nearly 70 million individuals, began turning 80 this year. Builders started only 1,000 units of new senior housing in the quarter. More 80-year-olds and very few new buildings push occupancy and rents higher, but operator health, labor costs, and government reimbursement decide how much of that reaches shareholders. The four REITs below are all equity REITs that own buildings. None is a mortgage REIT. Dividend safety is measured on FFO, FAD, or AFFO coverage, the cash-flow figures REITs actually pay dividends from.
#senior #million #housing #ventas

7 days ago
NBA rumors: 2 Clippers named as Thunder trade targets in addition to Herb Jones, Ty Jerome appeared first on ClutchPoints. Add ClutchPoints as a Preferred Source by clicking here.
After the Oklahoma City Thunder's first loss of the season in a 120-96 blowout to the Dallas Mavericks, will GM Sam Presti make a move for either New Orleans Pelicans' Herb Jones or Memphis Grizzlies' Ty Jerome sooner rather than later? The injuries continue to stack up for the Thunder, as Alex Caruso and Chet Holmgren were both out in addition to Jalen Williams and Cason Wallace's setbacks ahead of Wednesday's game against the Mavericks.
For a team like the LA Clippers, who lost first-round picks for the next five seasons, Derrick Jones Jr. and Kris Dunn have also been mentioned as potential trade targets for Presti, who has more future firsts than any other GM in the NBA. While the Thunder are in no rush to make a trade, Presti will most likely do so at some point before this year's deadline, as ClutchPoints' Brett Siegel noted, per Clutch Scoops.
"The Thunder are going to make at least one trade. That's a given," Siegel said. "We know that Sam Presti is always very adventagous on the trade market. We didn't think that they were going to make a trade last season. And then, Jared McCain fell in their lap because they leveraged some draft picks — first-round and second-round picks — that we're going to be of use to them. We could see something similar happen this year, where it's not going to be a big splashy name; a $20-plus million guy.
Watch sports LIVE with fuboTV (free trial)
#jones #clutchpoints #make
After the Oklahoma City Thunder's first loss of the season in a 120-96 blowout to the Dallas Mavericks, will GM Sam Presti make a move for either New Orleans Pelicans' Herb Jones or Memphis Grizzlies' Ty Jerome sooner rather than later? The injuries continue to stack up for the Thunder, as Alex Caruso and Chet Holmgren were both out in addition to Jalen Williams and Cason Wallace's setbacks ahead of Wednesday's game against the Mavericks.
For a team like the LA Clippers, who lost first-round picks for the next five seasons, Derrick Jones Jr. and Kris Dunn have also been mentioned as potential trade targets for Presti, who has more future firsts than any other GM in the NBA. While the Thunder are in no rush to make a trade, Presti will most likely do so at some point before this year's deadline, as ClutchPoints' Brett Siegel noted, per Clutch Scoops.
"The Thunder are going to make at least one trade. That's a given," Siegel said. "We know that Sam Presti is always very adventagous on the trade market. We didn't think that they were going to make a trade last season. And then, Jared McCain fell in their lap because they leveraged some draft picks — first-round and second-round picks — that we're going to be of use to them. We could see something similar happen this year, where it's not going to be a big splashy name; a $20-plus million guy.
Watch sports LIVE with fuboTV (free trial)
#jones #clutchpoints #make


11 days ago
This story was originally published on Marketing Dive. To receive daily news and insights, subscribe to our free daily Marketing Dive newsletter.
Walmart is reworking an iconic piece of pop culture history to bolster its holiday marketing and a "Who Knew?" brand platform starring Walton Goggins. The goal is to offer a unified marketing push with multigenerational appeal throughout the crucial gift-giving season.
The retailer in the past ran separate campaigns around different legs of the holiday season, such as the ramp-up to Black Friday, but has leveraged "Who Knew?" to streamline its storytelling. "Who Knew?," which launched last year, was developed to dispel misperceptions about the brand and position it as more style- and trend-forward as Walmart wins over higher-income shoppers.
"The holidays are an incredibly cluttered period of time from an advertising standpoint, and so the ability to break through is really important," Walmart CMO William White said in an interview. "Having one [theme], one campaign throughout the season allows a really quick read for customers to know it's Walmart."
#dive
Walmart is reworking an iconic piece of pop culture history to bolster its holiday marketing and a "Who Knew?" brand platform starring Walton Goggins. The goal is to offer a unified marketing push with multigenerational appeal throughout the crucial gift-giving season.
The retailer in the past ran separate campaigns around different legs of the holiday season, such as the ramp-up to Black Friday, but has leveraged "Who Knew?" to streamline its storytelling. "Who Knew?," which launched last year, was developed to dispel misperceptions about the brand and position it as more style- and trend-forward as Walmart wins over higher-income shoppers.
"The holidays are an incredibly cluttered period of time from an advertising standpoint, and so the ability to break through is really important," Walmart CMO William White said in an interview. "Having one [theme], one campaign throughout the season allows a really quick read for customers to know it's Walmart."
#dive

30 days ago
Updated on: October 7, 2026 / 5:42 AM EDT / CBS News
London — The involvement of a small American firm linked to **** ociates of President Trump in an energy project in Bosnia and Herzegovina worth more than $1.5 billion has raised questions about how the White House could be using its leverage in the fragile Balkan state.
U.S. lawmakers accuse the Trump administration of lifting sanctions on Bosnian Serb separatist leader Milorad Dodik in an effort to enrich and empower allies of Mr. Trump, and of undermining longstanding U.S. foreign policy interests in the region in the process.
On Sunday, Mr. Trump was hailed by Dodik after his Serb nationalist party won one of Bosnia and Herzegovina's three presidency seats, which are split between Bosnia's Muslim minority, known as Bosniaks, as well as Serb and Croat ethnic groups under the country's complex power-sharing electoral system.
"If it had not been for Donald Trump's magnificent victory … we would probably be political corpses today," Dodik told supporters in a speech, in which he also thanked Russian President Vladimir Putin for his support.
#Trump #bosnia #updated
London — The involvement of a small American firm linked to **** ociates of President Trump in an energy project in Bosnia and Herzegovina worth more than $1.5 billion has raised questions about how the White House could be using its leverage in the fragile Balkan state.
U.S. lawmakers accuse the Trump administration of lifting sanctions on Bosnian Serb separatist leader Milorad Dodik in an effort to enrich and empower allies of Mr. Trump, and of undermining longstanding U.S. foreign policy interests in the region in the process.
On Sunday, Mr. Trump was hailed by Dodik after his Serb nationalist party won one of Bosnia and Herzegovina's three presidency seats, which are split between Bosnia's Muslim minority, known as Bosniaks, as well as Serb and Croat ethnic groups under the country's complex power-sharing electoral system.
"If it had not been for Donald Trump's magnificent victory … we would probably be political corpses today," Dodik told supporters in a speech, in which he also thanked Russian President Vladimir Putin for his support.
#Trump #bosnia #updated



30 days ago
AGNC's Q2 spread income of 40 cents per share covered its 36-cent dividend, but the payout has been cut three times since 2015.
Annaly raised its quarterly dividend from $0.70 to $0.75, while Dynex rebounded to 6.4% economic return after both posted Q1 losses.
If Q3 spread income falls below 36 cents or book value drops below $8.38, shareholders' own capital funds the dividend and a cut becomes likely.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
AGNC Investment (NASDAQ:AGNC) is a mortgage REIT that borrows short-term money in the repo market, buys agency mortgage-backed securities, and keeps the spread between bond yields and borrowing costs. Leverage of 7.4 times tangible equity magnifies both gains and losses.
#times
Annaly raised its quarterly dividend from $0.70 to $0.75, while Dynex rebounded to 6.4% economic return after both posted Q1 losses.
If Q3 spread income falls below 36 cents or book value drops below $8.38, shareholders' own capital funds the dividend and a cut becomes likely.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
AGNC Investment (NASDAQ:AGNC) is a mortgage REIT that borrows short-term money in the repo market, buys agency mortgage-backed securities, and keeps the spread between bond yields and borrowing costs. Leverage of 7.4 times tangible equity magnifies both gains and losses.
#times
30 days ago
Certain celebrities don't just enter a room — they redefine it with an unforgettable presence. Whether it's a mesmerizing gaze, a striking smile, or a powerful stature, these stars have built iconic careers around characteristics that make them truly one-of-a-kind. We're pulling back the curtain to celebrate the bold, the beautiful, and the unique figures who became famous for more than just talent.
Jen Lowery/ Mega / MEGA
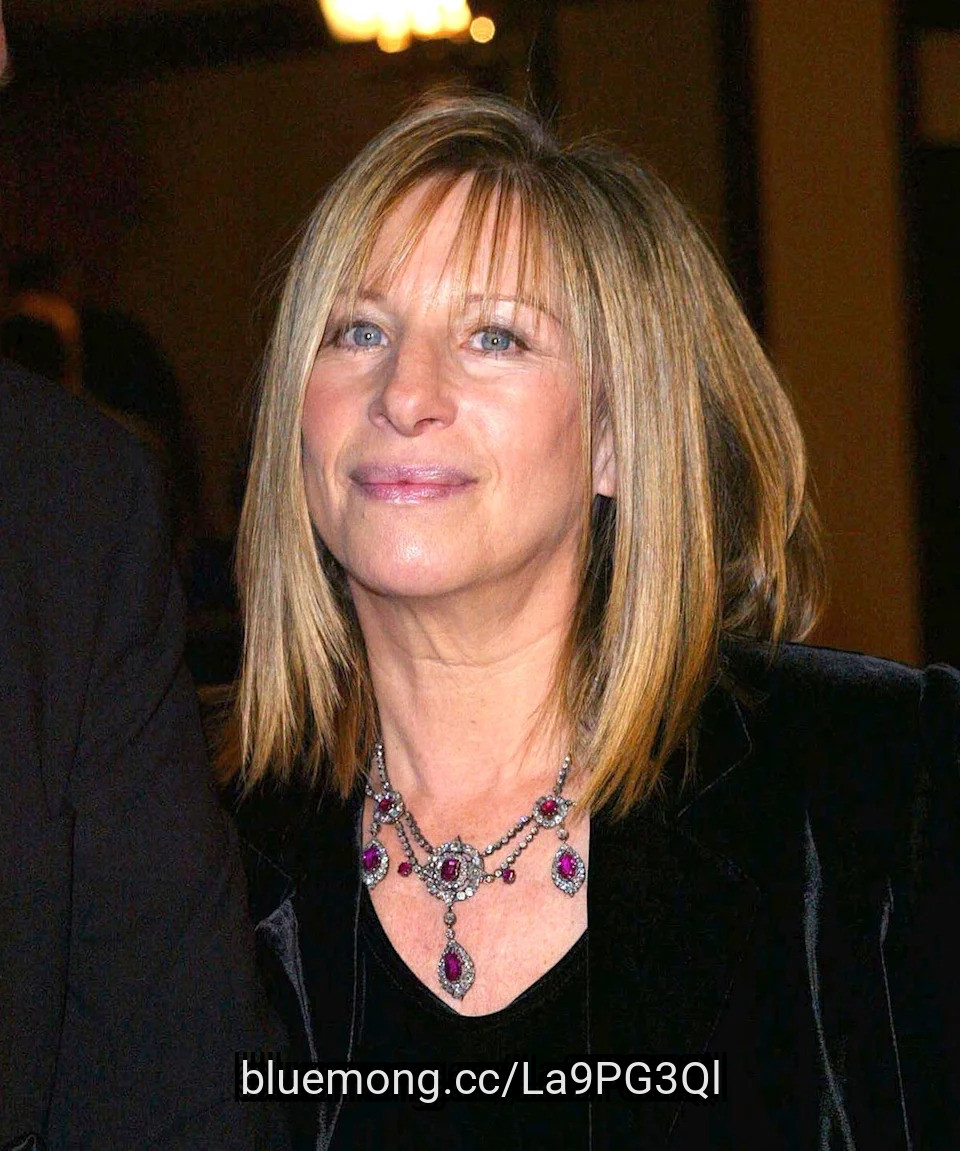
Barbra Streisand's inimitable profile and expressive eyes have become nearly as legendary as her storied voice. Throughout her decades-spanning career, she leveraged her distinctive look, refusing pressures to change and instead turning her uniqueness into a signature of elegance and confidence. Despite being told early in her career to alter her appearance, she resisted undergoing a rhinoplasty in part because of the risk it posed to her singing voice, as reported by TODAY.
Jen Lowery/ Mega / MEGA
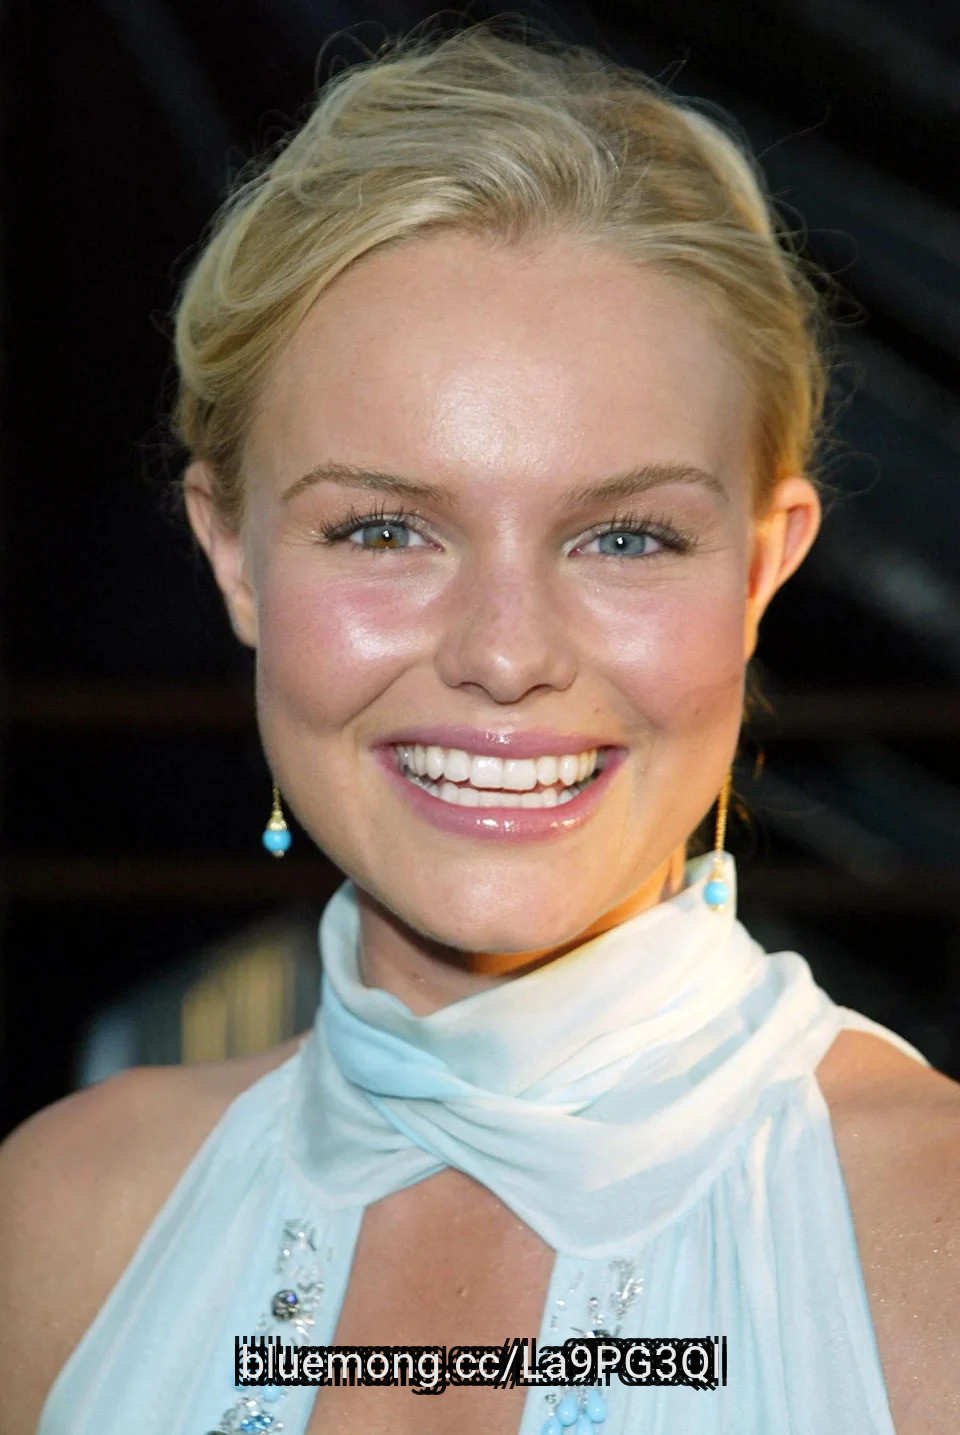
Kate Bosworth's different-colored eyes have made her stand out in every role she takes on. This rare feature gives her an instantly recognizable appearance and adds an enchanting element to her on-screen presence. She has a naturally occurring condition called heterochromia; one eye is blue while the other is partially hazel — a trait affecting less than one percent of the population, per Optometrists.org.
#mega #certain #we 're
Jen Lowery/ Mega / MEGA
Barbra Streisand's inimitable profile and expressive eyes have become nearly as legendary as her storied voice. Throughout her decades-spanning career, she leveraged her distinctive look, refusing pressures to change and instead turning her uniqueness into a signature of elegance and confidence. Despite being told early in her career to alter her appearance, she resisted undergoing a rhinoplasty in part because of the risk it posed to her singing voice, as reported by TODAY.
Jen Lowery/ Mega / MEGA
Kate Bosworth's different-colored eyes have made her stand out in every role she takes on. This rare feature gives her an instantly recognizable appearance and adds an enchanting element to her on-screen presence. She has a naturally occurring condition called heterochromia; one eye is blue while the other is partially hazel — a trait affecting less than one percent of the population, per Optometrists.org.
#mega #certain #we 're

30 days ago
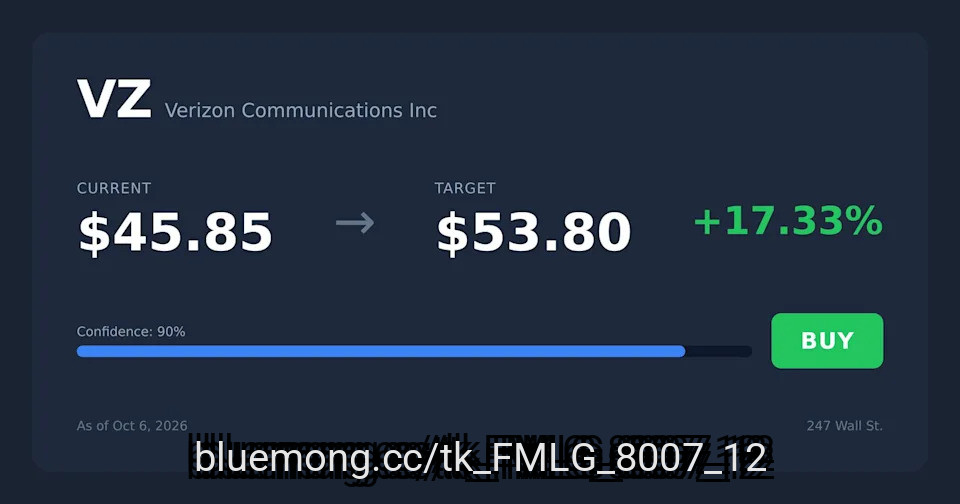
Verizon yields 6% versus AT&T's 5%, but AT&T slashed its dividend 47% in 2022 while Verizon has raised its payout for 20 consecutive years.
AT&T's EchoStar (SATS) spectrum purchase pushes its leverage from 2.68x toward 3.2x, delaying a return to its 2.5x target by roughly three years.
Verizon's 2026 free cash flow grows 9-10% to roughly $22B; AT&T's management says dividends and buybacks will consume essentially 100% of its FCF.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Verizon (NYSE:VZ) orAT&T (NYSE:T): Which yield can you trust to keep paying, and growing, for the next decade? I pick Verizon, and the gap between the two is wider than the reported yields suggest.
#verizon #years
AT&T's EchoStar (SATS) spectrum purchase pushes its leverage from 2.68x toward 3.2x, delaying a return to its 2.5x target by roughly three years.
Verizon's 2026 free cash flow grows 9-10% to roughly $22B; AT&T's management says dividends and buybacks will consume essentially 100% of its FCF.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Verizon (NYSE:VZ) orAT&T (NYSE:T): Which yield can you trust to keep paying, and growing, for the next decade? I pick Verizon, and the gap between the two is wider than the reported yields suggest.
#verizon #years


1 month ago
Exchanges liquidated $403.58 million in leveraged crypto longs within one hour as Bitcoin (BTC) slid to about $83,800. That equals about 0.27% of open interest, the total value of unsettled futures contracts.
Longs made up 97% of the $415.33 million total, so the flush hit one side of the market. However, it cleared only a small fraction of the leverage still outstanding.
The selling arrived in one burst. CoinGlass, a derivatives data tracker, logged 98% of the $412.99 million in four-hour long liquidations inside the final hour.
Over 24 hours, longs made up $487.02 million of $554.76 million in liquidations. That hour alone holds about 83% of the day's long total.
By comparison, the 10th-largest event on CoinGlass's all-time list reached $2.77 billion, about five times the 24-hour total.
#however
Longs made up 97% of the $415.33 million total, so the flush hit one side of the market. However, it cleared only a small fraction of the leverage still outstanding.
The selling arrived in one burst. CoinGlass, a derivatives data tracker, logged 98% of the $412.99 million in four-hour long liquidations inside the final hour.
Over 24 hours, longs made up $487.02 million of $554.76 million in liquidations. That hour alone holds about 83% of the day's long total.
By comparison, the 10th-largest event on CoinGlass's all-time list reached $2.77 billion, about five times the 24-hour total.
#however

1 month ago
Sarah Ferguson reportedly wants King Charles and senior royals to "throw her a bone" before she considers other options. The former **** ss of York was said to be delaying a tell-all while hoping for renewed royal acceptance.
A source claimed she still believed there was "a place for her within the royal family." However, the insider warned that continued exclusion could change her position. Her reported strategy mixed loyalty, leverage, and hopes for a royal comeback.
As per a Closer Online report, Sarah reportedly reconsidered her options. The source said Earl Spencer's memoir offered "a good reminder" of the disruption a royal tell-all could create. Moreover, the insider claimed Sarah's long history with the royals gave her considerable material. They said she could potentially do "a lot more damage to the King's legacy" than Spencer. Still, a spokesperson firmly denied a current memoir project. The representative said, "She is not writing a personal memoir."
However, the insider claimed Sarah Ferguson was keeping that possibility available while hoping for another route. The source said she was "holding off on a book deal for now." According to them, Sarah remained convinced "there's still a place for her within the royal family." She reportedly hoped loyalty would persuade King Charles and others to "cut her a break." That could mean "a path back towards respectability" or "at the very least a place to live." Meanwhile, the source said she still had "the tell-all up her sleeve" if that effort failed.
Additionally, the insider claimed Sarah was sending messages toward both Charles and Prince William. She was reportedly "imploring William and Charles to throw her a bone." The source added that she did not want to "go against the family if she can help it." Still, the report said Sarah could pursue other money-making opportunities if reconciliation failed. Those possibilities reportedly included reality television and rebuilding her social media profile. For now, Buckingham Palace had made no direct statement about Sarah. Meanwhile, senior royals had reportedly continued distancing themselves from the former York household.
#reportedly #royal
A source claimed she still believed there was "a place for her within the royal family." However, the insider warned that continued exclusion could change her position. Her reported strategy mixed loyalty, leverage, and hopes for a royal comeback.
As per a Closer Online report, Sarah reportedly reconsidered her options. The source said Earl Spencer's memoir offered "a good reminder" of the disruption a royal tell-all could create. Moreover, the insider claimed Sarah's long history with the royals gave her considerable material. They said she could potentially do "a lot more damage to the King's legacy" than Spencer. Still, a spokesperson firmly denied a current memoir project. The representative said, "She is not writing a personal memoir."
However, the insider claimed Sarah Ferguson was keeping that possibility available while hoping for another route. The source said she was "holding off on a book deal for now." According to them, Sarah remained convinced "there's still a place for her within the royal family." She reportedly hoped loyalty would persuade King Charles and others to "cut her a break." That could mean "a path back towards respectability" or "at the very least a place to live." Meanwhile, the source said she still had "the tell-all up her sleeve" if that effort failed.
Additionally, the insider claimed Sarah was sending messages toward both Charles and Prince William. She was reportedly "imploring William and Charles to throw her a bone." The source added that she did not want to "go against the family if she can help it." Still, the report said Sarah could pursue other money-making opportunities if reconciliation failed. Those possibilities reportedly included reality television and rebuilding her social media profile. For now, Buckingham Palace had made no direct statement about Sarah. Meanwhile, senior royals had reportedly continued distancing themselves from the former York household.
#reportedly #royal


2 months ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

2 months ago
On September 9, 2026, Independence Realty Trust, Inc. (NYSE:IRT) and Centerspace announced a definitive all-stock merger agreement. It creates a combined middle-market apartment REIT with a pro forma equity market capitalization of about $5.0 billion and a total enterprise value of approximately $8.1 billion, encompassing more than 44,000 units.
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management


2 months ago
On September 17, B. Riley initiated coverage of Nokia Oyj (NYSE:NOK), giving the stock a Buy rating and setting the price target at $15. The firm pointed to the company's position in telecom infrastructure, cloud software, and hardware networking solutions.
Riley noted that the company's networking businesses are seeing strong growth. In Q2 2026, Optical Networks revenue increased 20% year-over-year, while IP Networks grew 16%. Net sales to AI and cloud customers also surged 105%. The research firm noted that hyperscalers continue to purchase Nokia Oyj's (NYSE:NOK) AI networking products to support large-scale computing clusters.
The company's AI and cloud opportunity is also reflected in its order book. Nokia Oyj (NYSE:NOK) reported EUR 2.8 billion in AI and cloud order intake during the second quarter of 2026. B. Riley pointed out that this provides revenue visibility into 2027. The firm also noted that the carrier inventory correction cycle that had weighed on global capital expenditures has now concluded.
Riley derived its $15 price target using a sum-of-the-parts valuation that separates the company's legacy ****** ets from its data center business. The firm applied a premium hardware multiple to the data center segment, reflecting its view of the potential operating leverage in that business.
Profitability Remains a Concern
#riley #NYSE #firm
Riley noted that the company's networking businesses are seeing strong growth. In Q2 2026, Optical Networks revenue increased 20% year-over-year, while IP Networks grew 16%. Net sales to AI and cloud customers also surged 105%. The research firm noted that hyperscalers continue to purchase Nokia Oyj's (NYSE:NOK) AI networking products to support large-scale computing clusters.
The company's AI and cloud opportunity is also reflected in its order book. Nokia Oyj (NYSE:NOK) reported EUR 2.8 billion in AI and cloud order intake during the second quarter of 2026. B. Riley pointed out that this provides revenue visibility into 2027. The firm also noted that the carrier inventory correction cycle that had weighed on global capital expenditures has now concluded.
Riley derived its $15 price target using a sum-of-the-parts valuation that separates the company's legacy ****** ets from its data center business. The firm applied a premium hardware multiple to the data center segment, reflecting its view of the potential operating leverage in that business.
Profitability Remains a Concern
#riley #NYSE #firm

2 months ago
On September 9, 2026, Reuters reported that CEO Brian Niccol's first two years as Starbucks Corporation (NASDAQ:SBUX) CEO have succeeded in bringing customers back to the coffee chain. Comparable sales rose 7.9% in the fiscal third quarter for a fourth straight quarter of improvement, but his "Back to Starbucks" restructuring has raised costs and squeezed margins along the way. Global operating margin has fallen to 12.9% from 15.8% two years earlier. Niccol, who marks his second anniversary in the role, now faces pressure to convert the sales recovery into the sustainable profit growth investors are demanding.
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#
2 months ago
Toward the end of the lightning round on September 17, a caller asked for Mad Money's host Jim Cramer's thoughts on Iron Mountain Incorporated (NYSE:IRM), and he replied:
It's been an incredible stock. It's a real estate investment trust, basically. And you know, we know that they shred, 3% yield, down 20 points from its high. I think it's a buy.
Iron Mountain Incorporated (NYSE:IRM) operates a highly durable business model centered on physical records management, secure document destruction, and expanding digital infrastructure. In Q2, total revenue reached $2.03 billion, representing an 18.7% increase year-over-year and 16.8% organic growth. The core physical storage business provides reliable cash flow, with storage rental revenue expanding 11.5% year-over-year excluding foreign-exchange effects across a global customer base of 240,000. Adjusted funds from operations grew 17% to $432.7 million, or $1.44 per share.
At the same time, management has channeled capital into scaling higher-growth segments, including digital solutions, ***** et lifecycle management, and data center operations. The data center segment posted 39% revenue growth during the second quarter, securing 110 megawatts in new leases through July and increasing power capacity across major enterprise markets. Operating as a real estate investment trust, the company maintains a quarterly dividend of $0.864 per share, offering shareholders a forward yield of over 3%.
On the other hand, Iron Mountain Incorporated (NYSE:IRM) faces risks inherent to capital-intensive real estate infrastructure expansion. Rapid buildouts of data center power capacity demand substantial capital expenditure, leading to elevated leverage across the balance sheet. Long-term debt, net of the current portion, reached approximately $17.1 billion at the end of the second quarter, increasing sensitivity to interest rate fluctuations and refinancing costs.
#revenue #Growth
It's been an incredible stock. It's a real estate investment trust, basically. And you know, we know that they shred, 3% yield, down 20 points from its high. I think it's a buy.
Iron Mountain Incorporated (NYSE:IRM) operates a highly durable business model centered on physical records management, secure document destruction, and expanding digital infrastructure. In Q2, total revenue reached $2.03 billion, representing an 18.7% increase year-over-year and 16.8% organic growth. The core physical storage business provides reliable cash flow, with storage rental revenue expanding 11.5% year-over-year excluding foreign-exchange effects across a global customer base of 240,000. Adjusted funds from operations grew 17% to $432.7 million, or $1.44 per share.
At the same time, management has channeled capital into scaling higher-growth segments, including digital solutions, ***** et lifecycle management, and data center operations. The data center segment posted 39% revenue growth during the second quarter, securing 110 megawatts in new leases through July and increasing power capacity across major enterprise markets. Operating as a real estate investment trust, the company maintains a quarterly dividend of $0.864 per share, offering shareholders a forward yield of over 3%.
On the other hand, Iron Mountain Incorporated (NYSE:IRM) faces risks inherent to capital-intensive real estate infrastructure expansion. Rapid buildouts of data center power capacity demand substantial capital expenditure, leading to elevated leverage across the balance sheet. Long-term debt, net of the current portion, reached approximately $17.1 billion at the end of the second quarter, increasing sensitivity to interest rate fluctuations and refinancing costs.
#revenue #Growth

2 months ago
Trip.com Group Limited (NASDAQ:TCOM) reported second-quarter 2026 net revenue of RMB15.7 billion, up 6% year over year, in results released September 15. Revenue on its international platform increased more than 50%, highlighting a promising source of expansion against slower group growth.
Trip.com Group Limited (NASDAQ:TCOM) also recognized a RMB5.2 billion antimonopoly penalty in general and administrative expenses. The investment question extends beyond that charge: can international expansion generate enough profitable growth to offset pressure on domestic monetization?
International expansion gives Trip.com Group Limited (NASDAQ:TCOM) a potential route to reducing dependence on revenue earned from domestic travel. A broader customer base could make growth less reliant on a single market's commercial practices and regulatory environment.
The opportunity is especially attractive if new customers become repeat users. Over time, repeat bookings could reduce acquisition spending per transaction and allow technology and service costs to be spread across more revenue. That would turn international scale into operating leverage, with profits growing faster than sales.
Trip.com Group Limited (NASDAQ:TCOM) also grew accommodation revenue 6% year over year despite a regulator-imposed revenue reduction. That result offers some evidence of resilience, although reservation growth and the revenue earned from those reservations remain separate considerations.
#NASDAQ
Trip.com Group Limited (NASDAQ:TCOM) also recognized a RMB5.2 billion antimonopoly penalty in general and administrative expenses. The investment question extends beyond that charge: can international expansion generate enough profitable growth to offset pressure on domestic monetization?
International expansion gives Trip.com Group Limited (NASDAQ:TCOM) a potential route to reducing dependence on revenue earned from domestic travel. A broader customer base could make growth less reliant on a single market's commercial practices and regulatory environment.
The opportunity is especially attractive if new customers become repeat users. Over time, repeat bookings could reduce acquisition spending per transaction and allow technology and service costs to be spread across more revenue. That would turn international scale into operating leverage, with profits growing faster than sales.
Trip.com Group Limited (NASDAQ:TCOM) also grew accommodation revenue 6% year over year despite a regulator-imposed revenue reduction. That result offers some evidence of resilience, although reservation growth and the revenue earned from those reservations remain separate considerations.
#NASDAQ

2 months ago
Marathon Petroleum Corporation (NYSE:MPC) has substantially outperformed the wider market this year, supported by an unusually sharp surge in global refining margins as the prolonged Iran crisis has significantly tightened global refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
With Marathon up by over 150% since the beginning of 2026, there are now concerns that the stock may have topped out. However, the ****** ysts over at Morgan Stanley are convinced that the rally still has further room to run. On September 14, Morgan Stanley ****** yst Joe Laetsch significantly raised the firm's price target on MPC from $265 to $453, while reaffirming an 'Overweight' rating on the shares.
The target boost reflects an upside of over 9% from the current price level and even exceeds the stock's record high of just under $411 per share achieved earlier this month. The Morgan Stanley update comes amid broader Wall Street optimism surrounding the American refining giant, with ****** ysts from Raymon James, UBS, and several others also improving their respective outlooks on MPC.
Morgan Stanley's vote of confidence suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, especially given the fresh wave of attacks between Washington and Tehran. Even if the conflict in the Middle East subsides, the region's refined fuel output is expected to remain relatively tight, since the damaged or idled refineries in the Middle East are likely to take some time to return to full operations.
As the largest refiner by volume in the United States, Marathon has significant operating leverage to capitalize on the current high-margin environment. The company already demonstrated its ability to translate the high crack spreads into material earnings when it delivered an almost fourfold increase in profits in the second quarter.
#morgan #marathon #stanley #middle
With Marathon up by over 150% since the beginning of 2026, there are now concerns that the stock may have topped out. However, the ****** ysts over at Morgan Stanley are convinced that the rally still has further room to run. On September 14, Morgan Stanley ****** yst Joe Laetsch significantly raised the firm's price target on MPC from $265 to $453, while reaffirming an 'Overweight' rating on the shares.
The target boost reflects an upside of over 9% from the current price level and even exceeds the stock's record high of just under $411 per share achieved earlier this month. The Morgan Stanley update comes amid broader Wall Street optimism surrounding the American refining giant, with ****** ysts from Raymon James, UBS, and several others also improving their respective outlooks on MPC.
Morgan Stanley's vote of confidence suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, especially given the fresh wave of attacks between Washington and Tehran. Even if the conflict in the Middle East subsides, the region's refined fuel output is expected to remain relatively tight, since the damaged or idled refineries in the Middle East are likely to take some time to return to full operations.
As the largest refiner by volume in the United States, Marathon has significant operating leverage to capitalize on the current high-margin environment. The company already demonstrated its ability to translate the high crack spreads into material earnings when it delivered an almost fourfold increase in profits in the second quarter.
#morgan #marathon #stanley #middle
2 months ago
A 2022 Nasdaq crash turned $10,000 into just $2,100 with TQQQ but preserved $3,900 with QLD's lower 2x leverage.
Recovering from TQQQ's 79% loss requires a 376% gain just to break even, making the extra leverage a costly bet.
QLD's 5-year annualized return of 17% beat TQQQ's 15% as volatility drag quietly eroded the extra leverage's advantage.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Leveraged ETFs have become an increasingly popular way to participate in the recent AI-driven technology boom. One such fund favored by investors and traders alike is the ProShares UltraPro QQQ (NASDAQ:TQQQ), an ETF that targets three times the Nasdaq's daily return. For investors who are uncomfortable with the 3x target, the ProShares Ultra QQQ (NYSEARCA:QLD) offers similar exposure but targets 2x the Nasdaq-100's daily move. When the Nasdaq is advancing higher, TQQQ seems like the obvious choice, but during a serious selloff, the reduced leverage of QLD can dramatically change the amount of capital left standing when the decline is over.
#leverage
Recovering from TQQQ's 79% loss requires a 376% gain just to break even, making the extra leverage a costly bet.
QLD's 5-year annualized return of 17% beat TQQQ's 15% as volatility drag quietly eroded the extra leverage's advantage.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Leveraged ETFs have become an increasingly popular way to participate in the recent AI-driven technology boom. One such fund favored by investors and traders alike is the ProShares UltraPro QQQ (NASDAQ:TQQQ), an ETF that targets three times the Nasdaq's daily return. For investors who are uncomfortable with the 3x target, the ProShares Ultra QQQ (NYSEARCA:QLD) offers similar exposure but targets 2x the Nasdaq-100's daily move. When the Nasdaq is advancing higher, TQQQ seems like the obvious choice, but during a serious selloff, the reduced leverage of QLD can dramatically change the amount of capital left standing when the decline is over.
#leverage

2 months ago
On August 6, Wheaton Precious Metals (NYSE:WPM) reported second-quarter net earnings of $543 million on $929 million of revenue, both records. Through the first half, net earnings rose 106% to $1.1 billion. During the quarter, the company also made net upfront cash payments of $4.5 billion relative to mineral stream interests, and it now carries $2.0 billion of total debt against $100 million of cash on hand. Here is what that trade looks like up close.
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton
2 months ago
The CLARITY Act failed to pass votes in the Senate earlier this week, a piece of legislature that would set out guardrails and ground rules for crypto **** ets in the U.S. With the failure of passage, the Securities and Exchange Commission took matters into its own hands, passing a conditional exemption Thursday for tokenized stocks. This Innovation Exemption allows for a limited type of tokenized securities to trade on specific Tokenized Securities Venues (TSVs), giving them a 5-year runway to prove their trading chops.
Tokenization is one of the latest trends in the investing world, whereby an **** et is represented digitally on a blockchain. It's seen as the next frontier in finance, with digital trading opening up greater access both for a broader investor base as well as the potential to trade 24/7, while also offering the potential for increased efficiency. However, some argue that tokenized **** ets come with added, unique risks and that by moving investments to the blockchain you introduce greater exposure to bad actors in an as-yet unregulated **** e in the U.S. That is, until now.
The SEC exemption allows for a specific type of tokenized stocks to be traded, specifically ones that retain the investor rights of the stock they are tied to (voting and dividends for example). Only tokenized U.S. National Market System (NMS) stocks qualify that trade through U.S. venues who have established standards for who can trade, limit trading volumes to a certain percentage of the stock, and make public their trading activities as well as any affiliates on the TSV. In addition, venues must halt trading when the primary exchange halts, and leverage is not permitted. Any company that does not want tokenized shares has 30 days to object and prevent their shares from being created.
It's important to note that currently there are two main types of tokenized securities, those that are directly linked to the **** et they represent digitally and those that provide synthetic exposure. Of the two, only the direct exposure tokenized stocks qualify that meet all of the exemption's restrictions.
"The Commission is not cementing today's technology as the standard for tomorrow. Instead, it is allowing the market to evolve, monitoring its development, and using that insight to inform a nimbler and future-ready regulatory framework," SEC Chair Paul Atkins said in a statement.
#exposure #commission
Tokenization is one of the latest trends in the investing world, whereby an **** et is represented digitally on a blockchain. It's seen as the next frontier in finance, with digital trading opening up greater access both for a broader investor base as well as the potential to trade 24/7, while also offering the potential for increased efficiency. However, some argue that tokenized **** ets come with added, unique risks and that by moving investments to the blockchain you introduce greater exposure to bad actors in an as-yet unregulated **** e in the U.S. That is, until now.
The SEC exemption allows for a specific type of tokenized stocks to be traded, specifically ones that retain the investor rights of the stock they are tied to (voting and dividends for example). Only tokenized U.S. National Market System (NMS) stocks qualify that trade through U.S. venues who have established standards for who can trade, limit trading volumes to a certain percentage of the stock, and make public their trading activities as well as any affiliates on the TSV. In addition, venues must halt trading when the primary exchange halts, and leverage is not permitted. Any company that does not want tokenized shares has 30 days to object and prevent their shares from being created.
It's important to note that currently there are two main types of tokenized securities, those that are directly linked to the **** et they represent digitally and those that provide synthetic exposure. Of the two, only the direct exposure tokenized stocks qualify that meet all of the exemption's restrictions.
"The Commission is not cementing today's technology as the standard for tomorrow. Instead, it is allowing the market to evolve, monitoring its development, and using that insight to inform a nimbler and future-ready regulatory framework," SEC Chair Paul Atkins said in a statement.
#exposure #commission

2 months ago
Rocket Lab (RKLB) has gained 9.5% over the last five trading days, while the S&P 500 added 0.6%. A week like that pulls money in. The stock is still about 55% below its 52-week high. The run is not the question. What matters for your money is what this stock does to your portfolio when the market moves, because it travels about four times as far as the index in both directions.
On days the S&P 500 rose over the past year, Rocket Lab captured about 381% of the gain. On days the index fell, it absorbed about 403% of the loss. The down days take slightly more than the up days give.
That is leverage on the market rather than a cushion. Over the past five years Rocket Lab ran 79.2% annualized volatility against 17.2% for the S&P 500, and its daily moves tracked the index at a correlation of 0.46 over those five years.
A moderate correlation and a swing that size sit together. Correlation asks whether the stock and the index move the same way, not how far. A good part of what Rocket Lab does is its own.
Look at what you own. Rocket Lab booked a record $234 million of revenue in Q2 2026, up 62% from the same quarter a year earlier, and it has just flown its 16th Electron mission of 2026.
#days
On days the S&P 500 rose over the past year, Rocket Lab captured about 381% of the gain. On days the index fell, it absorbed about 403% of the loss. The down days take slightly more than the up days give.
That is leverage on the market rather than a cushion. Over the past five years Rocket Lab ran 79.2% annualized volatility against 17.2% for the S&P 500, and its daily moves tracked the index at a correlation of 0.46 over those five years.
A moderate correlation and a swing that size sit together. Correlation asks whether the stock and the index move the same way, not how far. A good part of what Rocket Lab does is its own.
Look at what you own. Rocket Lab booked a record $234 million of revenue in Q2 2026, up 62% from the same quarter a year earlier, and it has just flown its 16th Electron mission of 2026.
#days
2 months ago
SailPoint Inc. (NASDAQ:SAIL), a leading player within the enterprise identity security ****** e, recently expanded its strategic alliance with CrowdStrike. As part of the revised arrangement, the company's SailPoint SecOps Identity Intelligence will be integrated with CrowdStrike Falcon Next-Gen SIEM. This will help in expediting threat detection procedures, and will also incorporate access data and identity governance into the overall investigation process. The expanded partnership will facilitate security teams in lining up the identity insights with Falcon's existing security telemetry.
Copyright: franckito / 123RF Stock Photo
The announcement aligns strongly with SailPoint's broader strategic narrative revealed in its Q2 FY27 print. It builds upon several recent initiatives undertaken by the management, such as introduction of the SailPoint Identity Security solution. This is aimed toward integrating SailPoint Agentic Fabric with SailPoint Human Fabric for real-time discovery and security of complex digital ecosystems. The company also launched its Cursor Enterprise connector, which helps organizations to leverage a highly-integrated control plane to manage human developers and autonomous AI agents.
The recently released financials also back this narrative as the company delivered a 25% year-over-year growth in its annual recurring revenue, which stood at $1.231 billion. SailPoint generated $45 million in operating cash flow during the second quarter, along with $37 million in free cash flow.
By weaving SailPoint's identity intelligence into Falcon Next-Gen SIEM, customers gain extra context inside workflows they already rely on, making it easier to probe identity-related risks. The integration augments SailPoint's position at a time when identity threats are on a rise. This leads to an opportunity for SailPoint to cement itself as a leading provider of advanced security solutions.
#sailpoint #falcon #next
Copyright: franckito / 123RF Stock Photo
The announcement aligns strongly with SailPoint's broader strategic narrative revealed in its Q2 FY27 print. It builds upon several recent initiatives undertaken by the management, such as introduction of the SailPoint Identity Security solution. This is aimed toward integrating SailPoint Agentic Fabric with SailPoint Human Fabric for real-time discovery and security of complex digital ecosystems. The company also launched its Cursor Enterprise connector, which helps organizations to leverage a highly-integrated control plane to manage human developers and autonomous AI agents.
The recently released financials also back this narrative as the company delivered a 25% year-over-year growth in its annual recurring revenue, which stood at $1.231 billion. SailPoint generated $45 million in operating cash flow during the second quarter, along with $37 million in free cash flow.
By weaving SailPoint's identity intelligence into Falcon Next-Gen SIEM, customers gain extra context inside workflows they already rely on, making it easier to probe identity-related risks. The integration augments SailPoint's position at a time when identity threats are on a rise. This leads to an opportunity for SailPoint to cement itself as a leading provider of advanced security solutions.
#sailpoint #falcon #next


2 months ago
Coinbase Global (NASDAQ: $COIN) has filed for regulatory approval to list perpetual futures tied to individual large-cap U.S. stocks, opening the door to 24/7 leveraged trading of shares such as Apple, Microsoft, Tesla and Nvidia on a regulated U.S. platform.
The exchange plans to offer contracts linked to roughly 50 to 60 major stocks, with trading potentially starting later this year if regulators approve the products, according to The Wall Street Journal.
Perpetual futures, commonly known as perps, are derivatives that do not have an expiration date. Traders can keep positions open indefinitely, while leverage can magnify both gains and losses.
More From Cryptoprowl:
U.S. Regulators Push Crypto Rules As Clarity Act Stalls
#perpetual #global #coin
The exchange plans to offer contracts linked to roughly 50 to 60 major stocks, with trading potentially starting later this year if regulators approve the products, according to The Wall Street Journal.
Perpetual futures, commonly known as perps, are derivatives that do not have an expiration date. Traders can keep positions open indefinitely, while leverage can magnify both gains and losses.
More From Cryptoprowl:
U.S. Regulators Push Crypto Rules As Clarity Act Stalls
#perpetual #global #coin


2 months ago
Bitcoin's most violent rally of its two-year drawdown wasn't powered by fresh bullish bets. It was powered by bears getting crushed, according to a new report from ******* ytics firm Glassnode and crypto exchange Bybit.
Over five days in August, Bitcoin climbed 24.6% even as coin-denominated open interest, a measure of active leverage, fell 12.6%, the report found. That combination is the tell: rather than traders piling into new long positions, the move ran on the forced unwinding of existing shorts.
Roughly 64,000 BTC worth of open interest was closed out, and short positions supplied 89% of every liquidated dollar during the stretch.
The options market told the same story. Puts, the contracts traders buy to protect against a fall, had priced richer than calls for 361 straight days. A single session ended that run, flipping roughly a year of downside positioning as the market scrambled to reprice.
Bybit's own volatility index traveled four times its normal daily range in one session, and the front of the futures curve repriced sharply while longer-dated contracts barely moved, a sign the market read the move as a one-off event rather than a lasting regime change.
#interest
Over five days in August, Bitcoin climbed 24.6% even as coin-denominated open interest, a measure of active leverage, fell 12.6%, the report found. That combination is the tell: rather than traders piling into new long positions, the move ran on the forced unwinding of existing shorts.
Roughly 64,000 BTC worth of open interest was closed out, and short positions supplied 89% of every liquidated dollar during the stretch.
The options market told the same story. Puts, the contracts traders buy to protect against a fall, had priced richer than calls for 361 straight days. A single session ended that run, flipping roughly a year of downside positioning as the market scrambled to reprice.
Bybit's own volatility index traveled four times its normal daily range in one session, and the front of the futures curve repriced sharply while longer-dated contracts barely moved, a sign the market read the move as a one-off event rather than a lasting regime change.
#interest

2 months ago
Margin debt hit $1.45 trillion in August, up 140% since 2022 and outpacing the S&P 500's 98% gain, which leaves the market carrying far more forced-selling risk.
At roughly 4.5% of GDP, margin debt now exceeds the dot-com bubble's peak, meaning a routine correction could cascade into broker-forced liquidations across the market.
The real danger isn't high leverage itself but the simultaneous forced selling that erupts when overleveraged investors all need cash at once.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
The longer-term comparison is even more striking. Since the end of 2022 -- and the start of the current AI-dominated era -- investor borrowing has increased by $847 billion, or 140%, versus a 98% gain for the S&P 500 over the same period. That means leverage has grown faster than the market value investors have accumulated, presumably as they took on debt to buy into the AI boom.
#market #leverage #investors
At roughly 4.5% of GDP, margin debt now exceeds the dot-com bubble's peak, meaning a routine correction could cascade into broker-forced liquidations across the market.
The real danger isn't high leverage itself but the simultaneous forced selling that erupts when overleveraged investors all need cash at once.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
The longer-term comparison is even more striking. Since the end of 2022 -- and the start of the current AI-dominated era -- investor borrowing has increased by $847 billion, or 140%, versus a 98% gain for the S&P 500 over the same period. That means leverage has grown faster than the market value investors have accumulated, presumably as they took on debt to buy into the AI boom.
#market #leverage #investors
2 months ago
AGNC Investment (NASDAQ: AGNC) completed its IPO in May 2008 at $20 per share. Today, shares of the mortgage REIT trade at around $10 per share, a staggering 50% below their IPO price.
However, the company's monthly dividends have more than offset the slump in its share price. AGNC has paid out over $50 per share in ****** ulative dividends since its IPO, more than double its IPO price. With dividends reinvested, it has significantly outperformed mortgage REITs and other financial stocks since its IPO.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
AGNC Investment's founders formed it in the depths of the financial crisis, seeing an opportunity to create a leading Agency MBS (mortgage-backed securities guaranteed against credit losses by government agencies like Fannie Mae). It invests in Agency MBS on a leveraged basis, primarily through repurchase agreements, and uses dynamic risk management strategies to navigate market risks, including interest rate changes.
The company has had to maneuver around several market cycles, unexpected events, and market volatility over the years, which have weighed on its investment returns and earnings. AGNC Investment has still managed to significantly expand its Agency MBS portfolio (it reached $97.2 billion at the end of the second quarter), financed primarily by selling stock. As a result, its shares outstanding have risen a staggering 7,660% since its IPO. This combination of earnings volatility and dilution is why its share prices have fallen 50% since the IPO.
#since #agency #dividends
However, the company's monthly dividends have more than offset the slump in its share price. AGNC has paid out over $50 per share in ****** ulative dividends since its IPO, more than double its IPO price. With dividends reinvested, it has significantly outperformed mortgage REITs and other financial stocks since its IPO.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
AGNC Investment's founders formed it in the depths of the financial crisis, seeing an opportunity to create a leading Agency MBS (mortgage-backed securities guaranteed against credit losses by government agencies like Fannie Mae). It invests in Agency MBS on a leveraged basis, primarily through repurchase agreements, and uses dynamic risk management strategies to navigate market risks, including interest rate changes.
The company has had to maneuver around several market cycles, unexpected events, and market volatility over the years, which have weighed on its investment returns and earnings. AGNC Investment has still managed to significantly expand its Agency MBS portfolio (it reached $97.2 billion at the end of the second quarter), financed primarily by selling stock. As a result, its shares outstanding have risen a staggering 7,660% since its IPO. This combination of earnings volatility and dilution is why its share prices have fallen 50% since the IPO.
#since #agency #dividends



2 months ago
If you are looking for reliable high yields in the energy sector, Energy Transfer (NYSE: ET) is likely to be high up on the list of options. And Wall Street really likes the stock, with 19 of the 21 ***** ysts covering it rating it a buy or strong buy. And yet, I just can't get myself to buy it, instead owning lower-yielding Enbridge (NYSE: ENB). Here's why Energy Transfer's 6.3% yield, despite distribution coverage of 2.2x, isn't enough to get me to buy it.
Before getting to Energy Transfer, I want to highlight some facts about Enbridge, the North American pipeline giant I actually bought. For starters, Enbridge's yield is 5.8%, roughly half a percentage point lower. That's a big difference, as buying Energy Transfer would increase my income stream by nearly 9%.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
I can totally understand where a dividend investor would buy Energy Transfer for the added yield. But there's a big difference when you consider dividend history. Enbridge has increased its dividend annually for 31 consecutive years. Energy Transfer cut its distribution in 2020 during the COVID pandemic, right when most investors would probably have preferred dividend consistency. To Energy Transfer's credit, it lived up to its promise at the time to reduce leverage and return to distribution growth. In fact, the distribution is now above its level prior to the cut. And the cut was probably the right decision to make for the business.
But that distribution cut was a hit for unitholders. And it comes after another questionable situation back during the 1996 energy market downturn. At that point, Energy Transfer agreed to buy peer Williams (NYSE: WMB), but got cold feet. In an effort to scuttle the deal, Energy Transfer issued convertibles that appeared to protect insiders from a dividend cut, if one were made. The Williams deal was canceled, and the convertibles never became an issue, but it raised material trust issues for me.
#distribution #Dividend #yield
Before getting to Energy Transfer, I want to highlight some facts about Enbridge, the North American pipeline giant I actually bought. For starters, Enbridge's yield is 5.8%, roughly half a percentage point lower. That's a big difference, as buying Energy Transfer would increase my income stream by nearly 9%.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
I can totally understand where a dividend investor would buy Energy Transfer for the added yield. But there's a big difference when you consider dividend history. Enbridge has increased its dividend annually for 31 consecutive years. Energy Transfer cut its distribution in 2020 during the COVID pandemic, right when most investors would probably have preferred dividend consistency. To Energy Transfer's credit, it lived up to its promise at the time to reduce leverage and return to distribution growth. In fact, the distribution is now above its level prior to the cut. And the cut was probably the right decision to make for the business.
But that distribution cut was a hit for unitholders. And it comes after another questionable situation back during the 1996 energy market downturn. At that point, Energy Transfer agreed to buy peer Williams (NYSE: WMB), but got cold feet. In an effort to scuttle the deal, Energy Transfer issued convertibles that appeared to protect insiders from a dividend cut, if one were made. The Williams deal was canceled, and the convertibles never became an issue, but it raised material trust issues for me.
#distribution #Dividend #yield
2 months ago
On August 6, Millicom International Cellular (NASDAQ:TIGO) released its second-quarter 2026 results, and the numbers pulled in two directions at once. Revenue jumped 59.4% year over year to $2.18 billion, while Adjusted EBITDA crossed $1 billion for the first time in the company's history at $1.01 billion, up 58% from a year earlier. Yet net profit attributable to company owners fell 83.9% to just $109 million. Investors weighing this quarter have to decide which of those two stories actually describes the business.
The headline figures are hard to ignore. Service revenue reached $2.04 billion in the quarter, up 60.1% year over year, while H1 2026 revenue climbed to $4.16 billion from $2.74 billion a year earlier, a 52.3% increase. Equity free cash flow hit a quarterly record of $327 million, up 50.1% from a year ago, and leverage actually fell to 2.73x even after Millicom absorbed acquisitions in Colombia, Ecuador and Uruguay. That combination, rising cash generation alongside falling leverage during an acquisition spree, is the kind of signal that tends to matter more than a single quarter's headline growth rate.
Management is backing that signal with cash. Millicom already declared a $3.00 per share dividend in May, to be paid out quarterly over the next 12 months, and on August 5, the board approved an additional interim dividend of $1.50 per share, split into two $0.75 installments due January 15, 2027, and April 15, 2027. The company also raised its full-year 2026 equity free cash flow guidance from at least $900 million to around $1.1 billion, while lowering its year-end leverage target from about 2.5x to below 2.5x. CEO Marcelo Benitez pointed to Ecuador and Uruguay as evidence the integration playbook works, saying both markets have reached margins and cash generation broadly in line with the Millicom average, with Colombia and Chile now showing early improvement on the same path.
Strip out the acquisitions, and the picture looks far less dramatic. Organic revenue growth was just 4.3% in the quarter and 4.2% for the first half, a fraction of the 59.4% and 52.3% reported figures. Most of what shows up in the headline number is Millicom buying its way to a bigger top line, not the existing business accelerating on its own.
The profit line raises a separate question. Net profit attributable to company owners dropped to $109 million from $676 million a year earlier, and the first-half figure fell 74.9% to $218 million from $869 million, even as EBITDA and cash flow set records over the same stretch. That gap between a surging EBITDA number and a collapsing bottom line is the kind of divergence that deserves scrutiny rather than a shrug. Capital spending is climbing too, up 51.2% to $234 million in the quarter and 48.8% to $426 million for the half, running well ahead of the organic growth rate it is meant to fund. And the balance sheet is still in motion: in July 2026, Bolivia took on five new local bank loans totaling roughly $44 millio
The headline figures are hard to ignore. Service revenue reached $2.04 billion in the quarter, up 60.1% year over year, while H1 2026 revenue climbed to $4.16 billion from $2.74 billion a year earlier, a 52.3% increase. Equity free cash flow hit a quarterly record of $327 million, up 50.1% from a year ago, and leverage actually fell to 2.73x even after Millicom absorbed acquisitions in Colombia, Ecuador and Uruguay. That combination, rising cash generation alongside falling leverage during an acquisition spree, is the kind of signal that tends to matter more than a single quarter's headline growth rate.
Management is backing that signal with cash. Millicom already declared a $3.00 per share dividend in May, to be paid out quarterly over the next 12 months, and on August 5, the board approved an additional interim dividend of $1.50 per share, split into two $0.75 installments due January 15, 2027, and April 15, 2027. The company also raised its full-year 2026 equity free cash flow guidance from at least $900 million to around $1.1 billion, while lowering its year-end leverage target from about 2.5x to below 2.5x. CEO Marcelo Benitez pointed to Ecuador and Uruguay as evidence the integration playbook works, saying both markets have reached margins and cash generation broadly in line with the Millicom average, with Colombia and Chile now showing early improvement on the same path.
Strip out the acquisitions, and the picture looks far less dramatic. Organic revenue growth was just 4.3% in the quarter and 4.2% for the first half, a fraction of the 59.4% and 52.3% reported figures. Most of what shows up in the headline number is Millicom buying its way to a bigger top line, not the existing business accelerating on its own.
The profit line raises a separate question. Net profit attributable to company owners dropped to $109 million from $676 million a year earlier, and the first-half figure fell 74.9% to $218 million from $869 million, even as EBITDA and cash flow set records over the same stretch. That gap between a surging EBITDA number and a collapsing bottom line is the kind of divergence that deserves scrutiny rather than a shrug. Capital spending is climbing too, up 51.2% to $234 million in the quarter and 48.8% to $426 million for the half, running well ahead of the organic growth rate it is meant to fund. And the balance sheet is still in motion: in July 2026, Bolivia took on five new local bank loans totaling roughly $44 millio

2 months ago
On September 8, 2026, the Wall Street Journal reported United Natural Foods, Inc. (NYSE:UNFI)'s fiscal fourth-quarter results, in which adjusted earnings per share of $0.69 beat ***** yst expectations even as revenue of $7.64 billion came in below consensus.
The grocery wholesaler guided for fiscal 2027 net sales of $31.2 billion to $31.8 billion, a return to growth after full-year fiscal 2026 sales declined 2% to $31.2 billion. The business said full-year adjusted EBITDA rose 27% to $701 million and free cash flow hit a record $323 million as it continued executing what CEO Sandy Douglas called its second year of a value-creation strategy.
United Natural Foods, Inc. (NYSE:UNFI)'s turnaround is improving the financial metrics that matter most for a food distributor. Full-year adjusted EBITDA increased 27%. Net debt fell by $295 million and net leverage improved to 2.2 times. The stronger balance sheet gives UNFI more financial flexibility as it works to return to sales growth.
UNFI's natural-products business is providing an important growth engine. Fourth-quarter natural-products sales increased 6.6%, even as conventional-products sales declined 8.6%. The stronger performance in natural products backs up UNFI's strategy of expanding business with customers that can drive growth as the business restructures its operations.
Management also expects fiscal 2027 sales to reach $31.2 billion to $31.8 billion, up from $31.15 billion in fiscal 2026. Adjusted EPS should reach $3.00 to $3.50 versus $2.65 previously. Management anticipates about 10 basis points of margin expansion at the midpoint, which could help UNFI reach its fiscal 2028 margin target a year earlier than planned.
#billion
The grocery wholesaler guided for fiscal 2027 net sales of $31.2 billion to $31.8 billion, a return to growth after full-year fiscal 2026 sales declined 2% to $31.2 billion. The business said full-year adjusted EBITDA rose 27% to $701 million and free cash flow hit a record $323 million as it continued executing what CEO Sandy Douglas called its second year of a value-creation strategy.
United Natural Foods, Inc. (NYSE:UNFI)'s turnaround is improving the financial metrics that matter most for a food distributor. Full-year adjusted EBITDA increased 27%. Net debt fell by $295 million and net leverage improved to 2.2 times. The stronger balance sheet gives UNFI more financial flexibility as it works to return to sales growth.
UNFI's natural-products business is providing an important growth engine. Fourth-quarter natural-products sales increased 6.6%, even as conventional-products sales declined 8.6%. The stronger performance in natural products backs up UNFI's strategy of expanding business with customers that can drive growth as the business restructures its operations.
Management also expects fiscal 2027 sales to reach $31.2 billion to $31.8 billion, up from $31.15 billion in fiscal 2026. Adjusted EPS should reach $3.00 to $3.50 versus $2.65 previously. Management anticipates about 10 basis points of margin expansion at the midpoint, which could help UNFI reach its fiscal 2028 margin target a year earlier than planned.
#billion



