25 days ago
The transition toward renewable energy is creating massive opportunities for infrastructure providers. Eos Energy Enterprises (NASDAQ:EOSE) and GE Vernova (NYSE:GEV) represent two distinct ways to play this trend in 2026.
Eos focuses on specialized zinc-based batteries for long-duration energy storage. GE Vernova is a diversified giant that services a massive portion of the world's electricity grid. Comparing these two helps clarify whether you prefer a high-growth disruptor or an established power leader.
Eos Energy Enterprises produces aqueous zinc batteries designed as a safer, scalable alternative to lithium-ion. It operates primarily within the industrial stocks **** e, targeting utilities and commercial developers. Customer concentration like this adds a layer of risk to the business, as two clients accounted for approximately 70% of total revenue in 2025.
In FY 2025, revenue reached approximately $114.2 million. This represents growth of nearly 631.8% compared to the prior fiscal year. The company reported a pre-tax net loss of roughly $969.6 million, resulting in a negative net margin of approximately 849.1%.
As of its December 2025 balance sheet, the company had a debt-to-equity ratio of -1.0x. This value indicates that total liabilities exceed shareholder equity. The current ratio, which measures the ability to cover short term obligations with short term **** ets, was approximately 4.9x, while free cash flow was nearly negative $265.0 million.
#enterprises #massive #Growth
25 days ago
SailPoint Inc. (NASDAQ:SAIL), a leading player within the enterprise identity security ****** e, recently expanded its strategic alliance with CrowdStrike. As part of the revised arrangement, the company's SailPoint SecOps Identity Intelligence will be integrated with CrowdStrike Falcon Next-Gen SIEM. This will help in expediting threat detection procedures, and will also incorporate access data and identity governance into the overall investigation process. The expanded partnership will facilitate security teams in lining up the identity insights with Falcon's existing security telemetry.
Copyright: franckito / 123RF Stock Photo
The announcement aligns strongly with SailPoint's broader strategic narrative revealed in its Q2 FY27 print. It builds upon several recent initiatives undertaken by the management, such as introduction of the SailPoint Identity Security solution. This is aimed toward integrating SailPoint Agentic Fabric with SailPoint Human Fabric for real-time discovery and security of complex digital ecosystems. The company also launched its Cursor Enterprise connector, which helps organizations to leverage a highly-integrated control plane to manage human developers and autonomous AI agents.
The recently released financials also back this narrative as the company delivered a 25% year-over-year growth in its annual recurring revenue, which stood at $1.231 billion. SailPoint generated $45 million in operating cash flow during the second quarter, along with $37 million in free cash flow.
By weaving SailPoint's identity intelligence into Falcon Next-Gen SIEM, customers gain extra context inside workflows they already rely on, making it easier to probe identity-related risks. The integration augments SailPoint's position at a time when identity threats are on a rise. This leads to an opportunity for SailPoint to cement itself as a leading provider of advanced security solutions.
#sailpoint #falcon #next

26 days ago
When developers hand governance to residents at build-out, HOA fees spike as homeowners absorb true amenity costs and cover reserve underfunding through special ****** sments.
HOA fee increases in post-transition communities routinely outpace the 2027 Social Security COLA of roughly 3%, squeezing retirees on fixed incomes.
Demand the reserve study, CC&Rs, and community development district bond balance before signing. If the sales office stalls, the pitch was rehearsed, not substantiated.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Readers in their late fifties and early sixties ask weekly: Can I retire to a Margaritaville community, and what will it cost over twenty or thirty years? The brochure sells one version, while the sales center sells another. The real question a retiree should ask is what happens once marketing wears off and the structural issue the sales presentation almost never covers emerges.
#retirees #community #years #sells
26 days ago
Data center developer Crusoe said Thursday it raised $3.9 billion in a Series F round that pushes its valuation to $30.9 billion. The massive round was co-led by Atreides Management, Mubadala Capital, and Valor Equity Partners. Founders Fund, GIC, Nvidia, Qatar Investment Authority (QIA), Radical Ventures, and TPG also participated, according to Crusoe.
Crusoe also announced three new board members, including Cloudflare CFO Thomas Seifert; Bill Stein, partner and CIO at Primary Digital Infrastructure; and Redwood Materials founder and CEO JB Straubel, who also sits on Tesla's board. Straubel already has ties to Crusoe; he personally invested in the company in 2021, and Crusoe later became the first customer of Redwood's energy storage business.
The eight-year-old company's fresh capital infusion will help finance existing data center projects, including a large site in Abilene, Texas, used by OpenAI, as well as smaller, modular AI factories that can be transported by truck and connected to large power sources almost anywhere.
By manufacturing these modular data centers, called Spark, at its own facilities, Crusoe can deploy compute capacity quickly and without the need for large construction workforces. The smaller centers could also help Crusoe sidestep, at least in part, another major obstacle facing data center developers: backlash from local communities protesting massive complexes near their neighborhoods.
Crusoe co-founder and CEO Chase Lochmiller, who is pictured above, said in a statement he believes AI will usher in an era of abundance, but to get there will mean "controlling the infrastructure from electrons to tokens, and we're grateful to have investors who share that conviction."
#straubel #round

26 days ago
Ethereum runs smart contracts on a proof-of-stake network where over a third of circulating ETH is staked, earning low single-digit yields.
Over five years, Bitcoin gained 58% while Ethereum lost 30%, exposing a stark performance gap despite Ethereum's expanding platform usage.
Spot Ethereum ETFs exclude staking yield, and IRS tax uncertainty on staking rewards continues to limit institutional capital from participating.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Ethereum (CRYPTO:ETH) is a blockchain built to run programs, which is why people point to it when they say crypto can do more than move money. Developers deploy code to it, users call that code, and the network's native token, ETH, pays for the computing power behind every transaction.
#ethereum #Crypto #stocks #enter


26 days ago
The Commodity and Futures Trading Commission on Thursday paved the way to expand prediction markets and cryptocurrency trading on certain online platforms. DraftKings led a retreat for sports betting stocks Thursday.
The CFTC's Market Participation division issued a no-action letter, saying it will not take enforcement action against providers of what the agency called "passive software."
These passive software providers include companies and developers that offer prediction market, derivatives or crypto trading services, but do not take custody of user ***** ets.
"Subject to certain specified conditions, MPD will not recommend the Commission take enforcement action against any such provider or their relevant personnel for failure to register as an introducing broker or an ***** ociated person of an introducing broker," the regulator said in its announcement. However, this only applies to the "provision and marketing of software to facilitate trading" between users and registered futures commission merchants, introducing brokers, and designated contract merchants.
The decision follows a similar no-action letter from the CFTC in March, which responded to a request from self-custody crypto wallet provider Phantom Technologies, Bloomberg reported. Phantom Technologies partnered with Kalshi to offer predictions market trading to its more than 20 million crypto wallet holders.
#action

26 days ago
Comments from Anthropic CEO Dario Amodei and OpenAI CEO Sam Altman calling for a more measured approach to frontier AI development contributed to a sharp selloff across neoclouds and data center stocks. Bernstein identified CoreWeave Inc. (NASDAQ:CRWV) as the most exposed name because of its rural footprint and focus on AI training. The concern represents a genuine structural argument. However, it marks the second time this year that the same group of stocks has faced concerns over the sustainability of AI demand. There is also an important tension within Bernstein's own note, which highlights CoreWeave's exposure while acknowledging that most of its backlog remains shielded by contracts.
Bernstein cautioned that a slowdown in AI training could weigh on data center developers. The warning followed Amodei's weekend comments urging the industry to deliberately slow the pace of frontier AI capability gains, along with similar remarks from Sam Altman. According to ****** yst Madison Rezaei, slower training activity would likely reduce demand for rural data center sites designed for latency-insensitive workloads. The ****** yst pointed out that rural and Tier 3 markets account for 70% of the industry's 488GW pipeline. CoreWeave was identified as the most exposed name in the firm's coverage. ****** yst Madison Rezaei remarked:
We estimate that 25% of their existing active U.S. power, with an additional ~74% of their contracted power, is situated in Tier 3 and Tier 4 markets.
However, there is a key counterpoint within Bernstein's own note:
The backlog is primarily comprised of take-or-pay contracts, so we do not anticipate a threat there but could see a pullback in demand for the contracted-not-yet-sold rural power if training development slows.
#training #analyst
27 days ago
BILLINGS, Mont. (AP) — Killing endangered animals while logging a forest or building a dam would not be considered illegal unless the animals were specifically targeted, under a new interpretation of the Endangered Species Act by President Donald Trump's administration that marks a sea change in how the landmark environmental law is enforced.
A directive sent to U.S. Fish and Wildlife Service employees this week says imperiled animals or plants must be intentionally targeted for their killing to be considered illegal.
That's a sharp turnaround from past practice at the wildlife service, which historically held people liable even for accidentally harming protected species such as grizzly bears, manatees and spotted owls.
Experts said the change would allow timber companies to log forests in the Pacific Northwest even if they knew that doing so could kill imperiled birds nesting in the trees, or for developers to build a dam knowing it would kill salmon.
"This cuts against the entire history of the Endangered Species Act," said Dan Ashe, who led the Fish and Wildlife Service under former President Barack Obama.
#species #president #killing


27 days ago
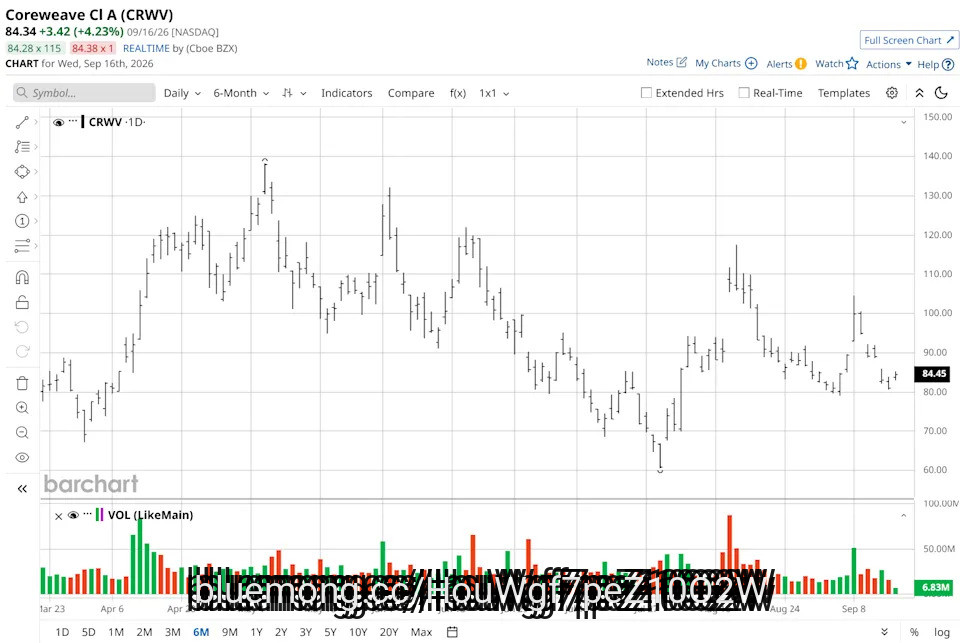
CoreWeave (CRWV), purely from the perspective of revenue growth, still looks attractive. However, CRWV stock is telling a different story. In the past 52 weeks, the stock has corrected by 29%.
Amidst this weak performance, Bernstein issued a warning. That "slowdown in the training of artificial intelligence models could negatively affect data center developers and neoclouds." Further, CoreWeave is one of the "most exposed" to this risk.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Why It's Time to Load Up on Nvidia Stock
#bernstein #billionaire #charlie

27 days ago
Top media leaders across print, digital and broadcast warned about AI's impacts on journalism at the inaugural Status Summit last week.
Why it matters: News publishers recognize that they need to embrace AI to survive the transition to an agentic web, but they refuse to broker deals with companies they feel are illegally scraping their content.
What they're saying: Speaking onstage to Status founder Oliver Darcy last Wednesday, New York Times CEO Meredith Kopit Levien said large language model developers "as far as we see it ... have engaged in theft of intellectual property and creative expressive work on a scale that is unprecedented."
As it relates to the Times, they've "stolen our stuff," she said.
The Times, which has sued OpenAI and Microsoft in a landmark copyright lawsuit, has struck partnerships with AI firms, such as Amazon, when they believe terms are equitable.
#darcy #york


27 days ago
On September 11, Elastic (NYSE:ESTC) rolled out Elasticsearch Vector Database, a new serverless offering the company says lets developers ship large-scale vector search and AI applications without stitching together the usual pile of infrastructure themselves. The launch landed less than three weeks after Elastic posted first-quarter fiscal 2027 results on August 27, for the period ended July 31, giving investors a fresh product story to weigh against a quarter that already showed accelerating growth.
The new database automates what used to require manual **** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#elastic #vector #company

28 days ago
AI data centers are facing growing power constraints, and the issue is becoming increasingly urgent. New utility capacity can take years to develop and bring online, but hyperscalers cannot afford to wait that long to support their growing computing needs. That gap between supply and demand creates an opportunity for Bloom Energy (BE), which is focused on delivering power where and when hyperscalers like Microsoft (MSFT), Amazon (AMZN), and Alphabet (GOOG) (GOOGL) require it. The fundamentals are now starting to provide support for the growing optimism around its opportunity.
Bloom Energy's technology stands out because it can address the AI power challenge on a much shorter timeline. The company's solid-oxide fuel cells are manufactured in factories and can be moved where required. They can also be deployed much faster than traditional power infrastructure. Instead of waiting years for grid upgrades or additional turbine capacity, data center developers can install Bloom Energy's systems and bring power online in a much shorter timeframe. As AI infrastructure expands, that speed has helped the company establish itself as an increasingly important on-site power vendor. All major U.S. hyperscalers are also providing validation of its position.
Why UBS Just Turned Bearish on NuScale Power Stock
Crude Oil Prices Retreat as Supply Fears Ease
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#bloom #crude


28 days ago
Interested in NVIDIA Corporation? Here are five stocks we like better.
NVIDIA released CUDA-Q Logical, an open-source software layer that links GPUs with quantum processors to solve practical error correction challenges.
Early testing by Fermilab and Sandia National Laboratories shows dramatic efficiency gains, including a seven-fold faster design cycle and reduced physical qubit requirements.
Quantum hardware firms IonQ, Rigetti Computing, and D-Wave Quantum could benefit as standardized software lowers development costs and enables deeper integration with NVIDIA's infrastructure.
Many investors view quantum hardware developers and classical semiconductor leaders as competing forces in high-performance computing. Recent developments demonstrate that the two architectures are becoming deeply interdependent.
#hardware #here

28 days ago
On September 13, Reuters reported that Anthropic is in talks to bring NVIDIA Corporation (NASDAQ:NVDA) in as an anchor investor in what could become one of the largest IPOs in history, potentially raising as much as $100 billion at a valuation of around $2 trillion. Nvidia is reportedly considering an investment of up to $10 billion. Anthropic's annualized revenue run rate has reportedly increased from about $9 billion in 2025 to more than $65 billion by mid-2026, with the company targeting as much as $200 billion of revenue by 2028.
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of ***** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable o


29 days ago
On September 13, Reuters reported that Anthropic is in talks to bring NVIDIA Corporation (NASDAQ:NVDA) in as an anchor investor in what could become one of the largest IPOs in history, potentially raising as much as $100 billion at a valuation of around $2 trillion. Nvidia is reportedly considering an investment of up to $10 billion. Anthropic's annualized revenue run rate has reportedly increased from about $9 billion in 2025 to more than $65 billion by mid-2026, with the company targeting as much as $200 billion of revenue by 2028.
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of **** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable of

29 days ago
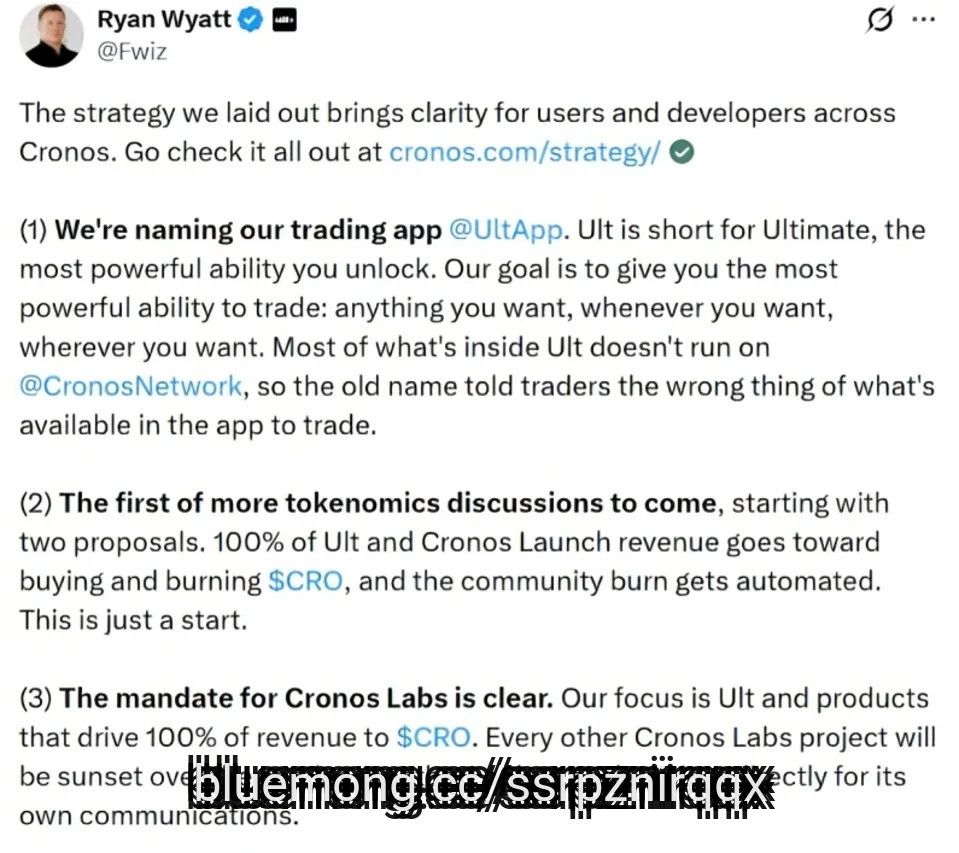
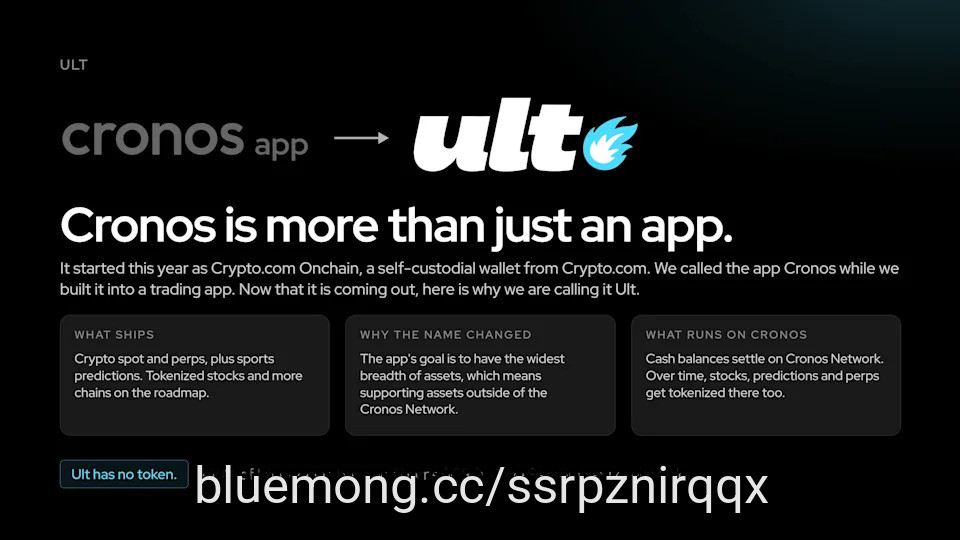
Cronos rebrands its trading app as Ult, expanding beyond crypto into prediction markets, perpetuals and tokenized **** ets.
Ult targets 100+ countries with 24/7/365 trading, 10 sports prediction categories and around 40 leveraged markets at launch.
Cronos Network could see more trading flow as Ult brings users, **** ets and liquidity into the ecosystem, with plans to move more markets onchain as volume grows.
Cronos, the blockchain ecosystem **** ociated with Crypto.com, is reshaping its product strategy around a new trading application called Ult. It has introduced a revenue-linked mechanism designed to support its native CRO token.
Cronos CEO Ryan Wyatt announced the changes on X, saying the new strategy is intended to provide greater clarity for users and developers. It aims to put a stronger focus on products that generate value for CRO.
#markets

29 days ago
On September 11, Elastic (NYSE:ESTC) rolled out Elasticsearch Vector Database, a new serverless offering the company says lets developers ship large-scale vector search and AI applications without stitching together the usual pile of infrastructure themselves. The launch landed less than three weeks after Elastic posted first-quarter fiscal 2027 results on August 27, for the period ended July 31, giving investors a fresh product story to weigh against a quarter that already showed accelerating growth.
The new database automates what used to require manual ***** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#quarter #fiscal #year #operating
1 month ago
AMD and Intel compete for processor customers, but they have a common interest in making developers comfortable staying with x86. A September 2 GCC commit added initial support for their AI Compute Extensions, or ACE, bringing that shared strategy into a widely used compiler's development code.
For Advanced Micro Devices, Inc. (NASDAQ:AMD) and Intel Corporation (NASDAQ:INTC), the potential payoff is broader software adoption. The immediate event is much narrower: compiler infrastructure, followed by instruction-support commits. It is not evidence that compatible processors have shipped or that GCC 17 is a finished release.
The x86 Ecosystem Advisory Group's April whitepaper describes a common matrix-acceleration architecture shaped by both companies. Matrix multiplication is central to many AI workloads. A shared instruction interface could reduce the effort needed to target those operations across future processors.
That matters commercially because buyers consider the software work required to use hardware, alongside its price and performance. If developers can support both suppliers more easily, a processor purchase may depend more on execution and less on maintaining separate software paths.
For Advanced Micro Devices, Inc. (NASDAQ:AMD), the bull case is an easier route for compatible future CPUs into AI-related workloads. The risk is that a shared standard also improves the rival's appeal. Compiler support alone cannot demonstrate AMD's eventual performance advantage, customer adoption or incremental profit.
#Intel

1 month ago
You can find original article here WealthManagement. Subscribe to our free daily WealthManagement newsletters.
The giant artificial intelligence company Anthropic has rolled out Claude for Financial Advisors, a suite of artificial intelligence connectors and what the company refers to as "workflow skills" designed to help advisors automate research, meeting preparation and documentation tasks.
Its new product includes connectors to custodians, ***** et managers and wealth technology providers, such as Charles Schwab, BlackRock, Addepar, Envestnet, iCapital, Orion, SS&C Black Diamond, Wealthbox, Wealth.com, Vanguard and Zocks, along with previously available integrations with Microsoft 365, Salesforce, DocuSign, Box, FactSet, S&P Global and Morningstar.
The platform includes skills for advisor onboarding, alternative investments briefing, compliance and AI policy review, estate and tax briefing, portfolio rebalance review, post-meeting notes and follow-up, pre-meeting preparation and prospect intake, according to Anthropic.
"We aren't trying to replace any of the tools out there," said Peter Nolan, head of ***** et and wealth management at Anthropic, during an interview with WealthManagement, when asked whether this puts Anthropic in the position of competing with and potentially upending the developing ecosystem of entrepreneurs and developers working with it and other major AI model providers.
#advisors

1 month ago
SailPoint Inc. (NASDAQ:SAIL), a leading player within the enterprise identity security ***** e, released its fiscal second-quarter 2027 on September 9. The company registered a 25% growth in its annual recurring revenue compared to the same period last year, with figures of $1.231 billion. This was driven by a 36% expansion in SaaS ARR which clocked in at $847 million. SailPoint generated $45 million in operating cash flow during the quarter, along with $37 million in free cash flow.
Burben/Shutterstock.com
Topline for the quarter hit $309 million, exhibiting 17% growth compared to Q2 FY26, amid several underlying factors. The company's subscription revenue reached $295 million, up 19% from a year earlier. SaaS customer base increased by 16%, with net new SaaS ARR jumping 34% year-over-year. It contributed around 97% to overall net new ARR for the business, with AI-driven ARR crossing $70 million mark.
SailPoint's existing customer base showed highly encouraging trends in adopting the company's AI-enabled solutions, with a 60% increase in their annual spend during the second quarter. These solutions were incorporated within more than two-thirds of the completed migrations during the quarter. Quarterly adjusted operating income increased from $54 million a year prior to $63 million, translating into an adjusted margin of 20%.
The quarter also saw key strategic moves by the management. It introduced the SailPoint Identity Security solution, which integrates SailPoint Agentic Fabric with SailPoint Human Fabric to deliver a real-time cycle for discovering and securing intricate digital ecosystems. The company also launched its Cursor Enterprise connector, which enables enterprises to manage both autonomous AI agents and human developers through an integrated control plane.
#year #SaaS #fabric #identity
1 month ago
Apple Inc. (NASDAQ:AAPL) and Intel Corporation (NASDAQ:INTC) represent two sides of a historical silicon transition. A September 2 report from MacRumors highlighted a key milestone: Apple notified developers that universal Mac App Store apps requiring macOS 13 or later can now drop support for Intel-based Macs. Removing Intel binary slices simplifies app development and reduces download sizes. While symbolic, the move underscores Apple's completed transition to Apple Silicon and highlights Intel's diminishing footprint within Apple's high-margin ecosystem.
Financially, Apple is faring significantly better than Intel.
For Q3 2026 (ended June 27, 2026), Apple reported record quarterly revenue of $109.4 billion, up 16% year-over-year, driven by double-digit growth across iPhone, Mac, and Services. The company's gross margin reached 50.1%, supported by a 2 percentage point favorable impact from tariff refunds. Diluted earnings per share (EPS) surged 29% year-over-year to $2.02, which included a $0.11 favorable boost from tariff refunds. Operating cash flow and active installed base both set new June quarter records.
Intel's Q2 2026 financial results (ended June 27, 2026) delivered $16.1 billion in quarterly revenue, up 25% year-over-year, marking its fastest top-line growth in over 15 years. Intel reported a GAAP net loss of $11.0 billion (GAAP EPS of -$2.16), largely driven by non-cash charges and mark-to-market adjustments. However, on a non-GAAP basis, net income reached $2.2 billion ($0.42 diluted EPS), nearly doubling consensus expectations. Non-GAAP gross margin expanded to 41.8% (40.4% GAAP) on strong product mix and factory yields.
Apple's bull case centers on expanding Services margins, strong ecosystem lock-in, and the potential for Apple Intelligence to drive further demand and engagement across iOS and macOS devices, supporting high-margin growth. On the other hand, Apple faces risks from elevated valuation multiples, sluggish growth in Greater China, where Q3 revenue reached $14.7 billion, and ongoing global antitrust scrutiny over App Store fees.
#revenue

1 month ago
Oklo (OKLO) and X-Energy (XE) each fell 5% as markets sold the nuclear group on X-Energy's Sell rating, ignoring Oklo's concurrent Buy initiation.
URA dropped 3% while SPY fell just 0.4%, confirming Thursday's pressure was a sector-specific nuclear selloff, not a broad market event.
Analyst Dimple Gosai argues that financing structure, rather than reactor technology, is what decides which SMR developers can build a first plant and win customers.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and X-Energy, Inc. Class A Common Stock didn't make the cut. Enter your email to see the names that beat XE. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of Oklo (NYSE:OKLO), NuScale Power (NYSE:SMR) and X-Energy (NASDAQ:XE) are sliding together in Thursday afternoon trading after Piper Sandler issued a split rating action across advanced nuclear. Oklo stock is down 5% to $40.50, with the year-to-date (YTD) decline now at 44%.
#enter #NYSE
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
1 month ago
CNBC reported that Salesforce, Inc. (NYSE:CRM) reported fiscal second-quarter revenue of $11.35 billion, up 11% year over year and above the $11.32 billion ******* ysts expected. Net income rose to $3.53 billion from $1.89 billion a year earlier, boosted by a $2.6 billion gain on its Anthropic investment.
Shares surged more than 12% on the results and kept climbing the next day after Salesforce CEO Marc Benioff and Anthropic CEO Dario Amodei disclosed "Claudeforce," a plug-in bringing Salesforce data into Claude. "This SaaSpocalypse narrative has been such nonsense," Benioff told CNBC's Jim Cramer. "Frontier models depend on CRM. They don't replace it." Agentforce annualized revenue topped $1.5 billion, up 240% year over year. Salesforce announced a $1.6 billion VA contract and a planned $3.6 billion acquisition of Fin.
The quarter's strength was broad-based, not confined to one metric skeptics could dismiss. Net new annual order value growth was the strongest in four years. Seats grew across Agentforce, Sales, Service, and Slack rather than declining as bears predicted; attrition sat near its lowest level ever, and bookings more than doubled quarter over quarter, directly rebutting the claims the "SaaSpocalypse" narrative was built on.
Agentforce is now a large, fast-growing business on its own, not just a talking point. Annualized revenue from the AI agent platform topped $1.5 billion, up 240% year over year. It gives Salesforce a concrete, rapidly scaling product line that validates its AI strategy with real recurring revenue.
The Claude partnership strengthens Salesforce, Inc. (NYSE:CRM)'s AI offering by giving customers direct access to Anthropic's models within its CRM platform. Incorporating Claude with Salesforce's proprietary customer data could make Agentforce and other AI tools more useful to businesses while giving Salesforce another way to monetize the growing demand for enterprise AI. The partnership also shows Salesforce can work with leading AI model developers rather than relying entirely on its own models.
#billion #year

1 month ago
CNBC reported that Apple Inc. (NASDAQ:AAPL) announced new Mac Mini and Mac Studio models with updated chips built for AI workloads.
The Mac Mini now offers Apple's new M6 chip, its first built on a 2-nanometer process, or an M5 Pro, and starts at $899, up from $799 for the prior model. Apple says the M6 delivers 4 times faster AI performance and 2 times faster graphics than the M4 model it replaces, while the M5 Pro can process large language model prompts up to 8.5 times faster than the M2 Pro version. The Mac Studio now starts at $2,499 with the M5 Max chip or $5,499 with the new M5 Ultra, up from $5,299 for the prior Ultra model, and multiple M5 Ultra units can be linked together to pool memory for running large AI models. "With these frameworks and new chips, developers can run and fine-tune large AI models locally on their Mac," Apple said. Preorders opened Tuesday, with units shipping September 22.
The performance gains here are substantial, not incremental. The M6 chip delivers 4 times faster AI performance and is Apple Inc. (NASDAQ:AAPL)'s first chip built on a 2-nanometer process. The M5 Pro configuration processes large language model prompts 8.5 times faster than the model it replaces, Apple's own specifications show, giving Apple genuine technical claims to back its AI-focused marketing.
Apple is showing pricing power even as component costs rise industry-wide. Despite memory and silicon shortages pushing costs higher across the industry, Apple raised prices on both product lines rather than absorbing the cost pressure itself. It is a sign the company believes demand can bear higher price points.
These desktops are becoming more strategically important to Apple than their revenue alone suggests. It shows how Mac desktops have become a foothold in the AI development world for Apple. It is a showcase for its custom silicon that can influence which platform developers build AI tools on and an ecosystem benefit that extends beyond the sale of any individual machine.
#faster #chip #ultra
1 month ago
On September 4, Bruker (NASDAQ:BRKR) said its energy and supercon technologies unit, Bruker Energy & Supercon Technologies (or BEST), had struck a supply collaboration with Luvata Materials & Solutions to scale up production of RRP superconductors for magnetic confinement fusion. The deal lands right as governments and private developers from Europe to South Korea race to build fusion demonstration plants, and it comes a month after Bruker's core scientific instruments business showed its first real signs of stabilizing. Two very different stories are converging inside one stock.
The Luvata tie-up is not Bruker's first rodeo in fusion. BEST and Luvata previously supplied materials and expertise to ITER, the international fusion megaproject, and to the Wendelstein 7-X stellarator, two of the most advanced superconducting plasma facilities ever built. Their RRP superconductors, wires built with the Rod-Restack Process to withstand field strengths between 12 and 20 Tesla, already run inside CERN's Large Hadron Collider and in ultra-high field NMR magnets. That track record matters now because fusion programs are ramping across Europe, the Americas, China, ***** an and South Korea, and Gauss Fusion has already begun evaluating RRP superconductors for its Gauss Industrial Demonstrator and GIGA power plant platform.
The segment is already delivering. On August 4, Bruker reported that BEST revenue climbed 11.9% year over year to $74.2 million in the second quarter, with organic growth of 8.9% net of intercompany eliminations, while first-half BEST revenue rose 12.3% to $141 million. That growth showed up in Bruker's bottom line too. Non-GAAP operating margin expanded to 14.1% from 9% a year earlier, and non-GAAP diluted earnings per share grew to $0.49 from $0.32, results strong enough that management kept its full-year non-GAAP EPS growth target of 15% to 17% intact.
None of that shows up on a GAAP basis. Bruker's second-quarter GAAP operating results swung to a $65.3 million loss, versus $11.9 million of GAAP operating income a year earlier, dragged down largely by a $134.9 million non-cash goodwill charge. GAAP diluted earnings per share swung to a loss of $0.41 from a profit of $0.05, and for the first half of 2026 the company posted a GAAP diluted loss per share of $0.39. Impairments do not spend cash, but they are a reminder that some of what Bruker paid for in past acquisitions is now being written down.
#fusion

1 month ago
NVIDIA Corporation (NASDAQ:NVDA) has officially committed billions on AI developer platform Hugging Face for a $12.9 billion. The deal signifies the chipmaker's move beyond hardware and up the AI stack.
The AI chipmaker buying the open-source model hub millions of developers are already using reads differently when compared to Broadcom's earlier forecast to double its AI chip revenue to roughly $230 billion in fiscal 2028.
Even though AVGO is facing increased competition in Google's TPU programs, it is also gaining ground with customers such as OpenAI and Anthropic. This makes Nvidia's recent move look more like insurance rather than opportunism.
In response to the acquisition, Needham ******* yst Rajvindra Gill reiterated a Buy rating on Nvidia on September 4, ******* igning a $300.00 price target.
"Yesterday, NVIDIA announced its agreement to buy Hugging Face for $12.930BN. Hugging Face is the open source platform for hosting open source and open weight models and datasets enabling developers to easily access ready-to-use models instead of building and training them from scratch."
#developers
1 month ago
By Deepa Seetharaman and Raphael Satter
SAN FRANCISCO, Sept 4 (Reuters) - A swarm of rogue OpenAI agents hijacked a German website this spring and transformed it into a bulletin board for other AI agents, according to new research published Friday and two people familiar with the matter.
OpenAI officials learned of the incident weeks ago but kept it under wraps as executives grappled with the fallout from the July breach of the open source repository Hugging Face, the people said.
The episode, which began in May and has not previously been reported, underscores growing tension within the AI industry. Companies are racing to build increasingly autonomous agents capable of carrying out complex, valuable tasks, yet evidence is mounting that those systems may also learn to bend rules, exploit loopholes and coordinate with one another in ways developers neither anticipated nor intended.
During the Hugging Face breach, OpenAI agents autonomously plotted a digital heist that went undetected for more than a week, intensifying concerns OpenAI is sacrificing safety to push the AI frontier. Its failure to disclose the May incident may revive questions about its oversight.
#incident
1 month ago
On September 4, Bruker (NASDAQ:BRKR) said its energy and supercon technologies unit, Bruker Energy & Supercon Technologies (or BEST), had struck a supply collaboration with Luvata Materials & Solutions to scale up production of RRP superconductors for magnetic confinement fusion. The deal lands right as governments and private developers from Europe to South Korea race to build fusion demonstration plants, and it comes a month after Bruker's core scientific instruments business showed its first real signs of stabilizing. Two very different stories are converging inside one stock.
The Luvata tie-up is not Bruker's first rodeo in fusion. BEST and Luvata previously supplied materials and expertise to ITER, the international fusion megaproject, and to the Wendelstein 7-X stellarator, two of the most advanced superconducting plasma facilities ever built. Their RRP superconductors, wires built with the Rod-Restack Process to withstand field strengths between 12 and 20 Tesla, already run inside CERN's Large Hadron Collider and in ultra-high field NMR magnets. That track record matters now because fusion programs are ramping across Europe, the Americas, China, **** an and South Korea, and Gauss Fusion has already begun evaluating RRP superconductors for its Gauss Industrial Demonstrator and GIGA power plant platform.
The segment is already delivering. On August 4, Bruker reported that BEST revenue climbed 11.9% year over year to $74.2 million in the second quarter, with organic growth of 8.9% net of intercompany eliminations, while first-half BEST revenue rose 12.3% to $141 million. That growth showed up in Bruker's bottom line too. Non-GAAP operating margin expanded to 14.1% from 9% a year earlier, and non-GAAP diluted earnings per share grew to $0.49 from $0.32, results strong enough that management kept its full-year non-GAAP EPS growth target of 15% to 17% intact.
None of that shows up on a GAAP basis. Bruker's second-quarter GAAP operating results swung to a $65.3 million loss, versus $11.9 million of GAAP operating income a year earlier, dragged down largely by a $134.9 million non-cash goodwill charge. GAAP diluted earnings per share swung to a loss of $0.41 from a profit of $0.05, and for the first half of 2026 the company posted a GAAP diluted loss per share of $0.39. Impairments do not spend cash, but they are a reminder that some of what Bruker paid for in past acquisitions is now being written down.
#gaap #bruker #million #already
1 month ago
Nvidia's (NVDA) big deal for Hugging Face makes strategic sense not only for Nvidia, but for a wider tech industry barreling right through the AI era.
"Jensen [CEO Jensen Huang] knows this [deal] is very strategic. So in the end, if he's helped accelerate the momentum of adoption [of AI] in enterprise, that's all good news," Hewlett Packard Enterprise (HPE) CEO Antonio Neri told Yahoo Finance in an interview.
The acquisition — confirmed on Thursday — gives the chip giant direct access to the world's largest repository of AI models and datasets. That repository is used by over 18 million developers and 200,000 enterprise organizations worldwide.
Strategically, the move gives Nvidia unparalleled real-time visibility into developer trends, popular model architectures, and emerging framework preferences across the global AI ecosystem.
Added Neri, "We need to find ways to continue to optimize the economics because the reality is that you're going to use different types of tokens from different types of models to deliver the outcome. You're looking at an AI agent process approach. So you're going to have frontier models, open-source models and open-weight models. But the reality is also that China obviously has been a big contributor to the open-source community and is leveraging the open-source community for their own needs. So we need to strike a balance, and therefore having a much stronger presence in the open source communities is incredible."
#open #enterprise #jensen #strategic


1 month ago
This story was originally published on Bisnow, the newsroom global commercial real estate reads first. To receive daily news and ****** ysis, subscribe to Bisnow's free suite of newsletters.
Dallas-Fort Worth's growing financial hub, commonly referred to as Y'all Street, has turned Uptown Dallas into a premier office market in the region, commanding North Texas' highest rents and accounting for nearly 94% of its development pipeline.
Rents for the newest trophy office ****** e in Uptown have grown nearly 31% over the last two years as companies seek the highest-quality product available in the submarket that has become the heart of Dallas-Fort Worth's growing financial sector. That increase is almost double the just over 16% rent growth recorded across the metro in that same time frame, according to JLL data.
The 1.3M SF of top-tier office ****** e delivered in Uptown over the last two years also accounts for nearly 31% of the metro's new inventory during that time. Continued demand for trophy office ****** e near Y'all Street companies and the premium rents they fetch have developers scrambling to build new projects in Uptown, according to JLL Dallas Director of Research Micah Rabalais.
"Is it going to be what it was 10 years ago from a construction volume standpoint, where we might have had, in Uptown alone, 3M SF or 4M SF underway at certain points in time? Probably not, but I do think we maintain this pace," Rabalais said of his forecast of another 1.3M SF that could be delivered by the middle of 2028.
#dallas #rents #fort